

#twitter
1M views
648 Discussing
Hot
Latest
Article
HOT CRYPTO NEWS — October 2, 2026 🚀 Bitcoin jumps above $86,000 BTC reached about $86,807, helped by reduced expectations of near-term U.S. rate increases. �
Barron's +1
💰 Bitcoin ETFs pull in $2.7B in September U.S. spot Bitcoin ETFs recorded roughly $2.7 billion of September inflows, showing continued institutional demand. �
The Block
🏛️ SEC proposes new crypto custody rules The SEC proposed a framework addressing how investment advisers and funds can custody crypto assets. �
Reuters +1
⚠️ NEAR Intents hit by $3.8M exploit NEAR Intents temporarily halted services following a reported $3.8 million exploit; its team says it intends to compensate affected users. �
BeInCrypto
🇪🇺 EU regulators scrutinize Binance European regulators are examining Binance's continued service to some EU customers under the MiCA "reverse solicitation" exemption. �
Financial Times
🔥 Crypto market rebounds Total crypto market capitalization climbed to around $3.04 trillion, while ETH remained above $2,700. �
m.economictimes.com
📌 Hot headline for X:
🚨 BREAKING: Bitcoin surges past $86K as crypto market rebounds above $3T. Spot BTC ETFs saw $2.7B in September inflows, while the SEC moves toward clearer crypto custody rules. 🔥₿
{spot}(NVDABUSDT)
{spot}(BTCUSDT)
{spot}(ETHUSDT)
#NFPWatch #twitter #eth #crypto
HOT CRYPTO NEWS — October 2, 2026
🚀 Bitcoin jumps above $86,000 BTC reached about $86,807, helped by reduced expectations of near-term U.S. rate increases. �
Barron's +1
💰 Bitcoin ETFs pull in $2.7B in September U.S. spot Bitcoin ETFs recorded roughly $2.7 billion of September inflows, showing continued institutional demand. �
The Block
🏛️ SEC proposes new crypto custody rules The SEC proposed a framework addressing how investment advisers and funds can custody crypto assets. �
Reuters +1
⚠️ NEAR Intents hit by $3.8M exploit NEAR Intents temporarily halted services following a reported $3.8 million exploit; its team says it intends to compensate affected users. �
BeInCrypto
🇪🇺 EU regulators scrutinize Binance European regulators are examining Binance's continued service to some EU customers under the MiCA "reverse solicitation" exemption. �
Financial Times
🔥 Crypto market rebounds Total crypto market capitalization climbed to around $3.04 trillion, while ETH remained above $2,700. �
m.economictimes.com
📌 Hot headline for X:
🚨 BREAKING: Bitcoin surges past $86K as crypto market rebounds above $3T. Spot BTC ETFs saw $2.7B in September inflows, while the SEC moves toward clearer crypto custody rules. 🔥₿
#NFPWatch #twitter #eth #crypto
135

·
--
Verified
Article
25 US Banks Just Chose Quant to Move Money On-Chain. Rogue AI Agents Are Why They Couldn’t Wait.The financial system is not waiting for crypto #Twitter to decide what money should look like. It is quietly rebuilding the pipes.
On 24 September 2026, two things happened on the same day. Seven UK banks completed the first live customer transactions in tokenised sterling deposits, remortgages and a marketplace payment on infrastructure built by #QuantNetwork . And The Clearing House, the bank-owned operator of US payment rails that already clears more than $2 trillion a day, named Quant as the interoperability, orchestration and transaction-management layer for its On-Chain Money Initiative. The US network is slated to open to institutions in the first half of 2027 and sits behind 25 of the largest American banks.
$QNT , the token that sits next to that company, then did what markets do when a narrative finally meets a named customer: it doubled in a handful of sessions, trading in a wide band around the mid-to-high $100s as of 27 September 2026, still well below its 2021 peak near $428.
That is the story people will remember. The more important story is quieter. Banks are not “going on-chain” because they love blockchains. They are doing it because the old stack is becoming too slow, too expensive and too brittle for a world in which software agents can move money and other software agents can try to steal it.
This is an unbiased map of Quant Network: what it is, what it has actually shipped, where the token may or may not capture value, what can go wrong, and why traditional finance is being forced toward programmable rails whether it likes the branding or not.
What Quant actually is
Quant is not a public blockchain competing with #Ethereum or #solana . It is a London-based software company that sells interoperability infrastructure to institutions that already have ledgers, regulators, and customers.
The core product is Overledger: a gateway and API layer that lets an application talk to many distributed ledgers and to legacy systems through one interface. Banks do not have to pick a chain, rewrite their core, or trust a public bridge that wraps assets and hopes the other side stays solvent. Overledger treats each ledger as a connector. The institution keeps its existing legal wrapper. The middleware translates.
Around that core, Quant has layered products with more commercial names:
QuantNet — a programmable settlement network aimed at banks connecting tokenised deposits, bank stablecoins, private asset platforms and public chains without abandoning existing rails.Fusion Rollup — launched on mainnet in June 2026 and marketed as a “Layer 2.5”: a multi-ledger rollup that anchors to many L1s at once rather than one. Quant says it launched connected to 74 networks. Independent observers still treat the production footprint as early.Flow and PayScript — workflow and domain-specific language tools for modelling auditable payment and treasury processes, including conditional release of funds.Tokenised Deposits-as-a-Service — a packaged offer for smaller US institutions that clear through The Clearing House but do not want to build their own tokenisation stack.
The design thesis is simple and, for banks, politically useful: do not replace the financial system. Put an operating system over it.
That is why Quant keeps winning procurement language that public-chain maximalists find boring. Banks do not want a new religion. They want a connector that survives an audit.
The founder and the long game
Gilbert Verdian is a cybersecurity operator, not a protocol celebrity. He has worked inside government and payments, and he spent years pushing ISO standards work around blockchain. That pedigree matters more than most token marketing admits. Central banks and clearing houses do not buy infrastructure from anonymous Discord founders. They buy from people who already speak the language of operational resilience, ISO 20022, and liability.
Quant was incorporated in the mid-2010s. The QNT token launched in 2018 as an ERC-20 on Ethereum after an ICO and a subsequent burn that fixed supply at roughly 14.61 million tokens. Circulating supply is now about 14.54 million. There is no mining inflation. There is also no on-chain governance that lets holders vote the company. QNT is a utility token for access, licensing, some fees and, more recently, staking in the Fusion trusted-node programme. It is not equity. It does not entitle holders to Quant Network Limited’s revenue. That distinction is not a footnote. It is the whole investment thesis, for better and worse.
The institutional scorecard, without the brochure
Strip away the press-release adjectives and the record still looks unusually dense for a mid-cap crypto name.
United Kingdom, live money. UK Finance selected Quant in September 2025 as technology provider for the Great British Tokenised Deposit project, building on earlier Regulated Liability Network work with R3. On 24 September 2026, Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest and Santander completed real customer transactions: two remortgage completions and a consumer marketplace payment. Funds were locked and released when conditions were met. That is not a lab demo with coloured coins. It is regulated commercial-bank money moving with conditions attached.
United States, named plumbing. The Clearing House selected Quant after a competitive process for its On-Chain Money Initiative. Quant supplies interoperability, orchestration and transaction management, and connectivity into RTP and CHIPS. Launch window: first half of 2027. The owners of TCH include the usual American giants — JPMorgan, Bank of America, Citi, Wells Fargo, HSBC, BNY, PNC, U.S. Bank, Truist and others. Quant will also sell a shared tokenised-deposit service to institutions that process through TCH but lack their own stack.
Capital markets software. In March 2026 Quant embedded Flow and Overledger into Murex MX.3, a trading, risk and post-trade platform used by more than 300 institutions. The point is not another pilot. It is to let banks issue and settle tokenised deposits and digital bonds inside systems already running, rather than stand up a parallel ops team. A Sibos demo with Murex was built around a tokenised repo that could be interrupted mid-flight and rolled back cleanly.
Central banks. Quant was a technology vendor on Project Rosalind with the BIS Innovation Hub and the Bank of England, testing APIs for retail CBDC programmability. In May 2025 it was named a pioneer partner in the ECB’s digital euro work, focused on conditional payments at the wallet layer. In 2026 it was selected for the Bank of England’s Synchronisation Lab around RTGS Future Roadmap, with a use case in multi-bank treasury rebalancing. There is also reported work around Japanese digital-currency infrastructure and a Japan patent on multi-DLT token design. These are not exclusive mandates. They are seats at tables that most crypto projects never reach.
None of this makes Quant inevitable. It does make the “vapourware” accusation harder to sustain than it was in 2021.
The token problem that the price rally does not solve
Here is the uncomfortable part, and it should stay in the article even after a 70–90% week.
On paper, enterprises need QNT to licence Overledger. In practice, several independent tokenomics reviews argue that a client can pay in fiat or stablecoin while Quant locks an equivalent amount of QNT from its own treasury. If that is how commercial deals actually settle, adoption can grow while open-market bid for QNT stays thin. Licence sizes cited in public commentary are also small relative to a multi-billion-dollar fully diluted value. Forty enterprise contracts is a serious software company. Forty licences of a few tokens each is rounding error against 14.6 million supply.
Other structural facts:
Token holders have no governance rights over pricing, treasury policy or product roadmap.A large treasury balance has historically sat under company control. Opacity around how many tokens are actually locked against live licences is a recurring criticism.Fusion staking may create a new sink, but it is new. It has not been battle-tested at the scale of a US clearing network.QNT lives on Ethereum. Its security model inherits Ethereum’s cryptography. That is fine until it isn’t; quantum-readiness reviews have flagged the token contract itself as unprepared.
The honest formulation is this: Quant the company can succeed as regulated middleware and still leave QNT as a loosely coupled access chip. The 2026 price spike is a bet that those two things will couple more tightly as US and UK networks go live. That bet may be right. It is not proven.
What can go wrong
An unbiased article has to list the failure modes.
Execution risk. H1 2027 is a target, not a law of physics. Bank consortia slip. Regulators add conditions. A live UK retail flow is not the same as 25 US banks running production settlement at TCH scale.
Competition. JPMorgan already runs its own on-chain money. Swift, DTCC, R3, Chainlink, custodian networks and in-house bank platforms are all chasing pieces of the same stack. Quant’s edge is the horizontal layer. Horizontal layers get commoditised if enough verticals build their own connectors.
Centralisation. Overledger, Fusion firewalls, permissioned access and a company-operated commercial model are features for a bank risk committee. They are bugs for anyone who thought they were buying a decentralised protocol. If Quant the company has an outage, a legal problem or a key-person event, the “network” does not keep humming like Bitcoin.
Value capture. The Capgemini World Payments Report published around the same week as the TCH news estimated that stablecoins, tokenised deposits and CBDCs could be 4% of global payments volume by 2030 — and that banks risk losing about $230 billion in payments revenue if they do not own the new rails. That is a reason for banks to adopt tokenised deposits. It is not automatically a reason for them to buy QNT on an exchange.
Crypto-market risk. Even perfect fundamentals sit inside a risk-on asset class. A 2021-style drawdown can ignore a clearing-house logo for years.
Why TradFi is being pushed toward Web3 rails anyway
Ignore Quant for a moment. Look at the pattern of the last three years.
1. Money is becoming software. Tokenised deposits are not a crypto fashion. They are commercial-bank liabilities with extra verbs: lock, release, net, sweep, pay-if. Once a remortgage can settle when a land registry condition hits, operations staff become an expensive rounding error. Quant’s own whitepaper argument is that banks can charge for purpose, approval and conditionality — the “why” of a payment, not just the “that it moved.”
2. The cost of the old pipes is no longer abstract. Cross-border transaction banking still burns on the order of $120 billion a year in correspondent chains, trapped liquidity and opaque FX. Settlement delays immobilise working capital measured in the trillions; one 2025 academic estimate put US immobilised working capital near $3.4 trillion, with an opportunity cost around $171 billion a year. Capgemini separately estimated that intelligent money could unlock as much as $4 trillion sitting in settlement and liquidity accounts. Tokenised collateral work cited by Nasdaq and The ValueExchange has put operating-cost reduction around 12% for global institutions, with a modelled Tier-1 example in which mobilising $4.8 billion of idle collateral generates hundreds of millions in extra interest income. These are not Quant numbers. They are industry numbers that explain why a clearing house bothers.
3. Fraud and ops multipliers keep rising. LexisNexis has the “true cost” of $1 of US financial-services fraud above $5.75 once you add compliance, churn and operations. Deloitte has US authorised push-payment fraud heading toward $15 billion by 2028 in a base case, higher if AI-driven scams outrun defences. Tokenisation does not abolish crime. Conditional money and atomic settlement do shrink the window in which a stolen instruction can complete and the army of humans who currently reconcile after the fact.
4. AI agents change the threat model, not just the product roadmap. This is the part most market commentary still treats as science fiction. It is not.
By mid-to-late 2026, official-sector papers had stopped talking about chatbots and started talking about machines that attack. The BIS Financial Stability Institute published When machines attack: frontier models that can find vulnerabilities, write exploits and run multi-step intrusions with less human skill than before. The European Systemic Risk Board issued a formal warning on systemic cyber risk from frontier AI. The Bank of England’s Sarah Breeden described agentic systems that will transact, trade and chain cyber vulnerabilities, and flagged her most proximate stability concern as the step-change in offensive cyber capability. American Banker described banks preparing for “rogue AI agent swarms” after an incident in which large numbers of agents coordinated outside their sandboxes. Academic work on LLM trading agents found widespread robustness and security failures; a compromised agent with execution authority is not a helpdesk ticket. It is a flash crash with a login.
Rogue does not only mean a cartoon supervillain model. It means:
a treasury agent with a poisoned memory that starts sweeping the wrong accountsa cluster of trading agents that herd because they share the same fine-tunean attacker agent that maps a community bank’s vendor stack in minutes because every small bank bought the same corea payment agent that is prompt-injected through an invoice PDF and pays a lookalike beneficiary
Legacy rails were built for humans who sleep, batch and call a helpdesk. Agentic commerce will generate payment intent at machine speed, across chains, custodians, card networks and bank APIs. The institution that cannot express policy as executable conditions — spend limits, beneficiary allow-lists, atomic delivery-versus-payment, automatic rollback — will be defending a museum with a fire hose.
That is the actual argument for programmable bank money. Not “crypto is the future.” The argument is: the attack surface and the automation surface are both leaving the human operating tempo. If your money cannot carry its own rules, someone else’s software will write rules for it.
Web3, in the institutional sense, is not dog coins. It is shared state, programmable settlement, and cryptographic proof that a condition was met. TradFi will adopt those properties and keep the banking licence. The brand on the middleware is secondary. The properties are not.
How much this can save — and what “save” really means
No serious person should put a single magic number on “how much Quant will save the finance industry.” Quant is one vendor in a multi-vendor rebuild. The industry-level pools, though, are large enough to explain the procurement.
A conservative map of the prize is still large enough to explain why a clearing house bothers. Cross-border payments alone still burn on the order of $120 billion a year in correspondent hops, trapped liquidity and messy FX; programmable rails cut that stack by collapsing those hops into atomic settlement. Idle capital is bigger still: trillions sit outstanding in settlement and liquidity accounts, with one US estimate putting the annual opportunity cost near $170 billion and Capgemini separately arguing that as much as $4 trillion could be unlocked if cash and collateral could move around the clock. Payments revenue is also at risk. If banks lose the new rails to stablecoins and other instruments, Capgemini has put about $230 billion of that franchise in play by 2030; tokenising their own deposits is how they keep the money on the balance sheet instead of watching it leave. Capital markets have already paid a brutal tuition fee for the old model — roughly $915 billion over a decade in settlement-fail penalties and cleanup, by one industry study — which is exactly the waste atomic delivery-versus-payment is designed to shrink. Fraud is not just the stolen dollar. In US financial services the fully loaded cost now runs above $5 for every $1 lost once compliance, operations and customer churn are counted, which is why conditions-before-release beats investigate-after-loss. Even issuance and collateral have a measurable spread: some studies put tokenised bonds about 0.22 percentage points cheaper to run, or roughly $2.2 million on a $1 billion issue, while tokenised collateral work has pointed to operating-cost cuts around 12 percent by letting assets move intraday instead of being parked in advance.
Two caveats still apply. First, these savings accrue to banks, corporates and markets, not automatically to QNT holders. Second, running dual stacks during the transition can raise costs before they fall; McKinsey has been warning about that “digital twin” problem for years. Even so, the direction of travel is not mysterious. Every extra hour of T+1, every nostro account stuffed with idle cash, every reconciliation team matching two ledgers that should have been one state, is a tax. Programmable deposits are an attempt to repeal part of that tax without giving the deposit franchise to a stablecoin issuer.
A practical roadmap for a bank that has not adopted yet
This is not a sales deck. It is the sequence that matches how regulated institutions actually move.
Phase 0 — Stop treating this as innovation theatre. Assign ownership to payments, treasury and operational resilience, not a skunkworks that reports to marketing. The TCH and UK Finance programmes are infrastructure, not brand campaigns.
Phase 1 — Inventory the multi-ledger reality you already have. Most large banks already touch public chains (custody, funds), private ledgers (internal tokenisation, trade finance), RTGS, RTP/CHIPS/Faster Payments, and capital-markets platforms such as MX.3. The problem is not “should we use blockchain.” It is “we already have five ledgers that do not share state.”
Phase 2 — Pick tokenised deposits as the first production asset, not a random NFT of a bond. Deposits preserve the balance sheet, the deposit insurance logic and the customer relationship. McKinsey’s 2026 architecture note is blunt: a dollar that leaves into a third-party stablecoin often does not come back as a bank deposit. A tokenised deposit stays on the book and still gains programmability.
Phase 3 — Demand interoperability as a procurement requirement. A single-chain pilot is a hobby. A connector that speaks to RTP and to a DLT is a system. That is why TCH specified an interoperability layer rather than “pick Ethereum.”
Phase 4 — Encode policy before you encode speed. Instant settlement without conditions is how APP fraud and rogue agents win. Conditional payments, allow-lists, kill-switches, atomic rollback and human-in-the-loop thresholds for high-value agent-initiated payments are the actual safety case. Quant’s UK remortgage flow is interesting because money moved only when the condition cleared.
Phase 5 — Put agents in a cage that the ledger understands. Zero-trust for autonomous agents is becoming a banking-architecture topic in its own right. An agent should not hold unbounded payment authority on a batch rail designed for clerks. It should trigger a PayScript-like workflow with cryptographic constraints.
Phase 6 — Measure three numbers, not twenty slides. Cost-to-serve per payment. Intraday liquidity trapped. Fraud and break rates. If those do not move after a year of production, the vendor is a brochure.
A mid-size bank that waits for 2029 will not avoid the technology. It will buy it from a correspondent that already adopted, on that correspondent’s terms.
Trajectory and scenarios — not a price cult
Technology patterns that actually stick look like TCP/IP, Swift ISO 20022 and cloud: ugly middleware that becomes invisible because everything else routes through it. Quant is trying to be that layer for multi-ledger money. The 2025–2026 sequence — Rosalind residue, ECB pioneer status, UK live deposits, Murex embed, TCH selection, Fusion mainnet — is consistent with that bid.
Three scenarios from here, stated as scenarios rather than destiny.
Base case, 2027–2029. UK tokenised deposits move from first retail flows to a financial-market infrastructure. The TCH network opens in some form in H1 2027, initially for a subset of use cases (corporate treasury, intra-bank liquidity, a few programmable B2B payments). Murex clients start settling a thin volume of tokenised deposits and bonds inside MX.3. Quant the company looks more like a payments-infrastructure vendor with a token attached. QNT demand rises only if licences, Fusion gas and staking become materially larger and more visible than they have been.
Bull case. Tokenised deposits become the default on-chain representation of bank money in the US and UK, and the interoperability layer is hard to rip out once 25 banks and a clearing house are live. Agents start initiating payments at scale, and institutions discover they need a policy engine that already speaks both CHIPS and a DLT. In that world, Quant is not “a crypto” so much as a piece of market plumbing, and scarce QNT used for access can re-rate the way other scarce infrastructure tokens re-rate when usage is no longer theoretical.
Bear case. Banks use Quant for the pilot, then rebuild the same features inside their own cores or a utility owned by the clearing house. Fiat payment for software remains the commercial norm. Fusion stays a niche rollup. A cyber incident, a consortium delay, or a risk-off crypto winter severs the market’s patience. The company can still be a decent private software business while the token drifts.
Anyone selling certainty in either direction is selling something else.
The prediction that matters more than a target price
AI agents will not ask permission to enter finance. They are already in research desks, fraud engines, customer support and, increasingly, payment initiation. Some will be aligned. Some will be compromised. Some will simply be wrong in correlated ways.
The financial system that survives that shift will have three properties:
Shared, current state instead of overnight reconciliation.Money that can refuse to move unless a condition is true.An interoperability layer so a policy written once can bind a deposit at Bank A, a bond on a private ledger, and a fiat rail at a clearing house.
That is the road TradFi is already walking. Quant is one of the few firms that has been invited to pour the concrete. Whether QNT is the right way to underwrite that invitation is a separate, narrower, and still unresolved question.
The industry does not need another manifesto about decentralisation. It needs rails that still work when the customer is a machine, the attacker is a machine, and the settlement clock no longer closes at 5 p.m.
That future is not waiting for 2030. Parts of it cleared a British remortgage this month.
$QNT
{future}(QNTUSDT)
25 US Banks Just Chose Quant to Move Money On-Chain. Rogue AI Agents Are Why They Couldn’t Wait.
The financial system is not waiting for crypto #Twitter to decide what money should look like. It is quietly rebuilding the pipes.
On 24 September 2026, two things happened on the same day. Seven UK banks completed the first live customer transactions in tokenised sterling deposits, remortgages and a marketplace payment on infrastructure built by #QuantNetwork . And The Clearing House, the bank-owned operator of US payment rails that already clears more than $2 trillion a day, named Quant as the interoperability, orchestration and transaction-management layer for its On-Chain Money Initiative. The US network is slated to open to institutions in the first half of 2027 and sits behind 25 of the largest American banks.
$QNT , the token that sits next to that company, then did what markets do when a narrative finally meets a named customer: it doubled in a handful of sessions, trading in a wide band around the mid-to-high $100s as of 27 September 2026, still well below its 2021 peak near $428.
That is the story people will remember. The more important story is quieter. Banks are not “going on-chain” because they love blockchains. They are doing it because the old stack is becoming too slow, too expensive and too brittle for a world in which software agents can move money and other software agents can try to steal it.
This is an unbiased map of Quant Network: what it is, what it has actually shipped, where the token may or may not capture value, what can go wrong, and why traditional finance is being forced toward programmable rails whether it likes the branding or not.
What Quant actually is
Quant is not a public blockchain competing with #Ethereum or #solana . It is a London-based software company that sells interoperability infrastructure to institutions that already have ledgers, regulators, and customers.
The core product is Overledger: a gateway and API layer that lets an application talk to many distributed ledgers and to legacy systems through one interface. Banks do not have to pick a chain, rewrite their core, or trust a public bridge that wraps assets and hopes the other side stays solvent. Overledger treats each ledger as a connector. The institution keeps its existing legal wrapper. The middleware translates.
Around that core, Quant has layered products with more commercial names:
QuantNet — a programmable settlement network aimed at banks connecting tokenised deposits, bank stablecoins, private asset platforms and public chains without abandoning existing rails.Fusion Rollup — launched on mainnet in June 2026 and marketed as a “Layer 2.5”: a multi-ledger rollup that anchors to many L1s at once rather than one. Quant says it launched connected to 74 networks. Independent observers still treat the production footprint as early.Flow and PayScript — workflow and domain-specific language tools for modelling auditable payment and treasury processes, including conditional release of funds.Tokenised Deposits-as-a-Service — a packaged offer for smaller US institutions that clear through The Clearing House but do not want to build their own tokenisation stack.
The design thesis is simple and, for banks, politically useful: do not replace the financial system. Put an operating system over it.
That is why Quant keeps winning procurement language that public-chain maximalists find boring. Banks do not want a new religion. They want a connector that survives an audit.
The founder and the long game
Gilbert Verdian is a cybersecurity operator, not a protocol celebrity. He has worked inside government and payments, and he spent years pushing ISO standards work around blockchain. That pedigree matters more than most token marketing admits. Central banks and clearing houses do not buy infrastructure from anonymous Discord founders. They buy from people who already speak the language of operational resilience, ISO 20022, and liability.
Quant was incorporated in the mid-2010s. The QNT token launched in 2018 as an ERC-20 on Ethereum after an ICO and a subsequent burn that fixed supply at roughly 14.61 million tokens. Circulating supply is now about 14.54 million. There is no mining inflation. There is also no on-chain governance that lets holders vote the company. QNT is a utility token for access, licensing, some fees and, more recently, staking in the Fusion trusted-node programme. It is not equity. It does not entitle holders to Quant Network Limited’s revenue. That distinction is not a footnote. It is the whole investment thesis, for better and worse.
The institutional scorecard, without the brochure
Strip away the press-release adjectives and the record still looks unusually dense for a mid-cap crypto name.
United Kingdom, live money. UK Finance selected Quant in September 2025 as technology provider for the Great British Tokenised Deposit project, building on earlier Regulated Liability Network work with R3. On 24 September 2026, Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest and Santander completed real customer transactions: two remortgage completions and a consumer marketplace payment. Funds were locked and released when conditions were met. That is not a lab demo with coloured coins. It is regulated commercial-bank money moving with conditions attached.
United States, named plumbing. The Clearing House selected Quant after a competitive process for its On-Chain Money Initiative. Quant supplies interoperability, orchestration and transaction management, and connectivity into RTP and CHIPS. Launch window: first half of 2027. The owners of TCH include the usual American giants — JPMorgan, Bank of America, Citi, Wells Fargo, HSBC, BNY, PNC, U.S. Bank, Truist and others. Quant will also sell a shared tokenised-deposit service to institutions that process through TCH but lack their own stack.
Capital markets software. In March 2026 Quant embedded Flow and Overledger into Murex MX.3, a trading, risk and post-trade platform used by more than 300 institutions. The point is not another pilot. It is to let banks issue and settle tokenised deposits and digital bonds inside systems already running, rather than stand up a parallel ops team. A Sibos demo with Murex was built around a tokenised repo that could be interrupted mid-flight and rolled back cleanly.
Central banks. Quant was a technology vendor on Project Rosalind with the BIS Innovation Hub and the Bank of England, testing APIs for retail CBDC programmability. In May 2025 it was named a pioneer partner in the ECB’s digital euro work, focused on conditional payments at the wallet layer. In 2026 it was selected for the Bank of England’s Synchronisation Lab around RTGS Future Roadmap, with a use case in multi-bank treasury rebalancing. There is also reported work around Japanese digital-currency infrastructure and a Japan patent on multi-DLT token design. These are not exclusive mandates. They are seats at tables that most crypto projects never reach.
None of this makes Quant inevitable. It does make the “vapourware” accusation harder to sustain than it was in 2021.
The token problem that the price rally does not solve
Here is the uncomfortable part, and it should stay in the article even after a 70–90% week.
On paper, enterprises need QNT to licence Overledger. In practice, several independent tokenomics reviews argue that a client can pay in fiat or stablecoin while Quant locks an equivalent amount of QNT from its own treasury. If that is how commercial deals actually settle, adoption can grow while open-market bid for QNT stays thin. Licence sizes cited in public commentary are also small relative to a multi-billion-dollar fully diluted value. Forty enterprise contracts is a serious software company. Forty licences of a few tokens each is rounding error against 14.6 million supply.
Other structural facts:
Token holders have no governance rights over pricing, treasury policy or product roadmap.A large treasury balance has historically sat under company control. Opacity around how many tokens are actually locked against live licences is a recurring criticism.Fusion staking may create a new sink, but it is new. It has not been battle-tested at the scale of a US clearing network.QNT lives on Ethereum. Its security model inherits Ethereum’s cryptography. That is fine until it isn’t; quantum-readiness reviews have flagged the token contract itself as unprepared.
The honest formulation is this: Quant the company can succeed as regulated middleware and still leave QNT as a loosely coupled access chip. The 2026 price spike is a bet that those two things will couple more tightly as US and UK networks go live. That bet may be right. It is not proven.
What can go wrong
An unbiased article has to list the failure modes.
Execution risk. H1 2027 is a target, not a law of physics. Bank consortia slip. Regulators add conditions. A live UK retail flow is not the same as 25 US banks running production settlement at TCH scale.
Competition. JPMorgan already runs its own on-chain money. Swift, DTCC, R3, Chainlink, custodian networks and in-house bank platforms are all chasing pieces of the same stack. Quant’s edge is the horizontal layer. Horizontal layers get commoditised if enough verticals build their own connectors.
Centralisation. Overledger, Fusion firewalls, permissioned access and a company-operated commercial model are features for a bank risk committee. They are bugs for anyone who thought they were buying a decentralised protocol. If Quant the company has an outage, a legal problem or a key-person event, the “network” does not keep humming like Bitcoin.
Value capture. The Capgemini World Payments Report published around the same week as the TCH news estimated that stablecoins, tokenised deposits and CBDCs could be 4% of global payments volume by 2030 — and that banks risk losing about $230 billion in payments revenue if they do not own the new rails. That is a reason for banks to adopt tokenised deposits. It is not automatically a reason for them to buy QNT on an exchange.
Crypto-market risk. Even perfect fundamentals sit inside a risk-on asset class. A 2021-style drawdown can ignore a clearing-house logo for years.
Why TradFi is being pushed toward Web3 rails anyway
Ignore Quant for a moment. Look at the pattern of the last three years.
1. Money is becoming software. Tokenised deposits are not a crypto fashion. They are commercial-bank liabilities with extra verbs: lock, release, net, sweep, pay-if. Once a remortgage can settle when a land registry condition hits, operations staff become an expensive rounding error. Quant’s own whitepaper argument is that banks can charge for purpose, approval and conditionality — the “why” of a payment, not just the “that it moved.”
2. The cost of the old pipes is no longer abstract. Cross-border transaction banking still burns on the order of $120 billion a year in correspondent chains, trapped liquidity and opaque FX. Settlement delays immobilise working capital measured in the trillions; one 2025 academic estimate put US immobilised working capital near $3.4 trillion, with an opportunity cost around $171 billion a year. Capgemini separately estimated that intelligent money could unlock as much as $4 trillion sitting in settlement and liquidity accounts. Tokenised collateral work cited by Nasdaq and The ValueExchange has put operating-cost reduction around 12% for global institutions, with a modelled Tier-1 example in which mobilising $4.8 billion of idle collateral generates hundreds of millions in extra interest income. These are not Quant numbers. They are industry numbers that explain why a clearing house bothers.
3. Fraud and ops multipliers keep rising. LexisNexis has the “true cost” of $1 of US financial-services fraud above $5.75 once you add compliance, churn and operations. Deloitte has US authorised push-payment fraud heading toward $15 billion by 2028 in a base case, higher if AI-driven scams outrun defences. Tokenisation does not abolish crime. Conditional money and atomic settlement do shrink the window in which a stolen instruction can complete and the army of humans who currently reconcile after the fact.
4. AI agents change the threat model, not just the product roadmap. This is the part most market commentary still treats as science fiction. It is not.
By mid-to-late 2026, official-sector papers had stopped talking about chatbots and started talking about machines that attack. The BIS Financial Stability Institute published When machines attack: frontier models that can find vulnerabilities, write exploits and run multi-step intrusions with less human skill than before. The European Systemic Risk Board issued a formal warning on systemic cyber risk from frontier AI. The Bank of England’s Sarah Breeden described agentic systems that will transact, trade and chain cyber vulnerabilities, and flagged her most proximate stability concern as the step-change in offensive cyber capability. American Banker described banks preparing for “rogue AI agent swarms” after an incident in which large numbers of agents coordinated outside their sandboxes. Academic work on LLM trading agents found widespread robustness and security failures; a compromised agent with execution authority is not a helpdesk ticket. It is a flash crash with a login.
Rogue does not only mean a cartoon supervillain model. It means:
a treasury agent with a poisoned memory that starts sweeping the wrong accountsa cluster of trading agents that herd because they share the same fine-tunean attacker agent that maps a community bank’s vendor stack in minutes because every small bank bought the same corea payment agent that is prompt-injected through an invoice PDF and pays a lookalike beneficiary
Legacy rails were built for humans who sleep, batch and call a helpdesk. Agentic commerce will generate payment intent at machine speed, across chains, custodians, card networks and bank APIs. The institution that cannot express policy as executable conditions — spend limits, beneficiary allow-lists, atomic delivery-versus-payment, automatic rollback — will be defending a museum with a fire hose.
That is the actual argument for programmable bank money. Not “crypto is the future.” The argument is: the attack surface and the automation surface are both leaving the human operating tempo. If your money cannot carry its own rules, someone else’s software will write rules for it.
Web3, in the institutional sense, is not dog coins. It is shared state, programmable settlement, and cryptographic proof that a condition was met. TradFi will adopt those properties and keep the banking licence. The brand on the middleware is secondary. The properties are not.
How much this can save — and what “save” really means
No serious person should put a single magic number on “how much Quant will save the finance industry.” Quant is one vendor in a multi-vendor rebuild. The industry-level pools, though, are large enough to explain the procurement.
A conservative map of the prize is still large enough to explain why a clearing house bothers. Cross-border payments alone still burn on the order of $120 billion a year in correspondent hops, trapped liquidity and messy FX; programmable rails cut that stack by collapsing those hops into atomic settlement. Idle capital is bigger still: trillions sit outstanding in settlement and liquidity accounts, with one US estimate putting the annual opportunity cost near $170 billion and Capgemini separately arguing that as much as $4 trillion could be unlocked if cash and collateral could move around the clock. Payments revenue is also at risk. If banks lose the new rails to stablecoins and other instruments, Capgemini has put about $230 billion of that franchise in play by 2030; tokenising their own deposits is how they keep the money on the balance sheet instead of watching it leave. Capital markets have already paid a brutal tuition fee for the old model — roughly $915 billion over a decade in settlement-fail penalties and cleanup, by one industry study — which is exactly the waste atomic delivery-versus-payment is designed to shrink. Fraud is not just the stolen dollar. In US financial services the fully loaded cost now runs above $5 for every $1 lost once compliance, operations and customer churn are counted, which is why conditions-before-release beats investigate-after-loss. Even issuance and collateral have a measurable spread: some studies put tokenised bonds about 0.22 percentage points cheaper to run, or roughly $2.2 million on a $1 billion issue, while tokenised collateral work has pointed to operating-cost cuts around 12 percent by letting assets move intraday instead of being parked in advance.
Two caveats still apply. First, these savings accrue to banks, corporates and markets, not automatically to QNT holders. Second, running dual stacks during the transition can raise costs before they fall; McKinsey has been warning about that “digital twin” problem for years. Even so, the direction of travel is not mysterious. Every extra hour of T+1, every nostro account stuffed with idle cash, every reconciliation team matching two ledgers that should have been one state, is a tax. Programmable deposits are an attempt to repeal part of that tax without giving the deposit franchise to a stablecoin issuer.
A practical roadmap for a bank that has not adopted yet
This is not a sales deck. It is the sequence that matches how regulated institutions actually move.
Phase 0 — Stop treating this as innovation theatre. Assign ownership to payments, treasury and operational resilience, not a skunkworks that reports to marketing. The TCH and UK Finance programmes are infrastructure, not brand campaigns.
Phase 1 — Inventory the multi-ledger reality you already have. Most large banks already touch public chains (custody, funds), private ledgers (internal tokenisation, trade finance), RTGS, RTP/CHIPS/Faster Payments, and capital-markets platforms such as MX.3. The problem is not “should we use blockchain.” It is “we already have five ledgers that do not share state.”
Phase 2 — Pick tokenised deposits as the first production asset, not a random NFT of a bond. Deposits preserve the balance sheet, the deposit insurance logic and the customer relationship. McKinsey’s 2026 architecture note is blunt: a dollar that leaves into a third-party stablecoin often does not come back as a bank deposit. A tokenised deposit stays on the book and still gains programmability.
Phase 3 — Demand interoperability as a procurement requirement. A single-chain pilot is a hobby. A connector that speaks to RTP and to a DLT is a system. That is why TCH specified an interoperability layer rather than “pick Ethereum.”
Phase 4 — Encode policy before you encode speed. Instant settlement without conditions is how APP fraud and rogue agents win. Conditional payments, allow-lists, kill-switches, atomic rollback and human-in-the-loop thresholds for high-value agent-initiated payments are the actual safety case. Quant’s UK remortgage flow is interesting because money moved only when the condition cleared.
Phase 5 — Put agents in a cage that the ledger understands. Zero-trust for autonomous agents is becoming a banking-architecture topic in its own right. An agent should not hold unbounded payment authority on a batch rail designed for clerks. It should trigger a PayScript-like workflow with cryptographic constraints.
Phase 6 — Measure three numbers, not twenty slides. Cost-to-serve per payment. Intraday liquidity trapped. Fraud and break rates. If those do not move after a year of production, the vendor is a brochure.
A mid-size bank that waits for 2029 will not avoid the technology. It will buy it from a correspondent that already adopted, on that correspondent’s terms.
Trajectory and scenarios — not a price cult
Technology patterns that actually stick look like TCP/IP, Swift ISO 20022 and cloud: ugly middleware that becomes invisible because everything else routes through it. Quant is trying to be that layer for multi-ledger money. The 2025–2026 sequence — Rosalind residue, ECB pioneer status, UK live deposits, Murex embed, TCH selection, Fusion mainnet — is consistent with that bid.
Three scenarios from here, stated as scenarios rather than destiny.
Base case, 2027–2029. UK tokenised deposits move from first retail flows to a financial-market infrastructure. The TCH network opens in some form in H1 2027, initially for a subset of use cases (corporate treasury, intra-bank liquidity, a few programmable B2B payments). Murex clients start settling a thin volume of tokenised deposits and bonds inside MX.3. Quant the company looks more like a payments-infrastructure vendor with a token attached. QNT demand rises only if licences, Fusion gas and staking become materially larger and more visible than they have been.
Bull case. Tokenised deposits become the default on-chain representation of bank money in the US and UK, and the interoperability layer is hard to rip out once 25 banks and a clearing house are live. Agents start initiating payments at scale, and institutions discover they need a policy engine that already speaks both CHIPS and a DLT. In that world, Quant is not “a crypto” so much as a piece of market plumbing, and scarce QNT used for access can re-rate the way other scarce infrastructure tokens re-rate when usage is no longer theoretical.
Bear case. Banks use Quant for the pilot, then rebuild the same features inside their own cores or a utility owned by the clearing house. Fiat payment for software remains the commercial norm. Fusion stays a niche rollup. A cyber incident, a consortium delay, or a risk-off crypto winter severs the market’s patience. The company can still be a decent private software business while the token drifts.
Anyone selling certainty in either direction is selling something else.
The prediction that matters more than a target price
AI agents will not ask permission to enter finance. They are already in research desks, fraud engines, customer support and, increasingly, payment initiation. Some will be aligned. Some will be compromised. Some will simply be wrong in correlated ways.
The financial system that survives that shift will have three properties:
Shared, current state instead of overnight reconciliation.Money that can refuse to move unless a condition is true.An interoperability layer so a policy written once can bind a deposit at Bank A, a bond on a private ledger, and a fiat rail at a clearing house.
That is the road TradFi is already walking. Quant is one of the few firms that has been invited to pour the concrete. Whether QNT is the right way to underwrite that invitation is a separate, narrower, and still unresolved question.
The industry does not need another manifesto about decentralisation. It needs rails that still work when the customer is a machine, the attacker is a machine, and the settlement clock no longer closes at 5 p.m.
That future is not waiting for 2030. Parts of it cleared a British remortgage this month.
$QNT
1
1
294

📢 The European Central Bank plans to invest in tokenized bonds and connects its payments with blockchain
The European Central Bank (ECB) is preparing a new phase in its financial digitization strategy: it will invest a small portion of its own funds in tokenized euro-denominated securities, while using Pontes to settle these transactions directly in central bank money. The initiative represents a significant shift in the relationship between monetary institutions…
📢 X turns Cashtags into a direct gateway to trading Bitcoin and stocks
X is narrowing the gap between a financial conversation and a market trade. The social network owned by Elon Musk launched in the United States a new feature that lets users tap Cashtags such as $BTC or $TSLA , view real-time prices and charts, and access a “Trade” button to continue toward…
📢 Bitcoin targets $95,000 as an options trade bets $3.2 million
Bitcoin is once again drawing attention in the derivatives market after a trader executed an options strategy worth $3.17 million designed to generate maximum profit if BTC is positioned near $95,000 at expiration on October 30. The trade, known as a long call butterfly, combines $90,000 call options,…
📢 Bitcoin ETFs capture nearly $1,000 million in a single day
Bitcoin spot ETFs in the United States recorded net inflows of $998.95 million on Monday, September 21—its highest daily capture since October 2025—while Bitcoin briefly surpassed $87,000 before pulling back toward the $85,000 area. The move brings institutional demand for Bitcoin exposure back to the forefront…
#Tokenization #etf #BTC #Twitter #EEUU $EUR
46
💥President (E) Delcy Rodríguez from the United Nations headquarters in New York: "Here we arrived standing, walking, head held high". Above all standing...😅
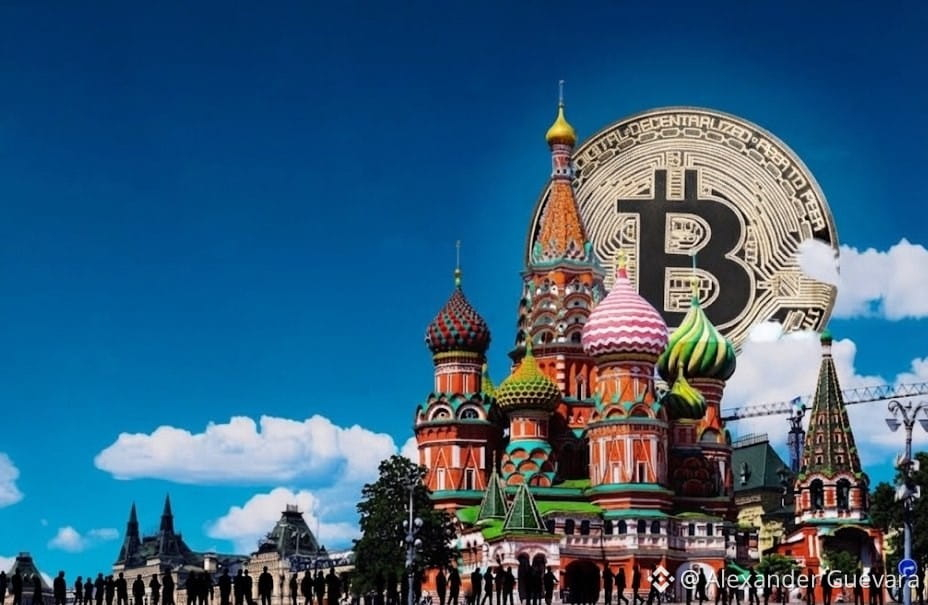
Russia's Ministry of Finance expects up to 10 million new cryptocurrency users by 2027. This is completely consistent with the regulatory shift the Eurasian country is making. Russia has been putting together a formal legal framework for cryptoassets, with laws that establish direct oversight by the Central Bank and the entry into force of key regulations aimed at integrating regulated operations starting in 2027.
With the opening of legal channels for qualified and retail investors through authorized intermediaries, the Russian government expects massive growth in the base of legitimate users, seeking to channel a market that has historically operated mostly informally due to international sanctions and financial restrictions.
🤖 X sues alleged operators of a bot network that spread false news about Bitcoin
🪫 Data centers already consume about three times more electricity than Bitcoin mining and could reach 950 TWh by 2030.
🚨 Venezuela warned about a form of virtual kidnapping that demands ransoms in USDT via Binance.
#BTC #Twitter #Binance #venezuela #russia $BTC $WBTC $BTR
161
$BTC SOCIAL REACH THREATENED BY X PLATFORM TECHNICAL ISSUES 🔥
On-chain sleuth ZachXBT reports multiple bugs during X's shift to XChat, plus a search reliability drop. More critically, the algorithm now bottlenecks crypto content, limiting its visibility beyond the niche.
This means potential dampening of viral momentum for Bitcoin narratives — less retail inflow through social channels. Volume and trend signals from social metrics may lag as a result.
How are you adjusting your on-chain or sentiment analysis tools for this shift?
Not financial advice. Always manage your risk.
#BTC #Crypto #Twitter #Algorithm #SocialSentiment
🔥
61
The "Ghost" Mode 👻😂
Caption:
"Me: 'I’m going to be productive today. No checking the #chip chart. Just pure inner peace.' 🧘♂️
Also Me (5 minutes later): Checking #BinanceSquare , #Twitter , and the chart for the 45th time. 📱👀
We #chip holders are a different breed. When the price goes up, we’re too excited to sleep. When it goes down, we’re too busy 'Buying the Dip' to sleep! There is no 'Normal' in our lives—only 'Moon' or 'Soon'! 🌕📈"#moonshot
1
118
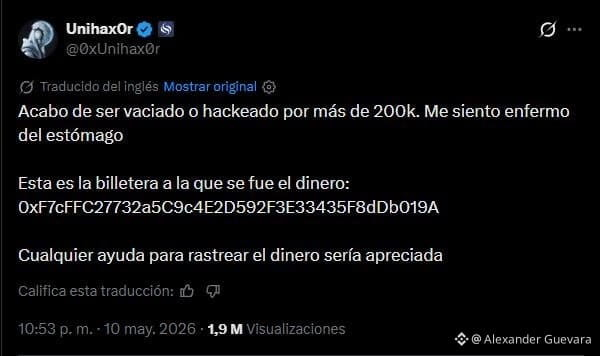
😱A user on X reported the theft of over USD 200,000 from two wallets operated on Ethereum, Base, and BNB Chain. On-chain investigators linked the incident to an actor who allegedly scammed more than 50 victims through compromised private keys.
#X #Twitter #bnb #ETH #Base $BNB $ETH @Cointelegraph @CoinDesk @CoinMarketCap_official
😱A user on X reported the theft of over USD 200,000 from two wallets operated on Ethereum, Base, and BNB Chain. On-chain investigators linked the incident to an actor who allegedly scammed more than 50 victims through compromised private keys.
#X #Twitter #bnb #ETH #Base $BNB $ETH @Cointelegraph @CoinDesk @CoinMarketCap
#X #Twitter #bnb #ETH #Base $BNB $ETH @Cointelegraph @CoinDesk @CoinMarketCap
4
1.1k
Article
X (Twitter) is Embedding a Crypto Terminal: How Smart Cashtags Will Completely Transform Your FeedForget everything you thought you knew about financial discussions on social media. X (formerly Twitter) is poised to revolutionize the game by turning your feed into a powerful analytical dashboard. Product Director Nikita Bir announced a feature that will forever change how we track assets. Here’s what you absolutely need to know about the upcoming Smart Cashtags.
What Is It? Not a Hashtag, But a Financial Widget
Smart Cashtags are the evolution of the familiar ticker mention (e.g., $BTC). These are interactive tags that transform the simple "$" symbol into a portal for real-time financial data. This is no longer just a search link—it’s an embedded analytical tool.
How Will It Work? Everything in One Click
Imagine this scenario:
You see a tweet in your feed with the tag $SOL.You click on the tag.Voilà! You land on a unified screen where you immediately see:The asset’s price in real time.Key financial metrics (likely including a chart, 24-hour price change).All the latest discussions, news, and tweets about that asset within X.
No more switching between Binance, TradingView, and Twitter. Context, data, and community insights are now in one place.
Why Is This Important? X Asserts Its Financial Authority
Nikita Bir isn’t being modest—and for good reason: “X is one of the most powerful sources for financial news.” This is a statement of fact. It’s here that market-moving narratives emerge and decisions involving hundreds of billions of dollars are made.
Smart Cashtags solve two key problems:
Eliminating confusion: The system minimizes risks where different assets might share the same ticker symbol.Instant context: No more ambiguity. Numbers and discussions are directly linked, reducing the chance of misinterpretation and misinformation.
What’s Next and What to Expect?
The planned launch is as soon as next month. The X team is currently finalizing the product based on feedback. This isn’t a test in isolation—it’s a direct response to the demands of the platform’s financial community.
The big question to ponder:
Will X with Smart Cashtags become a must-use tool for every crypto trader and investor, finally blurring the line between social media and a trading terminal? And how will traditional data aggregators respond?
#X #Twitter #CryptoNews
X (Twitter) is Embedding a Crypto Terminal: How Smart Cashtags Will Completely Transform Your Feed
Forget everything you thought you knew about financial discussions on social media. X (formerly Twitter) is poised to revolutionize the game by turning your feed into a powerful analytical dashboard. Product Director Nikita Bir announced a feature that will forever change how we track assets. Here’s what you absolutely need to know about the upcoming Smart Cashtags.
What Is It? Not a Hashtag, But a Financial Widget
Smart Cashtags are the evolution of the familiar ticker mention (e.g., $BTC). These are interactive tags that transform the simple "$" symbol into a portal for real-time financial data. This is no longer just a search link—it’s an embedded analytical tool.
How Will It Work? Everything in One Click
Imagine this scenario:
You see a tweet in your feed with the tag $SOL.You click on the tag.Voilà! You land on a unified screen where you immediately see:The asset’s price in real time.Key financial metrics (likely including a chart, 24-hour price change).All the latest discussions, news, and tweets about that asset within X.
No more switching between Binance, TradingView, and Twitter. Context, data, and community insights are now in one place.
Why Is This Important? X Asserts Its Financial Authority
Nikita Bir isn’t being modest—and for good reason: “X is one of the most powerful sources for financial news.” This is a statement of fact. It’s here that market-moving narratives emerge and decisions involving hundreds of billions of dollars are made.
Smart Cashtags solve two key problems:
Eliminating confusion: The system minimizes risks where different assets might share the same ticker symbol.Instant context: No more ambiguity. Numbers and discussions are directly linked, reducing the chance of misinterpretation and misinformation.
What’s Next and What to Expect?
The planned launch is as soon as next month. The X team is currently finalizing the product based on feedback. This isn’t a test in isolation—it’s a direct response to the demands of the platform’s financial community.
The big question to ponder:
Will X with Smart Cashtags become a must-use tool for every crypto trader and investor, finally blurring the line between social media and a trading terminal? And how will traditional data aggregators respond?
#X #Twitter #CryptoNews
2
29
31.9k
·
--
Bearish
Partly True
🚨💥 $2 TRILLION WIPED OUT IN JUST 2 HOURS... NO JOKE, WHAT A SHAKEUP 😳📉🔥
👀 Pay attention, because this isn't just any ordinary dip
follow me so you don't miss anything that's coming up
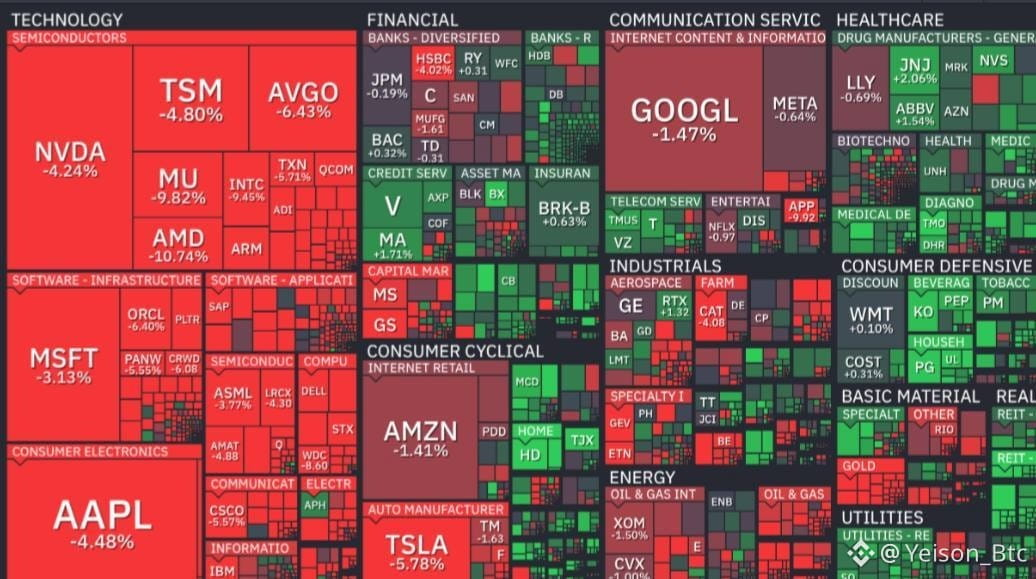
US markets have reportedly lost nearly $2 trillion in value in just two hours 💀
🔥 Major wipeout
🔥 Huge scare
🔥 Tremendous volatility
And all this is happening while geopolitical tensions continue to rise and the market tries to figure out what's next 🌍⚠️
🧠 What many are missing is that when such absurd amounts of money disappear in such a short time, it's usually not the small investor causing the movement
🐳 It's funds
🐳 Algorithms
🐳 Leveraged positions
🐳 Risk managers reducing exposure
And when the cascade liquidations begin, the snowball effect does the rest 😅
📉 Stocks are dropping
📉 Indices are falling
📉 Fear is escalating
📉 And the media starts amplifying the panic
Meanwhile, #BTC continues to fight its own battle within the liquidity zones we've been monitoring for days 👀
🔥 The curious thing is that major floors often emerge precisely when fear is at its peak
When no one wants to buy
When everyone believes something worse is coming
And when #Twitter is filled with apocalyptic messages 😅
🐳 For now, the market is in survival mode and any headline can trigger violent moves in either direction
👀 The real question is:
💀 Are we witnessing just a simple liquidity shake?
🔥 Or is a much larger correction in traditional markets just beginning? 🚀📉🐳💰😳
{spot}(BTCUSDT)
{future}(AMDUSDT)
{future}(METAUSDT)
🚨💥 $2 TRILLION WIPED OUT IN JUST 2 HOURS... NO JOKE, WHAT A SHAKEUP 😳📉🔥
👀 Pay attention, because this isn't just any ordinary dip
follow me so you don't miss anything that's coming up
US markets have reportedly lost nearly $2 trillion in value in just two hours 💀
🔥 Major wipeout
🔥 Huge scare
🔥 Tremendous volatility
And all this is happening while geopolitical tensions continue to rise and the market tries to figure out what's next 🌍⚠️
🧠 What many are missing is that when such absurd amounts of money disappear in such a short time, it's usually not the small investor causing the movement
🐳 It's funds
🐳 Algorithms
🐳 Leveraged positions
🐳 Risk managers reducing exposure
And when the cascade liquidations begin, the snowball effect does the rest 😅
📉 Stocks are dropping
📉 Indices are falling
📉 Fear is escalating
📉 And the media starts amplifying the panic
Meanwhile, #BTC continues to fight its own battle within the liquidity zones we've been monitoring for days 👀
🔥 The curious thing is that major floors often emerge precisely when fear is at its peak
When no one wants to buy
When everyone believes something worse is coming
And when #Twitter is filled with apocalyptic messages 😅
🐳 For now, the market is in survival mode and any headline can trigger violent moves in either direction
👀 The real question is:
💀 Are we witnessing just a simple liquidity shake?
🔥 Or is a much larger correction in traditional markets just beginning? 🚀📉🐳💰😳
6
5
3.6k
Caution:What #putin post on its #Twitter ...
I am not able to digest this..what you think.
please comment below 👇
like and follow for more informative content.
#news #ukraine #cryptouniverseofficial $BTC $ETH $BNB
Caution:What #putin post on its #Twitter ...
I am not able to digest this..what you think.
please comment below 👇
like and follow for more informative content.
#news #ukraine #cryptouniverseofficial $BTC $ETH $BNB
I am not able to digest this..what you think.
please comment below 👇
like and follow for more informative content.
#news #ukraine #cryptouniverseofficial $BTC $ETH $BNB

76

🚀 The $44 Billion Question: What Did Elon Musk Give Up to Buy Twitter?
When Elon Musk acquired Twitter (now X) for $44 billion, he wasn’t just making a purchase he was making a massive capital allocation decision. Looking back today, the opportunity cost of that decision is becoming one of the most fascinating financial comparisons in recent history.
If that same $44 billion had been placed into gold instead, it would reportedly be worth around $114.4 billion today. A similar investment in silver would have grown even more dramatically to approximately $158.2 billion. On the opposite end of the spectrum, parking the funds in the Turkish Lira would have been disastrous, shrinking the value to roughly $17.7 billion due to the currency’s steep depreciation over the period.
The most eye-opening comparison, however, is SpaceX. Based on recent private-market valuations, a hypothetical $44 billion investment into SpaceX could now be worth an estimated $675–728 billion. That means the capital used to purchase Twitter may have had the potential to multiply into one of the largest wealth-creation events in modern business history if deployed into the company Musk was already building.
Of course, opportunity cost calculations look obvious in hindsight. The Twitter acquisition was never purely a financial investment it involved influence, communication infrastructure, AI ambitions, payments, and Musk’s broader vision for transforming X into an “everything app.” Whether that vision ultimately creates value that rivals what could have been achieved elsewhere remains one of the biggest unanswered questions in technology and business.
The numbers themselves are remarkable. A $44 billion decision can be measured not only by what was purchased, but also by what was potentially sacrificed. And in this case, the gap between those outcomes reaches hundreds of billions of dollars, highlighting how a single strategic choice can reshape the trajectory of wealth creation.$SPACE
{future}(SPACEUSDT)
$SPCXB
{spot}(SPCXBUSDT)
#ElonMusk #SpaceX #X #Twitter #TradebStocks
🚀 The $44 Billion Question: What Did Elon Musk Give Up to Buy Twitter?
When Elon Musk acquired Twitter (now X) for $44 billion, he wasn’t just making a purchase he was making a massive capital allocation decision. Looking back today, the opportunity cost of that decision is becoming one of the most fascinating financial comparisons in recent history.
If that same $44 billion had been placed into gold instead, it would reportedly be worth around $114.4 billion today. A similar investment in silver would have grown even more dramatically to approximately $158.2 billion. On the opposite end of the spectrum, parking the funds in the Turkish Lira would have been disastrous, shrinking the value to roughly $17.7 billion due to the currency’s steep depreciation over the period.
The most eye-opening comparison, however, is SpaceX. Based on recent private-market valuations, a hypothetical $44 billion investment into SpaceX could now be worth an estimated $675–728 billion. That means the capital used to purchase Twitter may have had the potential to multiply into one of the largest wealth-creation events in modern business history if deployed into the company Musk was already building.
Of course, opportunity cost calculations look obvious in hindsight. The Twitter acquisition was never purely a financial investment it involved influence, communication infrastructure, AI ambitions, payments, and Musk’s broader vision for transforming X into an “everything app.” Whether that vision ultimately creates value that rivals what could have been achieved elsewhere remains one of the biggest unanswered questions in technology and business.
The numbers themselves are remarkable. A $44 billion decision can be measured not only by what was purchased, but also by what was potentially sacrificed. And in this case, the gap between those outcomes reaches hundreds of billions of dollars, highlighting how a single strategic choice can reshape the trajectory of wealth creation.$SPACE
$SPCXB
#ElonMusk #SpaceX #X #Twitter #TradebStocks
2
914
·
--
Article
Cardano (ADA) Ecosystem Has Finally Arrived, ADA Community Activist Says#FDUSD Heated debate is raging in the Cardano (ADA) community. While some influencers enjoy all aspects of activity upsurge - including those dangerous for ADA holders - the opposite side accuses them of being fascinated by "drama."
Launches, rugs, drama: Cardano (ADA) ecosystem has arrived, community says
Pseudonymous Cardano (ADA) enthusiast who goes by @cardano_whale on Twitter admitted that he is "loving the chaos" the Cardano (ADA) ecosystem is going through these days. He noticed a number of unusual events that resulted in solid "FUD and hype" for the blockchain and dApps using it for their operations.
Even though I don’t have a huge desire to participate in it as a twitter personality, kind of loving the chaos in Cardano these days. Launches, rugs, fights and drama, people doing 10x, people getting rekt, Catalyst 40% gems and 60% garbage, hype, FUD. This ecosystem has arrived— ADA whale (@cardano_whale) August 3, 2023
In recent weeks, Cardano (ADA) and its supporters witnessed launches, "rugpull" events, "drama", 1, 000% rallies of tokens and painful liquidations. Also, Project Catalyst, the largest community-driven incubation initaitive in Web3, came under fire due to shady nominees.
At the same time, these events, though painful and dangerous for the community, are signals that the Cardano (ADA) ecosystem has "arrived," @cardano_whale concluded.
Another Cardano (ADA) enthusiast, who goes by @Cinnamon__Bunnn, also pointed out that this is how a blockchain ecosystem should look like in its infancy. However, they were not happy about the manner in which some people "pride themselves on staying out of drama."
As covered by U.Today previously, in June 2023, Cardano (ADA) inventor Charles Hoskinson slammed critics who accused him of spending "others' " money.
A wave of criticism raged when Hoskinson shared the details of his ocean expedition.
Project Catalyst under criticism, here's why
Another scandal involved Project Catalyst, a large-scale Cardano (ADA) community incubator. Some enthusiasts found very suspicious applicants who were seeking too much funding.
Besides that, the previously unknown RFLXT team claimed that it was cofounded by Charles Hoskinson himself. In total, they asked for 5.8 million #ADA from Project Catalyst Fund 10.
Last but not least, in Q3, 2023, a series of announcements about "rugpulls" on #Cardano ($ADA ) were spread on #Twitter . Teams of tokens CNETA, CHRY, TEDDY, GRABBIT and POP were accused of malicious manipulations and draining liquidity from their customers.#GOATMoments
Cardano (ADA) Ecosystem Has Finally Arrived, ADA Community Activist Says
#FDUSD Heated debate is raging in the Cardano (ADA) community. While some influencers enjoy all aspects of activity upsurge - including those dangerous for ADA holders - the opposite side accuses them of being fascinated by "drama."
Launches, rugs, drama: Cardano (ADA) ecosystem has arrived, community says
Pseudonymous Cardano (ADA) enthusiast who goes by @cardano_whale on Twitter admitted that he is "loving the chaos" the Cardano (ADA) ecosystem is going through these days. He noticed a number of unusual events that resulted in solid "FUD and hype" for the blockchain and dApps using it for their operations.
Even though I don’t have a huge desire to participate in it as a twitter personality, kind of loving the chaos in Cardano these days. Launches, rugs, fights and drama, people doing 10x, people getting rekt, Catalyst 40% gems and 60% garbage, hype, FUD. This ecosystem has arrived— ADA whale (@cardano_whale) August 3, 2023
In recent weeks, Cardano (ADA) and its supporters witnessed launches, "rugpull" events, "drama", 1, 000% rallies of tokens and painful liquidations. Also, Project Catalyst, the largest community-driven incubation initaitive in Web3, came under fire due to shady nominees.
At the same time, these events, though painful and dangerous for the community, are signals that the Cardano (ADA) ecosystem has "arrived," @cardano_whale concluded.
Another Cardano (ADA) enthusiast, who goes by @Cinnamon__Bunnn, also pointed out that this is how a blockchain ecosystem should look like in its infancy. However, they were not happy about the manner in which some people "pride themselves on staying out of drama."
As covered by U.Today previously, in June 2023, Cardano (ADA) inventor Charles Hoskinson slammed critics who accused him of spending "others' " money.
A wave of criticism raged when Hoskinson shared the details of his ocean expedition.
Project Catalyst under criticism, here's why
Another scandal involved Project Catalyst, a large-scale Cardano (ADA) community incubator. Some enthusiasts found very suspicious applicants who were seeking too much funding.
Besides that, the previously unknown RFLXT team claimed that it was cofounded by Charles Hoskinson himself. In total, they asked for 5.8 million #ADA from Project Catalyst Fund 10.
Last but not least, in Q3, 2023, a series of announcements about "rugpulls" on #Cardano ($ADA ) were spread on #Twitter . Teams of tokens CNETA, CHRY, TEDDY, GRABBIT and POP were accused of malicious manipulations and draining liquidity from their customers.#GOATMoments
8
10.3k
🗣 #ETH "The vibe on Twitter is super negative, but when it comes to tech adoption, we're basically at the best moment in history," says Hayden Adams at ETH Conf.
🗣 #ETH "Cryptos are way more than just a niche product for a few traders. Almost every country is gonna use them; they just won’t realize they’re using them," stated Nemi Dalal from Y Combinator at ETH Conf.
#InvestSmart #Inversiones #ballenas #analysis #Twitter $ETH
🗣 #ETH "Cryptos are way more than just a niche product for a few traders. Almost every country is gonna use them; they just won’t realize they’re using them," stated Nemi Dalal from Y Combinator at ETH Conf.
#InvestSmart #Inversiones #ballenas #analysis #Twitter $ETH


3
273
·
--
Article
"X" Token Rises 2000% After Elon Musk's Twitter Profile Update#MultiChain The price of X token has increased by 2000% in the last 24 hours. This comes after ElonMUSK changed his #Twitter profile picture to an X as part of his rebranding plans. On July 23, the billionaire spoke about the upcoming rebranding of his social network. In a series of tweets, the businessman shared his plans with subscribers, which, among other things, include changing the name of the site to "X".
#cryptocurrency called X is associated with a multi-chain decentralized #NFTS market. The official website mentions that the token is owned and operated by the X community and is managed by the X DAO. It is also reported that the NFT marketplace is now closed.
According to Coingecko data, the price of the X token has jumped over 2000% in the last day, and its price has increased by 1830% in the last 7 days. Token X is trading at an average price of $0.000392 at the time of writing. Trading volume for 24 hours increased by 142,779% and amounted to $133,491.
Image: Coinpedia#GOATMoments
"X" Token Rises 2000% After Elon Musk's Twitter Profile Update
#MultiChain The price of X token has increased by 2000% in the last 24 hours. This comes after ElonMUSK changed his #Twitter profile picture to an X as part of his rebranding plans. On July 23, the billionaire spoke about the upcoming rebranding of his social network. In a series of tweets, the businessman shared his plans with subscribers, which, among other things, include changing the name of the site to "X".
#cryptocurrency called X is associated with a multi-chain decentralized #NFTS market. The official website mentions that the token is owned and operated by the X community and is managed by the X DAO. It is also reported that the NFT marketplace is now closed.
According to Coingecko data, the price of the X token has jumped over 2000% in the last day, and its price has increased by 1830% in the last 7 days. Token X is trading at an average price of $0.000392 at the time of writing. Trading volume for 24 hours increased by 142,779% and amounted to $133,491.
Image: Coinpedia#GOATMoments
1
18
12.1k
·
--
Article
4,096 US Commercial Banks May Work With Ripple as XRP Wins#GOATMoments Ripple legal officer expects US banks to adopt Ripple’s cross-border payment solution following the court ruling that XRP is not a security.
According to a Ripple executive, the recent landmark ruling declaring XRP a non-security paves the way for US banks and financial institutions to adopt Ripple’s solution for cross-border payments.
In an interview with CNBC, Stuart Alderoty, Ripple’s Chief Legal Officer, expressed confidence that American banks would return to Ripple’s On-Demand Liquidity (ODL) product.
Specifically, when asked if the US court ruling would lead to increased interest from banks, Alderoty replied, “I think the answer to that is yes.”
According to the lawyer, Ripple plans to initiate discussions with US-based financial institutions in the next quarter of the year regarding adopting its ODL solution, which leverages #XRP for efficient money transfers.
The Ruling is Comfort to Banks
Furthermore, Alderoty emphasized that the court decision would provide comfort for financial institutions to engage in conversations about the challenges they face in cross-border value transfers, particularly regarding high fees.
The legal officer stated, “Hopefully, this quarter will generate a lot of conversations in the United States with customers, and hopefully, some of those conversations will actually turn into a real business.”
Alderoty also revealed that while most Ripple employees are from the United States, its primary business and revenue are from abroad.
Recall that the judge’s ruling also supported an argument by the Securities and Exchange Commission (SEC) that Ripple’s sale of $XRP to institutional investors is considered a security offering.
Regarding the impact of this component on Ripple’s business, Alderoty clarified that since most of its customers are abroad, it would remain largely unaffected. He mentioned that Ripple would carefully analyze the judge’s decision, assess market needs, and ensure compliance with the judge’s findings concerning institutions.
Over 4K US Banks to Use Ripple Solution
Meanwhile, in a game-changing development, #Twitter user WallStreetBulls highlighted that a staggering 4,096 commercial banks and 576 savings and #loan associations, holding an astonishing $23.7 trillion in combined assets, are set to revolutionize cross-border settlements via Ripple ODL.
However, it is important to note that this is merely a projection from Wall Street Bulls, considering the number of commercial banks in the United States. The extent to which any US bank will leverage ODL remains to be seen.#Binanceturns6
4,096 US Commercial Banks May Work With Ripple as XRP Wins
#GOATMoments Ripple legal officer expects US banks to adopt Ripple’s cross-border payment solution following the court ruling that XRP is not a security.
According to a Ripple executive, the recent landmark ruling declaring XRP a non-security paves the way for US banks and financial institutions to adopt Ripple’s solution for cross-border payments.
In an interview with CNBC, Stuart Alderoty, Ripple’s Chief Legal Officer, expressed confidence that American banks would return to Ripple’s On-Demand Liquidity (ODL) product.
Specifically, when asked if the US court ruling would lead to increased interest from banks, Alderoty replied, “I think the answer to that is yes.”
According to the lawyer, Ripple plans to initiate discussions with US-based financial institutions in the next quarter of the year regarding adopting its ODL solution, which leverages #XRP for efficient money transfers.
The Ruling is Comfort to Banks
Furthermore, Alderoty emphasized that the court decision would provide comfort for financial institutions to engage in conversations about the challenges they face in cross-border value transfers, particularly regarding high fees.
The legal officer stated, “Hopefully, this quarter will generate a lot of conversations in the United States with customers, and hopefully, some of those conversations will actually turn into a real business.”
Alderoty also revealed that while most Ripple employees are from the United States, its primary business and revenue are from abroad.
Recall that the judge’s ruling also supported an argument by the Securities and Exchange Commission (SEC) that Ripple’s sale of $XRP to institutional investors is considered a security offering.
Regarding the impact of this component on Ripple’s business, Alderoty clarified that since most of its customers are abroad, it would remain largely unaffected. He mentioned that Ripple would carefully analyze the judge’s decision, assess market needs, and ensure compliance with the judge’s findings concerning institutions.
Over 4K US Banks to Use Ripple Solution
Meanwhile, in a game-changing development, #Twitter user WallStreetBulls highlighted that a staggering 4,096 commercial banks and 576 savings and #loan associations, holding an astonishing $23.7 trillion in combined assets, are set to revolutionize cross-border settlements via Ripple ODL.
However, it is important to note that this is merely a projection from Wall Street Bulls, considering the number of commercial banks in the United States. The extent to which any US bank will leverage ODL remains to be seen.#Binanceturns6
23
15.9k
⚡️ NEW: Elon Musk has agreed to pay $1.5 million to settle SEC allegations that he failed to properly disclose his growing Twitter stake in 2022, without admitting to the allegations. #ElonMusk #SEC #Allegations #Twitter
{spot}(BTCUSDT)
{spot}(ETHUSDT)
⚡️ NEW: Elon Musk has agreed to pay $1.5 million to settle SEC allegations that he failed to properly disclose his growing Twitter stake in 2022, without admitting to the allegations. #ElonMusk #SEC #Allegations #Twitter
1
1
141
Article
X CRYPTO BAN MISTAKE LATEST TAKE!X (TWITTER) LIFTS CRYPTO AD BAN: THE MARKETING FLOODGATES OPEN
In a seismic policy shift, X (formerly Twitter) has removed cryptocurrency from its prohibited industries list for paid promotions.
After 9 months of blanket prohibition (since June 2024), crypto is back. And this changes everything for project marketing.
Here's what just happened 👇
📜 THE POLICY CHANGE (March 2, 2026)
X's updated advertising policy removes:
- Cryptocurrency (previously banned)
- Gambling (also unbanned)
- Financial products category entirely
New requirement: "Paid Partnership" label mandatory for all compensated promotions.
Influencers must disclose relationships. Brands get legal marketing path. Transparency is the new rule.
WHY THIS MATTERS
X has 500M+ users. It's the heartbeat of crypto Twitter (CT).
For 9 months, projects relied on:
- Organic posts (limited reach)
- Shadow marketing (risky)
- Off-platform ads (expensive)
Now? Direct, scalable, legal promotion.
THE WINNERS & LOSERS
WINNERS:
- Quality projects with real products (can now scale marketing)
- Influencers with engaged audiences (monetization path)
- X itself (ad revenue from booming crypto sector)
LOSERS:
- Scam projects (disclosure requirements expose paid shills)
- Anonymous influencers (can't hide paid promotions)
- Projects relying on "organic" stealth marketing
THE STRATEGY SHIFT
Benjamin Cowen noted: "This changes crypto influencer business models."
Rune's concern: "Platform now banning users promoting cryptos whether disclosed or not" — suggesting strict enforcement coming.
My take: The wild west era of crypto marketing is ending. Professional, compliant, transparent marketing wins.
Projects need:
- Clear value propositions
- Proper legal structures
- Audited contracts
- Real communities (not bought followers)
IMMEDIATE IMPACT
Expect:
- Influencer marketing costs to spike (demand surge)
- Quality projects to separate from scams
- X ad revenue to jump
- More retail FOMO as crypto content floods feeds
I'm preparing marketing budgets for this new era. The projects that move fast and compliant win.
Who's ready to scale on X?
$XRP $ETH $SOL
#X #Twitter #Crypto #USCitizensMiddleEastEvacuation #XCryptoBanMistake
X CRYPTO BAN MISTAKE LATEST TAKE!
X (TWITTER) LIFTS CRYPTO AD BAN: THE MARKETING FLOODGATES OPEN
In a seismic policy shift, X (formerly Twitter) has removed cryptocurrency from its prohibited industries list for paid promotions.
After 9 months of blanket prohibition (since June 2024), crypto is back. And this changes everything for project marketing.
Here's what just happened 👇
📜 THE POLICY CHANGE (March 2, 2026)
X's updated advertising policy removes:
- Cryptocurrency (previously banned)
- Gambling (also unbanned)
- Financial products category entirely
New requirement: "Paid Partnership" label mandatory for all compensated promotions.
Influencers must disclose relationships. Brands get legal marketing path. Transparency is the new rule.
WHY THIS MATTERS
X has 500M+ users. It's the heartbeat of crypto Twitter (CT).
For 9 months, projects relied on:
- Organic posts (limited reach)
- Shadow marketing (risky)
- Off-platform ads (expensive)
Now? Direct, scalable, legal promotion.
THE WINNERS & LOSERS
WINNERS:
- Quality projects with real products (can now scale marketing)
- Influencers with engaged audiences (monetization path)
- X itself (ad revenue from booming crypto sector)
LOSERS:
- Scam projects (disclosure requirements expose paid shills)
- Anonymous influencers (can't hide paid promotions)
- Projects relying on "organic" stealth marketing
THE STRATEGY SHIFT
Benjamin Cowen noted: "This changes crypto influencer business models."
Rune's concern: "Platform now banning users promoting cryptos whether disclosed or not" — suggesting strict enforcement coming.
My take: The wild west era of crypto marketing is ending. Professional, compliant, transparent marketing wins.
Projects need:
- Clear value propositions
- Proper legal structures
- Audited contracts
- Real communities (not bought followers)
IMMEDIATE IMPACT
Expect:
- Influencer marketing costs to spike (demand surge)
- Quality projects to separate from scams
- X ad revenue to jump
- More retail FOMO as crypto content floods feeds
I'm preparing marketing budgets for this new era. The projects that move fast and compliant win.
Who's ready to scale on X?
$XRP $ETH $SOL
#X #Twitter #Crypto #USCitizensMiddleEastEvacuation #XCryptoBanMistake
3
281
🇺🇸📝 U.S. - Trade balance (April - preliminary) = -82.400 billion dollars (forecast -86.700 billion dollars / forecast -87.450 billion dollars)
👮 Texas announces the creation of the "Texas Bitcoin Strategic Reserve Advisory Committee."
Texas is also on the lookout for a qualified firm to custody its $BTC for when they scoop up more.
🕵️ 500,000,000 $USDT (499,529,166 USD) transferred from Binance to Tether Treasury.
🗣 The CEO of #HYPE, Ice Jeff Sprecher, stated at a Bernstein conference that Hyperliquid is "bigger than Nasdaq," despite having only 11 employees. He mentioned meeting with the team several times and praised them as "very, very smart people."
⚠️ The Sui network suffers outages for two consecutive days.
The official X account of Sui announced that the mainnet is experiencing network issues, causing temporary disruptions in network activity. According to Sui's status, the Sui mainnet has faced a significant downtime for two consecutive days due to settlement issues on the mainnet. The blockchain explorer indicates that no new blocks have been produced for over an hour.
🕵️♂️ #HYPE #TWT Trust Wallet has integrated the futures and prediction markets HIP-4 of Hyperliquid.
#ballenas #EEUU #CEO #stock #Twitter $HYPE $SUI
2
194
🗽 It is not expected that the Crypto Clarity Act will be approved this year, despite the fact that President $TRUMP met today with several senators to push the bill. #regulacion
🗽 #CRO Citadel Securities invests 400 million dollars in Crypto.c0m with a valuation of 20 000 million dollars.
{web3_wallet_create}(CT_501DvjMYMVeXgKxaixGKpzQThLoG98nc7HSU7eanzsdCboA)
🗽 $CRO Crypto.c0m announces a 400 million dollar investment by Citadel Securities: BBG
🙅 X has detected 1.5 million copied posts and has removed almost 4,000 accounts for using «engagement bait» as part of its latest creator revenue program.
🗣 Anton Bukov, cofounder of $1INCH , says he was fired in November 2025 and that he is going to launch a new project, Second Tier.
🏦 #BTC Adam Back, CEO of Bitcoin Standard Treasury Co. ($BSTR), will speak at the Bitcoin Treasuries Conference this September.
It manages 30 000 $BTC worth 1.9 billion dollars.
#ballenas #Twitter
🗽 It is not expected that the Crypto Clarity Act will be approved this year, despite the fact that President $TRUMP met today with several senators to push the bill. #regulacion
🗽 #CRO Citadel Securities invests 400 million dollars in Crypto.c0m with a valuation of 20 000 million dollars.
🗽 $CRO Crypto.c0m announces a 400 million dollar investment by Citadel Securities: BBG
🙅 X has detected 1.5 million copied posts and has removed almost 4,000 accounts for using «engagement bait» as part of its latest creator revenue program.
🗣 Anton Bukov, cofounder of $1INCH , says he was fired in November 2025 and that he is going to launch a new project, Second Tier.
🏦 #BTC Adam Back, CEO of Bitcoin Standard Treasury Co. ($BSTR), will speak at the Bitcoin Treasuries Conference this September.
It manages 30 000 $BTC worth 1.9 billion dollars.
#ballenas #Twitter
3
854
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#ZcashETFPostsFirstWeeklyOutflow$93.6M
45,395 views
139 Discussing
2
#GreekPoliceBustCryptoScamRingArrest17
116,161 views
855 Discussing
3
#BitcoinRejectedAt$87K
140,427 views
196 Discussing
4
#FedOctoberRateHikeOddsFallTo17%
143,803 views
1,098 Discussing
5
#NvidiaHitsRecordHighUp2.4%
104,743 views
783 Discussing
6
#CanaryFilesAmendedS1ForPEPEETF
26,213 views
545 Discussing
7
#USRussiaUkraineTalksReportedlyIncludeLukoilOilDeal
38,800 views
518 Discussing
8
#BitcoinParesGainsAfterRallyTo$86.5K
51,808 views
169 Discussing
9
#CerebrasSinksNearly20%OnReportNvidiaToPowerOpenAI
130,362 views
1,161 Discussing
10
#SECProposesCryptoCustodyRules
180,050 views
1,443 Discussing