

Kryptos Tax Re-poster
33 貼文
Kryptos Tax Re-poster
舉報
封鎖用戶
Crypto tax reports in minutes, not hours. 5,000+ integrations. 35+ jurisdictions. Powered by @KryptosConnect | https://t.co/OhWfPUX2kA
0 關注
1 粉絲
0 點讚數
貼文
全部
影片
查看翻譯
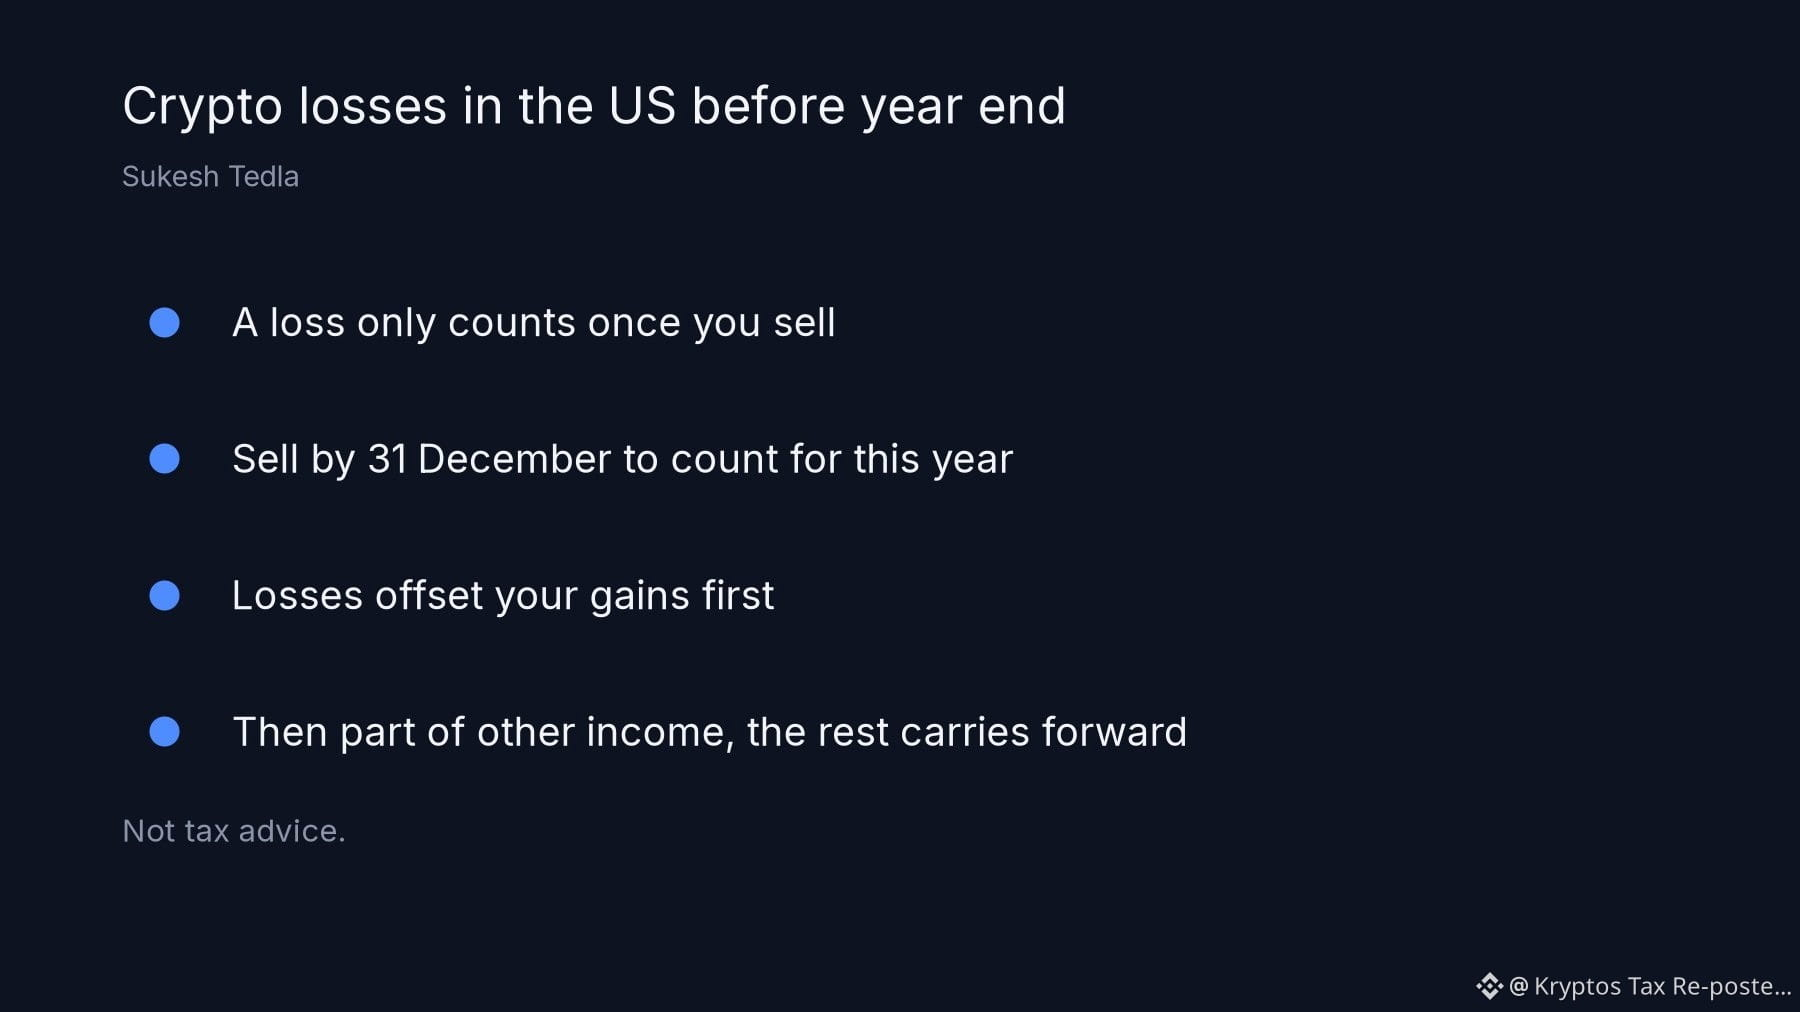
With roughly six weeks remaining in 2026, it is worth reviewing whether any of your digital assets are currently valued below their original purchase price.
For taxpayers in the US, a cryptocurrency loss is recognized only after you complete a sale, which must occur by Dec 31 to apply to this calendar year. When filing, these losses first counterbalance your capital gains. If you have excess losses remaining, they can offset up to $3,000 of other income, while any further unused balance carries forward into subsequent tax years.
Not tax advice.
With roughly six weeks remaining in 2026, it is worth reviewing whether any of your digital assets are currently valued below their original purchase price.
For taxpayers in the US, a cryptocurrency loss is recognized only after you complete a sale, which must occur by Dec 31 to apply to this calendar year. When filing, these losses first counterbalance your capital gains. If you have excess losses remaining, they can offset up to $3,000 of other income, while any further unused balance carries forward into subsequent tax years.
Not tax advice.
For taxpayers in the US, a cryptocurrency loss is recognized only after you complete a sale, which must occur by Dec 31 to apply to this calendar year. When filing, these losses first counterbalance your capital gains. If you have excess losses remaining, they can offset up to $3,000 of other income, while any further unused balance carries forward into subsequent tax years.
Not tax advice.
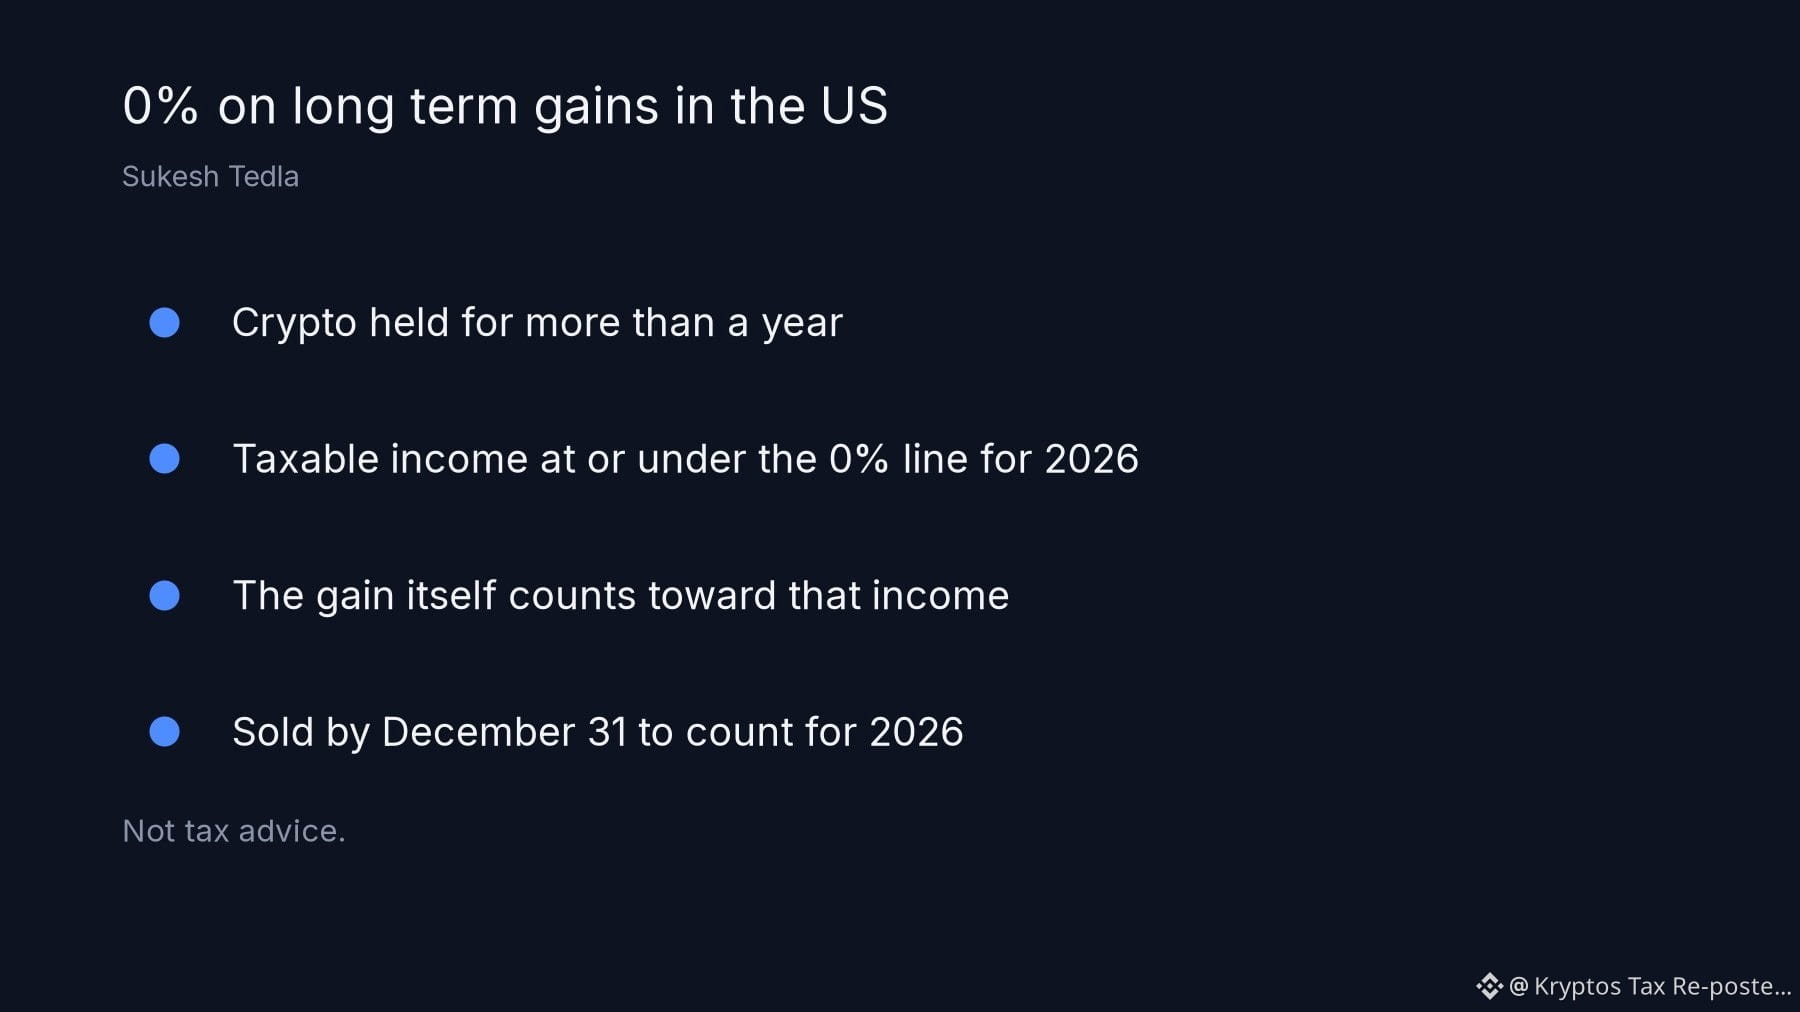
持有超過十二個月的加密貨幣投資,符合美國長期資本利得稅零稅率的條件,前提是您 2026 年的應稅收入不超過特定限額。對於單身納稅人,限額爲 49,450 美元;對於聯合申報的已婚夫婦,限額爲 98,900 美元。請注意,任何已實現的收益都會直接計入您的總收入。
爲了利用這項規定,一些投資者會選擇在 12 月 31 日之前出售資產,以零稅率鎖定收益,然後再買回資產,從而提高成本基礎。
您今年的收入會低於這些門檻嗎?
本文不構成稅務建議。
持有超過十二個月的加密貨幣投資,符合美國長期資本利得稅零稅率的條件,前提是您 2026 年的應稅收入不超過特定限額。對於單身納稅人,限額爲 49,450 美元;對於聯合申報的已婚夫婦,限額爲 98,900 美元。請注意,任何已實現的收益都會直接計入您的總收入。
爲了利用這項規定,一些投資者會選擇在 12 月 31 日之前出售資產,以零稅率鎖定收益,然後再買回資產,從而提高成本基礎。
您今年的收入會低於這些門檻嗎?
本文不構成稅務建議。
爲了利用這項規定,一些投資者會選擇在 12 月 31 日之前出售資產,以零稅率鎖定收益,然後再買回資產,從而提高成本基礎。
您今年的收入會低於這些門檻嗎?
本文不構成稅務建議。
61
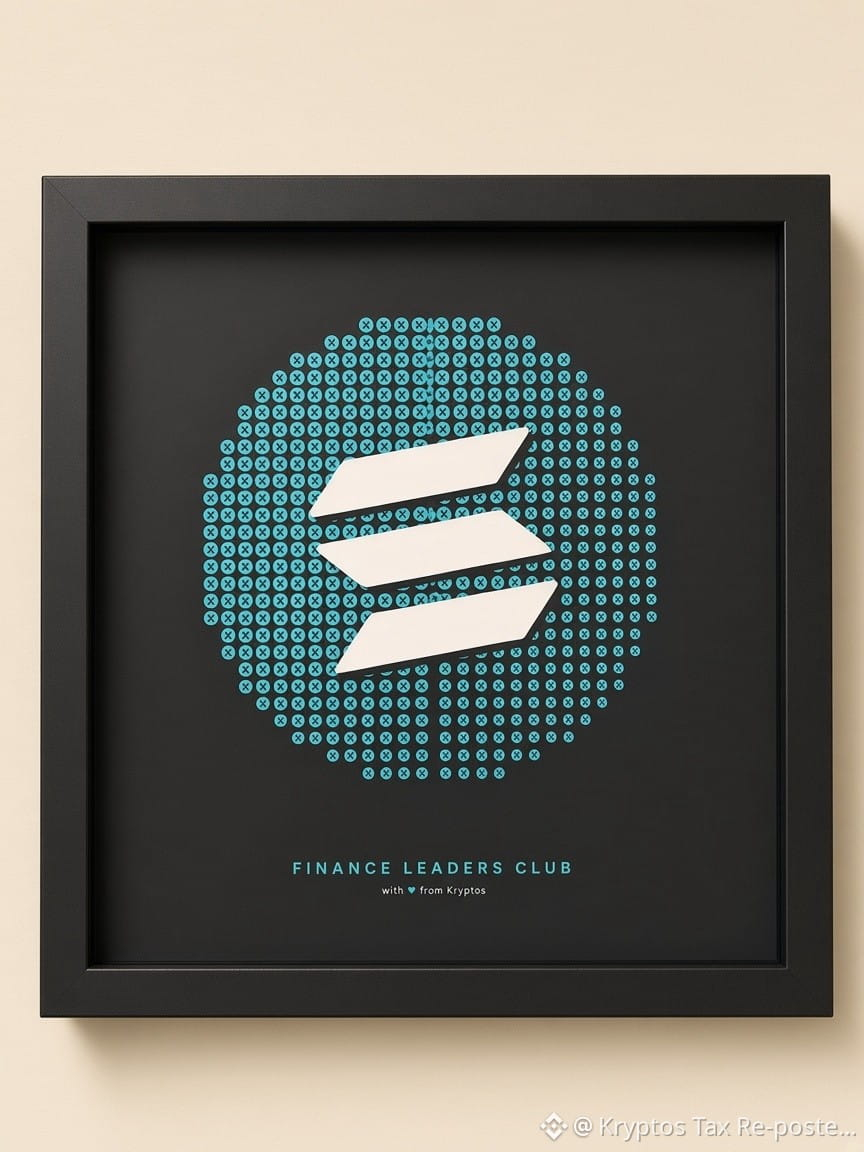
本週日,在倫敦參加我們金融領袖俱樂部晚宴的每位賓客,都會獲贈一幅裝裱好的 @solana 標誌帶回家。該標誌由微型 Kryptos 字母 K 組成。
由於名額有限,所有報名申請都需經過審覈。
你可以在此申請參加:https://luma.com/6lo0x0u1
本週日,在倫敦參加我們金融領袖俱樂部晚宴的每位賓客,都會獲贈一幅裝裱好的 @solana 標誌帶回家。該標誌由微型 Kryptos 字母 K 組成。
由於名額有限,所有報名申請都需經過審覈。
你可以在此申請參加:https://luma.com/6lo0x0u1
由於名額有限,所有報名申請都需經過審覈。
你可以在此申請參加:https://luma.com/6lo0x0u1
60
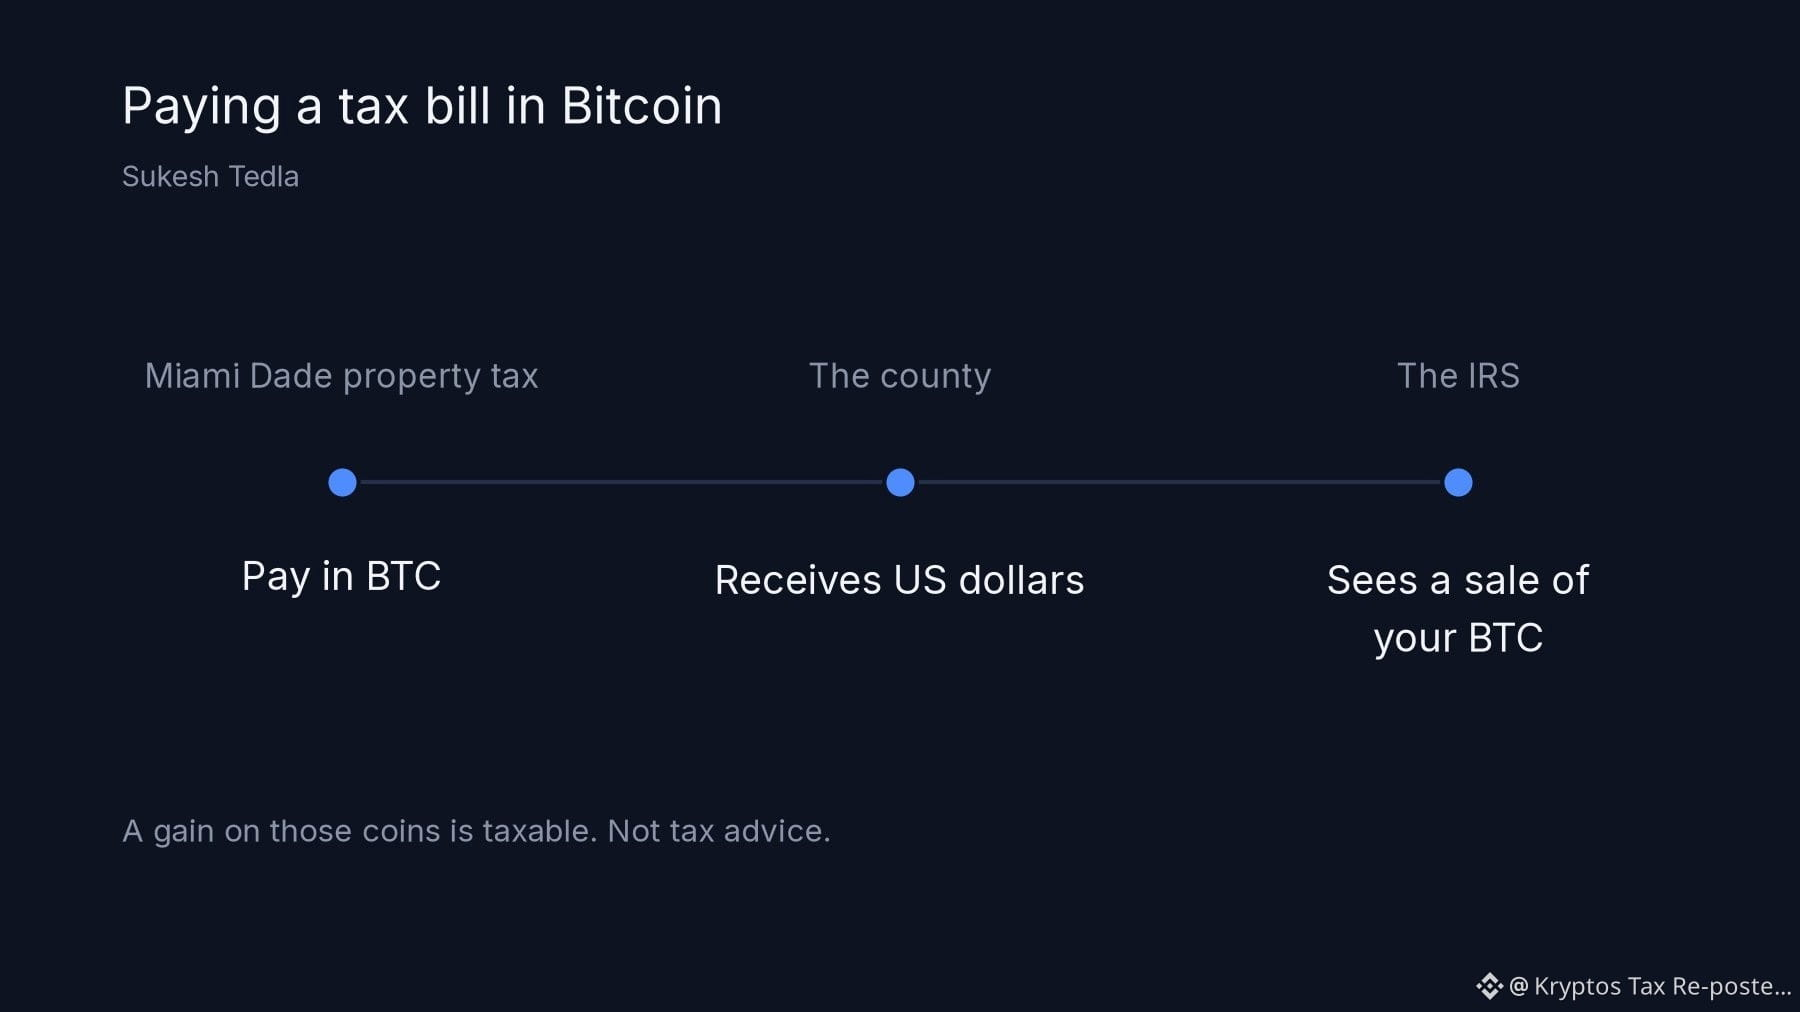
邁阿密-戴德縣的房產業主現在可以選擇使用比特幣繳納地方稅款,不過當地政府仍以美元收取款項。
從納稅人的角度來看,美國國稅局將用比特幣繳稅視同出售加密貨幣。因此,如果這些代幣的價值高於你最初購買時的價格,就會產生應稅資本利得。
你會考慮用比特幣繳納稅款嗎?
以上並非稅務建議。
邁阿密-戴德縣的房產業主現在可以選擇使用比特幣繳納地方稅款,不過當地政府仍以美元收取款項。
從納稅人的角度來看,美國國稅局將用比特幣繳稅視同出售加密貨幣。因此,如果這些代幣的價值高於你最初購買時的價格,就會產生應稅資本利得。
你會考慮用比特幣繳納稅款嗎?
以上並非稅務建議。
從納稅人的角度來看,美國國稅局將用比特幣繳稅視同出售加密貨幣。因此,如果這些代幣的價值高於你最初購買時的價格,就會產生應稅資本利得。
你會考慮用比特幣繳納稅款嗎?
以上並非稅務建議。
63
你已經計算出今年的總收益了嗎?
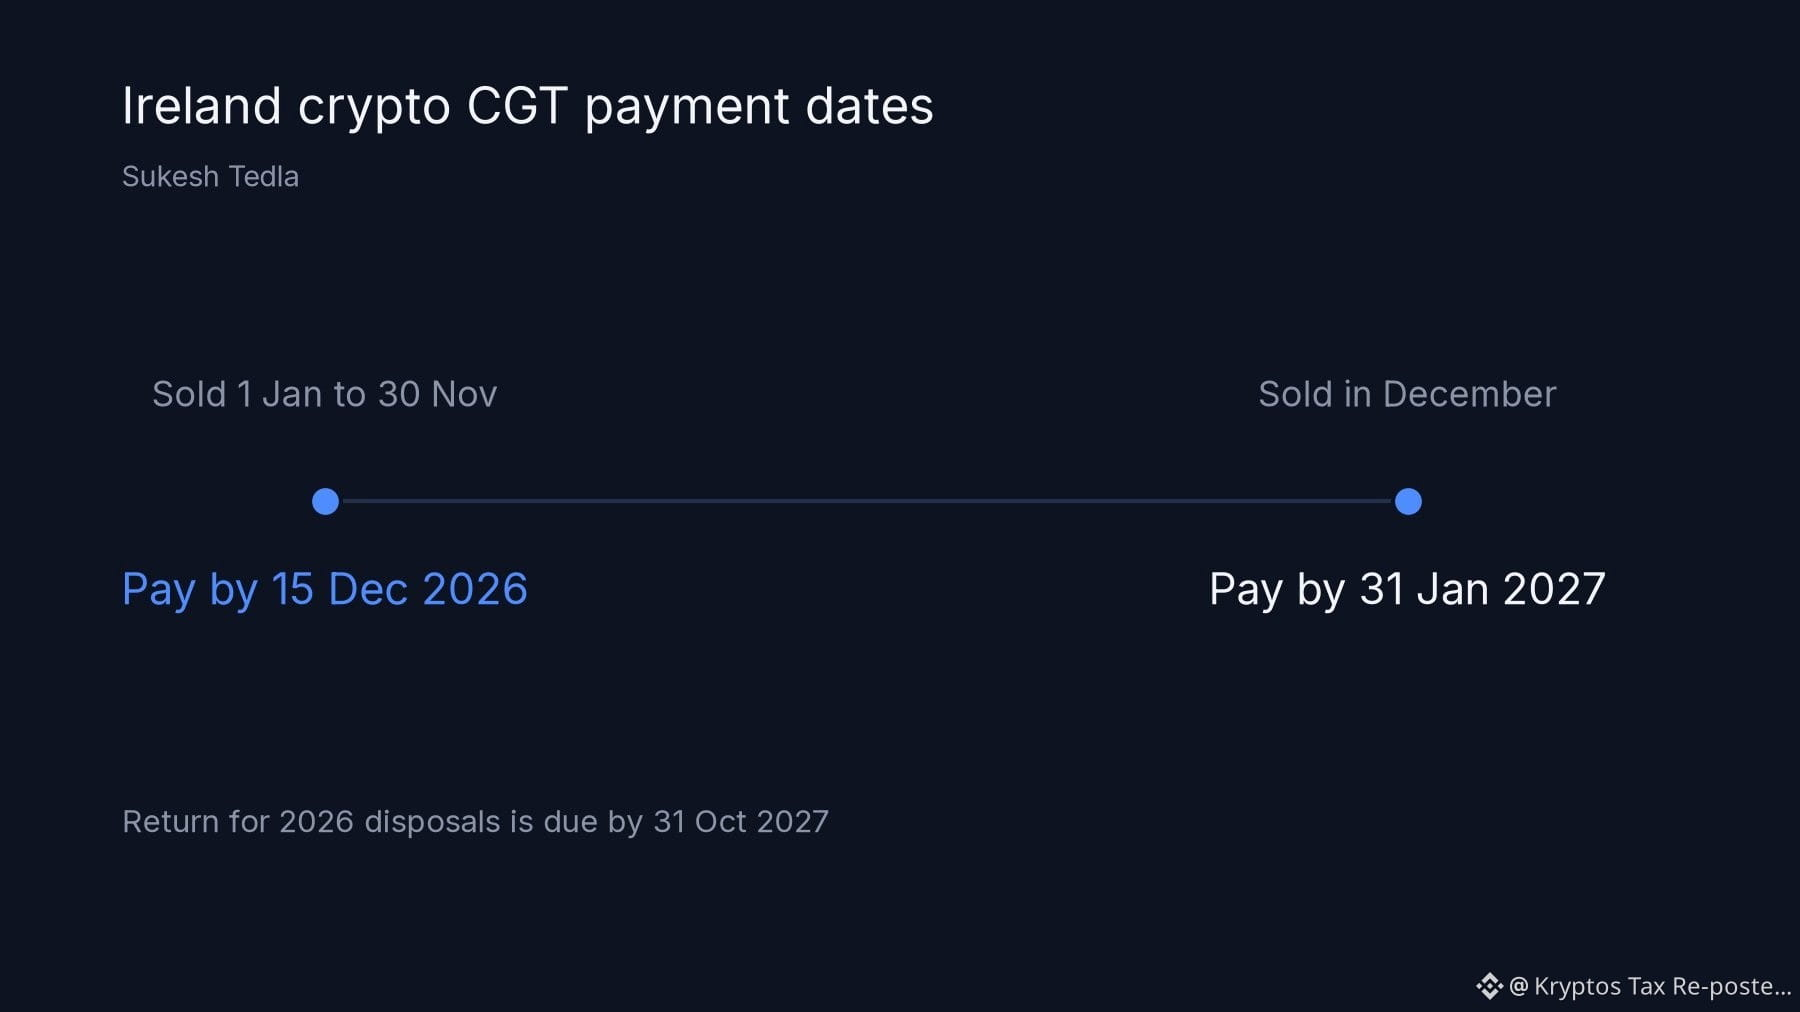
在愛爾蘭處理加密貨幣交易時,1月1日至11月30日期間處置資產所產生的資本利得稅(CGT),須於12月15日前繳納。而12月期間進行的銷售所產生的稅款,則須於1月31日前繳納。
以上內容不構成稅務建議。
你已經計算出今年的總收益了嗎?
在愛爾蘭處理加密貨幣交易時,1月1日至11月30日期間處置資產所產生的資本利得稅(CGT),須於12月15日前繳納。而12月期間進行的銷售所產生的稅款,則須於1月31日前繳納。
以上內容不構成稅務建議。
在愛爾蘭處理加密貨幣交易時,1月1日至11月30日期間處置資產所產生的資本利得稅(CGT),須於12月15日前繳納。而12月期間進行的銷售所產生的稅款,則須於1月31日前繳納。
以上內容不構成稅務建議。
62
香港已正式通過有關加密貨幣稅務申報的新法例。自 2027 年起,在香港營運的加密貨幣平台將開始向用戶收集與稅務相關的資料。到 2028 年,當地稅務機關將與合作國家交換這些資料。現在正是核實加密貨幣交易所的紀錄是否與你在稅務申報中正式提交的資料相符的理想時機。各司法管轄區的規定有所不同。本內容不構成稅務建議。
香港已正式通過有關加密貨幣稅務申報的新法例。自 2027 年起,在香港營運的加密貨幣平台將開始向用戶收集與稅務相關的資料。到 2028 年,當地稅務機關將與合作國家交換這些資料。現在正是核實加密貨幣交易所的紀錄是否與你在稅務申報中正式提交的資料相符的理想時機。各司法管轄區的規定有所不同。本內容不構成稅務建議。
129
根據《2027 年預算法案》所列規定,義大利計劃對個人移居海外時尚未實現的利潤徵稅。
這項離境稅針對過去 10 年中有 6 年居住在義大利,且持有價值達 80 萬歐元或以上金融資產的居民;金融資產總額也包括加密貨幣。離境後,截至離境日期累積的收益將須課稅。
對於數位貨幣,應稅收益是以資產在該特定日期的價值,減去最初的買入價格計算。如果你的代幣自 2020 年以來曾經轉過 4 家交易所,要確認最初的買入價格可能會格外困難。
你確定自己能算出確切數字嗎?
本文不構成稅務建議。
根據《2027 年預算法案》所列規定,義大利計劃對個人移居海外時尚未實現的利潤徵稅。
這項離境稅針對過去 10 年中有 6 年居住在義大利,且持有價值達 80 萬歐元或以上金融資產的居民;金融資產總額也包括加密貨幣。離境後,截至離境日期累積的收益將須課稅。
對於數位貨幣,應稅收益是以資產在該特定日期的價值,減去最初的買入價格計算。如果你的代幣自 2020 年以來曾經轉過 4 家交易所,要確認最初的買入價格可能會格外困難。
你確定自己能算出確切數字嗎?
本文不構成稅務建議。
這項離境稅針對過去 10 年中有 6 年居住在義大利,且持有價值達 80 萬歐元或以上金融資產的居民;金融資產總額也包括加密貨幣。離境後,截至離境日期累積的收益將須課稅。
對於數位貨幣,應稅收益是以資產在該特定日期的價值,減去最初的買入價格計算。如果你的代幣自 2020 年以來曾經轉過 4 家交易所,要確認最初的買入價格可能會格外困難。
你確定自己能算出確切數字嗎?
本文不構成稅務建議。
69
在美國境內,直接在自己的數位錢包之間轉移資產通常不成問題,但過程中產生的 Gas 費可能就另當別論了。
根據美國國稅局(IRS)的說法,使用加密貨幣支付轉帳費用屬於必須申報的事件。這些單筆費用看起來可能微不足道,但一整年的交易累積下來,可能會形成一份很長的明細清單。
你有記錄這些費用嗎?
以上內容不構成稅務建議。
在美國境內,直接在自己的數位錢包之間轉移資產通常不成問題,但過程中產生的 Gas 費可能就另當別論了。
根據美國國稅局(IRS)的說法,使用加密貨幣支付轉帳費用屬於必須申報的事件。這些單筆費用看起來可能微不足道,但一整年的交易累積下來,可能會形成一份很長的明細清單。
你有記錄這些費用嗎?
以上內容不構成稅務建議。
根據美國國稅局(IRS)的說法,使用加密貨幣支付轉帳費用屬於必須申報的事件。這些單筆費用看起來可能微不足道,但一整年的交易累積下來,可能會形成一份很長的明細清單。
你有記錄這些費用嗎?
以上內容不構成稅務建議。
68
法國居民的海外加密貨幣交易相關資訊,近期立法進展後,可能很快就會開放給國家稅務機關查閱。10月27日,法國參議院正式批准一項法案,以實施經濟合作暨發展組織(OECD)制定的加密資產資料協議 CARF。該法案目前正送交國民議會,進入下一階段的審議程序。透過這套申報架構,法國計劃於2027年首次交換資料,屆時將針對2026年全年的交易活動進行評估。
法國居民的海外加密貨幣交易相關資訊,近期立法進展後,可能很快就會開放給國家稅務機關查閱。10月27日,法國參議院正式批准一項法案,以實施經濟合作暨發展組織(OECD)制定的加密資產資料協議 CARF。該法案目前正送交國民議會,進入下一階段的審議程序。透過這套申報架構,法國計劃於2027年首次交換資料,屆時將針對2026年全年的交易活動進行評估。
32
準備報稅時,您應該知道,涵蓋您 2026 年銷售的 1099-DA 表格,將是美國券商首次被要求提供成本基礎資訊。儘管有這項新規定,您仍可預期,對於相當大一部分加密貨幣,這個特定欄位將完全空白。
原因在於,申報義務嚴格適用於 2026 年 1 月 1 日或之後購買的數位資產,且這些資產在出售前不得離開原本的券商帳戶。因此,如果您決定出售較早購入的代幣,或交易先前從外部錢包轉入交易所的資產,您的文件很可能不會顯示成本基礎。
準備報稅時,您應該知道,涵蓋您 2026 年銷售的 1099-DA 表格,將是美國券商首次被要求提供成本基礎資訊。儘管有這項新規定,您仍可預期,對於相當大一部分加密貨幣,這個特定欄位將完全空白。
原因在於,申報義務嚴格適用於 2026 年 1 月 1 日或之後購買的數位資產,且這些資產在出售前不得離開原本的券商帳戶。因此,如果您決定出售較早購入的代幣,或交易先前從外部錢包轉入交易所的資產,您的文件很可能不會顯示成本基礎。
原因在於,申報義務嚴格適用於 2026 年 1 月 1 日或之後購買的數位資產,且這些資產在出售前不得離開原本的券商帳戶。因此,如果您決定出售較早購入的代幣,或交易先前從外部錢包轉入交易所的資產,您的文件很可能不會顯示成本基礎。
144
當您收到 2026 年銷售交易的 1099-DA 表格時,這將是美國券商首次被要求提供成本基礎資訊。儘管有這項新規定,您可能會發現,許多加密貨幣的這個欄位仍然是空白的。原因是,券商只有在數位資產於 2026 年 1 月 1 日或之後購買,且在出售前一直存放於同一個券商帳戶時,才有義務申報其成本基礎。如果您持有的是較早購入的加密貨幣,或是從外部錢包轉入的資產,成本基礎欄位可能會直接顯示為「無」。
當您收到 2026 年銷售交易的 1099-DA 表格時,這將是美國券商首次被要求提供成本基礎資訊。儘管有這項新規定,您可能會發現,許多加密貨幣的這個欄位仍然是空白的。原因是,券商只有在數位資產於 2026 年 1 月 1 日或之後購買,且在出售前一直存放於同一個券商帳戶時,才有義務申報其成本基礎。如果您持有的是較早購入的加密貨幣,或是從外部錢包轉入的資產,成本基礎欄位可能會直接顯示為「無」。
101
在報稅季發現收益計算不準確,令人相當懊惱,而這通常只是因為有一筆交易缺少價格資料。您只要在 ChatGPT 中使用 Kryptos,就能輕鬆避免這種困擾。只需詢問系統:「我的哪些交易缺少價格或購買紀錄?」您就會收到一份完整清單,列出直接從您的個人紀錄中整理出的相關項目。
在報稅季發現收益計算不準確,令人相當懊惱,而這通常只是因為有一筆交易缺少價格資料。您只要在 ChatGPT 中使用 Kryptos,就能輕鬆避免這種困擾。只需詢問系統:「我的哪些交易缺少價格或購買紀錄?」您就會收到一份完整清單,列出直接從您的個人紀錄中整理出的相關項目。
29
來看看 Kryptos 平台上的 Bittensor 錢包介面。只要輸入您的公鑰,即可自動同步 TAO 餘額,所有獲得的獎勵也會自動分類並追蹤為收入。
@opentensor @taostats
來看看 Kryptos 平台上的 Bittensor 錢包介面。只要輸入您的公鑰,即可自動同步 TAO 餘額,所有獲得的獎勵也會自動分類並追蹤為收入。
@opentensor @taostats
@opentensor @taostats
73
透過經濟合作暨發展組織(OECD)建立的 CARF 架構,共有 77 個司法管轄區已正式同意透過交換加密貨幣帳戶資訊進行合作。這項全球倡議的時程因地區而異。英國和韓國預計於 2027 年開始參與,美國則將於 2029 年加入。同時,在歐盟和英國各地營運的交易平台,自 2026 年 1 月 1 日起便一直在蒐集這些特定資料。稅務機關預計明年將收到第一批此類報告。
透過經濟合作暨發展組織(OECD)建立的 CARF 架構,共有 77 個司法管轄區已正式同意透過交換加密貨幣帳戶資訊進行合作。這項全球倡議的時程因地區而異。英國和韓國預計於 2027 年開始參與,美國則將於 2029 年加入。同時,在歐盟和英國各地營運的交易平台,自 2026 年 1 月 1 日起便一直在蒐集這些特定資料。稅務機關預計明年將收到第一批此類報告。
66
用戶現在可以直接在 Kryptos 平臺上訪問 Bittensor。輸入您的公鑰後,您將看到每個子網的 alpha 均作爲獨立資產展示。此外,爲了讓您的賬目一目瞭然,所有挖礦收入都與質押獎勵完全分開,後者會按日記錄每個子網的收益。
@opentensor @taostats
用戶現在可以直接在 Kryptos 平臺上訪問 Bittensor。輸入您的公鑰後,您將看到每個子網的 alpha 均作爲獨立資產展示。此外,爲了讓您的賬目一目瞭然,所有挖礦收入都與質押獎勵完全分開,後者會按日記錄每個子網的收益。
@opentensor @taostats
@opentensor @taostats
73
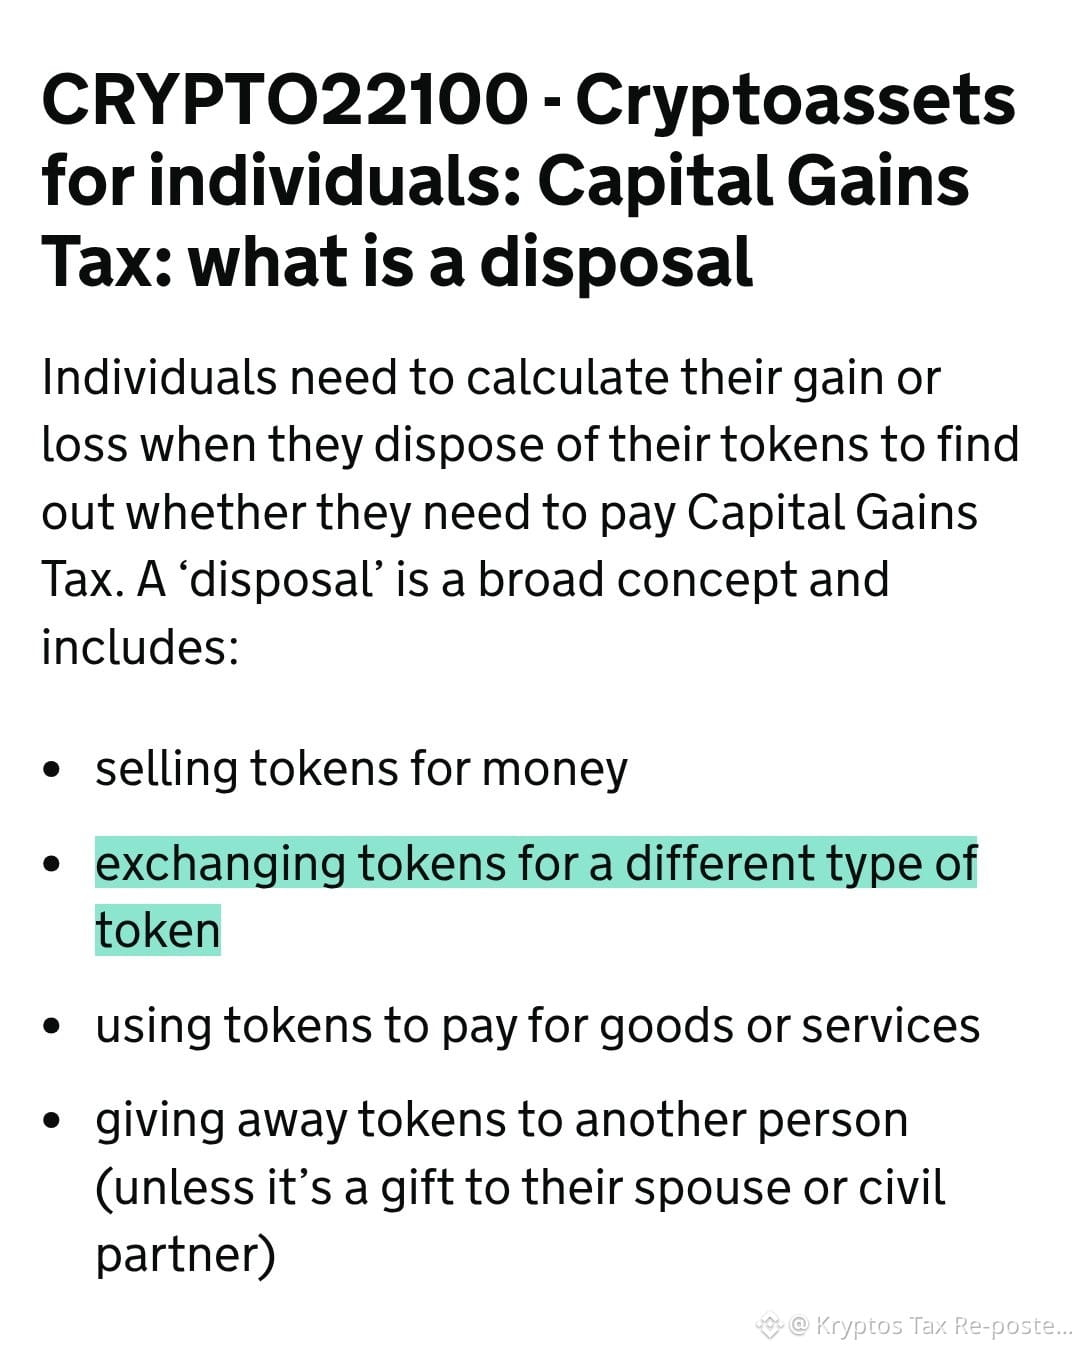
將 USDC 轉換爲 USDT 實際上可能會觸發納稅義務。即使你是按 1 美元換 1 美元進行交易,這條規定依然適用。
包括美國和英國在內的許多司法管轄區,其法律框架都將一種加密貨幣兌換爲另一種加密貨幣視爲資產處置。你需要在納稅文件中記錄這些交易,儘管由此產生的收益或損失通常很小。
爲了簡化這一流程,Kryptos 會自動追蹤你所有個人錢包和交易所中的此類兌換活動。
將 USDC 轉換爲 USDT 實際上可能會觸發納稅義務。即使你是按 1 美元換 1 美元進行交易,這條規定依然適用。
包括美國和英國在內的許多司法管轄區,其法律框架都將一種加密貨幣兌換爲另一種加密貨幣視爲資產處置。你需要在納稅文件中記錄這些交易,儘管由此產生的收益或損失通常很小。
爲了簡化這一流程,Kryptos 會自動追蹤你所有個人錢包和交易所中的此類兌換活動。
包括美國和英國在內的許多司法管轄區,其法律框架都將一種加密貨幣兌換爲另一種加密貨幣視爲資產處置。你需要在納稅文件中記錄這些交易,儘管由此產生的收益或損失通常很小。
爲了簡化這一流程,Kryptos 會自動追蹤你所有個人錢包和交易所中的此類兌換活動。
55
今天舉行的有關韓國加密貨幣稅可能第四次延期的討論,最終未能達成決議。儘管有關部門此前已三次推遲這項政策的實施,但目前仍未作出決定,這意味着現有時間表仍然有效。
除非出臺新的立法調整,否則該稅收框架將於2027年1月1日正式生效。根據即將實施的規定,投資者年度利潤超過250萬韓元的部分將被徵收22%的稅。
此外,針對已持有數字資產的成本基準計算,相關規定也已明確。在計算應稅收益時,現有持倉的成本基準將按以下兩項中的較高者確定:最初購買金額,或這些資產在2026年12月31日的市場價格。
今天舉行的有關韓國加密貨幣稅可能第四次延期的討論,最終未能達成決議。儘管有關部門此前已三次推遲這項政策的實施,但目前仍未作出決定,這意味着現有時間表仍然有效。
除非出臺新的立法調整,否則該稅收框架將於2027年1月1日正式生效。根據即將實施的規定,投資者年度利潤超過250萬韓元的部分將被徵收22%的稅。
此外,針對已持有數字資產的成本基準計算,相關規定也已明確。在計算應稅收益時,現有持倉的成本基準將按以下兩項中的較高者確定:最初購買金額,或這些資產在2026年12月31日的市場價格。
除非出臺新的立法調整,否則該稅收框架將於2027年1月1日正式生效。根據即將實施的規定,投資者年度利潤超過250萬韓元的部分將被徵收22%的稅。
此外,針對已持有數字資產的成本基準計算,相關規定也已明確。在計算應稅收益時,現有持倉的成本基準將按以下兩項中的較高者確定:最初購買金額,或這些資產在2026年12月31日的市場價格。
66
Kryptos 現已正式支援透過 @P2Pvalidator 在 @solana、@monad、@SuiNetwork、@Aptos 和 @HyperliquidX 進行質押。每當您累積獎勵,系統都會自動將其連同具體日期記錄在您的投資組合中。如此一來,您的所有財務資訊都能井然有序,並在報稅季來臨時做好萬全準備。
Kryptos 現已正式支援透過 @P2Pvalidator 在 @solana、@monad、@SuiNetwork、@Aptos 和 @HyperliquidX 進行質押。每當您累積獎勵,系統都會自動將其連同具體日期記錄在您的投資組合中。如此一來,您的所有財務資訊都能井然有序,並在報稅季來臨時做好萬全準備。
76
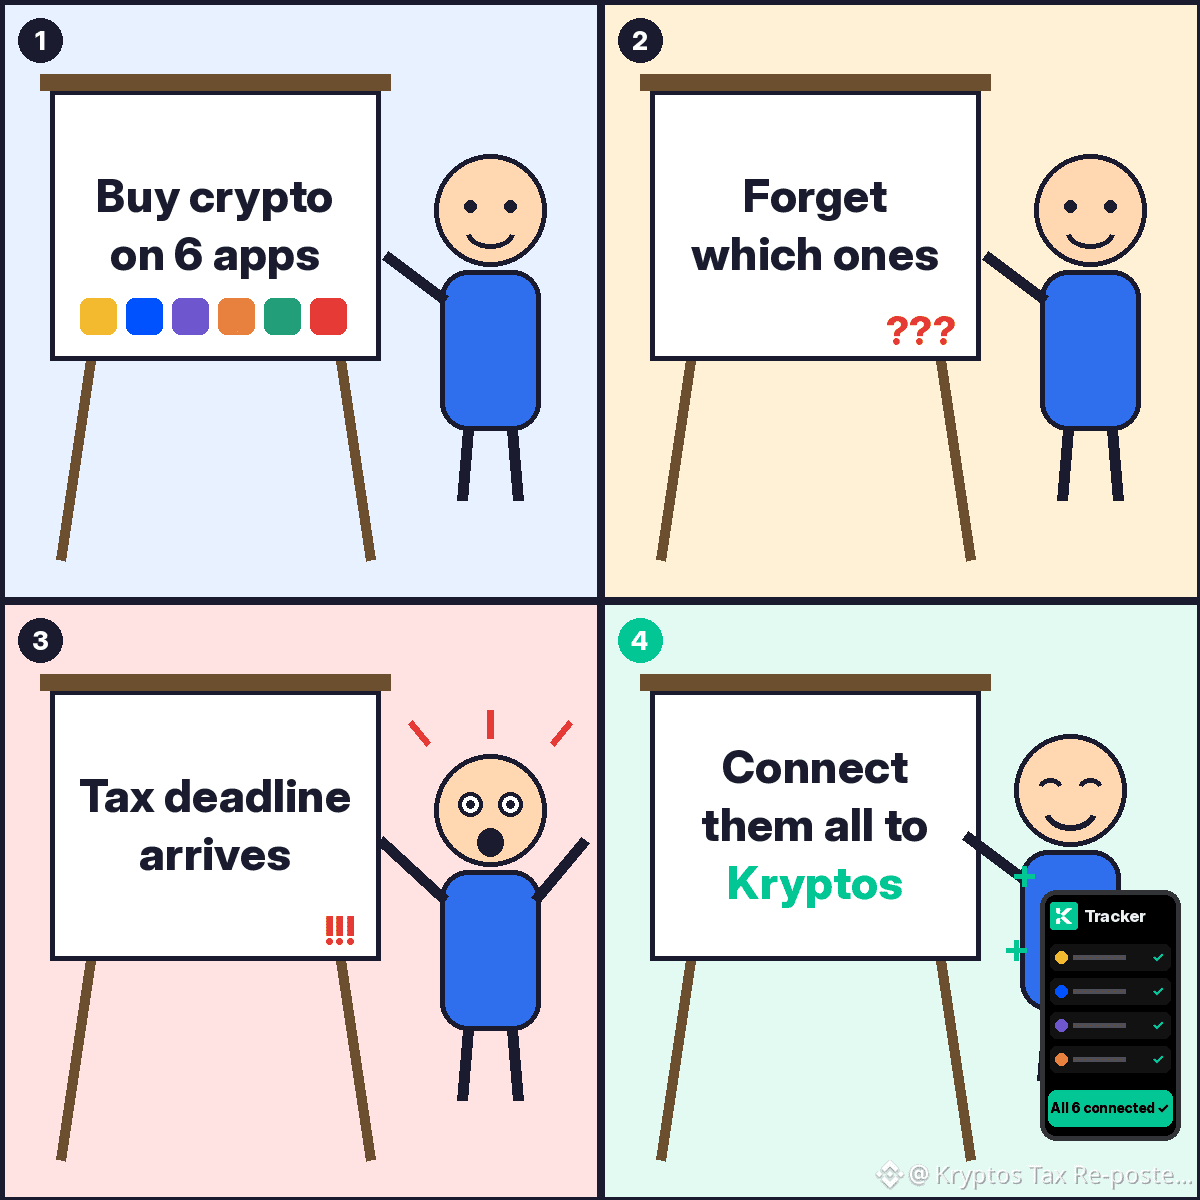
「購買加密貨幣」的搜尋量近期創下今年新高。這股趨勢往往會引發投資人熟悉的循環:先是購買數位資產,接著很快就忘了當初使用哪些平台進行交易。最後,報稅季便成了令人倍感壓力的時期。您可以徹底擺脫追蹤資產時的挫折感。Kryptos Tracker 會在一個完整的總覽畫面中,清楚顯示您使用的所有交易所和錢包,讓 Kryptos Tax 輕鬆處理其餘所有申報事宜。
「購買加密貨幣」的搜尋量近期創下今年新高。這股趨勢往往會引發投資人熟悉的循環:先是購買數位資產,接著很快就忘了當初使用哪些平台進行交易。最後,報稅季便成了令人倍感壓力的時期。您可以徹底擺脫追蹤資產時的挫折感。Kryptos Tracker 會在一個完整的總覽畫面中,清楚顯示您使用的所有交易所和錢包,讓 Kryptos Tax 輕鬆處理其餘所有申報事宜。
64
友善提醒大家,請務必在即將到來的 10 月 15 日截止日期前完成加密貨幣稅務申報。
友善提醒大家,請務必在即將到來的 10 月 15 日截止日期前完成加密貨幣稅務申報。
57
登入以探索更多內容
加入幣安廣場中的全球加密貨幣用戶
⚡️ 獲取加密貨幣的最新和實用資訊。
💬 受到全球最大加密貨幣交易所的信任。
👍 發掘來自經過驗證創作者的真實見解。
電子郵件 / 電話號碼