

000000000x
42 貼文

000000000x
舉報
封鎖用戶
一个小目标
4 關注
1 粉絲
1 點讚數
貼文
全部
影片
·
--
查看翻譯
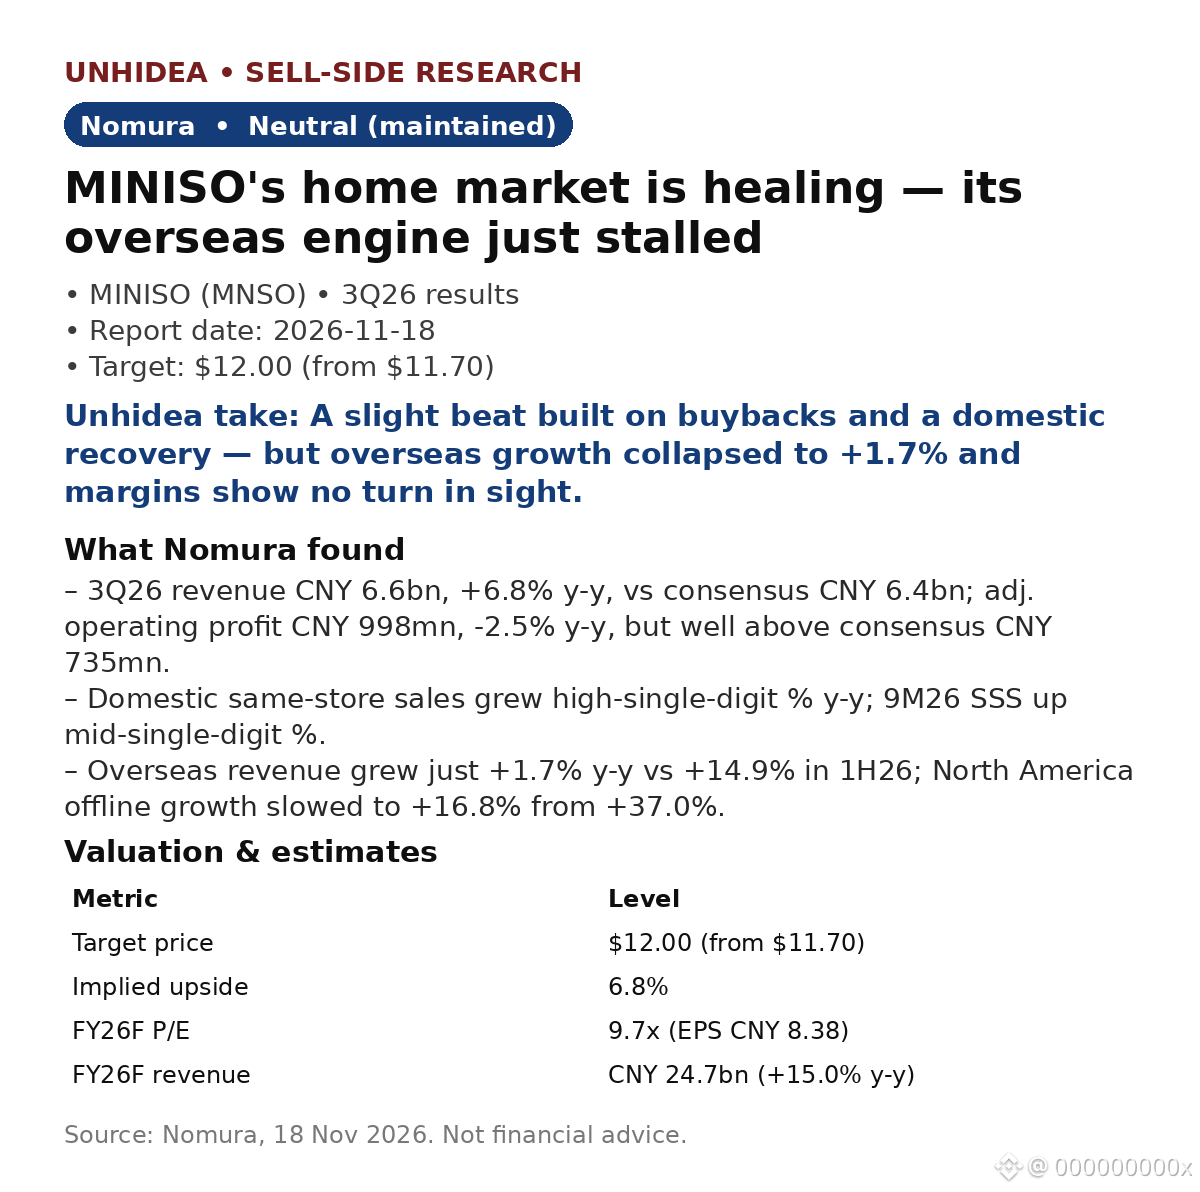
$MNSO: Nomura keeps Neutral — domestic recovery is real, but overseas growth just fell off a cliff
- 3Q26 revenue CNY 6.6bn, +6.8% y-y, ahead of consensus CNY 6.4bn; adj. operating profit CNY 998mn, -2.5% y-y but far above consensus CNY 735mn.
- Domestic same-store sales grew high-single-digit % y-y in 3Q26 (9M26: mid-single-digit %). The home market is healing.
- Overseas is the problem: revenue +1.7% y-y vs +14.9% in 1H26. North America offline growth slowed to +16.8% from +37.0%; overseas inventory hit 271 days (vs 212 a year ago).
- Margins: gross margin +0.6pp y-y, wiped out by sales & distribution costs +2.9pp y-y. Nomura sees no margin turnaround in 4Q26.
- Valuation: target $12.00 (from $11.70, 6.8% upside) at an unchanged 10.0x forward P/E; the stock trades at 9.7x FY26F P/E. FY26F revenue CNY 24.7bn, +15.0% y-y; FD normalized EPS CNY 8.38, -11.7% y-y.
Unhidea take: overseas was the growth story behind MINISO's premium — at +1.7% with 271 days of inventory, that story is on pause. Inventory ties up cash and forces discounting before it shows in margins.
Unhidea take: buybacks of >CNY 1bn (~4.5% of shares) are doing the heavy lifting while normalized EPS still falls 11.7% in FY26F. A cheap stock (9.7x) waiting for an overseas re-acceleration, not a turnaround yet.
Risks: domestic SSS slowdown, overseas uncertainty, intensifying competition.
Source: Nomura, 18 Nov 2026. Not financial advice.
$MNSO: Nomura keeps Neutral — domestic recovery is real, but overseas growth just fell off a cliff
- 3Q26 revenue CNY 6.6bn, +6.8% y-y, ahead of consensus CNY 6.4bn; adj. operating profit CNY 998mn, -2.5% y-y but far above consensus CNY 735mn.
- Domestic same-store sales grew high-single-digit % y-y in 3Q26 (9M26: mid-single-digit %). The home market is healing.
- Overseas is the problem: revenue +1.7% y-y vs +14.9% in 1H26. North America offline growth slowed to +16.8% from +37.0%; overseas inventory hit 271 days (vs 212 a year ago).
- Margins: gross margin +0.6pp y-y, wiped out by sales & distribution costs +2.9pp y-y. Nomura sees no margin turnaround in 4Q26.
- Valuation: target $12.00 (from $11.70, 6.8% upside) at an unchanged 10.0x forward P/E; the stock trades at 9.7x FY26F P/E. FY26F revenue CNY 24.7bn, +15.0% y-y; FD normalized EPS CNY 8.38, -11.7% y-y.
Unhidea take: overseas was the growth story behind MINISO's premium — at +1.7% with 271 days of inventory, that story is on pause. Inventory ties up cash and forces discounting before it shows in margins.
Unhidea take: buybacks of >CNY 1bn (~4.5% of shares) are doing the heavy lifting while normalized EPS still falls 11.7% in FY26F. A cheap stock (9.7x) waiting for an overseas re-acceleration, not a turnaround yet.
Risks: domestic SSS slowdown, overseas uncertainty, intensifying competition.
Source: Nomura, 18 Nov 2026. Not financial advice.
- 3Q26 revenue CNY 6.6bn, +6.8% y-y, ahead of consensus CNY 6.4bn; adj. operating profit CNY 998mn, -2.5% y-y but far above consensus CNY 735mn.
- Domestic same-store sales grew high-single-digit % y-y in 3Q26 (9M26: mid-single-digit %). The home market is healing.
- Overseas is the problem: revenue +1.7% y-y vs +14.9% in 1H26. North America offline growth slowed to +16.8% from +37.0%; overseas inventory hit 271 days (vs 212 a year ago).
- Margins: gross margin +0.6pp y-y, wiped out by sales & distribution costs +2.9pp y-y. Nomura sees no margin turnaround in 4Q26.
- Valuation: target $12.00 (from $11.70, 6.8% upside) at an unchanged 10.0x forward P/E; the stock trades at 9.7x FY26F P/E. FY26F revenue CNY 24.7bn, +15.0% y-y; FD normalized EPS CNY 8.38, -11.7% y-y.
Unhidea take: overseas was the growth story behind MINISO's premium — at +1.7% with 271 days of inventory, that story is on pause. Inventory ties up cash and forces discounting before it shows in margins.
Unhidea take: buybacks of >CNY 1bn (~4.5% of shares) are doing the heavy lifting while normalized EPS still falls 11.7% in FY26F. A cheap stock (9.7x) waiting for an overseas re-acceleration, not a turnaround yet.
Risks: domestic SSS slowdown, overseas uncertainty, intensifying competition.
Source: Nomura, 18 Nov 2026. Not financial advice.
MNSOUS-0.21%
12
·
--
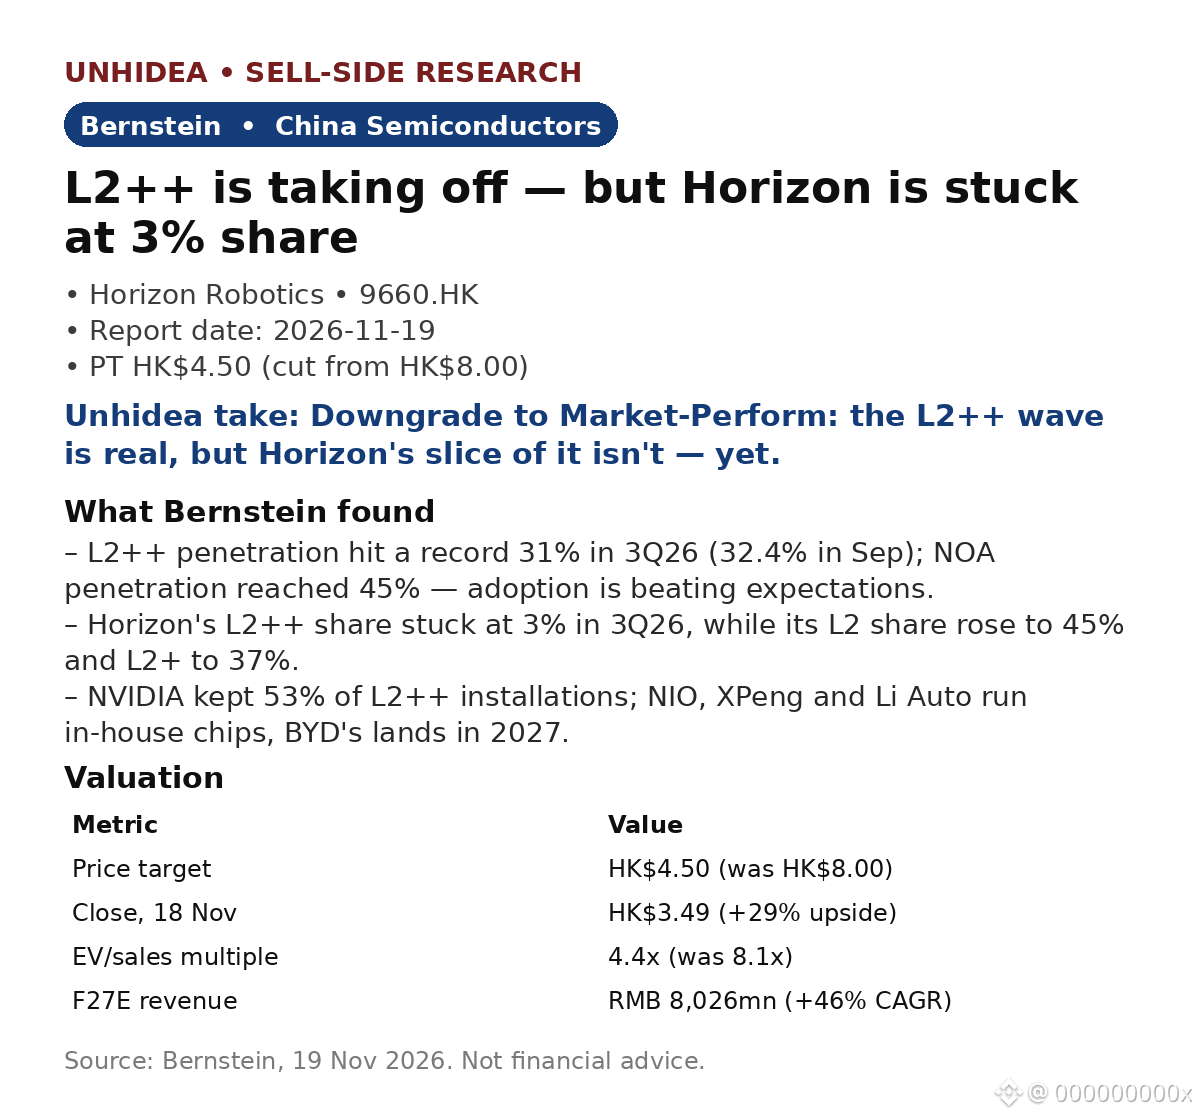
$9660.HK:Bernstein將地平線機器人評級下調至與大市持平,目標價從8.00港元大幅下調至4.50港元——L2++正蓬勃發展,地平線卻錯失良機
- 行業浪潮確實來勢洶洶:L2++滲透率在3Q26創下31%的紀錄(9月爲32.4%),NOA滲透率達到45%——市場普及速度快於Bernstein預期。
- 地平線的份額卻沒有跟上:3Q26其L2++份額維持在3%,同期L2份額升至45%,L2+升至37%。設計定點和搭載HSD車型的銷量持續不及預期。
- 競爭擠壓:NVIDIA在3Q26的L2++裝機量中佔據53%;蔚來、小鵬和理想汽車已採用自研芯片,比亞迪的芯片將於2027年推出,奇瑞也在開發自研芯片。
- 雙重阻力:3Q26中國乘用車銷量同比下降25%,地平線正轉向能見度較低的授權與服務模式。
- 估值:目標價4.50港元,較11月18日3.49港元收盤價高出29%;基於2026財年預估收入118億元人民幣,採用4.4倍EV/銷售額(此前爲8.1倍)。2027財年預估收入爲80.26億元人民幣(複合年增長率46.1%)——問題不在增長,而在份額。
Unhidea觀點:報告將此事歸結爲地平線自身的問題,但31%的滲透率加上NVIDIA的53%份額表明,獨立芯片供應商的競爭正圍繞現有領跑者走向集中——對其他獨立供應商而言,份額如今取決於車企是否決定自研芯片。
Unhidea觀點:如果比亞迪按計劃在2027年推出自研SoC,地平線的兩大關鍵客戶(比亞迪、大衆)就將構成其全部投資邏輯——應關注設計定點公告,而非季度收入,將其視爲領先指標。
風險:車企自研芯片、中國汽車行業週期疲軟、L2++設計定點轉化、授權模式的業務能見度。
來源:Bernstein,2026年11月19日。本文不構成投資建議。
$9660.HK:Bernstein將地平線機器人評級下調至與大市持平,目標價從8.00港元大幅下調至4.50港元——L2++正蓬勃發展,地平線卻錯失良機
- 行業浪潮確實來勢洶洶:L2++滲透率在3Q26創下31%的紀錄(9月爲32.4%),NOA滲透率達到45%——市場普及速度快於Bernstein預期。
- 地平線的份額卻沒有跟上:3Q26其L2++份額維持在3%,同期L2份額升至45%,L2+升至37%。設計定點和搭載HSD車型的銷量持續不及預期。
- 競爭擠壓:NVIDIA在3Q26的L2++裝機量中佔據53%;蔚來、小鵬和理想汽車已採用自研芯片,比亞迪的芯片將於2027年推出,奇瑞也在開發自研芯片。
- 雙重阻力:3Q26中國乘用車銷量同比下降25%,地平線正轉向能見度較低的授權與服務模式。
- 估值:目標價4.50港元,較11月18日3.49港元收盤價高出29%;基於2026財年預估收入118億元人民幣,採用4.4倍EV/銷售額(此前爲8.1倍)。2027財年預估收入爲80.26億元人民幣(複合年增長率46.1%)——問題不在增長,而在份額。
Unhidea觀點:報告將此事歸結爲地平線自身的問題,但31%的滲透率加上NVIDIA的53%份額表明,獨立芯片供應商的競爭正圍繞現有領跑者走向集中——對其他獨立供應商而言,份額如今取決於車企是否決定自研芯片。
Unhidea觀點:如果比亞迪按計劃在2027年推出自研SoC,地平線的兩大關鍵客戶(比亞迪、大衆)就將構成其全部投資邏輯——應關注設計定點公告,而非季度收入,將其視爲領先指標。
風險:車企自研芯片、中國汽車行業週期疲軟、L2++設計定點轉化、授權模式的業務能見度。
來源:Bernstein,2026年11月19日。本文不構成投資建議。
- 行業浪潮確實來勢洶洶:L2++滲透率在3Q26創下31%的紀錄(9月爲32.4%),NOA滲透率達到45%——市場普及速度快於Bernstein預期。
- 地平線的份額卻沒有跟上:3Q26其L2++份額維持在3%,同期L2份額升至45%,L2+升至37%。設計定點和搭載HSD車型的銷量持續不及預期。
- 競爭擠壓:NVIDIA在3Q26的L2++裝機量中佔據53%;蔚來、小鵬和理想汽車已採用自研芯片,比亞迪的芯片將於2027年推出,奇瑞也在開發自研芯片。
- 雙重阻力:3Q26中國乘用車銷量同比下降25%,地平線正轉向能見度較低的授權與服務模式。
- 估值:目標價4.50港元,較11月18日3.49港元收盤價高出29%;基於2026財年預估收入118億元人民幣,採用4.4倍EV/銷售額(此前爲8.1倍)。2027財年預估收入爲80.26億元人民幣(複合年增長率46.1%)——問題不在增長,而在份額。
Unhidea觀點:報告將此事歸結爲地平線自身的問題,但31%的滲透率加上NVIDIA的53%份額表明,獨立芯片供應商的競爭正圍繞現有領跑者走向集中——對其他獨立供應商而言,份額如今取決於車企是否決定自研芯片。
Unhidea觀點:如果比亞迪按計劃在2027年推出自研SoC,地平線的兩大關鍵客戶(比亞迪、大衆)就將構成其全部投資邏輯——應關注設計定點公告,而非季度收入,將其視爲領先指標。
風險:車企自研芯片、中國汽車行業週期疲軟、L2++設計定點轉化、授權模式的業務能見度。
來源:Bernstein,2026年11月19日。本文不構成投資建議。
NVDA-4.14%
LIUS-1.17%
125
·
--
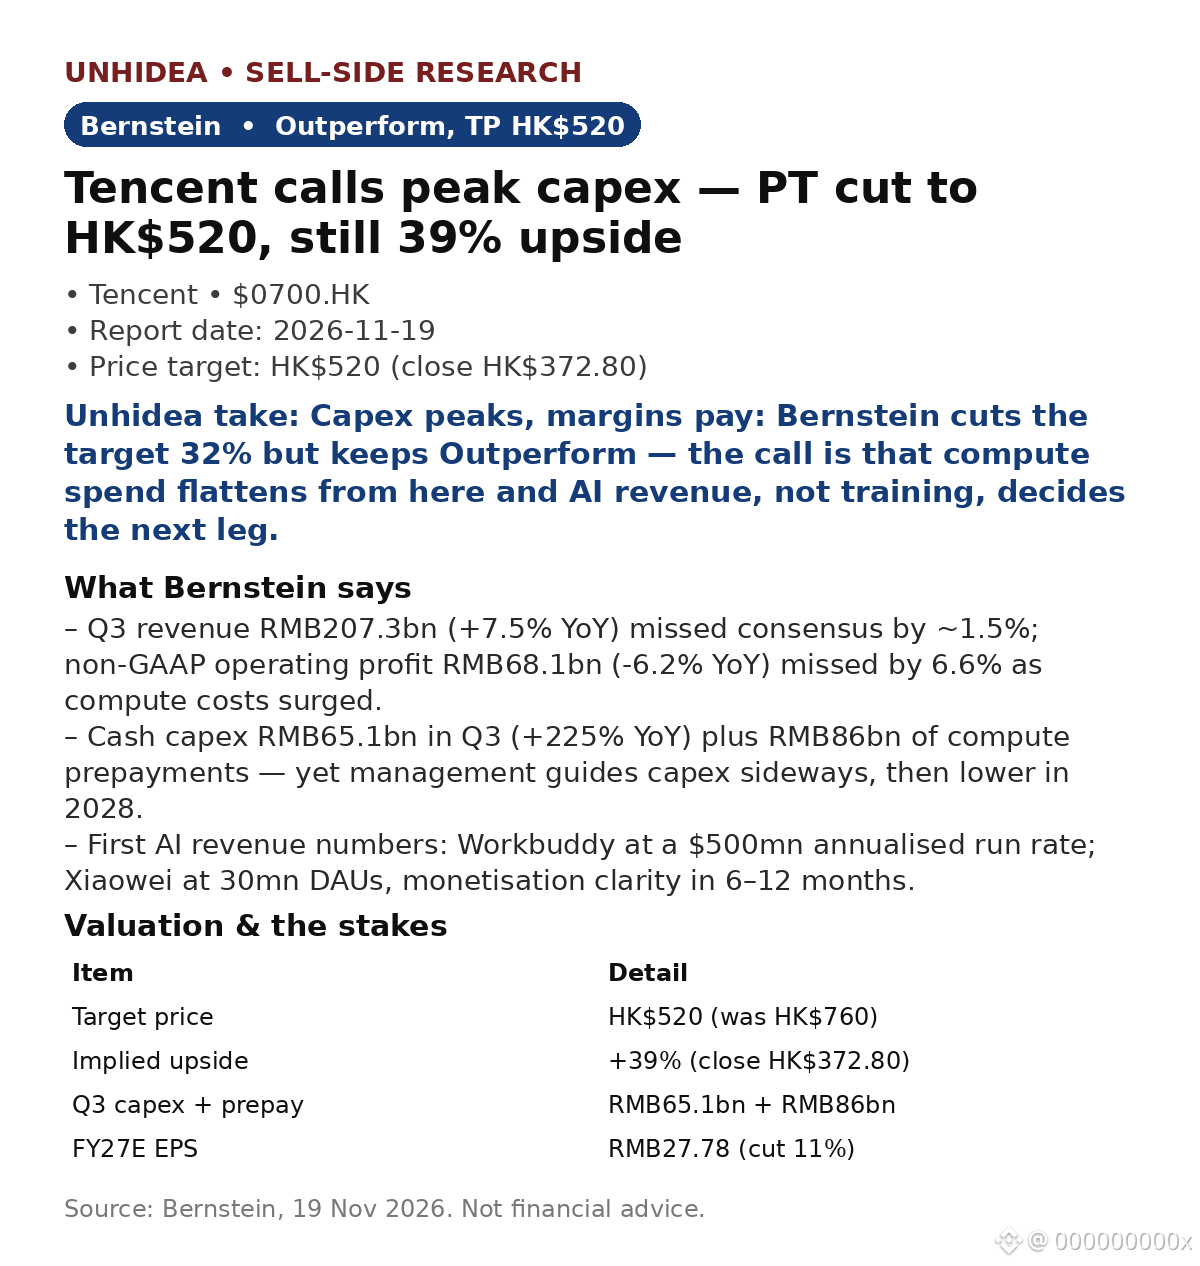
$0700.HK:騰訊稱資本開支見頂——伯恩斯坦維持「跑贏大市」,目標價520港元(由760港元下調)
- 第三季度收入2,073億元人民幣(同比增長7.5%),較市場共識低約1.5%;非GAAP營業利潤681億元人民幣(同比下降6.2%),較市場共識低6.6%——計算成本造成了衝擊。
- 資本開支是焦點:第三季度爲651億元人民幣(同比增長225%),另有860億元人民幣的算力預付款——但管理層表示,資本開支將持平,隨後於2028年下降。伯恩斯坦稱,繼索尼之後,騰訊是第二家認爲硬件成本不可持續的公司。
- 成本賬單:帶寬及服務器成本同比增長132%,非員工研發支出增長152%。廣告收入仍增長18.8%,達430億元人民幣;遊戲收入增長4.6%,達665億元人民幣;金融科技及企業服務(FBS)收入增長9.4%,達637億元人民幣。剔除AI支出的核心營業利潤增長8%,達833億元人民幣。
- 首批AI收入數據:Workbuddy年化收入運行率達5億美元;小微月活躍用戶(DAU)達3,000萬,預計6至12個月內實現商業化。伯恩斯坦稱,美國芯片限制會延緩訓練,但不會影響推理收入。
- 估值:目標價520港元,較11月18日372.80港元的收盤價高出39%;股價接近370港元的52周低點,在年初至今下跌38%後,按過去12個月盈利計算約爲11倍市盈率;2027財年預期每股收益下調11%至27.78元人民幣。
Unhidea觀點:資本開支是否見頂,是騰訊之外也在討論的問題——如果如此大規模的買家將支出趨於穩定,AI硬件週期能持續多久便成了關鍵問題。
Unhidea觀點:騰訊目前約爲11倍市盈率,AI期權價值尚未計入股價——Workbuddy和小微提供了首批確鑿數據;若商業化落地,伯恩斯坦給出的未來一年市盈率16倍將成爲估值重評的路徑。
風險:美國芯片限制、中國宏觀經濟、遊戲業務比較基數、AI商業化時點。
來源:伯恩斯坦,2026年11月19日。本文不構成投資建議。
$0700.HK:騰訊稱資本開支見頂——伯恩斯坦維持「跑贏大市」,目標價520港元(由760港元下調)
- 第三季度收入2,073億元人民幣(同比增長7.5%),較市場共識低約1.5%;非GAAP營業利潤681億元人民幣(同比下降6.2%),較市場共識低6.6%——計算成本造成了衝擊。
- 資本開支是焦點:第三季度爲651億元人民幣(同比增長225%),另有860億元人民幣的算力預付款——但管理層表示,資本開支將持平,隨後於2028年下降。伯恩斯坦稱,繼索尼之後,騰訊是第二家認爲硬件成本不可持續的公司。
- 成本賬單:帶寬及服務器成本同比增長132%,非員工研發支出增長152%。廣告收入仍增長18.8%,達430億元人民幣;遊戲收入增長4.6%,達665億元人民幣;金融科技及企業服務(FBS)收入增長9.4%,達637億元人民幣。剔除AI支出的核心營業利潤增長8%,達833億元人民幣。
- 首批AI收入數據:Workbuddy年化收入運行率達5億美元;小微月活躍用戶(DAU)達3,000萬,預計6至12個月內實現商業化。伯恩斯坦稱,美國芯片限制會延緩訓練,但不會影響推理收入。
- 估值:目標價520港元,較11月18日372.80港元的收盤價高出39%;股價接近370港元的52周低點,在年初至今下跌38%後,按過去12個月盈利計算約爲11倍市盈率;2027財年預期每股收益下調11%至27.78元人民幣。
Unhidea觀點:資本開支是否見頂,是騰訊之外也在討論的問題——如果如此大規模的買家將支出趨於穩定,AI硬件週期能持續多久便成了關鍵問題。
Unhidea觀點:騰訊目前約爲11倍市盈率,AI期權價值尚未計入股價——Workbuddy和小微提供了首批確鑿數據;若商業化落地,伯恩斯坦給出的未來一年市盈率16倍將成爲估值重評的路徑。
風險:美國芯片限制、中國宏觀經濟、遊戲業務比較基數、AI商業化時點。
來源:伯恩斯坦,2026年11月19日。本文不構成投資建議。
- 第三季度收入2,073億元人民幣(同比增長7.5%),較市場共識低約1.5%;非GAAP營業利潤681億元人民幣(同比下降6.2%),較市場共識低6.6%——計算成本造成了衝擊。
- 資本開支是焦點:第三季度爲651億元人民幣(同比增長225%),另有860億元人民幣的算力預付款——但管理層表示,資本開支將持平,隨後於2028年下降。伯恩斯坦稱,繼索尼之後,騰訊是第二家認爲硬件成本不可持續的公司。
- 成本賬單:帶寬及服務器成本同比增長132%,非員工研發支出增長152%。廣告收入仍增長18.8%,達430億元人民幣;遊戲收入增長4.6%,達665億元人民幣;金融科技及企業服務(FBS)收入增長9.4%,達637億元人民幣。剔除AI支出的核心營業利潤增長8%,達833億元人民幣。
- 首批AI收入數據:Workbuddy年化收入運行率達5億美元;小微月活躍用戶(DAU)達3,000萬,預計6至12個月內實現商業化。伯恩斯坦稱,美國芯片限制會延緩訓練,但不會影響推理收入。
- 估值:目標價520港元,較11月18日372.80港元的收盤價高出39%;股價接近370港元的52周低點,在年初至今下跌38%後,按過去12個月盈利計算約爲11倍市盈率;2027財年預期每股收益下調11%至27.78元人民幣。
Unhidea觀點:資本開支是否見頂,是騰訊之外也在討論的問題——如果如此大規模的買家將支出趨於穩定,AI硬件週期能持續多久便成了關鍵問題。
Unhidea觀點:騰訊目前約爲11倍市盈率,AI期權價值尚未計入股價——Workbuddy和小微提供了首批確鑿數據;若商業化落地,伯恩斯坦給出的未來一年市盈率16倍將成爲估值重評的路徑。
風險:美國芯片限制、中國宏觀經濟、遊戲業務比較基數、AI商業化時點。
來源:伯恩斯坦,2026年11月19日。本文不構成投資建議。
114
·
--
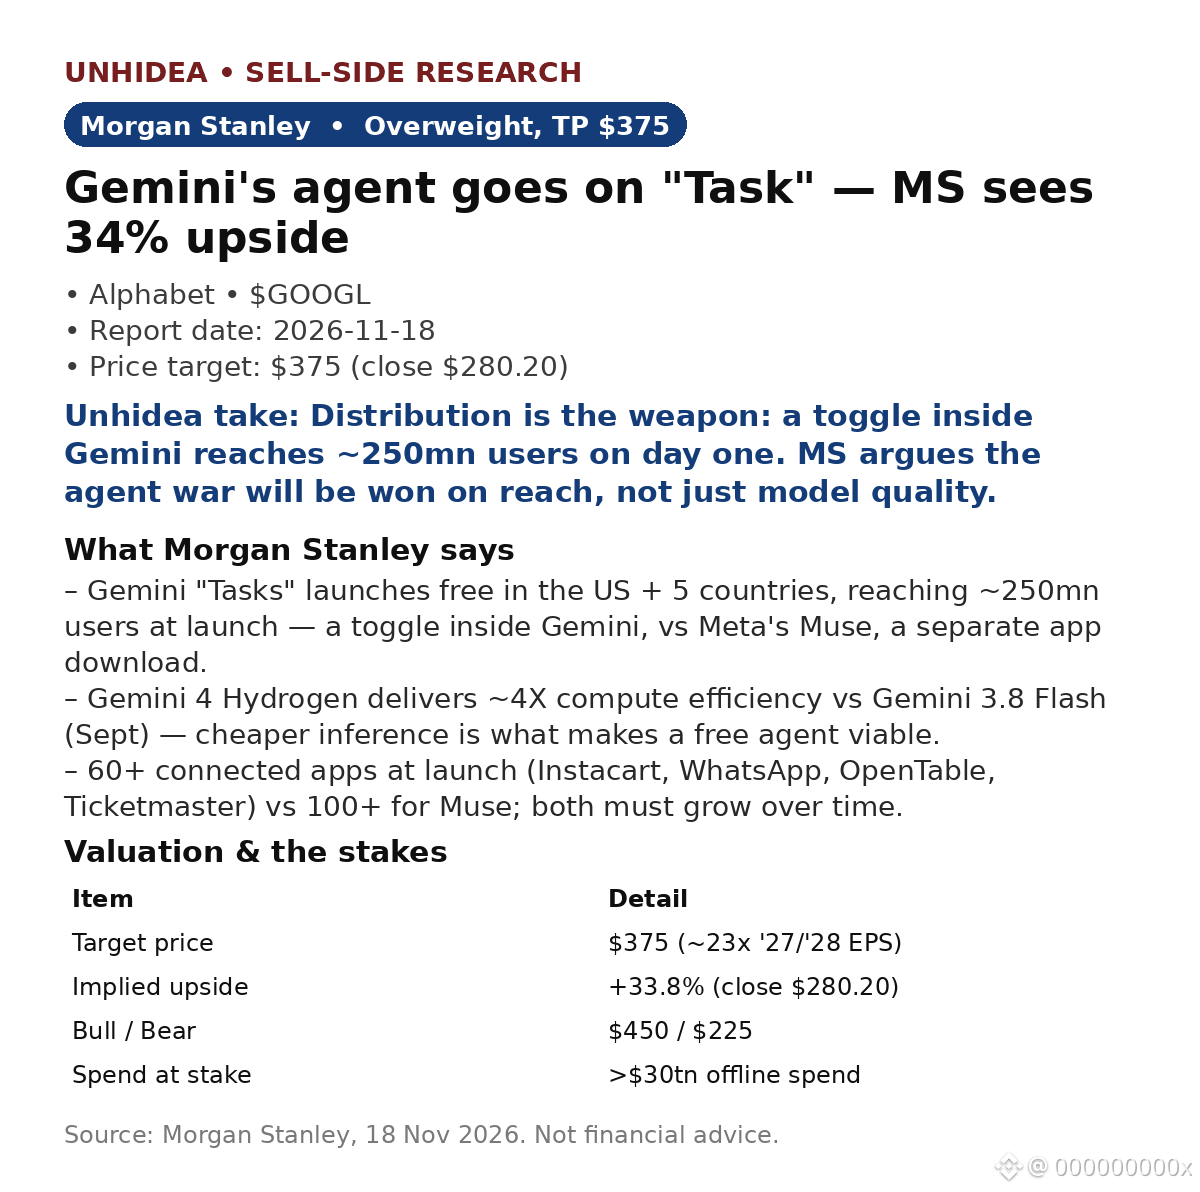
$GOOGL:Gemini 的代理功能現已推出「Tasks」——摩根士丹利維持「加碼」評級,目標價 375 美元(較 11 月 17 日收盤價 280.20 美元高 34%)
- 「Tasks」在美國及另外 5 個國家免費推出,適用於約 2.5 億名用戶——這是 Gemini(每月活躍用戶逾 10 億)內的一個切換開關,無需下載。Meta 的 Muse 則是獨立應用程式,每月活躍用戶約 1,200 萬(第三方數據)。
- Gemini 4 Hydrogen 的運算效率約為 Gemini 3.8 Flash(9 月推出)的 4 倍。Meta 計劃在 2027 年讓 Muse 的成本效益提升 10 倍——效率將決定誰能負擔得起免費代理功能。
- 上線時可連接 60 多個應用程式(Instacart、WhatsApp、OpenTable),Muse 則有 100 多個。摩根士丹利表示:率先擴大規模的代理產品將獲得更多企業採用——這有利於 Google。
- 但問題是:搜尋可變現約 20–40% 的交易價值,而代理服務的佣金僅為低個位數百分比。如果 Tasks 在不增加消費的情況下轉移搜尋查詢,就會侵蝕 Google 最好的利潤來源。
- 摩根士丹利認為,超過 30 兆美元的線下消費市場有待爭取;樂觀情境為 450 美元,悲觀情境為 225 美元。股價於 11 月 18 日上漲 0.8%,至 282.44 美元(報告發布後,Finnhub),較 408.61 美元的高點低約 31%。
Unhidea 觀點:代理大戰就是通路之戰——擺在 10 億用戶面前的一個切換開關,勝過要求用戶下載應用程式。關鍵在於 Tasks 會成為使用習慣,還是只是一場展示。
Unhidea 觀點:關注搜尋,而非 Tasks。如果代理購物成長、搜尋卻放緩,估值倍數就會收縮——摩根士丹利的 375 美元目標價假設搜尋業務能持續穩健。
風險:搜尋業務遭蠶食、Meta/Amazon 競爭、AI 資本支出/投資資本回報率、監管。
來源:摩根士丹利,2026 年 11 月 18 日。本文不構成財務建議。
$GOOGL :Gemini 的代理功能現已推出「Tasks」——摩根士丹利維持「加碼」評級,目標價 375 美元(較 11 月 17 日收盤價 280.20 美元高 34%)
- 「Tasks」在美國及另外 5 個國家免費推出,適用於約 2.5 億名用戶——這是 Gemini(每月活躍用戶逾 10 億)內的一個切換開關,無需下載。Meta 的 Muse 則是獨立應用程式,每月活躍用戶約 1,200 萬(第三方數據)。
- Gemini 4 Hydrogen 的運算效率約為 Gemini 3.8 Flash(9 月推出)的 4 倍。Meta 計劃在 2027 年讓 Muse 的成本效益提升 10 倍——效率將決定誰能負擔得起免費代理功能。
- 上線時可連接 60 多個應用程式(Instacart、WhatsApp、OpenTable),Muse 則有 100 多個。摩根士丹利表示:率先擴大規模的代理產品將獲得更多企業採用——這有利於 Google。
- 但問題是:搜尋可變現約 20–40% 的交易價值,而代理服務的佣金僅為低個位數百分比。如果 Tasks 在不增加消費的情況下轉移搜尋查詢,就會侵蝕 Google 最好的利潤來源。
- 摩根士丹利認為,超過 30 兆美元的線下消費市場有待爭取;樂觀情境為 450 美元,悲觀情境為 225 美元。股價於 11 月 18 日上漲 0.8%,至 282.44 美元(報告發布後,Finnhub),較 408.61 美元的高點低約 31%。
Unhidea 觀點:代理大戰就是通路之戰——擺在 10 億用戶面前的一個切換開關,勝過要求用戶下載應用程式。關鍵在於 Tasks 會成為使用習慣,還是只是一場展示。
Unhidea 觀點:關注搜尋,而非 Tasks。如果代理購物成長、搜尋卻放緩,估值倍數就會收縮——摩根士丹利的 375 美元目標價假設搜尋業務能持續穩健。
風險:搜尋業務遭蠶食、Meta/Amazon 競爭、AI 資本支出/投資資本回報率、監管。
來源:摩根士丹利,2026 年 11 月 18 日。本文不構成財務建議。
- 「Tasks」在美國及另外 5 個國家免費推出,適用於約 2.5 億名用戶——這是 Gemini(每月活躍用戶逾 10 億)內的一個切換開關,無需下載。Meta 的 Muse 則是獨立應用程式,每月活躍用戶約 1,200 萬(第三方數據)。
- Gemini 4 Hydrogen 的運算效率約為 Gemini 3.8 Flash(9 月推出)的 4 倍。Meta 計劃在 2027 年讓 Muse 的成本效益提升 10 倍——效率將決定誰能負擔得起免費代理功能。
- 上線時可連接 60 多個應用程式(Instacart、WhatsApp、OpenTable),Muse 則有 100 多個。摩根士丹利表示:率先擴大規模的代理產品將獲得更多企業採用——這有利於 Google。
- 但問題是:搜尋可變現約 20–40% 的交易價值,而代理服務的佣金僅為低個位數百分比。如果 Tasks 在不增加消費的情況下轉移搜尋查詢,就會侵蝕 Google 最好的利潤來源。
- 摩根士丹利認為,超過 30 兆美元的線下消費市場有待爭取;樂觀情境為 450 美元,悲觀情境為 225 美元。股價於 11 月 18 日上漲 0.8%,至 282.44 美元(報告發布後,Finnhub),較 408.61 美元的高點低約 31%。
Unhidea 觀點:代理大戰就是通路之戰——擺在 10 億用戶面前的一個切換開關,勝過要求用戶下載應用程式。關鍵在於 Tasks 會成為使用習慣,還是只是一場展示。
Unhidea 觀點:關注搜尋,而非 Tasks。如果代理購物成長、搜尋卻放緩,估值倍數就會收縮——摩根士丹利的 375 美元目標價假設搜尋業務能持續穩健。
風險:搜尋業務遭蠶食、Meta/Amazon 競爭、AI 資本支出/投資資本回報率、監管。
來源:摩根士丹利,2026 年 11 月 18 日。本文不構成財務建議。
89
·
--
查看翻譯
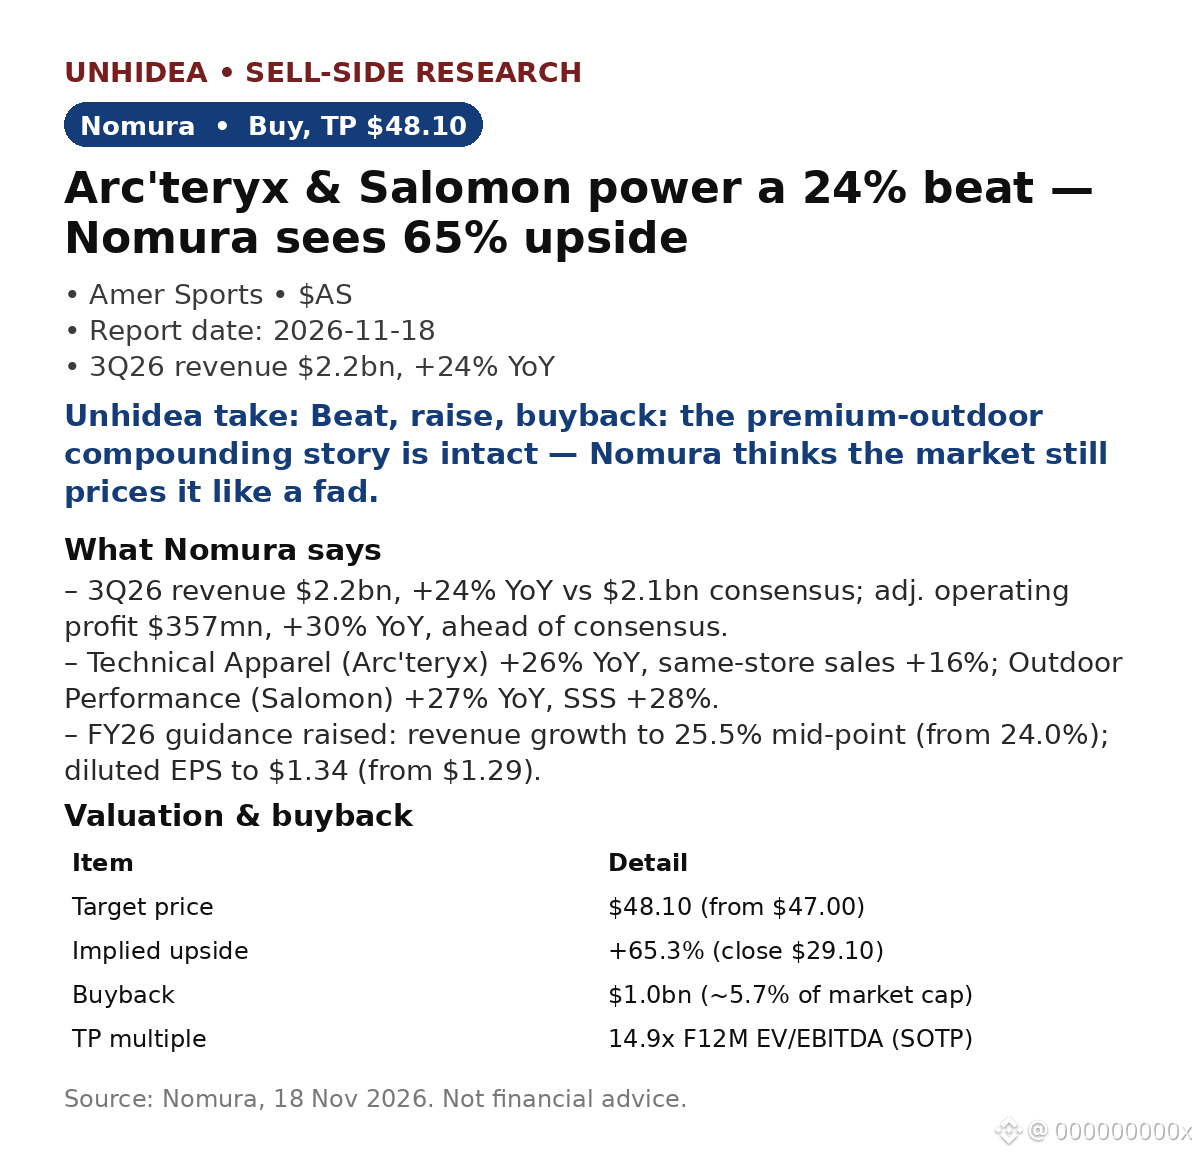
$AS: Arc'teryx & Salomon power a 24% beat — Nomura reiterates Buy, TP $48.10 (+65% upside)
- 3Q26 revenue $2.2bn, +24% YoY, vs $2.1bn consensus. Adj. operating profit $357mn, +30% YoY, ahead of consensus. Adj. EPS $0.42 vs $0.35 expected.
- Technical Apparel (Arc'teryx) +26% YoY, same-store sales +16%; Outdoor Performance (Salomon) +27% YoY, SSS +28%. Ball & Racquet +12%, but margin fell 2.1pp on Wilson investment.
- Guidance raised: FY26 revenue growth to 25.5% (from 24.0%); diluted EPS to $1.34 (from $1.29). A $1bn buyback (~5.7% of market cap) adds a floor.
- Shares +3.9% to $30.24 on 17 Nov while the S&P fell ~1%, then +2.3% to $30.95 on 18 Nov (post-report market data). SOTP target implies 14.9x forward EV/EBITDA.
Unhidea take: two brands growing 26–27% with DTC pricing power, plus a buyback floor — the market still prices Amer like a cyclical retailer; Nomura's 65% upside says brand platform.
Unhidea take: the Street is split — UBS cut its target to $56, Nomura holds $48.10, both Buy. That gap is the debate: what multiple for a 25% grower at 59.3% gross margin?
Risks: Wilson drag, DTC execution, tariffs/FX, premium-consumer slowdown.
Source: Nomura, 18 Nov 2026. Post-report prices: Finnhub/market data. Not financial advice.
$AS: Arc'teryx & Salomon power a 24% beat — Nomura reiterates Buy, TP $48.10 (+65% upside)
- 3Q26 revenue $2.2bn, +24% YoY, vs $2.1bn consensus. Adj. operating profit $357mn, +30% YoY, ahead of consensus. Adj. EPS $0.42 vs $0.35 expected.
- Technical Apparel (Arc'teryx) +26% YoY, same-store sales +16%; Outdoor Performance (Salomon) +27% YoY, SSS +28%. Ball & Racquet +12%, but margin fell 2.1pp on Wilson investment.
- Guidance raised: FY26 revenue growth to 25.5% (from 24.0%); diluted EPS to $1.34 (from $1.29). A $1bn buyback (~5.7% of market cap) adds a floor.
- Shares +3.9% to $30.24 on 17 Nov while the S&P fell ~1%, then +2.3% to $30.95 on 18 Nov (post-report market data). SOTP target implies 14.9x forward EV/EBITDA.
Unhidea take: two brands growing 26–27% with DTC pricing power, plus a buyback floor — the market still prices Amer like a cyclical retailer; Nomura's 65% upside says brand platform.
Unhidea take: the Street is split — UBS cut its target to $56, Nomura holds $48.10, both Buy. That gap is the debate: what multiple for a 25% grower at 59.3% gross margin?
Risks: Wilson drag, DTC execution, tariffs/FX, premium-consumer slowdown.
Source: Nomura, 18 Nov 2026. Post-report prices: Finnhub/market data. Not financial advice.
- 3Q26 revenue $2.2bn, +24% YoY, vs $2.1bn consensus. Adj. operating profit $357mn, +30% YoY, ahead of consensus. Adj. EPS $0.42 vs $0.35 expected.
- Technical Apparel (Arc'teryx) +26% YoY, same-store sales +16%; Outdoor Performance (Salomon) +27% YoY, SSS +28%. Ball & Racquet +12%, but margin fell 2.1pp on Wilson investment.
- Guidance raised: FY26 revenue growth to 25.5% (from 24.0%); diluted EPS to $1.34 (from $1.29). A $1bn buyback (~5.7% of market cap) adds a floor.
- Shares +3.9% to $30.24 on 17 Nov while the S&P fell ~1%, then +2.3% to $30.95 on 18 Nov (post-report market data). SOTP target implies 14.9x forward EV/EBITDA.
Unhidea take: two brands growing 26–27% with DTC pricing power, plus a buyback floor — the market still prices Amer like a cyclical retailer; Nomura's 65% upside says brand platform.
Unhidea take: the Street is split — UBS cut its target to $56, Nomura holds $48.10, both Buy. That gap is the debate: what multiple for a 25% grower at 59.3% gross margin?
Risks: Wilson drag, DTC execution, tariffs/FX, premium-consumer slowdown.
Source: Nomura, 18 Nov 2026. Post-report prices: Finnhub/market data. Not financial advice.
ASUS-0.25%
75
·
--
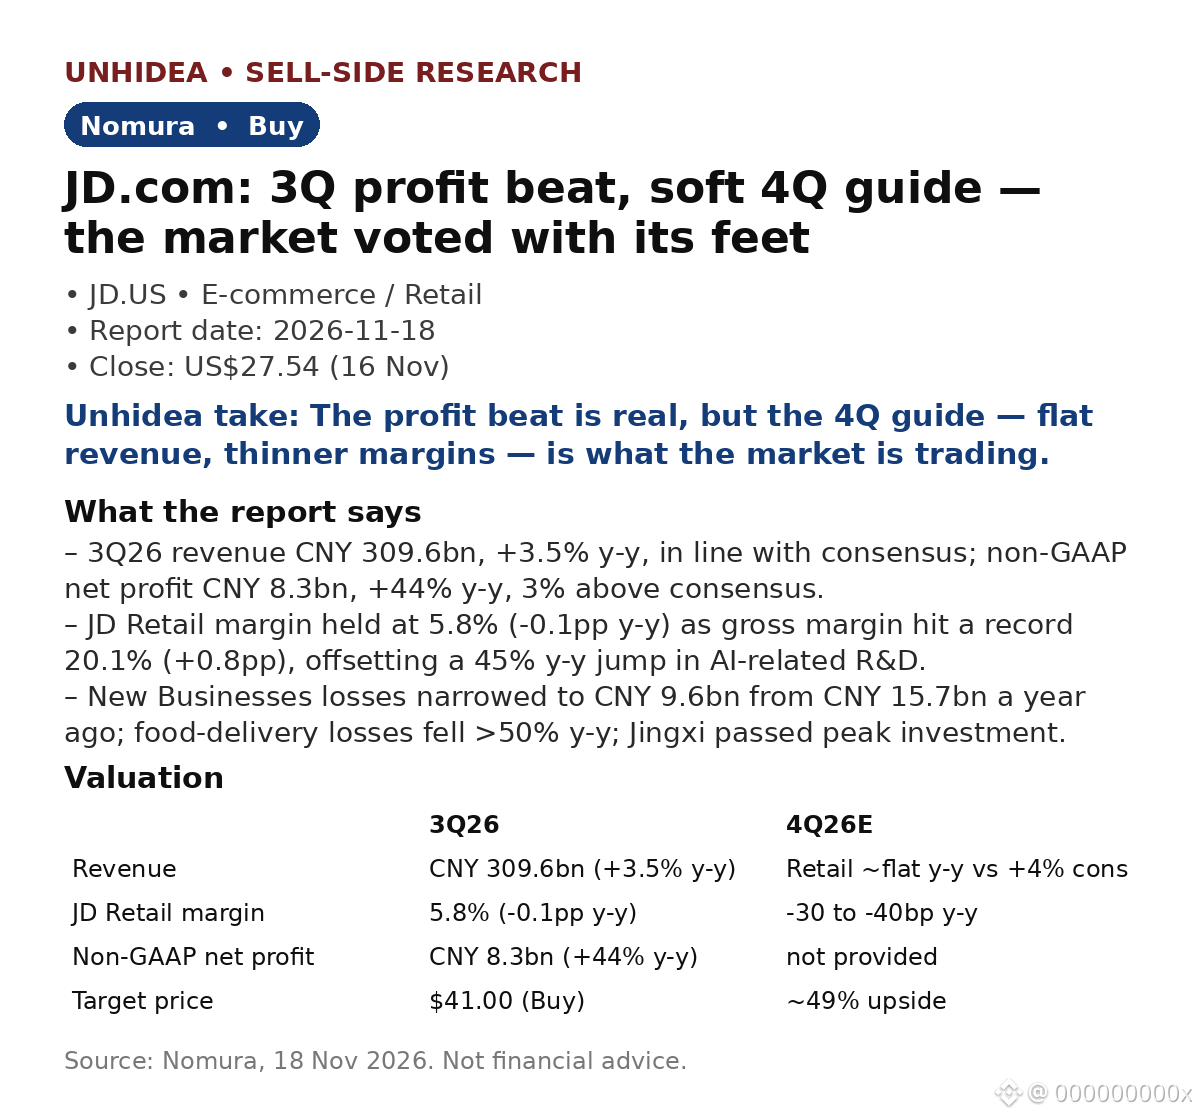
京東($JD):野村維持買入評級,目標價41美元——三季度利潤超預期、四季度指引疲軟,市場用腳投票
- 2026財年第三季度營收爲3096億元人民幣,同比增長3.5%,符合預期;非GAAP淨利潤爲83億元人民幣,同比增長44%,比市場一致預期高3%;非GAAP營業利潤爲73億元人民幣,比市場一致預期高15%。
- 京東零售利潤率保持在5.8%(同比下降0.1個百分點);毛利率達到創紀錄的20.1%(同比上升0.8個百分點),抵消了AI研發支出同比激增45%的影響。
- 新業務虧損從去年同期的157億元人民幣收窄至96億元人民幣;外賣業務虧損同比下降超過50%。
- 但第四季度前景疲軟:預計京東零售營收同比持平,而市場一致預期爲增長4%;利潤率預計同比下降30至40個基點,而市場預期爲下降10個基點。
- 估值:41美元目標價對應2027財年預期市盈率8.5倍,而當前爲5.7倍——較11月16日收盤價27.54美元有約49%的上漲空間。
Unhidea觀點:業績超預期確實屬實,但反映的是過去——市場交易的是第四季度指引,而不是第三季度業績。
Unhidea觀點:京東的核心敘事如今是利潤率管理,而非增長——虧損收窄比營收持平更重要。
市場反應:股價於11月17日下跌7.7%,至25.43美元;11月18日又下跌2.0%,至24.92美元(Finnhub)。
風險:消費疲軟;競爭;CECONYOMY整合(交易於11月12日完成)。
來源:野村,2026年11月18日。本文不構成財務建議。
京東($JD):野村維持買入評級,目標價41美元——三季度利潤超預期、四季度指引疲軟,市場用腳投票
- 2026財年第三季度營收爲3096億元人民幣,同比增長3.5%,符合預期;非GAAP淨利潤爲83億元人民幣,同比增長44%,比市場一致預期高3%;非GAAP營業利潤爲73億元人民幣,比市場一致預期高15%。
- 京東零售利潤率保持在5.8%(同比下降0.1個百分點);毛利率達到創紀錄的20.1%(同比上升0.8個百分點),抵消了AI研發支出同比激增45%的影響。
- 新業務虧損從去年同期的157億元人民幣收窄至96億元人民幣;外賣業務虧損同比下降超過50%。
- 但第四季度前景疲軟:預計京東零售營收同比持平,而市場一致預期爲增長4%;利潤率預計同比下降30至40個基點,而市場預期爲下降10個基點。
- 估值:41美元目標價對應2027財年預期市盈率8.5倍,而當前爲5.7倍——較11月16日收盤價27.54美元有約49%的上漲空間。
Unhidea觀點:業績超預期確實屬實,但反映的是過去——市場交易的是第四季度指引,而不是第三季度業績。
Unhidea觀點:京東的核心敘事如今是利潤率管理,而非增長——虧損收窄比營收持平更重要。
市場反應:股價於11月17日下跌7.7%,至25.43美元;11月18日又下跌2.0%,至24.92美元(Finnhub)。
風險:消費疲軟;競爭;CECONYOMY整合(交易於11月12日完成)。
來源:野村,2026年11月18日。本文不構成財務建議。
- 2026財年第三季度營收爲3096億元人民幣,同比增長3.5%,符合預期;非GAAP淨利潤爲83億元人民幣,同比增長44%,比市場一致預期高3%;非GAAP營業利潤爲73億元人民幣,比市場一致預期高15%。
- 京東零售利潤率保持在5.8%(同比下降0.1個百分點);毛利率達到創紀錄的20.1%(同比上升0.8個百分點),抵消了AI研發支出同比激增45%的影響。
- 新業務虧損從去年同期的157億元人民幣收窄至96億元人民幣;外賣業務虧損同比下降超過50%。
- 但第四季度前景疲軟:預計京東零售營收同比持平,而市場一致預期爲增長4%;利潤率預計同比下降30至40個基點,而市場預期爲下降10個基點。
- 估值:41美元目標價對應2027財年預期市盈率8.5倍,而當前爲5.7倍——較11月16日收盤價27.54美元有約49%的上漲空間。
Unhidea觀點:業績超預期確實屬實,但反映的是過去——市場交易的是第四季度指引,而不是第三季度業績。
Unhidea觀點:京東的核心敘事如今是利潤率管理,而非增長——虧損收窄比營收持平更重要。
市場反應:股價於11月17日下跌7.7%,至25.43美元;11月18日又下跌2.0%,至24.92美元(Finnhub)。
風險:消費疲軟;競爭;CECONYOMY整合(交易於11月12日完成)。
來源:野村,2026年11月18日。本文不構成財務建議。
JDUS+1.00%
4
·
--
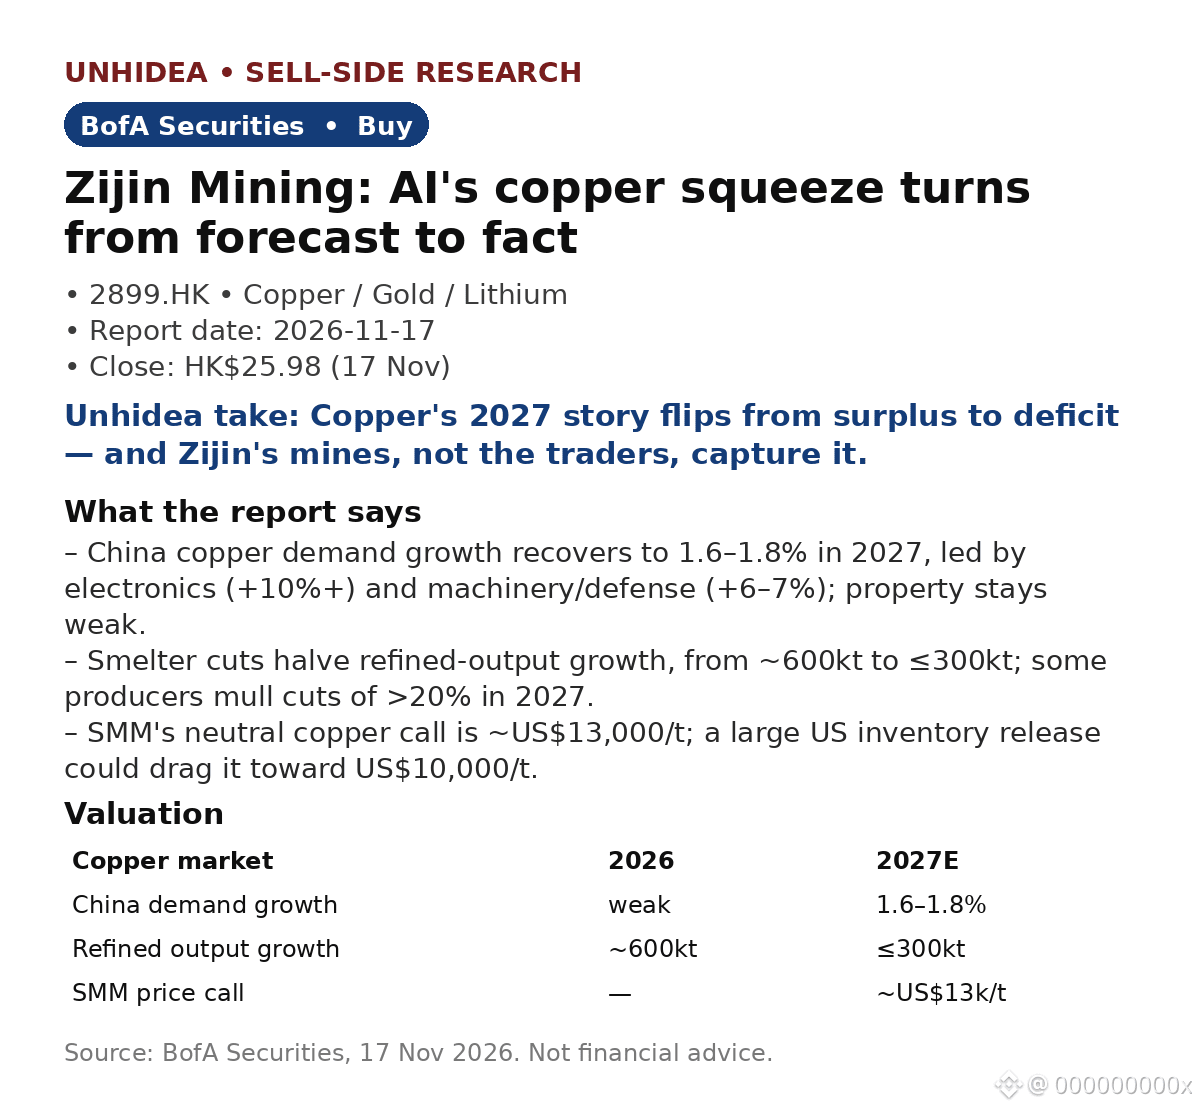
紫金礦業(2899.HK):美國銀行維持買入評級——中國銅需求回暖,冶煉廠減產
- 中國銅需求增速預計在2027年回升至1.6–1.8%,由電子產品(增長超過10%)和機械/國防(增長6–7%)帶動;房地產仍然疲軟。
- 冶煉廠減產使精煉銅產量增速減半,從約60萬噸降至不超過30萬噸;SMM中性預期爲約13,000美元/噸,美國釋放庫存則帶來價格跌向10,000美元/噸的風險。
- 紫金維持2026年指引(不包括Kamoa-Kakula約5萬噸的虧損);現有礦山2028年產量爲140萬至145萬噸,低於150萬噸的目標;非洲項目增產超過30萬噸。
- AI基礎設施是關鍵增量:到2027年底,M8 CCL需求將增長至原來的三倍,從每月250萬增至750萬;磷化銦(InP)佔雲南鍺業淨利潤的70%以上,利潤率超過65%,訂單已鎖定至2027年。
- 紫金評級爲買入,11月17日收盤價爲25.98港元;本報告未重申目標價。
Unhidea觀點:銅是AI被忽視的瓶頸——市場熱議GPU之際,爲每座數據中心佈線的銅正從供應過剩轉爲供應短缺。
Unhidea觀點:紫金的優勢在於供不應求之際擴大產量——冶煉廠減產時它仍在增產;在供應緊張的市場中,噸數勝過估值倍數。
風險:宏觀經濟疲軟;美國釋放庫存;Kamoa-Kakula項目受擾。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
紫金礦業(2899.HK):美國銀行維持買入評級——中國銅需求回暖,冶煉廠減產
- 中國銅需求增速預計在2027年回升至1.6–1.8%,由電子產品(增長超過10%)和機械/國防(增長6–7%)帶動;房地產仍然疲軟。
- 冶煉廠減產使精煉銅產量增速減半,從約60萬噸降至不超過30萬噸;SMM中性預期爲約13,000美元/噸,美國釋放庫存則帶來價格跌向10,000美元/噸的風險。
- 紫金維持2026年指引(不包括Kamoa-Kakula約5萬噸的虧損);現有礦山2028年產量爲140萬至145萬噸,低於150萬噸的目標;非洲項目增產超過30萬噸。
- AI基礎設施是關鍵增量:到2027年底,M8 CCL需求將增長至原來的三倍,從每月250萬增至750萬;磷化銦(InP)佔雲南鍺業淨利潤的70%以上,利潤率超過65%,訂單已鎖定至2027年。
- 紫金評級爲買入,11月17日收盤價爲25.98港元;本報告未重申目標價。
Unhidea觀點:銅是AI被忽視的瓶頸——市場熱議GPU之際,爲每座數據中心佈線的銅正從供應過剩轉爲供應短缺。
Unhidea觀點:紫金的優勢在於供不應求之際擴大產量——冶煉廠減產時它仍在增產;在供應緊張的市場中,噸數勝過估值倍數。
風險:宏觀經濟疲軟;美國釋放庫存;Kamoa-Kakula項目受擾。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
- 中國銅需求增速預計在2027年回升至1.6–1.8%,由電子產品(增長超過10%)和機械/國防(增長6–7%)帶動;房地產仍然疲軟。
- 冶煉廠減產使精煉銅產量增速減半,從約60萬噸降至不超過30萬噸;SMM中性預期爲約13,000美元/噸,美國釋放庫存則帶來價格跌向10,000美元/噸的風險。
- 紫金維持2026年指引(不包括Kamoa-Kakula約5萬噸的虧損);現有礦山2028年產量爲140萬至145萬噸,低於150萬噸的目標;非洲項目增產超過30萬噸。
- AI基礎設施是關鍵增量:到2027年底,M8 CCL需求將增長至原來的三倍,從每月250萬增至750萬;磷化銦(InP)佔雲南鍺業淨利潤的70%以上,利潤率超過65%,訂單已鎖定至2027年。
- 紫金評級爲買入,11月17日收盤價爲25.98港元;本報告未重申目標價。
Unhidea觀點:銅是AI被忽視的瓶頸——市場熱議GPU之際,爲每座數據中心佈線的銅正從供應過剩轉爲供應短缺。
Unhidea觀點:紫金的優勢在於供不應求之際擴大產量——冶煉廠減產時它仍在增產;在供應緊張的市場中,噸數勝過估值倍數。
風險:宏觀經濟疲軟;美國釋放庫存;Kamoa-Kakula項目受擾。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
53
·
--
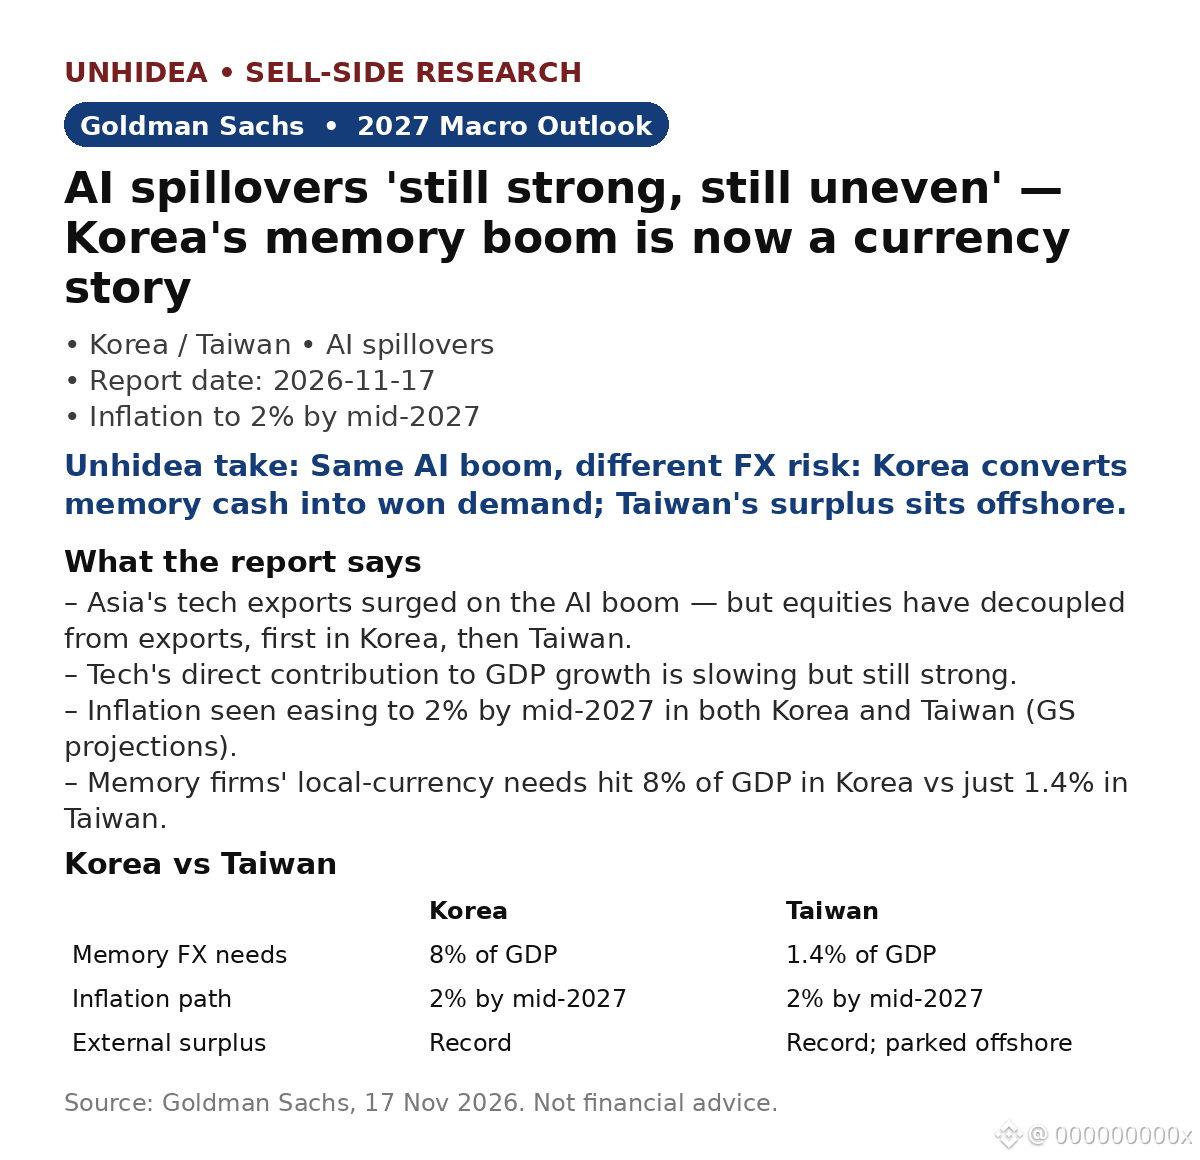
AI溢出效應“依然強勁,但仍不均衡”:高盛2027年韓國/臺灣展望——三星的存儲器紅利如今已成爲匯率故事
- 亞洲科技出口受AI熱潮推動大幅增長,但股市表現已與出口脫鉤——先是韓國,隨後是臺灣。指數已不再能準確反映出口週期。
- 科技業對GDP增長的直接貢獻正在放緩,但依然強勁。預計到2027年年中,韓國和臺灣的通脹率都將降至2%(高盛預測)。
- 存儲器企業的本幣需求在韓國達到GDP的8%,而臺灣僅爲1.4%。韓國將這波熱潮轉化爲韓元需求;臺灣創紀錄的貿易順差則被留存在海外。
- 報告發布後的市場消息:英偉達第三財季營收爲1,158.4億美元,同比增長103%,高於約1,090億美元的預期;公司預計營收約1,300億美元,高於約1,250億美元的預期——財報公佈後,三星和SK海力士股價在韓國上漲。
Unhidea的觀點:脫鉤本身就是信號——如今韓國/臺灣股市交易的是AI敘事和存儲器價格,而不是出口量。出口數據疲軟不再意味着指數表現疲軟,反之亦然。
Unhidea的觀點:8%與1.4%的差距纔是真正的交易機會。存儲器收入兌換成本幣,帶來結構性的韓元需求;而臺灣的順差則留存在海外——同一波AI熱潮,卻帶來相反的匯率壓力。關注韓元,而不只是KOSPI指數。
風險:AI資本開支削減、存儲器價格反轉、匯率波動、中美出口管制。
來源:高盛,2026年11月17日。不構成財務建議。
AI溢出效應“依然強勁,但仍不均衡”:高盛2027年韓國/臺灣展望——三星的存儲器紅利如今已成爲匯率故事
- 亞洲科技出口受AI熱潮推動大幅增長,但股市表現已與出口脫鉤——先是韓國,隨後是臺灣。指數已不再能準確反映出口週期。
- 科技業對GDP增長的直接貢獻正在放緩,但依然強勁。預計到2027年年中,韓國和臺灣的通脹率都將降至2%(高盛預測)。
- 存儲器企業的本幣需求在韓國達到GDP的8%,而臺灣僅爲1.4%。韓國將這波熱潮轉化爲韓元需求;臺灣創紀錄的貿易順差則被留存在海外。
- 報告發布後的市場消息:英偉達第三財季營收爲1,158.4億美元,同比增長103%,高於約1,090億美元的預期;公司預計營收約1,300億美元,高於約1,250億美元的預期——財報公佈後,三星和SK海力士股價在韓國上漲。
Unhidea的觀點:脫鉤本身就是信號——如今韓國/臺灣股市交易的是AI敘事和存儲器價格,而不是出口量。出口數據疲軟不再意味着指數表現疲軟,反之亦然。
Unhidea的觀點:8%與1.4%的差距纔是真正的交易機會。存儲器收入兌換成本幣,帶來結構性的韓元需求;而臺灣的順差則留存在海外——同一波AI熱潮,卻帶來相反的匯率壓力。關注韓元,而不只是KOSPI指數。
風險:AI資本開支削減、存儲器價格反轉、匯率波動、中美出口管制。
來源:高盛,2026年11月17日。不構成財務建議。
- 亞洲科技出口受AI熱潮推動大幅增長,但股市表現已與出口脫鉤——先是韓國,隨後是臺灣。指數已不再能準確反映出口週期。
- 科技業對GDP增長的直接貢獻正在放緩,但依然強勁。預計到2027年年中,韓國和臺灣的通脹率都將降至2%(高盛預測)。
- 存儲器企業的本幣需求在韓國達到GDP的8%,而臺灣僅爲1.4%。韓國將這波熱潮轉化爲韓元需求;臺灣創紀錄的貿易順差則被留存在海外。
- 報告發布後的市場消息:英偉達第三財季營收爲1,158.4億美元,同比增長103%,高於約1,090億美元的預期;公司預計營收約1,300億美元,高於約1,250億美元的預期——財報公佈後,三星和SK海力士股價在韓國上漲。
Unhidea的觀點:脫鉤本身就是信號——如今韓國/臺灣股市交易的是AI敘事和存儲器價格,而不是出口量。出口數據疲軟不再意味着指數表現疲軟,反之亦然。
Unhidea的觀點:8%與1.4%的差距纔是真正的交易機會。存儲器收入兌換成本幣,帶來結構性的韓元需求;而臺灣的順差則留存在海外——同一波AI熱潮,卻帶來相反的匯率壓力。關注韓元,而不只是KOSPI指數。
風險:AI資本開支削減、存儲器價格反轉、匯率波動、中美出口管制。
來源:高盛,2026年11月17日。不構成財務建議。
420
·
--
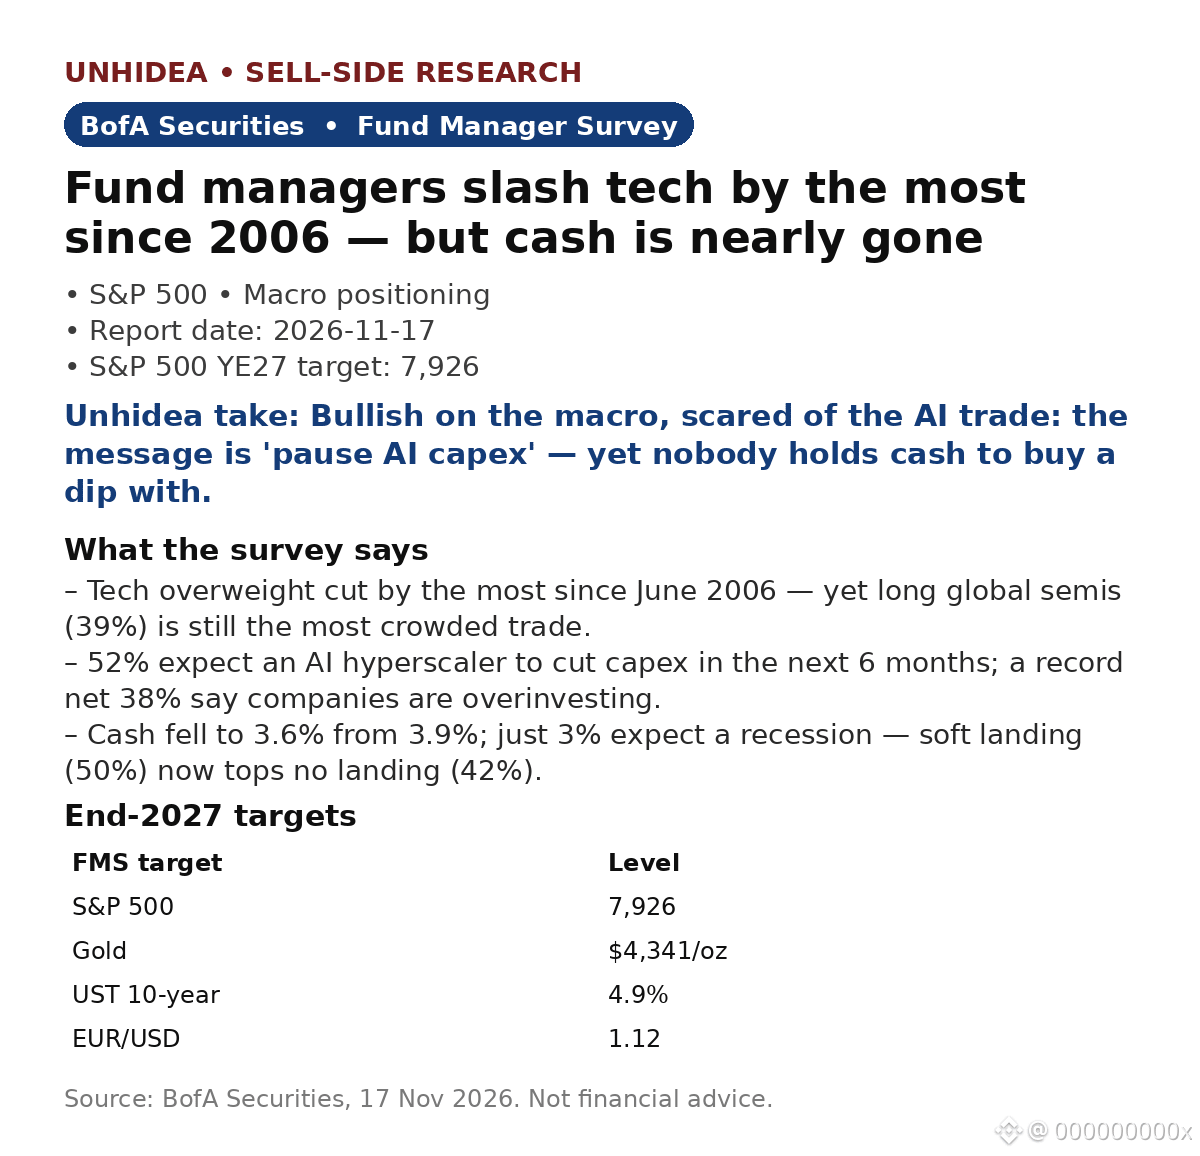
$SPX:美國銀行基金經理調查——科技股遭遇自2006年以來最大幅度減持,但現金幾乎耗盡
- 投資者將科技股超配比例削減至2006年6月以來最低,但做多全球半導體(39%)仍是最擁擠的交易。調查於11月6日至12日進行,涵蓋193位管理者,管理資產總額爲5260億美元。
- 52%預計未來6個月內某家AI超大規模雲服務商將削減資本支出;創紀錄的淨38%認爲企業投資過度;僅16%希望企業增加資本支出,爲2020年5月以來最低。
- 現金比例從3.9%降至3.6%。美國銀行繼續採取戰術性避險立場:市場“恐慌”還不夠,尚不足以買入。僅3%預計會出現衰退;軟着陸(50%)自6月以來首次超過無着陸(42%)。
- 主要尾部風險:AI泡沫(34%)和超大規模雲服務商信用事件(31%)。38%認爲AI超大規模雲服務商債券最有可能引發系統性信用事件,高於私人信貸(30%)。
- 2027年底目標:標普500指數7,926點,黃金每盎司4,341美元——淨23%的受訪者認爲黃金被低估,創紀錄高位——美國10年期國債收益率4.9%,歐元/美元1.12。
Unhidea觀點:這項調查一邊看多AI交易,一邊又對此感到擔憂——39%認爲半導體多頭倉位擁擠,52%預計資本支出將削減。這是倉位陷阱,不是泡沫判斷:最令人痛苦的交易風險是資本支出相關頭條,而非經濟衰退。
Unhidea觀點:現金比例僅爲3.6%,意味着幾乎沒有備用資金。美國銀行所說的“恐慌還不夠,尚不足以買入”,意味着如果市場接下來繼續下跌,就沒有天然買家承接。關注那52%:只要有一家超大規模雲服務商稍有遲疑,預期就可能自我實現。
風險:AI資本支出削減、超大規模雲服務商信用壓力、通脹頑固、債券收益率無序上升。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
$SPX :美國銀行基金經理調查——科技股遭遇自2006年以來最大幅度減持,但現金幾乎耗盡
- 投資者將科技股超配比例削減至2006年6月以來最低,但做多全球半導體(39%)仍是最擁擠的交易。調查於11月6日至12日進行,涵蓋193位管理者,管理資產總額爲5260億美元。
- 52%預計未來6個月內某家AI超大規模雲服務商將削減資本支出;創紀錄的淨38%認爲企業投資過度;僅16%希望企業增加資本支出,爲2020年5月以來最低。
- 現金比例從3.9%降至3.6%。美國銀行繼續採取戰術性避險立場:市場“恐慌”還不夠,尚不足以買入。僅3%預計會出現衰退;軟着陸(50%)自6月以來首次超過無着陸(42%)。
- 主要尾部風險:AI泡沫(34%)和超大規模雲服務商信用事件(31%)。38%認爲AI超大規模雲服務商債券最有可能引發系統性信用事件,高於私人信貸(30%)。
- 2027年底目標:標普500指數7,926點,黃金每盎司4,341美元——淨23%的受訪者認爲黃金被低估,創紀錄高位——美國10年期國債收益率4.9%,歐元/美元1.12。
Unhidea觀點:這項調查一邊看多AI交易,一邊又對此感到擔憂——39%認爲半導體多頭倉位擁擠,52%預計資本支出將削減。這是倉位陷阱,不是泡沫判斷:最令人痛苦的交易風險是資本支出相關頭條,而非經濟衰退。
Unhidea觀點:現金比例僅爲3.6%,意味着幾乎沒有備用資金。美國銀行所說的“恐慌還不夠,尚不足以買入”,意味着如果市場接下來繼續下跌,就沒有天然買家承接。關注那52%:只要有一家超大規模雲服務商稍有遲疑,預期就可能自我實現。
風險:AI資本支出削減、超大規模雲服務商信用壓力、通脹頑固、債券收益率無序上升。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
- 投資者將科技股超配比例削減至2006年6月以來最低,但做多全球半導體(39%)仍是最擁擠的交易。調查於11月6日至12日進行,涵蓋193位管理者,管理資產總額爲5260億美元。
- 52%預計未來6個月內某家AI超大規模雲服務商將削減資本支出;創紀錄的淨38%認爲企業投資過度;僅16%希望企業增加資本支出,爲2020年5月以來最低。
- 現金比例從3.9%降至3.6%。美國銀行繼續採取戰術性避險立場:市場“恐慌”還不夠,尚不足以買入。僅3%預計會出現衰退;軟着陸(50%)自6月以來首次超過無着陸(42%)。
- 主要尾部風險:AI泡沫(34%)和超大規模雲服務商信用事件(31%)。38%認爲AI超大規模雲服務商債券最有可能引發系統性信用事件,高於私人信貸(30%)。
- 2027年底目標:標普500指數7,926點,黃金每盎司4,341美元——淨23%的受訪者認爲黃金被低估,創紀錄高位——美國10年期國債收益率4.9%,歐元/美元1.12。
Unhidea觀點:這項調查一邊看多AI交易,一邊又對此感到擔憂——39%認爲半導體多頭倉位擁擠,52%預計資本支出將削減。這是倉位陷阱,不是泡沫判斷:最令人痛苦的交易風險是資本支出相關頭條,而非經濟衰退。
Unhidea觀點:現金比例僅爲3.6%,意味着幾乎沒有備用資金。美國銀行所說的“恐慌還不夠,尚不足以買入”,意味着如果市場接下來繼續下跌,就沒有天然買家承接。關注那52%:只要有一家超大規模雲服務商稍有遲疑,預期就可能自我實現。
風險:AI資本支出削減、超大規模雲服務商信用壓力、通脹頑固、債券收益率無序上升。
來源:美國銀行證券,2026年11月17日。本文不構成財務建議。
180
·
--
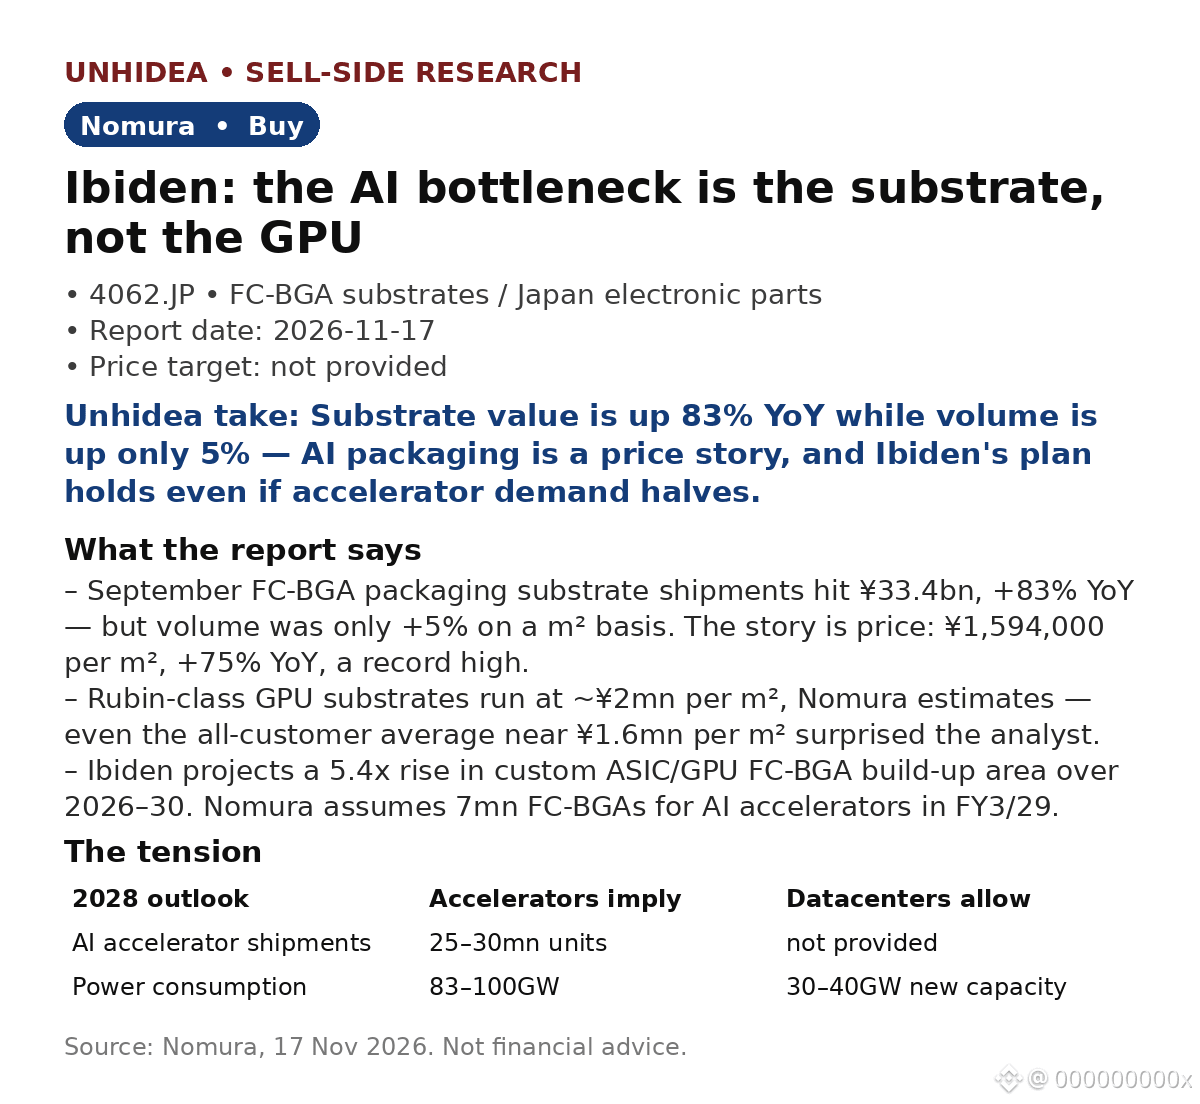
Ibiden(4062.JP):AI 的瓶頸不在 GPU,而在 GPU 所依託的基板。野村證券給予買入評級,日本 FC-BGA 出貨量同比大增 83%。
- 9 月 FC-BGA 基板銷售額達 334 億日元,同比 +83%,但出貨量僅 +5%。關鍵在於價格:每平方米 1,594,000 日元,同比 +75%,創下紀錄。Rubin 級 GPU 基板的價格約爲每平方米 200 萬日元。
- 野村證券警示:2028 年加速器預測出貨量爲 2,500 萬至 3,000 萬顆,對應功耗達 83–100GW;但市場預計 2028 年美國數據中心新增容量僅爲 30–40GW。供需之間必有一方需要調整。
- Ibiden 預計,2026–30 年 FC-BGA 增層面積將增長 5.4 倍;野村證券預計 FY3/29 AI 加速器用 FC-BGA 出貨量爲 700 萬片,即使加速器出貨量減半至 1,250 萬至 1,500 萬顆,這一目標仍可實現。
- 報告發布後:NVDA 於 11 月 17 日公佈 FQ3 業績——營收 1,158.4 億美元,同比 +103%;Q4 營收指引約爲 1,300 億美元——這爲需求與施工延誤擔憂之間的博弈提供了新信息。(報告發布後的市場消息。)
Unhidea 觀點:AI 需求在基板環節轉化爲有價格的實體瓶頸——價值增長依靠價格和產品組合,而非出貨量。
Unhidea 觀點:問題已不再是 AI 需求是否存在,而是數據中心能否及時建成以承載這些需求。Ibiden 的計劃是按照悲觀情景制定的。
風險:競爭對手擴產可能緩解供需緊張;數據中心建設延誤及美國出口管制趨嚴可能削弱加速器需求。
來源:野村證券,2026 年 11 月 17 日。本文不構成投資建議。
Ibiden(4062.JP):AI 的瓶頸不在 GPU,而在 GPU 所依託的基板。野村證券給予買入評級,日本 FC-BGA 出貨量同比大增 83%。
- 9 月 FC-BGA 基板銷售額達 334 億日元,同比 +83%,但出貨量僅 +5%。關鍵在於價格:每平方米 1,594,000 日元,同比 +75%,創下紀錄。Rubin 級 GPU 基板的價格約爲每平方米 200 萬日元。
- 野村證券警示:2028 年加速器預測出貨量爲 2,500 萬至 3,000 萬顆,對應功耗達 83–100GW;但市場預計 2028 年美國數據中心新增容量僅爲 30–40GW。供需之間必有一方需要調整。
- Ibiden 預計,2026–30 年 FC-BGA 增層面積將增長 5.4 倍;野村證券預計 FY3/29 AI 加速器用 FC-BGA 出貨量爲 700 萬片,即使加速器出貨量減半至 1,250 萬至 1,500 萬顆,這一目標仍可實現。
- 報告發布後:NVDA 於 11 月 17 日公佈 FQ3 業績——營收 1,158.4 億美元,同比 +103%;Q4 營收指引約爲 1,300 億美元——這爲需求與施工延誤擔憂之間的博弈提供了新信息。(報告發布後的市場消息。)
Unhidea 觀點:AI 需求在基板環節轉化爲有價格的實體瓶頸——價值增長依靠價格和產品組合,而非出貨量。
Unhidea 觀點:問題已不再是 AI 需求是否存在,而是數據中心能否及時建成以承載這些需求。Ibiden 的計劃是按照悲觀情景制定的。
風險:競爭對手擴產可能緩解供需緊張;數據中心建設延誤及美國出口管制趨嚴可能削弱加速器需求。
來源:野村證券,2026 年 11 月 17 日。本文不構成投資建議。
- 9 月 FC-BGA 基板銷售額達 334 億日元,同比 +83%,但出貨量僅 +5%。關鍵在於價格:每平方米 1,594,000 日元,同比 +75%,創下紀錄。Rubin 級 GPU 基板的價格約爲每平方米 200 萬日元。
- 野村證券警示:2028 年加速器預測出貨量爲 2,500 萬至 3,000 萬顆,對應功耗達 83–100GW;但市場預計 2028 年美國數據中心新增容量僅爲 30–40GW。供需之間必有一方需要調整。
- Ibiden 預計,2026–30 年 FC-BGA 增層面積將增長 5.4 倍;野村證券預計 FY3/29 AI 加速器用 FC-BGA 出貨量爲 700 萬片,即使加速器出貨量減半至 1,250 萬至 1,500 萬顆,這一目標仍可實現。
- 報告發布後:NVDA 於 11 月 17 日公佈 FQ3 業績——營收 1,158.4 億美元,同比 +103%;Q4 營收指引約爲 1,300 億美元——這爲需求與施工延誤擔憂之間的博弈提供了新信息。(報告發布後的市場消息。)
Unhidea 觀點:AI 需求在基板環節轉化爲有價格的實體瓶頸——價值增長依靠價格和產品組合,而非出貨量。
Unhidea 觀點:問題已不再是 AI 需求是否存在,而是數據中心能否及時建成以承載這些需求。Ibiden 的計劃是按照悲觀情景制定的。
風險:競爭對手擴產可能緩解供需緊張;數據中心建設延誤及美國出口管制趨嚴可能削弱加速器需求。
來源:野村證券,2026 年 11 月 17 日。本文不構成投資建議。
245
·
--
查看翻譯
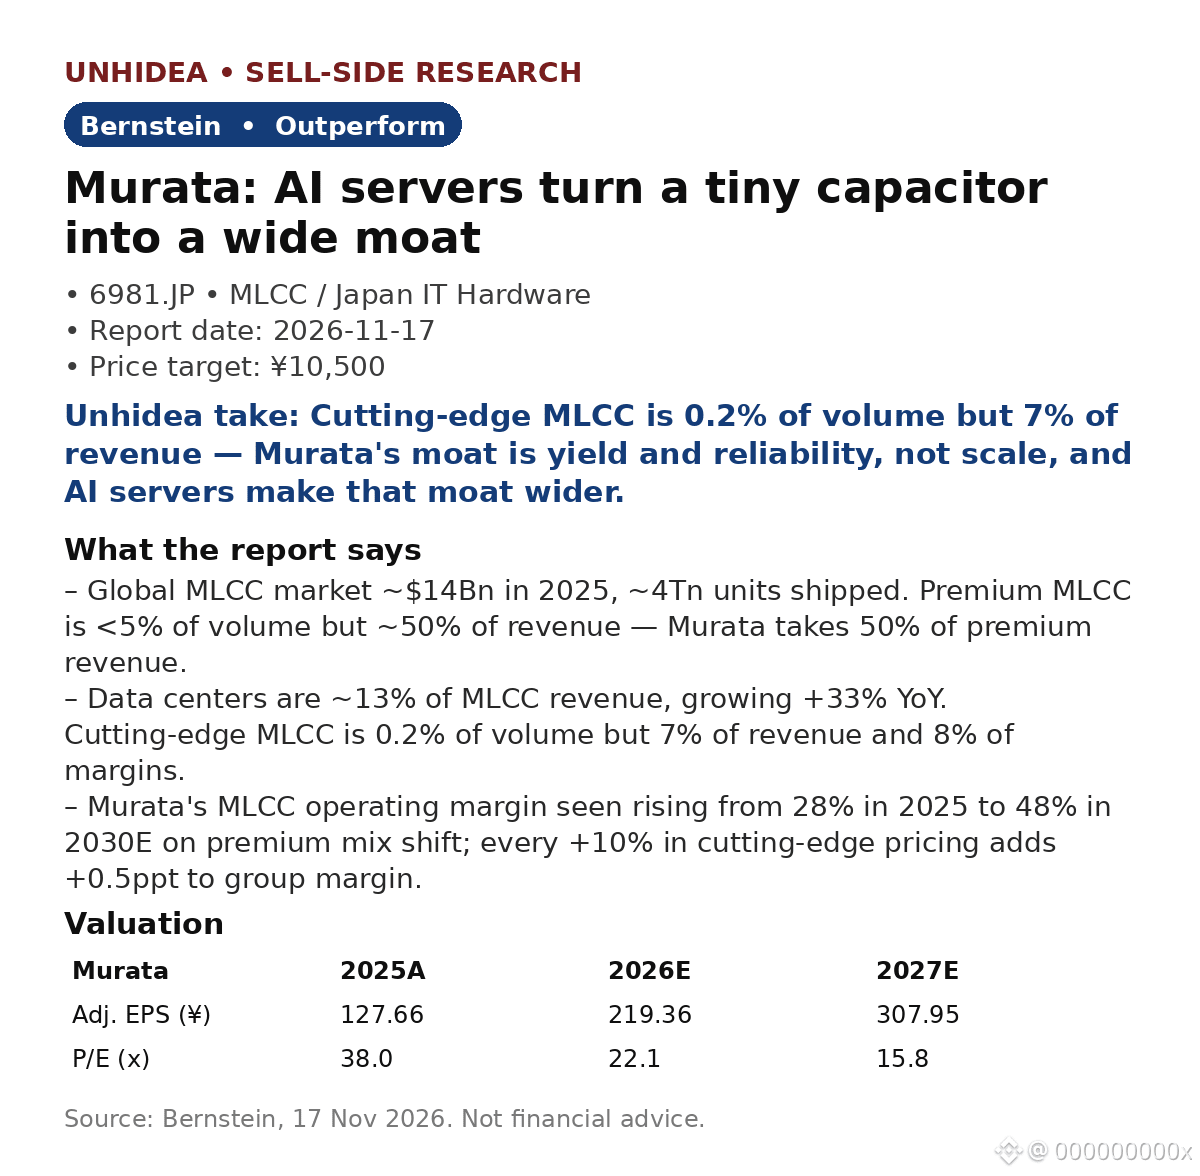
Murata (6981.JP): Bernstein sees ~116% upside as AI servers turn a tiny capacitor into a wide moat — target ¥10,500 vs ¥4,855 close on 16 Nov
- Global MLCC market ~$14Bn in 2025, ~4Tn units. Premium is <5% of volume but ~50% of revenue — Murata takes 50% of premium revenue.
- Data centers ~13% of MLCC revenue, +33% YoY. Cutting-edge MLCC: 0.2% of volume, 7% of revenue, 8% of margins.
- AI-server MLCCs must run 24/7 for 10+ years, near-zero failure — a bar most rivals can't clear at scale. Murata R&D is 9% of revenue vs 4–7% for peers.
- Mix shift, not price hikes: Murata MLCC margin seen rising 28% (2025) to 48% (2030E). Every +10% in cutting-edge pricing adds +0.5ppt to group margin.
- Bernstein reiterates Outperform, TP ¥10,500. Adj. EPS ¥219.36 in 2026E (+72% YoY), ¥307.95 in 2027E; 22.1x / 15.8x P/E.
Unhidea take: the AI trade has been about GPUs and power — but every AI rack needs thousands of MLCCs that cannot fail. Murata's edge is the boring, certified, yield-driven kind that compounds quietly.
Unhidea take: Bernstein gives China 5–10 years to catch up on premium MLCC. The AI buildout is happening now, and the qualified supplier list is effectively two names long — that window is the investment case.
Risks: Murata is reluctant to raise prices, so mix shift must deliver; an AI server slowdown or weak smartphone/auto demand would hit volumes.
Source: Bernstein, 17 Nov 2026. Not financial advice.
Murata (6981.JP): Bernstein sees ~116% upside as AI servers turn a tiny capacitor into a wide moat — target ¥10,500 vs ¥4,855 close on 16 Nov
- Global MLCC market ~$14Bn in 2025, ~4Tn units. Premium is <5% of volume but ~50% of revenue — Murata takes 50% of premium revenue.
- Data centers ~13% of MLCC revenue, +33% YoY. Cutting-edge MLCC: 0.2% of volume, 7% of revenue, 8% of margins.
- AI-server MLCCs must run 24/7 for 10+ years, near-zero failure — a bar most rivals can't clear at scale. Murata R&D is 9% of revenue vs 4–7% for peers.
- Mix shift, not price hikes: Murata MLCC margin seen rising 28% (2025) to 48% (2030E). Every +10% in cutting-edge pricing adds +0.5ppt to group margin.
- Bernstein reiterates Outperform, TP ¥10,500. Adj. EPS ¥219.36 in 2026E (+72% YoY), ¥307.95 in 2027E; 22.1x / 15.8x P/E.
Unhidea take: the AI trade has been about GPUs and power — but every AI rack needs thousands of MLCCs that cannot fail. Murata's edge is the boring, certified, yield-driven kind that compounds quietly.
Unhidea take: Bernstein gives China 5–10 years to catch up on premium MLCC. The AI buildout is happening now, and the qualified supplier list is effectively two names long — that window is the investment case.
Risks: Murata is reluctant to raise prices, so mix shift must deliver; an AI server slowdown or weak smartphone/auto demand would hit volumes.
Source: Bernstein, 17 Nov 2026. Not financial advice.
- Global MLCC market ~$14Bn in 2025, ~4Tn units. Premium is <5% of volume but ~50% of revenue — Murata takes 50% of premium revenue.
- Data centers ~13% of MLCC revenue, +33% YoY. Cutting-edge MLCC: 0.2% of volume, 7% of revenue, 8% of margins.
- AI-server MLCCs must run 24/7 for 10+ years, near-zero failure — a bar most rivals can't clear at scale. Murata R&D is 9% of revenue vs 4–7% for peers.
- Mix shift, not price hikes: Murata MLCC margin seen rising 28% (2025) to 48% (2030E). Every +10% in cutting-edge pricing adds +0.5ppt to group margin.
- Bernstein reiterates Outperform, TP ¥10,500. Adj. EPS ¥219.36 in 2026E (+72% YoY), ¥307.95 in 2027E; 22.1x / 15.8x P/E.
Unhidea take: the AI trade has been about GPUs and power — but every AI rack needs thousands of MLCCs that cannot fail. Murata's edge is the boring, certified, yield-driven kind that compounds quietly.
Unhidea take: Bernstein gives China 5–10 years to catch up on premium MLCC. The AI buildout is happening now, and the qualified supplier list is effectively two names long — that window is the investment case.
Risks: Murata is reluctant to raise prices, so mix shift must deliver; an AI server slowdown or weak smartphone/auto demand would hit volumes.
Source: Bernstein, 17 Nov 2026. Not financial advice.
4
·
--
查看翻譯
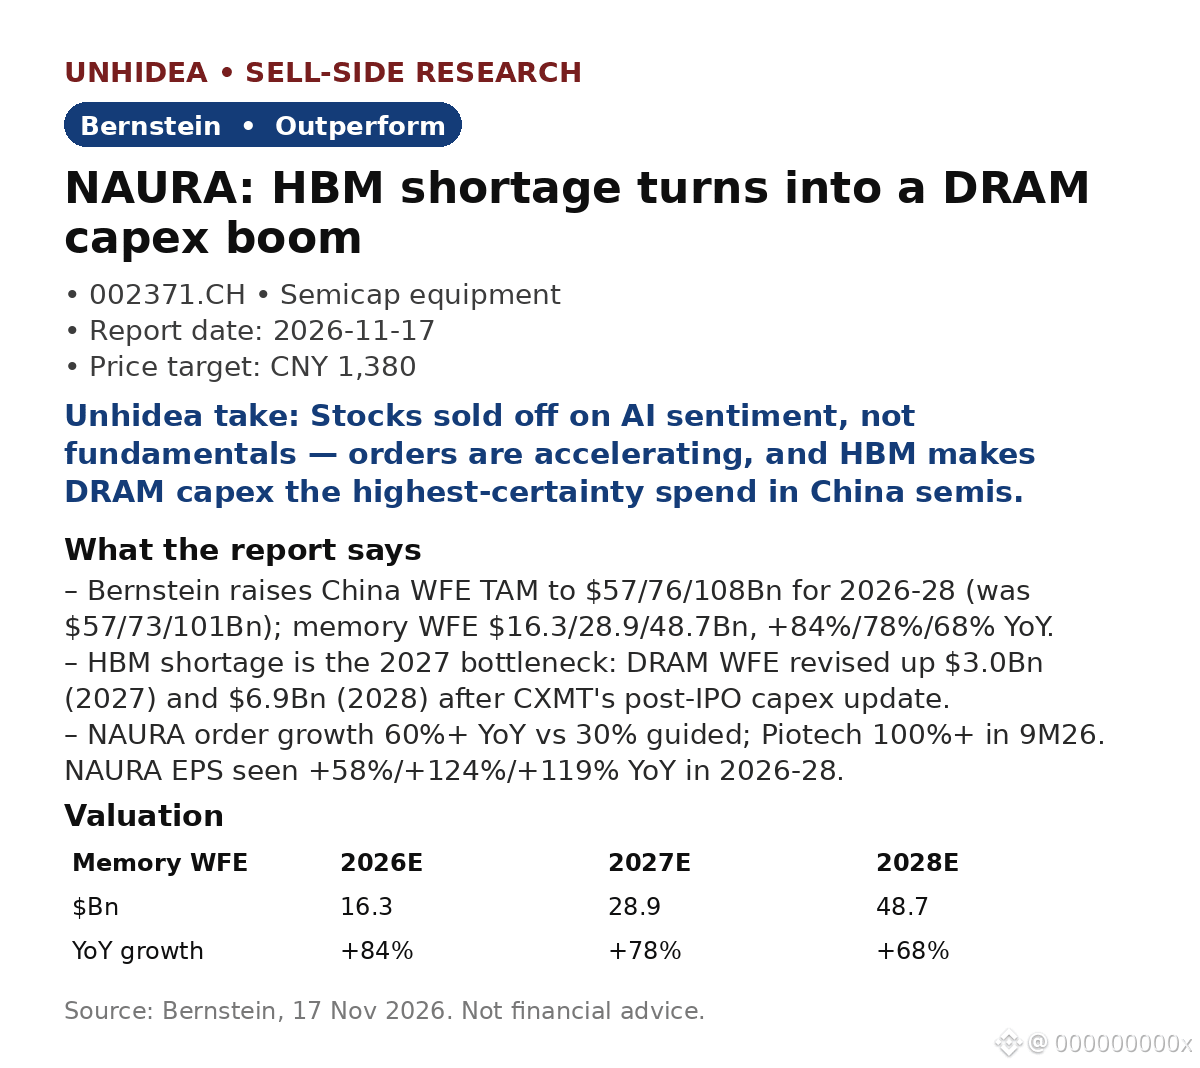
$NAURA: Bernstein's top pick as China's HBM shortage turns into a DRAM capex boom — target CNY 1,380 implies ~153% upside
- Bernstein raises China WFE TAM to $57/76/108Bn for 2026-28 (was $57/73/101Bn); memory WFE $16.3/28.9/48.7Bn, growing +84%/78%/68% YoY.
- HBM shortage is the 2027 bottleneck: DRAM WFE revised up $3.0Bn (2027) and $6.9Bn (2028) after CXMT's post-IPO capex update; YMTC DRAM expansion starts in 2027.
- NAURA order growth is 60%+ YoY vs 30% guided; EPS seen rising +58%/+124%/+119% YoY in 2026-28. Piotech orders 100%+ in 9M26.
- Localization steps up: mature-logic fabs' local-tool share jumps from <20% to 50%+ next year; Bernstein sees localization at 36%/49% in 2027/28.
- NAURA rated Outperform, target CNY 1,380 vs CNY 546.39 close on 16 Nov, at 32x 2028E P/E. AMEC CNY 660 and Piotech CNY 1,200, both Outperform.
Unhidea take: the market is pricing AI sentiment, not the order book — 60%+ order growth in a sector Bernstein says is "clearly not trading on fundamentals" is the disconnect; strong 1Q27 orders would be the re-rating trigger.
Unhidea take: HBM is the choke point that makes DRAM capex the most certain spend in semis — memory capacity can't be deferred if China wants AI self-sufficiency, so WFE is the purest localization play and NAURA's broadest portfolio captures the most of it.
Risks: no strong catalyst in 4Q26, near-term volatility; global AI sentiment.
Source: Bernstein, 17 Nov 2026. Not financial advice.
$NAURA: Bernstein's top pick as China's HBM shortage turns into a DRAM capex boom — target CNY 1,380 implies ~153% upside
- Bernstein raises China WFE TAM to $57/76/108Bn for 2026-28 (was $57/73/101Bn); memory WFE $16.3/28.9/48.7Bn, growing +84%/78%/68% YoY.
- HBM shortage is the 2027 bottleneck: DRAM WFE revised up $3.0Bn (2027) and $6.9Bn (2028) after CXMT's post-IPO capex update; YMTC DRAM expansion starts in 2027.
- NAURA order growth is 60%+ YoY vs 30% guided; EPS seen rising +58%/+124%/+119% YoY in 2026-28. Piotech orders 100%+ in 9M26.
- Localization steps up: mature-logic fabs' local-tool share jumps from <20% to 50%+ next year; Bernstein sees localization at 36%/49% in 2027/28.
- NAURA rated Outperform, target CNY 1,380 vs CNY 546.39 close on 16 Nov, at 32x 2028E P/E. AMEC CNY 660 and Piotech CNY 1,200, both Outperform.
Unhidea take: the market is pricing AI sentiment, not the order book — 60%+ order growth in a sector Bernstein says is "clearly not trading on fundamentals" is the disconnect; strong 1Q27 orders would be the re-rating trigger.
Unhidea take: HBM is the choke point that makes DRAM capex the most certain spend in semis — memory capacity can't be deferred if China wants AI self-sufficiency, so WFE is the purest localization play and NAURA's broadest portfolio captures the most of it.
Risks: no strong catalyst in 4Q26, near-term volatility; global AI sentiment.
Source: Bernstein, 17 Nov 2026. Not financial advice.
- Bernstein raises China WFE TAM to $57/76/108Bn for 2026-28 (was $57/73/101Bn); memory WFE $16.3/28.9/48.7Bn, growing +84%/78%/68% YoY.
- HBM shortage is the 2027 bottleneck: DRAM WFE revised up $3.0Bn (2027) and $6.9Bn (2028) after CXMT's post-IPO capex update; YMTC DRAM expansion starts in 2027.
- NAURA order growth is 60%+ YoY vs 30% guided; EPS seen rising +58%/+124%/+119% YoY in 2026-28. Piotech orders 100%+ in 9M26.
- Localization steps up: mature-logic fabs' local-tool share jumps from <20% to 50%+ next year; Bernstein sees localization at 36%/49% in 2027/28.
- NAURA rated Outperform, target CNY 1,380 vs CNY 546.39 close on 16 Nov, at 32x 2028E P/E. AMEC CNY 660 and Piotech CNY 1,200, both Outperform.
Unhidea take: the market is pricing AI sentiment, not the order book — 60%+ order growth in a sector Bernstein says is "clearly not trading on fundamentals" is the disconnect; strong 1Q27 orders would be the re-rating trigger.
Unhidea take: HBM is the choke point that makes DRAM capex the most certain spend in semis — memory capacity can't be deferred if China wants AI self-sufficiency, so WFE is the purest localization play and NAURA's broadest portfolio captures the most of it.
Risks: no strong catalyst in 4Q26, near-term volatility; global AI sentiment.
Source: Bernstein, 17 Nov 2026. Not financial advice.
2
·
--
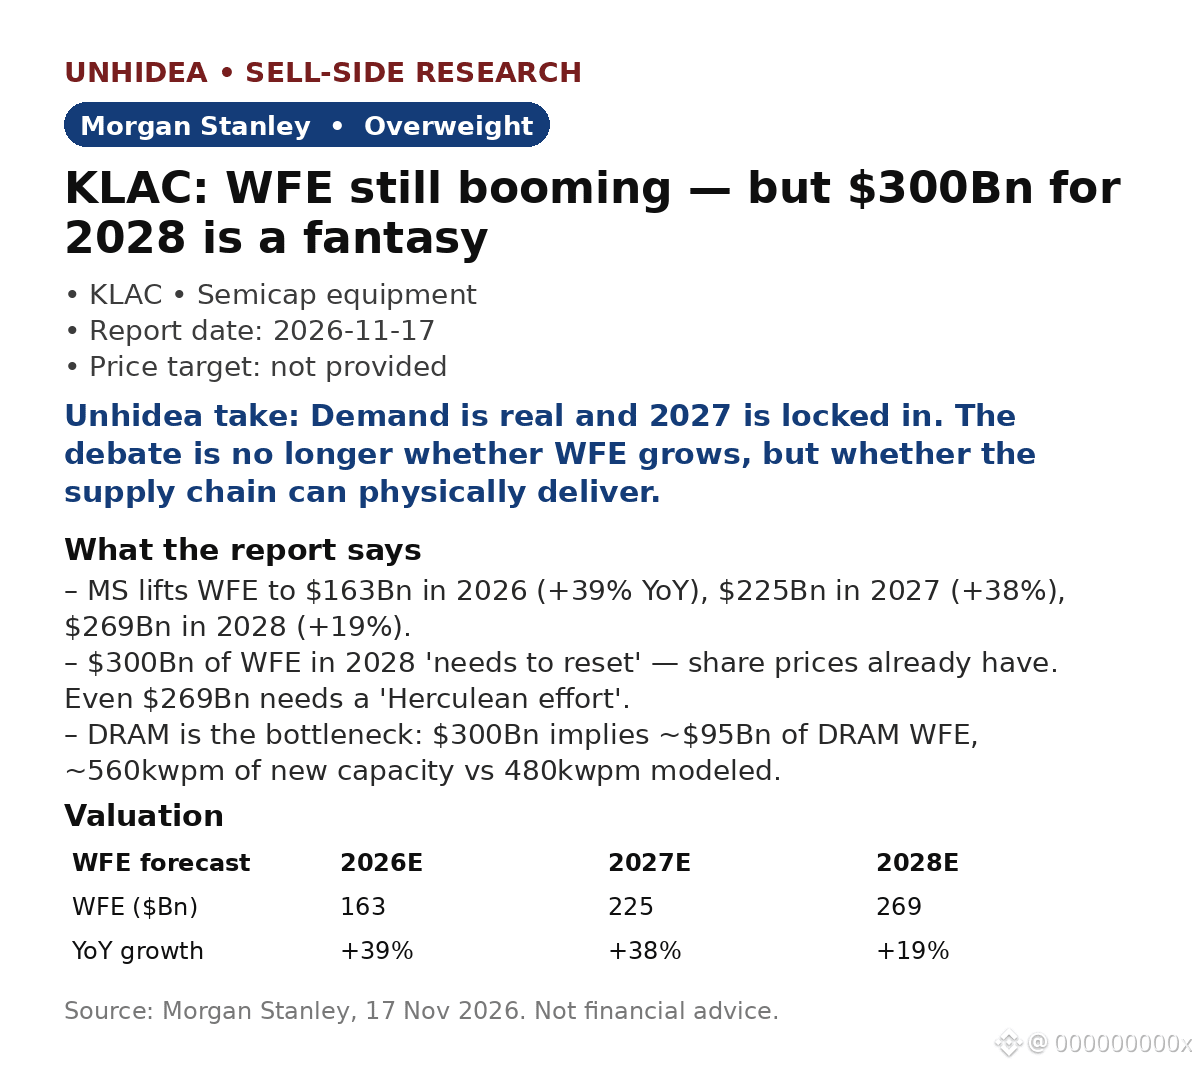
$KLAC:摩根士丹利稱,芯片設備熱潮確實存在——但2028年3000億美元WFE的夢想需要重新校準
- MS將WFE預期上調至2026年的1630億美元(同比增長39%)、2027年的2250億美元(增長38%)和2028年的2690億美元(增長19%),此前預期爲2540億美元。
- 2028年3000億美元的目標“需要重新校準,股價已經先行反映了這一點”:3年內將產能擴大2.5倍並不容易,而且OEM廠商已經因零部件短缺而無法按時交貨。
- DRAM是瓶頸:3000億美元意味着DRAM WFE約爲950億美元,需要新增約56萬片/月的產能,而模型預測爲48萬片/月;NAND和成熟製程邏輯芯片則需要增長超過40%。
- 出貨量目前對應的WFE年化規模爲2000億至2050億美元;2027年的樂觀情景已“逐步成爲現實”,包括英特爾支出超過200億美元,以及新增約50萬片/月的DRAM綠地項目產能。
- MS給予KLAC“增持”評級(本報告未給出目標價);對行業的看法爲“與大盤持平”。
- 報告發布後:NVIDIA公佈的第三財季業績超出預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:重新校準的是預期,而非需求——2028年2690億美元仍代表19%的增長;股價下跌是因爲此前按3000億美元的預期定價,而不是因爲晶圓廠停止下單。
Unhidea觀點:瓶頸已經從需求轉向物理條件——潔淨室空間、零部件,以及每月48萬片與56萬片產能之間的差距。每增加一片晶圓都需要更多檢測,因此過程控制需求會隨着產能爬坡而同步增長。
風險:零部件短缺、DRAM提前拉貨效應消退、估值倍數進一步壓縮。
來源:摩根士丹利,2026年11月17日。報告發布後新聞:CNBC。本文不構成投資建議。
$KLAC :摩根士丹利稱,芯片設備熱潮確實存在——但2028年3000億美元WFE的夢想需要重新校準
- MS將WFE預期上調至2026年的1630億美元(同比增長39%)、2027年的2250億美元(增長38%)和2028年的2690億美元(增長19%),此前預期爲2540億美元。
- 2028年3000億美元的目標“需要重新校準,股價已經先行反映了這一點”:3年內將產能擴大2.5倍並不容易,而且OEM廠商已經因零部件短缺而無法按時交貨。
- DRAM是瓶頸:3000億美元意味着DRAM WFE約爲950億美元,需要新增約56萬片/月的產能,而模型預測爲48萬片/月;NAND和成熟製程邏輯芯片則需要增長超過40%。
- 出貨量目前對應的WFE年化規模爲2000億至2050億美元;2027年的樂觀情景已“逐步成爲現實”,包括英特爾支出超過200億美元,以及新增約50萬片/月的DRAM綠地項目產能。
- MS給予KLAC“增持”評級(本報告未給出目標價);對行業的看法爲“與大盤持平”。
- 報告發布後:NVIDIA公佈的第三財季業績超出預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:重新校準的是預期,而非需求——2028年2690億美元仍代表19%的增長;股價下跌是因爲此前按3000億美元的預期定價,而不是因爲晶圓廠停止下單。
Unhidea觀點:瓶頸已經從需求轉向物理條件——潔淨室空間、零部件,以及每月48萬片與56萬片產能之間的差距。每增加一片晶圓都需要更多檢測,因此過程控制需求會隨着產能爬坡而同步增長。
風險:零部件短缺、DRAM提前拉貨效應消退、估值倍數進一步壓縮。
來源:摩根士丹利,2026年11月17日。報告發布後新聞:CNBC。本文不構成投資建議。
- MS將WFE預期上調至2026年的1630億美元(同比增長39%)、2027年的2250億美元(增長38%)和2028年的2690億美元(增長19%),此前預期爲2540億美元。
- 2028年3000億美元的目標“需要重新校準,股價已經先行反映了這一點”:3年內將產能擴大2.5倍並不容易,而且OEM廠商已經因零部件短缺而無法按時交貨。
- DRAM是瓶頸:3000億美元意味着DRAM WFE約爲950億美元,需要新增約56萬片/月的產能,而模型預測爲48萬片/月;NAND和成熟製程邏輯芯片則需要增長超過40%。
- 出貨量目前對應的WFE年化規模爲2000億至2050億美元;2027年的樂觀情景已“逐步成爲現實”,包括英特爾支出超過200億美元,以及新增約50萬片/月的DRAM綠地項目產能。
- MS給予KLAC“增持”評級(本報告未給出目標價);對行業的看法爲“與大盤持平”。
- 報告發布後:NVIDIA公佈的第三財季業績超出預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:重新校準的是預期,而非需求——2028年2690億美元仍代表19%的增長;股價下跌是因爲此前按3000億美元的預期定價,而不是因爲晶圓廠停止下單。
Unhidea觀點:瓶頸已經從需求轉向物理條件——潔淨室空間、零部件,以及每月48萬片與56萬片產能之間的差距。每增加一片晶圓都需要更多檢測,因此過程控制需求會隨着產能爬坡而同步增長。
風險:零部件短缺、DRAM提前拉貨效應消退、估值倍數進一步壓縮。
來源:摩根士丹利,2026年11月17日。報告發布後新聞:CNBC。本文不構成投資建議。
240
·
--
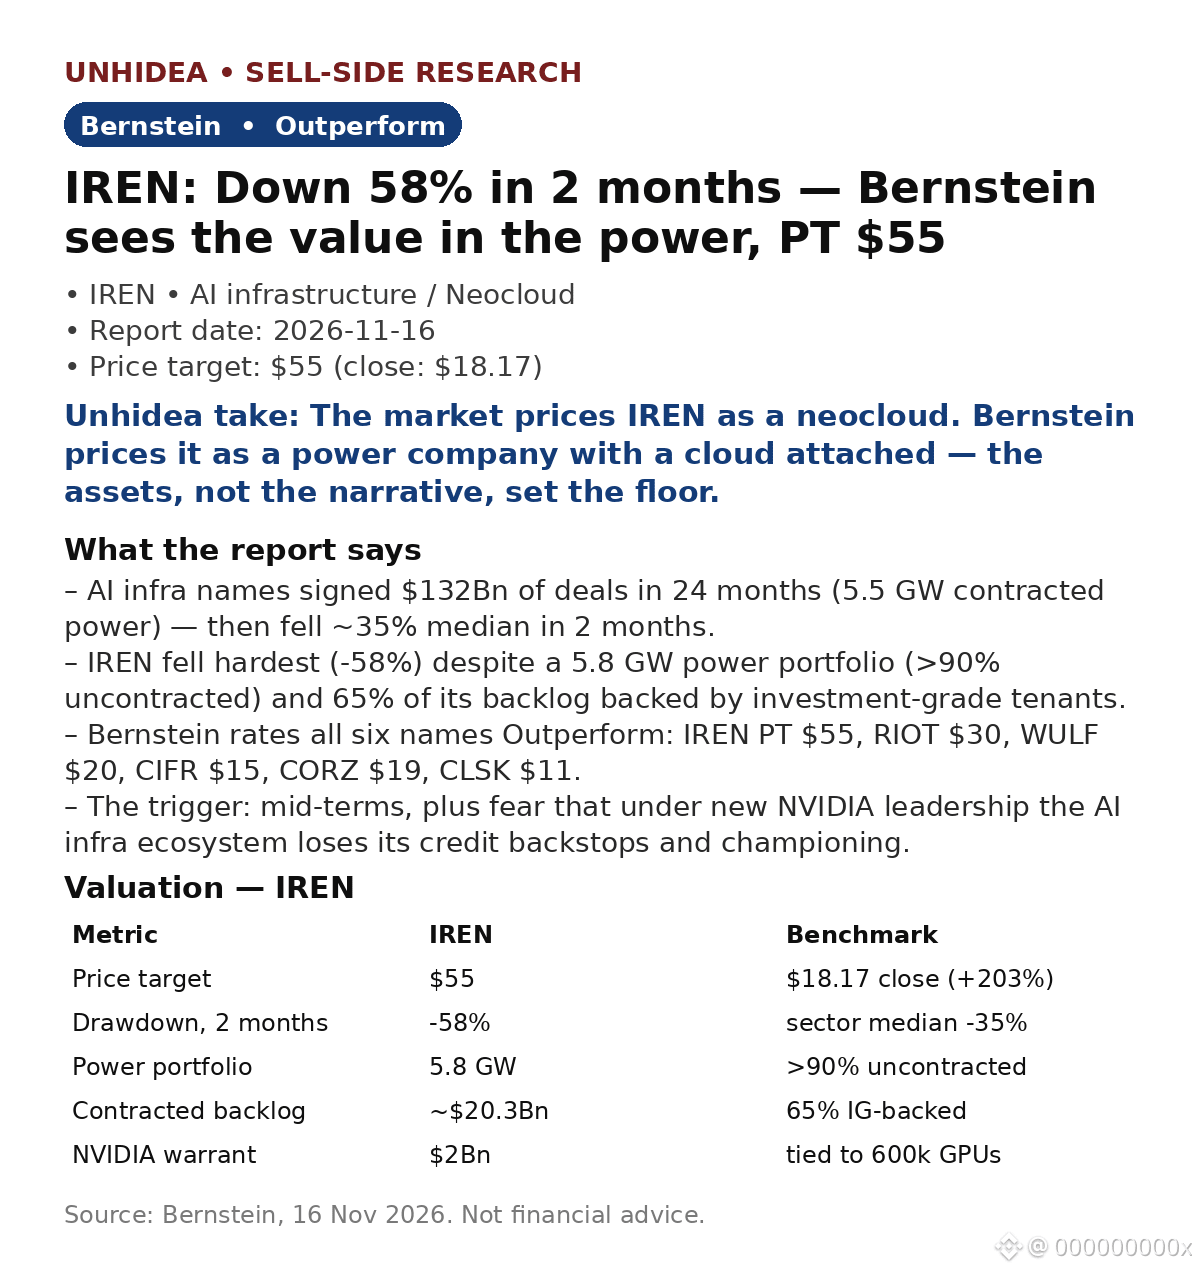
$IREN:Bernstein稱,受打擊最嚴重的AI基礎設施股,核心邏輯在於電力——兩個月內下跌58%,目標價55美元(較18.17美元收盤價上漲203%)
- 該行業在24個月內簽下了價值1320億美元的AI交易(5.5 GW),隨後因市場對中期前景感到不安,以及擔憂NVIDIA新任領導層會終止生態系統的信貸支持,兩個月內股價中位數下跌約35%。
- IREN跌幅最大(-58%),儘管其約203億美元積壓訂單中有65%由投資級客戶提供支持;MSFT是其最大客戶(48%),NVIDIA訂單金額爲34億美元。
- 其優勢:擁有5.8 GW電力,其中超過90%尚未簽約——公司可以按步調推進雲業務建設,也可以出售電力。此外,還有一份與60萬塊GPU掛鉤的20億美元NVIDIA認股權證。
- 六隻股票評級均爲跑贏大盤(RIOT 30美元、WULF 20美元、CIFR 15美元、CORZ 19美元、CLSK 11美元);RIOT股價較合同價值低約50%,WULF低22%。
- 報告發布後:NVIDIA第三財季業績超預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:市場對IREN雲業務執行風險的定價,彷彿電力一文不值——但電力是稀缺資產,即使雲業務受挫,仍可出售。
Unhidea觀點:58%的跌幅既是機遇,也是警示——投資邏輯成立的前提是IREN能夠按時完成對MSFT的交付,不再出現更多延誤。
風險:雲業務執行延誤、GPU現貨價格波動、CY27e大部分產能尚未簽約、NVIDIA領導層交接。
來源:Bernstein,2026年11月16日。報告發布後的消息:CNBC / Investing.com。本文不構成投資建議。
$IREN :Bernstein稱,受打擊最嚴重的AI基礎設施股,核心邏輯在於電力——兩個月內下跌58%,目標價55美元(較18.17美元收盤價上漲203%)
- 該行業在24個月內簽下了價值1320億美元的AI交易(5.5 GW),隨後因市場對中期前景感到不安,以及擔憂NVIDIA新任領導層會終止生態系統的信貸支持,兩個月內股價中位數下跌約35%。
- IREN跌幅最大(-58%),儘管其約203億美元積壓訂單中有65%由投資級客戶提供支持;MSFT是其最大客戶(48%),NVIDIA訂單金額爲34億美元。
- 其優勢:擁有5.8 GW電力,其中超過90%尚未簽約——公司可以按步調推進雲業務建設,也可以出售電力。此外,還有一份與60萬塊GPU掛鉤的20億美元NVIDIA認股權證。
- 六隻股票評級均爲跑贏大盤(RIOT 30美元、WULF 20美元、CIFR 15美元、CORZ 19美元、CLSK 11美元);RIOT股價較合同價值低約50%,WULF低22%。
- 報告發布後:NVIDIA第三財季業績超預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:市場對IREN雲業務執行風險的定價,彷彿電力一文不值——但電力是稀缺資產,即使雲業務受挫,仍可出售。
Unhidea觀點:58%的跌幅既是機遇,也是警示——投資邏輯成立的前提是IREN能夠按時完成對MSFT的交付,不再出現更多延誤。
風險:雲業務執行延誤、GPU現貨價格波動、CY27e大部分產能尚未簽約、NVIDIA領導層交接。
來源:Bernstein,2026年11月16日。報告發布後的消息:CNBC / Investing.com。本文不構成投資建議。
- 該行業在24個月內簽下了價值1320億美元的AI交易(5.5 GW),隨後因市場對中期前景感到不安,以及擔憂NVIDIA新任領導層會終止生態系統的信貸支持,兩個月內股價中位數下跌約35%。
- IREN跌幅最大(-58%),儘管其約203億美元積壓訂單中有65%由投資級客戶提供支持;MSFT是其最大客戶(48%),NVIDIA訂單金額爲34億美元。
- 其優勢:擁有5.8 GW電力,其中超過90%尚未簽約——公司可以按步調推進雲業務建設,也可以出售電力。此外,還有一份與60萬塊GPU掛鉤的20億美元NVIDIA認股權證。
- 六隻股票評級均爲跑贏大盤(RIOT 30美元、WULF 20美元、CIFR 15美元、CORZ 19美元、CLSK 11美元);RIOT股價較合同價值低約50%,WULF低22%。
- 報告發布後:NVIDIA第三財季業績超預期——營收1158.4億美元,預期約1090億美元;調整後每股收益2.68美元,預期2.48美元;第四財季營收指引約1300億美元(CNBC)。
Unhidea觀點:市場對IREN雲業務執行風險的定價,彷彿電力一文不值——但電力是稀缺資產,即使雲業務受挫,仍可出售。
Unhidea觀點:58%的跌幅既是機遇,也是警示——投資邏輯成立的前提是IREN能夠按時完成對MSFT的交付,不再出現更多延誤。
風險:雲業務執行延誤、GPU現貨價格波動、CY27e大部分產能尚未簽約、NVIDIA領導層交接。
來源:Bernstein,2026年11月16日。報告發布後的消息:CNBC / Investing.com。本文不構成投資建議。
487
·
--
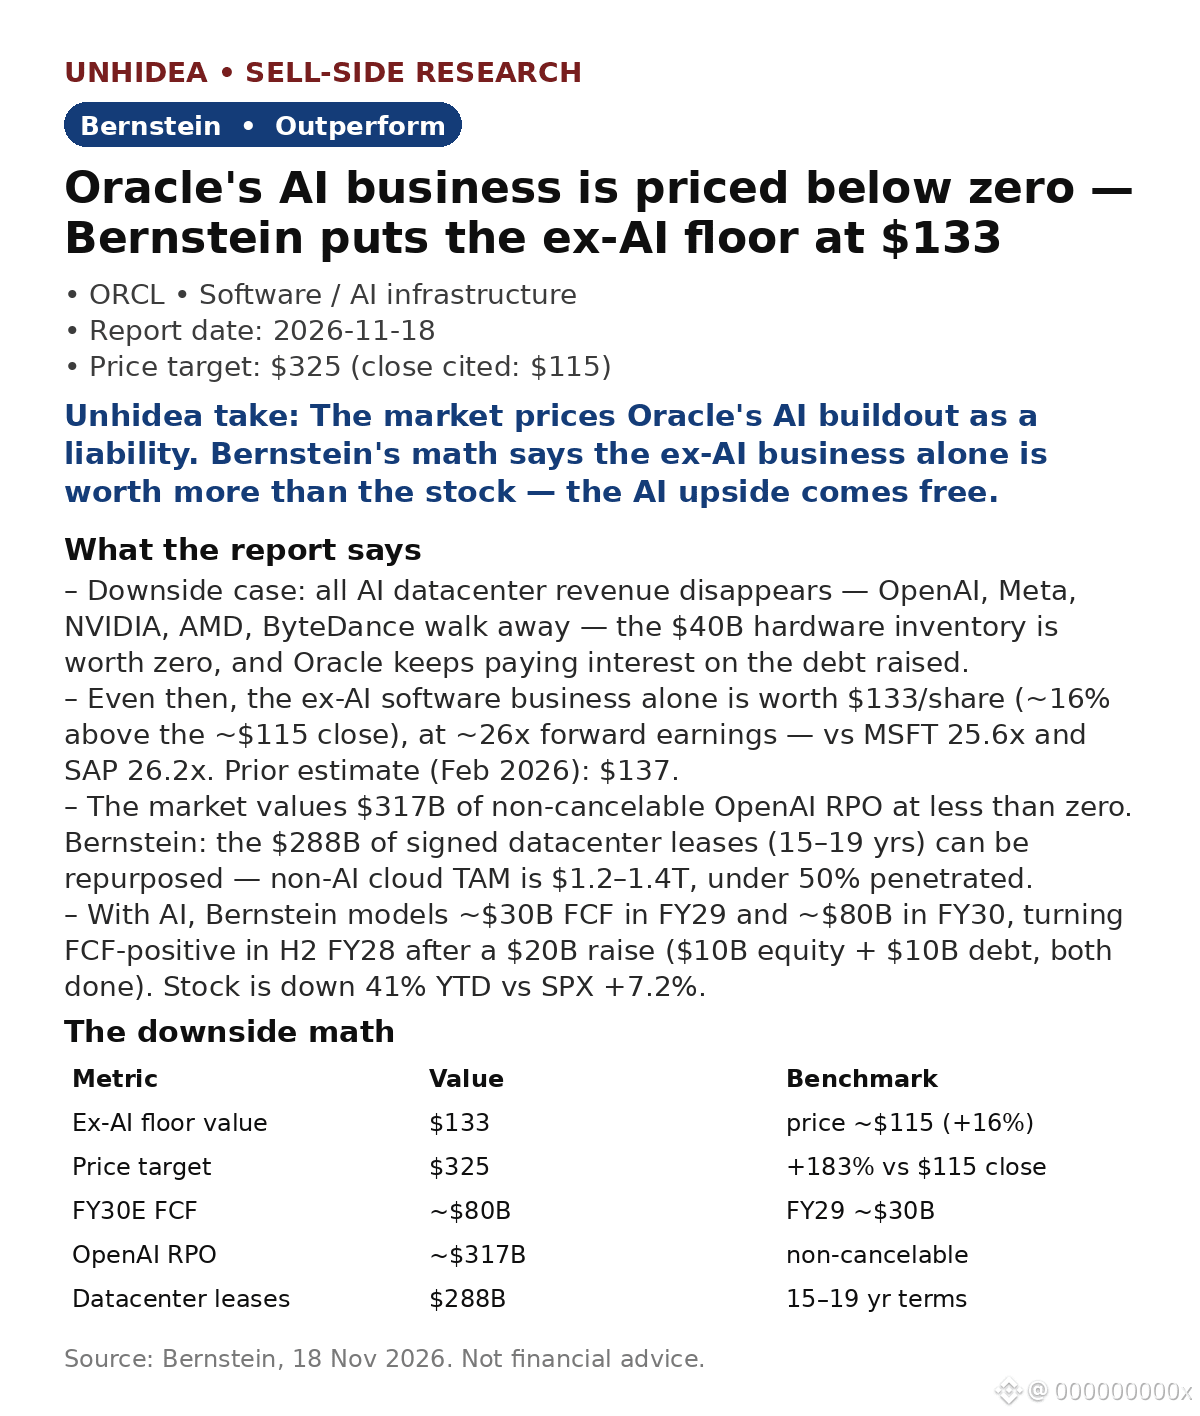
$ORCL:Bernstein稱,即使AI建設熱潮消失,Oracle仍值133美元——較115美元收盤價高16%——維持“跑贏大盤”評級,目標價325美元(+183%)
- 下行情景:所有AI數據中心收入都消失——OpenAI、Meta、NVIDIA、AMD、ByteDance全都退出——價值400億美元的硬件歸零,而Oracle仍要繼續支付利息。
- 即便如此,剔除AI後的軟件業務單獨估值也達每股133美元,約爲預期收益的26倍——與MSFT(25.6倍)和SAP(26.2倍)相當。(2026年2月:137美元。)
- 市場給3170億美元不可取消的OpenAI剩餘履約義務(RPO)估值低於零。價值2880億美元的租賃資產(15–19年)可以改作他用——非AI雲計算的總潛在市場(TAM)爲1.2萬億至1.4萬億美元,滲透率不到50%。
- Bernstein模型預測,計入AI後,Oracle在2029財年自由現金流(FCF)約爲300億美元,2030財年約爲800億美元;完成200億美元融資(100億美元股權融資+100億美元債務融資)後,將於2028財年下半年實現自由現金流轉正。
Unhidea觀點:這是一個定價錯位故事,而非增長故事——剔除AI後的估值底部提供約16%的保護,AI期權價值則是免費的。
Unhidea觀點:133美元的估值底部取決於26倍市盈率能否維持——如果SaaS估值倍數收縮,底部也會下移。關注估值倍數,而非OpenAI相關新聞。
風險:AI寒冬、客戶未履行承諾、債務/利息負擔、股權稀釋。
來源:Bernstein,2026年11月18日。本文不構成財務建議。
$ORCL :Bernstein稱,即使AI建設熱潮消失,Oracle仍值133美元——較115美元收盤價高16%——維持“跑贏大盤”評級,目標價325美元(+183%)
- 下行情景:所有AI數據中心收入都消失——OpenAI、Meta、NVIDIA、AMD、ByteDance全都退出——價值400億美元的硬件歸零,而Oracle仍要繼續支付利息。
- 即便如此,剔除AI後的軟件業務單獨估值也達每股133美元,約爲預期收益的26倍——與MSFT(25.6倍)和SAP(26.2倍)相當。(2026年2月:137美元。)
- 市場給3170億美元不可取消的OpenAI剩餘履約義務(RPO)估值低於零。價值2880億美元的租賃資產(15–19年)可以改作他用——非AI雲計算的總潛在市場(TAM)爲1.2萬億至1.4萬億美元,滲透率不到50%。
- Bernstein模型預測,計入AI後,Oracle在2029財年自由現金流(FCF)約爲300億美元,2030財年約爲800億美元;完成200億美元融資(100億美元股權融資+100億美元債務融資)後,將於2028財年下半年實現自由現金流轉正。
Unhidea觀點:這是一個定價錯位故事,而非增長故事——剔除AI後的估值底部提供約16%的保護,AI期權價值則是免費的。
Unhidea觀點:133美元的估值底部取決於26倍市盈率能否維持——如果SaaS估值倍數收縮,底部也會下移。關注估值倍數,而非OpenAI相關新聞。
風險:AI寒冬、客戶未履行承諾、債務/利息負擔、股權稀釋。
來源:Bernstein,2026年11月18日。本文不構成財務建議。
- 下行情景:所有AI數據中心收入都消失——OpenAI、Meta、NVIDIA、AMD、ByteDance全都退出——價值400億美元的硬件歸零,而Oracle仍要繼續支付利息。
- 即便如此,剔除AI後的軟件業務單獨估值也達每股133美元,約爲預期收益的26倍——與MSFT(25.6倍)和SAP(26.2倍)相當。(2026年2月:137美元。)
- 市場給3170億美元不可取消的OpenAI剩餘履約義務(RPO)估值低於零。價值2880億美元的租賃資產(15–19年)可以改作他用——非AI雲計算的總潛在市場(TAM)爲1.2萬億至1.4萬億美元,滲透率不到50%。
- Bernstein模型預測,計入AI後,Oracle在2029財年自由現金流(FCF)約爲300億美元,2030財年約爲800億美元;完成200億美元融資(100億美元股權融資+100億美元債務融資)後,將於2028財年下半年實現自由現金流轉正。
Unhidea觀點:這是一個定價錯位故事,而非增長故事——剔除AI後的估值底部提供約16%的保護,AI期權價值則是免費的。
Unhidea觀點:133美元的估值底部取決於26倍市盈率能否維持——如果SaaS估值倍數收縮,底部也會下移。關注估值倍數,而非OpenAI相關新聞。
風險:AI寒冬、客戶未履行承諾、債務/利息負擔、股權稀釋。
來源:Bernstein,2026年11月18日。本文不構成財務建議。
64
·
--
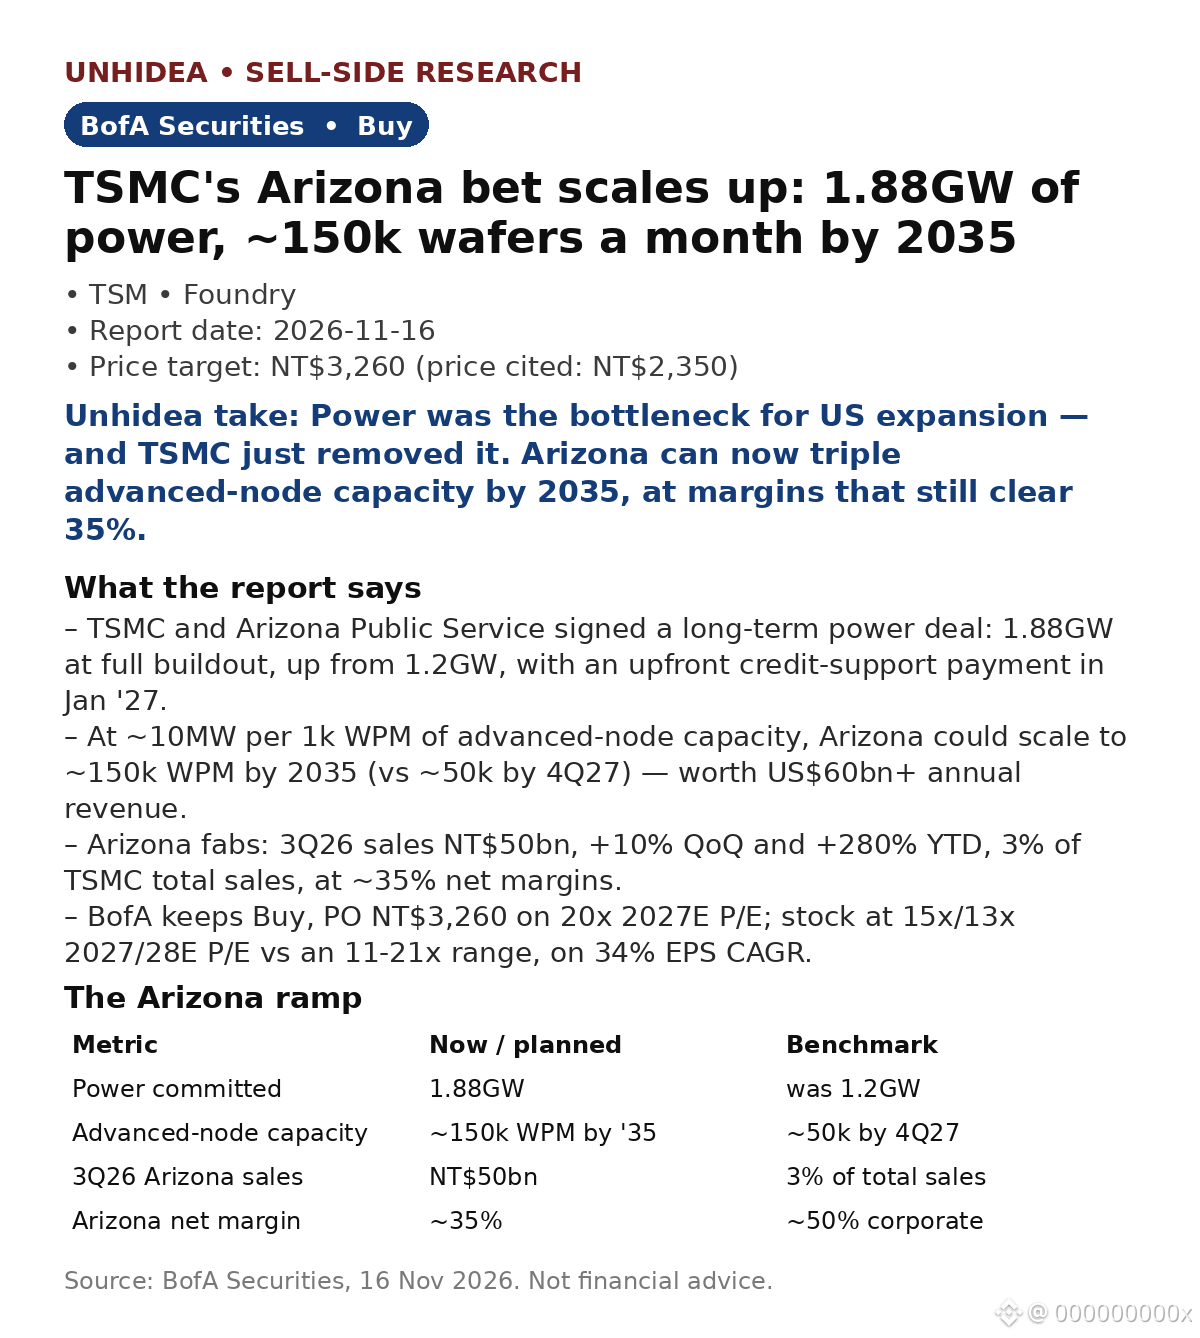
$TSM:美銀維持買進評等,目標價 NT$3,260——較文中提及的 NT$2,350 股價高約 39%;隨著亞利桑那州電力協議為美國更大規模的擴建解鎖
- 台積電與亞利桑那公共服務公司簽署長期電力協議:全面擴建後供電量將達 1.88GW,高於原先的 1.2GW,並將於 2027 年 1 月支付一筆前期信用支持款項。
- 以每月每 1,000 片晶圓先進製程產能約需 10MW 估算,美銀預計亞利桑那州的產能到 2035 年可達每月約 15 萬片(相較於 2027 年第四季的約 5 萬片),每年價值超過 600 億美元——台積電 2026 年營收預估為 1,760 億美元。
- 亞利桑那州晶圓廠已開始獲利:2026 年第三季營收為 NT$500 億,季增 10%、年初至今增長 280%,占總營收 3%;淨利率約 35%,低於 2026 年上半年的 43% 及公司整體約 50% 的水準。
- 評價:2027/2028 年預估本益比分別為 15 倍/13 倍,落在 11 至 21 倍區間內;EPS 年複合成長率為 34%;目標價相當於 2027 年預估本益比 20 倍。
- 市況背景(報告發布後的市場消息):輝達第三財季營收為 1,158 億美元,年增 103%。
Unhidea 觀點:限制美國晶片製造的瓶頸在電力,而非需求——1.88GW 的承諾,讓亞利桑那州從展示據點轉型為真正的第二供應基地。
Unhidea 觀點:留意利潤率的變化——亞利桑那州 35% 的利潤率,是美國供應韌性所付出的代價;與公司整體約 50% 的差距能以多快速度縮小,將是關鍵。
風險:智慧型手機/消費市場放緩、英特爾的晶圓代工雄心、先進製程執行風險、關稅。
來源:美銀證券,2026 年 11 月 16 日。本文不構成投資建議。
$TSM :美銀維持買進評等,目標價 NT$3,260——較文中提及的 NT$2,350 股價高約 39%;隨著亞利桑那州電力協議為美國更大規模的擴建解鎖
- 台積電與亞利桑那公共服務公司簽署長期電力協議:全面擴建後供電量將達 1.88GW,高於原先的 1.2GW,並將於 2027 年 1 月支付一筆前期信用支持款項。
- 以每月每 1,000 片晶圓先進製程產能約需 10MW 估算,美銀預計亞利桑那州的產能到 2035 年可達每月約 15 萬片(相較於 2027 年第四季的約 5 萬片),每年價值超過 600 億美元——台積電 2026 年營收預估為 1,760 億美元。
- 亞利桑那州晶圓廠已開始獲利:2026 年第三季營收為 NT$500 億,季增 10%、年初至今增長 280%,占總營收 3%;淨利率約 35%,低於 2026 年上半年的 43% 及公司整體約 50% 的水準。
- 評價:2027/2028 年預估本益比分別為 15 倍/13 倍,落在 11 至 21 倍區間內;EPS 年複合成長率為 34%;目標價相當於 2027 年預估本益比 20 倍。
- 市況背景(報告發布後的市場消息):輝達第三財季營收為 1,158 億美元,年增 103%。
Unhidea 觀點:限制美國晶片製造的瓶頸在電力,而非需求——1.88GW 的承諾,讓亞利桑那州從展示據點轉型為真正的第二供應基地。
Unhidea 觀點:留意利潤率的變化——亞利桑那州 35% 的利潤率,是美國供應韌性所付出的代價;與公司整體約 50% 的差距能以多快速度縮小,將是關鍵。
風險:智慧型手機/消費市場放緩、英特爾的晶圓代工雄心、先進製程執行風險、關稅。
來源:美銀證券,2026 年 11 月 16 日。本文不構成投資建議。
- 台積電與亞利桑那公共服務公司簽署長期電力協議:全面擴建後供電量將達 1.88GW,高於原先的 1.2GW,並將於 2027 年 1 月支付一筆前期信用支持款項。
- 以每月每 1,000 片晶圓先進製程產能約需 10MW 估算,美銀預計亞利桑那州的產能到 2035 年可達每月約 15 萬片(相較於 2027 年第四季的約 5 萬片),每年價值超過 600 億美元——台積電 2026 年營收預估為 1,760 億美元。
- 亞利桑那州晶圓廠已開始獲利:2026 年第三季營收為 NT$500 億,季增 10%、年初至今增長 280%,占總營收 3%;淨利率約 35%,低於 2026 年上半年的 43% 及公司整體約 50% 的水準。
- 評價:2027/2028 年預估本益比分別為 15 倍/13 倍,落在 11 至 21 倍區間內;EPS 年複合成長率為 34%;目標價相當於 2027 年預估本益比 20 倍。
- 市況背景(報告發布後的市場消息):輝達第三財季營收為 1,158 億美元,年增 103%。
Unhidea 觀點:限制美國晶片製造的瓶頸在電力,而非需求——1.88GW 的承諾,讓亞利桑那州從展示據點轉型為真正的第二供應基地。
Unhidea 觀點:留意利潤率的變化——亞利桑那州 35% 的利潤率,是美國供應韌性所付出的代價;與公司整體約 50% 的差距能以多快速度縮小,將是關鍵。
風險:智慧型手機/消費市場放緩、英特爾的晶圓代工雄心、先進製程執行風險、關稅。
來源:美銀證券,2026 年 11 月 16 日。本文不構成投資建議。
154
·
--
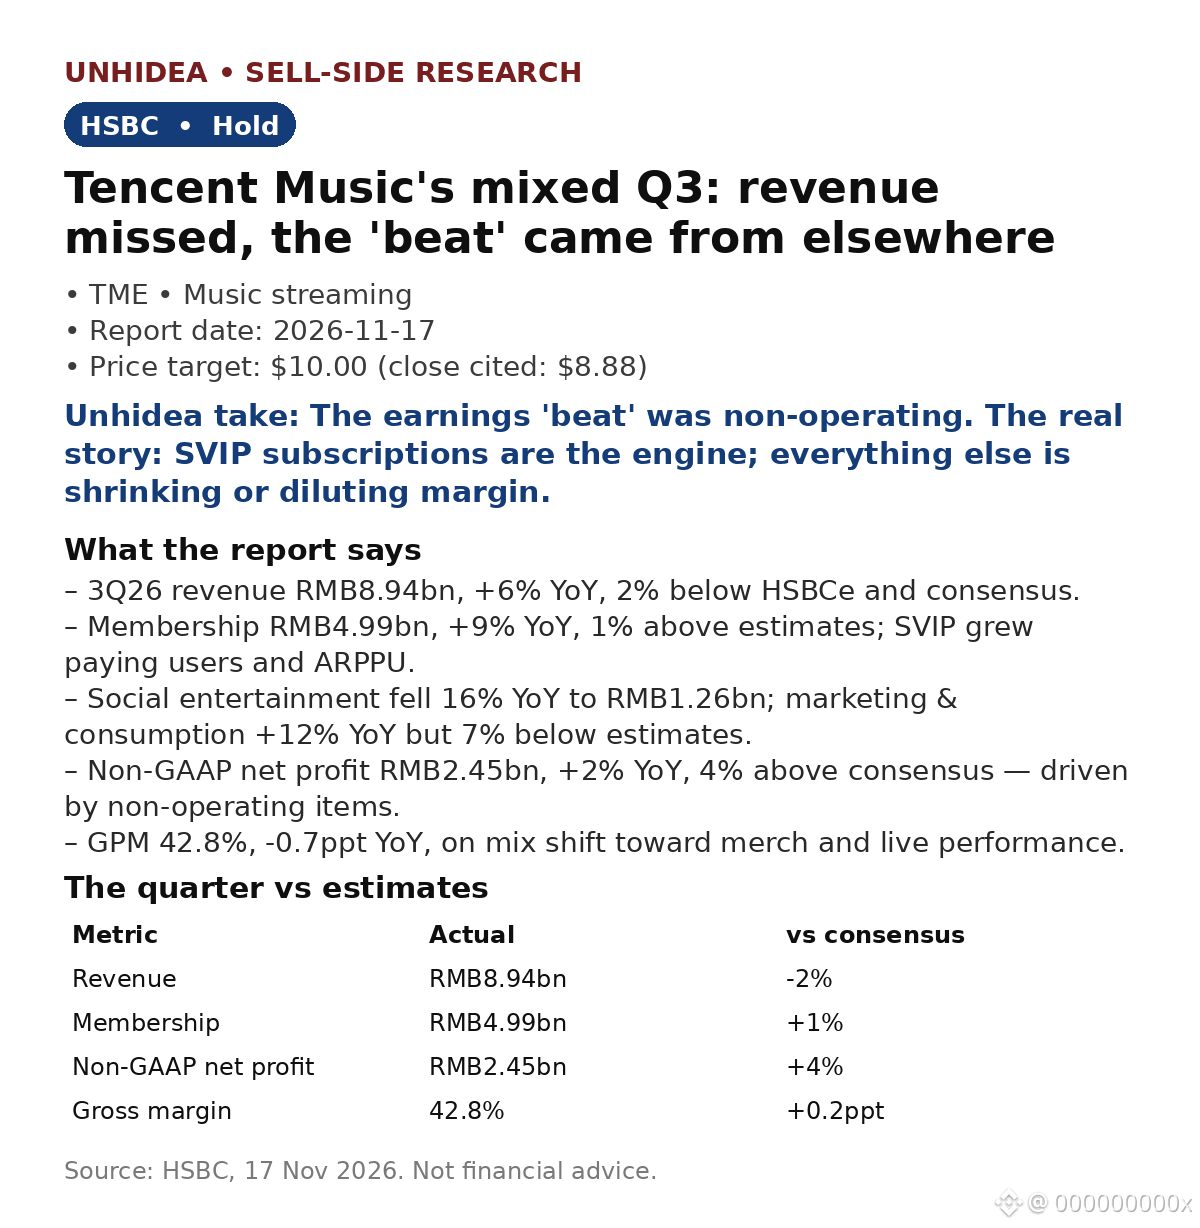
$TME:第三季度營收不及預期——人民幣89.4億元,同比增長6%,低於市場預期2%——但匯豐維持“持有”評級,目標價10.00美元
- 會員業務表現亮眼:營收人民幣49.9億元,同比增長9%,高於預期1%;SVIP付費用戶數和每付費用戶平均收入(ARPPU)均有所增長。
- 社交娛樂營收同比下降16%至人民幣12.6億元;營銷與消費業務增長12%,但低於預期7%。
- 非公認會計准則淨利潤爲人民幣24.5億元,同比增長2%,高於市場共識4%——但超預期主要來自非經營項目,而非業務本身。
- 毛利率爲42.8%,同比下降0.7個百分點,原因是商品銷售和現場演出在收入中的佔比上升。
- 股票回購:第三季度回購3,470萬份美國存托股,耗資約3億美元——單季回購規模相當於市值的2.1%。
估值:目標價10.00美元較所引用的8.88美元收盤價高約13%(截至11月16日)。
Unhidea觀點:依靠非經營項目實現的“超預期”,並不代表經營表現超預期——剔除這些項目後,本季度仍未達預期,非公認會計准則經營利潤同比持平。
Unhidea觀點:TME正悄然轉型爲一家訂閱型公司——SVIP是其持久的增長引擎;評估公司時應關注會員業務的ARPPU,而非綜合營收。
風險:喜馬拉雅整合成本、社交娛樂業務下滑、收入結構帶來的利潤率壓力。
來源:匯豐,2026年11月17日。本文不構成財務建議。
$TME:第三季度營收不及預期——人民幣89.4億元,同比增長6%,低於市場預期2%——但匯豐維持“持有”評級,目標價10.00美元
- 會員業務表現亮眼:營收人民幣49.9億元,同比增長9%,高於預期1%;SVIP付費用戶數和每付費用戶平均收入(ARPPU)均有所增長。
- 社交娛樂營收同比下降16%至人民幣12.6億元;營銷與消費業務增長12%,但低於預期7%。
- 非公認會計准則淨利潤爲人民幣24.5億元,同比增長2%,高於市場共識4%——但超預期主要來自非經營項目,而非業務本身。
- 毛利率爲42.8%,同比下降0.7個百分點,原因是商品銷售和現場演出在收入中的佔比上升。
- 股票回購:第三季度回購3,470萬份美國存托股,耗資約3億美元——單季回購規模相當於市值的2.1%。
估值:目標價10.00美元較所引用的8.88美元收盤價高約13%(截至11月16日)。
Unhidea觀點:依靠非經營項目實現的“超預期”,並不代表經營表現超預期——剔除這些項目後,本季度仍未達預期,非公認會計准則經營利潤同比持平。
Unhidea觀點:TME正悄然轉型爲一家訂閱型公司——SVIP是其持久的增長引擎;評估公司時應關注會員業務的ARPPU,而非綜合營收。
風險:喜馬拉雅整合成本、社交娛樂業務下滑、收入結構帶來的利潤率壓力。
來源:匯豐,2026年11月17日。本文不構成財務建議。
- 會員業務表現亮眼:營收人民幣49.9億元,同比增長9%,高於預期1%;SVIP付費用戶數和每付費用戶平均收入(ARPPU)均有所增長。
- 社交娛樂營收同比下降16%至人民幣12.6億元;營銷與消費業務增長12%,但低於預期7%。
- 非公認會計准則淨利潤爲人民幣24.5億元,同比增長2%,高於市場共識4%——但超預期主要來自非經營項目,而非業務本身。
- 毛利率爲42.8%,同比下降0.7個百分點,原因是商品銷售和現場演出在收入中的佔比上升。
- 股票回購:第三季度回購3,470萬份美國存托股,耗資約3億美元——單季回購規模相當於市值的2.1%。
估值:目標價10.00美元較所引用的8.88美元收盤價高約13%(截至11月16日)。
Unhidea觀點:依靠非經營項目實現的“超預期”,並不代表經營表現超預期——剔除這些項目後,本季度仍未達預期,非公認會計准則經營利潤同比持平。
Unhidea觀點:TME正悄然轉型爲一家訂閱型公司——SVIP是其持久的增長引擎;評估公司時應關注會員業務的ARPPU,而非綜合營收。
風險:喜馬拉雅整合成本、社交娛樂業務下滑、收入結構帶來的利潤率壓力。
來源:匯豐,2026年11月17日。本文不構成財務建議。
TMEUS+0.52%
51
·
--
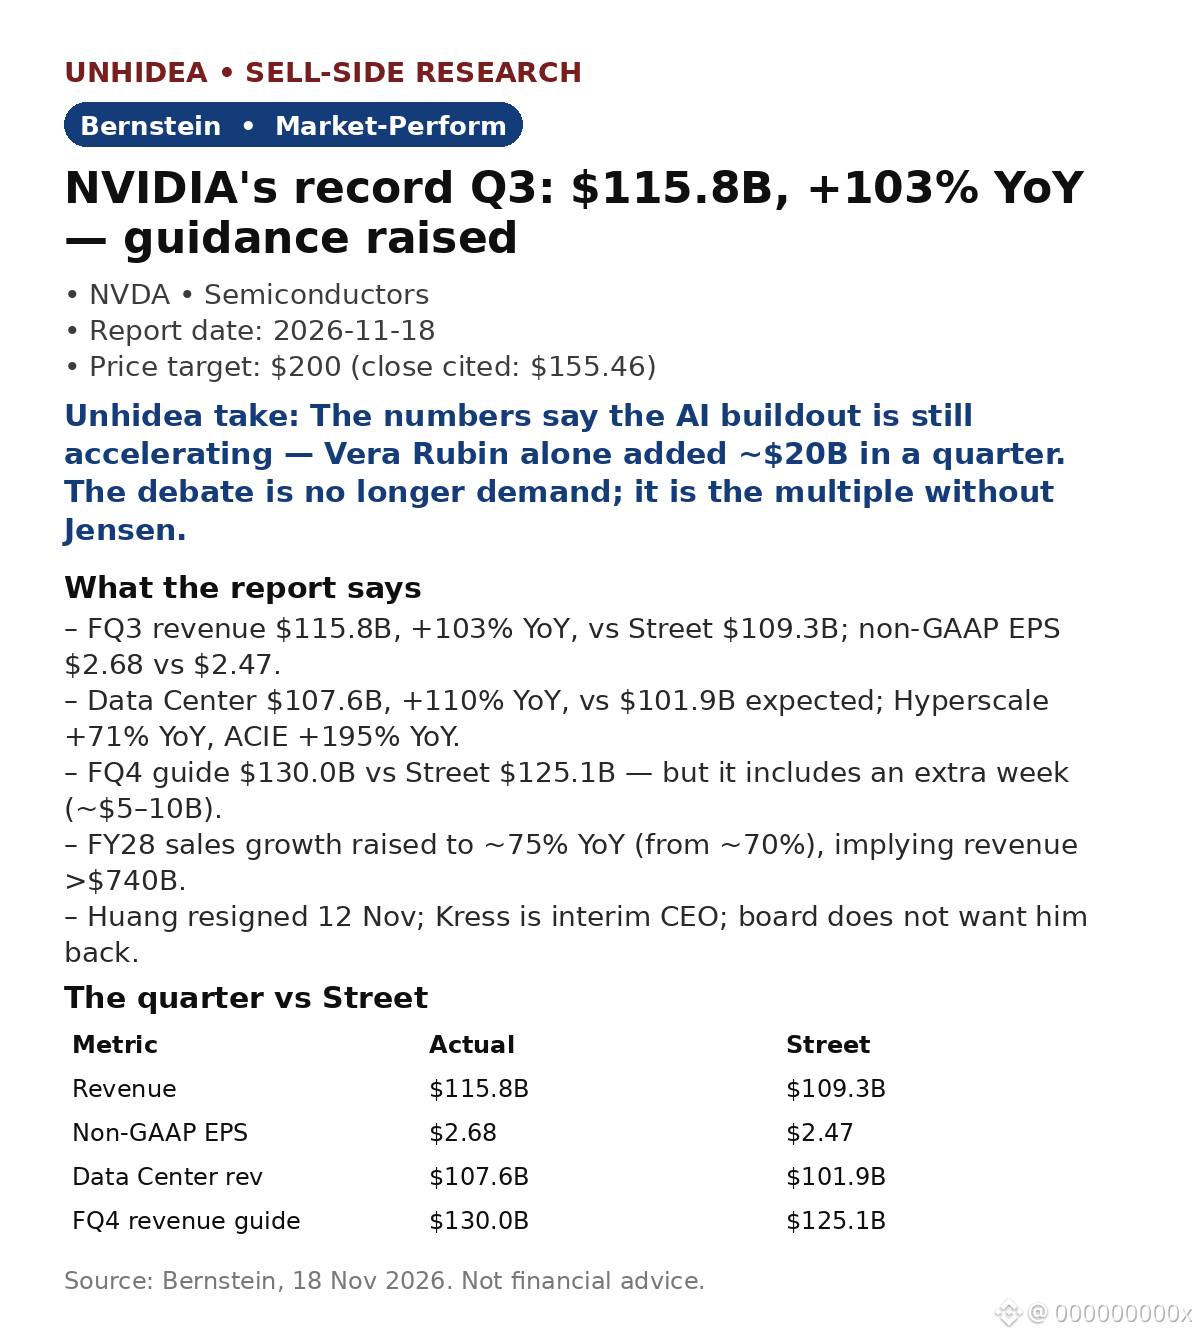
$NVDA:創紀錄的第三季度——營收1,158億美元,同比增長103%;但伯恩斯坦仍給予“與大盤表現一致”評級,目標價200美元
第三財季業績超預期:營收1,158億美元(同比增長103%,環比增長20%),高於市場預期的1,093億美元;每股收益2.68美元,高於預期的2.47美元。數據中心業務營收1,076億美元,同比增長110%,高於預期的1,019億美元。Vera Rubin貢獻約200億美元,創下公司歷史上最強勁的增長勢頭。
- 第四財季營收指引爲1,300億美元(±3%),高於市場預期的1,251億美元;但其中多了一週(約50億至100億美元),因此按正常週數計算的指引可能偏低。
- 2028財年銷售額增速預期從約70%上調至約75%,意味着營收將超過7,400億美元,即便面臨新的BIS制裁也不例外。
- 管理層:黃仁勳於11月12日辭職;科萊特·克雷斯擔任臨時CEO;董事會不希望他迴歸——短期穩定,但長期問題仍存。
估值:200美元目標價較文中所引的155.46美元收盤價(11月17日)高出約29%;52周區間爲148.80至243.37美元。
Unhidea觀點:數據表明,AI基礎設施建設仍在加速——僅Rubin一個季度就貢獻了約200億美元。如今爭論的焦點已不再是需求,而是失去黃仁勳後還能否維持當前估值倍數。
Unhidea觀點:剔除多出的一週後,第四財季指引就沒有標題所說的那麼亮眼;真正的信號是2028財年增速預期上調至約75%。
風險:管理層交接、出口管制、3,900億美元供應承諾、利潤率觸底。
來源:伯恩斯坦,2026年11月18日。本文不構成財務建議。
$NVDA :創紀錄的第三季度——營收1,158億美元,同比增長103%;但伯恩斯坦仍給予“與大盤表現一致”評級,目標價200美元
第三財季業績超預期:營收1,158億美元(同比增長103%,環比增長20%),高於市場預期的1,093億美元;每股收益2.68美元,高於預期的2.47美元。數據中心業務營收1,076億美元,同比增長110%,高於預期的1,019億美元。Vera Rubin貢獻約200億美元,創下公司歷史上最強勁的增長勢頭。
- 第四財季營收指引爲1,300億美元(±3%),高於市場預期的1,251億美元;但其中多了一週(約50億至100億美元),因此按正常週數計算的指引可能偏低。
- 2028財年銷售額增速預期從約70%上調至約75%,意味着營收將超過7,400億美元,即便面臨新的BIS制裁也不例外。
- 管理層:黃仁勳於11月12日辭職;科萊特·克雷斯擔任臨時CEO;董事會不希望他迴歸——短期穩定,但長期問題仍存。
估值:200美元目標價較文中所引的155.46美元收盤價(11月17日)高出約29%;52周區間爲148.80至243.37美元。
Unhidea觀點:數據表明,AI基礎設施建設仍在加速——僅Rubin一個季度就貢獻了約200億美元。如今爭論的焦點已不再是需求,而是失去黃仁勳後還能否維持當前估值倍數。
Unhidea觀點:剔除多出的一週後,第四財季指引就沒有標題所說的那麼亮眼;真正的信號是2028財年增速預期上調至約75%。
風險:管理層交接、出口管制、3,900億美元供應承諾、利潤率觸底。
來源:伯恩斯坦,2026年11月18日。本文不構成財務建議。
第三財季業績超預期:營收1,158億美元(同比增長103%,環比增長20%),高於市場預期的1,093億美元;每股收益2.68美元,高於預期的2.47美元。數據中心業務營收1,076億美元,同比增長110%,高於預期的1,019億美元。Vera Rubin貢獻約200億美元,創下公司歷史上最強勁的增長勢頭。
- 第四財季營收指引爲1,300億美元(±3%),高於市場預期的1,251億美元;但其中多了一週(約50億至100億美元),因此按正常週數計算的指引可能偏低。
- 2028財年銷售額增速預期從約70%上調至約75%,意味着營收將超過7,400億美元,即便面臨新的BIS制裁也不例外。
- 管理層:黃仁勳於11月12日辭職;科萊特·克雷斯擔任臨時CEO;董事會不希望他迴歸——短期穩定,但長期問題仍存。
估值:200美元目標價較文中所引的155.46美元收盤價(11月17日)高出約29%;52周區間爲148.80至243.37美元。
Unhidea觀點:數據表明,AI基礎設施建設仍在加速——僅Rubin一個季度就貢獻了約200億美元。如今爭論的焦點已不再是需求,而是失去黃仁勳後還能否維持當前估值倍數。
Unhidea觀點:剔除多出的一週後,第四財季指引就沒有標題所說的那麼亮眼;真正的信號是2028財年增速預期上調至約75%。
風險:管理層交接、出口管制、3,900億美元供應承諾、利潤率觸底。
來源:伯恩斯坦,2026年11月18日。本文不構成財務建議。
35
·
--
查看翻譯
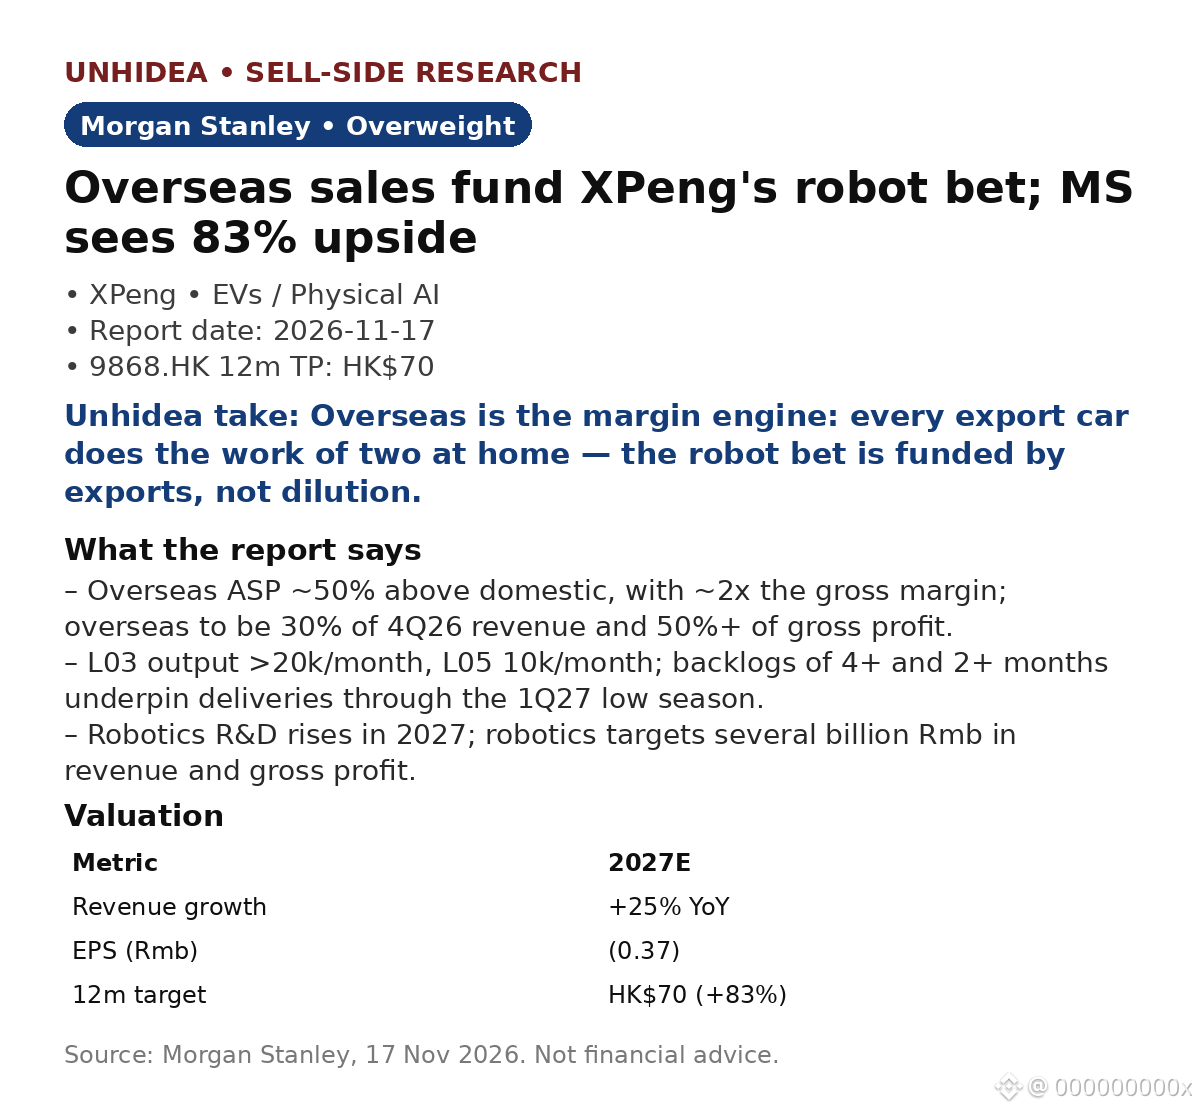
$9868.HK: XPeng's overseas cars earn ~2x domestic margins — Morgan Stanley says exports now fund the robot bet. Overweight, HK$70 target, 83% upside vs HK$38.28 close (17 Nov).
Overseas ASP is ~50% above domestic, at ~2x the gross margin. MS expects overseas to be 30% of 4Q26 revenue and over half of gross profit, holding vehicle GpM at 12–13% despite a richer MONA mix.
Production is sold out for months: L03 tops 20k/month, L05 10k/month, with 4+ and 2+ months of backlog, carrying deliveries through the 1Q27 low season.
Robotics is the next leg: auto R&D holds at ~Rmb5bn, robotics R&D rises in 2027, targeting several billion Rmb in revenue and gross profit, funded by positive FCF (Rmb3–4bn annual capex).
MS models 2027E revenue of Rmb103.3bn (+25% YoY) and a first profit in 2028E (EPS Rmb0.23 vs a Rmb0.37 loss in 2027E).
Unhidea take: overseas is the margin engine — every export car does the work of two at home, so the robot bet is funded by exports, not dilution.
Unhidea take: watch whether robotics revenue lands in 2027 — until then, XPeng is priced as a carmaker with a robot story.
Risks: competition; cash-flow pressure; slower demand. Source: Morgan Stanley, 17 Nov 2026. Not financial advice.
$9868.HK: XPeng's overseas cars earn ~2x domestic margins — Morgan Stanley says exports now fund the robot bet. Overweight, HK$70 target, 83% upside vs HK$38.28 close (17 Nov).
Overseas ASP is ~50% above domestic, at ~2x the gross margin. MS expects overseas to be 30% of 4Q26 revenue and over half of gross profit, holding vehicle GpM at 12–13% despite a richer MONA mix.
Production is sold out for months: L03 tops 20k/month, L05 10k/month, with 4+ and 2+ months of backlog, carrying deliveries through the 1Q27 low season.
Robotics is the next leg: auto R&D holds at ~Rmb5bn, robotics R&D rises in 2027, targeting several billion Rmb in revenue and gross profit, funded by positive FCF (Rmb3–4bn annual capex).
MS models 2027E revenue of Rmb103.3bn (+25% YoY) and a first profit in 2028E (EPS Rmb0.23 vs a Rmb0.37 loss in 2027E).
Unhidea take: overseas is the margin engine — every export car does the work of two at home, so the robot bet is funded by exports, not dilution.
Unhidea take: watch whether robotics revenue lands in 2027 — until then, XPeng is priced as a carmaker with a robot story.
Risks: competition; cash-flow pressure; slower demand. Source: Morgan Stanley, 17 Nov 2026. Not financial advice.
Overseas ASP is ~50% above domestic, at ~2x the gross margin. MS expects overseas to be 30% of 4Q26 revenue and over half of gross profit, holding vehicle GpM at 12–13% despite a richer MONA mix.
Production is sold out for months: L03 tops 20k/month, L05 10k/month, with 4+ and 2+ months of backlog, carrying deliveries through the 1Q27 low season.
Robotics is the next leg: auto R&D holds at ~Rmb5bn, robotics R&D rises in 2027, targeting several billion Rmb in revenue and gross profit, funded by positive FCF (Rmb3–4bn annual capex).
MS models 2027E revenue of Rmb103.3bn (+25% YoY) and a first profit in 2028E (EPS Rmb0.23 vs a Rmb0.37 loss in 2027E).
Unhidea take: overseas is the margin engine — every export car does the work of two at home, so the robot bet is funded by exports, not dilution.
Unhidea take: watch whether robotics revenue lands in 2027 — until then, XPeng is priced as a carmaker with a robot story.
Risks: competition; cash-flow pressure; slower demand. Source: Morgan Stanley, 17 Nov 2026. Not financial advice.
·
--
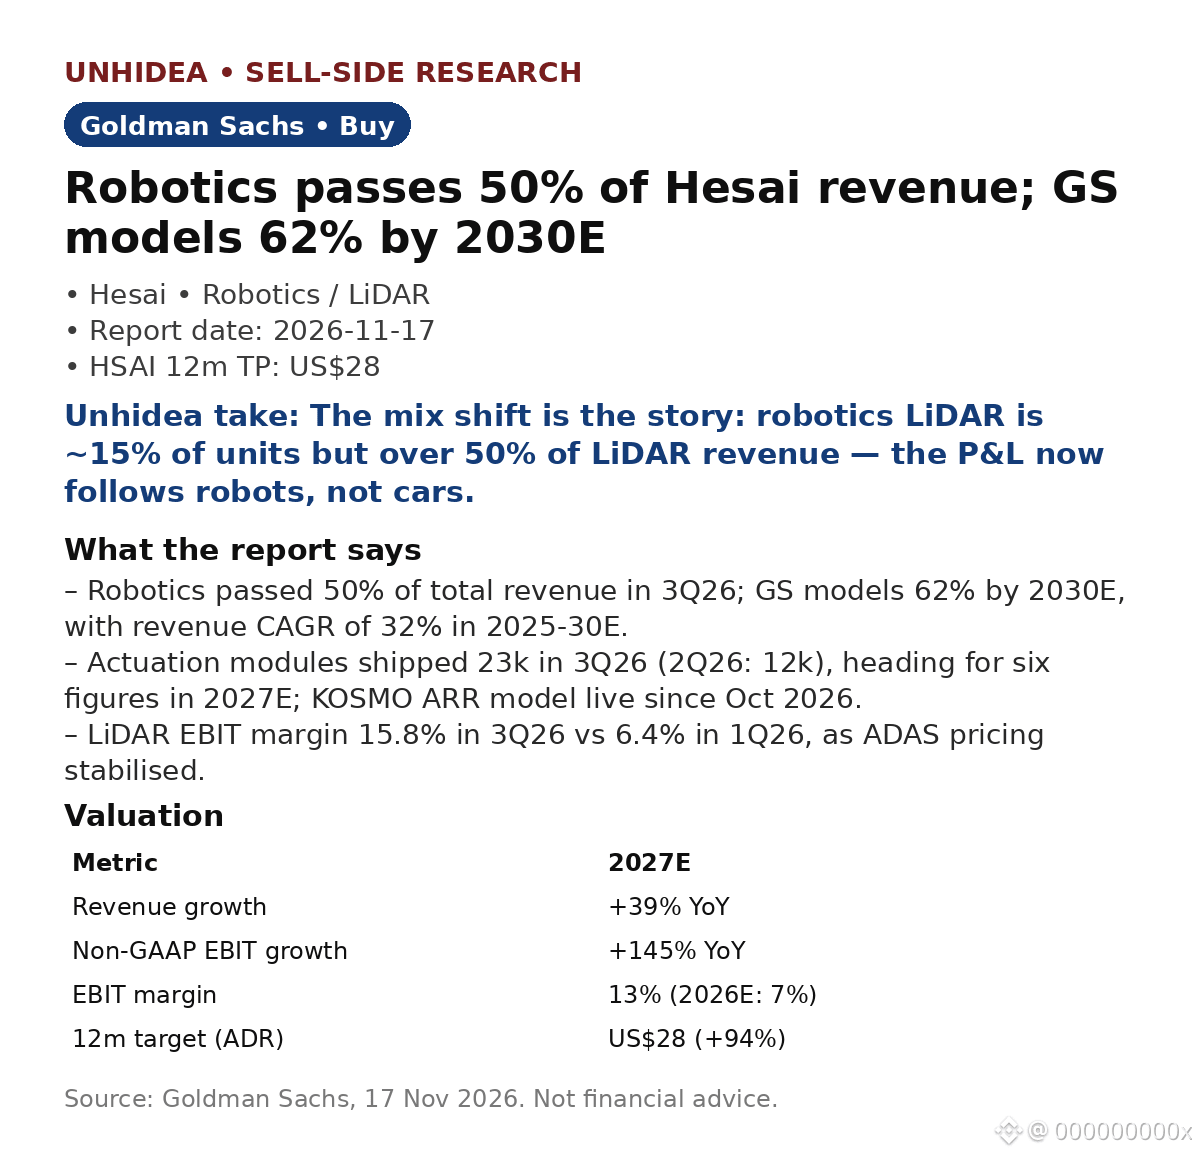
高盛:禾賽不再只是汽車零部件公司——機器人業務如今已貢獻超過一半的收入,而且是價值更高的那一半。
高盛重申對 $HSAI 的“買入”評級,12個月目標價爲28美元,意味着94%的上漲空間。機器人業務在3Q26的總收入佔比超過50%;高盛預計到2030E將達到62%,2025-30E收入複合年增長率爲32%。
執行器模塊:3Q26出貨量爲2.3萬套,高於2Q26的1.2萬套,預計2027E將達到六位數。隨着ADAS定價趨於穩定,激光雷達EBIT利潤率從1Q26的6.4%升至3Q26的15.8%。KOSMO於2026年10月推出,現已產生經常性收入——Pixar RenderMan是其用戶之一。
2027E:收入增長39%(ADAS同比增長27%,而2026E爲下降5%;非ADAS增長49%),非GAAP EBIT同比增長145%,利潤率爲13%,高於7%。
報告發布後:英偉達於11月17日收盤後公佈Q3收入爲1,158億美元,超出市場一致預期。據報告,禾賽是英偉達人形機器人平臺的主要供應商。
Unhidea觀點:業務組合轉變是關鍵——機器人激光雷達約佔出貨量的15%,卻貢獻了超過50%的激光雷達收入,因此如今損益表現取決於機器人,而非汽車。
Unhidea觀點:關注KOSMO的ARR——經常性的空間數據收入將改變市場對禾賽的估值方式,使其不再被視爲硬件供應商。
風險:激光雷達普及速度低於預期;價格壓力;政策風險。來源:高盛,2026年11月17日。本文不構成財務建議。
高盛:禾賽不再只是汽車零部件公司——機器人業務如今已貢獻超過一半的收入,而且是價值更高的那一半。
高盛重申對 $HSAI 的“買入”評級,12個月目標價爲28美元,意味着94%的上漲空間。機器人業務在3Q26的總收入佔比超過50%;高盛預計到2030E將達到62%,2025-30E收入複合年增長率爲32%。
執行器模塊:3Q26出貨量爲2.3萬套,高於2Q26的1.2萬套,預計2027E將達到六位數。隨着ADAS定價趨於穩定,激光雷達EBIT利潤率從1Q26的6.4%升至3Q26的15.8%。KOSMO於2026年10月推出,現已產生經常性收入——Pixar RenderMan是其用戶之一。
2027E:收入增長39%(ADAS同比增長27%,而2026E爲下降5%;非ADAS增長49%),非GAAP EBIT同比增長145%,利潤率爲13%,高於7%。
報告發布後:英偉達於11月17日收盤後公佈Q3收入爲1,158億美元,超出市場一致預期。據報告,禾賽是英偉達人形機器人平臺的主要供應商。
Unhidea觀點:業務組合轉變是關鍵——機器人激光雷達約佔出貨量的15%,卻貢獻了超過50%的激光雷達收入,因此如今損益表現取決於機器人,而非汽車。
Unhidea觀點:關注KOSMO的ARR——經常性的空間數據收入將改變市場對禾賽的估值方式,使其不再被視爲硬件供應商。
風險:激光雷達普及速度低於預期;價格壓力;政策風險。來源:高盛,2026年11月17日。本文不構成財務建議。
高盛重申對 $HSAI 的“買入”評級,12個月目標價爲28美元,意味着94%的上漲空間。機器人業務在3Q26的總收入佔比超過50%;高盛預計到2030E將達到62%,2025-30E收入複合年增長率爲32%。
執行器模塊:3Q26出貨量爲2.3萬套,高於2Q26的1.2萬套,預計2027E將達到六位數。隨着ADAS定價趨於穩定,激光雷達EBIT利潤率從1Q26的6.4%升至3Q26的15.8%。KOSMO於2026年10月推出,現已產生經常性收入——Pixar RenderMan是其用戶之一。
2027E:收入增長39%(ADAS同比增長27%,而2026E爲下降5%;非ADAS增長49%),非GAAP EBIT同比增長145%,利潤率爲13%,高於7%。
報告發布後:英偉達於11月17日收盤後公佈Q3收入爲1,158億美元,超出市場一致預期。據報告,禾賽是英偉達人形機器人平臺的主要供應商。
Unhidea觀點:業務組合轉變是關鍵——機器人激光雷達約佔出貨量的15%,卻貢獻了超過50%的激光雷達收入,因此如今損益表現取決於機器人,而非汽車。
Unhidea觀點:關注KOSMO的ARR——經常性的空間數據收入將改變市場對禾賽的估值方式,使其不再被視爲硬件供應商。
風險:激光雷達普及速度低於預期;價格壓力;政策風險。來源:高盛,2026年11月17日。本文不構成財務建議。
81
登入以探索更多內容
加入幣安廣場中的全球加密貨幣用戶
⚡️ 獲取加密貨幣的最新和實用資訊。
💬 受到全球最大加密貨幣交易所的信任。
👍 發掘來自經過驗證創作者的真實見解。
電子郵件 / 電話號碼