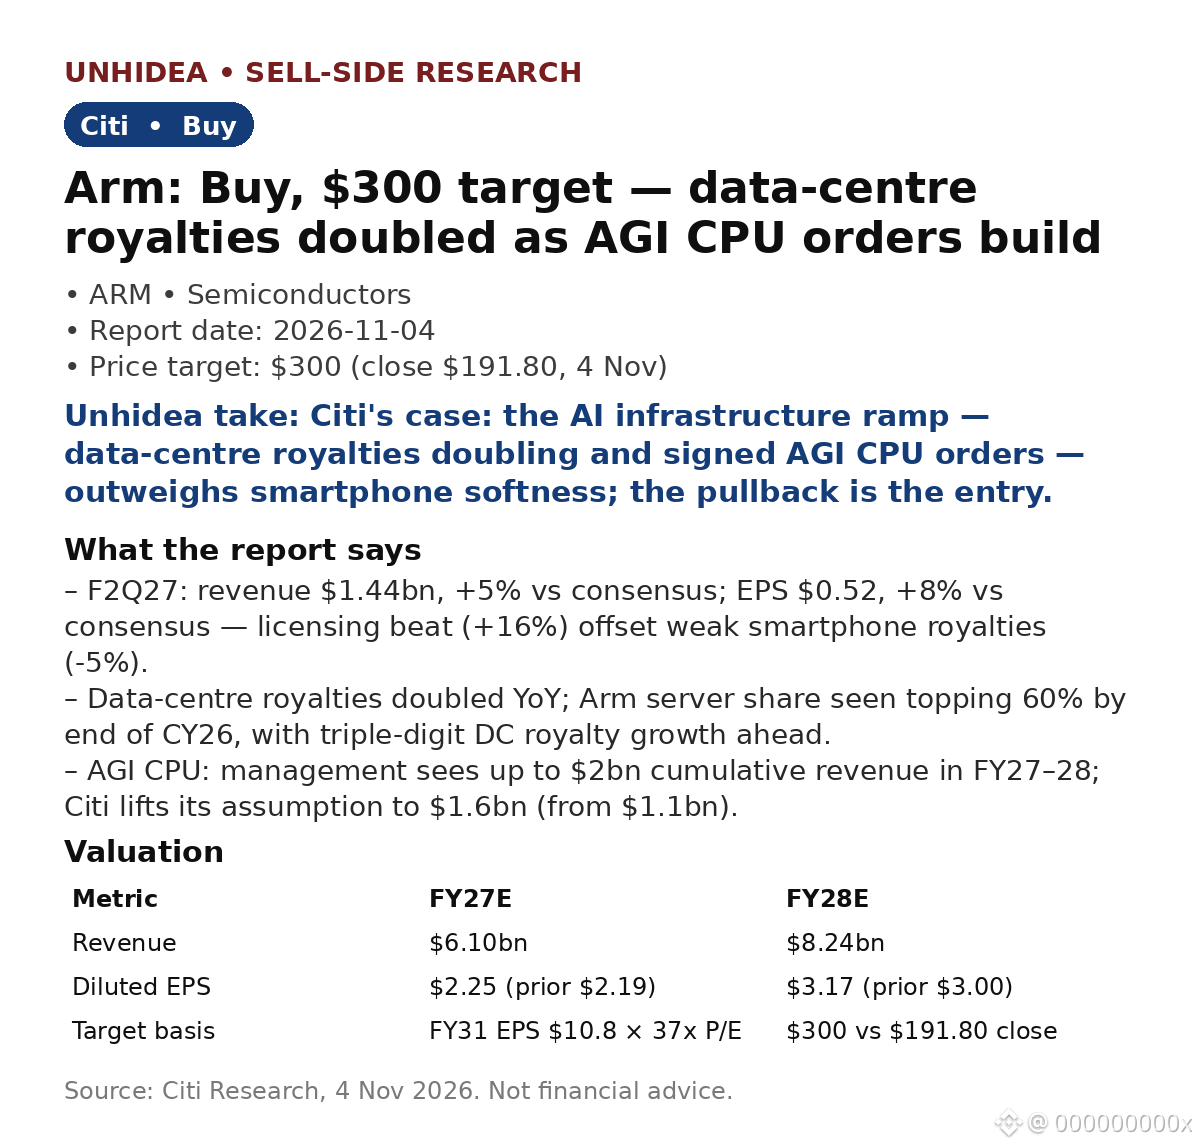
$ARM: Citi keeps Buy, $300 target — data-centre royalties doubled as AGI CPU orders build
Citi's 4 Nov note, after Arm's F2Q27 print: revenue $1.44bn (+5% vs consensus) and EPS $0.52 (+8%) — licensing beat (+16% vs consensus) more than offset smartphone royalty softness (-5%). F3Q27 guide of $1.54bn revenue and $0.56 EPS sits modestly ahead of consensus ($1.52bn / $0.55).
- Data centre: royalties doubled YoY; Arm server share seen above 60% by end of CY26, with triple-digit DC royalty growth expected in coming years.
- AGI CPU: management sees up to $2bn cumulative revenue in FY27–28; Citi lifts its assumption to $1.6bn (from $1.1bn) on signed purchase orders.
- Valuation: FY27E revenue $6.10bn, FY28E $8.24bn; EPS $2.25 / $3.17. Target $300 = FY31 EPS $10.8 at 37x P/E, discounted to 2028 — ~56% above the $191.80 close on 4 Nov.
Unhidea take: the quarter shows Arm monetising AI twice — licences today, royalties tomorrow — and the AGI CPU order book turns a story into contracted revenue.
Unhidea take: ARM shares were down ~8% intraday on 17 Nov in a broad chip sell-off — that's AI anxiety into Nvidia's print, not this report. The gap between Citi's $300 and the market's mood is the trade to watch.
Risks: execution and system deployment are the key constraint; smartphone royalties still weak; RISC-V competition; SoftBank holds ~90%.
Source: Citi Research, 4 Nov 2026. Not financial advice.
Citi's 4 Nov note, after Arm's F2Q27 print: revenue $1.44bn (+5% vs consensus) and EPS $0.52 (+8%) — licensing beat (+16% vs consensus) more than offset smartphone royalty softness (-5%). F3Q27 guide of $1.54bn revenue and $0.56 EPS sits modestly ahead of consensus ($1.52bn / $0.55).
- Data centre: royalties doubled YoY; Arm server share seen above 60% by end of CY26, with triple-digit DC royalty growth expected in coming years.
- AGI CPU: management sees up to $2bn cumulative revenue in FY27–28; Citi lifts its assumption to $1.6bn (from $1.1bn) on signed purchase orders.
- Valuation: FY27E revenue $6.10bn, FY28E $8.24bn; EPS $2.25 / $3.17. Target $300 = FY31 EPS $10.8 at 37x P/E, discounted to 2028 — ~56% above the $191.80 close on 4 Nov.
Unhidea take: the quarter shows Arm monetising AI twice — licences today, royalties tomorrow — and the AGI CPU order book turns a story into contracted revenue.
Unhidea take: ARM shares were down ~8% intraday on 17 Nov in a broad chip sell-off — that's AI anxiety into Nvidia's print, not this report. The gap between Citi's $300 and the market's mood is the trade to watch.
Risks: execution and system deployment are the key constraint; smartphone royalties still weak; RISC-V competition; SoftBank holds ~90%.
Source: Citi Research, 4 Nov 2026. Not financial advice.