

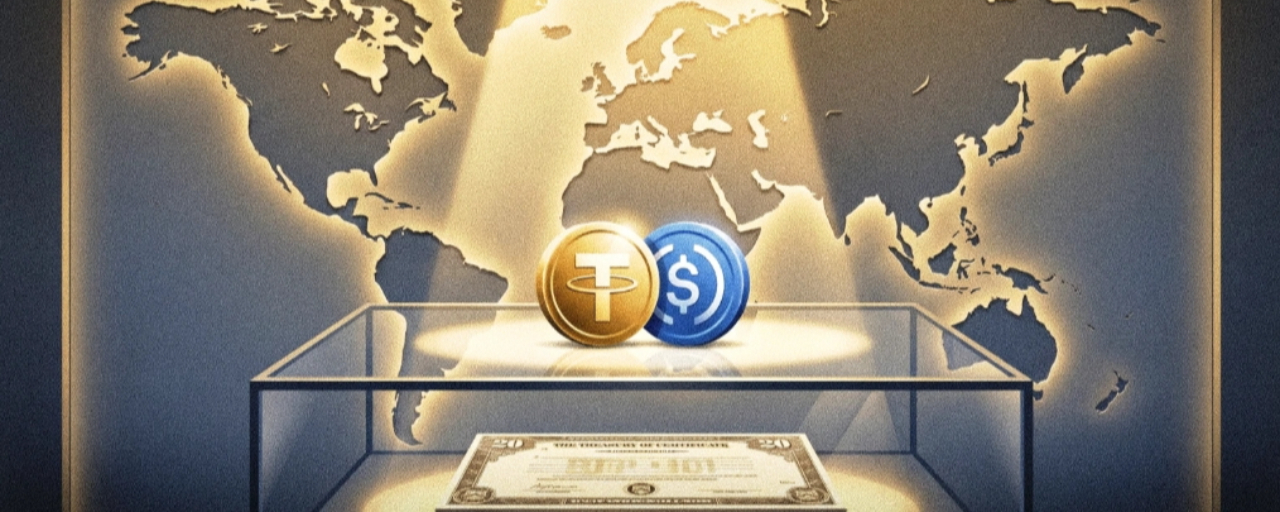
What caught my attention about stablecoins today is that the story is becoming much bigger than crypto payments.
The U.S. is reportedly exploring ways to promote dollar backed stablecoins overseas through public private partnerships. The stated strategic goal is to strengthen the dollar's position globally while potentially creating more demand for U.S. Treasury securities.
That connection actually makes sense when you look at how stablecoin reserves work.
Under the GENIUS Act framework payment stablecoins must be backed by assets such as cash and short maturity Treasury securities. Treasury's own advisory work has already identified stablecoin growth as a potential new source of demand for short term Treasuries.
This creates an interesting feedback loop.
More dollar stablecoins can mean more dollars moving through digital rails.
More stablecoin issuance can mean more demand for short term government debt.
And wider global usage can potentially strengthen the dollar's role in digital payments.
But I would not assume this automatically solves the Treasury market's larger problems.
Stablecoin issuers currently represent only a small share of the overall Treasury market. Treasury itself has also noted that stablecoin growth could partly replace demand that previously sat in bank deposits or money market funds rather than creating entirely new demand.
That distinction matters.
The really interesting question is what happens if stablecoins grow primarily because people outside the U.S. start holding more dollar exposure on chain.
Then stablecoins are no longer just a crypto product.
They become another channel through which global demand for dollars and short term U.S. government debt can develop.
That is why I think this narrative deserves attention.
The next phase of stablecoin growth may be less about trading crypto and more about who controls the digital rails for global dollar liquidity.
And that could make stablecoins one of the most important pieces of the Treasury market story to watch.