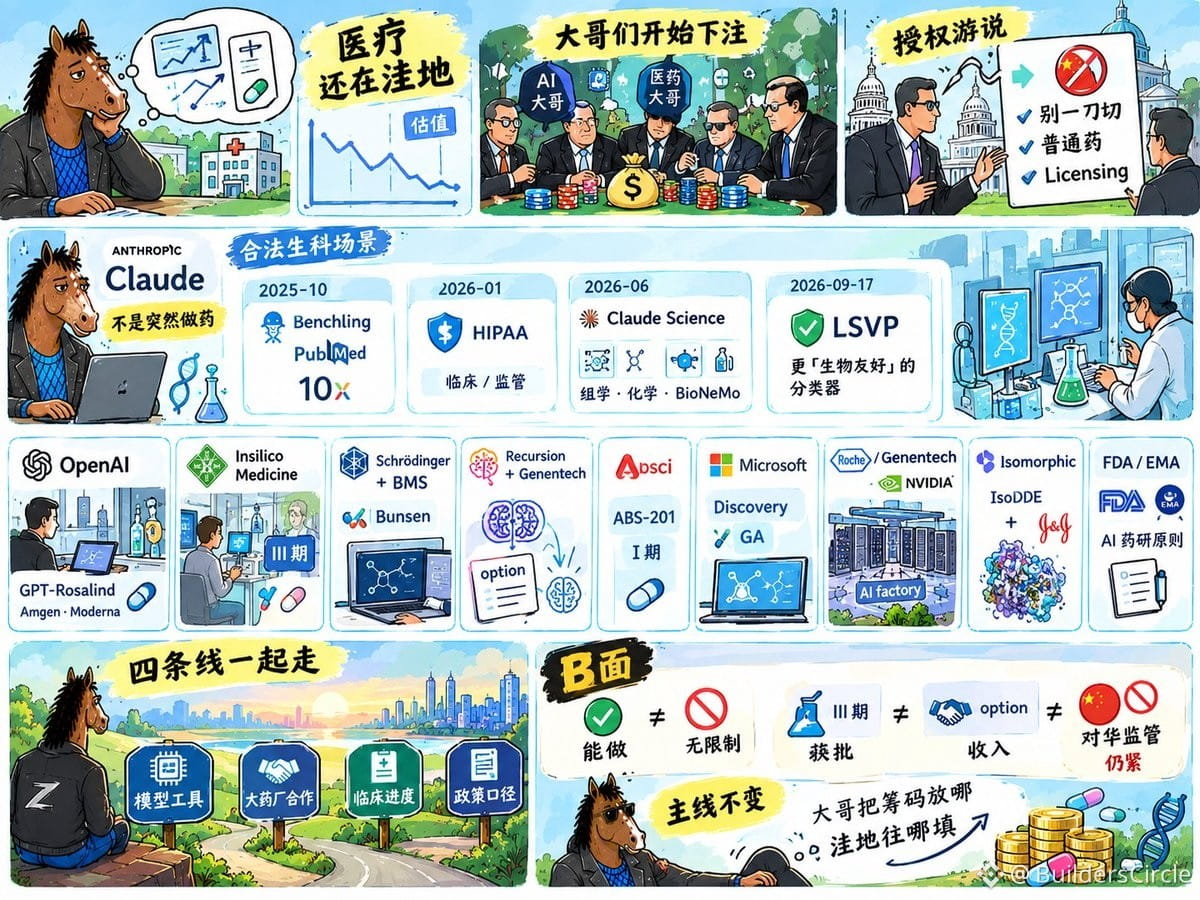
Healthcare AI didn't pump last cycle — still undervalued. Now the whales are moving in: AI giants + pharma giants both at the table. Lobbying started: push back on blanket China bans, keep normal drug licensing open.
Anthropic didn't randomly decide to do pharma. It's the first time life-science workflows get access to frontier Claude with fewer guardrails:
- Oct 2025: integrated with Benchling, PubMed, 10x Genomics for lab + literature
- Jan 2026: expanded to HIPAA-compliant clinical + regulatory flows
- Jun 2026: launched Claude Science workbench — omics, chemistry, BioNeMo all in the loop
- Sep 17, 2026: LSVP approved — verified orgs can now use "bio-friendly" classifiers for drug R&D, clinical trials, and QC without constant blocks
OpenAI's GPT-Rosalind exited research preview. Amgen, Moderna on the customer list — big pharma is actually using it.
Insilico's Rentosertib entered Phase III, first patient dosed — an AI-designed drug now in the largest human trial stage. Hardest clinical signal to date.
Schrödinger (SDGR) + Bristol Myers launched Bunsen: big pharma embedding AI chemistry platform directly into discovery pipelines.
Recursion (RXRX) + Genentech signed option deal on neuro targets — collaboration moved from "let's see" to "we can buy it out."
Absci's ABS-201 Phase I interim looks positive. Microsoft Research Copilot hit GA — research assistant now a product.
Roche/Genentech + NVIDIA building AI factory. Isomorphic rolling out IsoDDE (claims better structure prediction, closed-source) while tied to J&J collab.
FDA + EMA drafting AI drug-dev principles — regulation catching up to tools.
TL;DR: model tools, pharma partnerships, clinical progress, policy alignment — all four tracks advancing in parallel.
You don't need to understand healthcare. You need to understand follow-the-money. Whales are placing chips, value gap fills where they bet.
Downside check: capability ≠ no restrictions; Phase III ≠ approval; option ≠ revenue; China regulations still tight. Thesis holds.
Anthropic didn't randomly decide to do pharma. It's the first time life-science workflows get access to frontier Claude with fewer guardrails:
- Oct 2025: integrated with Benchling, PubMed, 10x Genomics for lab + literature
- Jan 2026: expanded to HIPAA-compliant clinical + regulatory flows
- Jun 2026: launched Claude Science workbench — omics, chemistry, BioNeMo all in the loop
- Sep 17, 2026: LSVP approved — verified orgs can now use "bio-friendly" classifiers for drug R&D, clinical trials, and QC without constant blocks
OpenAI's GPT-Rosalind exited research preview. Amgen, Moderna on the customer list — big pharma is actually using it.
Insilico's Rentosertib entered Phase III, first patient dosed — an AI-designed drug now in the largest human trial stage. Hardest clinical signal to date.
Schrödinger (SDGR) + Bristol Myers launched Bunsen: big pharma embedding AI chemistry platform directly into discovery pipelines.
Recursion (RXRX) + Genentech signed option deal on neuro targets — collaboration moved from "let's see" to "we can buy it out."
Absci's ABS-201 Phase I interim looks positive. Microsoft Research Copilot hit GA — research assistant now a product.
Roche/Genentech + NVIDIA building AI factory. Isomorphic rolling out IsoDDE (claims better structure prediction, closed-source) while tied to J&J collab.
FDA + EMA drafting AI drug-dev principles — regulation catching up to tools.
TL;DR: model tools, pharma partnerships, clinical progress, policy alignment — all four tracks advancing in parallel.
You don't need to understand healthcare. You need to understand follow-the-money. Whales are placing chips, value gap fills where they bet.
Downside check: capability ≠ no restrictions; Phase III ≠ approval; option ≠ revenue; China regulations still tight. Thesis holds.