


XRP derivatives exposure has contracted sharply since August 22, while sell-side activity has remained dominant across both Binance perpetuals and the broader centralized spot market.
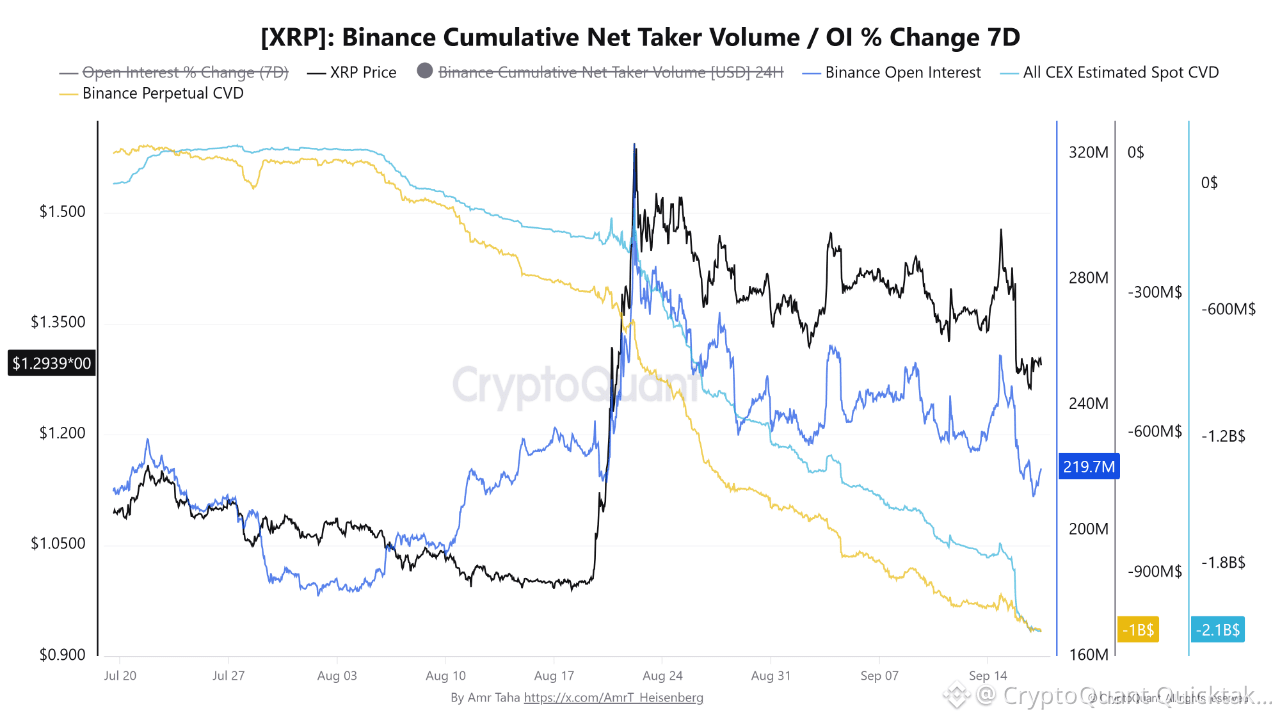
Binance XRP Open Interest fell from about $323M on August 22 to roughly $219M on September 17, a decline of around 32%. This means position closures outpaced new openings, reducing outstanding derivatives exposure by nearly one-third in less than four weeks.
Over the same period, XRP price fell by roughly 11%, making the percentage drop in Open Interest almost three times larger than the price decline.
Binance Perpetual CVD also fell from around -$361 million to -$1 billion, its lowest reading in the chart’s July-to-September window. All-CEX Estimated Spot CVD dropped even more sharply, from about -$111 million to -$2.1 billion, also reaching the lowest level shown in the period.
The Spot CVD shift was nearly $2 billion, more than three times the roughly $639 million decline in Perpetual CVD.
This indicates that sell-side taker activity was not limited to Binance derivatives but was also broad-based across centralized spot markets.
Lower Open Interest alongside negative Perpetual CVD is consistent with traders reducing leveraged exposure while aggressive sells continue to exceed aggressive buys.
A smaller Open Interest base may also reduce the amount of highly leveraged exposure in the market. This can help cool leverage-related imbalances and allow funding rates to remain closer to neutral.
If short positioning becomes dominant among the remaining open positions, funding rates could move further into cooling or negative territory.
The key signal is clear: XRP traders are reducing derivatives exposure while sell-side taker activity remains elevated across both futures and spot markets.
Historically, similar deleveraging phases have often favored price recovery, as excessive leverage is flushed out and the market becomes less vulnerable to long-liquidation cascades.
Written by Amr Taha