

ARIA Web3
69 Публікації

ARIA Web3
Поскаржитись
Заблокувати користувача
15 Підписки
15 Підписники
44 Вподобань
Публікації
PINNED
·
--
Оптимістично
Переглянути переклад
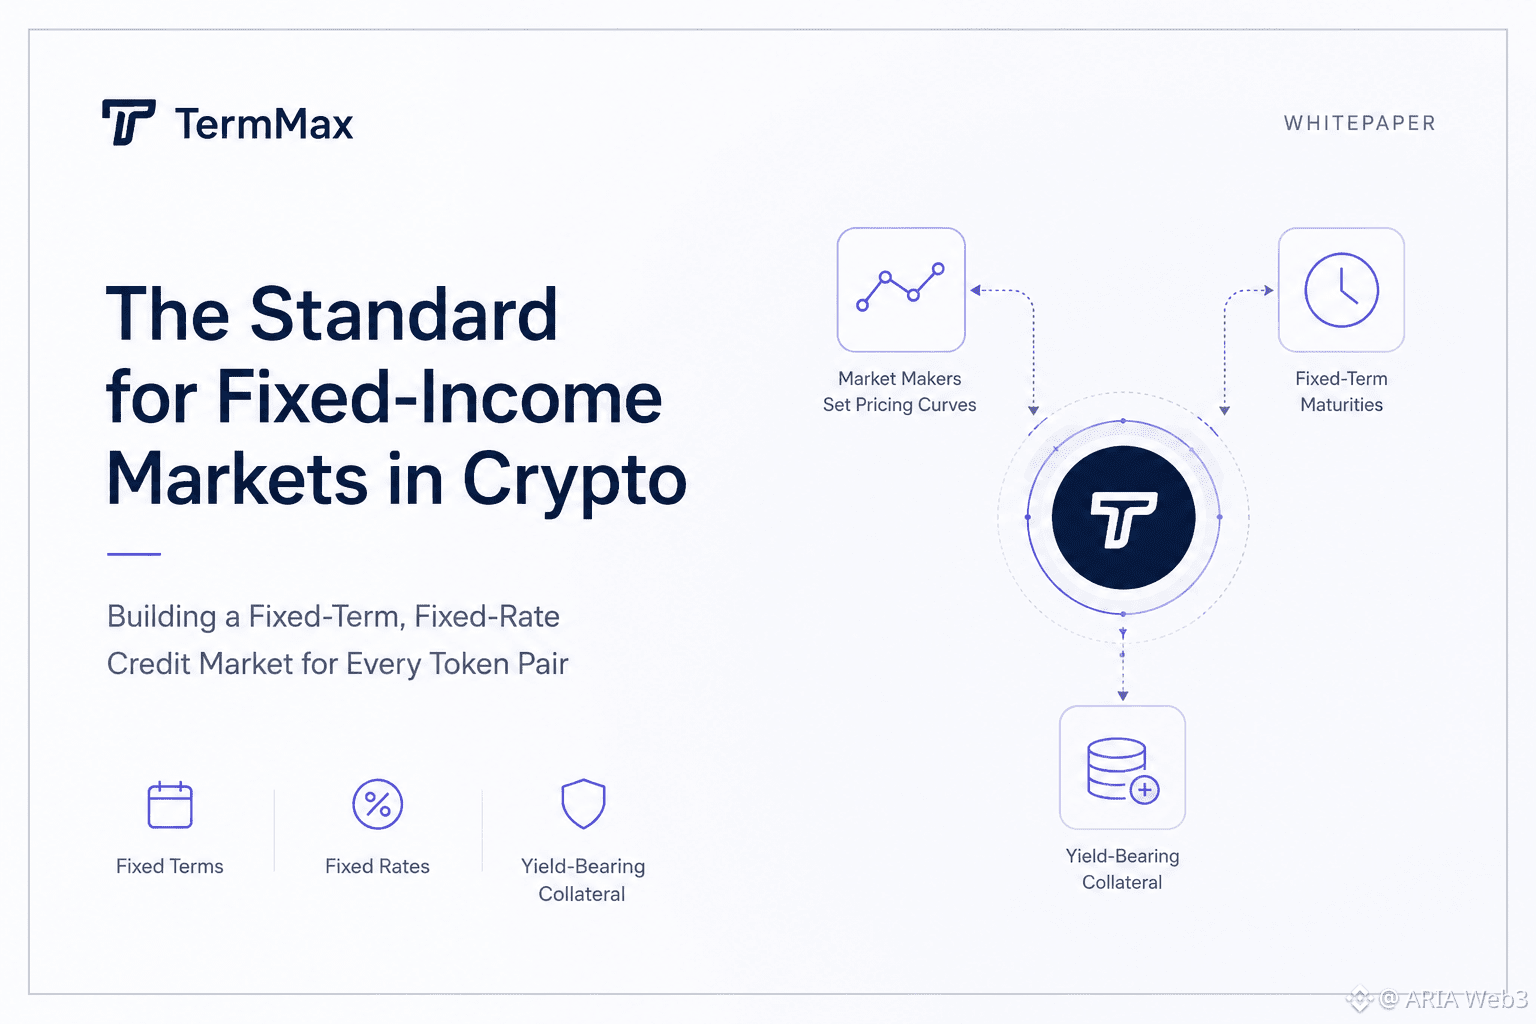
I was reading through TermMax's documentation, trying to figure out what they mean by calling themselves "the standard for fixed-income markets" in crypto. My first assumption was that this was just another lending protocol competing on rates.
After checking the official vision page, one detail caught my attention: they talk about building "an entire credit market for each token pair, just like what we have in real life." That phrase stuck with me, it's a different framing than most DeFi lending pitches.
That's when it clicked. The goal isn't just lending, it's giving every asset pair its own fixed-term, fixed-rate market, where market makers set the pricing curves. They also use yield-bearing tokens as collateral, so fixed terms bring predictability while the collateral itself keeps generating returns.
What surprised me was how intentional the limits feel. Fixed maturities mean less flexibility than open-ended lending, but that trade-off is what makes a real credit market possible on-chain in the first place.
With the TGE set for August 25, 2026, it feels less like a standalone launch and more like the next milestone in building that credit market out. I'm still wondering how much of the curve-setting process will eventually open up beyond curators.
#termmax @termmax
I was reading through TermMax's documentation, trying to figure out what they mean by calling themselves "the standard for fixed-income markets" in crypto. My first assumption was that this was just another lending protocol competing on rates.
After checking the official vision page, one detail caught my attention: they talk about building "an entire credit market for each token pair, just like what we have in real life." That phrase stuck with me, it's a different framing than most DeFi lending pitches.
That's when it clicked. The goal isn't just lending, it's giving every asset pair its own fixed-term, fixed-rate market, where market makers set the pricing curves. They also use yield-bearing tokens as collateral, so fixed terms bring predictability while the collateral itself keeps generating returns.
What surprised me was how intentional the limits feel. Fixed maturities mean less flexibility than open-ended lending, but that trade-off is what makes a real credit market possible on-chain in the first place.
With the TGE set for August 25, 2026, it feels less like a standalone launch and more like the next milestone in building that credit market out. I'm still wondering how much of the curve-setting process will eventually open up beyond curators.
#termmax @TermMax
1
1
85
·
--
Переглянути переклад
today live match, AS Roma vs Cagliari: Roma look like the clear favorites with a 74% win probability, while Cagliari have just 8%. I’m leaning towards a Roma win. #BinancePick
today live match, AS Roma vs Cagliari: Roma look like the clear favorites with a 74% win probability, while Cagliari have just 8%. I’m leaning towards a Roma win. #BinancePick
81
·
--
Вітаю «Інтер» із перемогою! Команда вже виглядає явним фаворитом. Я схиляюся до перемоги «Інтера», але футбол завжди може нас здивувати. #BinancePick
Вітаю «Інтер» із перемогою! Команда вже виглядає явним фаворитом. Я схиляюся до перемоги «Інтера», але футбол завжди може нас здивувати. #BinancePick
87
·
--
Переглянути переклад
#BinancePick Live, G2 Esports vs Dplus KIA
DK looks like the favorite with a 60% win chance, while G2 stands at 39%. Can G2 pull off an upset,
will DK take the win?
#BinancePick Live, G2 Esports vs Dplus KIA
DK looks like the favorite with a 60% win chance, while G2 stands at 39%. Can G2 pull off an upset,
will DK take the win?
DK looks like the favorite with a 60% win chance, while G2 stands at 39%. Can G2 pull off an upset,
will DK take the win?
67
·
--
Переглянути переклад
#BinancePick today live match, Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction.
#BinancePick today live match, Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction.
·
--
Оптимістично
Переглянути переклад
#BinancePick today, gen.g looks like the stronger side going into this match
#BinancePick today, gen.g looks like the stronger side going into this match
63
·
--
Переглянути переклад
#BinancePick Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction?
#BinancePick Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction?
78
·
--
Оптимістично
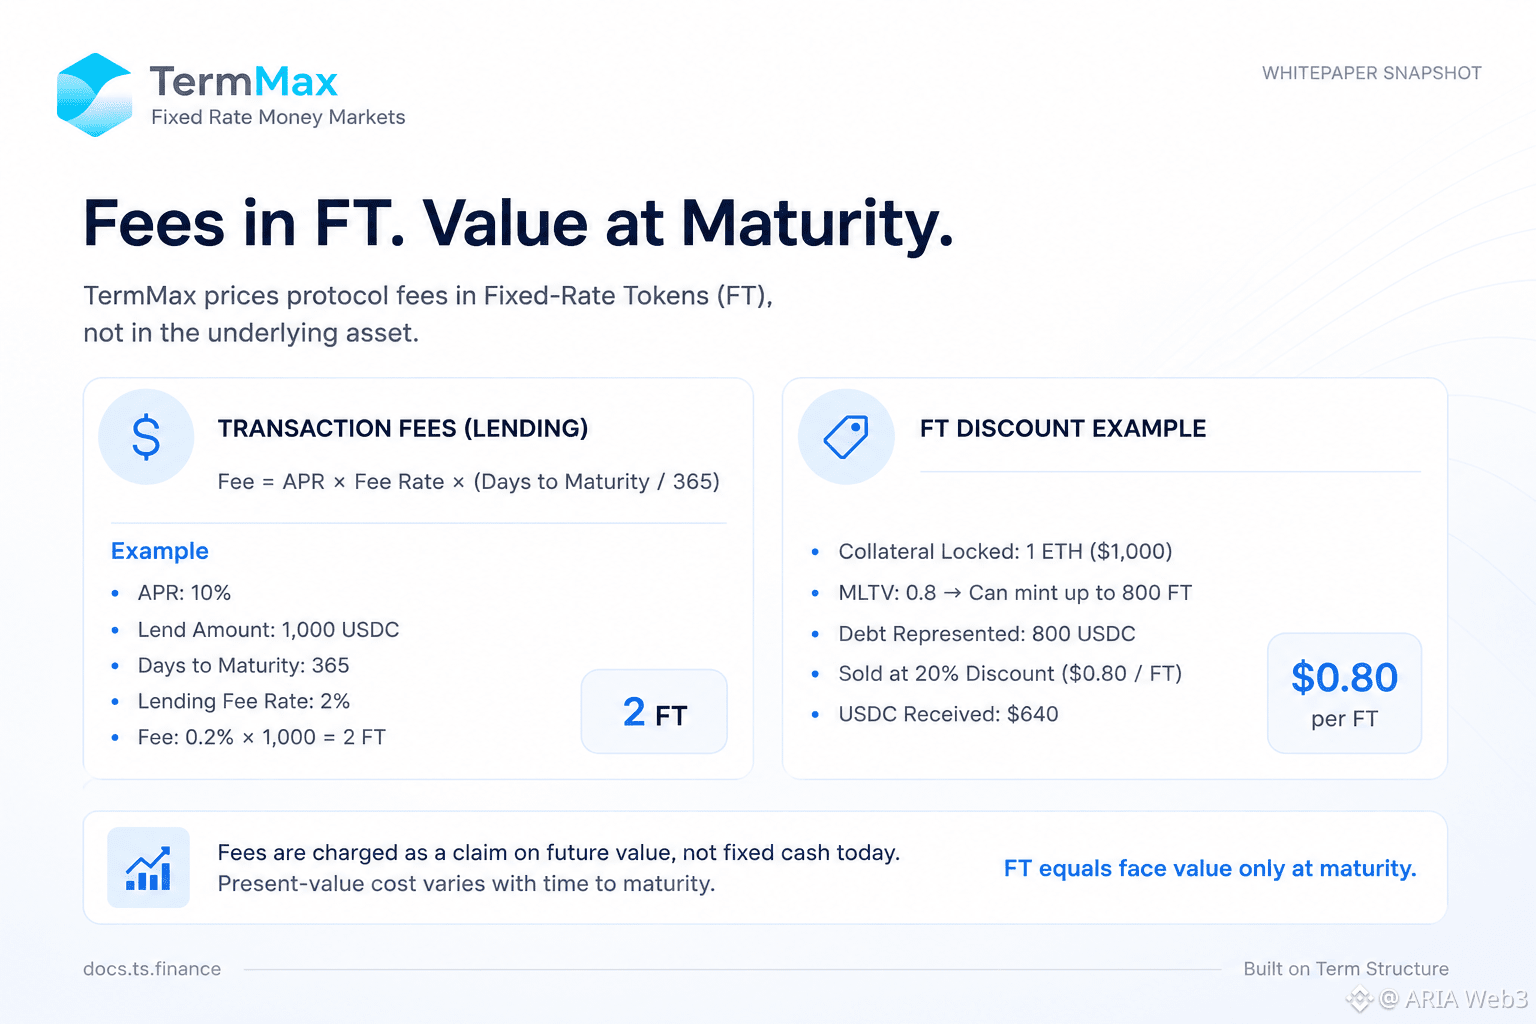
Я читав сторінку про комісії за транзакції TermMax на docs.ts.finance. Формули прості — APR × ставка комісії × (днів до погашення/365) — але одна деталь привернула мою увагу: комісії розраховуються "в одиницях FT", а не в USDC. Їхній власний приклад: видача в позику 1,000 USDC під 10% річних на 365 днів за ставки комісії 2% коштує всього 2 FT.
Я припустив, що це лише умовність відображення. Після перевірки документації Fixed-Rate Tokenization з’ясувалося, що це більш усвідомлено. FT — це дисконтний інструмент, який коштує номінальну вартість лише на дату погашення. У їхньому прикладі 800 FT продаються зі знижкою 20% ($0.80 за штуку) — тобто $640, а не $800.
Тоді мені стало зрозуміло: ціна комісій у FT означає стягнення вимоги до майбутньої вартості, а не фіксованих грошей сьогодні. Два позикодавці, які платять "однакову" комісію 2% у різні моменти до погашення, несуть різні витрати в теперішній вартості.
Схоже не на недолік, а на компроміс: прив’язувати комісії до одиниці, яку позикодавці вже тримають, замість того щоб щоразу конвертувати через USDC. Хоча досі неясно, як це узгоджується, коли протокол звітує про сукупні доходи від комісій в одній конкретній валюті.
Хтось знає, де це задокументовано?#termmax @termmax
Я читав сторінку про комісії за транзакції TermMax на docs.ts.finance. Формули прості — APR × ставка комісії × (днів до погашення/365) — але одна деталь привернула мою увагу: комісії розраховуються "в одиницях FT", а не в USDC. Їхній власний приклад: видача в позику 1,000 USDC під 10% річних на 365 днів за ставки комісії 2% коштує всього 2 FT.
Я припустив, що це лише умовність відображення. Після перевірки документації Fixed-Rate Tokenization з’ясувалося, що це більш усвідомлено. FT — це дисконтний інструмент, який коштує номінальну вартість лише на дату погашення. У їхньому прикладі 800 FT продаються зі знижкою 20% ($0.80 за штуку) — тобто $640, а не $800.
Тоді мені стало зрозуміло: ціна комісій у FT означає стягнення вимоги до майбутньої вартості, а не фіксованих грошей сьогодні. Два позикодавці, які платять "однакову" комісію 2% у різні моменти до погашення, несуть різні витрати в теперішній вартості.
Схоже не на недолік, а на компроміс: прив’язувати комісії до одиниці, яку позикодавці вже тримають, замість того щоб щоразу конвертувати через USDC. Хоча досі неясно, як це узгоджується, коли протокол звітує про сукупні доходи від комісій в одній конкретній валюті.
Хтось знає, де це задокументовано?#termmax @TermMax
4
5
80
·
--
Оптимістично
Переглянути переклад
I was reading through Dusk Trade's landing page expecting a typical RWA access page: join a waitlist, verify, invest. One detail caught my attention once I moved past that surface and into the documentation.
I assumed the product itself would be as simple as the page makes it sound: three steps, nothing more. After checking the official docs, the description shifts. Dusk Trade is called an application layer sitting above the base protocol, and the docs are explicit that it is not the base protocol itself. It turns market-infrastructure primitives into workflows covering asset discovery, investor onboarding, wallet connection, payment coordination, and settlement.
What surprised me was the gap between the two official sources. The landing page sells access in three steps. The docs describe eligibility checks, disclosure logic, and settlement that reconciles the asset leg with the payment leg before anything finalizes. That's when it clicked: the trade-off makes sense once you consider audience. A waitlist page has to convert visitors quickly, while documentation has to satisfy builders and regulators who need to know how eligibility and settlement actually get enforced on-chain. Still, I wonder how much of that complexity investors will actually see once the interface goes live, or whether it stays buried behind the clean three-step flow.
The landing page sells access in three steps. The docs describe eligibility, disclosure, and settlement logic underneath.
What matters most for Dusk Trade's success?
#dusk $DUSK @Dusk_Foundation
I was reading through Dusk Trade's landing page expecting a typical RWA access page: join a waitlist, verify, invest. One detail caught my attention once I moved past that surface and into the documentation.
I assumed the product itself would be as simple as the page makes it sound: three steps, nothing more. After checking the official docs, the description shifts. Dusk Trade is called an application layer sitting above the base protocol, and the docs are explicit that it is not the base protocol itself. It turns market-infrastructure primitives into workflows covering asset discovery, investor onboarding, wallet connection, payment coordination, and settlement.
What surprised me was the gap between the two official sources. The landing page sells access in three steps. The docs describe eligibility checks, disclosure logic, and settlement that reconciles the asset leg with the payment leg before anything finalizes. That's when it clicked: the trade-off makes sense once you consider audience. A waitlist page has to convert visitors quickly, while documentation has to satisfy builders and regulators who need to know how eligibility and settlement actually get enforced on-chain. Still, I wonder how much of that complexity investors will actually see once the interface goes live, or whether it stays buried behind the clean three-step flow.
The landing page sells access in three steps. The docs describe eligibility, disclosure, and settlement logic underneath.
What matters most for Dusk Trade's success?
#dusk $DUSK @Dusk
Compliance design
50%
Liquidity depth
50%
Onboarding speed
0%
Investor trust
0%
4 Голосів • Голосування закрито
1
1
83
·
--
Оптимістично
Переглянути переклад
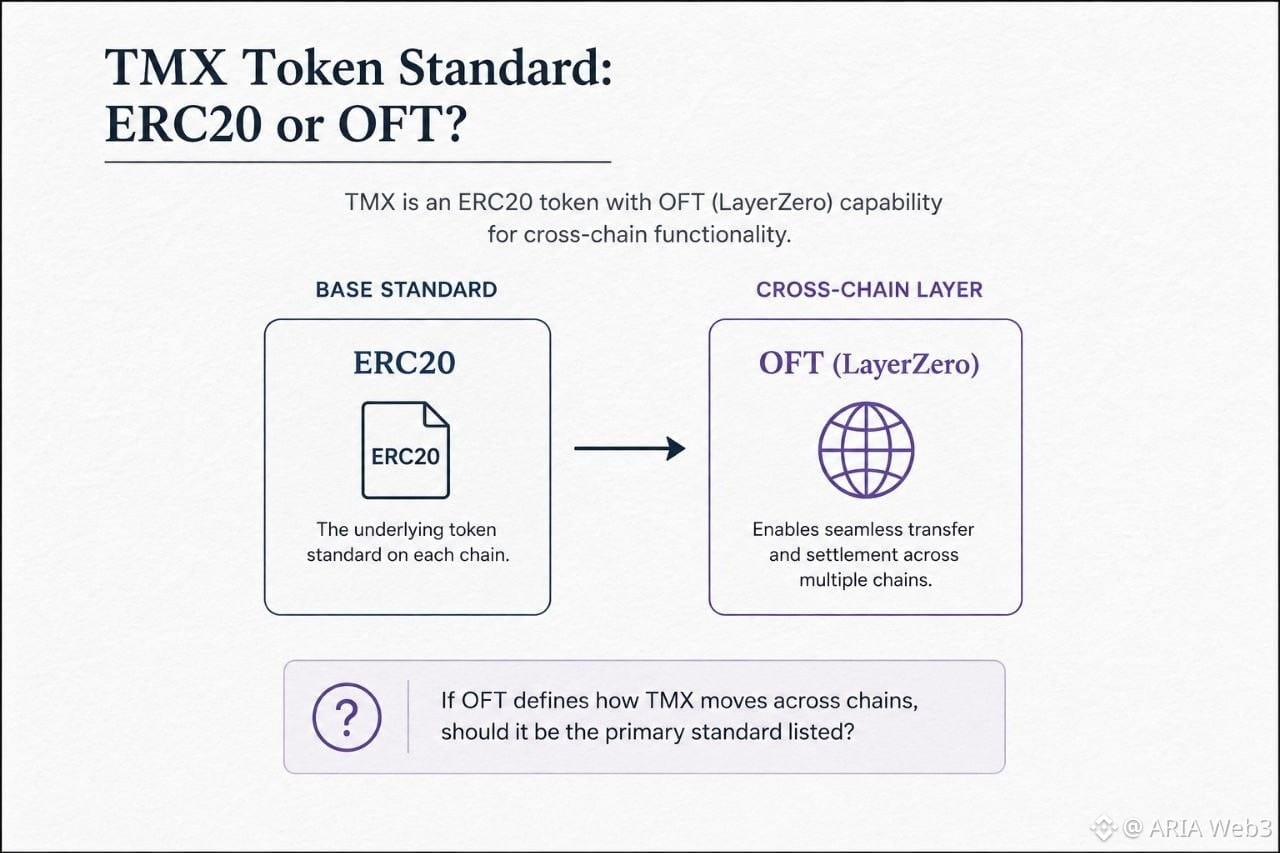
I was scrolling through the TMX tokenomics table and stopped at the Standard field. It just says ERC20, listed as a plain, separate line item from the token address and total supply. One detail caught my attention a few lines above it though. The Bridge Mechanism field describes TMX as a LayerZero OFT, an Omnichain Fungible Token, deployed on Ethereum and BNB Chain with more EVM chains supported. I assumed OFT would replace ERC20 as the listed standard, since it's the newer cross-chain spec.
After checking the executive summary section of the same whitepaper, the terminology got less consistent, not more. There, the token standard is written as ERC20 (OFT on multiple blockchains), treating OFT as a bracketed extension rather than the primary classification. So within the same document, TMX is presented once as ERC20 with OFT as a side note, and once as ERC20 sitting quietly next to a full OFT description with no explicit link between the two. That's when it clicked that this isn't really a contradiction, LayerZero's OFT standard is built as a wrapper around ERC20, adding cross-chain messaging without changing the base token behavior on any single chain. So calling it ERC20 isn't wrong, it's just incomplete without the bridge mechanism line filling in the rest.
Still, it raises a fair question: if OFT defines how the token actually moves and settles across chains, should it be the primary standard listed, with ERC20 treated as the underlying implementation detail instead of the headline?
#termmax @termmax
I was scrolling through the TMX tokenomics table and stopped at the Standard field. It just says ERC20, listed as a plain, separate line item from the token address and total supply. One detail caught my attention a few lines above it though. The Bridge Mechanism field describes TMX as a LayerZero OFT, an Omnichain Fungible Token, deployed on Ethereum and BNB Chain with more EVM chains supported. I assumed OFT would replace ERC20 as the listed standard, since it's the newer cross-chain spec.
After checking the executive summary section of the same whitepaper, the terminology got less consistent, not more. There, the token standard is written as ERC20 (OFT on multiple blockchains), treating OFT as a bracketed extension rather than the primary classification. So within the same document, TMX is presented once as ERC20 with OFT as a side note, and once as ERC20 sitting quietly next to a full OFT description with no explicit link between the two. That's when it clicked that this isn't really a contradiction, LayerZero's OFT standard is built as a wrapper around ERC20, adding cross-chain messaging without changing the base token behavior on any single chain. So calling it ERC20 isn't wrong, it's just incomplete without the bridge mechanism line filling in the rest.
Still, it raises a fair question: if OFT defines how the token actually moves and settles across chains, should it be the primary standard listed, with ERC20 treated as the underlying implementation detail instead of the headline?
#termmax @TermMax
10
4
76
·
--
Оптимістично
Я читав розділ про налаштування сеттерів діапазону позик (borrowing range order setters) і одна цифра мене зупинила: у прикладі Аліса блокує 1 ETH, отримує матчинг на 500 USDC, і її GT зрештою записує 535 FTs як борг. Мій перший здогад був такий, що вона нібито якимось чином позичила більше, ніж отримала.
Перевіривши ще раз механіку в розділі, я побачив, що це не так. 500 USDC фінансують 500 FTs (principal) і 500 XTs (interest). XTs обмінюються всередині її власної range order на ще 35 додаткових FTs, карбованих з її GT — саме це й підштовхує зафіксований борг до 535. Вона ніколи не торкається XT сама.
Мене здивувало те, що XT тут не просто простоює: це механізм, який перетворює плаваюче зобов’язання зі сплати відсотків на фіксоване ще до того, як позика навіть врегулюється. Замість того, щоб відсотки нараховувалися з часом, вони оцінюються та фіксуються у вигляді додаткових FTs у момент матчингу. Компроміс полягає в тому, що GT борг сеттера borrowing order — це не лише «що я позичив», а «що я позичив плюс відсоток, який я вже погодився сплатити», і це видно в on-chain уже з першого дня, а не нараховується тихо з плином часу. Схоже, це навмисно: фіксованій ставці позики потрібне повне зобов’язання, зафіксоване наперед, а не розраховане пізніше. Проте мені все ще цікаво, як саме крива ціноутворення визначає розподіл між ранніми заповненнями на 8% і пізнішими заповненнями ближче до 6% в межах того ж самого ордера.
#termmax @termmax
Я читав розділ про налаштування сеттерів діапазону позик (borrowing range order setters) і одна цифра мене зупинила: у прикладі Аліса блокує 1 ETH, отримує матчинг на 500 USDC, і її GT зрештою записує 535 FTs як борг. Мій перший здогад був такий, що вона нібито якимось чином позичила більше, ніж отримала.
Перевіривши ще раз механіку в розділі, я побачив, що це не так. 500 USDC фінансують 500 FTs (principal) і 500 XTs (interest). XTs обмінюються всередині її власної range order на ще 35 додаткових FTs, карбованих з її GT — саме це й підштовхує зафіксований борг до 535. Вона ніколи не торкається XT сама.
Мене здивувало те, що XT тут не просто простоює: це механізм, який перетворює плаваюче зобов’язання зі сплати відсотків на фіксоване ще до того, як позика навіть врегулюється. Замість того, щоб відсотки нараховувалися з часом, вони оцінюються та фіксуються у вигляді додаткових FTs у момент матчингу. Компроміс полягає в тому, що GT борг сеттера borrowing order — це не лише «що я позичив», а «що я позичив плюс відсоток, який я вже погодився сплатити», і це видно в on-chain уже з першого дня, а не нараховується тихо з плином часу. Схоже, це навмисно: фіксованій ставці позики потрібне повне зобов’язання, зафіксоване наперед, а не розраховане пізніше. Проте мені все ще цікаво, як саме крива ціноутворення визначає розподіл між ранніми заповненнями на 8% і пізнішими заповненнями ближче до 6% в межах того ж самого ордера.
#termmax @TermMax

6
1
80
·
--
Оптимістично
Переглянути переклад
I was reading through TermMax's docs to understand how they handle leveraged positions, and one detail caught my attention: the Gearing Token isn't an ERC-20 like everything else in the system.
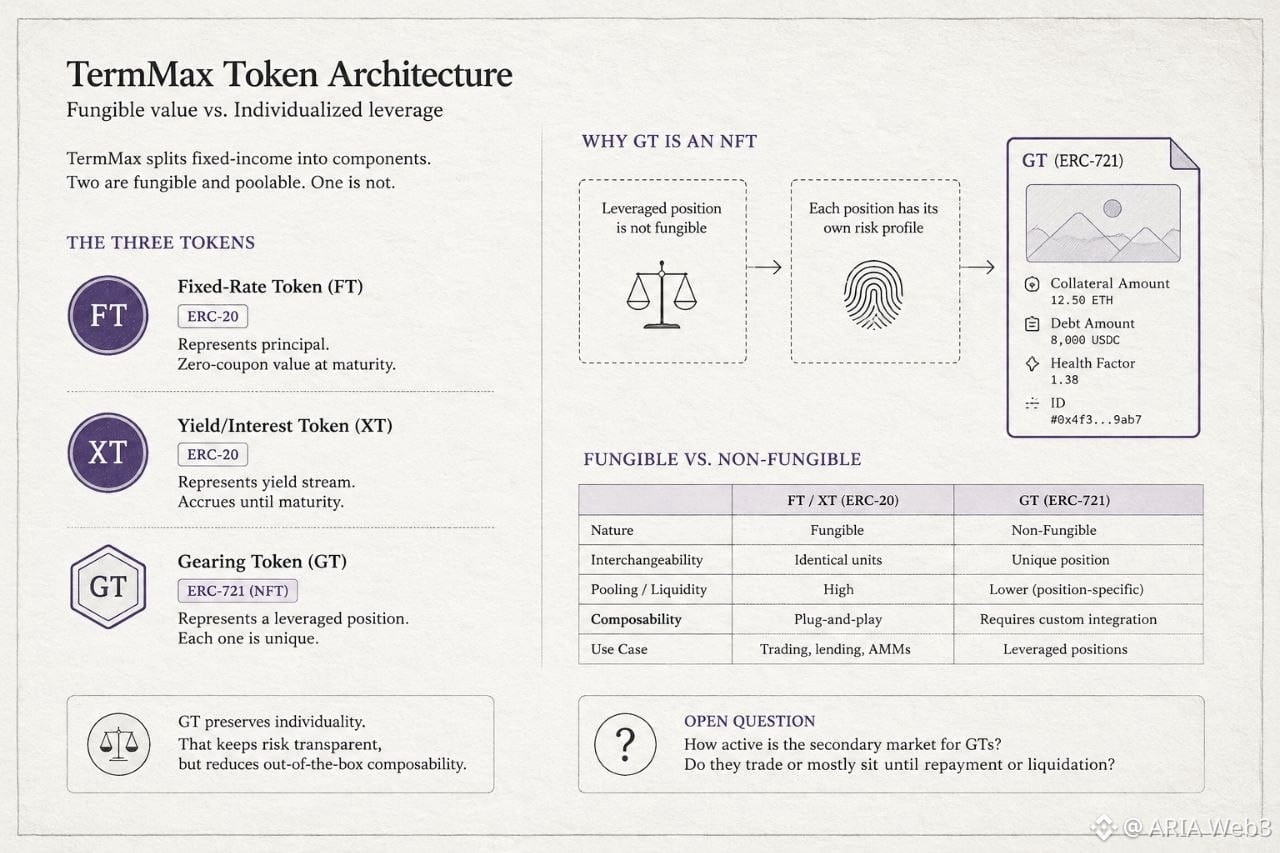
I assumed all three of TermMax's tokens — FT, XT, and GT — would follow the same standard, since the introduction page talks about "Gearing Token and Fixed-rate Token trading" almost interchangeably, like they're just different flavors of the same tradable asset. After checking the docs page on token components, that assumption didn't hold. FT and XT are both ERC-20, representing principal and interest as fungible, poolable value. GT, though, is an ERC-721 NFT. Each one encapsulates a specific collateral amount, a specific debt, and its own health factor as metadata.
What surprised me was realizing why. A leveraged position isn't really a fungible claim — two GTs with the same face value could carry different collateral ratios or liquidation risk. Making it an NFT preserves that individuality instead of averaging it away in a shared pool. The trade-off is composability. Fungible tokens are easier to plug into other protocols; NFTs require more custom integration work from anyone building on top of TermMax.
Still not sure how that affects secondary-market liquidity for GT positions themselves. Anyone looked into whether GTs trade actively, or mostly just sit until repayment or liquidation? @termmax #termmax
I was reading through TermMax's docs to understand how they handle leveraged positions, and one detail caught my attention: the Gearing Token isn't an ERC-20 like everything else in the system.
I assumed all three of TermMax's tokens — FT, XT, and GT — would follow the same standard, since the introduction page talks about "Gearing Token and Fixed-rate Token trading" almost interchangeably, like they're just different flavors of the same tradable asset. After checking the docs page on token components, that assumption didn't hold. FT and XT are both ERC-20, representing principal and interest as fungible, poolable value. GT, though, is an ERC-721 NFT. Each one encapsulates a specific collateral amount, a specific debt, and its own health factor as metadata.
What surprised me was realizing why. A leveraged position isn't really a fungible claim — two GTs with the same face value could carry different collateral ratios or liquidation risk. Making it an NFT preserves that individuality instead of averaging it away in a shared pool. The trade-off is composability. Fungible tokens are easier to plug into other protocols; NFTs require more custom integration work from anyone building on top of TermMax.
Still not sure how that affects secondary-market liquidity for GT positions themselves. Anyone looked into whether GTs trade actively, or mostly just sit until repayment or liquidation? @TermMax #termmax
1
1
69
·
--
Оптимістично
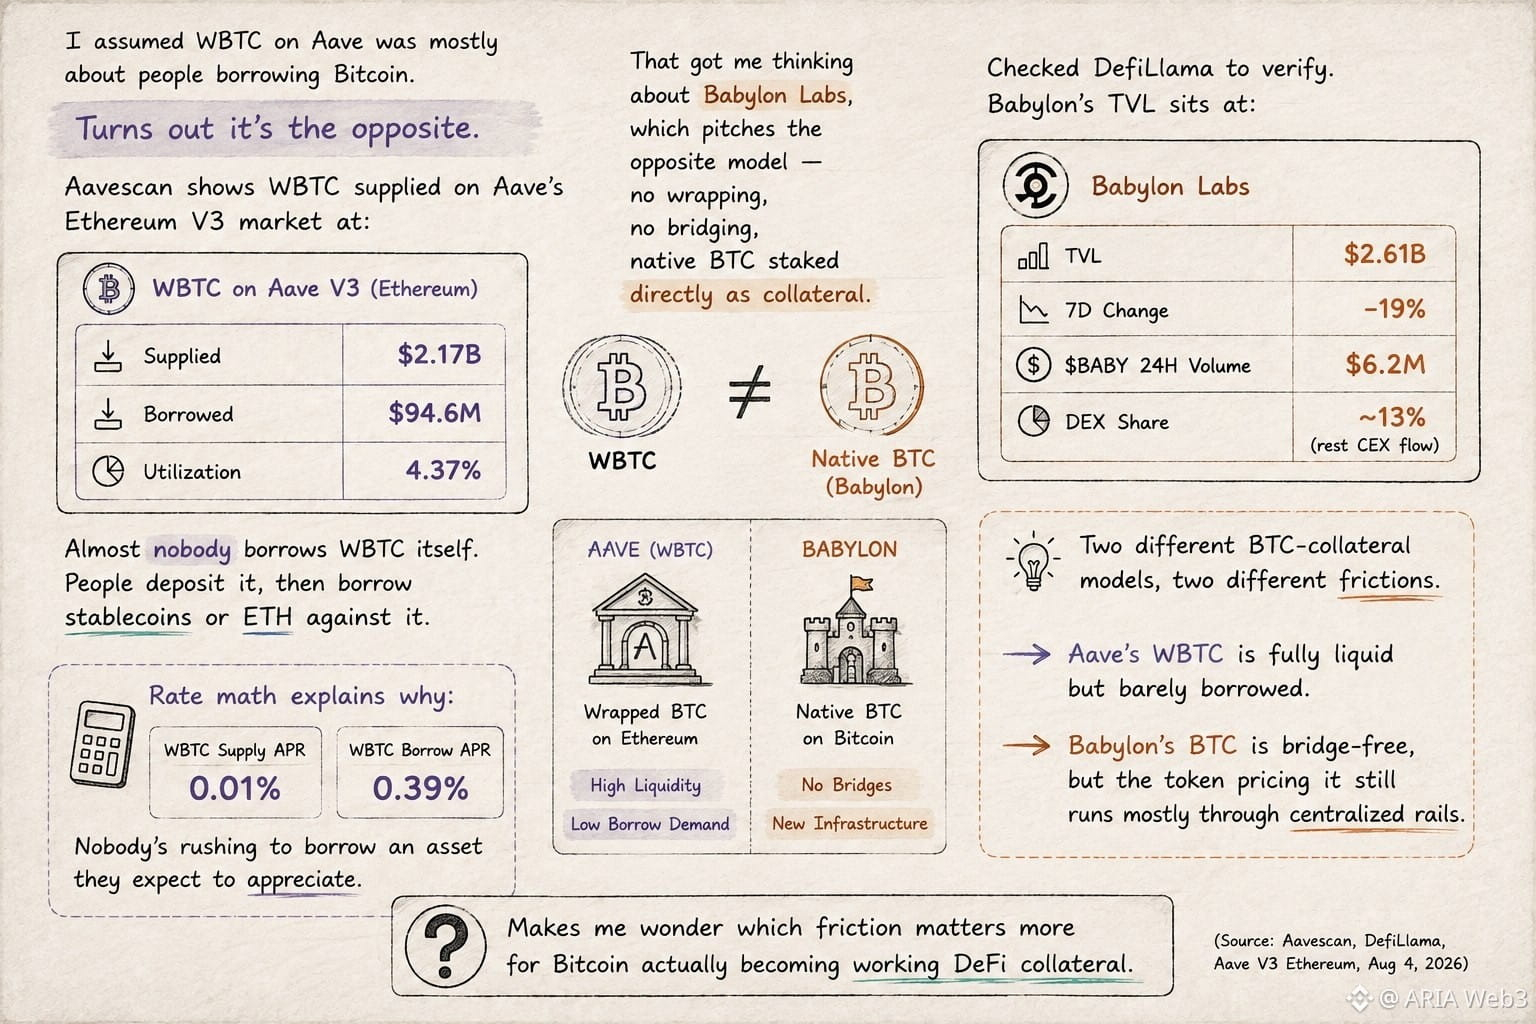
Я припустив, що WBTC на Aave — це переважно про те, як люди позичають Bitcoin.
Але виявилось навпаки.
Aavescan показує, що WBTC, який постачають на Aave на ринку Ethereum V3, становить $2.17B. Позичено: лише $94.6M. Завантаження: 4.37%.
Майже ніхто не бере в позику сам WBTC. Люди його депонують, а потім позичають під нього стейблкоїни або ETH.
Це змусило мене задуматись про @babylonlabs_io , який пропонує протилежну модель — без обгортання, без бриджів: нативний BTC напряму стейкається як заставу.
Перевірив у DefiLlama. TVL Babylon становить $2.61B, і знизився на 19% за минулий тиждень. $BABY робить близько $6.2M у обсязі за 24 години, але лише ~13% цього торгується на DEX — решта це потік централізованих бірж.
Дві різні моделі BTC-застави, дві різні тертя. WBTC від Aave повністю ліквідний, але його майже не беруть у позику. BTC від Babylon без бриджу, але ціни на токен усе ще значною мірою проходять через централізовані канали.
Мене змушує замислитись, яке саме тертя важливіше для того, щоб Bitcoin реально став робочою DeFi-заставою.
#baby
Я припустив, що WBTC на Aave — це переважно про те, як люди позичають Bitcoin.
Але виявилось навпаки.
Aavescan показує, що WBTC, який постачають на Aave на ринку Ethereum V3, становить $2.17B. Позичено: лише $94.6M. Завантаження: 4.37%.
Майже ніхто не бере в позику сам WBTC. Люди його депонують, а потім позичають під нього стейблкоїни або ETH.
Це змусило мене задуматись про @BabylonLabs_io , який пропонує протилежну модель — без обгортання, без бриджів: нативний BTC напряму стейкається як заставу.
Перевірив у DefiLlama. TVL Babylon становить $2.61B, і знизився на 19% за минулий тиждень. $BABY робить близько $6.2M у обсязі за 24 години, але лише ~13% цього торгується на DEX — решта це потік централізованих бірж.
Дві різні моделі BTC-застави, дві різні тертя. WBTC від Aave повністю ліквідний, але його майже не беруть у позику. BTC від Babylon без бриджу, але ціни на токен усе ще значною мірою проходять через централізовані канали.
Мене змушує замислитись, яке саме тертя важливіше для того, щоб Bitcoin реально став робочою DeFi-заставою.
#baby
2
99
·
--
Оптимістично
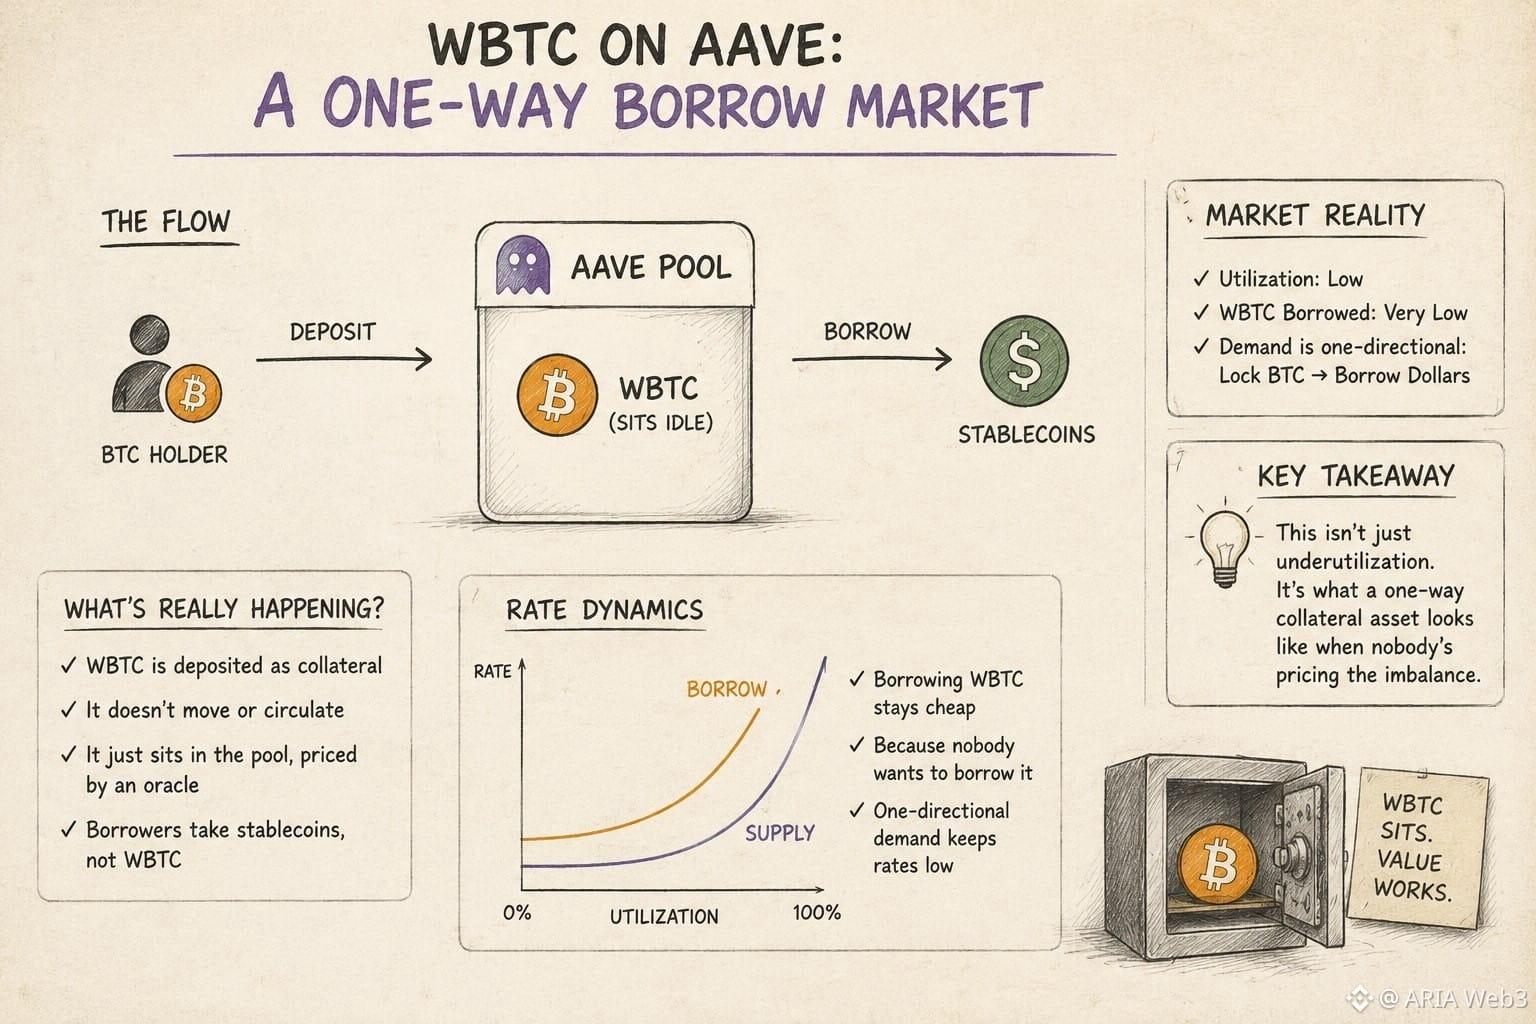
Я припустив, що запозичення під заставу WBTC на Aave означає, що біткоїн виконує подвійну роль — як застава, при цьому його вартість підкріплює позику в іншому місці.
Насправді все простіше — і водночас дивніше.
WBTC у пулі не циркулює. Він просто лежить, оцінюється оракулом, поки під нього позичають чиїсь інші стейблкоїни.
Я звірив історію ставок Aave та актуальні ринки WBTC на Aavescan, щоб це підтвердити. Використання залишається низьким. Майже ніхто не бере в позику сам WBTC.
Що кидалося в очі: попит однобічний. Люди блокують BTC, щоб позичити долари, а не навпаки.
Це формує криву ставок. Модель Aave оцінює ту сторону, якій бракує ліквідності — і оскільки власники BTC рідко хочуть позичати свій BTC, його запозичення залишається дешевим за задумом, а не випадково.
Це ринок, де «сторона запозичення» в запозичувальному ринку майже не використовується.
Задумуюсь, чи це справді недовикористання, чи просто те, як виглядає однобічний актив-застава, коли ніхто не цінив несиметричність.
#baby $BABY @babylonlabs_io
Я припустив, що запозичення під заставу WBTC на Aave означає, що біткоїн виконує подвійну роль — як застава, при цьому його вартість підкріплює позику в іншому місці.
Насправді все простіше — і водночас дивніше.
WBTC у пулі не циркулює. Він просто лежить, оцінюється оракулом, поки під нього позичають чиїсь інші стейблкоїни.
Я звірив історію ставок Aave та актуальні ринки WBTC на Aavescan, щоб це підтвердити. Використання залишається низьким. Майже ніхто не бере в позику сам WBTC.
Що кидалося в очі: попит однобічний. Люди блокують BTC, щоб позичити долари, а не навпаки.
Це формує криву ставок. Модель Aave оцінює ту сторону, якій бракує ліквідності — і оскільки власники BTC рідко хочуть позичати свій BTC, його запозичення залишається дешевим за задумом, а не випадково.
Це ринок, де «сторона запозичення» в запозичувальному ринку майже не використовується.
Задумуюсь, чи це справді недовикористання, чи просто те, як виглядає однобічний актив-застава, коли ніхто не цінив несиметричність.
#baby $BABY @BabylonLabs_io
2
90
·
--
Оптимістично
Частково правда
Переглянути переклад
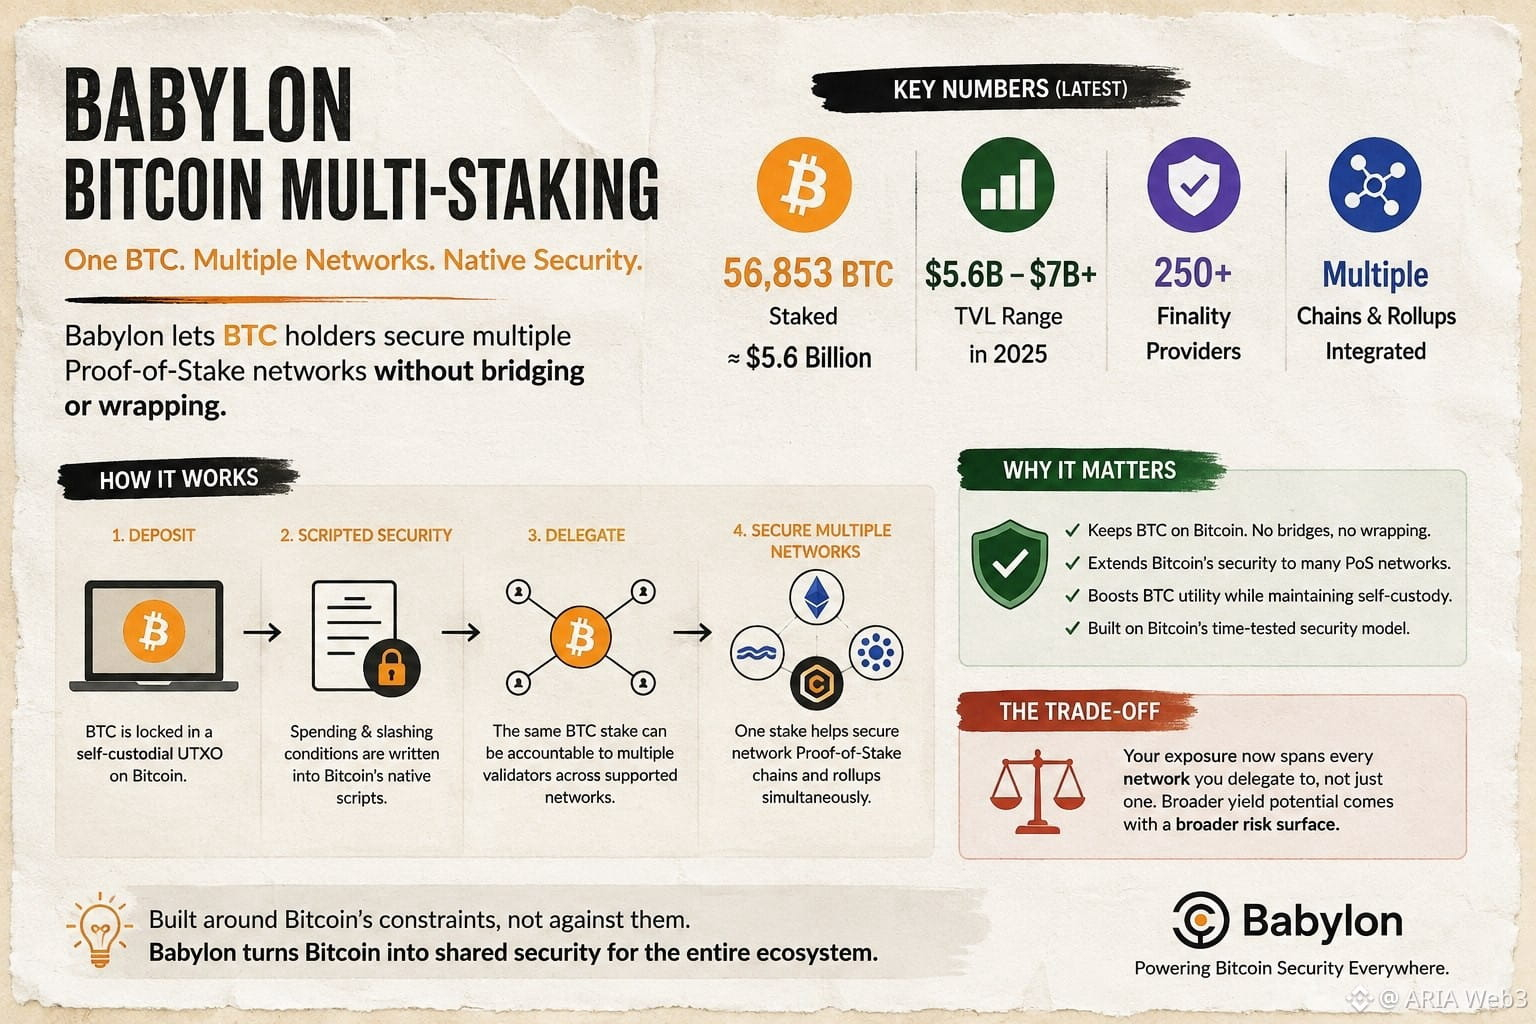
I assumed Bitcoin staking worked like typical restaking, pick a chain, commit your assets. So I checked Babylon's official documentation to confirm.
That's when it clicked. Babylon currently secures roughly 56,853 BTC, about $5.6 billion in value, across more than 250 finality providers. The BTC stays locked in a self-custodial UTXO on Bitcoin itself, no bridging, no wrapping, and that same stake can back multiple Bitcoin Supercharged Networks at once.
What surprised me was the mechanism. Spending and slashing conditions are written directly into Bitcoin's scripting layer, so one locked position can be accountable to several validators simultaneously, without ever leaving the Bitcoin chain.
The trade-off is straightforward: your exposure now spans every network you delegate to, not just one. That's the cost of shared security, broader yield potential in exchange for broader risk surface.
With TVL having ranged between $5.6 billion and over $7 billion this year, I keep wondering how stakers are actually balancing that spread, chasing more rewards, or spreading risk more carefully.#baby $BABY @babylonlabs_io
I assumed Bitcoin staking worked like typical restaking, pick a chain, commit your assets. So I checked Babylon's official documentation to confirm.
That's when it clicked. Babylon currently secures roughly 56,853 BTC, about $5.6 billion in value, across more than 250 finality providers. The BTC stays locked in a self-custodial UTXO on Bitcoin itself, no bridging, no wrapping, and that same stake can back multiple Bitcoin Supercharged Networks at once.
What surprised me was the mechanism. Spending and slashing conditions are written directly into Bitcoin's scripting layer, so one locked position can be accountable to several validators simultaneously, without ever leaving the Bitcoin chain.
The trade-off is straightforward: your exposure now spans every network you delegate to, not just one. That's the cost of shared security, broader yield potential in exchange for broader risk surface.
With TVL having ranged between $5.6 billion and over $7 billion this year, I keep wondering how stakers are actually balancing that spread, chasing more rewards, or spreading risk more carefully.#baby $BABY @BabylonLabs_io
6
1
81
·
--
Оптимістично
Переглянути переклад
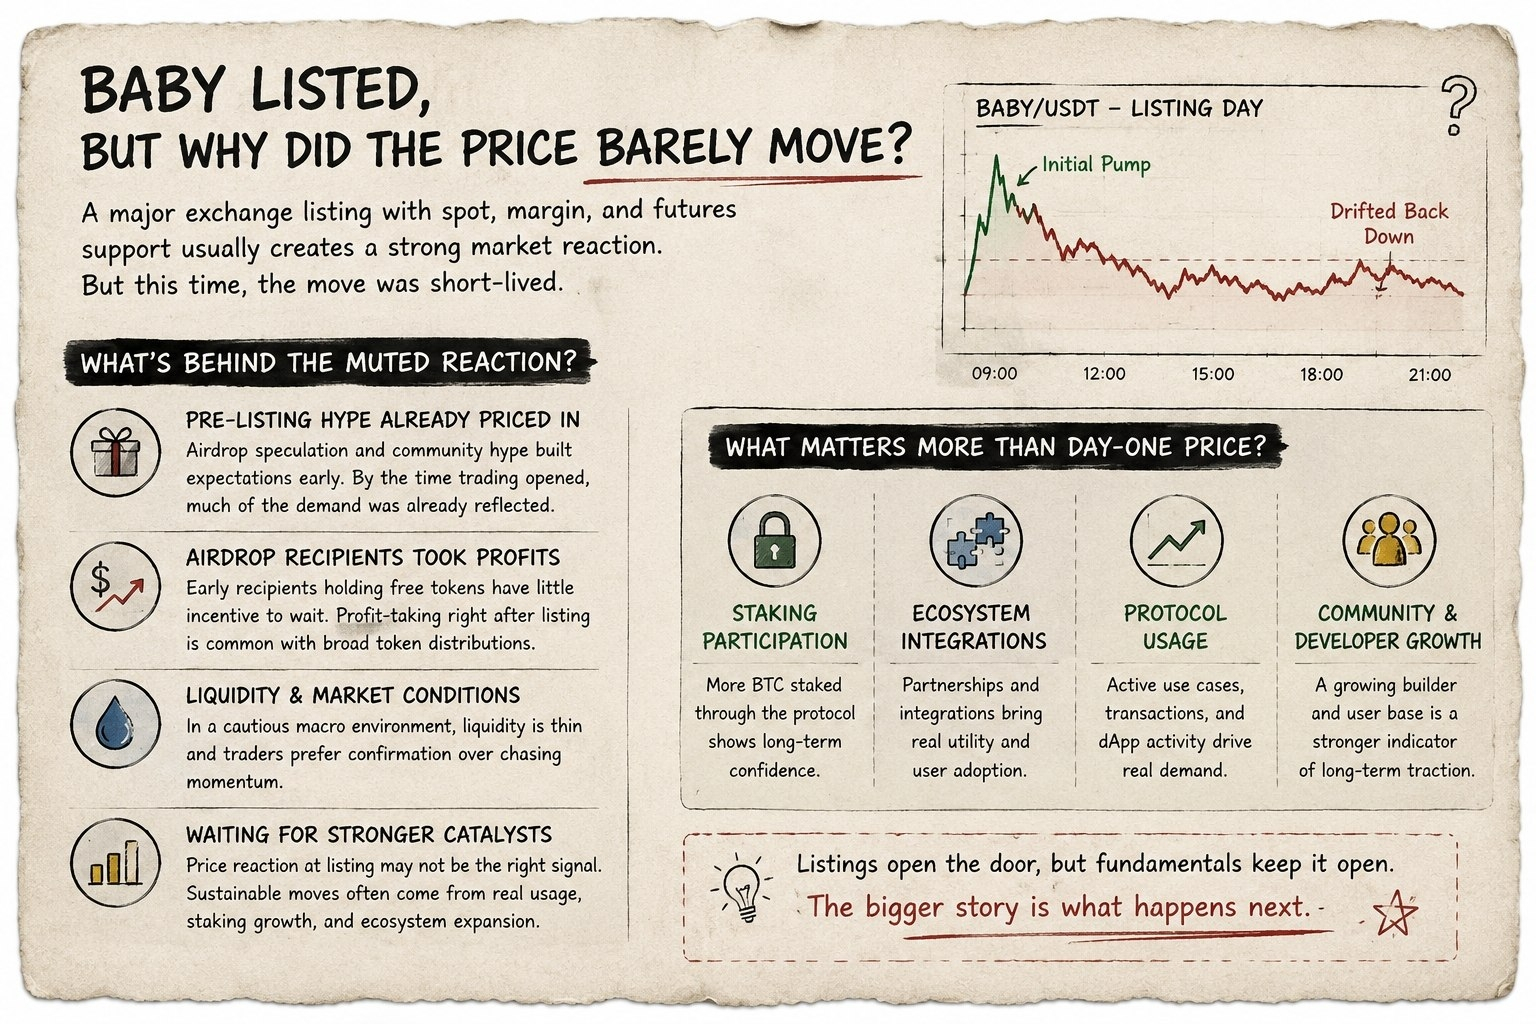
I was reading through recent listing data for BABY, and one detail caught my attention: despite landing on a major exchange with full spot, margin, and futures support, the price barely moved beyond an initial pop before drifting back down. I assumed a listing that big would trigger a sustained rally, so the muted follow-through confused me.
After checking exchange notices and on-chain activity around the listing date, a pattern emerged. Much of the anticipated demand had likely already been priced in through pre-listing airdrop speculation and community hype. That's when it clicked — by the time trading actually opened, a lot of the "buy the news" enthusiasm had already played out as "sell the news."
What surprised me was the airdrop angle. Early recipients holding free tokens have little incentive to wait, so a wave of profit-taking right after listing is a common trade-off of broad token distributions, not a flaw unique to this project.
Liquidity conditions and overall market sentiment matter too. In a cautious macro environment, traders tend to wait for confirmation rather than chase momentum.
It made me wonder whether price reaction at listing is even the right signal to watch. Maybe the more meaningful catalysts — staking participation, ecosystem integrations, actual protocol usage — simply haven't arrived yet. What would you consider a stronger indicator of long-term traction than day-one price action?#baby @babylonlabs_io $BABY
I was reading through recent listing data for BABY, and one detail caught my attention: despite landing on a major exchange with full spot, margin, and futures support, the price barely moved beyond an initial pop before drifting back down. I assumed a listing that big would trigger a sustained rally, so the muted follow-through confused me.
After checking exchange notices and on-chain activity around the listing date, a pattern emerged. Much of the anticipated demand had likely already been priced in through pre-listing airdrop speculation and community hype. That's when it clicked — by the time trading actually opened, a lot of the "buy the news" enthusiasm had already played out as "sell the news."
What surprised me was the airdrop angle. Early recipients holding free tokens have little incentive to wait, so a wave of profit-taking right after listing is a common trade-off of broad token distributions, not a flaw unique to this project.
Liquidity conditions and overall market sentiment matter too. In a cautious macro environment, traders tend to wait for confirmation rather than chase momentum.
It made me wonder whether price reaction at listing is even the right signal to watch. Maybe the more meaningful catalysts — staking participation, ecosystem integrations, actual protocol usage — simply haven't arrived yet. What would you consider a stronger indicator of long-term traction than day-one price action?#baby @BabylonLabs_io $BABY
6
2
75
·
--
Верифіковано
Переглянути переклад
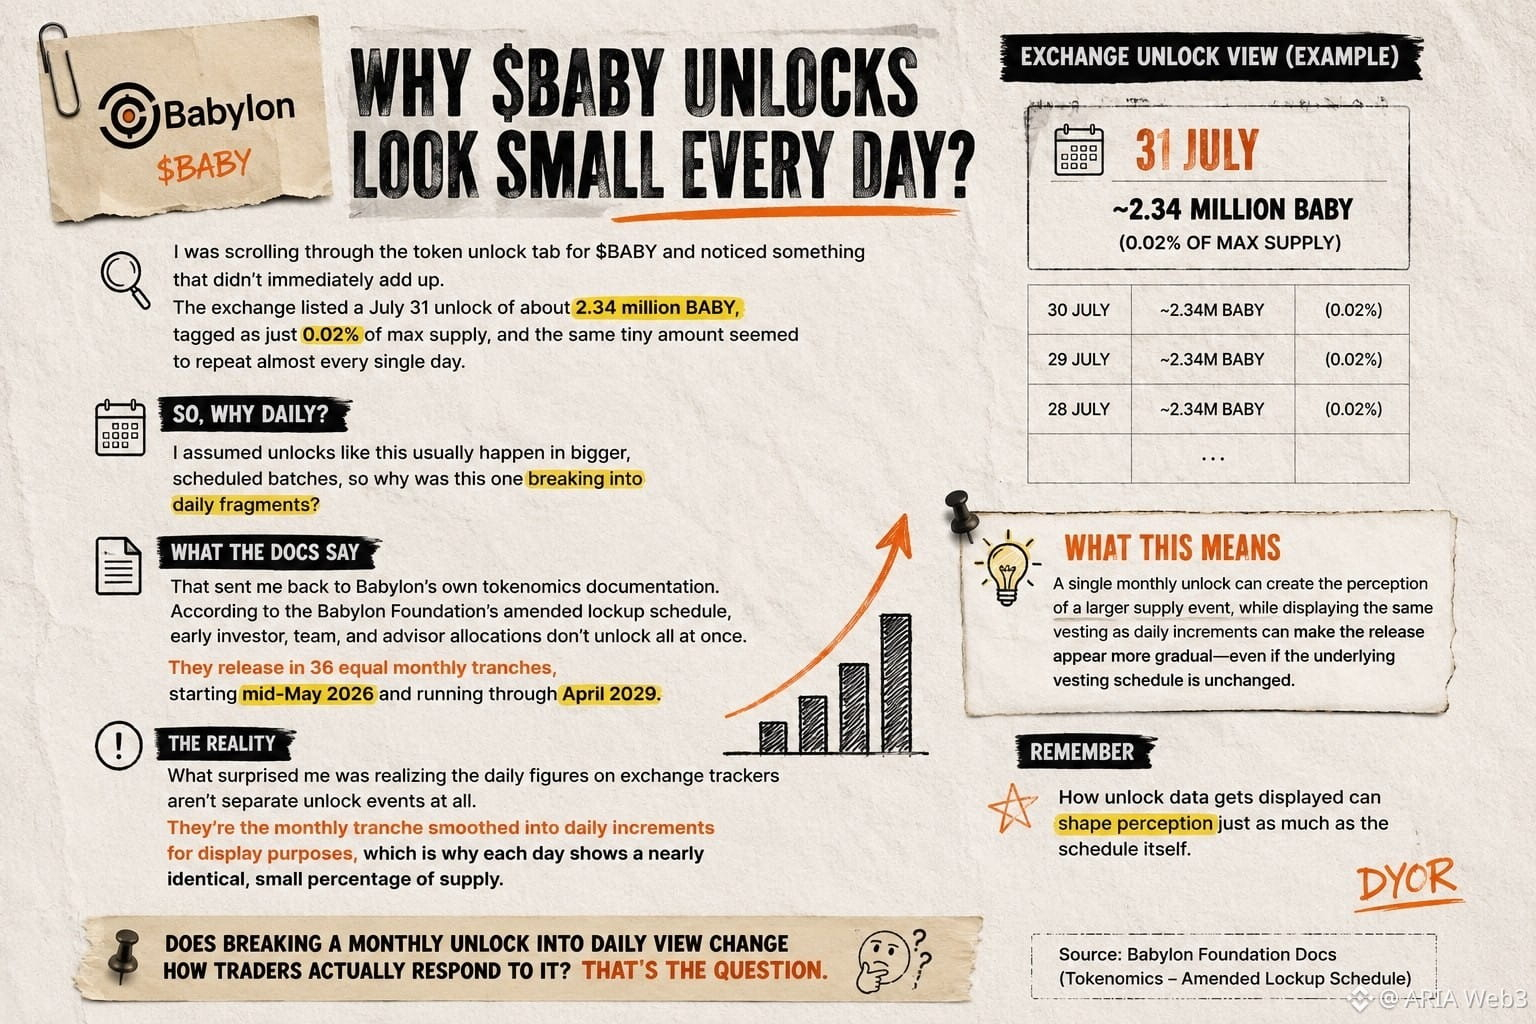
I was scrolling through the token unlock tab for BABY and noticed something that didn't immediately add up. The exchange listed a July 31 unlock of about 2.34 million BABY, tagged as just 0.02% of max supply, and the same tiny amount seemed to repeat almost every single day.
I assumed unlocks like this usually happen in bigger, scheduled batches, so why was this one breaking into daily fragments?
That sent me back to Babylon's own tokenomics documentation. According to the Babylon Foundation's amended lockup schedule, early investor, team, and advisor allocations don't unlock all at once. They release in 36 equal monthly tranches, starting mid-May 2026 and running through April 2029.
What surprised me was realizing the daily figures on exchange trackers aren't separate unlock events at all. They're the monthly tranche smoothed into daily increments for display purposes, which is why each day shows a nearly identical, small percentage of supply. That's the trade-off worth sitting with. A single large monthly cliff can shock the market with a sudden supply jump, while spreading it visually into daily slices makes the release feel gradual, even though the underlying vesting math hasn't changed at all.
It's a reminder that how unlock data gets displayed can shape perception just as much as the schedule itself. Does breaking a monthly unlock into daily view change how traders actually respond to it?
#baby $BABY @babylonlabs_io
I was scrolling through the token unlock tab for BABY and noticed something that didn't immediately add up. The exchange listed a July 31 unlock of about 2.34 million BABY, tagged as just 0.02% of max supply, and the same tiny amount seemed to repeat almost every single day.
I assumed unlocks like this usually happen in bigger, scheduled batches, so why was this one breaking into daily fragments?
That sent me back to Babylon's own tokenomics documentation. According to the Babylon Foundation's amended lockup schedule, early investor, team, and advisor allocations don't unlock all at once. They release in 36 equal monthly tranches, starting mid-May 2026 and running through April 2029.
What surprised me was realizing the daily figures on exchange trackers aren't separate unlock events at all. They're the monthly tranche smoothed into daily increments for display purposes, which is why each day shows a nearly identical, small percentage of supply. That's the trade-off worth sitting with. A single large monthly cliff can shock the market with a sudden supply jump, while spreading it visually into daily slices makes the release feel gradual, even though the underlying vesting math hasn't changed at all.
It's a reminder that how unlock data gets displayed can shape perception just as much as the schedule itself. Does breaking a monthly unlock into daily view change how traders actually respond to it?
#baby $BABY @BabylonLabs_io
4
3
69
·
--
Оптимістично
Переглянути переклад
I've read "slashing" in every Babylon post I've seen, and pictured the same thing every time: a validator misbehaves, and some rule takes their money.
That picture held up until I tried to explain who actually enforces it.
Is there a vote? A dispute period? Someone reviewing evidence?
I went looking for that process, expecting a committee.
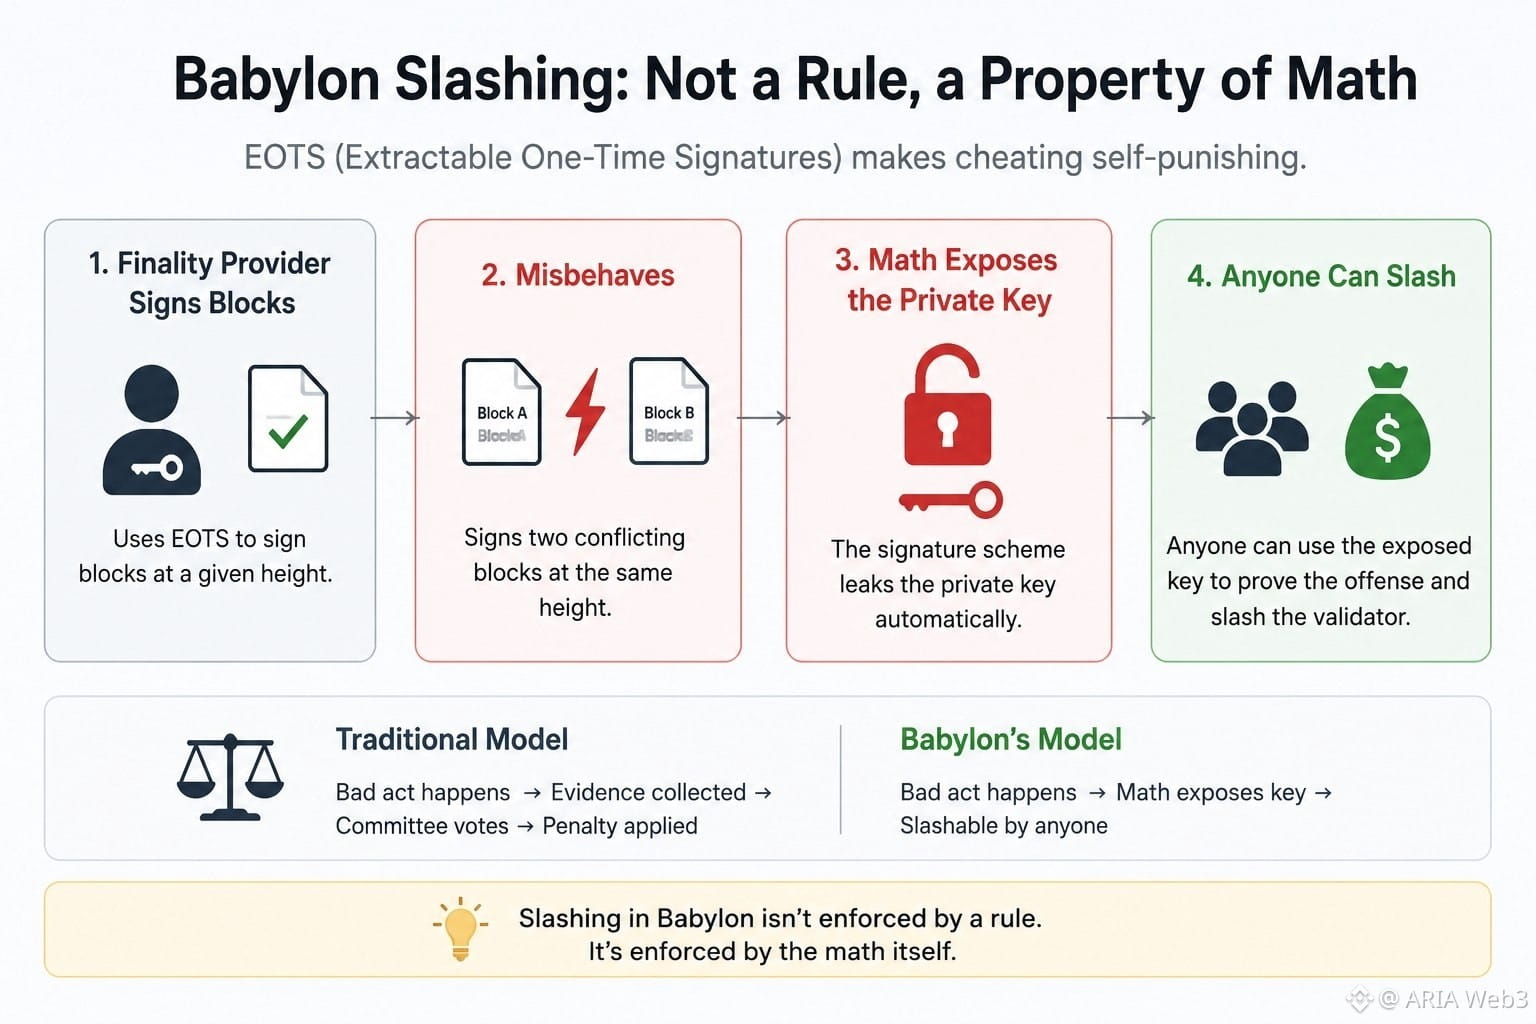
Instead I found something called EOTS — Extractable One-Time Signatures — the way Babylon's finality providers sign blocks.
I assumed it was just a fancier signature scheme. Then I read what "extractable" means.
If a finality provider signs two conflicting blocks at the same height, the signature math itself leaks their private key. Not as a penalty applied afterward. As a direct result of the act.
I sat with that for a second. There's no judge deciding guilt. The cheating and the exposure are the same event. That's different from how I usually think about enforcement — a bad act happens, then a separate process decides the consequence. Here, doing the bad thing is handing over the key to punish yourself.
Once I saw that, "slashing" stopped feeling like a rule Babylon enforces, and started feeling like something the math simply makes true on its own.
I still don't know how that holds up outside clean theory — implementation bugs, edge cases nobody planned for. Cryptography being correct on paper isn't the same as behaving correctly under real network stress.
But I like sitting with the idea that punishment here isn't a decision. It's a fact that reveals itself.
#baby $BABY @babylonlabs_io
I've read "slashing" in every Babylon post I've seen, and pictured the same thing every time: a validator misbehaves, and some rule takes their money.
That picture held up until I tried to explain who actually enforces it.
Is there a vote? A dispute period? Someone reviewing evidence?
I went looking for that process, expecting a committee.
Instead I found something called EOTS — Extractable One-Time Signatures — the way Babylon's finality providers sign blocks.
I assumed it was just a fancier signature scheme. Then I read what "extractable" means.
If a finality provider signs two conflicting blocks at the same height, the signature math itself leaks their private key. Not as a penalty applied afterward. As a direct result of the act.
I sat with that for a second. There's no judge deciding guilt. The cheating and the exposure are the same event. That's different from how I usually think about enforcement — a bad act happens, then a separate process decides the consequence. Here, doing the bad thing is handing over the key to punish yourself.
Once I saw that, "slashing" stopped feeling like a rule Babylon enforces, and started feeling like something the math simply makes true on its own.
I still don't know how that holds up outside clean theory — implementation bugs, edge cases nobody planned for. Cryptography being correct on paper isn't the same as behaving correctly under real network stress.
But I like sitting with the idea that punishment here isn't a decision. It's a fact that reveals itself.
#baby $BABY @BabylonLabs_io
1
1
72
·
--
Переглянути переклад
The more I read through Babylon's code this week, the more one small detail kept sticking in my head.
Every checkpoint sent to Bitcoin actually goes out as two separate transactions, not one. My first thought was redundancy, like a backup copy in case something gets orphaned. Turns out that's not it at all. A Bitcoin OP_RETURN output only holds 80 bytes, and a full checkpoint just doesn't fit in that space. So it gets split in half and sent as two txs, then pieced back together once both confirm. Simple once you know it, but I hadn't seen anyone point it out before.
What actually got me curious was who submits these.
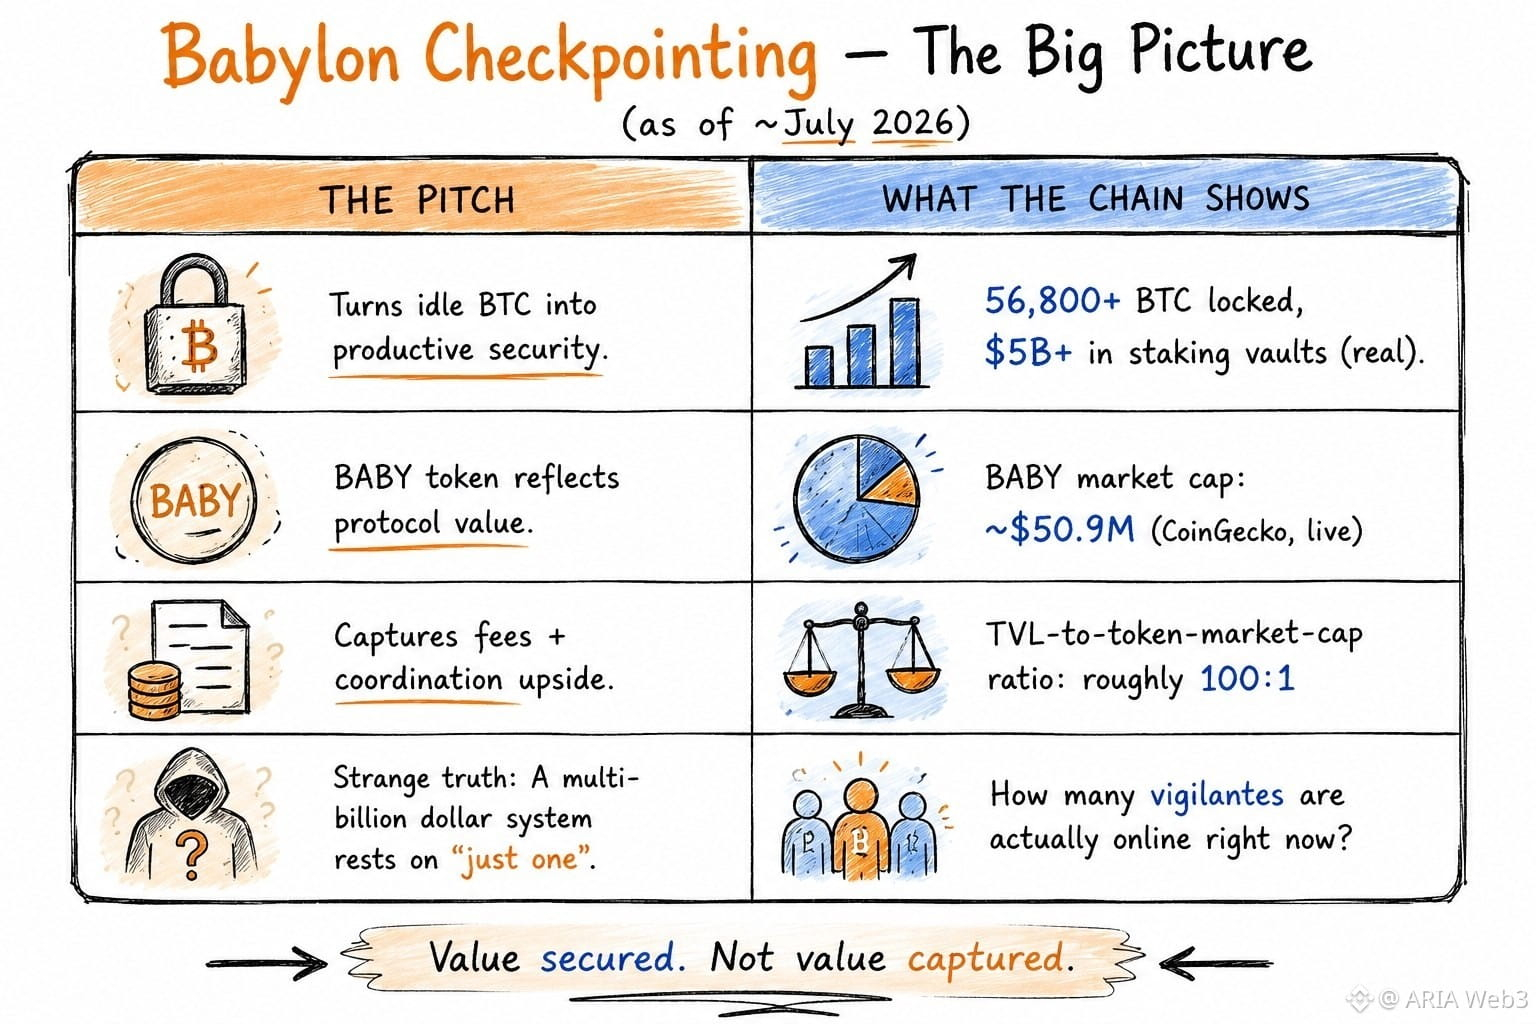
Not validators, not @babylonlabs_io itself, just anyone who wants to. They're called "vigilantes." You run the software, grab the checkpoint, pay the Bitcoin fee out of your own pocket, and broadcast it. No bond, no whitelist, nothing stopping you from just... stopping. And the whole system only needs one of these people online and honest at any given moment. Not a majority, just one.
Feels strange knowing a multi-billion dollar staking system quietly rests on that. Makes me wonder how many vigilantes are actually running right now, and whether most people staking through Babylon even know this part exists.
$BABY #baby
The more I read through Babylon's code this week, the more one small detail kept sticking in my head.
Every checkpoint sent to Bitcoin actually goes out as two separate transactions, not one. My first thought was redundancy, like a backup copy in case something gets orphaned. Turns out that's not it at all. A Bitcoin OP_RETURN output only holds 80 bytes, and a full checkpoint just doesn't fit in that space. So it gets split in half and sent as two txs, then pieced back together once both confirm. Simple once you know it, but I hadn't seen anyone point it out before.
What actually got me curious was who submits these.
Not validators, not @BabylonLabs_io itself, just anyone who wants to. They're called "vigilantes." You run the software, grab the checkpoint, pay the Bitcoin fee out of your own pocket, and broadcast it. No bond, no whitelist, nothing stopping you from just... stopping. And the whole system only needs one of these people online and honest at any given moment. Not a majority, just one.
Feels strange knowing a multi-billion dollar staking system quietly rests on that. Makes me wonder how many vigilantes are actually running right now, and whether most people staking through Babylon even know this part exists.
$BABY #baby
16
4
87
·
--
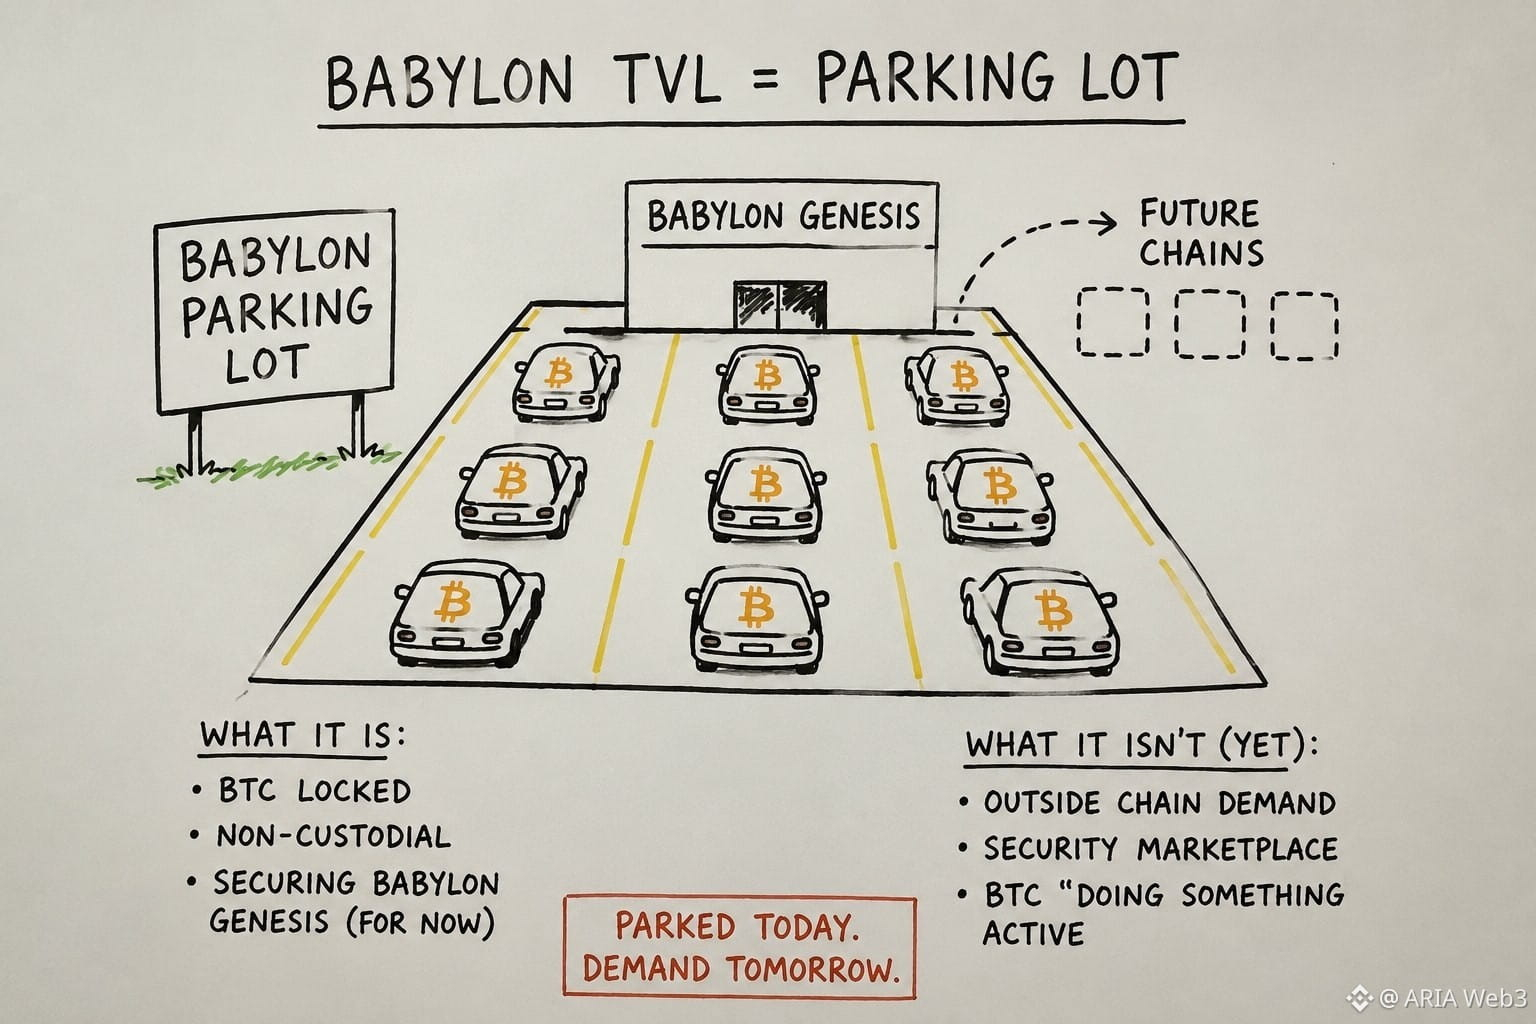
Збережено, виходячи з припущення, що TVL-графік Babylon є графіком попиту. Ні, це не так. Це стоянка.
Мультистейкінг — функція, яка дозволяє одному BTC-депозиту одночасно забезпечити кілька PoS-ланцюгів, як і раніше є основним меседжем.
Але майже весь стейкований BTC зараз підтримує лише один ланцюг: Babylon Genesis, який також є керувальною площиною для кожної майбутньої мережі, що має підключитися пізніше. Тож число, що читається як «попит на безпеку», переважно є капіталом, який сидить усередині системи, що зібрала вимірювальну шкалу. Це не шахрайство — радше послідовність кроків. Спочатку забезпечити постачання (bootstrap), довести механізм, а потім хай попит наздожене. Кожен ринок безпеки починає саме так.
Але це означає, що TVL дає відповідь на запитання, яке фактично ніхто не ставить: чи можна некастодіально заблокувати BTC, щоб підтримати валідаторів, замість того, яке має значення: чи зовнішні ланцюги вважають цю безпеку достатньо цінною, щоб платити за неї замість власної токен-інфляції. Відчувається, що ринок це вже відчуває. Оцінка BABY відносно BTC, залишеного «позаду», не рухається як актив попиту. Вона рухається як токен, який усе ще намагається зрозуміти, для чого він. Неприємне прочитання: Babylon, можливо, розв’язав складнішу криптографічну задачу ще до того, як вирішив простішу економічну. Більшість інфраструктурних ставок виходять із того, що саме технологія є вузьким місцем. А що як тут це ніколи не було так?
#baby $BABY @babylonlabs_io
Збережено, виходячи з припущення, що TVL-графік Babylon є графіком попиту. Ні, це не так. Це стоянка.
Мультистейкінг — функція, яка дозволяє одному BTC-депозиту одночасно забезпечити кілька PoS-ланцюгів, як і раніше є основним меседжем.
Але майже весь стейкований BTC зараз підтримує лише один ланцюг: Babylon Genesis, який також є керувальною площиною для кожної майбутньої мережі, що має підключитися пізніше. Тож число, що читається як «попит на безпеку», переважно є капіталом, який сидить усередині системи, що зібрала вимірювальну шкалу. Це не шахрайство — радше послідовність кроків. Спочатку забезпечити постачання (bootstrap), довести механізм, а потім хай попит наздожене. Кожен ринок безпеки починає саме так.
Але це означає, що TVL дає відповідь на запитання, яке фактично ніхто не ставить: чи можна некастодіально заблокувати BTC, щоб підтримати валідаторів, замість того, яке має значення: чи зовнішні ланцюги вважають цю безпеку достатньо цінною, щоб платити за неї замість власної токен-інфляції. Відчувається, що ринок це вже відчуває. Оцінка BABY відносно BTC, залишеного «позаду», не рухається як актив попиту. Вона рухається як токен, який усе ще намагається зрозуміти, для чого він. Неприємне прочитання: Babylon, можливо, розв’язав складнішу криптографічну задачу ще до того, як вирішив простішу економічну. Більшість інфраструктурних ставок виходять із того, що саме технологія є вузьким місцем. А що як тут це ніколи не було так?
#baby $BABY @BabylonLabs_io
6
3
86
Увійдіть, щоб переглянути інший контент
Приєднуйтесь до користувачів криптовалют по всьому світу на Binance Square
⚡️ Отримуйте актуальну та корисну інформацію про криптовалюти.
💬 Приєднуйтесь до найбільшої у світі криптобіржі.
👍 Відкрийте справжні ідеї від перевірених авторів.
Електронна пошта / номер телефону
Трендові теми
fomcвідстеження
95,200 переглядів
468 обговорюють
ФРС сьогодні без сюрпризів, але з нюансами. Ставка незмінна — 3.75% - 4.00%.
Але голосування було не таким вже й єдиним: 10 проти 2 причому двоє членів комітету реально тиснули за підвищення через стійку інфляцію.По суті, регулятор у глухому куті і чекає нової статистики, щоб зрозуміти, що робити далі.
Для ринку це нейтрально але тиск відчувається.Хто що думає, куди підемо далі найближчими тижнями? 👇
#fomcвідстеження
#CanMicrosoftDeliverOnAI
#CanGoogleDefindItsCore
#KOSPISurges6.63%BackAbove6000
$BTC
$NVDA
$NIL
VoLoDyMyR7
·20 вподобань
·2.3k переглядів
$1.5BInLeveragedCryptoBetsLiquidated
2,241 переглядів
41 обговорюють
KOSPIFalls3.53%BackBelow6000
5,017 переглядів
188 обговорюють