

#tarding
tarding
12,257 views
65 Discussing
Hot
Latest
·
--
Bullish
🌊 $CYC Is Charging Up!
🎯 EP: 0.00803
🎯 TP1: 0.00860
🎯 TP2: 0.00910
🎯 TP3: 0.00980
🛑 SL: 0.00770
✨ Consolidation often comes before acceleration. Watch for confirmation and ride the momentum with proper risk management. 📈
#Crypto_Jobs🎯 #tarding #binace #cyc
$CYC
{alpha}(560x5845684b49aef79a5c0f887f50401c247dca7ac6)
🌊 $CYC Is Charging Up!
🎯 EP: 0.00803
🎯 TP1: 0.00860
🎯 TP2: 0.00910
🎯 TP3: 0.00980
🛑 SL: 0.00770
✨ Consolidation often comes before acceleration. Watch for confirmation and ride the momentum with proper risk management. 📈
#Crypto_Jobs🎯 #tarding #binace #cyc
$CYC
🎯 EP: 0.00803
🎯 TP1: 0.00860
🎯 TP2: 0.00910
🎯 TP3: 0.00980
🛑 SL: 0.00770
✨ Consolidation often comes before acceleration. Watch for confirmation and ride the momentum with proper risk management. 📈
#Crypto_Jobs🎯 #tarding #binace #cyc
$CYC
1
154
·
--
Bullish
NVDA – The Market Is Still Pricing in AI Growth
#NVDA $NVDA.US
{stock_us}(NVDA.US)
Looking at both the news backdrop and the technical structure, I remain positive on NVDA. What keeps me interested is not only that the stock remains in an uptrend, but also that Nvidia’s underlying growth story has yet to lose its main driver. Continued investment in AI, data centers, and computing capacity keeps Nvidia among the biggest direct beneficiaries of the AI infrastructure expansion cycle. For that reason, the current pullbacks look more like the market repricing future growth opportunities than a sign that the long-term thesis has changed.
From a fundamental perspective, the most important factor remains the scale of global spending on AI infrastructure. Major technology companies continue to require enormous computing capacity to build and operate AI models, which sits directly at the heart of Nvidia’s business. At the same time, maintaining access to at least part of China’s chip demand could provide additional revenue upside if restrictions allow. The company’s third-quarter revenue forecast of around $108 billion also suggests that AI demand is still translating into real business growth. Competition from Huawei, Alibaba, and other chipmakers remains a risk worth monitoring, but for now, NVDA’s investment case continues to be driven more by expanding AI demand and revenue growth potential.
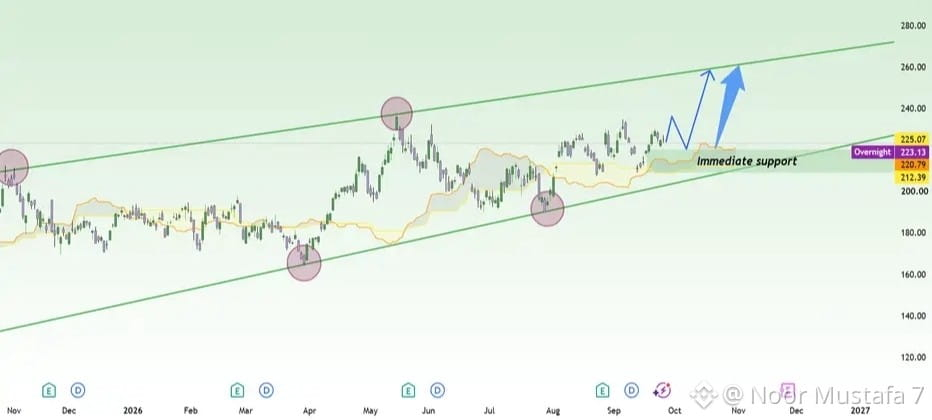
On the daily chart, the market has yet to give me a strong reason to question that thesis. NVDA continues to trade within a long-term ascending channel, with larger pullbacks repeatedly attracting demand near the lower part of the structure. The stock is currently trading around $225 and remains above the Ichimoku Cloud, while $212–$220 is the area I consider the key near-term support base. If buyers continue to absorb supply there and the higher-low structure remains intact, $260–$270 becomes a reasonable next target, which also aligns with the upper portion of the rising channel.
#NVDA/SOL #TARDING
{future}(NVDAUSDT)
NVDA – The Market Is Still Pricing in AI Growth
#NVDA $NVDA.US
Looking at both the news backdrop and the technical structure, I remain positive on NVDA. What keeps me interested is not only that the stock remains in an uptrend, but also that Nvidia’s underlying growth story has yet to lose its main driver. Continued investment in AI, data centers, and computing capacity keeps Nvidia among the biggest direct beneficiaries of the AI infrastructure expansion cycle. For that reason, the current pullbacks look more like the market repricing future growth opportunities than a sign that the long-term thesis has changed.
From a fundamental perspective, the most important factor remains the scale of global spending on AI infrastructure. Major technology companies continue to require enormous computing capacity to build and operate AI models, which sits directly at the heart of Nvidia’s business. At the same time, maintaining access to at least part of China’s chip demand could provide additional revenue upside if restrictions allow. The company’s third-quarter revenue forecast of around $108 billion also suggests that AI demand is still translating into real business growth. Competition from Huawei, Alibaba, and other chipmakers remains a risk worth monitoring, but for now, NVDA’s investment case continues to be driven more by expanding AI demand and revenue growth potential.
On the daily chart, the market has yet to give me a strong reason to question that thesis. NVDA continues to trade within a long-term ascending channel, with larger pullbacks repeatedly attracting demand near the lower part of the structure. The stock is currently trading around $225 and remains above the Ichimoku Cloud, while $212–$220 is the area I consider the key near-term support base. If buyers continue to absorb supply there and the higher-low structure remains intact, $260–$270 becomes a reasonable next target, which also aligns with the upper portion of the rising channel.
#NVDA/SOL #TARDING
NVDAUS+0.05%
40
·
--
Bullish
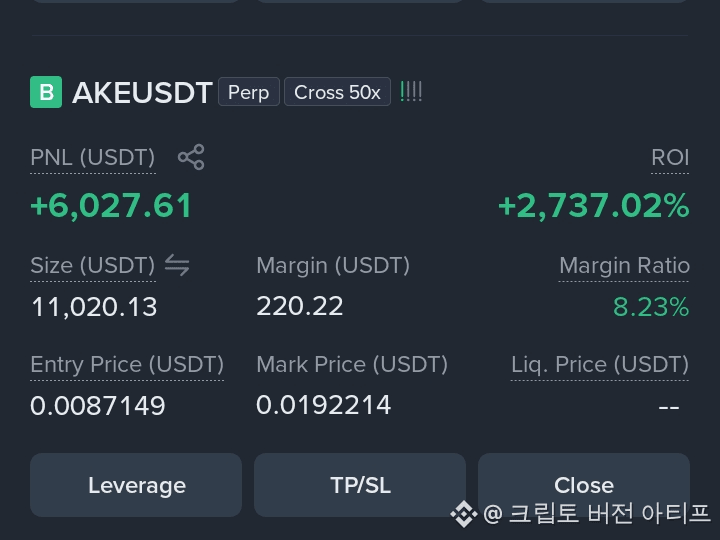
🔥 $AKE PROFIT HIT! 🚀
AKE ..gave a very good profit! 💰📈
$MAGMA and $USELESS are also on the radar. 🔥
Trade smart. DYOR.
{future}(USELESSUSDT)
#TARDING
#Bitcoin❗
#MARSCONIUSDT
#ake
🔥 $AKE PROFIT HIT! 🚀
AKE ..gave a very good profit! 💰📈
$MAGMA and $USELESS are also on the radar. 🔥
Trade smart. DYOR.
#TARDING
#Bitcoin❗
#MARSCONIUSDT
#ake
AKE ..gave a very good profit! 💰📈
$MAGMA and $USELESS are also on the radar. 🔥
Trade smart. DYOR.
#TARDING
#Bitcoin❗
#MARSCONIUSDT
#ake

314
·
--
Bullish
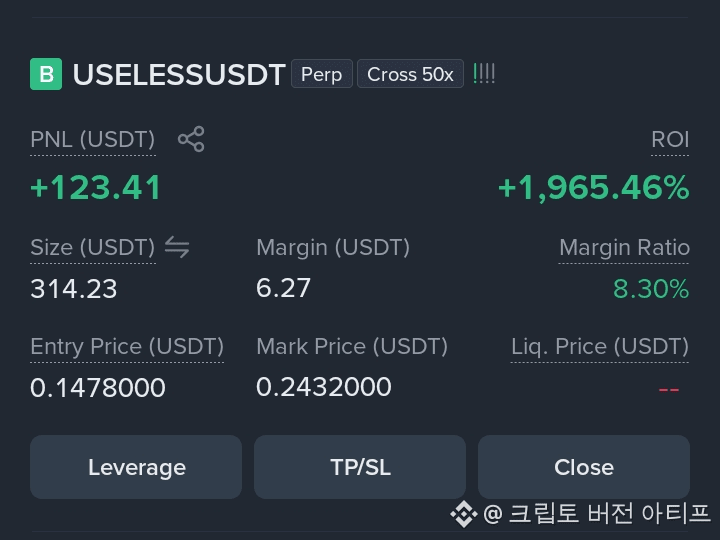
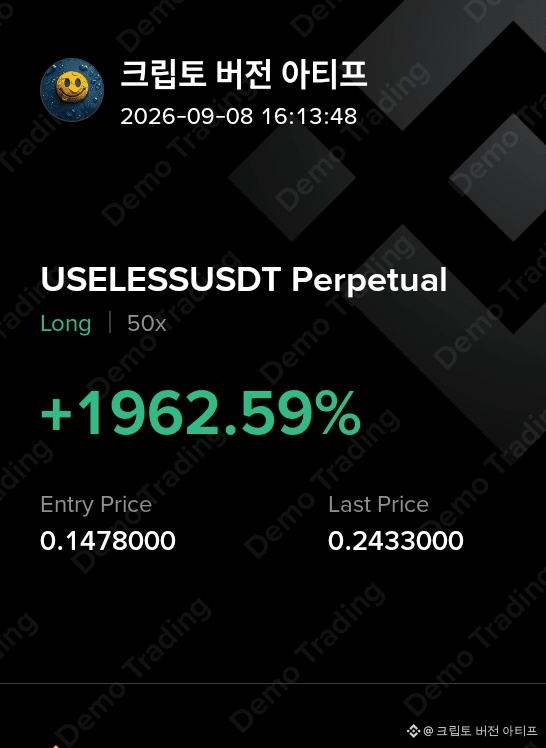
🔥 $USELESS — WHAT A PROFIT!
$USELESS gave an amazing profit! 🚀💰
Clean move, clean profit. 🔥
$SNDK #TARDING #Binance #Follow_Like_Comment
🔥 $USELESS — WHAT A PROFIT!
$USELESS gave an amazing profit! 🚀💰
Clean move, clean profit. 🔥
$SNDK #TARDING #Binance #Follow_Like_Comment
$USELESS gave an amazing profit! 🚀💰
Clean move, clean profit. 🔥
$SNDK #TARDING #Binance #Follow_Like_Comment
113
·
--
Bullish
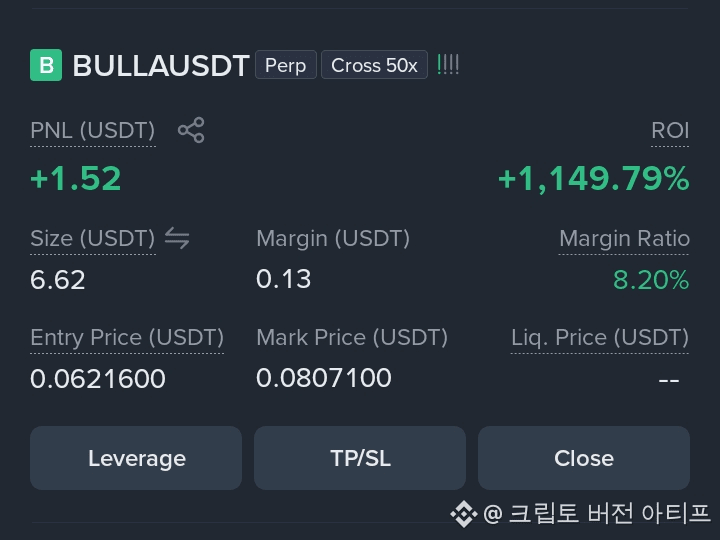
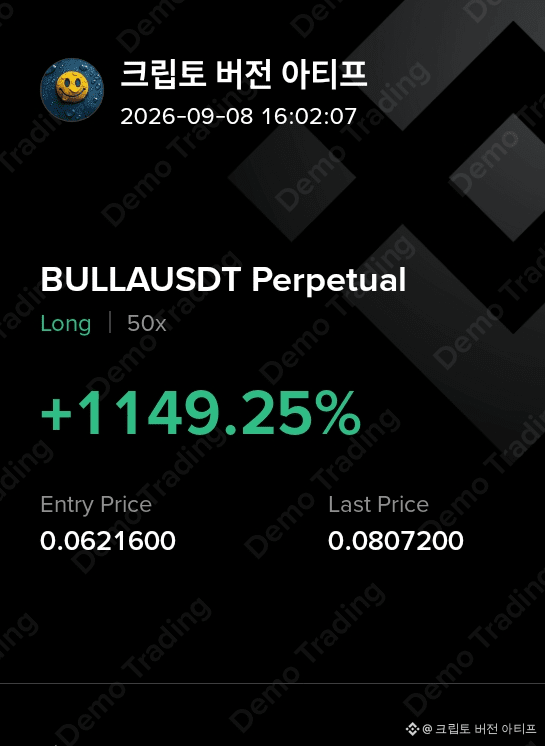
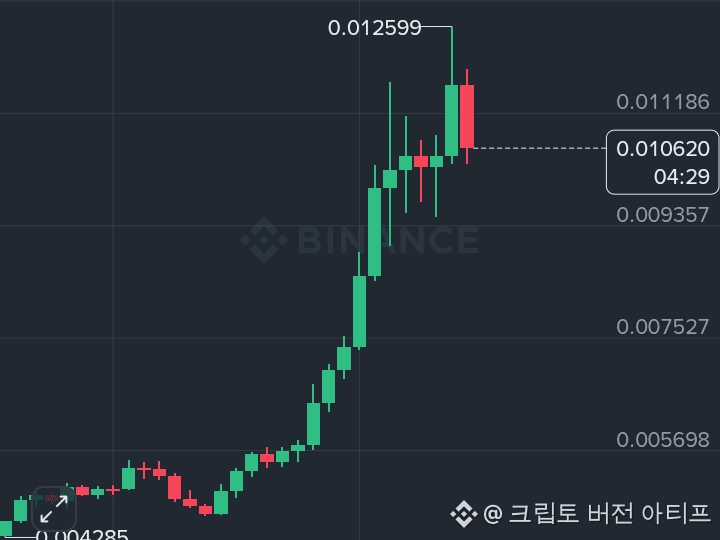
🔥 $BULLA JUST DELIVERED A SWEET PROFIT! 💫
The crazy part? I started with just $0.13 and managed to make Roi 1149.25% profit! 🤯📈
Small capital, but a very satisfying result! 🔥💪
$BULLA $SNDK
{future}(SNDKUSDT)
#TARDING
#Binance
#FunnyMemes
#Follow_Like_Comment
🔥 $BULLA JUST DELIVERED A SWEET PROFIT! 💫
The crazy part? I started with just $0.13 and managed to make Roi 1149.25% profit! 🤯📈
Small capital, but a very satisfying result! 🔥💪
$BULLA $SNDK
#TARDING
#Binance
#FunnyMemes
#Follow_Like_Comment
The crazy part? I started with just $0.13 and managed to make Roi 1149.25% profit! 🤯📈
Small capital, but a very satisfying result! 🔥💪
$BULLA $SNDK
#TARDING
#Binance
#FunnyMemes
#Follow_Like_Comment
558
·
--
Bearish
🚀 $SOPH SHOW — Everyone, get ready! 🔥
All eyes are on $SOPH… 👀
Let’s see what the next move brings! 📈
{spot}(SOPHUSDT)
$MARSCOIN $SNDK
#TARDING
#CanadaTariffsOnUSTakeEffect
#YenBreaks155NearingYearHigh
#IMFSaysElSalvadorBTCNoPublicFunds
#SideSwapSuspendsLiquidServices
🚀 $SOPH SHOW — Everyone, get ready! 🔥
All eyes are on $SOPH … 👀
Let’s see what the next move brings! 📈
$MARSCOIN $SNDK
#TARDING
#CanadaTariffsOnUSTakeEffect
#YenBreaks155NearingYearHigh
#IMFSaysElSalvadorBTCNoPublicFunds
#SideSwapSuspendsLiquidServices
All eyes are on $SOPH … 👀
Let’s see what the next move brings! 📈
$MARSCOIN $SNDK
#TARDING
#CanadaTariffsOnUSTakeEffect
#YenBreaks155NearingYearHigh
#IMFSaysElSalvadorBTCNoPublicFunds
#SideSwapSuspendsLiquidServices

79
·
--
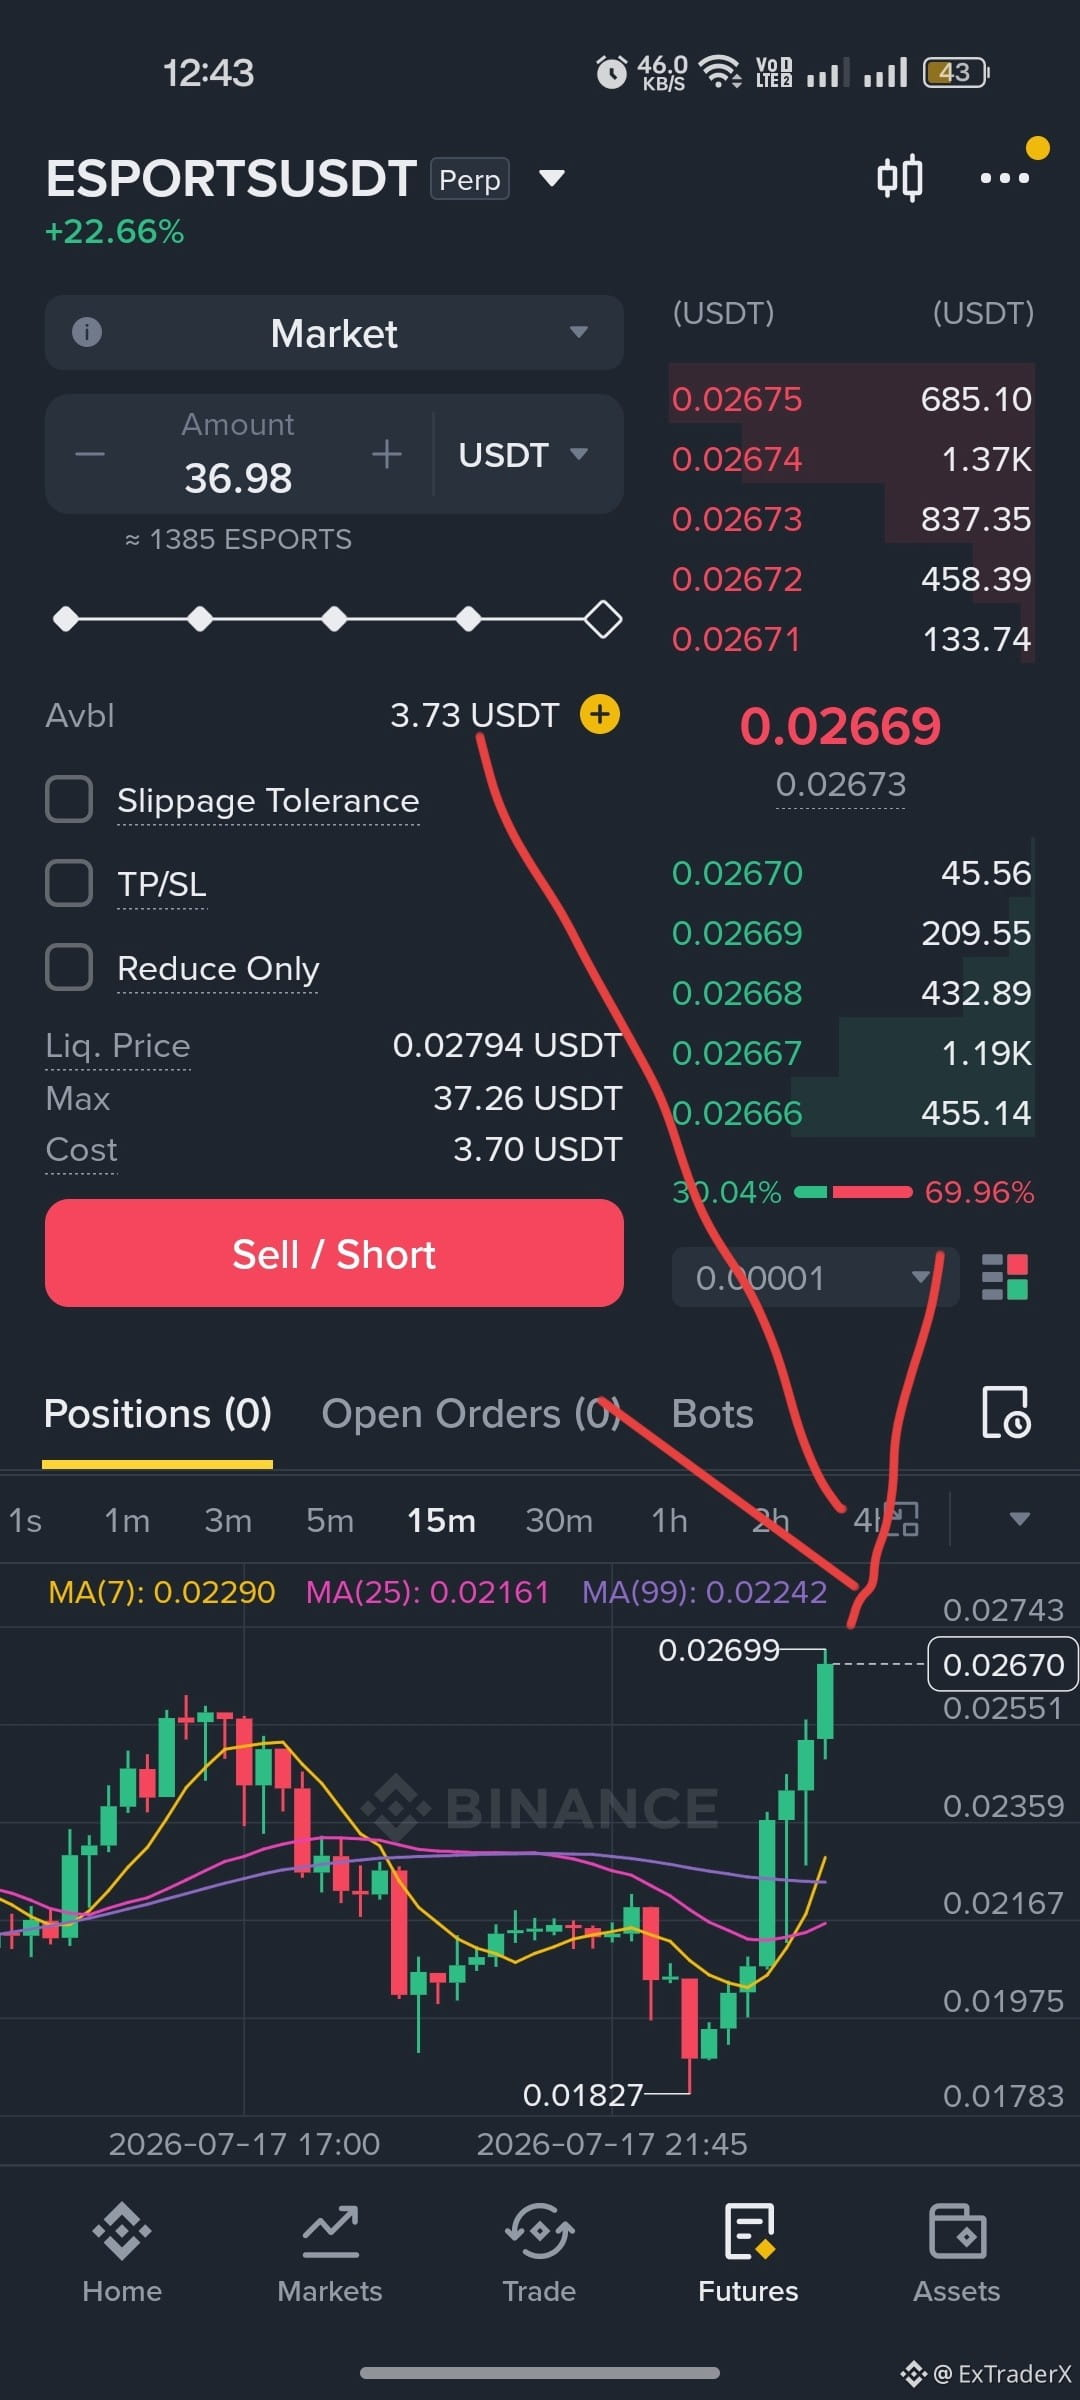
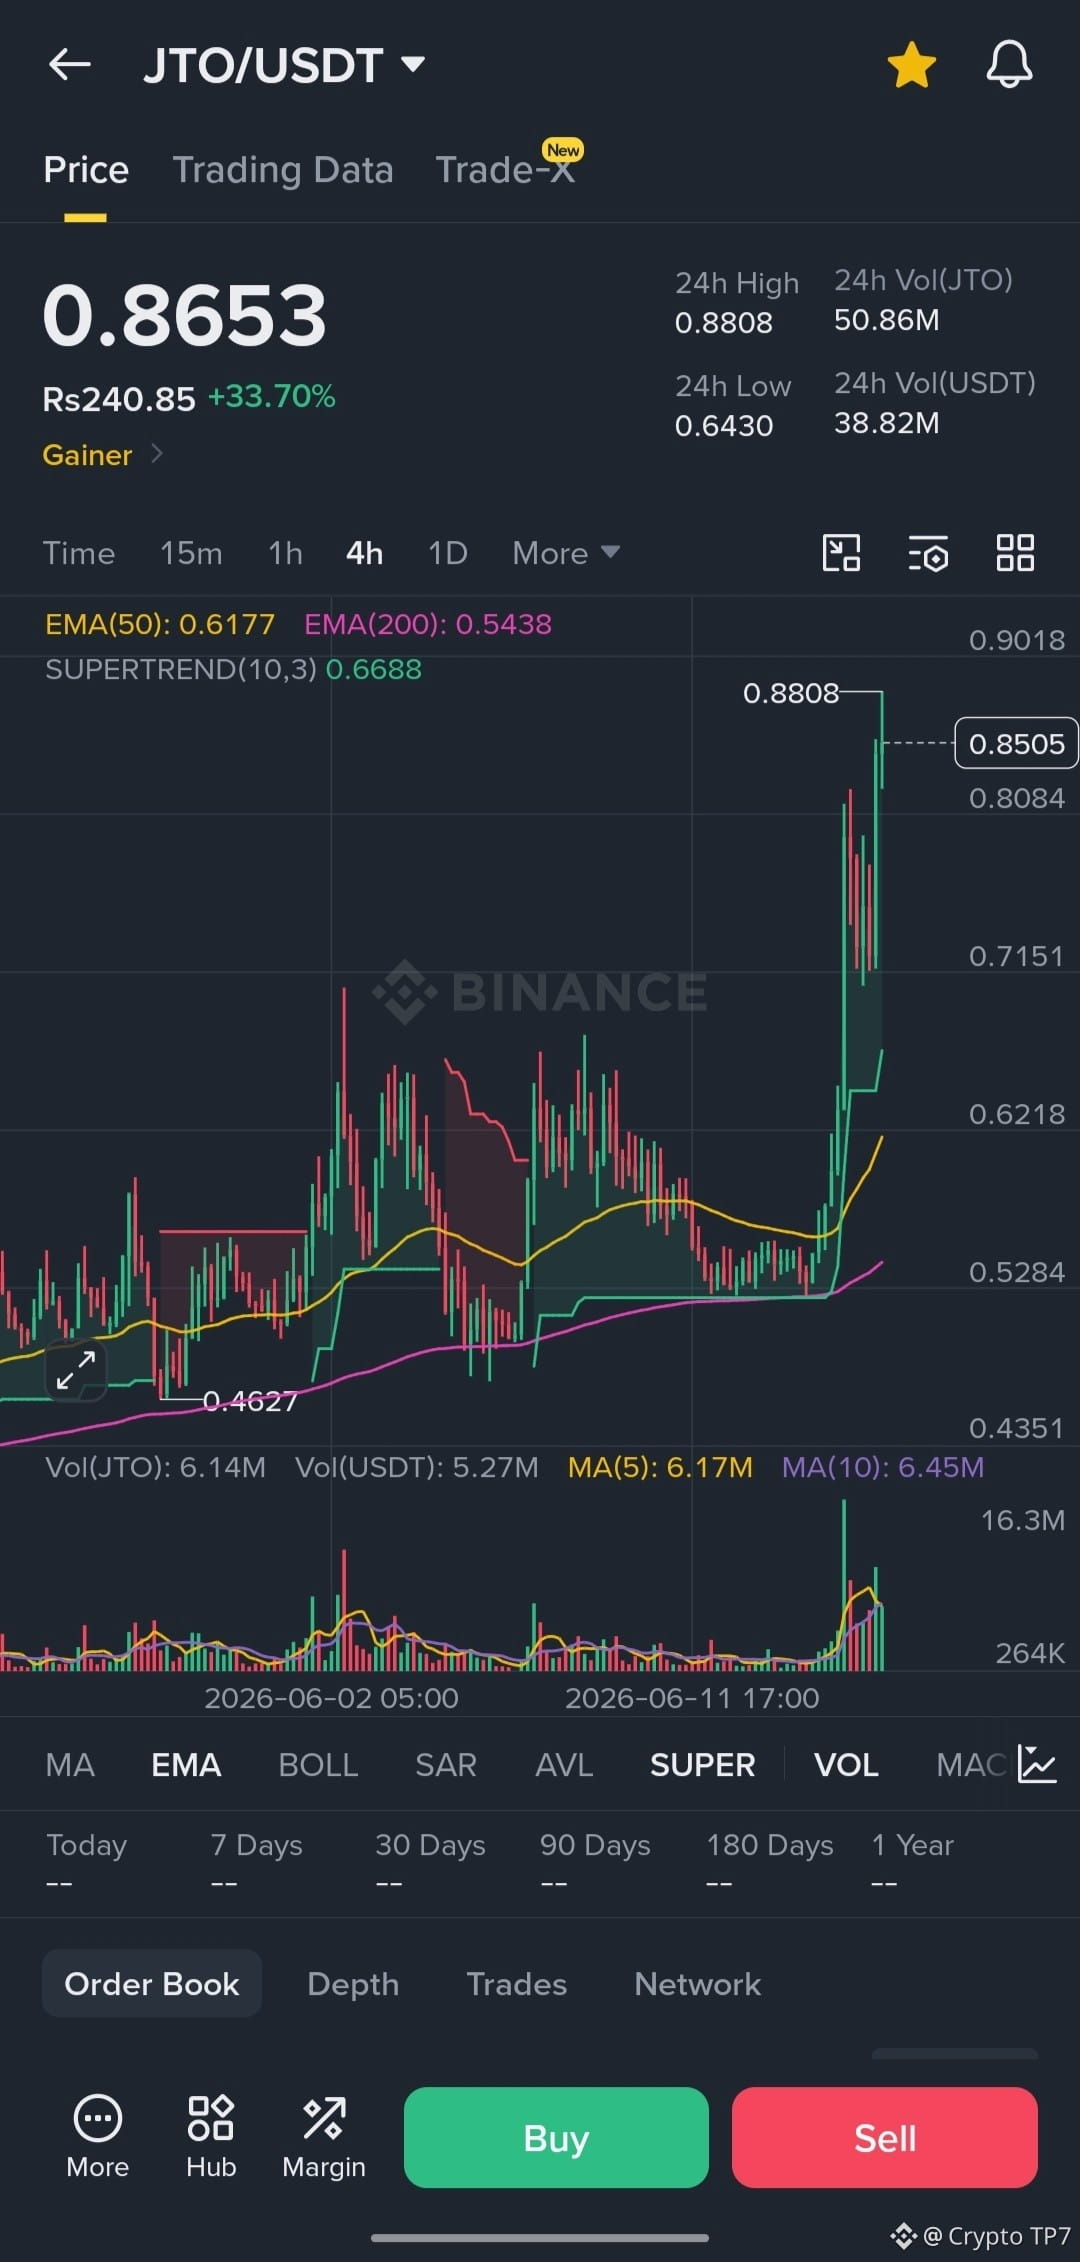
🚨 $JTO Trade Alert 🚨
🚀 $JTO Become a 1$ 🚀
" Don't miss the entry "
💰Click and trade now make profits💰 And enjoy💥
⚠️ DYOR (Do Your Own Research). Crypto market volatile hai.
❤️ Like if you're bullish on JTO 💬 Comment your target 🔄 Share with your trading friends ➕ Follow for more crypto updates & trading setups
#JTO🔥🔥🔥 #TARDING #CryptoSignal:
158
·
--
Bearish
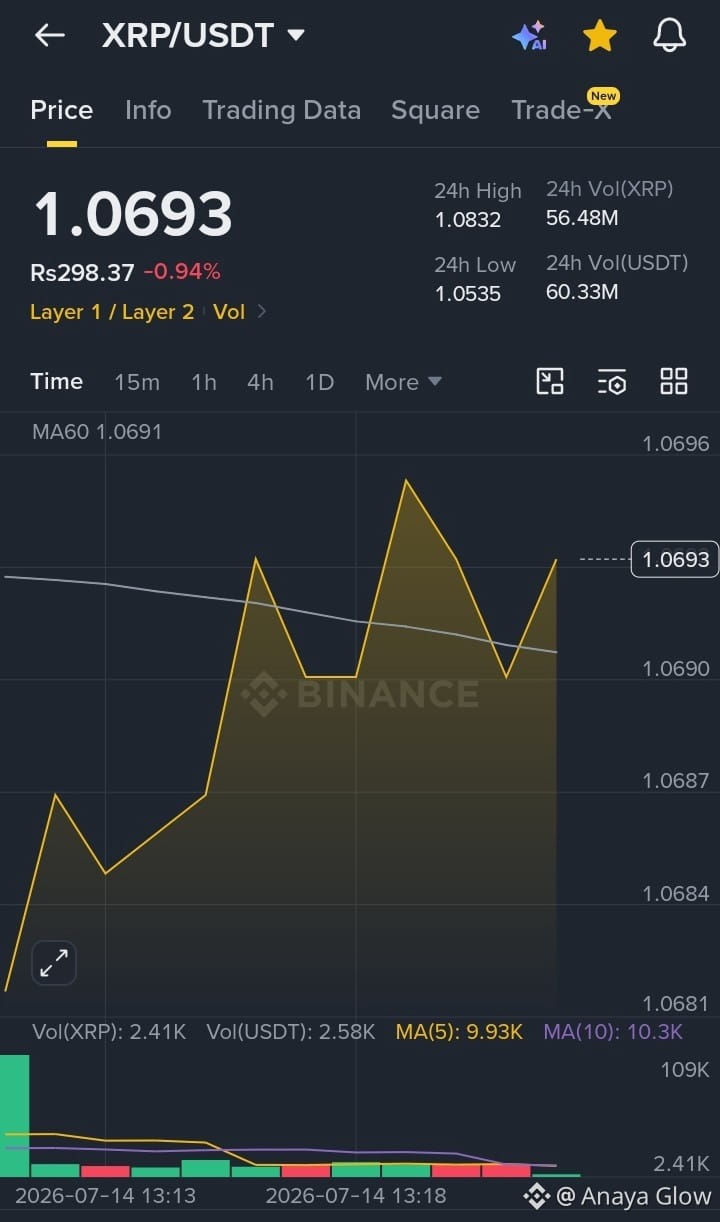
💜 $XRP is holding a key demand zone. Watch for a breakout to catch the next move! 🚀
🎯 EP: $1.06–1.08
🎯 TP: $1.11 | $1.16 | $1.22
🛑 SL: $1.03
⚡ #XRP #Ripple #Crypto_Jobs🎯 #tarding
$XRP
{future}(XRPUSDT)
💜 $XRP is holding a key demand zone. Watch for a breakout to catch the next move! 🚀
🎯 EP: $1.06–1.08
🎯 TP: $1.11 | $1.16 | $1.22
🛑 SL: $1.03
⚡ #XRP #Ripple #Crypto_Jobs🎯 #tarding
$XRP
🎯 EP: $1.06–1.08
🎯 TP: $1.11 | $1.16 | $1.22
🛑 SL: $1.03
⚡ #XRP #Ripple #Crypto_Jobs🎯 #tarding
$XRP
3
100
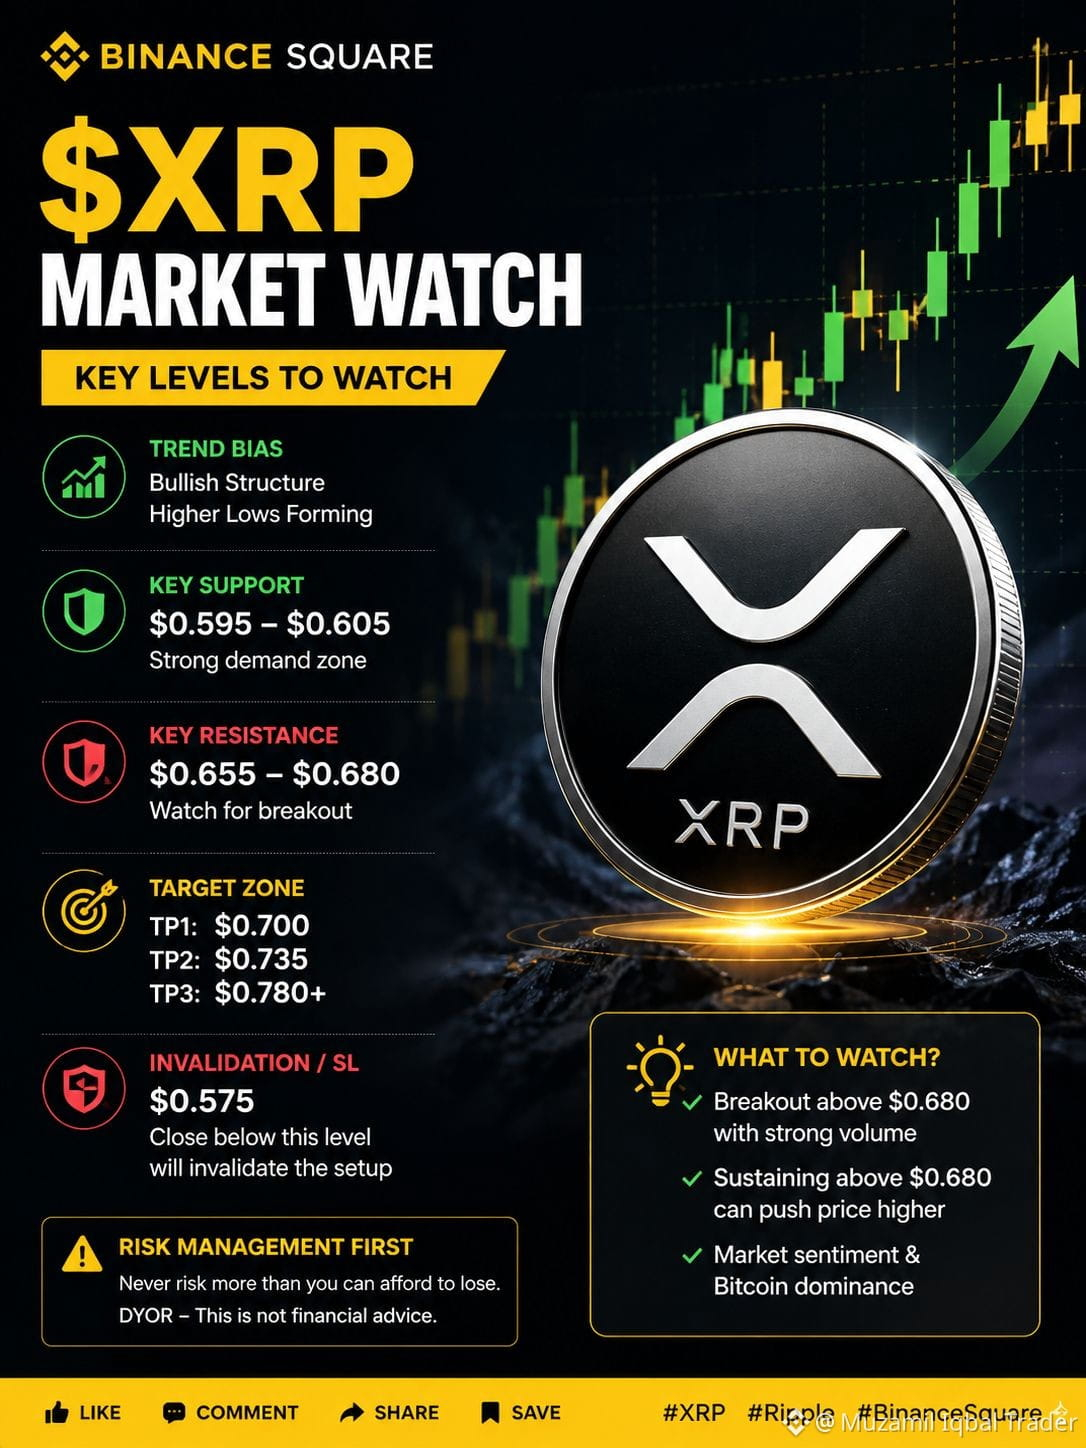
🟡 $XRP MARKET WATCH
🚀 🟡 $XRP MARKET WATCH
🚀 XRP — Key Level to Watch
📊 XRP is approaching an important market area.
👀 Watch for a strong breakout or rejection before taking any decision.
🎯 Target Zone: Resistance area
🛑 Invalidation: Below key support
📈 Confirmation: Strong volume + bullish price action
Trade carefully & DYOR.
⚠️ This is market analysis, not financial advice.
#XRP #Ripple #Crypto #TARDING
{spot}(XRPUSDT)
🟡 $XRP MARKET WATCH
🚀 🟡 $XRP MARKET WATCH
🚀 XRP — Key Level to Watch
📊 XRP is approaching an important market area.
👀 Watch for a strong breakout or rejection before taking any decision.
🎯 Target Zone: Resistance area
🛑 Invalidation: Below key support
📈 Confirmation: Strong volume + bullish price action
Trade carefully & DYOR.
⚠️ This is market analysis, not financial advice.
#XRP #Ripple #Crypto #TARDING
1
119
·
--
Bearish
"That liquidation wiped out the top of the entry zone. Now the key question is whether $MYX
can reclaim $0.145 as support or if more downside liquidity gets hunted first. Watching price action closely here."
Or shorter:
"Top of the entry zone got taken out. Sometimes that's where the best setups begin—waiting to see if $0.145 flips back into support."
#bincen #crypto #tarding
$MYX
{future}(MYXUSDT)
"That liquidation wiped out the top of the entry zone. Now the key question is whether $MYX
can reclaim $0.145 as support or if more downside liquidity gets hunted first. Watching price action closely here."
Or shorter:
"Top of the entry zone got taken out. Sometimes that's where the best setups begin—waiting to see if $0.145 flips back into support."
#bincen #crypto #tarding
$MYX
can reclaim $0.145 as support or if more downside liquidity gets hunted first. Watching price action closely here."
Or shorter:
"Top of the entry zone got taken out. Sometimes that's where the best setups begin—waiting to see if $0.145 flips back into support."
#bincen #crypto #tarding
$MYX
9
879
Trading Engine
·
--
Bullish📊 Polkadot (DOT) Analysis
Polkadot (DOT) is a very promising cryptocurrency, in my personal opinion. I believe that if you invest in DOT with a long-term perspective, it could potentially deliver good returns in the future.
At the moment, DOT is trading around $0.87, but I believe it has the potential to perform well this year. It wouldn't be wrong to say that, if the market conditions are favorable, DOT could eventually react strongly and show a recovery similar to what we have seen with coins like SOL.
Many people may consider DOT a "dead coin," but I don't agree with that. In my opinion, DOT still has potential, and I believe it could move into a much better position in the future.
⚠️ This is only my personal opinion and analysis, not financial advice. Always do your own research before investing.
#Polkadot #DOT #Crypto #CryptoAnalysis #Bitcoin #Altcoins #Investing
If you want, I can also make it �more professional and bullish, like a Binance-style crypto analysis post.
$DOT $BTC $ETH
#Follow_Like_Comment
#eveyone #EVERYTHING #newscrypto
#Announcement
1
74
·
--
📈 $SOL L spot ETFs recorded $8.8M inflows — the strongest single-day inflow since May.
💰 Institutional interest appears to be picking up again.
⚡ SOL is holding around the $75–$78 zone, with a breakout above $78 potentially opening the door toward $80+.
If bullish momentum continues, SOL could be ready for another strong move.
#solana
#BinanceSquareTalks
#news
#TARDING
{spot}(SOLUSDT)
📈 $SOL L spot ETFs recorded $8.8M inflows — the strongest single-day inflow since May.
💰 Institutional interest appears to be picking up again.
⚡ SOL is holding around the $75–$78 zone, with a breakout above $78 potentially opening the door toward $80+.
If bullish momentum continues, SOL could be ready for another strong move.
#solana
#BinanceSquareTalks
#news
#TARDING
💰 Institutional interest appears to be picking up again.
⚡ SOL is holding around the $75–$78 zone, with a breakout above $78 potentially opening the door toward $80+.
If bullish momentum continues, SOL could be ready for another strong move.
#solana
#BinanceSquareTalks
#news
#TARDING
73
Title: During crazy volatile days, I actually stay off social media now
Post:
Used to scroll through every panic post during a big red day, everyone screaming "it's over" or "buy now" at the same time. Made my own decisions way worse cause I was just reacting to the noise, not thinking clearly.
Now on days like that, I close the apps, look at my own plan, and just follow what I already decided beforehand, calmly.
Timeline panic spreads fast and it's contagious, doesn't mean any of it is actually useful information for your specific trade.
Your plan made with a clear head beats a decision made while scrolling through 500 panicked posts.
Do you check social media or avoid it during crazy days?
#Crypto #TARDING #Mindset
1
74
·
--
$GRASS /USDT Trade Setup
🟢 LONG
Entry: 0.4790–0.4810
🎯 TP1: 0.4865
🎯 TP2: 0.4920
🎯 TP3: 0.5000
🛑 SL: 0.4680
⚡ Momentum remains bullish. A clean breakout above 0.4865 could accelerate the move toward 0.50. 🚀
#TradingSignals #tarding #TRUMP $GRASS
{future}(GRASSUSDT)
$CAP
{alpha}(560x99991c6aabba5a096f24f250b73580f5179b9999)
$GRASS /USDT Trade Setup
🟢 LONG
Entry: 0.4790–0.4810
🎯 TP1: 0.4865
🎯 TP2: 0.4920
🎯 TP3: 0.5000
🛑 SL: 0.4680
⚡ Momentum remains bullish. A clean breakout above 0.4865 could accelerate the move toward 0.50. 🚀
#TradingSignals #tarding #TRUMP $GRASS
$CAP
🟢 LONG
Entry: 0.4790–0.4810
🎯 TP1: 0.4865
🎯 TP2: 0.4920
🎯 TP3: 0.5000
🛑 SL: 0.4680
⚡ Momentum remains bullish. A clean breakout above 0.4865 could accelerate the move toward 0.50. 🚀
#TradingSignals #tarding #TRUMP $GRASS
$CAP
424

·
--
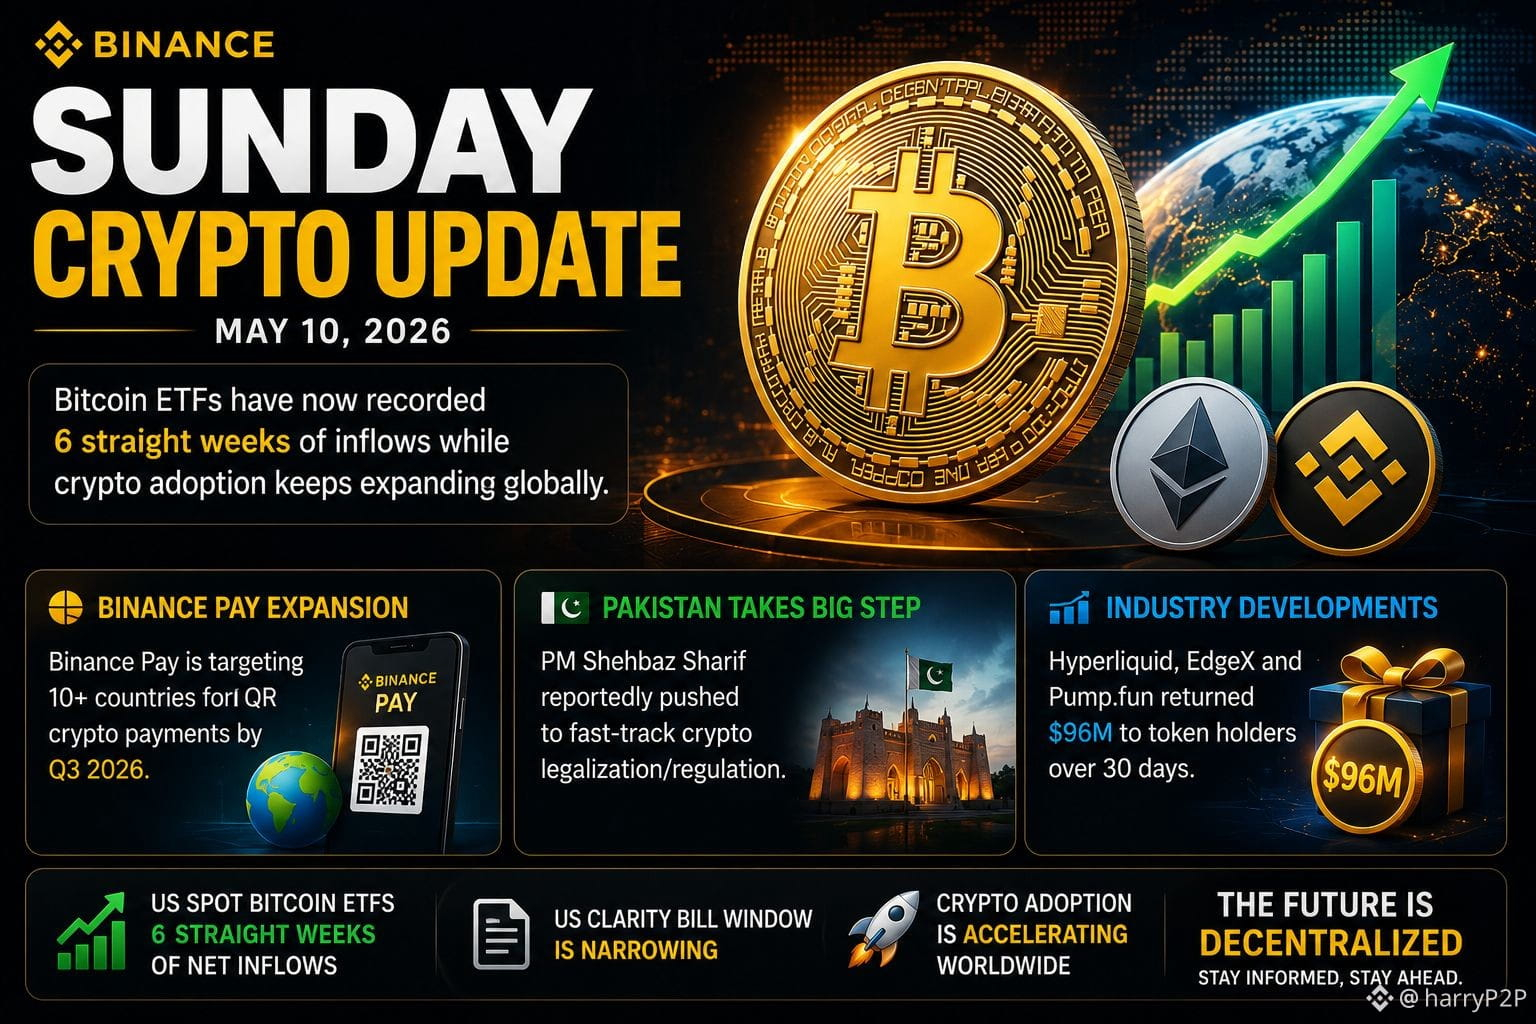
🚨 SUNDAY CRYPTO UPDATE 🚨
#BTC走势分析 Bitcoin ETFs have now recorded 6 straight weeks of inflows while crypto adoption keeps expanding globally. 👀
🔹 Binance Pay is reportedly expanding QR crypto payments to 10+ countries
🔹 Pakistan is moving closer toward crypto regulation 🇵🇰
🔹 Major platforms are returning millions back to token holders 📈
#$BTC Despite market uncertainty… crypto development isn’t slowing down. 🚀
Could 2026 become the biggest adoption year for crypto? 🤔
#Bitcoin #BTC #Binance #Crypto #Pakistan #Ethereum #MarketUpdate #tarding
1
103
·
--
Bullish
$RAVE 🚀 Bullish on $RAVE!
I'm backing $RAVE because I believe strong builders and growing communities create lasting value. The project is still early, and I'm excited to see how the ecosystem develops over time.
I'm staying patient, holding my position, and watching the next milestones closely.
Let's build. 🔥
#BullishMomentum
#StayInvested
#TARDING
#profitsignal
#signalcrypto
$RAVE
#RAVE #RaveDAO #Web3 #Crypto
$RAVE 🚀 Bullish on $RAVE !
I'm backing $RAVE because I believe strong builders and growing communities create lasting value. The project is still early, and I'm excited to see how the ecosystem develops over time.
I'm staying patient, holding my position, and watching the next milestones closely.
Let's build. 🔥
#BullishMomentum
#StayInvested
#TARDING
#profitsignal
#signalcrypto
$RAVE
#RAVE #RaveDAO #Web3 #Crypto
2
156
·
--

Article
🚨🌍 GLOBAL PEACE DEVELOPMENTS — 48-HOUR WINDOW UNDER WATCHRecent reports suggest that diplomatic discussions between Washington and Tehran are entering a sensitive phase, with attention focused on a potential short-term framework agreement.
While details remain unconfirmed, analysts say even a preliminary understanding could have significant geopolitical and economic implications.
⏳ NEXT 48 HOURS ARE CRITICAL
Observers describe this period as a key decision window where negotiations could either progress toward de-escalation or stall entirely.
🇮🇷 IRAN — REPORTED DISCUSSION POINTS:
• Possible limits on nuclear enrichment activities
• Expanded international monitoring and inspections
• Signals aimed at reducing escalation concerns
🇺🇸 UNITED STATES — REPORTED OPTIONS:
• Consideration of limited sanctions relief
• Potential unlocking of restricted financial assets
• Steps toward easing economic pressure if compliance is verified
🌊 STRAIT OF HORMUZ — STRATEGIC FOCUS AREA
The waterway remains central to global energy flows. Any improvement in regional stability could influence oil transportation and supply confidence worldwide.
📊 MARKET REACTION (EARLY INDICATORS): • Oil prices showing sensitivity to diplomatic headlines
• Equity markets adjusting to uncertainty and speculation
• Investors positioning for volatility in risk assets
⚠️ KEY RISK FACTOR
Despite ongoing discussions, the situation remains fragile. Diplomatic progress can shift quickly depending on political developments, internal pressures, or unexpected events.
🔥 POTENTIAL SCENARIOS
If talks succeed:
• Reduced geopolitical tension
• Possible stabilization in energy markets
• Improved investor confidence
• Shift toward risk-on sentiment
If talks fail:
• Renewed escalation risks
• Possible surge in oil prices
• Increased market volatility
• Flight to safe-haven assets
📌 BOTTOM LINE
This remains an evolving situation shaped by high-level diplomacy and uncertainty. Markets and observers are closely watching for verified developments before drawing conclusions.
Stay alert, as the next phase of negotiations could significantly influence global economic and geopolitical trends.$SIREN
{alpha}(560x997a58129890bbda032231a52ed1ddc845fc18e1)
$FF
{future}(FFUSDT)
$OPEN
{future}(OPENUSDT)
🚨🌍 GLOBAL PEACE DEVELOPMENTS — 48-HOUR WINDOW UNDER WATCH
Recent reports suggest that diplomatic discussions between Washington and Tehran are entering a sensitive phase, with attention focused on a potential short-term framework agreement.
While details remain unconfirmed, analysts say even a preliminary understanding could have significant geopolitical and economic implications.
⏳ NEXT 48 HOURS ARE CRITICAL
Observers describe this period as a key decision window where negotiations could either progress toward de-escalation or stall entirely.
🇮🇷 IRAN — REPORTED DISCUSSION POINTS:
• Possible limits on nuclear enrichment activities
• Expanded international monitoring and inspections
• Signals aimed at reducing escalation concerns
🇺🇸 UNITED STATES — REPORTED OPTIONS:
• Consideration of limited sanctions relief
• Potential unlocking of restricted financial assets
• Steps toward easing economic pressure if compliance is verified
🌊 STRAIT OF HORMUZ — STRATEGIC FOCUS AREA
The waterway remains central to global energy flows. Any improvement in regional stability could influence oil transportation and supply confidence worldwide.
📊 MARKET REACTION (EARLY INDICATORS): • Oil prices showing sensitivity to diplomatic headlines
• Equity markets adjusting to uncertainty and speculation
• Investors positioning for volatility in risk assets
⚠️ KEY RISK FACTOR
Despite ongoing discussions, the situation remains fragile. Diplomatic progress can shift quickly depending on political developments, internal pressures, or unexpected events.
🔥 POTENTIAL SCENARIOS
If talks succeed:
• Reduced geopolitical tension
• Possible stabilization in energy markets
• Improved investor confidence
• Shift toward risk-on sentiment
If talks fail:
• Renewed escalation risks
• Possible surge in oil prices
• Increased market volatility
• Flight to safe-haven assets
📌 BOTTOM LINE
This remains an evolving situation shaped by high-level diplomacy and uncertainty. Markets and observers are closely watching for verified developments before drawing conclusions.
Stay alert, as the next phase of negotiations could significantly influence global economic and geopolitical trends.$SIREN
$FF
$OPEN
2
234
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#UKFCAWinsCourtOrderToRecover851400Pounds
18,246 views
643 Discussing
2
#ChainlinkLaunchesCCIP2WithEnterpriseVerification
32,747 views
842 Discussing
3
#GoldFallsTo$4144
11,957 views
144 Discussing
4
#QNTFallsOver40%FromMorningHigh
74,006 views
1,267 Discussing
5
#USDTAdds845900HoldersInPast7Days
11,832 views
373 Discussing
6
#KospiFalls2.7%SamsungSKHynixDropOver5%
21,951 views
546 Discussing
7
#BitgetCEOConfirms$388MStolenInHack
4,865 views
41 Discussing
8
#BTCFallsBelow$83000
28,431 views
162 Discussing
9
#BitgetDetailsSecurityIncidentTimeline
40,742 views
691 Discussing
10
#BitcoinSpotETFs$2.39BWeeklyNetInflow
13,246 views
48 Discussing