

CryptoQuant Quicktake
9.3k පෝස්ටු

CryptoQuant Quicktake
 Binance චතුරශ්ර සත්යාපිත+
වාර්තා කරන්න
පරිශීලක අවහිර කරන්න
CryptoQuant.com - Leading On-chain Data/Analytics Provider
0 හඹා යමින්
25.2K+ හඹා යන්නන්
27.4K+ කැමති විය
පෝස්ටු
ලිපිය
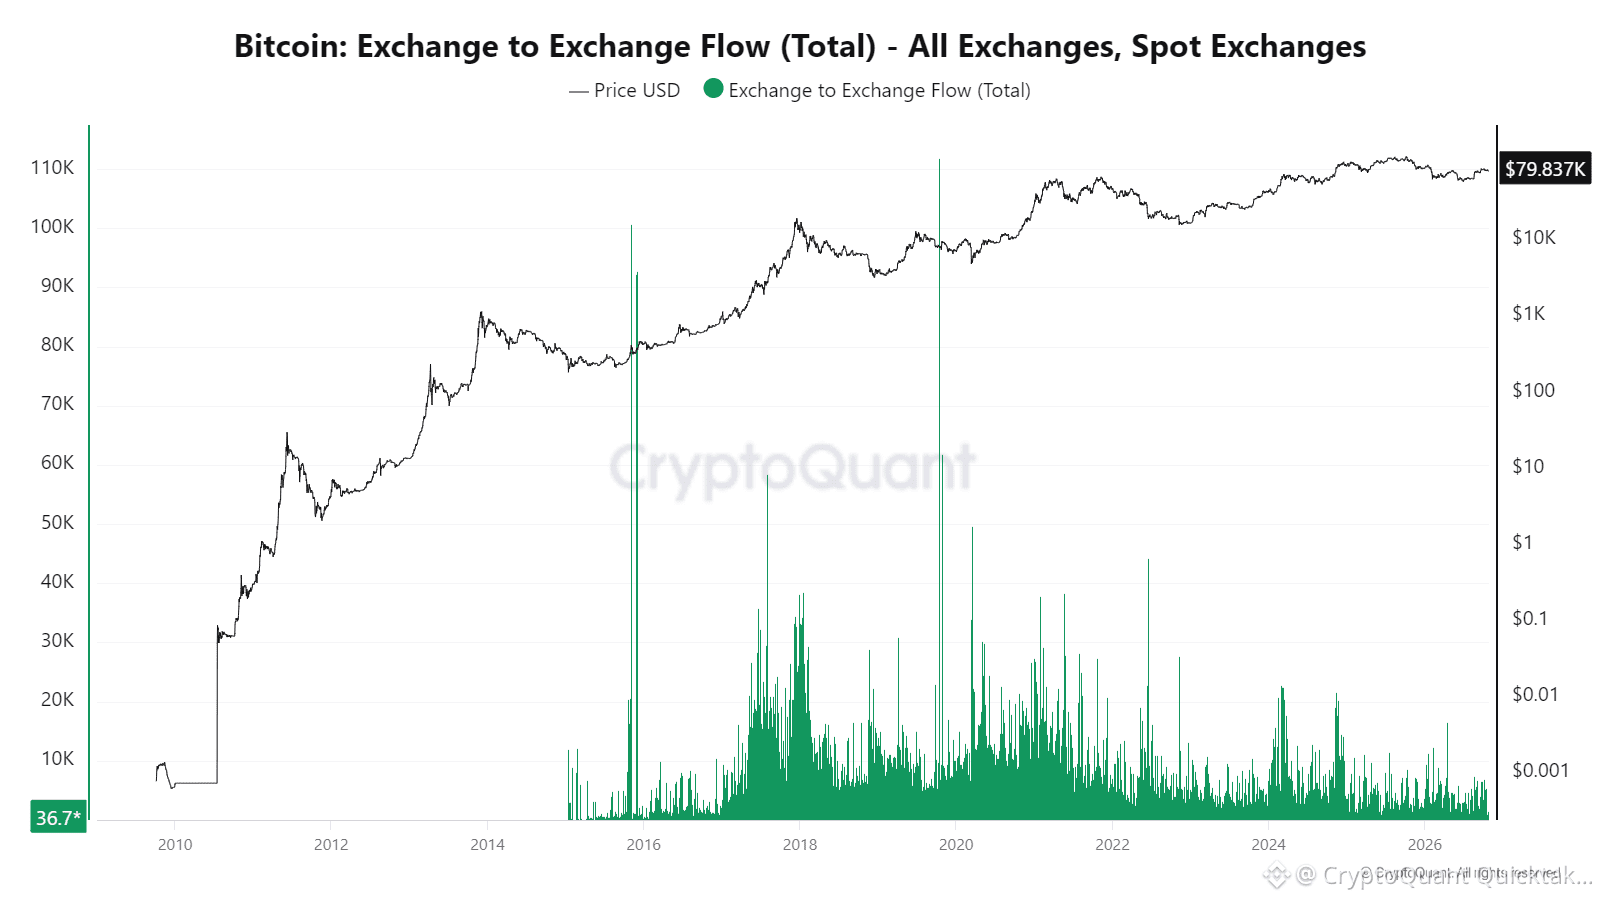
Bitcoin’s Exchange-to-exchange Flows Have Gone Quiet, and That’s Easy to MissIn earlier cycles, coins were constantly moving between exchanges, with spikes that reached tens of thousands of BTC. Today the bars sit far lower, even with price holding around $79.8K.
What stands out to me is the contrast. Price still sits high on its long-term trend, but the plumbing underneath looks calmer than in past cycles. Exchange-to-exchange flow is mostly traders and market makers moving coins for arbitrage, liquidity, and rebalancing. Less movement can mean less frantic positioning between venues.
It could also say something about where activity has moved. Part of today’s demand runs through ETFs and custody, and this metric doesn’t capture that. This says more about market structure than price itself.
The risk is reading too much into it. Low flow isn’t a signal by itself, and one chart can’t tell you direction. I’d pair it with exchange reserves, ETF flows, and whale activity before drawing a conclusion.
The bullish possibility is that calm plumbing alongside a steady price suggests coins aren’t being rushed around in fear.
Personally, I think quiet periods are easy to ignore because they don’t feel like news. I’d rather notice the quiet than guess what it’s hiding.
Written by R3N
Bitcoin’s Exchange-to-exchange Flows Have Gone Quiet, and That’s Easy to Miss
In earlier cycles, coins were constantly moving between exchanges, with spikes that reached tens of thousands of BTC. Today the bars sit far lower, even with price holding around $79.8K.
What stands out to me is the contrast. Price still sits high on its long-term trend, but the plumbing underneath looks calmer than in past cycles. Exchange-to-exchange flow is mostly traders and market makers moving coins for arbitrage, liquidity, and rebalancing. Less movement can mean less frantic positioning between venues.
It could also say something about where activity has moved. Part of today’s demand runs through ETFs and custody, and this metric doesn’t capture that. This says more about market structure than price itself.
The risk is reading too much into it. Low flow isn’t a signal by itself, and one chart can’t tell you direction. I’d pair it with exchange reserves, ETF flows, and whale activity before drawing a conclusion.
The bullish possibility is that calm plumbing alongside a steady price suggests coins aren’t being rushed around in fear.
Personally, I think quiet periods are easy to ignore because they don’t feel like news. I’d rather notice the quiet than guess what it’s hiding.
Written by R3N
3
ලිපිය
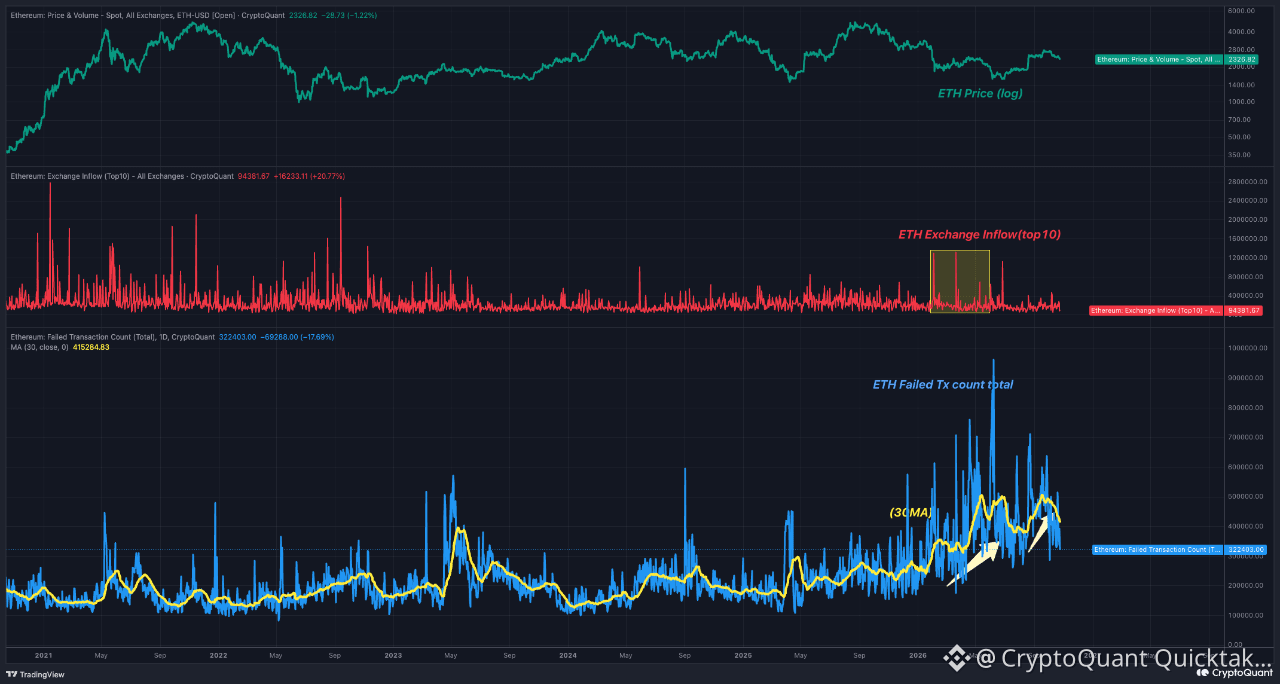
Ethereum On-Chain Activity Cools: Is Capital Rotating Into the AI Narrative?On-chain momentum across Ethereum appears to be cooling after a prolonged stretch of heavy congestion. The 30-day moving average of failed transactions—often a gauge of aggressive friction and speculative network heat—has rolled over sharply from its recent peak, while major exchange inflows remain largely subdued. Rather than signaling structural deterioration, this lull suggests capital may simply be taking a breather; with risk appetite and liquidity increasingly absorbed by the ongoing AI trade, participants might be parking dry powder on the sidelines until a clearer narrative returns to the base layer.
Written by nino
Ethereum On-Chain Activity Cools: Is Capital Rotating Into the AI Narrative?
On-chain momentum across Ethereum appears to be cooling after a prolonged stretch of heavy congestion. The 30-day moving average of failed transactions—often a gauge of aggressive friction and speculative network heat—has rolled over sharply from its recent peak, while major exchange inflows remain largely subdued. Rather than signaling structural deterioration, this lull suggests capital may simply be taking a breather; with risk appetite and liquidity increasingly absorbed by the ongoing AI trade, participants might be parking dry powder on the sidelines until a clearer narrative returns to the base layer.
Written by nino
Written by nino
68
ලිපිය
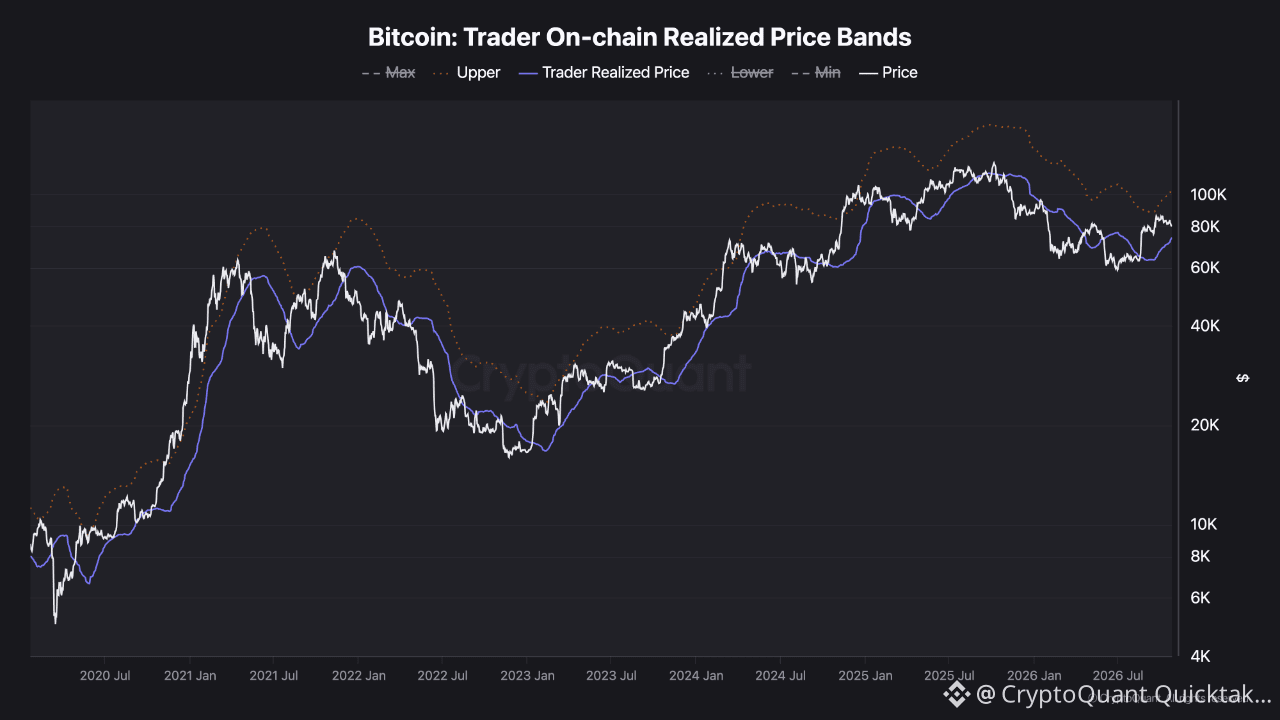
Trader Realized Price Is Rising Again — Key Support If BTC CorrectsThe Trader On-chain Realized Price reflects the average acquisition price of BTC that last moved between 1 and 3 months ago — effectively the cost basis of relatively recent market participants.
The current structure is interesting.
BTC is trading around the low-$80K area, while the Trader Realized Price has risen into the mid-$70K region.
This means price is still trading above the average cost basis of recent traders.
Historically, during bullish phases, this realized price has often acted as support when BTC corrected toward it. When price stayed below it, however, the same level could turn into resistance as underwater traders sold near breakeven.
The Upper Band is also worth monitoring.
In previous periods, price approaching the Upper Band often coincided with increased profit-taking pressure and short-term corrections.
So I currently read the structure in two steps:
• If BTC continues higher: watch the Upper Band for signs of increasing profit-taking risk.
• If BTC corrects: the Trader Realized Price becomes an important support level to monitor.
The key point is that neither level should be treated as an automatic trade signal.
The Upper Band does not guarantee a top, and the Realized Price does not guarantee a bounce.
But they provide useful reference points for where recent market participants may begin changing behavior.
For now, BTC remains above the Trader Realized Price, so the short-to-medium-term cost-basis structure is still constructive.
If a deeper correction develops, I would pay close attention to whether this rising realized price can continue acting as support.
Written by Trdaer_Gemini
Trader Realized Price Is Rising Again — Key Support If BTC Corrects
The Trader On-chain Realized Price reflects the average acquisition price of BTC that last moved between 1 and 3 months ago — effectively the cost basis of relatively recent market participants.
The current structure is interesting.
BTC is trading around the low-$80K area, while the Trader Realized Price has risen into the mid-$70K region.
This means price is still trading above the average cost basis of recent traders.
Historically, during bullish phases, this realized price has often acted as support when BTC corrected toward it. When price stayed below it, however, the same level could turn into resistance as underwater traders sold near breakeven.
The Upper Band is also worth monitoring.
In previous periods, price approaching the Upper Band often coincided with increased profit-taking pressure and short-term corrections.
So I currently read the structure in two steps:
• If BTC continues higher: watch the Upper Band for signs of increasing profit-taking risk.
• If BTC corrects: the Trader Realized Price becomes an important support level to monitor.
The key point is that neither level should be treated as an automatic trade signal.
The Upper Band does not guarantee a top, and the Realized Price does not guarantee a bounce.
But they provide useful reference points for where recent market participants may begin changing behavior.
For now, BTC remains above the Trader Realized Price, so the short-to-medium-term cost-basis structure is still constructive.
If a deeper correction develops, I would pay close attention to whether this rising realized price can continue acting as support.
Written by Trdaer_Gemini
126
ලිපිය
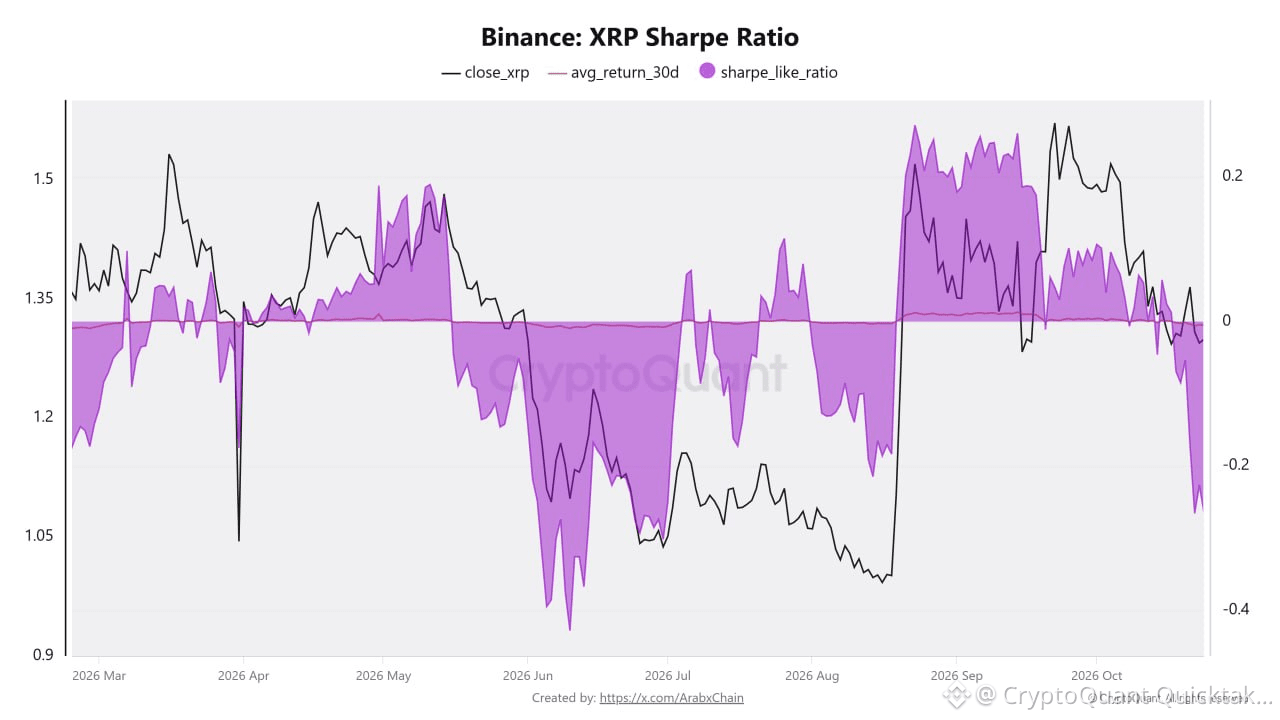
Binance XRP Sharpe-Like Ratio Falls to Four-Month LowThe Sharpe-like Ratio for XRP on Binance has fallen to approximately -0.2641, its lowest level in four months. This decline coincides with a drop in the price of XRP to around $1.29, reflecting a deterioration in risk-adjusted returns over the recent period.
The decline in Binance’s XRP Sharpe-like Ratio points to worsening risk-adjusted returns, suggesting that the returns generated during the measured period have become less attractive relative to the level of risk and volatility involved. A negative reading of approximately -0.2641 indicates that returns have underperformed relative to the benchmark used in the calculation, potentially reflecting less favorable trading conditions and heightened market uncertainty. Although reaching a four-month low signals continued weakness in risk-adjusted performance, it does not necessarily mean that the price of XRP will continue to fall.
The decline in the Sharpe-like Ratio may indicate that returns have become less attractive relative to the risks involved in trading, particularly given the inherent volatility of the cryptocurrency market. Furthermore, sustained negative readings could suggest that recent price movements have failed to generate sufficient returns to adequately compensate for the risks taken.
Written by Arab Chain
Binance XRP Sharpe-Like Ratio Falls to Four-Month Low
The Sharpe-like Ratio for XRP on Binance has fallen to approximately -0.2641, its lowest level in four months. This decline coincides with a drop in the price of XRP to around $1.29, reflecting a deterioration in risk-adjusted returns over the recent period.
The decline in Binance’s XRP Sharpe-like Ratio points to worsening risk-adjusted returns, suggesting that the returns generated during the measured period have become less attractive relative to the level of risk and volatility involved. A negative reading of approximately -0.2641 indicates that returns have underperformed relative to the benchmark used in the calculation, potentially reflecting less favorable trading conditions and heightened market uncertainty. Although reaching a four-month low signals continued weakness in risk-adjusted performance, it does not necessarily mean that the price of XRP will continue to fall.
The decline in the Sharpe-like Ratio may indicate that returns have become less attractive relative to the risks involved in trading, particularly given the inherent volatility of the cryptocurrency market. Furthermore, sustained negative readings could suggest that recent price movements have failed to generate sufficient returns to adequately compensate for the risks taken.
Written by Arab Chain
88
ලිපිය
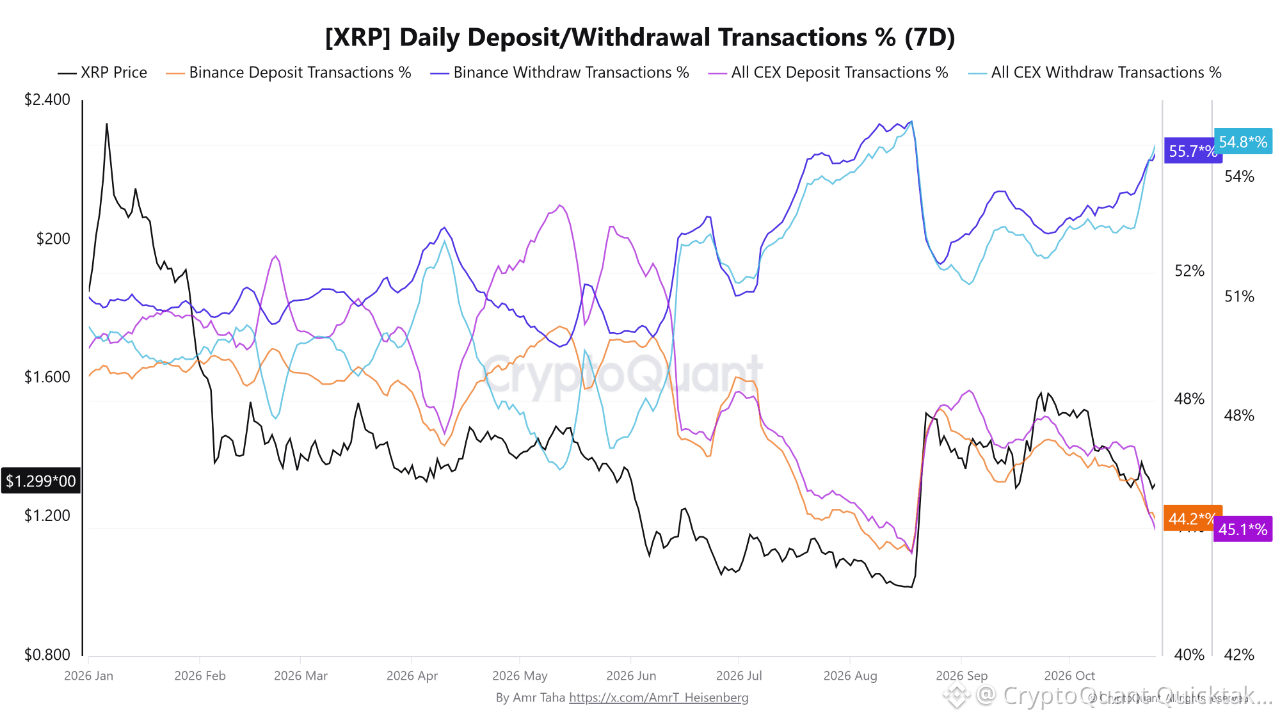
Ahead of Fed Decision, XRP Withdrawals Hit Highest Share Since August 18 As Deposits Near LowsXRP's withdrawal-transaction share is nearing its August highs, while deposit shares on both Binance and All CEX are approaching their lowest levels since August 18, just before the Federal Reserve's October 28 rate decision.
On October 25, withdrawals represented 55.75% of XRP deposit/withdrawal transactions on Binance and 54.85% across All CEX, only 1 and 0.55 percentage points below their August 18 readings of 56.75% and 55.4%.
Conversely, Binance's deposit share fell to 44.25%, near its August 18 low of 43.25%.
The All CEX deposit share stood at 45.15%, approaching its August 18 low of 44.5%.
These seven-day shares measure transaction counts, not XRP volumes or net flows; declining deposit shares mirror rising withdrawal shares.
A second chart shows a contrasting trend in the Whale vs Retail Spread, a seven-day average measuring the relative dominance of large versus small exchange outflows.
On October 26, Binance registered 49.5%, compared with 29.7% for All CEX—a 19.8-point gap.
On July 28, the readings were 35.5% and 33%, respectively, just 2.5 points apart.
The gap has widened nearly eightfold, despite only a 0.9-point difference in withdrawal-transaction shares.
Ahead of the Fed decision, an October 24 CME FedWatch snapshot showed an 89.7% probability of holding rates at 3.75%–4.00%, versus 10.3% for a 25-basis-point hike.
Crypto traders may focus on the Fed's guidance as much as the decision itself. Hawkish signals could prompt investors to turn cautious, reduce crypto exposure, or open short positions betting on price declines.
Softer signals could instead encourage greater exposure and bullish positioning.
The data show a broadly withdrawal-heavy transaction mix, but sharply different large-versus-small outflow patterns.
Written by Amr Taha
Ahead of Fed Decision, XRP Withdrawals Hit Highest Share Since August 18 As Deposits Near Lows
XRP's withdrawal-transaction share is nearing its August highs, while deposit shares on both Binance and All CEX are approaching their lowest levels since August 18, just before the Federal Reserve's October 28 rate decision.
On October 25, withdrawals represented 55.75% of XRP deposit/withdrawal transactions on Binance and 54.85% across All CEX, only 1 and 0.55 percentage points below their August 18 readings of 56.75% and 55.4%.
Conversely, Binance's deposit share fell to 44.25%, near its August 18 low of 43.25%.
The All CEX deposit share stood at 45.15%, approaching its August 18 low of 44.5%.
These seven-day shares measure transaction counts, not XRP volumes or net flows; declining deposit shares mirror rising withdrawal shares.
A second chart shows a contrasting trend in the Whale vs Retail Spread, a seven-day average measuring the relative dominance of large versus small exchange outflows.
On October 26, Binance registered 49.5%, compared with 29.7% for All CEX—a 19.8-point gap.
On July 28, the readings were 35.5% and 33%, respectively, just 2.5 points apart.
The gap has widened nearly eightfold, despite only a 0.9-point difference in withdrawal-transaction shares.
Ahead of the Fed decision, an October 24 CME FedWatch snapshot showed an 89.7% probability of holding rates at 3.75%–4.00%, versus 10.3% for a 25-basis-point hike.
Crypto traders may focus on the Fed's guidance as much as the decision itself. Hawkish signals could prompt investors to turn cautious, reduce crypto exposure, or open short positions betting on price declines.
Softer signals could instead encourage greater exposure and bullish positioning.
The data show a broadly withdrawal-heavy transaction mix, but sharply different large-versus-small outflow patterns.
Written by Amr Taha
147
ලිපිය
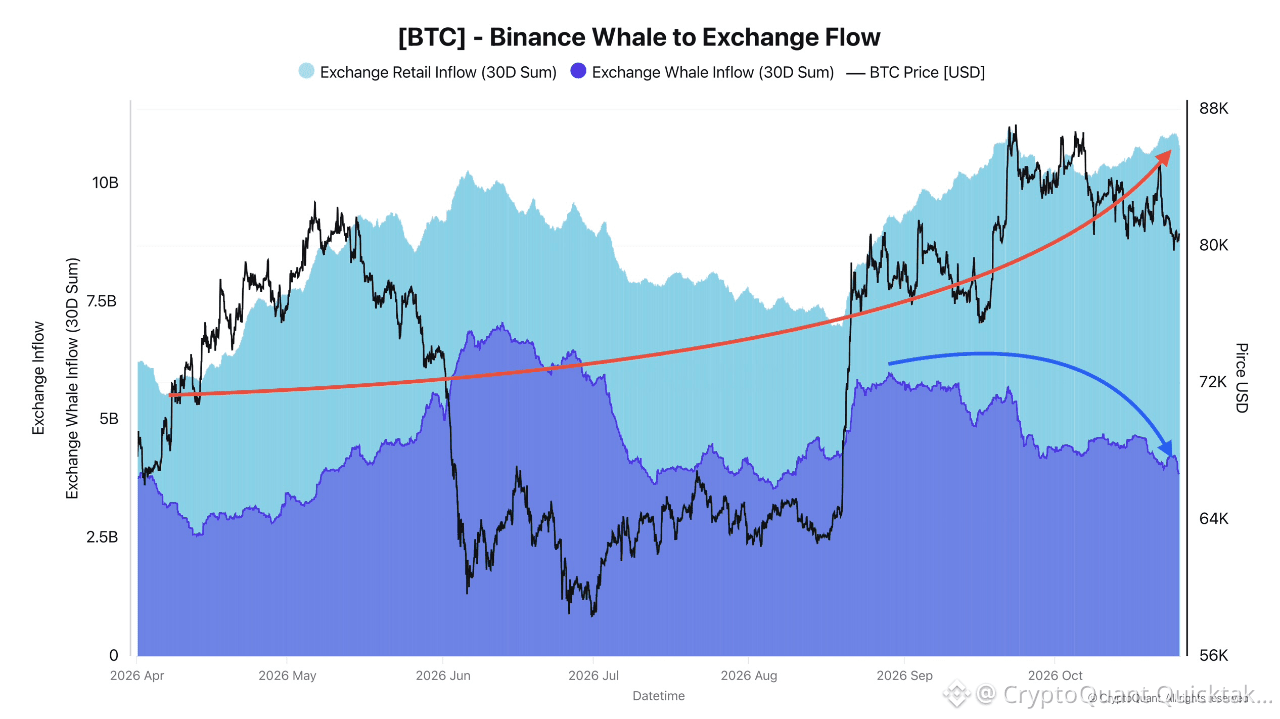
Retail Inflows Hit a 6-Month High As BTC Holds $80KBTC flow analysis shows that whales and retail investors are behaving in radically opposite ways right now.
This is not new, retail investors are known for being more emotional, more unstable and more reactive to market moves than whales. But the gap we are seeing today is particularly wide.
On the retail side, inflows are surging on Binance. With Bitcoin holding above $80 000 for several weeks, deposits from small holders have reached their highest level in 6 months. On a 30-day sum basis, they have gone from $5.5B to $10.75B, nearly doubling in a very short time.
On the whale side, it's the opposite. Their BTC inflows to Binance have been declining steadily for almost 2 months, falling from $5.9B at the end of August to $3.8B today. No sign of rush.
After a decline that lasted a full year, retail investors seem to be treating this first rebound as an exit window, a chance to sell at more comfortable levels and relieve built-up pressure.
Whales, on the other hand, are staying patient and are in no hurry to send their BTC to exchanges, which suggests they are not looking to distribute at these levels.
This divergence is worth watching, particularly to see whether whales will maintain this restraint if the price keeps climbing.
Written by Darkfost
Retail Inflows Hit a 6-Month High As BTC Holds $80K
BTC flow analysis shows that whales and retail investors are behaving in radically opposite ways right now.
This is not new, retail investors are known for being more emotional, more unstable and more reactive to market moves than whales. But the gap we are seeing today is particularly wide.
On the retail side, inflows are surging on Binance. With Bitcoin holding above $80 000 for several weeks, deposits from small holders have reached their highest level in 6 months. On a 30-day sum basis, they have gone from $5.5B to $10.75B, nearly doubling in a very short time.
On the whale side, it's the opposite. Their BTC inflows to Binance have been declining steadily for almost 2 months, falling from $5.9B at the end of August to $3.8B today. No sign of rush.
After a decline that lasted a full year, retail investors seem to be treating this first rebound as an exit window, a chance to sell at more comfortable levels and relieve built-up pressure.
Whales, on the other hand, are staying patient and are in no hurry to send their BTC to exchanges, which suggests they are not looking to distribute at these levels.
This divergence is worth watching, particularly to see whether whales will maintain this restraint if the price keeps climbing.
Written by Darkfost
1
267
ලිපිය
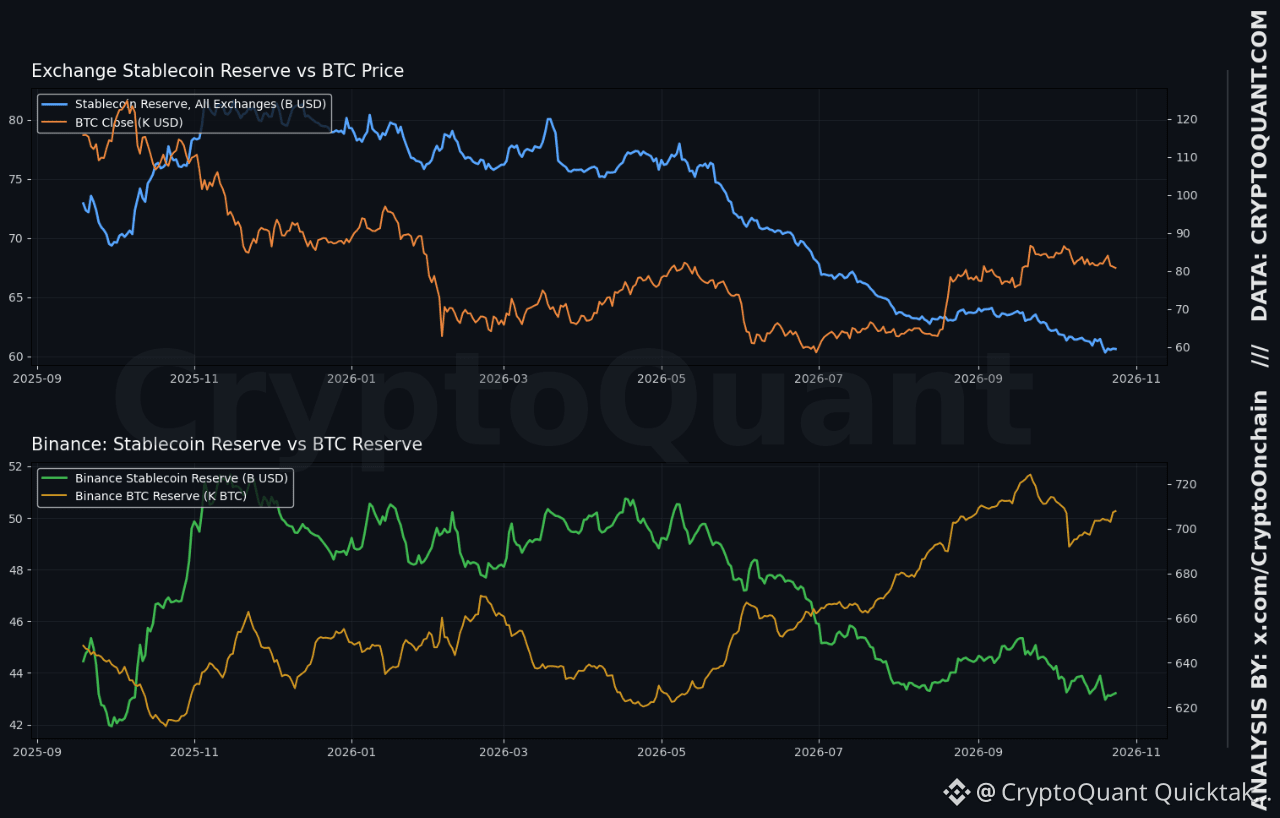
Exchange Stablecoin Reserves At 60.6B, a 12-Month LowStablecoin reserves across all exchanges were 60.62B on Oct 24, at the 1st percentile of the past year.
Binance stablecoin reserves were 43.21B on Oct 24, at the 2nd percentile.
BTC closed at 80.8K on Oct 24, at the 66th percentile of the past year.
Data notes: 50 columns were stale and excluded, and the macro module did not load. Metrics with low denominators were not published.
Macro context: [Insert this week's CPI/PPI/rate/DXY event here. The macro module failed, so it was not verified.]
Observation → Context: Stablecoin netflow across all exchanges was -34.2M on Oct 24, and the 7-day average was -93.9M. Binance stablecoin netflow was +48.2M on the day, against a 7-day average of -61.2M. Binance's BTC reserve was 707.9K, at the 88th percentile, while Coinbase's was 848.1K, at the 4th percentile. The Coinbase Premium Index was -0.1465, at the 13th percentile.
Comparison with baseline: Binance open interest was 9.15B and funding was 0.0045. Both sit in the upper-middle of their 1-year ranges (OI 54th percentile, funding 70th). Leverage looks moderate rather than stretched.
One candidate explanation, unverified: stablecoins may be moving to self-custody, to other venues, or into redemptions. This would reduce the buying capacity held on exchanges.
Lower stablecoin reserves with a negative Coinbase premium suggest US spot demand may be soft. This creates conditions that historically preceded range-bound periods. Binance's higher BTC reserve and mixed stablecoin flows add context to that reading.
For now, the clearest reading is that exchange-side buying capacity is thinner, while leverage has not yet stretched.
Written by CryptoOnchain
Exchange Stablecoin Reserves At 60.6B, a 12-Month Low
Stablecoin reserves across all exchanges were 60.62B on Oct 24, at the 1st percentile of the past year.
Binance stablecoin reserves were 43.21B on Oct 24, at the 2nd percentile.
BTC closed at 80.8K on Oct 24, at the 66th percentile of the past year.
Data notes: 50 columns were stale and excluded, and the macro module did not load. Metrics with low denominators were not published.
Macro context: [Insert this week's CPI/PPI/rate/DXY event here. The macro module failed, so it was not verified.]
Observation → Context: Stablecoin netflow across all exchanges was -34.2M on Oct 24, and the 7-day average was -93.9M. Binance stablecoin netflow was +48.2M on the day, against a 7-day average of -61.2M. Binance's BTC reserve was 707.9K, at the 88th percentile, while Coinbase's was 848.1K, at the 4th percentile. The Coinbase Premium Index was -0.1465, at the 13th percentile.
Comparison with baseline: Binance open interest was 9.15B and funding was 0.0045. Both sit in the upper-middle of their 1-year ranges (OI 54th percentile, funding 70th). Leverage looks moderate rather than stretched.
One candidate explanation, unverified: stablecoins may be moving to self-custody, to other venues, or into redemptions. This would reduce the buying capacity held on exchanges.
Lower stablecoin reserves with a negative Coinbase premium suggest US spot demand may be soft. This creates conditions that historically preceded range-bound periods. Binance's higher BTC reserve and mixed stablecoin flows add context to that reading.
For now, the clearest reading is that exchange-side buying capacity is thinner, while leverage has not yet stretched.
Written by CryptoOnchain
1
223
ලිපිය
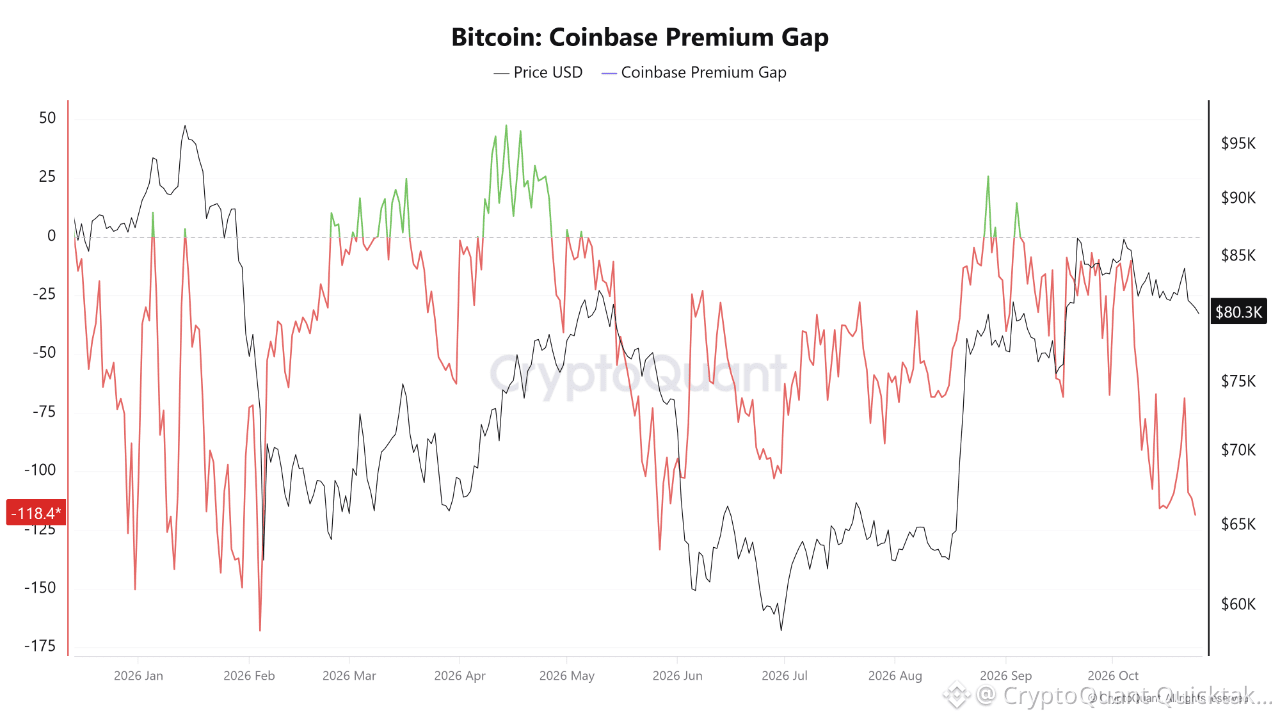
Bitcoin Coinbase Premium Gap Falls to Five-Month Low, Signaling Weaker US DemandThe Coinbase Premium Gap indicator recorded a negative value of -$118.49, coinciding with Bitcoin trading at approximately $80,000, its lowest level in five months. This reading reflects a lower Bitcoin price on Coinbase compared to Binance, indicating a widening negative price gap between the two exchanges.
The indicator measures the absolute price difference between an asset on Coinbase Pro, traded against the US dollar (USD), and its price on Binance, traded against the USDT stablecoin. It expresses this difference in dollar terms rather than as a percentage. When the reading is positive and the gap widens, Bitcoin is priced higher on Coinbase than on Binance, potentially reflecting stronger relative demand from US-based market participants, including institutional investors and traders using USD-denominated markets.
Conversely, when the gap narrows or turns negative, it may indicate weakening demand from US market participants relative to those trading on Binance. This can result from reduced buying activity or increased selling pressure among participants using USD-denominated markets. The current reading of -$118.49 indicates that Bitcoin is priced relatively higher on Binance than on Coinbase, suggesting weaker relative demand on Coinbase. However, the indicator alone cannot determine whether this is driven by reduced buying activity or increased selling pressure.
persistent negative readings may reflect relatively weaker demand on Coinbase compared to Binance, while a narrowing gap or a return to positive territory could signal an improvement in relative demand. Monitoring these indicators alongside trading volumes, ETF flows, and derivatives data can provide a more comprehensive view of Bitcoin market conditions.
Written by Arab Chain
Bitcoin Coinbase Premium Gap Falls to Five-Month Low, Signaling Weaker US Demand
The Coinbase Premium Gap indicator recorded a negative value of -$118.49, coinciding with Bitcoin trading at approximately $80,000, its lowest level in five months. This reading reflects a lower Bitcoin price on Coinbase compared to Binance, indicating a widening negative price gap between the two exchanges.
The indicator measures the absolute price difference between an asset on Coinbase Pro, traded against the US dollar (USD), and its price on Binance, traded against the USDT stablecoin. It expresses this difference in dollar terms rather than as a percentage. When the reading is positive and the gap widens, Bitcoin is priced higher on Coinbase than on Binance, potentially reflecting stronger relative demand from US-based market participants, including institutional investors and traders using USD-denominated markets.
Conversely, when the gap narrows or turns negative, it may indicate weakening demand from US market participants relative to those trading on Binance. This can result from reduced buying activity or increased selling pressure among participants using USD-denominated markets. The current reading of -$118.49 indicates that Bitcoin is priced relatively higher on Binance than on Coinbase, suggesting weaker relative demand on Coinbase. However, the indicator alone cannot determine whether this is driven by reduced buying activity or increased selling pressure.
persistent negative readings may reflect relatively weaker demand on Coinbase compared to Binance, while a narrowing gap or a return to positive territory could signal an improvement in relative demand. Monitoring these indicators alongside trading volumes, ETF flows, and derivatives data can provide a more comprehensive view of Bitcoin market conditions.
Written by Arab Chain
1
140
ලිපිය
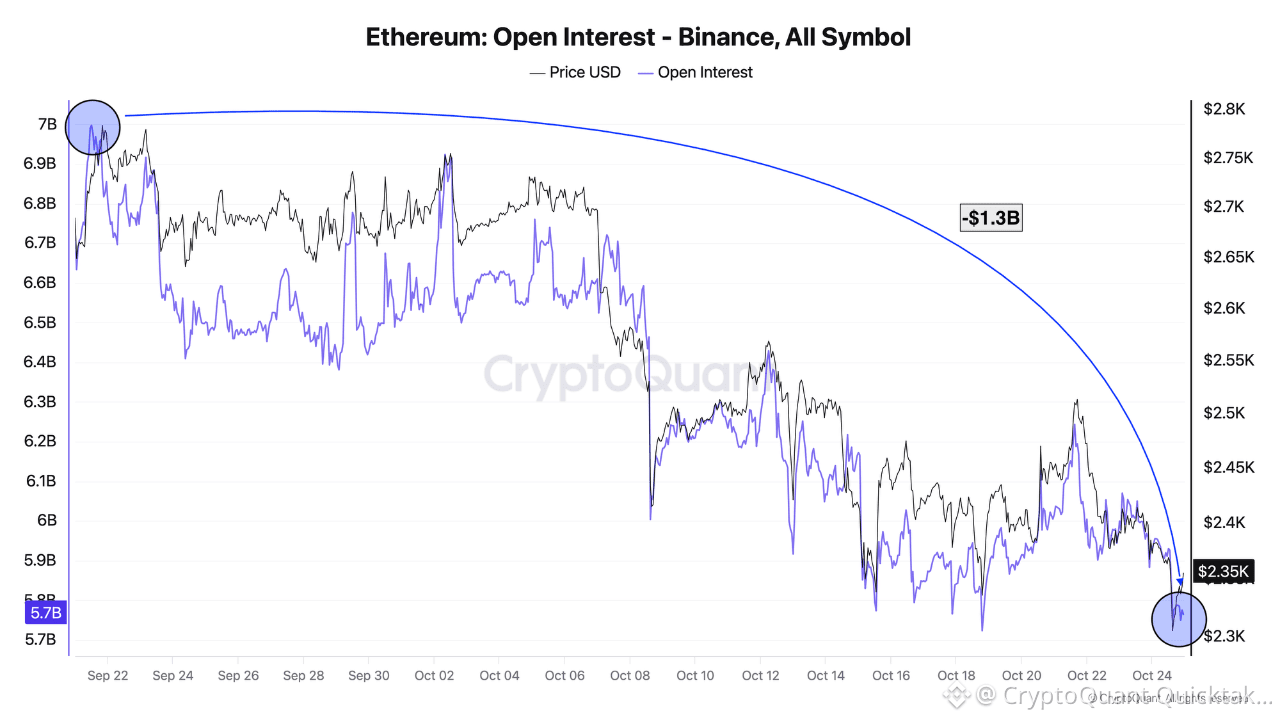
Ethereum Loses $54B in Market Cap As Open Interest Falls to $11.5BOver the past three weeks, altcoins, and Ethereum in particular, have posted largely negative performance. ETH has corrected by around 15% over the period, a loss of $54B in market cap.
This trend is especially visible in derivatives: ETH Open Interest on Binance has lost $1.3B in a month, nearly 20%, bringing it back to $5.7B.
Across all exchanges, total Open Interest has fallen to $11.5B. On a 30-day basis, other platforms have also recorded a sharp drop: Gate shows -$995M, HTX -$857M, and Bybit -$310M.
Binance nonetheless still concentrates 50% of Ethereum's Open Interest, versus 17.5% for Bybit and 14.7% for Gate and OKX.
This widespread decline is the result of several factors combined: the price drop, the liquidations it triggers, and investor behavior, as traders often reduce risk by closing positions when prices fall.
In July, Open Interest had dropped even more sharply. That deleveraging phase allowed Ethereum to stabilize before launching a technical rebound of more than 32% pushing its price above $2 800 for the first time since January.
These deleveraging periods are part of the correction process. They create fear in the market and often mark the final phase of a correction.
Written by Darkfost
Ethereum Loses $54B in Market Cap As Open Interest Falls to $11.5B
Over the past three weeks, altcoins, and Ethereum in particular, have posted largely negative performance. ETH has corrected by around 15% over the period, a loss of $54B in market cap.
This trend is especially visible in derivatives: ETH Open Interest on Binance has lost $1.3B in a month, nearly 20%, bringing it back to $5.7B.
Across all exchanges, total Open Interest has fallen to $11.5B. On a 30-day basis, other platforms have also recorded a sharp drop: Gate shows -$995M, HTX -$857M, and Bybit -$310M.
Binance nonetheless still concentrates 50% of Ethereum's Open Interest, versus 17.5% for Bybit and 14.7% for Gate and OKX.
This widespread decline is the result of several factors combined: the price drop, the liquidations it triggers, and investor behavior, as traders often reduce risk by closing positions when prices fall.
In July, Open Interest had dropped even more sharply. That deleveraging phase allowed Ethereum to stabilize before launching a technical rebound of more than 32% pushing its price above $2 800 for the first time since January.
These deleveraging periods are part of the correction process. They create fear in the market and often mark the final phase of a correction.
Written by Darkfost
1
157
ලිපිය
U.S. Midterms in 9 Days: What Will Happen to Bitcoin? Polls and the $80K BattleThe U.S. midterm elections are set for November 3, just nine days away. All 435 House seats and 35 Senate seats are on the ballot. The results could reshape the final two years of President Trump's term—and influence financial markets.
An October Reuters/Ipsos poll showed Democrats leading Republicans 47% to 35% in congressional voting intentions, while Trump's approval stood at 31%. But nationwide polls do not directly predict seats won in individual districts.
Crypto regulation is another issue. Progress on the CLARITY Act stalled in the Senate in September. The new Congress could affect the pace and shape of digital-asset legislation, regardless of which party controls it.
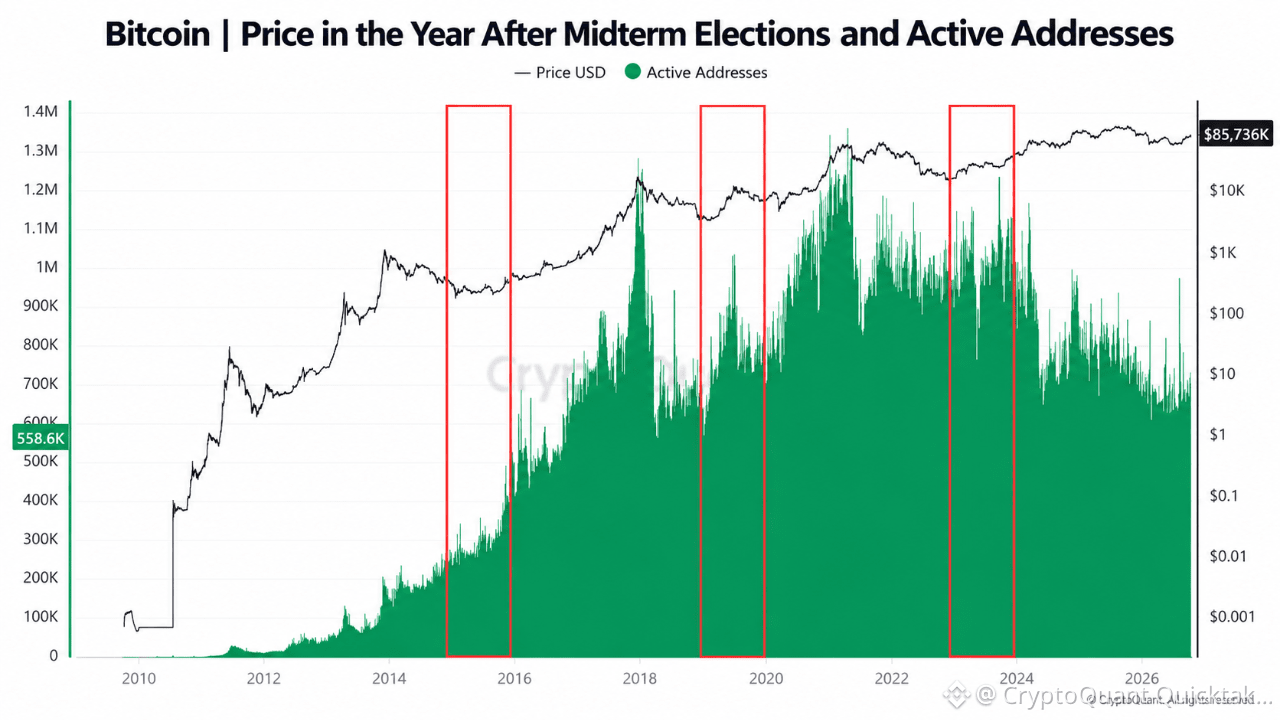
History offers some encouragement, but no guarantee. Bitcoin recovered in the year following the 2014, 2018 and 2022 midterms. Yet each period had different monetary conditions, and Bitcoin's four-year cycle also complicates comparisons.
This time, spot Bitcoin ETFs are a major source of demand. Coinbase Institutional reported roughly $6.4 billion in ETF inflows since August, compared with $1.5 billion in corporate BTC purchases. Flows remain volatile: approximately $525 million entered on October 21, followed by $636 million in outflows the next day.
For BTC, $80,000–$82,000 is a key area to watch, while $85,000–$87,500 may present resistance. Oil prices, inflation, bond yields and Federal Reserve policy could matter as much as the election.
At XWIN, we believe the key question is not simply who wins, but what happens to capital afterward. Do ETF inflows resume? Does U.S. spot demand improve? Are large holders buying or selling? Follow the money, not just the headlines.
Written by XWIN Japan
U.S. Midterms in 9 Days: What Will Happen to Bitcoin? Polls and the $80K Battle
The U.S. midterm elections are set for November 3, just nine days away. All 435 House seats and 35 Senate seats are on the ballot. The results could reshape the final two years of President Trump's term—and influence financial markets.
An October Reuters/Ipsos poll showed Democrats leading Republicans 47% to 35% in congressional voting intentions, while Trump's approval stood at 31%. But nationwide polls do not directly predict seats won in individual districts.
Crypto regulation is another issue. Progress on the CLARITY Act stalled in the Senate in September. The new Congress could affect the pace and shape of digital-asset legislation, regardless of which party controls it.
History offers some encouragement, but no guarantee. Bitcoin recovered in the year following the 2014, 2018 and 2022 midterms. Yet each period had different monetary conditions, and Bitcoin's four-year cycle also complicates comparisons.
This time, spot Bitcoin ETFs are a major source of demand. Coinbase Institutional reported roughly $6.4 billion in ETF inflows since August, compared with $1.5 billion in corporate BTC purchases. Flows remain volatile: approximately $525 million entered on October 21, followed by $636 million in outflows the next day.
For BTC, $80,000–$82,000 is a key area to watch, while $85,000–$87,500 may present resistance. Oil prices, inflation, bond yields and Federal Reserve policy could matter as much as the election.
At XWIN, we believe the key question is not simply who wins, but what happens to capital afterward. Do ETF inflows resume? Does U.S. spot demand improve? Are large holders buying or selling? Follow the money, not just the headlines.
Written by XWIN Japan
248
ලිපිය
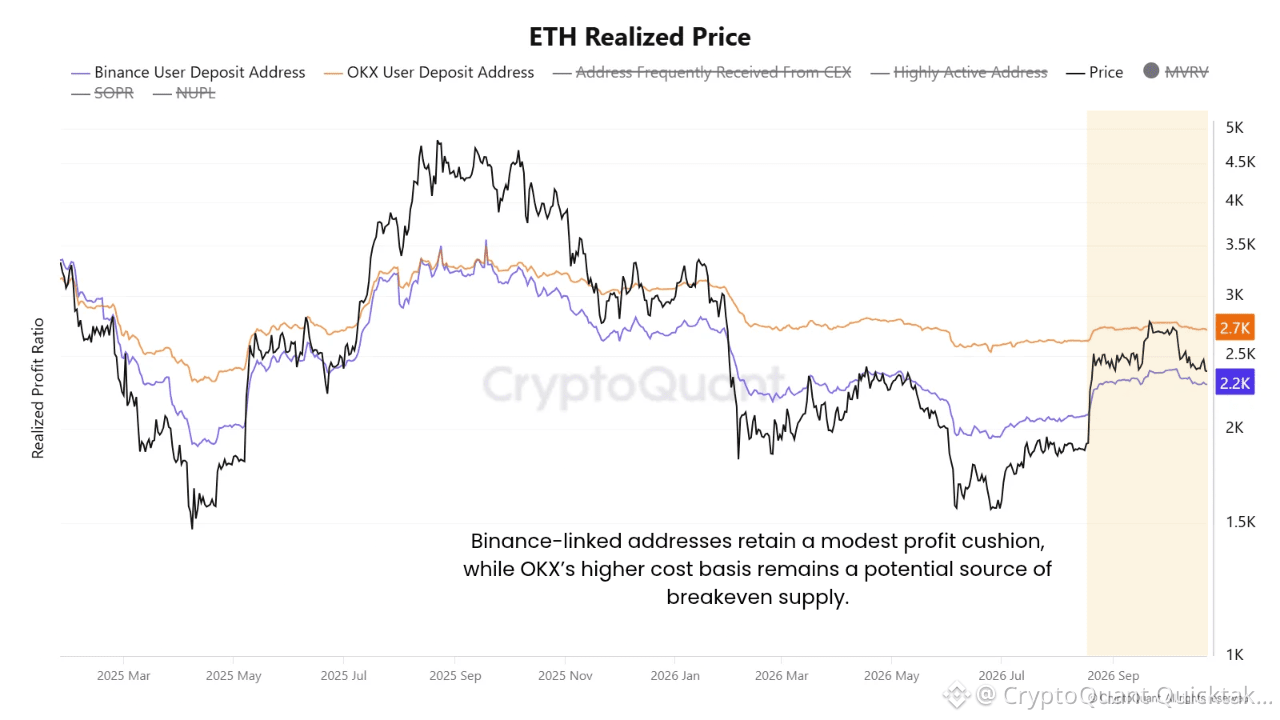
ETH Between Binance’s Profit Cushion and OKX’s Potential Exit SupplyEthereum’s recovery has restored profitability unevenly across exchange-linked cohorts, leaving price between two distinct cost-basis levels.
The realized price of Binance user deposit addresses stands near $2,200, compared with approximately $2,700 for OKX. With ETH trading around $2,350–$2,400 in the chart, the Binance-linked cohort retains a modest aggregate profit cushion, while the OKX-linked cohort remains underwater.
This $500 gap reveals different incentives beneath the same price action. A pullback toward $2,200 would erode the remaining profitability of the Binance-linked cohort. A recovery toward $2,700 would bring the OKX-linked cohort closer to breakeven, potentially giving holders an opportunity to reduce exposure after spending time at a loss.
The latest rebound reached the vicinity of the OKX cost basis before retreating. That is consistent with potential breakeven selling, although the chart alone cannot establish who sold or whether those sales drove the rejection.
The recovery therefore remains incomplete across these cohorts. ETH has moved above one on-chain cost benchmark but has yet to establish sustained acceptance above the other.
Holding the Binance reference through another pullback would strengthen the recovery thesis. Reclaiming and holding above the OKX reference would extend the improvement to both cohorts. A sustained break below $2,200 would instead place both underwater, broadening the potential pressure on holders.
Written by MorenoDV_
ETH Between Binance’s Profit Cushion and OKX’s Potential Exit Supply
Ethereum’s recovery has restored profitability unevenly across exchange-linked cohorts, leaving price between two distinct cost-basis levels.
The realized price of Binance user deposit addresses stands near $2,200, compared with approximately $2,700 for OKX. With ETH trading around $2,350–$2,400 in the chart, the Binance-linked cohort retains a modest aggregate profit cushion, while the OKX-linked cohort remains underwater.
This $500 gap reveals different incentives beneath the same price action. A pullback toward $2,200 would erode the remaining profitability of the Binance-linked cohort. A recovery toward $2,700 would bring the OKX-linked cohort closer to breakeven, potentially giving holders an opportunity to reduce exposure after spending time at a loss.
The latest rebound reached the vicinity of the OKX cost basis before retreating. That is consistent with potential breakeven selling, although the chart alone cannot establish who sold or whether those sales drove the rejection.
The recovery therefore remains incomplete across these cohorts. ETH has moved above one on-chain cost benchmark but has yet to establish sustained acceptance above the other.
Holding the Binance reference through another pullback would strengthen the recovery thesis. Reclaiming and holding above the OKX reference would extend the improvement to both cohorts. A sustained break below $2,200 would instead place both underwater, broadening the potential pressure on holders.
Written by MorenoDV_
1
1.3k
ලිපිය
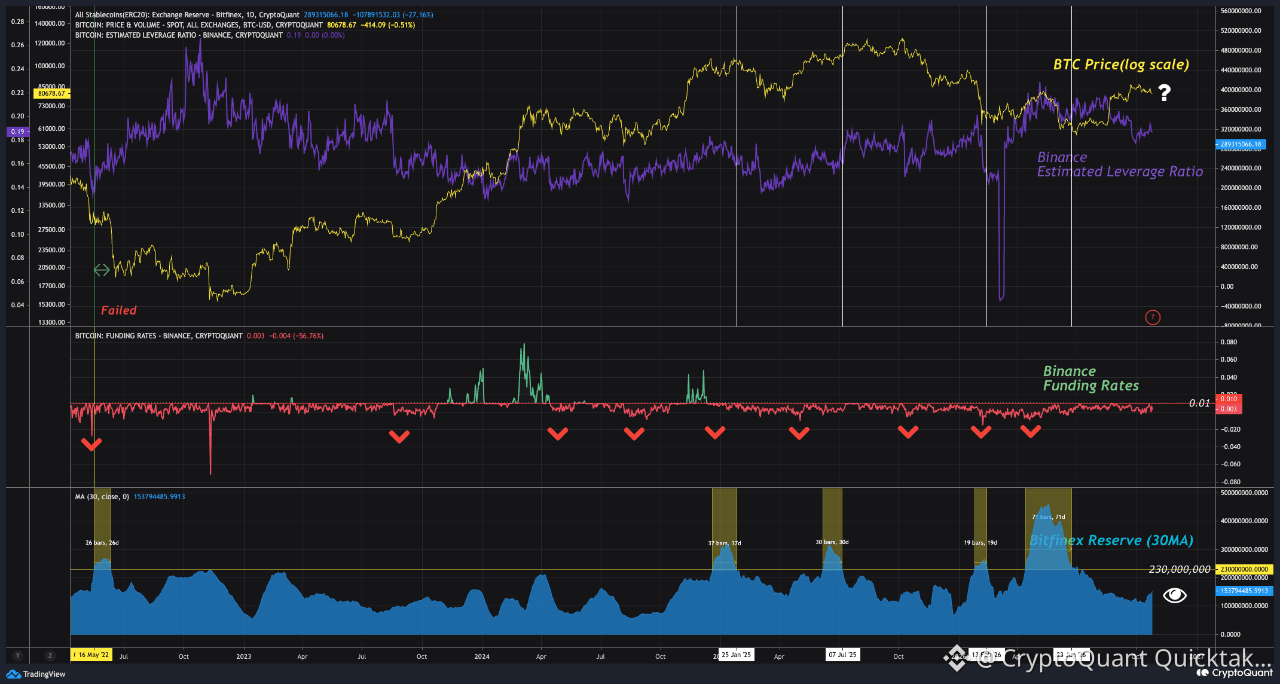
Bitfinex Reserves Subdued: Trend Extension or Lack of Conviction?Bitfinex stablecoin reserves remain subdued well below past critical thresholds, pointing to an environment where active market participation has quietly dried up. With leverage ratios largely contained and funding hovering near neutral, the price action lacks the speculative froth typically seen at major cycle exhaustion points. This absence of aggressive retail interest hints that the broader trend might still have room to grind upward—though in a market this hollow, any sudden liquidity shift could easily trigger erratic chop before clear directional conviction emerges.
Written by nino
Bitfinex Reserves Subdued: Trend Extension or Lack of Conviction?
Bitfinex stablecoin reserves remain subdued well below past critical thresholds, pointing to an environment where active market participation has quietly dried up. With leverage ratios largely contained and funding hovering near neutral, the price action lacks the speculative froth typically seen at major cycle exhaustion points. This absence of aggressive retail interest hints that the broader trend might still have room to grind upward—though in a market this hollow, any sudden liquidity shift could easily trigger erratic chop before clear directional conviction emerges.
Written by nino
Written by nino
270
ලිපිය
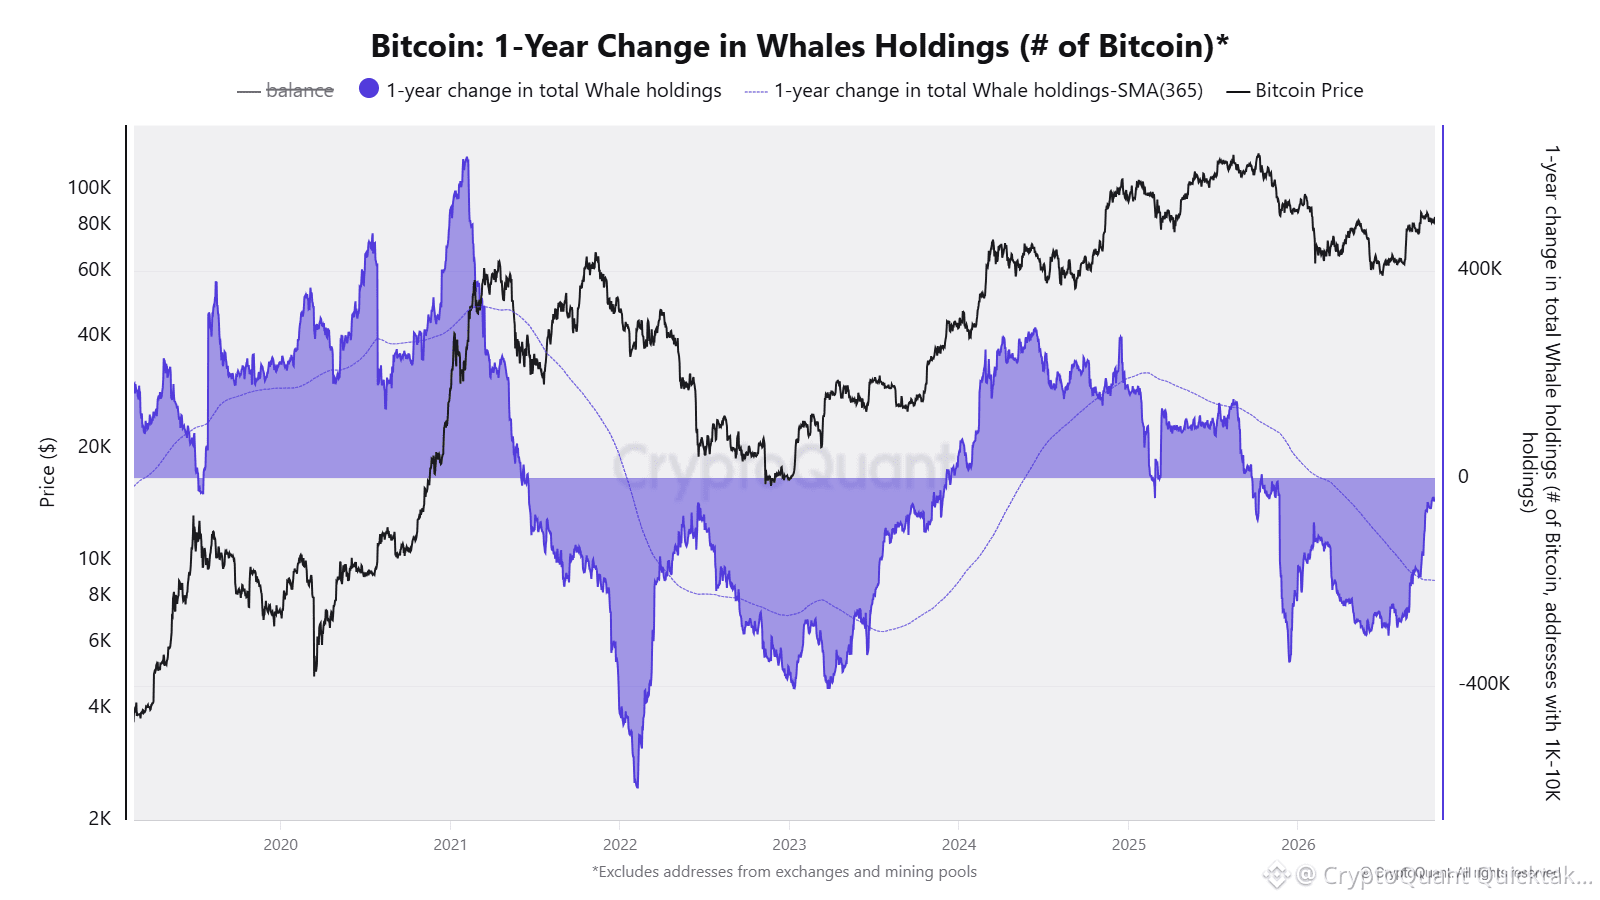
Bitcoin Whales Finished Their Selling in July and Are Now Rapidly Increasing Their Holdings.The $BTC 1-Year Change in Whale Holdings indicator is nearing positive territory.
Whale accumulation is accelerating, with their 1-year holdings change approaching a shift into the positive.
The selling pressure from whales concluded in July, and the change in their $BTC holdings has risen rapidly from -282k to the current level of -39k.
In less than three months, $BTC whales have made a net purchase of 243k $BTC.
Written by CW8900
Bitcoin Whales Finished Their Selling in July and Are Now Rapidly Increasing Their Holdings.
The $BTC 1-Year Change in Whale Holdings indicator is nearing positive territory.
Whale accumulation is accelerating, with their 1-year holdings change approaching a shift into the positive.
The selling pressure from whales concluded in July, and the change in their $BTC holdings has risen rapidly from -282k to the current level of -39k.
In less than three months, $BTC whales have made a net purchase of 243k $BTC.
Written by CW8900
1
313
ලිපිය
Bitcoin Below $80,000: CryptoQuant’s Downside Levels and Rebound ScenariosBitcoin’s $80,000 level is a key test amid rising US yields, oil prices and Fed uncertainty. Yet what matters most is who buys and sells if BTC breaks it.
CryptoQuant’s October 13 report placed the 365-day moving average near $80,000 and the 200-day average near $71,000. Its Bull Score Index stood at 80, indicating that bullish signals persisted.
Scenario 1 — Brief break, then rebound.
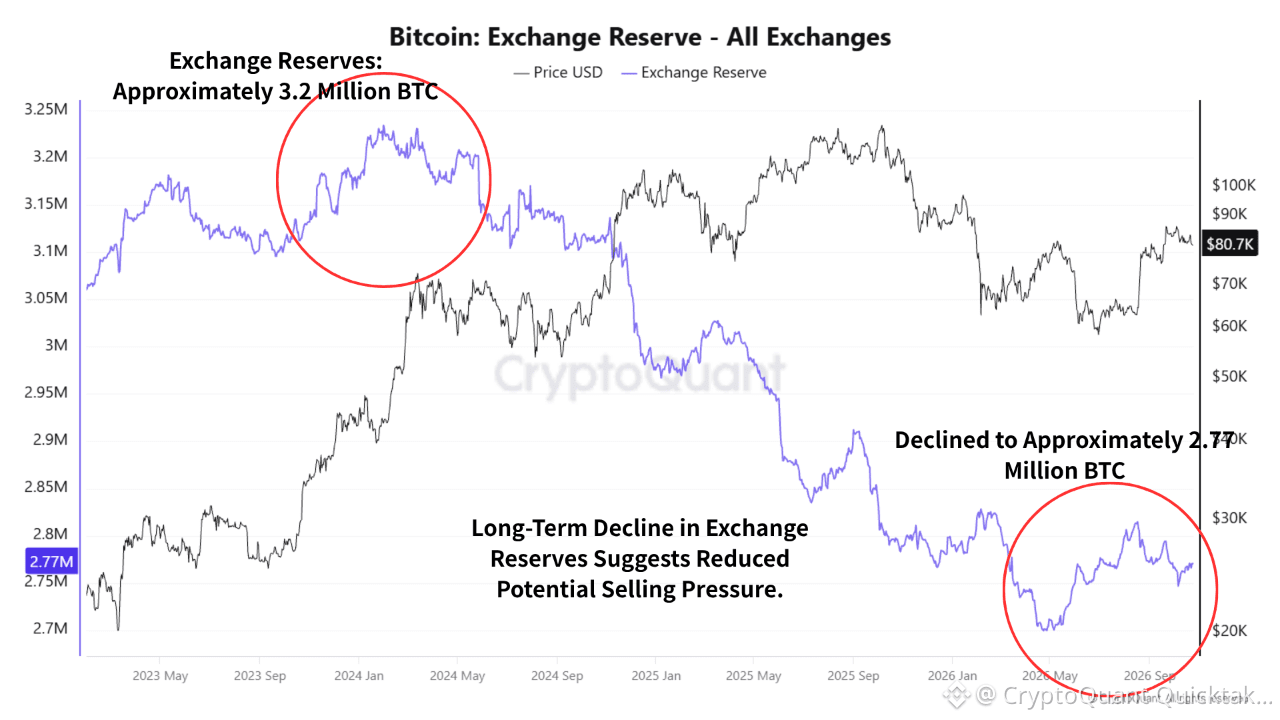
Exchange reserves have fallen over time, suggesting less BTC is readily available for sale. Some whales have accumulated. If leveraged longs are liquidated but spot demand holds, BTC could reclaim $80,000 and test $83,000–$85,000.
Scenario 2 — A slide toward $77,000.
CryptoQuant estimated new whales’ realized price, or average cost basis, at roughly $77,000 in mid-October. If spot demand stays weak after an $80,000 break, that becomes the next key level. Below it, newer whales may face unrealized losses. Watch whether they send BTC to exchanges or keep holding.
Scenario 3 — Support holds, but momentum stalls.
Holding $80,000 does not guarantee a rally. Whale positions are mixed and spot demand uneven. Improvements in Apparent Demand and Coinbase Premium would better confirm renewed buying.
The October 27–28 FOMC meeting and US economic releases could affect yields, the dollar and BTC. Futures open interest and funding rates also warrant attention amid liquidation risks.
XWIN’s view: A break below $80,000 alone does not signal a bear market. ETF inflows, whale accumulation and spot buying could support a rebound. But weakening demand and rising exchange inflows would increase downside risk toward $77,000. The $71,000 moving average is a longer-term reference, not a price forecast.
The real question: Who will buy Bitcoin at $80,000?
Written by XWIN Japan
Bitcoin Below $80,000: CryptoQuant’s Downside Levels and Rebound Scenarios
Bitcoin’s $80,000 level is a key test amid rising US yields, oil prices and Fed uncertainty. Yet what matters most is who buys and sells if BTC breaks it.
CryptoQuant’s October 13 report placed the 365-day moving average near $80,000 and the 200-day average near $71,000. Its Bull Score Index stood at 80, indicating that bullish signals persisted.
Scenario 1 — Brief break, then rebound.
Exchange reserves have fallen over time, suggesting less BTC is readily available for sale. Some whales have accumulated. If leveraged longs are liquidated but spot demand holds, BTC could reclaim $80,000 and test $83,000–$85,000.
Scenario 2 — A slide toward $77,000.
CryptoQuant estimated new whales’ realized price, or average cost basis, at roughly $77,000 in mid-October. If spot demand stays weak after an $80,000 break, that becomes the next key level. Below it, newer whales may face unrealized losses. Watch whether they send BTC to exchanges or keep holding.
Scenario 3 — Support holds, but momentum stalls.
Holding $80,000 does not guarantee a rally. Whale positions are mixed and spot demand uneven. Improvements in Apparent Demand and Coinbase Premium would better confirm renewed buying.
The October 27–28 FOMC meeting and US economic releases could affect yields, the dollar and BTC. Futures open interest and funding rates also warrant attention amid liquidation risks.
XWIN’s view: A break below $80,000 alone does not signal a bear market. ETF inflows, whale accumulation and spot buying could support a rebound. But weakening demand and rising exchange inflows would increase downside risk toward $77,000. The $71,000 moving average is a longer-term reference, not a price forecast.
The real question: Who will buy Bitcoin at $80,000?
Written by XWIN Japan
1
432
ලිපිය
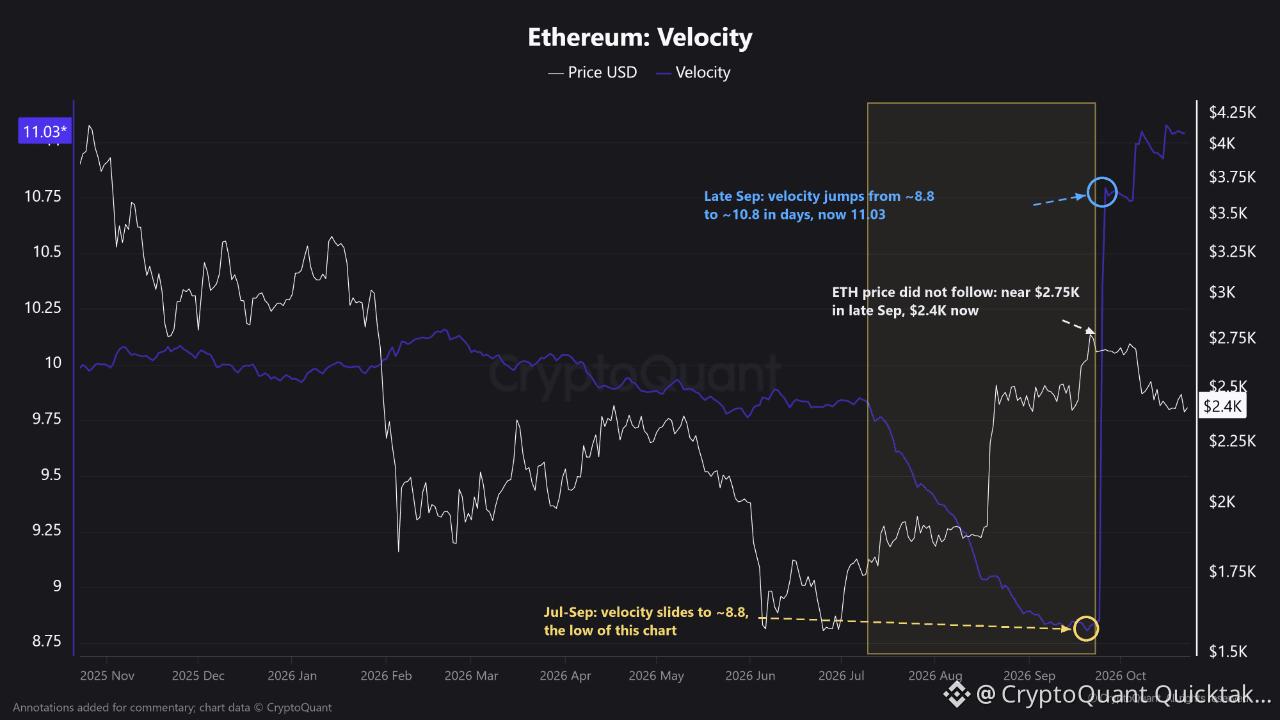
ETH Velocity: a Step Change in the One-year Window, With No Follow-through in PriceEthereum Velocity (CryptoQuant, daily) is calculated from ETH's trailing one-year on-chain transfer volume relative to supply. Because the numerator is a rolling one-year sum, the metric normally moves slowly. Day-to-day changes are small, since each new day is added while the day from a year ago drops out.
That is what makes the recent move stand out.
- Nov 2025 - mid-Jul 2026: velocity held between roughly 9.8 and 10.1.
- Mid-Jul - late Sep: a steady decline to around 8.8, the low of the period. The newer days recorded far less transfer volume than the days rolling out of the window.
- Late Sep: a near-vertical step from around 8.8 to around 10.8, followed by smaller steps to the latest reading of 11.03.
A rise of about 2 points in a few days means the window absorbed transfer volume worth around 23% of its previous one-year total in a very short span. That pattern fits a handful of very large transfers better than a broad pickup in network use. Possible sources include exchange or custodian wallet reshuffles, contract migrations or large holder repositioning. Entity-level flow data is needed to confirm which.
Price context matters. ETH printed its local high near 2.75K around the step and has since slipped to about 2.4K. Elevated turnover with weakening price leans toward supply moving into the market rather than fresh demand.
Invalidation: if exchange inflows stay muted and ETH reclaims the late-September high, the spike is more likely internal movement than distribution.
Conclusion: the velocity jump is real, but its source is still unconfirmed. Until price confirms, treat it as a caution signal, not a demand signal.
Written by Rei Researcher
ETH Velocity: a Step Change in the One-year Window, With No Follow-through in Price
Ethereum Velocity (CryptoQuant, daily) is calculated from ETH's trailing one-year on-chain transfer volume relative to supply. Because the numerator is a rolling one-year sum, the metric normally moves slowly. Day-to-day changes are small, since each new day is added while the day from a year ago drops out.
That is what makes the recent move stand out.
- Nov 2025 - mid-Jul 2026: velocity held between roughly 9.8 and 10.1.
- Mid-Jul - late Sep: a steady decline to around 8.8, the low of the period. The newer days recorded far less transfer volume than the days rolling out of the window.
- Late Sep: a near-vertical step from around 8.8 to around 10.8, followed by smaller steps to the latest reading of 11.03.
A rise of about 2 points in a few days means the window absorbed transfer volume worth around 23% of its previous one-year total in a very short span. That pattern fits a handful of very large transfers better than a broad pickup in network use. Possible sources include exchange or custodian wallet reshuffles, contract migrations or large holder repositioning. Entity-level flow data is needed to confirm which.
Price context matters. ETH printed its local high near 2.75K around the step and has since slipped to about 2.4K. Elevated turnover with weakening price leans toward supply moving into the market rather than fresh demand.
Invalidation: if exchange inflows stay muted and ETH reclaims the late-September high, the spike is more likely internal movement than distribution.
Conclusion: the velocity jump is real, but its source is still unconfirmed. Until price confirms, treat it as a caution signal, not a demand signal.
Written by Rei Researcher
186
ලිපිය
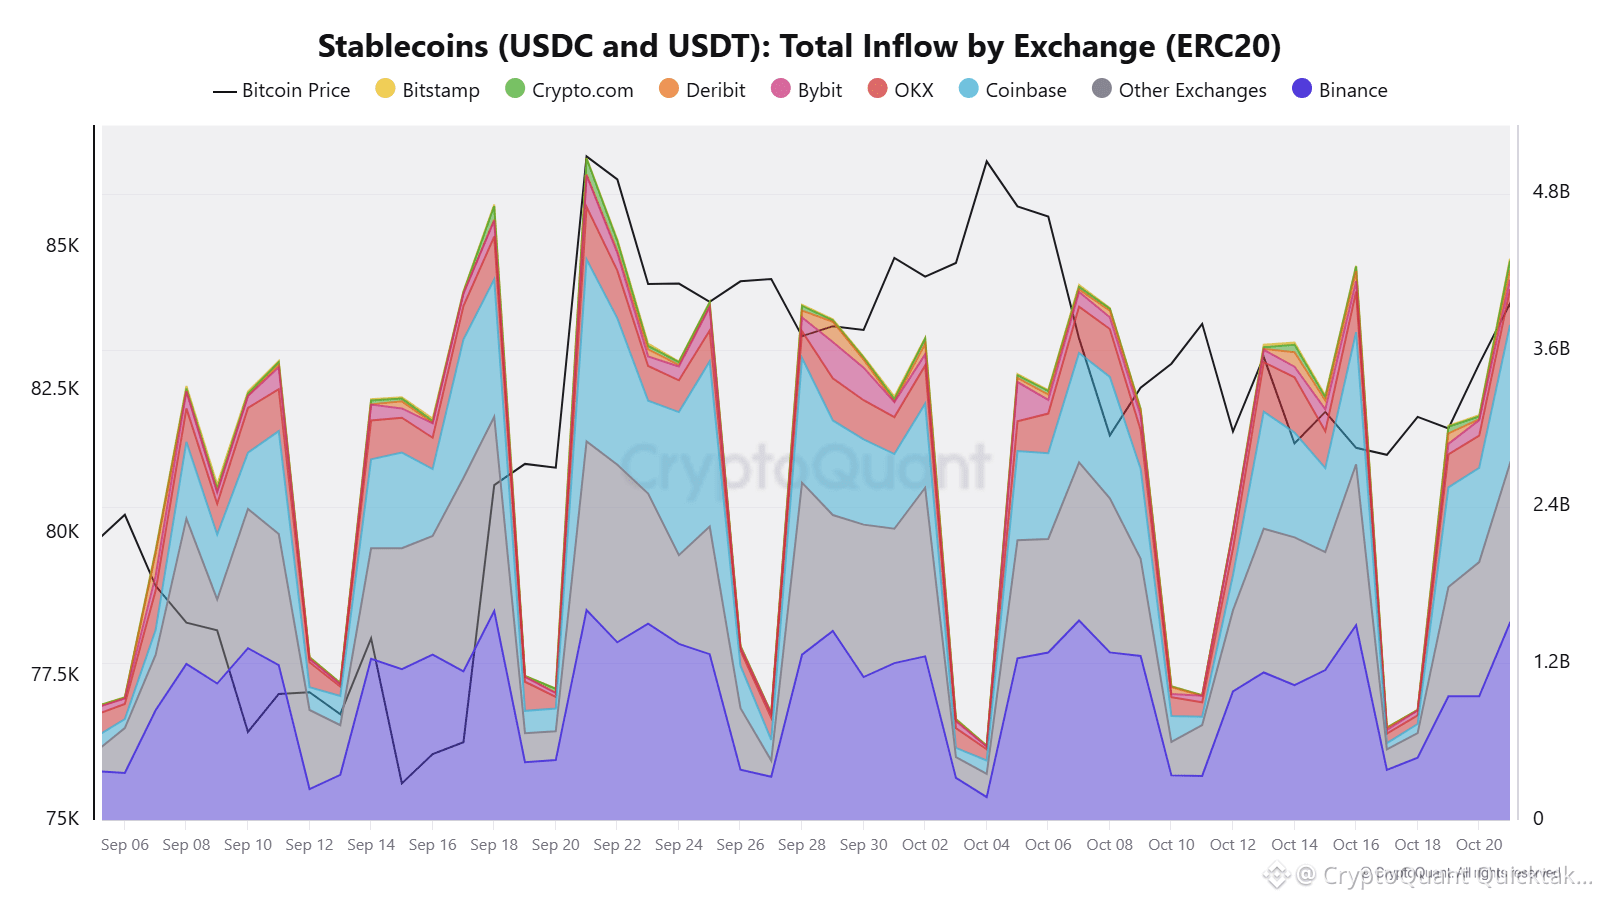
Stablecoin Inflows to Binance Remain Robust, and Fund Inflows to Other Exchanges Are Also Picking...The inflow of stablecoins to exchanges signifies an inflwo of fund.
Typically, periods of upward market momentum are accompanied by a significant increase in stablecoin inflows.
As $BTC climbed from the $62k to $80k range, daily stablecoin inflows to Binance reached $1.6B. During the same period, stablecoin inflows to Coinbase also rose to $1.0B-$1.4B.
The $BTC rise occurred alongside this robust fund inflow.
However, after that, stablecoin inflows to other exchanges dropped significantly. In contrast, Binance maintained an average inflow of $1.2B, standing out as the only exchange to sustain a solid flow of fund.
This week, stablecoin inflows have begun to rise once again. Inflows to Binance have climbed to $1.51B, while Coinbase has also seen its stablecoin inflows reach the $1B mark for the first time in about a month.
While Binance has demonstrated a consistently strong fund inflow, other exchanges tend to follow short-term trends. The confirmed pattern suggests that fund inflows are a response to the rise in $BTC, rather than the primary driver of the price increase itself.
Binance is the only exchange showing a steady, sustained influx of stablecoins. It is currently the driving force behind the trading activity, operating under the surface.
Written by CW8900
Stablecoin Inflows to Binance Remain Robust, and Fund Inflows to Other Exchanges Are Also Picking...
The inflow of stablecoins to exchanges signifies an inflwo of fund.
Typically, periods of upward market momentum are accompanied by a significant increase in stablecoin inflows.
As $BTC climbed from the $62k to $80k range, daily stablecoin inflows to Binance reached $1.6B. During the same period, stablecoin inflows to Coinbase also rose to $1.0B-$1.4B.
The $BTC rise occurred alongside this robust fund inflow.
However, after that, stablecoin inflows to other exchanges dropped significantly. In contrast, Binance maintained an average inflow of $1.2B, standing out as the only exchange to sustain a solid flow of fund.
This week, stablecoin inflows have begun to rise once again. Inflows to Binance have climbed to $1.51B, while Coinbase has also seen its stablecoin inflows reach the $1B mark for the first time in about a month.
While Binance has demonstrated a consistently strong fund inflow, other exchanges tend to follow short-term trends. The confirmed pattern suggests that fund inflows are a response to the rise in $BTC, rather than the primary driver of the price increase itself.
Binance is the only exchange showing a steady, sustained influx of stablecoins. It is currently the driving force behind the trading activity, operating under the surface.
Written by CW8900
1
135
ලිපිය
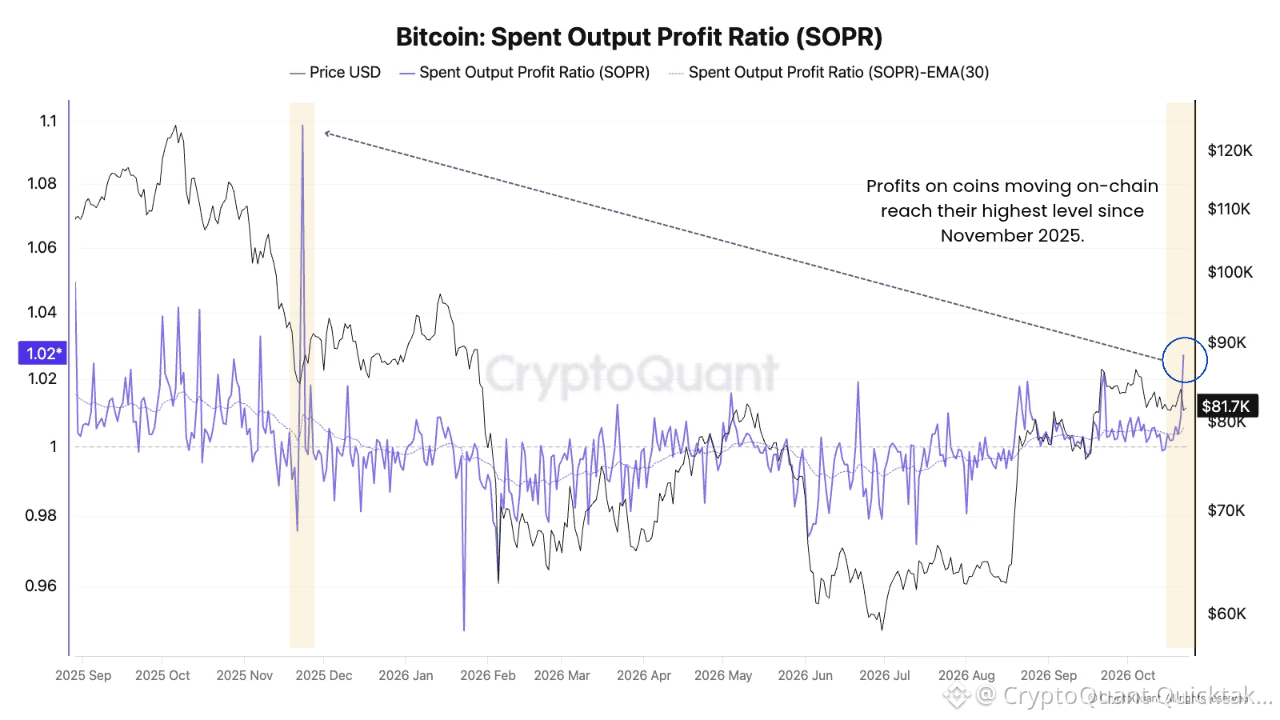
Rising Realized Gains Put Bitcoin’s Recovery in the SpotlightBitcoin’s SOPR has climbed above 1.02, marking what appears to be its highest reading since November 2025, during the initial decline from the all-time high. The earlier spike was substantially larger, so the comparison concerns timing and rarity rather than equal intensity.
SOPR compares the USD value of spent coins with their value when their outputs were created. Above 1, those coins move at an aggregate profit. A reading near 1.02 implies roughly 2% profit relative to their recorded cost basis, not that 2% of holders are selling.
The notable feature is that profitability is expanding while Bitcoin remains well below its peak. This can reflect spending by holders with lower cost bases, including buyers of the earlier drawdown. It does not require the broader market to have recovered its losses. The spike therefore raises a question about potential profit-taking supply during the recovery.
However, SOPR measures profit intensity, not the volume of coins sold. Older profitable outputs can lift the ratio, and transfers do not necessarily represent sales. The chart alone cannot establish broad distribution or identify the responsible cohort.
Unlike the November episode, the latest spike follows months of readings around or below breakeven, making the recovery in spending profitability especially relevant.
The 30-period EMA has also moved modestly above 1, suggesting an improvement beyond a single observation. The next test is whether that profitability can persist without renewed price weakness. If SOPR cools toward 1 while price holds recent support, the pattern would be consistent with profit-taking being absorbed. Repeated spikes alongside stalled price, followed by a sustained move below 1, would instead strengthen the case for a fragile recovery.
The signal is a test of demand, not a standalone top call: the market is moving from loss realization toward renewed profitability, but the durability of that transition depends on how price responds.
Written by MorenoDV_
Rising Realized Gains Put Bitcoin’s Recovery in the Spotlight
Bitcoin’s SOPR has climbed above 1.02, marking what appears to be its highest reading since November 2025, during the initial decline from the all-time high. The earlier spike was substantially larger, so the comparison concerns timing and rarity rather than equal intensity.
SOPR compares the USD value of spent coins with their value when their outputs were created. Above 1, those coins move at an aggregate profit. A reading near 1.02 implies roughly 2% profit relative to their recorded cost basis, not that 2% of holders are selling.
The notable feature is that profitability is expanding while Bitcoin remains well below its peak. This can reflect spending by holders with lower cost bases, including buyers of the earlier drawdown. It does not require the broader market to have recovered its losses. The spike therefore raises a question about potential profit-taking supply during the recovery.
However, SOPR measures profit intensity, not the volume of coins sold. Older profitable outputs can lift the ratio, and transfers do not necessarily represent sales. The chart alone cannot establish broad distribution or identify the responsible cohort.
Unlike the November episode, the latest spike follows months of readings around or below breakeven, making the recovery in spending profitability especially relevant.
The 30-period EMA has also moved modestly above 1, suggesting an improvement beyond a single observation. The next test is whether that profitability can persist without renewed price weakness. If SOPR cools toward 1 while price holds recent support, the pattern would be consistent with profit-taking being absorbed. Repeated spikes alongside stalled price, followed by a sustained move below 1, would instead strengthen the case for a fragile recovery.
The signal is a test of demand, not a standalone top call: the market is moving from loss realization toward renewed profitability, but the durability of that transition depends on how price responds.
Written by MorenoDV_
137
ලිපිය
Bitcoin Exchange Inflows Shrink By 9,061 BTC While BlackRock and Fidelity Post $1.147 Billion in ...Bitcoin deposits from mid-size investors fell across four major exchanges between September 21 and October 23, while Binance whale inflows also declined, even as BlackRock and Fidelity’s spot Bitcoin ETFs recorded positive changes in USD-denominated holdings.
The combined 7-day average of mid-size inflows to
Coinbase Advanced, Coinbase Prime, Binance, and Kraken dropped from 20,591 BTC to 11,530 BTC, a decline of 9,061 BTC (44.0%).
Coinbase Advanced led the decline, falling 3,881 BTC (55.1%) from 7,041 to 3,160 BTC.
Binance declined 2,120 BTC (41.8%) to 2,950 BTC;
Coinbase Prime fell 2,100 BTC (46.4%) to 2,430 BTC; and
Kraken dropped 960 BTC (24.3%) to 2,990 BTC.
Meanwhile, Binance's 30-day sum of whale inflows declined from $5.67 billion to $4.00 billion, a $1.67 billion (29.5%) reduction over the same period.
ETF holdings showed a contrasting pattern.
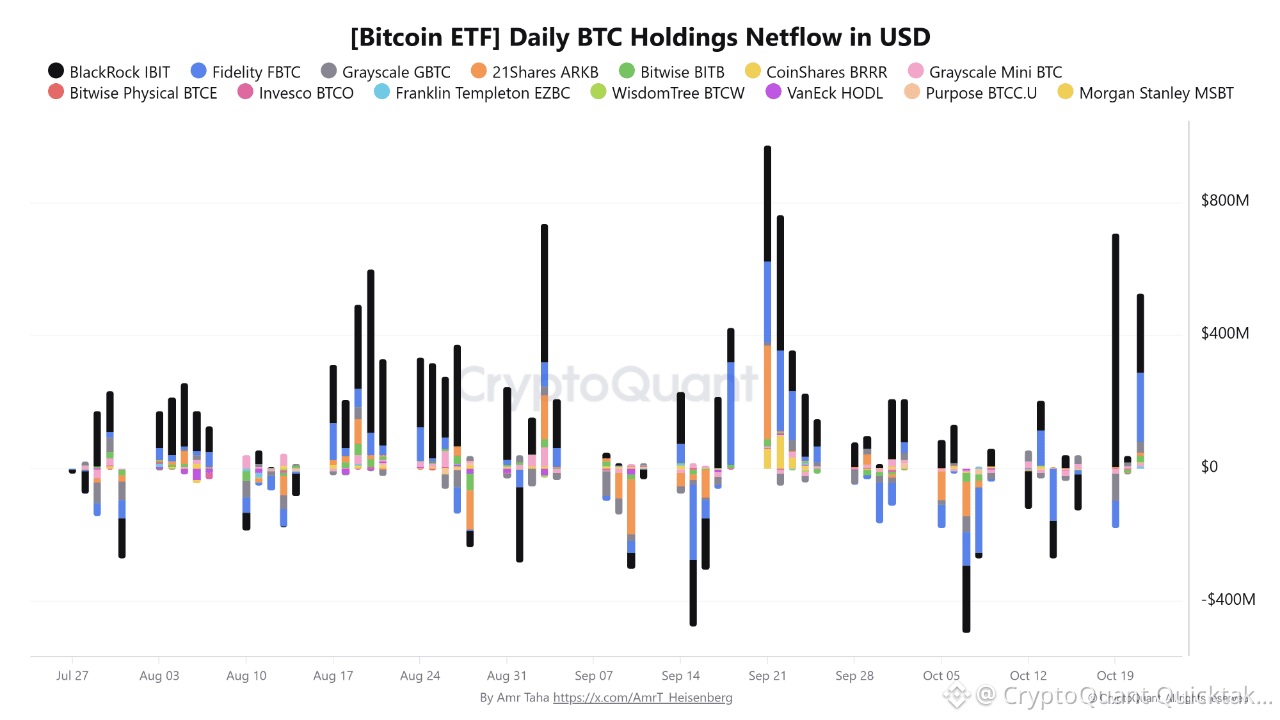
BlackRock's IBIT registered a positive $703 million reading on October 19 and another $238 million on October 21, totaling $941 million across two sessions within three days.
Fidelity's FBTC added a positive $206 million reading on October 21, bringing the two funds' combined positive readings that day to $444 million.
Conclusion:
The simultaneous decline in exchange inflows from mid-size investors and whales, alongside rising Bitcoin ETF holdings, suggests a broader pattern of reduced potential selling pressure and growing ETF exposure.
This combination may indicate a growing trend toward holding Bitcoin for a longer period.
Written by Amr Taha
Bitcoin Exchange Inflows Shrink By 9,061 BTC While BlackRock and Fidelity Post $1.147 Billion in ...
Bitcoin deposits from mid-size investors fell across four major exchanges between September 21 and October 23, while Binance whale inflows also declined, even as BlackRock and Fidelity’s spot Bitcoin ETFs recorded positive changes in USD-denominated holdings.
The combined 7-day average of mid-size inflows to
Coinbase Advanced, Coinbase Prime, Binance, and Kraken dropped from 20,591 BTC to 11,530 BTC, a decline of 9,061 BTC (44.0%).
Coinbase Advanced led the decline, falling 3,881 BTC (55.1%) from 7,041 to 3,160 BTC.
Binance declined 2,120 BTC (41.8%) to 2,950 BTC;
Coinbase Prime fell 2,100 BTC (46.4%) to 2,430 BTC; and
Kraken dropped 960 BTC (24.3%) to 2,990 BTC.
Meanwhile, Binance's 30-day sum of whale inflows declined from $5.67 billion to $4.00 billion, a $1.67 billion (29.5%) reduction over the same period.
ETF holdings showed a contrasting pattern.
BlackRock's IBIT registered a positive $703 million reading on October 19 and another $238 million on October 21, totaling $941 million across two sessions within three days.
Fidelity's FBTC added a positive $206 million reading on October 21, bringing the two funds' combined positive readings that day to $444 million.
Conclusion:
The simultaneous decline in exchange inflows from mid-size investors and whales, alongside rising Bitcoin ETF holdings, suggests a broader pattern of reduced potential selling pressure and growing ETF exposure.
This combination may indicate a growing trend toward holding Bitcoin for a longer period.
Written by Amr Taha
103
ලිපිය
Bitcoin Faces a Tough Macro Backdrop As Brent Holds Above $100With persistent tensions in the Gulf and intensifying Ukrainian attacks on Russian refineries, the price of Brent is holding above $100.
This cost is passing through to economies worldwide: inflation is becoming more deeply embedded in production processes, in the price of services, commodities, and so on. A sustained rise in Brent can therefore signal an economic slowdown, which constrains the liquidity available to markets, particularly the riskiest ones like Bitcoin.
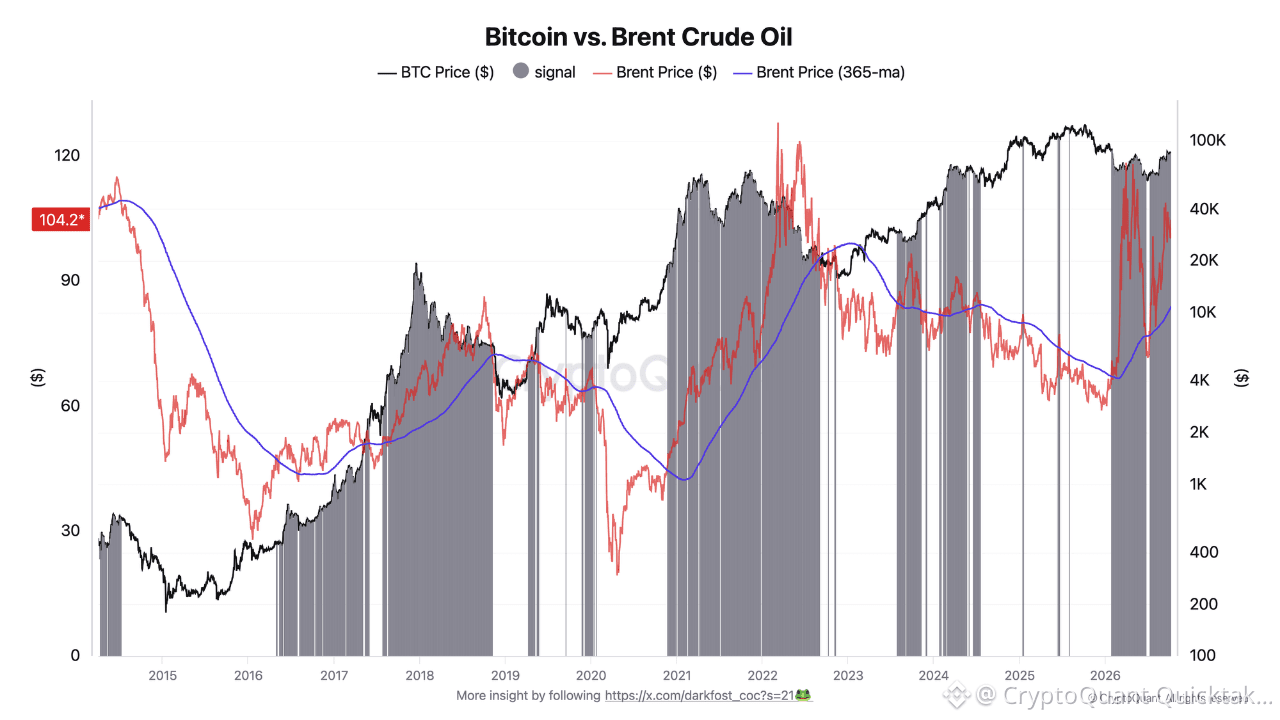
Over the long term, we can see that when Brent settles into a strong upward trend, above its annual average, Bitcoin has often slowed down. Conversely, when Brent drops sharply, it has often coincided with a recovery for Bitcoin.
Note, as I mentioned in the preamble, that this is not a simple cause-and-effect relationship between Bitcoin and Brent. What can prove harmful to risk assets is the economic climate that comes with rising oil prices.
In July, we had a brief respite, and Bitcoin immediately took advantage of it. Brent has since rebounded strongly, however. I'm not saying Bitcoin can't keep up its momentum, since liquidity can rotate from one market to another, but economic conditions aren't very favorable for fresh liquidity to come in.
Written by Darkfost
Bitcoin Faces a Tough Macro Backdrop As Brent Holds Above $100
With persistent tensions in the Gulf and intensifying Ukrainian attacks on Russian refineries, the price of Brent is holding above $100.
This cost is passing through to economies worldwide: inflation is becoming more deeply embedded in production processes, in the price of services, commodities, and so on. A sustained rise in Brent can therefore signal an economic slowdown, which constrains the liquidity available to markets, particularly the riskiest ones like Bitcoin.
Over the long term, we can see that when Brent settles into a strong upward trend, above its annual average, Bitcoin has often slowed down. Conversely, when Brent drops sharply, it has often coincided with a recovery for Bitcoin.
Note, as I mentioned in the preamble, that this is not a simple cause-and-effect relationship between Bitcoin and Brent. What can prove harmful to risk assets is the economic climate that comes with rising oil prices.
In July, we had a brief respite, and Bitcoin immediately took advantage of it. Brent has since rebounded strongly, however. I'm not saying Bitcoin can't keep up its momentum, since liquidity can rotate from one market to another, but economic conditions aren't very favorable for fresh liquidity to come in.
Written by Darkfost
229
ලිපිය
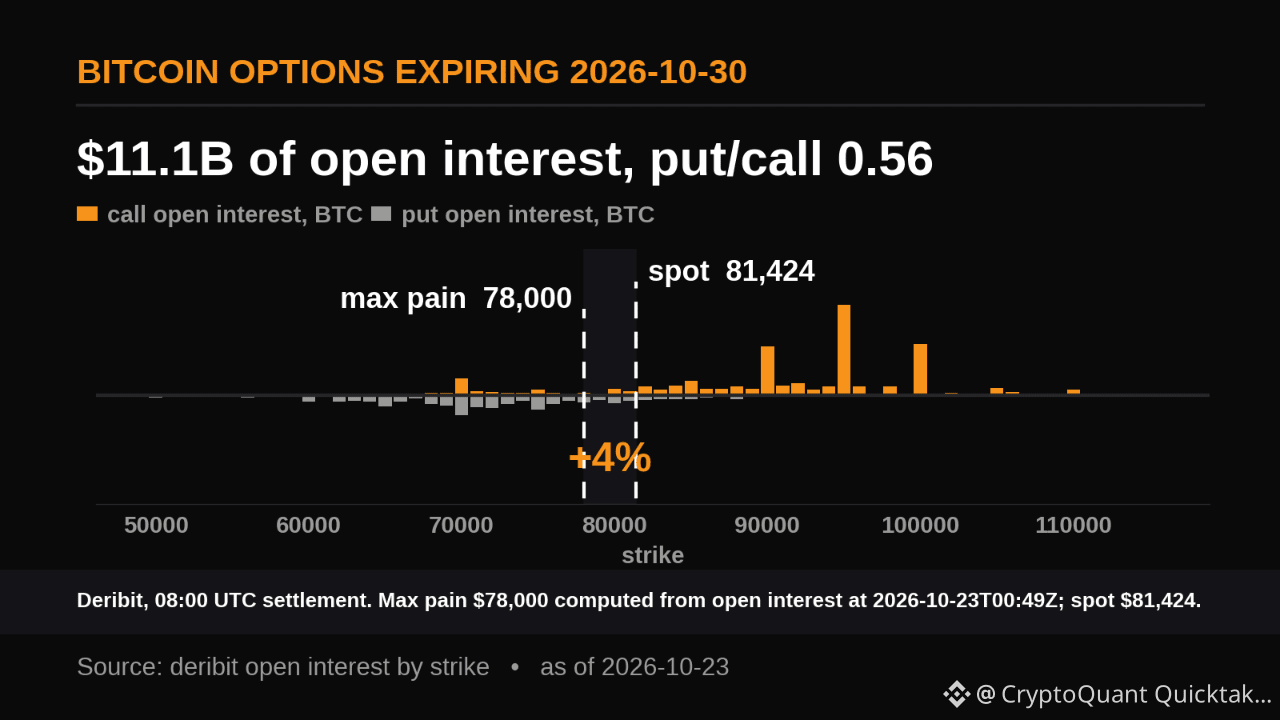
$11.1 Billion in Bitcoin Options Expire October 30, With Max Pain At $78,000$11.1 billion of Bitcoin options on Deribit expire on October 30 at 08:00 UTC, 34.6% of all BTC options open interest on the venue. Max pain, computed from Deribit open interest at 00:49 UTC on October 23, sits at $78,000 with spot at $81,424.
The book leans to calls. The put/call open-interest ratio is 0.56, and the largest strike is $95,000, holding 20,209 BTC ($1.6 billion), mostly calls. For that strike to pay anything, Bitcoin has to rally more than $13,000 in a week.
A caveat before reading too much into the pin. Max pain is the price at which option holders collectively lose the most at expiry. It is not a price target, and nothing forces spot toward it.
Perpetual futures do not share the appetite. CryptoQuant's all-exchange Funding Rates read 0.0049% on October 22, and the daily reading has stayed between 0.0017% and 0.0102% for the past month. Longs are paying a modest premium, not a crowded one.
Volatility tells the same calm story. 30-day realized volatility at 25.03 is lower than on 96% of days since 2021, and options still charge more than that. That is normal: across 1,609 days from April 2022 to September 2026, DVOL priced more volatility than the next 30 days delivered on 73.7% of them. Cheap realized vol is not a signal that options are a bargain.
The October call wall is a bet on a rally that the futures market is not paying to fund.
What changes the read: funding back above 0.01% with spot through $88,000 before October 30 would put the upper calls in play and make this a positioning squeeze. A daily close under $78,000 would hand control to the lighter put side instead.
Written by The Daily Digits
$11.1 Billion in Bitcoin Options Expire October 30, With Max Pain At $78,000
$11.1 billion of Bitcoin options on Deribit expire on October 30 at 08:00 UTC, 34.6% of all BTC options open interest on the venue. Max pain, computed from Deribit open interest at 00:49 UTC on October 23, sits at $78,000 with spot at $81,424.
The book leans to calls. The put/call open-interest ratio is 0.56, and the largest strike is $95,000, holding 20,209 BTC ($1.6 billion), mostly calls. For that strike to pay anything, Bitcoin has to rally more than $13,000 in a week.
A caveat before reading too much into the pin. Max pain is the price at which option holders collectively lose the most at expiry. It is not a price target, and nothing forces spot toward it.
Perpetual futures do not share the appetite. CryptoQuant's all-exchange Funding Rates read 0.0049% on October 22, and the daily reading has stayed between 0.0017% and 0.0102% for the past month. Longs are paying a modest premium, not a crowded one.
Volatility tells the same calm story. 30-day realized volatility at 25.03 is lower than on 96% of days since 2021, and options still charge more than that. That is normal: across 1,609 days from April 2022 to September 2026, DVOL priced more volatility than the next 30 days delivered on 73.7% of them. Cheap realized vol is not a signal that options are a bargain.
The October call wall is a bet on a rally that the futures market is not paying to fund.
What changes the read: funding back above 0.01% with spot through $88,000 before October 30 would put the upper calls in play and make this a positioning squeeze. A daily close under $78,000 would hand control to the lighter put side instead.
Written by The Daily Digits
206
තවත් අන්තර්ගතයන් ගවේෂණය කිරීමට ඇතුල් වන්න
Binance චතුරශ්රය හි ගෝලීය ක්රිප්ටෝ පරිශීලකයින් හා එක්වන්න
⚡️ ක්රිප්ටෝ පිළිබඳ නවතම සහ ප්රයෝජනවත් තොරතුරු ලබා ගන්න.
💬 ලොව විශාලතම ක්රිප්ටෝ හුවමාරුව මගින් විශ්වාස කෙරේ.
👍 සත්යායනය කරන ලද නිර්මාණකරුවන්ගෙන් සැබෑ විදසුන් සොයා ගන්න.
විද්යුත් තැපෑල / දුරකථන අංකය
නැගී එන මාතෘකා
BinancePick
2.6M නැරඹීම්
138,898 සාකච්ඡා කරමින්
Join #EarningsSeason: Predict Earnings on Binance Pick, Share Your Take on Binance Square!
Binance Square Official
·400 කැමත්ත දැක්වීම්
·337.4k නැරඹීම්
EarningsSeason
5M නැරඹීම්
24,034 සාකච්ඡා කරමින්
ElectrumWalletBugLetRogueServersStealFunds
3,821 නැරඹීම්
171 සාකච්ඡා කරමින්