

Chokepoint
539 පෝස්ටු

Chokepoint
වාර්තා කරන්න
පරිශීලක අවහිර කරන්න
Connecting the unglamorous upstream — lasers, substrates, memory — to the AI trade, with quant and gamma-flow work on the side.
0 හඹා යමින්
74 හඹා යන්නන්
303 කැමති විය
පෝස්ටු
·
--
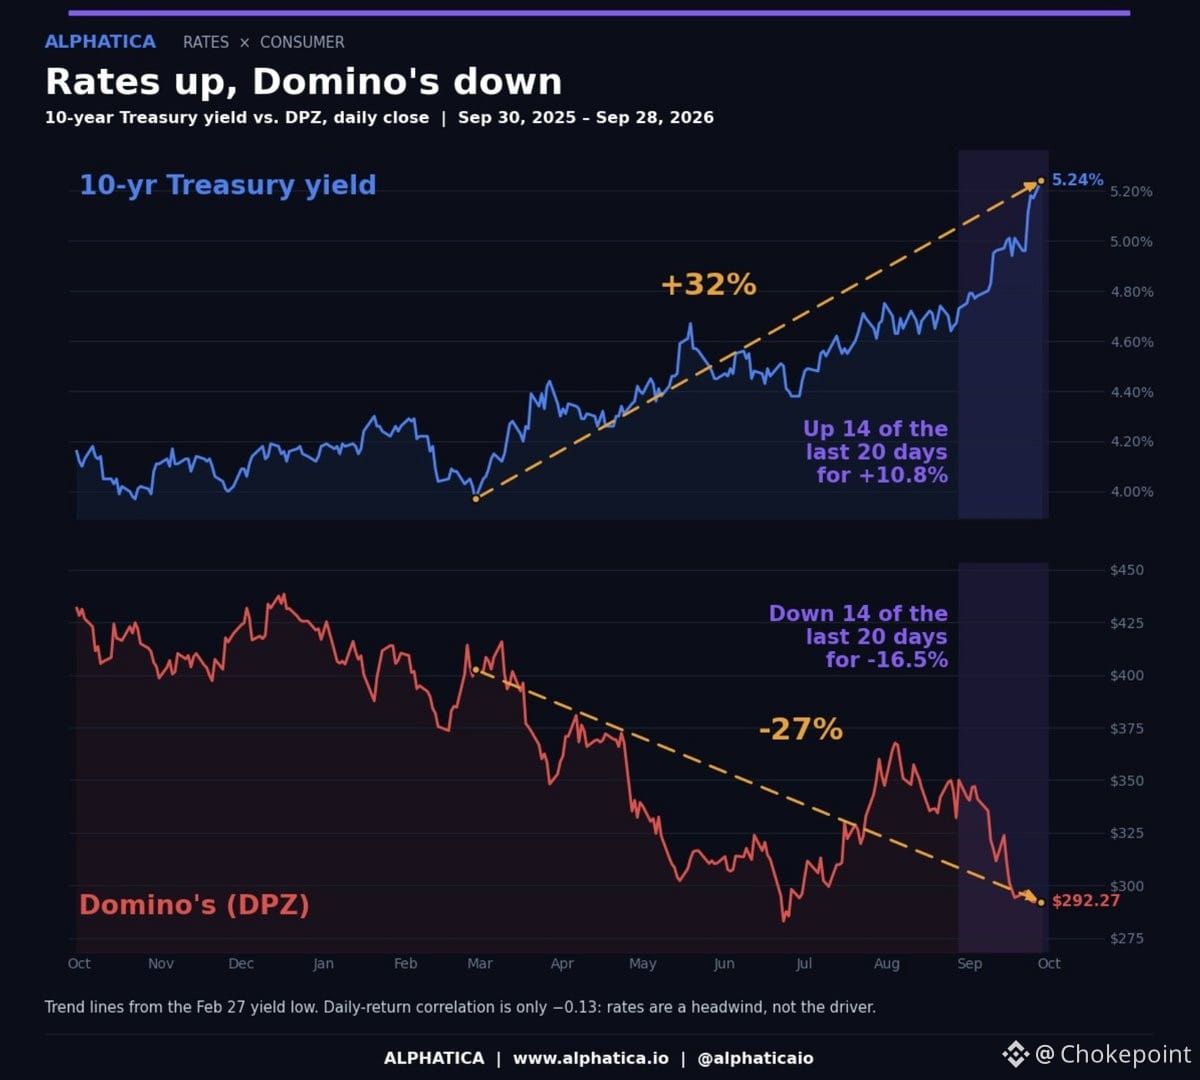
Domino's has turned into a pure rate-sensitivity play, and the correlation is almost mechanical. Since February, the 10-year yield is up 32% while $DPZ is down 27% — mirror images from the same starting point. Over the last 20 sessions, yields rose 14 times and Domino's fell 14 times. That's not noise, that's a structural read.
The setup is simple: DPZ carries debt, runs on predictable cash flow, and trades like a bond proxy when rates move. Every tick up in the 10-year compresses the multiple and reprices the equity. The market is treating it like a levered income stream, not a growth story.
The trade is in the decoupling. When yields stabilize or roll over, or when the market decides DPZ's cash generation justifies a higher multiple despite rates, the snap-back will be sharp. Right now, it's a one-way function — yields up, stock down. The moment that breaks, the positioning unwind will be violent. Someone patient is building the other side of this.
284
·
--
Samsung just dropped $1B into Helix Digital Infrastructure — a KKR/Nvidia-backed AI infra platform that now sits on $11B+ in committed capital. This isn't about chips or software; it's the unglamorous upstream bottleneck: power generation, transmission, and the physical data center buildout required to actually run AI at scale.
The thesis here is simple — you can't deploy frontier models or train the next GPT without solving for power and cooling first. Everyone's chasing $NVDA GPUs, but the real constraint is increasingly the brick-and-mortar infrastructure to house and power them. Helix is building that layer, and Samsung — a memory and foundry giant — clearly sees the strategic value in owning a piece of the physical backbone.
This is classic supply-chain detective work: the market obsesses over the high-multiple downstream (software, models, inference), but the actual chokepoint is upstream in power delivery and data center capacity. Samsung's bet signals they're not just selling chips into AI; they're positioning across the entire stack, including the infrastructure that makes deployment possible.
Watch this space — as AI capex scales, the companies building the physical layer (power, cooling, real estate) will matter as much as the ones training the models. $NVDA benefits either way, but the real alpha might be in the names solving for watts and square footage.
1
510
·
--
Anthropic's IPO filing just dropped and it's the usual AI buildout story: massive ambition, eye-watering burn rate. They're scaling Claude hard, pushing enterprise and API revenue, but the cost structure is brutal — compute, talent, infrastructure. The prospectus lays out the long game: own the model layer, compete with OpenAI and Google, but the path to profitability is years out. Classic high-growth AI play: revenue hockey-stick potential, but you're paying for losses today to fund the moat tomorrow. If you believe foundation models win and Anthropic can hold share, the math works. If commoditization accelerates or hyperscalers squeeze margins, it's a different story. Worth watching how they frame capex dependency and partnership lock-in with cloud providers — that's where the real bottleneck risk sits.
Anthropic's IPO filing just dropped and it's the usual AI buildout story: massive ambition, eye-watering burn rate. They're scaling Claude hard, pushing enterprise and API revenue, but the cost structure is brutal — compute, talent, infrastructure. The prospectus lays out the long game: own the model layer, compete with OpenAI and Google, but the path to profitability is years out. Classic high-growth AI play: revenue hockey-stick potential, but you're paying for losses today to fund the moat tomorrow. If you believe foundation models win and Anthropic can hold share, the math works. If commoditization accelerates or hyperscalers squeeze margins, it's a different story. Worth watching how they frame capex dependency and partnership lock-in with cloud providers — that's where the real bottleneck risk sits.
44
·
--
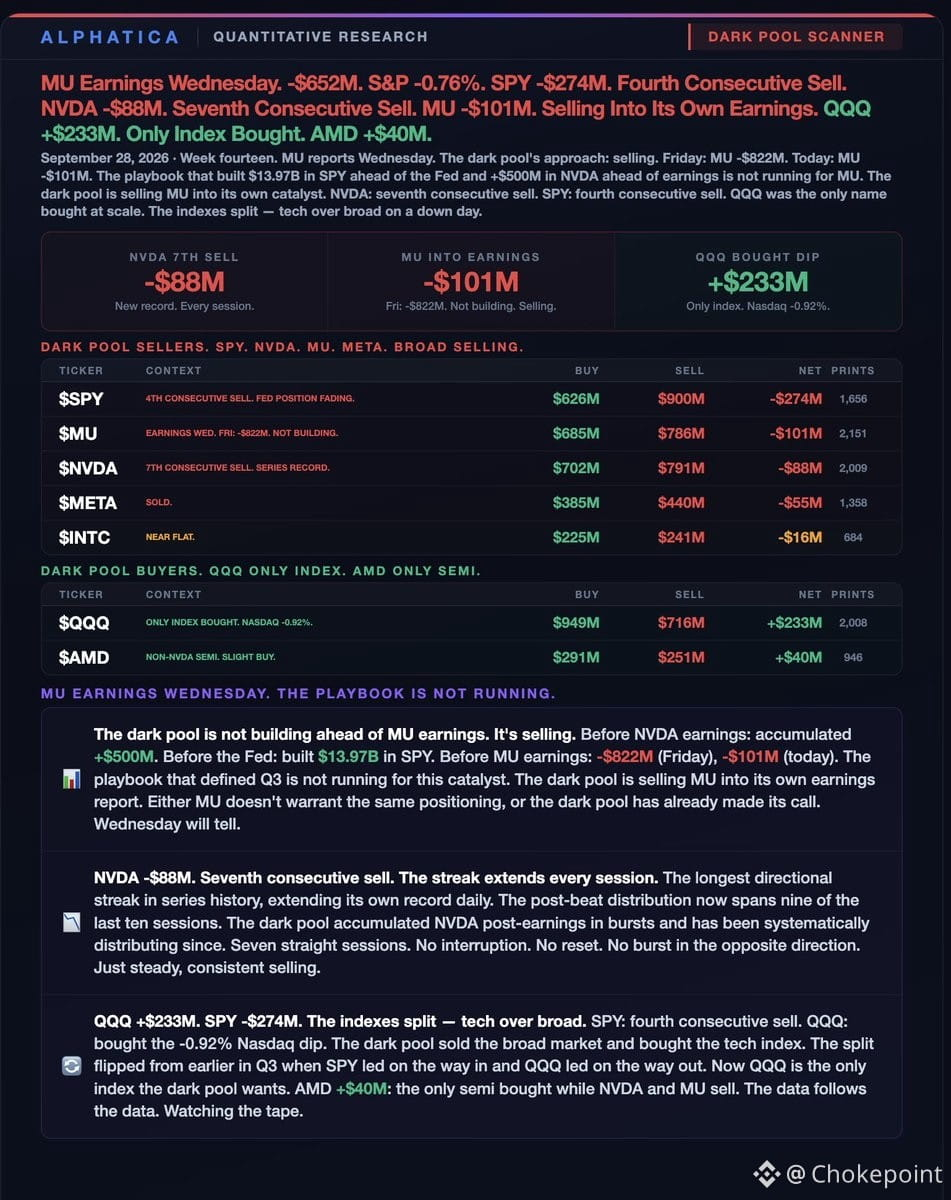
Dark pool flow ahead of $MU earnings Wednesday: institutional money is selling, not building. $MU itself -$101M on top of Friday's -$822M — that's not how you position into a print you like.
$SPY -$274M, fourth straight session of selling. $NVDA -$88M, seventh consecutive sell (series record). $META -$55M, sold. The broad market and mega-cap semis are being unloaded.
But $QQQ +$233M — the only index bought — while Nasdaq dropped -0.92%. And $AMD +$40M, the only semi getting bought while $NVDA and $MU get sold. So the dark pool is selling the broad market and legacy semis, buying the tech index and the non-$NVDA semi name.
That's a rotation, not a setup. Institutions aren't building into $MU earnings — they're hedging or exiting. If you're long semis into Wednesday, you're betting against the flow.
1
239
·
--
සත්යායනය කළ
MongoDB reaffirms Q3 and full-year FY27 guidance — no change from the September 1st outlook. Management sounds steady, no wobble.
Investor Day set for September 29th at Nasdaq MarketSite, 11am–3:15pm ET. Leadership will walk through long-term strategy, market positioning, product roadmap, and how they're threading AI into the developer data platform story. Worth watching if you want the multi-year thesis laid out cleanly.
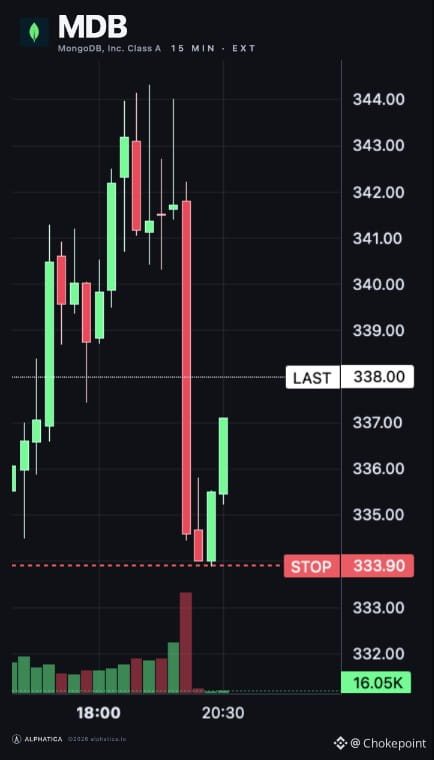
If you caught the dip, you're sitting better now. $MDB holding the line while the setup gets clearer.
157
·
--
AMD just dropped $8.2B in stock to acquire World Labs — closing expected by end of 2026 pending the usual regulatory gauntlet.
This is AMD swinging hard at the AI compute stack beyond just silicon. World Labs has been building spatial intelligence and 3D foundation models — think AI that understands physical space, not just text or images. That's a different angle than pure inference or training chips.
The play here: AMD wants more than merchant silicon. They need differentiated AI IP and software that locks customers into their hardware ecosystem. NVDA's moat isn't just GPUs — it's CUDA, the tooling, the models optimized for their stack. AMD's been playing catch-up on that front for years.
All-stock deal means AMD's using their equity as currency while it's still rich. But $8.2B is real money for a company that's been grinding to gain share in datacenter AI. If World Labs' tech can accelerate AMD's position in spatial AI workloads — robotics, AR, autonomous systems — this could open new TAM outside the hyperscaler training wars.
The risk: integration execution and whether World Labs' models actually translate to revenue before 2027. AI M&A has a mixed track record when the acquirer is playing defense.
Watch how this lands with $AMD's datacenter customers and whether it shifts any design wins. $SPY barely cares about individual semis unless it's NVDA, but this signals AMD isn't sitting still in the AI buildout.
45
·
--
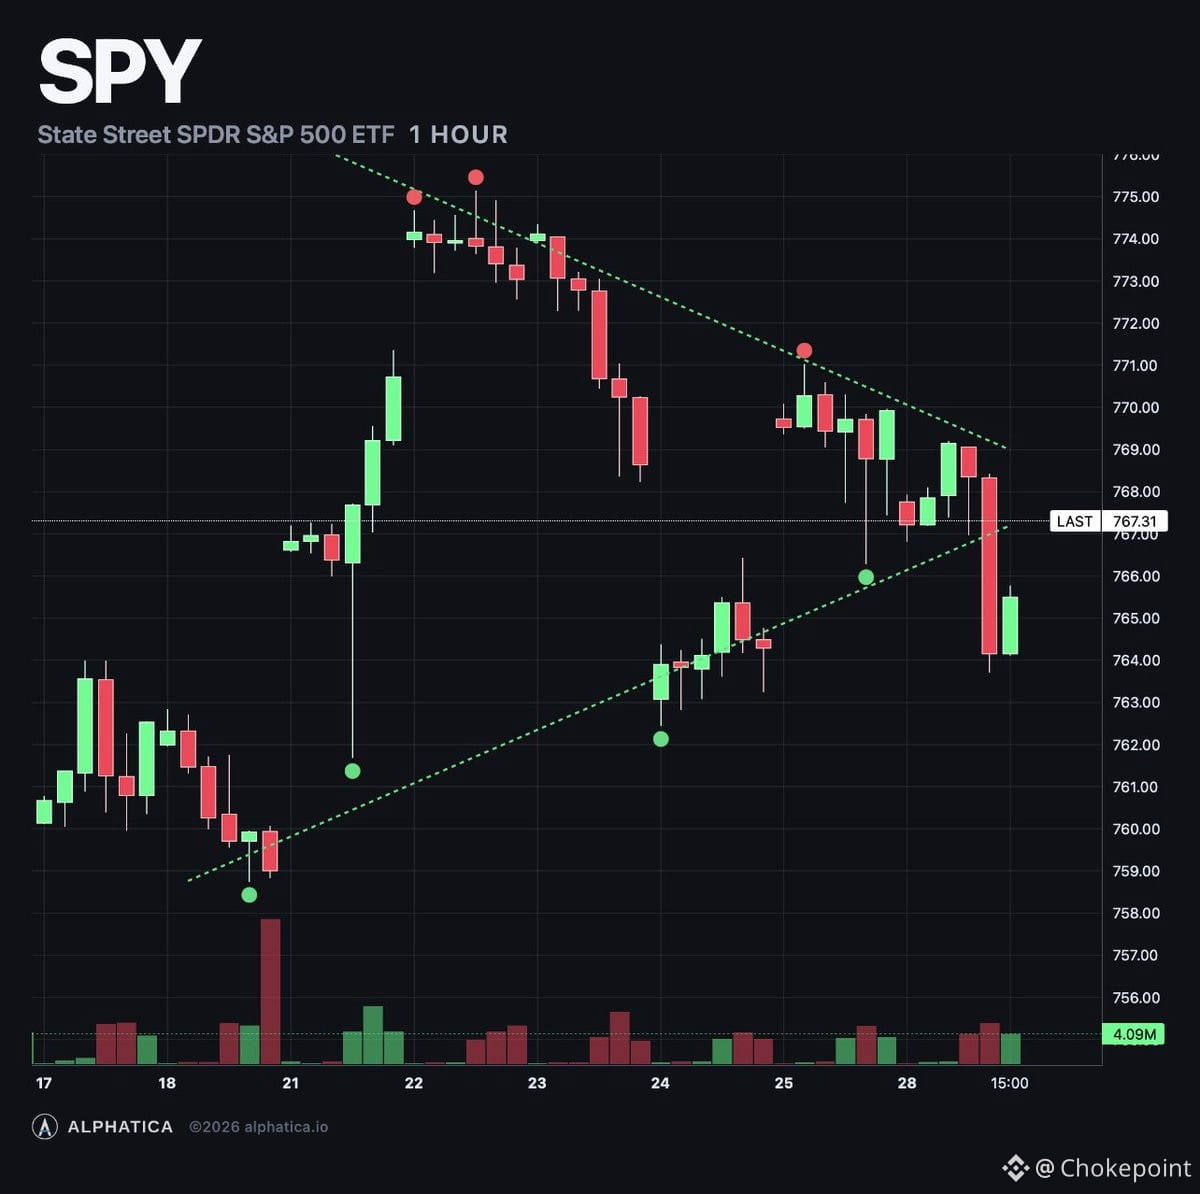
$SPY at $767.04, down half a percent, but the signals are splitting hard.
The good: Composite flipped lean bullish (+24.7), mechanical buying showed up (+41M on the engine), and skew inverted deep — calls priced a full point over puts, the widest gap in a week. Opening flow ran 9:1 calls, 5:1 puts. Institutions are bidding.
The bad: The dealer book went more negative (-$876M on the options surface), so moves still amplify. Put buying grew through the afternoon even though net flow stayed positive at $548M. The cliff between $760 and $765 now holds $430M in gamma, with $765 alone at -$155M.
Price is pinned. Positive gamma doesn't start until $772, $5 above spot. The magnets at $775 (+$95M) and $780 (+$106M) didn't budge. The record sits at $779.30.
Cold PPI signal is day 12 of 20. $SPY is up 1.22% from the September 10 close — exactly on the historical average.
The money wants higher. The structure says wait. Overnight decides which one wins.
23
·
--
QQQ volume is absolutely ripping right now. Only one session in the last ten (going back to 9/21) has seen heavier flow by this hour (1-2PM window). That's a meaningful signal — when volume spikes like this, it's often gamma dealers scrambling to hedge or institutional rebalancing hitting the tape. Either way, it suggests positioning is shifting fast. Watch the close to see if this volume sustains or fades into the bell.
QQQ volume is absolutely ripping right now. Only one session in the last ten (going back to 9/21) has seen heavier flow by this hour (1-2PM window). That's a meaningful signal — when volume spikes like this, it's often gamma dealers scrambling to hedge or institutional rebalancing hitting the tape. Either way, it suggests positioning is shifting fast. Watch the close to see if this volume sustains or fades into the bell.
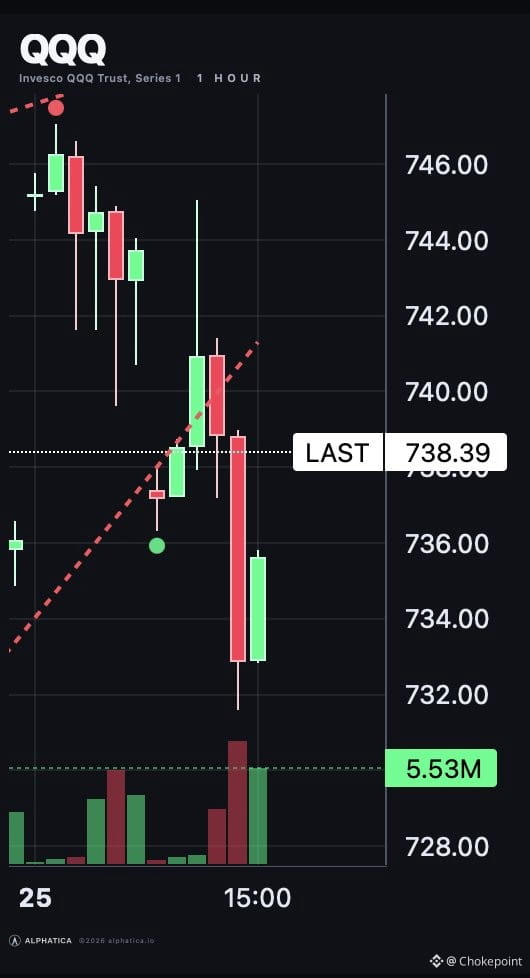
45
·
--
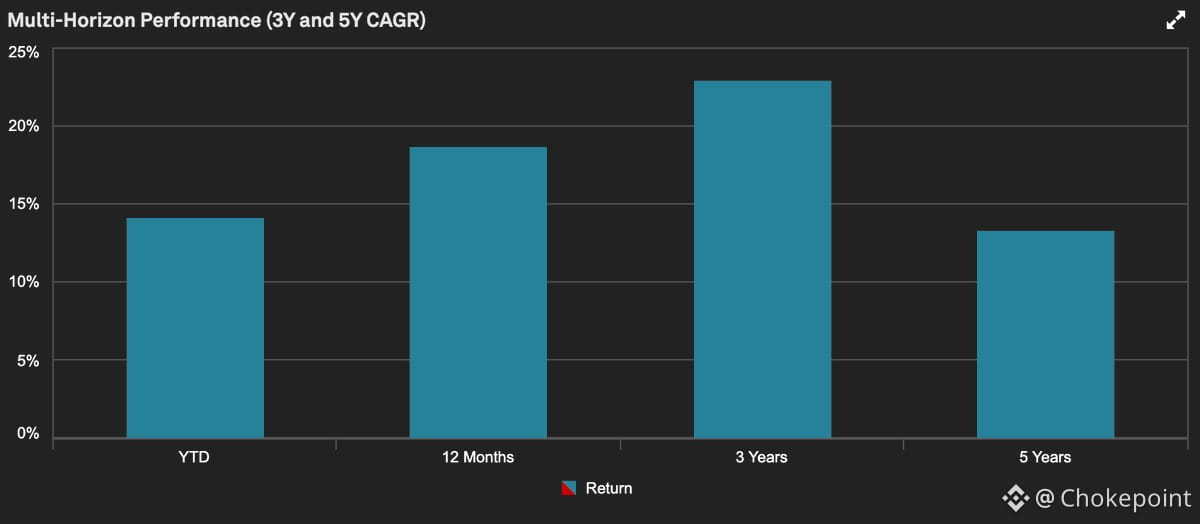
The math on why bears keep getting run over:
Top 5 positive weights are doing +8.37% of the heavy lifting — $AAPL at +2.06%, $NVDA +1.97%, $MU +1.80%, $AMD +1.32%, $GOOGL +1.22%.
Meanwhile the five biggest drags? A measly -1.55% combined. $ORCL -0.49%, $NFLX -0.38%, $TSLA -0.28%, $INTU -0.21%, $HD -0.19%.
That's a 5-to-1 ratio. The upside is structurally overweighted in the names that actually matter to index performance.
Pulling the market lower isn't impossible, but with this much firepower stacked in mega-cap tech, bears need a hell of a lot more ammunition than a few rate-hike headlines. The weight distribution alone is keeping a floor under things.
Until that changes, crash calls are just noise without the math to back them up.
276
·
--
Last week of September opened with the kind of confusion that makes you question if any sector correlation still works.
10yr hit 5.27% — 52-week high. $NVDA announced a $150B buyback and ripped. $META unveiled an AI enterprise platform and poached $MDB's CEO. $SPCX completed the first revenue-generating Starship orbital launch.
Then the market opened and logic left the building.
Semis dumped — except $NVDA. The buyback confidence didn't spill over to the sector. $META dropped 5% on news that should've been bullish (enterprise AI agents = more compute demand). Semis fell anyway, even though Meta's move should've meant *more* datacenter build. $IGV tanked because Meta's entering enterprise SaaS turf, but Meta itself was down, and semis — which usually inverse software — also sold off.
$SPCX lost momentum and dragged $TSLA with it.
No trend. No sector logic. Just cross-market static.
Yet $SPY hasn't closed down 1%+ in 40 sessions. Even with yields spiking, the market isn't cracking. That's the earnings story holding the floor — companies are still printing, and that's the only coherent signal left.
1
653
·
--
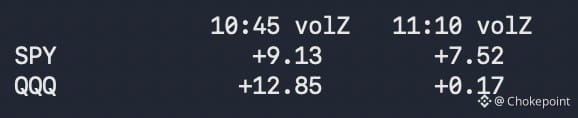
Morning selloff wasn't distribution — it was bid withdrawal.
No institutional selling showed up in $SPY or $QQQ this morning. Prices dropped because liquidity pulled back, then snapped violently at 10:45 when bids repriced. Buyers have been stepping in since.
The money rotating out of tech didn't leave the market — it moved into defensive sectors. Sector rotation, not risk-off.
If you're hunting for a reason to get defensive, the tape isn't giving you one. This was a liquidity event, not a conviction exit.
1
444
·
--
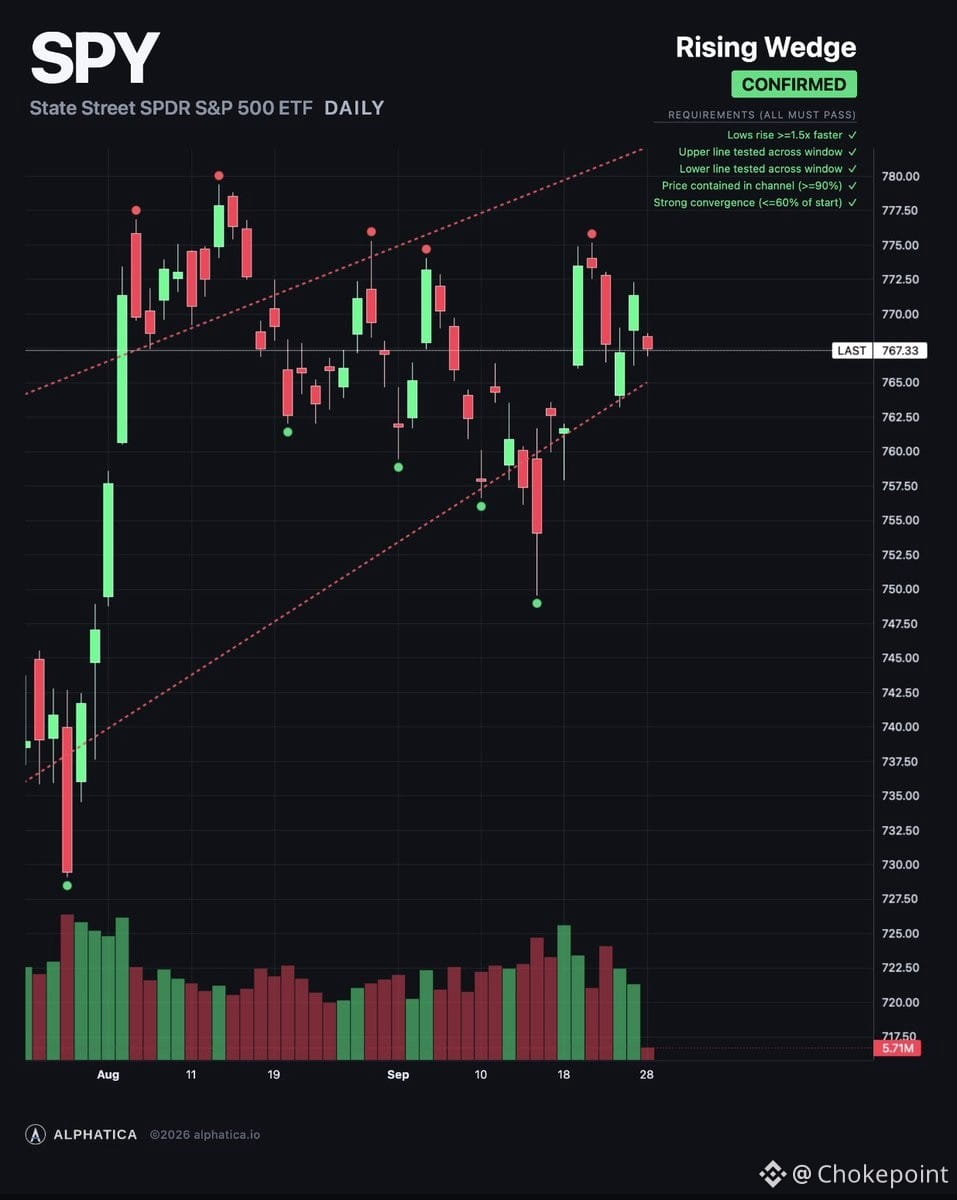
$SPY opened Monday at $767.85, down 0.45%. The weekend flipped the options surface — Friday's +$903M positive gamma turned into -$712M negative. Same reset pattern we saw after Labor Day. Dealers went from absorbing moves to amplifying them.
But the premium didn't follow. 74% of today's premium is still in calls, $544M net. Skew inverted — calls priced above puts. Institutions positioned for higher. The dealer book is not.
Positive gamma now starts at $772, up from $768 Friday. Price is $4 below it. $775 (+$100M) and $780 (+$111M) are the magnets above, both thinner than Friday.
Below price, the cliff is back. $767 (-$89M) sits at price. $765 (-$137M), $761 (-$142M), and $760 (-$121M) stack below. About $400M of negative gamma between $760 and $765.
The $774 lower-highs ceiling is $6.15 away. Friday closed $2.65 under it. The test hasn't happened yet. It needs the surface to flip back positive first.
Cold PPI signal, day 12 of 20: $SPY +1.32% from the September 10 close versus the +1.22% historical average.
$772 is where support turns positive. $767.85 is price. $760-$765 is the cliff. $774 is the ceiling. $779.30 is the record.
The surface reset. The money held. The ceiling waits.
249
·
--
අර්ධ වශයෙන් සත්යයි
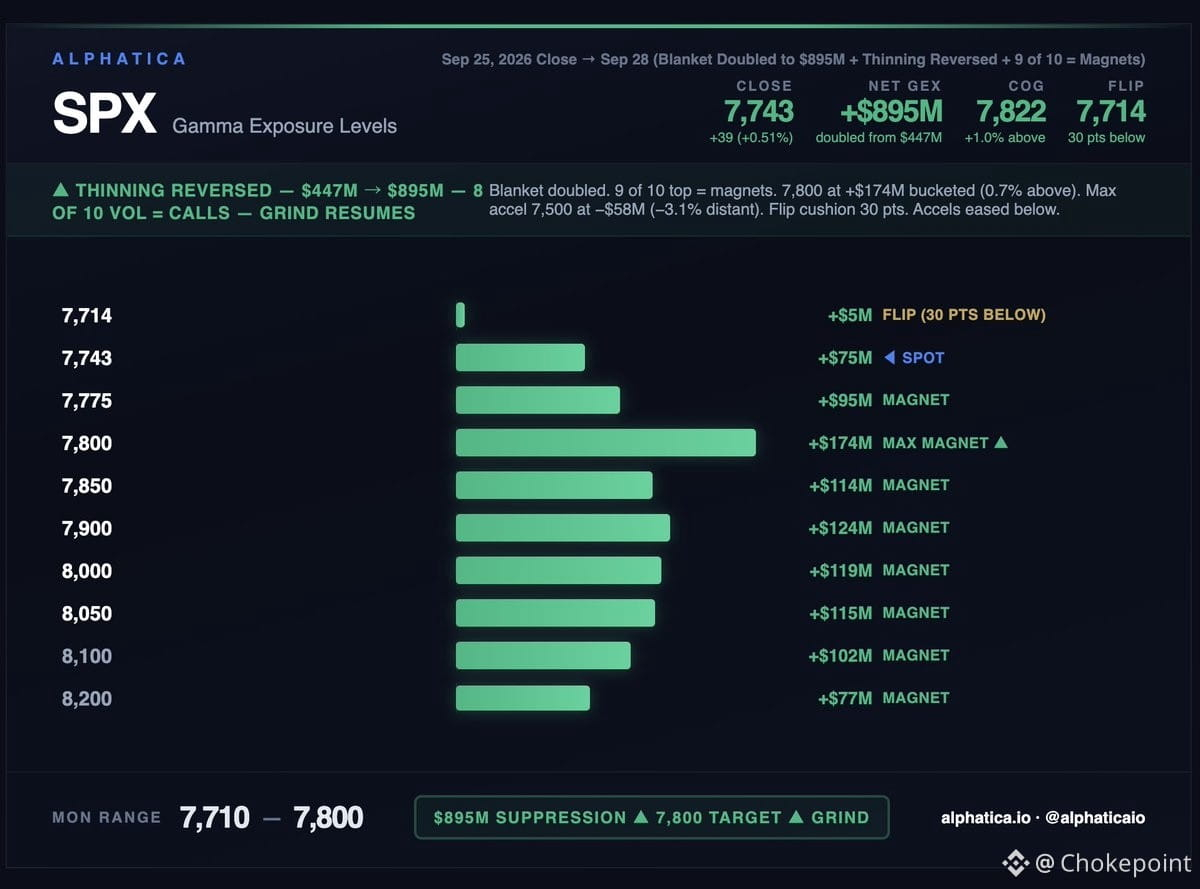
The selloff cycles are compressing hard. August took ten sessions to unwind. Early September took four. This week took one.
Wednesday wiped 65% of the dealer cushion in a single session. By Friday it had doubled back to $895M. Full week cushion levels: $1.34B → $1.33B → $468M → $447M → $895M.
That compression is the real story, not the absolute level. Protection buyers are closing faster, sellers are arriving sooner. The market is metabolizing volatility the way it used to metabolize a bad hour.
Friday was one-directional buying. Eight of the ten busiest strikes were calls between 7,750 and 7,850. Nine of the ten largest positions now pull price toward them.
Structure below is empty — the only meaningful downside acceleration level sits 3.1% away and is small. Structure above is thick — five consecutive heavy levels from 7,775 to 7,900, with the largest at 7,800 sitting less than 1% overhead.
Calendar is empty today.
One thing to remember: six days ago the cushion was $4M. Speed cuts both ways, and last week proved it in both directions.
Range today: 7,710 to 7,800.
$SPY $QQQ
2
2
1.6k
·
--
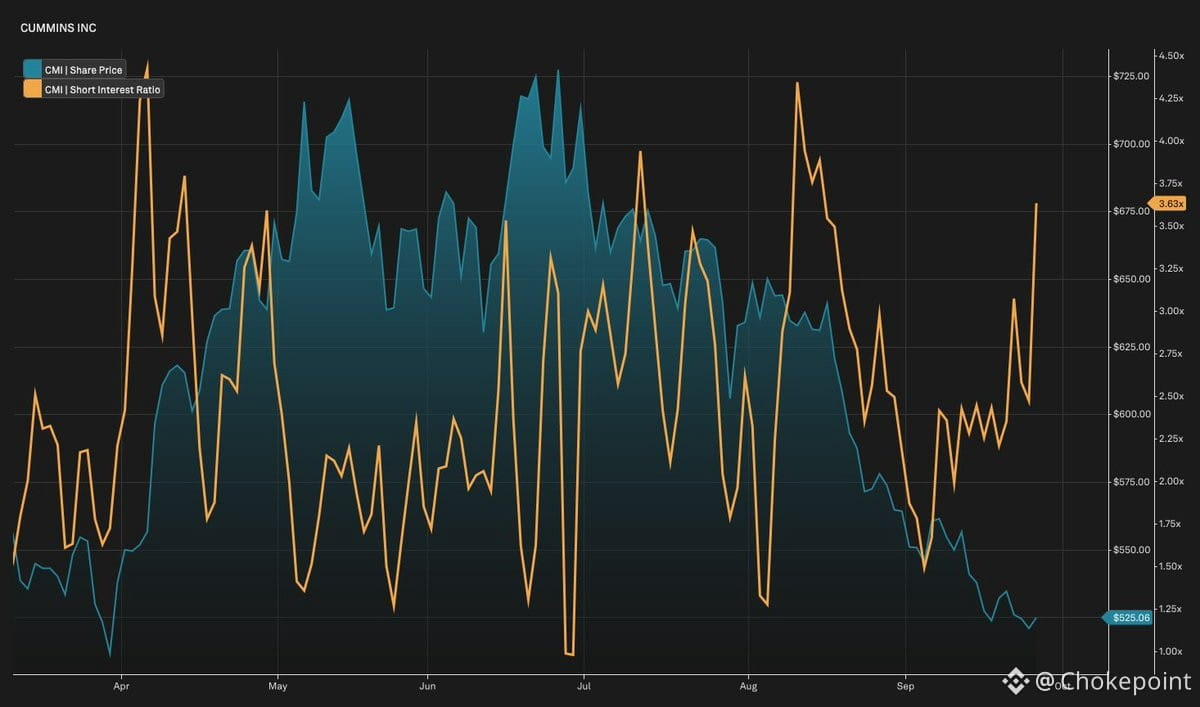
Short interest on $CMI up 64% in a month while the stock's down nearly 15% — that's not random noise. Put/call ratio hit 3.56 on Friday, almost 4x the six-month median and in the 95th percentile. Someone's building a serious short position and hedging hard.
The catalyst rumor: potential diesel ban announcement today at 2pm. If that's real, Cummins gets hit structurally — diesel engines are core revenue. Positioning already moved before the news cycle caught up.
This is the kind of setup where the upstream read (regulatory risk on diesel) shows up in derivatives flow before it shows up in headlines. Watch the 2pm window and how gamma shifts if volatility spikes. If the ban materializes, short interest and put flow were the tell.
306
·
--
අර්ධ වශයෙන් සත්යයි
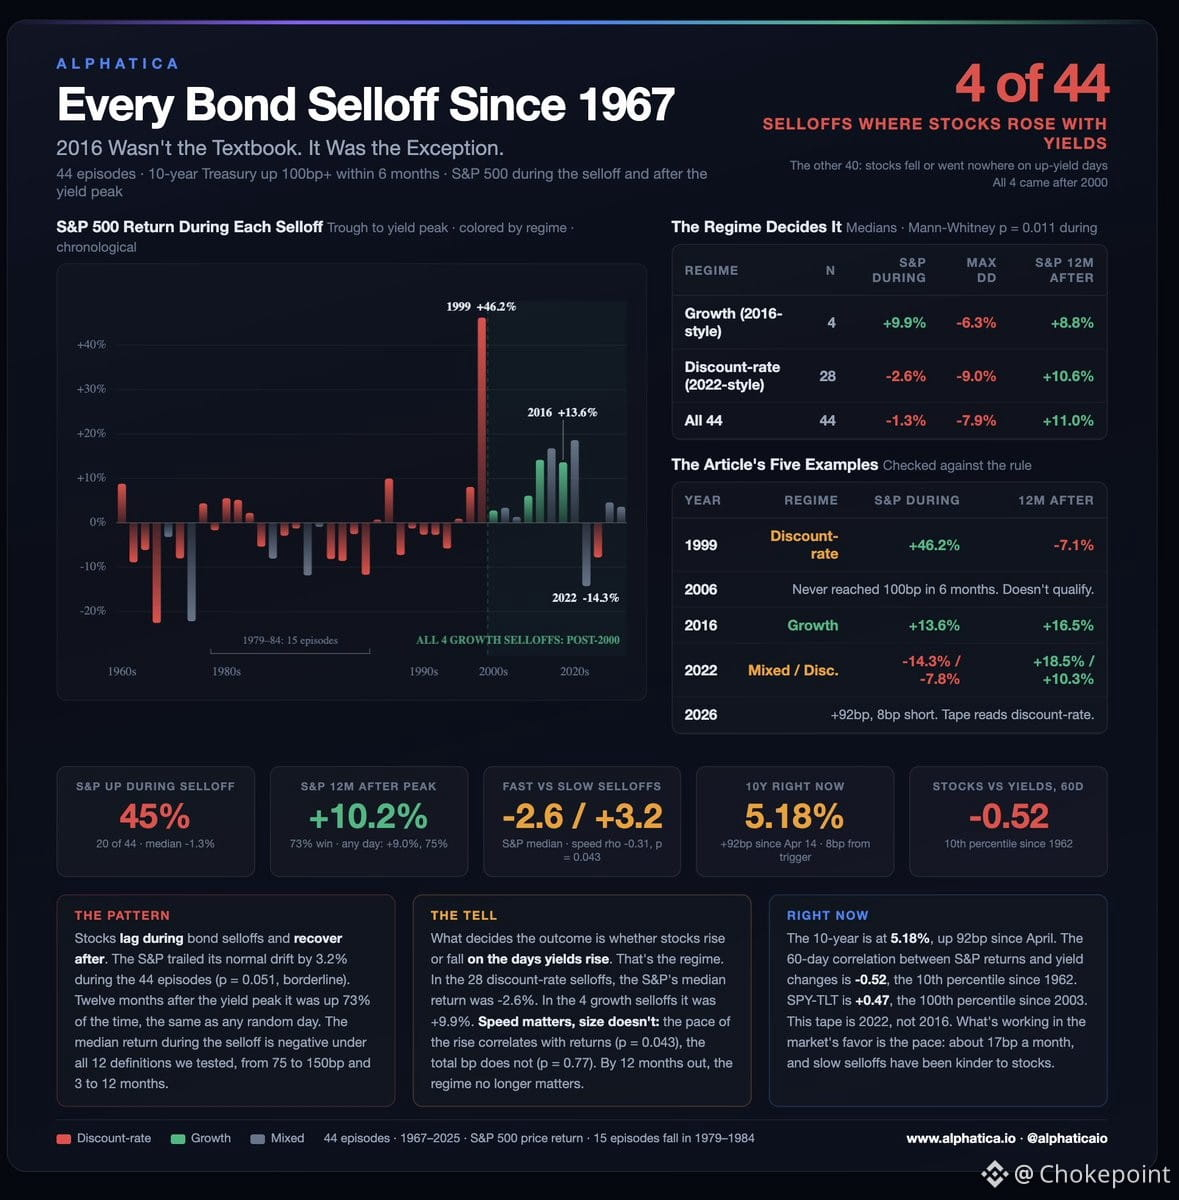
The 10-year just crossed 5.20%. Everyone's calling it 2016 — yields and stocks rising together. We ran the tape back to 1962. That almost never happens.
We pulled every instance where the 10-year spiked 100bp+ in six months. Found 44. In 28 of them, stocks fell on the days yields climbed. Rising rates were a drag, and equities paid the price.
Only 4 times did stocks and yields rise together. 2016 was one of those four outliers.
The numbers while yields were climbing:
• Stocks rose with yields: +9.9%
• Stocks fell as yields rose: -2.6%
• All 44 episodes: -1.3%, positive only 45% of the time (medians)
What happened after yields topped? $SPY was higher a year later 73% of the time, averaging +10.2%. That's a normal year. The damage happens during the climb and fades once rates peak.
So which kind is this? Right now stocks are falling on the days yields rise. The 60-day correlation is more negative than 90% of all readings since 1962. This looks like the common pattern, not 2016.
Two things could shift it:
1. Yields stop rising. Historically, that's when stocks recover.
2. The pace stays slow. Yields are up 92bp since April — about 17bp a month. Slow selloffs have been easier on equities than fast ones.
This isn't a crash signal. It's a headwind. Expect stocks to lag while yields climb. Watch for the peak.
$SPY $QQQ $TLT
2
3.5k
·
--
සත්යායනය කළ
Wednesday is the pivot. Core PCE drops at 8:30 AM, Micron reports after close, and quarter-end rebalancing happens in between. Friday brings payrolls.
Tuesday has JOLTS and Consumer Confidence, plus earnings from Jabil, Carnival, and FactSet.
The $MU call matters — not just the print, but the guide and what management says about memory pricing. That's the real signal for the buildout cycle.
$SPY $MU
Tuesday has JOLTS and Consumer Confidence, plus earnings from Jabil, Carnival, and FactSet.
The $MU call matters — not just the print, but the guide and what management says about memory pricing. That's the real signal for the buildout cycle.
$SPY $MU
3
773
·
--
10-year yield hit 5.2% last week — cost of capital just went from background noise to existential threat. We're now in a regime where the discount rate actually matters again, and that changes everything.
The easy money cohort — the names that worked because rates were pinned at zero — are about to get stress-tested in real time. If $SPY and $QQQ decide 5%+ borrowing costs are incompatible with 40x multiples, you'll see violent repricing. Not a dip. A repricing.
This is the setup tactical traders dream about: clarity on the macro constraint (rates), uncertainty on who survives it (valuation dispersion), and enough volatility to actually get paid for being right. If you've been waiting for a market that rewards precision over passive beta, this is it.
Watch gamma levels on $SPY around key strikes — dealer hedging flows will amplify moves in both directions. The vol structure is telling you the market knows something broke, it just hasn't decided what yet.
1
377
·
--
Want to know if food inflation is sticky? Don't wait for the CPI print. Look at the farm.
Diesel above $6.50/gal. Fertilizer and fuel costs surging on Iran war backdrop. Tariffs made equipment pricier. These are production costs that feed straight into every crop price and eventually into food on the shelf.
Then add supply disruption. ICE activity around major Kansas beef plants delayed shifts and cut production. Cattle groups say it plainly: that means higher beef prices. Labor hits at processing chokepoints tighten supply fast.
This is the ground-level version of the story we've tracked all month. The commodity complex is running hot, and here's why it stays hot: the input costs underneath are not easing.
Goolsbee just retired the word transitory. Persistent supply-cost pressure at the source is exactly what he's now assuming won't quickly reverse.
Everyone is pricing the oil headline. The farm is pricing diesel, fertilizer, labor, and beef all at once. Input costs lead. The number the Fed watches follows.
$SPY $QQQ
1
265
·
--
Boeing knew about a MAX software glitch in November 2024. Opened a formal safety review this month — 22 months later.
The company says the issue didn't initially meet safety review criteria. That phrase matters, given what MCAS cost them in 2018-19.
The glitch hits an automated nav feature during missed approaches. Pilots can lose autopilot functions at low altitude. Boeing told operators in August it wasn't a safety risk.
Permanent fix: early 2028. They're trying to accelerate.
But the commercial damage is live. Southwest and United just told Boeing they don't want new MAX aircraft with this software — they want the older version.
Problem: newly produced aircraft must match the certified design. FAA approved the MAX 7 last month with the new software. Southwest has been waiting years and plans to fly it next year.
FAA is investigating. Outcome could block MAX 10 certification if the glitch is deemed unsafe. Delta, United, American, and Alaska all have MAX 10s on order.
GE Aerospace wrote the software.
Watch deliveries, not headlines. Two of Boeing's largest customers just refused a certified aircraft configuration. The cert path for its two newest variants runs through the same code.
$BA $GE $SPY
1
313
·
--
Boeing's 737 MAX software saga just got messier. In August, Boeing told operators a software issue wasn't a safety risk — but United and Southwest didn't buy it. Both airlines are now demanding newly delivered MAX jets come with the old software instead of the flawed update, per WSJ sources.
This is the kind of quiet pushback that matters. When your two biggest domestic customers reject your "it's fine" narrative and insist on rolling back to legacy code, that's not a minor IT hiccup — it's a trust problem. Boeing's already operating under a microscope post-grounding, and this adds another layer of operational friction and reputational drag.
For $BA, it's another speed bump in the MAX ramp narrative. For $SPY, it's a reminder that even marquee industrials can't fully escape their own supply chain and certification issues — especially when the customer base has learned to push back hard.
267
තවත් අන්තර්ගතයන් ගවේෂණය කිරීමට ඇතුල් වන්න
Binance චතුරශ්රය හි ගෝලීය ක්රිප්ටෝ පරිශීලකයින් හා එක්වන්න
⚡️ ක්රිප්ටෝ පිළිබඳ නවතම සහ ප්රයෝජනවත් තොරතුරු ලබා ගන්න.
💬 ලොව විශාලතම ක්රිප්ටෝ හුවමාරුව මගින් විශ්වාස කෙරේ.
👍 සත්යායනය කරන ලද නිර්මාණකරුවන්ගෙන් සැබෑ විදසුන් සොයා ගන්න.
විද්යුත් තැපෑල / දුරකථන අංකය
නැගී එන මාතෘකා
NvidiaApproves$150BBuyback
216 views
10 සාකච්ඡා කරමින්
🚨 NVIDIA JUST MADE A $150 BILLION BET ON ITSELF!
AI giant NVIDIA has approved an additional $150 billion share buyback, pushing its total remaining repurchase authorization to $235 billion — the largest buyback program in U.S. corporate history.
Why does this matter? 👇
🔥 Massive buybacks often signal strong confidence from management.
💰 NVIDIA is using huge AI-driven cash flows to return capital to shareholders.
📈 The move also highlights NVIDIA’s belief that the AI boom is far from over.
CEO Jensen Huang says AI and accelerated computing are creating a “once-in-a-generation” opportunity, and NVIDIA plans to continue investing aggressively while rewarding investors.
👀 Traders are now watching whether this historic announcement adds more momentum to AI-related stocks and the broader tech market.
#NvidiaApproves$150BBuyback #NVIDIA
$NVDA.US $NVDAB
ASHFAQ NAEEM
·0 කැමත්ත දැක්වීම්
·26 views
OpenAIDelaysGPT6.1OverSafetyIssues
657 views
53 සාකච්ඡා කරමින්
AMDToAcquireWorldLabsFor$8.2B
86 views
16 සාකච්ඡා කරමින්