

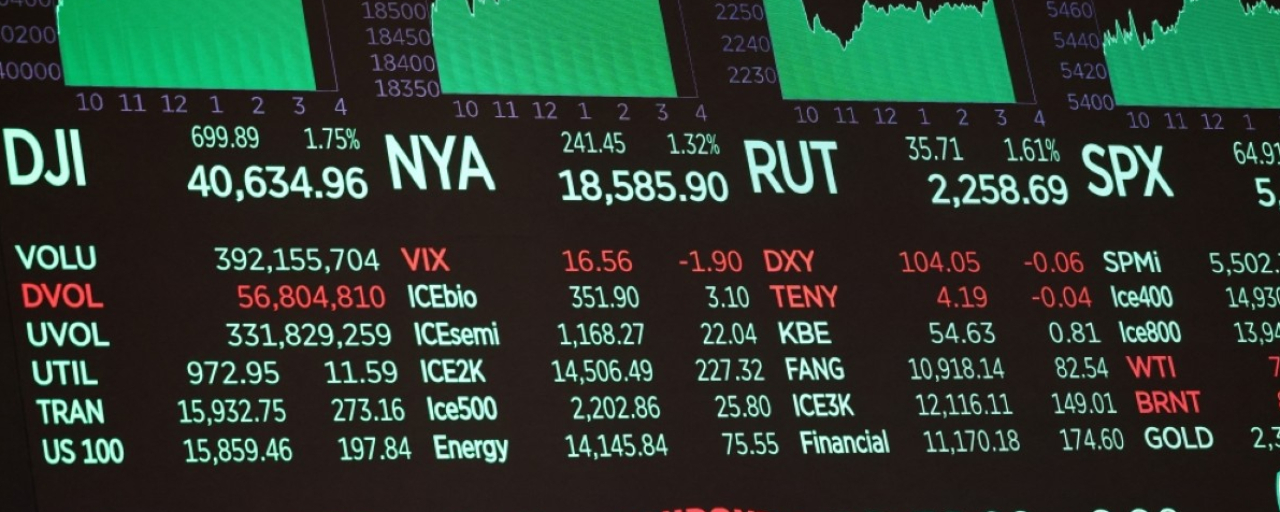

Stocks closed higher Friday, and tech carried more of the load than Thursday had earned it. The week had been a rough ride: Treasury yields that kept climbing, oil that stayed expensive, and a sell-off in AI names that left the Nasdaq looking shaky.
Thursday's trigger was a number. OpenAI had told investors it hit about $50 billion in annualized revenue at the end of September, CNBC confirmed, and that landed badly next to the $68 billion figure floating around a month earlier. AI-linked shares sold off on it. By Friday, the market barely seemed to remember.
Russian Diesel Gets a Six-Month Pass
Trump added to the mood. Posting on Truth Social after a call with Vladimir Putin, the president said Russia would put more than 300,000 tons of diesel into U.S. and global markets right away, another 500,000 tons in November and a million after that. Treasury backed him up the same day with a temporary license waiving sanctions on Russian diesel for about six months, through April 2027.
Diesel futures dropped about 4% on the headline. Crude barely flinched by comparison: West Texas Intermediate settled near $92 a barrel and Brent just over $104.
Households Are Not Celebrating
Americans weren't feeling any of it. The University of Michigan's preliminary October sentiment reading slipped to 46.3 from 48.1 in September, a five-month low. Worries about living costs and economic uncertainty keep building, with the midterm elections less than a month away.
The Scoreboard Looks Better Than the Week Felt
The Dow did the most work, adding 423.31 points, or 0.83%, to settle at 51,654.95. The S&P 500 finished at 7,811.54 (up 0.59%) and the Nasdaq Composite at 27,366.17 (up 0.64%). Small caps came along for the ride, with the Russell 2000 closing at 2,806.98, a 0.46% gain.
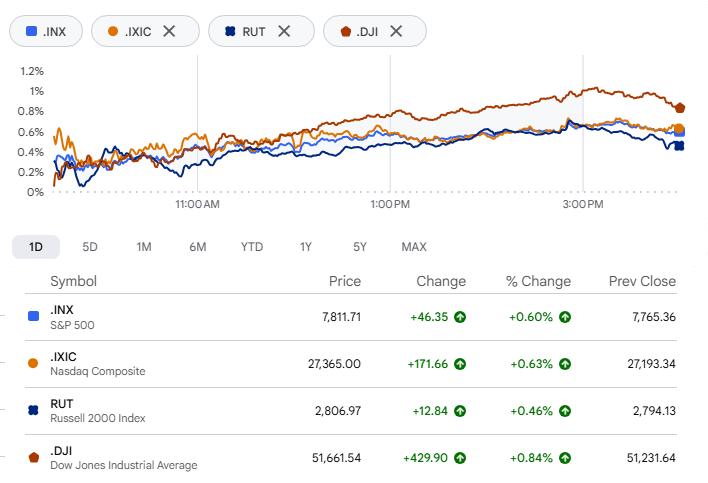
Over five days, the damage from rising yields never really showed up in the averages. Longer-dated Treasury yields reached 24-year highs on Wednesday, yet all three major indexes ended the week ahead. The S&P 500 gained about 1.2% and the Dow 0.9%. The Nasdaq's 0.6% was its fourth weekly advance in a row.
SpaceX Walks Into the Wireless Business
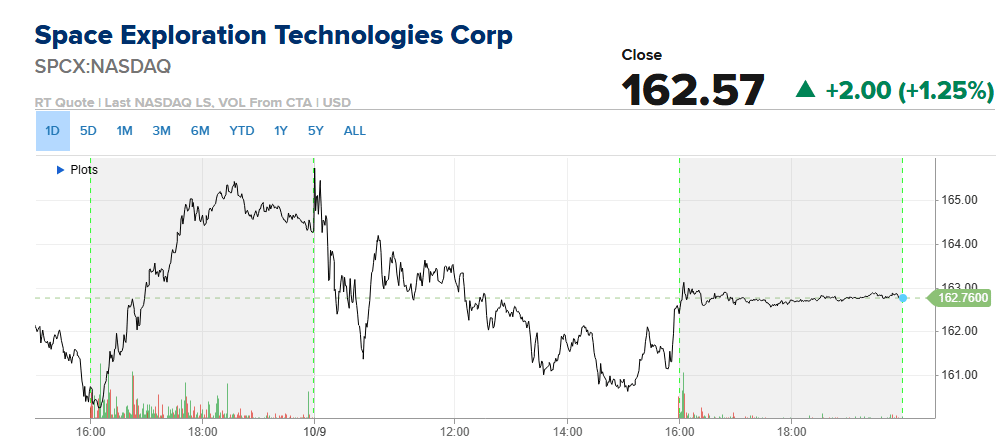
SpaceX rose about 1% after announcing it had agreed to buy a nationwide spectrum portfolio, a deal that moves it closer to competing as a U.S. mobile carrier. The company describes the package as up to 14 megahertz of paired spectrum in the 800 MHz band, bought from Grain Management. The Wall Street Journal put the price near $8 billion. The Federal Communications Commission still has to approve it.
For tower owners, SpaceX looked like a prospective tenant. American Tower closed up 9.3%. Crown Castle did better still, at 15.6%. Bernstein noted the obvious catch: owning spectrum doesn't commit SpaceX to building more towers.
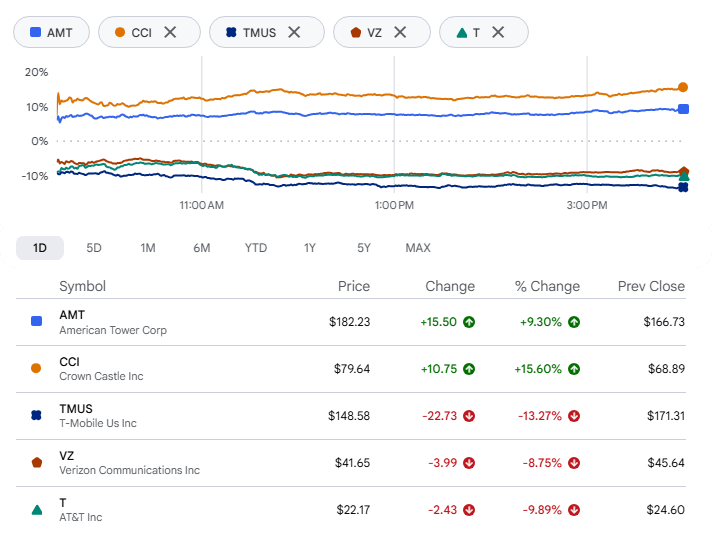
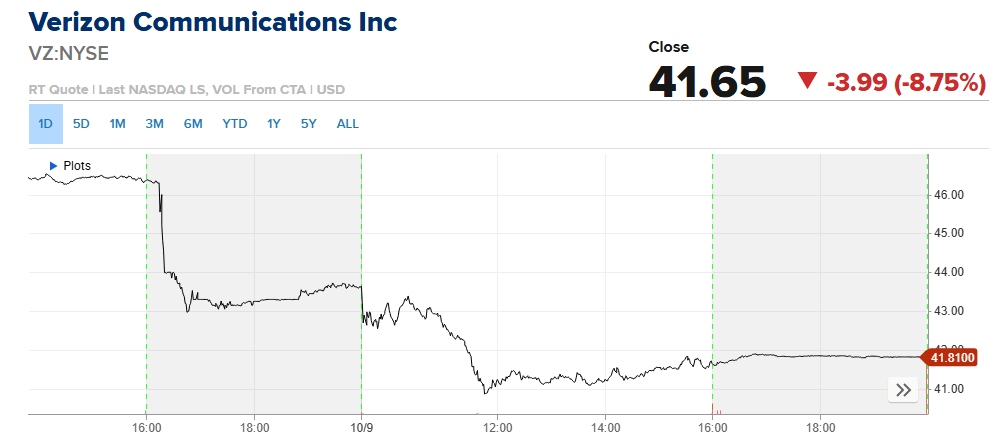
The carriers were on the wrong end of it. T-Mobile took the worst of it, down 13.27% to $148.58, a $22.73 drop per share. Verizon, which finished at $41.65, gave up $3.99, or 8.75%. AT&T, at $22.17, was off nearly 10%.
JPMorgan analysts urged some perspective, arguing the incumbents face limited near-term risk because a competitive network takes time, infrastructure and capital to build.
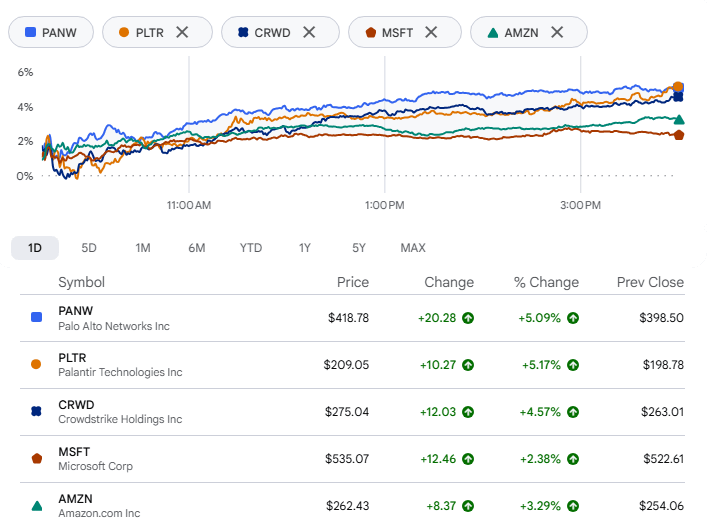
Other Software stocks rose in tandem. Palo Alto Networks and Palantir Technologies picked up about 5% apiece, CrowdStrike around 4.6%. Microsoft ended up 2.4%, and Amazon, another Magnificent Seven member, gained 3.3%.
Cancer Vaccines Give Healthcare a Lift
Healthcare had a story of its own. The New York Times reported that the National Institutes of Health intends to launch a public-private push to speed along personalized cancer vaccines, with a December start. Pancreatic, liver and colorectal cancers come first, along with certain pediatric tumors.
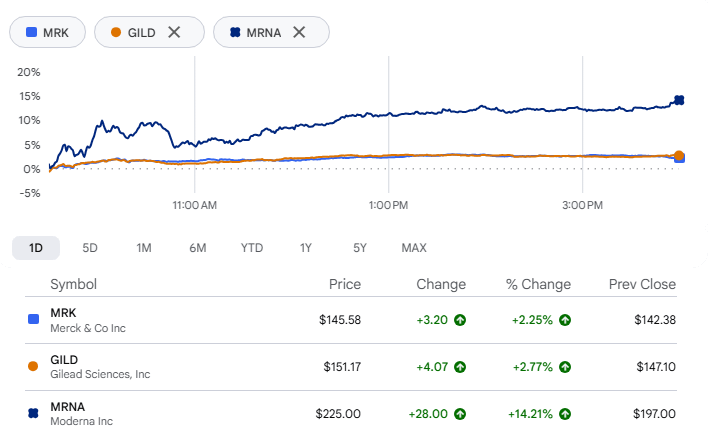
Merck and Gilead Sciences both climbed more than 2%. Moderna, which is working on a personalized mRNA cancer vaccine with Merck, did a good deal better, jumping more than 14%.
Sold-Out Lasers and Swinging Star Ratings
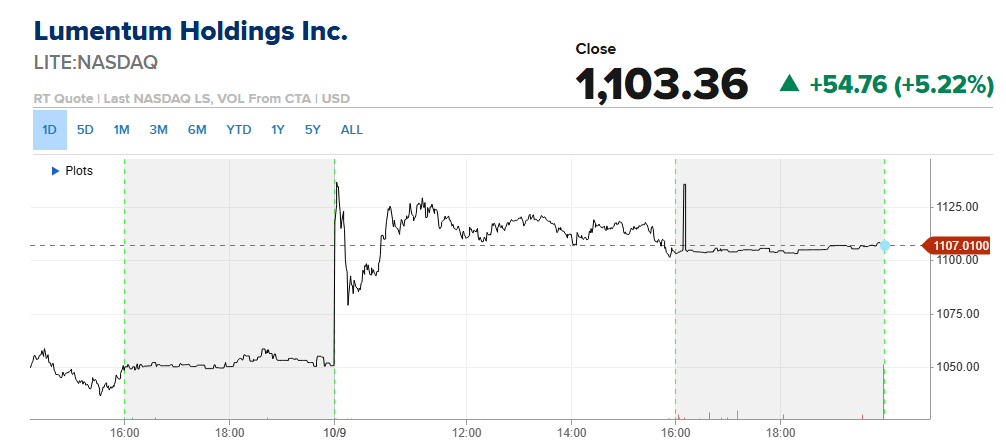
Lumentum gained close to 6% after CEO Michael Hurlston told Bloomberg Television in Tokyo that its optical components are "completely sold out" through early 2029. For some products, he said, the company can't meet roughly 70% of demand even through next year.
Insurers spent the day reading report cards. The Centers for Medicare & Medicaid Services released its 2027 Star Ratings ahead of open enrollment this fall, and Humana came out ahead: its largest Medicare Advantage contract rose to 4 stars from 3.5, and the shares gained nearly 12%. Alignment Healthcare went the opposite way. Its biggest California plan landed at 3.5 stars, short of the 4-star line that qualifies for bonus payments, and the stock fell sharply.
Verizon Posts Its Roughest Session Since 2002
Verizon's decline had some history behind it. It was the stock's worst day since July 22, 2002, when it dropped nearly 9%. T-Mobile and AT&T didn't escape the record books either. T-Mobile's slide was its worst since 2013, AT&T's its worst since 2000.
Good Earnings, Smaller Forecast
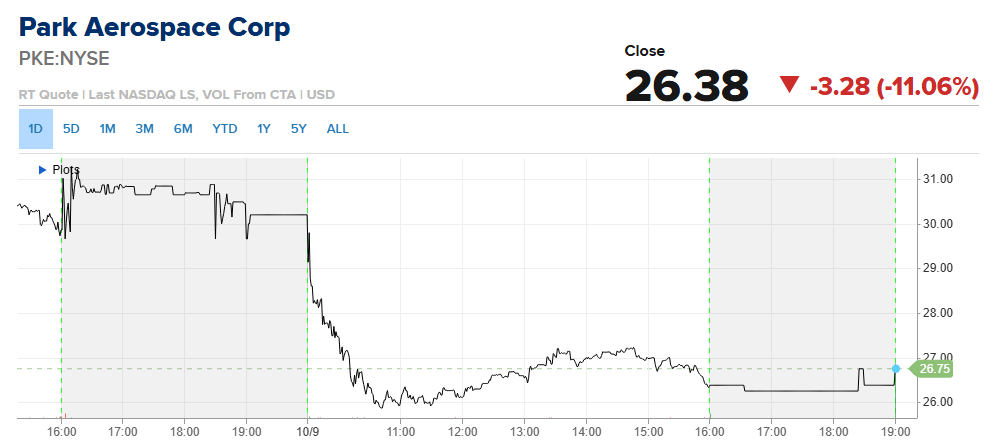
Park Aerospace makes composite materials for the aerospace industry, and its stock lost about 11% on a quarter that looked strong on its face. Earnings came in at 21 cents a share on $20.8 million in revenue for the fiscal second quarter, against 12 cents and $16.4 million a year earlier. The problem was the outlook. Park now expects $32 million to $35 million in full-year sales tied to GE Aerospace jet-engine programs, down from a prior range of $34 million to $38 million.
Sector Analysis
Best-Performing Sectors
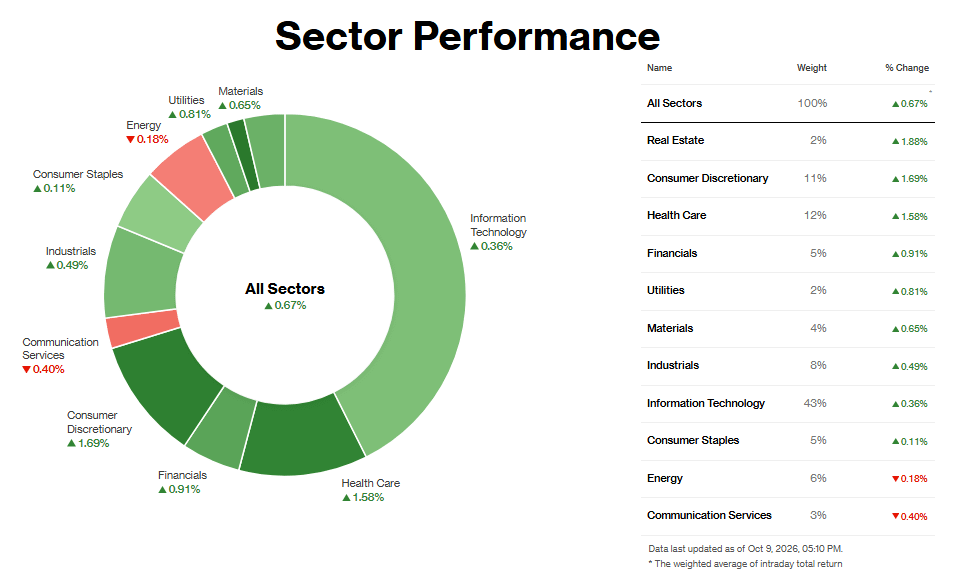
Friday closed out the week on a firm note with only 2 of the nine sectors finishing in losses. Real Estate (+1.88%) led, but at a 2% weight, only a few stocks moved it. SpaceX’s roughly $8 billion purchase of Grain Management’s nationwide 800 MHz spectrum sent tower owners surging. Treasuries helped at the margin, since yields finished the week lower across the curve for the first time in six weeks.
Consumer Discretionary (+1.69%) rode the megacap bounce. Amazon rose 3.29% and Tesla 2.05% as AI-linked names recovered from Thursday’s selloff, which followed a report that OpenAI’s annualized revenue was about $20 billion below the figure circulating in late September.
Health Care (+1.58%) was stock-driven. Humana jumped about 12% after CMS restored a four-star rating to its flagship Medicare Advantage contract, covering more than 2 million members, and Moderna climbed after rejoining the Nasdaq-100.
Worst-Performing Sectors
Communication Services (-0.40%) paid for that same SpaceX deal. Verizon fell about 9%, its worst day since 2002, with T-Mobile and AT&T also sold hard as investors priced in a Starlink-backed rival in wireless. The damage was industry-specific rather than sector-wide, and Alphabet’s roughly 1% gain cushioned the group.
Energy (-0.18%) had no single dominant driver. Trump’s pledge not to attack Iran before the November 3 midterms knocked crude lower early, Hurricane Isaias shut in nearly 63% of Gulf oil output, and WTI still settled up 0.39% at $91.85. The shares lagged a tape that favored buyers elsewhere.
Earnings season gets going in earnest next week, with inflation data and retail sales alongside it. Adam Crisafulli of Vital Knowledge doesn't expect AI-linked stocks to snap back in a clean V, since the crowded positioning behind Thursday's sell-off has, in his view, more unwinding to do. A good Friday doesn't settle that argument, and next week's earnings will get the first say.