

translog1c
2 Публикации
translog1c
Отправить жалобу
Заблокировать пользователя
Buy-side investor researching
AI infrastructure & semiconductors.

TradFi KOL
0 подписок(и/а)
21 подписчиков(а)
6 понравилось
1 Значки
Посты
·
--
Рост
Проверено
One of the most important comments from One of the most important comments from $MUB earnings call was that FQ1 should be the gross margin floor for FY27.
Micron expects revenue to grow sequentially every quarter in FY27, while gross margin should move higher after Q1. Pricing is still expected to improve, just at a slower pace than before.
My view is that FY27 EPS can go above $200.
FQ1 EPS guidance is already $38.15. If earnings keep growing from here, I don’t think $200 requires a very aggressive assumption.
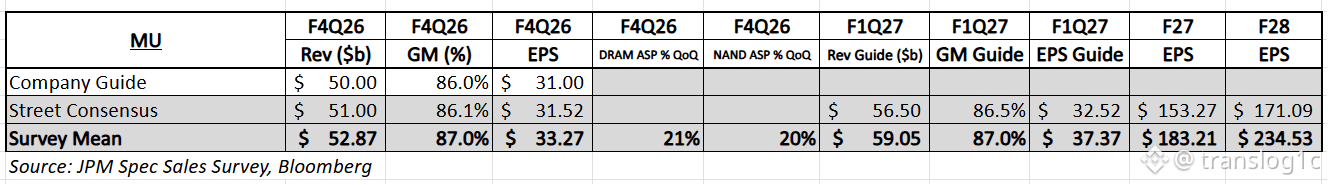
JPM’s channel survey had FY27 EPS around $180, while FY28 consensus was around $234. I also think FY28 earnings can continue to move higher if the current memory cycle lasts.
Capital return is another thing I’m watching closely.
At $200 EPS and around 1.15B diluted shares, Micron would generate roughly $230B of earnings.
Even if only around half of that turns into excess free cash flow available for capital returns, the potential buyback capacity could still be very significant.
Micron has already said it plans to increase capital returns from December 9, mainly through share repurchases, and will seek additional buyback authorization.
On pricing, I still think there is a gap between market expectations and what I’m hearing from the industry.
After talking with memory industry contacts recently, demand looks tighter than it did a few months ago.
I’m hearing the same thing in China. China internet companies are even aggressively buying up memory in the secondary market, along with RTX 5090 GPUs.
There has also been some discussion about a 30% quarterly cap on memory price increases.
Based on my own channel checks, I have not seen evidence of a broad 30% quarterly pricing cap on conventional DRAM or NAND.
#EarningsSeason
3
2
20.8k
·
--
$MUB is probably the most important earnings print this week. #EarningsSeason
Memory is still one of the most favored trades right now, but positioning doesn’t look excessively crowded even after the recent rebound. The options market is telling a similar story.
For this print, I’m mainly watching two things: the buyback starting in December, and management’s pricing outlook.
The market seems to be pricing in a much flatter memory pricing curve from here. I think that’s too conservative.
My recent channel checks still point to further DRAM and SSD price increases, with sequential pricing momentum remaining intact. That gap is what I’ll be watching most closely into the print.
5
1
4
4.8k
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона
В тренде
BinanceKZ
Просмотров: 31,438
75 обсуждают
Как я потерял 180 000 тенге на «менеджере Binance» из WhatsApp — и почему всё равно остался в крипте
phpdead
·Лайков: 6
·Просмотров: 2.4k
EtherGains70.9%InQ3
Просмотров: 71,087
756 обсуждают
TreasuryLetsStatesFileStablecoinCertificationsEarly
Просмотров: 3,418
36 обсуждают