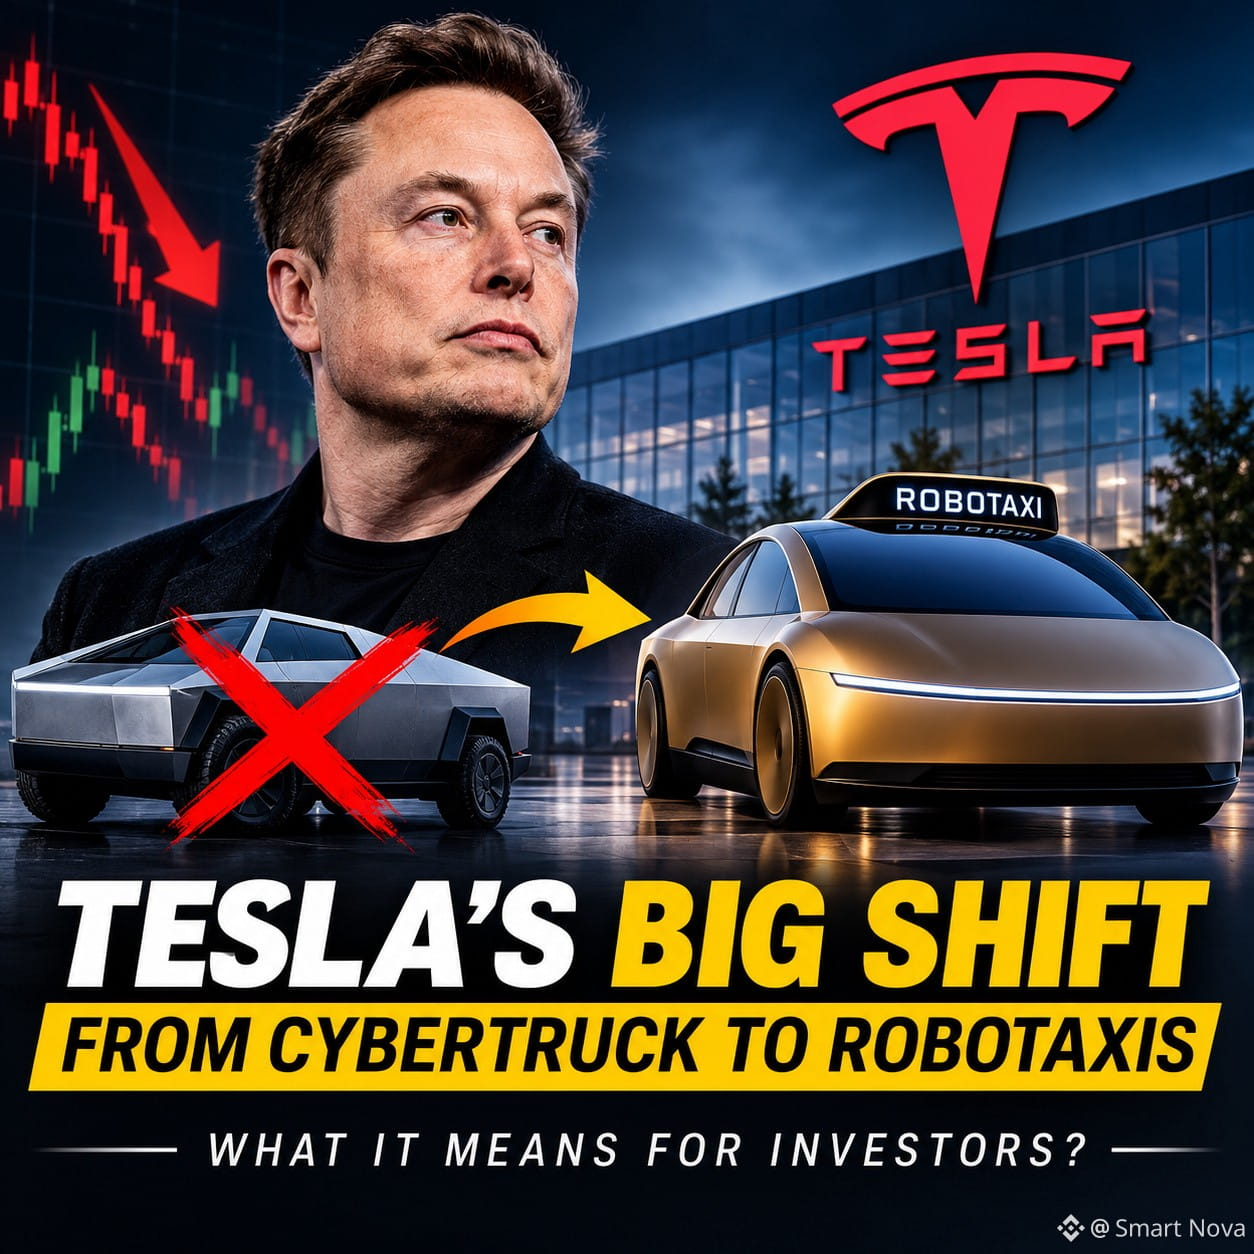
🔥 ELON MUSK IS BETTING TESLA'S FUTURE ON ROBOTAXIS — BUT WHAT ABOUT CYBERTRUCK?
Tesla ($TSLA ) is preparing to dismantle its Cybertruck production line around June–July 2027 and redirect capacity toward its Cybercab robotaxi.
Here's what investors need to understand:
📉 The Cybertruck problem: US sales dropped from nearly 39,000 in 2024 to around 20,000 in 2025. That's a significant gap from Musk's original ambition of 250,000 annual sales.
🤖 The bigger opportunity: Tesla wants to move beyond selling electric vehicles and build a scalable autonomous transportation business.
Why this matters for investors:
Bullish case: Successful robotaxi deployment could create recurring revenue and a new growth engine.
Bearish case: Weak Cybertruck demand highlights execution challenges, while robotaxi development requires substantial investment.
Key risk: Regulatory approval, autonomous driving safety and commercial profitability remain critical hurdles.
4 things to watch next:
Cybercab production and deployment timelines.
Tesla's automotive revenue and profit margins.
Robotaxi expansion and regulatory approvals.
Whether autonomous services can generate meaningful recurring revenue.
MY TAKE: Tesla's long-term valuation increasingly depends on whether it can turn its AI and autonomous-driving ambitions into profitable businesses.
A promising vision isn't the same as proven earnings.
👀 Would you value $TSLA as an EV company or an AI and robotics company?
#Robotaxi #AI #StockMarket #Investing
Tesla ($TSLA ) is preparing to dismantle its Cybertruck production line around June–July 2027 and redirect capacity toward its Cybercab robotaxi.
Here's what investors need to understand:
📉 The Cybertruck problem: US sales dropped from nearly 39,000 in 2024 to around 20,000 in 2025. That's a significant gap from Musk's original ambition of 250,000 annual sales.
🤖 The bigger opportunity: Tesla wants to move beyond selling electric vehicles and build a scalable autonomous transportation business.
Why this matters for investors:
Bullish case: Successful robotaxi deployment could create recurring revenue and a new growth engine.
Bearish case: Weak Cybertruck demand highlights execution challenges, while robotaxi development requires substantial investment.
Key risk: Regulatory approval, autonomous driving safety and commercial profitability remain critical hurdles.
4 things to watch next:
Cybercab production and deployment timelines.
Tesla's automotive revenue and profit margins.
Robotaxi expansion and regulatory approvals.
Whether autonomous services can generate meaningful recurring revenue.
MY TAKE: Tesla's long-term valuation increasingly depends on whether it can turn its AI and autonomous-driving ambitions into profitable businesses.
A promising vision isn't the same as proven earnings.
👀 Would you value $TSLA as an EV company or an AI and robotics company?
#Robotaxi #AI #StockMarket #Investing