Let's break down what just happened to $INTC — this is a textbook lesson in how guidance kills price, even when the quarter itself beats.
The Numbers:
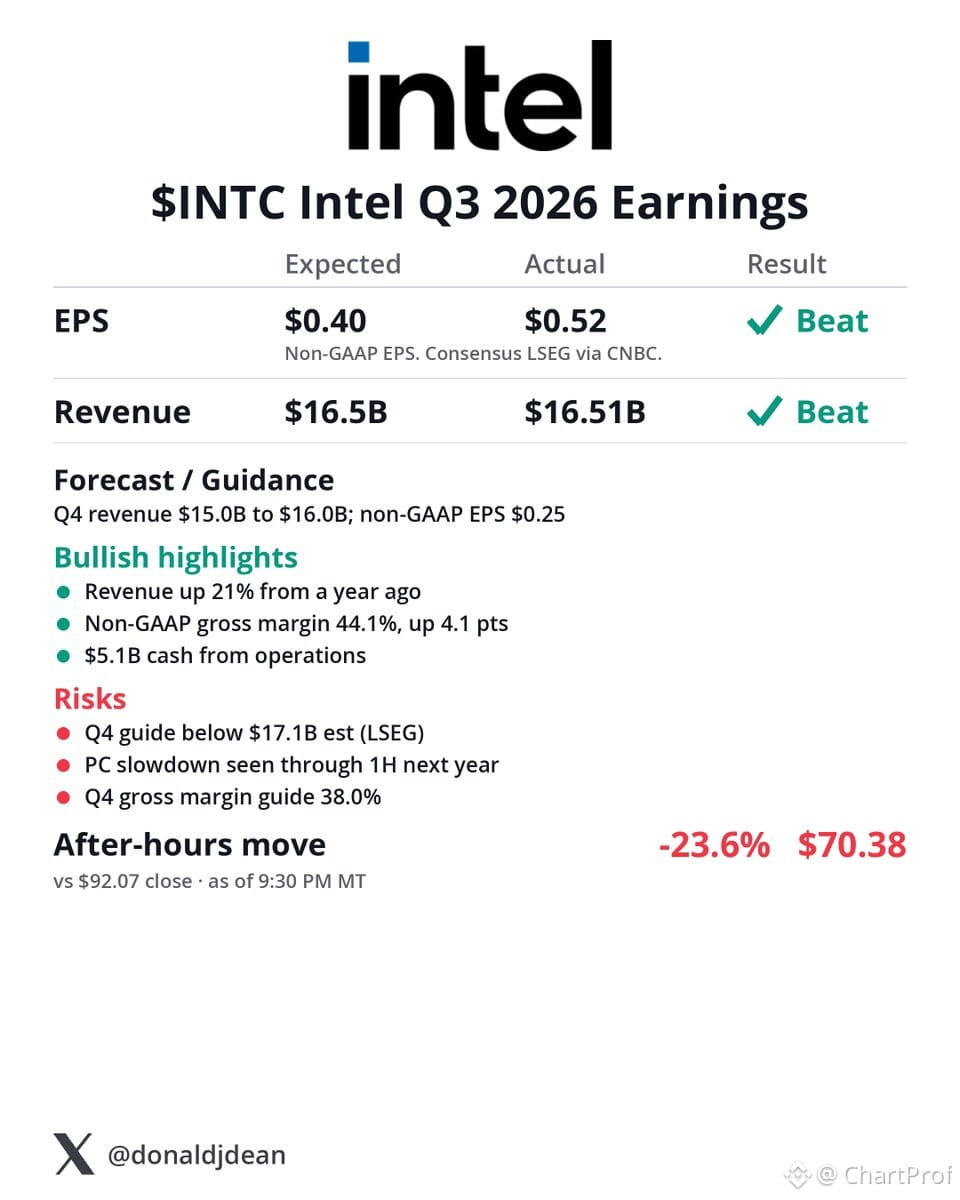
Q4 delivered — $0.52 EPS vs $0.40 expected, revenue $16.51B (up 21% YoY) vs $16.5B consensus. Clean beat. But here's the problem: forward guidance came in at $15B–$16B for next quarter vs $17.1B expected. That's a ~$1B+ miss on the low end. Market doesn't trade what you did — it trades what you're about to do.
The Structure:
Stock down 23.6% after hours to $70.38. That's not noise — that's a re-rate. When you miss guidance by this margin, especially citing "PC slowdown through H1 next year," the market assumes demand weakness, not just conservative forecasting. This is a demand story now, not an execution story.
What This Teaches:
Earnings are a two-part test — the quarter and the outlook. You can ace the first and still fail if the second disappoints. The 24% drop tells you the guide matters more than the beat. Watch how $INTC holds $70 — if it breaks, next support is likely mid-$60s. If it reclaims $75, that's your first sign the sell-off overshot.
Invalidation: A guidance revision higher or sector-wide PC data that contradicts the slowdown narrative. Until then, this is a show-me story.
The Numbers:
Q4 delivered — $0.52 EPS vs $0.40 expected, revenue $16.51B (up 21% YoY) vs $16.5B consensus. Clean beat. But here's the problem: forward guidance came in at $15B–$16B for next quarter vs $17.1B expected. That's a ~$1B+ miss on the low end. Market doesn't trade what you did — it trades what you're about to do.
The Structure:
Stock down 23.6% after hours to $70.38. That's not noise — that's a re-rate. When you miss guidance by this margin, especially citing "PC slowdown through H1 next year," the market assumes demand weakness, not just conservative forecasting. This is a demand story now, not an execution story.
What This Teaches:
Earnings are a two-part test — the quarter and the outlook. You can ace the first and still fail if the second disappoints. The 24% drop tells you the guide matters more than the beat. Watch how $INTC holds $70 — if it breaks, next support is likely mid-$60s. If it reclaims $75, that's your first sign the sell-off overshot.
Invalidation: A guidance revision higher or sector-wide PC data that contradicts the slowdown narrative. Until then, this is a show-me story.