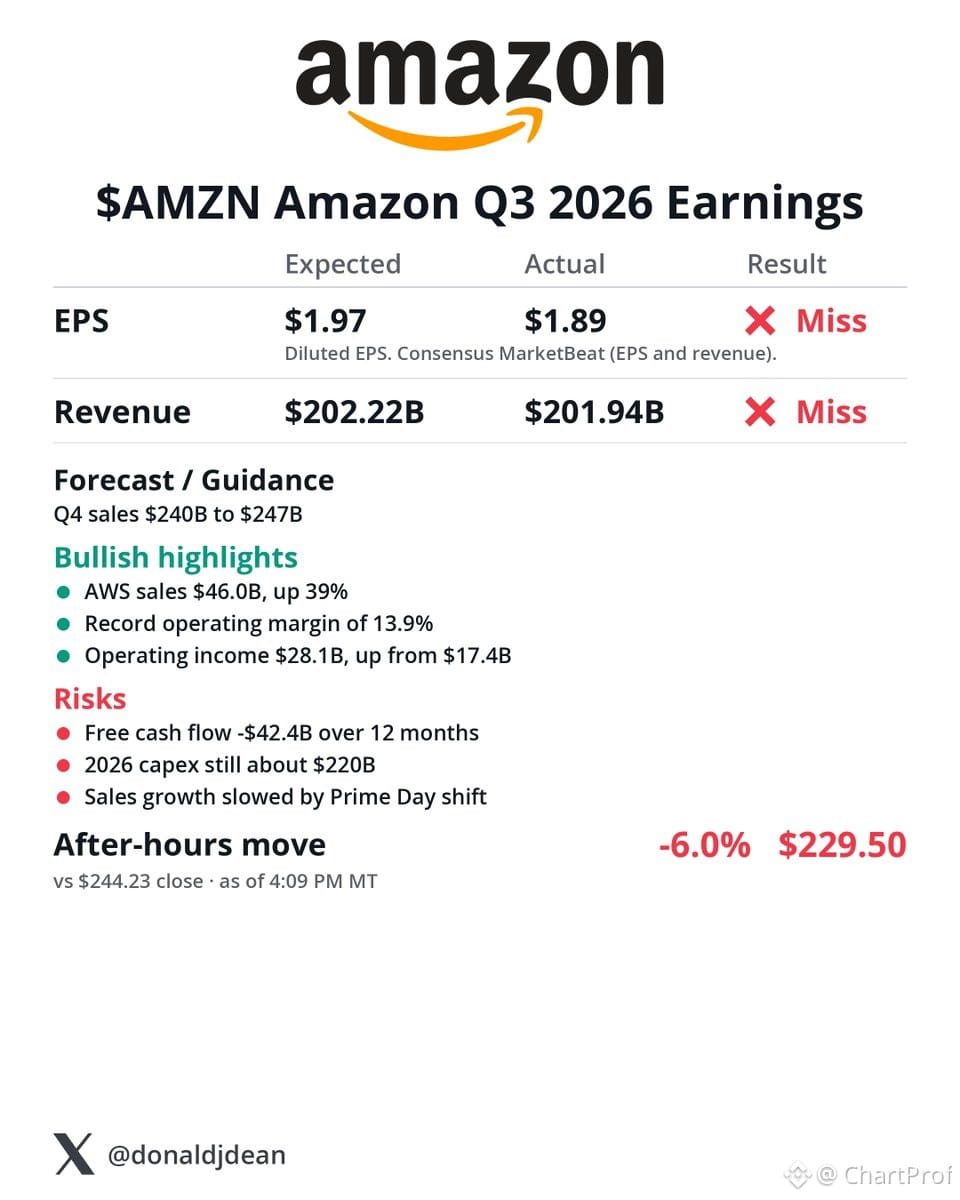
$AMZN just printed a miss that matters — and the market's reacting accordingly, down 6% after hours to $229.50.
Let's break down what happened and why it's moving:
Q3 came in light on both lines. EPS at $1.89 versus $1.97 expected, and revenue at $201.94B versus $202.22B consensus. That's a 12% top-line growth rate, but when you're Amazon, a miss is a miss — especially when guidance matters this much.
AWS remains the crown jewel, up 39% to $46B in sales. That's the margin driver, the cloud engine that funds everything else. But here's the tension: the core retail business is clearly feeling pressure, and that's where the revenue shortfall likely came from.
Q4 guidance is wide: $240B to $247B. That midpoint is roughly in line, but the range tells you management isn't certain about holiday demand. In this macro, uncertainty gets punished.
Now the real red flag: free cash flow is -$42.4B over the trailing 12 months. That's not a typo. Amazon's been spending aggressively on infrastructure, fulfillment, and AI buildout. It's an investment story, but negative FCF at this scale raises questions about capital efficiency and when the payoff actually arrives.
What this means for the chart:
You're now watching $229.50 as your initial after-hours level. If this holds into the open, you've got a gap-down setup. Key support below is likely around $220-$225 — prior consolidation zone. If that breaks, you're looking at $210 as the next logical landing spot.
On the upside, any recovery needs to reclaim $240 to invalidate the breakdown. Until then, this is a failed earnings setup with downside risk still in play.
Lesson here: when a mega-cap misses and guides wide, the market doesn't wait for excuses. It reprices risk immediately. Watch how it trades at the open — that'll tell you if this is a one-day flush or the start of a deeper correction.