


Across 1,602 days from April 2022 to September 2026, Deribit's DVOL index priced more volatility than bitcoin delivered over the following 30 days on 73.6% of them, by a median 10.6 vol points.
That gap exists for a plain reason. Option sellers carry gap risk, and buyers pay for protection the way homeowners pay for insurance. The premium is the price of that cover.
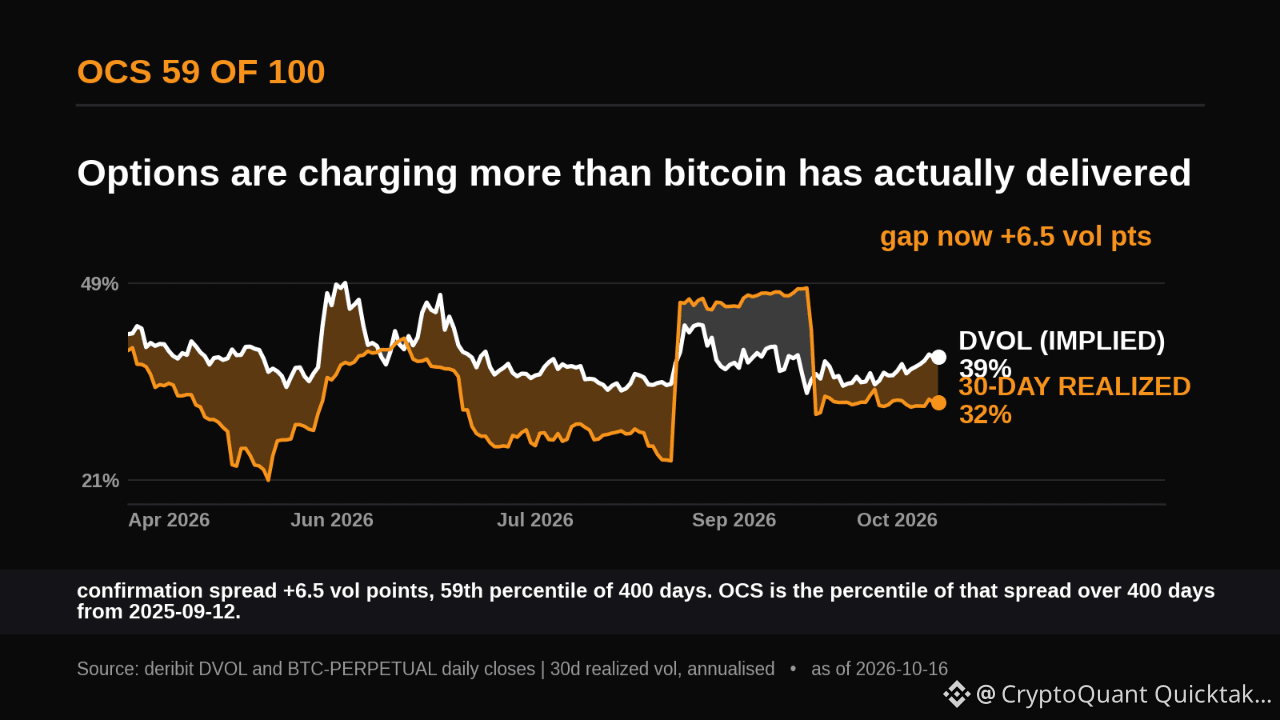
Today the same gap is open but narrow. DVOL sits at 38.75 against 30-day realized volatility of 32.24, a spread of 6.51 points, with spot at $82,302 after the hot CPI print. Traders are paying a little more for downside puts than for upside calls, with 25-delta skew at -2.71.
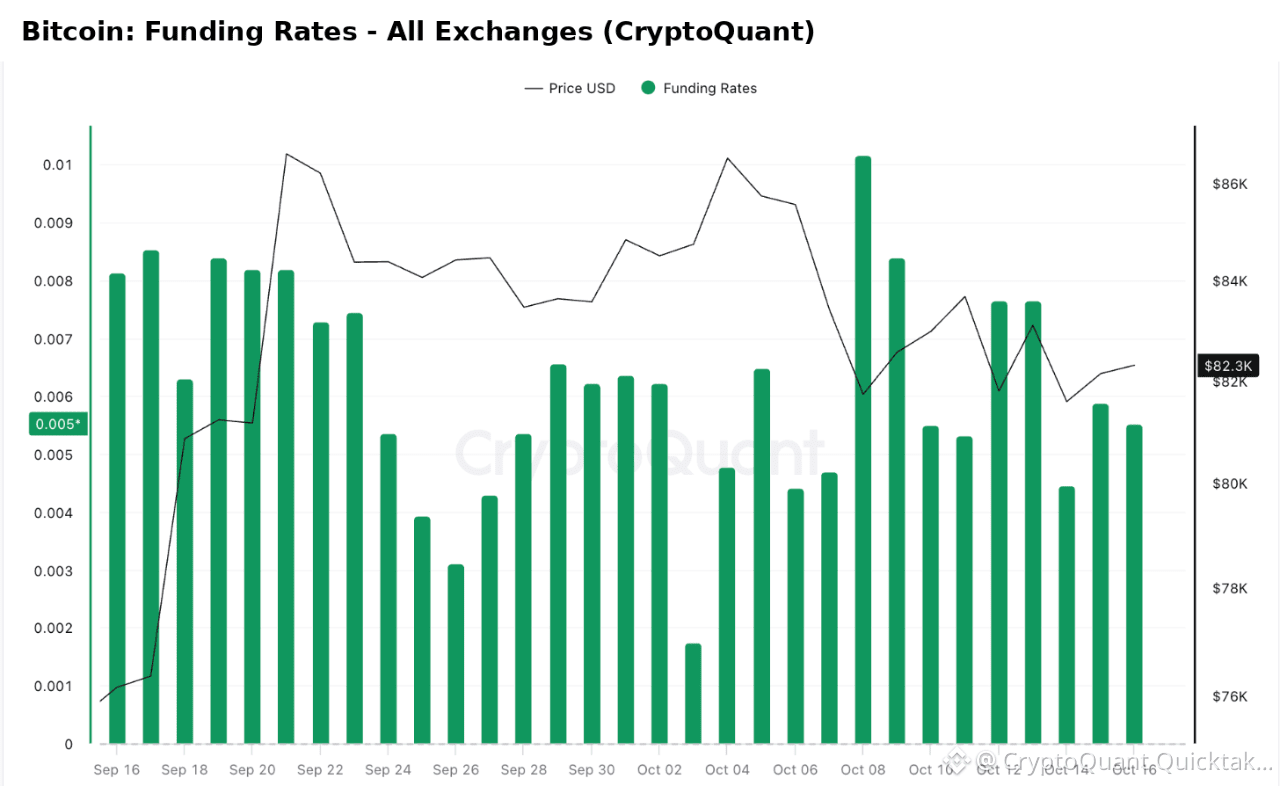
The perpetual market is not crowded either way. CryptoQuant's all-exchange Funding Rates averaged 0.0059% on October 15, below the 0.01% neutral baseline, and stayed between 0.0018% and 0.0102% over the past 30 days. Single venues have dipped negative; the aggregate has not.
A caveat belongs early: a premium is normal, not a signal. On roughly a quarter of days, the next month delivered more movement than options priced, and a narrow spread does not tell you which kind of month is coming.
Options are charging for a calm month while perpetual traders lean slightly short.
Two prints would change this read. If 30-day realized volatility climbs above DVOL before the October 30 expiry, sellers were underpaid and the premium flipped. If DVOL falls below 32 while funding holds under 0.01%, options are pricing calm outright and the cushion is gone.
Written by The Daily Digits