AI stocks are rising, but I think the more interesting question now is: what gets paid when the AI buildout moves beyond GPUs?
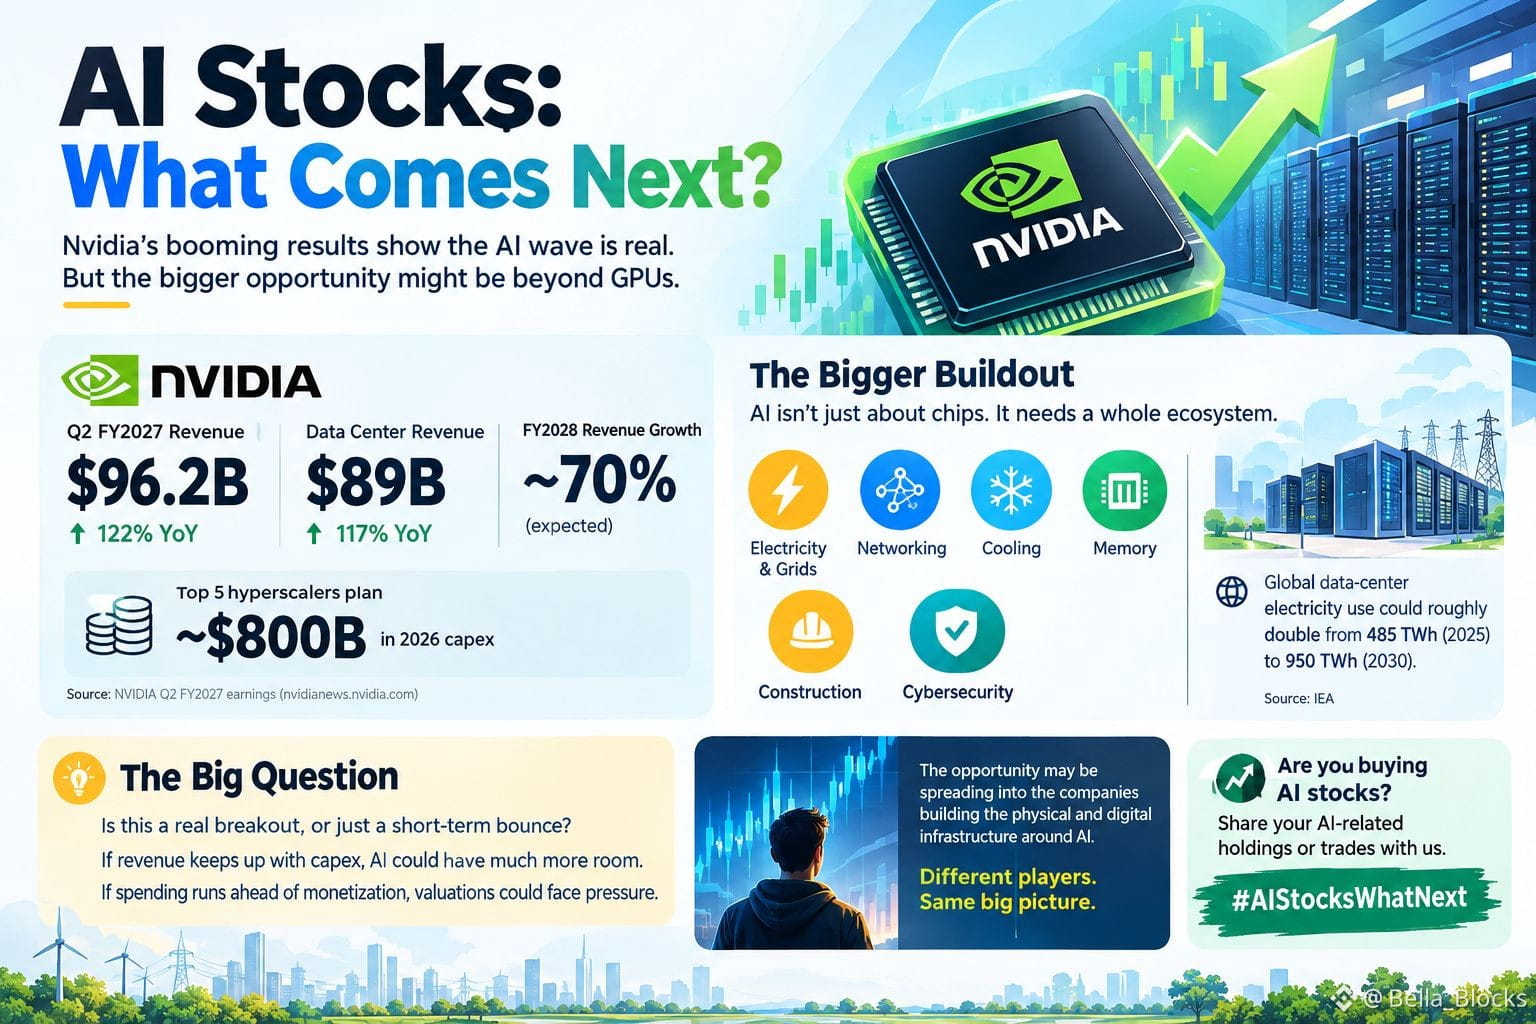
NVIDIA just reported $96.2B in quarterly revenue, with Data Center revenue reaching $89B, up 117% YoY. Jensen Huang also said NVIDIA expects roughly 70% revenue growth for fiscal 2028, while its earnings call highlighted nearly $800B of 2026 capex from the top five hyperscalers.
But this spending creates a second investment layer.
AI data centers need electricity, grids, networking, cooling, memory, construction and cybersecurity. The IEA estimates global data-center electricity consumption could roughly double from 485 TWh in 2025 to 950 TWh by 2030, while AI-focused data centers are expected to grow even faster. In the US, data centers could account for around half of electricity-demand growth through 2030.
That changes how I look at the AI trade. It isn't only a semiconductor story anymore.
The opportunity may be spreading into the companies building the physical and digital infrastructure around AI—but so is the risk. If hyperscaler capex eventually slows, companies depending on constant AI spending could face pressure.
So I'm watching two things together: AI revenue growth vs. the cost of building all this compute.
If revenue keeps catching up with capex, the AI cycle could have much more room. If spending runs far ahead of monetization, today's excitement could become tomorrow's valuation problem.
I’m bullish on the long-term AI theme, but I’m increasingly interested in the picks-and-shovels behind it rather than simply chasing the headline.
#AIStocksWhatNext
$4Stock
$AGT
$AKE
NVIDIA just reported $96.2B in quarterly revenue, with Data Center revenue reaching $89B, up 117% YoY. Jensen Huang also said NVIDIA expects roughly 70% revenue growth for fiscal 2028, while its earnings call highlighted nearly $800B of 2026 capex from the top five hyperscalers.
But this spending creates a second investment layer.
AI data centers need electricity, grids, networking, cooling, memory, construction and cybersecurity. The IEA estimates global data-center electricity consumption could roughly double from 485 TWh in 2025 to 950 TWh by 2030, while AI-focused data centers are expected to grow even faster. In the US, data centers could account for around half of electricity-demand growth through 2030.
That changes how I look at the AI trade. It isn't only a semiconductor story anymore.
The opportunity may be spreading into the companies building the physical and digital infrastructure around AI—but so is the risk. If hyperscaler capex eventually slows, companies depending on constant AI spending could face pressure.
So I'm watching two things together: AI revenue growth vs. the cost of building all this compute.
If revenue keeps catching up with capex, the AI cycle could have much more room. If spending runs far ahead of monetization, today's excitement could become tomorrow's valuation problem.
I’m bullish on the long-term AI theme, but I’m increasingly interested in the picks-and-shovels behind it rather than simply chasing the headline.
#AIStocksWhatNext
$4Stock
$AGT
$AKE