

Mohamed A. El-Erian Re-poster
1.1k ໂພສ
Mohamed A. El-Erian Re-poster
ລາຍງານ
ບລັອກຜູ້ໃຊ້
Rene M Kern Prof of Prac at Wharton. Allianz Advisor. Gramercy Chair. Chair of UnderArmour Board. Former Pimco CEO/co-CIO and President of Queens' Col Cambridge
0 ກໍາລັງຕິດຕາມ
650 ຜູ້ຕິດຕາມ
1.1K+ Liked
ໂພສ
ທັງໝົດ
ວີດີໂອ
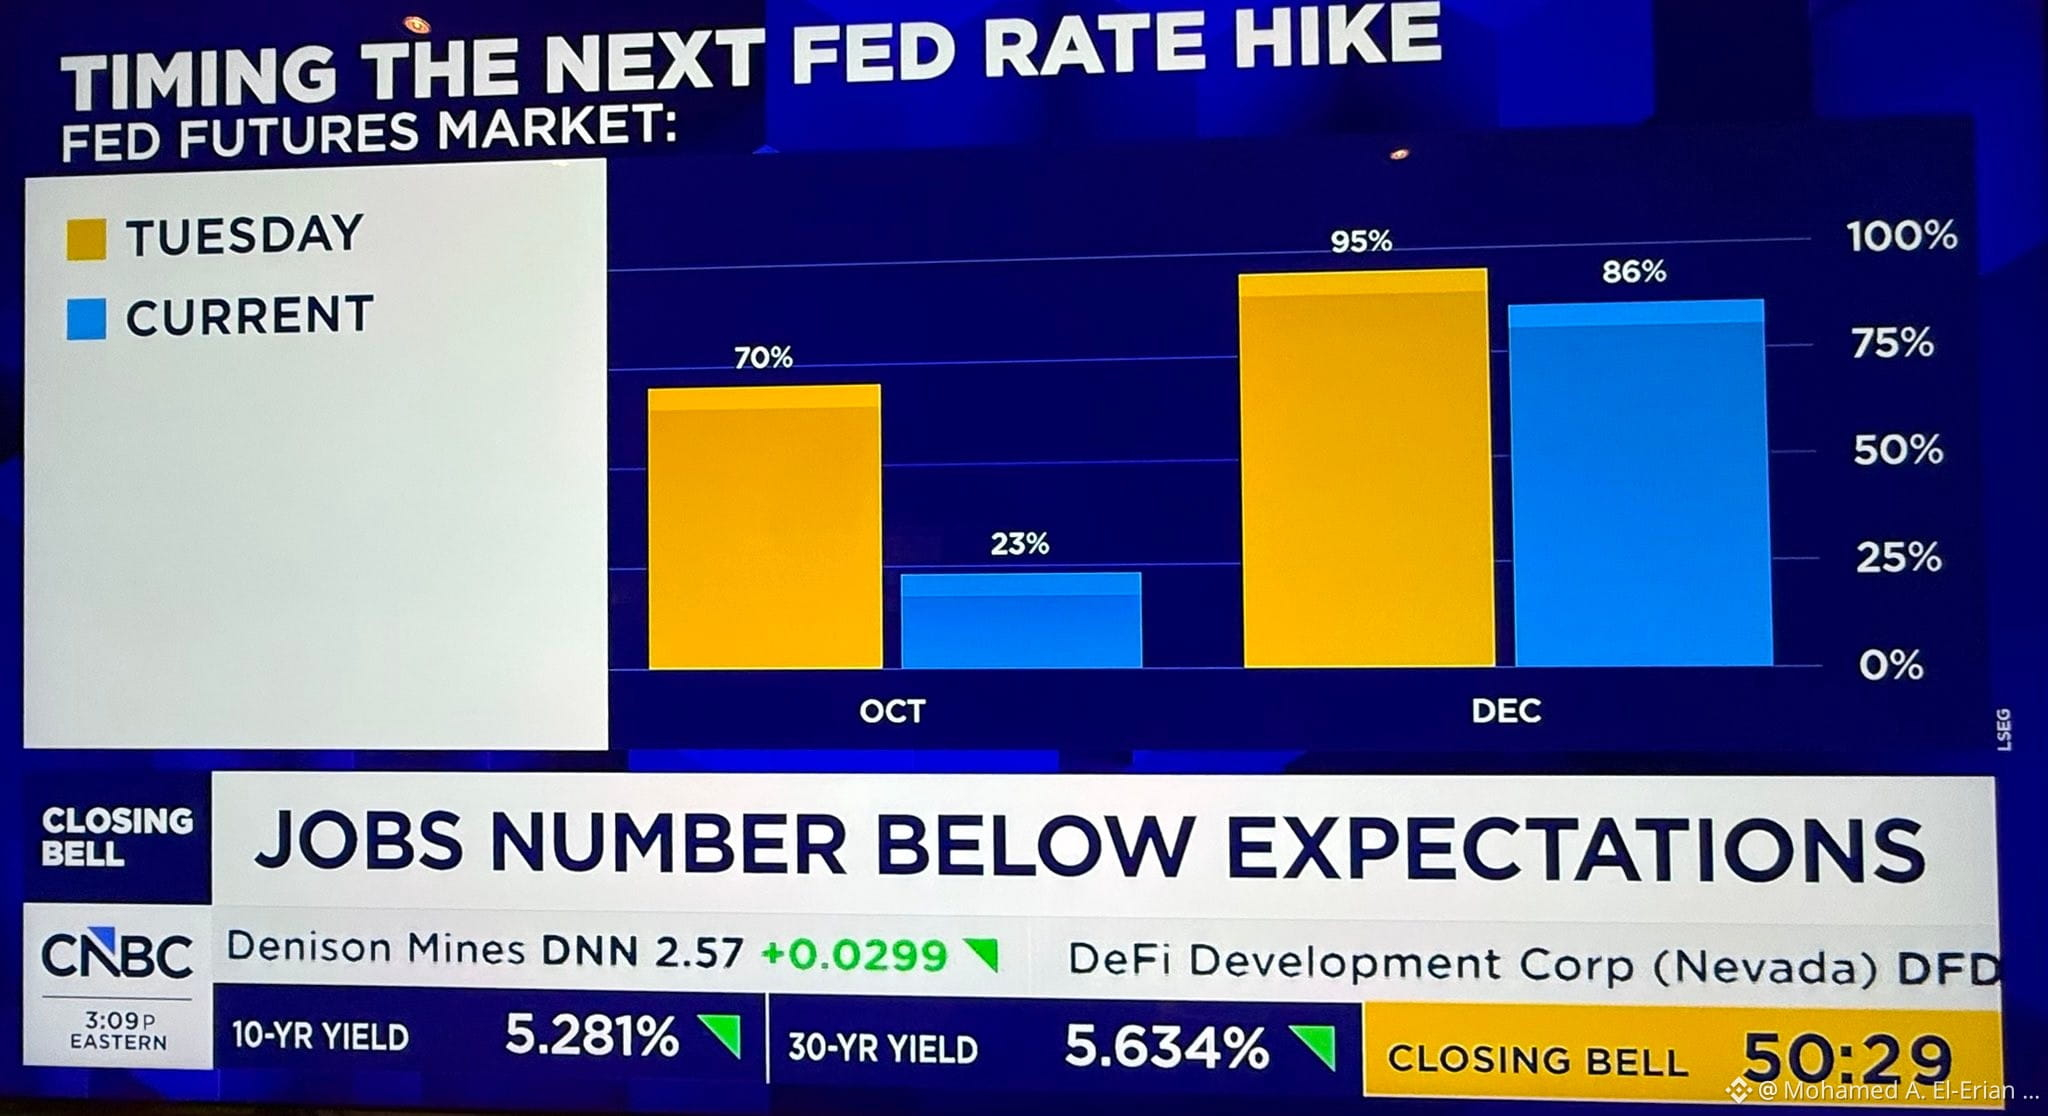
We have seen a major adjustment this week in how the market is pricing upcoming policy decisions from the Federal Reserve. Over the span of just three days, the market-based odds for a rate increase at the October FOMC meeting, which takes place in three weeks, experienced a steep drop from 70% down to 23%, as highlighted by CNBC. In a similar trend, the likelihood of a rate hike taking place on December 9th has also decreased, moving from 95% to 86%.
#economy #markets #federalreserve
#economy #markets #federalreserve
11
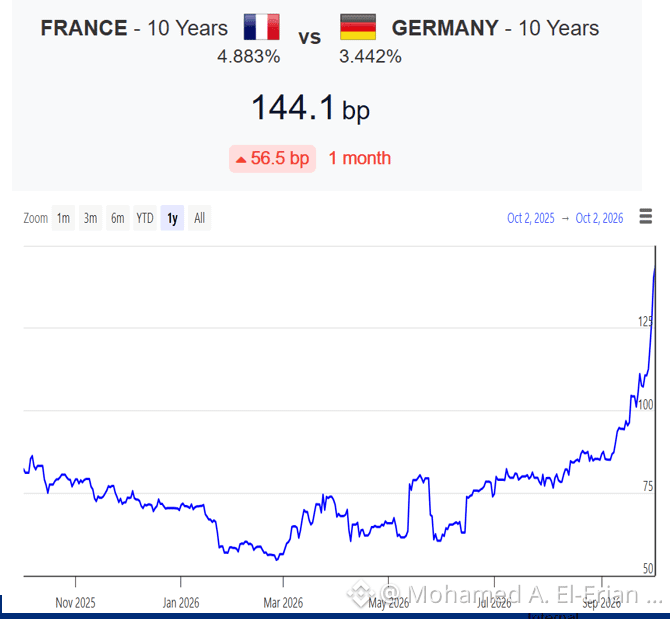
Out of the three most bond-sensitive economies within the G7, a group that also includes Japan and the UK, France is currently capturing the spotlight. This surge in attention comes as we have seen the 10-year yield spread between France and Germany shift by over 50 bps during the past month.
#economy #markets #france #eurozone #europe #bonds #yields
#economy #markets #france #eurozone #europe #bonds #yields
8
For anyone interested in catching up, several web addresses from the discussion that aired this morning on Yahoo Finance are available below for your convenience.
https://finance.yahoo.com/video/jobs-report-definitely-puts-fed-134022850.html
https://finance.yahoo.com/video/theres-fundamental-imbalance-bond-market-150000261.html
https://www.linkedin.com/posts/yahoo-finance_economist-mohamed-el-erian-thinks-its-ridiculous-activity-7511773498000797697-7gvb
#economy #markets #jobs #federalreserve #employment
6
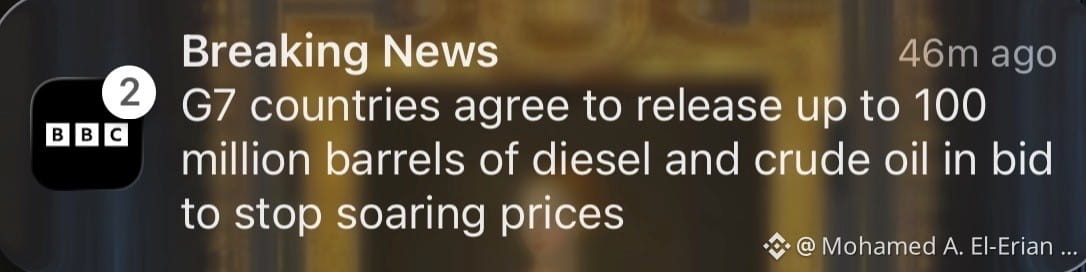
Tapping into strategic reserves provides everyday buyers with a welcome, albeit partial, buffer against skyrocketing costs. Yet, this choice introduces a substantial economic hazard over the long term. Essentially, the leaders of the G7 are taking a massive gamble by hoping that supply levels will stabilize before the heavy winter demand arrives. Looking at the broader landscape, this scenario stands as a prime illustration of how our modern age of geo-economics is constantly shaped by a mix of global tensions and local political motives guiding financial strategy.
#economy #energy #oil #inventories #geoeconomics #markets
#economy #energy #oil #inventories #geoeconomics #markets
433
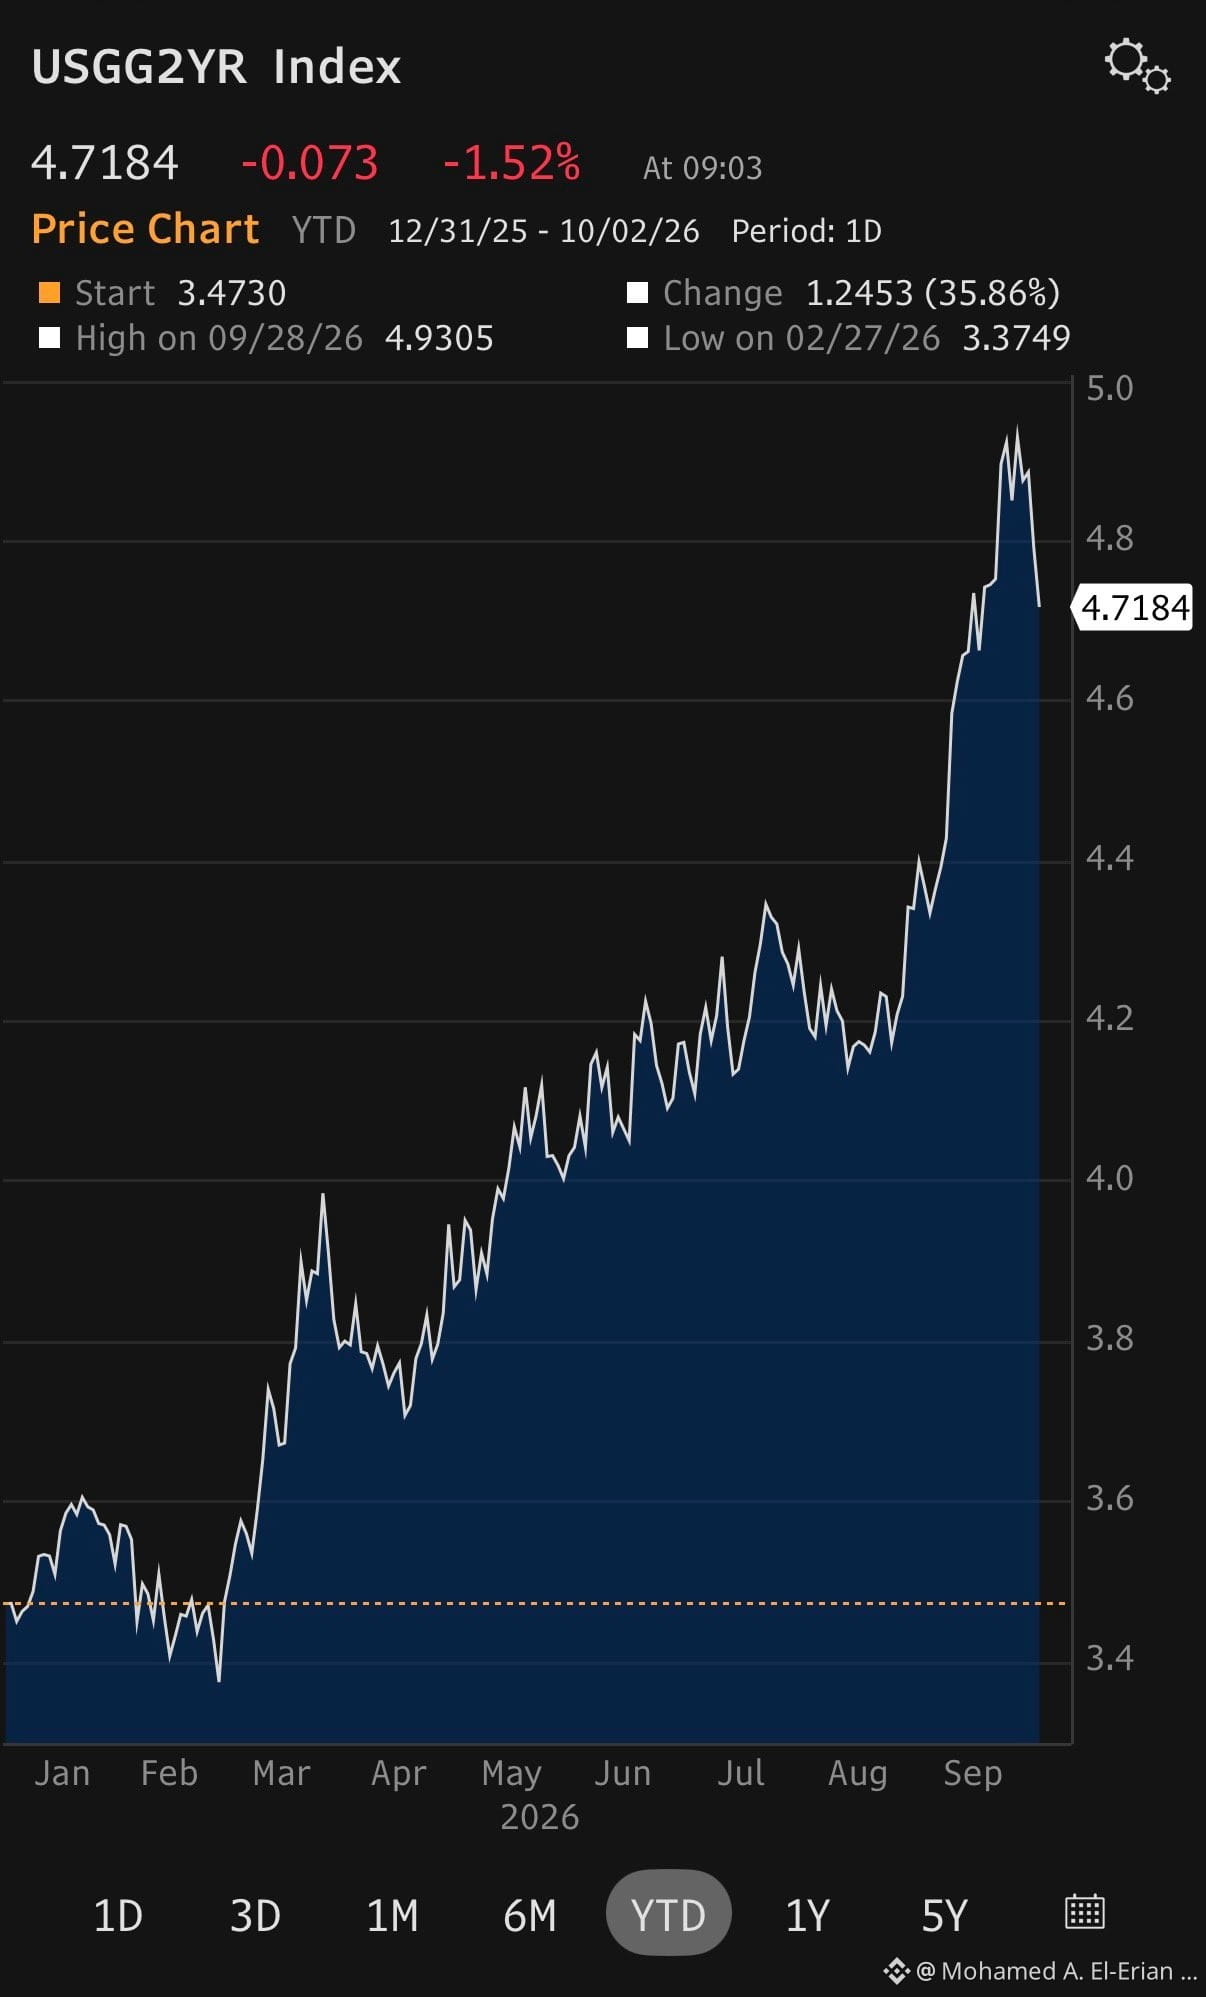
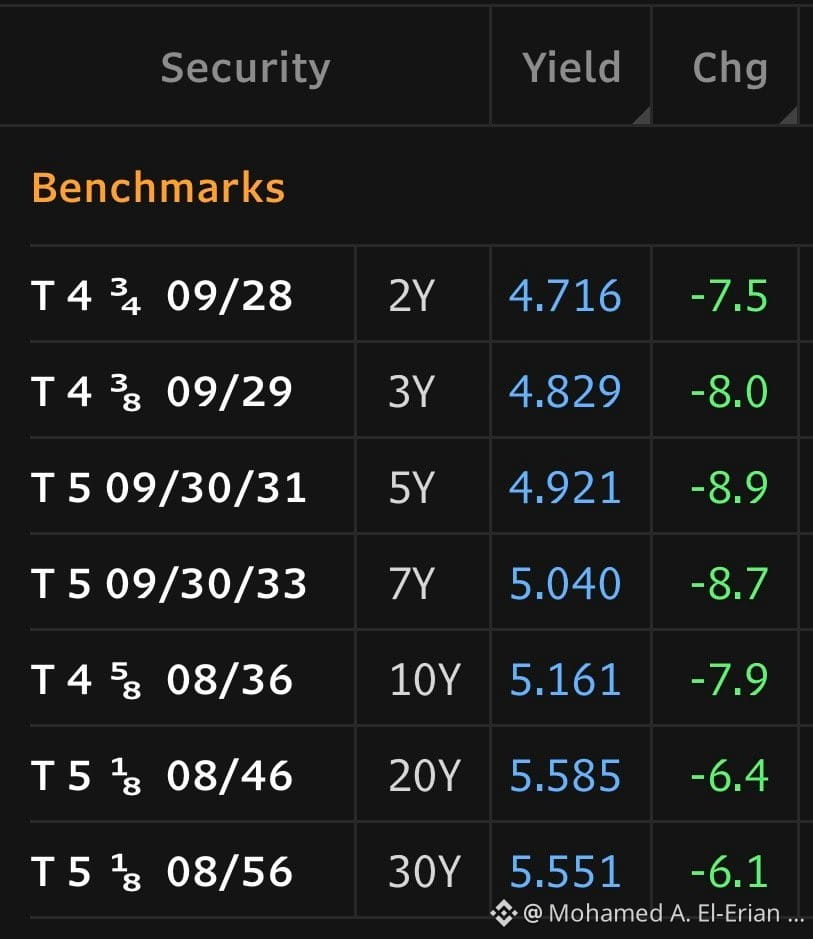
Take a look at how the United States Treasury market is responding to the latest soft jobs report. A key detail to observe is the ongoing pullback in two-year yields, which is taking place as market participants scale back their forecasts for Federal Reserve interest rate increases. Moving forward, the CPI inflation release scheduled for October 14th will act as the next major data catalyst for market activity. The associated figures from Bloomberg can be found just below for your review.
#economy #markets #bonds #inflation
#economy #markets #bonds #inflation
IEFETF-0,27%
8
Although a majority of us are holding out for the national inflation figures from Japan, it is highly probable that the Bank of Japan is closely evaluating the latest Tokyo metrics published overnight. Reaching a peak not seen in 10 months, the core CPI for Tokyo experienced a sharp increase to 2.7%. This recent surge noticeably exceeded both the anticipated consensus forecast of 2.4% and the prior reading of 1.8%.
#economy #japan #inflation #markets
#economy #japan #inflation #markets
6
I have previously shared my concern that risks associated with interest rates could eventually develop into credit and spread risks, and this scenario appears to be unfolding. A recent update from Bloomberg notes a growing sense of hesitation within credit markets. Because of persistent anxieties over unprecedented borrowing levels and ongoing inflation, investors are stepping back from the traditional view that high-grade debt serves as an absolute safe haven.
#economy #markets
#economy #markets
5
Welcome to another US Jobs Friday! As we look at the latest consensus estimates, expectations suggest that September will bring an addition of roughly 85,000 nonfarm payrolls. This represents a noticeable slowdown compared to the growth of 162,000 we experienced in August.
Aside from the primary payroll numbers, forecasters anticipate that the remaining vital metrics will stay completely stable. The unemployment rate is projected to hold its ground at 4.1%, just as the labor force participation rate is expected to remain steady at 61.6%. Regarding wages, average hourly earnings are predicted to show a monthly increase of 0.3%, which translates to a yearly growth rate of 3.1%.
#economy #markets #jobs #employment #unemployment #wages
31
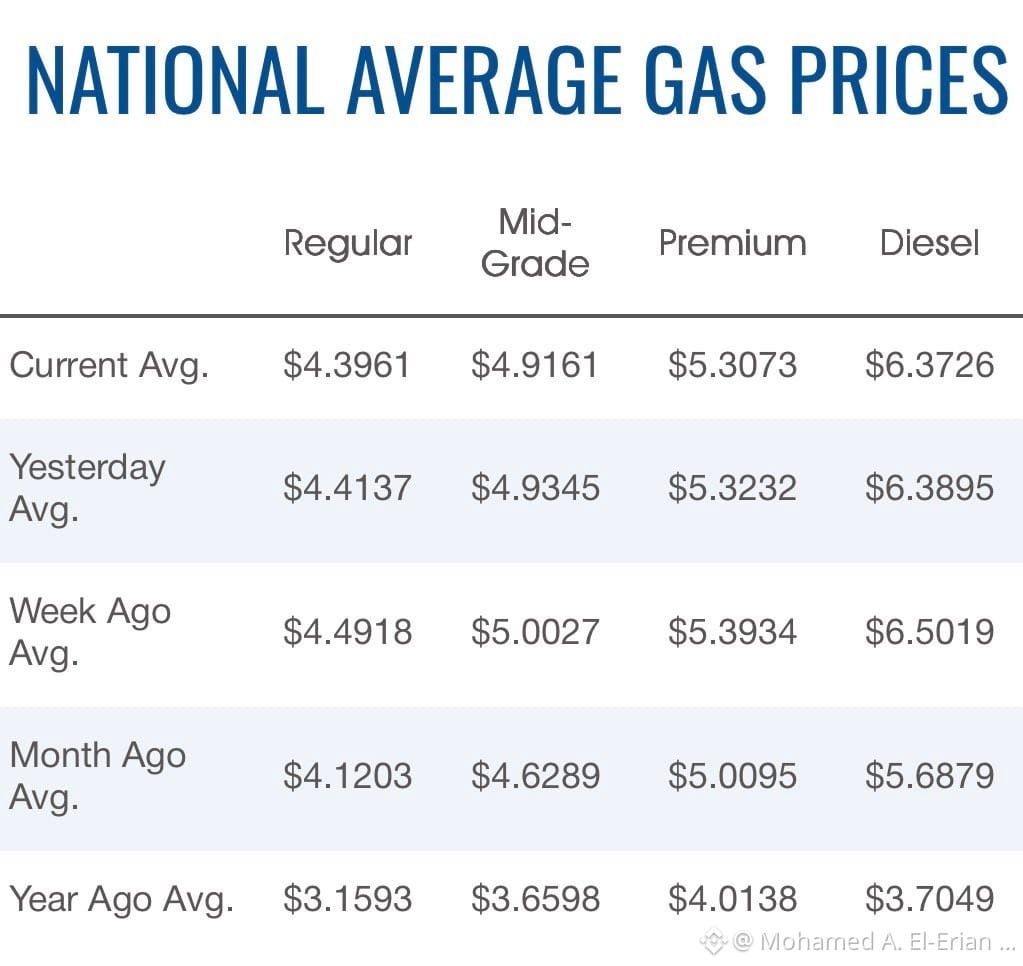
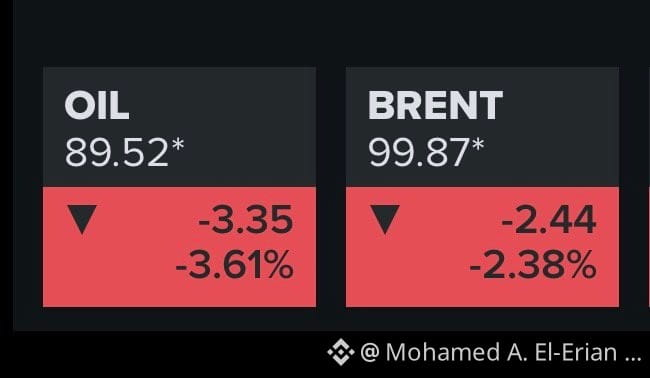
In some of the most significant market shifts from early this morning, Brent crude oil aligned with WTI by dropping beneath the $100 per barrel mark. Furthermore, WTI itself took a deeper dive and slipped below $90. Turning our attention to refined products, the national average cost for a gallon of diesel across the US has decreased to $6.37.
#oil #economy #markets
#oil #economy #markets
189
Turning our attention to Europe, the annual inflation rate across the eurozone climbed to 3.8% in September, up from 3.2% in August. Primarily fueled by escalating energy costs, this latest figure exceeded the consensus forecast of 3.6%. As a result, the ECB is facing increased pressure at a time when regional economies are already working to manage elevated borrowing expenses.
#economy #markets #inflation #europe
#economy #markets #inflation #europe
33
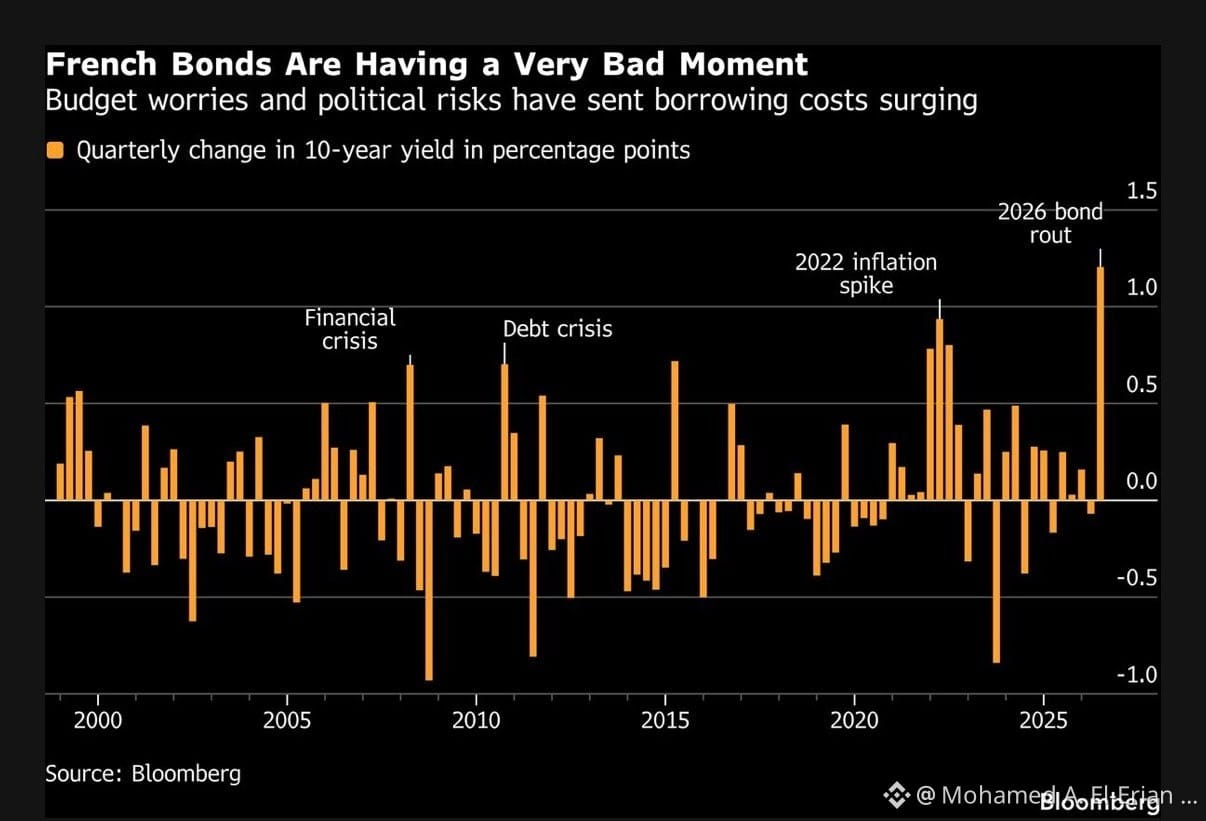
Building on our recent conversations about vulnerabilities within the G7, a new update from Bloomberg provides some eye-opening insights. Since June, the country's 10-year yield has climbed by over a full percentage point, marking its most difficult quarterly period since the introduction of the single currency. At the same time, the extra premium investors are demanding to keep these bonds rather than comparable German bunds has skyrocketed. This gap is currently heading toward an unprecedented weekly expansion.
#economy #markets #france #bonds #yields
#economy #markets #france #bonds #yields
67
An unexpected moment occurred during a recent CNN segment focused on financial markets and the global economy. The serious dialogue took an abrupt and delightful detour straight into the realm of American football, specifically highlighting my favorite franchise, the New York Jets.
@nyjets #jets
An unexpected moment occurred during a recent CNN segment focused on financial markets and the global economy. The serious dialogue took an abrupt and delightful detour straight into the realm of American football, specifically highlighting my favorite franchise, the New York Jets.
@nyjets #jets
@nyjets #jets
87
It is definitely out of the ordinary for the IMF to step forward with a public statement aimed at reassuring everyone that bond markets are functioning in an orderly manner. While the intention is to offer comfort, this highly uncommon move might actually have the opposite effect, potentially sparking more questions than it manages to resolve.
#economy #markets #bonds #yields @IMFNews
#economy #markets #bonds #yields @IMFNews
90
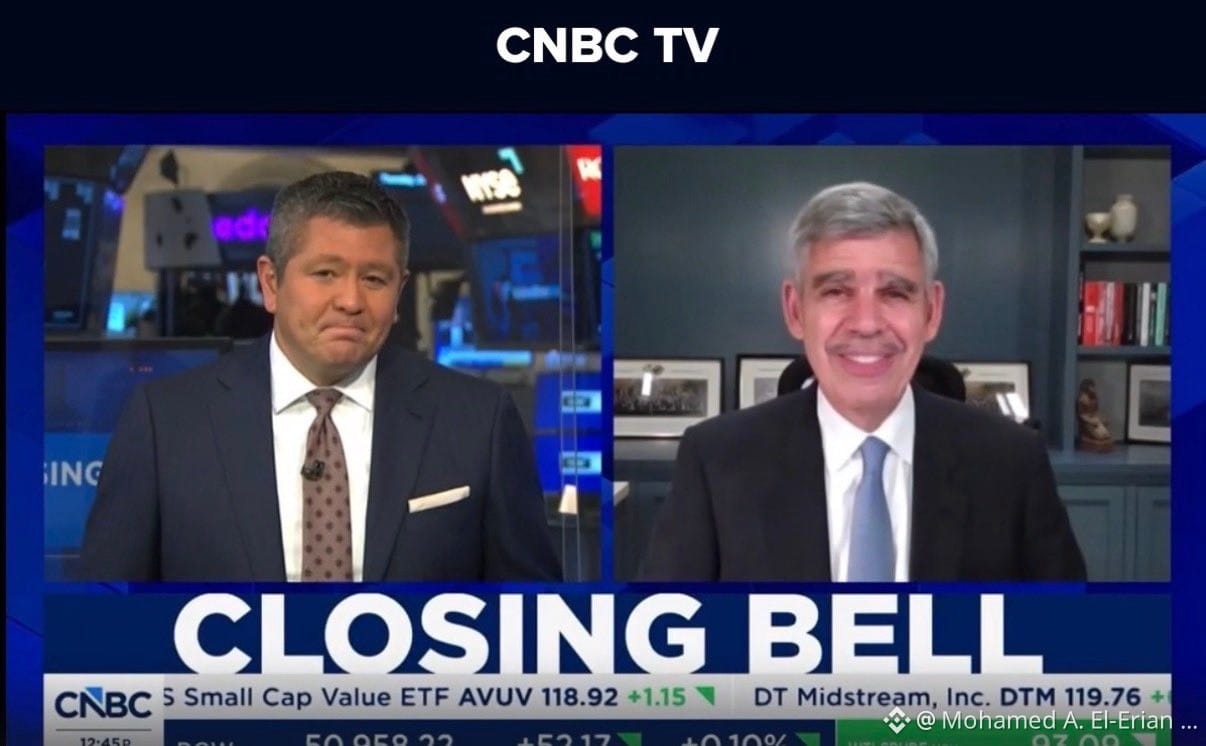
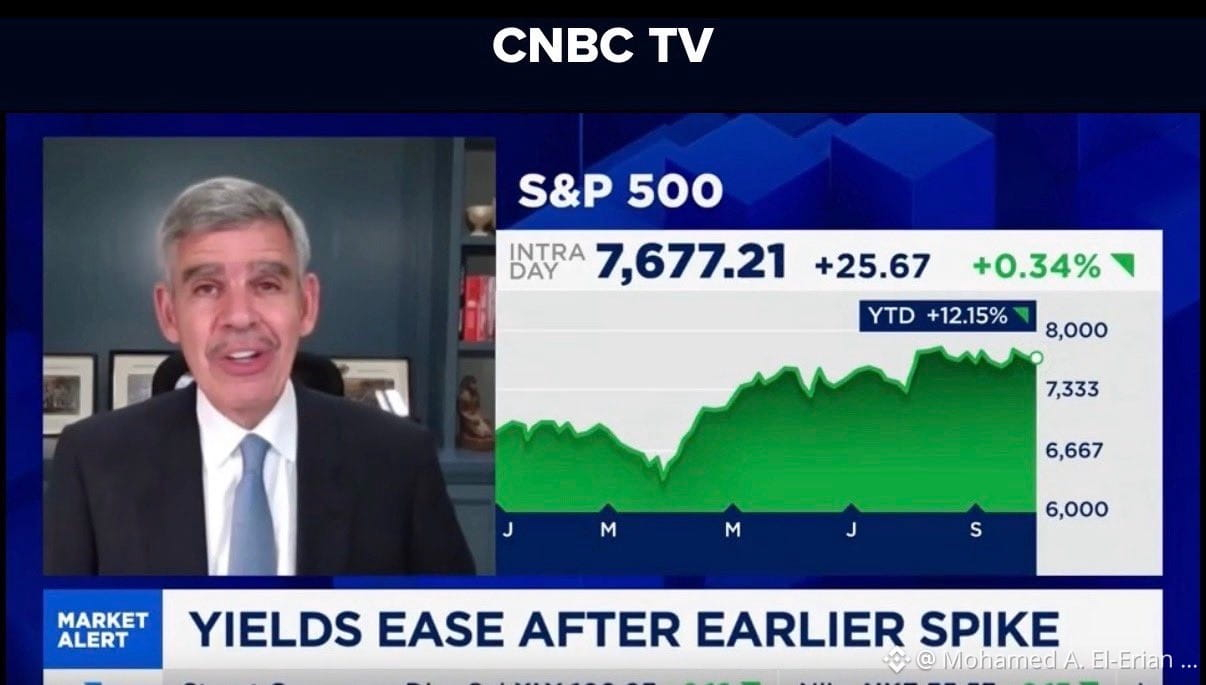
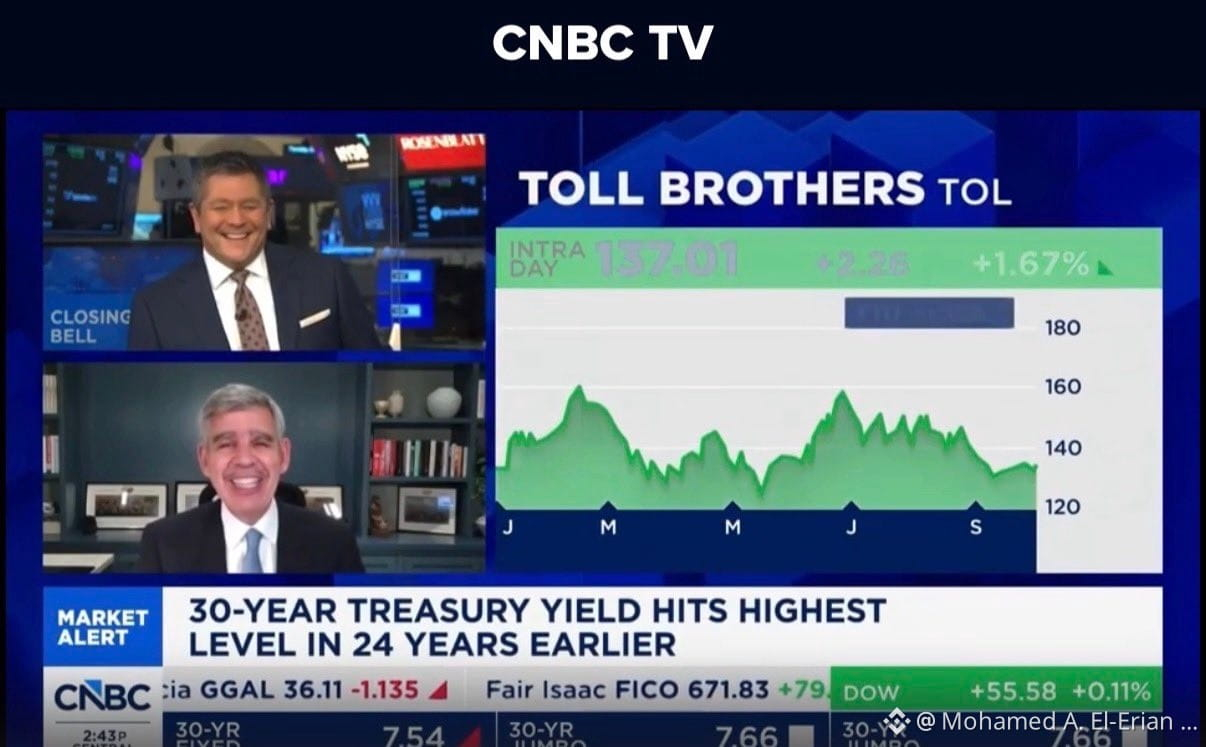
To view my discussion with @carlquintanilla from this afternoon, please follow the web address provided below.
https://www.cnbc.com/video/2026/10/01/allianzs-mohamed-el-erian-on-10-year-yields-easing-back-from-earlier-spike.html
#economy #markets @cnbc @CNBCClosingBell
To view my discussion with @carlquintanilla from this afternoon, please follow the web address provided below.
https://www.cnbc.com/video/2026/10/01/allianzs-mohamed-el-erian-on-10-year-yields-easing-back-from-earlier-spike.html
#economy #markets @cnbc @CNBCClosingBell
https://www.cnbc.com/video/2026/10/01/allianzs-mohamed-el-erian-on-10-year-yields-easing-back-from-earlier-spike.html
#economy #markets @cnbc @CNBCClosingBell
2
A recent update from the FT highlights a challenging moment for American homebuyers, as US mortgage rates have just experienced their sharpest climb in a four-year span. On Thursday, Freddie Mac reported that the standard 30-year fixed-rate mortgage reached an average of 7.28 per cent as of October 1, which represents a noticeable increase of 0.25 percentage points compared to just one week prior. This rapid spike is currently being driven by an accelerating sell-off within the government bond market, delivering yet another setback to the housing sector. Notably, these significant economic shifts are unfolding only a few weeks before the upcoming midterm elections.
#economy #markets #housing #mortgages @ft
#economy #markets #housing #mortgages @ft
5
I greatly appreciate the engaging discussion we shared on Closing Bell, Carl.
#economy #markets @cnbc @CNBCClosingBell @carlquintanilla
I greatly appreciate the engaging discussion we shared on Closing Bell, Carl.
#economy #markets @cnbc @CNBCClosingBell @carlquintanilla
#economy #markets @cnbc @CNBCClosingBell @carlquintanilla
5
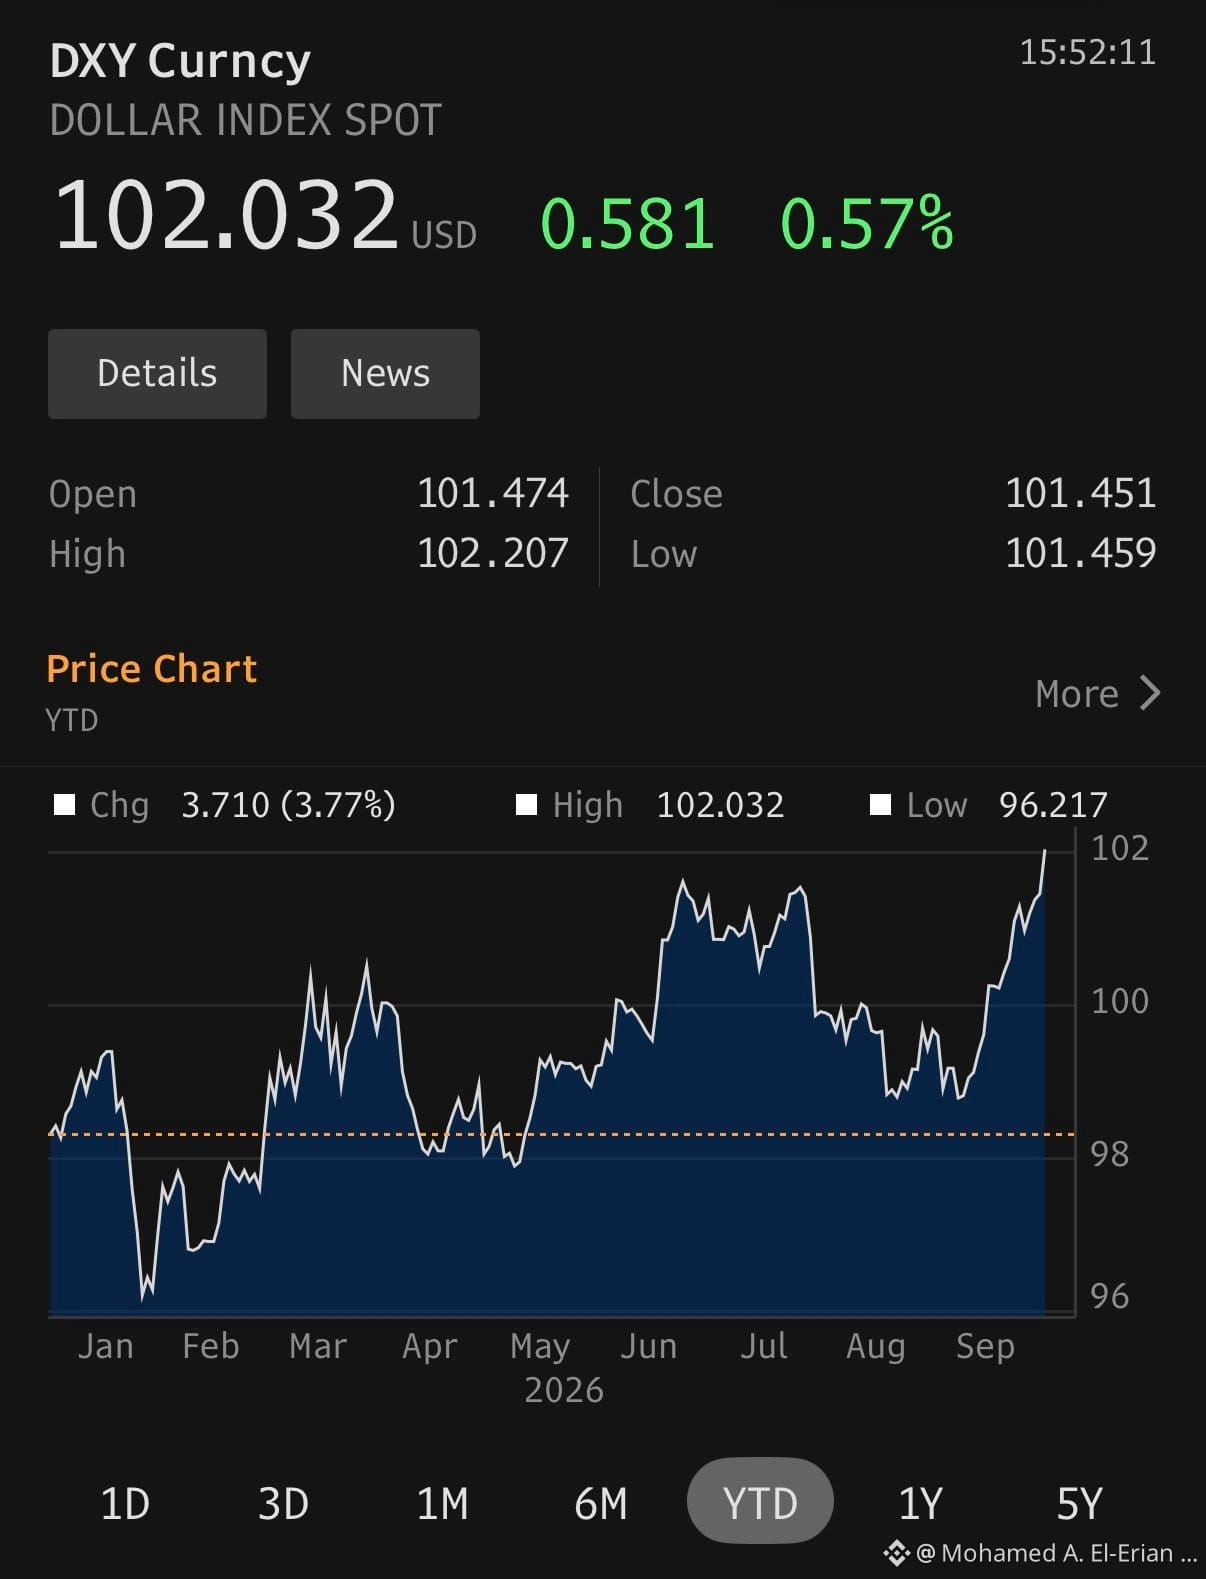
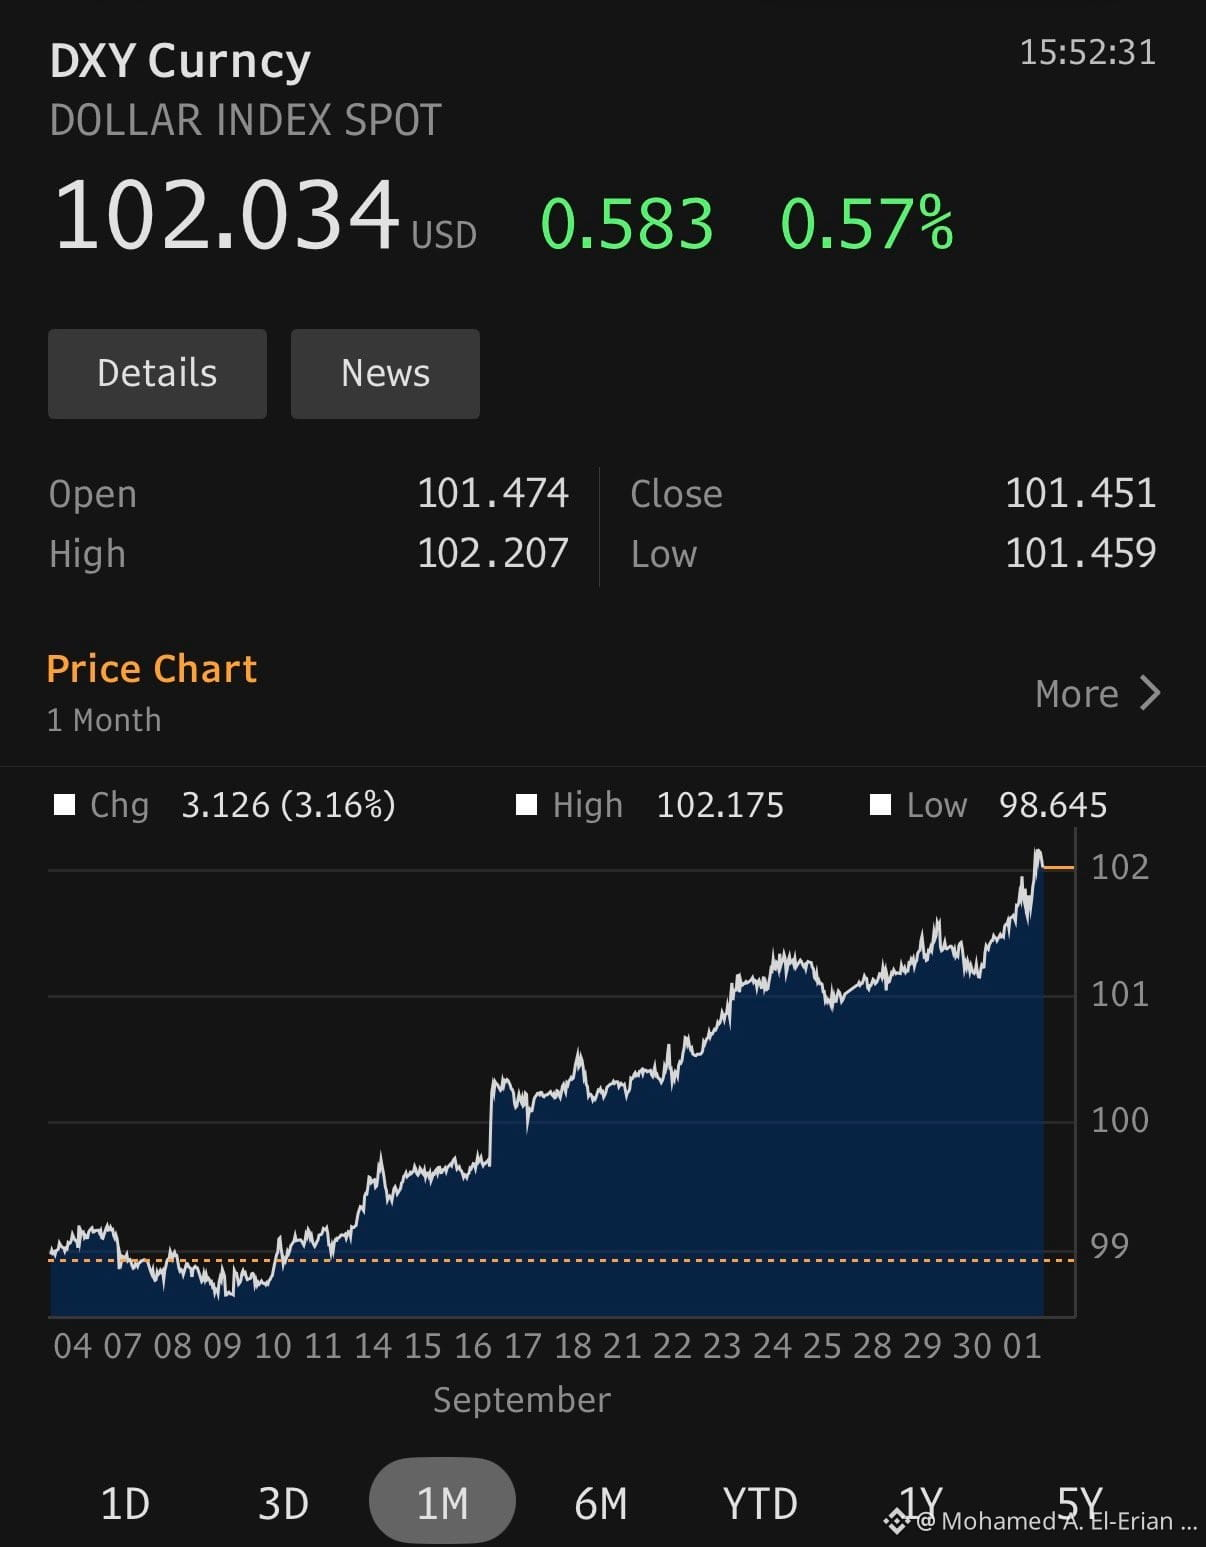
Over the past several weeks, the US Dollar Index (DXY) has experienced a notable upward rally. As a result of this recent momentum, it is currently trading at its highest peak of the entire year. Please refer to the Bloomberg charts provided below for a visual breakdown of these market movements.
#economy #markets #dollar #currency #fx
#economy #markets #dollar #currency #fx
1
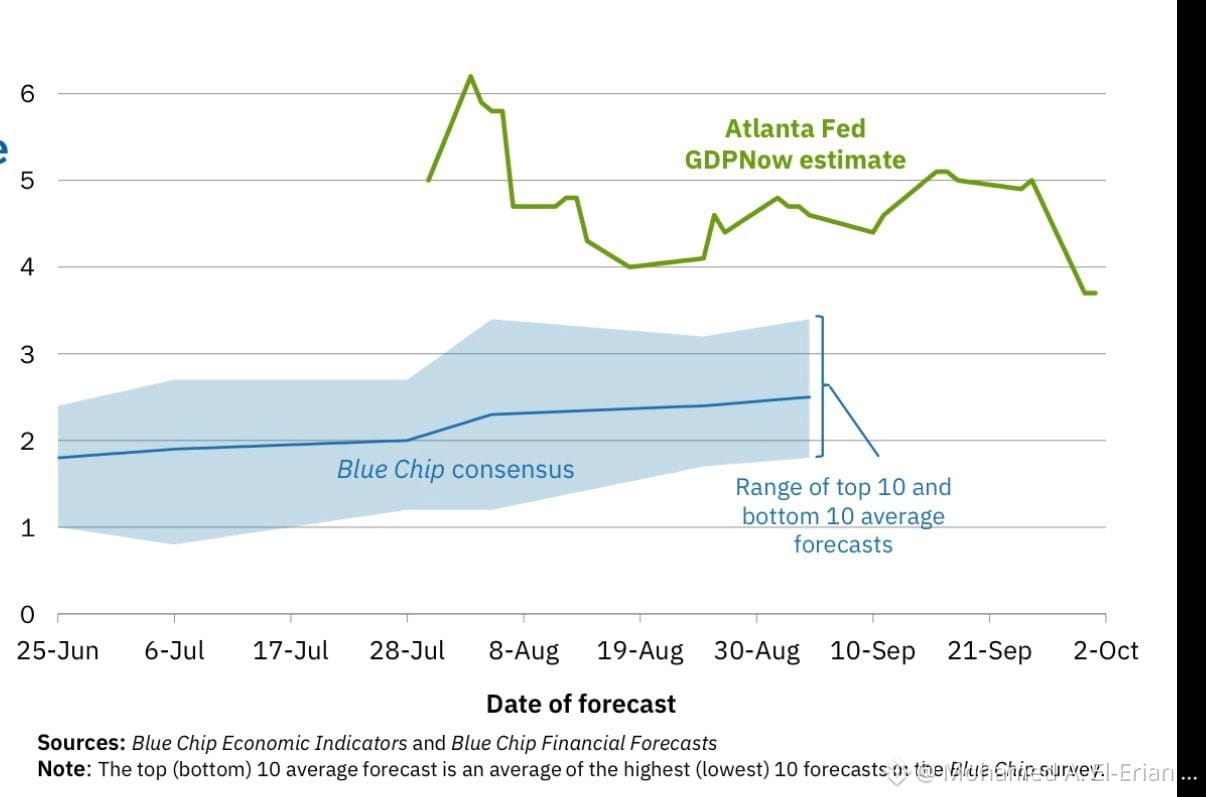
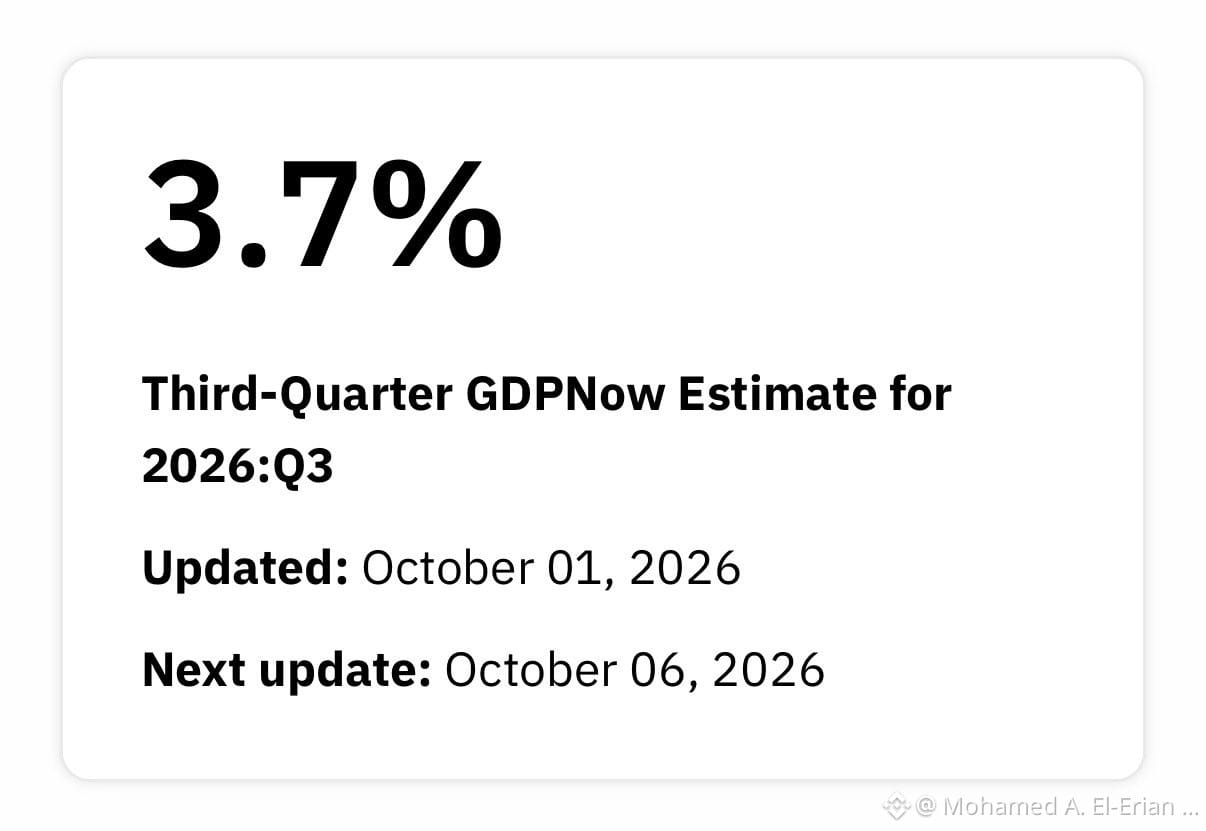
We now have the updated GDP Now forecast from the Atlanta Fed, detailing the expected US economic growth for Q-3.
#economy #growth #markets @AtlantaFed
We now have the updated GDP Now forecast from the Atlanta Fed, detailing the expected US economic growth for Q-3.
#economy #growth #markets @AtlantaFed
#economy #growth #markets @AtlantaFed
16
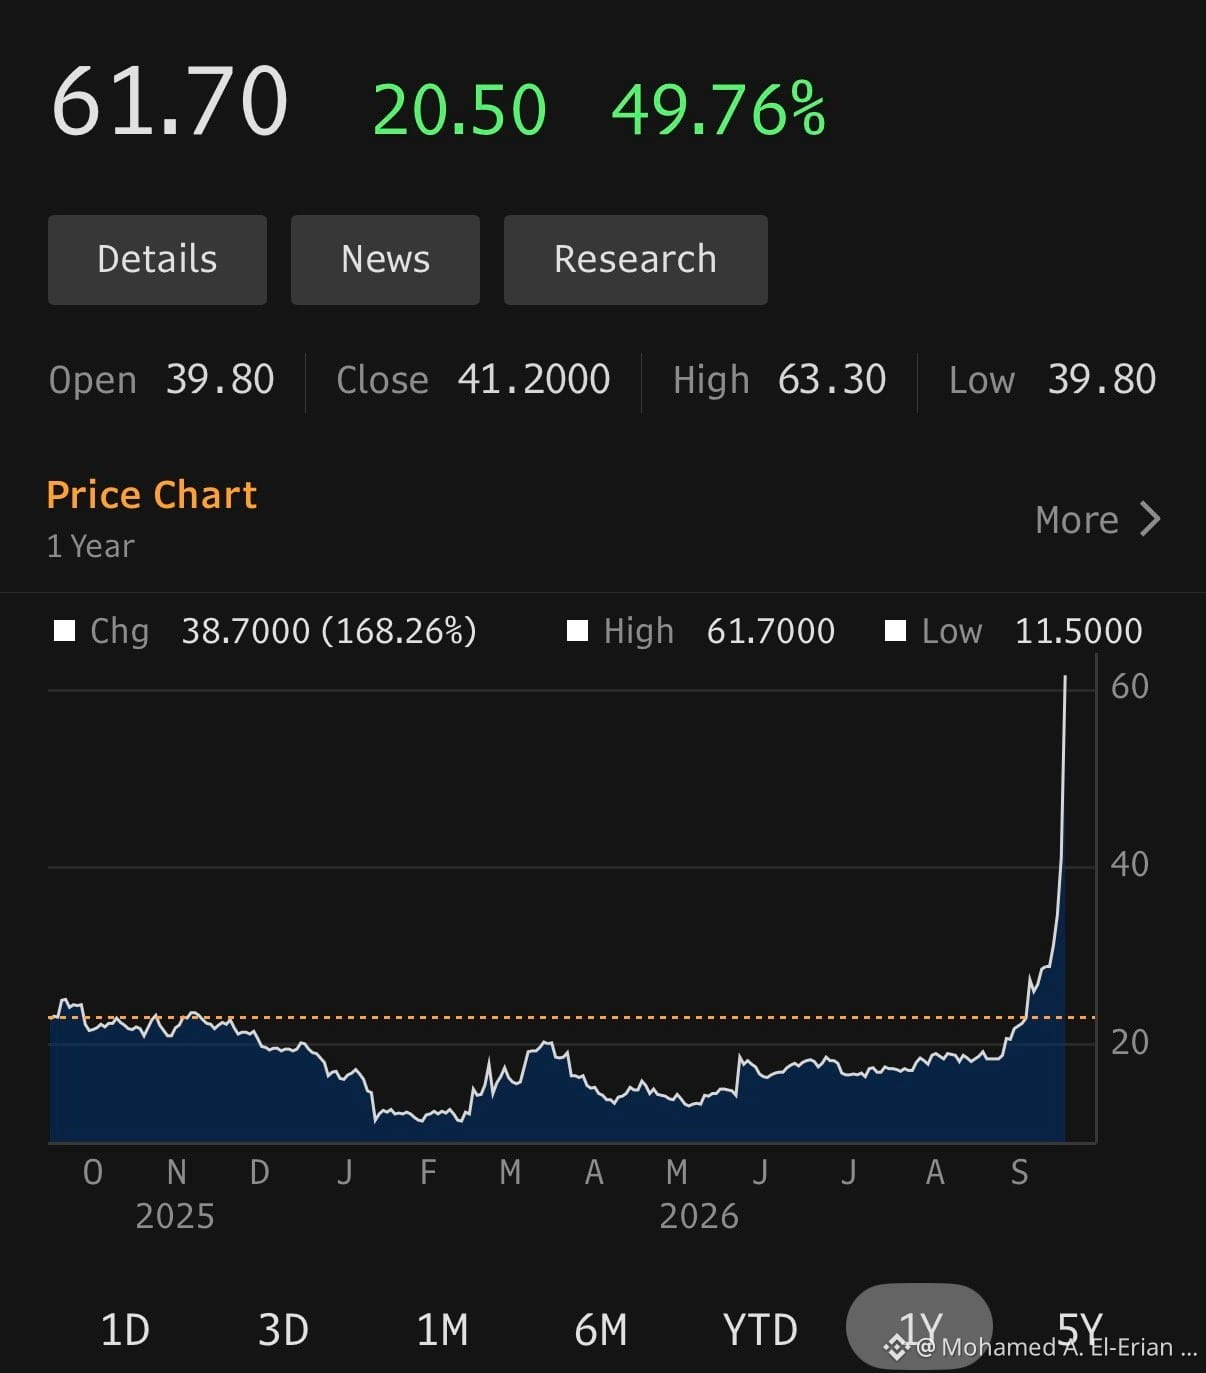
Over in Europe, financial markets are quickly adjusting their views on French sovereign risk. We can see a striking example of this rapid repricing in a recent Bloomberg chart, which shows the 2-year spread between the primary eurozone nations of France and Germany jumping to 62 bps. This movement at the short end of the curve provides a fascinating development. For the past several weeks, observers have understandably fixed their attention on the 10-year France-Germany spread as it expanded well beyond 100 bps. Yet, the current dynamics of the shorter-term bonds are proving to be equally, if not more, compelling.
#economy #bonds #germany #france #markets
#economy #bonds #germany #france #markets
IEFETF-0,27%
23
When examining the current forces shaping US government bond yields, there are a few important observations to keep in mind. First, from a relative valuation perspective, the yields on US Treasuries are looking highly attractive today compared to the sovereign debt of certain other countries. Second, even though the commentary from Federal Reserve officials this week leaned hawkish, their actual tone was noticeably less aggressive than the steep trajectory of interest rate hikes that the financial markets have already factored in.
Additionally, a significant shift in supply and demand has been underway. For several months, I have highlighted a widening gap driven by an influx of higher bond supply meeting reduced demand from traditional, long-term purchasers. However, the most recent jump in yields seems to have pushed past what this imbalance and other primary factors would normally dictate. This exaggerated spike is a dynamic that makes perfect sense when you factor in the increasingly large role that hedge funds are playing within this segment of the market.
Despite the presence of these stabilizing elements, the broader global environment remains complex. Because of ongoing geo-economic crosscurrents, market dispersion and volatility will continue to be dominant themes. Furthermore, I believe the ongoing transition from interest rate risk over to credit risk is a process that has yet to fully run its course.
#economy #markets #bonds #yields
IEFETF-0,27%
34
ເຂົ້າສູ່ລະບົບເພື່ອສຳຫຼວດເນື້ອຫາເພີ່ມເຕີມ
ເຂົ້າຮ່ວມກຸ່ມຜູ້ໃຊ້ຄຣິບໂຕທົ່ວໂລກໃນ Binance Square.
⚡️ ໄດ້ຮັບຂໍ້ມູນຫຼ້າສຸດ ແລະ ທີ່ມີປະໂຫຍດກ່ຽວກັບຄຣິບໂຕ.
💬 ໄດ້ຮັບຄວາມໄວ້ວາງໃຈຈາກຕະຫຼາດແລກປ່ຽນຄຣິບໂຕທີ່ໃຫຍ່ທີ່ສຸດໃນໂລກ.
👍 ຄົ້ນຫາຂໍ້ມູນເຊີງເລິກທີ່ແທ້ຈາກນັກສ້າງທີ່ໄດ້ຮັບການຢືນຢັນ.
ອີເມວ / ເບີໂທລະສັບ
ຫົວຂໍ້ທີ່ກໍາລັງນິຍົມ
BitcoinRejectedAt$87K
35,795 views
74 ກຳລັງສົນທະນາ
$BTC Update 🚨 🐼 Skip THIS Warning at Your Own Risk ⚠️
BTC is knocking on 87K like it already owns the place 😂Bulls are awake… but BTC usually likes to shake a few people out before the real move.
Overall, BTC is breaking out and the higher-timeframe picture is still bullish. The 4H and daily structure are strong, price is holding above the major averages, and momentum is still supporting the move.
83K was honestly a beautiful buy location. That was the area where risk/reward made sense. Anyone who bought there is already sitting enjoying profit
Now come to main
BTC is sitting right under the previous high around 87K. So I would not be surprised if we first see a little downside liquidity grab, flush some late longs, and then BTC decides whether it wants the real breakout.
For today’s scalp, This is my Plan 👇
BTC SHORT scalp Entry: 86,550–86,900
TP1: 85,650
TP2: 84,850
TP3: 84,050
SL: 87,800
I only like this if we get a proper rejection near the highs. No blind shorting.
For the bigger picture, I’m still bullish as long as the 82.5K–83K area keeps holding. If BTC gets a clean breakout and starts accepting above 87.4K, then this whole short idea is invalid and the next bullish leg becomes much more interesting.
SO BASICALLY OCTOBER HISTORICAL IS BULLISH MONTH FOR BITCOIN.
ALWAYS DYOR
Panda Traders
·33 ຖືກໃຈ
·13k views
FedOctoberRateHikeOddsFallTo17%
22,411 views
372 ກຳລັງສົນທະນາ
NvidiaHitsRecordHighUp2.4%
7,139 views
236 ກຳລັງສົນທະນາ