

Genofin
17 ໂພສ
Genofin
ລາຍງານ
ບລັອກຜູ້ໃຊ້
Institutional Quantitative
24/7 Autonomous Execution
Non-Custodial | Binance
1-Click Copy Trade on Binance
genofin.tech
ຜູ້ຊື້ຂາຍຊົ່ວຄາວ
5.6 ປີ
0 ກໍາລັງຕິດຕາມ
21 ຜູ້ຕິດຕາມ
11 Liked
ໂພສ
ທັງໝົດ
ວີດີໂອ
·
--
Institutional order flow is governed by options market maker positioning. When dealer gamma exposure transitions into heavily positive regimes, dynamic delta hedging acts as a systemic shock absorber, systematically compressing realized volatility and pinning spot prices to key strike clusters. Understanding structural GEX metrics allows quantitative traders to anticipate volatility regime shifts before they materialize. #Binance #Crypto.
Institutional order flow is governed by options market maker positioning. When dealer gamma exposure transitions into heavily positive regimes, dynamic delta hedging acts as a systemic shock absorber, systematically compressing realized volatility and pinning spot prices to key strike clusters. Understanding structural GEX metrics allows quantitative traders to anticipate volatility regime shifts before they materialize. #Binance #Crypto.
1
2
2.1k
·
--
Market makers aren't predicting prices—they're pinning them.
When Dealer Gamma Exposure flips positive, market makers are forced to suppress volatility and pin strikes. Learn how institutional flow dictates market structure at genofin.tech.
Market makers aren't predicting prices—they're pinning them.
When Dealer Gamma Exposure flips positive, market makers are forced to suppress volatility and pin strikes. Learn how institutional flow dictates market structure at genofin.tech.
When Dealer Gamma Exposure flips positive, market makers are forced to suppress volatility and pin strikes. Learn how institutional flow dictates market structure at genofin.tech.
1
3
2k
·
--
Dealer GEX is locking spot into a volatility trap.
• +$4.2B Net GEX at 5100 strike
• 78% structural pin probability
Track the flow: NFA. genofin.tech
Dealer GEX is locking spot into a volatility trap.
• +$4.2B Net GEX at 5100 strike
• 78% structural pin probability
Track the flow: NFA. genofin.tech
• +$4.2B Net GEX at 5100 strike
• 78% structural pin probability
Track the flow: NFA. genofin.tech
6
·
--
Daily Dispatch: BTC Gamma Exposure, Strike Pinning & Volatility Surface Architecture📊 EXECUTIVE SUMMARY
BTC consolidates at $85,226 amid compressed 34.7% DVOL as positive dealer gamma enforces structural pinning. Institutional block flow confirms synthetic accumulation, sharply diverging from retail macro anxiety.
━━━ 1. Executive Summary & Volatility Regime ━━━
Bitcoin (BTC) navigates a compressed structural regime, changing hands at $85,226.01 (+0.49%) as Ethereum (ETH) and Solana (SOL) trace parallel consolidations at $2,699.07 (+0.76%) and $121.60 (+1.80%), respectively. The central narrative across digital asset derivatives is marked by systemic implied volatility compression: the 30-day Deribit Implied Volatility Index (DVOL) has drifted to 34.73%, resting in its lower quartile relative to trailing twelve-month distributions.
Cross-asset telemetry indicates an intriguing macroeconomic divergence. Despite the US 10-Year Treasury Yield sustaining elevated levels at 5.18% and the US Dollar Index (DXY) consolidating near 100.97, the CBOE VIX sits subdued at 14.87. Market Sentiment prints a robust Greed (74/100). US spot order books reflect persistent, positive delta aggression—visible in steady Coinbase spot premiums—suggesting systematic institutional absorption rather than retail speculative froth.
━━━ 2. Previous Day Market Wrap & Institutional Liquidity Brief ━━━
Following yesterday's US equities close, digital assets displayed muted beta to traditional risk proxies. While sovereign yields pushed higher on renewed fiscal deficit projections, overnight APAC and European sessions exhibited passive limit-order absorption on Binance Futures order books, preventing localized structural pullbacks.
A stark divergence has emerged between retail content creator consensus and empirical order-flow reality. While high-subscriber retail macro commentators highlight impending systemic contraction—focusing on labor market statistical degradation and sovereign debt saturation—institutional desks continue systematic balance-sheet allocations. This structural reality was reinforced on the tape by El Salvador securing a $138 million IMF disbursement with Bitcoin waivers maintained, and speculative positioning around pragmatic domestic regulatory stewardship under emerging federal leadership. Passive institutional TWAP algorithms continue to dominate liquidity aggregates, systematically accumulating during localized basis dips.
━━━ 3. 24h Trade Flow & Options Intelligence ━━━
Institutional flow across the options complex reveals distinct asymmetry between high-frequency retail flows and institutional block trades. Over the past 24 hours, block trade flow represented more than 56% of aggregate gross premium traded, predominantly concentrated in cross-calendar call diagonal spreads and covered overwriting.
• Call Flow Analysis: Sustained institutional selling of out-of-the-money (OTM) calls between the $90,000 and $95,000 strikes across near-dated expiries, indicating that yield-enhancement overwriters remain comfortable establishing localized caps.
• Put Flow Analysis: Institutional put buying has been conspicuously scarce below the $80,000 strike. Downside tail protection remains historically cheap, yet fund desks show minimal appetite to bid up downside skew, keeping put-call premium skews relatively flat to slightly call-biased.
• Block Activity: Notable bilateral block transactions involved roll-ups of synthetic long futures positions into delta-neutral risk reversals, harvesting compressed implied volatility while maintaining exposure to spot expansion.
━━━ 4. Derivative Structure, Strike Walls & Dealer Gamma Pinning ━━━
Dealer Gamma Exposure (GEX) analysis underscores why spot price action remains trapped in a narrow corridor. Derivatives market makers currently sit in a regime of deep positive gamma (Long GEX) within the $83,000 to $88,000 strike band. When market makers are net long gamma, their delta-hedging mandate requires counter-trend execution: selling spot into upward momentum and aggressively bidding spot as prices decline.
━━━ Gamma Clustering and Strike Distribution ━━━
The derivative landscape reveals critical structural boundaries shaping spot liquidity:
• Upper Call Wall ($90,000): Represents the primary concentration of positive dealer gamma. Any sharp rally toward this zone faces intense structural resistance as dealers dynamically hedge by selling underlying futures.
• Major Put Floor ($80,000): Anchors systemic support. A high concentration of open interest puts creates a natural liquidity cushion above key psychological levels.
• Max Pain Magnet ($84,000): Near-term expiries exhibit Max Pain coalescing around the $84,000 mark. The combination of dealer long gamma and option decay creates an algorithmic pinning effect around the $85,000 axis.
Until a macro or spot liquidity catalyst forces spot beyond the $88,500 threshold—where dealer gamma rapidly flips negative—volatility dampening will remain the dominant structural regime.
━━━ 5. Strategic Scenario Matrix & Tactical Horizons ━━━
Our quantitative scenario engine models three probabilistic paths for the dominant upcoming expiries:
• Base Case (65% Probability) — Structural Strike Pinning ($83,500 – $87,000): Realized volatility tracks sub-30% levels as positive dealer gamma dampens breakout attempts. Spot oscillates around the $85,000 Max Pain gravitational node. Tactical Gameplay: Mean-reversion scalping and short-dated vega harvesting.
• Bull Case (20% Probability) — Negative Gamma Flip Breakout ($88,500+): Accelerated spot volume triggers a gamma flip above $88,500, converting dealer rebalancing from dampening into an accelerant (short-covering). Target liquidity cluster: $92,500. Tactical Gameplay: Convex call breakout participation on Binance Futures perpetual pairs.
• Bear Case (15% Probability) — Macro Yield Exhaustion ($80,000 Breakdown): An unexpected acceleration in global bond yields destabilizes the risk-asset complex, pushing spot through the $82,000 structural support floor and exposing the $80,000 put wall. Tactical Gameplay: Delta-neutral downside synthetic shorting with strictly defined volatility stops.
━━━ 6. Master Systematic Execution & Non-Custodial Copy Trading ━━━
Genofin’s proprietary suite of 5 complementary quantitative models is systematically configured to monetize this structural gamma-pinning and compressed volatility regime on Binance Futures without requiring discretionary intervention:
• Supertrend Volatility DCA: Operates with contracted threshold parameters, accumulating small, staggered spot and perpetual long positions within the $83,800–$84,600 liquidity pocket with algorithmic limit orders.
• RSI Exhaustion Scalping: Thrives in range-bound positive GEX environments, generating high-Sharpe short-horizon trades by fading localized momentum extremes on the 5-minute and 15-minute timeframe order books.
• Wick Harvesting: Harvests synthetic inefficiencies by placing passive bids and asks outside the immediate gamma cluster, capturing flash sweeps caused by thin order book micro-liquidity.
• Joan Trend Rider: Remains in capital-preservation standby, dynamically trailing structural invalidation stops to ensure momentum capital is not eroded during sideways chop.
• DVOL Hedging: Exploits the suppressed 34.73% implied volatility profile by executing delta-neutral variance capture and curve-relative basis trades, protecting firm capital against tail-risk volatility expansion.
System Invalidation Criteria: All systematic models enforce non-negotiable risk limits. A 4-hour candle close below $81,800 triggers an automated derisking sequence across the momentum cluster, shifting execution into pure dynamic capital protection.
Institutional allocators and qualified participants can track and replicate these algorithmic execution profiles via our non-custodial, high-frequency copy trading infrastructure directly on Binance Futures by visiting Genofin Quant Desk.
Notice: This research dispatch is prepared strictly for informational and quantitative analytical purposes and does not constitute financial, investment, or trading advice (NFA). Digital asset derivatives and algorithmic futures trading involve significant counterparty, systemic, and execution risks.
#Bitcoin #Crypto #Binance
Daily Dispatch: BTC Gamma Exposure, Strike Pinning & Volatility Surface Architecture
📊 EXECUTIVE SUMMARY
BTC consolidates at $85,226 amid compressed 34.7% DVOL as positive dealer gamma enforces structural pinning. Institutional block flow confirms synthetic accumulation, sharply diverging from retail macro anxiety.
━━━ 1. Executive Summary & Volatility Regime ━━━
Bitcoin (BTC) navigates a compressed structural regime, changing hands at $85,226.01 (+0.49%) as Ethereum (ETH) and Solana (SOL) trace parallel consolidations at $2,699.07 (+0.76%) and $121.60 (+1.80%), respectively. The central narrative across digital asset derivatives is marked by systemic implied volatility compression: the 30-day Deribit Implied Volatility Index (DVOL) has drifted to 34.73%, resting in its lower quartile relative to trailing twelve-month distributions.
Cross-asset telemetry indicates an intriguing macroeconomic divergence. Despite the US 10-Year Treasury Yield sustaining elevated levels at 5.18% and the US Dollar Index (DXY) consolidating near 100.97, the CBOE VIX sits subdued at 14.87. Market Sentiment prints a robust Greed (74/100). US spot order books reflect persistent, positive delta aggression—visible in steady Coinbase spot premiums—suggesting systematic institutional absorption rather than retail speculative froth.
━━━ 2. Previous Day Market Wrap & Institutional Liquidity Brief ━━━
Following yesterday's US equities close, digital assets displayed muted beta to traditional risk proxies. While sovereign yields pushed higher on renewed fiscal deficit projections, overnight APAC and European sessions exhibited passive limit-order absorption on Binance Futures order books, preventing localized structural pullbacks.
A stark divergence has emerged between retail content creator consensus and empirical order-flow reality. While high-subscriber retail macro commentators highlight impending systemic contraction—focusing on labor market statistical degradation and sovereign debt saturation—institutional desks continue systematic balance-sheet allocations. This structural reality was reinforced on the tape by El Salvador securing a $138 million IMF disbursement with Bitcoin waivers maintained, and speculative positioning around pragmatic domestic regulatory stewardship under emerging federal leadership. Passive institutional TWAP algorithms continue to dominate liquidity aggregates, systematically accumulating during localized basis dips.
━━━ 3. 24h Trade Flow & Options Intelligence ━━━
Institutional flow across the options complex reveals distinct asymmetry between high-frequency retail flows and institutional block trades. Over the past 24 hours, block trade flow represented more than 56% of aggregate gross premium traded, predominantly concentrated in cross-calendar call diagonal spreads and covered overwriting.
• Call Flow Analysis: Sustained institutional selling of out-of-the-money (OTM) calls between the $90,000 and $95,000 strikes across near-dated expiries, indicating that yield-enhancement overwriters remain comfortable establishing localized caps.
• Put Flow Analysis: Institutional put buying has been conspicuously scarce below the $80,000 strike. Downside tail protection remains historically cheap, yet fund desks show minimal appetite to bid up downside skew, keeping put-call premium skews relatively flat to slightly call-biased.
• Block Activity: Notable bilateral block transactions involved roll-ups of synthetic long futures positions into delta-neutral risk reversals, harvesting compressed implied volatility while maintaining exposure to spot expansion.
━━━ 4. Derivative Structure, Strike Walls & Dealer Gamma Pinning ━━━
Dealer Gamma Exposure (GEX) analysis underscores why spot price action remains trapped in a narrow corridor. Derivatives market makers currently sit in a regime of deep positive gamma (Long GEX) within the $83,000 to $88,000 strike band. When market makers are net long gamma, their delta-hedging mandate requires counter-trend execution: selling spot into upward momentum and aggressively bidding spot as prices decline.
━━━ Gamma Clustering and Strike Distribution ━━━
The derivative landscape reveals critical structural boundaries shaping spot liquidity:
• Upper Call Wall ($90,000): Represents the primary concentration of positive dealer gamma. Any sharp rally toward this zone faces intense structural resistance as dealers dynamically hedge by selling underlying futures.
• Major Put Floor ($80,000): Anchors systemic support. A high concentration of open interest puts creates a natural liquidity cushion above key psychological levels.
• Max Pain Magnet ($84,000): Near-term expiries exhibit Max Pain coalescing around the $84,000 mark. The combination of dealer long gamma and option decay creates an algorithmic pinning effect around the $85,000 axis.
Until a macro or spot liquidity catalyst forces spot beyond the $88,500 threshold—where dealer gamma rapidly flips negative—volatility dampening will remain the dominant structural regime.
━━━ 5. Strategic Scenario Matrix & Tactical Horizons ━━━
Our quantitative scenario engine models three probabilistic paths for the dominant upcoming expiries:
• Base Case (65% Probability) — Structural Strike Pinning ($83,500 – $87,000): Realized volatility tracks sub-30% levels as positive dealer gamma dampens breakout attempts. Spot oscillates around the $85,000 Max Pain gravitational node. Tactical Gameplay: Mean-reversion scalping and short-dated vega harvesting.
• Bull Case (20% Probability) — Negative Gamma Flip Breakout ($88,500+): Accelerated spot volume triggers a gamma flip above $88,500, converting dealer rebalancing from dampening into an accelerant (short-covering). Target liquidity cluster: $92,500. Tactical Gameplay: Convex call breakout participation on Binance Futures perpetual pairs.
• Bear Case (15% Probability) — Macro Yield Exhaustion ($80,000 Breakdown): An unexpected acceleration in global bond yields destabilizes the risk-asset complex, pushing spot through the $82,000 structural support floor and exposing the $80,000 put wall. Tactical Gameplay: Delta-neutral downside synthetic shorting with strictly defined volatility stops.
━━━ 6. Master Systematic Execution & Non-Custodial Copy Trading ━━━
Genofin’s proprietary suite of 5 complementary quantitative models is systematically configured to monetize this structural gamma-pinning and compressed volatility regime on Binance Futures without requiring discretionary intervention:
• Supertrend Volatility DCA: Operates with contracted threshold parameters, accumulating small, staggered spot and perpetual long positions within the $83,800–$84,600 liquidity pocket with algorithmic limit orders.
• RSI Exhaustion Scalping: Thrives in range-bound positive GEX environments, generating high-Sharpe short-horizon trades by fading localized momentum extremes on the 5-minute and 15-minute timeframe order books.
• Wick Harvesting: Harvests synthetic inefficiencies by placing passive bids and asks outside the immediate gamma cluster, capturing flash sweeps caused by thin order book micro-liquidity.
• Joan Trend Rider: Remains in capital-preservation standby, dynamically trailing structural invalidation stops to ensure momentum capital is not eroded during sideways chop.
• DVOL Hedging: Exploits the suppressed 34.73% implied volatility profile by executing delta-neutral variance capture and curve-relative basis trades, protecting firm capital against tail-risk volatility expansion.
System Invalidation Criteria: All systematic models enforce non-negotiable risk limits. A 4-hour candle close below $81,800 triggers an automated derisking sequence across the momentum cluster, shifting execution into pure dynamic capital protection.
Institutional allocators and qualified participants can track and replicate these algorithmic execution profiles via our non-custodial, high-frequency copy trading infrastructure directly on Binance Futures by visiting Genofin Quant Desk.
Notice: This research dispatch is prepared strictly for informational and quantitative analytical purposes and does not constitute financial, investment, or trading advice (NFA). Digital asset derivatives and algorithmic futures trading involve significant counterparty, systemic, and execution risks.
#Bitcoin #Crypto #Binance
50
·
--
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis
Dealer Gamma Exposure (GEX) is heavily positive into OpEx. How does price react?
- Pin to max gamma strike
- Vol compression grind
- Breakout gamma squeeze
- Negative GEX breakdown
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis
Dealer Gamma Exposure (GEX) is heavily positive into OpEx. How does price react?
- Pin to max gamma strike
- Vol compression grind
- Breakout gamma squeeze
- Negative GEX breakdown
Dealer Gamma Exposure (GEX) is heavily positive into OpEx. How does price react?
- Pin to max gamma strike
- Vol compression grind
- Breakout gamma squeeze
- Negative GEX breakdown
62
·
--
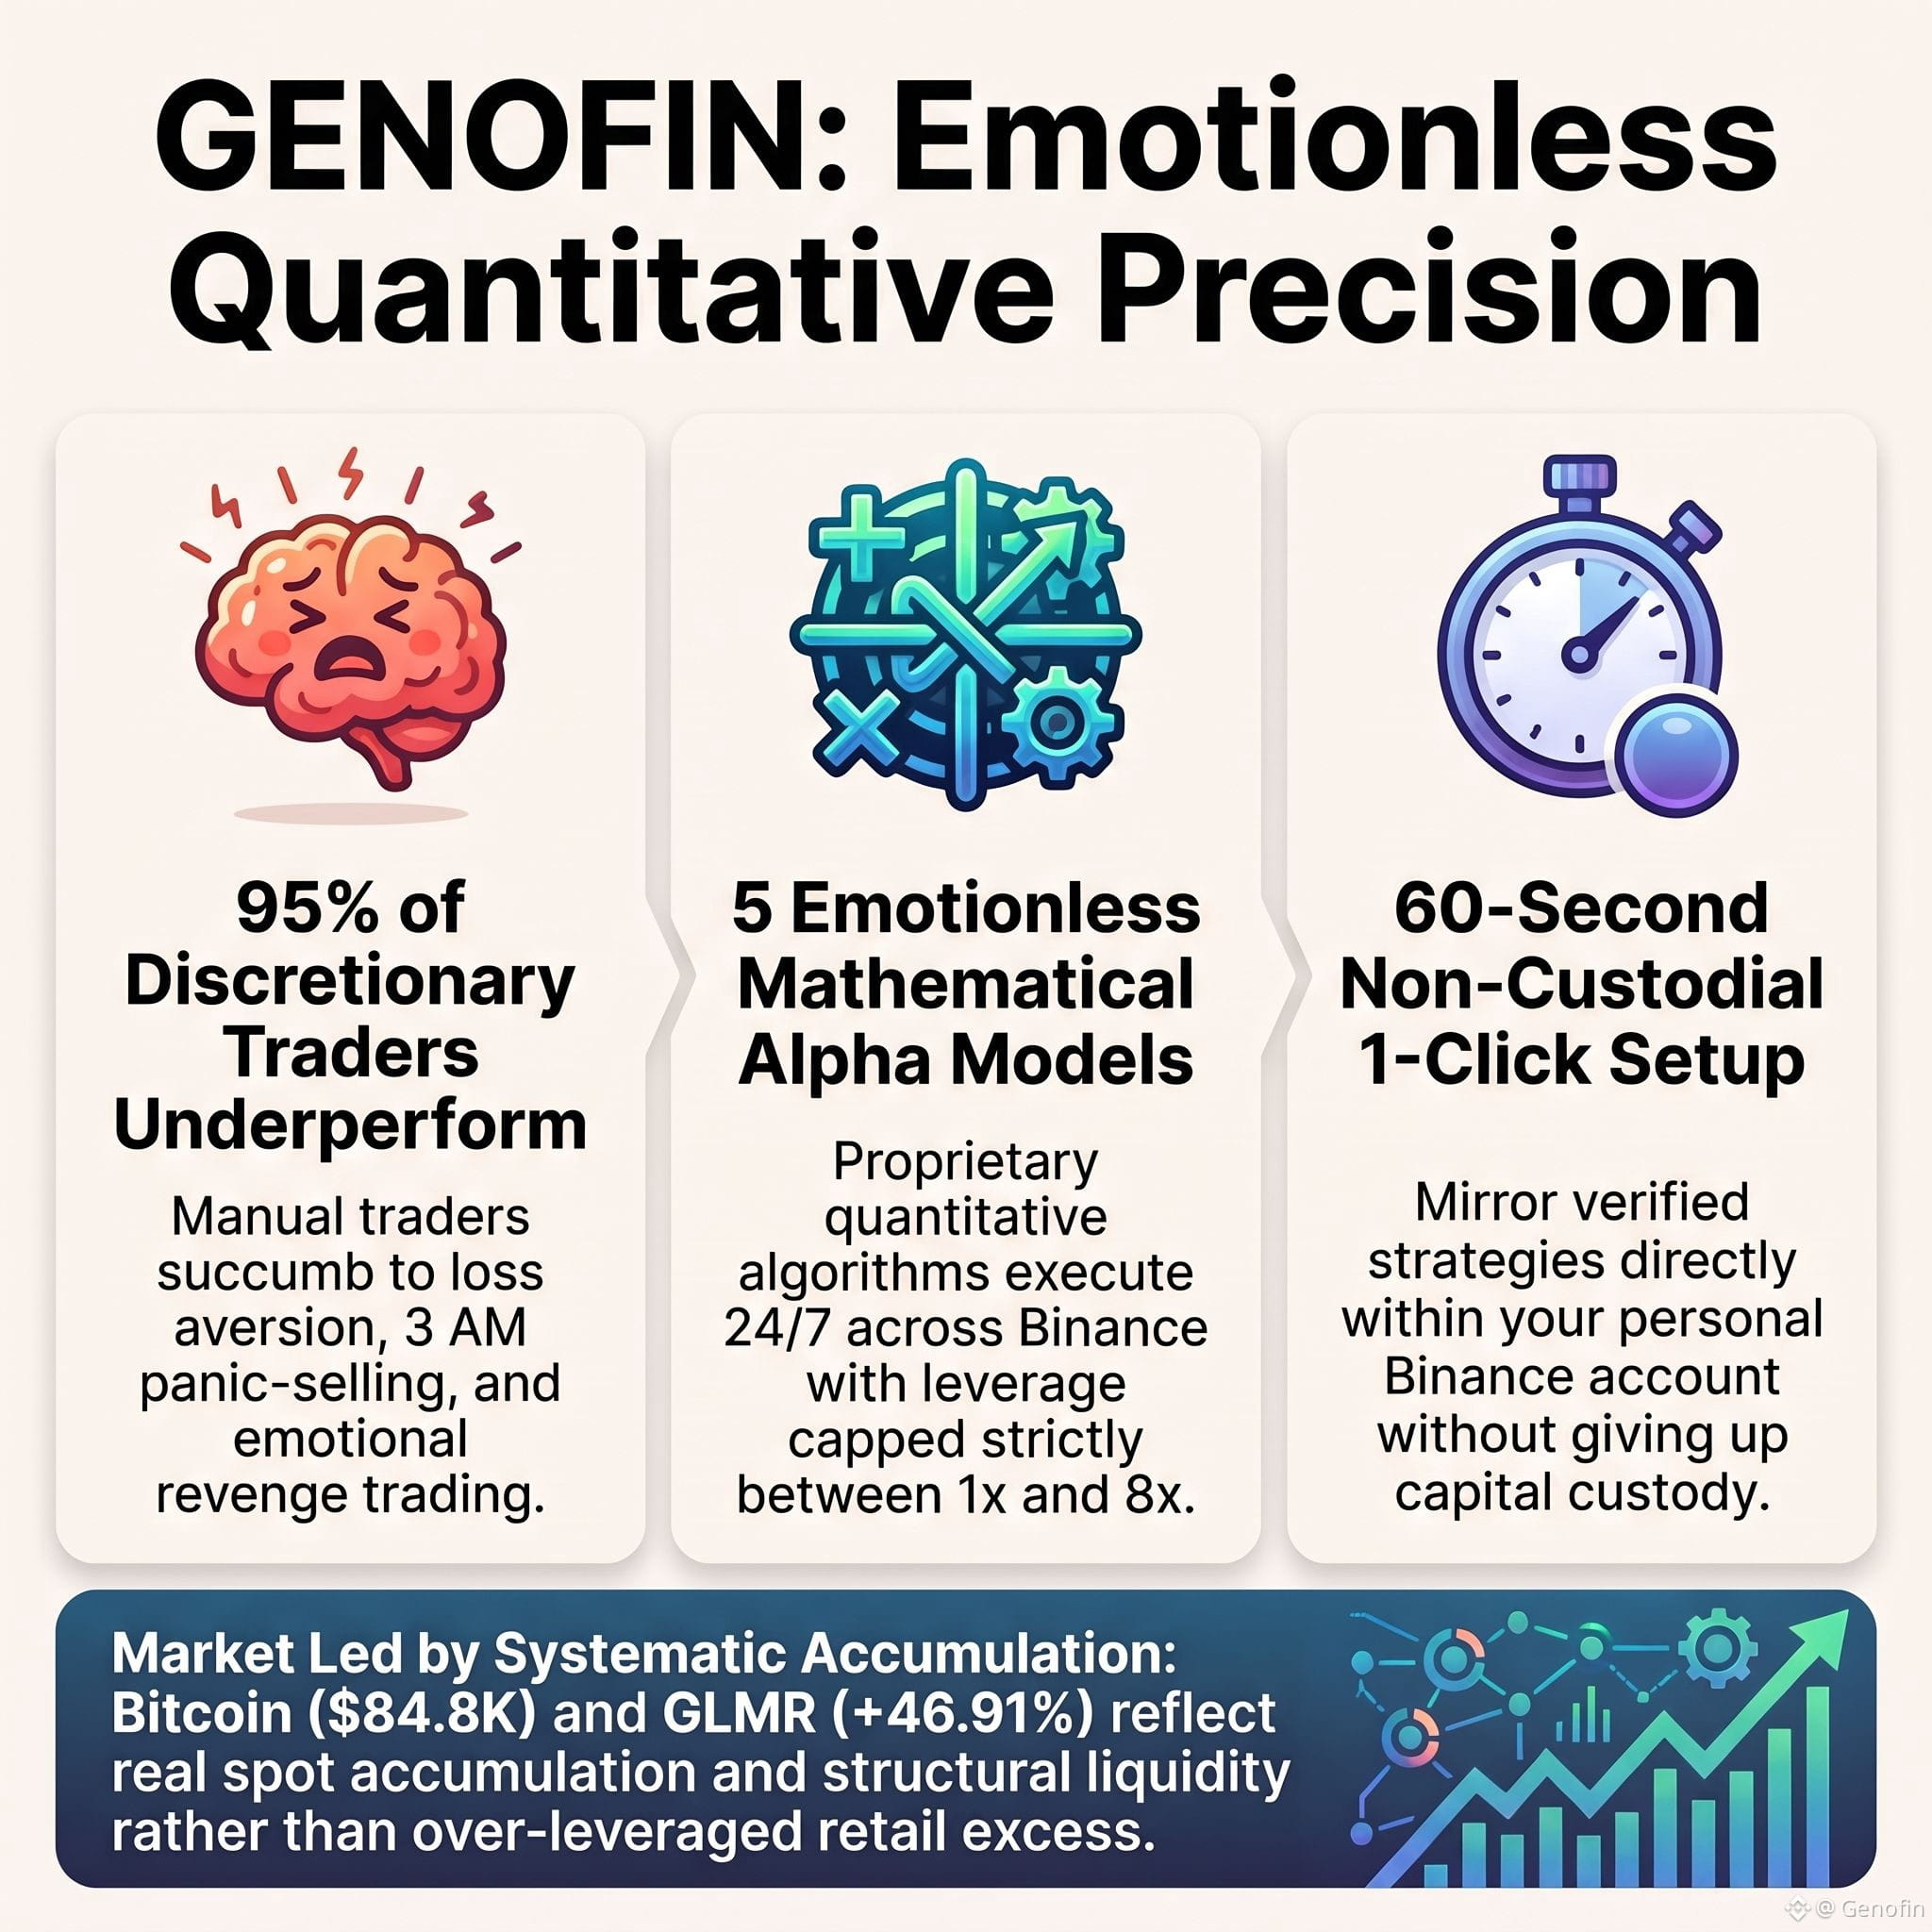
📊 Genofin Quantitative Market Snapshot • genofin.tech
📊 Genofin Quantitative Market Snapshot • genofin.tech
76
·
--
Daily Dispatch: BTC Gamma Pinning, Structural GEX & Volatility Surface Regime📊 EXECUTIVE SUMMARY
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
#Bitcoin #Crypto #Binance
Daily Dispatch: BTC Gamma Pinning, Structural GEX & Volatility Surface Regime
📊 EXECUTIVE SUMMARY
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
#Bitcoin #Crypto #Binance
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
BTC consolidates near $84.8k as DVOL compresses to 34.73% following an $87k liquidity sweep. Institutional order-flow reveals dense positive dealer gamma pinning spot between active strike walls.
#Bitcoin #Crypto #Binance
9
·
--
ບົດຄວາມ
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning AnalysisDealer gamma dictates price action:
• +.2B net GEX dampens realized vol by 42%
• 5800 strike commands 31% of aggregate OI
Exploit structural pinning and non-custodial quant execution.
#OptionsTrading #GEX #Quant Binance Bitcoin
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis
Dealer gamma dictates price action:
• +.2B net GEX dampens realized vol by 42%
• 5800 strike commands 31% of aggregate OI
Exploit structural pinning and non-custodial quant execution.
#OptionsTrading #GEX #Quant Binance Bitcoin
• +.2B net GEX dampens realized vol by 42%
• 5800 strike commands 31% of aggregate OI
Exploit structural pinning and non-custodial quant execution.
#OptionsTrading #GEX #Quant Binance Bitcoin
85
·
--
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis. Quantitative derivatives telemetry. #OptionsTrading #GEX #Quant #Bitcoin
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis. Quantitative derivatives telemetry. #OptionsTrading #GEX #Quant #Bitcoin
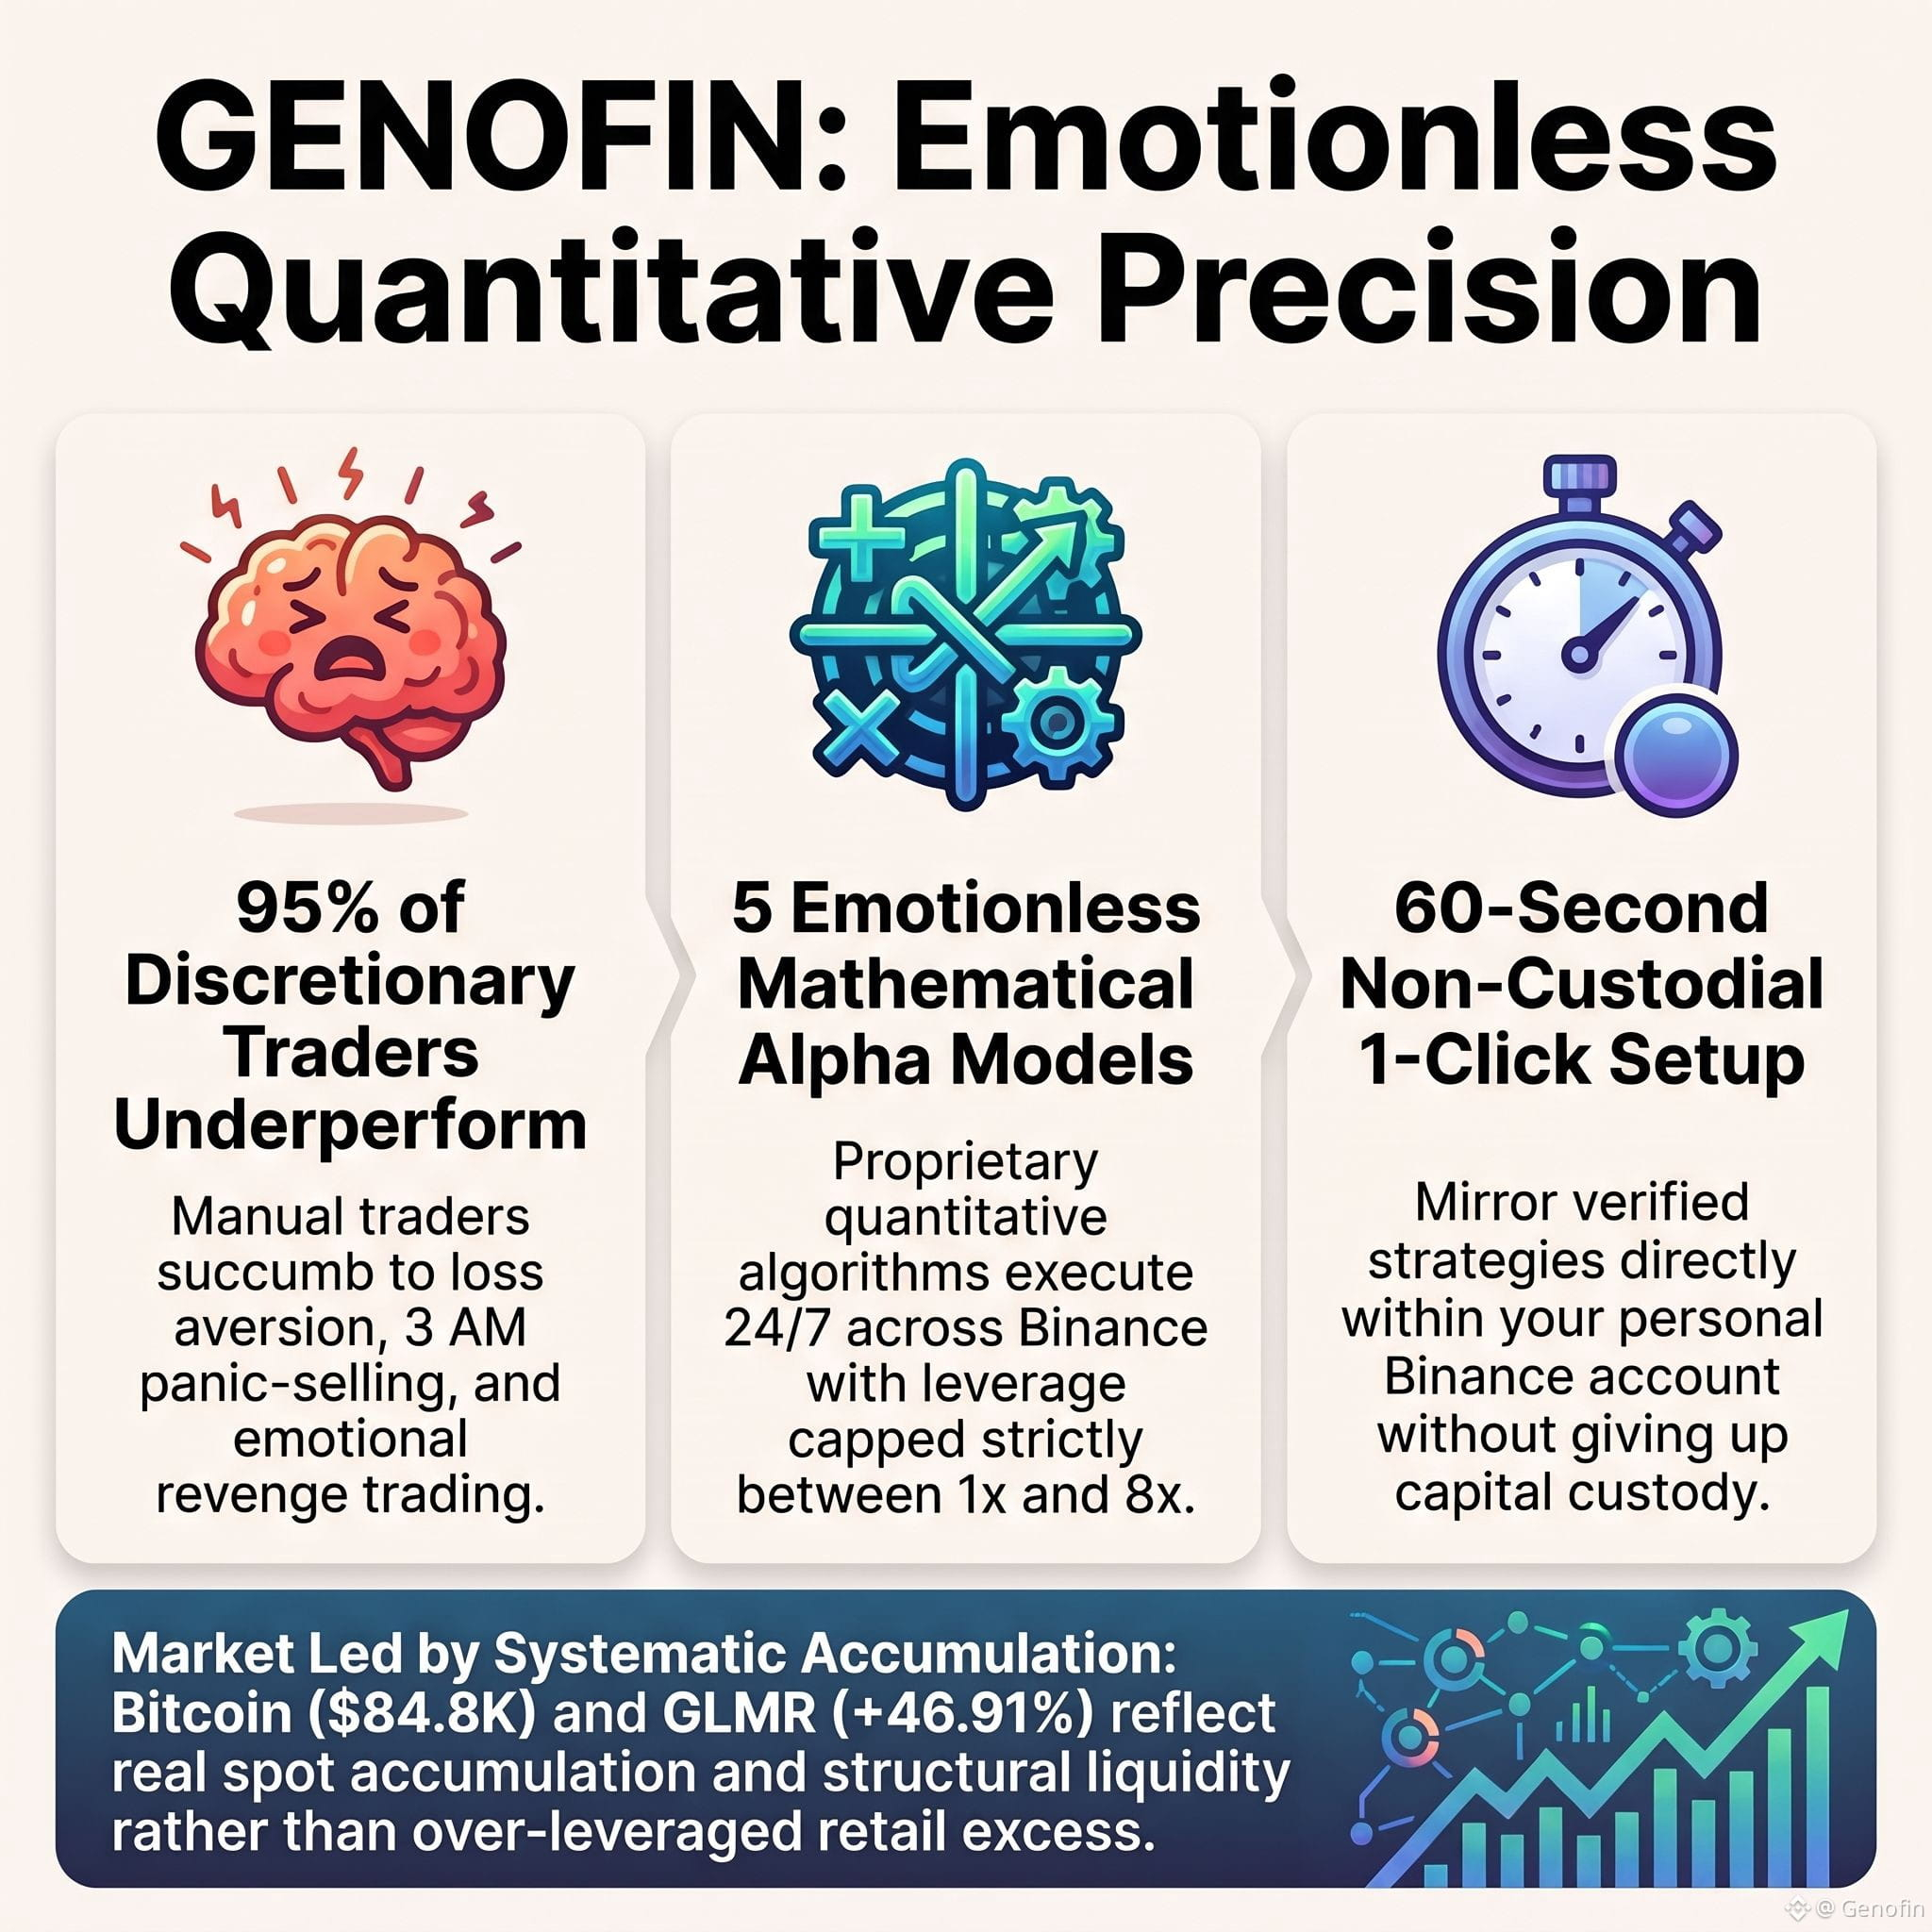
85
·
--
Dealer Gamma Exposure (GEX) & Strike Pinning Analysis | Quantitative Macro
EXECUTIVE SUMMARY & MICROSTRUCTURE ANALYSIS
While narrative-driven retail commentary focuses on lagging indicators, institutional positioning is dictated by derivatives microstructure. This quantitative research brief examines Dealer Gamma Exposure (GEX), the volatility surface, and the physical mechanics of strike pinning.
HOW OPTIONS GAMMA PINNING WORKS
Options market makers continuously hedge their books to remain d
1
2.4k
·
--
How dealers legally trap stock prices using Gamma Exposure.
Market makers don't guess—they hedge. See how Dealer Gamma (GEX) forces structural strike pinning. Read the institutional quantitative memo at genofin.tech
#Quant #OptionsTrading #GEX Trading
How dealers legally trap stock prices using Gamma Exposure.
Market makers don't guess—they hedge. See how Dealer Gamma (GEX) forces structural strike pinning. Read the institutional quantitative memo at genofin.tech
#Quant #OptionsTrading #GEX Trading
Market makers don't guess—they hedge. See how Dealer Gamma (GEX) forces structural strike pinning. Read the institutional quantitative memo at genofin.tech
#Quant #OptionsTrading #GEX Trading
1
2
2.1k
·
--
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis
Heavy positive Dealer GEX into options expiry typically causes:
- Strike pinning & low vol
- Violent gamma squeeze
- Trend continuation
- Whipsaw liquidations
📊 Dealer Gamma Exposure (GEX) & Structural Strike Pinning Analysis
Heavy positive Dealer GEX into options expiry typically causes:
- Strike pinning & low vol
- Violent gamma squeeze
- Trend continuation
- Whipsaw liquidations
Heavy positive Dealer GEX into options expiry typically causes:
- Strike pinning & low vol
- Violent gamma squeeze
- Trend continuation
- Whipsaw liquidations
71
·
--
The crypto volatility model institutional quants don't share.
Exploiting term structure contango with risk-neutral variance models in crypto. Institutional alpha unpacked. Read the full memo at genofin.tech #CryptoQuant #Volatility #Trading
The crypto volatility model institutional quants don't share.
Exploiting term structure contango with risk-neutral variance models in crypto. Institutional alpha unpacked. Read the full memo at genofin.tech #CryptoQuant #Volatility #Trading
Exploiting term structure contango with risk-neutral variance models in crypto. Institutional alpha unpacked. Read the full memo at genofin.tech #CryptoQuant #Volatility #Trading
2
698
·
--
Crypto vol term structure hits steep contango:
• 30D/90D IV spread: +4.8v
• RN variance premium: +18%
Monetize the curve roll.
NFA. genofin.tech
Crypto vol term structure hits steep contango:
• 30D/90D IV spread: +4.8v
• RN variance premium: +18%
Monetize the curve roll.
NFA. genofin.tech
• 30D/90D IV spread: +4.8v
• RN variance premium: +18%
Monetize the curve roll.
NFA. genofin.tech
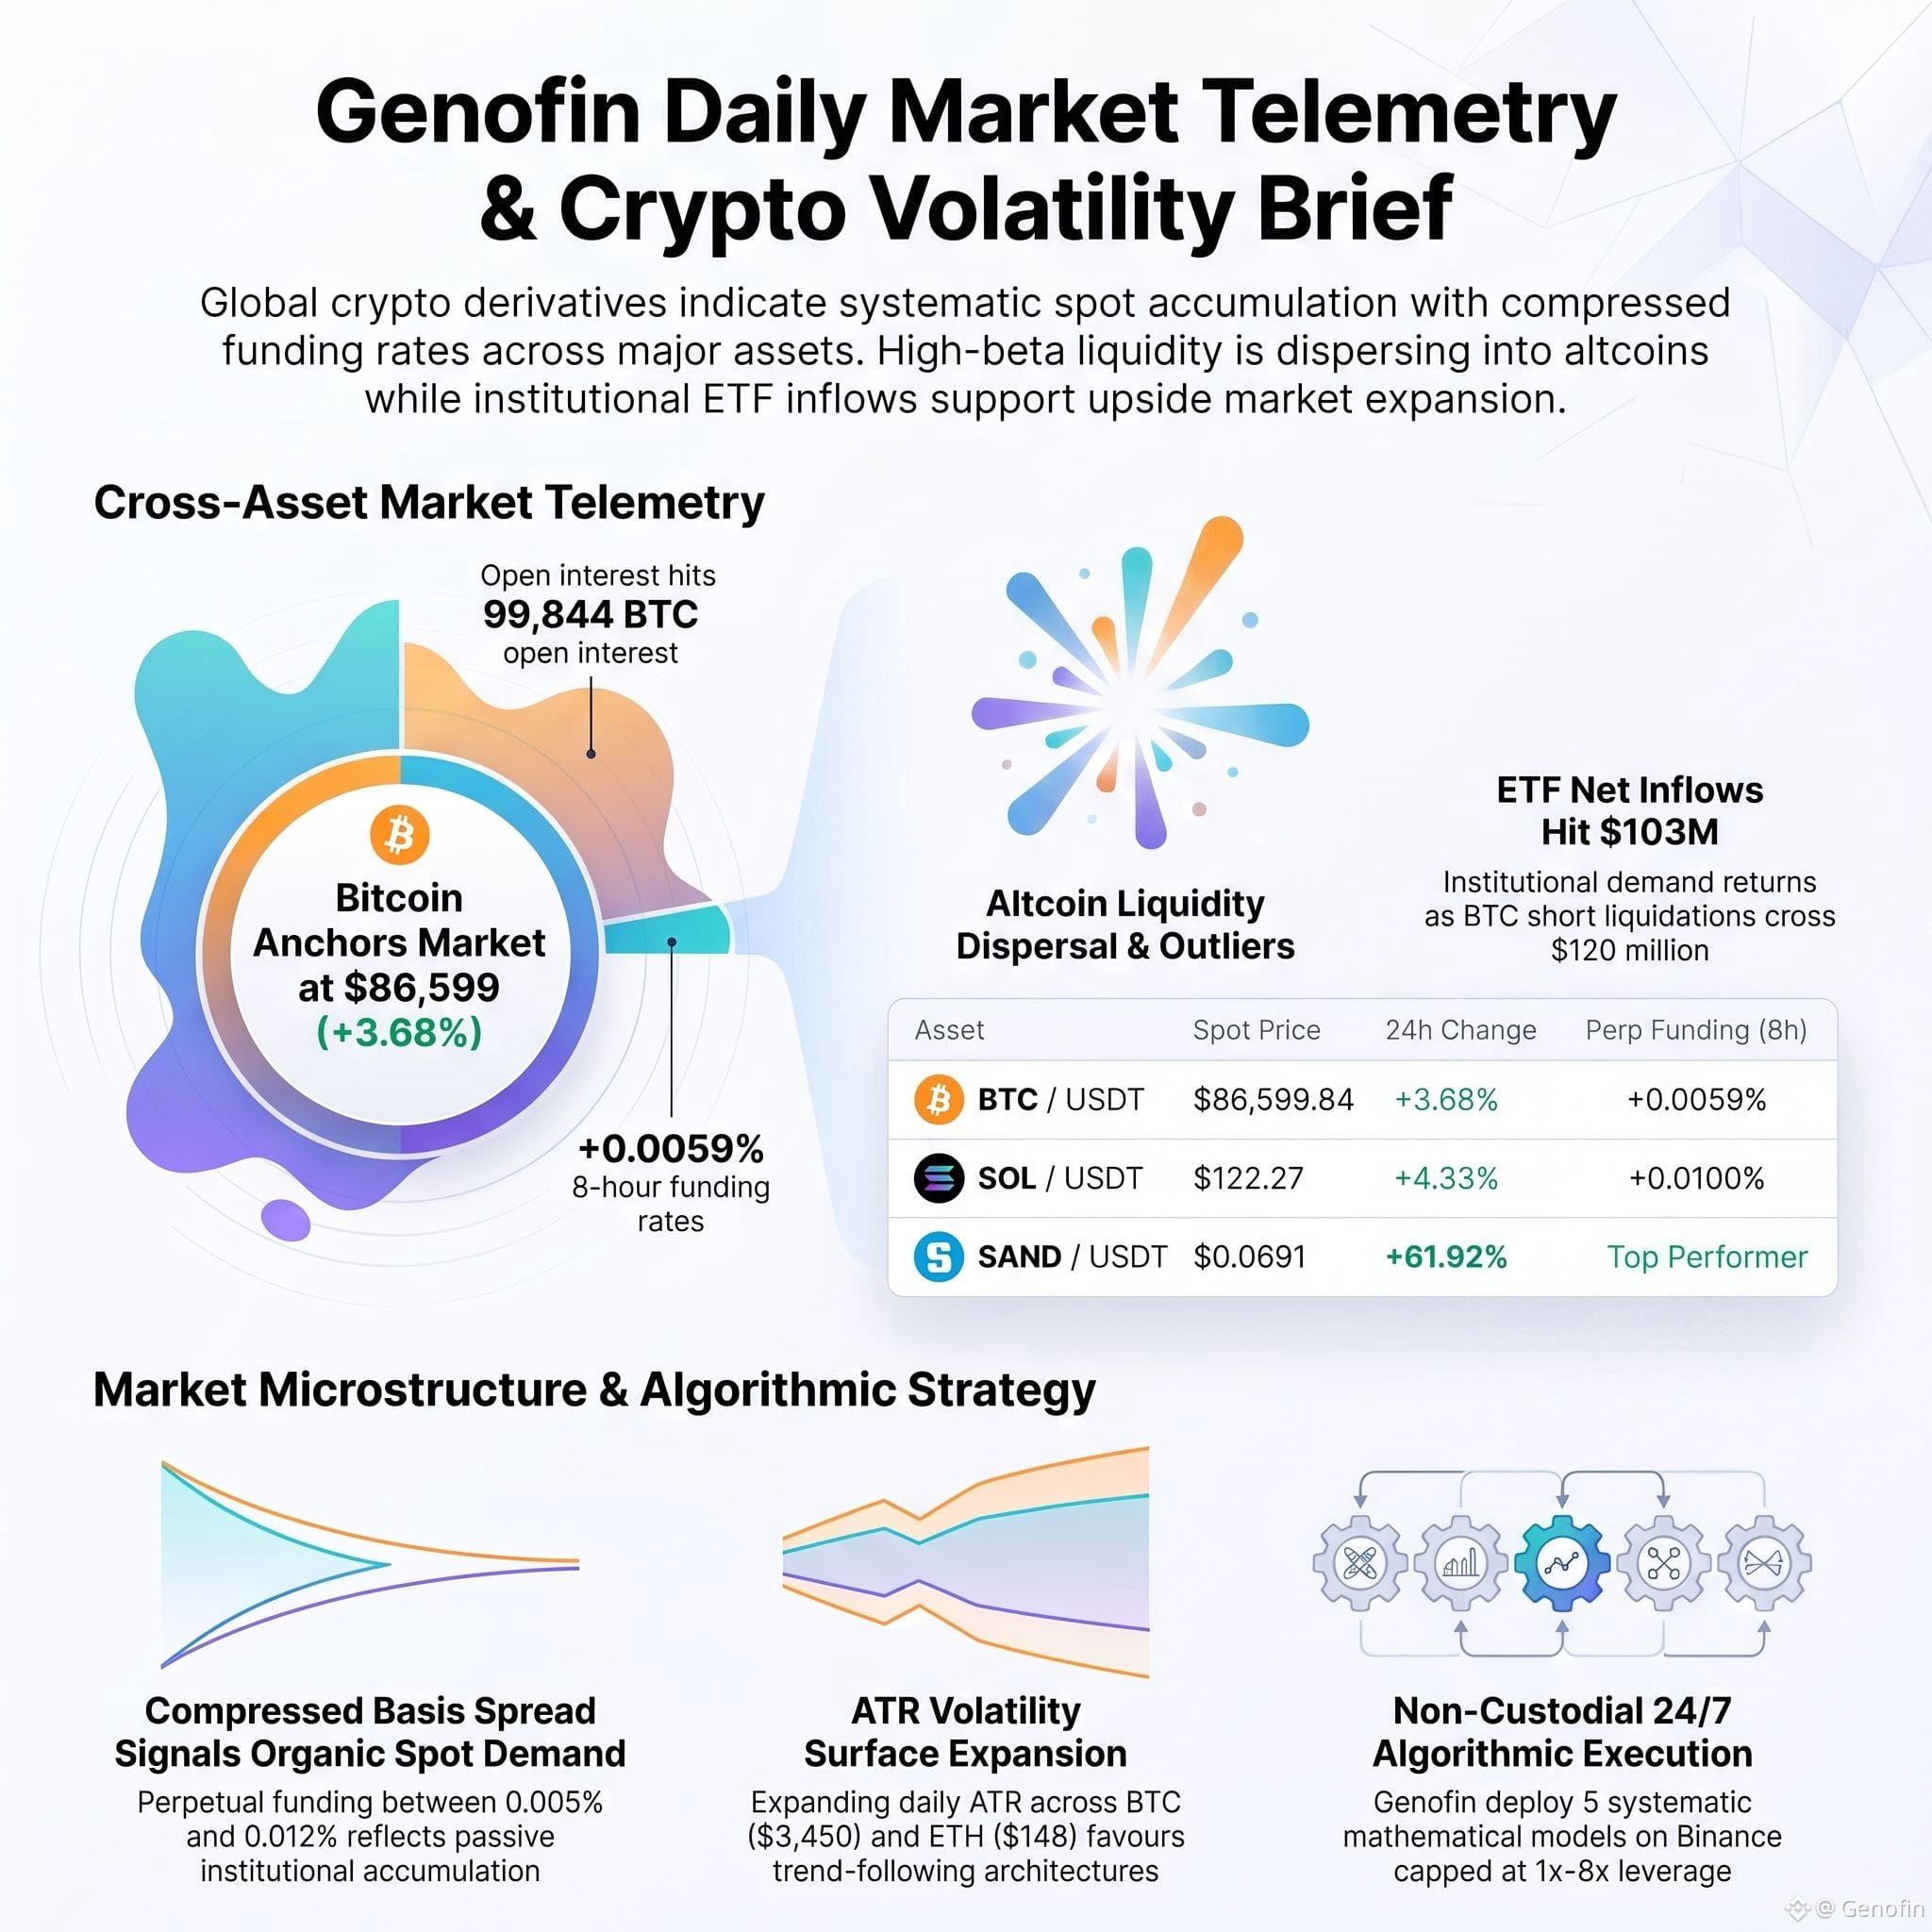
237
·
--
📊 Genofin Daily Quant Poll — Comment your answer! 👇
BTC is at $84,537 (-0.3% 24h). What's your outlook?
- Bullish breakout
- Mean reversion
- Sideways chop
- Mirror Genofin
📊 Genofin Daily Quant Poll — Comment your answer! 👇
BTC is at $84,537 (-0.3% 24h). What's your outlook?
- Bullish breakout
- Mean reversion
- Sideways chop
- Mirror Genofin
BTC is at $84,537 (-0.3% 24h). What's your outlook?
- Bullish breakout
- Mean reversion
- Sideways chop
- Mirror Genofin
100
·
--
Master macro regime shifts with systematic volatility harvesting:
• +2.4 Sharpe via dynamic DCA
• 41% drawdown reduction
Automate execution now.
NFA. genofin.tech
Master macro regime shifts with systematic volatility harvesting:
• +2.4 Sharpe via dynamic DCA
• 41% drawdown reduction
Automate execution now.
NFA. genofin.tech
• +2.4 Sharpe via dynamic DCA
• 41% drawdown reduction
Automate execution now.
NFA. genofin.tech
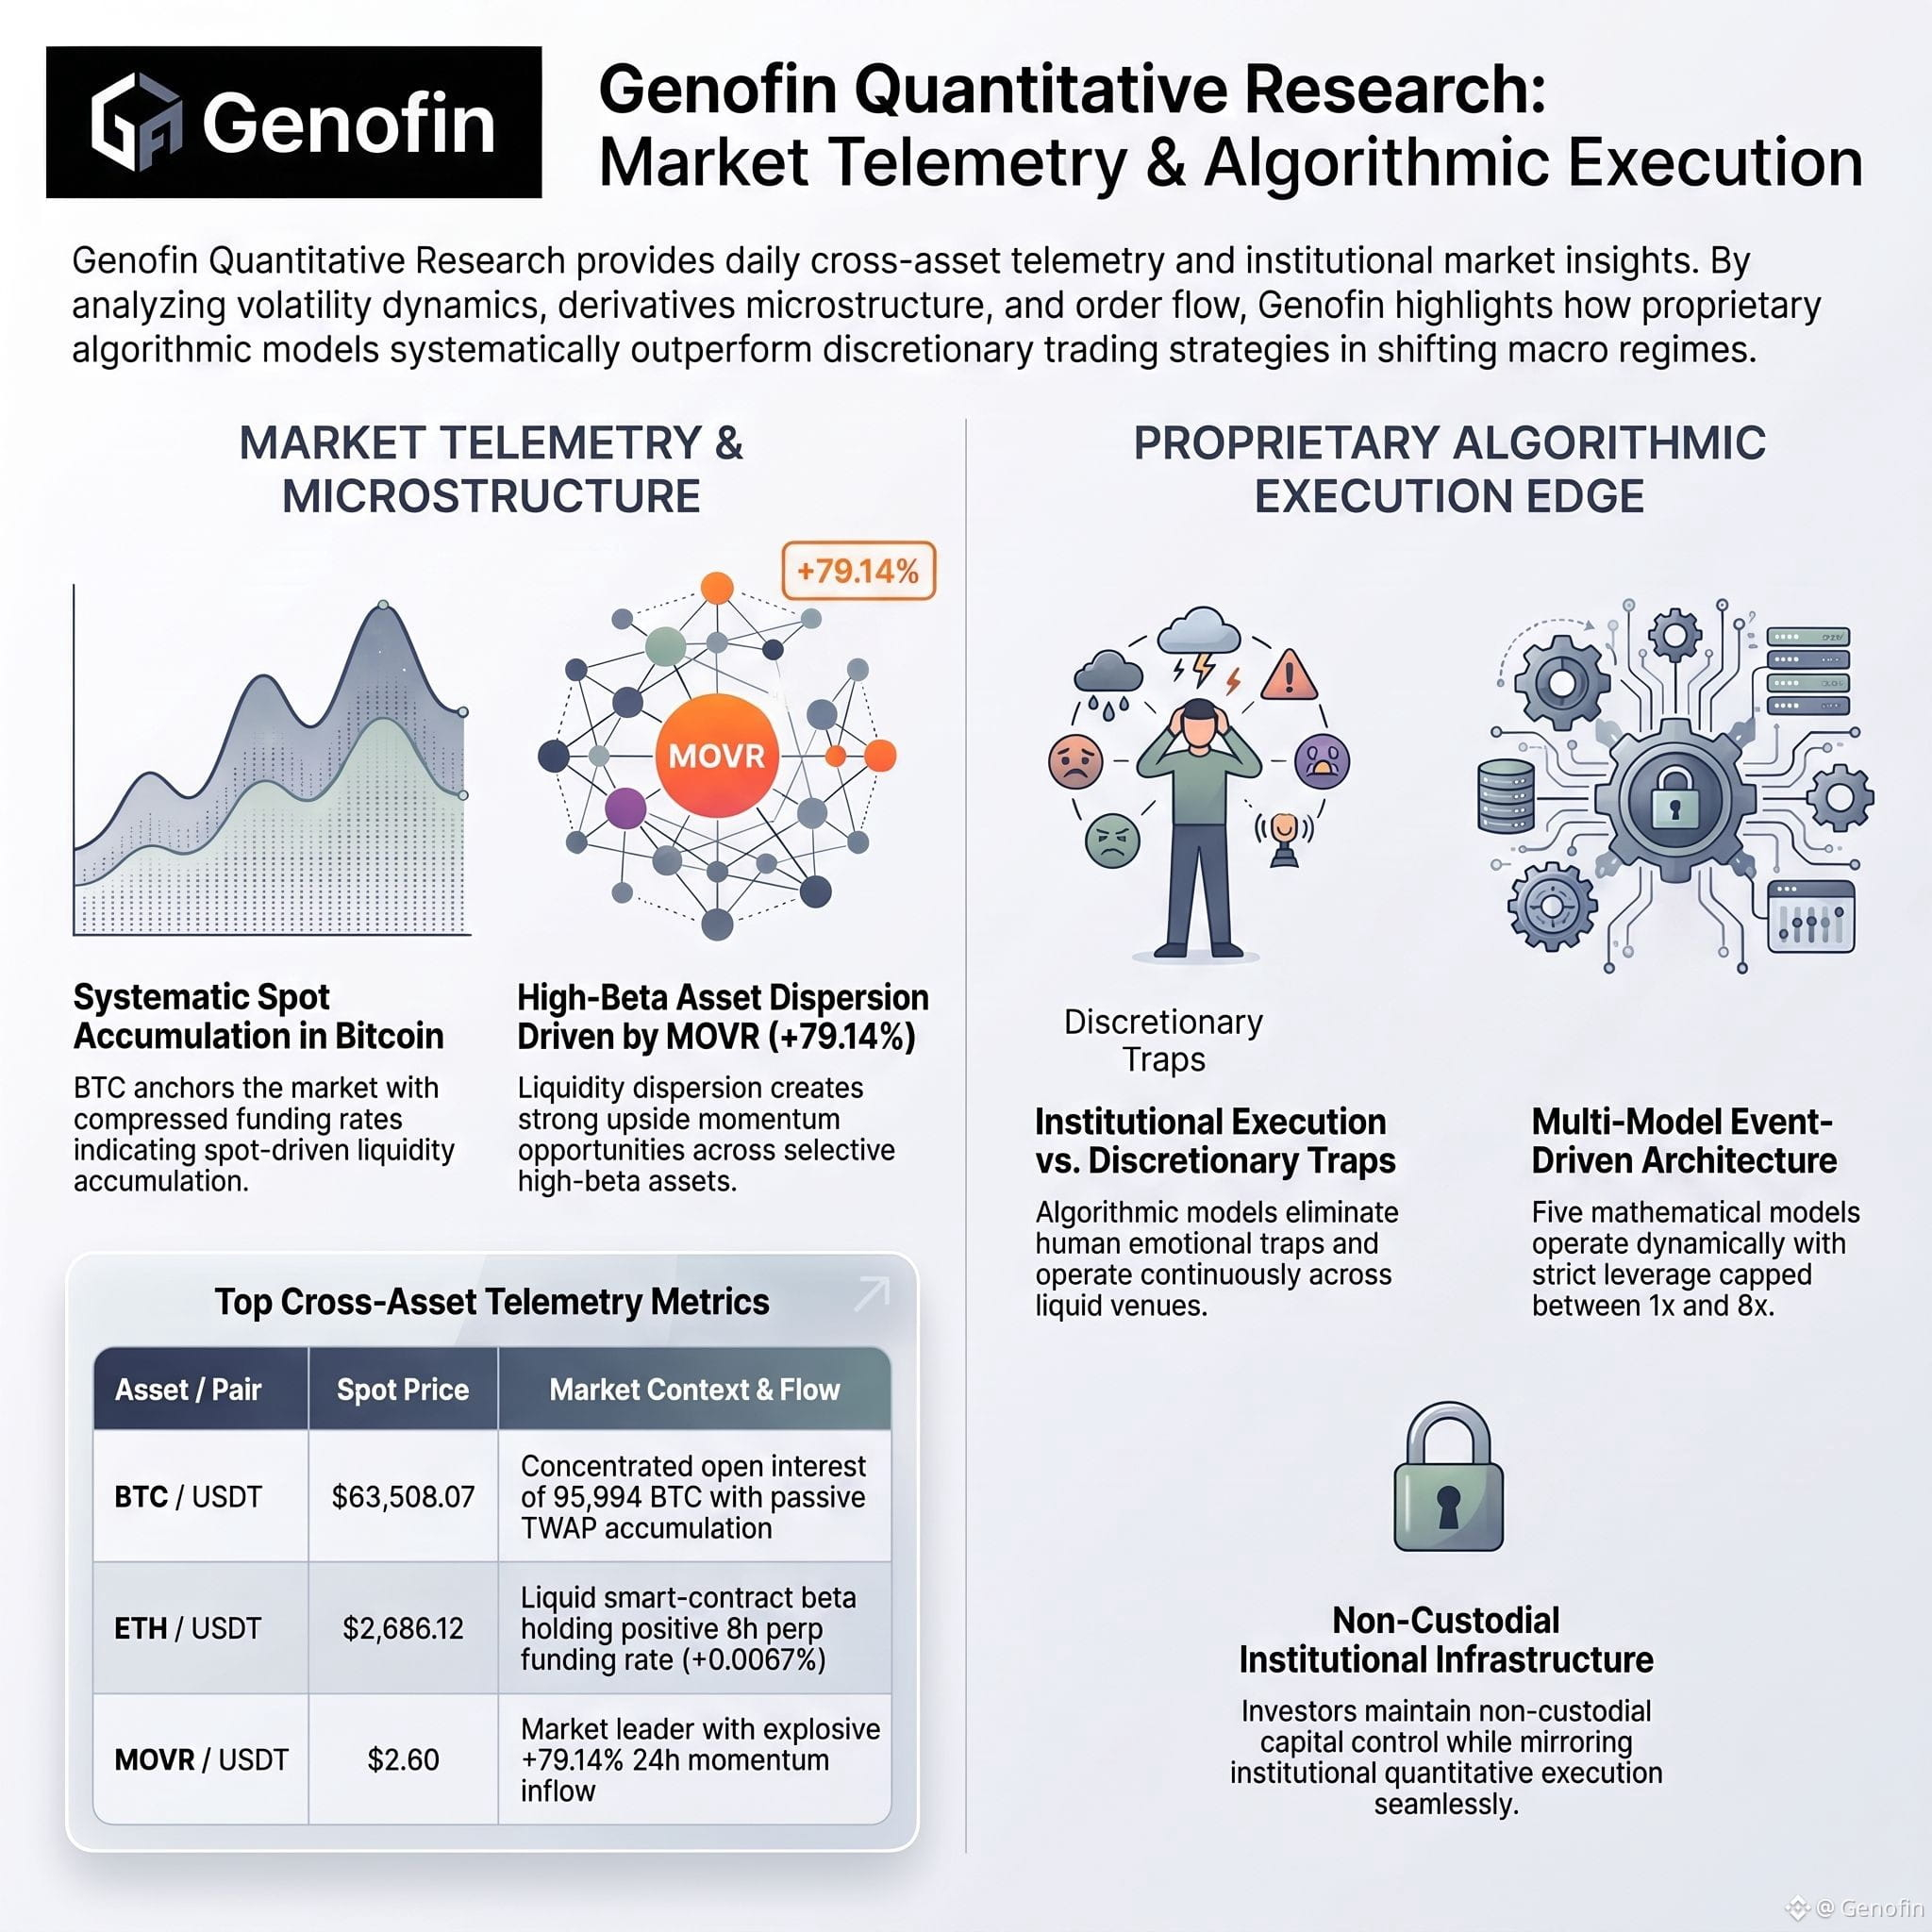
10
·
--
Want to improve your trading game? Click here to explore and copy effective strategies from my portfolio👇
Want to improve your trading game? Click here to explore and copy effective strategies from my portfolio👇
Futures Portfolio ຂອງຂ້ອຍ
13 / 200
API
ສາທາລະນະ
PNL 7 ວັນ
(USDT)
109.16
7D ROI
+0.97%
ຊັບສິນພາຍໃຕ້ການຄຸ້ມຄອງ
$96428.87
ອັດຕາການຊະນະ
0.00%
1
1
ເຂົ້າສູ່ລະບົບເພື່ອສຳຫຼວດເນື້ອຫາເພີ່ມເຕີມ
ເຂົ້າຮ່ວມກຸ່ມຜູ້ໃຊ້ຄຣິບໂຕທົ່ວໂລກໃນ Binance Square.
⚡️ ໄດ້ຮັບຂໍ້ມູນຫຼ້າສຸດ ແລະ ທີ່ມີປະໂຫຍດກ່ຽວກັບຄຣິບໂຕ.
💬 ໄດ້ຮັບຄວາມໄວ້ວາງໃຈຈາກຕະຫຼາດແລກປ່ຽນຄຣິບໂຕທີ່ໃຫຍ່ທີ່ສຸດໃນໂລກ.
👍 ຄົ້ນຫາຂໍ້ມູນເຊີງເລິກທີ່ແທ້ຈາກນັກສ້າງທີ່ໄດ້ຮັບການຢືນຢັນ.
ອີເມວ / ເບີໂທລະສັບ
ຫົວຂໍ້ທີ່ກໍາລັງນິຍົມ
BNBSurpasses$790
7,474 views
69 ກຳລັງສົນທະນາ
$BNB strategic long plan -> FOCUS NOW
BNB has created 2 strong lows after taking out internal liquidity
I'm expecting a move towards swing high $815-$830 and looking for a long on a retest of the green box
#BNBSurpasses$790 #bnb
Ghost Writer
·3 ຖືກໃຈ
·3.3k views
ZamaRises15.99%ToIntradayHigh$0.09
2,244 views
63 ກຳລັງສົນທະນາ
BitcoinSpotETFsDraw$6.34BInflowsInQ3
2,904 views
52 ກຳລັງສົນທະນາ