
Frogleim
103 ໂພສ
Frogleim
ລາຍງານ
ບລັອກຜູ້ໃຊ້
Algo Trader | AI & Algo Trading | DeFi Enthusiast Building AI-driven trading bots & automated strategies
follow me on twitter - @SFrogleim
2 ກໍາລັງຕິດຕາມ
288 ຜູ້ຕິດຕາມ
365 Liked
ໂພສ
ທັງໝົດ
ວົງຢືມ
ວີດີໂອ
·
--
ເບິ່ງການແປ
Another trade from my no code backtester
Simply build and runs automate signals without coding skills
#FutureTarding
Another trade from my no code backtester
Simply build and runs automate signals without coding skills
#FutureTarding
Simply build and runs automate signals without coding skills
#FutureTarding
203
·
--
ເບິ່ງການແປ
Just closed my positions.
The strategy was built using my no-code backtester, and the signals were also received from the same platform.
#futures
Just closed my positions.
The strategy was built using my no-code backtester, and the signals were also received from the same platform.
#futures
The strategy was built using my no-code backtester, and the signals were also received from the same platform.
#futures
437
·
--
ເບິ່ງການແປ
One of todays trades results
Strategy was built on my no code backtester
virtuum-lab.com
#futures
One of todays trades results
Strategy was built on my no code backtester
virtuum-lab.com
#futures
Strategy was built on my no code backtester
virtuum-lab.com
#futures
273
·
--
ບົດຄວາມ
ເບິ່ງການແປ
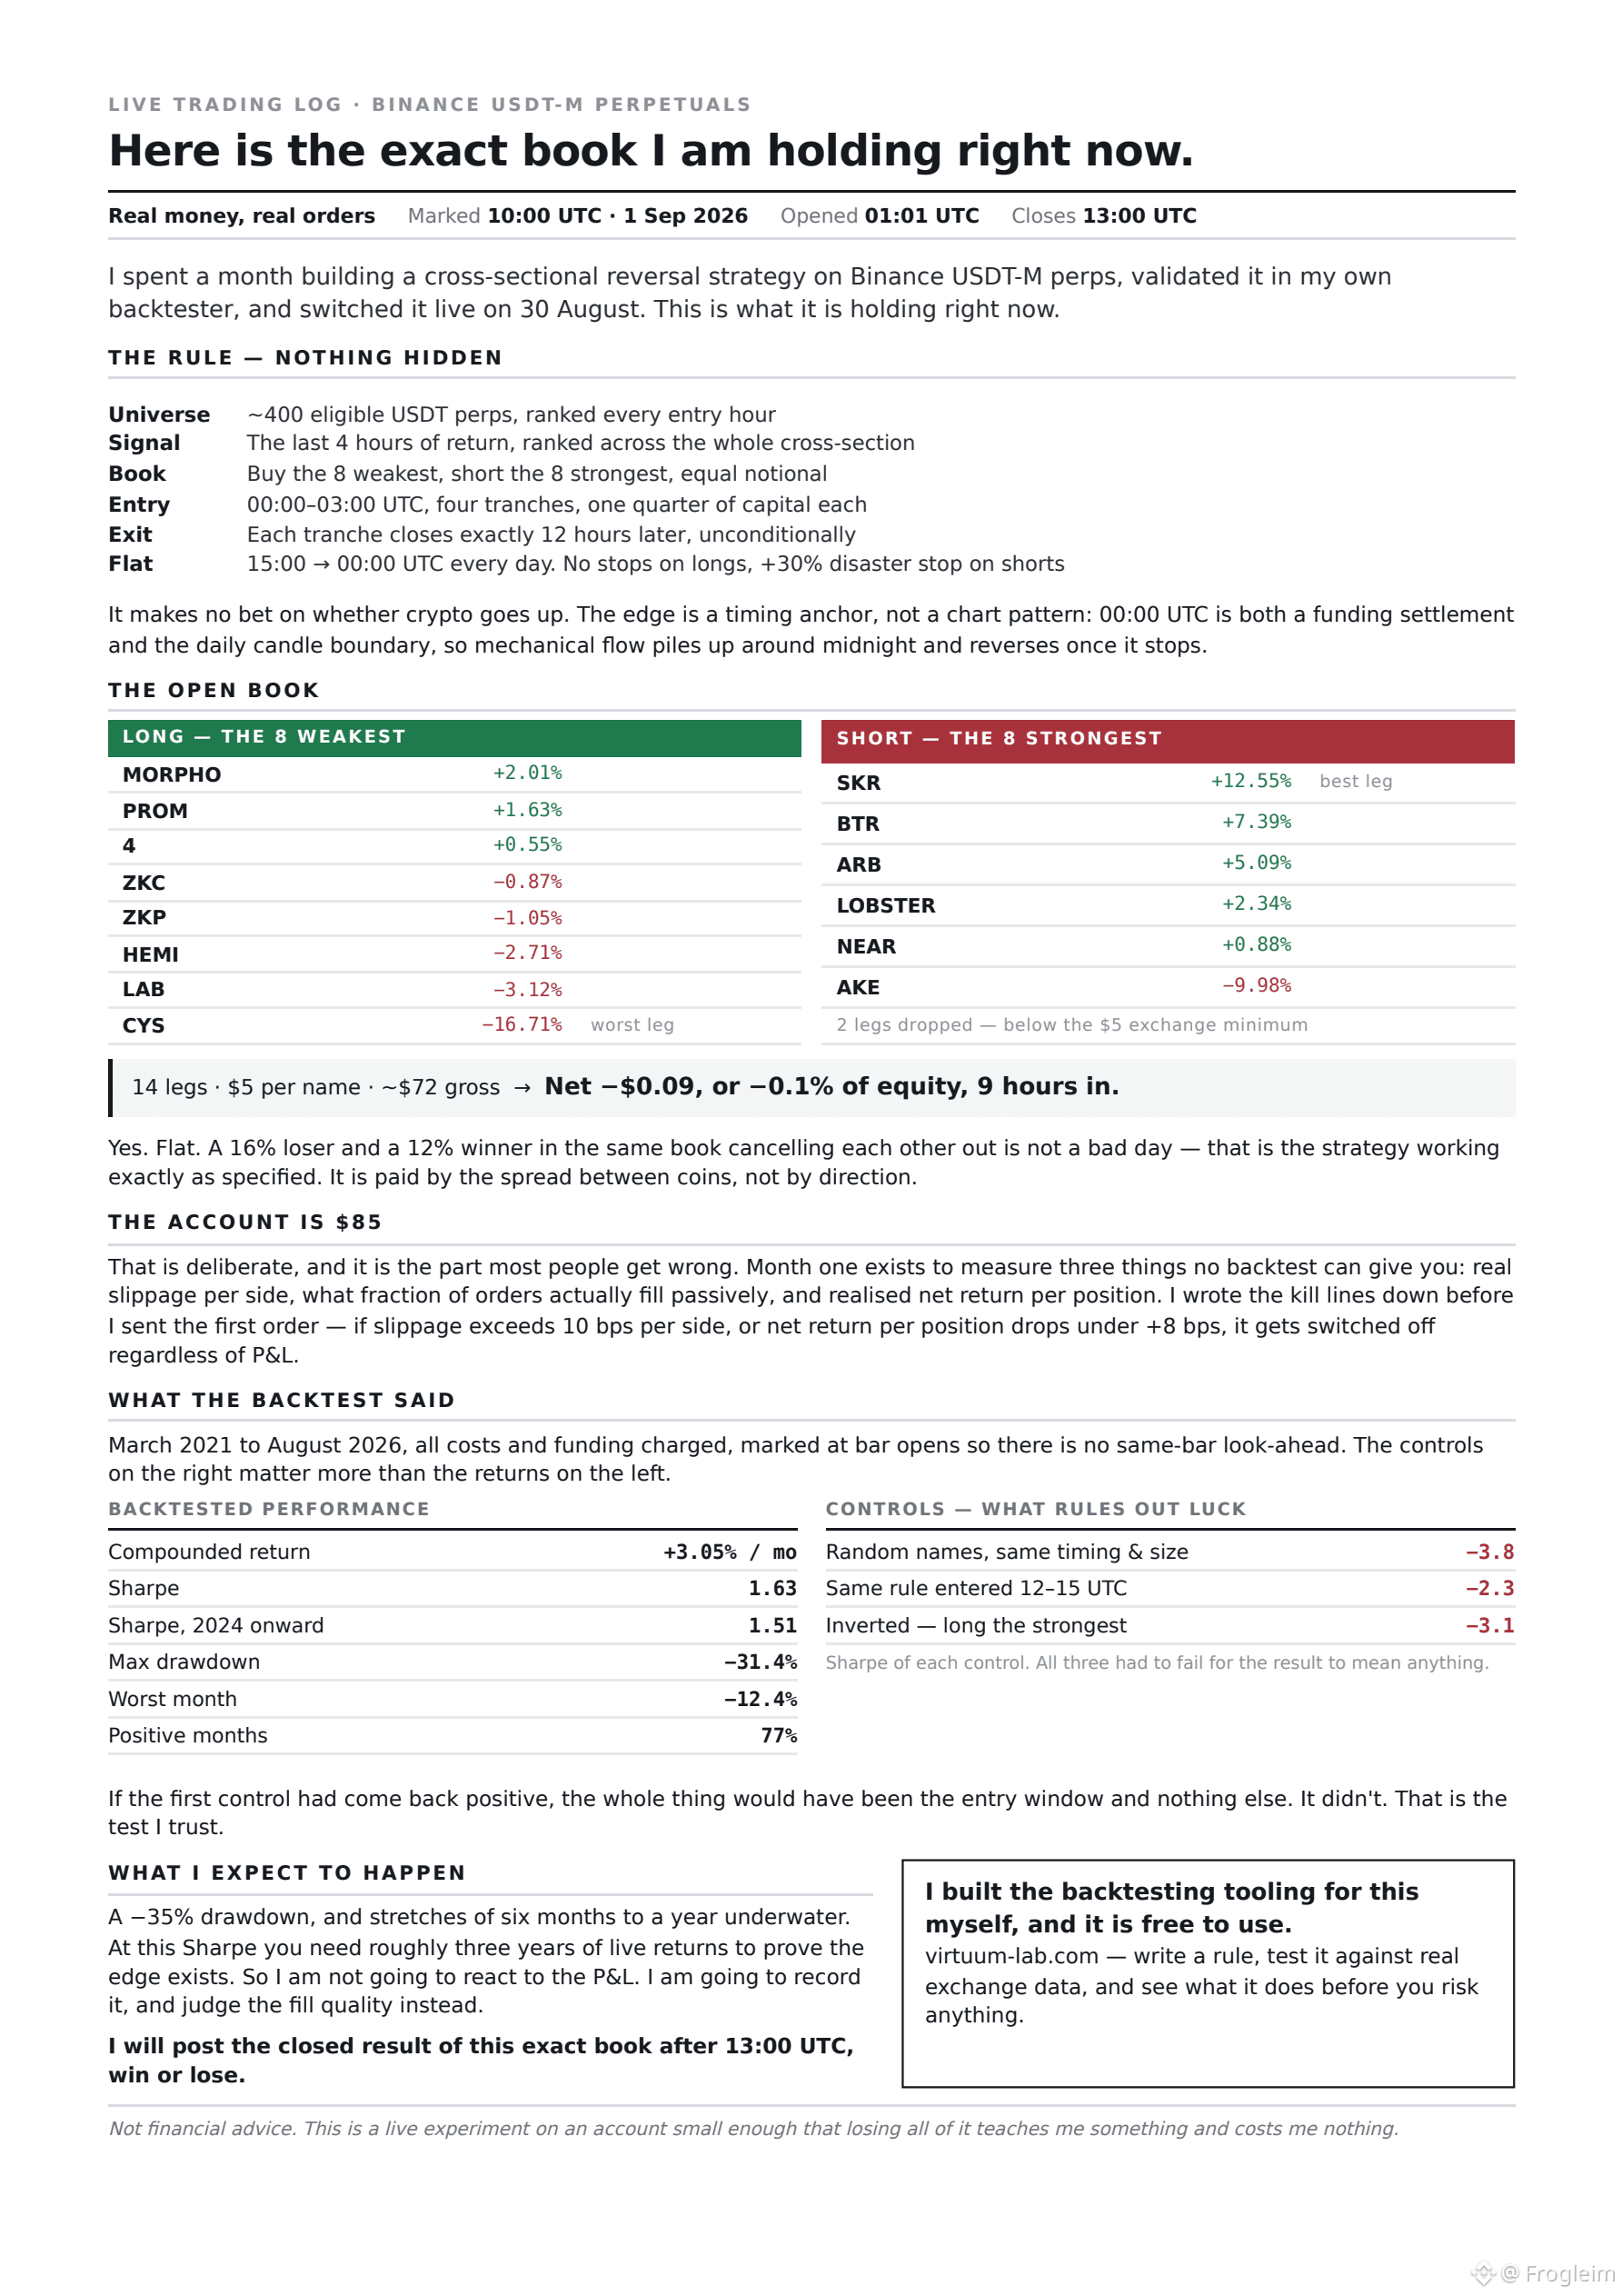
Here is the exact book I am holding right nowReal money, real orders, and it closes at 13:00 UTC today.
I spent a month building a cross-sectional reversal strategy on Binance USDT-M perps, validated it in my own backtester, and switched it live on Aug 30. This is what it is holding at 10:00 UTC today.
THE RULE (nothing hidden)
Every day at 00–03 UTC I rank ~400 eligible USDT perps by their last 4 hours of return. I buy the 8 weakest, short the 8 strongest, equal notional. Each tranche closes exactly 12 hours later, unconditionally. Flat from 15:00 to 00:00 UTC every day. No stops on longs, a +30% disaster stop on shorts. It makes no bet on whether crypto goes up.
The edge is a timing anchor, not a chart pattern: 00:00 UTC is both a funding settlement and the daily candle boundary, so mechanical flow piles up around midnight and reverses once it stops.
THE OPEN BOOK — opened 01:01 UTC, closes 13:00 UTC
LONG
PROM +1.63%
MORPHO +2.01%
4 +0.55%
ZKC -0.87%
ZKP -1.05%
HEMI -2.71%
LAB -3.12%
CYS -16.71% <- the worst leg in the book
SHORT
SKR +12.55% <- the best leg in the book
BTR +7.39%
ARB +5.09%
LOBSTER +2.34%
NEAR +0.88%
AKE -9.98%
14 legs, $5 per name, ~$72 gross. Net: -$0.09, or -0.1% of equity, 9 hours in.
Yes. Flat. A 16% loser and a 12% winner in the same book cancelling each other out is not a bad day - that is the strategy working exactly as specified. It is paid by the spread between coins, not by direction.
THE ACCOUNT IS $85
That is deliberate, and it is the part most people get wrong. Month one exists to measure three things no backtest can give you: real slippage per side, what fraction of orders actually fill passively, and realised net return per position. I wrote the kill lines down before I sent the first order - if slippage exceeds 10 bps per side, or net return per position drops under +8 bps, it gets switched off regardless of P&L.
WHAT THE BACKTEST SAID
2021-03 to 2026-08, all costs and funding charged, marked at bar opens so there is no same-bar look-ahead:
+3.05% / month compounded
Sharpe 1.63 (1.51 from 2024 onward)
Max drawdown -31.4%
Worst month -12.4%
77% of months positive
And the three controls that matter more than any of those:
Random names, identical timing and size -> Sharpe -3.8
Same rule entered at 12–15 UTC instead -> Sharpe -2.3
Inverted: long the strongest -> Sharpe -3.1
If the first control had come back positive, the whole thing would have been the entry window and nothing else. It didn't. That is the test I trust.
WHAT I EXPECT TO HAPPEN
A -35% drawdown, and stretches of six months to a year underwater. At this Sharpe you need roughly three years of live returns to prove the edge exists. So I am not going to react to the P&L. I am going to record it, and judge the fill quality instead.
I will post the closed result of this exact book after 13:00 UTC, win or lose.
I built the backtesting tooling for this myself and it is free to use at virtuum-lab.com - write a rule, test it against real exchange data, see what it does before you risk anything.
Not financial advice. This is a live experiment on an account small enough that losing all of it teaches me something and costs me nothing.
Here is the exact book I am holding right now
Real money, real orders, and it closes at 13:00 UTC today.
I spent a month building a cross-sectional reversal strategy on Binance USDT-M perps, validated it in my own backtester, and switched it live on Aug 30. This is what it is holding at 10:00 UTC today.
THE RULE (nothing hidden)
Every day at 00–03 UTC I rank ~400 eligible USDT perps by their last 4 hours of return. I buy the 8 weakest, short the 8 strongest, equal notional. Each tranche closes exactly 12 hours later, unconditionally. Flat from 15:00 to 00:00 UTC every day. No stops on longs, a +30% disaster stop on shorts. It makes no bet on whether crypto goes up.
The edge is a timing anchor, not a chart pattern: 00:00 UTC is both a funding settlement and the daily candle boundary, so mechanical flow piles up around midnight and reverses once it stops.
THE OPEN BOOK — opened 01:01 UTC, closes 13:00 UTC
LONG
PROM +1.63%
MORPHO +2.01%
4 +0.55%
ZKC -0.87%
ZKP -1.05%
HEMI -2.71%
LAB -3.12%
CYS -16.71% <- the worst leg in the book
SHORT
SKR +12.55% <- the best leg in the book
BTR +7.39%
ARB +5.09%
LOBSTER +2.34%
NEAR +0.88%
AKE -9.98%
14 legs, $5 per name, ~$72 gross. Net: -$0.09, or -0.1% of equity, 9 hours in.
Yes. Flat. A 16% loser and a 12% winner in the same book cancelling each other out is not a bad day - that is the strategy working exactly as specified. It is paid by the spread between coins, not by direction.
THE ACCOUNT IS $85
That is deliberate, and it is the part most people get wrong. Month one exists to measure three things no backtest can give you: real slippage per side, what fraction of orders actually fill passively, and realised net return per position. I wrote the kill lines down before I sent the first order - if slippage exceeds 10 bps per side, or net return per position drops under +8 bps, it gets switched off regardless of P&L.
WHAT THE BACKTEST SAID
2021-03 to 2026-08, all costs and funding charged, marked at bar opens so there is no same-bar look-ahead:
+3.05% / month compounded
Sharpe 1.63 (1.51 from 2024 onward)
Max drawdown -31.4%
Worst month -12.4%
77% of months positive
And the three controls that matter more than any of those:
Random names, identical timing and size -> Sharpe -3.8
Same rule entered at 12–15 UTC instead -> Sharpe -2.3
Inverted: long the strongest -> Sharpe -3.1
If the first control had come back positive, the whole thing would have been the entry window and nothing else. It didn't. That is the test I trust.
WHAT I EXPECT TO HAPPEN
A -35% drawdown, and stretches of six months to a year underwater. At this Sharpe you need roughly three years of live returns to prove the edge exists. So I am not going to react to the P&L. I am going to record it, and judge the fill quality instead.
I will post the closed result of this exact book after 13:00 UTC, win or lose.
I built the backtesting tooling for this myself and it is free to use at virtuum-lab.com - write a rule, test it against real exchange data, see what it does before you risk anything.
Not financial advice. This is a live experiment on an account small enough that losing all of it teaches me something and costs me nothing.
I spent a month building a cross-sectional reversal strategy on Binance USDT-M perps, validated it in my own backtester, and switched it live on Aug 30. This is what it is holding at 10:00 UTC today.
THE RULE (nothing hidden)
Every day at 00–03 UTC I rank ~400 eligible USDT perps by their last 4 hours of return. I buy the 8 weakest, short the 8 strongest, equal notional. Each tranche closes exactly 12 hours later, unconditionally. Flat from 15:00 to 00:00 UTC every day. No stops on longs, a +30% disaster stop on shorts. It makes no bet on whether crypto goes up.
The edge is a timing anchor, not a chart pattern: 00:00 UTC is both a funding settlement and the daily candle boundary, so mechanical flow piles up around midnight and reverses once it stops.
THE OPEN BOOK — opened 01:01 UTC, closes 13:00 UTC
LONG
PROM +1.63%
MORPHO +2.01%
4 +0.55%
ZKC -0.87%
ZKP -1.05%
HEMI -2.71%
LAB -3.12%
CYS -16.71% <- the worst leg in the book
SHORT
SKR +12.55% <- the best leg in the book
BTR +7.39%
ARB +5.09%
LOBSTER +2.34%
NEAR +0.88%
AKE -9.98%
14 legs, $5 per name, ~$72 gross. Net: -$0.09, or -0.1% of equity, 9 hours in.
Yes. Flat. A 16% loser and a 12% winner in the same book cancelling each other out is not a bad day - that is the strategy working exactly as specified. It is paid by the spread between coins, not by direction.
THE ACCOUNT IS $85
That is deliberate, and it is the part most people get wrong. Month one exists to measure three things no backtest can give you: real slippage per side, what fraction of orders actually fill passively, and realised net return per position. I wrote the kill lines down before I sent the first order - if slippage exceeds 10 bps per side, or net return per position drops under +8 bps, it gets switched off regardless of P&L.
WHAT THE BACKTEST SAID
2021-03 to 2026-08, all costs and funding charged, marked at bar opens so there is no same-bar look-ahead:
+3.05% / month compounded
Sharpe 1.63 (1.51 from 2024 onward)
Max drawdown -31.4%
Worst month -12.4%
77% of months positive
And the three controls that matter more than any of those:
Random names, identical timing and size -> Sharpe -3.8
Same rule entered at 12–15 UTC instead -> Sharpe -2.3
Inverted: long the strongest -> Sharpe -3.1
If the first control had come back positive, the whole thing would have been the entry window and nothing else. It didn't. That is the test I trust.
WHAT I EXPECT TO HAPPEN
A -35% drawdown, and stretches of six months to a year underwater. At this Sharpe you need roughly three years of live returns to prove the edge exists. So I am not going to react to the P&L. I am going to record it, and judge the fill quality instead.
I will post the closed result of this exact book after 13:00 UTC, win or lose.
I built the backtesting tooling for this myself and it is free to use at virtuum-lab.com - write a rule, test it against real exchange data, see what it does before you risk anything.
Not financial advice. This is a live experiment on an account small enough that losing all of it teaches me something and costs me nothing.
304
·
--
Bacaan kuring tina backtester kuring sorangan nyebutkeun strategi kuring kalah ku ngan saukur teu ngalakukeun nanaon.
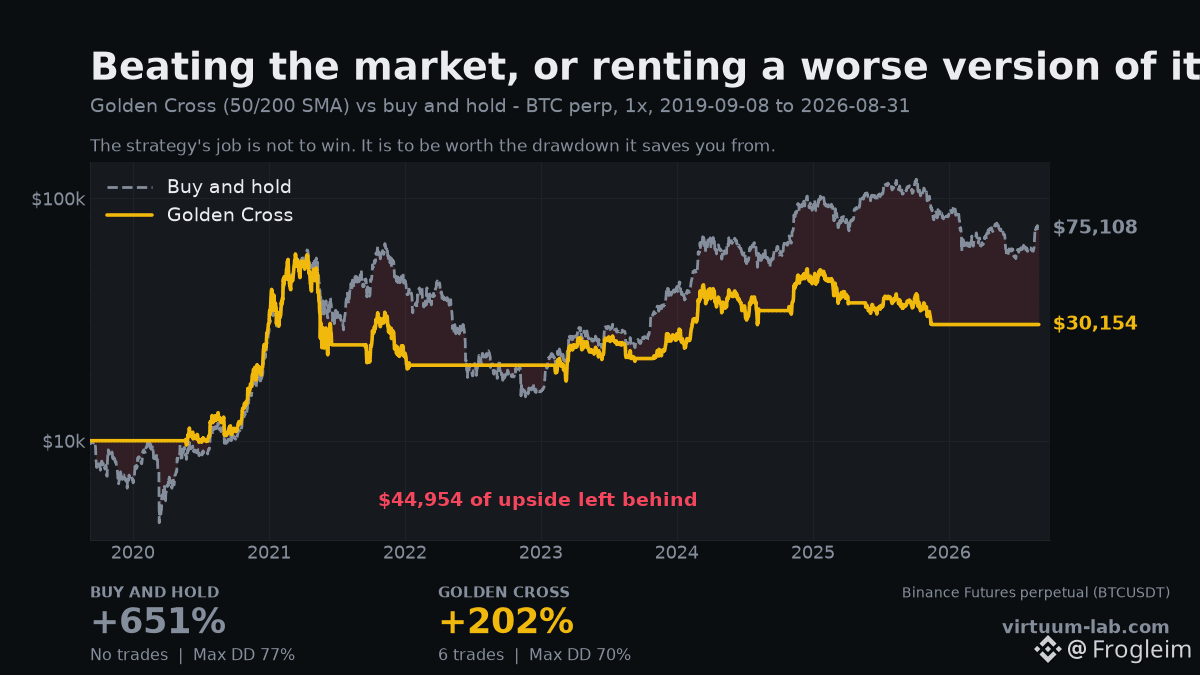
Golden Cross, 50/200 SMA, BTCUSDT perp dina 1x, ti 2019-09-08 nepi ka kiwari. Lawan buy and hold, dina jandela waktu nu sarua.
Buy and hold: +651%, max drawdown 77%
Golden Cross: +202%, max drawdown 70%
Genep transaksi salila tujuh taun, ahirna jadi leungit $44,954 ti batur anu meuli sakali sarta tuluy kabur ka luar.
Kuring unggah ieu sabab ieu perbandingan nu ampir teu aya nu ngajalankeun, sarta ngan ieu nu nangtukeun naha hiji strategi bener-bener aya hartina. Strategi mah lain keur bersaing jeung nol. Strategi bersaing jeung hal nu anjeun bakal lakukeun heula.
Di mana eta manggihan gunana, lamun memang aya gunana: drawdown. Nahan hartina ningali 77% ludes jeung teu ngajual. Rentang paling parah tina strategi nyaéta 70% — leuwih alus, tapi teu cukup pikeun ngajustifikasi genep kaputusan jeung genep taun perhatian.
Ieu hasil nyata tina alat kuring sorangan, sarta eta nyebutkeun yén strategina teu cukup alus. Backtester anu ngan bisa ngagombalkeun anjeun nyaéta cocooan.
Bandingkeun milik anjeun jeung buy and hold saméméh anjeun dagangkeun 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
Bacaan kuring tina backtester kuring sorangan nyebutkeun strategi kuring kalah ku ngan saukur teu ngalakukeun nanaon.
Golden Cross, 50/200 SMA, BTCUSDT perp dina 1x, ti 2019-09-08 nepi ka kiwari. Lawan buy and hold, dina jandela waktu nu sarua.
Buy and hold: +651%, max drawdown 77%
Golden Cross: +202%, max drawdown 70%
Genep transaksi salila tujuh taun, ahirna jadi leungit $44,954 ti batur anu meuli sakali sarta tuluy kabur ka luar.
Kuring unggah ieu sabab ieu perbandingan nu ampir teu aya nu ngajalankeun, sarta ngan ieu nu nangtukeun naha hiji strategi bener-bener aya hartina. Strategi mah lain keur bersaing jeung nol. Strategi bersaing jeung hal nu anjeun bakal lakukeun heula.
Di mana eta manggihan gunana, lamun memang aya gunana: drawdown. Nahan hartina ningali 77% ludes jeung teu ngajual. Rentang paling parah tina strategi nyaéta 70% — leuwih alus, tapi teu cukup pikeun ngajustifikasi genep kaputusan jeung genep taun perhatian.
Ieu hasil nyata tina alat kuring sorangan, sarta eta nyebutkeun yén strategina teu cukup alus. Backtester anu ngan bisa ngagombalkeun anjeun nyaéta cocooan.
Bandingkeun milik anjeun jeung buy and hold saméméh anjeun dagangkeun 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
Golden Cross, 50/200 SMA, BTCUSDT perp dina 1x, ti 2019-09-08 nepi ka kiwari. Lawan buy and hold, dina jandela waktu nu sarua.
Buy and hold: +651%, max drawdown 77%
Golden Cross: +202%, max drawdown 70%
Genep transaksi salila tujuh taun, ahirna jadi leungit $44,954 ti batur anu meuli sakali sarta tuluy kabur ka luar.
Kuring unggah ieu sabab ieu perbandingan nu ampir teu aya nu ngajalankeun, sarta ngan ieu nu nangtukeun naha hiji strategi bener-bener aya hartina. Strategi mah lain keur bersaing jeung nol. Strategi bersaing jeung hal nu anjeun bakal lakukeun heula.
Di mana eta manggihan gunana, lamun memang aya gunana: drawdown. Nahan hartina ningali 77% ludes jeung teu ngajual. Rentang paling parah tina strategi nyaéta 70% — leuwih alus, tapi teu cukup pikeun ngajustifikasi genep kaputusan jeung genep taun perhatian.
Ieu hasil nyata tina alat kuring sorangan, sarta eta nyebutkeun yén strategina teu cukup alus. Backtester anu ngan bisa ngagombalkeun anjeun nyaéta cocooan.
Bandingkeun milik anjeun jeung buy and hold saméméh anjeun dagangkeun 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
99
·
--
Ọ̀nà kan náà. Ìpẹ̀yà kan náà. Ìṣòro ìdánwò mẹ́wàá [five trades], ní ọjọ́ kan náà. Ẹgbẹ̀ méjì, tó yàtọ̀ sí 14 points.
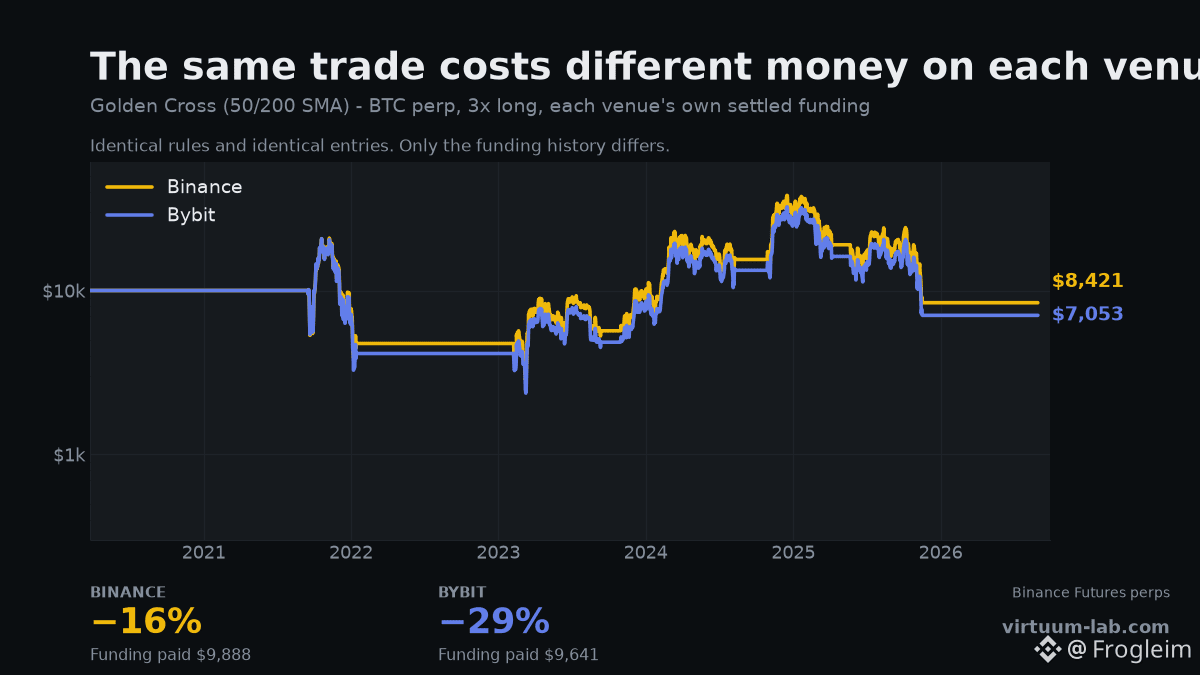
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 títí dé òní, ibi kọọkan ni san èrè ìdúró (settled funding) tirẹ̀.
Binance: −16% — $9,888 ti a san fún funding
Bybit: −29% — $9,641 ti a san fún funding
Àwọn ìwọlé àti ìjáde jọra gan-an. Àwọn ọjọ́ ìfọwọ́yíyàn jọra, gbogbo 5 nínú wọn. Kódà àwọn owó funding náà wà ní àyè díẹ̀ ọgọ̀rọ̀ (few hundred dollars) láàárín wọn, nítorí náà kì í ṣe ìyẹn ni ìdí náà.
Ààfiyèsí yàtọ̀ ni àwọn candle. Ẹgbẹ̀ kọ̀ọ̀kan ń tẹ́ ìye owo tirẹ̀ jáde, àti ìlànà tó ka “close above the 200 SMA” ń tú close tó yàtọ̀ díẹ̀ sí i lórí ọkọọkan. Ìlànà kan náà, ẹ̀rọ ìtẹ̀jade tó yàtọ̀, ìkún-owo (fills) tó yàtọ̀ — àti ìyàtọ̀ 14 points títí dé òpin.
Èyí túmọ̀ sí pé ìdánwò ẹ̀yẹ (backtest) jẹ́ gẹ́gẹ́ bí ojú-irin (venue) tí a ṣe e. Bí o bá dánwò lórí data ẹ̀rọ kan tí o sì rà tà lórí ẹ̀rọ míì, o ti dánwò ọgbọ́n tí o kò fi ránṣẹ́ (deploy).
Ó tún fi ààlà sí ìpamọ́ tó peye. Bí orísun data olóòótọ́ méjì bá yàtọ̀ sí 14 points lórí àwọn ìlànà tó dára gan-an, kò sí abajade backtest tí ó péye títí dé decimal point, àti ẹnikẹ́ni tó bá n sọ fún ọ pé ó péye sí ìyẹn ń ta nkan fún ọ.
Yan exchange tí o ń trade gangan 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Ọ̀nà kan náà. Ìpẹ̀yà kan náà. Ìṣòro ìdánwò mẹ́wàá [five trades], ní ọjọ́ kan náà. Ẹgbẹ̀ méjì, tó yàtọ̀ sí 14 points.
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 títí dé òní, ibi kọọkan ni san èrè ìdúró (settled funding) tirẹ̀.
Binance: −16% — $9,888 ti a san fún funding
Bybit: −29% — $9,641 ti a san fún funding
Àwọn ìwọlé àti ìjáde jọra gan-an. Àwọn ọjọ́ ìfọwọ́yíyàn jọra, gbogbo 5 nínú wọn. Kódà àwọn owó funding náà wà ní àyè díẹ̀ ọgọ̀rọ̀ (few hundred dollars) láàárín wọn, nítorí náà kì í ṣe ìyẹn ni ìdí náà.
Ààfiyèsí yàtọ̀ ni àwọn candle. Ẹgbẹ̀ kọ̀ọ̀kan ń tẹ́ ìye owo tirẹ̀ jáde, àti ìlànà tó ka “close above the 200 SMA” ń tú close tó yàtọ̀ díẹ̀ sí i lórí ọkọọkan. Ìlànà kan náà, ẹ̀rọ ìtẹ̀jade tó yàtọ̀, ìkún-owo (fills) tó yàtọ̀ — àti ìyàtọ̀ 14 points títí dé òpin.
Èyí túmọ̀ sí pé ìdánwò ẹ̀yẹ (backtest) jẹ́ gẹ́gẹ́ bí ojú-irin (venue) tí a ṣe e. Bí o bá dánwò lórí data ẹ̀rọ kan tí o sì rà tà lórí ẹ̀rọ míì, o ti dánwò ọgbọ́n tí o kò fi ránṣẹ́ (deploy).
Ó tún fi ààlà sí ìpamọ́ tó peye. Bí orísun data olóòótọ́ méjì bá yàtọ̀ sí 14 points lórí àwọn ìlànà tó dára gan-an, kò sí abajade backtest tí ó péye títí dé decimal point, àti ẹnikẹ́ni tó bá n sọ fún ọ pé ó péye sí ìyẹn ń ta nkan fún ọ.
Yan exchange tí o ń trade gangan 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 títí dé òní, ibi kọọkan ni san èrè ìdúró (settled funding) tirẹ̀.
Binance: −16% — $9,888 ti a san fún funding
Bybit: −29% — $9,641 ti a san fún funding
Àwọn ìwọlé àti ìjáde jọra gan-an. Àwọn ọjọ́ ìfọwọ́yíyàn jọra, gbogbo 5 nínú wọn. Kódà àwọn owó funding náà wà ní àyè díẹ̀ ọgọ̀rọ̀ (few hundred dollars) láàárín wọn, nítorí náà kì í ṣe ìyẹn ni ìdí náà.
Ààfiyèsí yàtọ̀ ni àwọn candle. Ẹgbẹ̀ kọ̀ọ̀kan ń tẹ́ ìye owo tirẹ̀ jáde, àti ìlànà tó ka “close above the 200 SMA” ń tú close tó yàtọ̀ díẹ̀ sí i lórí ọkọọkan. Ìlànà kan náà, ẹ̀rọ ìtẹ̀jade tó yàtọ̀, ìkún-owo (fills) tó yàtọ̀ — àti ìyàtọ̀ 14 points títí dé òpin.
Èyí túmọ̀ sí pé ìdánwò ẹ̀yẹ (backtest) jẹ́ gẹ́gẹ́ bí ojú-irin (venue) tí a ṣe e. Bí o bá dánwò lórí data ẹ̀rọ kan tí o sì rà tà lórí ẹ̀rọ míì, o ti dánwò ọgbọ́n tí o kò fi ránṣẹ́ (deploy).
Ó tún fi ààlà sí ìpamọ́ tó peye. Bí orísun data olóòótọ́ méjì bá yàtọ̀ sí 14 points lórí àwọn ìlànà tó dára gan-an, kò sí abajade backtest tí ó péye títí dé decimal point, àti ẹnikẹ́ni tó bá n sọ fún ọ pé ó péye sí ìyẹn ń ta nkan fún ọ.
Yan exchange tí o ń trade gangan 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
103
·
--
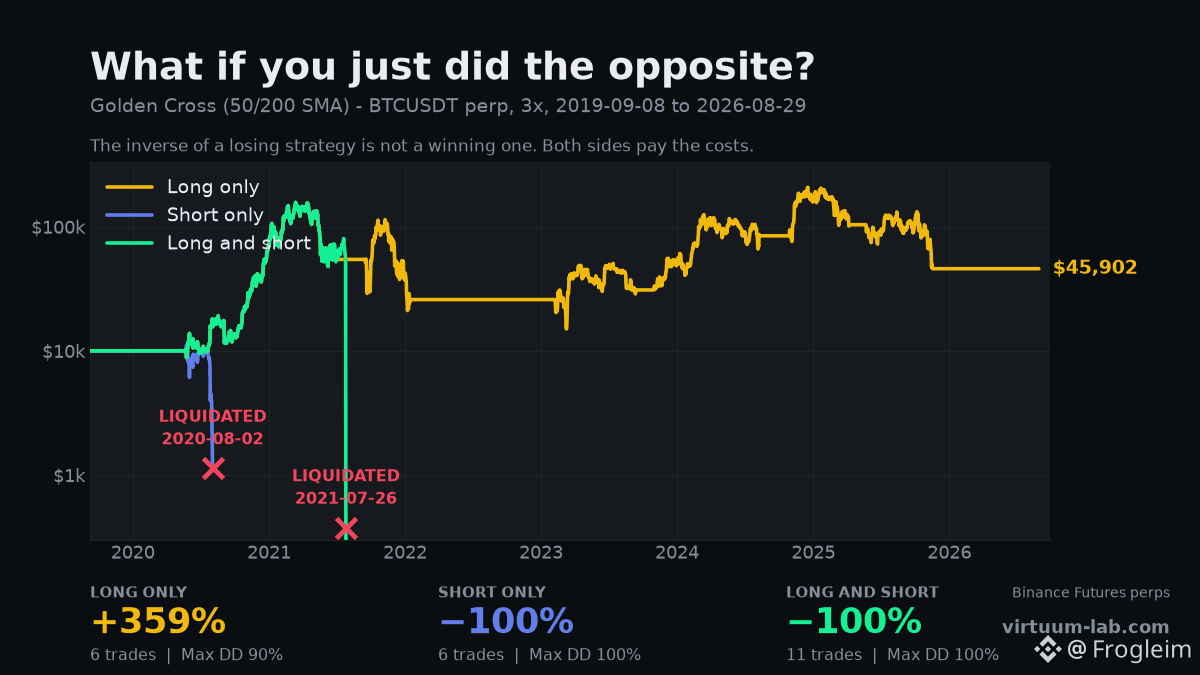
"Basta gumawa ng kabaligtaran ng isang nawawalang strategy." Sige, sinubukan ko.
Golden Cross, 50/200 SMA, 3x, BTCUSDT perp, 2019-09-08 hanggang ngayon, totoong Binance funding na sinisingil.
Long lang: +359%
Short lang: −100% — na-liquidate
Long at short: −100% — na-liquidate
Ang inverso ng isang strategy ay hindi ito eksaktong mirror image nito, at iyon ang bahagi na hindi napapansin ng mga tao.
Hindi nagbabago ang mga gastos ayon sa iyo. Ang funding, fees at slippage ay sinisingil sa parehong direksyon, kaya ang isang strategy na kumakain ng kaunti habang long ay talo rin na *kasama* ang parehong gastos ulit kapag short. Namamana mo ang mga lugi at binabayaran mo ang toll nang dalawang beses.
At ang asymmetry ay grabe sa perp. Ang long ay puwedeng mawala ang 100% ng margin nito. Ang short ay nasa harap ng isang asset na puwedeng tumaas nang walang limit, kaya ang short-only run ay hindi lang nag-underperform — nai-liquidate ito at humihinto nang tuluyan.
Ang pagkuha sa kabilang side ng isang masamang strategy ay nagbibigay sa iyo ng ibang masamang strategy. Ang talagang kumikita ay hindi pagkakaroon ng mga costs, at tanging paraan para malaman ay ang pagsingil nang tama sa mga iyon.
Patakbuhin nang long, short, o pareho, at tingnan 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Shorting
"Basta gumawa ng kabaligtaran ng isang nawawalang strategy." Sige, sinubukan ko.
Golden Cross, 50/200 SMA, 3x, BTCUSDT perp, 2019-09-08 hanggang ngayon, totoong Binance funding na sinisingil.
Long lang: +359%
Short lang: −100% — na-liquidate
Long at short: −100% — na-liquidate
Ang inverso ng isang strategy ay hindi ito eksaktong mirror image nito, at iyon ang bahagi na hindi napapansin ng mga tao.
Hindi nagbabago ang mga gastos ayon sa iyo. Ang funding, fees at slippage ay sinisingil sa parehong direksyon, kaya ang isang strategy na kumakain ng kaunti habang long ay talo rin na *kasama* ang parehong gastos ulit kapag short. Namamana mo ang mga lugi at binabayaran mo ang toll nang dalawang beses.
At ang asymmetry ay grabe sa perp. Ang long ay puwedeng mawala ang 100% ng margin nito. Ang short ay nasa harap ng isang asset na puwedeng tumaas nang walang limit, kaya ang short-only run ay hindi lang nag-underperform — nai-liquidate ito at humihinto nang tuluyan.
Ang pagkuha sa kabilang side ng isang masamang strategy ay nagbibigay sa iyo ng ibang masamang strategy. Ang talagang kumikita ay hindi pagkakaroon ng mga costs, at tanging paraan para malaman ay ang pagsingil nang tama sa mga iyon.
Patakbuhin nang long, short, o pareho, at tingnan 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Shorting
Golden Cross, 50/200 SMA, 3x, BTCUSDT perp, 2019-09-08 hanggang ngayon, totoong Binance funding na sinisingil.
Long lang: +359%
Short lang: −100% — na-liquidate
Long at short: −100% — na-liquidate
Ang inverso ng isang strategy ay hindi ito eksaktong mirror image nito, at iyon ang bahagi na hindi napapansin ng mga tao.
Hindi nagbabago ang mga gastos ayon sa iyo. Ang funding, fees at slippage ay sinisingil sa parehong direksyon, kaya ang isang strategy na kumakain ng kaunti habang long ay talo rin na *kasama* ang parehong gastos ulit kapag short. Namamana mo ang mga lugi at binabayaran mo ang toll nang dalawang beses.
At ang asymmetry ay grabe sa perp. Ang long ay puwedeng mawala ang 100% ng margin nito. Ang short ay nasa harap ng isang asset na puwedeng tumaas nang walang limit, kaya ang short-only run ay hindi lang nag-underperform — nai-liquidate ito at humihinto nang tuluyan.
Ang pagkuha sa kabilang side ng isang masamang strategy ay nagbibigay sa iyo ng ibang masamang strategy. Ang talagang kumikita ay hindi pagkakaroon ng mga costs, at tanging paraan para malaman ay ang pagsingil nang tama sa mga iyon.
Patakbuhin nang long, short, o pareho, at tingnan 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Shorting
92
·
--
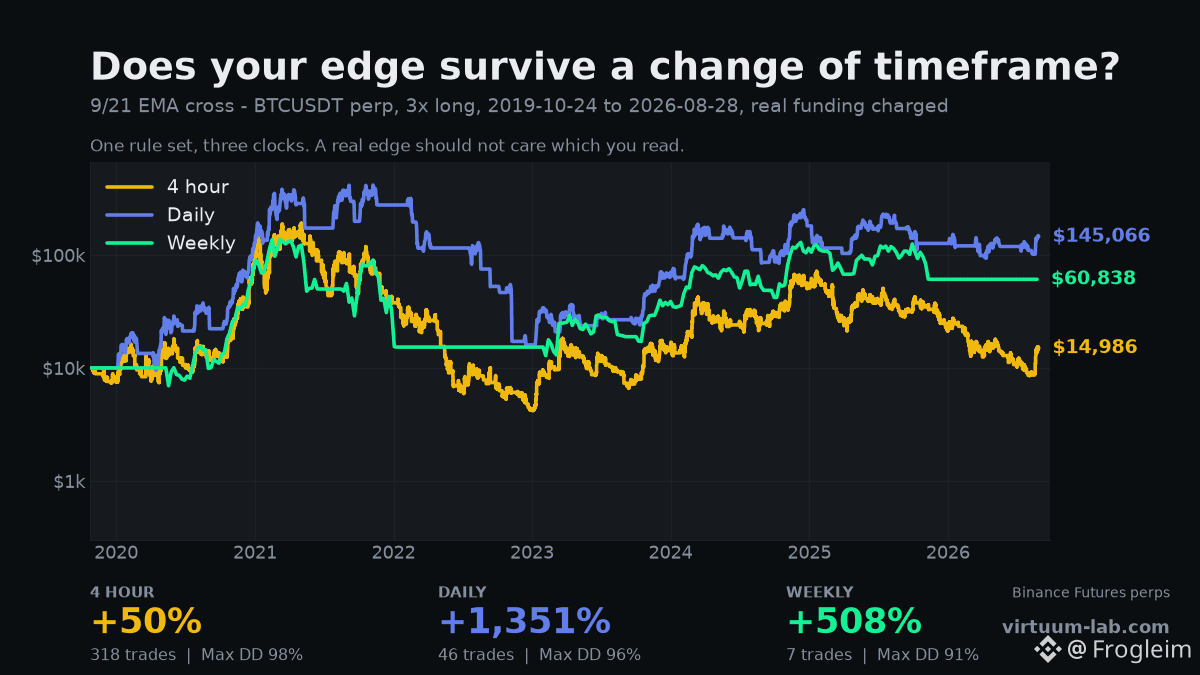
ច្បាប់ដូចគ្នា។ នាឡិកា 3 គ្រឿង។ ចន្លោះ 1,301 ចំណុច។
ការឆ្លង 9/21 EMA, ឡុង BTCUSDT perp 3x, funding ពិតប្រាកដរបស់ Binance, បង្អួចដូចគ្នាលើនាឡិកាទាំងបី ដើម្បីឲ្យគ្មានអ្វីបានចាប់ផ្តើមមុនឡើយ។
4 ម៉ោង: +50% — 318 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 98%
ប្រចាំថ្ងៃ: +1,351% — 46 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 96%
ប្រចាំសប្ដាហ៍: +508% — 7 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 91%
គ្មានអ្នកណាជ្រើសរើស timeframe ដោយគ្មានហេតុផល។ អ្នកបានជ្រើសរើសមួយដែលតារាង (chart) របស់អ្នកបើកនៅលើវា។
កំណែ 4 ម៉ោង ធ្វើពាណិជ្ជកម្ម 318 ដង ហើយប្រគល់វាភាគច្រើនត្រឡប់វិញ — រាល់ការឆ្លងនីមួយៗចំណាយថ្លៃ, slippage និង funding ហើយនៅលើនាឡិការលឿន ការឆ្លងភាគច្រើនគ្រាន់តែជាសំឡេង (noise)។ កំណែប្រចាំសប្ដាហ៍ យកតែ 7 ការធ្វើពាណិជ្ជកម្ម ក្នុង 41 ឆ្នាំ និងរក្សាទុកអ្វីដែលវារកបានបានច្រើនជាង។
ការអានដែលមិនស្រួល: ប្រសិនបើយុទ្ធសាស្ត្រ (strategy) ដំណើរការតែ timeframe មួយ នោះ timeframe កំពុងធ្វើការងារ មិនមែន strategy ទេ។ អត្ថប្រយោជន៍ពិត (real edge) ធ្លាក់ថយយ៉ាងរលូនពេលអ្នកប្តូរនាឡិកា។ មួយនេះមិនមែនបែបនោះទេ — វារញ្ជួយដោយ 1,301 ចំណុច។
មុននឹងអ្នកទុកចិត្ត backtest សូមដំណើរការវានៅលើ timeframe នៅម្ខាងទាំងពីរនៃមួយដែលអ្នកពេញចិត្ត។
ប្តូរនាឡិកា ហើយមើលថាអ្វីនៅរស់ 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
ច្បាប់ដូចគ្នា។ នាឡិកា 3 គ្រឿង។ ចន្លោះ 1,301 ចំណុច។
ការឆ្លង 9/21 EMA, ឡុង BTCUSDT perp 3x, funding ពិតប្រាកដរបស់ Binance, បង្អួចដូចគ្នាលើនាឡិកាទាំងបី ដើម្បីឲ្យគ្មានអ្វីបានចាប់ផ្តើមមុនឡើយ។
4 ម៉ោង: +50% — 318 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 98%
ប្រចាំថ្ងៃ: +1,351% — 46 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 96%
ប្រចាំសប្ដាហ៍: +508% — 7 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 91%
គ្មានអ្នកណាជ្រើសរើស timeframe ដោយគ្មានហេតុផល។ អ្នកបានជ្រើសរើសមួយដែលតារាង (chart) របស់អ្នកបើកនៅលើវា។
កំណែ 4 ម៉ោង ធ្វើពាណិជ្ជកម្ម 318 ដង ហើយប្រគល់វាភាគច្រើនត្រឡប់វិញ — រាល់ការឆ្លងនីមួយៗចំណាយថ្លៃ, slippage និង funding ហើយនៅលើនាឡិការលឿន ការឆ្លងភាគច្រើនគ្រាន់តែជាសំឡេង (noise)។ កំណែប្រចាំសប្ដាហ៍ យកតែ 7 ការធ្វើពាណិជ្ជកម្ម ក្នុង 41 ឆ្នាំ និងរក្សាទុកអ្វីដែលវារកបានបានច្រើនជាង។
ការអានដែលមិនស្រួល: ប្រសិនបើយុទ្ធសាស្ត្រ (strategy) ដំណើរការតែ timeframe មួយ នោះ timeframe កំពុងធ្វើការងារ មិនមែន strategy ទេ។ អត្ថប្រយោជន៍ពិត (real edge) ធ្លាក់ថយយ៉ាងរលូនពេលអ្នកប្តូរនាឡិកា។ មួយនេះមិនមែនបែបនោះទេ — វារញ្ជួយដោយ 1,301 ចំណុច។
មុននឹងអ្នកទុកចិត្ត backtest សូមដំណើរការវានៅលើ timeframe នៅម្ខាងទាំងពីរនៃមួយដែលអ្នកពេញចិត្ត។
ប្តូរនាឡិកា ហើយមើលថាអ្វីនៅរស់ 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
ការឆ្លង 9/21 EMA, ឡុង BTCUSDT perp 3x, funding ពិតប្រាកដរបស់ Binance, បង្អួចដូចគ្នាលើនាឡិកាទាំងបី ដើម្បីឲ្យគ្មានអ្វីបានចាប់ផ្តើមមុនឡើយ។
4 ម៉ោង: +50% — 318 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 98%
ប្រចាំថ្ងៃ: +1,351% — 46 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 96%
ប្រចាំសប្ដាហ៍: +508% — 7 ការធ្វើពាណិជ្ជកម្ម, ការខាតបង់អតិបរមា 91%
គ្មានអ្នកណាជ្រើសរើស timeframe ដោយគ្មានហេតុផល។ អ្នកបានជ្រើសរើសមួយដែលតារាង (chart) របស់អ្នកបើកនៅលើវា។
កំណែ 4 ម៉ោង ធ្វើពាណិជ្ជកម្ម 318 ដង ហើយប្រគល់វាភាគច្រើនត្រឡប់វិញ — រាល់ការឆ្លងនីមួយៗចំណាយថ្លៃ, slippage និង funding ហើយនៅលើនាឡិការលឿន ការឆ្លងភាគច្រើនគ្រាន់តែជាសំឡេង (noise)។ កំណែប្រចាំសប្ដាហ៍ យកតែ 7 ការធ្វើពាណិជ្ជកម្ម ក្នុង 41 ឆ្នាំ និងរក្សាទុកអ្វីដែលវារកបានបានច្រើនជាង។
ការអានដែលមិនស្រួល: ប្រសិនបើយុទ្ធសាស្ត្រ (strategy) ដំណើរការតែ timeframe មួយ នោះ timeframe កំពុងធ្វើការងារ មិនមែន strategy ទេ។ អត្ថប្រយោជន៍ពិត (real edge) ធ្លាក់ថយយ៉ាងរលូនពេលអ្នកប្តូរនាឡិកា។ មួយនេះមិនមែនបែបនោះទេ — វារញ្ជួយដោយ 1,301 ចំណុច។
មុននឹងអ្នកទុកចិត្ត backtest សូមដំណើរការវានៅលើ timeframe នៅម្ខាងទាំងពីរនៃមួយដែលអ្នកពេញចិត្ត។
ប្តូរនាឡិកា ហើយមើលថាអ្វីនៅរស់ 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
96
·
--
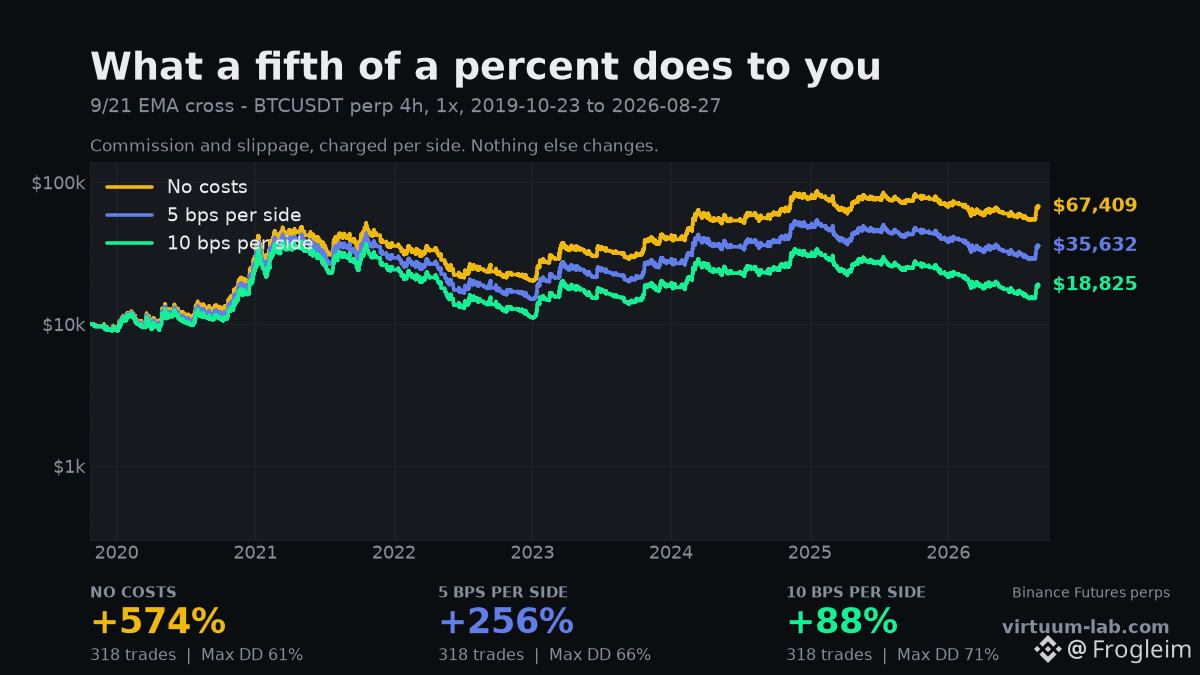
0.1% a trade cost this strategy 486 points.
ការឆ្លងកាត់ 9/21 EMA នៅលើ BTCUSDT perp, បារ 4 ម៉ោង, 1x, ចាប់ពី 2019-10-23 រហូតដល់ថ្ងៃនេះ។ 318 ការប្តូរ។ យុទ្ធសាស្ត្រនេះមិនផ្លាស់ប្តូរ—មានតែអ្វីដែលកម្រៃនៃការប្តូរនីមួយៗប៉ុណ្ណោះ។
គ្មានថ្លៃសោះ: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps គឺ 0.1%។ វាជាអ្វីដែលអ្នកពិតជាបង់ជា taker ប្រហាក់ប្រហែល នៅពេលរាប់ spread និង slippage ហើយវាប្រែក្លាយ backtest ដ៏អស្ចារ្យមួយ ទៅជារឿងធម្មតាវិញ។
ហេតុអ្វីវាខ្លាំងដូចនេះ? មាន 318 ការប្តូរ។ ថ្លៃត្រូវបានគិតក្នុងមួយការប្តូរ ដូច្នេះវាកើនតាមសកម្មភាព ខណៈដែលសមត្ថភាពអត្ថប្រយោជន៍របស់អ្នកមិនកើន។ យុទ្ធសាស្ត្រយឺតអាចមិនខ្វល់ថ្លៃ។ យុទ្ធសាស្ត្រដែលធ្វើការប្តូររៀងរាល់ពីរបីថ្ងៃម្តង មិនអាចមិនខ្វល់បានទេ—វាកំពុងបង់ជួល 318 ដង។
នេះហើយជាមូលហេតុដែលកំហុស backtesting ដែលពบบ្រើច្រើន មិនមែនជាសញ្ញាអាក្រក់ទេ។ វាជា “សូន្យ” នៅប្រអប់ថ្លៃ។ យុទ្ធសាស្ត្រដែលមានប្រេកង់ខ្ពស់ទាំងអស់មើលទៅអស្ចារ្យនៅ 0 bps។
បើ backtester របស់អ្នកមិនគិត commission និង slippage ក្នុងមួយ side នោះ វាមិនមែនជាការធ្វើតេស្តយុទ្ធសាស្ត្ររបស់អ្នកទេ។ វាកំពុងធ្វើតេស្តកំណែប្រឌិតដែលធ្វើការប្តូរដោយឥតគិតថ្លៃ។
គិតថ្លៃឲ្យខ្លួនឯងដូចអ្វីដែល exchange របស់អ្នកគិត 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
0.1% a trade cost this strategy 486 points.
ការឆ្លងកាត់ 9/21 EMA នៅលើ BTCUSDT perp, បារ 4 ម៉ោង, 1x, ចាប់ពី 2019-10-23 រហូតដល់ថ្ងៃនេះ។ 318 ការប្តូរ។ យុទ្ធសាស្ត្រនេះមិនផ្លាស់ប្តូរ—មានតែអ្វីដែលកម្រៃនៃការប្តូរនីមួយៗប៉ុណ្ណោះ។
គ្មានថ្លៃសោះ: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps គឺ 0.1%។ វាជាអ្វីដែលអ្នកពិតជាបង់ជា taker ប្រហាក់ប្រហែល នៅពេលរាប់ spread និង slippage ហើយវាប្រែក្លាយ backtest ដ៏អស្ចារ្យមួយ ទៅជារឿងធម្មតាវិញ។
ហេតុអ្វីវាខ្លាំងដូចនេះ? មាន 318 ការប្តូរ។ ថ្លៃត្រូវបានគិតក្នុងមួយការប្តូរ ដូច្នេះវាកើនតាមសកម្មភាព ខណៈដែលសមត្ថភាពអត្ថប្រយោជន៍របស់អ្នកមិនកើន។ យុទ្ធសាស្ត្រយឺតអាចមិនខ្វល់ថ្លៃ។ យុទ្ធសាស្ត្រដែលធ្វើការប្តូររៀងរាល់ពីរបីថ្ងៃម្តង មិនអាចមិនខ្វល់បានទេ—វាកំពុងបង់ជួល 318 ដង។
នេះហើយជាមូលហេតុដែលកំហុស backtesting ដែលពบบ្រើច្រើន មិនមែនជាសញ្ញាអាក្រក់ទេ។ វាជា “សូន្យ” នៅប្រអប់ថ្លៃ។ យុទ្ធសាស្ត្រដែលមានប្រេកង់ខ្ពស់ទាំងអស់មើលទៅអស្ចារ្យនៅ 0 bps។
បើ backtester របស់អ្នកមិនគិត commission និង slippage ក្នុងមួយ side នោះ វាមិនមែនជាការធ្វើតេស្តយុទ្ធសាស្ត្ររបស់អ្នកទេ។ វាកំពុងធ្វើតេស្តកំណែប្រឌិតដែលធ្វើការប្តូរដោយឥតគិតថ្លៃ។
គិតថ្លៃឲ្យខ្លួនឯងដូចអ្វីដែល exchange របស់អ្នកគិត 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
ការឆ្លងកាត់ 9/21 EMA នៅលើ BTCUSDT perp, បារ 4 ម៉ោង, 1x, ចាប់ពី 2019-10-23 រហូតដល់ថ្ងៃនេះ។ 318 ការប្តូរ។ យុទ្ធសាស្ត្រនេះមិនផ្លាស់ប្តូរ—មានតែអ្វីដែលកម្រៃនៃការប្តូរនីមួយៗប៉ុណ្ណោះ។
គ្មានថ្លៃសោះ: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps គឺ 0.1%។ វាជាអ្វីដែលអ្នកពិតជាបង់ជា taker ប្រហាក់ប្រហែល នៅពេលរាប់ spread និង slippage ហើយវាប្រែក្លាយ backtest ដ៏អស្ចារ្យមួយ ទៅជារឿងធម្មតាវិញ។
ហេតុអ្វីវាខ្លាំងដូចនេះ? មាន 318 ការប្តូរ។ ថ្លៃត្រូវបានគិតក្នុងមួយការប្តូរ ដូច្នេះវាកើនតាមសកម្មភាព ខណៈដែលសមត្ថភាពអត្ថប្រយោជន៍របស់អ្នកមិនកើន។ យុទ្ធសាស្ត្រយឺតអាចមិនខ្វល់ថ្លៃ។ យុទ្ធសាស្ត្រដែលធ្វើការប្តូររៀងរាល់ពីរបីថ្ងៃម្តង មិនអាចមិនខ្វល់បានទេ—វាកំពុងបង់ជួល 318 ដង។
នេះហើយជាមូលហេតុដែលកំហុស backtesting ដែលពบบ្រើច្រើន មិនមែនជាសញ្ញាអាក្រក់ទេ។ វាជា “សូន្យ” នៅប្រអប់ថ្លៃ។ យុទ្ធសាស្ត្រដែលមានប្រេកង់ខ្ពស់ទាំងអស់មើលទៅអស្ចារ្យនៅ 0 bps។
បើ backtester របស់អ្នកមិនគិត commission និង slippage ក្នុងមួយ side នោះ វាមិនមែនជាការធ្វើតេស្តយុទ្ធសាស្ត្ររបស់អ្នកទេ។ វាកំពុងធ្វើតេស្តកំណែប្រឌិតដែលធ្វើការប្តូរដោយឥតគិតថ្លៃ។
គិតថ្លៃឲ្យខ្លួនឯងដូចអ្វីដែល exchange របស់អ្នកគិត 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
117
·
--
ເບິ່ງການແປ
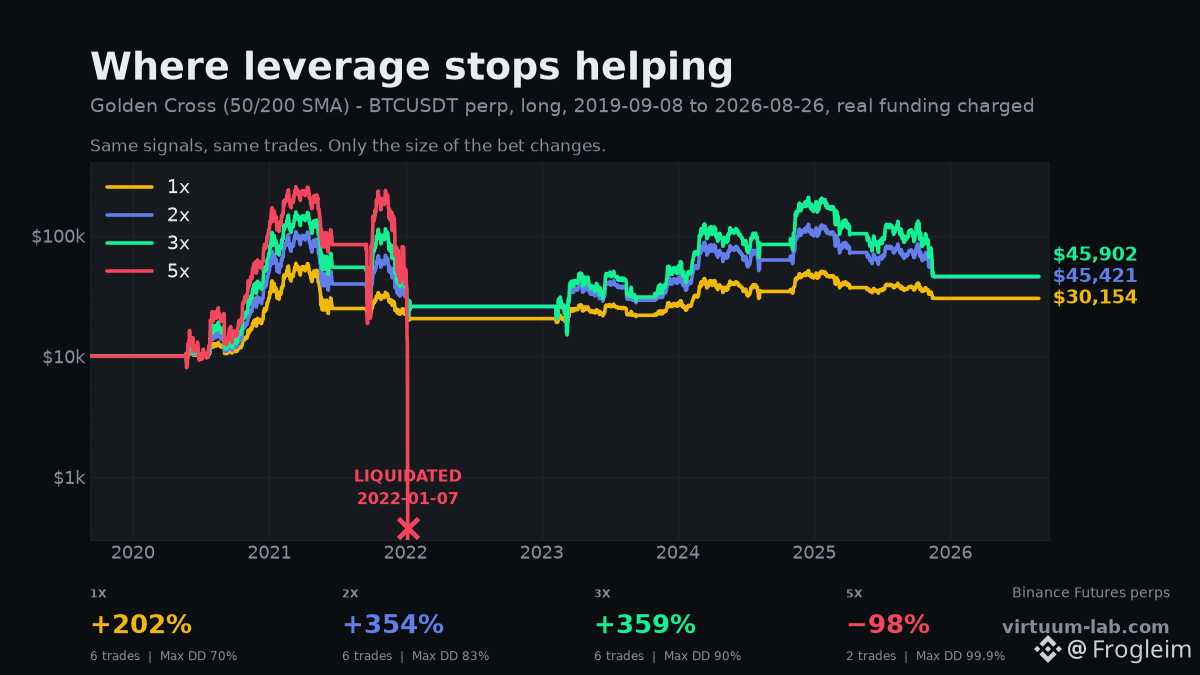
3x nearly doubled my return. 5x deleted the account.
Golden Cross, 50/200 SMA, long BTCUSDT perp, 2019-09-08 to today, real Binance funding charged. Same signals, same 6 trades. The only thing that changes is the size of the bet.
1x: +202%
2x: +354%
3x: +359%
5x: −98% — liquidated
Look at where it stops paying. Going from 1x to 2x adds serious return. Going from 2x to 3x adds almost nothing, because funding scales with the position and eats what the leverage adds.
And 5x never gets to find out. It's liquidated 7 Jan 2022, 2 trades in, and there is no coming back from that — the remaining four signals happen to an account with nothing in it.
That's the part a return curve hides. Leverage doesn't scale your outcome, it scales your outcome until the first time it doesn't, and then the number is −100% forever.
Max drawdown at 3x is 90%. If that number doesn't frighten you, you haven't sat through one.
Find your own cliff before the market shows you where it is 👉 https://virtuum-lab.com
#BTC #Leverage #TradingStrategy
3x nearly doubled my return. 5x deleted the account.
Golden Cross, 50/200 SMA, long BTCUSDT perp, 2019-09-08 to today, real Binance funding charged. Same signals, same 6 trades. The only thing that changes is the size of the bet.
1x: +202%
2x: +354%
3x: +359%
5x: −98% — liquidated
Look at where it stops paying. Going from 1x to 2x adds serious return. Going from 2x to 3x adds almost nothing, because funding scales with the position and eats what the leverage adds.
And 5x never gets to find out. It's liquidated 7 Jan 2022, 2 trades in, and there is no coming back from that — the remaining four signals happen to an account with nothing in it.
That's the part a return curve hides. Leverage doesn't scale your outcome, it scales your outcome until the first time it doesn't, and then the number is −100% forever.
Max drawdown at 3x is 90%. If that number doesn't frighten you, you haven't sat through one.
Find your own cliff before the market shows you where it is 👉 https://virtuum-lab.com
#BTC #Leverage #TradingStrategy
Golden Cross, 50/200 SMA, long BTCUSDT perp, 2019-09-08 to today, real Binance funding charged. Same signals, same 6 trades. The only thing that changes is the size of the bet.
1x: +202%
2x: +354%
3x: +359%
5x: −98% — liquidated
Look at where it stops paying. Going from 1x to 2x adds serious return. Going from 2x to 3x adds almost nothing, because funding scales with the position and eats what the leverage adds.
And 5x never gets to find out. It's liquidated 7 Jan 2022, 2 trades in, and there is no coming back from that — the remaining four signals happen to an account with nothing in it.
That's the part a return curve hides. Leverage doesn't scale your outcome, it scales your outcome until the first time it doesn't, and then the number is −100% forever.
Max drawdown at 3x is 90%. If that number doesn't frighten you, you haven't sat through one.
Find your own cliff before the market shows you where it is 👉 https://virtuum-lab.com
#BTC #Leverage #TradingStrategy
134
·
--
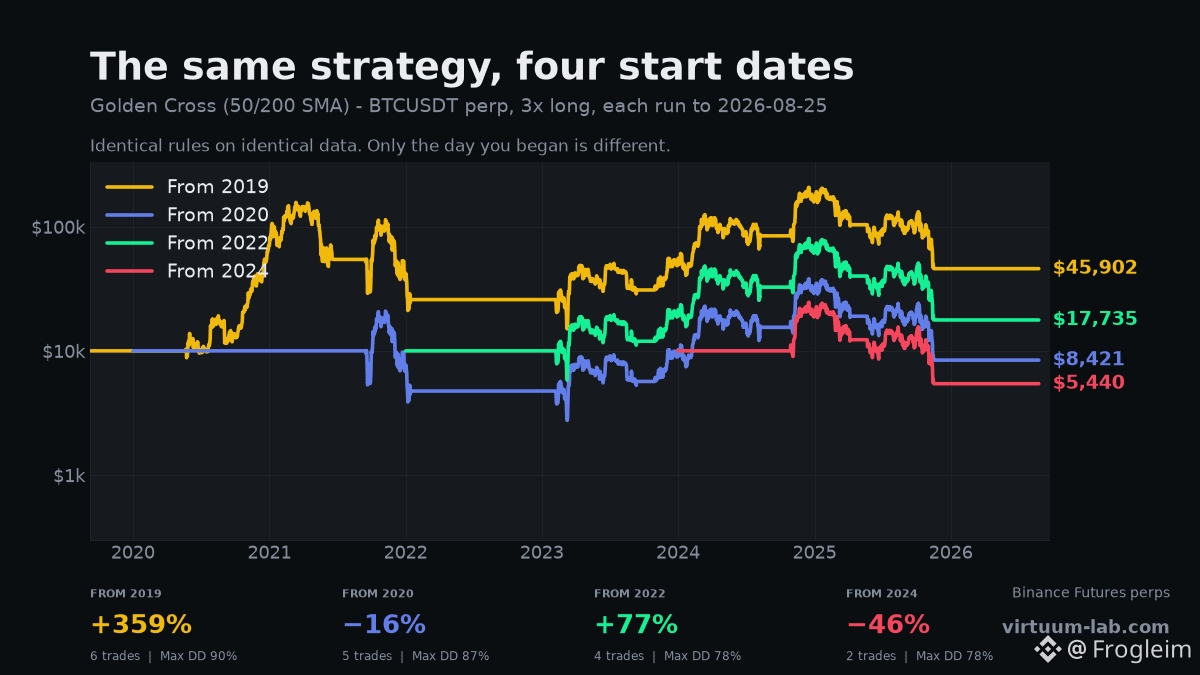
同一の戦略で +359% と −46% を出しています。違いは、始めた日のみでした。
ゴールデンクロス、50/200 SMA、3倍ロングのBTCUSDTパーペチュアル、実際のBinanceの資金調達(ファンディング)を請求。ルールも同じ、データも同じ。4つとも今日まで稼働中。唯一の変数は、スイッチを入れたタイミングだけです。
2019年に開始:+359%
2020年に開始:−16%
2022年に開始:+77%
2024年に開始:−46%
スプレッドは405ポイントで、戦略が変わった行は1行もありません。
誰も公表しない数字です。誰かがバックテストを見せてきたら、その時点で彼らはすでに開始日を選んでいます。そして、その開始日は結果を見た後に選ばれています。そこから1年ずらすと、同じルールが“幸運”から“穴”に変わります。
時間が経って運が均されている、という話でもありません。2019年の稼働は、とても大きなトレンドを十分早く掴んでくれたので、その後のすべてを支払えるだけのものになりました。2024年の稼働は2回の取引で終わり、その“贈り物”には一度も出会えませんでした。
どうすればいいか:信じる前に、複数の開始日であなたのルールを走らせてください。答えが特定のある火曜日にだけしか機能しないなら、それはエッジではなく、良いマーケティングによる偶然です。
好きな開始日すべてで、同じルールをテストしてみてください 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
同一の戦略で +359% と −46% を出しています。違いは、始めた日のみでした。
ゴールデンクロス、50/200 SMA、3倍ロングのBTCUSDTパーペチュアル、実際のBinanceの資金調達(ファンディング)を請求。ルールも同じ、データも同じ。4つとも今日まで稼働中。唯一の変数は、スイッチを入れたタイミングだけです。
2019年に開始:+359%
2020年に開始:−16%
2022年に開始:+77%
2024年に開始:−46%
スプレッドは405ポイントで、戦略が変わった行は1行もありません。
誰も公表しない数字です。誰かがバックテストを見せてきたら、その時点で彼らはすでに開始日を選んでいます。そして、その開始日は結果を見た後に選ばれています。そこから1年ずらすと、同じルールが“幸運”から“穴”に変わります。
時間が経って運が均されている、という話でもありません。2019年の稼働は、とても大きなトレンドを十分早く掴んでくれたので、その後のすべてを支払えるだけのものになりました。2024年の稼働は2回の取引で終わり、その“贈り物”には一度も出会えませんでした。
どうすればいいか:信じる前に、複数の開始日であなたのルールを走らせてください。答えが特定のある火曜日にだけしか機能しないなら、それはエッジではなく、良いマーケティングによる偶然です。
好きな開始日すべてで、同じルールをテストしてみてください 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
ゴールデンクロス、50/200 SMA、3倍ロングのBTCUSDTパーペチュアル、実際のBinanceの資金調達(ファンディング)を請求。ルールも同じ、データも同じ。4つとも今日まで稼働中。唯一の変数は、スイッチを入れたタイミングだけです。
2019年に開始:+359%
2020年に開始:−16%
2022年に開始:+77%
2024年に開始:−46%
スプレッドは405ポイントで、戦略が変わった行は1行もありません。
誰も公表しない数字です。誰かがバックテストを見せてきたら、その時点で彼らはすでに開始日を選んでいます。そして、その開始日は結果を見た後に選ばれています。そこから1年ずらすと、同じルールが“幸運”から“穴”に変わります。
時間が経って運が均されている、という話でもありません。2019年の稼働は、とても大きなトレンドを十分早く掴んでくれたので、その後のすべてを支払えるだけのものになりました。2024年の稼働は2回の取引で終わり、その“贈り物”には一度も出会えませんでした。
どうすればいいか:信じる前に、複数の開始日であなたのルールを走らせてください。答えが特定のある火曜日にだけしか機能しないなら、それはエッジではなく、良いマーケティングによる偶然です。
好きな開始日すべてで、同じルールをテストしてみてください 👉 https://virtuum-lab.com
#BTC #Backtesting #TradingStrategy
112
·
--
ເບິ່ງການແປ
Same strategy. Three coins. Two accounts went to zero.
My last post showed what real funding does to a Golden Cross on BTC. The obvious next question: does the strategy work, or does BTC just go up?
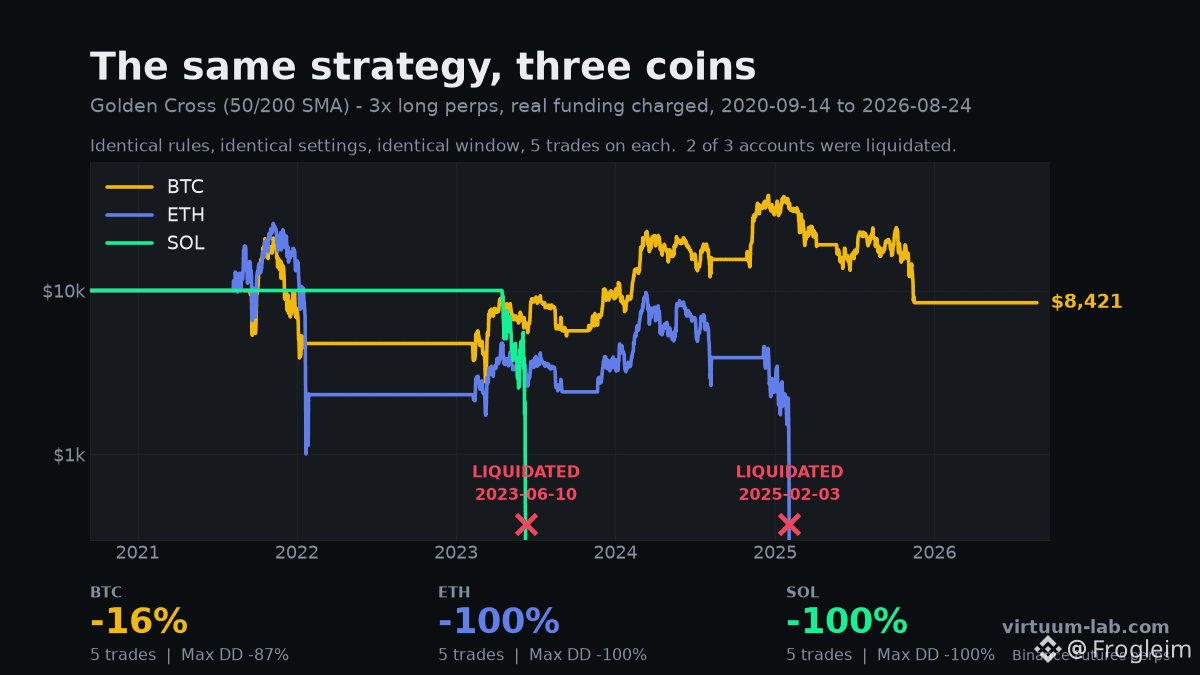
So I ran the identical rules on ETH and SOL. Same 50/200 SMA cross, same 3x long, same window, real Binance funding charged. All three start on the same day, so nobody gets a head start.
BTC: −16% — survived, but with an 87% drawdown
ETH: −99.9% — liquidated 3 Feb 2025
SOL: −100% — liquidated twice, the first time on its opening trade
Five trades each. Identical rules. One account limps out, two are gone.
Now drop the leverage to 1x and nothing gets liquidated: BTC +21%, ETH −38%, SOL +2%. Over six years. That's the actual edge — roughly nothing. 3x didn't amplify an edge. It just moved the liquidation price close enough to touch.
If a strategy only survives on the coin you built it on, you didn't find an edge. You fitted a chart.
Two limitations before anyone else says them: five trades is a tiny sample, and SOL's first entry doesn't come until 2023, because a 200-day SMA needs 200 days and SOL listed late.
And yes — BTC made +359% in my last post and −16% here. Same rules, same coin, same engine. The only difference is the start date: 2019 instead of 2020.
Test your rules on the coins you didn't design them for 👉 https://virtuum-lab.com
#BTC #ETH #SOL #TradingStrategy
Same strategy. Three coins. Two accounts went to zero.
My last post showed what real funding does to a Golden Cross on BTC. The obvious next question: does the strategy work, or does BTC just go up?
So I ran the identical rules on ETH and SOL. Same 50/200 SMA cross, same 3x long, same window, real Binance funding charged. All three start on the same day, so nobody gets a head start.
BTC: −16% — survived, but with an 87% drawdown
ETH: −99.9% — liquidated 3 Feb 2025
SOL: −100% — liquidated twice, the first time on its opening trade
Five trades each. Identical rules. One account limps out, two are gone.
Now drop the leverage to 1x and nothing gets liquidated: BTC +21%, ETH −38%, SOL +2%. Over six years. That's the actual edge — roughly nothing. 3x didn't amplify an edge. It just moved the liquidation price close enough to touch.
If a strategy only survives on the coin you built it on, you didn't find an edge. You fitted a chart.
Two limitations before anyone else says them: five trades is a tiny sample, and SOL's first entry doesn't come until 2023, because a 200-day SMA needs 200 days and SOL listed late.
And yes — BTC made +359% in my last post and −16% here. Same rules, same coin, same engine. The only difference is the start date: 2019 instead of 2020.
Test your rules on the coins you didn't design them for 👉 https://virtuum-lab.com
#BTC #ETH #SOL #TradingStrategy
My last post showed what real funding does to a Golden Cross on BTC. The obvious next question: does the strategy work, or does BTC just go up?
So I ran the identical rules on ETH and SOL. Same 50/200 SMA cross, same 3x long, same window, real Binance funding charged. All three start on the same day, so nobody gets a head start.
BTC: −16% — survived, but with an 87% drawdown
ETH: −99.9% — liquidated 3 Feb 2025
SOL: −100% — liquidated twice, the first time on its opening trade
Five trades each. Identical rules. One account limps out, two are gone.
Now drop the leverage to 1x and nothing gets liquidated: BTC +21%, ETH −38%, SOL +2%. Over six years. That's the actual edge — roughly nothing. 3x didn't amplify an edge. It just moved the liquidation price close enough to touch.
If a strategy only survives on the coin you built it on, you didn't find an edge. You fitted a chart.
Two limitations before anyone else says them: five trades is a tiny sample, and SOL's first entry doesn't come until 2023, because a 200-day SMA needs 200 days and SOL listed late.
And yes — BTC made +359% in my last post and −16% here. Same rules, same coin, same engine. The only difference is the start date: 2019 instead of 2020.
Test your rules on the coins you didn't design them for 👉 https://virtuum-lab.com
#BTC #ETH #SOL #TradingStrategy
99
·
--
ເບິ່ງການແປ
Your BTC backtest is lying to you by about 1,600%I ran the Golden Cross (50/200 SMA) on BTCUSDT perps. 3x long. Binance data, Sept 2019 → today.
Ignoring funding: +2,003%
Charging real Binance funding: +359%
Same strategy. Same entries. Same exits. Same six trades. The gap is $96,561 in funding payments.
Why it's so big: BTCUSDT funding has averaged 0.0106% per 8h settlement since 2019 — about 11.6% a year. Sounds like nothing. At 3x leverage on full equity that's roughly 35% of your account per year, and the Golden Cross holds for months at a time.
You pay rent on the position the entire time you're right.
It hits the downside too. Max drawdown goes from −81.6% to −90.4%. Funding doesn't just shave the top off your returns, it digs the hole deeper.
Most backtest tools treat a perp like spot. No funding, no liquidation price, no margin mechanics. Then people go live at 3x and can't work out where the money went.
Two caveats before anyone accuses me of selling a dream: six trades is a tiny sample, and a −90% drawdownld trade. That's the point. This is what the honest version looks like.
I built a no-code backtester that charges the real funding history from the exchange you pick. Free to try check comments 👇
#BTC #Bianace
Your BTC backtest is lying to you by about 1,600%
I ran the Golden Cross (50/200 SMA) on BTCUSDT perps. 3x long. Binance data, Sept 2019 → today.
Ignoring funding: +2,003%
Charging real Binance funding: +359%
Same strategy. Same entries. Same exits. Same six trades. The gap is $96,561 in funding payments.
Why it's so big: BTCUSDT funding has averaged 0.0106% per 8h settlement since 2019 — about 11.6% a year. Sounds like nothing. At 3x leverage on full equity that's roughly 35% of your account per year, and the Golden Cross holds for months at a time.
You pay rent on the position the entire time you're right.
It hits the downside too. Max drawdown goes from −81.6% to −90.4%. Funding doesn't just shave the top off your returns, it digs the hole deeper.
Most backtest tools treat a perp like spot. No funding, no liquidation price, no margin mechanics. Then people go live at 3x and can't work out where the money went.
Two caveats before anyone accuses me of selling a dream: six trades is a tiny sample, and a −90% drawdownld trade. That's the point. This is what the honest version looks like.
I built a no-code backtester that charges the real funding history from the exchange you pick. Free to try check comments 👇
#BTC #Bianace
Ignoring funding: +2,003%
Charging real Binance funding: +359%
Same strategy. Same entries. Same exits. Same six trades. The gap is $96,561 in funding payments.
Why it's so big: BTCUSDT funding has averaged 0.0106% per 8h settlement since 2019 — about 11.6% a year. Sounds like nothing. At 3x leverage on full equity that's roughly 35% of your account per year, and the Golden Cross holds for months at a time.
You pay rent on the position the entire time you're right.
It hits the downside too. Max drawdown goes from −81.6% to −90.4%. Funding doesn't just shave the top off your returns, it digs the hole deeper.
Most backtest tools treat a perp like spot. No funding, no liquidation price, no margin mechanics. Then people go live at 3x and can't work out where the money went.
Two caveats before anyone accuses me of selling a dream: six trades is a tiny sample, and a −90% drawdownld trade. That's the point. This is what the honest version looks like.
I built a no-code backtester that charges the real funding history from the exchange you pick. Free to try check comments 👇
#BTC #Bianace
1
117
·
--
ເບິ່ງການແປ
7-Day Algo Trading Update 📊
Over the last week I’ve been running a fully automated futures trading system built around a momentum/trend-following framework on the 15-minute timeframe.
The system uses multiple confirmations before entering trades, including:
• Trend detection
• Momentum confirmation
• Volume filters
• Volatility-adjusted risk management
The goal is not to predict the market, but to systematically capture momentum while controlling downside risk.
#signaladvisor
7-Day Algo Trading Update 📊
Over the last week I’ve been running a fully automated futures trading system built around a momentum/trend-following framework on the 15-minute timeframe.
The system uses multiple confirmations before entering trades, including:
• Trend detection
• Momentum confirmation
• Volume filters
• Volatility-adjusted risk management
The goal is not to predict the market, but to systematically capture momentum while controlling downside risk.
#signaladvisor
Over the last week I’ve been running a fully automated futures trading system built around a momentum/trend-following framework on the 15-minute timeframe.
The system uses multiple confirmations before entering trades, including:
• Trend detection
• Momentum confirmation
• Volume filters
• Volatility-adjusted risk management
The goal is not to predict the market, but to systematically capture momentum while controlling downside risk.
#signaladvisor
1
98
·
--
ເບິ່ງການແປ
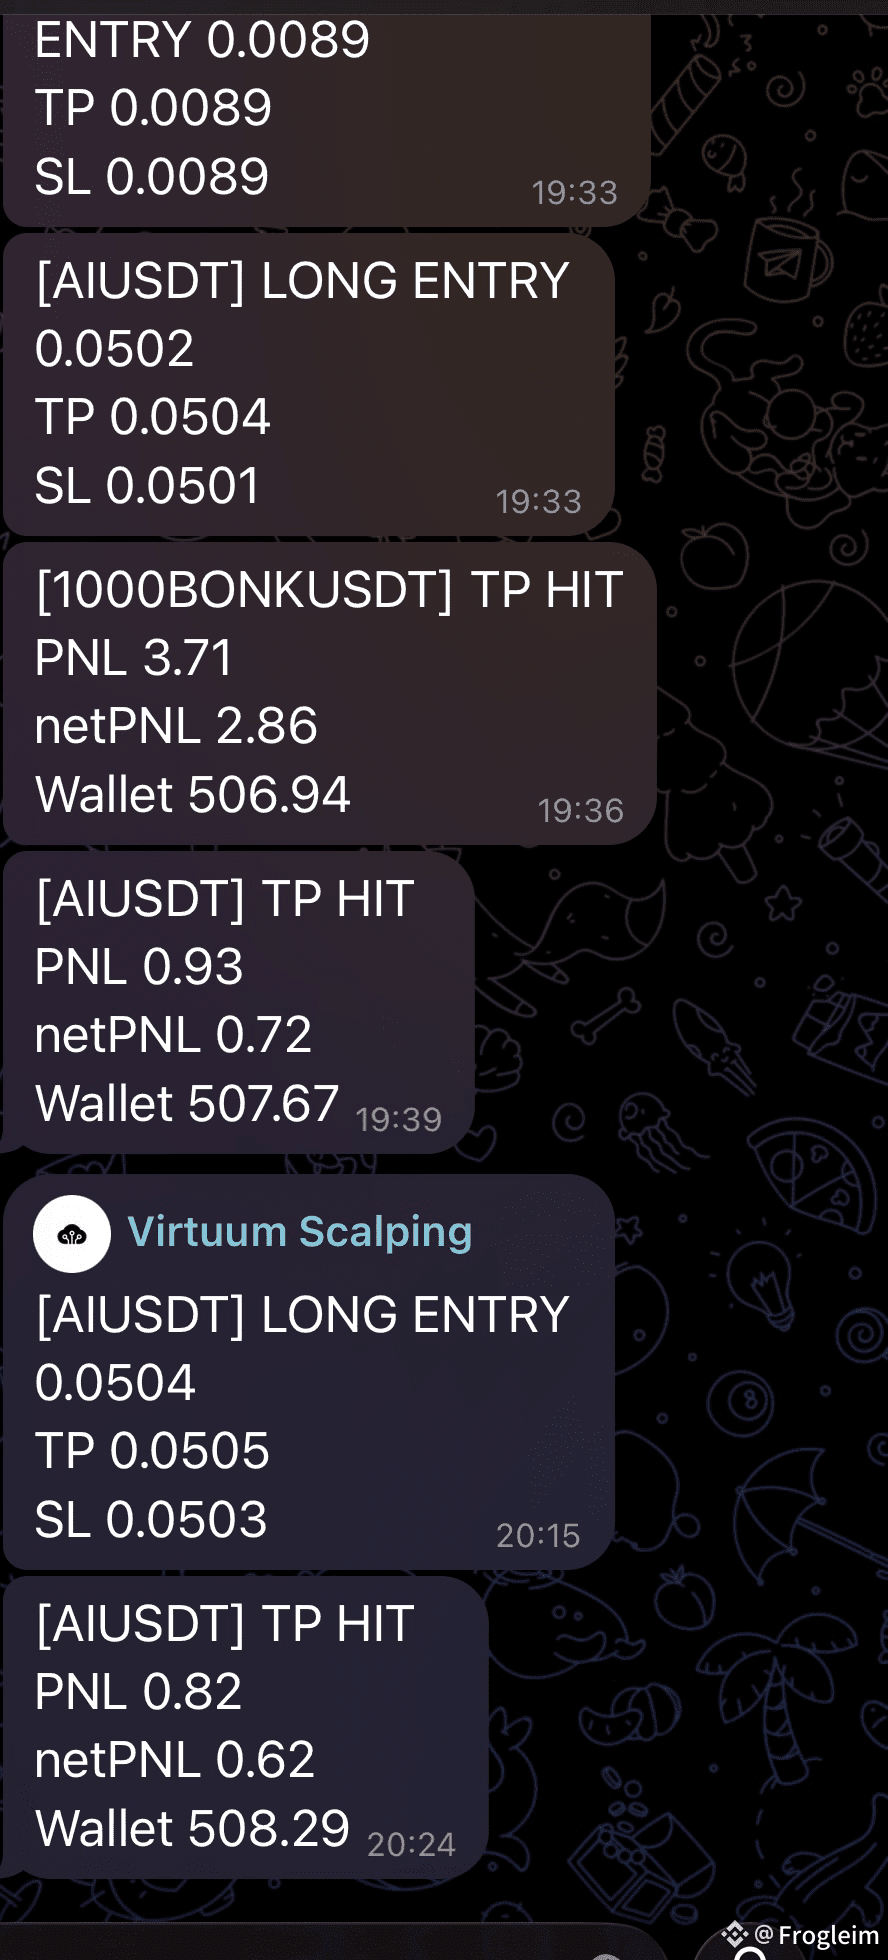
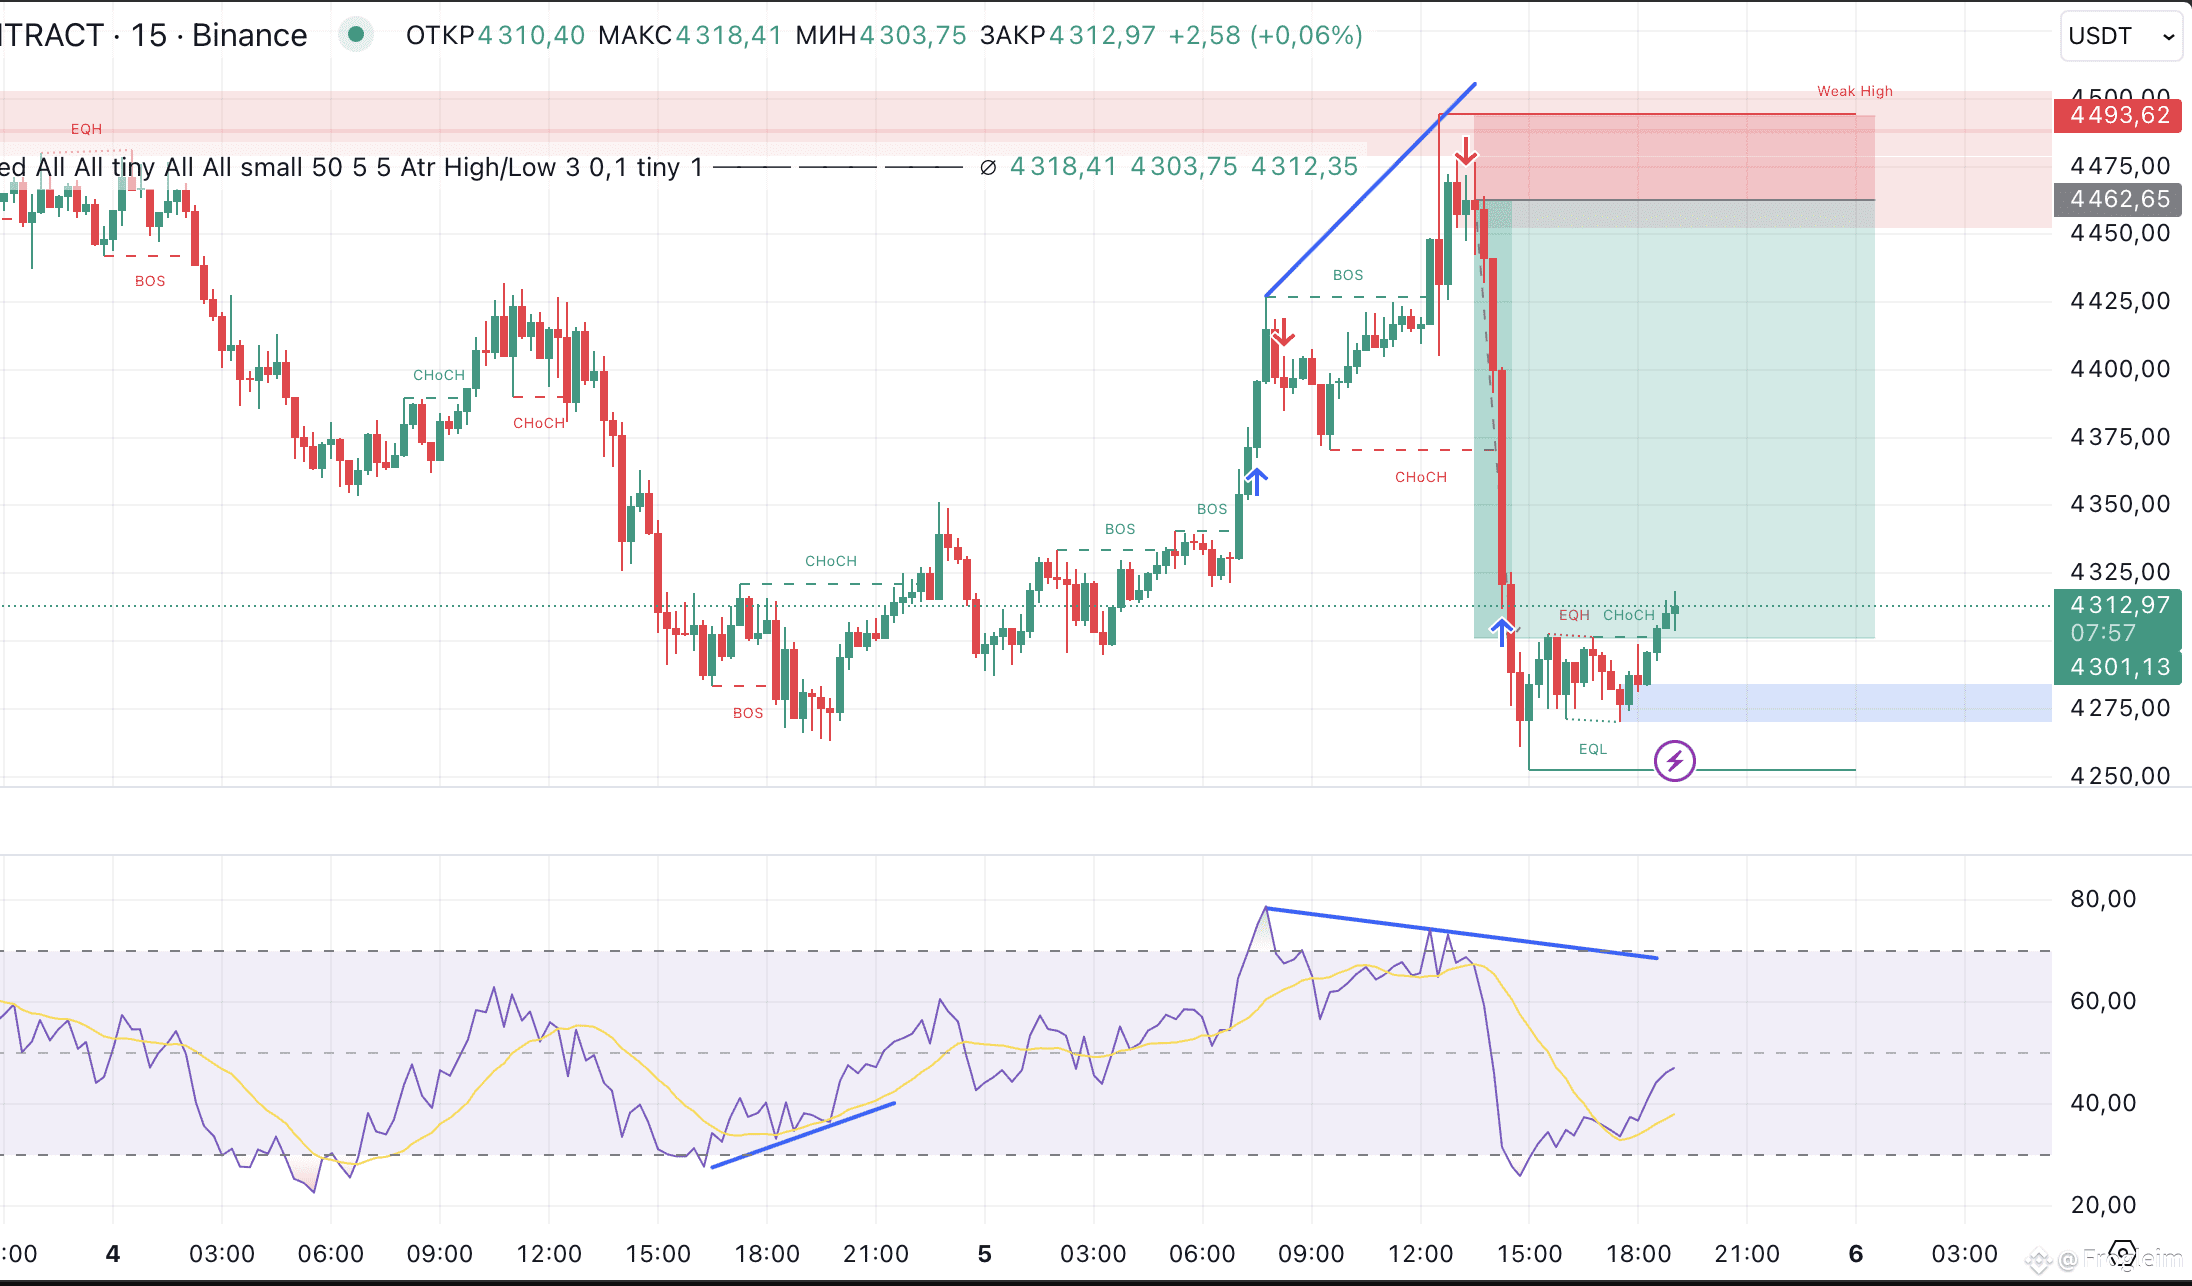
After two years of development, our team has finally finished our scalping bot 🔥
It’s already running on a live account 💪
#cryptosignals
After two years of development, our team has finally finished our scalping bot 🔥
It’s already running on a live account 💪
#cryptosignals
It’s already running on a live account 💪
#cryptosignals
2
723
·
--
ເບິ່ງການແປ
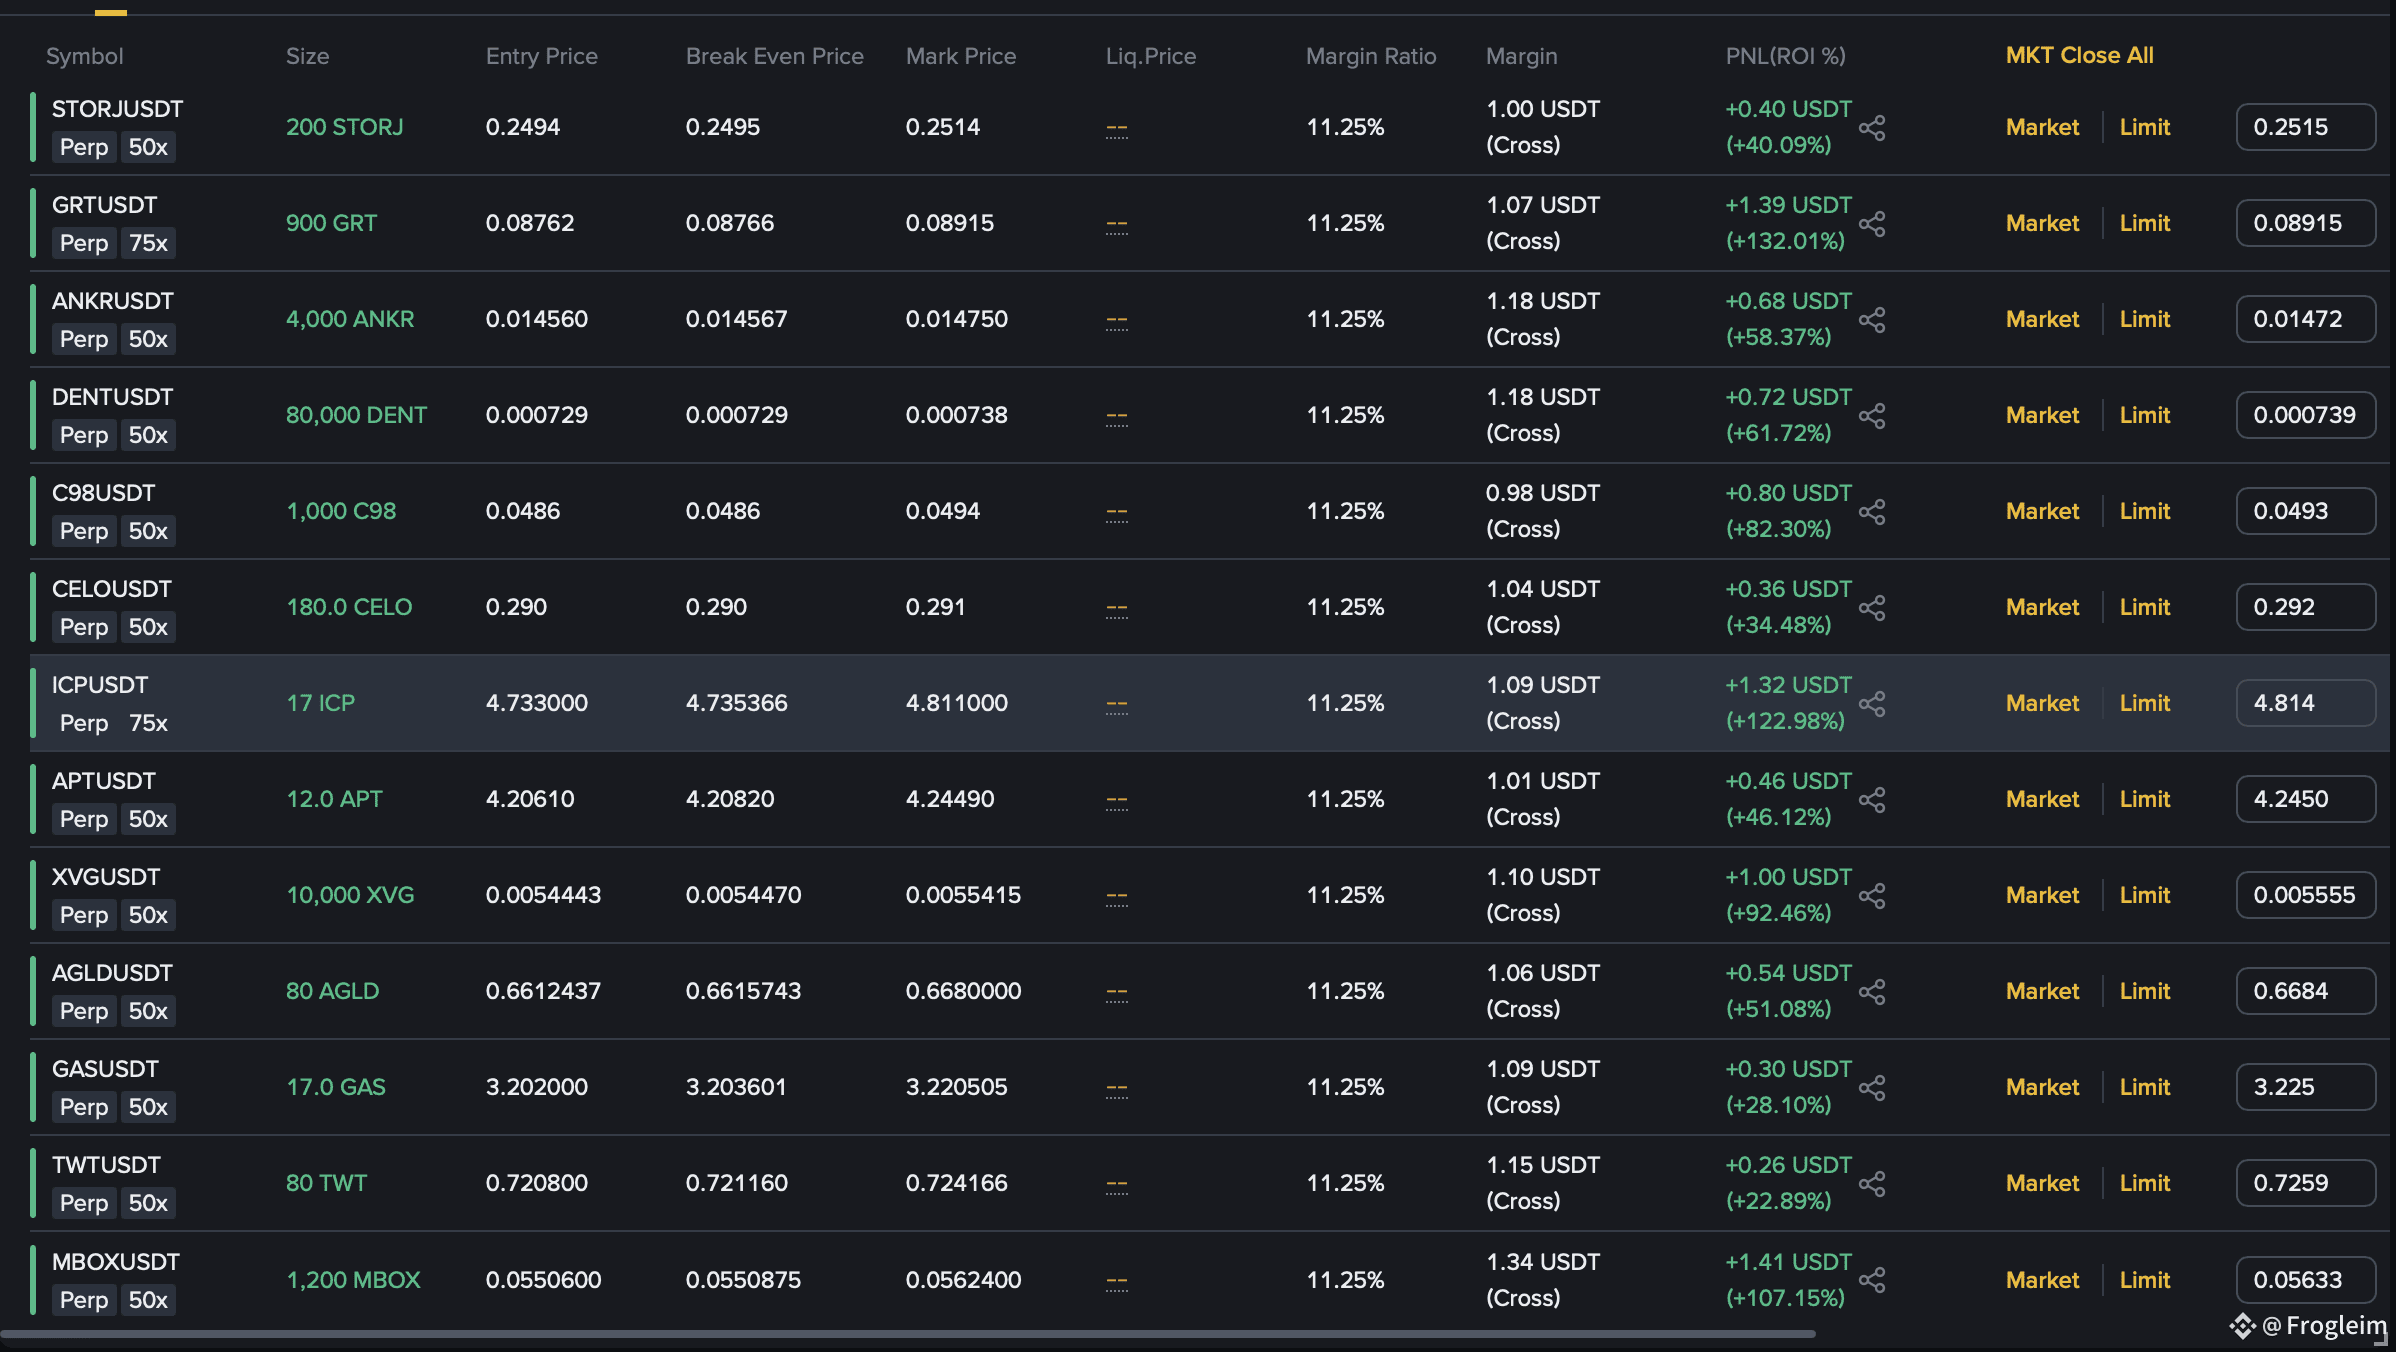
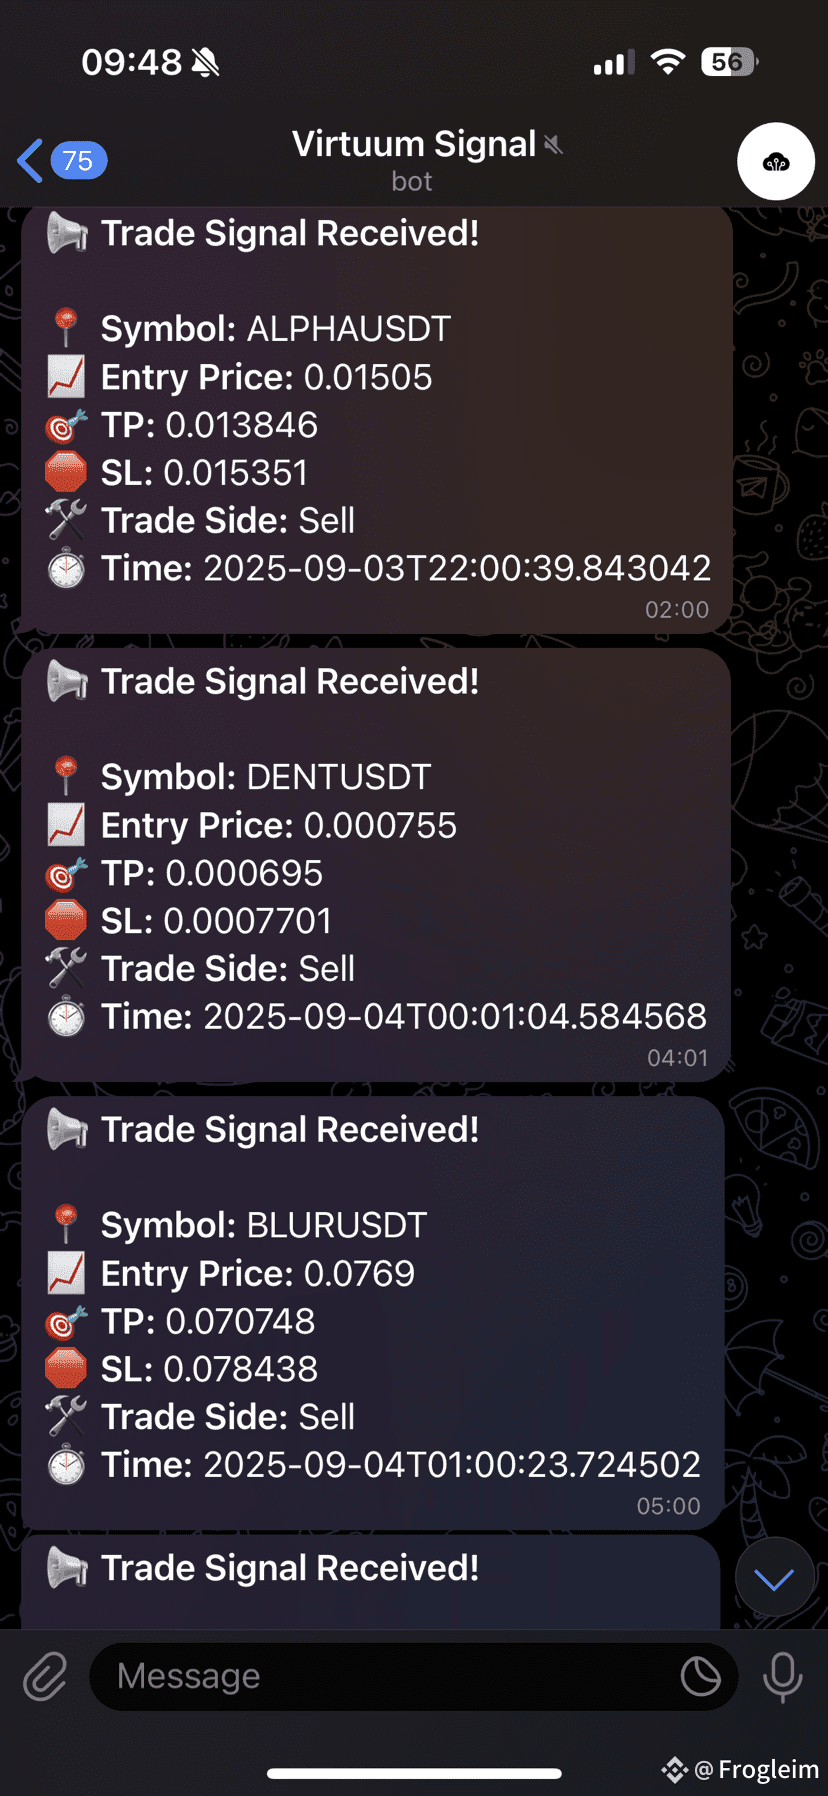
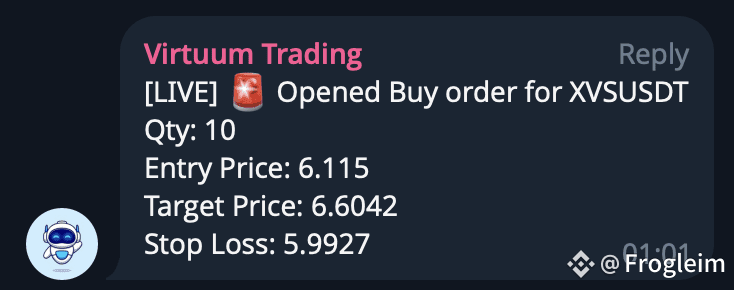
Consistency is what transforms average into excellence.
#TradingSignals
Consistency is what transforms average into excellence.
#TradingSignals
#TradingSignals
1k
ເຂົ້າສູ່ລະບົບເພື່ອສຳຫຼວດເນື້ອຫາເພີ່ມເຕີມ
ເຂົ້າຮ່ວມກຸ່ມຜູ້ໃຊ້ຄຣິບໂຕທົ່ວໂລກໃນ Binance Square.
⚡️ ໄດ້ຮັບຂໍ້ມູນຫຼ້າສຸດ ແລະ ທີ່ມີປະໂຫຍດກ່ຽວກັບຄຣິບໂຕ.
💬 ໄດ້ຮັບຄວາມໄວ້ວາງໃຈຈາກຕະຫຼາດແລກປ່ຽນຄຣິບໂຕທີ່ໃຫຍ່ທີ່ສຸດໃນໂລກ.
👍 ຄົ້ນຫາຂໍ້ມູນເຊີງເລິກທີ່ແທ້ຈາກນັກສ້າງທີ່ໄດ້ຮັບການຢືນຢັນ.
ອີເມວ / ເບີໂທລະສັບ
ຫົວຂໍ້ທີ່ກໍາລັງນິຍົມ
AIStocksWhatNext
672,313 views
4,997 ກຳລັງສົນທະນາ
Пាចែក ແລະ ຮັບຮາງວັນຈາກການແຂ່ງຂັນ Trending Hashtag ຂອງພວກເຮົາ
✨ຫົວຂໍ້: ມີໂອກາດການລົງທຶນອື່ນໃດອີກ ຍັງເຫຼືອບໍ ໃນເວລາທີ່ຫຸ້ນ AI ຍັງຂຶ້ນຢ່າງຕໍ່ເນື່ອງ?
👉ວິທີເຂົ້າຮ່ວມ:
ໂພດຂໍ້ຄວາມສັ້ນຫຼືບົດຄວາມພ້ອມ hashtag #AIStocksWhatNext
ແບ່ງປັນວ່າທ່ານເບີກບວກ (bullish) ຫຼືຂາດບວກ (bearish) ແລະ ໂພດການຖືຫຸ້ນ AI ຫຼືການຊື້ຂາຍຂອງທ່ານ — ການໃຊ້ trade widget ອາດຊ່ວຍໃຫ້ມີສິດກໍານົດໄດ້ດີຂຶ້ນ.
ທ່ານຍັງສາມາດເສີມໃຫ້ໂພດຂອງທ່ານໂດຍການແບ່ງປັນຂໍ້ມູນ ຫຼື ກຣາຟ, ແລະຫຼີກລ້ຽງຮູບພາບທີ່ສ້າງຈາກ AI.
✍️ສ້າງເນື້ອຫາຕາມມຸມມອງດ້ານລຸ່ມນີ້:
- Nvidia ກ່າວວ່າຍອດຂາຍຊິບຈະເພີ່ມເປັນສອງເທົ່າໃນປີໜ້າ, ແລະ ບໍລິສັດ AI ຊັ້ນນໍາຍັງຕີຍອດລາຍຮັບສູງສຸດຕໍ່ເນື່ອງ—ການໃຊ້ຈ່າຍດ້ານ compute ທີ່ຢູ່ຫຼັງມັນກໍ່ຊັດເຈນຫຼາຍ. ຄວາມຕ້ອງການຂອງ AI ຈິງໆກໍາລັງຂຶ້ນບໍ? ແລະ ມັນຈະຢູ່ໄດ້ດົນປານໃດ? ຫຸ້ນ AI ຂຶ້ນທົ່ວກະດານ. ນີ້ແມ່ນການປະຕິບັດສະລຸດຈິງ (real breakout) ຫຼືແພ້ແຄ່ການເດັ້ງກັ້ນໄລຍະສັ້ນ?
- ຜູ້ນໍາໃນອຸດສາຫະກໍາເອີ້ນໃຫ້ຊະລໍການພັດທະນາ AI, ໃນຂະນະທີ່ Trump ວາງແຜນຈະສ້າງ “AI Force” ໂດຍອ້າງວ່າ AI ອາດຈະກວມ 25% ຂອງ GDP ຂອງສະຫະລັດ ໃນອະນາຄົດ. ທ່ານຢູ່ຝ່າຍໃດ? ການໜູນຊ່ວຍຈາກລະດັບລັດ (state-level backing) ຈະເປັນໄຊຊະນະໄລຍະຍາວສໍາລັບຫຸ້ນ AI ບໍ?
- ທ່ານກໍ່າລັງຊື້ຫຸ້ນ AI ບໍ? ແບ່ງປັນການຊື້ຂາຍ/ການຖືຄອງທີ່ກ່ຽວຂ້ອງກັບ AI ຂອງທ່ານຜ່ານ trade sharing widget ຂອງພວກເຮົາ.
⏰ໄລຍະການແຄມເປນ:
- 2026-09-22 7:00 - 2026-09-24 4:00 UTC
🎁ລາງວັນ:
- ໂພດທີ່ມີຄຸນສົມບັດຕາມກົດລະບຽບຂ້າງເທິງ ແລະ ມີຫຼາຍກວ່າ 100 ຄໍາຈະຖືກທວດສອບ ແລະ ອາດຈະໄດ້ຮັບການເພີ່ມເຂົ້າເບິ່ງແບບສຸ່ມ 500 ຫາ 3,000 ຄັ້ງ. ທ່ານຈະໄດ້ຮັບແຈ້ງເຕືອນຈາກເຈົ້າໜ້າທີ່ຂອງ feed ຂອງພວກເຮົາ ຖ້າໂພດຂອງທ່ານຖືກເລືອກ.
- ມີໂອກາດໃຫ້ບົດຄວາມຂອງທ່ານຖືກນໍາໄປສະແດງໃນ Binance Square Official
ຕ້ອງການໄອເດຍສໍາລັບໂພດຂອງທ່ານບໍ? ເຂົ້າໄປທີ່ໜ້າຫົວຂໍ້ #AIStocksWhatNext ຫຼື Square Guide on How to Post for Better Reach.
Binance Square Official
·492 ຖືກໃຈ
·1.3M views
21SharesLaunchesEuropesFirstZcashETP
14,097 views
495 ກຳລັງສົນທະນາ
CardanoJoinsX402PaymentStandard
10,166 views
377 ກຳລັງສົນທະນາ