
伊泽99131
72 Жариялаулар

伊泽99131
Хабарлау
Пайдаланушыны блоктау
推特X:@EZ99131
专注链上Alphat投研优质项目分享建设
持有$BTC | $BNB | $SOL| | $Aster | 1000X GEM
#Runes 和铭文以及比特生态狂热者,持续多年现货量化ing
#Runestone 符石信仰者 |$DOG
美股专注中,专注马斯克板块和AI板块以及能源板块
Ашық сауда

BTC ұстаушы
Жиі сауда жасайтын трейдер
5.6 жыл
10 Жазылым
221 Жазылушылар
147 лайк басылған
Жазбалар
Портфолио
Барлығы
Видеолар
·
--
说到底黄仁勋也没做什么伤天害理的事情
光是当前Ai发展的结果,已经造福了太多不懂代码不懂编辑,减少了太多太多的信息差
可以说没有他的三十年深耕,不会让科技和人类新的工业革命产生如此巨大的量变
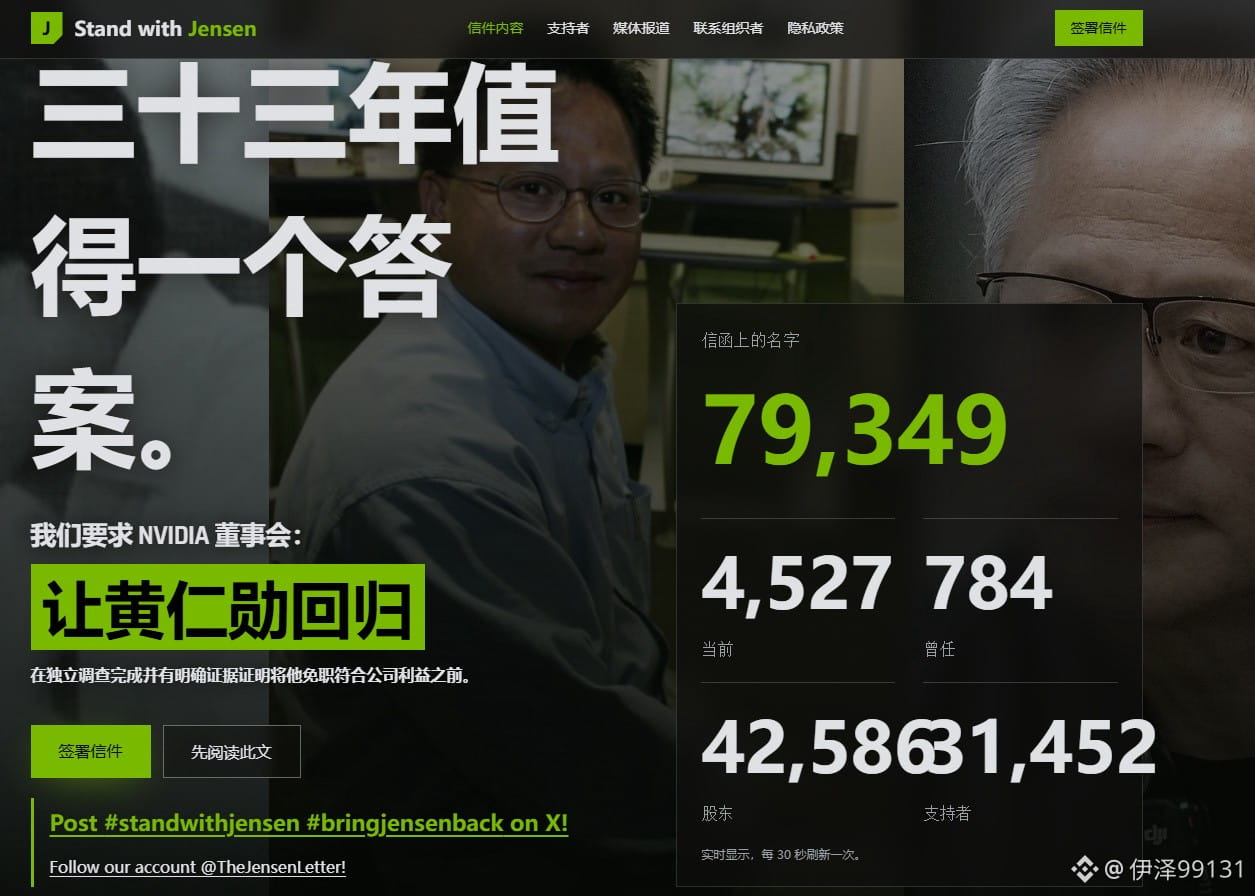
网站支持黄仁勋回归的人数一直在暴力增加,并且都是知名企业家和知名人士
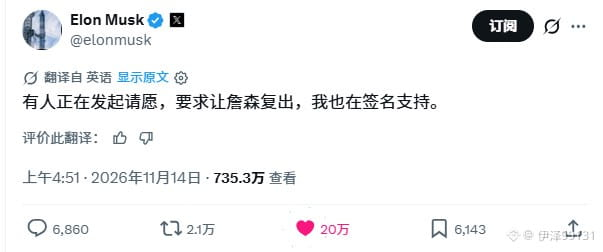
马斯克和币安CEO 一姐都签署了支持黄仁勋回归,希望能让他再次领导AI时代占据不可代替的角色
传送门 :standwithjensen点com
说到底黄仁勋也没做什么伤天害理的事情
光是当前Ai发展的结果,已经造福了太多不懂代码不懂编辑,减少了太多太多的信息差
可以说没有他的三十年深耕,不会让科技和人类新的工业革命产生如此巨大的量变
网站支持黄仁勋回归的人数一直在暴力增加,并且都是知名企业家和知名人士
马斯克和币安CEO 一姐都签署了支持黄仁勋回归,希望能让他再次领导AI时代占据不可代替的角色
传送门 :standwithjensen点com
光是当前Ai发展的结果,已经造福了太多不懂代码不懂编辑,减少了太多太多的信息差
可以说没有他的三十年深耕,不会让科技和人类新的工业革命产生如此巨大的量变
网站支持黄仁勋回归的人数一直在暴力增加,并且都是知名企业家和知名人士
马斯克和币安CEO 一姐都签署了支持黄仁勋回归,希望能让他再次领导AI时代占据不可代替的角色
传送门 :standwithjensen点com
2
2k
·
--
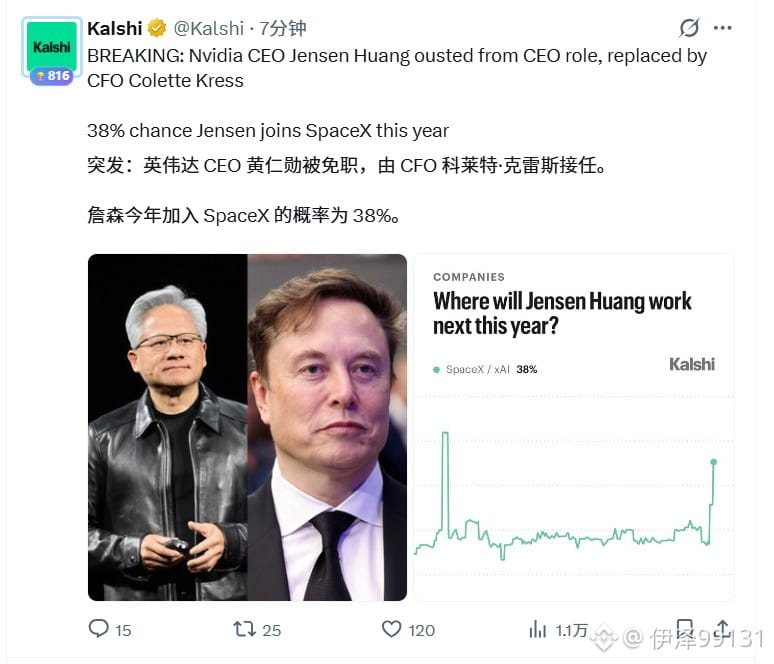
真是见证历史,黑天鹅居然能发生在内裤里
😅
那么这种情况,老黄离职肯定是需要调整心态一段时间
摆在他面前的有三个可能性
1.马斯克公司做的东西刚好也有芯片研发,如果黄仁勋过去,那就是双剑合璧,甚至未来出现跟英伟达抗衡的公司
2.厚积薄发,冷静熬两年,看看28年是否再次共和党当选,新任总统让他再次上位
3.退居幕后,辅助他女儿,跟CZ一样当泉水指挥官
真是见证历史,黑天鹅居然能发生在内裤里
😅
那么这种情况,老黄离职肯定是需要调整心态一段时间
摆在他面前的有三个可能性
1.马斯克公司做的东西刚好也有芯片研发,如果黄仁勋过去,那就是双剑合璧,甚至未来出现跟英伟达抗衡的公司
2.厚积薄发,冷静熬两年,看看28年是否再次共和党当选,新任总统让他再次上位
3.退居幕后,辅助他女儿,跟CZ一样当泉水指挥官
😅
那么这种情况,老黄离职肯定是需要调整心态一段时间
摆在他面前的有三个可能性
1.马斯克公司做的东西刚好也有芯片研发,如果黄仁勋过去,那就是双剑合璧,甚至未来出现跟英伟达抗衡的公司
2.厚积薄发,冷静熬两年,看看28年是否再次共和党当选,新任总统让他再次上位
3.退居幕后,辅助他女儿,跟CZ一样当泉水指挥官
5
2.8k
·
--
Расталды
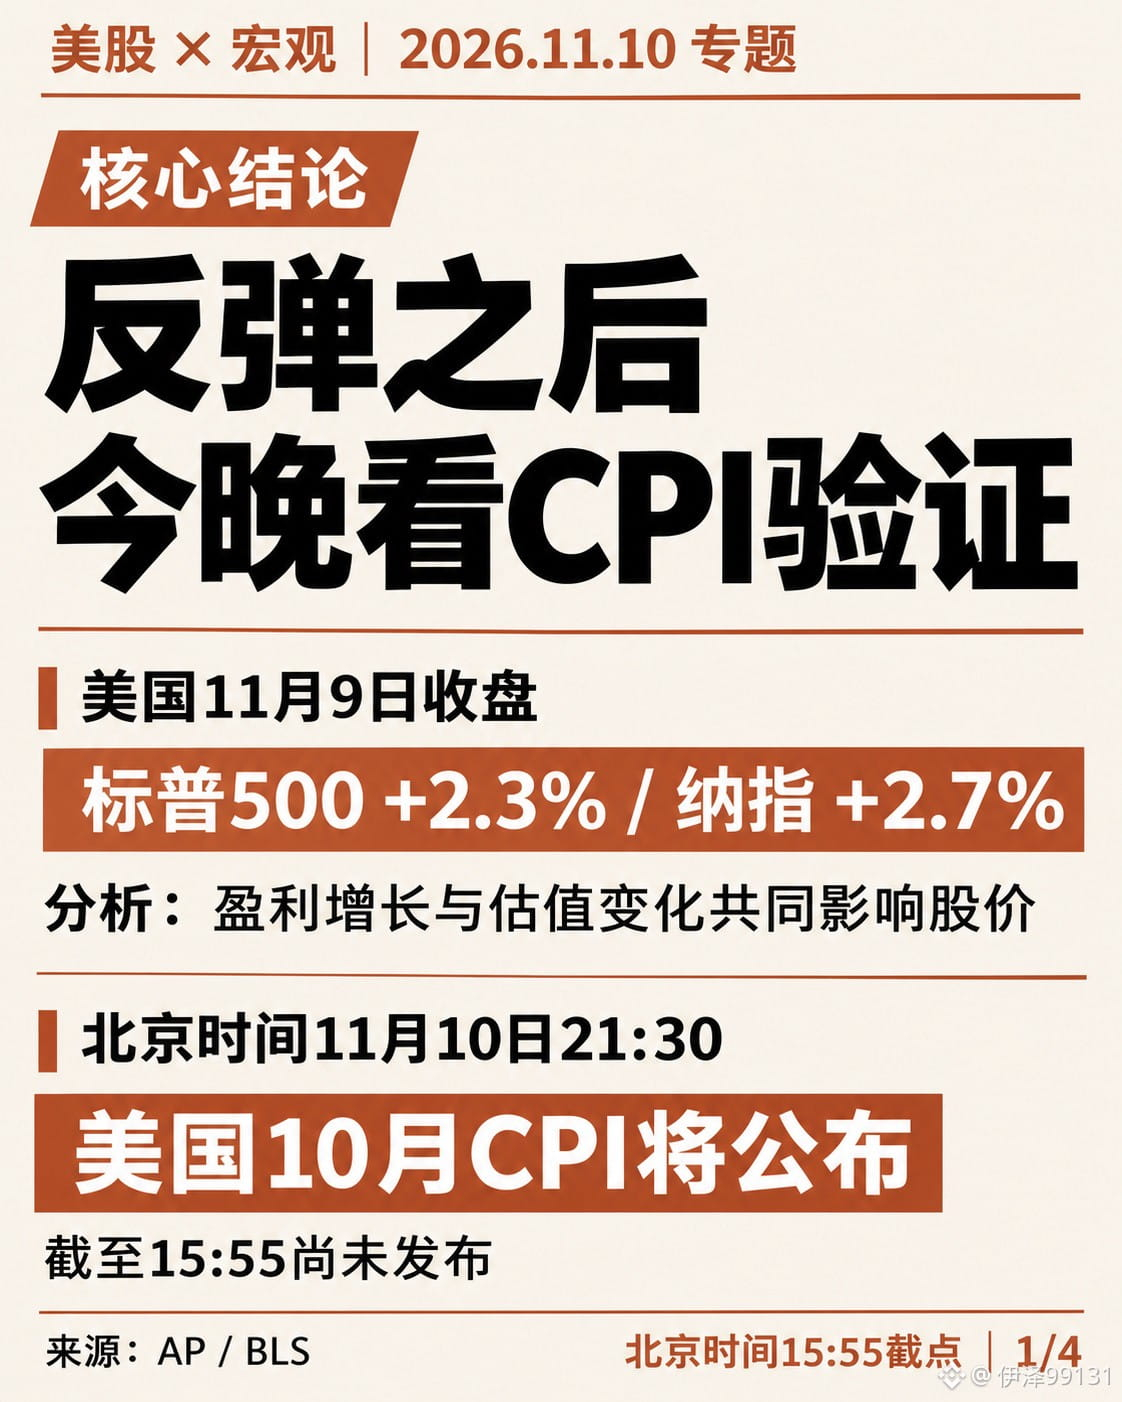
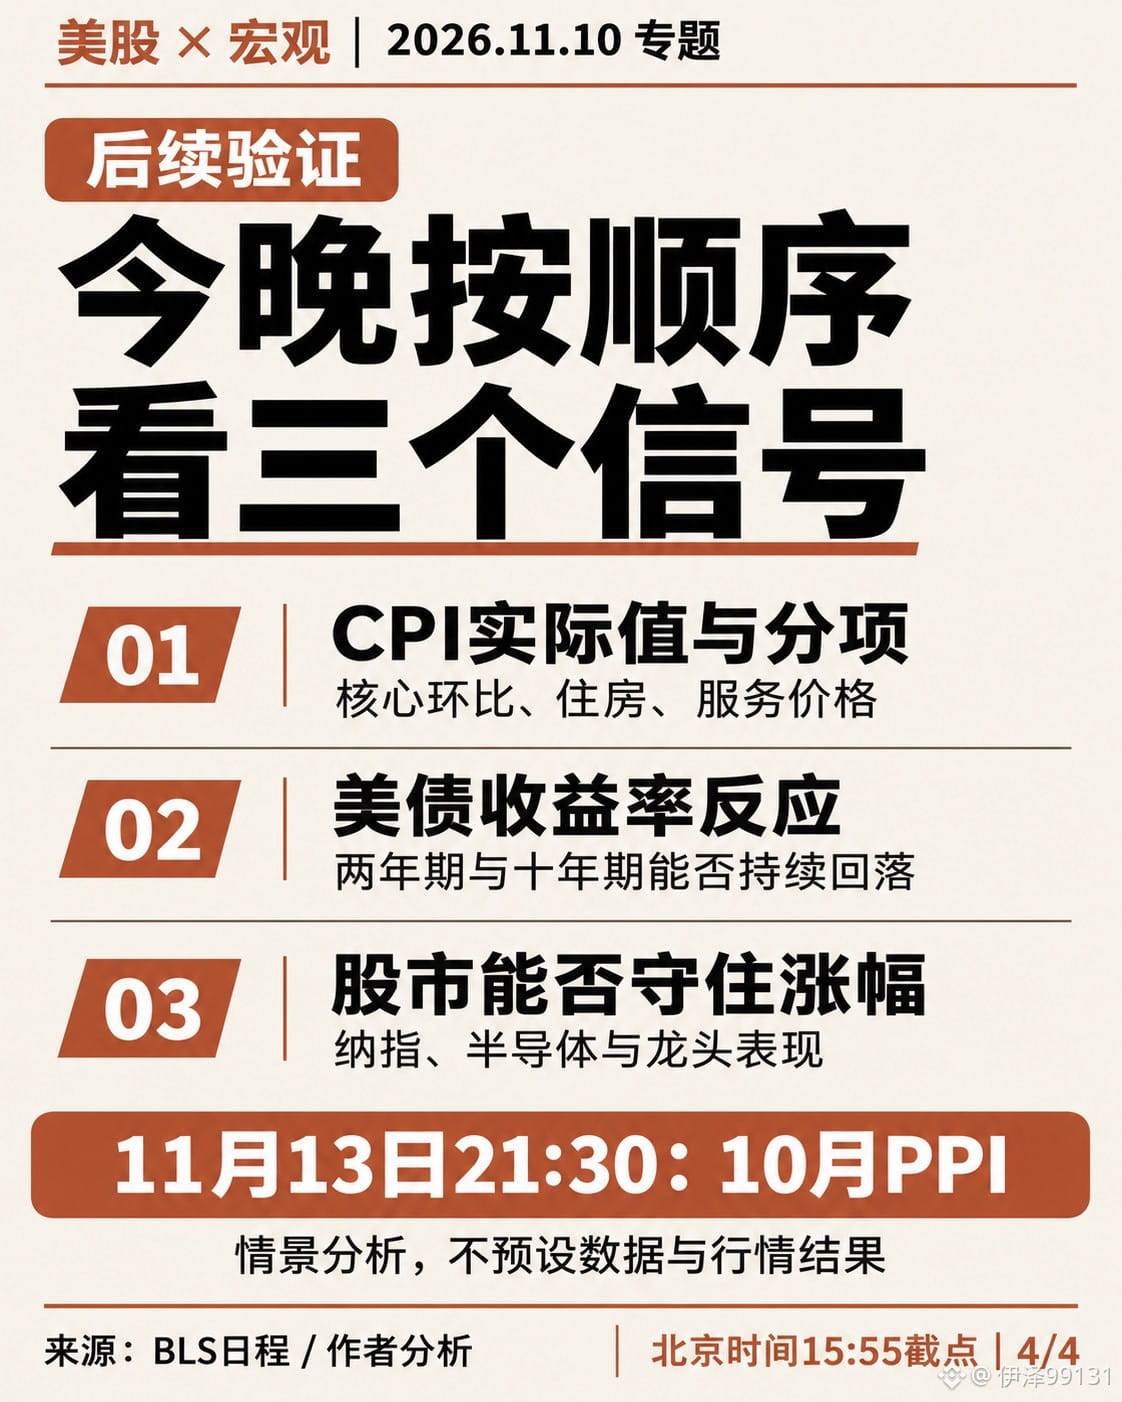
美股反弹之后,今晚CPI能否支持估值修复?
昨夜美股明显反弹,但我更关心的是:这轮修复,能不能经受今晚通胀数据的检验?
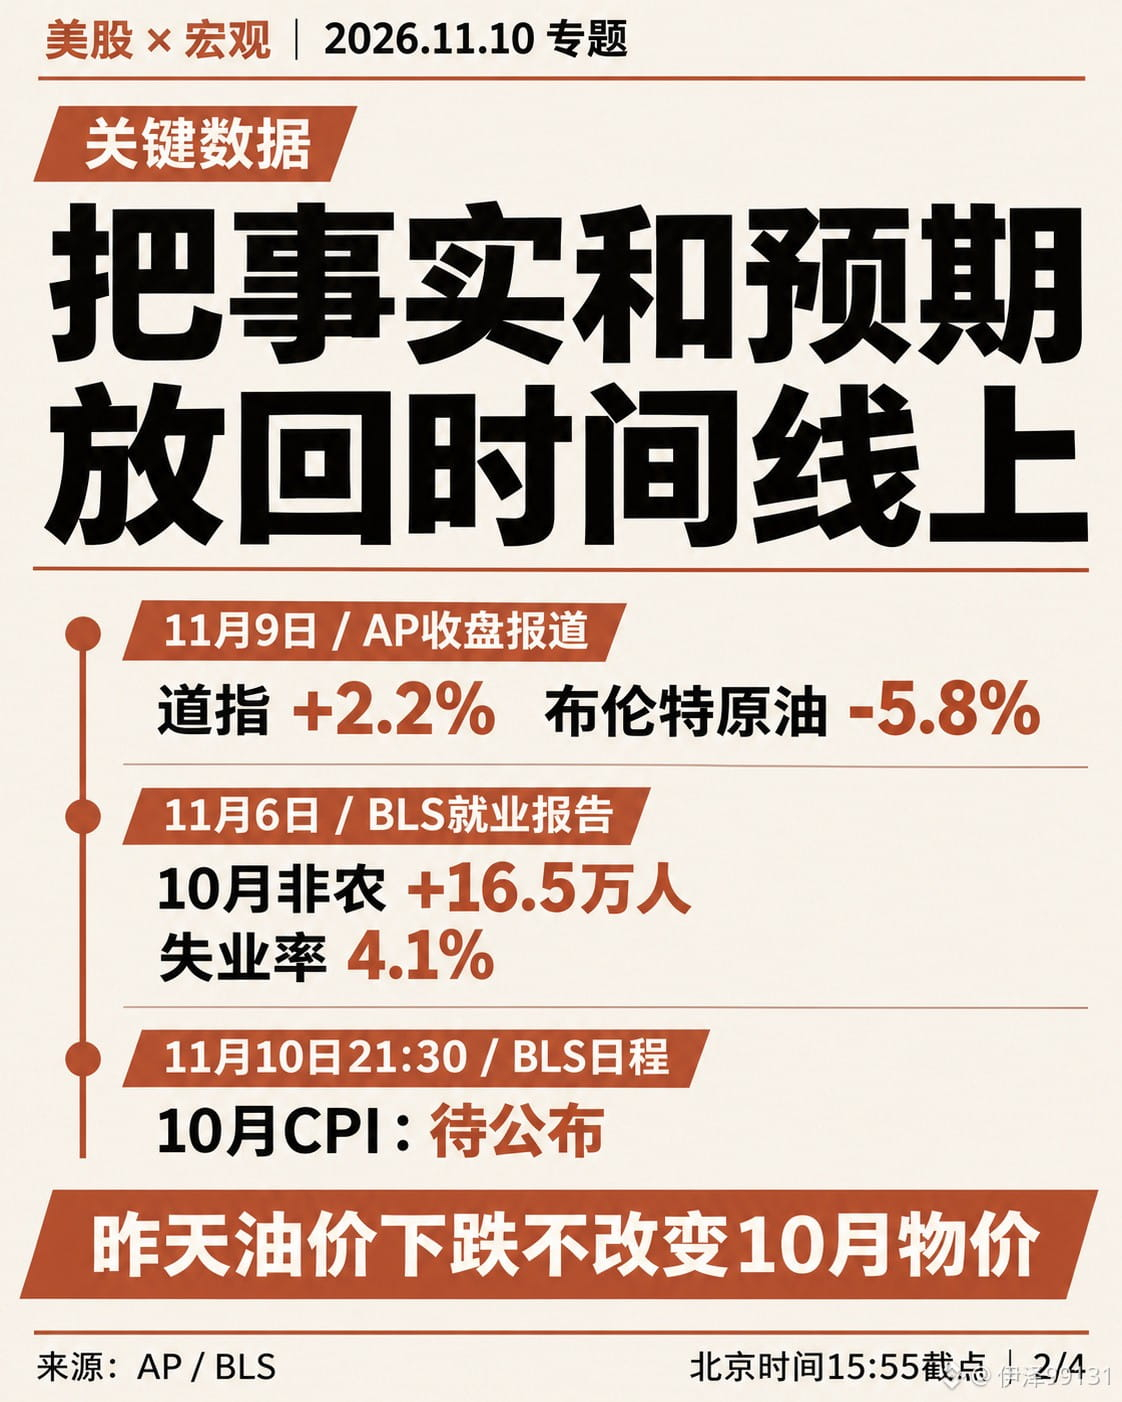
标普500上涨2.3%,道指上涨2.2%,纳指上涨2.7%;布伦特原油当天下跌5.8%。
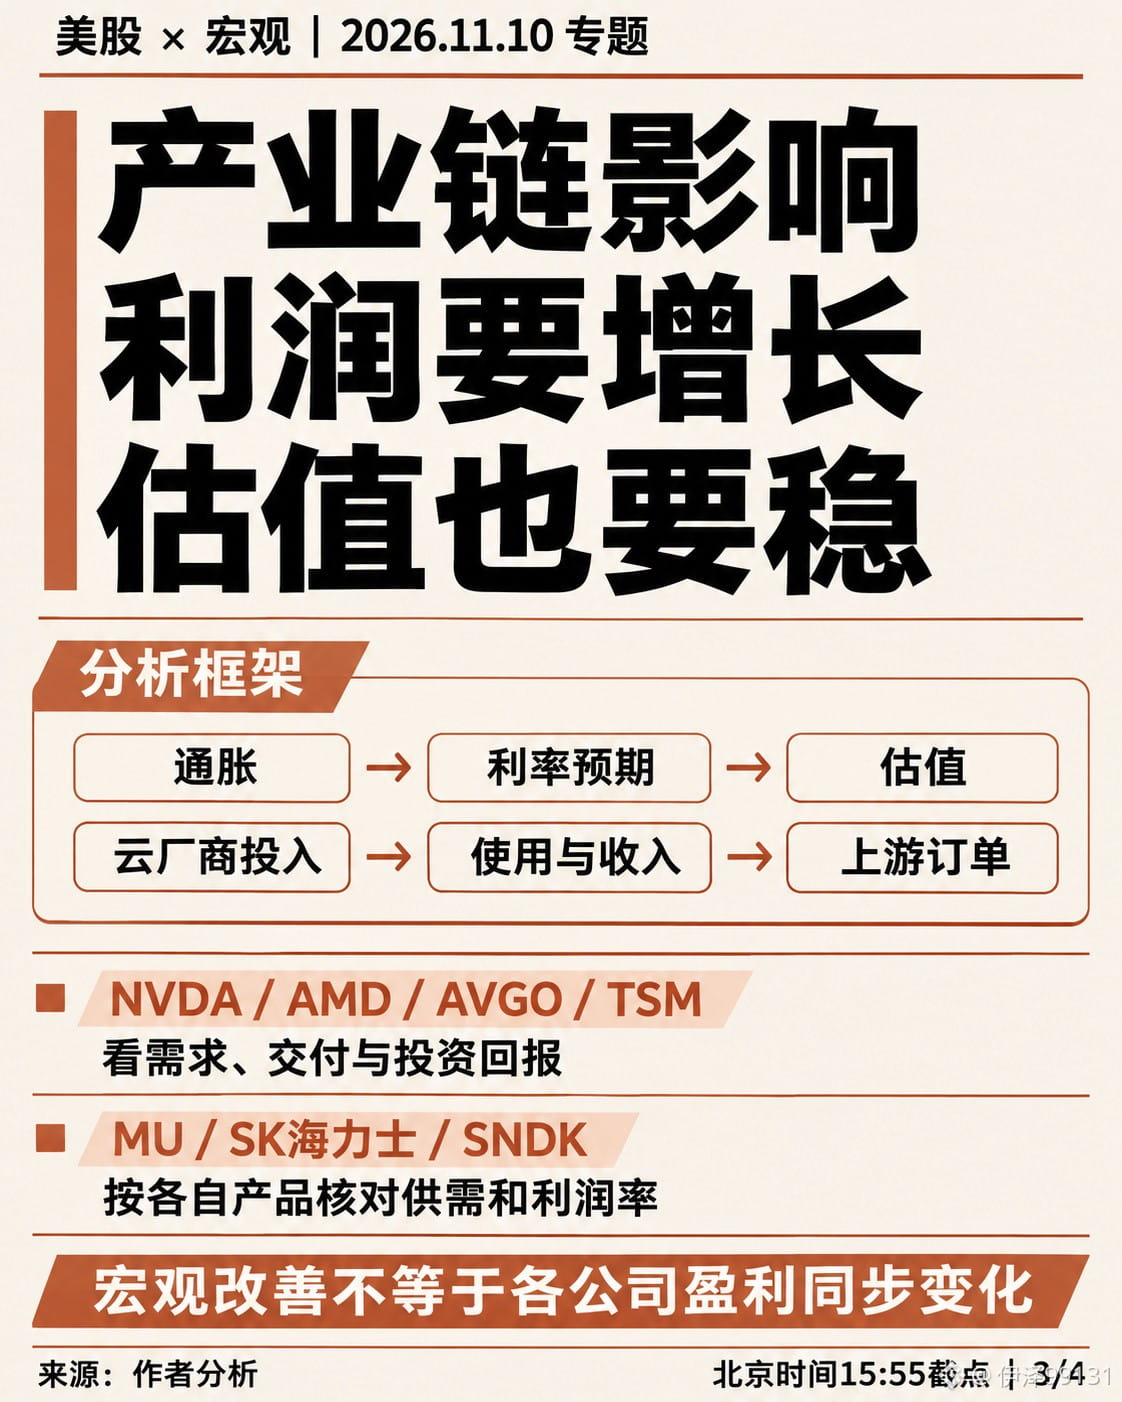
接下来要同时看两条线:企业能赚多少钱,以及市场愿意给这些利润多少估值。
先说宏观。原油回落有助于缓解未来能源价格压力,但11月9日的油价变化,不能倒过来改变10月份已经发生的物价。今晚公布的是美国10月CPI,它检验的是此前一个月的通胀情况。把昨天油价下跌直接写成今晚CPI必然走低,会混淆时间顺序。
先看核心CPI环比,再看住房和服务价格的变化。如果只是能源拖低总体通胀,而核心项目仍然偏强,利率预期未必持续放松。反过来,如果价格压力缓解的范围扩大,同时经济活动保持韧性,对股票估值的环境会更有利。
科技股目前需要面对的组合:盈利增长可以支撑股价,利率压力却可能压低估值。举个纯假设的例子,企业每股盈利增长20%,市盈率却从30倍降到25倍,两者相乘后的价格大致不变。公司交出增长,与股东获得相同幅度的回报,中间还隔着估值变化。
英伟达、AMD和博通需要看需求与交付;台积电需要看先进制程和客户订单;MU、SK海力士和SNDK则需要核对各自产品的供需与利润率。这些企业处在不同环节,不能用同一条宏观新闻推断它们的盈利会同步变化。
更关键的连接点仍然是云厂商。如果资本开支继续增长,实际使用和收入也能跟上,上游订单的支撑会更充分。如果投入增长快于回报,融资成本又保持高位,市场提高对投资回收期的要求。资本开支规模和投资效率一起看。
今晚判断:
CPI实际值与分项,再看两年期、十年期美债收益率的反应。
如果通胀压力缓解、美债收益率回落,企业盈利预期又能稳定,修复条件会改善
美股反弹之后,今晚CPI能否支持估值修复?
昨夜美股明显反弹,但我更关心的是:这轮修复,能不能经受今晚通胀数据的检验?
标普500上涨2.3%,道指上涨2.2%,纳指上涨2.7%;布伦特原油当天下跌5.8%。
接下来要同时看两条线:企业能赚多少钱,以及市场愿意给这些利润多少估值。
先说宏观。原油回落有助于缓解未来能源价格压力,但11月9日的油价变化,不能倒过来改变10月份已经发生的物价。今晚公布的是美国10月CPI,它检验的是此前一个月的通胀情况。把昨天油价下跌直接写成今晚CPI必然走低,会混淆时间顺序。
先看核心CPI环比,再看住房和服务价格的变化。如果只是能源拖低总体通胀,而核心项目仍然偏强,利率预期未必持续放松。反过来,如果价格压力缓解的范围扩大,同时经济活动保持韧性,对股票估值的环境会更有利。
科技股目前需要面对的组合:盈利增长可以支撑股价,利率压力却可能压低估值。举个纯假设的例子,企业每股盈利增长20%,市盈率却从30倍降到25倍,两者相乘后的价格大致不变。公司交出增长,与股东获得相同幅度的回报,中间还隔着估值变化。
英伟达、AMD和博通需要看需求与交付;台积电需要看先进制程和客户订单;MU、SK海力士和SNDK则需要核对各自产品的供需与利润率。这些企业处在不同环节,不能用同一条宏观新闻推断它们的盈利会同步变化。
更关键的连接点仍然是云厂商。如果资本开支继续增长,实际使用和收入也能跟上,上游订单的支撑会更充分。如果投入增长快于回报,融资成本又保持高位,市场提高对投资回收期的要求。资本开支规模和投资效率一起看。
今晚判断:
CPI实际值与分项,再看两年期、十年期美债收益率的反应。
如果通胀压力缓解、美债收益率回落,企业盈利预期又能稳定,修复条件会改善
昨夜美股明显反弹,但我更关心的是:这轮修复,能不能经受今晚通胀数据的检验?
标普500上涨2.3%,道指上涨2.2%,纳指上涨2.7%;布伦特原油当天下跌5.8%。
接下来要同时看两条线:企业能赚多少钱,以及市场愿意给这些利润多少估值。
先说宏观。原油回落有助于缓解未来能源价格压力,但11月9日的油价变化,不能倒过来改变10月份已经发生的物价。今晚公布的是美国10月CPI,它检验的是此前一个月的通胀情况。把昨天油价下跌直接写成今晚CPI必然走低,会混淆时间顺序。
先看核心CPI环比,再看住房和服务价格的变化。如果只是能源拖低总体通胀,而核心项目仍然偏强,利率预期未必持续放松。反过来,如果价格压力缓解的范围扩大,同时经济活动保持韧性,对股票估值的环境会更有利。
科技股目前需要面对的组合:盈利增长可以支撑股价,利率压力却可能压低估值。举个纯假设的例子,企业每股盈利增长20%,市盈率却从30倍降到25倍,两者相乘后的价格大致不变。公司交出增长,与股东获得相同幅度的回报,中间还隔着估值变化。
英伟达、AMD和博通需要看需求与交付;台积电需要看先进制程和客户订单;MU、SK海力士和SNDK则需要核对各自产品的供需与利润率。这些企业处在不同环节,不能用同一条宏观新闻推断它们的盈利会同步变化。
更关键的连接点仍然是云厂商。如果资本开支继续增长,实际使用和收入也能跟上,上游订单的支撑会更充分。如果投入增长快于回报,融资成本又保持高位,市场提高对投资回收期的要求。资本开支规模和投资效率一起看。
今晚判断:
CPI实际值与分项,再看两年期、十年期美债收益率的反应。
如果通胀压力缓解、美债收益率回落,企业盈利预期又能稳定,修复条件会改善
1
808
·
--
Расталды
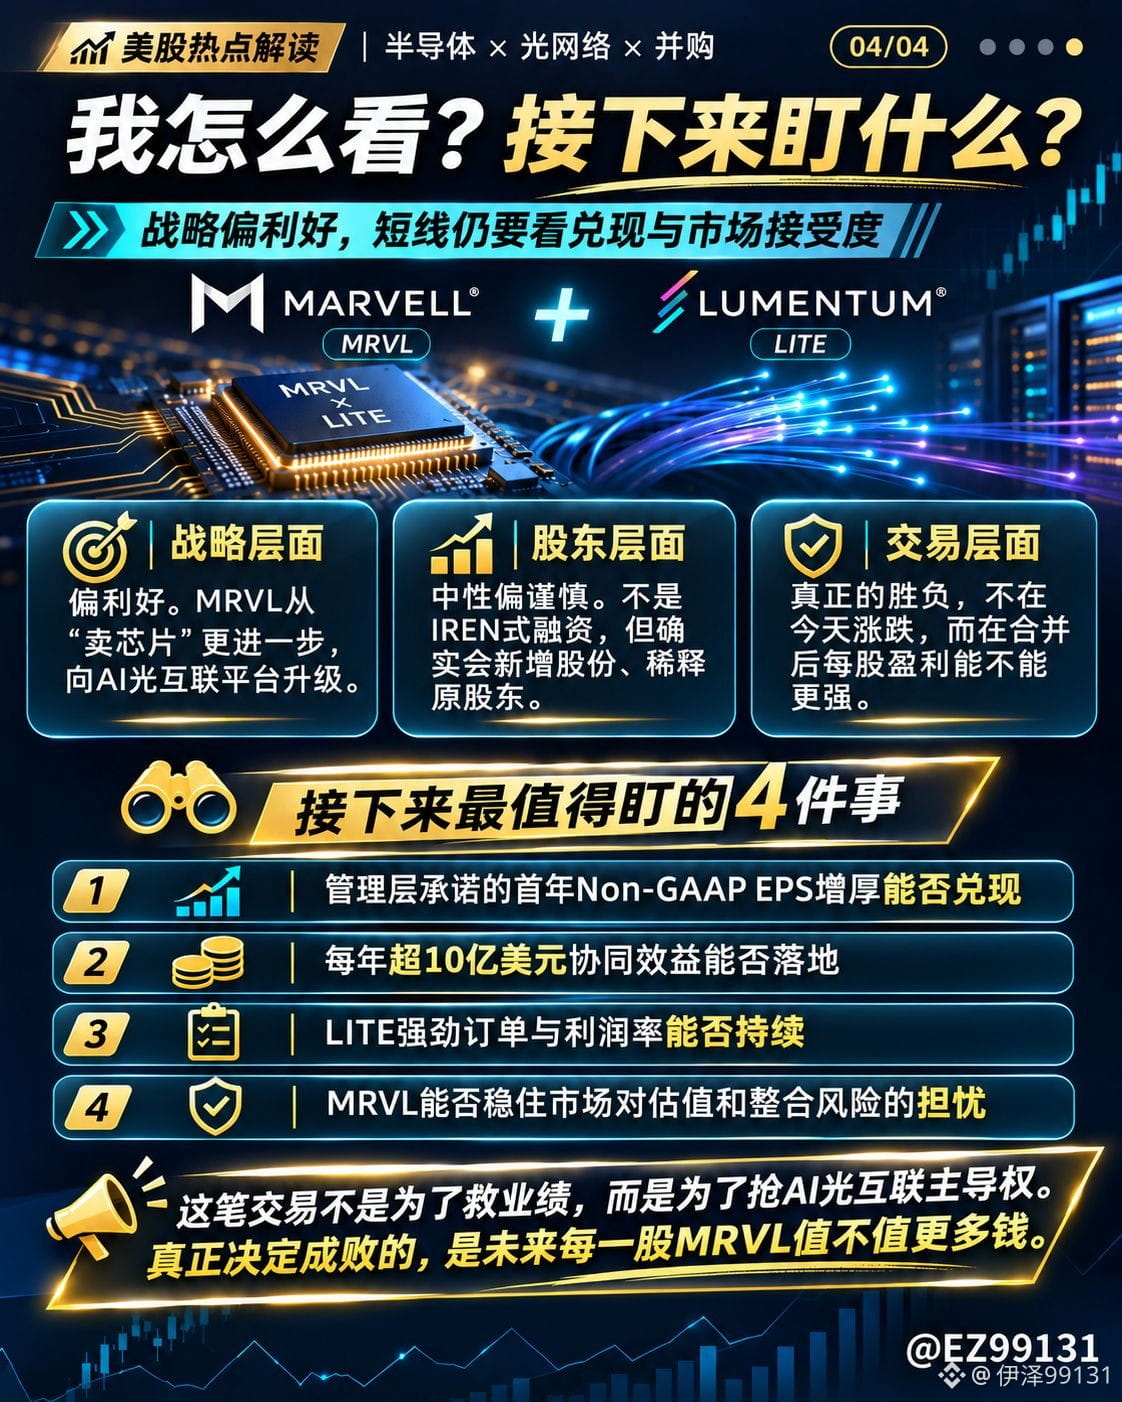
美股重头戏: $MRVL 豪掷1150亿美元收购 $LITE !
今天Marvell终于官宣收购Lumentum。
这笔交易的规模确实超出了很多人的预期。
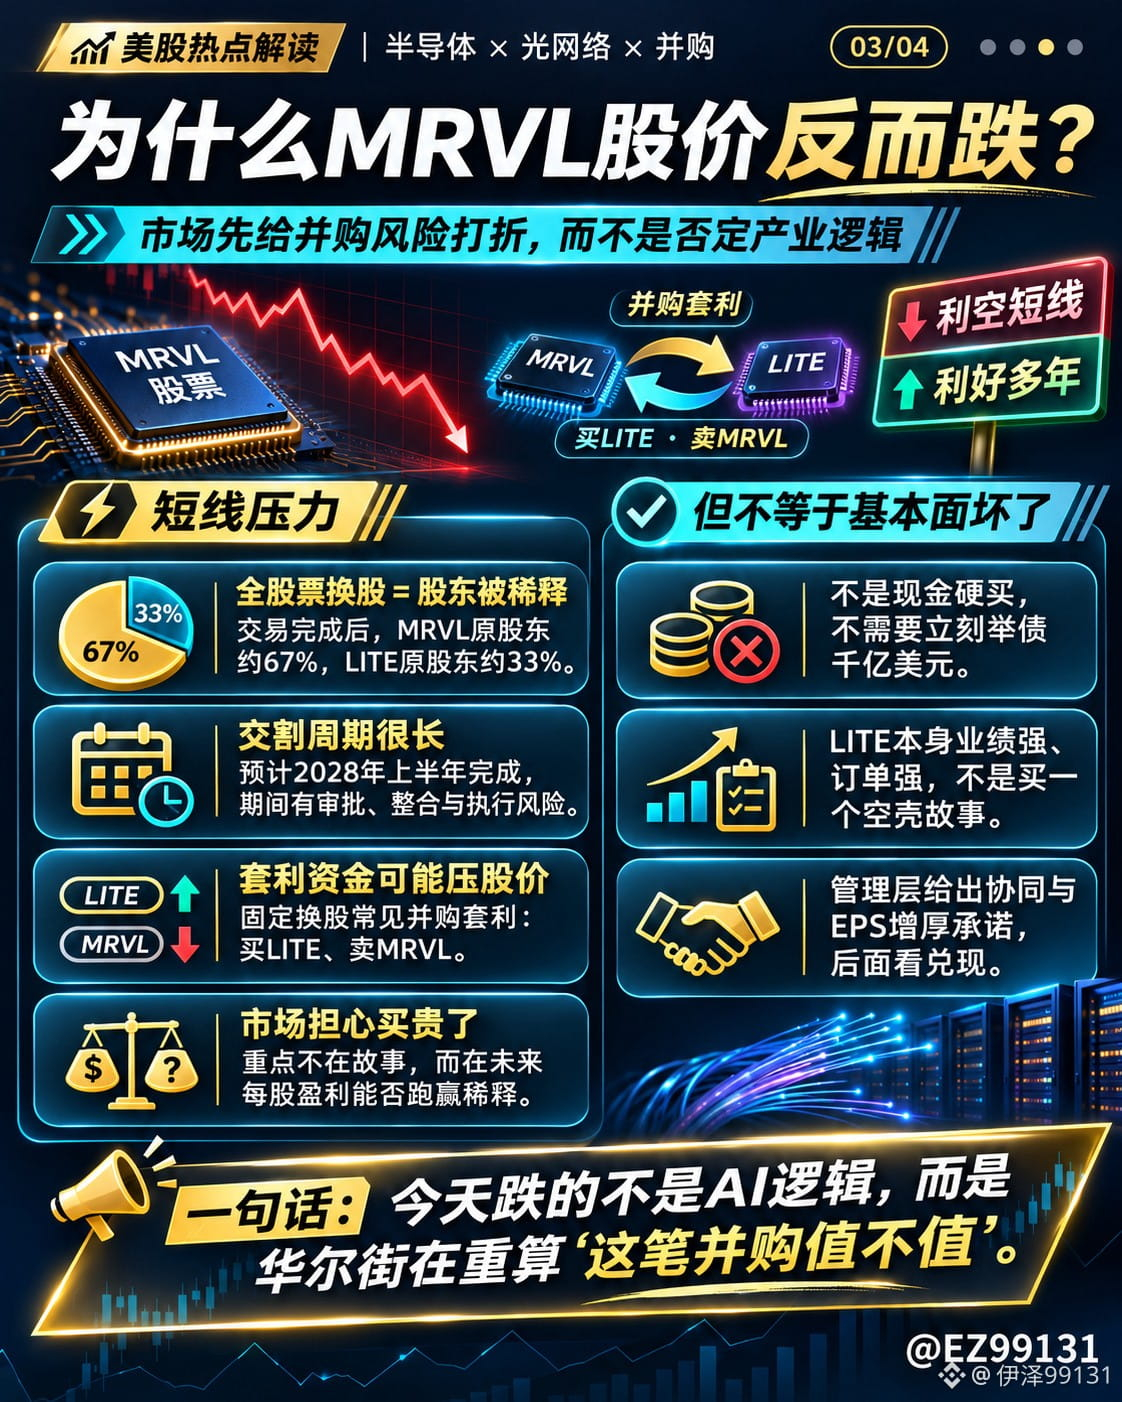
$MRVL 豪掷1150亿美元收购 $LITE,股价却连续暴跌。我觉得这笔交易没那么简单。
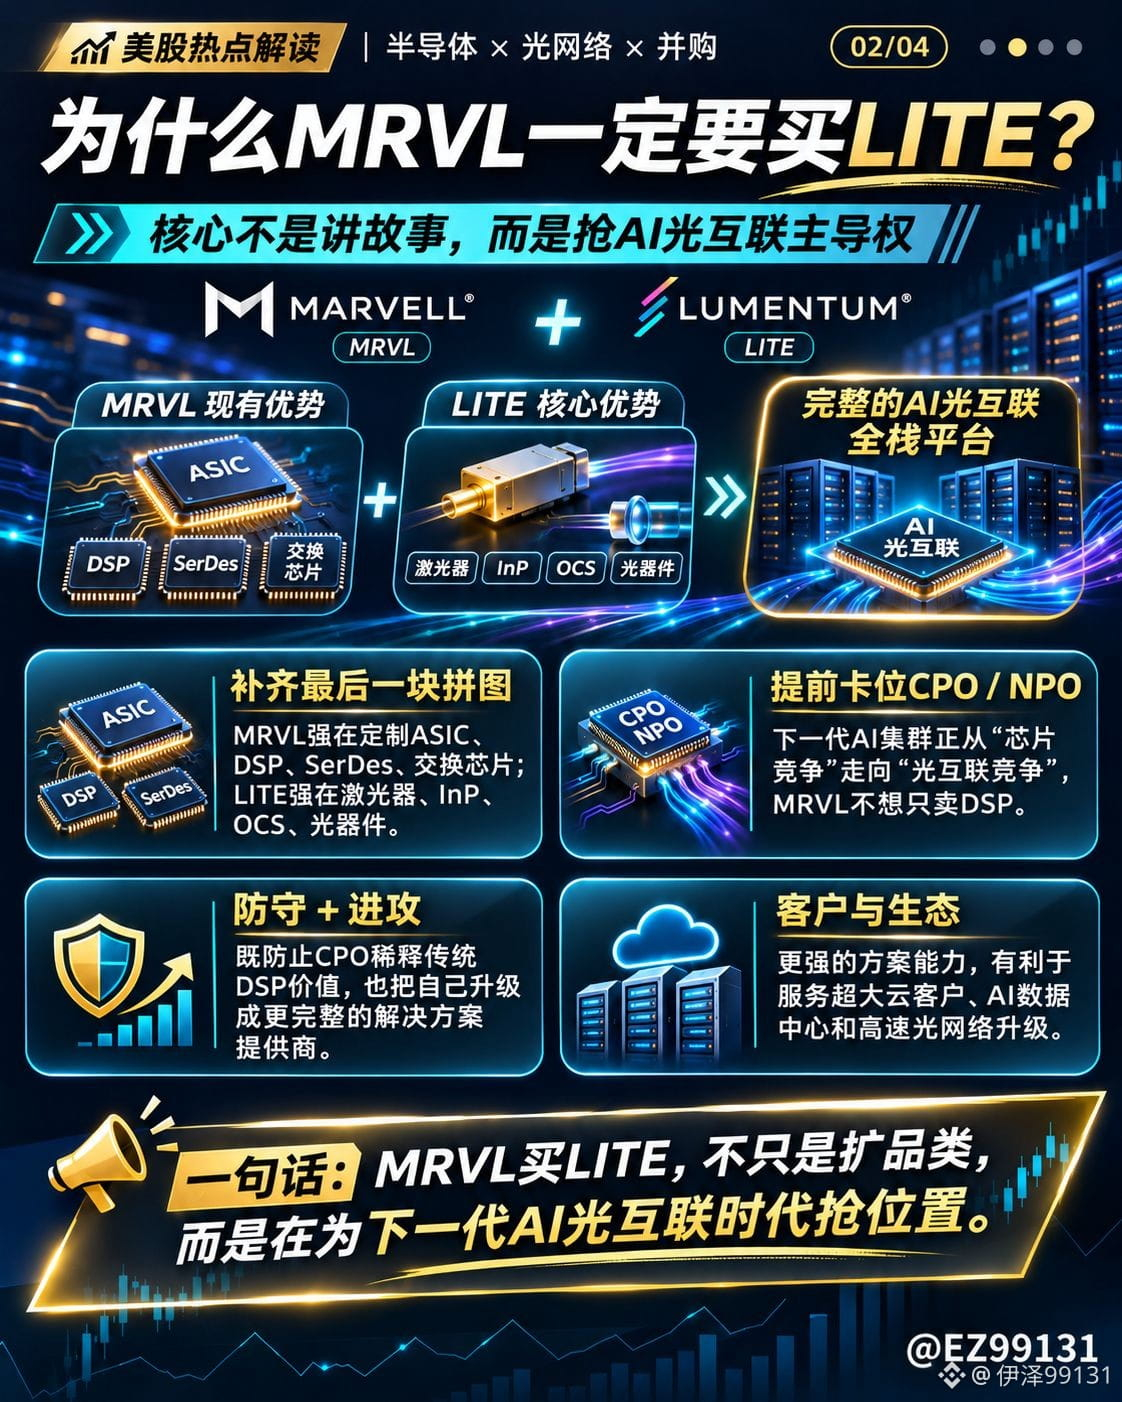
Marvell真正想买的,不只是Lumentum的营收,而是它手里的磷化铟(InP)激光器、光学器件和制造产能。
MRVL本身强在ASIC、DSP、SerDes和高速网络芯片,但AI集群越来越大,未来竞争的重点正在从算力延伸到光互联。
尤其是CPO技术的发展,可能削弱部分传统DSP的价值。MRVL现在买LITE,既是在补齐自己的技术短板,也是在提前布局下一代AI数据中心。
但问题是,这笔收购真的划算吗?
交易隐含企业价值约1150亿美元,采用100%股票交换,1股LITE换4.5股MRVL,预计2028年上半年完成。
这不是为了收购而向市场融资上千亿美元,但确实存在股权稀释。交易完成后,MRVL原股东预计只占合并后公司的67%。
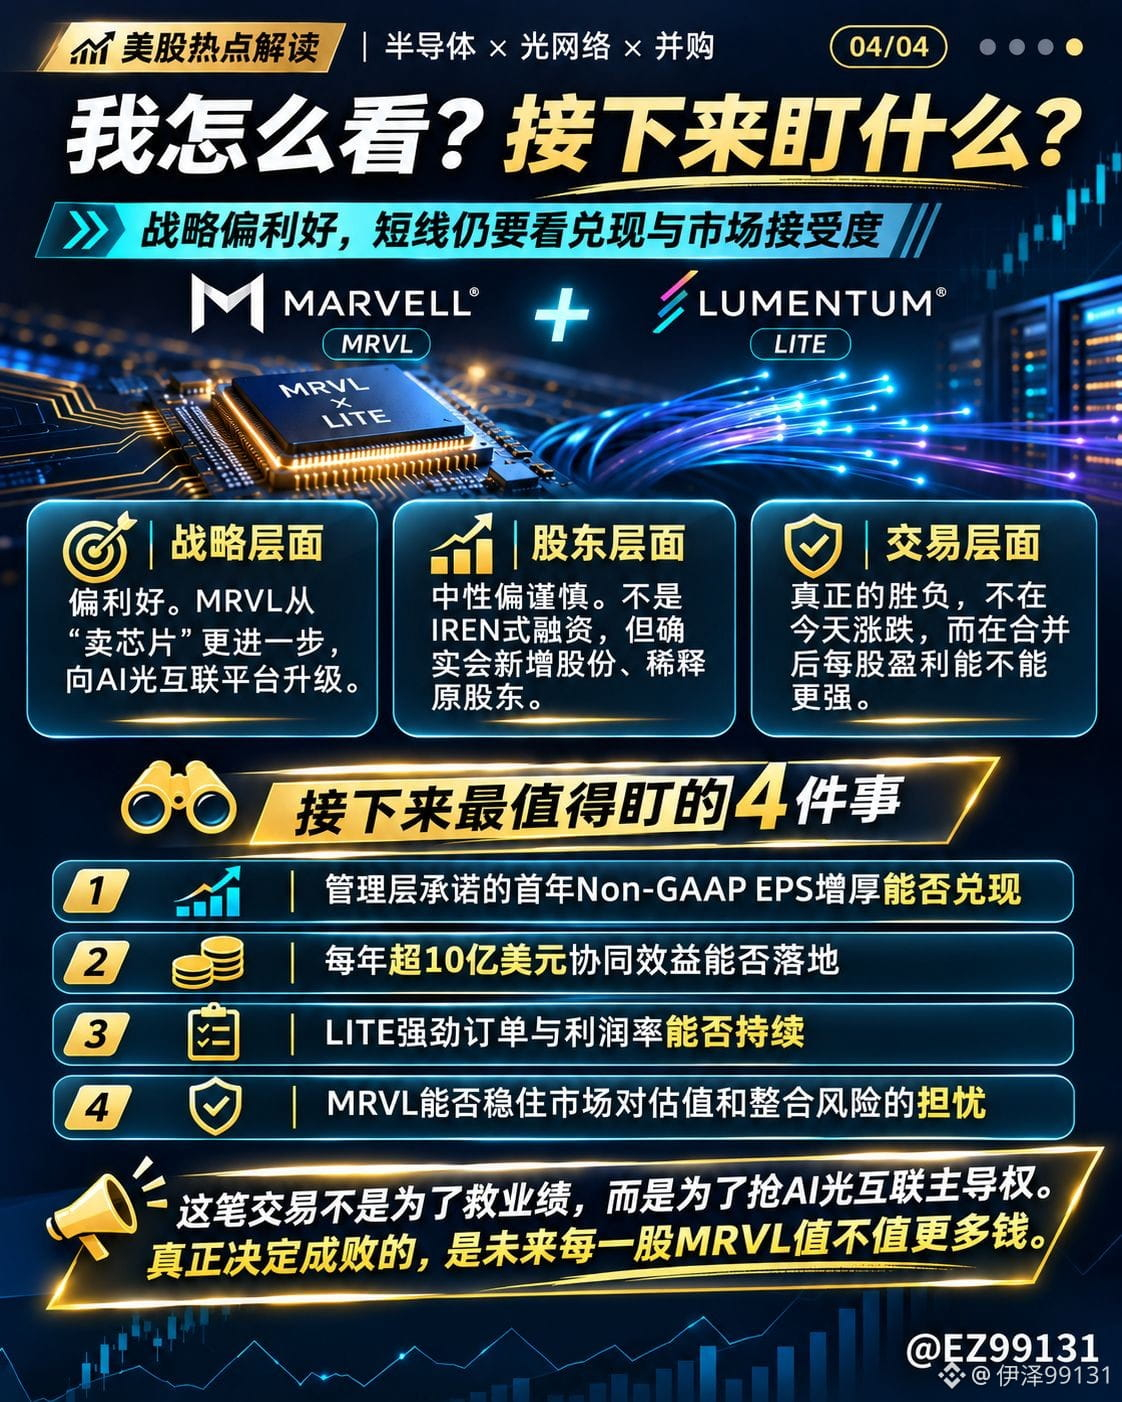
管理层承诺每年超过10亿美元的协同效益,并预计交割后第一年就能增厚调整后EPS。
这些如果兑现,长期确实有想象空间。
个人的看法是,MRVL的战略方向没问题,但好资产不代表任何价格都值得买。
华尔街担心的不是AI光互联没有未来,而是Marvell为了抢占这个市场,会不会付出太高的代价。
这笔交易最终是利好还是利空,关键不在今天股价涨跌,而在未来每股盈利能否真正跑赢稀释带来的成本。
AI光互联的机会很大,但股东最终赚不赚钱,还得看资本回报率。
美股重头戏: $MRVL 豪掷1150亿美元收购 $LITE !
今天Marvell终于官宣收购Lumentum。
这笔交易的规模确实超出了很多人的预期。
$MRVL 豪掷1150亿美元收购 $LITE ,股价却连续暴跌。我觉得这笔交易没那么简单。
Marvell真正想买的,不只是Lumentum的营收,而是它手里的磷化铟(InP)激光器、光学器件和制造产能。
MRVL本身强在ASIC、DSP、SerDes和高速网络芯片,但AI集群越来越大,未来竞争的重点正在从算力延伸到光互联。
尤其是CPO技术的发展,可能削弱部分传统DSP的价值。MRVL现在买LITE,既是在补齐自己的技术短板,也是在提前布局下一代AI数据中心。
但问题是,这笔收购真的划算吗?
交易隐含企业价值约1150亿美元,采用100%股票交换,1股LITE换4.5股MRVL,预计2028年上半年完成。
这不是为了收购而向市场融资上千亿美元,但确实存在股权稀释。交易完成后,MRVL原股东预计只占合并后公司的67%。
管理层承诺每年超过10亿美元的协同效益,并预计交割后第一年就能增厚调整后EPS。
这些如果兑现,长期确实有想象空间。
个人的看法是,MRVL的战略方向没问题,但好资产不代表任何价格都值得买。
华尔街担心的不是AI光互联没有未来,而是Marvell为了抢占这个市场,会不会付出太高的代价。
这笔交易最终是利好还是利空,关键不在今天股价涨跌,而在未来每股盈利能否真正跑赢稀释带来的成本。
AI光互联的机会很大,但股东最终赚不赚钱,还得看资本回报率。
今天Marvell终于官宣收购Lumentum。
这笔交易的规模确实超出了很多人的预期。
$MRVL 豪掷1150亿美元收购 $LITE ,股价却连续暴跌。我觉得这笔交易没那么简单。
Marvell真正想买的,不只是Lumentum的营收,而是它手里的磷化铟(InP)激光器、光学器件和制造产能。
MRVL本身强在ASIC、DSP、SerDes和高速网络芯片,但AI集群越来越大,未来竞争的重点正在从算力延伸到光互联。
尤其是CPO技术的发展,可能削弱部分传统DSP的价值。MRVL现在买LITE,既是在补齐自己的技术短板,也是在提前布局下一代AI数据中心。
但问题是,这笔收购真的划算吗?
交易隐含企业价值约1150亿美元,采用100%股票交换,1股LITE换4.5股MRVL,预计2028年上半年完成。
这不是为了收购而向市场融资上千亿美元,但确实存在股权稀释。交易完成后,MRVL原股东预计只占合并后公司的67%。
管理层承诺每年超过10亿美元的协同效益,并预计交割后第一年就能增厚调整后EPS。
这些如果兑现,长期确实有想象空间。
个人的看法是,MRVL的战略方向没问题,但好资产不代表任何价格都值得买。
华尔街担心的不是AI光互联没有未来,而是Marvell为了抢占这个市场,会不会付出太高的代价。
这笔交易最终是利好还是利空,关键不在今天股价涨跌,而在未来每股盈利能否真正跑赢稀释带来的成本。
AI光互联的机会很大,但股东最终赚不赚钱,还得看资本回报率。
1
4
4.6k
·
--
SpaceX 财报炸了!AI收入暴增830%,但最赚钱的竟然不是AI
$SPCX 昨晚这份Q3财报,确实有点夸张。
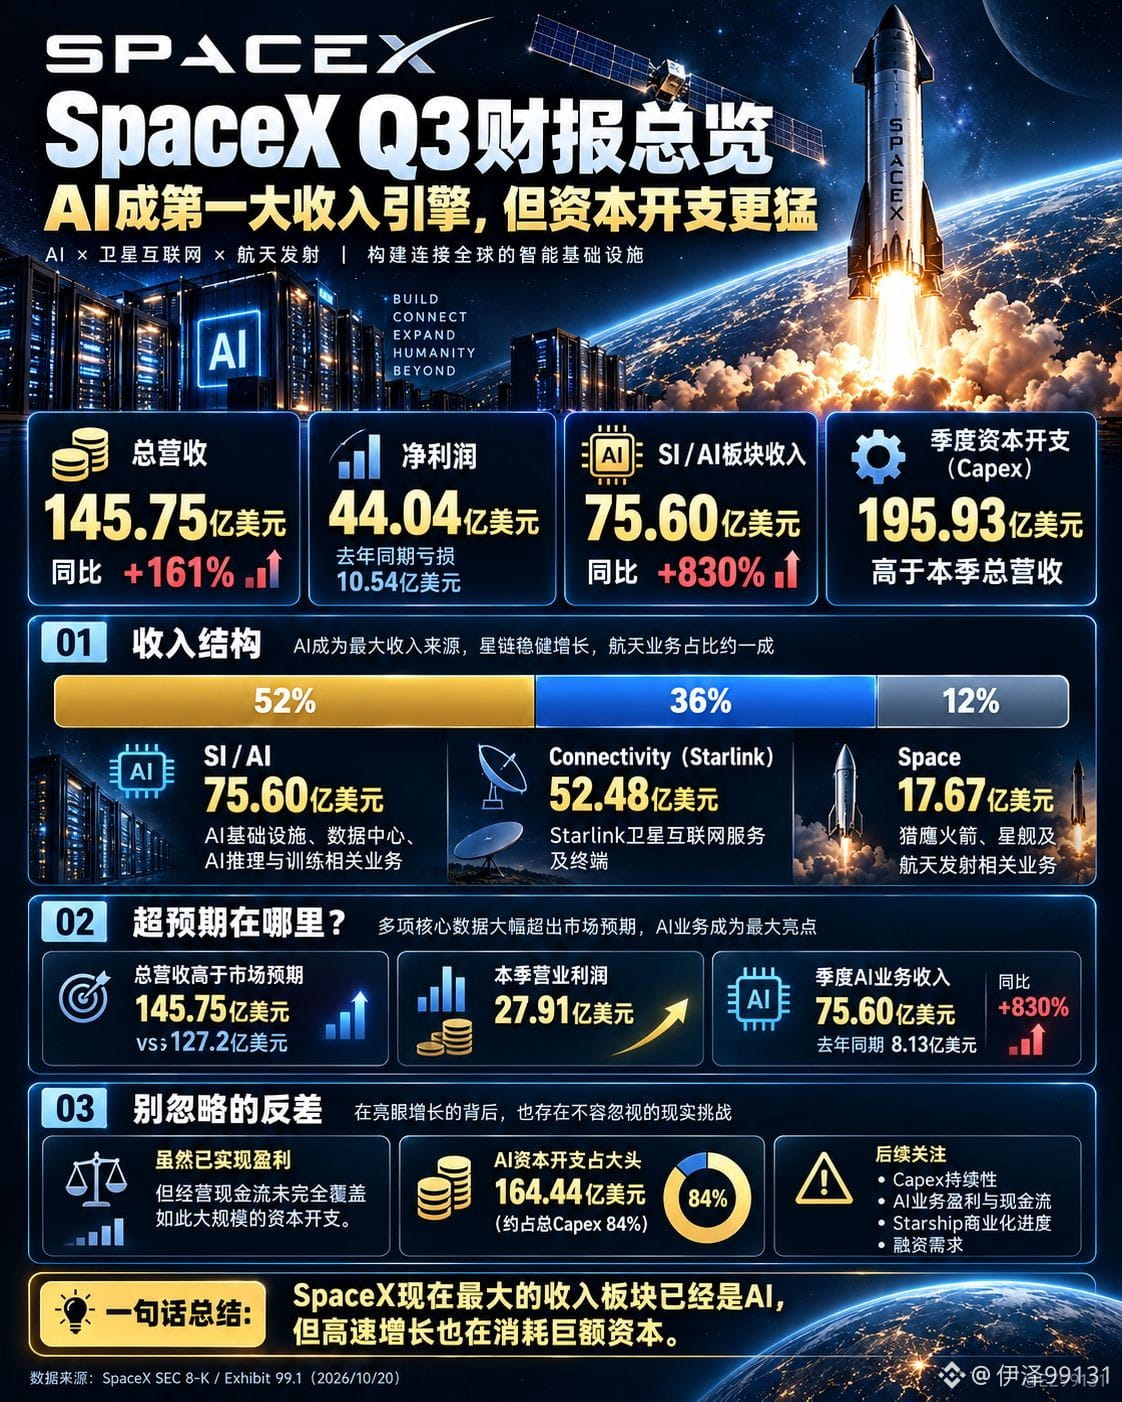
总营收145.75亿美元,同比增长161%。
净利润44.04亿美元,去年同期还亏损10.54亿美元。
最猛的是AI业务,单季度收入75.60亿美元,同比增长830%,已经占到SpaceX总收入的52%。
也就是说,大家一直印象中那个造火箭、发卫星的SpaceX,如今最大的收入来源竟然已经变成了AI
但我仔细看完财报后,反而觉得另外两组数字更值得关注。
第一组是利润
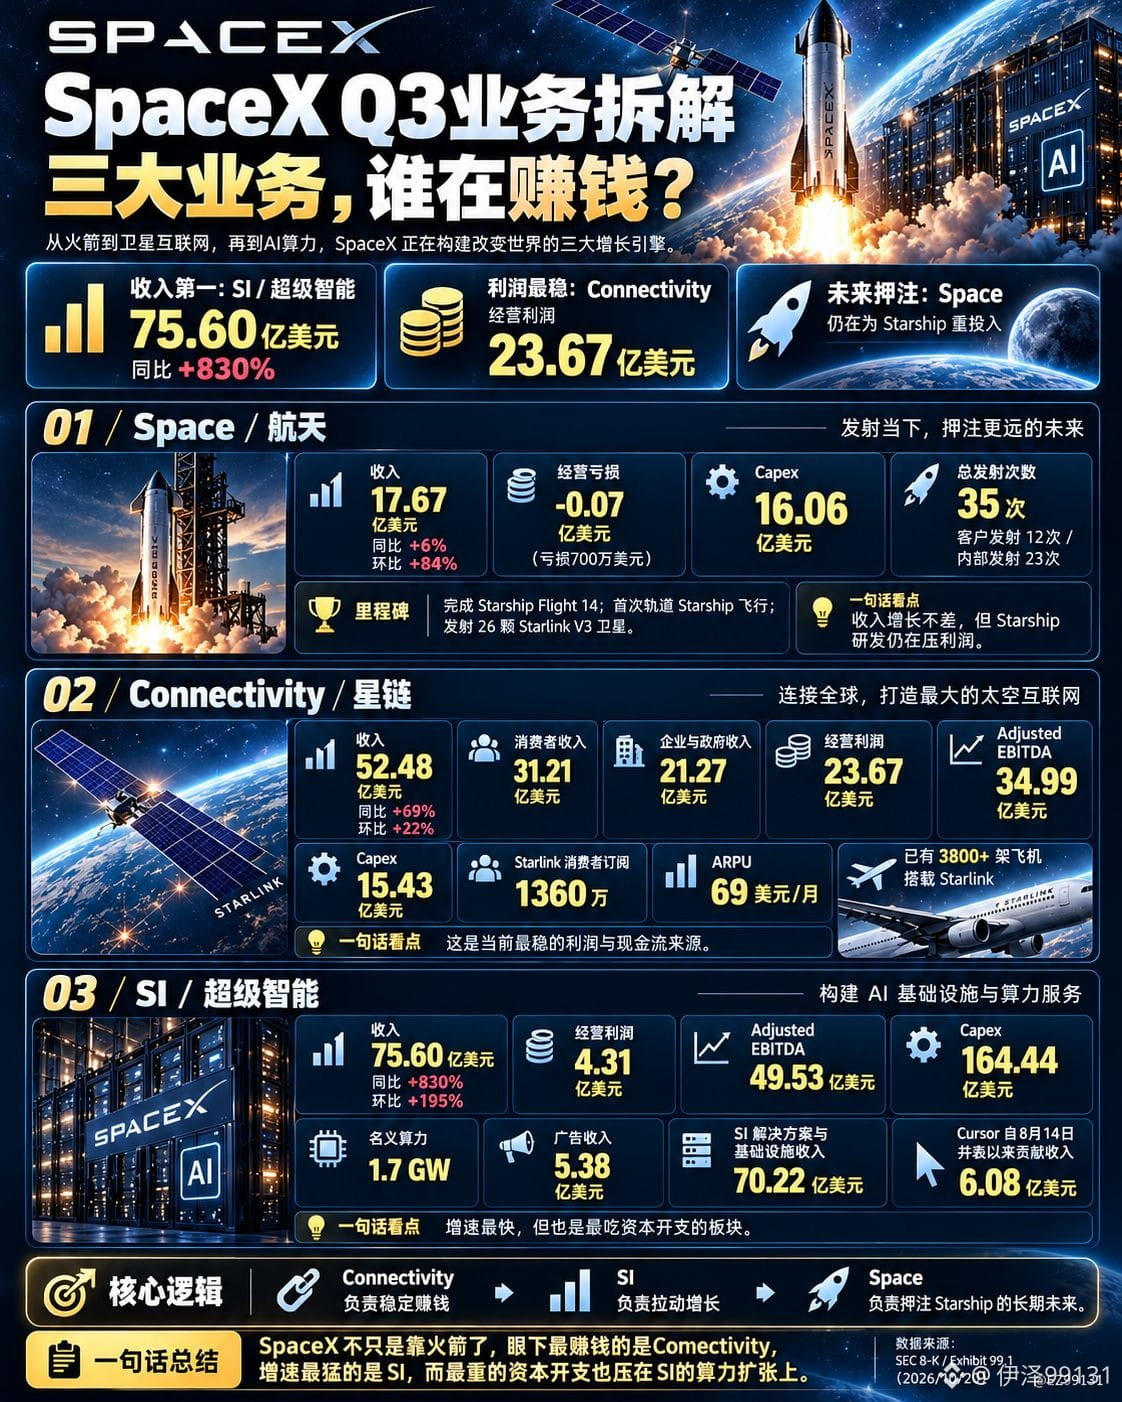
AI业务收入75.60亿美元,但经营利润只有4.31亿美元。
反倒是Starlink所在的连接业务,收入52.48亿美元,却创造了23.67亿美元经营利润。
SpaceX目前增长最快的业务是AI,但真正稳定贡献利润的,仍然是Starlink。
第二组是资本开支。
本季度SpaceX总资本开支195.93亿美元,其中164.44亿美元投入AI,占比接近84%。
这是单季度!
花在AI上的钱,已经超过整个公司的季度营收。
虽然SpaceX已经实现44亿美元净利润,但会计利润不等于自由现金流。后续还需要观察这些庞大的数据中心和算力投入,究竟能产生多少现金回报。
整个美股AI产业链正在面临的问题。
从 $NVDA、 $AVGO、 $MRVL,到 $MSFT、 $META、 $AMZN、 $GOOGL,大家都在围绕AI进行巨额资本投入。
芯片订单越来越大,算力需求越来越强,营收也确实在增长。
SpaceX的商业结构已经越来越清晰。
我依然看好AI基础设施未来几年的发展空间,但我不认为收入增长越快,股价就一定越值得追。
真正决定长期回报的,还是利润率、资本效率和现金流。
份财报恰好把AI超级周期最有意思的一面展示出来了:
增长是真的,需求也是真的,但烧钱同样是真的。
未来最值得研究的,可能不再是谁的AI收入增长最快,而是谁能真正把算力变成持续、可观的自由现金流。
#SpaceX #SPCX #NVDA #美股 #人工智能
SpaceX 财报炸了!AI收入暴增830%,但最赚钱的竟然不是AI
$SPCX 昨晚这份Q3财报,确实有点夸张。
总营收145.75亿美元,同比增长161%。
净利润44.04亿美元,去年同期还亏损10.54亿美元。
最猛的是AI业务,单季度收入75.60亿美元,同比增长830%,已经占到SpaceX总收入的52%。
也就是说,大家一直印象中那个造火箭、发卫星的SpaceX,如今最大的收入来源竟然已经变成了AI
但我仔细看完财报后,反而觉得另外两组数字更值得关注。
第一组是利润
AI业务收入75.60亿美元,但经营利润只有4.31亿美元。
反倒是Starlink所在的连接业务,收入52.48亿美元,却创造了23.67亿美元经营利润。
SpaceX目前增长最快的业务是AI,但真正稳定贡献利润的,仍然是Starlink。
第二组是资本开支。
本季度SpaceX总资本开支195.93亿美元,其中164.44亿美元投入AI,占比接近84%。
这是单季度!
花在AI上的钱,已经超过整个公司的季度营收。
虽然SpaceX已经实现44亿美元净利润,但会计利润不等于自由现金流。后续还需要观察这些庞大的数据中心和算力投入,究竟能产生多少现金回报。
整个美股AI产业链正在面临的问题。
从 $NVDA、 $AVGO、 $MRVL,到 $MSFT、 $META、 $AMZN、 $GOOGL,大家都在围绕AI进行巨额资本投入。
芯片订单越来越大,算力需求越来越强,营收也确实在增长。
SpaceX的商业结构已经越来越清晰。
我依然看好AI基础设施未来几年的发展空间,但我不认为收入增长越快,股价就一定越值得追。
真正决定长期回报的,还是利润率、资本效率和现金流。
份财报恰好把AI超级周期最有意思的一面展示出来了:
增长是真的,需求也是真的,但烧钱同样是真的。
未来最值得研究的,可能不再是谁的AI收入增长最快,而是谁能真正把算力变成持续、可观的自由现金流。
#SpaceX #SPCX #NVDA #美股 #人工智能
$SPCX 昨晚这份Q3财报,确实有点夸张。
总营收145.75亿美元,同比增长161%。
净利润44.04亿美元,去年同期还亏损10.54亿美元。
最猛的是AI业务,单季度收入75.60亿美元,同比增长830%,已经占到SpaceX总收入的52%。
也就是说,大家一直印象中那个造火箭、发卫星的SpaceX,如今最大的收入来源竟然已经变成了AI
但我仔细看完财报后,反而觉得另外两组数字更值得关注。
第一组是利润
AI业务收入75.60亿美元,但经营利润只有4.31亿美元。
反倒是Starlink所在的连接业务,收入52.48亿美元,却创造了23.67亿美元经营利润。
SpaceX目前增长最快的业务是AI,但真正稳定贡献利润的,仍然是Starlink。
第二组是资本开支。
本季度SpaceX总资本开支195.93亿美元,其中164.44亿美元投入AI,占比接近84%。
这是单季度!
花在AI上的钱,已经超过整个公司的季度营收。
虽然SpaceX已经实现44亿美元净利润,但会计利润不等于自由现金流。后续还需要观察这些庞大的数据中心和算力投入,究竟能产生多少现金回报。
整个美股AI产业链正在面临的问题。
从 $NVDA、 $AVGO、 $MRVL,到 $MSFT、 $META、 $AMZN、 $GOOGL,大家都在围绕AI进行巨额资本投入。
芯片订单越来越大,算力需求越来越强,营收也确实在增长。
SpaceX的商业结构已经越来越清晰。
我依然看好AI基础设施未来几年的发展空间,但我不认为收入增长越快,股价就一定越值得追。
真正决定长期回报的,还是利润率、资本效率和现金流。
份财报恰好把AI超级周期最有意思的一面展示出来了:
增长是真的,需求也是真的,但烧钱同样是真的。
未来最值得研究的,可能不再是谁的AI收入增长最快,而是谁能真正把算力变成持续、可观的自由现金流。
#SpaceX #SPCX #NVDA #美股 #人工智能
1
167
·
--
Расталды
Мақала
$NVDA AI服务器突然要涨价15%以上,真正的大赢家可能是 $MUNVIDIA服务器涨价超过15%。
① 最重要利好
1. $NVDA 服务器被曝涨价超过15%,真正受益的可能不只是英伟达
Bloomberg周六报道称,NVIDIA部分最大客户已经收到通知,搭载AI芯片的服务器价格很多情况下将上涨 15%以上。
涨价主要会影响2027年初开始交付的系统,包括:
Vera Rubin
Grace Blackwell
而这次涨价一个非常重要的原因是:
内存芯片价格大幅上涨。
Reuters已经对Bloomberg这条报道进行了确认。
市场过去几个月一直在讨论:
HBM是不是快到周期顶部了?
现在出现的信号反而是:
内存价格已经开始高到直接推升整台AI服务器售价。
这条消息不只是 $NVDA 利好。
对:
$MU
SK海力士
三星
HBM供应链
反而可能更重要。
服务器厂商已经开始把成本直接往微软、Google、Oracle这些客户身上传导。
这说明目前AI需求仍然强到一个程度:
价格上涨还没有立刻把需求打掉。
但这里也有一个风险。
如果一台AI服务器越来越贵,Hyperscaler未来会不会开始重新计算:
每增加1美元Capex,到底还能创造多少AI收入?
这会是明年非常重要的问题。
所以判断
短期利好NVDA和MU,长期会进一步放大市场对AI Capex回报率的关注。
2. $MU 现在的逻辑开始从“HBM涨价”变成“整个AI服务器成本上涨”
海力士回购287亿美元
三星准备超过700亿美元级别股东回报
MU继续投入AI存储
这些都说明存储厂商现金流非常强。
但今天NVIDIA服务器涨价的消息等于从另外一个角度验证:
内存供需真的非常紧。
而且不仅是HBM。
AI服务器本身需要大量:
HBM
DDR
SSD / NAND
所以只要AI服务器出货继续增长,MU吃到的不只是单一HBM需求,而是整个AI服务器存储容量提升。
不过长期还是要盯YMTC。
YMTC母公司准备在上海科创板募资约 49亿美元,继续投入先进NAND产能和研发。Reuters数据显示,YMTC目前已经进入全球NAND前三。
所以对MU现在的判断是:
短中期供需仍然强,真正需要担心的是未来两三年供给,而不是下个季度突然需求崩掉。
② 重要利空
1. AI现在最大的风险开始从“芯片够不够”转向“资本够不够”
这周Broadcom讨论超过 600亿美元AI融资,整体规模甚至可能接近1000亿美元。
NVIDIA又和大型金融机构合作,希望撬动超过 5000亿美元AI基础设施资金。
与此同时,AI服务器现在又开始涨价超过15%。
把这几个消息放在一起,就会发现一个很明显的变化:
过去两年AI产业的问题是:
GPU不够。
现在越来越变成:
钱够不够?
服务器越来越贵
电力越来越贵
土地越来越贵
融资成本也越来越高
所以我认为下一个阶段AI公司的分化会越来越大。
像:$NVDA
$AVGO
$MRVL
$MU
本质上更接近卖芯片、卖设备、卖基础设施。
而:
$CRWV
$NBIS
$APLD
部分高杠杆AI数据中心公司
需要不断借钱把基础设施建出来。
后者对30年美债和信用利差会敏感得多。
2. 美伊周末继续升级,Brent 95美元还是下周第一道风险线
周末美伊没有明显降温。
伊朗最新表示,美国新一轮制裁是非法的,并继续威胁未经许可通过霍尔木兹海峡的油轮。
美国财政部长Bessent将在周一公布新一轮对伊朗制裁细节,并称这是“史上最严厉”的制裁。
有一个消息看起来像缓和:
伊朗允许部分伊拉克油轮通过霍尔木兹海峡。
但这里不能误读。
这是特别许可,不是海峡恢复正常通航。
所以不会因为这条消息就判断油价风险解除。
周五Brent最终收在:
94.39美元
本周累计上涨 6.39%。
下周一第一件事还是看:
Brent 95美元。
如果制裁细节比市场预期更严,同时伊朗继续反击,那么油价可能重新向100美元靠近。
到时候传导链还是:
油价 ↑ → 通胀预期 ↑ → 美债收益率 ↑ → AI估值压力 ↑
③ 宏观 / 美债 / 美元 / BTC
美债
财政部扩大长期国债回购以后,市场只喘了一口气。
到周五,全球市场仍然在交易高长债收益率,Reuters直接指出30年美债此前已经冲到2007年以来最高附近。
所以我还是原来的判断:
现在不是正式YCC。
财政部可以改善流动性,但:
40万亿美元国债
超过6%的财政赤字
超过1万亿美元利息支出
这些东西并没有消失。
美元
美元上周反而跌了接近1%。
市场开始担心财政部压长债以后,压力会从债市转移到美元。
这个逻辑目前利好:
黄金
BTC
$BTC上周累计上涨接近20%,是两年半以来表现最好的一周之一。
所以市场现在并不是全面Risk-off。
更像是:
不喜欢长期美元资产,但愿意买稀缺资产。
这对 $HUT 这种BTC + AI基础设施属性公司会比较有意思。
但对纯AI数据中心公司,我还是那句话:
长债比BTC重要。
④ 公司 / 订单 / 政策
$NVDA
今天最大的新消息就是服务器涨价超过15%。
同时下周三8月26日就是财报。
所以这条消息出来以后,财报里有几个问题会更重要:
Blackwell需求有没有因为价格上涨放缓
Rubin订单情况
HBM成本上涨能不能完全转嫁给客户
Hyperscaler是否继续维持高Capex
客户融资能力
这次财报我觉得市场不会只看EPS。
$MRVL / $AVGO
截至今天早上,没有新的一级客户订单。
Google × MRVL和Broadcom巨额融资都是前几天的新闻。
无重大新增。
$AMD / $TSM / $ASML / $AMAT / $LRCX
没有发现新的足以改变基本面的正式订单或指引。
无重大更新。
$CRWV / $NBIS / $HUT / $APLD
没有新的一级重大客户合同。
但融资成本仍然是整个板块最值得看的风险。
无公司级重大更新。
⑤ 下周必须盯的事情
真正需要准备的是下周。
第一件事:
周一美伊新制裁
Bessent将在美东周一下午公布细节。
先看Brent有没有破95。
第二件事:
8月26日 $NVDA 财报
这会直接决定:
$NVDA
$AVGO
$MRVL
$MU
$CRWV
$NBIS
$APLD
整个AI链下半周怎么走。
第三件事:
8月26日美国PCE
现在油价已经重新接近95美元。
如果PCE再高于预期,市场对Fed加息的押注可能继续升温。
第四件事:
Jackson Hole
市场目前仍然在定价今年继续加息的可能性。
Reuters此前统计,市场给9月加息大约35%概率,年底前大约66%。
所以NVDA财报哪怕很好,
如果同一周Fed明显转鹰,也可能出现:
财报很好,股票却不涨
$NVDA AI服务器突然要涨价15%以上,真正的大赢家可能是 $MU
NVIDIA服务器涨价超过15%。
① 最重要利好
1. $NVDA 服务器被曝涨价超过15%,真正受益的可能不只是英伟达
Bloomberg周六报道称,NVIDIA部分最大客户已经收到通知,搭载AI芯片的服务器价格很多情况下将上涨 15%以上。
涨价主要会影响2027年初开始交付的系统,包括:
Vera Rubin
Grace Blackwell
而这次涨价一个非常重要的原因是:
内存芯片价格大幅上涨。
Reuters已经对Bloomberg这条报道进行了确认。
市场过去几个月一直在讨论:
HBM是不是快到周期顶部了?
现在出现的信号反而是:
内存价格已经开始高到直接推升整台AI服务器售价。
这条消息不只是 $NVDA 利好。
对:
$MU
SK海力士
三星
HBM供应链
反而可能更重要。
服务器厂商已经开始把成本直接往微软、Google、Oracle这些客户身上传导。
这说明目前AI需求仍然强到一个程度:
价格上涨还没有立刻把需求打掉。
但这里也有一个风险。
如果一台AI服务器越来越贵,Hyperscaler未来会不会开始重新计算:
每增加1美元Capex,到底还能创造多少AI收入?
这会是明年非常重要的问题。
所以判断
短期利好NVDA和MU,长期会进一步放大市场对AI Capex回报率的关注。
2. $MU 现在的逻辑开始从“HBM涨价”变成“整个AI服务器成本上涨”
海力士回购287亿美元
三星准备超过700亿美元级别股东回报
MU继续投入AI存储
这些都说明存储厂商现金流非常强。
但今天NVIDIA服务器涨价的消息等于从另外一个角度验证:
内存供需真的非常紧。
而且不仅是HBM。
AI服务器本身需要大量:
HBM
DDR
SSD / NAND
所以只要AI服务器出货继续增长,MU吃到的不只是单一HBM需求,而是整个AI服务器存储容量提升。
不过长期还是要盯YMTC。
YMTC母公司准备在上海科创板募资约 49亿美元,继续投入先进NAND产能和研发。Reuters数据显示,YMTC目前已经进入全球NAND前三。
所以对MU现在的判断是:
短中期供需仍然强,真正需要担心的是未来两三年供给,而不是下个季度突然需求崩掉。
② 重要利空
1. AI现在最大的风险开始从“芯片够不够”转向“资本够不够”
这周Broadcom讨论超过 600亿美元AI融资,整体规模甚至可能接近1000亿美元。
NVIDIA又和大型金融机构合作,希望撬动超过 5000亿美元AI基础设施资金。
与此同时,AI服务器现在又开始涨价超过15%。
把这几个消息放在一起,就会发现一个很明显的变化:
过去两年AI产业的问题是:
GPU不够。
现在越来越变成:
钱够不够?
服务器越来越贵
电力越来越贵
土地越来越贵
融资成本也越来越高
所以我认为下一个阶段AI公司的分化会越来越大。
像:$NVDA
$AVGO
$MRVL
$MU
本质上更接近卖芯片、卖设备、卖基础设施。
而:
$CRWV
$NBIS
$APLD
部分高杠杆AI数据中心公司
需要不断借钱把基础设施建出来。
后者对30年美债和信用利差会敏感得多。
2. 美伊周末继续升级,Brent 95美元还是下周第一道风险线
周末美伊没有明显降温。
伊朗最新表示,美国新一轮制裁是非法的,并继续威胁未经许可通过霍尔木兹海峡的油轮。
美国财政部长Bessent将在周一公布新一轮对伊朗制裁细节,并称这是“史上最严厉”的制裁。
有一个消息看起来像缓和:
伊朗允许部分伊拉克油轮通过霍尔木兹海峡。
但这里不能误读。
这是特别许可,不是海峡恢复正常通航。
所以不会因为这条消息就判断油价风险解除。
周五Brent最终收在:
94.39美元
本周累计上涨 6.39%。
下周一第一件事还是看:
Brent 95美元。
如果制裁细节比市场预期更严,同时伊朗继续反击,那么油价可能重新向100美元靠近。
到时候传导链还是:
油价 ↑ → 通胀预期 ↑ → 美债收益率 ↑ → AI估值压力 ↑
③ 宏观 / 美债 / 美元 / BTC
美债
财政部扩大长期国债回购以后,市场只喘了一口气。
到周五,全球市场仍然在交易高长债收益率,Reuters直接指出30年美债此前已经冲到2007年以来最高附近。
所以我还是原来的判断:
现在不是正式YCC。
财政部可以改善流动性,但:
40万亿美元国债
超过6%的财政赤字
超过1万亿美元利息支出
这些东西并没有消失。
美元
美元上周反而跌了接近1%。
市场开始担心财政部压长债以后,压力会从债市转移到美元。
这个逻辑目前利好:
黄金
BTC
$BTC上周累计上涨接近20%,是两年半以来表现最好的一周之一。
所以市场现在并不是全面Risk-off。
更像是:
不喜欢长期美元资产,但愿意买稀缺资产。
这对 $HUT 这种BTC + AI基础设施属性公司会比较有意思。
但对纯AI数据中心公司,我还是那句话:
长债比BTC重要。
④ 公司 / 订单 / 政策
$NVDA
今天最大的新消息就是服务器涨价超过15%。
同时下周三8月26日就是财报。
所以这条消息出来以后,财报里有几个问题会更重要:
Blackwell需求有没有因为价格上涨放缓
Rubin订单情况
HBM成本上涨能不能完全转嫁给客户
Hyperscaler是否继续维持高Capex
客户融资能力
这次财报我觉得市场不会只看EPS。
$MRVL / $AVGO
截至今天早上,没有新的一级客户订单。
Google × MRVL和Broadcom巨额融资都是前几天的新闻。
无重大新增。
$AMD / $TSM / $ASML / $AMAT / $LRCX
没有发现新的足以改变基本面的正式订单或指引。
无重大更新。
$CRWV / $NBIS / $HUT / $APLD
没有新的一级重大客户合同。
但融资成本仍然是整个板块最值得看的风险。
无公司级重大更新。
⑤ 下周必须盯的事情
真正需要准备的是下周。
第一件事:
周一美伊新制裁
Bessent将在美东周一下午公布细节。
先看Brent有没有破95。
第二件事:
8月26日 $NVDA 财报
这会直接决定:
$NVDA
$AVGO
$MRVL
$MU
$CRWV
$NBIS
$APLD
整个AI链下半周怎么走。
第三件事:
8月26日美国PCE
现在油价已经重新接近95美元。
如果PCE再高于预期,市场对Fed加息的押注可能继续升温。
第四件事:
Jackson Hole
市场目前仍然在定价今年继续加息的可能性。
Reuters此前统计,市场给9月加息大约35%概率,年底前大约66%。
所以NVDA财报哪怕很好,
如果同一周Fed明显转鹰,也可能出现:
财报很好,股票却不涨
① 最重要利好
1. $NVDA 服务器被曝涨价超过15%,真正受益的可能不只是英伟达
Bloomberg周六报道称,NVIDIA部分最大客户已经收到通知,搭载AI芯片的服务器价格很多情况下将上涨 15%以上。
涨价主要会影响2027年初开始交付的系统,包括:
Vera Rubin
Grace Blackwell
而这次涨价一个非常重要的原因是:
内存芯片价格大幅上涨。
Reuters已经对Bloomberg这条报道进行了确认。
市场过去几个月一直在讨论:
HBM是不是快到周期顶部了?
现在出现的信号反而是:
内存价格已经开始高到直接推升整台AI服务器售价。
这条消息不只是 $NVDA 利好。
对:
$MU
SK海力士
三星
HBM供应链
反而可能更重要。
服务器厂商已经开始把成本直接往微软、Google、Oracle这些客户身上传导。
这说明目前AI需求仍然强到一个程度:
价格上涨还没有立刻把需求打掉。
但这里也有一个风险。
如果一台AI服务器越来越贵,Hyperscaler未来会不会开始重新计算:
每增加1美元Capex,到底还能创造多少AI收入?
这会是明年非常重要的问题。
所以判断
短期利好NVDA和MU,长期会进一步放大市场对AI Capex回报率的关注。
2. $MU 现在的逻辑开始从“HBM涨价”变成“整个AI服务器成本上涨”
海力士回购287亿美元
三星准备超过700亿美元级别股东回报
MU继续投入AI存储
这些都说明存储厂商现金流非常强。
但今天NVIDIA服务器涨价的消息等于从另外一个角度验证:
内存供需真的非常紧。
而且不仅是HBM。
AI服务器本身需要大量:
HBM
DDR
SSD / NAND
所以只要AI服务器出货继续增长,MU吃到的不只是单一HBM需求,而是整个AI服务器存储容量提升。
不过长期还是要盯YMTC。
YMTC母公司准备在上海科创板募资约 49亿美元,继续投入先进NAND产能和研发。Reuters数据显示,YMTC目前已经进入全球NAND前三。
所以对MU现在的判断是:
短中期供需仍然强,真正需要担心的是未来两三年供给,而不是下个季度突然需求崩掉。
② 重要利空
1. AI现在最大的风险开始从“芯片够不够”转向“资本够不够”
这周Broadcom讨论超过 600亿美元AI融资,整体规模甚至可能接近1000亿美元。
NVIDIA又和大型金融机构合作,希望撬动超过 5000亿美元AI基础设施资金。
与此同时,AI服务器现在又开始涨价超过15%。
把这几个消息放在一起,就会发现一个很明显的变化:
过去两年AI产业的问题是:
GPU不够。
现在越来越变成:
钱够不够?
服务器越来越贵
电力越来越贵
土地越来越贵
融资成本也越来越高
所以我认为下一个阶段AI公司的分化会越来越大。
像:$NVDA
$AVGO
$MRVL
$MU
本质上更接近卖芯片、卖设备、卖基础设施。
而:
$CRWV
$NBIS
$APLD
部分高杠杆AI数据中心公司
需要不断借钱把基础设施建出来。
后者对30年美债和信用利差会敏感得多。
2. 美伊周末继续升级,Brent 95美元还是下周第一道风险线
周末美伊没有明显降温。
伊朗最新表示,美国新一轮制裁是非法的,并继续威胁未经许可通过霍尔木兹海峡的油轮。
美国财政部长Bessent将在周一公布新一轮对伊朗制裁细节,并称这是“史上最严厉”的制裁。
有一个消息看起来像缓和:
伊朗允许部分伊拉克油轮通过霍尔木兹海峡。
但这里不能误读。
这是特别许可,不是海峡恢复正常通航。
所以不会因为这条消息就判断油价风险解除。
周五Brent最终收在:
94.39美元
本周累计上涨 6.39%。
下周一第一件事还是看:
Brent 95美元。
如果制裁细节比市场预期更严,同时伊朗继续反击,那么油价可能重新向100美元靠近。
到时候传导链还是:
油价 ↑ → 通胀预期 ↑ → 美债收益率 ↑ → AI估值压力 ↑
③ 宏观 / 美债 / 美元 / BTC
美债
财政部扩大长期国债回购以后,市场只喘了一口气。
到周五,全球市场仍然在交易高长债收益率,Reuters直接指出30年美债此前已经冲到2007年以来最高附近。
所以我还是原来的判断:
现在不是正式YCC。
财政部可以改善流动性,但:
40万亿美元国债
超过6%的财政赤字
超过1万亿美元利息支出
这些东西并没有消失。
美元
美元上周反而跌了接近1%。
市场开始担心财政部压长债以后,压力会从债市转移到美元。
这个逻辑目前利好:
黄金
BTC
$BTC上周累计上涨接近20%,是两年半以来表现最好的一周之一。
所以市场现在并不是全面Risk-off。
更像是:
不喜欢长期美元资产,但愿意买稀缺资产。
这对 $HUT 这种BTC + AI基础设施属性公司会比较有意思。
但对纯AI数据中心公司,我还是那句话:
长债比BTC重要。
④ 公司 / 订单 / 政策
$NVDA
今天最大的新消息就是服务器涨价超过15%。
同时下周三8月26日就是财报。
所以这条消息出来以后,财报里有几个问题会更重要:
Blackwell需求有没有因为价格上涨放缓
Rubin订单情况
HBM成本上涨能不能完全转嫁给客户
Hyperscaler是否继续维持高Capex
客户融资能力
这次财报我觉得市场不会只看EPS。
$MRVL / $AVGO
截至今天早上,没有新的一级客户订单。
Google × MRVL和Broadcom巨额融资都是前几天的新闻。
无重大新增。
$AMD / $TSM / $ASML / $AMAT / $LRCX
没有发现新的足以改变基本面的正式订单或指引。
无重大更新。
$CRWV / $NBIS / $HUT / $APLD
没有新的一级重大客户合同。
但融资成本仍然是整个板块最值得看的风险。
无公司级重大更新。
⑤ 下周必须盯的事情
真正需要准备的是下周。
第一件事:
周一美伊新制裁
Bessent将在美东周一下午公布细节。
先看Brent有没有破95。
第二件事:
8月26日 $NVDA 财报
这会直接决定:
$NVDA
$AVGO
$MRVL
$MU
$CRWV
$NBIS
$APLD
整个AI链下半周怎么走。
第三件事:
8月26日美国PCE
现在油价已经重新接近95美元。
如果PCE再高于预期,市场对Fed加息的押注可能继续升温。
第四件事:
Jackson Hole
市场目前仍然在定价今年继续加息的可能性。
Reuters此前统计,市场给9月加息大约35%概率,年底前大约66%。
所以NVDA财报哪怕很好,
如果同一周Fed明显转鹰,也可能出现:
财报很好,股票却不涨
1
806
·
--
Мақала
财政部刚刚“救”完美债一天,30Y又回到5.26%,所以美国真的开始YCC了吗#美股 #AI #半导体
𝗔𝗜需求没有崩,市场正在从“买AI”变成“买确定性”
昨晚美股继续调整。
道指 -1.32%,标普500 -0.87%,纳指 -1.00%。
但半导体内部完全不是一个走势:
$MRVL +5.8%
$MU +3.97%
$AVGO +0.43%
$NVDA 小幅下跌
现在的市场其实很有意思
指数在交易美债和油价,资金却开始在AI里面寻找真正有订单、有现金流的公司。
① 最重要利好
$MU 真正的利好不是涨4%,而是海力士和三星开始把AI赚到的钱还给股东。
SK海力士宣布回购并注销40万亿韩元股票,约287亿美元,同时把股东回报政策提高到自由现金流的50%以上。
过去市场一直担心:
HBM赚很多钱 → 存储厂商疯狂扩产 → 最后重新变成DRAM价格战。
但现在海力士开始把大量现金直接返还股东。
这至少说明一个问题:
𝗔𝗜存储带来的现金流,已经强到可以支撑大规模股东回报。
三星也准备提高股东回报。
所以我现在对MU的判断反而比前几天更积极。
真正值得观察的已经不是HBM价格还能涨多少,而是:
𝗔𝗜存储超级周期能不能真正转化成持续的自由现金流。
② $AVGO 有一个容易被忽略的新变化
昨天Google选择MRVL以后,很多人第一反应是:
Google是不是开始抛弃Broadcom?
Bloomberg报道,Broadcom正在和银行讨论超过600亿美元的AI融资,整体规模甚至可能做到1000亿美元,其中Anthropic是重要受益方。
Anthropic计划到2028年获得超过20GW的AI算力。
这说明现在AI行业真正缺的已经不只是GPU。
而是:
GPU
电力
数据中心
网络
ASIC
以及几十亿美元甚至上百亿美元的融资。
所以Google找MRVL,并不一定意味着AVGO失去市场。
更可能意味着:
𝗖𝘂𝘀𝘁𝗼𝗺 𝗔𝗦𝗜𝗖市场正在变得足够大,可以同时容纳多个供应商。
这对MRVL和AVGO的长期逻辑都不算坏。
③ 最大利空还是美债
财政部前一天刚刚扩大长期国债回购。
30年美债收益率一度从5.34%附近快速跌到5.18%。
结果一天以后又回到了5.26%左右。
这说明一个问题:
财政部能够改善债券市场流动性,但还没有解决美国长期债务供需的问题。
现在真正压着AI估值的还是:
财政赤字
国债供应
AI巨额融资
油价
Fed
所以我还是不认为美国已经开始YCC。
如果真的是收益率控制,30Y不会这么快又回到5.26%。
④ 油价又是一个麻烦
Brent已经重新接近94美元。
现在市场出现了一个比较麻烦的组合:
美国经济没有明显衰退
就业依然比较强
油价却越来越高
这对Fed并不友好。
如果Brent突破95美元,同时30Y重新突破5.30%,那么AI股票的估值压力还会继续。
所以今天最看两个数字:
𝗕𝗿𝗲𝗻𝘁:95美元
𝗨𝗦 30𝗬:5.30%
这两个位置,比单纯看纳指涨跌更重要。
⑤ 今天最值得关注
$MRVL
连续第二天逆势上涨。
如果今天大盘继续弱,而MRVL还能保持强势,那么Google这件事情越来越像机构重新给MRVL未来收入路径定价,而不是一次消息炒作。
$MU
如果MU继续跑赢SOX,同时海力士和三星继续提高股东回报,我会认为资金正在重新交易HBM和AI存储超级周期。
$NVDA
下一次真正的大考还是8月26日财报。
现在市场已经不只是看Blackwell卖多少,而是开始关注:
AI客户的巨额Capex到底能不能转化成真正的收入和现金流。
判断:
𝗔𝗜需求没有明显恶化。
真正发生变化的是,市场已经从“AI全面上涨”进入“只给真实订单和现金流定价”的阶段。
MRVL和MU是现在最明显的两个例子。
而下一阶段真正决定AI估值的,还是30年美债和油价。
#MRVL #MU #NVDA #AVGO #AI #美股
财政部刚刚“救”完美债一天,30Y又回到5.26%,所以美国真的开始YCC了吗
#美股 #AI #半导体
𝗔𝗜需求没有崩,市场正在从“买AI”变成“买确定性”
昨晚美股继续调整。
道指 -1.32%,标普500 -0.87%,纳指 -1.00%。
但半导体内部完全不是一个走势:
$MRVL +5.8%
$MU +3.97%
$AVGO +0.43%
$NVDA 小幅下跌
现在的市场其实很有意思
指数在交易美债和油价,资金却开始在AI里面寻找真正有订单、有现金流的公司。
① 最重要利好
$MU 真正的利好不是涨4%,而是海力士和三星开始把AI赚到的钱还给股东。
SK海力士宣布回购并注销40万亿韩元股票,约287亿美元,同时把股东回报政策提高到自由现金流的50%以上。
过去市场一直担心:
HBM赚很多钱 → 存储厂商疯狂扩产 → 最后重新变成DRAM价格战。
但现在海力士开始把大量现金直接返还股东。
这至少说明一个问题:
𝗔𝗜存储带来的现金流,已经强到可以支撑大规模股东回报。
三星也准备提高股东回报。
所以我现在对MU的判断反而比前几天更积极。
真正值得观察的已经不是HBM价格还能涨多少,而是:
𝗔𝗜存储超级周期能不能真正转化成持续的自由现金流。
② $AVGO 有一个容易被忽略的新变化
昨天Google选择MRVL以后,很多人第一反应是:
Google是不是开始抛弃Broadcom?
Bloomberg报道,Broadcom正在和银行讨论超过600亿美元的AI融资,整体规模甚至可能做到1000亿美元,其中Anthropic是重要受益方。
Anthropic计划到2028年获得超过20GW的AI算力。
这说明现在AI行业真正缺的已经不只是GPU。
而是:
GPU
电力
数据中心
网络
ASIC
以及几十亿美元甚至上百亿美元的融资。
所以Google找MRVL,并不一定意味着AVGO失去市场。
更可能意味着:
𝗖𝘂𝘀𝘁𝗼𝗺 𝗔𝗦𝗜𝗖市场正在变得足够大,可以同时容纳多个供应商。
这对MRVL和AVGO的长期逻辑都不算坏。
③ 最大利空还是美债
财政部前一天刚刚扩大长期国债回购。
30年美债收益率一度从5.34%附近快速跌到5.18%。
结果一天以后又回到了5.26%左右。
这说明一个问题:
财政部能够改善债券市场流动性,但还没有解决美国长期债务供需的问题。
现在真正压着AI估值的还是:
财政赤字
国债供应
AI巨额融资
油价
Fed
所以我还是不认为美国已经开始YCC。
如果真的是收益率控制,30Y不会这么快又回到5.26%。
④ 油价又是一个麻烦
Brent已经重新接近94美元。
现在市场出现了一个比较麻烦的组合:
美国经济没有明显衰退
就业依然比较强
油价却越来越高
这对Fed并不友好。
如果Brent突破95美元,同时30Y重新突破5.30%,那么AI股票的估值压力还会继续。
所以今天最看两个数字:
𝗕𝗿𝗲𝗻𝘁:95美元
𝗨𝗦 30𝗬:5.30%
这两个位置,比单纯看纳指涨跌更重要。
⑤ 今天最值得关注
$MRVL
连续第二天逆势上涨。
如果今天大盘继续弱,而MRVL还能保持强势,那么Google这件事情越来越像机构重新给MRVL未来收入路径定价,而不是一次消息炒作。
$MU
如果MU继续跑赢SOX,同时海力士和三星继续提高股东回报,我会认为资金正在重新交易HBM和AI存储超级周期。
$NVDA
下一次真正的大考还是8月26日财报。
现在市场已经不只是看Blackwell卖多少,而是开始关注:
AI客户的巨额Capex到底能不能转化成真正的收入和现金流。
判断:
𝗔𝗜需求没有明显恶化。
真正发生变化的是,市场已经从“AI全面上涨”进入“只给真实订单和现金流定价”的阶段。
MRVL和MU是现在最明显的两个例子。
而下一阶段真正决定AI估值的,还是30年美债和油价。
#MRVL #MU #NVDA #AVGO #AI #美股
𝗔𝗜需求没有崩,市场正在从“买AI”变成“买确定性”
昨晚美股继续调整。
道指 -1.32%,标普500 -0.87%,纳指 -1.00%。
但半导体内部完全不是一个走势:
$MRVL +5.8%
$MU +3.97%
$AVGO +0.43%
$NVDA 小幅下跌
现在的市场其实很有意思
指数在交易美债和油价,资金却开始在AI里面寻找真正有订单、有现金流的公司。
① 最重要利好
$MU 真正的利好不是涨4%,而是海力士和三星开始把AI赚到的钱还给股东。
SK海力士宣布回购并注销40万亿韩元股票,约287亿美元,同时把股东回报政策提高到自由现金流的50%以上。
过去市场一直担心:
HBM赚很多钱 → 存储厂商疯狂扩产 → 最后重新变成DRAM价格战。
但现在海力士开始把大量现金直接返还股东。
这至少说明一个问题:
𝗔𝗜存储带来的现金流,已经强到可以支撑大规模股东回报。
三星也准备提高股东回报。
所以我现在对MU的判断反而比前几天更积极。
真正值得观察的已经不是HBM价格还能涨多少,而是:
𝗔𝗜存储超级周期能不能真正转化成持续的自由现金流。
② $AVGO 有一个容易被忽略的新变化
昨天Google选择MRVL以后,很多人第一反应是:
Google是不是开始抛弃Broadcom?
Bloomberg报道,Broadcom正在和银行讨论超过600亿美元的AI融资,整体规模甚至可能做到1000亿美元,其中Anthropic是重要受益方。
Anthropic计划到2028年获得超过20GW的AI算力。
这说明现在AI行业真正缺的已经不只是GPU。
而是:
GPU
电力
数据中心
网络
ASIC
以及几十亿美元甚至上百亿美元的融资。
所以Google找MRVL,并不一定意味着AVGO失去市场。
更可能意味着:
𝗖𝘂𝘀𝘁𝗼𝗺 𝗔𝗦𝗜𝗖市场正在变得足够大,可以同时容纳多个供应商。
这对MRVL和AVGO的长期逻辑都不算坏。
③ 最大利空还是美债
财政部前一天刚刚扩大长期国债回购。
30年美债收益率一度从5.34%附近快速跌到5.18%。
结果一天以后又回到了5.26%左右。
这说明一个问题:
财政部能够改善债券市场流动性,但还没有解决美国长期债务供需的问题。
现在真正压着AI估值的还是:
财政赤字
国债供应
AI巨额融资
油价
Fed
所以我还是不认为美国已经开始YCC。
如果真的是收益率控制,30Y不会这么快又回到5.26%。
④ 油价又是一个麻烦
Brent已经重新接近94美元。
现在市场出现了一个比较麻烦的组合:
美国经济没有明显衰退
就业依然比较强
油价却越来越高
这对Fed并不友好。
如果Brent突破95美元,同时30Y重新突破5.30%,那么AI股票的估值压力还会继续。
所以今天最看两个数字:
𝗕𝗿𝗲𝗻𝘁:95美元
𝗨𝗦 30𝗬:5.30%
这两个位置,比单纯看纳指涨跌更重要。
⑤ 今天最值得关注
$MRVL
连续第二天逆势上涨。
如果今天大盘继续弱,而MRVL还能保持强势,那么Google这件事情越来越像机构重新给MRVL未来收入路径定价,而不是一次消息炒作。
$MU
如果MU继续跑赢SOX,同时海力士和三星继续提高股东回报,我会认为资金正在重新交易HBM和AI存储超级周期。
$NVDA
下一次真正的大考还是8月26日财报。
现在市场已经不只是看Blackwell卖多少,而是开始关注:
AI客户的巨额Capex到底能不能转化成真正的收入和现金流。
判断:
𝗔𝗜需求没有明显恶化。
真正发生变化的是,市场已经从“AI全面上涨”进入“只给真实订单和现金流定价”的阶段。
MRVL和MU是现在最明显的两个例子。
而下一阶段真正决定AI估值的,还是30年美债和油价。
#MRVL #MU #NVDA #AVGO #AI #美股
1
723
·
--
Мақала
Google 谷歌不是投资 $MRVL 121亿美元这么简单,真正值钱的是背后的1200亿美元收入路径昨夜美股三大指数小幅收涨,但半导体内部明显分化:MRVL +9.9%,AVGO -4.6%,AMD -3.6%,NVDA -1.0%,MU -0.4%。与此同时,美国财政部突然加大长债回购,压低长端收益率;但 Fed 会议纪要又明显偏鹰,Brent 仍在 91美元以上。所以这是一个“宏观暂时托底、AI内部继续分化”的市场。
① 最重要利好
1. Google × Marvell:这不是普通合作,是 MRVL 估值逻辑升级
这是昨夜整个 AI 半导体最重要的新闻。
Google 与 Marvell(MRVL) 达成新的定制 AI 芯片合作,合作范围覆盖 TPU 生态中的 AI推理加速器、存储控制器、网络接口、内存接口以及 near-memory compute。更关键的是,Google 获得购买最多 5,897万股 MRVL 的权利,执行价 206.58美元,如果全部行权,价值约 121.8亿美元,并可能成为 Marvell 第五大股东。Reuters 报道,如果 Google 达到相关采购目标,这项合作到 FY2033 可能给 Marvell 带来大约 1,200亿美元收入。
这相当于正式确认:
Marvell 已经从“可能拿到 Google TPU 项目”升级为“Google核心 AI 自研芯片供应链之一”。
市场昨天直接用股价投票:MRVL 收涨约9.9%至237.27美元,成交量约4,401万股。
影响:
MRVL:强利好
GOOGL:中长期偏利好
AVGO:短期利空
NVDA:中长期轻微竞争压力,但不是直接替代
2. 美国财政部突然扩大长债回购,暂时压住 AI 股最大的估值压力
美国财政部宣布,把 10–30年期国债的流动性回购规模从每次20亿美元至少提高至40亿美元,9月9日至11月4日实施。消息出来后,30年美债收益率从此前接近 5.34% 的19年高位明显回落,一度跌到约 5.18%;10年期收益率降至约 4.66%。
这是昨天美股能够止跌回升的重要原因。S&P 500 最终 +0.21%,Nasdaq +0.16%,Dow +0.22%。
AI/半导体目前最大的外部估值压力就是:
长端收益率持续上升。
因此只要:
30Y ↓ → 10Y ↓ → 折现率下降
高估值 AI 股票就获得喘息空间。
3. Analog Devices 财报再次验证:AI 数据中心需求正外溢到“非GPU芯片”
ADI 昨天公布的季度业绩明显超过预期:
Q3收入:40.2亿美元
市场预期约:39.2亿美元
调整后EPS:3.45美元
市场预期:3.34美元
更重要的是,公司给出的下一季度收入指引约 43亿美元,高于市场约40.8亿美元的预期。增长主要来自 AI数据中心和工业需求。
AI Capex 已经从 GPU → 网络 → 存储 → 电力管理 → 模拟芯片继续扩散。
② 利空
1. Fed会议纪要明显偏鹰,而且第一次直接把“AI估值与融资”列为金融稳定风险
这是今天最容易被忽略、但非常重要的一条。
Fed 7月会议纪要显示:
多名官员认为如果通胀不下降,未来需要进一步加息;
几名官员在7月会议上就已经倾向加息25bp;
最终有 3名委员投票支持加息;
Fed认为当前金融条件可能仍“不够紧”。
更值得 AI 投资者注意的是,Fed 工作人员明确指出:
当前股票估值压力仍然很高,而考虑到长期利率以后,股票风险溢价已经接近只有“互联网泡沫时期”才更低的水平。
会议还特别讨论了:
AI基础设施开始越来越依赖债务融资
非银机构和地区银行参与AI融资
如果 AI 长期盈利预期被大幅下修,可能导致股票大范围重估,并进一步收紧金融条件。
这其实是非常重要的信号:
Fed已经开始把AI资本开支和AI资产估值当作宏观金融稳定问题来看。
2. 油价又回到91美元以上,美伊问题仍然没解决
Brent 昨日收在约 91.42美元/桶,WTI约 85.59美元。霍尔木兹海峡船舶通行仍然缓慢,同时阿联酋暂停了与伊朗的金融和经济交易。
这意味着:
财政部刚刚把收益率压下来,但油价还在给通胀添火。
所以现在市场存在一个很明显的拉扯:
财政部长债回购 → 利好科技估值
油价 > $90 → 通胀预期 ↑ → Fed鹰派 → 利空科技估值
今天必须盯的事件
1. 美国初请失业金
市场预期约 21万人,前值20.9万人。
如果明显高于预期:
经济变弱 → Fed加息预期下降 → 短线利好科技股
但如果失业突然恶化过快,则会变成增长担忧。
2. Philadelphia Fed制造业指数
同样 今晚20:30。
前值约 41.4,市场预期明显回落。
这个数据会影响:
美债收益率 + 工业周期 + 半导体周期预期。
3. Walmart财报
Walmart将在 8月20日美东早间公布Q2业绩,公司官方确认当天举行财报电话会。
虽然不是AI核心股,但它是今天判断:
美国消费者有没有因为油价和通胀开始明显变弱
最重要的数据之一。
对 AMZN、消费股以及 Fed 预期都有影响。
4. 30年美债收益率
今天看:
5.15% / 5.30%
如果今晚继续维持在5.2%附近甚至下破:
AI股估值压力继续缓和。
如果重新突破5.3%:
昨天财政部的利好基本被市场“打回去”。
另外,距离川普中期选举越来越近了,如果川普想赢得选举,那么美股市场的股民是他重要的一块支持率。
AI需求没有问题,真正发生变化的是市场开始只奖励“有真实订单、有收入能见度”的公司。#MRVL 昨天就是最典型案例,而高利率与AI债务融资已经成为下一阶段最大的估值约束。
Google 谷歌不是投资 $MRVL 121亿美元这么简单,真正值钱的是背后的1200亿美元收入路径
昨夜美股三大指数小幅收涨,但半导体内部明显分化:MRVL +9.9%,AVGO -4.6%,AMD -3.6%,NVDA -1.0%,MU -0.4%。与此同时,美国财政部突然加大长债回购,压低长端收益率;但 Fed 会议纪要又明显偏鹰,Brent 仍在 91美元以上。所以这是一个“宏观暂时托底、AI内部继续分化”的市场。
① 最重要利好
1. Google × Marvell:这不是普通合作,是 MRVL 估值逻辑升级
这是昨夜整个 AI 半导体最重要的新闻。
Google 与 Marvell(MRVL) 达成新的定制 AI 芯片合作,合作范围覆盖 TPU 生态中的 AI推理加速器、存储控制器、网络接口、内存接口以及 near-memory compute。更关键的是,Google 获得购买最多 5,897万股 MRVL 的权利,执行价 206.58美元,如果全部行权,价值约 121.8亿美元,并可能成为 Marvell 第五大股东。Reuters 报道,如果 Google 达到相关采购目标,这项合作到 FY2033 可能给 Marvell 带来大约 1,200亿美元收入。
这相当于正式确认:
Marvell 已经从“可能拿到 Google TPU 项目”升级为“Google核心 AI 自研芯片供应链之一”。
市场昨天直接用股价投票:MRVL 收涨约9.9%至237.27美元,成交量约4,401万股。
影响:
MRVL:强利好
GOOGL:中长期偏利好
AVGO:短期利空
NVDA:中长期轻微竞争压力,但不是直接替代
2. 美国财政部突然扩大长债回购,暂时压住 AI 股最大的估值压力
美国财政部宣布,把 10–30年期国债的流动性回购规模从每次20亿美元至少提高至40亿美元,9月9日至11月4日实施。消息出来后,30年美债收益率从此前接近 5.34% 的19年高位明显回落,一度跌到约 5.18%;10年期收益率降至约 4.66%。
这是昨天美股能够止跌回升的重要原因。S&P 500 最终 +0.21%,Nasdaq +0.16%,Dow +0.22%。
AI/半导体目前最大的外部估值压力就是:
长端收益率持续上升。
因此只要:
30Y ↓ → 10Y ↓ → 折现率下降
高估值 AI 股票就获得喘息空间。
3. Analog Devices 财报再次验证:AI 数据中心需求正外溢到“非GPU芯片”
ADI 昨天公布的季度业绩明显超过预期:
Q3收入:40.2亿美元
市场预期约:39.2亿美元
调整后EPS:3.45美元
市场预期:3.34美元
更重要的是,公司给出的下一季度收入指引约 43亿美元,高于市场约40.8亿美元的预期。增长主要来自 AI数据中心和工业需求。
AI Capex 已经从 GPU → 网络 → 存储 → 电力管理 → 模拟芯片继续扩散。
② 利空
1. Fed会议纪要明显偏鹰,而且第一次直接把“AI估值与融资”列为金融稳定风险
这是今天最容易被忽略、但非常重要的一条。
Fed 7月会议纪要显示:
多名官员认为如果通胀不下降,未来需要进一步加息;
几名官员在7月会议上就已经倾向加息25bp;
最终有 3名委员投票支持加息;
Fed认为当前金融条件可能仍“不够紧”。
更值得 AI 投资者注意的是,Fed 工作人员明确指出:
当前股票估值压力仍然很高,而考虑到长期利率以后,股票风险溢价已经接近只有“互联网泡沫时期”才更低的水平。
会议还特别讨论了:
AI基础设施开始越来越依赖债务融资
非银机构和地区银行参与AI融资
如果 AI 长期盈利预期被大幅下修,可能导致股票大范围重估,并进一步收紧金融条件。
这其实是非常重要的信号:
Fed已经开始把AI资本开支和AI资产估值当作宏观金融稳定问题来看。
2. 油价又回到91美元以上,美伊问题仍然没解决
Brent 昨日收在约 91.42美元/桶,WTI约 85.59美元。霍尔木兹海峡船舶通行仍然缓慢,同时阿联酋暂停了与伊朗的金融和经济交易。
这意味着:
财政部刚刚把收益率压下来,但油价还在给通胀添火。
所以现在市场存在一个很明显的拉扯:
财政部长债回购 → 利好科技估值
油价 > $90 → 通胀预期 ↑ → Fed鹰派 → 利空科技估值
今天必须盯的事件
1. 美国初请失业金
市场预期约 21万人,前值20.9万人。
如果明显高于预期:
经济变弱 → Fed加息预期下降 → 短线利好科技股
但如果失业突然恶化过快,则会变成增长担忧。
2. Philadelphia Fed制造业指数
同样 今晚20:30。
前值约 41.4,市场预期明显回落。
这个数据会影响:
美债收益率 + 工业周期 + 半导体周期预期。
3. Walmart财报
Walmart将在 8月20日美东早间公布Q2业绩,公司官方确认当天举行财报电话会。
虽然不是AI核心股,但它是今天判断:
美国消费者有没有因为油价和通胀开始明显变弱
最重要的数据之一。
对 AMZN、消费股以及 Fed 预期都有影响。
4. 30年美债收益率
今天看:
5.15% / 5.30%
如果今晚继续维持在5.2%附近甚至下破:
AI股估值压力继续缓和。
如果重新突破5.3%:
昨天财政部的利好基本被市场“打回去”。
另外,距离川普中期选举越来越近了,如果川普想赢得选举,那么美股市场的股民是他重要的一块支持率。
AI需求没有问题,真正发生变化的是市场开始只奖励“有真实订单、有收入能见度”的公司。#MRVL 昨天就是最典型案例,而高利率与AI债务融资已经成为下一阶段最大的估值约束。
① 最重要利好
1. Google × Marvell:这不是普通合作,是 MRVL 估值逻辑升级
这是昨夜整个 AI 半导体最重要的新闻。
Google 与 Marvell(MRVL) 达成新的定制 AI 芯片合作,合作范围覆盖 TPU 生态中的 AI推理加速器、存储控制器、网络接口、内存接口以及 near-memory compute。更关键的是,Google 获得购买最多 5,897万股 MRVL 的权利,执行价 206.58美元,如果全部行权,价值约 121.8亿美元,并可能成为 Marvell 第五大股东。Reuters 报道,如果 Google 达到相关采购目标,这项合作到 FY2033 可能给 Marvell 带来大约 1,200亿美元收入。
这相当于正式确认:
Marvell 已经从“可能拿到 Google TPU 项目”升级为“Google核心 AI 自研芯片供应链之一”。
市场昨天直接用股价投票:MRVL 收涨约9.9%至237.27美元,成交量约4,401万股。
影响:
MRVL:强利好
GOOGL:中长期偏利好
AVGO:短期利空
NVDA:中长期轻微竞争压力,但不是直接替代
2. 美国财政部突然扩大长债回购,暂时压住 AI 股最大的估值压力
美国财政部宣布,把 10–30年期国债的流动性回购规模从每次20亿美元至少提高至40亿美元,9月9日至11月4日实施。消息出来后,30年美债收益率从此前接近 5.34% 的19年高位明显回落,一度跌到约 5.18%;10年期收益率降至约 4.66%。
这是昨天美股能够止跌回升的重要原因。S&P 500 最终 +0.21%,Nasdaq +0.16%,Dow +0.22%。
AI/半导体目前最大的外部估值压力就是:
长端收益率持续上升。
因此只要:
30Y ↓ → 10Y ↓ → 折现率下降
高估值 AI 股票就获得喘息空间。
3. Analog Devices 财报再次验证:AI 数据中心需求正外溢到“非GPU芯片”
ADI 昨天公布的季度业绩明显超过预期:
Q3收入:40.2亿美元
市场预期约:39.2亿美元
调整后EPS:3.45美元
市场预期:3.34美元
更重要的是,公司给出的下一季度收入指引约 43亿美元,高于市场约40.8亿美元的预期。增长主要来自 AI数据中心和工业需求。
AI Capex 已经从 GPU → 网络 → 存储 → 电力管理 → 模拟芯片继续扩散。
② 利空
1. Fed会议纪要明显偏鹰,而且第一次直接把“AI估值与融资”列为金融稳定风险
这是今天最容易被忽略、但非常重要的一条。
Fed 7月会议纪要显示:
多名官员认为如果通胀不下降,未来需要进一步加息;
几名官员在7月会议上就已经倾向加息25bp;
最终有 3名委员投票支持加息;
Fed认为当前金融条件可能仍“不够紧”。
更值得 AI 投资者注意的是,Fed 工作人员明确指出:
当前股票估值压力仍然很高,而考虑到长期利率以后,股票风险溢价已经接近只有“互联网泡沫时期”才更低的水平。
会议还特别讨论了:
AI基础设施开始越来越依赖债务融资
非银机构和地区银行参与AI融资
如果 AI 长期盈利预期被大幅下修,可能导致股票大范围重估,并进一步收紧金融条件。
这其实是非常重要的信号:
Fed已经开始把AI资本开支和AI资产估值当作宏观金融稳定问题来看。
2. 油价又回到91美元以上,美伊问题仍然没解决
Brent 昨日收在约 91.42美元/桶,WTI约 85.59美元。霍尔木兹海峡船舶通行仍然缓慢,同时阿联酋暂停了与伊朗的金融和经济交易。
这意味着:
财政部刚刚把收益率压下来,但油价还在给通胀添火。
所以现在市场存在一个很明显的拉扯:
财政部长债回购 → 利好科技估值
油价 > $90 → 通胀预期 ↑ → Fed鹰派 → 利空科技估值
今天必须盯的事件
1. 美国初请失业金
市场预期约 21万人,前值20.9万人。
如果明显高于预期:
经济变弱 → Fed加息预期下降 → 短线利好科技股
但如果失业突然恶化过快,则会变成增长担忧。
2. Philadelphia Fed制造业指数
同样 今晚20:30。
前值约 41.4,市场预期明显回落。
这个数据会影响:
美债收益率 + 工业周期 + 半导体周期预期。
3. Walmart财报
Walmart将在 8月20日美东早间公布Q2业绩,公司官方确认当天举行财报电话会。
虽然不是AI核心股,但它是今天判断:
美国消费者有没有因为油价和通胀开始明显变弱
最重要的数据之一。
对 AMZN、消费股以及 Fed 预期都有影响。
4. 30年美债收益率
今天看:
5.15% / 5.30%
如果今晚继续维持在5.2%附近甚至下破:
AI股估值压力继续缓和。
如果重新突破5.3%:
昨天财政部的利好基本被市场“打回去”。
另外,距离川普中期选举越来越近了,如果川普想赢得选举,那么美股市场的股民是他重要的一块支持率。
AI需求没有问题,真正发生变化的是市场开始只奖励“有真实订单、有收入能见度”的公司。#MRVL 昨天就是最典型案例,而高利率与AI债务融资已经成为下一阶段最大的估值约束。
1
614
·
--
Расталды
中国放宽英伟达H200芯片限制,字节跳动与唇讯各获1万枚
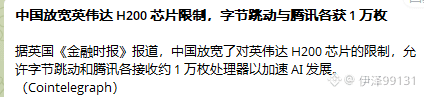
据英国《金融时报》报道,中国放宽了 对$NVDAB 英伟达H200芯片的限制,允许字节跳动和腾讯各接收约1万枚处理器以加速AI发展。
$SKHY
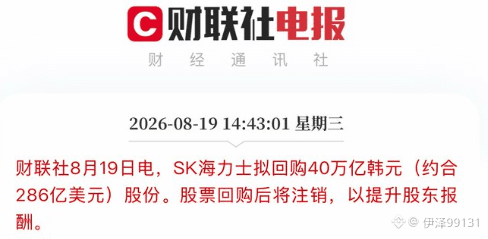
将回购价值40万亿韩元的股票,回购股
份用于注销并回报股东。(价值286亿美元)
AI泡沫远远还没到,只不过最近的债券市场低迷,且看8.28号美联储如何给政策方案了
中国放宽英伟达H200芯片限制,字节跳动与唇讯各获1万枚
据英国《金融时报》报道,中国放宽了 对$NVDAB 英伟达H200芯片的限制,允许字节跳动和腾讯各接收约1万枚处理器以加速AI发展。
$SKHY
将回购价值40万亿韩元的股票,回购股
份用于注销并回报股东。(价值286亿美元)
AI泡沫远远还没到,只不过最近的债券市场低迷,且看8.28号美联储如何给政策方案了
据英国《金融时报》报道,中国放宽了 对$NVDAB 英伟达H200芯片的限制,允许字节跳动和腾讯各接收约1万枚处理器以加速AI发展。
$SKHY
将回购价值40万亿韩元的股票,回购股
份用于注销并回报股东。(价值286亿美元)
AI泡沫远远还没到,只不过最近的债券市场低迷,且看8.28号美联储如何给政策方案了
3
3
9.7k
·
--
Расталды
Мақала
Nokia 7 月 23 日想继续涨,必须证明三件事: AI/cloud 订单没有降温,Optical/IP 增长能继续上修,利润率没有被重资产和整合成本吃掉,利好风险点财报前分析美股 $NOK Nokia 已确认将在 2026 年 7 月 23 日发布 Q2 和上半年业绩Corporation | Nokia
财报前,Nokia 当前的核心
现在 Nokia 已经不是单纯的“传统通信设备股”了,市场正在按三条 AI 基建线重新看它:
第一条:Optical Networks / AI DCI。 AI 数据中心扩张带来跨数据中心互联需求,Nokia 通过 Infinera 补强相干光学和光传输系统。
Q1 里 Optical Networks 增长 20%,Network Infrastructure 增长 6%,公司还把 2026 年 Network Infrastructure 增长目标上调到 12%–14%,并假设 IP + Optical Networks 合计增长 18%–20%
第二条:美国本土 AI 光网络供应链。
6 月 16 日,Nokia 宣布扩建 Allentown 光子芯片 advanced test and packaging 产能,产能最高提升到当前水平的 10 倍,新产能预计在 Q3 末商用;这个项目也是 Nokia 在美国 AI-ready network connectivity 上 40 亿美元多年投资计划的一部分
第三条:AI 网络软件化。
6 月下旬,Nokia 和 Google Cloud 宣布把 Gemini 模型做成 AI agents,集成进 Nokia Assurance Center,用来帮助运营商做故障定位、告警筛选、自动化修复和自主管理网络。Nokia 同期还升级了 autonomous networks 产品组合,强调 agentic AI、IP/fixed/optical 网络自动化和 RAN 自动化。
这三条合起来,Nokia 的故事就从“卖设备”变成了: AI 数据中心需要光网络。 AI 光网络需要本土供应链。 复杂网络需要 AI 自动化软件。
7 月 23 日财报可能带来上涨的利好点 利好一: AI/cloud 订单继续强,最好再次接近或超过 Q1 的 10 亿欧元
Q1 最大亮点不是总营收,而是 AI/cloud 客户销售 +49%,订单约 10 亿欧元。这直接让市场相信 Nokia 真在吃到 AI 数据中心光网络需求。
Q2 如果继续披露: AI/cloud 订单仍然强 book-to-bill 继续明显高于 1 hyperscaler / cloud 客户订单扩大 pluggables 和 line systems 继续拿 design wins 那就是强利好
尤其要看管理层有没有说类似:
“AI/cloud demand accelerated in Q2” “Order intake remained strong” “Book-to-bill remained well above one” 如果 Q2 订单明显弱于 Q1,市场可能会担心 Q1 是一次性订单高峰。
利好二: Optical Networks 继续 20% 左右增长,或者全年目标再上修
Q1 Optical Networks 增长 20%,这已经是 Nokia 最关键的 AI 线。公司目前对 IP + Optical Networks 2026 年增长假设是 18%–20%。
Q2 如果 Optical 继续高增长,市场会认为:
AI DCI 需求不是短期情绪,而是正在转成收入。
更强的情况是公司把 18%–20% 继续上修,或者暗示下半年订单能见度更高。那会是推动股价继续上涨的重要催化。
但如果 Optical 增速放缓,或者订单强但收入确认慢,股价可能短线承压。
利好三:Q2 营收和利润站在指引高端 Nokia 在 Q1 报告里给出的 Q2 季节性假设是:Q2 净销售额环比增长 5%–9%,Q2 comparable operating profit 占全年 comparable operating profit 的 12%–16%。公司全年 comparable operating profit 目标区间是 20 亿–25 亿欧元
换算一下,市场会大致这样看:
指标偏利好表现Q2 净销售靠近或超过环比 +9%Q2 comparable operating profit靠近全年利润的 16%全年利润指引维持高端,甚至上调Network Infrastructure继续跑赢集团整体Optical/IP继续强于传统通信业务
如果营收只是中位数,但利润率超预期,也可能利好。因为市场现在更关心 Nokia 能不能把 AI 光网络订单转成高质量利润,而不是只做规模
利好四: Aureon 100–400Tb/s AI 光网络项目被管理层作为“可复制模板”强调
6 月 18 日,Nokia、t3 Broadband 和 Aureon 宣布部署 AI-ready optical network,初始可提供 100Tb/s,未来可扩展至 400Tb/s,连接北达科他数据中心和芝加哥,用的是 Nokia 1830 GX、Super C/L-band 和 1.2T ICE7 相干光学。
这个项目对财报的意义不是金额本身,而是它证明 Nokia 的 AI DCI 方案已经在真实场景里落地。
如果电话会上管理层说:
类似 Aureon 的项目 pipeline 正在增加 区域运营商和 hyperscale AI 数据中心开始复制这种架构 1.2T ICE7 和 1830 GX 需求强
那对 Optical Networks 的中期重估很有帮助。
利好五:Allentown 扩产被市场理解为美国 AI 光网络供应链卡位
Allentown 扩产是中长期利好。Nokia 表示该厂是美国少数能将 photonic chips 做 ATP 并封装成 optical modules 的设施之一,扩产后产能最高提升至 10 倍,预计 Q3 末可用。(Nokia Corporation | Nokia)
如果 Q2 电话会里管理层进一步确认:
美国 hyperscaler 对本土化光网络供应链需求强 Allentown 扩产对应真实客户需求 扩产不会显著压低利润率 Infinera + Allentown 能带来供应链优势
那会强化 Nokia 与 Ciena、Lumentum、Coherent、Marvell 等 AI 光互联链条的相关性。
利好六:AI 网络软件和 Google Gemini 合作被市场当成“软件估值”加分项
Google Cloud + Nokia Assurance Center 的重点是:Nokia 正在把 AI agent 放进运营商网络运维里,用来做故障诊断、KPI 分析、异常推理和自动化修复。
这不会立刻带来爆炸收入,但它会让市场看到 Nokia 的另一条增长线:
不是只卖硬件,而是卖 AI 网络软件、自动化和运营商降本增效工具。
如果管理层披露 SaaS 化、Google Cloud Marketplace、运营商试点数量、软件订单或 autonomous network pipeline,这会让估值逻辑更舒服。
财报里最需要警惕的风险点
风险一:AI 订单强,但收入确认慢 Nokia 现在最怕的不是“没有故事”,而是“故事很多,但 Q2 数字没跟上”
如果 Q2 AI/cloud 订单还不错,但 Optical/IP 收入没有明显加速,市场可能会说: 订单还在 backlog 里,短期兑现不够
这对已经提前上涨的股票很容易造成 sell the news。
风险二:利润率不够好
Nokia Q2 指引里,利润占全年比例只有 12%–16%,这意味着 Q2 本来就不一定是全年最强利润季度。
如果出现: 营收增长但毛利率承压 Infinera 整合成本高 光模块/相干光学供应链成本上涨 AI 光网络订单利润率低于预期 那市场可能会担心 Nokia 是“收入增长但利润质量一般”
这点非常关键。因为 AI 光网络如果只能带来低毛利增长,估值不会持续重估。
风险三:Fixed Networks 和 Mobile Infrastructure 拖后腿
Q1 Fixed Networks 净销售下降 13%,Mobile Infrastructure 虽然有所改善,但传统运营商 capex 周期并没有全面复苏。
如果 Q2 里传统通信业务继续疲软,而 AI/Optical 又不足以完全抵消,市场会重新把 Nokia 拉回“老电信设备股”的估值框架。
这就是 Nokia 和 $MRVL、 $LITE、 $COHR 最大区别:
Nokia 有 AI 光网络弹性,但仍然有传统通信业务包袱。
风险四:Infinera 整合低于预期
市场看好 Nokia 的一个原因,是收购 Infinera 后补强了 optical transport 和相干光学能力。Reuters 也提到,Nokia 在收购 Infinera 后已成为重要的 optical transport 系统供应商
但整合是双刃剑。 财报里要看:
协同效应是否按计划兑现 产品整合是否顺利 客户是否接受新组合方案 成本和库存是否拖累利润率
如果 Infinera 带来的只是收入,利润还没跟上,市场会打折。
风险五:股价已提前定价一部分 AI 乐观预期
Nokia ADR 当前约 12.07 美元,市值约 666.6 亿美元。 MarketScreener 的欧洲报价页面显示,Nokia 年初以来涨幅已经非常大,且近期分析师意见分化:
7 月初有 BofA 因预期强 Q2 AI 订单上调目标,也有 UBS 中性、Barclays 卖出等不同观点。
这说明市场已经不再把 Nokia 当便宜冷门股看。
所以 Q2 财报的门槛提高了:
符合指引可能不够。 需要订单、利润和指引至少有一个明显超预期。
风险六:AI CapEx 情绪变化
Nokia 现在被市场归入 AI 基建链条,所以也会受 AI CapEx 情绪影响。
如果 7 月前后市场开始质疑 hyperscaler AI 支出、Neocloud 折旧压力、GPU 投资回报,Nokia 即使基本面没坏,也可能跟随 AI 基建板块回调。
这类风险不是公司特有风险,而是板块估值风险。
三种财报情景推演
Bullish 情景:股价继续上行
如果 Q2 出现以下组合,NOK 很可能继续上涨:
AI/cloud 订单继续强 Optical Networks 继续 20%+ 增长 IP Networks 明显加速 全年 Network Infrastructure / Optical+IP 指引再上修 利润率没有被 Infinera 和供应链成本拖累 管理层强调下半年 AI DCI pipeline 强
这种情况下,市场会继续把 Nokia 从通信设备股往 AI 光网络平台股重估。
Neutral 情景:短线震荡
如果结果是:
营收符合公司指引 利润中规中矩 Optical 强,但没有继续上修 AI/cloud 订单不错但不惊艳
那股价可能震荡,因为市场已经提前反映不少预期。
这种情况下,NOK 不一定大跌,但短线可能缺少继续上冲动力。
Bearish 情景:sell the news
如果出现:
AI/cloud 订单低于 Q1 很多 Optical 增速明显放缓 Q2 利润靠近指引低端 传统业务拖累明显 Infinera 整合成本超预期 全年指引不变甚至语气谨慎
那市场可能会认为: AI 故事还在,但短期兑现不够。
这种情况下,NOK 很容易被当成“前期 AI 重估过快”的股票回调。
我认为 7 月 23 日 Nokia 财报的核心不是“会不会盈利”,而是:
AI 光网络订单能否继续转化成收入和利润。
目前对 Nokia 的中期逻辑仍然偏正面: Optical Networks 是最强增长曲线 AI/cloud 客户需求已经被 Q1 验证 Aureon 项目给了 AI DCI 商业模板 Allentown 扩产提升美国本土供应链价值 Google Gemini 合作让 Nokia 多了一条 AI 网络软件化路线。
但短线风险也很现实:
股价已经明显重估。 市场对 Q2 期待很高。 传统通信业务仍有拖累。 Infinera 整合和毛利率需要证明。 如果只有故事没有指引上修,容易 sell the news。
Nokia 7 月 23 日想继续涨,必须证明三件事: AI/cloud 订单没有降温,Optical/IP 增长能继续上修,利润率没有被重资产和整合成本吃掉。
Nokia 7 月 23 日想继续涨,必须证明三件事: AI/cloud 订单没有降温,Optical/IP 增长能继续上修,利润率没有被重资产和整合成本吃掉,利好风险点财报前分析
美股 $NOK Nokia 已确认将在 2026 年 7 月 23 日发布 Q2 和上半年业绩Corporation | Nokia
财报前,Nokia 当前的核心
现在 Nokia 已经不是单纯的“传统通信设备股”了,市场正在按三条 AI 基建线重新看它:
第一条:Optical Networks / AI DCI。 AI 数据中心扩张带来跨数据中心互联需求,Nokia 通过 Infinera 补强相干光学和光传输系统。
Q1 里 Optical Networks 增长 20%,Network Infrastructure 增长 6%,公司还把 2026 年 Network Infrastructure 增长目标上调到 12%–14%,并假设 IP + Optical Networks 合计增长 18%–20%
第二条:美国本土 AI 光网络供应链。
6 月 16 日,Nokia 宣布扩建 Allentown 光子芯片 advanced test and packaging 产能,产能最高提升到当前水平的 10 倍,新产能预计在 Q3 末商用;这个项目也是 Nokia 在美国 AI-ready network connectivity 上 40 亿美元多年投资计划的一部分
第三条:AI 网络软件化。
6 月下旬,Nokia 和 Google Cloud 宣布把 Gemini 模型做成 AI agents,集成进 Nokia Assurance Center,用来帮助运营商做故障定位、告警筛选、自动化修复和自主管理网络。Nokia 同期还升级了 autonomous networks 产品组合,强调 agentic AI、IP/fixed/optical 网络自动化和 RAN 自动化。
这三条合起来,Nokia 的故事就从“卖设备”变成了: AI 数据中心需要光网络。 AI 光网络需要本土供应链。 复杂网络需要 AI 自动化软件。
7 月 23 日财报可能带来上涨的利好点 利好一: AI/cloud 订单继续强,最好再次接近或超过 Q1 的 10 亿欧元
Q1 最大亮点不是总营收,而是 AI/cloud 客户销售 +49%,订单约 10 亿欧元。这直接让市场相信 Nokia 真在吃到 AI 数据中心光网络需求。
Q2 如果继续披露: AI/cloud 订单仍然强 book-to-bill 继续明显高于 1 hyperscaler / cloud 客户订单扩大 pluggables 和 line systems 继续拿 design wins 那就是强利好
尤其要看管理层有没有说类似:
“AI/cloud demand accelerated in Q2” “Order intake remained strong” “Book-to-bill remained well above one” 如果 Q2 订单明显弱于 Q1,市场可能会担心 Q1 是一次性订单高峰。
利好二: Optical Networks 继续 20% 左右增长,或者全年目标再上修
Q1 Optical Networks 增长 20%,这已经是 Nokia 最关键的 AI 线。公司目前对 IP + Optical Networks 2026 年增长假设是 18%–20%。
Q2 如果 Optical 继续高增长,市场会认为:
AI DCI 需求不是短期情绪,而是正在转成收入。
更强的情况是公司把 18%–20% 继续上修,或者暗示下半年订单能见度更高。那会是推动股价继续上涨的重要催化。
但如果 Optical 增速放缓,或者订单强但收入确认慢,股价可能短线承压。
利好三:Q2 营收和利润站在指引高端 Nokia 在 Q1 报告里给出的 Q2 季节性假设是:Q2 净销售额环比增长 5%–9%,Q2 comparable operating profit 占全年 comparable operating profit 的 12%–16%。公司全年 comparable operating profit 目标区间是 20 亿–25 亿欧元
换算一下,市场会大致这样看:
指标偏利好表现Q2 净销售靠近或超过环比 +9%Q2 comparable operating profit靠近全年利润的 16%全年利润指引维持高端,甚至上调Network Infrastructure继续跑赢集团整体Optical/IP继续强于传统通信业务
如果营收只是中位数,但利润率超预期,也可能利好。因为市场现在更关心 Nokia 能不能把 AI 光网络订单转成高质量利润,而不是只做规模
利好四: Aureon 100–400Tb/s AI 光网络项目被管理层作为“可复制模板”强调
6 月 18 日,Nokia、t3 Broadband 和 Aureon 宣布部署 AI-ready optical network,初始可提供 100Tb/s,未来可扩展至 400Tb/s,连接北达科他数据中心和芝加哥,用的是 Nokia 1830 GX、Super C/L-band 和 1.2T ICE7 相干光学。
这个项目对财报的意义不是金额本身,而是它证明 Nokia 的 AI DCI 方案已经在真实场景里落地。
如果电话会上管理层说:
类似 Aureon 的项目 pipeline 正在增加 区域运营商和 hyperscale AI 数据中心开始复制这种架构 1.2T ICE7 和 1830 GX 需求强
那对 Optical Networks 的中期重估很有帮助。
利好五:Allentown 扩产被市场理解为美国 AI 光网络供应链卡位
Allentown 扩产是中长期利好。Nokia 表示该厂是美国少数能将 photonic chips 做 ATP 并封装成 optical modules 的设施之一,扩产后产能最高提升至 10 倍,预计 Q3 末可用。(Nokia Corporation | Nokia)
如果 Q2 电话会里管理层进一步确认:
美国 hyperscaler 对本土化光网络供应链需求强 Allentown 扩产对应真实客户需求 扩产不会显著压低利润率 Infinera + Allentown 能带来供应链优势
那会强化 Nokia 与 Ciena、Lumentum、Coherent、Marvell 等 AI 光互联链条的相关性。
利好六:AI 网络软件和 Google Gemini 合作被市场当成“软件估值”加分项
Google Cloud + Nokia Assurance Center 的重点是:Nokia 正在把 AI agent 放进运营商网络运维里,用来做故障诊断、KPI 分析、异常推理和自动化修复。
这不会立刻带来爆炸收入,但它会让市场看到 Nokia 的另一条增长线:
不是只卖硬件,而是卖 AI 网络软件、自动化和运营商降本增效工具。
如果管理层披露 SaaS 化、Google Cloud Marketplace、运营商试点数量、软件订单或 autonomous network pipeline,这会让估值逻辑更舒服。
财报里最需要警惕的风险点
风险一:AI 订单强,但收入确认慢 Nokia 现在最怕的不是“没有故事”,而是“故事很多,但 Q2 数字没跟上”
如果 Q2 AI/cloud 订单还不错,但 Optical/IP 收入没有明显加速,市场可能会说: 订单还在 backlog 里,短期兑现不够
这对已经提前上涨的股票很容易造成 sell the news。
风险二:利润率不够好
Nokia Q2 指引里,利润占全年比例只有 12%–16%,这意味着 Q2 本来就不一定是全年最强利润季度。
如果出现: 营收增长但毛利率承压 Infinera 整合成本高 光模块/相干光学供应链成本上涨 AI 光网络订单利润率低于预期 那市场可能会担心 Nokia 是“收入增长但利润质量一般”
这点非常关键。因为 AI 光网络如果只能带来低毛利增长,估值不会持续重估。
风险三:Fixed Networks 和 Mobile Infrastructure 拖后腿
Q1 Fixed Networks 净销售下降 13%,Mobile Infrastructure 虽然有所改善,但传统运营商 capex 周期并没有全面复苏。
如果 Q2 里传统通信业务继续疲软,而 AI/Optical 又不足以完全抵消,市场会重新把 Nokia 拉回“老电信设备股”的估值框架。
这就是 Nokia 和 $MRVL、 $LITE、 $COHR 最大区别:
Nokia 有 AI 光网络弹性,但仍然有传统通信业务包袱。
风险四:Infinera 整合低于预期
市场看好 Nokia 的一个原因,是收购 Infinera 后补强了 optical transport 和相干光学能力。Reuters 也提到,Nokia 在收购 Infinera 后已成为重要的 optical transport 系统供应商
但整合是双刃剑。 财报里要看:
协同效应是否按计划兑现 产品整合是否顺利 客户是否接受新组合方案 成本和库存是否拖累利润率
如果 Infinera 带来的只是收入,利润还没跟上,市场会打折。
风险五:股价已提前定价一部分 AI 乐观预期
Nokia ADR 当前约 12.07 美元,市值约 666.6 亿美元。 MarketScreener 的欧洲报价页面显示,Nokia 年初以来涨幅已经非常大,且近期分析师意见分化:
7 月初有 BofA 因预期强 Q2 AI 订单上调目标,也有 UBS 中性、Barclays 卖出等不同观点。
这说明市场已经不再把 Nokia 当便宜冷门股看。
所以 Q2 财报的门槛提高了:
符合指引可能不够。 需要订单、利润和指引至少有一个明显超预期。
风险六:AI CapEx 情绪变化
Nokia 现在被市场归入 AI 基建链条,所以也会受 AI CapEx 情绪影响。
如果 7 月前后市场开始质疑 hyperscaler AI 支出、Neocloud 折旧压力、GPU 投资回报,Nokia 即使基本面没坏,也可能跟随 AI 基建板块回调。
这类风险不是公司特有风险,而是板块估值风险。
三种财报情景推演
Bullish 情景:股价继续上行
如果 Q2 出现以下组合,NOK 很可能继续上涨:
AI/cloud 订单继续强 Optical Networks 继续 20%+ 增长 IP Networks 明显加速 全年 Network Infrastructure / Optical+IP 指引再上修 利润率没有被 Infinera 和供应链成本拖累 管理层强调下半年 AI DCI pipeline 强
这种情况下,市场会继续把 Nokia 从通信设备股往 AI 光网络平台股重估。
Neutral 情景:短线震荡
如果结果是:
营收符合公司指引 利润中规中矩 Optical 强,但没有继续上修 AI/cloud 订单不错但不惊艳
那股价可能震荡,因为市场已经提前反映不少预期。
这种情况下,NOK 不一定大跌,但短线可能缺少继续上冲动力。
Bearish 情景:sell the news
如果出现:
AI/cloud 订单低于 Q1 很多 Optical 增速明显放缓 Q2 利润靠近指引低端 传统业务拖累明显 Infinera 整合成本超预期 全年指引不变甚至语气谨慎
那市场可能会认为: AI 故事还在,但短期兑现不够。
这种情况下,NOK 很容易被当成“前期 AI 重估过快”的股票回调。
我认为 7 月 23 日 Nokia 财报的核心不是“会不会盈利”,而是:
AI 光网络订单能否继续转化成收入和利润。
目前对 Nokia 的中期逻辑仍然偏正面: Optical Networks 是最强增长曲线 AI/cloud 客户需求已经被 Q1 验证 Aureon 项目给了 AI DCI 商业模板 Allentown 扩产提升美国本土供应链价值 Google Gemini 合作让 Nokia 多了一条 AI 网络软件化路线。
但短线风险也很现实:
股价已经明显重估。 市场对 Q2 期待很高。 传统通信业务仍有拖累。 Infinera 整合和毛利率需要证明。 如果只有故事没有指引上修,容易 sell the news。
Nokia 7 月 23 日想继续涨,必须证明三件事: AI/cloud 订单没有降温,Optical/IP 增长能继续上修,利润率没有被重资产和整合成本吃掉。
财报前,Nokia 当前的核心
现在 Nokia 已经不是单纯的“传统通信设备股”了,市场正在按三条 AI 基建线重新看它:
第一条:Optical Networks / AI DCI。 AI 数据中心扩张带来跨数据中心互联需求,Nokia 通过 Infinera 补强相干光学和光传输系统。
Q1 里 Optical Networks 增长 20%,Network Infrastructure 增长 6%,公司还把 2026 年 Network Infrastructure 增长目标上调到 12%–14%,并假设 IP + Optical Networks 合计增长 18%–20%
第二条:美国本土 AI 光网络供应链。
6 月 16 日,Nokia 宣布扩建 Allentown 光子芯片 advanced test and packaging 产能,产能最高提升到当前水平的 10 倍,新产能预计在 Q3 末商用;这个项目也是 Nokia 在美国 AI-ready network connectivity 上 40 亿美元多年投资计划的一部分
第三条:AI 网络软件化。
6 月下旬,Nokia 和 Google Cloud 宣布把 Gemini 模型做成 AI agents,集成进 Nokia Assurance Center,用来帮助运营商做故障定位、告警筛选、自动化修复和自主管理网络。Nokia 同期还升级了 autonomous networks 产品组合,强调 agentic AI、IP/fixed/optical 网络自动化和 RAN 自动化。
这三条合起来,Nokia 的故事就从“卖设备”变成了: AI 数据中心需要光网络。 AI 光网络需要本土供应链。 复杂网络需要 AI 自动化软件。
7 月 23 日财报可能带来上涨的利好点 利好一: AI/cloud 订单继续强,最好再次接近或超过 Q1 的 10 亿欧元
Q1 最大亮点不是总营收,而是 AI/cloud 客户销售 +49%,订单约 10 亿欧元。这直接让市场相信 Nokia 真在吃到 AI 数据中心光网络需求。
Q2 如果继续披露: AI/cloud 订单仍然强 book-to-bill 继续明显高于 1 hyperscaler / cloud 客户订单扩大 pluggables 和 line systems 继续拿 design wins 那就是强利好
尤其要看管理层有没有说类似:
“AI/cloud demand accelerated in Q2” “Order intake remained strong” “Book-to-bill remained well above one” 如果 Q2 订单明显弱于 Q1,市场可能会担心 Q1 是一次性订单高峰。
利好二: Optical Networks 继续 20% 左右增长,或者全年目标再上修
Q1 Optical Networks 增长 20%,这已经是 Nokia 最关键的 AI 线。公司目前对 IP + Optical Networks 2026 年增长假设是 18%–20%。
Q2 如果 Optical 继续高增长,市场会认为:
AI DCI 需求不是短期情绪,而是正在转成收入。
更强的情况是公司把 18%–20% 继续上修,或者暗示下半年订单能见度更高。那会是推动股价继续上涨的重要催化。
但如果 Optical 增速放缓,或者订单强但收入确认慢,股价可能短线承压。
利好三:Q2 营收和利润站在指引高端 Nokia 在 Q1 报告里给出的 Q2 季节性假设是:Q2 净销售额环比增长 5%–9%,Q2 comparable operating profit 占全年 comparable operating profit 的 12%–16%。公司全年 comparable operating profit 目标区间是 20 亿–25 亿欧元
换算一下,市场会大致这样看:
指标偏利好表现Q2 净销售靠近或超过环比 +9%Q2 comparable operating profit靠近全年利润的 16%全年利润指引维持高端,甚至上调Network Infrastructure继续跑赢集团整体Optical/IP继续强于传统通信业务
如果营收只是中位数,但利润率超预期,也可能利好。因为市场现在更关心 Nokia 能不能把 AI 光网络订单转成高质量利润,而不是只做规模
利好四: Aureon 100–400Tb/s AI 光网络项目被管理层作为“可复制模板”强调
6 月 18 日,Nokia、t3 Broadband 和 Aureon 宣布部署 AI-ready optical network,初始可提供 100Tb/s,未来可扩展至 400Tb/s,连接北达科他数据中心和芝加哥,用的是 Nokia 1830 GX、Super C/L-band 和 1.2T ICE7 相干光学。
这个项目对财报的意义不是金额本身,而是它证明 Nokia 的 AI DCI 方案已经在真实场景里落地。
如果电话会上管理层说:
类似 Aureon 的项目 pipeline 正在增加 区域运营商和 hyperscale AI 数据中心开始复制这种架构 1.2T ICE7 和 1830 GX 需求强
那对 Optical Networks 的中期重估很有帮助。
利好五:Allentown 扩产被市场理解为美国 AI 光网络供应链卡位
Allentown 扩产是中长期利好。Nokia 表示该厂是美国少数能将 photonic chips 做 ATP 并封装成 optical modules 的设施之一,扩产后产能最高提升至 10 倍,预计 Q3 末可用。(Nokia Corporation | Nokia)
如果 Q2 电话会里管理层进一步确认:
美国 hyperscaler 对本土化光网络供应链需求强 Allentown 扩产对应真实客户需求 扩产不会显著压低利润率 Infinera + Allentown 能带来供应链优势
那会强化 Nokia 与 Ciena、Lumentum、Coherent、Marvell 等 AI 光互联链条的相关性。
利好六:AI 网络软件和 Google Gemini 合作被市场当成“软件估值”加分项
Google Cloud + Nokia Assurance Center 的重点是:Nokia 正在把 AI agent 放进运营商网络运维里,用来做故障诊断、KPI 分析、异常推理和自动化修复。
这不会立刻带来爆炸收入,但它会让市场看到 Nokia 的另一条增长线:
不是只卖硬件,而是卖 AI 网络软件、自动化和运营商降本增效工具。
如果管理层披露 SaaS 化、Google Cloud Marketplace、运营商试点数量、软件订单或 autonomous network pipeline,这会让估值逻辑更舒服。
财报里最需要警惕的风险点
风险一:AI 订单强,但收入确认慢 Nokia 现在最怕的不是“没有故事”,而是“故事很多,但 Q2 数字没跟上”
如果 Q2 AI/cloud 订单还不错,但 Optical/IP 收入没有明显加速,市场可能会说: 订单还在 backlog 里,短期兑现不够
这对已经提前上涨的股票很容易造成 sell the news。
风险二:利润率不够好
Nokia Q2 指引里,利润占全年比例只有 12%–16%,这意味着 Q2 本来就不一定是全年最强利润季度。
如果出现: 营收增长但毛利率承压 Infinera 整合成本高 光模块/相干光学供应链成本上涨 AI 光网络订单利润率低于预期 那市场可能会担心 Nokia 是“收入增长但利润质量一般”
这点非常关键。因为 AI 光网络如果只能带来低毛利增长,估值不会持续重估。
风险三:Fixed Networks 和 Mobile Infrastructure 拖后腿
Q1 Fixed Networks 净销售下降 13%,Mobile Infrastructure 虽然有所改善,但传统运营商 capex 周期并没有全面复苏。
如果 Q2 里传统通信业务继续疲软,而 AI/Optical 又不足以完全抵消,市场会重新把 Nokia 拉回“老电信设备股”的估值框架。
这就是 Nokia 和 $MRVL、 $LITE、 $COHR 最大区别:
Nokia 有 AI 光网络弹性,但仍然有传统通信业务包袱。
风险四:Infinera 整合低于预期
市场看好 Nokia 的一个原因,是收购 Infinera 后补强了 optical transport 和相干光学能力。Reuters 也提到,Nokia 在收购 Infinera 后已成为重要的 optical transport 系统供应商
但整合是双刃剑。 财报里要看:
协同效应是否按计划兑现 产品整合是否顺利 客户是否接受新组合方案 成本和库存是否拖累利润率
如果 Infinera 带来的只是收入,利润还没跟上,市场会打折。
风险五:股价已提前定价一部分 AI 乐观预期
Nokia ADR 当前约 12.07 美元,市值约 666.6 亿美元。 MarketScreener 的欧洲报价页面显示,Nokia 年初以来涨幅已经非常大,且近期分析师意见分化:
7 月初有 BofA 因预期强 Q2 AI 订单上调目标,也有 UBS 中性、Barclays 卖出等不同观点。
这说明市场已经不再把 Nokia 当便宜冷门股看。
所以 Q2 财报的门槛提高了:
符合指引可能不够。 需要订单、利润和指引至少有一个明显超预期。
风险六:AI CapEx 情绪变化
Nokia 现在被市场归入 AI 基建链条,所以也会受 AI CapEx 情绪影响。
如果 7 月前后市场开始质疑 hyperscaler AI 支出、Neocloud 折旧压力、GPU 投资回报,Nokia 即使基本面没坏,也可能跟随 AI 基建板块回调。
这类风险不是公司特有风险,而是板块估值风险。
三种财报情景推演
Bullish 情景:股价继续上行
如果 Q2 出现以下组合,NOK 很可能继续上涨:
AI/cloud 订单继续强 Optical Networks 继续 20%+ 增长 IP Networks 明显加速 全年 Network Infrastructure / Optical+IP 指引再上修 利润率没有被 Infinera 和供应链成本拖累 管理层强调下半年 AI DCI pipeline 强
这种情况下,市场会继续把 Nokia 从通信设备股往 AI 光网络平台股重估。
Neutral 情景:短线震荡
如果结果是:
营收符合公司指引 利润中规中矩 Optical 强,但没有继续上修 AI/cloud 订单不错但不惊艳
那股价可能震荡,因为市场已经提前反映不少预期。
这种情况下,NOK 不一定大跌,但短线可能缺少继续上冲动力。
Bearish 情景:sell the news
如果出现:
AI/cloud 订单低于 Q1 很多 Optical 增速明显放缓 Q2 利润靠近指引低端 传统业务拖累明显 Infinera 整合成本超预期 全年指引不变甚至语气谨慎
那市场可能会认为: AI 故事还在,但短期兑现不够。
这种情况下,NOK 很容易被当成“前期 AI 重估过快”的股票回调。
我认为 7 月 23 日 Nokia 财报的核心不是“会不会盈利”,而是:
AI 光网络订单能否继续转化成收入和利润。
目前对 Nokia 的中期逻辑仍然偏正面: Optical Networks 是最强增长曲线 AI/cloud 客户需求已经被 Q1 验证 Aureon 项目给了 AI DCI 商业模板 Allentown 扩产提升美国本土供应链价值 Google Gemini 合作让 Nokia 多了一条 AI 网络软件化路线。
但短线风险也很现实:
股价已经明显重估。 市场对 Q2 期待很高。 传统通信业务仍有拖累。 Infinera 整合和毛利率需要证明。 如果只有故事没有指引上修,容易 sell the news。
Nokia 7 月 23 日想继续涨,必须证明三件事: AI/cloud 订单没有降温,Optical/IP 增长能继续上修,利润率没有被重资产和整合成本吃掉。
2
4.3k
·
--
Meta的老总真该挨骂啊,也不出来澄清!
其实就是模型做得菜,追不上open ai和claude。
收入只能学着马斯克把多余的算力租出去多一笔收入了。
市场担心的是:
Meta 砸上千亿美元做 AI 基建,最后 ROI 不明确。
现在如果 Meta 能把闲置或阶段性富余算力对外出租,就等于把“资本开支压力”部分转化成“可变现资产”。
这会缓解投资人对 AI capex 回报率的担忧。
逻辑主要有三层:
第一,说明 AI 算力确实有外部需求。
如果企业客户愿意买 Meta 的模型访问或原始 GPU 算力,说明市场不是没有需求,而是算力仍然稀缺。
Reuters 也提到,这可能帮助 Meta 参与企业 AI 服务需求,并降低对广告业务的依赖。
第二,说明 Meta 的 AI capex 不一定是纯成本。
Meta 官方 Q1 里已经把 2026 年 capex 指引提高到 1250–1450 亿美元,之前市场把这理解成现金流压力。现在如果部分算力可以外租,市场会重新思考这些数据中心和 GPU 是不是也能产生收入。
第三,暂时没有证据证明 Meta 要削减 AI 投入。
Meta 官方同时还说,预计 2026 年经营利润高于 2025 年,并未释放“全面收缩 AI 支出”的信号。
所以 Wells Fargo 说“市场误解了 Meta 的 excess compute comment”
Meta的老总真该挨骂啊,也不出来澄清!
其实就是模型做得菜,追不上open ai和claude。
收入只能学着马斯克把多余的算力租出去多一笔收入了。
市场担心的是:
Meta 砸上千亿美元做 AI 基建,最后 ROI 不明确。
现在如果 Meta 能把闲置或阶段性富余算力对外出租,就等于把“资本开支压力”部分转化成“可变现资产”。
这会缓解投资人对 AI capex 回报率的担忧。
逻辑主要有三层:
第一,说明 AI 算力确实有外部需求。
如果企业客户愿意买 Meta 的模型访问或原始 GPU 算力,说明市场不是没有需求,而是算力仍然稀缺。
Reuters 也提到,这可能帮助 Meta 参与企业 AI 服务需求,并降低对广告业务的依赖。
第二,说明 Meta 的 AI capex 不一定是纯成本。
Meta 官方 Q1 里已经把 2026 年 capex 指引提高到 1250–1450 亿美元,之前市场把这理解成现金流压力。现在如果部分算力可以外租,市场会重新思考这些数据中心和 GPU 是不是也能产生收入。
第三,暂时没有证据证明 Meta 要削减 AI 投入。
Meta 官方同时还说,预计 2026 年经营利润高于 2025 年,并未释放“全面收缩 AI 支出”的信号。
所以 Wells Fargo 说“市场误解了 Meta 的 excess compute comment”
其实就是模型做得菜,追不上open ai和claude。
收入只能学着马斯克把多余的算力租出去多一笔收入了。
市场担心的是:
Meta 砸上千亿美元做 AI 基建,最后 ROI 不明确。
现在如果 Meta 能把闲置或阶段性富余算力对外出租,就等于把“资本开支压力”部分转化成“可变现资产”。
这会缓解投资人对 AI capex 回报率的担忧。
逻辑主要有三层:
第一,说明 AI 算力确实有外部需求。
如果企业客户愿意买 Meta 的模型访问或原始 GPU 算力,说明市场不是没有需求,而是算力仍然稀缺。
Reuters 也提到,这可能帮助 Meta 参与企业 AI 服务需求,并降低对广告业务的依赖。
第二,说明 Meta 的 AI capex 不一定是纯成本。
Meta 官方 Q1 里已经把 2026 年 capex 指引提高到 1250–1450 亿美元,之前市场把这理解成现金流压力。现在如果部分算力可以外租,市场会重新思考这些数据中心和 GPU 是不是也能产生收入。
第三,暂时没有证据证明 Meta 要削减 AI 投入。
Meta 官方同时还说,预计 2026 年经营利润高于 2025 年,并未释放“全面收缩 AI 支出”的信号。
所以 Wells Fargo 说“市场误解了 Meta 的 excess compute comment”

2
11
4.6k
·
--
Мақала
$SHAZ 从“高风险 AI 云小票”,开始变成“被顶级 AI 基建资金验证的 APAC AI Factory 平台”。果然!两周前建仓 $SHAZ 建对了!
$NBIS $CRWV 都涨了非常多了,SHAZ才刚刚开始!
按私募条款推算,Situational Awareness 这批 $SHAZ 仓位的等效成本基本就是 $68.73/股附近。这个价位可以当作 Leopold 这次战略入场的核心成本线
Leopold Aschenbrenner 背后的 Situational Awareness 披露持有 Sharon AI 19.9% 的受益所有权。
注意,这不是简单的“散户博主喊单”。
这是一个真正押注 AI 基建的核心资金,把 SHAZ 放进了自己的重仓体系里。
文件显示,Situational Awareness 相关实体、Leopold Aschenbrenner 和 Carl Shulman 共同披露,对 5,404,540 股拥有 shared voting / dispositive power,对应 19.9% 的 Class A 普通股受益所有权。
更细看,这个仓位由两部分组成:
1,696,127 股 Class A 普通股
以及可购买 6,374,823 股的预融资权证
但这个权证受到 19.99% beneficial ownership limitation 限制。
所以这件事不能误读成“今天二级市场直接扫货 19.9%”。
更准确地说:
Situational Awareness 参与了 SHAZ 的战略融资,现在通过 13G 把重仓位置正式披露出来。
这件事真正重要的地方在于:
第一,SHAZ 的融资闭环被进一步确认。
此前市场最大的问题是:
澳洲 AI Factory 要部署这么多 GPU,CapEx 这么重,钱到底从哪里来
现在 16 亿美元融资已经完成,且由 Situational Awareness 和 Oaktree 这类资金锚定。
这对 SHAZ 来说,是非常关键的资本信用背书。
第二,Situational Awareness 的入场,会强化 SHAZ 的市场认知
Leopold 这只基金的标签很明确:
它不是普通科技基金,而是围绕 AGI、算力、电力、数据中心、AI 基础设施做系统性布局。
它愿意重仓 SHAZ,本质上是在押:
澳洲 / APAC 主权 AI 云
NVIDIA-backed AI Factory
Neocloud 算力供给缺口
GPU 资源区域化
AI 数据中心从巨头垄断走向区域复制
这和 SHAZ 的故事完全对上。
第三,19.9% 这个比例本身很重。
对一家小市值 neocloud 来说,接近 20% 的核心资金持仓,不只是财务投资,更是市场信号。
它会带来三个效果:
浮筹变少
关注度上升
估值重定价概率提高
第四,这件事会让市场重新审视 SHAZ 的位置。
过去大家看 SHAZ,更多是在看一个高风险 AI 云小票。
现在它的标签正在变化:
NVIDIA 六年合作
最多 40,000 颗 GB300 GPU
132MW AI Factory capacity
102MW contracted to end customers
55,000+ NVIDIA GPUs expected by mid-2027
16 亿美元战略融资完成
Situational Awareness / Oaktree 锚定
这些信息放在一起,SHAZ 就不是普通 AI 概念股,而是一个正在被资本市场验证的 APAC neocloud 平台。
风险:
13G 是偏被动持仓披露,不是 13D。
这不代表 Leopold 要控制公司,也不代表他会进董事会推动战略。
而且这次融资里有股票、预融资权证和可转债,未来股本摊薄和债务压力仍然存在。
SHAZ 后面真正要证明的不是“谁买了”。
而是:
GPU 能不能按期部署
客户合同能不能转收入
收入能不能覆盖折旧
毛利率能不能跑出来
现金流能不能改善
如果 SHAZ 能把 16 亿美元资金、NVIDIA 合作、客户合同和 GPU 部署真正转成收入,那么这次 19.9% 持仓披露可能会成为市场重新定价 SHAZ 的关键节点。
但如果后续只是融资和故事,收入兑现慢,那市场还是会重新回到稀释、CapEx 和现金流压力上。
SHAZ 从“高风险 AI 云小票”,开始变成“被顶级 AI 基建资金验证的 APAC AI Factory 平台”。
对我来说,这是一条非常不错的利好。
但它不是终点,而是执行周期的开始!
$SHAZ 从“高风险 AI 云小票”,开始变成“被顶级 AI 基建资金验证的 APAC AI Factory 平台”。
果然!两周前建仓 $SHAZ 建对了!
$NBIS $CRWV 都涨了非常多了,SHAZ才刚刚开始!
按私募条款推算,Situational Awareness 这批 $SHAZ 仓位的等效成本基本就是 $68.73/股附近。这个价位可以当作 Leopold 这次战略入场的核心成本线
Leopold Aschenbrenner 背后的 Situational Awareness 披露持有 Sharon AI 19.9% 的受益所有权。
注意,这不是简单的“散户博主喊单”。
这是一个真正押注 AI 基建的核心资金,把 SHAZ 放进了自己的重仓体系里。
文件显示,Situational Awareness 相关实体、Leopold Aschenbrenner 和 Carl Shulman 共同披露,对 5,404,540 股拥有 shared voting / dispositive power,对应 19.9% 的 Class A 普通股受益所有权。
更细看,这个仓位由两部分组成:
1,696,127 股 Class A 普通股
以及可购买 6,374,823 股的预融资权证
但这个权证受到 19.99% beneficial ownership limitation 限制。
所以这件事不能误读成“今天二级市场直接扫货 19.9%”。
更准确地说:
Situational Awareness 参与了 SHAZ 的战略融资,现在通过 13G 把重仓位置正式披露出来。
这件事真正重要的地方在于:
第一,SHAZ 的融资闭环被进一步确认。
此前市场最大的问题是:
澳洲 AI Factory 要部署这么多 GPU,CapEx 这么重,钱到底从哪里来
现在 16 亿美元融资已经完成,且由 Situational Awareness 和 Oaktree 这类资金锚定。
这对 SHAZ 来说,是非常关键的资本信用背书。
第二,Situational Awareness 的入场,会强化 SHAZ 的市场认知
Leopold 这只基金的标签很明确:
它不是普通科技基金,而是围绕 AGI、算力、电力、数据中心、AI 基础设施做系统性布局。
它愿意重仓 SHAZ,本质上是在押:
澳洲 / APAC 主权 AI 云
NVIDIA-backed AI Factory
Neocloud 算力供给缺口
GPU 资源区域化
AI 数据中心从巨头垄断走向区域复制
这和 SHAZ 的故事完全对上。
第三,19.9% 这个比例本身很重。
对一家小市值 neocloud 来说,接近 20% 的核心资金持仓,不只是财务投资,更是市场信号。
它会带来三个效果:
浮筹变少
关注度上升
估值重定价概率提高
第四,这件事会让市场重新审视 SHAZ 的位置。
过去大家看 SHAZ,更多是在看一个高风险 AI 云小票。
现在它的标签正在变化:
NVIDIA 六年合作
最多 40,000 颗 GB300 GPU
132MW AI Factory capacity
102MW contracted to end customers
55,000+ NVIDIA GPUs expected by mid-2027
16 亿美元战略融资完成
Situational Awareness / Oaktree 锚定
这些信息放在一起,SHAZ 就不是普通 AI 概念股,而是一个正在被资本市场验证的 APAC neocloud 平台。
风险:
13G 是偏被动持仓披露,不是 13D。
这不代表 Leopold 要控制公司,也不代表他会进董事会推动战略。
而且这次融资里有股票、预融资权证和可转债,未来股本摊薄和债务压力仍然存在。
SHAZ 后面真正要证明的不是“谁买了”。
而是:
GPU 能不能按期部署
客户合同能不能转收入
收入能不能覆盖折旧
毛利率能不能跑出来
现金流能不能改善
如果 SHAZ 能把 16 亿美元资金、NVIDIA 合作、客户合同和 GPU 部署真正转成收入,那么这次 19.9% 持仓披露可能会成为市场重新定价 SHAZ 的关键节点。
但如果后续只是融资和故事,收入兑现慢,那市场还是会重新回到稀释、CapEx 和现金流压力上。
SHAZ 从“高风险 AI 云小票”,开始变成“被顶级 AI 基建资金验证的 APAC AI Factory 平台”。
对我来说,这是一条非常不错的利好。
但它不是终点,而是执行周期的开始!
$NBIS $CRWV 都涨了非常多了,SHAZ才刚刚开始!
按私募条款推算,Situational Awareness 这批 $SHAZ 仓位的等效成本基本就是 $68.73/股附近。这个价位可以当作 Leopold 这次战略入场的核心成本线
Leopold Aschenbrenner 背后的 Situational Awareness 披露持有 Sharon AI 19.9% 的受益所有权。
注意,这不是简单的“散户博主喊单”。
这是一个真正押注 AI 基建的核心资金,把 SHAZ 放进了自己的重仓体系里。
文件显示,Situational Awareness 相关实体、Leopold Aschenbrenner 和 Carl Shulman 共同披露,对 5,404,540 股拥有 shared voting / dispositive power,对应 19.9% 的 Class A 普通股受益所有权。
更细看,这个仓位由两部分组成:
1,696,127 股 Class A 普通股
以及可购买 6,374,823 股的预融资权证
但这个权证受到 19.99% beneficial ownership limitation 限制。
所以这件事不能误读成“今天二级市场直接扫货 19.9%”。
更准确地说:
Situational Awareness 参与了 SHAZ 的战略融资,现在通过 13G 把重仓位置正式披露出来。
这件事真正重要的地方在于:
第一,SHAZ 的融资闭环被进一步确认。
此前市场最大的问题是:
澳洲 AI Factory 要部署这么多 GPU,CapEx 这么重,钱到底从哪里来
现在 16 亿美元融资已经完成,且由 Situational Awareness 和 Oaktree 这类资金锚定。
这对 SHAZ 来说,是非常关键的资本信用背书。
第二,Situational Awareness 的入场,会强化 SHAZ 的市场认知
Leopold 这只基金的标签很明确:
它不是普通科技基金,而是围绕 AGI、算力、电力、数据中心、AI 基础设施做系统性布局。
它愿意重仓 SHAZ,本质上是在押:
澳洲 / APAC 主权 AI 云
NVIDIA-backed AI Factory
Neocloud 算力供给缺口
GPU 资源区域化
AI 数据中心从巨头垄断走向区域复制
这和 SHAZ 的故事完全对上。
第三,19.9% 这个比例本身很重。
对一家小市值 neocloud 来说,接近 20% 的核心资金持仓,不只是财务投资,更是市场信号。
它会带来三个效果:
浮筹变少
关注度上升
估值重定价概率提高
第四,这件事会让市场重新审视 SHAZ 的位置。
过去大家看 SHAZ,更多是在看一个高风险 AI 云小票。
现在它的标签正在变化:
NVIDIA 六年合作
最多 40,000 颗 GB300 GPU
132MW AI Factory capacity
102MW contracted to end customers
55,000+ NVIDIA GPUs expected by mid-2027
16 亿美元战略融资完成
Situational Awareness / Oaktree 锚定
这些信息放在一起,SHAZ 就不是普通 AI 概念股,而是一个正在被资本市场验证的 APAC neocloud 平台。
风险:
13G 是偏被动持仓披露,不是 13D。
这不代表 Leopold 要控制公司,也不代表他会进董事会推动战略。
而且这次融资里有股票、预融资权证和可转债,未来股本摊薄和债务压力仍然存在。
SHAZ 后面真正要证明的不是“谁买了”。
而是:
GPU 能不能按期部署
客户合同能不能转收入
收入能不能覆盖折旧
毛利率能不能跑出来
现金流能不能改善
如果 SHAZ 能把 16 亿美元资金、NVIDIA 合作、客户合同和 GPU 部署真正转成收入,那么这次 19.9% 持仓披露可能会成为市场重新定价 SHAZ 的关键节点。
但如果后续只是融资和故事,收入兑现慢,那市场还是会重新回到稀释、CapEx 和现金流压力上。
SHAZ 从“高风险 AI 云小票”,开始变成“被顶级 AI 基建资金验证的 APAC AI Factory 平台”。
对我来说,这是一条非常不错的利好。
但它不是终点,而是执行周期的开始!
CRWVUS-8,49%
SHAZUS-7,82%
NBISUS-12,41%
11
5.9k
·
--
Мақала
美股行情最新一周新的宏观新闻看点,利好和利空因素,持续输出高质量分析Weekend → Monday U.S. Market Brief
🟢 Bullish developments
Middle East tensions eased, supporting risk assets
The biggest macro driver into Monday is a reported de-escalation between the U.S. and Iran after weekend military exchanges. Markets interpreted the latest developments as reducing the probability of a prolonged disruption to oil shipping. U.S. equity futures, especially Nasdaq futures, moved higher before the open as investors rotated back toward growth assets. (Reuters)
Most positive for
$NVDA $AMD $AVGO $MRVL $ARM
Oil remains well below panic levels
Despite geopolitical headlines, oil has remained relatively contained instead of spiking dramatically.
Lower energy prices generally:
reduce inflation pressure
improve expectations for future Fed policy benefit long-duration growth stocks This is particularly supportive for AI infrastructure names whose valuations are sensitive to interest rates. (Reuters)
AI infrastructure spending remains the dominant long-term theme
Although investors have become more selective, reports continue to highlight that semiconductor and memory companies have been the strongest-performing segment of 2026.
Companies still benefiting from AI capex include:
NVDA MU WDC STX SK Hynix Samsung
The market narrative remains centered on AI infrastructure rather than consumer AI software. (The Guardian)
🔴 Bearish developments
AI valuation concerns continue
The largest headwind remains valuation.
Investors continue questioning:
whether hyperscalers can maintain AI spending
when AI investments generate meaningful cash flow
whether current semiconductor multiples are sustainable
Profit-taking has continued across many AI leaders after an exceptional first half of the year. (Reuters) 2. Rising-rate concerns remain Although geopolitical risks eased, markets are still focused on inflation and Fed policy.
Recent commentary has kept alive expectations that rates could stay higher for longer if inflation proves persistent.
Higher real yields are generally negative for:
NVDA MSFT AMZN GOOGL META other long-duration AI names.
Rotation away from mega-cap AI Several reports note that: semiconductor stocks have significantly outperformed investors have started rotating into other sectors
software and mega-cap AI names have underperformed recently
This does not necessarily imply the AI cycle is ending, but it increases short-term volatility. (The Guardian)
AI company-specific updates
NVIDIA (NVDA) No major company announcement over the weekend. Remains highly sensitive to macro sentiment and AI capex expectations.
Likely to trade with Nasdaq direction and Treasury yields.
Marvell (MRVL)
No significant company-specific news.
Continues trading primarily on AI networking and custom silicon sentiment.
Broadcom (AVGO) No major weekend developments. AMD
No significant company-specific catalyst.
Micron (MU) No new guidance since last week's earnings.
Still viewed as one of the strongest beneficiaries of AI memory demand despite recent profit-taking. (Reuters)
Nokia (NOK)
No meaningful AI-related news over the weekend.
SHAZ
No significant new company announcement over the weekend.
Earnings / Guidance No major AI-company earnings or guidance updates over the weekend.
Macro events to watch this week
This is a shortened trading week.
Key events include:
Tuesday: Consumer Confidence, JOLTS job openings
Wednesday: ADP employment, ISM Manufacturing PMI
Thursday: U.S. Nonfarm Payrolls, Unemployment Rate, Average Hourly Earnings (released early because of the Independence Day holiday)
Friday: U.S. equity markets closed for Independence Day observance. (Schwab Brokerage)
These labor-market reports are likely to be the biggest drivers of Treasury yields and AI stock performance this week.
Policy / Geopolitics
Positive
Reported U.S.–Iran de-escalation reduced immediate fears of a prolonged conflict and major disruption in the Strait of Hormuz. (Reuters)
Risk remains The ceasefire and diplomatic progress remain fragile, and markets could react quickly if tensions escalate again. (Reuters) Overall sentiment for Monday Bullish factors
✅ Reduced geopolitical stress
✅ Stable oil prices
✅ Strong long-term AI infrastructure demand
Bearish factors
⚠️ Continued valuation pressure on AI leaders
⚠️ Higher-for-longer rate concerns
⚠️ Profit-taking after a very strong first half for semiconductor stocks
The backdrop into Monday is moderately constructive for U.S. AI stocks because easing geopolitical tensions and relatively contained oil prices support risk appetite. However, the market's focus is shifting from geopolitical headlines back to Fed expectations, labor-market data, and the sustainability of AI capital spending, which are likely to determine whether the AI sector can regain momentum later in the week.
美股行情最新一周新的宏观新闻看点,利好和利空因素,持续输出高质量分析
Weekend → Monday U.S. Market Brief
🟢 Bullish developments
Middle East tensions eased, supporting risk assets
The biggest macro driver into Monday is a reported de-escalation between the U.S. and Iran after weekend military exchanges. Markets interpreted the latest developments as reducing the probability of a prolonged disruption to oil shipping. U.S. equity futures, especially Nasdaq futures, moved higher before the open as investors rotated back toward growth assets. (Reuters)
Most positive for
$NVDA $AMD $AVGO $MRVL $ARM
Oil remains well below panic levels
Despite geopolitical headlines, oil has remained relatively contained instead of spiking dramatically.
Lower energy prices generally:
reduce inflation pressure
improve expectations for future Fed policy benefit long-duration growth stocks This is particularly supportive for AI infrastructure names whose valuations are sensitive to interest rates. (Reuters)
AI infrastructure spending remains the dominant long-term theme
Although investors have become more selective, reports continue to highlight that semiconductor and memory companies have been the strongest-performing segment of 2026.
Companies still benefiting from AI capex include:
NVDA MU WDC STX SK Hynix Samsung
The market narrative remains centered on AI infrastructure rather than consumer AI software. (The Guardian)
🔴 Bearish developments
AI valuation concerns continue
The largest headwind remains valuation.
Investors continue questioning:
whether hyperscalers can maintain AI spending
when AI investments generate meaningful cash flow
whether current semiconductor multiples are sustainable
Profit-taking has continued across many AI leaders after an exceptional first half of the year. (Reuters) 2. Rising-rate concerns remain Although geopolitical risks eased, markets are still focused on inflation and Fed policy.
Recent commentary has kept alive expectations that rates could stay higher for longer if inflation proves persistent.
Higher real yields are generally negative for:
NVDA MSFT AMZN GOOGL META other long-duration AI names.
Rotation away from mega-cap AI Several reports note that: semiconductor stocks have significantly outperformed investors have started rotating into other sectors
software and mega-cap AI names have underperformed recently
This does not necessarily imply the AI cycle is ending, but it increases short-term volatility. (The Guardian)
AI company-specific updates
NVIDIA (NVDA) No major company announcement over the weekend. Remains highly sensitive to macro sentiment and AI capex expectations.
Likely to trade with Nasdaq direction and Treasury yields.
Marvell (MRVL)
No significant company-specific news.
Continues trading primarily on AI networking and custom silicon sentiment.
Broadcom (AVGO) No major weekend developments. AMD
No significant company-specific catalyst.
Micron (MU) No new guidance since last week's earnings.
Still viewed as one of the strongest beneficiaries of AI memory demand despite recent profit-taking. (Reuters)
Nokia (NOK)
No meaningful AI-related news over the weekend.
SHAZ
No significant new company announcement over the weekend.
Earnings / Guidance No major AI-company earnings or guidance updates over the weekend.
Macro events to watch this week
This is a shortened trading week.
Key events include:
Tuesday: Consumer Confidence, JOLTS job openings
Wednesday: ADP employment, ISM Manufacturing PMI
Thursday: U.S. Nonfarm Payrolls, Unemployment Rate, Average Hourly Earnings (released early because of the Independence Day holiday)
Friday: U.S. equity markets closed for Independence Day observance. (Schwab Brokerage)
These labor-market reports are likely to be the biggest drivers of Treasury yields and AI stock performance this week.
Policy / Geopolitics
Positive
Reported U.S.–Iran de-escalation reduced immediate fears of a prolonged conflict and major disruption in the Strait of Hormuz. (Reuters)
Risk remains The ceasefire and diplomatic progress remain fragile, and markets could react quickly if tensions escalate again. (Reuters) Overall sentiment for Monday Bullish factors
✅ Reduced geopolitical stress
✅ Stable oil prices
✅ Strong long-term AI infrastructure demand
Bearish factors
⚠️ Continued valuation pressure on AI leaders
⚠️ Higher-for-longer rate concerns
⚠️ Profit-taking after a very strong first half for semiconductor stocks
The backdrop into Monday is moderately constructive for U.S. AI stocks because easing geopolitical tensions and relatively contained oil prices support risk appetite. However, the market's focus is shifting from geopolitical headlines back to Fed expectations, labor-market data, and the sustainability of AI capital spending, which are likely to determine whether the AI sector can regain momentum later in the week.
🟢 Bullish developments
Middle East tensions eased, supporting risk assets
The biggest macro driver into Monday is a reported de-escalation between the U.S. and Iran after weekend military exchanges. Markets interpreted the latest developments as reducing the probability of a prolonged disruption to oil shipping. U.S. equity futures, especially Nasdaq futures, moved higher before the open as investors rotated back toward growth assets. (Reuters)
Most positive for
$NVDA $AMD $AVGO $MRVL $ARM
Oil remains well below panic levels
Despite geopolitical headlines, oil has remained relatively contained instead of spiking dramatically.
Lower energy prices generally:
reduce inflation pressure
improve expectations for future Fed policy benefit long-duration growth stocks This is particularly supportive for AI infrastructure names whose valuations are sensitive to interest rates. (Reuters)
AI infrastructure spending remains the dominant long-term theme
Although investors have become more selective, reports continue to highlight that semiconductor and memory companies have been the strongest-performing segment of 2026.
Companies still benefiting from AI capex include:
NVDA MU WDC STX SK Hynix Samsung
The market narrative remains centered on AI infrastructure rather than consumer AI software. (The Guardian)
🔴 Bearish developments
AI valuation concerns continue
The largest headwind remains valuation.
Investors continue questioning:
whether hyperscalers can maintain AI spending
when AI investments generate meaningful cash flow
whether current semiconductor multiples are sustainable
Profit-taking has continued across many AI leaders after an exceptional first half of the year. (Reuters) 2. Rising-rate concerns remain Although geopolitical risks eased, markets are still focused on inflation and Fed policy.
Recent commentary has kept alive expectations that rates could stay higher for longer if inflation proves persistent.
Higher real yields are generally negative for:
NVDA MSFT AMZN GOOGL META other long-duration AI names.
Rotation away from mega-cap AI Several reports note that: semiconductor stocks have significantly outperformed investors have started rotating into other sectors
software and mega-cap AI names have underperformed recently
This does not necessarily imply the AI cycle is ending, but it increases short-term volatility. (The Guardian)
AI company-specific updates
NVIDIA (NVDA) No major company announcement over the weekend. Remains highly sensitive to macro sentiment and AI capex expectations.
Likely to trade with Nasdaq direction and Treasury yields.
Marvell (MRVL)
No significant company-specific news.
Continues trading primarily on AI networking and custom silicon sentiment.
Broadcom (AVGO) No major weekend developments. AMD
No significant company-specific catalyst.
Micron (MU) No new guidance since last week's earnings.
Still viewed as one of the strongest beneficiaries of AI memory demand despite recent profit-taking. (Reuters)
Nokia (NOK)
No meaningful AI-related news over the weekend.
SHAZ
No significant new company announcement over the weekend.
Earnings / Guidance No major AI-company earnings or guidance updates over the weekend.
Macro events to watch this week
This is a shortened trading week.
Key events include:
Tuesday: Consumer Confidence, JOLTS job openings
Wednesday: ADP employment, ISM Manufacturing PMI
Thursday: U.S. Nonfarm Payrolls, Unemployment Rate, Average Hourly Earnings (released early because of the Independence Day holiday)
Friday: U.S. equity markets closed for Independence Day observance. (Schwab Brokerage)
These labor-market reports are likely to be the biggest drivers of Treasury yields and AI stock performance this week.
Policy / Geopolitics
Positive
Reported U.S.–Iran de-escalation reduced immediate fears of a prolonged conflict and major disruption in the Strait of Hormuz. (Reuters)
Risk remains The ceasefire and diplomatic progress remain fragile, and markets could react quickly if tensions escalate again. (Reuters) Overall sentiment for Monday Bullish factors
✅ Reduced geopolitical stress
✅ Stable oil prices
✅ Strong long-term AI infrastructure demand
Bearish factors
⚠️ Continued valuation pressure on AI leaders
⚠️ Higher-for-longer rate concerns
⚠️ Profit-taking after a very strong first half for semiconductor stocks
The backdrop into Monday is moderately constructive for U.S. AI stocks because easing geopolitical tensions and relatively contained oil prices support risk appetite. However, the market's focus is shifting from geopolitical headlines back to Fed expectations, labor-market data, and the sustainability of AI capital spending, which are likely to determine whether the AI sector can regain momentum later in the week.
1
2.9k
·
--
Мақала
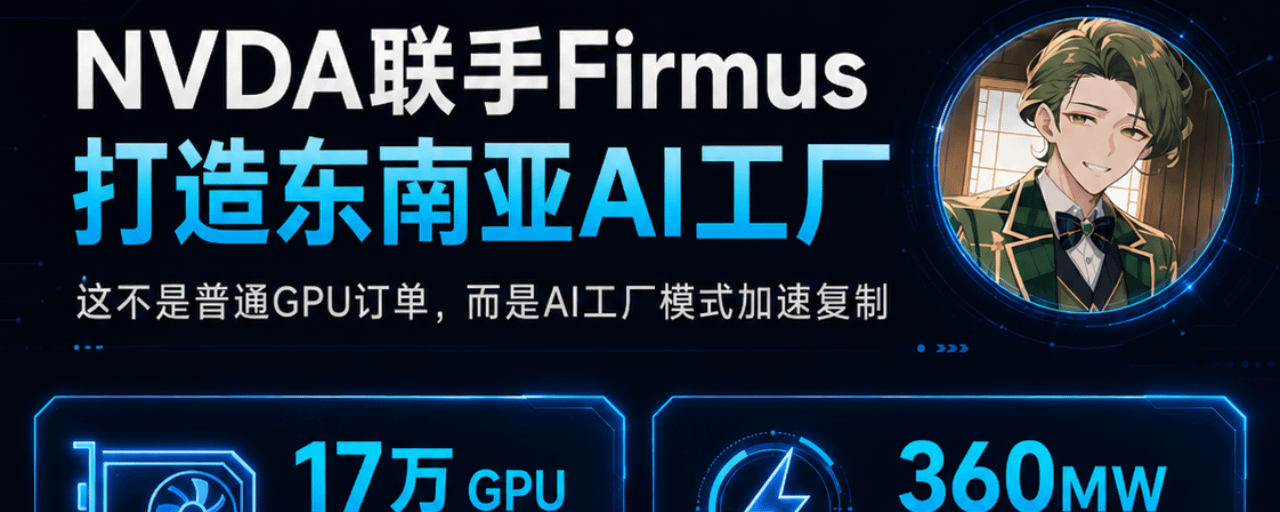
澳大利亚人工智能基础设施公司Firmus Technologies周一表示,已与英伟达公司(NVDA.O)签署战略合作协议Firmus 将在印尼巴淡岛建设 360MW NVIDIA DSX AI Factory,协议覆盖最多 17 万个 NVIDIA AI 加速器,包括 Grace Blackwell、Vera Rubin、Vera 等平台,交付时间集中在 2027 到 2028 年。
Firmus 预计,基于现有客户承购承诺,前 6 年可能带来 250 到 300 亿美元收入
AI 算力正在从“巨头自建”走向“区域 AI 工厂批发零售模式”。
以前只有 Microsoft、Meta、Google、Amazon 这种巨头,能以最低成本拿到顶级 GPU 和基础设施。
现在 NVIDIA 正在通过 Firmus 这种 AI Factory 运营商,把顶级算力开放给 AI Native 公司、企业客户和中小型 AI 开发商。
这背后是一个很大的商业模式变化。
NVIDIA 不只是卖芯片给 Firmus。
Firmus 买 NVIDIA 基础设施,再向客户销售 NVIDIA-powered cloud services。
NVIDIA 除了拿产品收入,还能分享一部分云服务收入。
也就是说,NVIDIA 正在从一次性硬件收入,延伸到 usage-linked revenue。
这很像 NVIDIA 版的“AI 工厂授权 + 收入分成”。
它真正想做的不是卖更多 GPU,而是让全球越来越多 AI 数据中心按照 NVIDIA DSX 标准来建设。
DSX 的意义在于,它不是单个芯片规格,而是一整套 AI 工厂蓝图。
计算
网络
存储
液冷
电力
软件
设施级集成
未来如果越来越多 #Firmus、#Naver Cloud、#SHAZ 这类区域 AI 云厂商采用 DSX,NVIDIA 的生态锁定会越来越强。
客户买的就不只是 GPU,而是一整套 AI 工厂架构。
第一,最直接利好 NVDA。
17 万 GPU / AI 加速器交付,加上云服务收入分成,说明 NVIDIA 的商业模式还在进化。
第二,利好 MRVL 和 AVGO
AI 工厂越多,数据搬运、CXL、SerDes、光互联、交换芯片、自研 ASIC 的需求越强
GPU 只是大脑,网络和内存决定这个大脑能不能高效运转
第三,利好 MU / DRAM
17 万级别 GPU 集群意味着更大的 HBM、DRAM、NAND、企业 SSD 需求
AI 工厂不是只吃 GPU,也会吃掉整个 memory stack。
第四,利好 VRT、ETN、PWR、FIX
360MW 液冷 AI 工厂,本质上是电力、液冷、配电、机柜、工程能力的超级订单池。
AI 基建越大,卖铲子的确定性越高。
第五,利好 LITE、COHR、AAOI、NOK、CIEN、ANET
AI 工厂扩张之后,数据中心内部和数据中心之间的数据搬运会继续暴涨。
1.6T 光模块、激光器、光传输、DCI、以太网交换都会受益。
这条新闻的精华是,AI 基建正在进入“工厂化复制”阶段。
第一阶段,市场只看谁买 GPU。
第二阶段,市场开始看谁能把 GPU 变成低成本、可规模化、可盈利的 AI 工厂。
第三阶段,真正值钱的公司会是那些控制 AI 工厂标准、供应链、能源、网络和客户入口的公司。
NVIDIA 现在明显不想只做第一层。
它要做 AI 工厂时代的标准制定者。
说明 AI 算力正在从巨头专属资源,变成全球化、工厂化、标准化的基础设施。
最直接利好 NVDA。
中长期利好 $MRVL、 $AVGO、 $MU、 $VRT、 $ETN、 $PWR、 $LITE、 $COHR、 $NOK、 $CIEN。
对 $SHAZ 这种 neocloud 来说,是赛道验证,也是竞争提醒
数据中心我已经上了一部分仓位给 $SHAZ ,属于高弹性彩票系列
澳大利亚人工智能基础设施公司Firmus Technologies周一表示,已与英伟达公司(NVDA.O)签署战略合作协议
Firmus 将在印尼巴淡岛建设 360MW NVIDIA DSX AI Factory,协议覆盖最多 17 万个 NVIDIA AI 加速器,包括 Grace Blackwell、Vera Rubin、Vera 等平台,交付时间集中在 2027 到 2028 年。
Firmus 预计,基于现有客户承购承诺,前 6 年可能带来 250 到 300 亿美元收入
AI 算力正在从“巨头自建”走向“区域 AI 工厂批发零售模式”。
以前只有 Microsoft、Meta、Google、Amazon 这种巨头,能以最低成本拿到顶级 GPU 和基础设施。
现在 NVIDIA 正在通过 Firmus 这种 AI Factory 运营商,把顶级算力开放给 AI Native 公司、企业客户和中小型 AI 开发商。
这背后是一个很大的商业模式变化。
NVIDIA 不只是卖芯片给 Firmus。
Firmus 买 NVIDIA 基础设施,再向客户销售 NVIDIA-powered cloud services。
NVIDIA 除了拿产品收入,还能分享一部分云服务收入。
也就是说,NVIDIA 正在从一次性硬件收入,延伸到 usage-linked revenue。
这很像 NVIDIA 版的“AI 工厂授权 + 收入分成”。
它真正想做的不是卖更多 GPU,而是让全球越来越多 AI 数据中心按照 NVIDIA DSX 标准来建设。
DSX 的意义在于,它不是单个芯片规格,而是一整套 AI 工厂蓝图。
计算
网络
存储
液冷
电力
软件
设施级集成
未来如果越来越多 #Firmus、#Naver Cloud、#SHAZ 这类区域 AI 云厂商采用 DSX,NVIDIA 的生态锁定会越来越强。
客户买的就不只是 GPU,而是一整套 AI 工厂架构。
第一,最直接利好 NVDA。
17 万 GPU / AI 加速器交付,加上云服务收入分成,说明 NVIDIA 的商业模式还在进化。
第二,利好 MRVL 和 AVGO
AI 工厂越多,数据搬运、CXL、SerDes、光互联、交换芯片、自研 ASIC 的需求越强
GPU 只是大脑,网络和内存决定这个大脑能不能高效运转
第三,利好 MU / DRAM
17 万级别 GPU 集群意味着更大的 HBM、DRAM、NAND、企业 SSD 需求
AI 工厂不是只吃 GPU,也会吃掉整个 memory stack。
第四,利好 VRT、ETN、PWR、FIX
360MW 液冷 AI 工厂,本质上是电力、液冷、配电、机柜、工程能力的超级订单池。
AI 基建越大,卖铲子的确定性越高。
第五,利好 LITE、COHR、AAOI、NOK、CIEN、ANET
AI 工厂扩张之后,数据中心内部和数据中心之间的数据搬运会继续暴涨。
1.6T 光模块、激光器、光传输、DCI、以太网交换都会受益。
这条新闻的精华是,AI 基建正在进入“工厂化复制”阶段。
第一阶段,市场只看谁买 GPU。
第二阶段,市场开始看谁能把 GPU 变成低成本、可规模化、可盈利的 AI 工厂。
第三阶段,真正值钱的公司会是那些控制 AI 工厂标准、供应链、能源、网络和客户入口的公司。
NVIDIA 现在明显不想只做第一层。
它要做 AI 工厂时代的标准制定者。
说明 AI 算力正在从巨头专属资源,变成全球化、工厂化、标准化的基础设施。
最直接利好 NVDA。
中长期利好 $MRVL、 $AVGO、 $MU、 $VRT、 $ETN、 $PWR、 $LITE、 $COHR、 $NOK、 $CIEN。
对 $SHAZ 这种 neocloud 来说,是赛道验证,也是竞争提醒
数据中心我已经上了一部分仓位给 $SHAZ ,属于高弹性彩票系列
Firmus 预计,基于现有客户承购承诺,前 6 年可能带来 250 到 300 亿美元收入
AI 算力正在从“巨头自建”走向“区域 AI 工厂批发零售模式”。
以前只有 Microsoft、Meta、Google、Amazon 这种巨头,能以最低成本拿到顶级 GPU 和基础设施。
现在 NVIDIA 正在通过 Firmus 这种 AI Factory 运营商,把顶级算力开放给 AI Native 公司、企业客户和中小型 AI 开发商。
这背后是一个很大的商业模式变化。
NVIDIA 不只是卖芯片给 Firmus。
Firmus 买 NVIDIA 基础设施,再向客户销售 NVIDIA-powered cloud services。
NVIDIA 除了拿产品收入,还能分享一部分云服务收入。
也就是说,NVIDIA 正在从一次性硬件收入,延伸到 usage-linked revenue。
这很像 NVIDIA 版的“AI 工厂授权 + 收入分成”。
它真正想做的不是卖更多 GPU,而是让全球越来越多 AI 数据中心按照 NVIDIA DSX 标准来建设。
DSX 的意义在于,它不是单个芯片规格,而是一整套 AI 工厂蓝图。
计算
网络
存储
液冷
电力
软件
设施级集成
未来如果越来越多 #Firmus、#Naver Cloud、#SHAZ 这类区域 AI 云厂商采用 DSX,NVIDIA 的生态锁定会越来越强。
客户买的就不只是 GPU,而是一整套 AI 工厂架构。
第一,最直接利好 NVDA。
17 万 GPU / AI 加速器交付,加上云服务收入分成,说明 NVIDIA 的商业模式还在进化。
第二,利好 MRVL 和 AVGO
AI 工厂越多,数据搬运、CXL、SerDes、光互联、交换芯片、自研 ASIC 的需求越强
GPU 只是大脑,网络和内存决定这个大脑能不能高效运转
第三,利好 MU / DRAM
17 万级别 GPU 集群意味着更大的 HBM、DRAM、NAND、企业 SSD 需求
AI 工厂不是只吃 GPU,也会吃掉整个 memory stack。
第四,利好 VRT、ETN、PWR、FIX
360MW 液冷 AI 工厂,本质上是电力、液冷、配电、机柜、工程能力的超级订单池。
AI 基建越大,卖铲子的确定性越高。
第五,利好 LITE、COHR、AAOI、NOK、CIEN、ANET
AI 工厂扩张之后,数据中心内部和数据中心之间的数据搬运会继续暴涨。
1.6T 光模块、激光器、光传输、DCI、以太网交换都会受益。
这条新闻的精华是,AI 基建正在进入“工厂化复制”阶段。
第一阶段,市场只看谁买 GPU。
第二阶段,市场开始看谁能把 GPU 变成低成本、可规模化、可盈利的 AI 工厂。
第三阶段,真正值钱的公司会是那些控制 AI 工厂标准、供应链、能源、网络和客户入口的公司。
NVIDIA 现在明显不想只做第一层。
它要做 AI 工厂时代的标准制定者。
说明 AI 算力正在从巨头专属资源,变成全球化、工厂化、标准化的基础设施。
最直接利好 NVDA。
中长期利好 $MRVL、 $AVGO、 $MU、 $VRT、 $ETN、 $PWR、 $LITE、 $COHR、 $NOK、 $CIEN。
对 $SHAZ 这种 neocloud 来说,是赛道验证,也是竞争提醒
数据中心我已经上了一部分仓位给 $SHAZ ,属于高弹性彩票系列
4
5.8k
·
--
Мақала
AI 时代,内存墙正在变成和光互联一样重要的基础设施瓶颈!而 #Marvell 正在同时布局这两堵墙过去大家看 Marvell,第一反应是 AI ASIC、光互联、SerDes、DSP、硅光、DCI。
但这次 Structera X 和 Structera A 的重点,是把 MRVL 拉进了 AI 内存瓶颈这条主线。
现在 AI 数据中心最贵的东西不只是 GPU。
内存也越来越贵。
长上下文、多智能体、推理服务、向量数据库、in-memory database、推荐模型,这些场景都在疯狂吃 DRAM。
GPU 负责计算。
Memory 负责记忆。
光互联负责数据搬运。
如果内存不够,GPU 再强也会被卡住
这就是 MRVL 这次 CXL 方案的意义
Structera X 和 Structera A 的核心,不是简单加一块内存控制器,而是通过 CXL 把服务器外部 DRAM 接入进来,再用硬件内联压缩,把每 1GB 物理内存变成更多可用容量。
官方数据里,数据库类数据压缩率最高可以达到 3.64x。
XML 大约 2.75x。
源代码大约 2.0x。
当然,这不是说所有数据都能 1GB 变 3.64GB。
压缩率取决于数据类型。
但重点是:
如果 hyperscaler 能把一部分可压缩数据通过硬件压缩提高有效内存容量,那就相当于在不增加太多 DRAM 采购的情况下,缓解内存短缺和成本压力。
这件事对云厂商非常有吸引力。
因为现在服务器级 DDR5 RDIMM 已经很贵。
一个 12TB 内存池,单 DRAM 成本就可能接近 50 万美元。
当 AI 基建扩张速度快过晶圆厂供给速度,内存就不再是普通配件,而是战略资源。
这和美光最近财报透露出来的逻辑是同一条线。
AI 正在把存储和内存从周期品,重新定价成基础设施瓶颈。
$MU 解决的是 HBM、DRAM、NAND 的供给问题。
$MRVL 这次解决的是:
当内存越来越贵,如何让每一 GB 更值钱。
这就是 Structera 的真正看点。
Structera X 更像内存扩展控制器。
它解决的是服务器内存池怎么变大。
Structera A 更像近内存计算加速器。
它解决的是一些内存带宽受限任务,能不能把计算搬到内存附近。
大白话说:
X 负责扩容。
A 负责加速。
两者共同解决 AI 时代的数据中心内存墙。
因为 Structera 产品线不是今天第一次出现,最早 2024 年就已经发布。
这次更像是 Marvell 把“CXL + 硬件压缩”的经济价值重新推到台前。
所以短线它不是传统意义上的订单利好。
但中长期,它对 MRVL 的叙事非常重要。
因为 MRVL 的 AI 基建拼图越来越完整了
第一块是 custom ASIC。
解决 AI 计算效率
第二块是光互联和 coherent DCI。
解决 AI 数据搬运。
第三块是 CXL 和 memory expansion。
解决 AI 内存墙。
如果再加上 Celestial AI 的 photonic fabric,Marvell 其实正在往一个方向走:
它不只是卖单点芯片。
它想成为 AI 数据基础设施的核心半导体平台。
这点非常关键。
AI 基建的下一阶段,不会只看谁能提供 GPU。
而是看谁能解决系统级瓶颈。
计算瓶颈
内存瓶颈
网络瓶颈
功耗瓶颈
数据中心越大,瓶颈越多。
而 MRVL 正好卡在很多瓶颈之间。
它说明 Marvell 不只是光互联受益者,也不是纯 ASIC 受益者。
它还在内存架构层面抢位置。
如果未来 CXL memory pooling、CXL expansion、near-memory compute 成为 hyperscaler 的标准架构,Structera 会是一条非常有想象力的产品线。
风险在于:
第一,这条消息目前更多是技术和产品叙事,不是新增大订单公告。
第二,CXL 的大规模部署还需要客户验证、生态成熟和软件适配。
第三,压缩率不是所有场景都能达到 3.64x,实际效果要看 workload。
第四,MRVL 现在估值已经不低,市场需要看到这些产品最终进入财报,而不是只停留在技术故事。
如果被 hyperscaler 大规模采用,意义会很大。
它真正强化的是一个判断:
AI 时代,内存墙正在变成和光互联一样重要的基础设施瓶颈。
而 Marvell 正在同时布局这两堵墙。
这不是“1GB 变 3.64GB”的噱头。
这是 MRVL 在 AI memory wall 方向的一次战略补位。
如果 AI 计算继续扩张,未来最值钱的公司,不只是卖算力的公司。
也包括那些能让算力不被内存、网络和数据搬运拖死的公司。
$MRVL 正在往这个位置靠。
AI 时代,内存墙正在变成和光互联一样重要的基础设施瓶颈!而 #Marvell 正在同时布局这两堵墙
过去大家看 Marvell,第一反应是 AI ASIC、光互联、SerDes、DSP、硅光、DCI。
但这次 Structera X 和 Structera A 的重点,是把 MRVL 拉进了 AI 内存瓶颈这条主线。
现在 AI 数据中心最贵的东西不只是 GPU。
内存也越来越贵。
长上下文、多智能体、推理服务、向量数据库、in-memory database、推荐模型,这些场景都在疯狂吃 DRAM。
GPU 负责计算。
Memory 负责记忆。
光互联负责数据搬运。
如果内存不够,GPU 再强也会被卡住
这就是 MRVL 这次 CXL 方案的意义
Structera X 和 Structera A 的核心,不是简单加一块内存控制器,而是通过 CXL 把服务器外部 DRAM 接入进来,再用硬件内联压缩,把每 1GB 物理内存变成更多可用容量。
官方数据里,数据库类数据压缩率最高可以达到 3.64x。
XML 大约 2.75x。
源代码大约 2.0x。
当然,这不是说所有数据都能 1GB 变 3.64GB。
压缩率取决于数据类型。
但重点是:
如果 hyperscaler 能把一部分可压缩数据通过硬件压缩提高有效内存容量,那就相当于在不增加太多 DRAM 采购的情况下,缓解内存短缺和成本压力。
这件事对云厂商非常有吸引力。
因为现在服务器级 DDR5 RDIMM 已经很贵。
一个 12TB 内存池,单 DRAM 成本就可能接近 50 万美元。
当 AI 基建扩张速度快过晶圆厂供给速度,内存就不再是普通配件,而是战略资源。
这和美光最近财报透露出来的逻辑是同一条线。
AI 正在把存储和内存从周期品,重新定价成基础设施瓶颈。
$MU 解决的是 HBM、DRAM、NAND 的供给问题。
$MRVL 这次解决的是:
当内存越来越贵,如何让每一 GB 更值钱。
这就是 Structera 的真正看点。
Structera X 更像内存扩展控制器。
它解决的是服务器内存池怎么变大。
Structera A 更像近内存计算加速器。
它解决的是一些内存带宽受限任务,能不能把计算搬到内存附近。
大白话说:
X 负责扩容。
A 负责加速。
两者共同解决 AI 时代的数据中心内存墙。
因为 Structera 产品线不是今天第一次出现,最早 2024 年就已经发布。
这次更像是 Marvell 把“CXL + 硬件压缩”的经济价值重新推到台前。
所以短线它不是传统意义上的订单利好。
但中长期,它对 MRVL 的叙事非常重要。
因为 MRVL 的 AI 基建拼图越来越完整了
第一块是 custom ASIC。
解决 AI 计算效率
第二块是光互联和 coherent DCI。
解决 AI 数据搬运。
第三块是 CXL 和 memory expansion。
解决 AI 内存墙。
如果再加上 Celestial AI 的 photonic fabric,Marvell 其实正在往一个方向走:
它不只是卖单点芯片。
它想成为 AI 数据基础设施的核心半导体平台。
这点非常关键。
AI 基建的下一阶段,不会只看谁能提供 GPU。
而是看谁能解决系统级瓶颈。
计算瓶颈
内存瓶颈
网络瓶颈
功耗瓶颈
数据中心越大,瓶颈越多。
而 MRVL 正好卡在很多瓶颈之间。
它说明 Marvell 不只是光互联受益者,也不是纯 ASIC 受益者。
它还在内存架构层面抢位置。
如果未来 CXL memory pooling、CXL expansion、near-memory compute 成为 hyperscaler 的标准架构,Structera 会是一条非常有想象力的产品线。
风险在于:
第一,这条消息目前更多是技术和产品叙事,不是新增大订单公告。
第二,CXL 的大规模部署还需要客户验证、生态成熟和软件适配。
第三,压缩率不是所有场景都能达到 3.64x,实际效果要看 workload。
第四,MRVL 现在估值已经不低,市场需要看到这些产品最终进入财报,而不是只停留在技术故事。
如果被 hyperscaler 大规模采用,意义会很大。
它真正强化的是一个判断:
AI 时代,内存墙正在变成和光互联一样重要的基础设施瓶颈。
而 Marvell 正在同时布局这两堵墙。
这不是“1GB 变 3.64GB”的噱头。
这是 MRVL 在 AI memory wall 方向的一次战略补位。
如果 AI 计算继续扩张,未来最值钱的公司,不只是卖算力的公司。
也包括那些能让算力不被内存、网络和数据搬运拖死的公司。
$MRVL 正在往这个位置靠。
但这次 Structera X 和 Structera A 的重点,是把 MRVL 拉进了 AI 内存瓶颈这条主线。
现在 AI 数据中心最贵的东西不只是 GPU。
内存也越来越贵。
长上下文、多智能体、推理服务、向量数据库、in-memory database、推荐模型,这些场景都在疯狂吃 DRAM。
GPU 负责计算。
Memory 负责记忆。
光互联负责数据搬运。
如果内存不够,GPU 再强也会被卡住
这就是 MRVL 这次 CXL 方案的意义
Structera X 和 Structera A 的核心,不是简单加一块内存控制器,而是通过 CXL 把服务器外部 DRAM 接入进来,再用硬件内联压缩,把每 1GB 物理内存变成更多可用容量。
官方数据里,数据库类数据压缩率最高可以达到 3.64x。
XML 大约 2.75x。
源代码大约 2.0x。
当然,这不是说所有数据都能 1GB 变 3.64GB。
压缩率取决于数据类型。
但重点是:
如果 hyperscaler 能把一部分可压缩数据通过硬件压缩提高有效内存容量,那就相当于在不增加太多 DRAM 采购的情况下,缓解内存短缺和成本压力。
这件事对云厂商非常有吸引力。
因为现在服务器级 DDR5 RDIMM 已经很贵。
一个 12TB 内存池,单 DRAM 成本就可能接近 50 万美元。
当 AI 基建扩张速度快过晶圆厂供给速度,内存就不再是普通配件,而是战略资源。
这和美光最近财报透露出来的逻辑是同一条线。
AI 正在把存储和内存从周期品,重新定价成基础设施瓶颈。
$MU 解决的是 HBM、DRAM、NAND 的供给问题。
$MRVL 这次解决的是:
当内存越来越贵,如何让每一 GB 更值钱。
这就是 Structera 的真正看点。
Structera X 更像内存扩展控制器。
它解决的是服务器内存池怎么变大。
Structera A 更像近内存计算加速器。
它解决的是一些内存带宽受限任务,能不能把计算搬到内存附近。
大白话说:
X 负责扩容。
A 负责加速。
两者共同解决 AI 时代的数据中心内存墙。
因为 Structera 产品线不是今天第一次出现,最早 2024 年就已经发布。
这次更像是 Marvell 把“CXL + 硬件压缩”的经济价值重新推到台前。
所以短线它不是传统意义上的订单利好。
但中长期,它对 MRVL 的叙事非常重要。
因为 MRVL 的 AI 基建拼图越来越完整了
第一块是 custom ASIC。
解决 AI 计算效率
第二块是光互联和 coherent DCI。
解决 AI 数据搬运。
第三块是 CXL 和 memory expansion。
解决 AI 内存墙。
如果再加上 Celestial AI 的 photonic fabric,Marvell 其实正在往一个方向走:
它不只是卖单点芯片。
它想成为 AI 数据基础设施的核心半导体平台。
这点非常关键。
AI 基建的下一阶段,不会只看谁能提供 GPU。
而是看谁能解决系统级瓶颈。
计算瓶颈
内存瓶颈
网络瓶颈
功耗瓶颈
数据中心越大,瓶颈越多。
而 MRVL 正好卡在很多瓶颈之间。
它说明 Marvell 不只是光互联受益者,也不是纯 ASIC 受益者。
它还在内存架构层面抢位置。
如果未来 CXL memory pooling、CXL expansion、near-memory compute 成为 hyperscaler 的标准架构,Structera 会是一条非常有想象力的产品线。
风险在于:
第一,这条消息目前更多是技术和产品叙事,不是新增大订单公告。
第二,CXL 的大规模部署还需要客户验证、生态成熟和软件适配。
第三,压缩率不是所有场景都能达到 3.64x,实际效果要看 workload。
第四,MRVL 现在估值已经不低,市场需要看到这些产品最终进入财报,而不是只停留在技术故事。
如果被 hyperscaler 大规模采用,意义会很大。
它真正强化的是一个判断:
AI 时代,内存墙正在变成和光互联一样重要的基础设施瓶颈。
而 Marvell 正在同时布局这两堵墙。
这不是“1GB 变 3.64GB”的噱头。
这是 MRVL 在 AI memory wall 方向的一次战略补位。
如果 AI 计算继续扩张,未来最值钱的公司,不只是卖算力的公司。
也包括那些能让算力不被内存、网络和数据搬运拖死的公司。
$MRVL 正在往这个位置靠。
3
3.9k
·
--
Мақала
AI 时代的记忆能力,正在变得和计算能力一样重要。如果 GPU 是大脑的算力,那么 memory 就是大脑的记忆。没有记忆,再强的 AI 也跑不远。存储为王!昨晚美光 $MU 业绩几乎交了满分答案!
$MU 这份财报,它重新定义了存储行业。
AI 时代,存储不再只是配套零件,而是算力系统的核心资源。
Q3 数字已经很夸张。
营收 414.6 亿美元。
Non-GAAP EPS 25.11 美元。
毛利率接近 85%。
Q4 指引更猛。
营收指引 490 到 510 亿美元。
Non-GAAP EPS 指引 30 到 32 美元。
毛利率指引约 86%。
这已经不是小幅超预期,而是直接把华尔街模型往上推了一大截。
这份财报最值得看的,不是数字本身,而是数字背后的行业变化。
第一,存储正在从周期品变成 AI 基建的稀缺资源。
过去市场看 DRAM 和 NAND,逻辑很简单。
涨价周期来了,利润暴涨。
扩产太多,价格崩掉。
然后再等下一轮周期。
但这次不一样。
AI 把存储需求的结构改了。
以前大家觉得 AI 基建最重要的是 GPU。
现在越来越清楚,GPU 只是计算核心,内存和存储决定系统能不能真正跑起来。
Agentic AI、多智能体、长上下文、推理负载、数据缓存、向量数据库、模型服务,这些东西都会持续吃掉内存和存储。
AI 不是只增加 HBM 需求。
AI 也在增加 data center DRAM、enterprise SSD、NAND、LPDRAM、CXL memory、服务器内存模组的需求。
这就是为什么美光管理层反复强调:
内存已经成为 AI 时代的战略资产。
这个说法很关键。
战略资产和普通商品不一样。
普通商品看价格。
战略资产看供给安全、长期合作、产能锁定和客户关系。
第二,客户已经开始用长约锁供应。
这次最容易被低估的点,是 Micron 的 Strategic Customer Agreements。
公司披露已经签了 16 份 SCA,覆盖数据中心、消费电子、汽车等市场。
这些协议不是普通意向订单。
它们带有 take-or-pay 结构。
简单说就是客户锁定供应,不买也要承担相应义务。
更重要的是,这些协议还包含现金押金、价格下限和长期供货安排。
过去存储行业最大的缺点,是客户太灵活,价格太周期。
需求好时大家抢货。
需求差时客户马上砍单。
但 SCA 出现后,美光的商业模式开始变得不一样。
收入可见度更高。
价格保护更强。
客户关系更深。
产能利用率更稳。
这不是简单多了几份合同。
这是存储行业从短周期现货交易,逐步走向长期基础设施供应模式。
如果这个趋势持续,市场给 MU 的估值方式也会变。
以前是周期 PE。
未来可能会往 AI 基建核心供应商重新定价。
第三,供给端不是想扩就能扩。
这轮多头逻辑最核心的支撑,不只是需求强,而是供给跟不上。
HBM 会吞噬大量 DRAM wafer capacity。
先进 DRAM 节点越来越难。
新 fab 建设周期很长。
先进封装和测试也不是一夜之间能补齐。
NAND 那边也一样,过去几年行业被低价折磨太久,厂商不可能马上疯狂扩产。
甚至部分 NAND 资源还可能被重新分配给 DRAM 方向。
这就是为什么管理层说,目前看不到供应什么时候能追上需求。
它的含义不是短期缺货,而是结构性紧缺。
如果供应紧张真的延续到 2027 年以后,那 MU 的定价能力和利润率可能会比市场想象得更持久。
第四,HBM4 是下一阶段胜负手。
这份财报里,HBM4 的信息非常关键。
美光说 HBM4 已经在 lead customer 平台高量出货,同时也已经向多个终端客户送出认证样品。
HBM4E 也在推进,预计 2027 年量产。
这说明 MU 不是只靠 HBM3E 吃一轮景气,它已经在往下一代产品迁移。
这点非常重要。
HBM 是 AI memory trade 的估值核心。
如果 MU 在 HBM4 这一代继续保持客户认证、供货节奏和良率优势,那市场会继续把它当 AI 核心链条,而不是普通 DRAM 公司。
反过来,如果 HBM4 节奏不顺,估值就会被重新压回周期股。
所以后面最该盯的不是一句“需求强劲”,而是:
HBM4 良率。
客户认证进度。
2027 年订单可见度。
HBM4E 量产时间。
和 #NVIDIA、#ASIC 客户、云厂商的绑定深度。
第五,非 HBM 业务也在被 AI 拉动。
很多人只看 HBM,但这次更大的变化是:
普通 DRAM 和 NAND 也开始受益。
数据中心不只需要 GPU 节点,还需要 CPU 服务器、存储服务器、缓存层、数据库、企业 SSD、冷数据和热数据分层。
AI 推理越来越多后,内存压力不只集中在训练集群。
边缘推理、企业私有 AI、机器人、自动驾驶、AI PC、手机端大模型都会带来新的存储需求。
汽车这条线也值得看。
L2+ 车型需要更多 #DRAM 和 #NAND。
robotaxi 需要更高可靠性和更高容量。
机器人未来如果放量,存储需求可能比现在市场建模更大。
这就是为什么我觉得 MU 的故事不是单一 HBM,而是整个 memory stack 被 AI 重新定价。
第六,CapEx 是最大分歧。
多头看到的是供给紧缺。
空头看到的是资本开支上升。
这次美光 Q3 资本开支已经超过 70 亿美元,Q4 还要继续往上走,2027 年每季度 capex 可能比 Q4 更高。
这就是未来最大的争议点。
如果这些钱主要投向 HBM、先进 DRAM、先进封装、cleanroom 和高价值客户锁定产能,市场会把它理解成高回报投资。
但如果行业所有玩家都开始扩产,几年后还是可能重新走向供给过剩。
所以 MU 后面最大的风险,不是需求明天突然消失,而是供给纪律被高利润诱惑打破。
这也是为什么我不会说存储行业从此没有周期。
更准确地说:
周期还在,但周期的形态变了。
以前是价格周期主导。
以后可能是 AI 长约、先进制程、HBM 产能、客户绑定、资本开支纪律共同决定周期。
第七,这份财报对整个 AI 链条也有启示
如果 MU 的说法成立,那 AI 投资逻辑要重新排序。
过去大家习惯把 AI 链条分成:
GPU 第一
网络第二。
应用第三
但现在可能要改成:
算力和内存一起构成第一层
光互联和网络构成第二层
电力、散热、封装、材料构成第三层
应用放在更后面
因为 AI 系统真正的瓶颈,不是单点算力,而是系统级吞吐
GPU 再强,如果 HBM 不够,DRAM 不够,SSD 不够,数据搬不动,整个系统效率都会掉下来。
所以我现在更倾向于把 AI 基建看成一套系统:
计算负责推理。
内存负责上下文。
存储负责数据。
光互联负责搬运。
电力散热负责承载。
任何一环紧缺,都会变成利润池。
MU 这份财报的意义就在这里。
它证明存储正在从 AI 配角变成 AI 基础设施的主角之一。
这份财报不是普通 beat。
它更像是存储行业的一次身份切换。
从周期品,走向战略资源。
从现货波动,走向长约锁供。
从单纯涨价,走向 AI 需求驱动的结构性紧缺。
从普通 DRAM 公司,走向 AI memory infrastructure 公司。
当然,风险也很清楚。
第一,股价已经涨很多,预期极高。
第二,毛利率已经非常高,后面每一步都要继续证明可持续。
第三,CapEx 增长会让市场担心下一轮供给过剩。
第四,一旦客户需求放缓,或者供应缓解,定价权会最先被质疑。
但至少这一次,MU 给出的答案非常强。
强业绩
强指引
强毛利
强 HBM4 进展
强客户长约
强供需紧缺叙事
AI 时代的记忆能力,正在变得和计算能力一样重要。
如果 GPU 是大脑的算力,那么 memory 就是大脑的记忆。
没有记忆,再强的 AI 也跑不远。
AI 时代的记忆能力,正在变得和计算能力一样重要。如果 GPU 是大脑的算力,那么 memory 就是大脑的记忆。没有记忆,再强的 AI 也跑不远。
存储为王!昨晚美光 $MU 业绩几乎交了满分答案!
$MU 这份财报,它重新定义了存储行业。
AI 时代,存储不再只是配套零件,而是算力系统的核心资源。
Q3 数字已经很夸张。
营收 414.6 亿美元。
Non-GAAP EPS 25.11 美元。
毛利率接近 85%。
Q4 指引更猛。
营收指引 490 到 510 亿美元。
Non-GAAP EPS 指引 30 到 32 美元。
毛利率指引约 86%。
这已经不是小幅超预期,而是直接把华尔街模型往上推了一大截。
这份财报最值得看的,不是数字本身,而是数字背后的行业变化。
第一,存储正在从周期品变成 AI 基建的稀缺资源。
过去市场看 DRAM 和 NAND,逻辑很简单。
涨价周期来了,利润暴涨。
扩产太多,价格崩掉。
然后再等下一轮周期。
但这次不一样。
AI 把存储需求的结构改了。
以前大家觉得 AI 基建最重要的是 GPU。
现在越来越清楚,GPU 只是计算核心,内存和存储决定系统能不能真正跑起来。
Agentic AI、多智能体、长上下文、推理负载、数据缓存、向量数据库、模型服务,这些东西都会持续吃掉内存和存储。
AI 不是只增加 HBM 需求。
AI 也在增加 data center DRAM、enterprise SSD、NAND、LPDRAM、CXL memory、服务器内存模组的需求。
这就是为什么美光管理层反复强调:
内存已经成为 AI 时代的战略资产。
这个说法很关键。
战略资产和普通商品不一样。
普通商品看价格。
战略资产看供给安全、长期合作、产能锁定和客户关系。
第二,客户已经开始用长约锁供应。
这次最容易被低估的点,是 Micron 的 Strategic Customer Agreements。
公司披露已经签了 16 份 SCA,覆盖数据中心、消费电子、汽车等市场。
这些协议不是普通意向订单。
它们带有 take-or-pay 结构。
简单说就是客户锁定供应,不买也要承担相应义务。
更重要的是,这些协议还包含现金押金、价格下限和长期供货安排。
过去存储行业最大的缺点,是客户太灵活,价格太周期。
需求好时大家抢货。
需求差时客户马上砍单。
但 SCA 出现后,美光的商业模式开始变得不一样。
收入可见度更高。
价格保护更强。
客户关系更深。
产能利用率更稳。
这不是简单多了几份合同。
这是存储行业从短周期现货交易,逐步走向长期基础设施供应模式。
如果这个趋势持续,市场给 MU 的估值方式也会变。
以前是周期 PE。
未来可能会往 AI 基建核心供应商重新定价。
第三,供给端不是想扩就能扩。
这轮多头逻辑最核心的支撑,不只是需求强,而是供给跟不上。
HBM 会吞噬大量 DRAM wafer capacity。
先进 DRAM 节点越来越难。
新 fab 建设周期很长。
先进封装和测试也不是一夜之间能补齐。
NAND 那边也一样,过去几年行业被低价折磨太久,厂商不可能马上疯狂扩产。
甚至部分 NAND 资源还可能被重新分配给 DRAM 方向。
这就是为什么管理层说,目前看不到供应什么时候能追上需求。
它的含义不是短期缺货,而是结构性紧缺。
如果供应紧张真的延续到 2027 年以后,那 MU 的定价能力和利润率可能会比市场想象得更持久。
第四,HBM4 是下一阶段胜负手。
这份财报里,HBM4 的信息非常关键。
美光说 HBM4 已经在 lead customer 平台高量出货,同时也已经向多个终端客户送出认证样品。
HBM4E 也在推进,预计 2027 年量产。
这说明 MU 不是只靠 HBM3E 吃一轮景气,它已经在往下一代产品迁移。
这点非常重要。
HBM 是 AI memory trade 的估值核心。
如果 MU 在 HBM4 这一代继续保持客户认证、供货节奏和良率优势,那市场会继续把它当 AI 核心链条,而不是普通 DRAM 公司。
反过来,如果 HBM4 节奏不顺,估值就会被重新压回周期股。
所以后面最该盯的不是一句“需求强劲”,而是:
HBM4 良率。
客户认证进度。
2027 年订单可见度。
HBM4E 量产时间。
和 #NVIDIA、#ASIC 客户、云厂商的绑定深度。
第五,非 HBM 业务也在被 AI 拉动。
很多人只看 HBM,但这次更大的变化是:
普通 DRAM 和 NAND 也开始受益。
数据中心不只需要 GPU 节点,还需要 CPU 服务器、存储服务器、缓存层、数据库、企业 SSD、冷数据和热数据分层。
AI 推理越来越多后,内存压力不只集中在训练集群。
边缘推理、企业私有 AI、机器人、自动驾驶、AI PC、手机端大模型都会带来新的存储需求。
汽车这条线也值得看。
L2+ 车型需要更多 #DRAM 和 #NAND。
robotaxi 需要更高可靠性和更高容量。
机器人未来如果放量,存储需求可能比现在市场建模更大。
这就是为什么我觉得 MU 的故事不是单一 HBM,而是整个 memory stack 被 AI 重新定价。
第六,CapEx 是最大分歧。
多头看到的是供给紧缺。
空头看到的是资本开支上升。
这次美光 Q3 资本开支已经超过 70 亿美元,Q4 还要继续往上走,2027 年每季度 capex 可能比 Q4 更高。
这就是未来最大的争议点。
如果这些钱主要投向 HBM、先进 DRAM、先进封装、cleanroom 和高价值客户锁定产能,市场会把它理解成高回报投资。
但如果行业所有玩家都开始扩产,几年后还是可能重新走向供给过剩。
所以 MU 后面最大的风险,不是需求明天突然消失,而是供给纪律被高利润诱惑打破。
这也是为什么我不会说存储行业从此没有周期。
更准确地说:
周期还在,但周期的形态变了。
以前是价格周期主导。
以后可能是 AI 长约、先进制程、HBM 产能、客户绑定、资本开支纪律共同决定周期。
第七,这份财报对整个 AI 链条也有启示
如果 MU 的说法成立,那 AI 投资逻辑要重新排序。
过去大家习惯把 AI 链条分成:
GPU 第一
网络第二。
应用第三
但现在可能要改成:
算力和内存一起构成第一层
光互联和网络构成第二层
电力、散热、封装、材料构成第三层
应用放在更后面
因为 AI 系统真正的瓶颈,不是单点算力,而是系统级吞吐
GPU 再强,如果 HBM 不够,DRAM 不够,SSD 不够,数据搬不动,整个系统效率都会掉下来。
所以我现在更倾向于把 AI 基建看成一套系统:
计算负责推理。
内存负责上下文。
存储负责数据。
光互联负责搬运。
电力散热负责承载。
任何一环紧缺,都会变成利润池。
MU 这份财报的意义就在这里。
它证明存储正在从 AI 配角变成 AI 基础设施的主角之一。
这份财报不是普通 beat。
它更像是存储行业的一次身份切换。
从周期品,走向战略资源。
从现货波动,走向长约锁供。
从单纯涨价,走向 AI 需求驱动的结构性紧缺。
从普通 DRAM 公司,走向 AI memory infrastructure 公司。
当然,风险也很清楚。
第一,股价已经涨很多,预期极高。
第二,毛利率已经非常高,后面每一步都要继续证明可持续。
第三,CapEx 增长会让市场担心下一轮供给过剩。
第四,一旦客户需求放缓,或者供应缓解,定价权会最先被质疑。
但至少这一次,MU 给出的答案非常强。
强业绩
强指引
强毛利
强 HBM4 进展
强客户长约
强供需紧缺叙事
AI 时代的记忆能力,正在变得和计算能力一样重要。
如果 GPU 是大脑的算力,那么 memory 就是大脑的记忆。
没有记忆,再强的 AI 也跑不远。
$MU 这份财报,它重新定义了存储行业。
AI 时代,存储不再只是配套零件,而是算力系统的核心资源。
Q3 数字已经很夸张。
营收 414.6 亿美元。
Non-GAAP EPS 25.11 美元。
毛利率接近 85%。
Q4 指引更猛。
营收指引 490 到 510 亿美元。
Non-GAAP EPS 指引 30 到 32 美元。
毛利率指引约 86%。
这已经不是小幅超预期,而是直接把华尔街模型往上推了一大截。
这份财报最值得看的,不是数字本身,而是数字背后的行业变化。
第一,存储正在从周期品变成 AI 基建的稀缺资源。
过去市场看 DRAM 和 NAND,逻辑很简单。
涨价周期来了,利润暴涨。
扩产太多,价格崩掉。
然后再等下一轮周期。
但这次不一样。
AI 把存储需求的结构改了。
以前大家觉得 AI 基建最重要的是 GPU。
现在越来越清楚,GPU 只是计算核心,内存和存储决定系统能不能真正跑起来。
Agentic AI、多智能体、长上下文、推理负载、数据缓存、向量数据库、模型服务,这些东西都会持续吃掉内存和存储。
AI 不是只增加 HBM 需求。
AI 也在增加 data center DRAM、enterprise SSD、NAND、LPDRAM、CXL memory、服务器内存模组的需求。
这就是为什么美光管理层反复强调:
内存已经成为 AI 时代的战略资产。
这个说法很关键。
战略资产和普通商品不一样。
普通商品看价格。
战略资产看供给安全、长期合作、产能锁定和客户关系。
第二,客户已经开始用长约锁供应。
这次最容易被低估的点,是 Micron 的 Strategic Customer Agreements。
公司披露已经签了 16 份 SCA,覆盖数据中心、消费电子、汽车等市场。
这些协议不是普通意向订单。
它们带有 take-or-pay 结构。
简单说就是客户锁定供应,不买也要承担相应义务。
更重要的是,这些协议还包含现金押金、价格下限和长期供货安排。
过去存储行业最大的缺点,是客户太灵活,价格太周期。
需求好时大家抢货。
需求差时客户马上砍单。
但 SCA 出现后,美光的商业模式开始变得不一样。
收入可见度更高。
价格保护更强。
客户关系更深。
产能利用率更稳。
这不是简单多了几份合同。
这是存储行业从短周期现货交易,逐步走向长期基础设施供应模式。
如果这个趋势持续,市场给 MU 的估值方式也会变。
以前是周期 PE。
未来可能会往 AI 基建核心供应商重新定价。
第三,供给端不是想扩就能扩。
这轮多头逻辑最核心的支撑,不只是需求强,而是供给跟不上。
HBM 会吞噬大量 DRAM wafer capacity。
先进 DRAM 节点越来越难。
新 fab 建设周期很长。
先进封装和测试也不是一夜之间能补齐。
NAND 那边也一样,过去几年行业被低价折磨太久,厂商不可能马上疯狂扩产。
甚至部分 NAND 资源还可能被重新分配给 DRAM 方向。
这就是为什么管理层说,目前看不到供应什么时候能追上需求。
它的含义不是短期缺货,而是结构性紧缺。
如果供应紧张真的延续到 2027 年以后,那 MU 的定价能力和利润率可能会比市场想象得更持久。
第四,HBM4 是下一阶段胜负手。
这份财报里,HBM4 的信息非常关键。
美光说 HBM4 已经在 lead customer 平台高量出货,同时也已经向多个终端客户送出认证样品。
HBM4E 也在推进,预计 2027 年量产。
这说明 MU 不是只靠 HBM3E 吃一轮景气,它已经在往下一代产品迁移。
这点非常重要。
HBM 是 AI memory trade 的估值核心。
如果 MU 在 HBM4 这一代继续保持客户认证、供货节奏和良率优势,那市场会继续把它当 AI 核心链条,而不是普通 DRAM 公司。
反过来,如果 HBM4 节奏不顺,估值就会被重新压回周期股。
所以后面最该盯的不是一句“需求强劲”,而是:
HBM4 良率。
客户认证进度。
2027 年订单可见度。
HBM4E 量产时间。
和 #NVIDIA、#ASIC 客户、云厂商的绑定深度。
第五,非 HBM 业务也在被 AI 拉动。
很多人只看 HBM,但这次更大的变化是:
普通 DRAM 和 NAND 也开始受益。
数据中心不只需要 GPU 节点,还需要 CPU 服务器、存储服务器、缓存层、数据库、企业 SSD、冷数据和热数据分层。
AI 推理越来越多后,内存压力不只集中在训练集群。
边缘推理、企业私有 AI、机器人、自动驾驶、AI PC、手机端大模型都会带来新的存储需求。
汽车这条线也值得看。
L2+ 车型需要更多 #DRAM 和 #NAND。
robotaxi 需要更高可靠性和更高容量。
机器人未来如果放量,存储需求可能比现在市场建模更大。
这就是为什么我觉得 MU 的故事不是单一 HBM,而是整个 memory stack 被 AI 重新定价。
第六,CapEx 是最大分歧。
多头看到的是供给紧缺。
空头看到的是资本开支上升。
这次美光 Q3 资本开支已经超过 70 亿美元,Q4 还要继续往上走,2027 年每季度 capex 可能比 Q4 更高。
这就是未来最大的争议点。
如果这些钱主要投向 HBM、先进 DRAM、先进封装、cleanroom 和高价值客户锁定产能,市场会把它理解成高回报投资。
但如果行业所有玩家都开始扩产,几年后还是可能重新走向供给过剩。
所以 MU 后面最大的风险,不是需求明天突然消失,而是供给纪律被高利润诱惑打破。
这也是为什么我不会说存储行业从此没有周期。
更准确地说:
周期还在,但周期的形态变了。
以前是价格周期主导。
以后可能是 AI 长约、先进制程、HBM 产能、客户绑定、资本开支纪律共同决定周期。
第七,这份财报对整个 AI 链条也有启示
如果 MU 的说法成立,那 AI 投资逻辑要重新排序。
过去大家习惯把 AI 链条分成:
GPU 第一
网络第二。
应用第三
但现在可能要改成:
算力和内存一起构成第一层
光互联和网络构成第二层
电力、散热、封装、材料构成第三层
应用放在更后面
因为 AI 系统真正的瓶颈,不是单点算力,而是系统级吞吐
GPU 再强,如果 HBM 不够,DRAM 不够,SSD 不够,数据搬不动,整个系统效率都会掉下来。
所以我现在更倾向于把 AI 基建看成一套系统:
计算负责推理。
内存负责上下文。
存储负责数据。
光互联负责搬运。
电力散热负责承载。
任何一环紧缺,都会变成利润池。
MU 这份财报的意义就在这里。
它证明存储正在从 AI 配角变成 AI 基础设施的主角之一。
这份财报不是普通 beat。
它更像是存储行业的一次身份切换。
从周期品,走向战略资源。
从现货波动,走向长约锁供。
从单纯涨价,走向 AI 需求驱动的结构性紧缺。
从普通 DRAM 公司,走向 AI memory infrastructure 公司。
当然,风险也很清楚。
第一,股价已经涨很多,预期极高。
第二,毛利率已经非常高,后面每一步都要继续证明可持续。
第三,CapEx 增长会让市场担心下一轮供给过剩。
第四,一旦客户需求放缓,或者供应缓解,定价权会最先被质疑。
但至少这一次,MU 给出的答案非常强。
强业绩
强指引
强毛利
强 HBM4 进展
强客户长约
强供需紧缺叙事
AI 时代的记忆能力,正在变得和计算能力一样重要。
如果 GPU 是大脑的算力,那么 memory 就是大脑的记忆。
没有记忆,再强的 AI 也跑不远。
3k
·
--
Мақала
Nokia 的 AI 叙事正在从硬件扩展到软件层。光网络是血管,AI-RAN 是神经,Assurance Center + Gemini 更像网络运维的大脑诺基亚盘前又来利好!
$NOK 这条 Google Cloud 合作,我觉得市场可能低估了它的含义。
Google Cloud 宣布与 Nokia 合作,把 Gemini 模型集成到 Nokia Assurance Center。
这不是一个简单的“AI 贴牌新闻”。
Nokia Assurance Center 本质上是运营商网络的 AIOps 保障平台,用来做网络监控、故障识别、性能分析、服务质量保障。
以前运营商网络出了问题,很多流程是:
告警出现
工程师排查
找根因
开工单
修复
复盘
而 Gemini 接进去之后,方向会变成:
AI 读懂网络告警
AI 总结异常模式
AI 帮工程师定位根因
AI 给出修复建议
未来甚至走向半自动闭环运维
这件事真正重要的地方在于:
Nokia 正在把自己从传统通信设备商,往 AI-native network software 公司重新定义。
过去大家看 Nokia,第一反应是 5G 设备、光网络、IP 路由、Infinera。
但 AI 时代的网络,不只是硬件堆叠。
更大的变化是网络会变得越来越复杂。
5G-A、6G、AI-RAN、数据中心互联、边缘计算、企业专网、云原生核心网全部叠在一起,运营商不可能只靠人工去管理。
所以 autonomous network,也就是自主网络,会变成下一轮运营商降本增效的关键方向。
这就是 Google Cloud + Nokia 的意义。
Google 提供 Gemini 和 cloud AI 能力。
Nokia 提供电信网络知识、Assurance Center、Network as Code、运营商客户关系和网络场景。
两者结合,瞄准的是运营商最痛的地方:
网络越来越复杂
人工运维越来越贵
故障定位越来越慢
客户体验越来越难保障
AI 必须进入网络运营核心流程
我认为这对 Nokia 有三层利好。
第一层,强化 AI 网络软件叙事。
Nokia 不只是 AI 光网络和 AI-RAN 受益者,它也在做电信网络软件层的 AI 化。
第二层,提高客户粘性。
Assurance Center 一旦进入运营商核心运维流程,粘性比单次硬件订单更强,因为它绑定的是日常运营、故障处理、服务质量和网络自动化。
第三层,提升软件估值逻辑。
硬件设备订单容易被周期影响,但 AI assurance、automation、orchestration 这类软件能力,如果能持续渗透运营商,估值逻辑会更接近高毛利软件和平台服务。
这条新闻也和 Nokia 之前的 Network as Code 合作是连在一起的。
之前 Nokia 和 Google Cloud 是让网络 API 更容易被 AI agent 调用。
现在 Gemini 进入 Assurance Center,是让 AI 更深入网络运维系统。
一个是让应用调用网络。
一个是让 AI 管理网络。
这两件事拼起来,才是 Nokia 的大方向:
把通信网络从封闭基础设施,变成可编程、可理解、可自动优化的 AI-native platform。
当然,这不是短期爆炸式订单。
不要把它理解成 Google 马上给 Nokia 带来几十亿美元收入。
全球云巨头愿意把 Gemini 放进 Nokia 的网络软件体系里,说明 Nokia 在 AI telecom software 这条线仍然有位置。
这条新闻不是说 Nokia 又多了一个 AI 标签,而是说明 Nokia 正在把 AI 直接嵌进运营商网络的大脑。
如果 AI 光网络解决的是数据怎么传,AI-RAN 解决的是无线网络怎么变聪明,那么 Gemini + Assurance Center 解决的就是:
未来复杂网络,谁来理解、诊断和自动维护。
这对 Nokia 的长期重估,是加分项。
Nokia 的 AI 叙事正在从硬件扩展到软件层。光网络是血管,AI-RAN 是神经,Assurance Center + Gemini 更像网络运维的大脑
诺基亚盘前又来利好!
$NOK 这条 Google Cloud 合作,我觉得市场可能低估了它的含义。
Google Cloud 宣布与 Nokia 合作,把 Gemini 模型集成到 Nokia Assurance Center。
这不是一个简单的“AI 贴牌新闻”。
Nokia Assurance Center 本质上是运营商网络的 AIOps 保障平台,用来做网络监控、故障识别、性能分析、服务质量保障。
以前运营商网络出了问题,很多流程是:
告警出现
工程师排查
找根因
开工单
修复
复盘
而 Gemini 接进去之后,方向会变成:
AI 读懂网络告警
AI 总结异常模式
AI 帮工程师定位根因
AI 给出修复建议
未来甚至走向半自动闭环运维
这件事真正重要的地方在于:
Nokia 正在把自己从传统通信设备商,往 AI-native network software 公司重新定义。
过去大家看 Nokia,第一反应是 5G 设备、光网络、IP 路由、Infinera。
但 AI 时代的网络,不只是硬件堆叠。
更大的变化是网络会变得越来越复杂。
5G-A、6G、AI-RAN、数据中心互联、边缘计算、企业专网、云原生核心网全部叠在一起,运营商不可能只靠人工去管理。
所以 autonomous network,也就是自主网络,会变成下一轮运营商降本增效的关键方向。
这就是 Google Cloud + Nokia 的意义。
Google 提供 Gemini 和 cloud AI 能力。
Nokia 提供电信网络知识、Assurance Center、Network as Code、运营商客户关系和网络场景。
两者结合,瞄准的是运营商最痛的地方:
网络越来越复杂
人工运维越来越贵
故障定位越来越慢
客户体验越来越难保障
AI 必须进入网络运营核心流程
我认为这对 Nokia 有三层利好。
第一层,强化 AI 网络软件叙事。
Nokia 不只是 AI 光网络和 AI-RAN 受益者,它也在做电信网络软件层的 AI 化。
第二层,提高客户粘性。
Assurance Center 一旦进入运营商核心运维流程,粘性比单次硬件订单更强,因为它绑定的是日常运营、故障处理、服务质量和网络自动化。
第三层,提升软件估值逻辑。
硬件设备订单容易被周期影响,但 AI assurance、automation、orchestration 这类软件能力,如果能持续渗透运营商,估值逻辑会更接近高毛利软件和平台服务。
这条新闻也和 Nokia 之前的 Network as Code 合作是连在一起的。
之前 Nokia 和 Google Cloud 是让网络 API 更容易被 AI agent 调用。
现在 Gemini 进入 Assurance Center,是让 AI 更深入网络运维系统。
一个是让应用调用网络。
一个是让 AI 管理网络。
这两件事拼起来,才是 Nokia 的大方向:
把通信网络从封闭基础设施,变成可编程、可理解、可自动优化的 AI-native platform。
当然,这不是短期爆炸式订单。
不要把它理解成 Google 马上给 Nokia 带来几十亿美元收入。
全球云巨头愿意把 Gemini 放进 Nokia 的网络软件体系里,说明 Nokia 在 AI telecom software 这条线仍然有位置。
这条新闻不是说 Nokia 又多了一个 AI 标签,而是说明 Nokia 正在把 AI 直接嵌进运营商网络的大脑。
如果 AI 光网络解决的是数据怎么传,AI-RAN 解决的是无线网络怎么变聪明,那么 Gemini + Assurance Center 解决的就是:
未来复杂网络,谁来理解、诊断和自动维护。
这对 Nokia 的长期重估,是加分项。
$NOK 这条 Google Cloud 合作,我觉得市场可能低估了它的含义。
Google Cloud 宣布与 Nokia 合作,把 Gemini 模型集成到 Nokia Assurance Center。
这不是一个简单的“AI 贴牌新闻”。
Nokia Assurance Center 本质上是运营商网络的 AIOps 保障平台,用来做网络监控、故障识别、性能分析、服务质量保障。
以前运营商网络出了问题,很多流程是:
告警出现
工程师排查
找根因
开工单
修复
复盘
而 Gemini 接进去之后,方向会变成:
AI 读懂网络告警
AI 总结异常模式
AI 帮工程师定位根因
AI 给出修复建议
未来甚至走向半自动闭环运维
这件事真正重要的地方在于:
Nokia 正在把自己从传统通信设备商,往 AI-native network software 公司重新定义。
过去大家看 Nokia,第一反应是 5G 设备、光网络、IP 路由、Infinera。
但 AI 时代的网络,不只是硬件堆叠。
更大的变化是网络会变得越来越复杂。
5G-A、6G、AI-RAN、数据中心互联、边缘计算、企业专网、云原生核心网全部叠在一起,运营商不可能只靠人工去管理。
所以 autonomous network,也就是自主网络,会变成下一轮运营商降本增效的关键方向。
这就是 Google Cloud + Nokia 的意义。
Google 提供 Gemini 和 cloud AI 能力。
Nokia 提供电信网络知识、Assurance Center、Network as Code、运营商客户关系和网络场景。
两者结合,瞄准的是运营商最痛的地方:
网络越来越复杂
人工运维越来越贵
故障定位越来越慢
客户体验越来越难保障
AI 必须进入网络运营核心流程
我认为这对 Nokia 有三层利好。
第一层,强化 AI 网络软件叙事。
Nokia 不只是 AI 光网络和 AI-RAN 受益者,它也在做电信网络软件层的 AI 化。
第二层,提高客户粘性。
Assurance Center 一旦进入运营商核心运维流程,粘性比单次硬件订单更强,因为它绑定的是日常运营、故障处理、服务质量和网络自动化。
第三层,提升软件估值逻辑。
硬件设备订单容易被周期影响,但 AI assurance、automation、orchestration 这类软件能力,如果能持续渗透运营商,估值逻辑会更接近高毛利软件和平台服务。
这条新闻也和 Nokia 之前的 Network as Code 合作是连在一起的。
之前 Nokia 和 Google Cloud 是让网络 API 更容易被 AI agent 调用。
现在 Gemini 进入 Assurance Center,是让 AI 更深入网络运维系统。
一个是让应用调用网络。
一个是让 AI 管理网络。
这两件事拼起来,才是 Nokia 的大方向:
把通信网络从封闭基础设施,变成可编程、可理解、可自动优化的 AI-native platform。
当然,这不是短期爆炸式订单。
不要把它理解成 Google 马上给 Nokia 带来几十亿美元收入。
全球云巨头愿意把 Gemini 放进 Nokia 的网络软件体系里,说明 Nokia 在 AI telecom software 这条线仍然有位置。
这条新闻不是说 Nokia 又多了一个 AI 标签,而是说明 Nokia 正在把 AI 直接嵌进运营商网络的大脑。
如果 AI 光网络解决的是数据怎么传,AI-RAN 解决的是无线网络怎么变聪明,那么 Gemini + Assurance Center 解决的就是:
未来复杂网络,谁来理解、诊断和自动维护。
这对 Nokia 的长期重估,是加分项。
1
2
3.5k
·
--
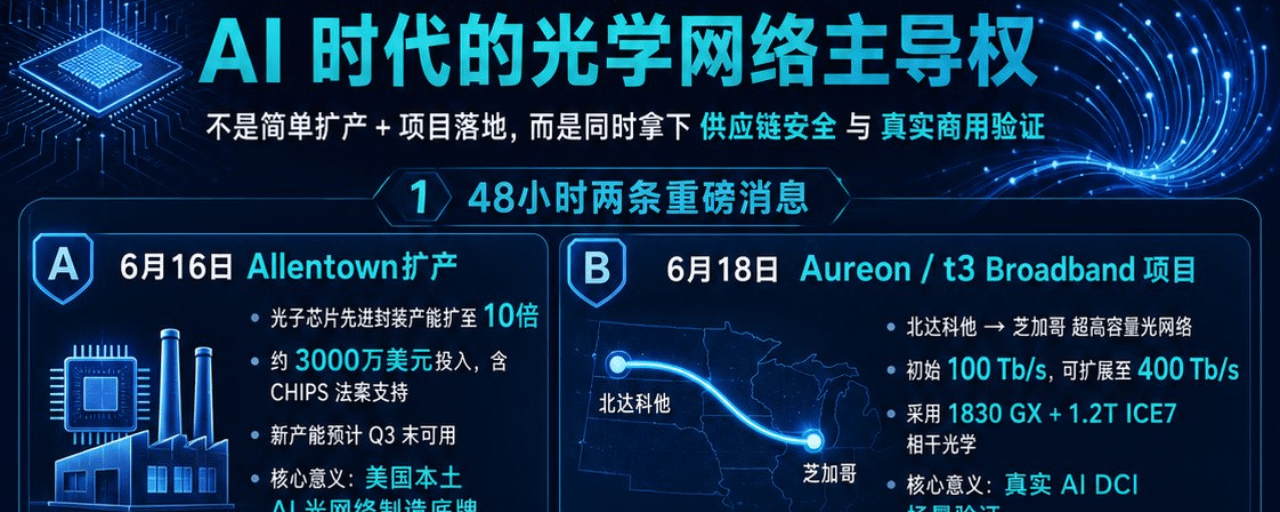
Мақала
诺基亚Anllentown 光子芯片先进封装产能扩到原来的 10 倍。和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready光传输网络美股 $NOK 诺基亚最近洗得是真狠!
上周三巫日又是借着期权继续在洗!
这不周末诺基亚连续放了两条大新闻消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 $MRVL、 $LITE、 $COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
诺基亚Anllentown 光子芯片先进封装产能扩到原来的 10 倍。和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready光传输网络
美股 $NOK 诺基亚最近洗得是真狠!
上周三巫日又是借着期权继续在洗!
这不周末诺基亚连续放了两条大新闻消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 $MRVL、 $LITE、 $COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
上周三巫日又是借着期权继续在洗!
这不周末诺基亚连续放了两条大新闻消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 $MRVL、 $LITE、 $COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
我把文章重写成更像个人判断的长推版本了。事实底座我顺手核了一遍:Allentown 扩产是 6 月 16 日诺基亚公告,核心是美国本土 ATP 产能最多扩 10 倍,新产能预计 Q3 末可商用,且是诺基亚美国 AI 网络连接 40 亿美元多年投资计划的一部分。(markets.businessinsider.com) Aureon 项目是 6 月 18 日诺基亚公告,初始 100 Tb/s,可扩到 400 Tb/s,路线连接北达科他数据中心到芝加哥,用的是 1830 GX、Super C/L-band 和 1.2T ICE7。(Nokia Corporation | Nokia) 市场层面,Dell’Oro 最新把 2026 年光传输设备市场增速预期从 10% 上调到 16%,并认为 DCI 直接采购收入在 Q1 继续约 40% 增长。(Dell'Oro Group) 诺基亚 Q1 也显示 AI & Cloud 客户销售增长 49%,Optical Networks 增长 20%,并把 2026 年 Optical + IP Networks 增长目标上调到 18%–20%。(Nokia Corporation | Nokia)
我最近看诺基亚,越来越觉得它不是在讲一个普通通信设备股的反弹故事。
它更像是在悄悄把自己重新放进 AI 基础设施的核心链条里。
6 月中旬,诺基亚连续放了两条消息。
第一条,Allentown 光子芯片先进封装产能扩到原来的 10 倍。
第二条,和 t3 Broadband、Aureon 合作,在北达科他到芝加哥之间落地一条 AI-ready 光传输网络,初始容量 100 Tb/s,未来可以扩到 400 Tb/s。
单独看,这两条新闻都不算特别复杂。
一个是扩产。
一个是项目落地。
但放在一起看,味道就不一样了。
我觉得诺基亚这两步棋真正瞄准的,不是短期多拿几个订单,而是 AI 时代光学网络的主导权。
AI 数据中心现在最大的问题,不只是 GPU 不够,也不是电力一个变量。
更大的问题是数据怎么搬。
GPU 集群越来越大,模型越来越大,训练和推理都需要海量数据在服务器、机柜、园区和数据中心之间来回流动。
所以光网络从以前的“通信基础设施”,正在变成 AI 工厂的“血管系统”。
这也是为什么我觉得诺基亚这次动作很关键。
Allentown 解决的是供给问题。
Aureon 解决的是验证问题。
一个问的是,未来美国市场真需要大量 AI 光网络设备时,你能不能供得上。
另一个问的是,你的技术能不能在真实 AI 数据中心互联场景里跑起来。
这两件事同时发生,意义比单条新闻大很多。
先说 Allentown。
诺基亚这次扩的是美国本土的 advanced test and packaging,也就是先进测试和封装能力。
重点不是它花了多少钱,而是它在美国少数能把光子芯片封装成光模块的地方,把产能直接拉到 10 倍。
这件事放在现在的背景下很敏感。
AI 数据中心对光模块、相干光学、低功耗传输的需求正在暴涨,但全球封装和光器件供应链仍然高度依赖亚洲。
美国 hyperscaler 后面如果继续大规模建设 AI 数据中心,不可能完全不考虑供应链安全、本土制造、关税、地缘风险这些问题。
诺基亚在 Allentown 加码,本质上是在给美国 AI 光网络提供一个本土化底座。
这不是简单扩产。
这是在告诉客户:
我不只是能给你技术,我还能在美国本土交付关键光学组件。
这对于未来争取 hyperscaler、运营商、政府和高安全需求客户,可能会越来越重要。
再看 Aureon 这条线路。
北达科他到芝加哥,初始 100 Tb/s,未来扩到 400 Tb/s。
用的是诺基亚 1830 GX 平台、Super C/L-band 光线路系统和 1.2T ICE7 相干光学。
这个项目的价值,不只是容量大。
真正重要的是它把诺基亚最新一代光传输方案,放进了 AI 数据中心互联的真实场景里。
AI 时代的 DCI,不再只是城域里多铺几根光纤。
未来越来越多需求会变成:
更远距离。
更高单纤容量。
更低功耗。
更好地把区域数据中心接入核心云节点。
北达科他到芝加哥这类路线,就是这种趋势的缩影。
很多人看 AI 基建,只盯 GPU、HBM、ASIC、光模块。
但如果 AI 工厂开始分布式扩张,跨区域数据中心互联一定会变成刚需。
这就是诺基亚 Optical Networks 真正有想象力的地方。
更有意思的是,行业数据也在配合这个逻辑。
Dell’Oro 之前说,2025 年全球光传输设备市场增长 10%,规模到了 160 亿美元左右,DCI 相关的 WDM 直接采购收入接近 40% 增长。
最新一版预测更猛。
他们把 2026 年光传输设备市场增速预期从 10% 上调到 16%,预计市场收入会超过 180 亿美元。
原因很直接:
AI 数据中心拉动 DCI 需求,很多供应商已经开始出现订单积压和交期拉长。
这句话其实很重要。
它说明光网络不是一个冷门配套环节,而是 AI 基建里正在变紧的供应链。
需求不是没有。
现在的问题反而是,谁能交付。
这就又回到了诺基亚的两步棋。
Allentown 是产能。
Aureon 是样板。
前者让客户相信它供得上。
后者让客户相信它跑得通。
两者叠加,诺基亚就不只是“我们也有光网络产品”,而是在构建一个更完整的商业闭环。
和 Ciena 比,诺基亚以前在 DCI 这个赛道并不是最纯的玩家。
Ciena 长期是光学传输里的强势公司,WaveLogic 在 hyperscaler 里也有很深的存在感。
但诺基亚收购 Infinera 之后,情况变了。
它补上了相干引擎、光传输系统和垂直整合能力。
现在再叠加美国本土 ATP 扩产,以及北美真实 AI DCI 项目落地,诺基亚的牌变得更完整。
Ciena 更像专注度极高的光学技术玩家。
诺基亚现在走的是另一种打法:
光学技术。
IP 网络。
本土制造。
系统交付。
运营商关系。
hyperscaler 和 AI cloud 机会。
这不是单点突破,而是组合拳。
短期看,Ciena 不会轻易让出份额。
甚至在很多 hyperscaler 项目里,Ciena 依然更有传统优势。
但从 2026 到 2028 这个时间窗口看,客户在意的东西可能会变多。
不只是性能。
还有供应链多元化。
本土交付能力。
产能确定性。
系统级解决方案。
在这个维度上,诺基亚正在补最关键的一环。
这也是我为什么觉得诺基亚现在不能只按“老通信设备股”来看。
Q1 的数据已经开始反映变化。
AI & Cloud 客户销售增长 49%。
Optical Networks 增长 20%。
公司把 Optical + IP Networks 的 2026 年增长目标上调到 18% 到 20%。
这说明光网络已经不是诺基亚故事里的边角料,而是 Network Infrastructure 里最能代表 AI 周期的增长曲线。
Allentown 扩产解决的是能不能供。
Aureon 项目解决的是别人愿不愿意买。
Q1 订单和增长数据解决的是这条线是不是已经开始兑现。
这三件事放一起,才是我对诺基亚重新感兴趣的原因。
当然,风险也要讲。
第一,竞争很强。
Ciena、Huawei、ZTE、Cisco Acacia、Marvell 这些玩家都在不同层面卡位光网络。
第二,hyperscaler 也会继续推动可插拔光模块和 IPoDWDM,部分价值可能从系统设备转向模块和芯片。
第三,诺基亚要证明 Infinera 整合以后,毛利率和交付效率真的能改善。
第四,短期股价如果已经提前反映 AI 光网络预期,财报验证就会更重要。
所以我不会把诺基亚说成一个没有风险的低估值白马。
更准确地说,它是一个正在被 AI 光网络周期重新定价的老牌基础设施公司。
它的弹性可能不如 MRVL、LITE、COHR 这种更前端的光互联标的。
但它的优势是位置更系统,估值更低,叙事正在从“电信设备”转向“AI 数据中心互联基础设施”。
我对诺基亚这两步棋的理解是:
Allentown 是供应链牌。
Aureon 是客户验证牌。
Q1 光网络增长是基本面牌。
如果后面诺基亚能继续复制类似北美 DCI 项目,并把 Infinera 的能力吃透,那 Optical Networks 很可能成为它未来两三年最重要的增长曲线。
这不是一个项目的故事。
也不是简单的产能扩张。
这是诺基亚在 AI 时代给自己重新找位置。
过去大家记住诺基亚,是手机。
后来大家把它看成 5G 设备商。
但现在,它可能正在变成 AI 数据中心之间那条“看不见的光路”的重要玩家。
我现在对 Nokia 的判断很简单:
短期看订单和财报。
中期看 Optical Networks 的增长能不能持续超过集团平均。
长期看它能不能在 AI DCI 和 scale-across 网络里,从参与者变成核心供应商之一。
如果这条线走通,诺基亚的重估可能才刚刚开始。
1
4.4k
·
--
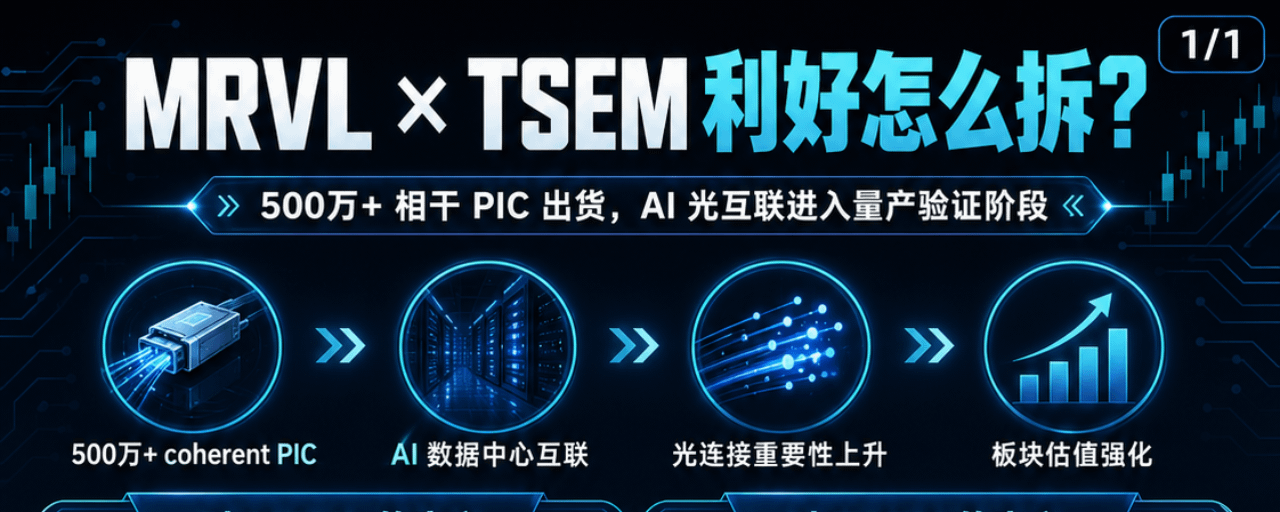
Мақала
Marvell ( $MRVL) 和 Tower Semiconductor ( $TSEM)宣布已出货超过 500 万个相干光子集成芯片!突发新闻:
Marvell ( $MRVL) 和 Tower Semiconductor ( $TSEM)
宣布已出货超过 500 万个相干光子集成芯片!
这一里程碑事件突显了光学连接在人工智能驱动的数据中心互连网络中日益增长的重要性。
这条消息对 MRVL 和 TSEM 都是利好,但利好性质不一样:
对 MRVL:这是“AI 光互联主线被验证”的利好。
对 TSEM:这是“硅光代工能力被验证”的更直接利好。
今天市场反应也很强,MRVL 当前约 323.12 美元,日内涨约 11.6%,TSEM 当前约 276.47 美元,日内涨约 3.5%。
证明 #MRVL 的相干光互联产品已经不是实验室概念,而是规模化出货了。
MRVL 的光互联产品已经有量产经验。
TSEM 的硅光平台已经被大客户验证。
AI 数据中心互联正在从“铜线/传统电互联”加速切向“光互联”。
AI 数据中心需要 coherent PIC
AI 集群变大以后,瓶颈已经不只是 GPU 算力,而是 数据怎么搬。
以前大家更关注单机柜、单服务器内部的连接。现在 AI 训练和推理集群越来越大,流量会跨服务器、跨机柜、跨数据中心流动。
距离一拉长,传统电连接会遇到几个问题:
带宽不够。
AI workload 需要大量 GPU 之间交换数据,模型越大,通信压力越大。
功耗太高。
数据搬运本身越来越耗电,电互联距离越远,损耗和功耗越难压。
延迟和信号完整性压力增加。
大规模集群不是简单把更多 GPU 堆上去,互联效率会直接影响训练效率。
数据中心之间的连接需求上升。
这就是 DCI,也就是 data center interconnect。MRVL 在 OFC 2026 展示资料里也把 connectivity 定义为现代 hyperscale 和 cloud 数据中心的主要瓶颈之一,并强调需要专门的半导体互联方案来解决性能、功耗和设计挑战。(Marvell Technology)
coherent PIC 的意义就在这里:
它可以用更复杂的光学调制和接收方式,在更远距离、更高带宽、更高效率的场景里传输数据。
一句话就是:
AI 越大,数据搬运越贵。数据搬运越贵,光互联越值钱。
MRVL 现在的市场叙事,已经不只是“芯片公司”,而是:
AI ASIC + SerDes + DSP + 光模块 + silicon photonics + DCI + photonic fabric。
这次 500 万颗相干 PIC 出货,直接验证了 MRVL 在光互联里的一个核心位置。
第一,证明 MRVL 的 coherent / DCI 产品有真实量产
这不是早期 demo,也不是单个客户验证,而是累计超过 500 万颗。Tower 公告里说这些 coherent PIC 已经交付给 Marvell 全球客户,用于满足 AI-driven DCI 网络对带宽和能效的需求。(Tower Semiconductor)
对 MRVL 来说,这说明它在 DCI 光互联里有真实市场份额。
第二,强化 MRVL 的“scale-across”叙事
Tower 公告里引用 Marvell 光学工程 CTO 的话,提到双方会继续推进下一代 coherent 技术,用于 scale-across data center architectures,支撑高级 AI workloads。(Tower Semiconductor)
AI 网络可以粗分三层:
层级大概意思对应机会scale-up单机柜或近距离芯片/GPU 互联NVLink、CPO、NPO、photonic fabricscale-out多机柜、多服务器集群互联Ethernet、switch、DSP、opticsscale-across跨数据中心、跨园区互联DCI、coherent optics、ZR/ZR+
MRVL 之前在 OFC 2026 展示里也把自己的产品覆盖到 scale-up、scale-out 和 scale-across,并展示了 DCI modules、coherent DSPs、800G ZR/ZR+ pluggable optics 等方向。
第三,和 MRVL 收购 Celestial AI、Polariton 是同一条主线
MRVL 之前收购 Celestial AI,是为了补强 photonic fabric 和 AI 芯片互联。Reuters 报道称,Celestial AI 的 photonic fabric 技术会增强 Marvell 的 CPO 能力,预计到 FY2028 后期贡献 5 亿美元年化收入,到次年翻倍到 10 亿美元。(Reuters)
MRVL 今年又收购 Polariton,官方说是为了增强光学路线图,推进 3.2T 及以上的带宽扩展,并补强 coherent 和 optical interconnect 平台。(Marvell Technology, Inc.)
所以这条 500 万颗 PIC 新闻,其实把 MRVL 的路线串起来了:
过去:coherent PIC 已经大规模出货。
现在:1.6T、800G ZR/ZR+、DCI、硅光继续放量。
未来:Celestial AI + Polariton + photonic fabric / CPO / NPO 继续往 AI 集群内部走。
这就是为什么市场会兴奋。它不是单点新闻,而是证明 MRVL 光互联不是 PPT。
AI 客户需求正在从“验证”进入“抢产能”。
Tower 5 月还宣布签下 2027 年 13 亿美元 silicon photonics revenue 相关客户合同,这说明今天这条 500 万颗出货不是孤立事件,而是 Tower 硅光订单正在系统性抬升。
它正在从传统特色工艺 foundry,被市场重新定价为 AI 硅光代工平台。
LITE / COHR
它们更偏激光器、光组件、材料和模块侧。NVIDIA 今年宣布分别向 Lumentum 和 Coherent 投资 20 亿美元,以强化 AI 数据中心芯片和光子技术生态,这本身已经说明光器件是 AI 基建瓶颈之一。(Reuters)
如果 MRVL / TSEM 的 coherent PIC 放量,市场会顺着逻辑继续看好:
激光器
调制器
光引擎
InP / SiPho
CPO / NPO
800G / 1.6T / 3.2T
Nokia
Nokia 不是这条新闻的直接受益方。
但如果 AI DCI 和跨数据中心互联需求继续上升,Nokia 的 Optical / IP / DCI 网络设备会间接受益。它更偏基础设施层,不是 PIC 或 DSP 最前端。
AVGO
Broadcom 也有 AI networking、custom ASIC、switch、DSP 和光互联相关敞口。
MRVL 这条新闻会强化整个 “custom AI silicon + connectivity” 叙事,但 MRVL 受益更直接,因为新闻就是它和 Tower 的合作里程碑。
过 500 万颗。所以它不是传统意义上的“新订单公告”。
三个价值:
第一,规模验证。
500 万颗说明产品已经跨过量产门槛。
第二,技术验证。
coherent PIC 工艺难度高,能规模出货代表平台成熟度高。
第三,趋势验证。
AI DCI 对高带宽、低功耗光互联的需求越来越强。
市场正在重新定价 AI connectivity。
MRVL 当前市值约 2889 亿美元,PE 约 111 倍。 这说明它已经不是便宜股,市场给的是高增长预期。
这条新闻对 MRVL 的影响,我会分成三层:
时间维度影响短线情绪利好,验证 AI 光互联主线,可能继续吸引 momentum 资金中线强化 DCI、coherent DSP、silicon photonics、photonic fabric 的估值逻辑长线如果 AI 集群架构继续向光互联迁移,MRVL 的数据中心互联收入空间会被继续上修
但短线风险也要看:
第一,涨幅太快后可能回踩。
今天 MRVL 日内涨幅已经很大,追高容易被震。
第二,估值已经很贵。
111 倍 PE 意味着市场容错率不高。
第三,不是新增营收指引。
如果后续财报没有体现更强订单或指引上修,市场可能会把它当作情绪催化消化掉。
我认为 TSEM 的核心看点是:
2027 年 13 亿美元 silicon photonics revenue 合同能不能兑现。
Tower IR 页面显示,它在 5 月 13 日发布过“签署 2027 年 13 亿美元硅光收入客户合同”的公告。(Tower Semiconductor)
Marvell 之外是否还有更多大客户。
如果 Tower 的 SiPho 平台不只是服务 MRVL,而是服务 LITE、COHR、Scintil、其他 AI 光器件公司,那估值空间更大。
300mm / 200mm 产能扩张能否跟上。
硅光不是普通逻辑代工,工艺和封装良率很关键。产能扩张慢,收入兑现就慢。
MRVL 和 TSEM 共同证明了 AI 数据中心互联的光化趋势已经进入量产阶段。MRVL 是 AI 光互联方案商,TSEM 是硅光工艺平台商。前者吃系统和芯片价值,后者吃工艺和产能价值。
Marvell ( $MRVL) 和 Tower Semiconductor ( $TSEM)宣布已出货超过 500 万个相干光子集成芯片!
突发新闻:
Marvell ( $MRVL) 和 Tower Semiconductor ( $TSEM)
宣布已出货超过 500 万个相干光子集成芯片!
这一里程碑事件突显了光学连接在人工智能驱动的数据中心互连网络中日益增长的重要性。
这条消息对 MRVL 和 TSEM 都是利好,但利好性质不一样:
对 MRVL:这是“AI 光互联主线被验证”的利好。
对 TSEM:这是“硅光代工能力被验证”的更直接利好。
今天市场反应也很强,MRVL 当前约 323.12 美元,日内涨约 11.6%,TSEM 当前约 276.47 美元,日内涨约 3.5%。
证明 #MRVL 的相干光互联产品已经不是实验室概念,而是规模化出货了。
MRVL 的光互联产品已经有量产经验。
TSEM 的硅光平台已经被大客户验证。
AI 数据中心互联正在从“铜线/传统电互联”加速切向“光互联”。
AI 数据中心需要 coherent PIC
AI 集群变大以后,瓶颈已经不只是 GPU 算力,而是 数据怎么搬。
以前大家更关注单机柜、单服务器内部的连接。现在 AI 训练和推理集群越来越大,流量会跨服务器、跨机柜、跨数据中心流动。
距离一拉长,传统电连接会遇到几个问题:
带宽不够。
AI workload 需要大量 GPU 之间交换数据,模型越大,通信压力越大。
功耗太高。
数据搬运本身越来越耗电,电互联距离越远,损耗和功耗越难压。
延迟和信号完整性压力增加。
大规模集群不是简单把更多 GPU 堆上去,互联效率会直接影响训练效率。
数据中心之间的连接需求上升。
这就是 DCI,也就是 data center interconnect。MRVL 在 OFC 2026 展示资料里也把 connectivity 定义为现代 hyperscale 和 cloud 数据中心的主要瓶颈之一,并强调需要专门的半导体互联方案来解决性能、功耗和设计挑战。(Marvell Technology)
coherent PIC 的意义就在这里:
它可以用更复杂的光学调制和接收方式,在更远距离、更高带宽、更高效率的场景里传输数据。
一句话就是:
AI 越大,数据搬运越贵。数据搬运越贵,光互联越值钱。
MRVL 现在的市场叙事,已经不只是“芯片公司”,而是:
AI ASIC + SerDes + DSP + 光模块 + silicon photonics + DCI + photonic fabric。
这次 500 万颗相干 PIC 出货,直接验证了 MRVL 在光互联里的一个核心位置。
第一,证明 MRVL 的 coherent / DCI 产品有真实量产
这不是早期 demo,也不是单个客户验证,而是累计超过 500 万颗。Tower 公告里说这些 coherent PIC 已经交付给 Marvell 全球客户,用于满足 AI-driven DCI 网络对带宽和能效的需求。(Tower Semiconductor)
对 MRVL 来说,这说明它在 DCI 光互联里有真实市场份额。
第二,强化 MRVL 的“scale-across”叙事
Tower 公告里引用 Marvell 光学工程 CTO 的话,提到双方会继续推进下一代 coherent 技术,用于 scale-across data center architectures,支撑高级 AI workloads。(Tower Semiconductor)
AI 网络可以粗分三层:
层级大概意思对应机会scale-up单机柜或近距离芯片/GPU 互联NVLink、CPO、NPO、photonic fabricscale-out多机柜、多服务器集群互联Ethernet、switch、DSP、opticsscale-across跨数据中心、跨园区互联DCI、coherent optics、ZR/ZR+
MRVL 之前在 OFC 2026 展示里也把自己的产品覆盖到 scale-up、scale-out 和 scale-across,并展示了 DCI modules、coherent DSPs、800G ZR/ZR+ pluggable optics 等方向。
第三,和 MRVL 收购 Celestial AI、Polariton 是同一条主线
MRVL 之前收购 Celestial AI,是为了补强 photonic fabric 和 AI 芯片互联。Reuters 报道称,Celestial AI 的 photonic fabric 技术会增强 Marvell 的 CPO 能力,预计到 FY2028 后期贡献 5 亿美元年化收入,到次年翻倍到 10 亿美元。(Reuters)
MRVL 今年又收购 Polariton,官方说是为了增强光学路线图,推进 3.2T 及以上的带宽扩展,并补强 coherent 和 optical interconnect 平台。(Marvell Technology, Inc.)
所以这条 500 万颗 PIC 新闻,其实把 MRVL 的路线串起来了:
过去:coherent PIC 已经大规模出货。
现在:1.6T、800G ZR/ZR+、DCI、硅光继续放量。
未来:Celestial AI + Polariton + photonic fabric / CPO / NPO 继续往 AI 集群内部走。
这就是为什么市场会兴奋。它不是单点新闻,而是证明 MRVL 光互联不是 PPT。
AI 客户需求正在从“验证”进入“抢产能”。
Tower 5 月还宣布签下 2027 年 13 亿美元 silicon photonics revenue 相关客户合同,这说明今天这条 500 万颗出货不是孤立事件,而是 Tower 硅光订单正在系统性抬升。
它正在从传统特色工艺 foundry,被市场重新定价为 AI 硅光代工平台。
LITE / COHR
它们更偏激光器、光组件、材料和模块侧。NVIDIA 今年宣布分别向 Lumentum 和 Coherent 投资 20 亿美元,以强化 AI 数据中心芯片和光子技术生态,这本身已经说明光器件是 AI 基建瓶颈之一。(Reuters)
如果 MRVL / TSEM 的 coherent PIC 放量,市场会顺着逻辑继续看好:
激光器
调制器
光引擎
InP / SiPho
CPO / NPO
800G / 1.6T / 3.2T
Nokia
Nokia 不是这条新闻的直接受益方。
但如果 AI DCI 和跨数据中心互联需求继续上升,Nokia 的 Optical / IP / DCI 网络设备会间接受益。它更偏基础设施层,不是 PIC 或 DSP 最前端。
AVGO
Broadcom 也有 AI networking、custom ASIC、switch、DSP 和光互联相关敞口。
MRVL 这条新闻会强化整个 “custom AI silicon + connectivity” 叙事,但 MRVL 受益更直接,因为新闻就是它和 Tower 的合作里程碑。
过 500 万颗。所以它不是传统意义上的“新订单公告”。
三个价值:
第一,规模验证。
500 万颗说明产品已经跨过量产门槛。
第二,技术验证。
coherent PIC 工艺难度高,能规模出货代表平台成熟度高。
第三,趋势验证。
AI DCI 对高带宽、低功耗光互联的需求越来越强。
市场正在重新定价 AI connectivity。
MRVL 当前市值约 2889 亿美元,PE 约 111 倍。 这说明它已经不是便宜股,市场给的是高增长预期。
这条新闻对 MRVL 的影响,我会分成三层:
时间维度影响短线情绪利好,验证 AI 光互联主线,可能继续吸引 momentum 资金中线强化 DCI、coherent DSP、silicon photonics、photonic fabric 的估值逻辑长线如果 AI 集群架构继续向光互联迁移,MRVL 的数据中心互联收入空间会被继续上修
但短线风险也要看:
第一,涨幅太快后可能回踩。
今天 MRVL 日内涨幅已经很大,追高容易被震。
第二,估值已经很贵。
111 倍 PE 意味着市场容错率不高。
第三,不是新增营收指引。
如果后续财报没有体现更强订单或指引上修,市场可能会把它当作情绪催化消化掉。
我认为 TSEM 的核心看点是:
2027 年 13 亿美元 silicon photonics revenue 合同能不能兑现。
Tower IR 页面显示,它在 5 月 13 日发布过“签署 2027 年 13 亿美元硅光收入客户合同”的公告。(Tower Semiconductor)
Marvell 之外是否还有更多大客户。
如果 Tower 的 SiPho 平台不只是服务 MRVL,而是服务 LITE、COHR、Scintil、其他 AI 光器件公司,那估值空间更大。
300mm / 200mm 产能扩张能否跟上。
硅光不是普通逻辑代工,工艺和封装良率很关键。产能扩张慢,收入兑现就慢。
MRVL 和 TSEM 共同证明了 AI 数据中心互联的光化趋势已经进入量产阶段。MRVL 是 AI 光互联方案商,TSEM 是硅光工艺平台商。前者吃系统和芯片价值,后者吃工艺和产能价值。
Marvell ( $MRVL) 和 Tower Semiconductor ( $TSEM)
宣布已出货超过 500 万个相干光子集成芯片!
这一里程碑事件突显了光学连接在人工智能驱动的数据中心互连网络中日益增长的重要性。
这条消息对 MRVL 和 TSEM 都是利好,但利好性质不一样:
对 MRVL:这是“AI 光互联主线被验证”的利好。
对 TSEM:这是“硅光代工能力被验证”的更直接利好。
今天市场反应也很强,MRVL 当前约 323.12 美元,日内涨约 11.6%,TSEM 当前约 276.47 美元,日内涨约 3.5%。
证明 #MRVL 的相干光互联产品已经不是实验室概念,而是规模化出货了。
MRVL 的光互联产品已经有量产经验。
TSEM 的硅光平台已经被大客户验证。
AI 数据中心互联正在从“铜线/传统电互联”加速切向“光互联”。
AI 数据中心需要 coherent PIC
AI 集群变大以后,瓶颈已经不只是 GPU 算力,而是 数据怎么搬。
以前大家更关注单机柜、单服务器内部的连接。现在 AI 训练和推理集群越来越大,流量会跨服务器、跨机柜、跨数据中心流动。
距离一拉长,传统电连接会遇到几个问题:
带宽不够。
AI workload 需要大量 GPU 之间交换数据,模型越大,通信压力越大。
功耗太高。
数据搬运本身越来越耗电,电互联距离越远,损耗和功耗越难压。
延迟和信号完整性压力增加。
大规模集群不是简单把更多 GPU 堆上去,互联效率会直接影响训练效率。
数据中心之间的连接需求上升。
这就是 DCI,也就是 data center interconnect。MRVL 在 OFC 2026 展示资料里也把 connectivity 定义为现代 hyperscale 和 cloud 数据中心的主要瓶颈之一,并强调需要专门的半导体互联方案来解决性能、功耗和设计挑战。(Marvell Technology)
coherent PIC 的意义就在这里:
它可以用更复杂的光学调制和接收方式,在更远距离、更高带宽、更高效率的场景里传输数据。
一句话就是:
AI 越大,数据搬运越贵。数据搬运越贵,光互联越值钱。
MRVL 现在的市场叙事,已经不只是“芯片公司”,而是:
AI ASIC + SerDes + DSP + 光模块 + silicon photonics + DCI + photonic fabric。
这次 500 万颗相干 PIC 出货,直接验证了 MRVL 在光互联里的一个核心位置。
第一,证明 MRVL 的 coherent / DCI 产品有真实量产
这不是早期 demo,也不是单个客户验证,而是累计超过 500 万颗。Tower 公告里说这些 coherent PIC 已经交付给 Marvell 全球客户,用于满足 AI-driven DCI 网络对带宽和能效的需求。(Tower Semiconductor)
对 MRVL 来说,这说明它在 DCI 光互联里有真实市场份额。
第二,强化 MRVL 的“scale-across”叙事
Tower 公告里引用 Marvell 光学工程 CTO 的话,提到双方会继续推进下一代 coherent 技术,用于 scale-across data center architectures,支撑高级 AI workloads。(Tower Semiconductor)
AI 网络可以粗分三层:
层级大概意思对应机会scale-up单机柜或近距离芯片/GPU 互联NVLink、CPO、NPO、photonic fabricscale-out多机柜、多服务器集群互联Ethernet、switch、DSP、opticsscale-across跨数据中心、跨园区互联DCI、coherent optics、ZR/ZR+
MRVL 之前在 OFC 2026 展示里也把自己的产品覆盖到 scale-up、scale-out 和 scale-across,并展示了 DCI modules、coherent DSPs、800G ZR/ZR+ pluggable optics 等方向。
第三,和 MRVL 收购 Celestial AI、Polariton 是同一条主线
MRVL 之前收购 Celestial AI,是为了补强 photonic fabric 和 AI 芯片互联。Reuters 报道称,Celestial AI 的 photonic fabric 技术会增强 Marvell 的 CPO 能力,预计到 FY2028 后期贡献 5 亿美元年化收入,到次年翻倍到 10 亿美元。(Reuters)
MRVL 今年又收购 Polariton,官方说是为了增强光学路线图,推进 3.2T 及以上的带宽扩展,并补强 coherent 和 optical interconnect 平台。(Marvell Technology, Inc.)
所以这条 500 万颗 PIC 新闻,其实把 MRVL 的路线串起来了:
过去:coherent PIC 已经大规模出货。
现在:1.6T、800G ZR/ZR+、DCI、硅光继续放量。
未来:Celestial AI + Polariton + photonic fabric / CPO / NPO 继续往 AI 集群内部走。
这就是为什么市场会兴奋。它不是单点新闻,而是证明 MRVL 光互联不是 PPT。
AI 客户需求正在从“验证”进入“抢产能”。
Tower 5 月还宣布签下 2027 年 13 亿美元 silicon photonics revenue 相关客户合同,这说明今天这条 500 万颗出货不是孤立事件,而是 Tower 硅光订单正在系统性抬升。
它正在从传统特色工艺 foundry,被市场重新定价为 AI 硅光代工平台。
LITE / COHR
它们更偏激光器、光组件、材料和模块侧。NVIDIA 今年宣布分别向 Lumentum 和 Coherent 投资 20 亿美元,以强化 AI 数据中心芯片和光子技术生态,这本身已经说明光器件是 AI 基建瓶颈之一。(Reuters)
如果 MRVL / TSEM 的 coherent PIC 放量,市场会顺着逻辑继续看好:
激光器
调制器
光引擎
InP / SiPho
CPO / NPO
800G / 1.6T / 3.2T
Nokia
Nokia 不是这条新闻的直接受益方。
但如果 AI DCI 和跨数据中心互联需求继续上升,Nokia 的 Optical / IP / DCI 网络设备会间接受益。它更偏基础设施层,不是 PIC 或 DSP 最前端。
AVGO
Broadcom 也有 AI networking、custom ASIC、switch、DSP 和光互联相关敞口。
MRVL 这条新闻会强化整个 “custom AI silicon + connectivity” 叙事,但 MRVL 受益更直接,因为新闻就是它和 Tower 的合作里程碑。
过 500 万颗。所以它不是传统意义上的“新订单公告”。
三个价值:
第一,规模验证。
500 万颗说明产品已经跨过量产门槛。
第二,技术验证。
coherent PIC 工艺难度高,能规模出货代表平台成熟度高。
第三,趋势验证。
AI DCI 对高带宽、低功耗光互联的需求越来越强。
市场正在重新定价 AI connectivity。
MRVL 当前市值约 2889 亿美元,PE 约 111 倍。 这说明它已经不是便宜股,市场给的是高增长预期。
这条新闻对 MRVL 的影响,我会分成三层:
时间维度影响短线情绪利好,验证 AI 光互联主线,可能继续吸引 momentum 资金中线强化 DCI、coherent DSP、silicon photonics、photonic fabric 的估值逻辑长线如果 AI 集群架构继续向光互联迁移,MRVL 的数据中心互联收入空间会被继续上修
但短线风险也要看:
第一,涨幅太快后可能回踩。
今天 MRVL 日内涨幅已经很大,追高容易被震。
第二,估值已经很贵。
111 倍 PE 意味着市场容错率不高。
第三,不是新增营收指引。
如果后续财报没有体现更强订单或指引上修,市场可能会把它当作情绪催化消化掉。
我认为 TSEM 的核心看点是:
2027 年 13 亿美元 silicon photonics revenue 合同能不能兑现。
Tower IR 页面显示,它在 5 月 13 日发布过“签署 2027 年 13 亿美元硅光收入客户合同”的公告。(Tower Semiconductor)
Marvell 之外是否还有更多大客户。
如果 Tower 的 SiPho 平台不只是服务 MRVL,而是服务 LITE、COHR、Scintil、其他 AI 光器件公司,那估值空间更大。
300mm / 200mm 产能扩张能否跟上。
硅光不是普通逻辑代工,工艺和封装良率很关键。产能扩张慢,收入兑现就慢。
MRVL 和 TSEM 共同证明了 AI 数据中心互联的光化趋势已经进入量产阶段。MRVL 是 AI 光互联方案商,TSEM 是硅光工艺平台商。前者吃系统和芯片价值,后者吃工艺和产能价值。
3.9k
·
--
Мақала
$SHAZ 的故事是澳大利亚本土 AI 云,主权 AI,GPU 算力基础设施,NVIDIA Cloud Partner。美股板块,最近在研究 $SHAZ。
我发现SHAZ是一支被忽视的潜力彩票股!
而且最重要的是有 #英伟达 背书,以及与澳大利亚达成了协议!
于是我上了底仓!据我调研,#Leopold 在54左右还买过
这家公司我觉得不能简单当成小盘 AI 概念股看,它真正有意思的地方,是它可能正在变成澳大利亚版的 AI neocloud 平台。
很多人看 AI 基建,第一反应是 $IREN, $CRWV, $NBIS, $APLD。
但 SHAZ 的故事不太一样。
#IREN 的底色还是矿企转 AI 数据中心,市场会纠结它到底是比特币矿企,能源股,还是 AI 云平台。
$SHAZ 的故事更干净。
它现在讲的是澳大利亚本土 AI 云,主权 AI,GPU 算力基础设施,NVIDIA Cloud Partner。
这几个标签叠在一起,弹性就完全不一样了。
我看好 #SHAZ 的第一个原因,是它的叙事很稀缺。
AI 不是只有美国要搞。澳大利亚,亚太地区,政府,企业,大学,科研机构,都需要本地可用的 AI 算力。
特别是涉及数据安全,合规,主权 AI 的场景,不是所有客户都愿意把数据和训练任务放到海外云上。
这就是 SHAZ 的位置。
它卖的不是一个软件,也不是一个普通机房,而是把 GPU,网络,存储,数据中心容量和运维交付打包成 AI 工厂。
客户不需要自己买 GPU,不需要自己搭集群,不需要自己处理电力,散热,网络和调度。
客户只需要买算力。
这就是 neocloud 最性感的地方。
第二个原因,是 NVIDIA 这条线。
SHAZ 和 NVIDIA 的六年战略计算合作,计划部署最多 40,000 个 Grace Blackwell GB300 GPU。
合作后,公司总 AI factory capacity 提升到 132MW,其中 102MW 已经签给终端客户,目标是在 2027 年中部署超过 55,000 个 NVIDIA GPU。
对一家小市值公司来说,这不是普通新闻。
这相当于市场突然发现,SHAZ 不是在讲 PPT,它真的拿到了上游资源,也真的在把产能往前推。
当然,NVIDIA 合作不等于 NVIDIA 直接送钱,更不等于 NVIDIA 保证股价上涨。
但在 AI 基建这个赛道里,能拿到 NVIDIA 的 GPU,能进入 NVIDIA 的生态,能把客户合同和 GPU 供给打通,这本身就是稀缺资源。
第三个原因,是收入拐点可能还没完全被市场消化。
目前 SHAZ 的历史收入很小,所以用传统 PE 去看没有意义。
它真正的定价方式,是看未来签约容量能不能转成收入。
如果 2026 下半年合同开始确认收入,2027 年营收继续爬坡,市场可能会从“小盘 AI 概念股”重新给它定价成“澳洲 AI 基建平台”。
这也是为什么有人喊 100 亿美元市值。
我不觉得这个目标一定会到,但我觉得这个逻辑不是纯瞎喊。
如果公司未来做到 10 亿美元以上年收入,市场给 8 到 10 倍 PS,100 亿美元市值就不是不能讨论。
关键不是口号,而是收入兑现速度。
第四个原因,是 SHAZ 比 IREN 更有弹性。
IREN 确定性更高,规模也更大,但市值已经大很多。
SHAZ 的优势在于早期,小,故事纯,市场认知还没完全统一。
小公司一旦从“能不能活下来”变成“能不能做大”,估值弹性会非常夸张。
这就是小盘成长股最迷人的地方。
但这也是风险最大的地方。
SHAZ 最大的问题不是故事不够大,而是故事太大,执行太难。
买这么多 GPU,要钱。
部署这么多 AI factory,要钱。
扩张这么快,还要钱。
所以稀释风险一定要放在桌面上讲。
公司刚刚做了 16 亿美元融资,其中一部分是股权和预融资权证,一部分是可转债。
这对基本面是燃料,对老股东是稀释。
如果后面收入兑现很快,市场会说这叫成长融资。
如果收入兑现慢,市场就会说这叫继续摊薄。
所以 SHAZ 不是低风险资产。
它不是 MRVL,也不是 Nokia。
MRVL 是 AI 互联和 ASIC 的核心链条,Nokia 是低估值 AI 网络重估。
SHAZ 更像公开市场里的 VC 项目。
如果成功,它可能从小盘 AI 云重估到区域级主权 AI 基建平台。
如果失败,它也可能变成高 capex,高稀释,高波动的小盘故事股。
我现在看 SHAZ,核心就盯四件事。
第一,NVIDIA 合作里的 GPU 部署速度。
第二,102MW 已签约容量什么时候开始稳定贡献收入。
第三,毛利率和现金流能不能证明这不是烧钱换规模。
第四,后续还有没有更大的增发或债务压力。
SHAZ 比 IREN 潜力更大,不是因为它更稳,而是因为它更早期,更小,更稀缺,叙事更纯。
IREN 是确定性更高的 AI 数据中心平台。
SHAZ 是弹性更大的澳洲主权 AI 云期权。
这票不能重仓信仰,更不能无脑追高。
但如果它真的把 #NVIDIA 合作,AI factory 容量,客户合同和收入拐点全部兑现,那现在市场给它的定价可能还只是第一阶段。
我会把它放在高波动卫星仓里看。
不是喊单,只是记录一个我认为值得深挖的 AI 基建小盘机会。
#DYOR
$SHAZ 的故事是澳大利亚本土 AI 云,主权 AI,GPU 算力基础设施,NVIDIA Cloud Partner。
美股板块,最近在研究 $SHAZ。
我发现SHAZ是一支被忽视的潜力彩票股!
而且最重要的是有 #英伟达 背书,以及与澳大利亚达成了协议!
于是我上了底仓!据我调研,#Leopold 在54左右还买过
这家公司我觉得不能简单当成小盘 AI 概念股看,它真正有意思的地方,是它可能正在变成澳大利亚版的 AI neocloud 平台。
很多人看 AI 基建,第一反应是 $IREN, $CRWV, $NBIS, $APLD。
但 SHAZ 的故事不太一样。
#IREN 的底色还是矿企转 AI 数据中心,市场会纠结它到底是比特币矿企,能源股,还是 AI 云平台。
$SHAZ 的故事更干净。
它现在讲的是澳大利亚本土 AI 云,主权 AI,GPU 算力基础设施,NVIDIA Cloud Partner。
这几个标签叠在一起,弹性就完全不一样了。
我看好 #SHAZ 的第一个原因,是它的叙事很稀缺。
AI 不是只有美国要搞。澳大利亚,亚太地区,政府,企业,大学,科研机构,都需要本地可用的 AI 算力。
特别是涉及数据安全,合规,主权 AI 的场景,不是所有客户都愿意把数据和训练任务放到海外云上。
这就是 SHAZ 的位置。
它卖的不是一个软件,也不是一个普通机房,而是把 GPU,网络,存储,数据中心容量和运维交付打包成 AI 工厂。
客户不需要自己买 GPU,不需要自己搭集群,不需要自己处理电力,散热,网络和调度。
客户只需要买算力。
这就是 neocloud 最性感的地方。
第二个原因,是 NVIDIA 这条线。
SHAZ 和 NVIDIA 的六年战略计算合作,计划部署最多 40,000 个 Grace Blackwell GB300 GPU。
合作后,公司总 AI factory capacity 提升到 132MW,其中 102MW 已经签给终端客户,目标是在 2027 年中部署超过 55,000 个 NVIDIA GPU。
对一家小市值公司来说,这不是普通新闻。
这相当于市场突然发现,SHAZ 不是在讲 PPT,它真的拿到了上游资源,也真的在把产能往前推。
当然,NVIDIA 合作不等于 NVIDIA 直接送钱,更不等于 NVIDIA 保证股价上涨。
但在 AI 基建这个赛道里,能拿到 NVIDIA 的 GPU,能进入 NVIDIA 的生态,能把客户合同和 GPU 供给打通,这本身就是稀缺资源。
第三个原因,是收入拐点可能还没完全被市场消化。
目前 SHAZ 的历史收入很小,所以用传统 PE 去看没有意义。
它真正的定价方式,是看未来签约容量能不能转成收入。
如果 2026 下半年合同开始确认收入,2027 年营收继续爬坡,市场可能会从“小盘 AI 概念股”重新给它定价成“澳洲 AI 基建平台”。
这也是为什么有人喊 100 亿美元市值。
我不觉得这个目标一定会到,但我觉得这个逻辑不是纯瞎喊。
如果公司未来做到 10 亿美元以上年收入,市场给 8 到 10 倍 PS,100 亿美元市值就不是不能讨论。
关键不是口号,而是收入兑现速度。
第四个原因,是 SHAZ 比 IREN 更有弹性。
IREN 确定性更高,规模也更大,但市值已经大很多。
SHAZ 的优势在于早期,小,故事纯,市场认知还没完全统一。
小公司一旦从“能不能活下来”变成“能不能做大”,估值弹性会非常夸张。
这就是小盘成长股最迷人的地方。
但这也是风险最大的地方。
SHAZ 最大的问题不是故事不够大,而是故事太大,执行太难。
买这么多 GPU,要钱。
部署这么多 AI factory,要钱。
扩张这么快,还要钱。
所以稀释风险一定要放在桌面上讲。
公司刚刚做了 16 亿美元融资,其中一部分是股权和预融资权证,一部分是可转债。
这对基本面是燃料,对老股东是稀释。
如果后面收入兑现很快,市场会说这叫成长融资。
如果收入兑现慢,市场就会说这叫继续摊薄。
所以 SHAZ 不是低风险资产。
它不是 MRVL,也不是 Nokia。
MRVL 是 AI 互联和 ASIC 的核心链条,Nokia 是低估值 AI 网络重估。
SHAZ 更像公开市场里的 VC 项目。
如果成功,它可能从小盘 AI 云重估到区域级主权 AI 基建平台。
如果失败,它也可能变成高 capex,高稀释,高波动的小盘故事股。
我现在看 SHAZ,核心就盯四件事。
第一,NVIDIA 合作里的 GPU 部署速度。
第二,102MW 已签约容量什么时候开始稳定贡献收入。
第三,毛利率和现金流能不能证明这不是烧钱换规模。
第四,后续还有没有更大的增发或债务压力。
SHAZ 比 IREN 潜力更大,不是因为它更稳,而是因为它更早期,更小,更稀缺,叙事更纯。
IREN 是确定性更高的 AI 数据中心平台。
SHAZ 是弹性更大的澳洲主权 AI 云期权。
这票不能重仓信仰,更不能无脑追高。
但如果它真的把 #NVIDIA 合作,AI factory 容量,客户合同和收入拐点全部兑现,那现在市场给它的定价可能还只是第一阶段。
我会把它放在高波动卫星仓里看。
不是喊单,只是记录一个我认为值得深挖的 AI 基建小盘机会。
#DYOR
我发现SHAZ是一支被忽视的潜力彩票股!
而且最重要的是有 #英伟达 背书,以及与澳大利亚达成了协议!
于是我上了底仓!据我调研,#Leopold 在54左右还买过
这家公司我觉得不能简单当成小盘 AI 概念股看,它真正有意思的地方,是它可能正在变成澳大利亚版的 AI neocloud 平台。
很多人看 AI 基建,第一反应是 $IREN, $CRWV, $NBIS, $APLD。
但 SHAZ 的故事不太一样。
#IREN 的底色还是矿企转 AI 数据中心,市场会纠结它到底是比特币矿企,能源股,还是 AI 云平台。
$SHAZ 的故事更干净。
它现在讲的是澳大利亚本土 AI 云,主权 AI,GPU 算力基础设施,NVIDIA Cloud Partner。
这几个标签叠在一起,弹性就完全不一样了。
我看好 #SHAZ 的第一个原因,是它的叙事很稀缺。
AI 不是只有美国要搞。澳大利亚,亚太地区,政府,企业,大学,科研机构,都需要本地可用的 AI 算力。
特别是涉及数据安全,合规,主权 AI 的场景,不是所有客户都愿意把数据和训练任务放到海外云上。
这就是 SHAZ 的位置。
它卖的不是一个软件,也不是一个普通机房,而是把 GPU,网络,存储,数据中心容量和运维交付打包成 AI 工厂。
客户不需要自己买 GPU,不需要自己搭集群,不需要自己处理电力,散热,网络和调度。
客户只需要买算力。
这就是 neocloud 最性感的地方。
第二个原因,是 NVIDIA 这条线。
SHAZ 和 NVIDIA 的六年战略计算合作,计划部署最多 40,000 个 Grace Blackwell GB300 GPU。
合作后,公司总 AI factory capacity 提升到 132MW,其中 102MW 已经签给终端客户,目标是在 2027 年中部署超过 55,000 个 NVIDIA GPU。
对一家小市值公司来说,这不是普通新闻。
这相当于市场突然发现,SHAZ 不是在讲 PPT,它真的拿到了上游资源,也真的在把产能往前推。
当然,NVIDIA 合作不等于 NVIDIA 直接送钱,更不等于 NVIDIA 保证股价上涨。
但在 AI 基建这个赛道里,能拿到 NVIDIA 的 GPU,能进入 NVIDIA 的生态,能把客户合同和 GPU 供给打通,这本身就是稀缺资源。
第三个原因,是收入拐点可能还没完全被市场消化。
目前 SHAZ 的历史收入很小,所以用传统 PE 去看没有意义。
它真正的定价方式,是看未来签约容量能不能转成收入。
如果 2026 下半年合同开始确认收入,2027 年营收继续爬坡,市场可能会从“小盘 AI 概念股”重新给它定价成“澳洲 AI 基建平台”。
这也是为什么有人喊 100 亿美元市值。
我不觉得这个目标一定会到,但我觉得这个逻辑不是纯瞎喊。
如果公司未来做到 10 亿美元以上年收入,市场给 8 到 10 倍 PS,100 亿美元市值就不是不能讨论。
关键不是口号,而是收入兑现速度。
第四个原因,是 SHAZ 比 IREN 更有弹性。
IREN 确定性更高,规模也更大,但市值已经大很多。
SHAZ 的优势在于早期,小,故事纯,市场认知还没完全统一。
小公司一旦从“能不能活下来”变成“能不能做大”,估值弹性会非常夸张。
这就是小盘成长股最迷人的地方。
但这也是风险最大的地方。
SHAZ 最大的问题不是故事不够大,而是故事太大,执行太难。
买这么多 GPU,要钱。
部署这么多 AI factory,要钱。
扩张这么快,还要钱。
所以稀释风险一定要放在桌面上讲。
公司刚刚做了 16 亿美元融资,其中一部分是股权和预融资权证,一部分是可转债。
这对基本面是燃料,对老股东是稀释。
如果后面收入兑现很快,市场会说这叫成长融资。
如果收入兑现慢,市场就会说这叫继续摊薄。
所以 SHAZ 不是低风险资产。
它不是 MRVL,也不是 Nokia。
MRVL 是 AI 互联和 ASIC 的核心链条,Nokia 是低估值 AI 网络重估。
SHAZ 更像公开市场里的 VC 项目。
如果成功,它可能从小盘 AI 云重估到区域级主权 AI 基建平台。
如果失败,它也可能变成高 capex,高稀释,高波动的小盘故事股。
我现在看 SHAZ,核心就盯四件事。
第一,NVIDIA 合作里的 GPU 部署速度。
第二,102MW 已签约容量什么时候开始稳定贡献收入。
第三,毛利率和现金流能不能证明这不是烧钱换规模。
第四,后续还有没有更大的增发或债务压力。
SHAZ 比 IREN 潜力更大,不是因为它更稳,而是因为它更早期,更小,更稀缺,叙事更纯。
IREN 是确定性更高的 AI 数据中心平台。
SHAZ 是弹性更大的澳洲主权 AI 云期权。
这票不能重仓信仰,更不能无脑追高。
但如果它真的把 #NVIDIA 合作,AI factory 容量,客户合同和收入拐点全部兑现,那现在市场给它的定价可能还只是第一阶段。
我会把它放在高波动卫星仓里看。
不是喊单,只是记录一个我认为值得深挖的 AI 基建小盘机会。
#DYOR
3.1k
Көбірек контент көру үшін кіріңіз
Binance Square платформасында әлемдік криптоқоғамдастыққа қосылыңыз
⚡️ Криптовалюта туралы ең соңғы және пайдалы ақпаратты алыңыз.
💬 Әлемдегі ең ірі криптобиржаның сеніміне ие.
👍 Расталған авторлардың нақты пікірлерін табыңыз.
Электрондық пошта/телефон нөмірі
Трендтегі тақырыптар
CryptoSelloffTriggersMultipleWhaleLiquidations
178,434 рет көрілді
1,782 адам талқылап жатыр
Crypto Liquidations Top $2B in 24 Hours as 329,000 Traders Are Wiped Out
Binance News
·40 лайк
·54.8k рет көрілді
USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
158,536 рет көрілді
1,550 адам талқылап жатыр
WillFOMCMinutesReinforceRateHikeExpectations?
46,504 рет көрілді
738 адам талқылап жатыр