
◢ Re-poster
802 Жариялаулар
◢ Re-poster
Хабарлау
Пайдаланушыны блоктау
“Only a fool trips on what’s behind them.” — Iceberg Slim ◢ Founder, CEO, Asymmetric Financial & Asymmetric Information
0 Жазылым
12 Жазылушылар
4 лайк басылған
Жазбалар
Барлығы
Видеолар
·
--
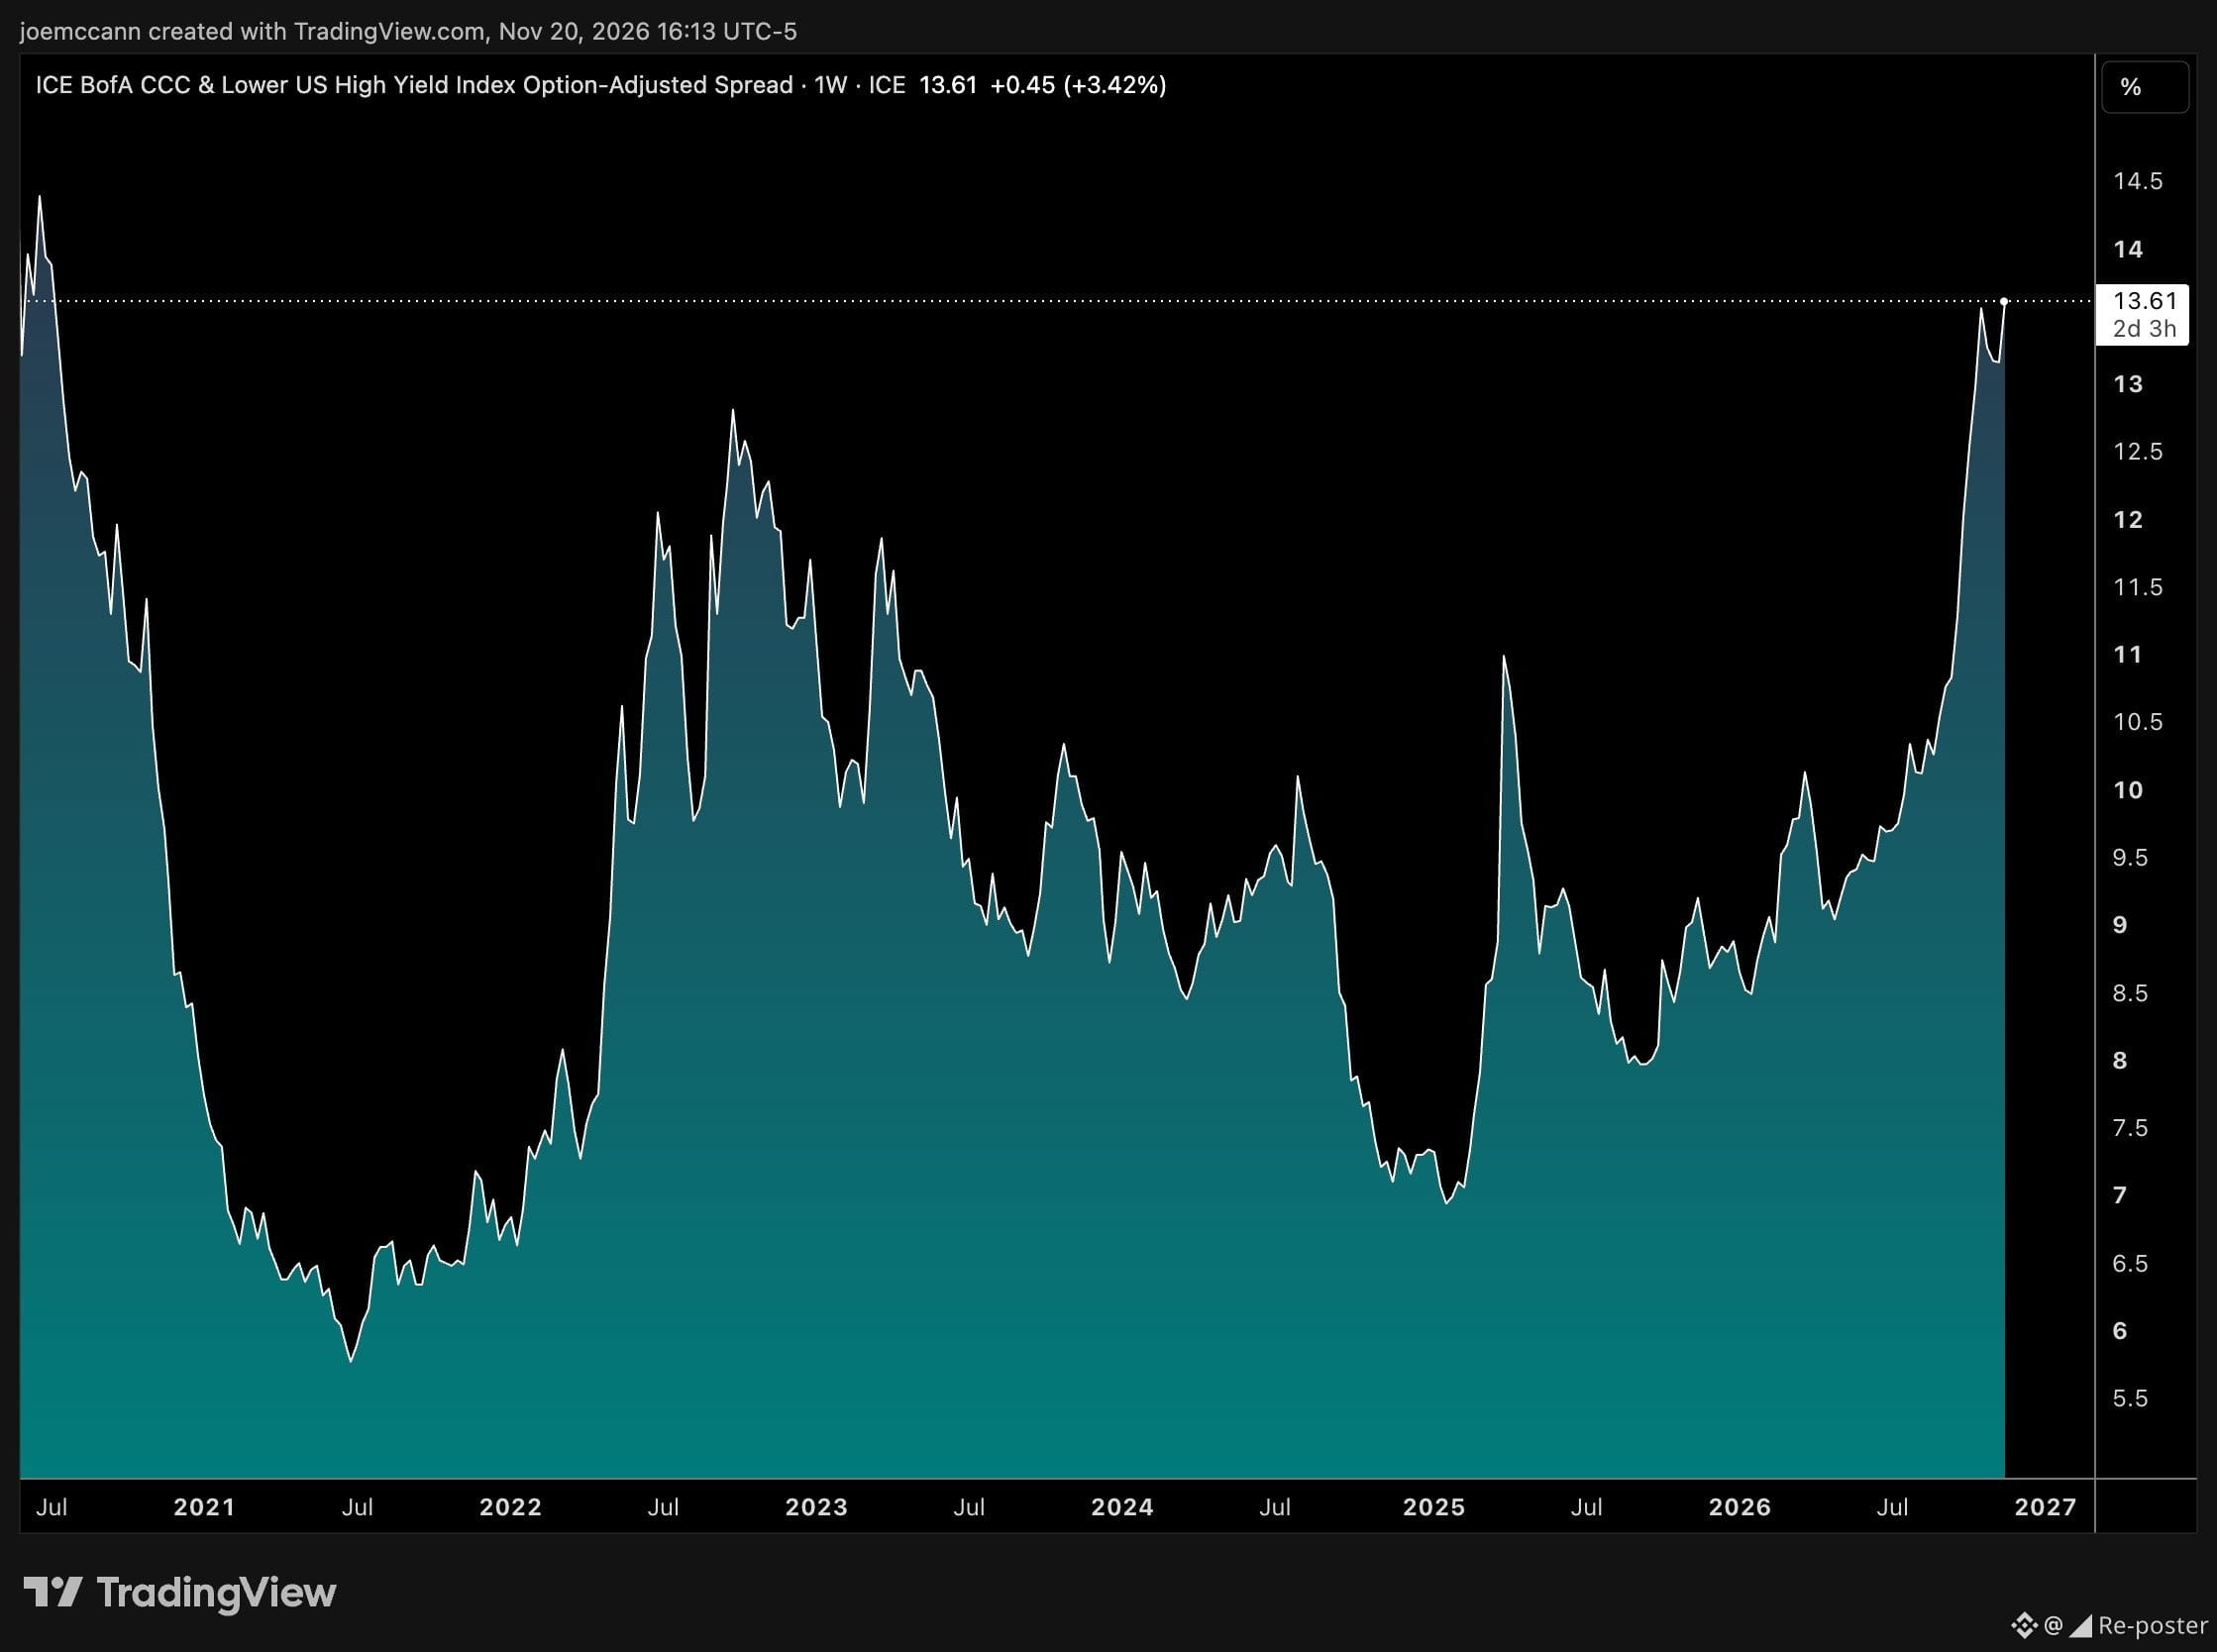
The weakest of the junk bond yields just widened even further today, the worst since 2020.
The weakest of the junk bond yields just widened even further today, the worst since 2020.
10
·
--
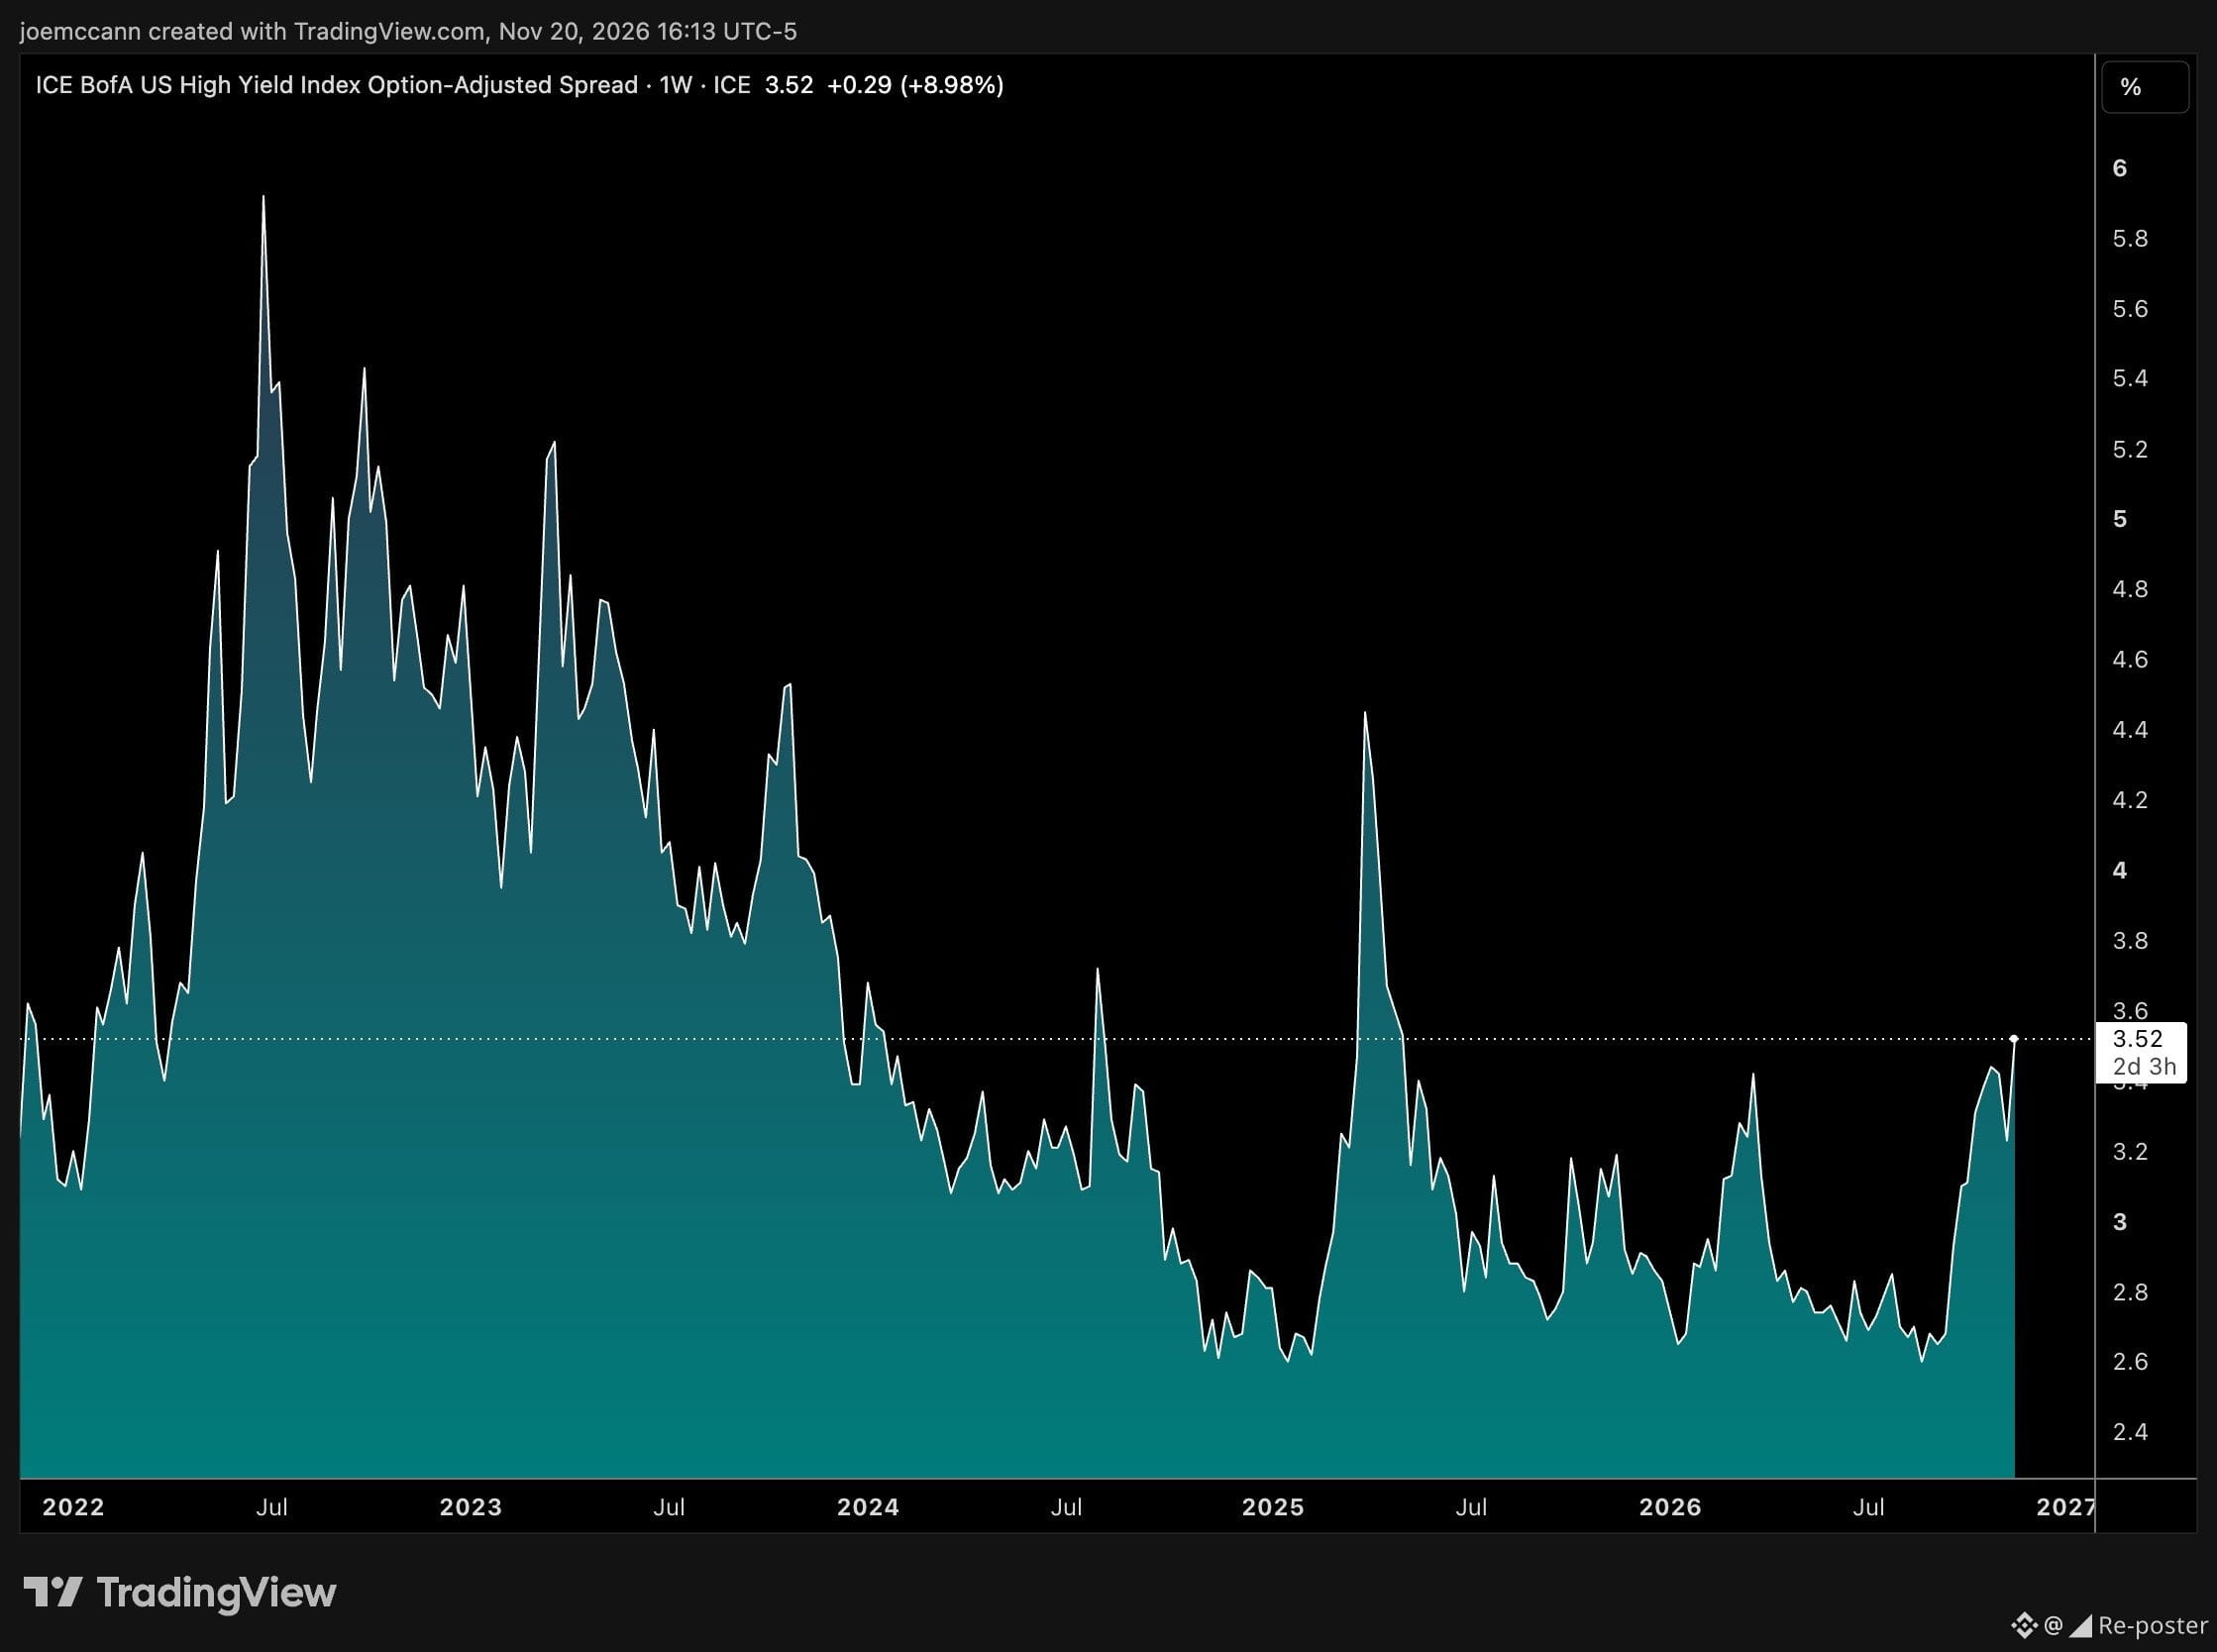
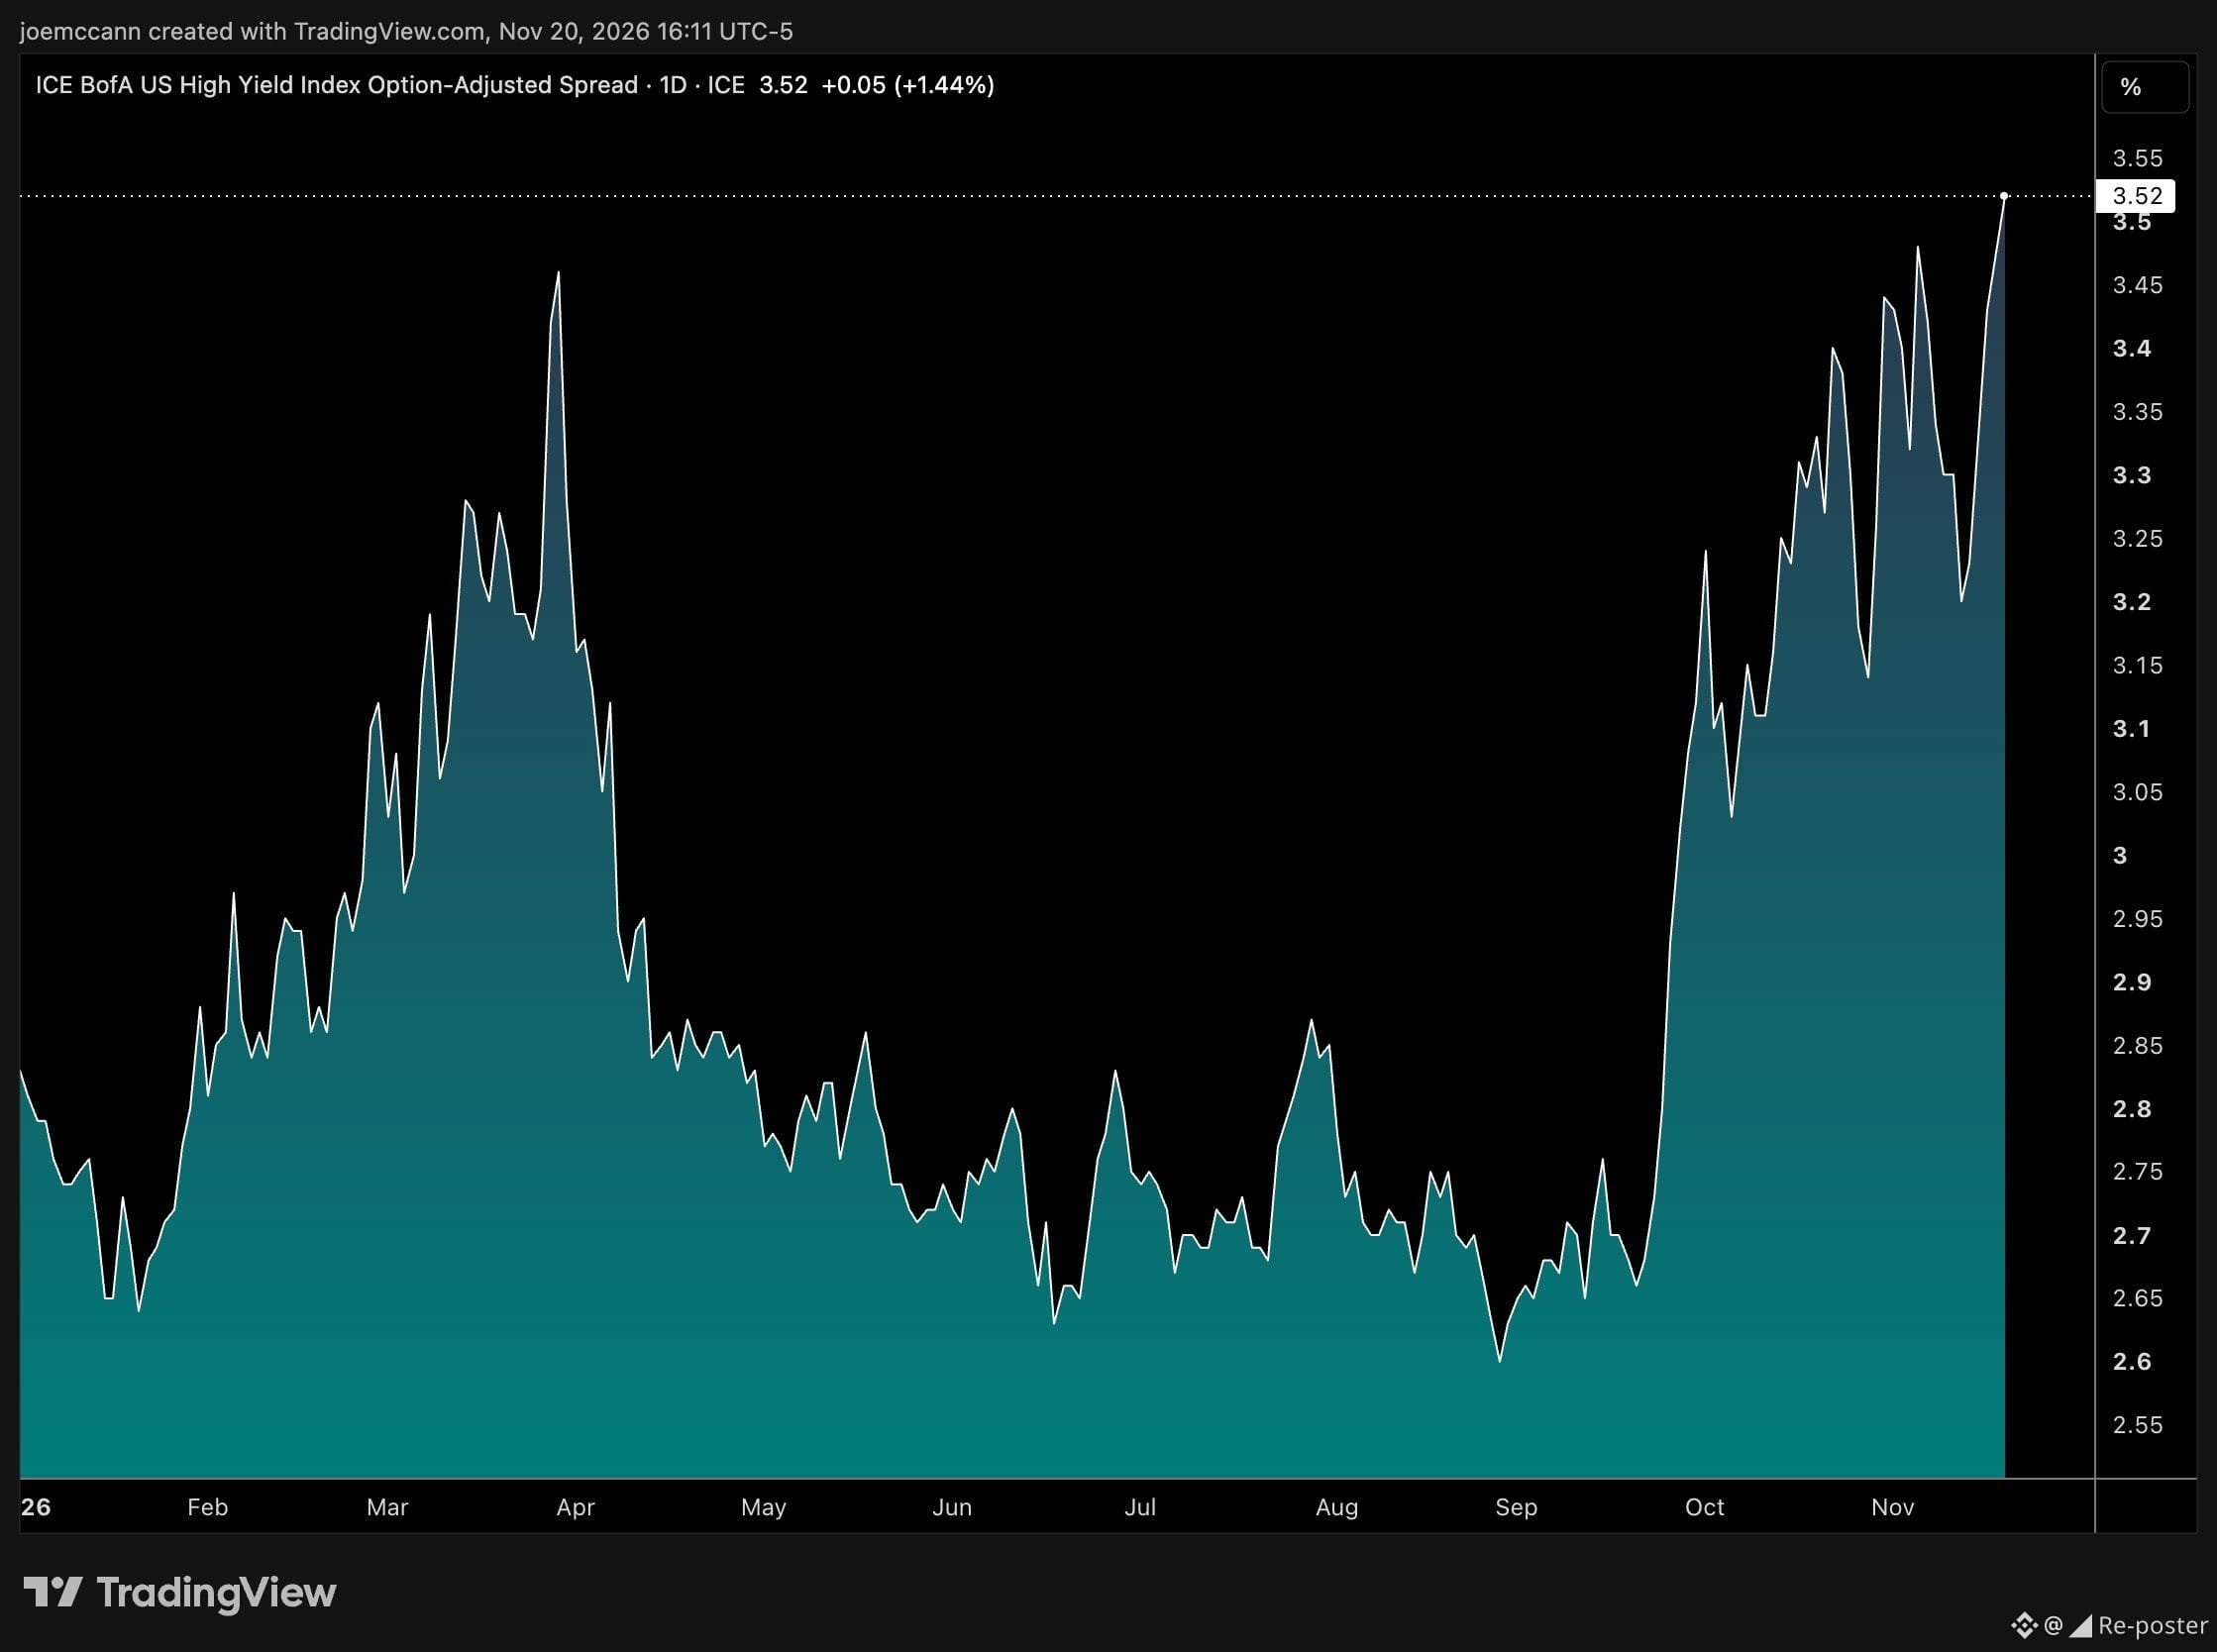
BofA US High Yield Option-Adjusted Spread is the widest of the year...but still benign in the long term.
BofA US High Yield Option-Adjusted Spread is the extra yield junk-rated corporate bonds pay over Treasuries, after stripping out the value of call options embedded in the bonds.
It is the bond market’s running estimate of default risk plus how much compensation investors demand to hold it.
Wider means stress.
Tighter means complacency or genuine health.
BofA US High Yield Option-Adjusted Spread is the widest of the year...but still benign in the long term.
BofA US High Yield Option-Adjusted Spread is the extra yield junk-rated corporate bonds pay over Treasuries, after stripping out the value of call options embedded in the bonds.
It is the bond market’s running estimate of default risk plus how much compensation investors demand to hold it.
Wider means stress.
Tighter means complacency or genuine health.
BofA US High Yield Option-Adjusted Spread is the extra yield junk-rated corporate bonds pay over Treasuries, after stripping out the value of call options embedded in the bonds.
It is the bond market’s running estimate of default risk plus how much compensation investors demand to hold it.
Wider means stress.
Tighter means complacency or genuine health.
2
·
--
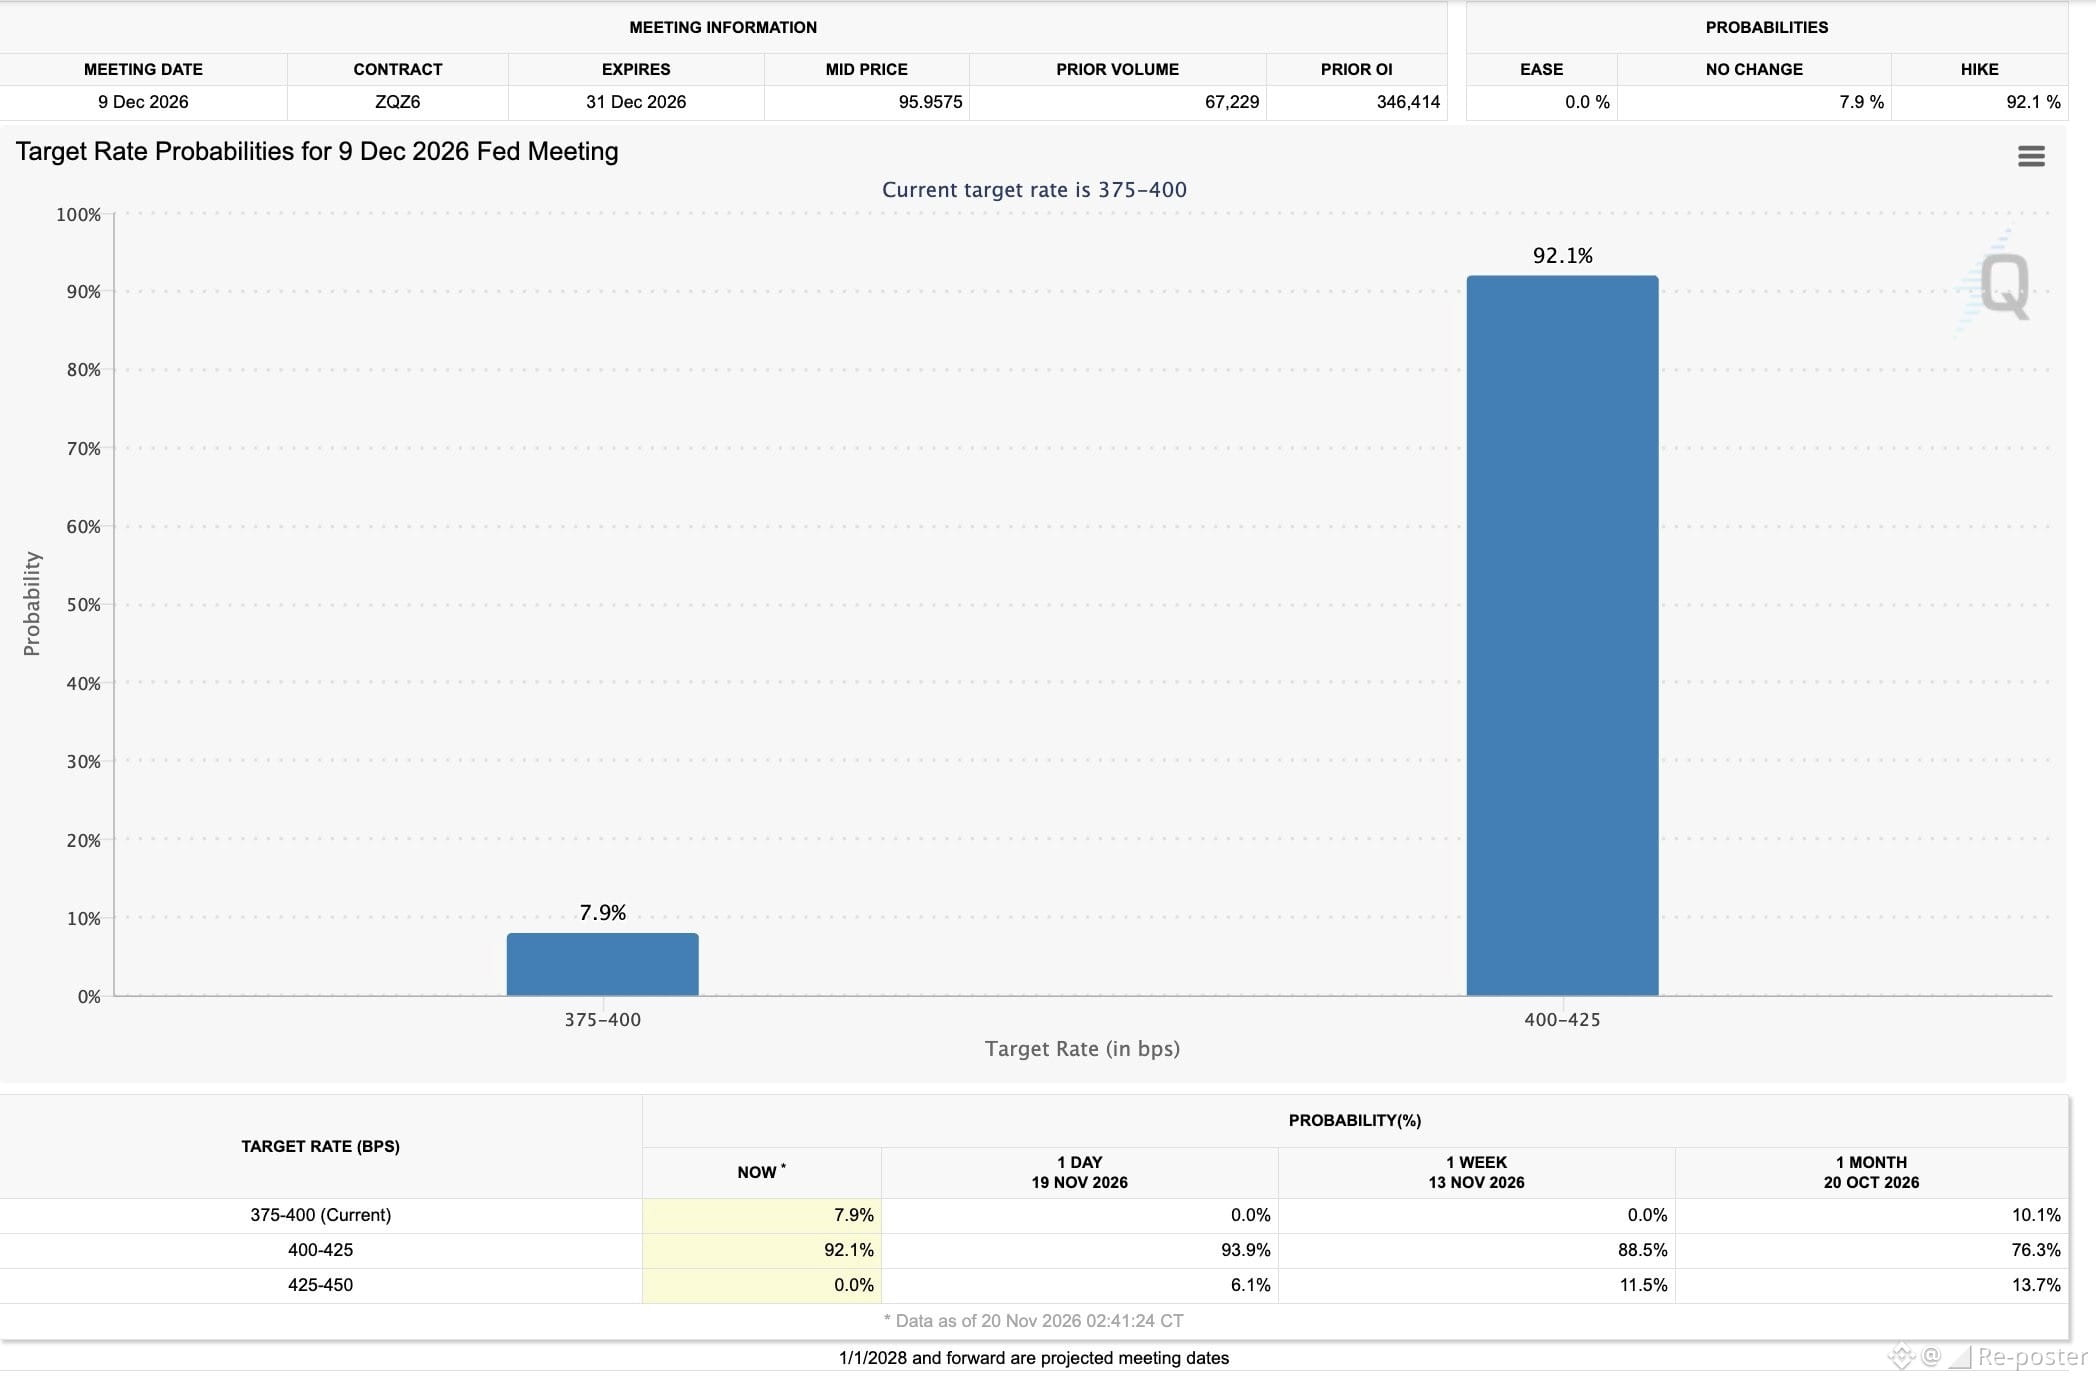
Now a 25 bps cut is being priced in the December Fed meeting, albeit an 8% chance.
Now a 25 bps cut is being priced in the December Fed meeting, albeit an 8% chance.
·
--
Dow Jones Industrial Average topped in August.
Fed hiked in September.
SP 500 and Nasdaq topped in October.
Boomer lesson there.
Dow Jones Industrial Average topped in August.
Fed hiked in September.
SP 500 and Nasdaq topped in October.
Boomer lesson there.
Fed hiked in September.
SP 500 and Nasdaq topped in October.
Boomer lesson there.
·
--
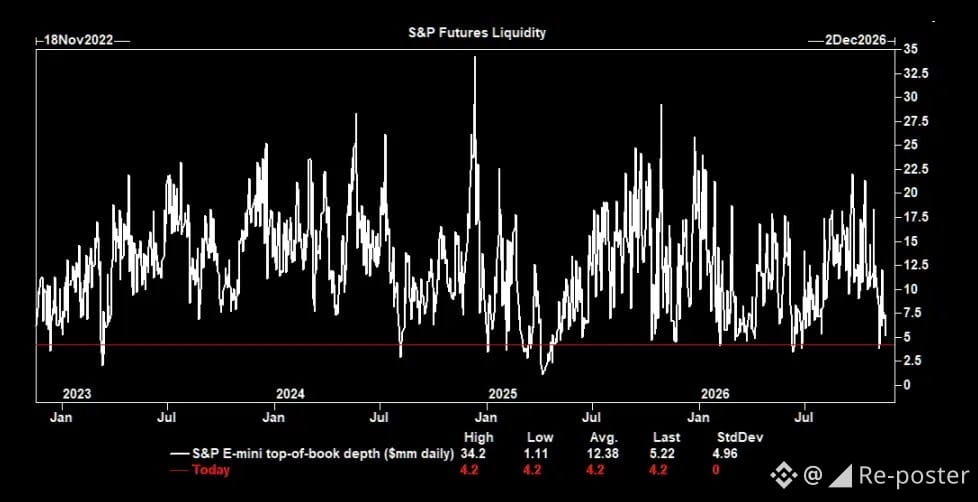
Top of order book liquidity the worst in 4 years.
Top of order book liquidity the worst in 4 years.
5
·
--
More signs of extreme stress
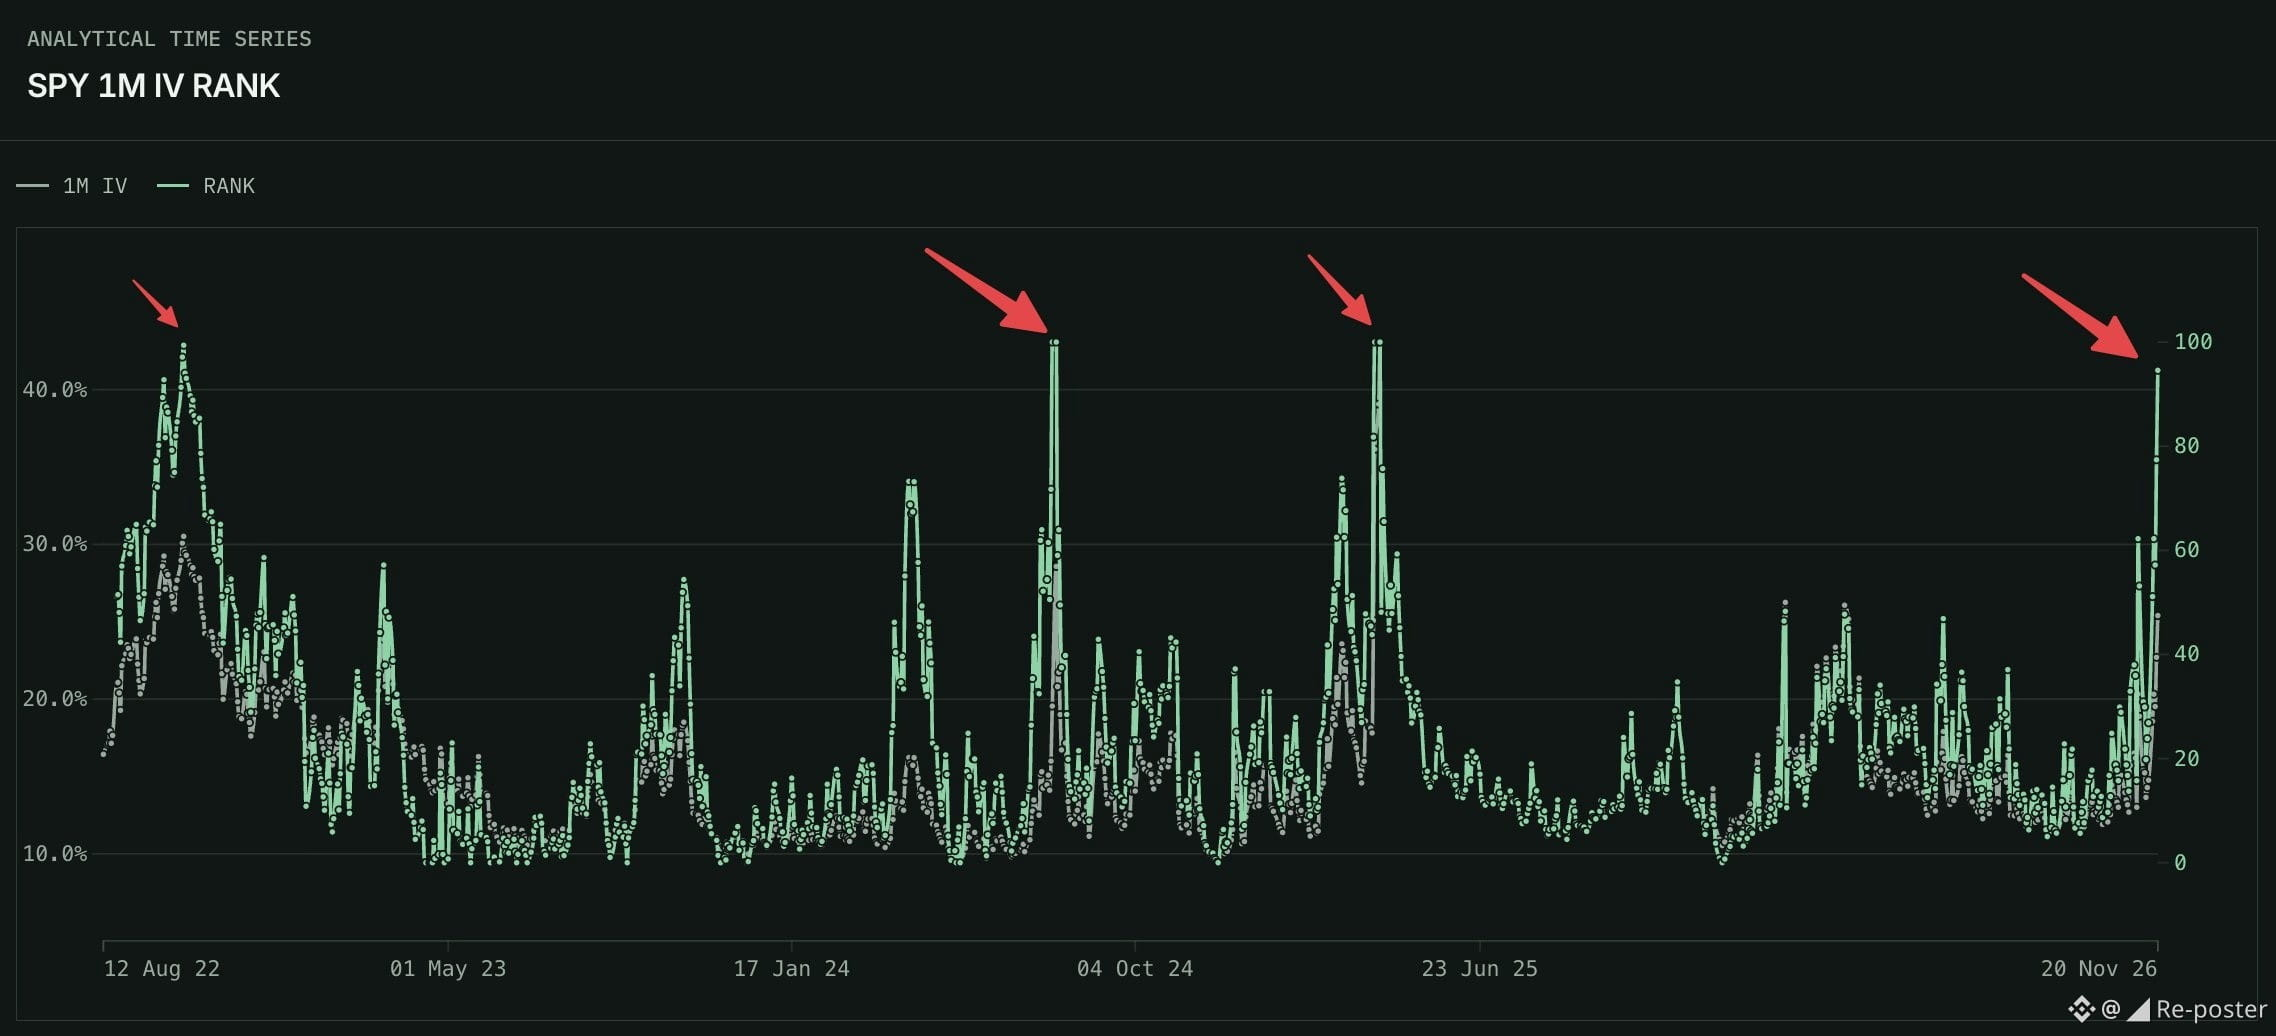
$SPY 1M Implied Volatility Rank is now at 95%, an extremely rare occurrence.
Prior readings at this level:
October 12, 2022
August 2, 2024
April 4, 2025
April 8, 2025
More signs of extreme stress
$SPY 1M Implied Volatility Rank is now at 95%, an extremely rare occurrence.
Prior readings at this level:
October 12, 2022
August 2, 2024
April 4, 2025
April 8, 2025
$SPY 1M Implied Volatility Rank is now at 95%, an extremely rare occurrence.
Prior readings at this level:
October 12, 2022
August 2, 2024
April 4, 2025
April 8, 2025
4
·
--
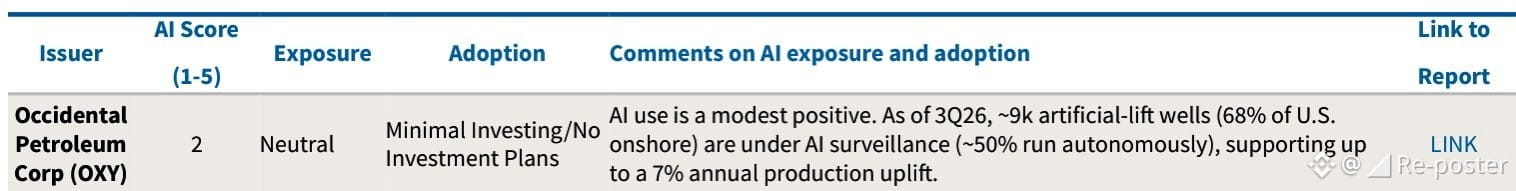
AI applications in the real world - oil wells.
Occidental's AI surveillance supports up to 7% production uplift
$OXY Petroleum's AI well surveillance covers 68% of U.S. onshore wells and supports up to a 7% annual production uplift, according to @Barclays' 16 Nov 2026 credit research. That's a concrete operating benefit, though @Barclays still classifies its AI exposure as neutral and its investment as minimal.
AI applications in the real world - oil wells.
Occidental's AI surveillance supports up to 7% production uplift
$OXY Petroleum's AI well surveillance covers 68% of U.S. onshore wells and supports up to a 7% annual production uplift, according to @Barclays' 16 Nov 2026 credit research. That's a concrete operating benefit, though @Barclays still classifies its AI exposure as neutral and its investment as minimal.
Occidental's AI surveillance supports up to 7% production uplift
$OXY Petroleum's AI well surveillance covers 68% of U.S. onshore wells and supports up to a 7% annual production uplift, according to @Barclays' 16 Nov 2026 credit research. That's a concrete operating benefit, though @Barclays still classifies its AI exposure as neutral and its investment as minimal.
37
·
--
Regulatory capture in plain sight.
Attaching the “China” label is intentional. If something is open source it has no domicile.
*HOUSE CMTES CALL TO REMOVE CHINA OPEN-WEIGHT MODELS FROM US GOV
Regulatory capture in plain sight.
Attaching the “China” label is intentional. If something is open source it has no domicile.
*HOUSE CMTES CALL TO REMOVE CHINA OPEN-WEIGHT MODELS FROM US GOV
Attaching the “China” label is intentional. If something is open source it has no domicile.
*HOUSE CMTES CALL TO REMOVE CHINA OPEN-WEIGHT MODELS FROM US GOV
37
·
--
This would be a positive for risk assets.
@UBS targets DXY below 100 after French elections
UBS targets DXY below 100 and EURUSD above 1.15 post-French elections. For now, resilient US activity and persistent inflation sustain USD strength. EURUSD is sideways as European inflation eases and the Fed shifts to the rate-cut debate.
UBS favors MXN, BRL, ZAR and INR for carry, volatility and yield differentials. GBP is its G10 preference for carry and low volatility. The bank retains an Attractive view on CNY, with 3.0-3.5% gains forecast for 2027.
UBS downgrades AUD/NZD to Unattractive on RBA rate-cut risks and external deficits. A faster decline in US inflation would accelerate USD depreciation. A global slowdown or geopolitical escalation would threaten the higher-yielding currencies the bank favors.
This would be a positive for risk assets.
@UBS targets DXY below 100 after French elections
UBS targets DXY below 100 and EURUSD above 1.15 post-French elections. For now, resilient US activity and persistent inflation sustain USD strength. EURUSD is sideways as European inflation eases and the Fed shifts to the rate-cut debate.
UBS favors MXN, BRL, ZAR and INR for carry, volatility and yield differentials. GBP is its G10 preference for carry and low volatility. The bank retains an Attractive view on CNY, with 3.0-3.5% gains forecast for 2027.
UBS downgrades AUD/NZD to Unattractive on RBA rate-cut risks and external deficits. A faster decline in US inflation would accelerate USD depreciation. A global slowdown or geopolitical escalation would threaten the higher-yielding currencies the bank favors.
@UBS targets DXY below 100 after French elections
UBS targets DXY below 100 and EURUSD above 1.15 post-French elections. For now, resilient US activity and persistent inflation sustain USD strength. EURUSD is sideways as European inflation eases and the Fed shifts to the rate-cut debate.
UBS favors MXN, BRL, ZAR and INR for carry, volatility and yield differentials. GBP is its G10 preference for carry and low volatility. The bank retains an Attractive view on CNY, with 3.0-3.5% gains forecast for 2027.
UBS downgrades AUD/NZD to Unattractive on RBA rate-cut risks and external deficits. A faster decline in US inflation would accelerate USD depreciation. A global slowdown or geopolitical escalation would threaten the higher-yielding currencies the bank favors.
51
·
--
Milei crushing it.
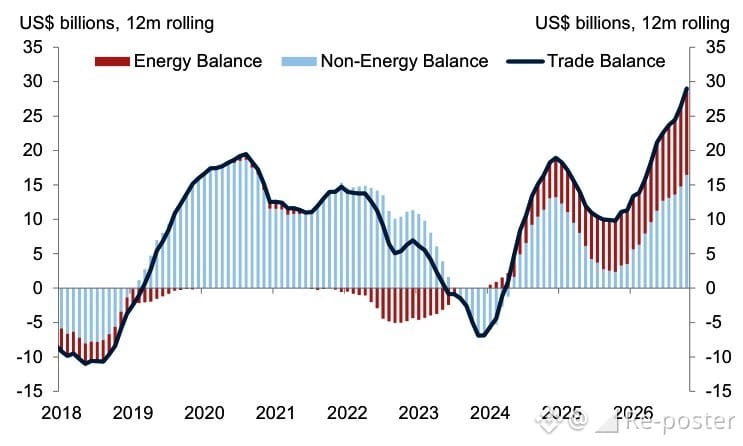
Argentina's October trade surplus hits a record US$3.34bn
Argentina posted a monthly record trade surplus of US$3.34bn in October, according to @GoldmanSachs. Total exports hit US$10.1bn, with energy exports up 94% YoY to US$1.73bn.
The 12-month cumulative surplus reached US$29bn (4% of GDP), up from US$11.3bn (1.6% of GDP) at year-end 2023.
The improvement extends across energy and non-energy trade balances. Primary-product exports rose 22.3% YoY, while import volumes fell 17.3%, partially offset by price effects. Export growth and lower import volumes both supported the surplus.
Milei crushing it.
Argentina's October trade surplus hits a record US$3.34bn
Argentina posted a monthly record trade surplus of US$3.34bn in October, according to @GoldmanSachs. Total exports hit US$10.1bn, with energy exports up 94% YoY to US$1.73bn.
The 12-month cumulative surplus reached US$29bn (4% of GDP), up from US$11.3bn (1.6% of GDP) at year-end 2023.
The improvement extends across energy and non-energy trade balances. Primary-product exports rose 22.3% YoY, while import volumes fell 17.3%, partially offset by price effects. Export growth and lower import volumes both supported the surplus.
Argentina's October trade surplus hits a record US$3.34bn
Argentina posted a monthly record trade surplus of US$3.34bn in October, according to @GoldmanSachs. Total exports hit US$10.1bn, with energy exports up 94% YoY to US$1.73bn.
The 12-month cumulative surplus reached US$29bn (4% of GDP), up from US$11.3bn (1.6% of GDP) at year-end 2023.
The improvement extends across energy and non-energy trade balances. Primary-product exports rose 22.3% YoY, while import volumes fell 17.3%, partially offset by price effects. Export growth and lower import volumes both supported the surplus.
60
·
--
⚠️ Crash Risk index now at 51/100 — high and approaching crisis levels.
The risk regime has shifted
$VIX at 28.73 is above its comfort zone.
$ COR1M at 31.3 shows correlations ticking higher.
SPX is 5.6% below its 100-day MA: the trend has broken and institutions are adjusting.
CTA positioning: SPX at -0.13 (5th pctile, z=-1.50).
⚠️ Crash Risk index now at 51/100 — high and approaching crisis levels.
The risk regime has shifted
$VIX at 28.73 is above its comfort zone.
$ COR1M at 31.3 shows correlations ticking higher.
SPX is 5.6% below its 100-day MA: the trend has broken and institutions are adjusting.
CTA positioning: SPX at -0.13 (5th pctile, z=-1.50).
The risk regime has shifted
$VIX at 28.73 is above its comfort zone.
$ COR1M at 31.3 shows correlations ticking higher.
SPX is 5.6% below its 100-day MA: the trend has broken and institutions are adjusting.
CTA positioning: SPX at -0.13 (5th pctile, z=-1.50).
31
·
--
$VIX highest print since March 31st 2026
$COR1M highest print since March 31st 2026.
What happened next?
$VIX highest print since March 31st 2026
$COR1M highest print since March 31st 2026.
What happened next?
$COR1M highest print since March 31st 2026.
What happened next?
46
·
--
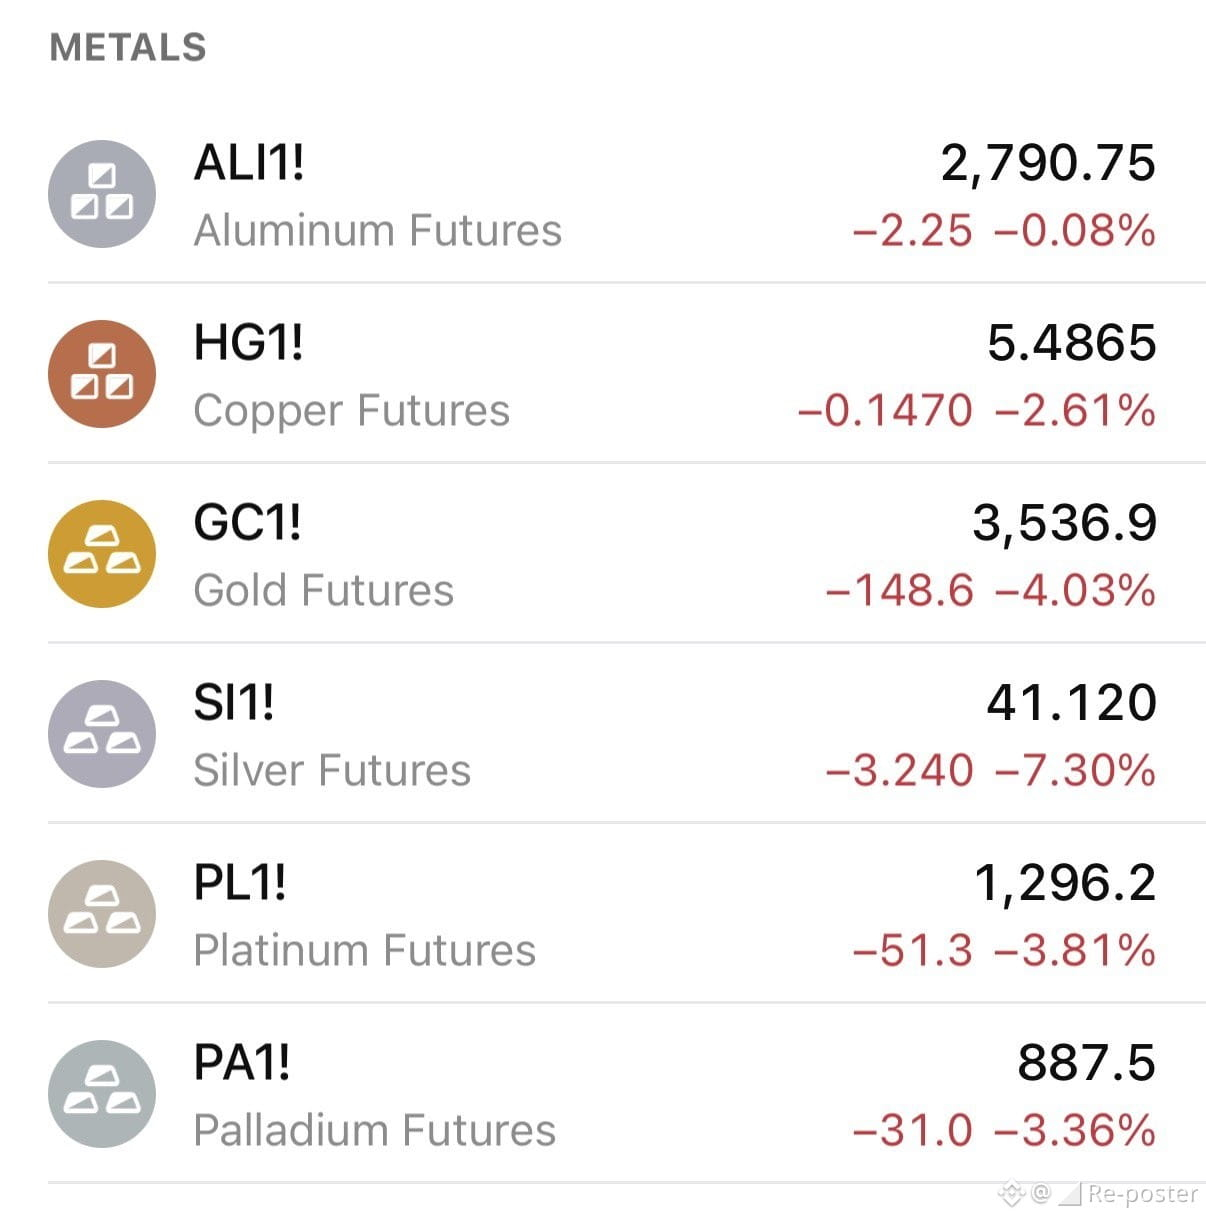
Metals are getting smoked: Copper selling extends to a 7th consecutive week
@GoldmanSachs' Quinn flags a 7th consecutive week of speculative selling in High Grade Copper futures. Managed Money sold $1.3bn, while price fell 4.1% (Nov 10-17) amid tighter financial conditions.
PMPU positioning went the other way. Bull positioning surged $1.1bn net, and gross longs hit multiyear highs. Quinn flags overextension risk. That leaves the bullish positioning vulnerable to changes in tariff policy.
Options sentiment is impaired too. The 25 delta put-call skew is at a 99% 1-year rank, a measure of where skew sits within its historical range. Copper's Short, Medium and Long trend thresholds are all moving down. The near-term evidence points to weaker momentum, with tariff resolve still a policy risk.
Metals are getting smoked: Copper selling extends to a 7th consecutive week
@GoldmanSachs' Quinn flags a 7th consecutive week of speculative selling in High Grade Copper futures. Managed Money sold $1.3bn, while price fell 4.1% (Nov 10-17) amid tighter financial conditions.
PMPU positioning went the other way. Bull positioning surged $1.1bn net, and gross longs hit multiyear highs. Quinn flags overextension risk. That leaves the bullish positioning vulnerable to changes in tariff policy.
Options sentiment is impaired too. The 25 delta put-call skew is at a 99% 1-year rank, a measure of where skew sits within its historical range. Copper's Short, Medium and Long trend thresholds are all moving down. The near-term evidence points to weaker momentum, with tariff resolve still a policy risk.
@GoldmanSachs' Quinn flags a 7th consecutive week of speculative selling in High Grade Copper futures. Managed Money sold $1.3bn, while price fell 4.1% (Nov 10-17) amid tighter financial conditions.
PMPU positioning went the other way. Bull positioning surged $1.1bn net, and gross longs hit multiyear highs. Quinn flags overextension risk. That leaves the bullish positioning vulnerable to changes in tariff policy.
Options sentiment is impaired too. The 25 delta put-call skew is at a 99% 1-year rank, a measure of where skew sits within its historical range. Copper's Short, Medium and Long trend thresholds are all moving down. The near-term evidence points to weaker momentum, with tariff resolve still a policy risk.
149
·
--
@BankofAmerica stays bullish USD into 2027
@BankofAmerica's USD bull case into 2027 rests on strong US growth and Fed policy. The bank treats election-related weakness as temporary noise within that longer-term view.
Brent fell 11% post-election while USD rose. @BankofAmerica points to interest rate differentials as the driver of the dollar's move. Its charts show a small dollar sensitivity to oil and a stronger relationship with rate differentials.
Inward US investment also remains strong, according to @BankofAmerica. That supports its dollar thesis despite equity underperformance and risks to AI sentiment.
The clearest risk to that view is weaker US data. In @BankofAmerica's FX and Rates Sentiment Survey, 42% of respondents cite deteriorating US data that forces a more dovish Fed as the primary catalyst for USD weakness. A faltering AI rally is the secondary risk at 25%. Those are survey views on potential catalysts.
@BankofAmerica stays bullish USD into 2027
@BankofAmerica's USD bull case into 2027 rests on strong US growth and Fed policy. The bank treats election-related weakness as temporary noise within that longer-term view.
Brent fell 11% post-election while USD rose. @BankofAmerica points to interest rate differentials as the driver of the dollar's move. Its charts show a small dollar sensitivity to oil and a stronger relationship with rate differentials.
Inward US investment also remains strong, according to @BankofAmerica. That supports its dollar thesis despite equity underperformance and risks to AI sentiment.
The clearest risk to that view is weaker US data. In @BankofAmerica's FX and Rates Sentiment Survey, 42% of respondents cite deteriorating US data that forces a more dovish Fed as the primary catalyst for USD weakness. A faltering AI rally is the secondary risk at 25%. Those are survey views on potential catalysts.
@BankofAmerica's USD bull case into 2027 rests on strong US growth and Fed policy. The bank treats election-related weakness as temporary noise within that longer-term view.
Brent fell 11% post-election while USD rose. @BankofAmerica points to interest rate differentials as the driver of the dollar's move. Its charts show a small dollar sensitivity to oil and a stronger relationship with rate differentials.
Inward US investment also remains strong, according to @BankofAmerica. That supports its dollar thesis despite equity underperformance and risks to AI sentiment.
The clearest risk to that view is weaker US data. In @BankofAmerica's FX and Rates Sentiment Survey, 42% of respondents cite deteriorating US data that forces a more dovish Fed as the primary catalyst for USD weakness. A faltering AI rally is the secondary risk at 25%. Those are survey views on potential catalysts.
73
Көбірек контент көру үшін кіріңіз
Binance Square платформасында әлемдік криптоқоғамдастыққа қосылыңыз
⚡️ Криптовалюта туралы ең соңғы және пайдалы ақпаратты алыңыз.
💬 Әлемдегі ең ірі криптобиржаның сеніміне ие.
👍 Расталған авторлардың нақты пікірлерін табыңыз.
Электрондық пошта/телефон нөмірі
Трендтегі тақырыптар
NvidiaLoses$2.7TrillionInMonthAndAHalf
21,076 рет көрілді
136 адам талқылап жатыр
Nvidia’s $2.7 Trillion Wipeout: When Narrative Overrides Numbers 📉
Crypto With Faisal
·7 лайк
·5.6k рет көрілді
CanBTCReboundAfterFallingBelow60K?
787,243 рет көрілді
3,018 адам талқылап жатыр
GlobalStocksFaceLongestLosingStreakSince2023
286,132 рет көрілді
2,015 адам талқылап жатыр