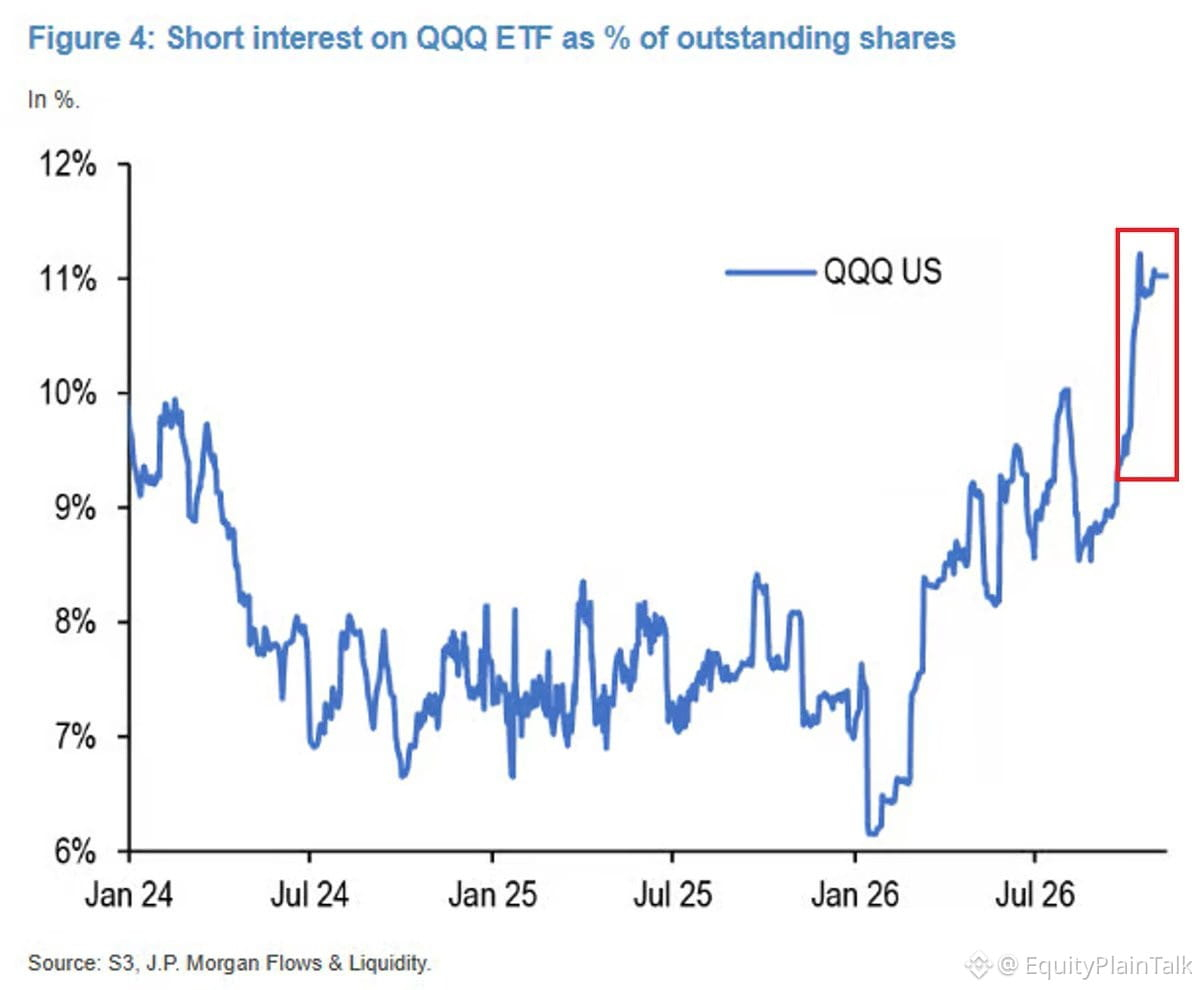
Short interest in $QQQ just hit 11% of outstanding shares—highest since 2023. That's a 5-point jump since January alone.
For context: during the 2022 bear market, it peaked around 14%. We're getting close.
Meanwhile, hedge fund positioning tells the same story. Goldman Sachs data shows the tech long-to-short ratio among hedge funds dropped to 1.5—the lowest reading since they started tracking it in 2016. That's down 0.6 points just since June.
What this means: a lot of smart money is betting against tech right now. When positioning gets this extreme, you have to ask—what happens if they're wrong? Or even if they're just early?
Short squeezes don't need a bull thesis. They just need crowded positioning and a catalyst. If tech catches any bid, those shorts become forced buyers. That's how violent moves happen.
Not saying it will squeeze. Just saying the setup is there.
For context: during the 2022 bear market, it peaked around 14%. We're getting close.
Meanwhile, hedge fund positioning tells the same story. Goldman Sachs data shows the tech long-to-short ratio among hedge funds dropped to 1.5—the lowest reading since they started tracking it in 2016. That's down 0.6 points just since June.
What this means: a lot of smart money is betting against tech right now. When positioning gets this extreme, you have to ask—what happens if they're wrong? Or even if they're just early?
Short squeezes don't need a bull thesis. They just need crowded positioning and a catalyst. If tech catches any bid, those shorts become forced buyers. That's how violent moves happen.
Not saying it will squeeze. Just saying the setup is there.