Macro-hardity vs AI rally: the main thing in the markets
On world platforms, the tough rhetoric of the US Federal Reserve has faced a continuous positive in the AI sector. Markets are traded in different directions 👇
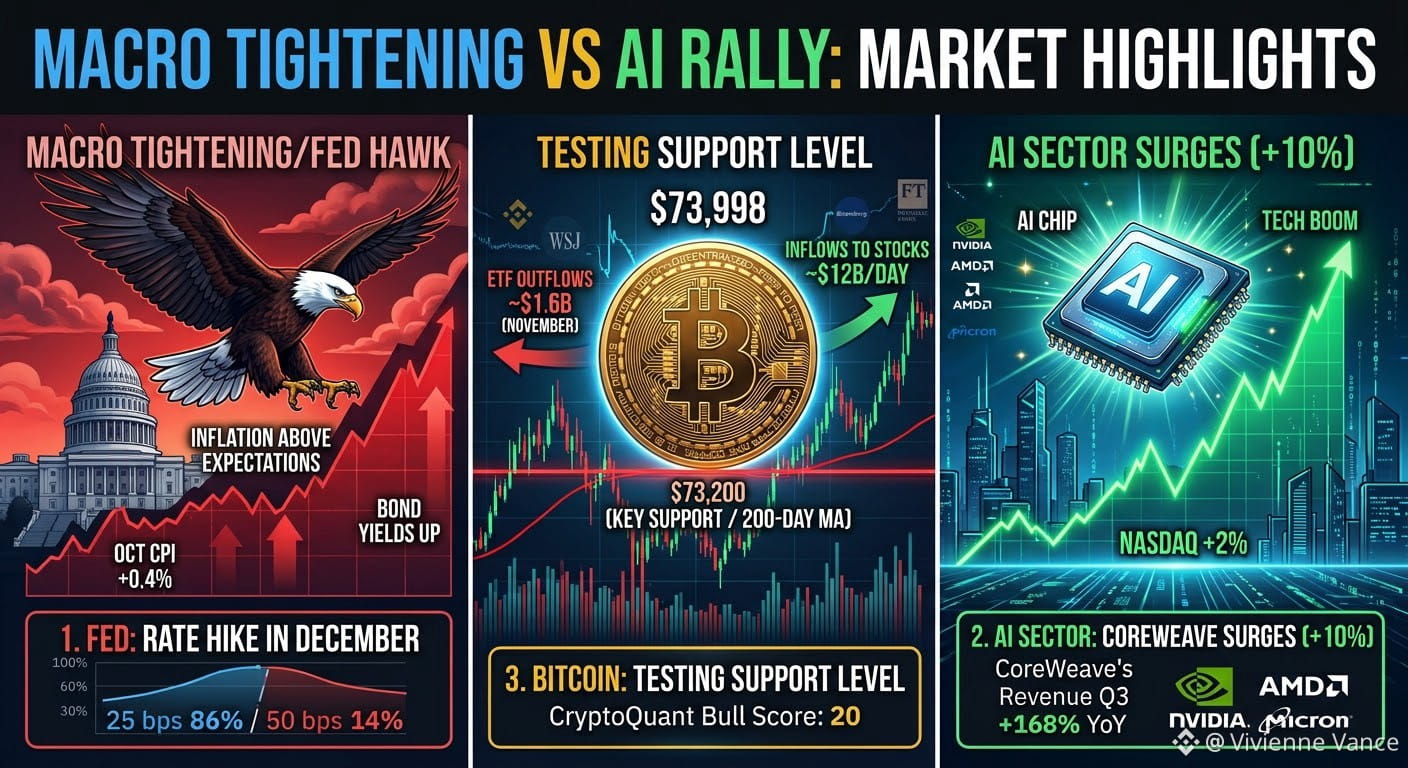
🦅 1. The Fed is preparing to raise the rate in December
The Inflation is higher than forecasts: the October CPI rose by 0.4% M/M (0.3 was expected), causing a bond sale.
Increase is "almost inevitable": Nick Timiraos (WSJ) writes that the meeting on December 8-9 will bring tightening.
Probability Markets lay 86% for a step of +25 b.p. and 14% for +50 b.p. Fed speakers (Waller, Logan) do not exclude acceleration.
💻 2. The AI sector drags Nasdaq up
CoreWeave Report: Revenue for Q3 soared by 168% YoY, and the forecast for 2026 increased to $13-13.3 billion. Shares +10%, Nasdaq futures 100 +2%.
Token of the list of Rally chipmakers and optics: AXT (+10.1%), Lumentum (+9.5%), Seagate (+8.6%), AMD (+7.3%), Micron (+6.9%), Nvidia (+4.1%).
Anthropic According to FT, bankers are considering the company's valuation of $1.5 trillion+, and IT giants are preparing $26 billion in investments.
🪙 3. Bitcoin is testing support
Price BTC is trading near $74,000 (-5.2% per week).
Outflow from BTC-ETF In November, funds lost ~$1.6 billion, but sales are slowing down (from $430 million to $95 million per day).
Stock Growth List Marker: Against the background of outflow from the crypt, American ETF shares receive ~$12 billion per day (by-the-deep).
Level from CryptoQuant: Key support zone - $73,200 (200-day moving average).
On world platforms, the tough rhetoric of the US Federal Reserve has faced a continuous positive in the AI sector. Markets are traded in different directions 👇
🦅 1. The Fed is preparing to raise the rate in December
The Inflation is higher than forecasts: the October CPI rose by 0.4% M/M (0.3 was expected), causing a bond sale.
Increase is "almost inevitable": Nick Timiraos (WSJ) writes that the meeting on December 8-9 will bring tightening.
Probability Markets lay 86% for a step of +25 b.p. and 14% for +50 b.p. Fed speakers (Waller, Logan) do not exclude acceleration.
💻 2. The AI sector drags Nasdaq up
CoreWeave Report: Revenue for Q3 soared by 168% YoY, and the forecast for 2026 increased to $13-13.3 billion. Shares +10%, Nasdaq futures 100 +2%.
Token of the list of Rally chipmakers and optics: AXT (+10.1%), Lumentum (+9.5%), Seagate (+8.6%), AMD (+7.3%), Micron (+6.9%), Nvidia (+4.1%).
Anthropic According to FT, bankers are considering the company's valuation of $1.5 trillion+, and IT giants are preparing $26 billion in investments.
🪙 3. Bitcoin is testing support
Price BTC is trading near $74,000 (-5.2% per week).
Outflow from BTC-ETF In November, funds lost ~$1.6 billion, but sales are slowing down (from $430 million to $95 million per day).
Stock Growth List Marker: Against the background of outflow from the crypt, American ETF shares receive ~$12 billion per day (by-the-deep).
Level from CryptoQuant: Key support zone - $73,200 (200-day moving average).