


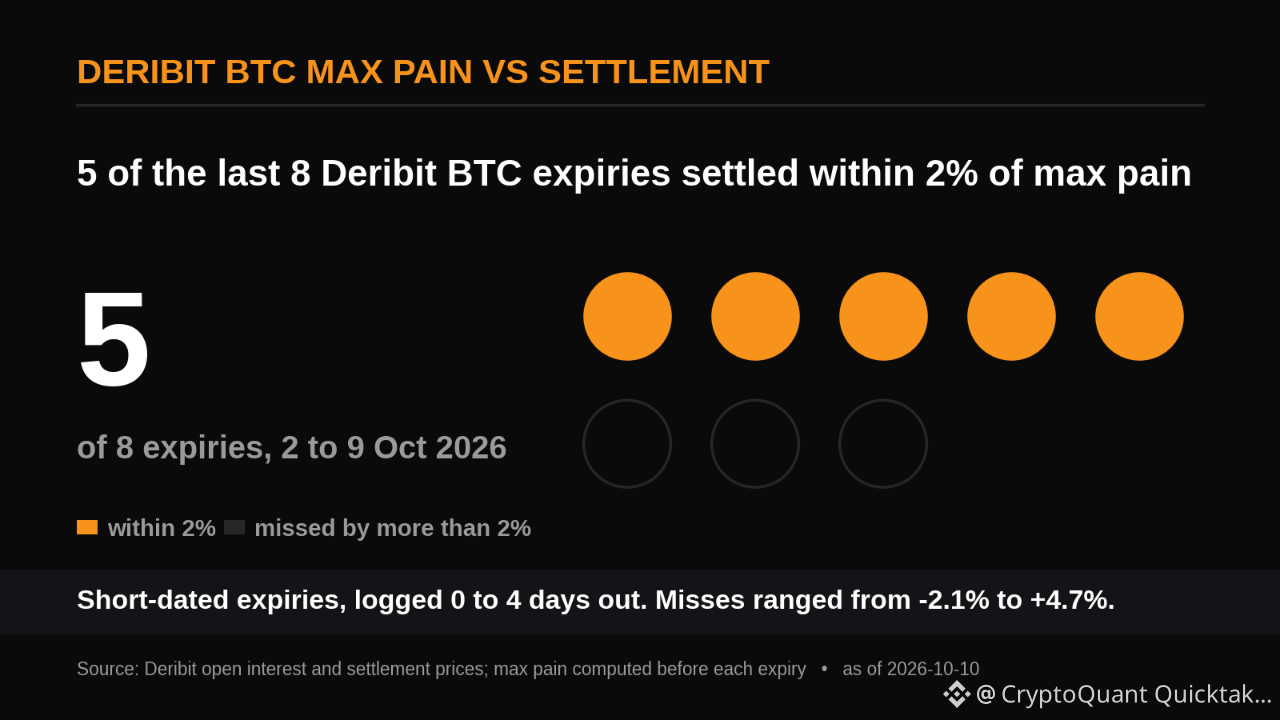
Bitcoin settled within 2% of the Deribit max pain level we computed beforehand on 5 of the last 8 expiries, from 2 to 9 October. The three misses ran as wide as 4.7%.
Max pain is the strike where option holders collectively lose the most at expiry, not a price target. These were short-dated expiries, logged 0 to 4 days out, and over that span 2% is roughly one ordinary day of movement at current realized volatility. A 5-of-8 hit rate on dailies says more about how quiet spot was than about any pull toward a strike.
The positioning is louder further out. On the 30 October monthly, max pain sits at $78,000 with spot at $82,555. The largest single strike on that expiry is the $95,000 call, with 25,032 BTC of open interest, about $2.1 billion at spot. Traders are paying for upside, not hiding from it.
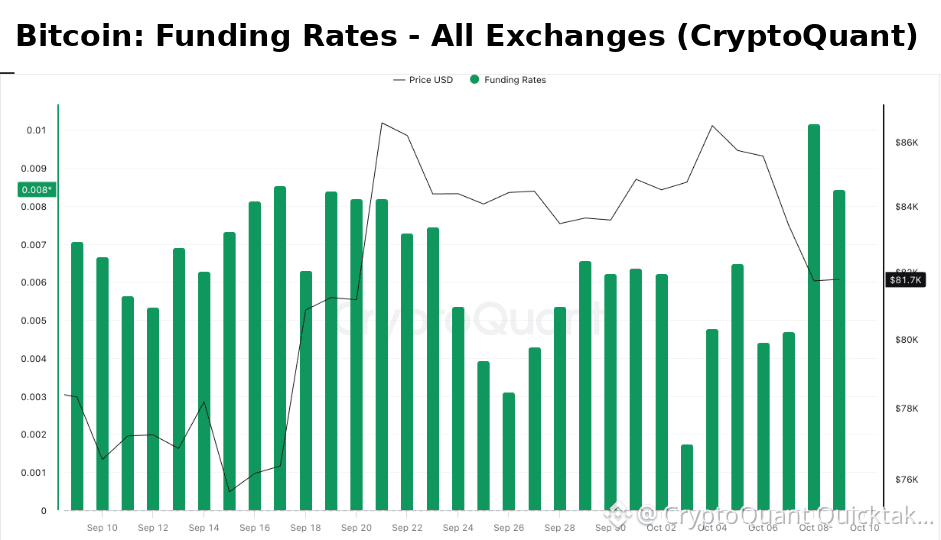
CryptoQuant's all-exchange Funding Rates show the futures side. The 8 October bar is the tallest of the past 30 days, at about 0.010, and it printed on a day price fell. Perpetual longs paid more to hold exposure as BTC slipped.
Max pain on a daily expiry describes where spot already is.
Options also tend to overprice movement. Across 1,595 days from April 2022 to September 2026, DVOL priced more volatility than the next 30 days delivered on 73.5% of them.
What would change this read: a 30 October settlement within 2% of $78,000 would give max pain a cleaner monthly data point than any daily can. A settlement up toward the $95,000 strike would say the call-heavy open interest, and the longs paying funding, mattered more than the pain math.
Data: Deribit open interest and settlements; CryptoQuant all-exchange Funding Rates.
Written by The Daily Digits