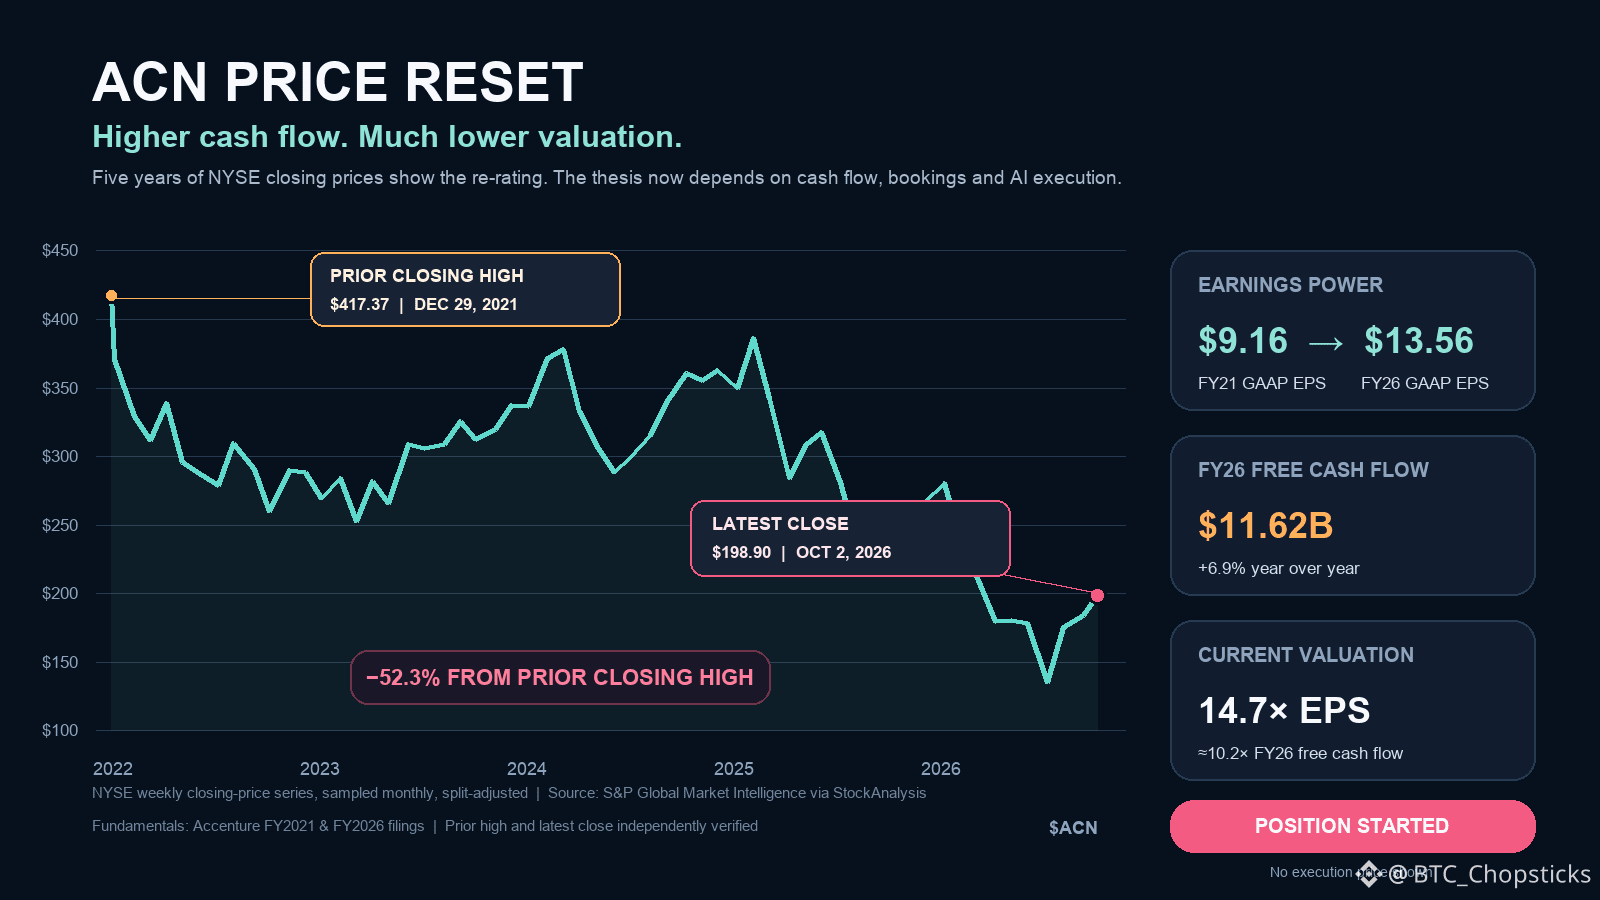
I started a position in $ACN .
The stock is down 52.3% from its 2021 closing high, but the business didn't shrink with the share price.
At $198.90, Accenture trades at roughly 14.7× FY2026 GAAP EPS, with about a 9.8% trailing FCF yield.
FY2026 free cash flow reached $11.62B, up 6.9% YoY.
The bet is the AI contradiction.
AI can automate work consultants used to bill for. Enterprises still need someone to connect models, data, security and workflows inside production systems.
I think Accenture's client relationships and delivery scale can capture enough implementation and managed-services demand to offset that pressure.
I'm watching bookings, margins and free cash flow, not AI headlines.
If automation erodes billable work faster than new AI revenue develops, the thesis breaks.
The stock got much cheaper. Now the business has to prove the market got too pessimistic.