StableSwap vs Constant Product which curve fits the pair?
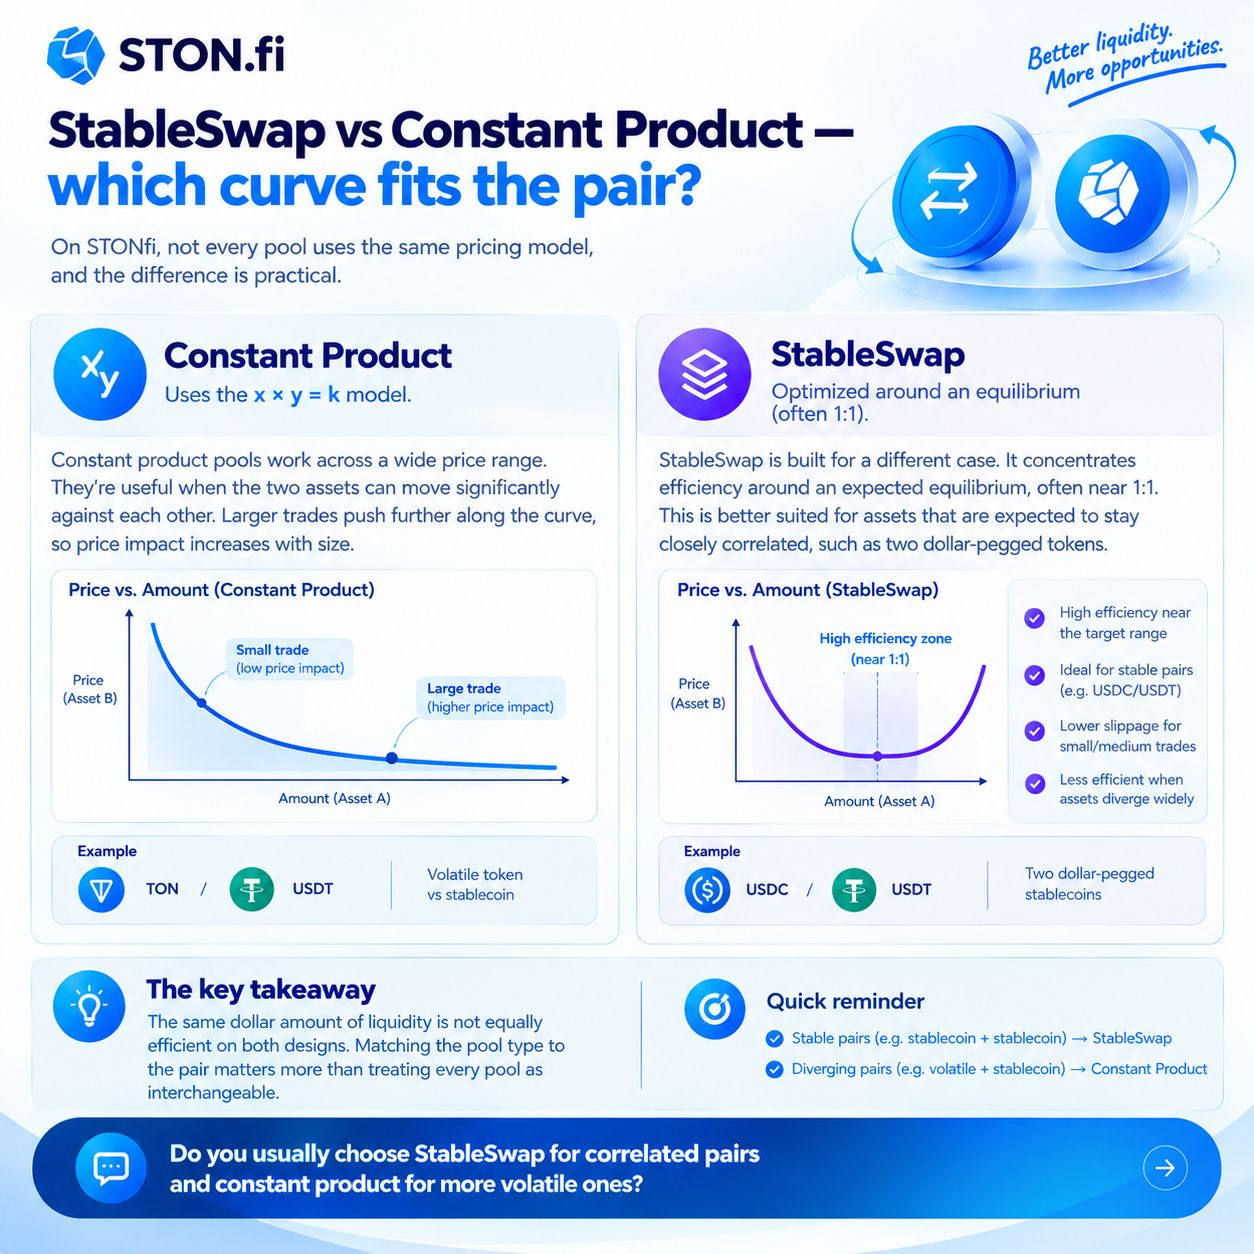
On STONfi, not every pool uses the same pricing model, and the difference is practical.
Constant product pools follow the x * y = k design. They work across a wide price range, which makes them useful when the two assets can move significantly against each other. Larger trades push further along the curve, so price impact increases with size.
StableSwap is built for a different case. It concentrates efficiency around an expected equilibrium, often near 1:1. This is better suited for assets that are expected to stay closely correlated, such as two dollar-pegged tokens. The same liquidity can be more efficient when the price stays near that range.
The important takeaway is simple: the same dollar amount of liquidity is not equally efficient on both curves. Matching the pool type to the pair matters more than treating every pool as interchangeable.
Do you usually choose StableSwap for correlated pairs and constant product for more volatile ones?
#STONfi #defi $GRAM