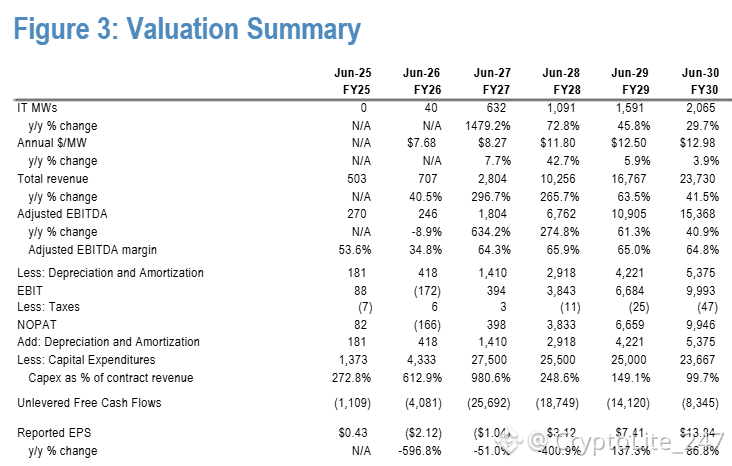
JPMorgan sees $IREN becoming a 2,065 MW business generating ~$24B of revenue with 65% EBITDA margins by 2030.
Whats really interesting is the pricing assumption because JPMorgan only models ~$13M per MW by FY30 while IREN is already around ~$11M today and management is discussing contracts closer to ~$25M.
So if we use the ~$25M on same 2,065 MW base then that would imply $50B+ of revenue before any additional capacity upside.
Whats really interesting is the pricing assumption because JPMorgan only models ~$13M per MW by FY30 while IREN is already around ~$11M today and management is discussing contracts closer to ~$25M.
So if we use the ~$25M on same 2,065 MW base then that would imply $50B+ of revenue before any additional capacity upside.