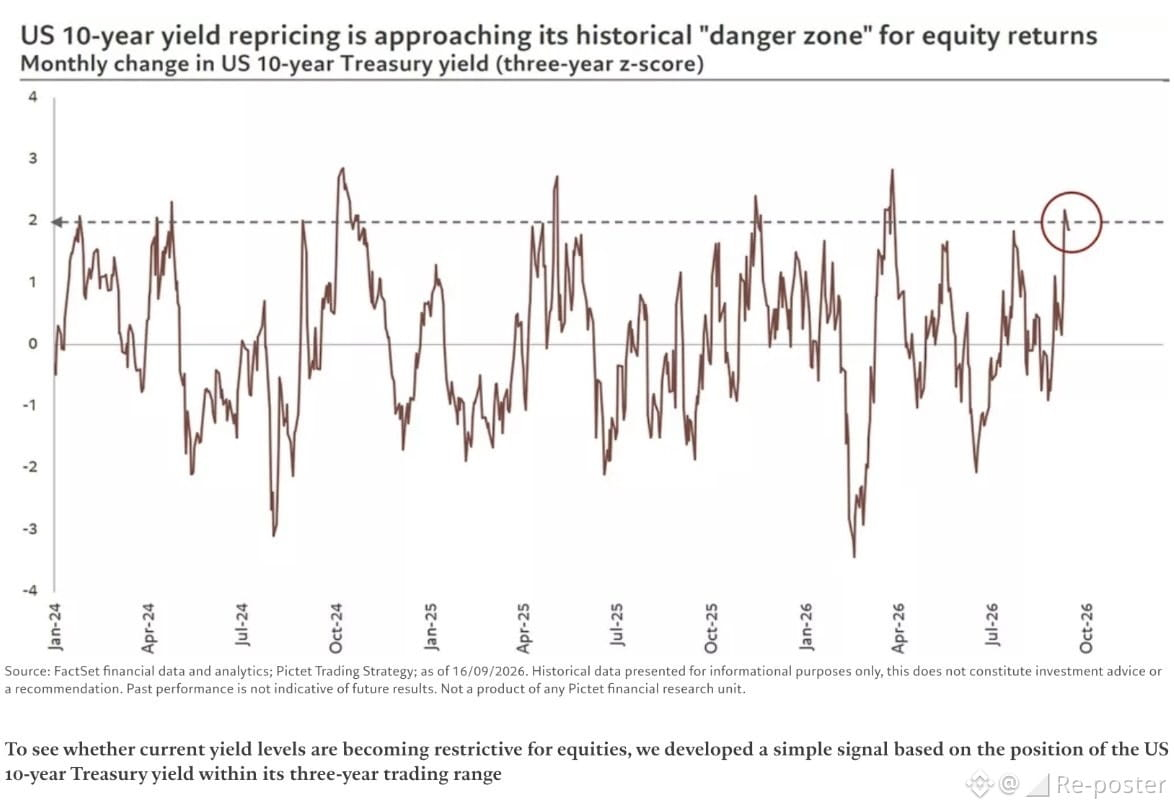
@PictetGroup makes the case that it is not just the absolute level of yields that damages equities, but the pace of the move.
The speed of yield repricing matters more than level.
Moves above 2 standard deviations are historically the worst.
We just passed +2 standard deviations last week.
The speed of yield repricing matters more than level.
Moves above 2 standard deviations are historically the worst.
We just passed +2 standard deviations last week.