$TRUMP
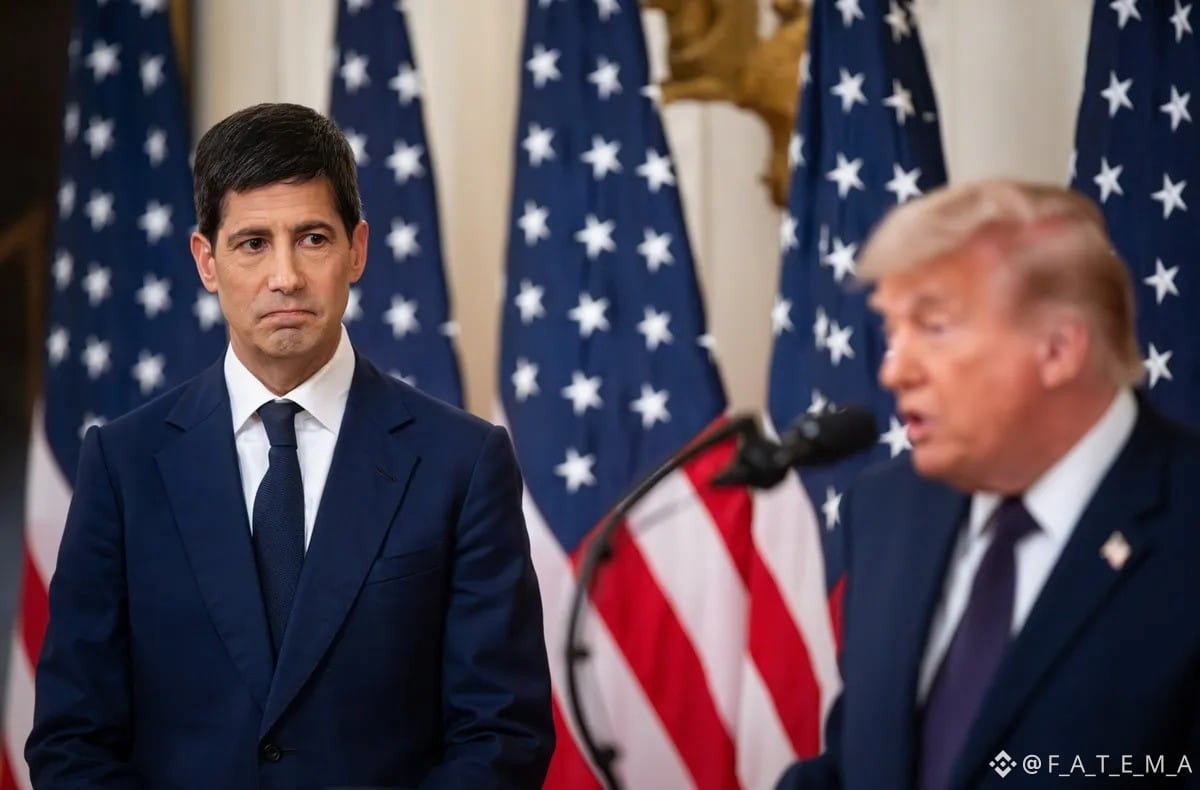
🇺🇸 The Fed just did exactly what Trump didn’t want.
Interest rates are going UP for the first time in 3 years, with officials unanimously voting for a quarter-point hike to 3.75% to 4%.
Trump has spent more than a year demanding dramatically lower rates and, within hours of the decision, was back on Truth Social calling for rates of “1%, or less.”
“LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”
Instead, Fed Chair Kevin Warsh, the man Trump picked expecting lower rates, said the Fed had “removed a dose of accommodation.”
The problem is inflation still won’t behave.
Tariffs, the Iran war pushing up energy prices and an enormous AI investment boom have all added pressure. The Fed now expects inflation to remain above its 2% target until 2029.
And this probably isn’t one-and-done.
16 of 18 Fed officials see at least one more hike before the end of the year. 4 officials even expect 2 hikes.
What does that mean for your wallet?
Credit cards: more expensive almost immediately. Carrying a balance just got uglier.
Mortgages: fixed-rate owners are insulated. New buyers and anyone on an adjustable rate, not so much, with mortgage rates already hovering near 7%.
Savings: finally, some good news. High-yield accounts, CDs and money-market funds should benefit, assuming your bank actually passes the higher rates on.
WalletHub estimates this single quarter-point hike could cost credit-card borrowers around $2 billion in additional interest over the next 12 months.
So while Washington fights over whether rates should be 1% or 4%, anyone carrying debt gets to pay for the argument.
Sources: Reuters, Bloomberg, Federal Reserve,
#FedRateWatch
🇺🇸 The Fed just did exactly what Trump didn’t want.
Interest rates are going UP for the first time in 3 years, with officials unanimously voting for a quarter-point hike to 3.75% to 4%.
Trump has spent more than a year demanding dramatically lower rates and, within hours of the decision, was back on Truth Social calling for rates of “1%, or less.”
“LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”
Instead, Fed Chair Kevin Warsh, the man Trump picked expecting lower rates, said the Fed had “removed a dose of accommodation.”
The problem is inflation still won’t behave.
Tariffs, the Iran war pushing up energy prices and an enormous AI investment boom have all added pressure. The Fed now expects inflation to remain above its 2% target until 2029.
And this probably isn’t one-and-done.
16 of 18 Fed officials see at least one more hike before the end of the year. 4 officials even expect 2 hikes.
What does that mean for your wallet?
Credit cards: more expensive almost immediately. Carrying a balance just got uglier.
Mortgages: fixed-rate owners are insulated. New buyers and anyone on an adjustable rate, not so much, with mortgage rates already hovering near 7%.
Savings: finally, some good news. High-yield accounts, CDs and money-market funds should benefit, assuming your bank actually passes the higher rates on.
WalletHub estimates this single quarter-point hike could cost credit-card borrowers around $2 billion in additional interest over the next 12 months.
So while Washington fights over whether rates should be 1% or 4%, anyone carrying debt gets to pay for the argument.
Sources: Reuters, Bloomberg, Federal Reserve,
#FedRateWatch