
Almost nobody is arguing about 25 basis points anymore 🤔
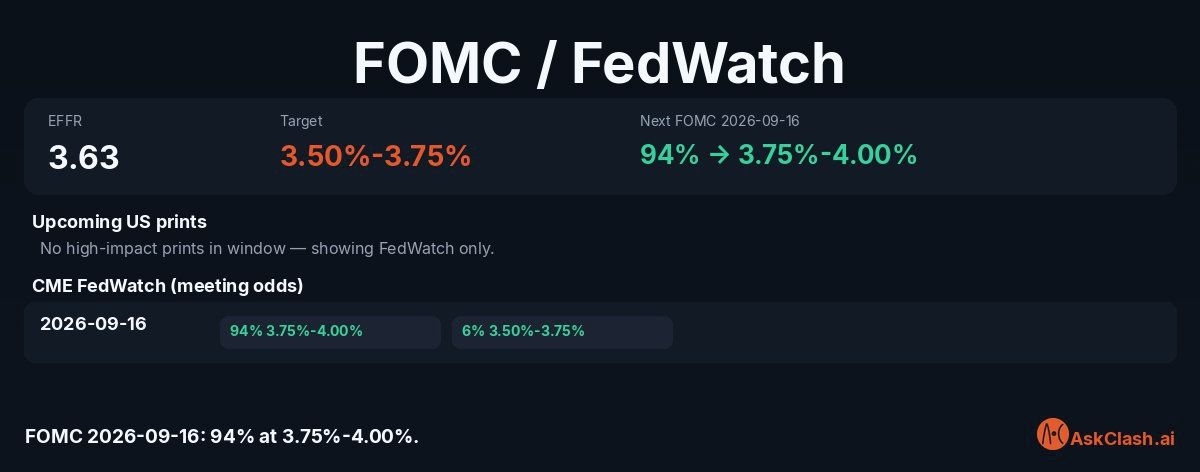
Look at the probability chart. A month ago, holding at 3.50–3.75% was the popular bet. A week ago it was a fight. Now the 3.75–4.00% bucket is a wall, close to 94%. That means Wednesday’s decision is not the event. The event is whether the statement treats August inflation as a messy month, or as the first brick of a new tightening cycle.
That distinction is where most posts go flat. They ask “hike or hold?” The market already answered. The tradeable question is: one insurance hike, or the start of a bill that keeps arriving?
The print that looks soft and hard at the same time
August #CPI did something awkward.
Headline rose 0.4% on the month and 3.4% over the year. Core CPI includes food and energy stripped out, rose 0.3% month-over-month versus a 0.2% consensus. The annual core rate still eased to 2.4%, the slowest since 2021.
So you can write two honest headlines from the same release:
“Underlying inflation is the coolest in five years.”
“The monthly core run-rate just accelerated.”
The Fed lives in the second sentence. Year-over-year core is a rear-view mirror still digesting older, hotter prints. Officials vote on whether the latest month looks like progress or like a pause that failed. Energy did the loud part: +2.1% on the month, +16.3% over the year. That is not the same animal as 2022 demand-overheating. It is a supply bruise sitting on a labor market that still printed firm payrolls.
A 25bp hike can be rational as insurance. It is a much weaker case as the opening of a multi-meeting campaign — unless the press conference pretends energy is “just inflation” and ignores the source.
Why a fully priced hike still moves risk
If 90% is already in the price, why would Bitcoin, Nasdaq, or gold $XAU care?
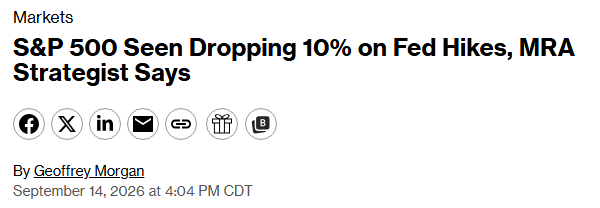
Because assets do not reprice the 25bp. They reprice the path.
Tech is duration. A hike that sounds like “we are done after this” is a shrug. A hike that keeps December alive is a valuation haircut. Long-duration names feel language before they feel the funds rate.
Gold splits in two. If the story is sticky inflation and messy geopolitics, gold keeps a bid. If the story is higher real rates and a stronger dollar, gold pays the rate tax like everything else.
Bitcoin is the awkward guest. Some weeks it still tags along with Nasdaq beta. Other stretches this year it has spent more time walking next to gold. Into a priced hike, the first hour is usually a liquidity squeeze. The second hour is a referendum on whether the Fed sounded finished.
That is why “BTC dumps on hikes” is a lazy rule. BTC dumped in 2022 because the path was many hikes from zero. A single, widely advertised 25bp from 3.50–3.75% is a different machine. The damage lives in the adjective: “ongoing,” “further,” “restrictive for longer.”
One-off versus cycle: A simple test
A cycle needs the Fed to believe demand is the problem.
Watch three things Wednesday, not the vote itself:
Do they call energy a temporary shock or a reason to keep tightening?
Does the statement keep “further firming” on the table, or does it go back to data-dependence without a threat?
Do the dots show one move, or a staircase?
If it is one-and-done language, the 90% odds were the whole show. Risk can even bid the fact that uncertainty just collapsed. If the dots lean hawkish, the market has to price a second invoice it has only half-written.
What I am doing with Bitcoin
I am not using FOMC as an entry trigger.
I hold $BTC as a multi-year position. The plan is boring on purpose. If the statement is hotter than a fully priced hike and spot gives a cleaner level than the coins I already own, I add on a fixed DCA size. Same rules as any other dip I did not cause. No leverage into the announcement. No “I knew they’d hike” after the fact.

The edge this week is not prediction. It is refusing to confuse a 25bp that everyone sees with a cycle that nobody has proven.
Most feeds will celebrate or panic at 2:00 p.m. Eastern. The useful work starts in the paragraph after the decision, the one that tells you whether September was an insurance premium, or the first line of a longer tab.
Educational only. Not financial advice. Size for both paths.