


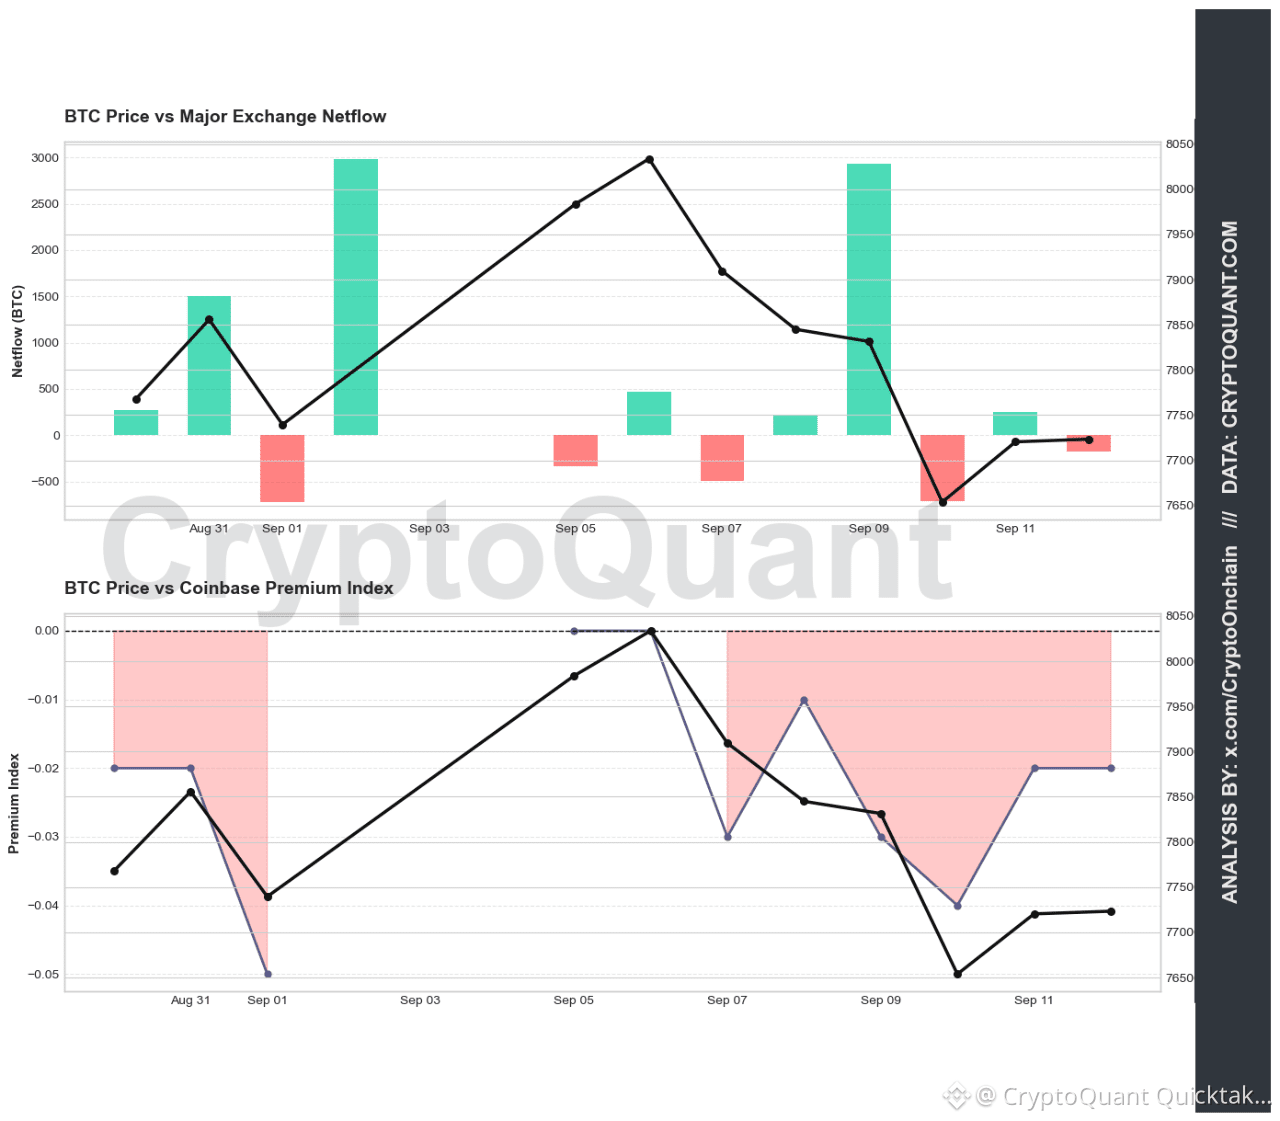
Aggregate exchange netflow averaged +717 BTC daily over the trailing seven days. The NVT Golden Cross registered a reading of 0.80 on September 12. Coinbase inflows from entities holding 1k–10k BTC averaged 712 BTC daily across the observation window.
The same week carried PPI (Sep 10) and CPI (Sep 11). Headline CPI printed 3.4% YoY for August 2026, released Sep 11, with core at 2.4%. PPI final demand stood at 5.4% YoY for August 2026, released Sep 10. The 10-year yield closed at 4.95%, holding a +39bp spread over the 2-year. The dollar index softened 1.9% across the 60-day window. One candidate explanation, unverified: the rotation may reflect positioning ahead of CPI rather than a response to it.
Broad exchange netflow expanded across multiple venues, with OKX (+4,590% vs. quarterly baseline), Bitget (+441%), and Upbit (+236%) all showing structural advances. This supply arrival coincides with a 102% increase in spending from the 10-year-plus cohort (326 BTC daily). While dormant supply and whale-tier deposits mobilize simultaneously, Binance funding holds flat (0.00–0.01) and the Coinbase Premium Index maintains a negative posture (-0.04 on September 10). Combining multi-venue supply deposits with subdued US institutional spot premiums creates conditions that historically preceded extended absorption phases rather than immediate markup.
September 3 and 4 carry no price, funding, or exchange flow prints; weekly trailing means rest on five sessions, not seven. The Binance 12m–18m age-band inflow series carries no information due to a near-zero denominator and is excluded. The dollar figure is the Fed broad dollar proxy.
For now, the clearest reading is that broad supply arrival has temporarily outpaced institutional spot demand, requiring the market to digest excess inventory before positioning can safely reset.
Written by CryptoOnchain