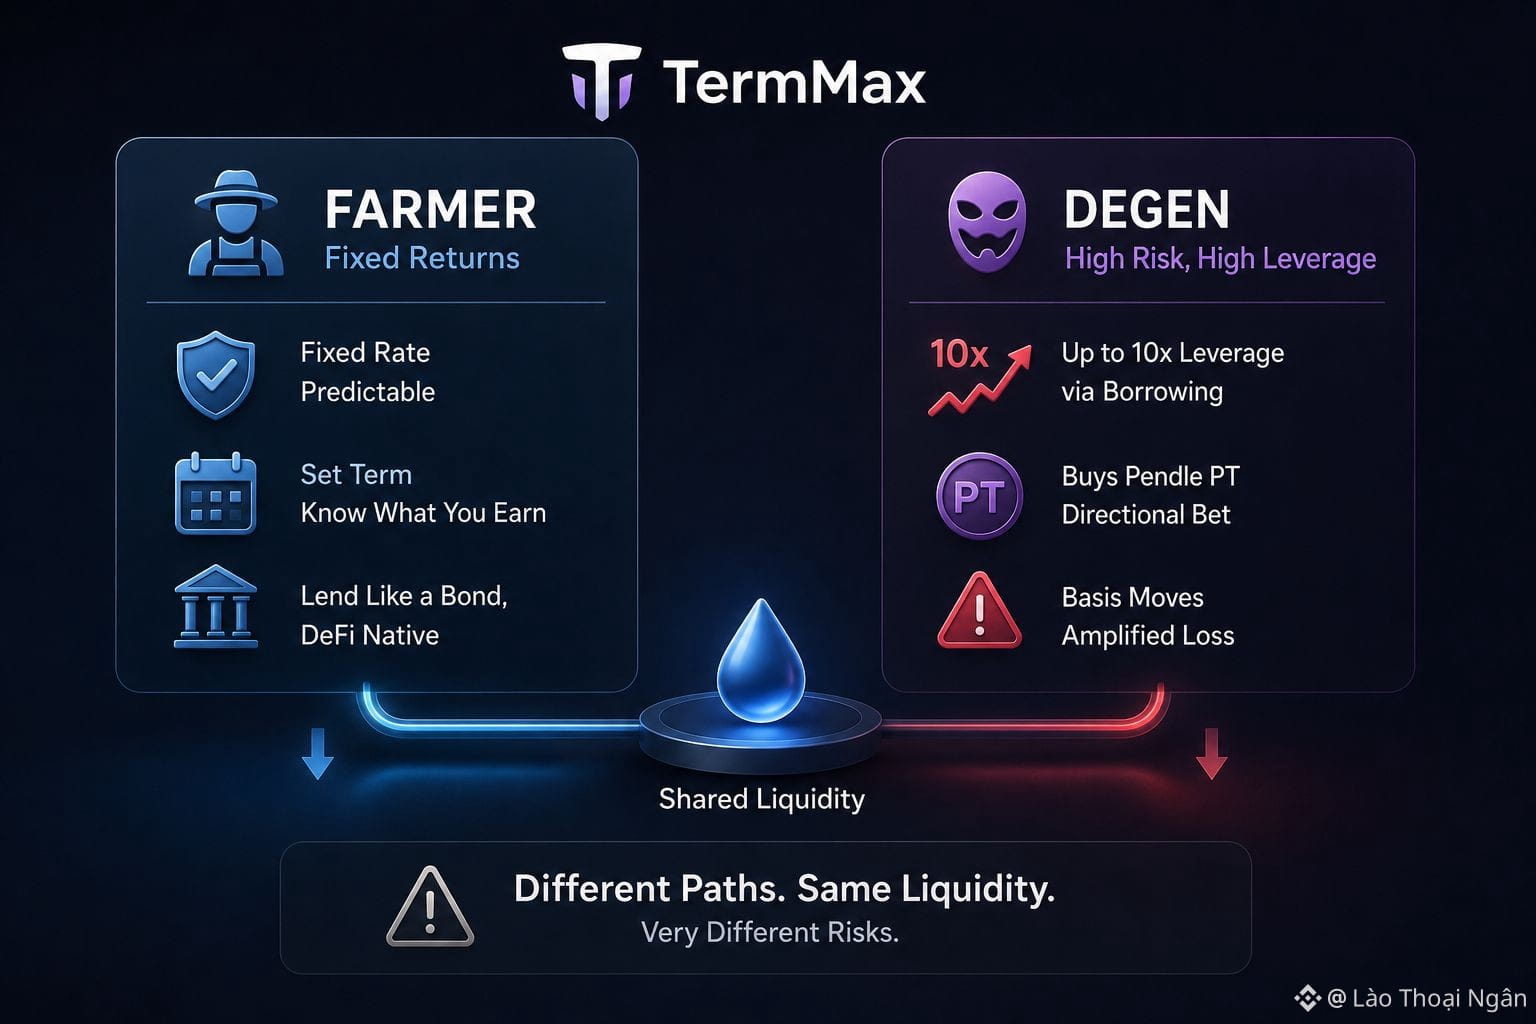
Read TermMax's own framing and you'll find three types of users described right in the documentation: Degens, Farmers, and LPs. That's an honest label, and I respect the honesty, but it also exposes a gap I keep coming back to. TermMax markets its fixed-rate architecture as the antidote to DeFi's floating-rate chaos, a place where lenders finally get the predictability of a bond instead of a number that resets with every block. That's the Farmer pitch, and it's a good one.
Then there's the Degen vault. A depositor puts in capital, the vault borrows nine times that amount from LP liquidity at a fixed rate, and the combined position buys Pendle Principal Tokens for roughly 10x leverage on the underlying yield spread. That's not a bond. That's a leveraged directional bet with a fixed financing cost, closer in spirit to a margin trade than to a term deposit, and TermMax builds it into the same platform that pitches "predictable returns for lenders" front and center.
It's also worth asking who actually reads the fine print before depositing. A Farmer chasing a fixed 6% doesn't necessarily open the same page as a Degen chasing 10x, yet both deposits ultimately draw from and feed back into the same underlying liquidity, which means the calm product and the loud product are more connected under the hood than the separate branding on the homepage might suggest to a first-time visitor.
Neither product is wrong to offer. But the branding sits closer to fixed income than the full product range actually is, and a new user scanning "fixed-rate DeFi" might not immediately clock that one path on TermMax carries default risk multiplied tenfold if the PT basis moves against the position. I'd want TermMax to draw a brighter line between the Farmer product and the Degen product in its own marketing, because right now the calm framing up front covers a much louder mechanism underneath, and two very different audiences reading that same homepage are taking on very different risk without equal warning.
@TermMax #TermMax $BTW $PORTAL $HEMI
Then there's the Degen vault. A depositor puts in capital, the vault borrows nine times that amount from LP liquidity at a fixed rate, and the combined position buys Pendle Principal Tokens for roughly 10x leverage on the underlying yield spread. That's not a bond. That's a leveraged directional bet with a fixed financing cost, closer in spirit to a margin trade than to a term deposit, and TermMax builds it into the same platform that pitches "predictable returns for lenders" front and center.
It's also worth asking who actually reads the fine print before depositing. A Farmer chasing a fixed 6% doesn't necessarily open the same page as a Degen chasing 10x, yet both deposits ultimately draw from and feed back into the same underlying liquidity, which means the calm product and the loud product are more connected under the hood than the separate branding on the homepage might suggest to a first-time visitor.
Neither product is wrong to offer. But the branding sits closer to fixed income than the full product range actually is, and a new user scanning "fixed-rate DeFi" might not immediately clock that one path on TermMax carries default risk multiplied tenfold if the PT basis moves against the position. I'd want TermMax to draw a brighter line between the Farmer product and the Degen product in its own marketing, because right now the calm framing up front covers a much louder mechanism underneath, and two very different audiences reading that same homepage are taking on very different risk without equal warning.
@TermMax #TermMax $BTW $PORTAL $HEMI