To view keyboard shortcuts, press question markView keyboard shortcuts
Wall Street Is Modeling Micron's Smallest Beat in Six Quarters
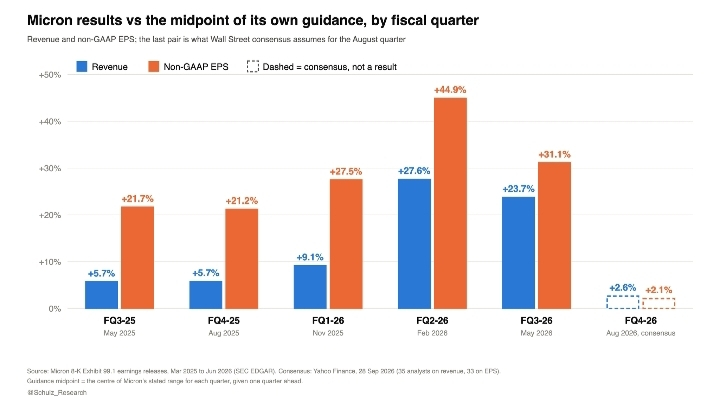
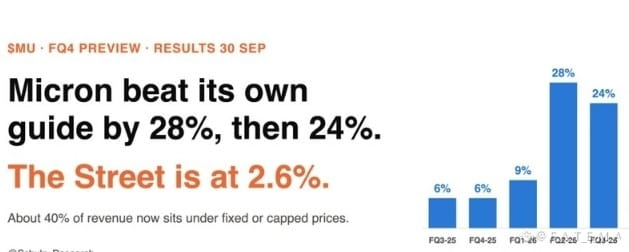
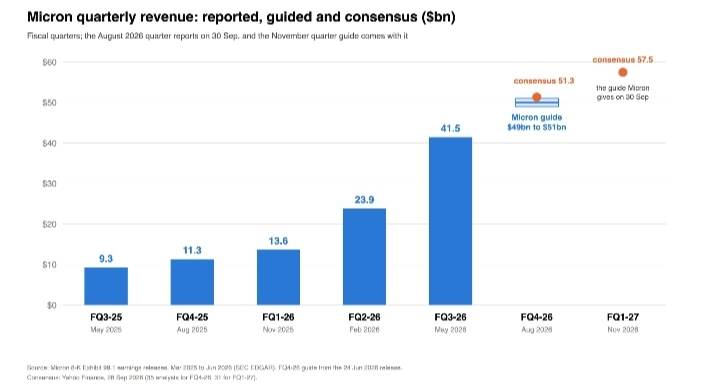
beat the midpoint of its own revenue guidance by 28% in the February quarter and 24% in the May quarter. For the August quarter, which it reports on Wednesday, the Street is at
$51.3bn
against a
$50bn
guide. That's a 2.6% beat, less than half the smallest one Micron actually delivered in any of the last five quarters.
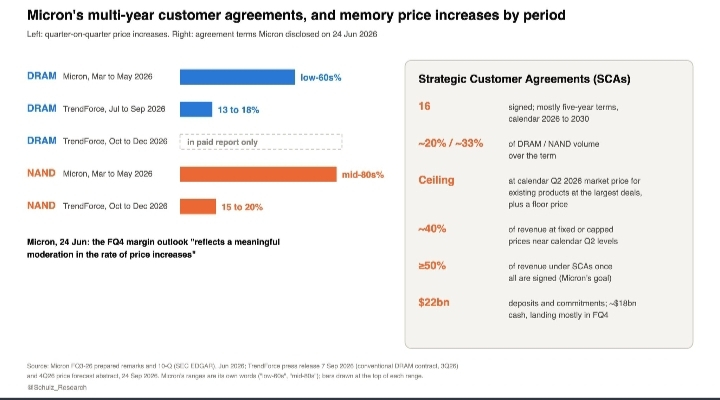
We think the Street has a reason. In June Micron said about 40% of its revenue now sits at fixed prices or under ceilings set at spring market prices. Capped prices leave less room for surprise, so the number that decides Wednesday is the November-quarter guide, against a
$57.5bn
consensus.
This is the first of four pieces on this print: the preview, the numbers when they land, the call, and a full report at the end. The questions at the bottom are the ones the next piece will answer.
The bar for Wednesday
Micron guided the August quarter to revenue of
$50.0bn
plus or minus
$1.0bn
, gross margin of about 86% and non-GAAP EPS of $31.00 plus or minus $1.00. Consensus is
$51.32bn
from 35 analysts and EPS of $31.65 from 33, above the top of Micron's range on revenue and inside it on EPS. For the November quarter consensus sits at
$57.46bn
and $35.58.
Results come after the US close on Wednesday 30 September, with the call at 4:30pm Eastern, which is 04:30 Thursday in Beijing.
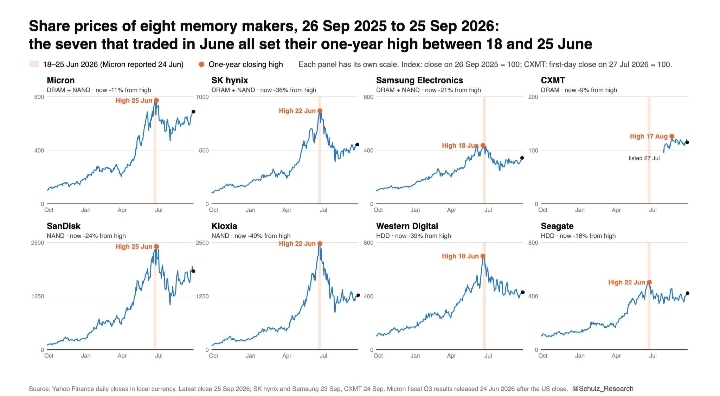
In Monday's US pre-market the stock was around $1,060, down about 2% from Friday's $1,082 close. That's 6.6 times consensus fiscal 2027 EPS of $160.19. A multiple like that says the market is treating this year as close to the peak.
Why the beats should shrink
Micron flagged this in June. The August-quarter margin outlook, in its words, "reflects a meaningful moderation in the rate of price increases." In the May quarter its DRAM prices rose in the "low-60s" percent and NAND in the "mid-80s". TrendForce now projects conventional DRAM contract prices up 13% to 18% for the September quarter and total NAND up 15% to 20% for December. Its December DRAM numbers sit behind a paywall, but the public summary carries one line that matters here: "LTAs cap hikes."
The contracts are the real change. Micron has signed 16 Strategic Customer Agreements, mostly five years running through 2030, covering about 20% of its DRAM volume and a third of its NAND. The largest carry a ceiling at the calendar Q2 2026 market price, plus a floor. Micron puts fixed or capped revenue at about 40% of the total and wants half or more of revenue under these agreements once they're all signed.
So Micron swapped part of its upside on 40% of sales for a floor that, in its words, gives "a very robust gross margin for Micron, well above our peak quarterly margins in any past cycle." Beats get smaller. In exchange the downside has a floor, and there's about
$100bn
of cumulative revenue at minimum prices across 14 of the 16 deals.
How much margin is left
Gross margin landed 2.2, 3.7, 5.5, 7.4 and then 3.6 points above the guide over the last five quarters. Last quarter's beat was half the one before it. At 86%, cost of goods is 14 cents on the dollar, so almost every extra point from here has to come from price, and price is the thing the contracts now limit.
Where estimates are moving
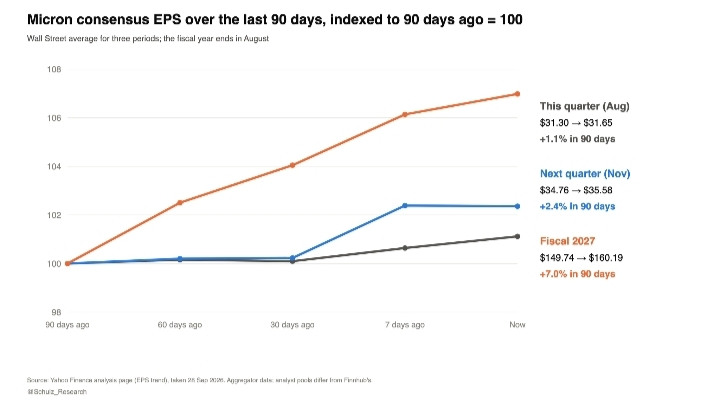
Consensus EPS for this quarter has barely moved in 90 days, from $31.30 to $31.65. In the last 30 days two analysts cut it and none raised it. The November quarter is up 2.4%. Fiscal 2027 is up 7.0% to $160.19.
Analysts aren't leaning on Wednesday's number. They're leaning on next year, which makes the guide and anything Micron says about fiscal 2027 supply the part that can move estimates.
HBM is no longer the top-margin unit
In the May quarter Cloud Memory, the unit that sells to hyperscalers and includes HBM, had an operating margin of 78%. Mobile and Client made 86% and Core Data Center 83%. A year earlier Cloud Memory had the highest operating margin of the four, at 46%.
Our read: HBM pricing was set in advance, while phone, PC and server DRAM re-priced every quarter through a very steep run. Micron said HBM4 revenue has already passed
$1bn
and the 12-high ramp is "tracking twice as fast as HBM3E 12-high." If Cloud Memory's margin closes the gap this quarter, HBM pricing has caught up. If the gap widens, commodity DRAM is still the better business right now.
Capex
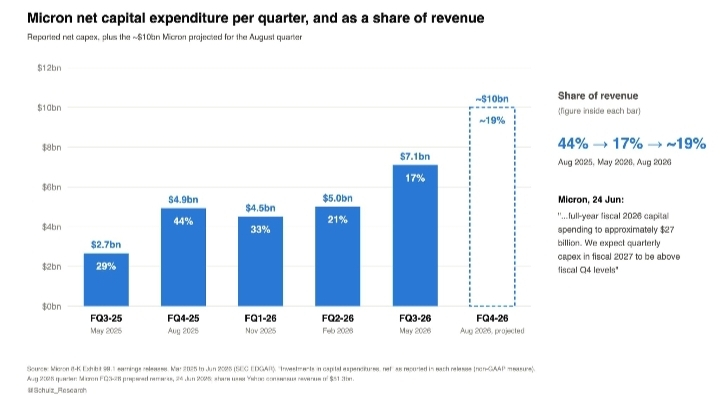
Net capex was
$7.1bn
in the May quarter, 17% of revenue, down from 44% a year earlier. Micron projected about
$10bn
for the August quarter, around
$27bn
for fiscal 2026, and said quarterly capex in fiscal 2027 will run above the August level, with more than half of the year-on-year increase going to construction.
It also said supply and demand for both DRAM and NAND should stay tight "beyond calendar 2027" and that it has no "line of sight as to when memory supply will be able to catch up." The first fiscal 2027 capex figure will show how long management expects that to last.
Three outcomes
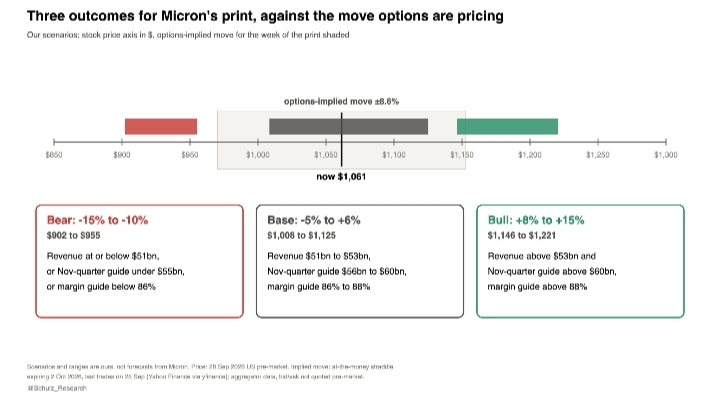
Options expiring 2 October price a move of about 8.6% either way, based on Friday's at-the-money straddle.
Bear, down 10% to 15%: revenue at or below
$51bn
, a November guide under
$55bn
, or a margin guide below 86%. EPS near $31.
Base, down 5% to up 6%: revenue of
$51bn
to
$53bn
, a November guide of
$56bn
to
$60bn
, margin guide of 86% to 88%. EPS around $32.
Bull, up 8% to 15%: revenue above
$53bn
, a November guide above
$60bn
and a margin guide above 88%. EPS of $33 or more.
We lean to the base case. Revenue around
$52bn
would be a smaller beat than Micron's recent record but still above the Street, and a November guide near
$58bn
would keep the stock inside the implied move. A bull outcome needs prices on the roughly 60% of revenue that isn't fixed or capped to still be running hot, and TrendForce's numbers say the rate of increase is slowing.
Dates around the print
Taiwan runs straight into the results. The Taoyuan union holds a briefing on 29 September and votes on a strike from 1 to 6 October. The Taichung union's second mediation is on 22 October. Micron said on 21 September that it mediated in good faith and asked to keep talking. The union wants a profit-sharing scheme, and Taiwan press reports the proposal is waiting on Micron's US board.
Also open: a Munich court granted YMTC two first-instance injunc
Sources
Micron earnings releases and prepared remarks (company; management leans optimistic, though its guidance has been conservative for five straight quarters). Micron 10-Q and 8-K via SEC EDGAR (filed under liability, no discount). Consensus and EPS trend from Yahoo Finance (aggregator of sell-side estimates; sell-side leans long).