


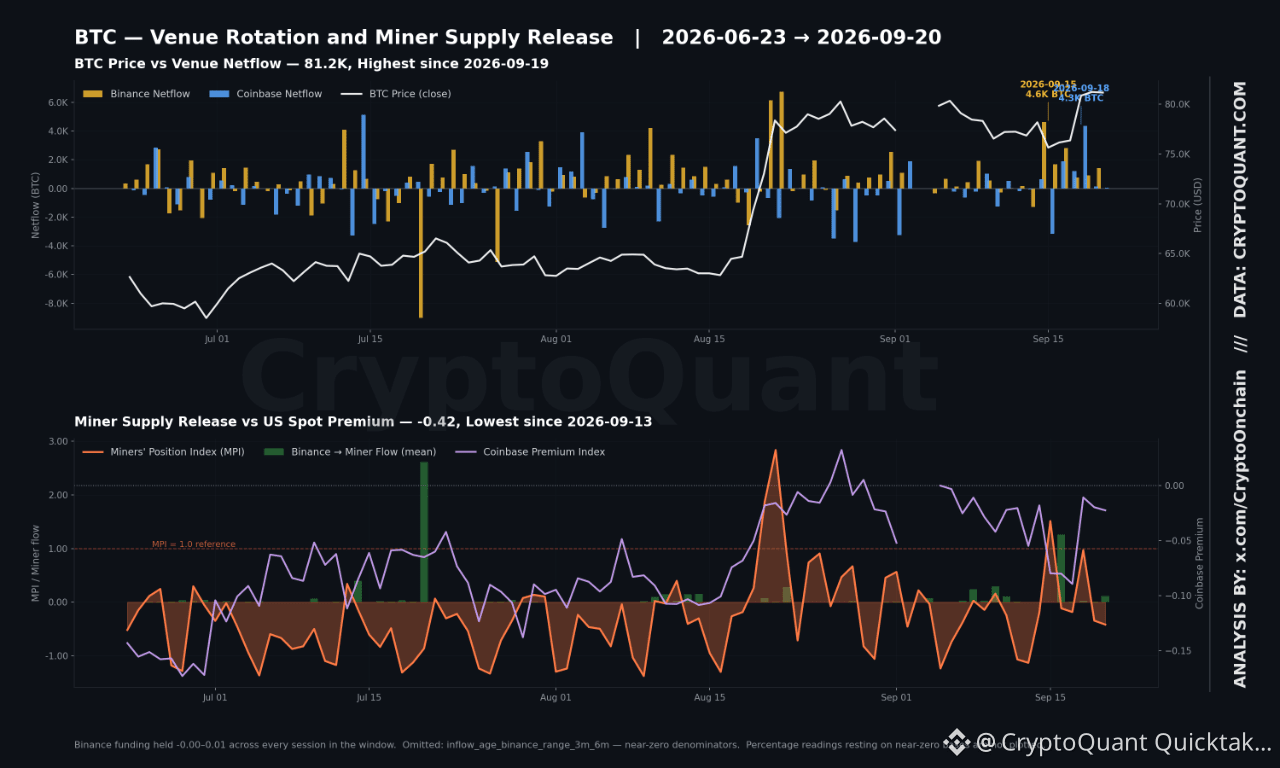
Bitcoin closed at 81,224.60 on September 19, the highest print of the reported window. Coinbase netflow reached +4,347.08 BTC on September 18. The Miners’ Position Index averaged 0.17 in the week ending September 20, 814% above the monthly baseline.
Two series are excluded: NVT Golden Cross shows +37,431% quarterly on a near-zero base — only its 0.47 level and −47% weekly move are usable. Age-band inflows (binance_3m_6m at 0.23 BTC, all_10y_inf at 3.59 BTC) sit on denominators too low to publish, and the former returns no week-over-week value at all.
The FOMC decision and Retail Sales both landed September 16, two sessions before the move. The 10-year closed 4.94% at +27bp over the 2-year, and the broad dollar index softened 1.7% across 60 days. One candidate explanation, unverified: the advance may reflect post-decision repositioning rather than fresh spot demand. Note the dollar figure is the Fed broad index, not ICE DXY.
Venue leadership rotated, and that is the more useful read. On September 15 Binance absorbed +4,617.90 BTC while Coinbase drained −3,170.75 at the 75,639.55 low; by September 18 Coinbase took +4,347.08 against Binance’s +769.64 as price gained 5.9% in one session. The Coinbase Premium repaired from −0.09 to −0.01 across those two sessions without crossing zero. Weekly aggregates confirm the shift — Coinbase netflow averaged +731.96 daily (+731% WoW) versus Binance at +1,559.23 (+268%). Meanwhile miner outflow measures expanded: MPI rose 144% week-over-week and Binance-to-miner flow reached 0.20 (+396% monthly), though MPI at 0.17 remains far below the 1.0 threshold. Funding held 0.00–0.01 every session, and net realized P/L at $153.4M sits 55% under its monthly average.
A price advance carried by US venue inflows, flat funding, and miners beginning to move coins without realizing proportional profit creates conditions that historically preceded trend continuation tested by supply release more often than a clean directional extension.
Written by CryptoOnchain