#termmax @TermMax
I keep coming back to one number while digging through TermMax: the gap between capital sitting in the protocol and the fees it’s actually generating.
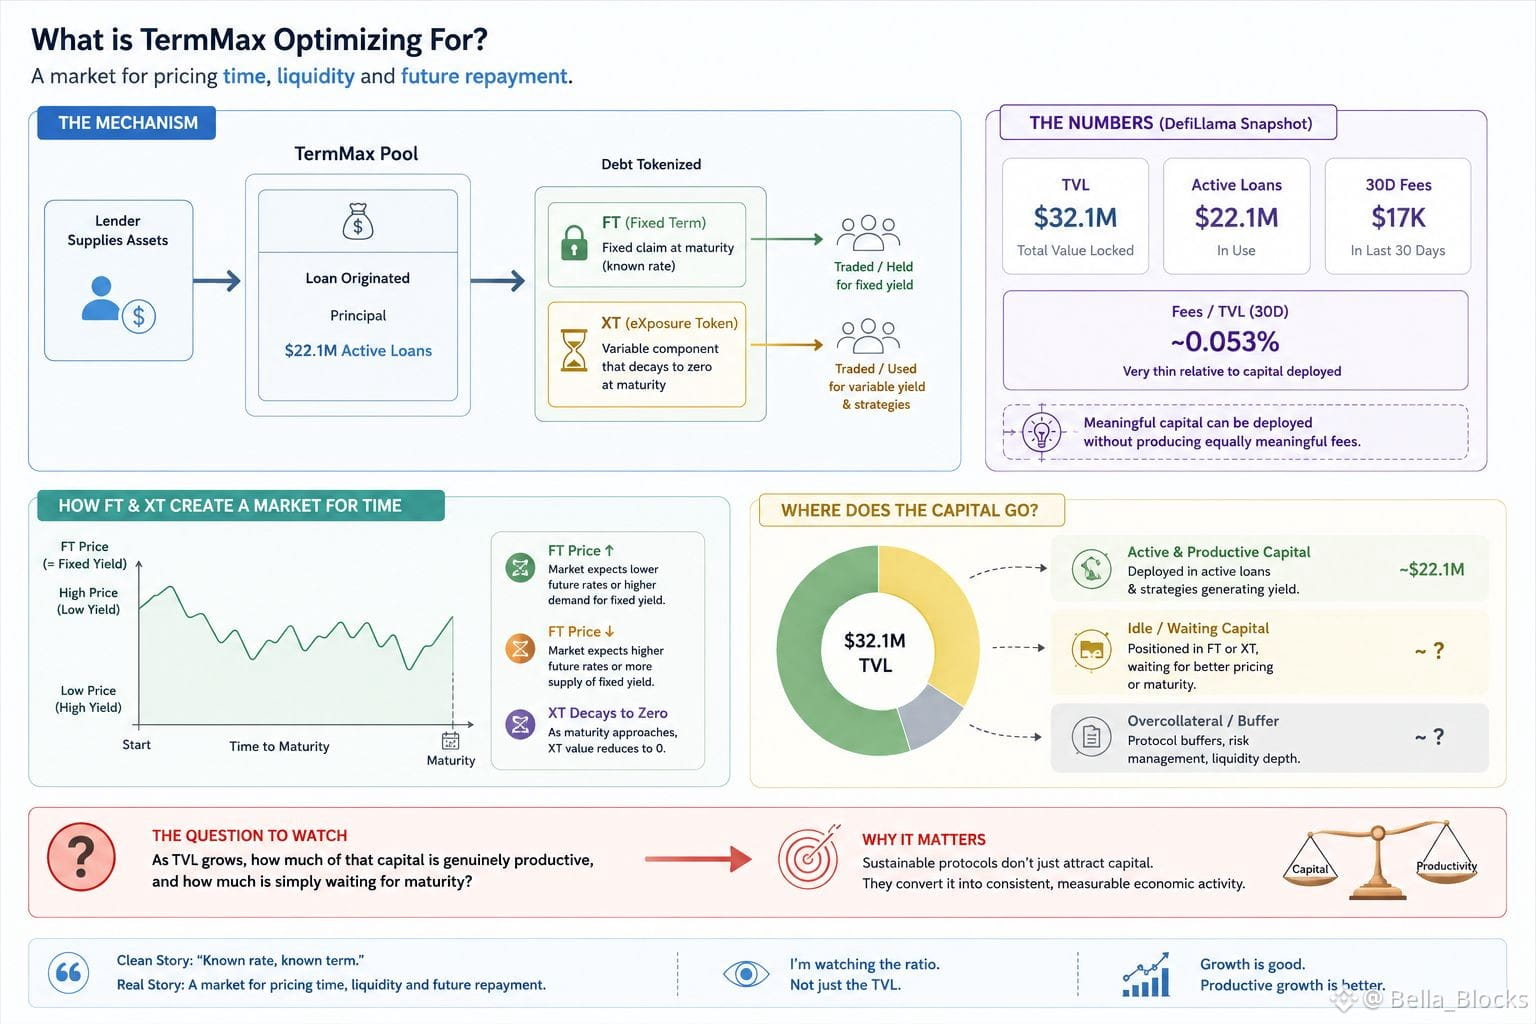
The latest DefiLlama snapshot I found shows about $32.1M TVL, with roughly $22.1M in active loans, while 30-day fees were only around $17K.
I thought I had misread it, so I went back into the docs to understand what TermMax is actually optimizing for.
The mechanism is more interesting than a simple “fixed-rate lending” label suggests. TermMax tokenizes debt into FT and XT. FT represents the fixed claim at maturity, while XT carries the remaining variable component and eventually goes to zero.
That creates a different behavior from a normal lending pool. Capital isn’t simply earning a floating rate. Users are trading around specific maturities, and the FT price effectively determines the fixed yield.
So the clean story is “known rate, known term.” Underneath, it’s really a market for pricing time, liquidity and future repayment.
The interesting part is that meaningful capital can be deployed without producing equally meaningful fees. That isn’t automatically a problem. Usage could still be concentrated in certain markets or strategies.
But it raises a question I think is worth watching:
As TVL grows, how much of that capital is genuinely productive, and how much is simply waiting for maturity?
$ONG
$PEOPLE
$NEIRO
I keep coming back to one number while digging through TermMax: the gap between capital sitting in the protocol and the fees it’s actually generating.
The latest DefiLlama snapshot I found shows about $32.1M TVL, with roughly $22.1M in active loans, while 30-day fees were only around $17K.
I thought I had misread it, so I went back into the docs to understand what TermMax is actually optimizing for.
The mechanism is more interesting than a simple “fixed-rate lending” label suggests. TermMax tokenizes debt into FT and XT. FT represents the fixed claim at maturity, while XT carries the remaining variable component and eventually goes to zero.
That creates a different behavior from a normal lending pool. Capital isn’t simply earning a floating rate. Users are trading around specific maturities, and the FT price effectively determines the fixed yield.
So the clean story is “known rate, known term.” Underneath, it’s really a market for pricing time, liquidity and future repayment.
The interesting part is that meaningful capital can be deployed without producing equally meaningful fees. That isn’t automatically a problem. Usage could still be concentrated in certain markets or strategies.
But it raises a question I think is worth watching:
As TVL grows, how much of that capital is genuinely productive, and how much is simply waiting for maturity?
$ONG
$PEOPLE
$NEIRO