

#lseg
lseg
2,499 penayangan
18 Berdiskusi
Populer
Terbaru
·
--
Bullish
Terverifikasi
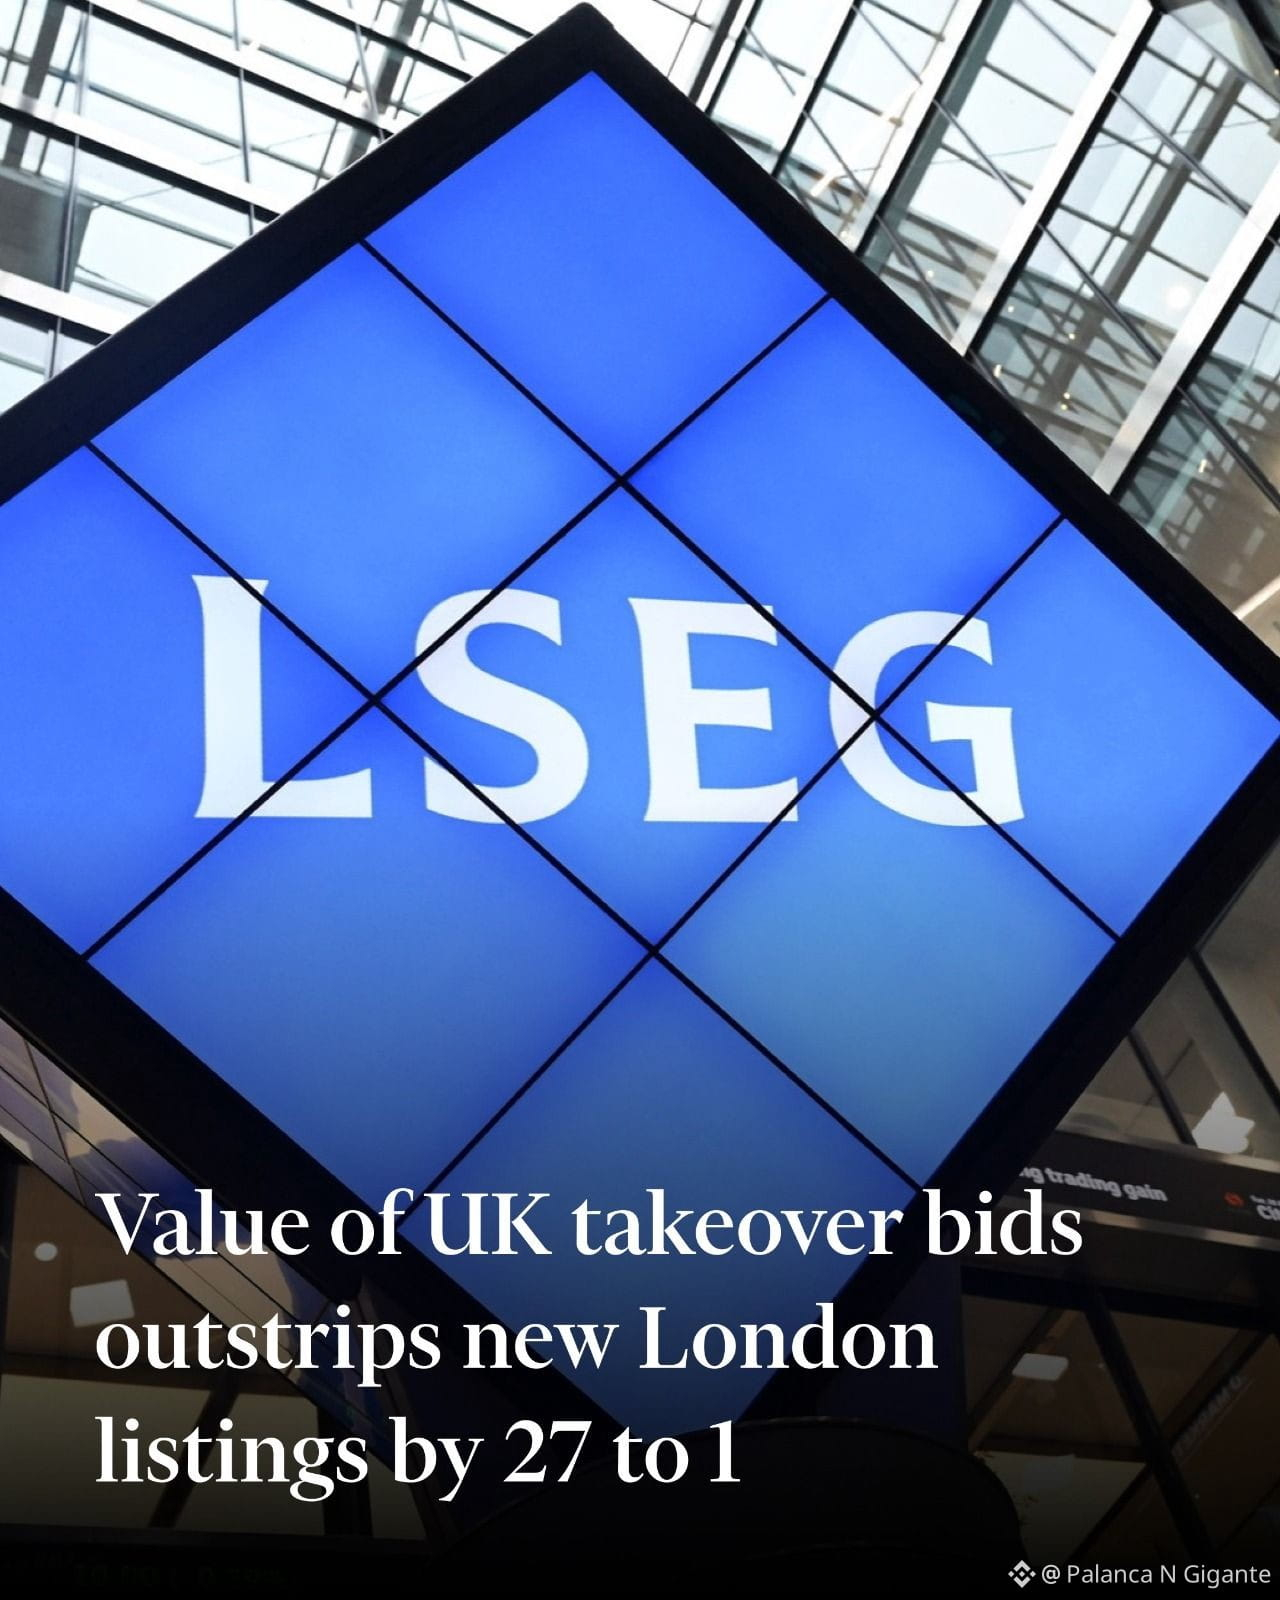
Nilai proposal untuk perusahaan di Bursa Efek London adalah 27 kali lebih besar dibandingkan nilai partisipan baru tahun ini, memunculkan kekhawatiran baru tentang penurunan pasar publik di Inggris. $EVAA
Meskipun ada ekspektasi awal bahwa 2026 akan membawa pemulihan bagi LSE, hanya ada tujuh pencatatan pada semester pertama tahun tersebut, dengan total dana terkumpul sebesar £577,2 juta, menurut data dari perusahaan layanan profesional EY. $EDGE
Nilai total pasar dari properti baru adalah £2,2 miliar, didorong terutama oleh pencatatan saham di bursa atas partisipasi dalam dana investasi nasional Uzbekistan, yang juga meraih nilai terbesar dari semua pengumuman, mencapai £511 juta. $CLO
{future}(EVAAUSDT)
{future}(CLOUSDT)
{future}(EDGEUSDT)
#news #LSEG #bullish #UK #LSE
Nilai proposal untuk perusahaan di Bursa Efek London adalah 27 kali lebih besar dibandingkan nilai partisipan baru tahun ini, memunculkan kekhawatiran baru tentang penurunan pasar publik di Inggris. $EVAA
Meskipun ada ekspektasi awal bahwa 2026 akan membawa pemulihan bagi LSE, hanya ada tujuh pencatatan pada semester pertama tahun tersebut, dengan total dana terkumpul sebesar £577,2 juta, menurut data dari perusahaan layanan profesional EY. $EDGE
Nilai total pasar dari properti baru adalah £2,2 miliar, didorong terutama oleh pencatatan saham di bursa atas partisipasi dalam dana investasi nasional Uzbekistan, yang juga meraih nilai terbesar dari semua pengumuman, mencapai £511 juta. $CLO
#news #LSEG #bullish #UK #LSE
1.2k
·
--
Bearish
Lihat terjemahan
#lseg
LSEG has for several years been more concerned with revenue from selling data products than investing in a functioning market," he said. Recent reductions in the cost of retail price distribution help, he added, but do little to encourage participation.
On proposals to extend U.K. trading hours, Saunders argued the effect would be to stretch existing liquidity rather than create new liquidity.
He described the mechanism as a decline in liquidity density, where the same number of shares change hands, but orders are spread across a longer period, leaving the order book shallower at any given moment.
"Market makers and institutional traders do not double their risk capital just because the clock says they should," he said. "They allocate the same risk budget across a longer day."
The consequence, he believes, is that a market maker filling an order holds inventory for longer before finding a counterparty, increasing the risk that prices move against the position. Market makers compensate by widening spreads, raising the average effective cost of trading.
Furthermore, he feels execution quality would diverge by order type. Market orders would deteriorate, running through more price tiers to fill and producing execution prices materially worse than the touch price.
Limit orders would improve marginally, competing against fewer resting orders across a wider spread, but with a lower probability of being filled, and potentially sit unexecuted for hours or expiring at the close.
Saunders noted that demand for longer access to U.K. stocks does exist, but is conditional on sufficient liquidity being available. Rising costs of trading in illiquid hours would eventually suppress that demand.
Concentrating liquidity into auctions could offset the effect, he said, while a continuous order book across extended hours represents a threat to liquidity and, in turn, to the exchange’s viability.
1
2

·
--
LSEG Naik Menjadi Canton Super Validator: Grup Bursa Turun Tangan Menjaga JaringanLSEG, grup Bursa Efek London, meningkatkan statusnya di Canton dari validator biasa menjadi Super Validator.
Rilis resmi 28 Sep menulisnya dengan sangat gamblang: LSEG memang sudah memakai aplikasi cash Digital Settlement House (DiSH) di Canton sebagai validator; setelah ditingkatkan, mereka akan ikut tata kelola jaringan, memperkuat infrastruktur, dan berencana membawa lebih banyak layanan LSEG ke privacy chain yang ditujukan untuk keuangan institusional.
Saya tidak menatap slogan “lagi-lagi institusi besar di-on-chain”; yang saya soroti adalah upaya mengunci di lapisan settlement—DiSH sudah menggunakan DiSH cash untuk settlement repo intraday di PoC, melalui jalur dana bank komersial, bukan menerbitkan stablecoin lagi.
LSEG Naik Menjadi Canton Super Validator: Grup Bursa Turun Tangan Menjaga Jaringan
LSEG, grup Bursa Efek London, meningkatkan statusnya di Canton dari validator biasa menjadi Super Validator.
Rilis resmi 28 Sep menulisnya dengan sangat gamblang: LSEG memang sudah memakai aplikasi cash Digital Settlement House (DiSH) di Canton sebagai validator; setelah ditingkatkan, mereka akan ikut tata kelola jaringan, memperkuat infrastruktur, dan berencana membawa lebih banyak layanan LSEG ke privacy chain yang ditujukan untuk keuangan institusional.
Saya tidak menatap slogan “lagi-lagi institusi besar di-on-chain”; yang saya soroti adalah upaya mengunci di lapisan settlement—DiSH sudah menggunakan DiSH cash untuk settlement repo intraday di PoC, melalui jalur dana bank komersial, bukan menerbitkan stablecoin lagi.
28
Masuk untuk menjelajahi konten lainnya
Bergabunglah dengan pengguna kripto global di Binance Square
⚡️ Dapatkan informasi terbaru dan berguna tentang kripto.
💬 Dipercayai oleh bursa kripto terbesar di dunia.
👍 Temukan wawasan nyata dari kreator terverifikasi.
Email/Nomor Ponsel
Topik Sedang Tren
1
#EarningsSeason
134,749 penayangan
1,293 Berdiskusi
2
#BitwiseLaunchesFirstSpotNEARETF
575 penayangan
75 Berdiskusi
3
#USJobOpeningsFallToFiveMonthLow
871 penayangan
57 Berdiskusi
4
#ECBToTestAIAgentsInDigitalEuroPayments
6,639 penayangan
255 Berdiskusi
5
#JapanFSABacksFourthStablecoinTradeSettlementPilot
7,305 penayangan
321 Berdiskusi
6
#BitgetHackerFailsToMoveStolenFunds
19,483 penayangan
452 Berdiskusi
7
#BitMineETHHoldingsTop6Million
20,373 penayangan
594 Berdiskusi
8
#StrategyAdds1666BTCHoldingsReach847666
16,355 penayangan
419 Berdiskusi
9
#NvidiaApproves$150BBuyback
3,907 penayangan
65 Berdiskusi
10
#OpenAIDelaysGPT6.1OverSafetyIssues
29,239 penayangan
773 Berdiskusi