

CryptoLite_247
1.5k Publications
CryptoLite_247
Signaler
Bloquer l’utilisateur
Free Stock Market News ACCURATE, CONSISTENT, & RELIABLE || https://x.com/Yusty121 || Crypto first commentary with Marco Market Context
Ouvert au trading
Trade régulièrement
5.5 an(s)
7 Suivis
883 Abonnés
3.0K+ J’aime
Publications
Portefeuille
Tous
Citations
Vidéos
PINNED
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
39
11
191
198.9k
PINNED
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
25
15
137
128.1k
·
--
Baissier
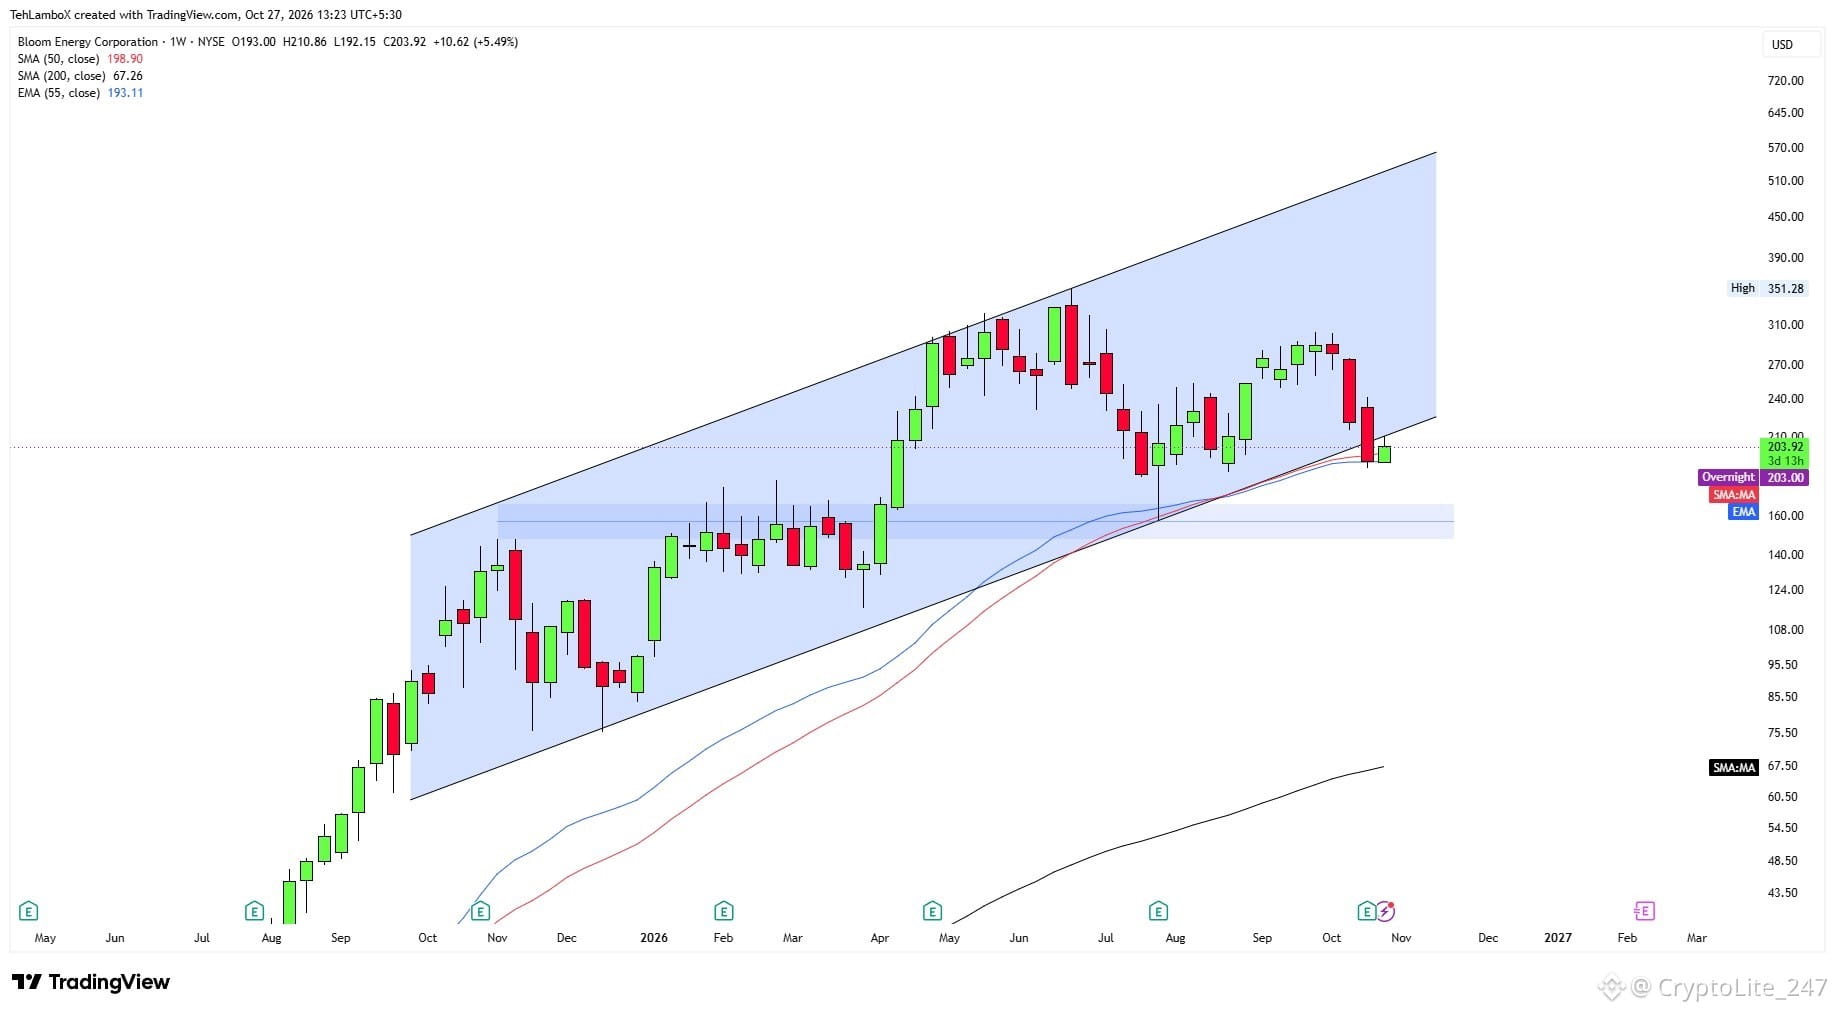
$BEB now you know why I said this?
Retested the breakdown and bearish unless closes back inside the pattern above 215-220 on D1 basis (Chart is W1 though)
For me, below 192, this targets 160-165 easily..
$BEB now you know why I said this?
Retested the breakdown and bearish unless closes back inside the pattern above 215-220 on D1 basis (Chart is W1 though)
For me, below 192, this targets 160-165 easily..
Retested the breakdown and bearish unless closes back inside the pattern above 215-220 on D1 basis (Chart is W1 though)
For me, below 192, this targets 160-165 easily..
1
18
·
--
Baissier
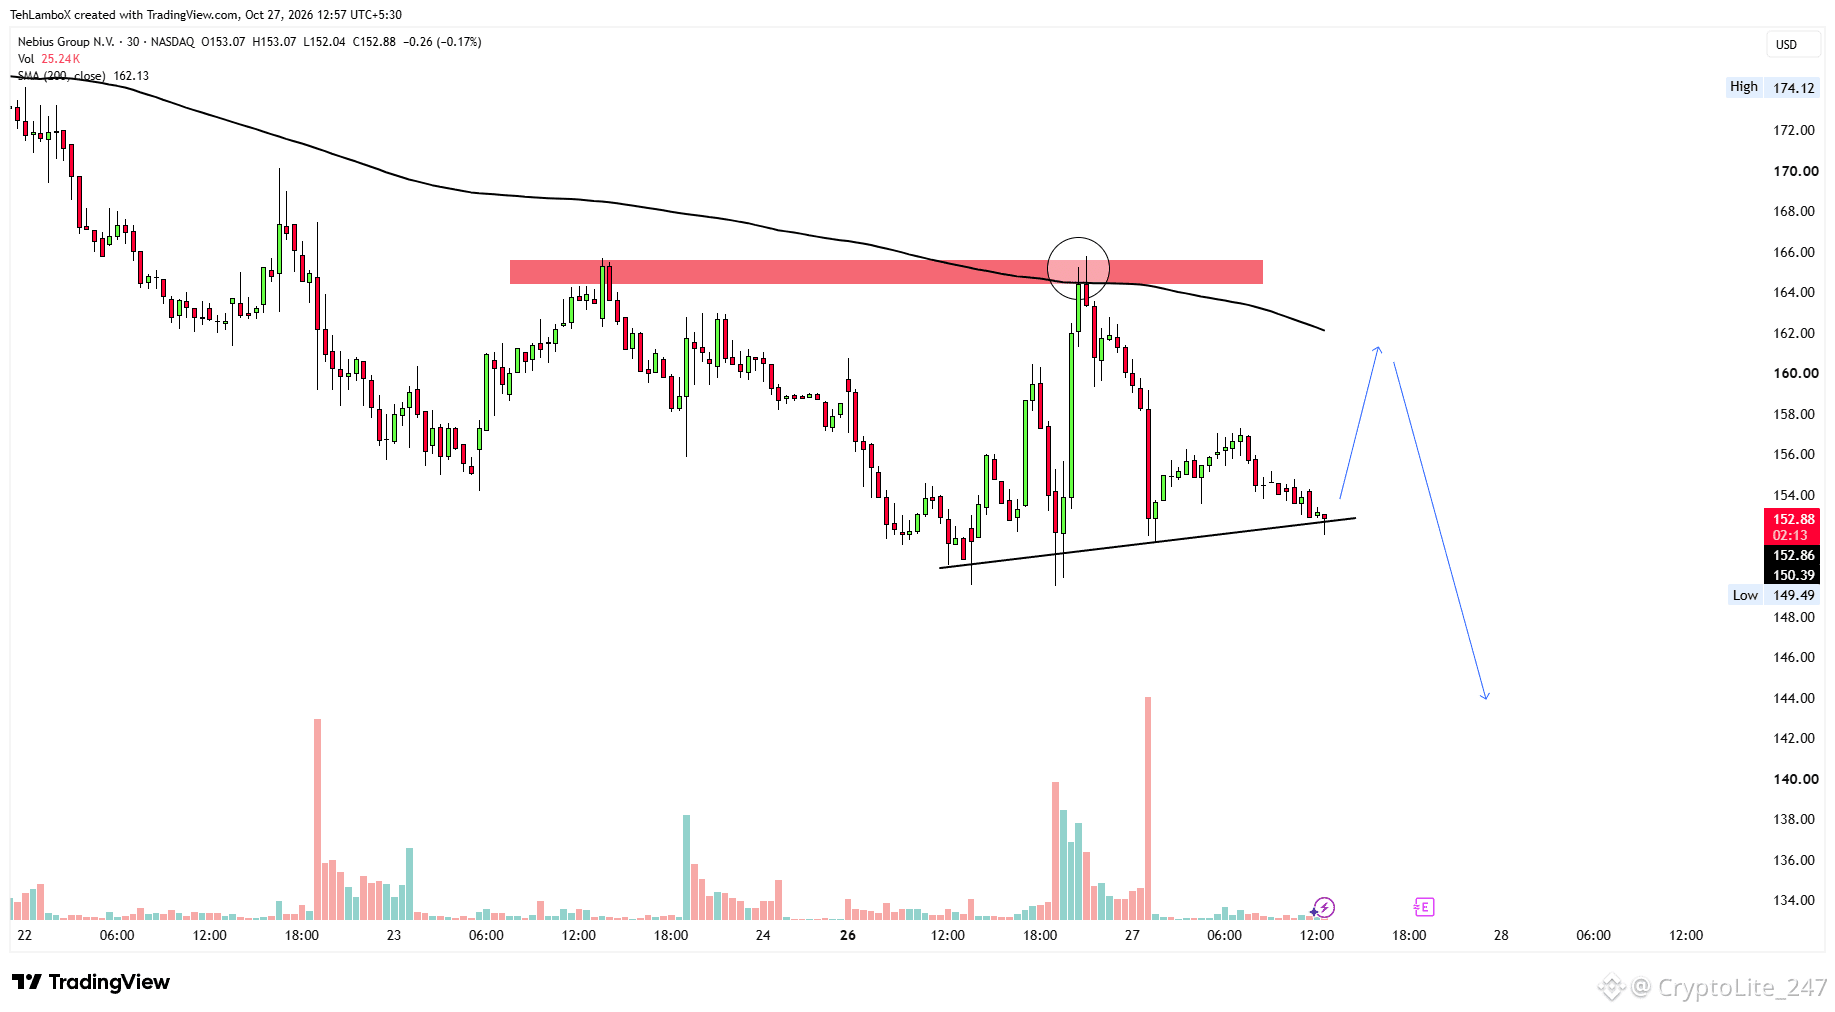
$NBIS that it has hit a confluent resistance at 165 with SMA200 on M30 and a local high.
It has retraced since then, almost 8% and is now lookin to bounce off this diagonal support.
I am still bearish and feel if get another bounce towards 160-162 zone, we get a rejection a break below 150 then!!
$NBIS that it has hit a confluent resistance at 165 with SMA200 on M30 and a local high.
It has retraced since then, almost 8% and is now lookin to bounce off this diagonal support.
I am still bearish and feel if get another bounce towards 160-162 zone, we get a rejection a break below 150 then!!
It has retraced since then, almost 8% and is now lookin to bounce off this diagonal support.
I am still bearish and feel if get another bounce towards 160-162 zone, we get a rejection a break below 150 then!!
1
128
·
--
Baissier
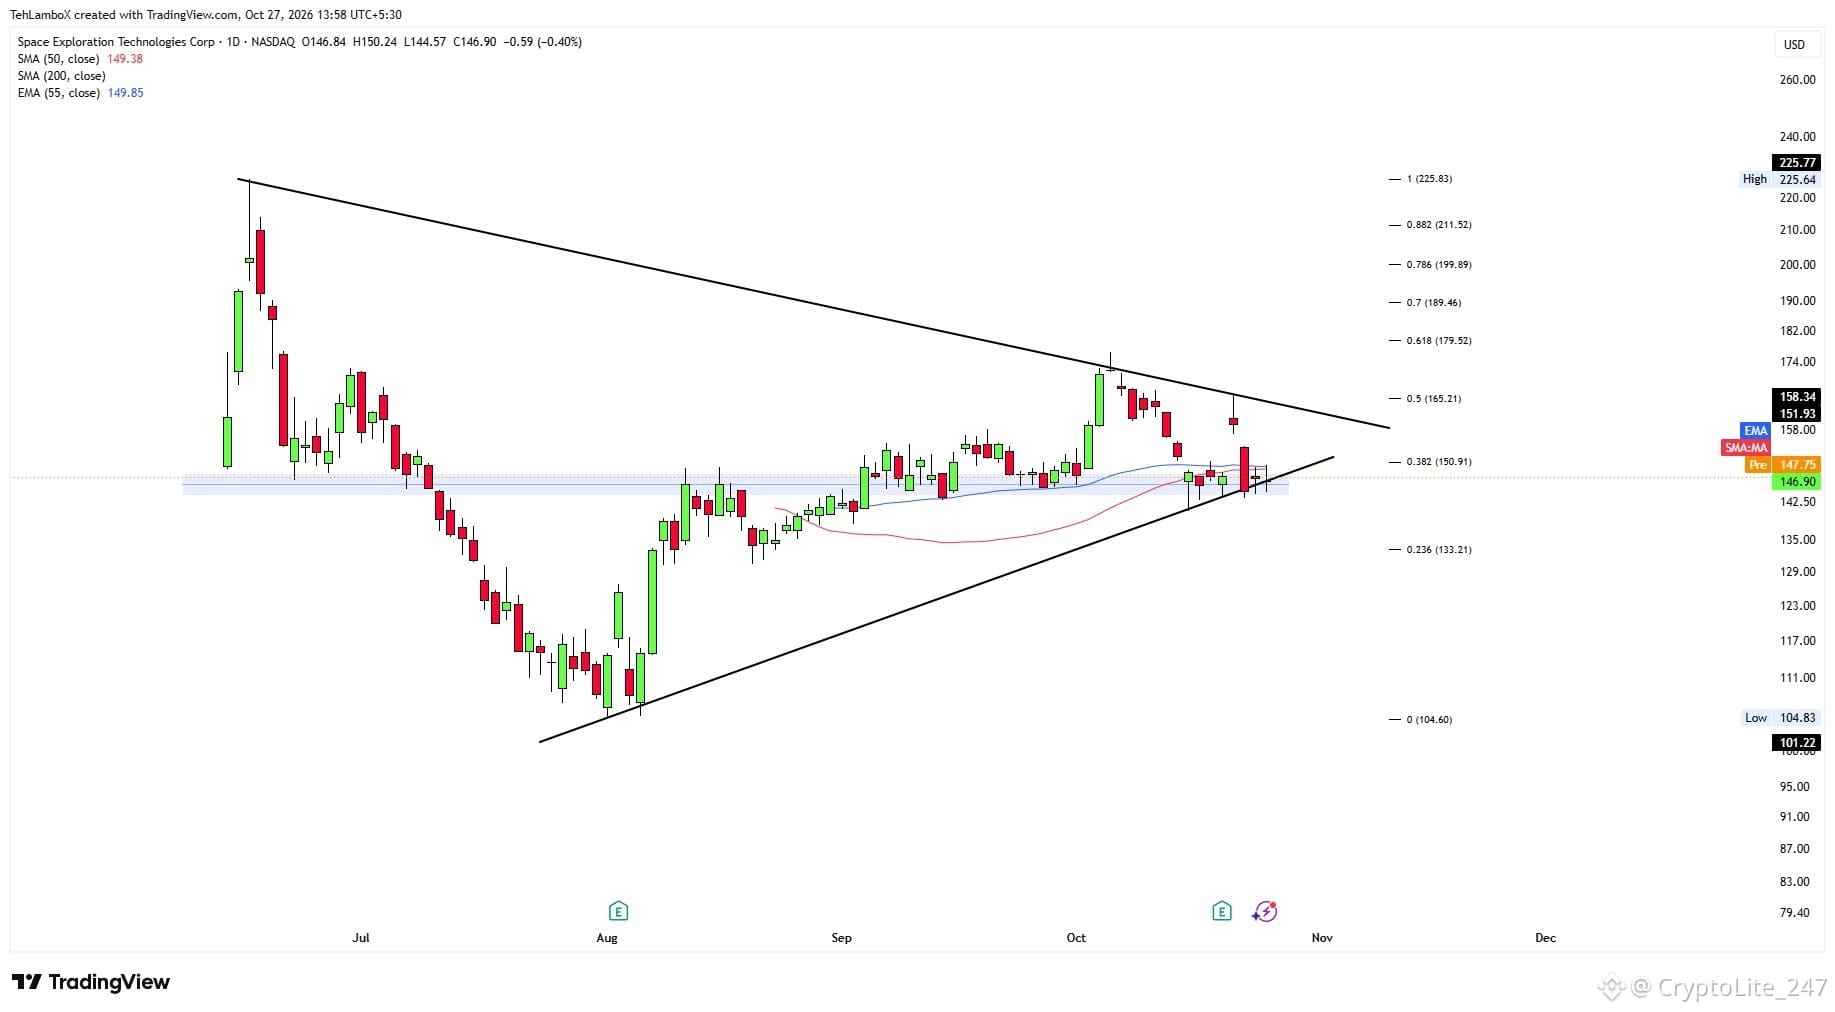
$SPCX is at a make or break zone..
Below 140, this would be bearish while above 152, this cane easily give a 8-9% move inside the triangle
$SPCX is at a make or break zone..
Below 140, this would be bearish while above 152, this cane easily give a 8-9% move inside the triangle
Below 140, this would be bearish while above 152, this cane easily give a 8-9% move inside the triangle
1
301
·
--
Haussier
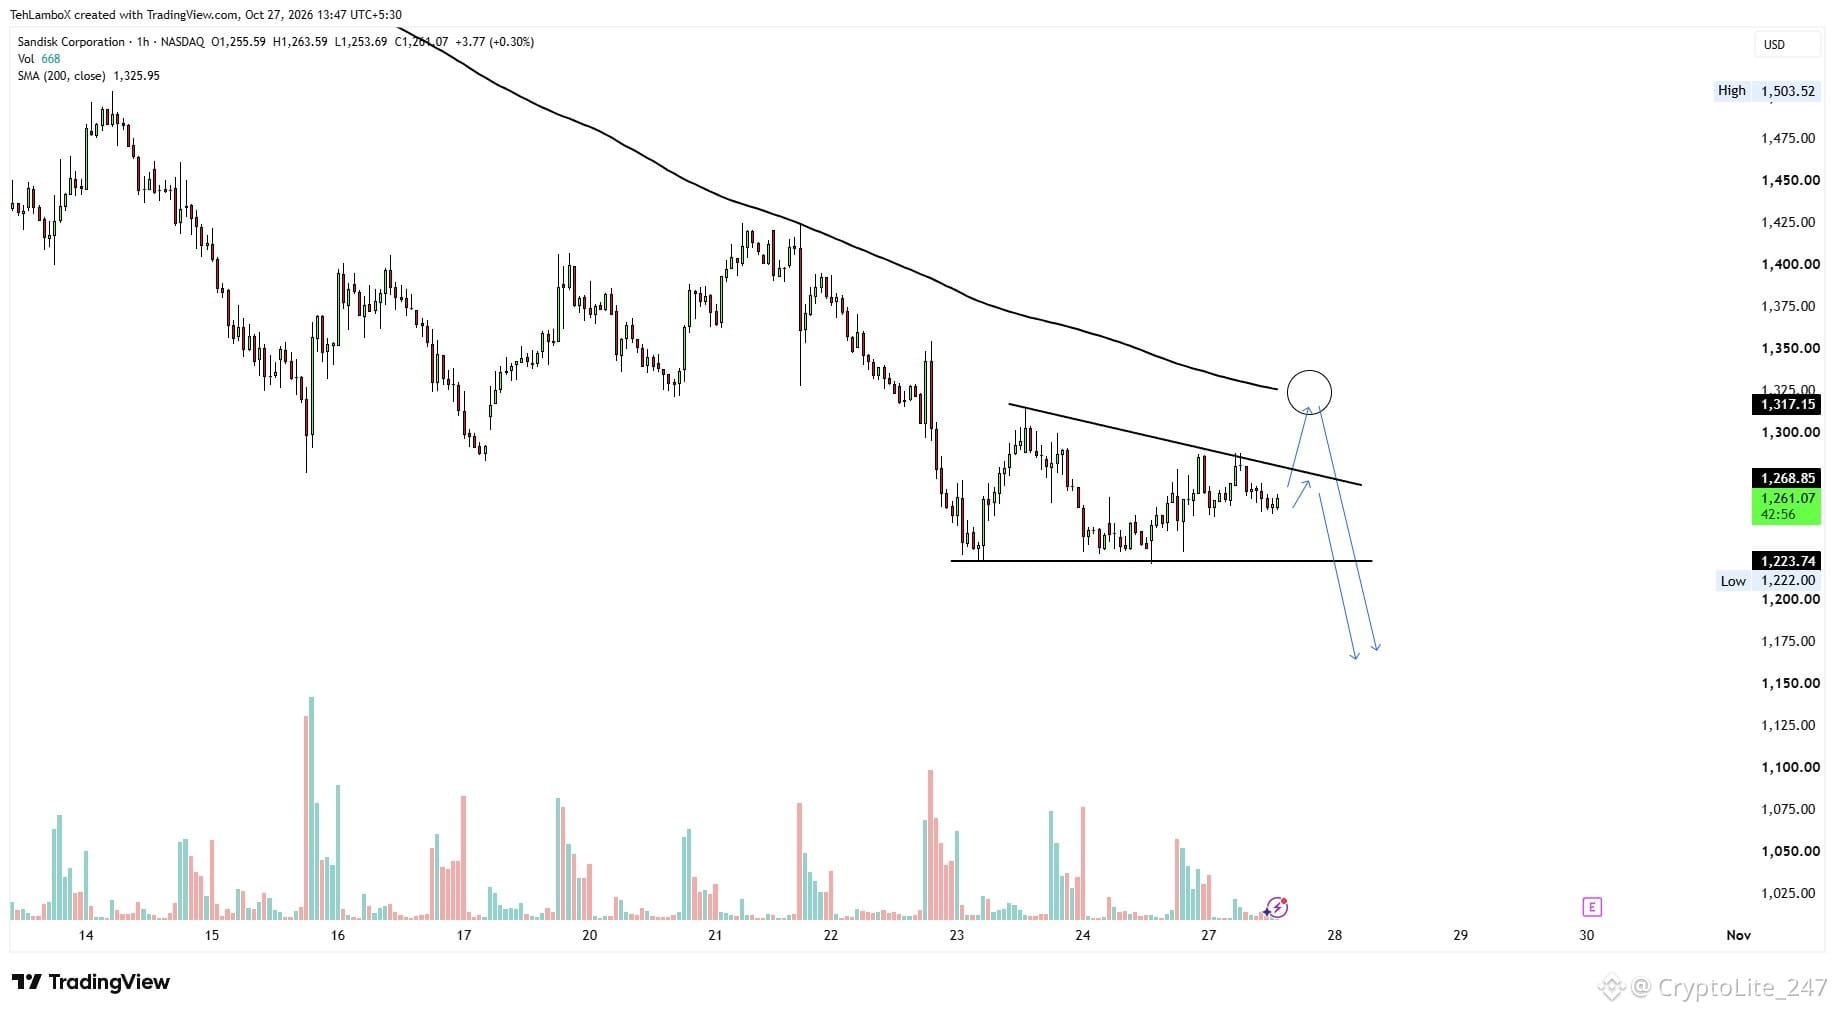
$SNDK if a bull move is to come, I think it goes to test SMA200 on H1 and then get a rejection.
I will be bullish short term if SMA200 above 1330 breaks .. For now this is a descending triangle ready to break downwards..
$SNDK if a bull move is to come, I think it goes to test SMA200 on H1 and then get a rejection.
I will be bullish short term if SMA200 above 1330 breaks .. For now this is a descending triangle ready to break downwards..
I will be bullish short term if SMA200 above 1330 breaks .. For now this is a descending triangle ready to break downwards..
2
486
·
--
Baissier
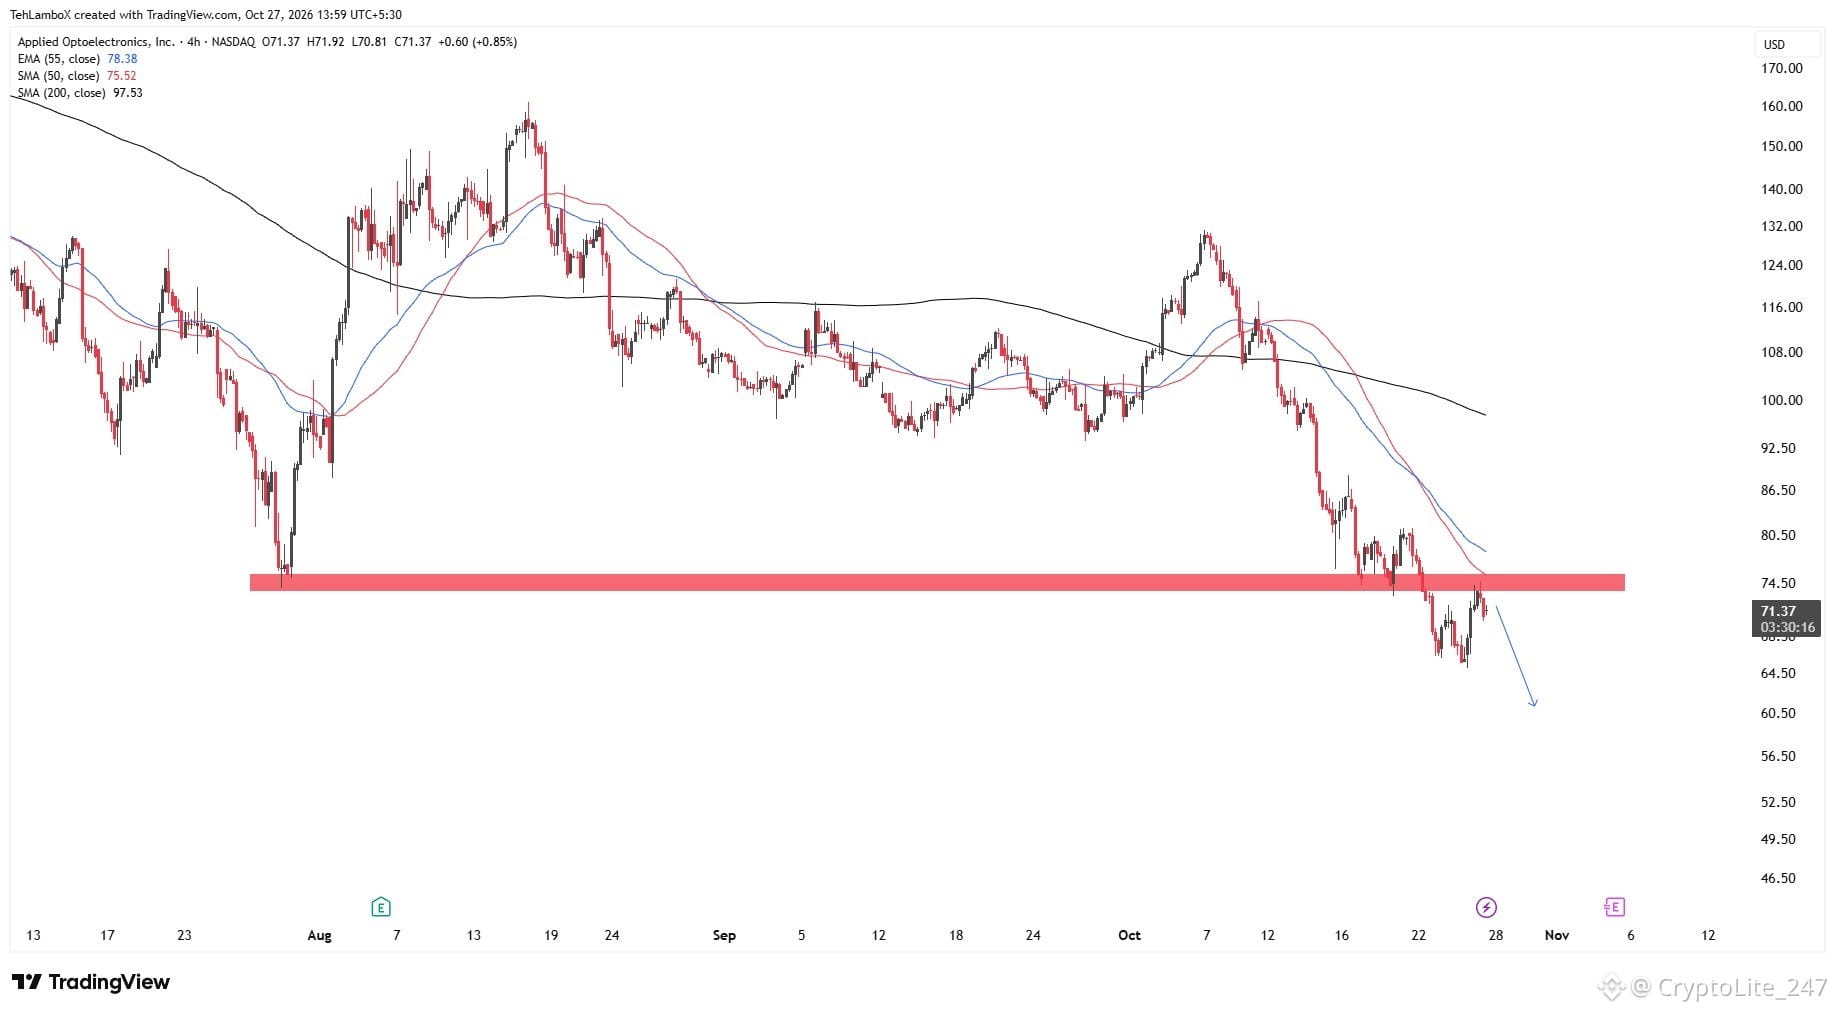
$AAOI is still bearish for me..
It retested the breakdown and has rejected..
Now should be looking for a move lower.
$AAOI is still bearish for me..
It retested the breakdown and has rejected..
Now should be looking for a move lower.
It retested the breakdown and has rejected..
Now should be looking for a move lower.
2
181
·
--
Haussier
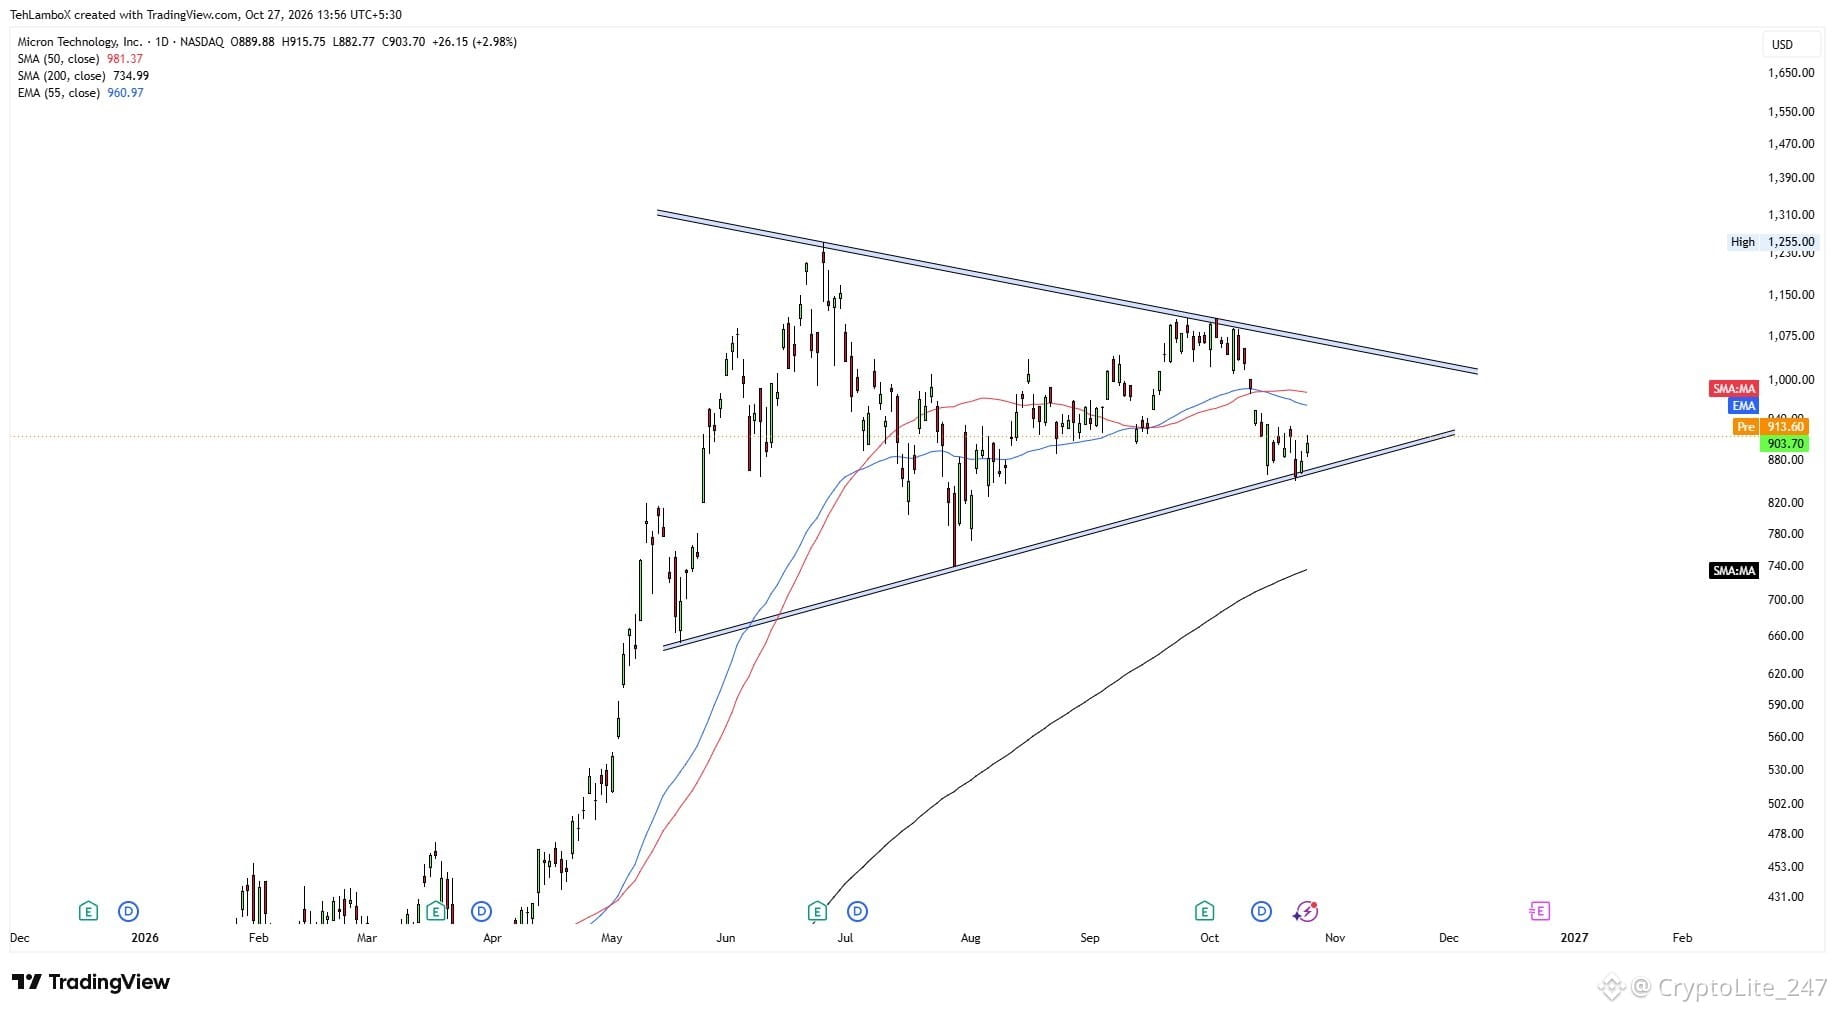
$MU Bull flag on D1 maintained..
Defended 860 and bounced..
My view is still the same, below 860/850 zone we are bearish on closing basis.
$MU Bull flag on D1 maintained..
Defended 860 and bounced..
My view is still the same, below 860/850 zone we are bearish on closing basis.
Defended 860 and bounced..
My view is still the same, below 860/850 zone we are bearish on closing basis.
1
337
·
--
Haussier
$NBIS is tackling one of AI infrastructure’s biggest bottlenecks: power.
Nebius has activated its first Bloom Energy fuel cell power block at its 300 MW New Jersey data center site, marking a step toward dedicated, on-site electricity generation for its AI operations.
Building data centers and securing GPUs isn't enough. AI cloud providers also need reliable power to bring capacity online and deliver computing services to customers.
The multiyear Bloom Energy arrangement could help Nebius address that challenge as it expands its infrastructure footprint. If the power setup supports dependable operations and strong utilization, it could strengthen the company’s ability to turn capacity into recurring AI-cloud revenue.
Fuel cells and large-scale data center development come with substantial costs and long-term commitments. Nebius still needs to demonstrate that its expanding infrastructure can generate enough revenue and cash flow to justify the investment.
The activation is real operational progress, but it doesn't yet prove the economics will work at scale.
1
351
·
--
Haussier
Elon Musk just delivered another blow to the neocloud trade: “Pointless.”
CRWV, NBIS and IREN extended their declines after Musk said SpaceX has no interest in acquiring a neocloud company, warning that more than 200 players could face consolidation and failures.
The overnight reaction was immediate:
🔻 $CRWV : -2.3%
🔻 $NBIS : -2.3%
🔻 $IREN : -2%
The bigger concern is funding. Musk argued that debt markets have become far less accessible for companies without substantial revenue streams independent of AI data centers. SpaceX, he said, is in a different position.
Venture capitalist Chamath Palihapitiya echoed the warning, highlighting weak capitalization, potential data-center delays and the risk that expensive computing capacity could sit underutilized in 2027.
That’s the real issue for neocloud investors. AI demand can be enormous, but demand alone doesn't guarantee that every infrastructure provider will earn an attractive return on billions of dollars in spending.
Still, this isn't proof that every neocloud will fail. Companies with strong customer commitments, reliable power, disciplined financing and high utilization could emerge stronger as the sector consolidates.
1
5
4.4k
·
--
Haussier
Today's Key Events (All EST) $BTC — 10/26/2026
08:30: Chicago National Activity Index
10:30: Dallas Fed Mfg. Bus. Index
13:00: US 2-Year Note Auction
Before Open 👇
07:00: Verizon Communications (VZ)
BMO: Medifast (MED)
BMO: MakeMyTrip (MMYT)
After Hours 👇
16:00: Cadence Design Systems (CDNS)
16:00: Amkor (AMKR)
16:00: Kforce (KFRC)
16:05: Rambus (RMBS)
16:05: Welltower (WELL)
16:05: Whirlpool (WHR)
16:05: The Hartford Financial Services (HIG)
16:05: Public Storage (PSA)
16:05: Agilysys (AGYS)
16:05: Northwest Bancshares (NWBI)
16:10: Flexsteel Industries (FLXS)
16:10: Hawkins (HWKN)
16:15: Principal Financial Group (PFG)
16:15: Phillips Edison & Company (PECO)
16:30: Nucor (NUE)
16:30: Sun Communities (SUI)
16:35: Celestica (CLS)
17:00: Brown & Brown (BRO)
1
122
·
--
Haussier
$NBIS : The fact that Griffin has the temerity to talk about GPU overcapacity when the world is still scrambling for compute is sickening.
Have we already forgotten the FUD that reportedly helped trigger the July selloff involving Leopold Aschenbrenner?
Now, with the market already gripped by panic, here comes another overcapacity narrative that could fuel further selling.
This is how fear works. Create doubt, exploit uncertainty, and let panic do the damage.
Sadly, too many investors fall for it, forgetting that short-term market narratives don't automatically change long-term fundamentals.
2
630
·
--
Haussier
Please stop DMing asking me if "I think $NBIS R/R is attractive at this level"
You should already know where I stand from day one.
I know a lot of people are scared about Elon Musk statement which I feel is way blown out of proportion.
You work hard for your money so I shouldn't be the one dictating for you how to invest it.
If you think there is opportunity there, take it and if you are not comfortable yet, leave it.
1
443
·
--
Haussier
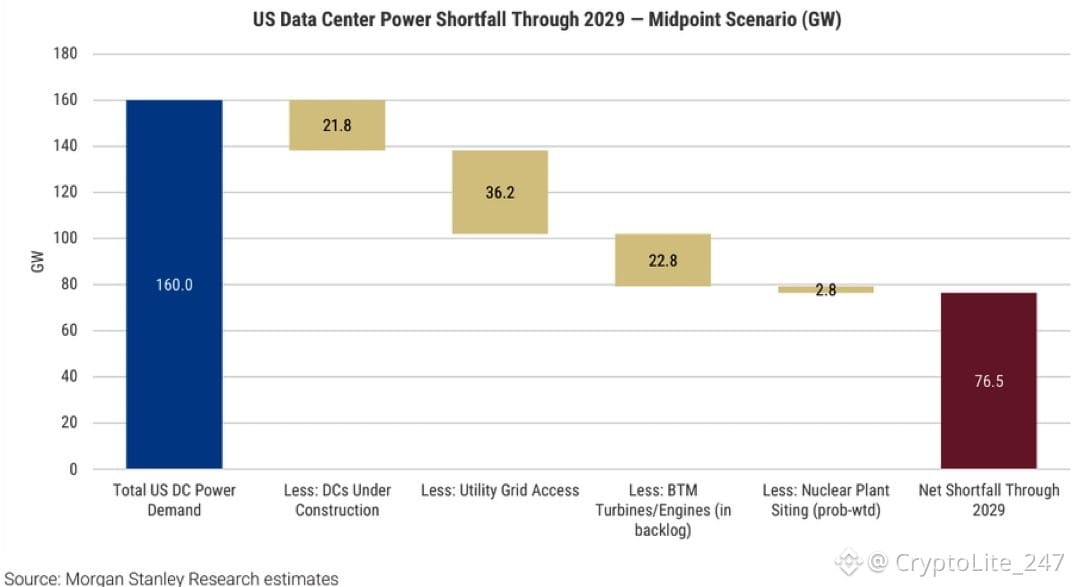
Morgan Stanley sees ~160 GW of U.S. data center power demand through 2029 against an insane ~77 GW shortfall leaving nearly half of that demand at risk of going unpowered.
That’s a massive opportunity for $GEV with its sold-out gas turbines and $BEB with onsite fuel cells that can generate electricity without relying on turbines.
And getting that power into AI data centers creates another opportunity for VRT in power delivery and cooling, FPS in transformers and prefabricated electrical systems and ON and NVTS in improving efficiency through SiC and GaN.
1
243
·
--
Haussier
$SPCX CEO Elon Musk says we’re going to see “a lot of stranded compute in partially complete data centers” as GPUs arrive faster than power infrastructure needed to run them.
That sounds bearish but could actually keep GPU rental prices higher for longer as companies with power already secured benefit from tight supply while idle chips lose value with every new generation.
That sounds bearish but could actually keep GPU rental prices higher for longer as companies with power already secured benefit from tight supply while idle chips lose value with every new generation.
2
2
5
5.8k
·
--
Haussier
Vérifié
This is what I mean when I say $AAOI has a massive opportunity but an even bigger execution risk with Glassdoor showing just 1.7 stars and 1% CEO approval.
When management is trying to ramp monthly production from ~150K to over 650K transceivers keeping experienced workers becomes just as important as having strong customer demand.
When management is trying to ramp monthly production from ~150K to over 650K transceivers keeping experienced workers becomes just as important as having strong customer demand.
1
841
·
--
Haussier
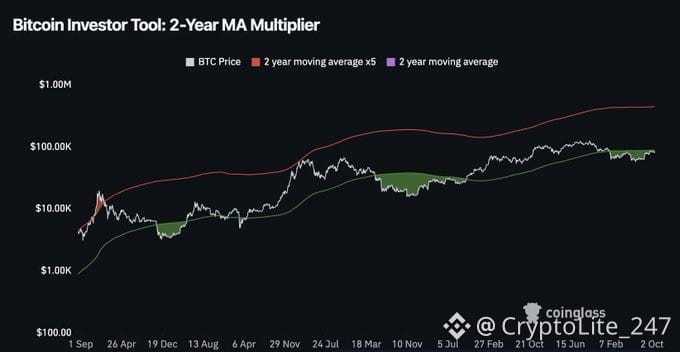
$BTC
Has meanwhile moved back to its 2 year moving average price after deviating below it for some time.
In my previous tweet I mentioned how Bitcoin tends to. historically trade at good high timeframe value when it is below that level. The big question is usually how long it remains below that area. In this case it didn't take a long time because since then, price moved up from $63K to $87K at its recent high in just 3 months.
Good reason why I always like to keep looking at these high timeframe "indicators" to determine when BTC is at historically good value levels.
1
390
·
--
Haussier
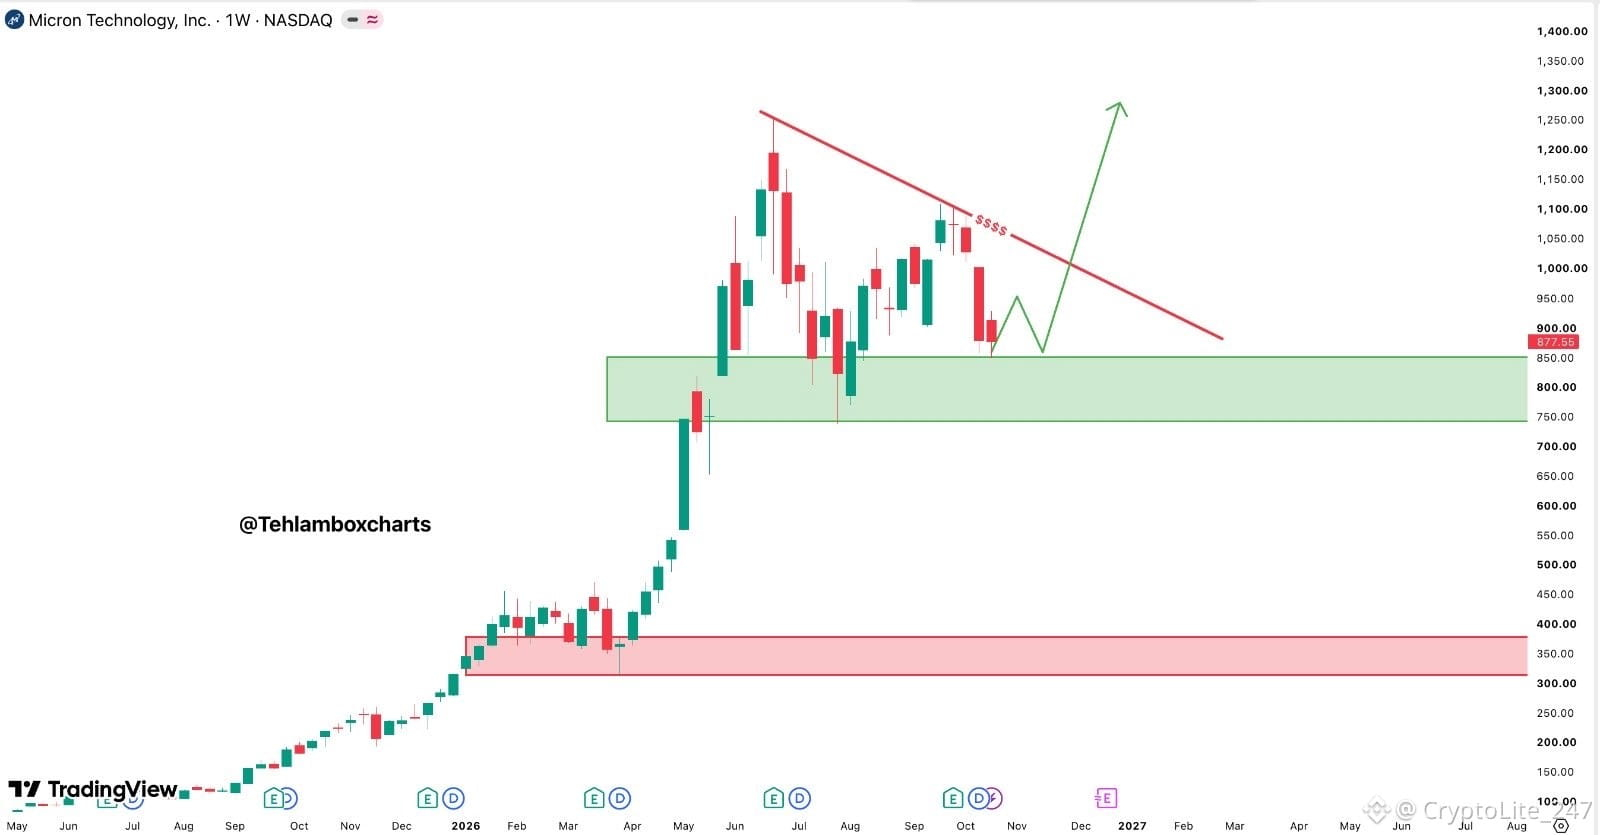
$MU is at a make-or-break zone
$850 needs to hold
if bulls reclaim this trendline, $1,000+ could be back on the table
$MU is at a make-or-break zone
$850 needs to hold
if bulls reclaim this trendline, $1,000+ could be back on the table
$850 needs to hold
if bulls reclaim this trendline, $1,000+ could be back on the table
1
470
·
--
Haussier
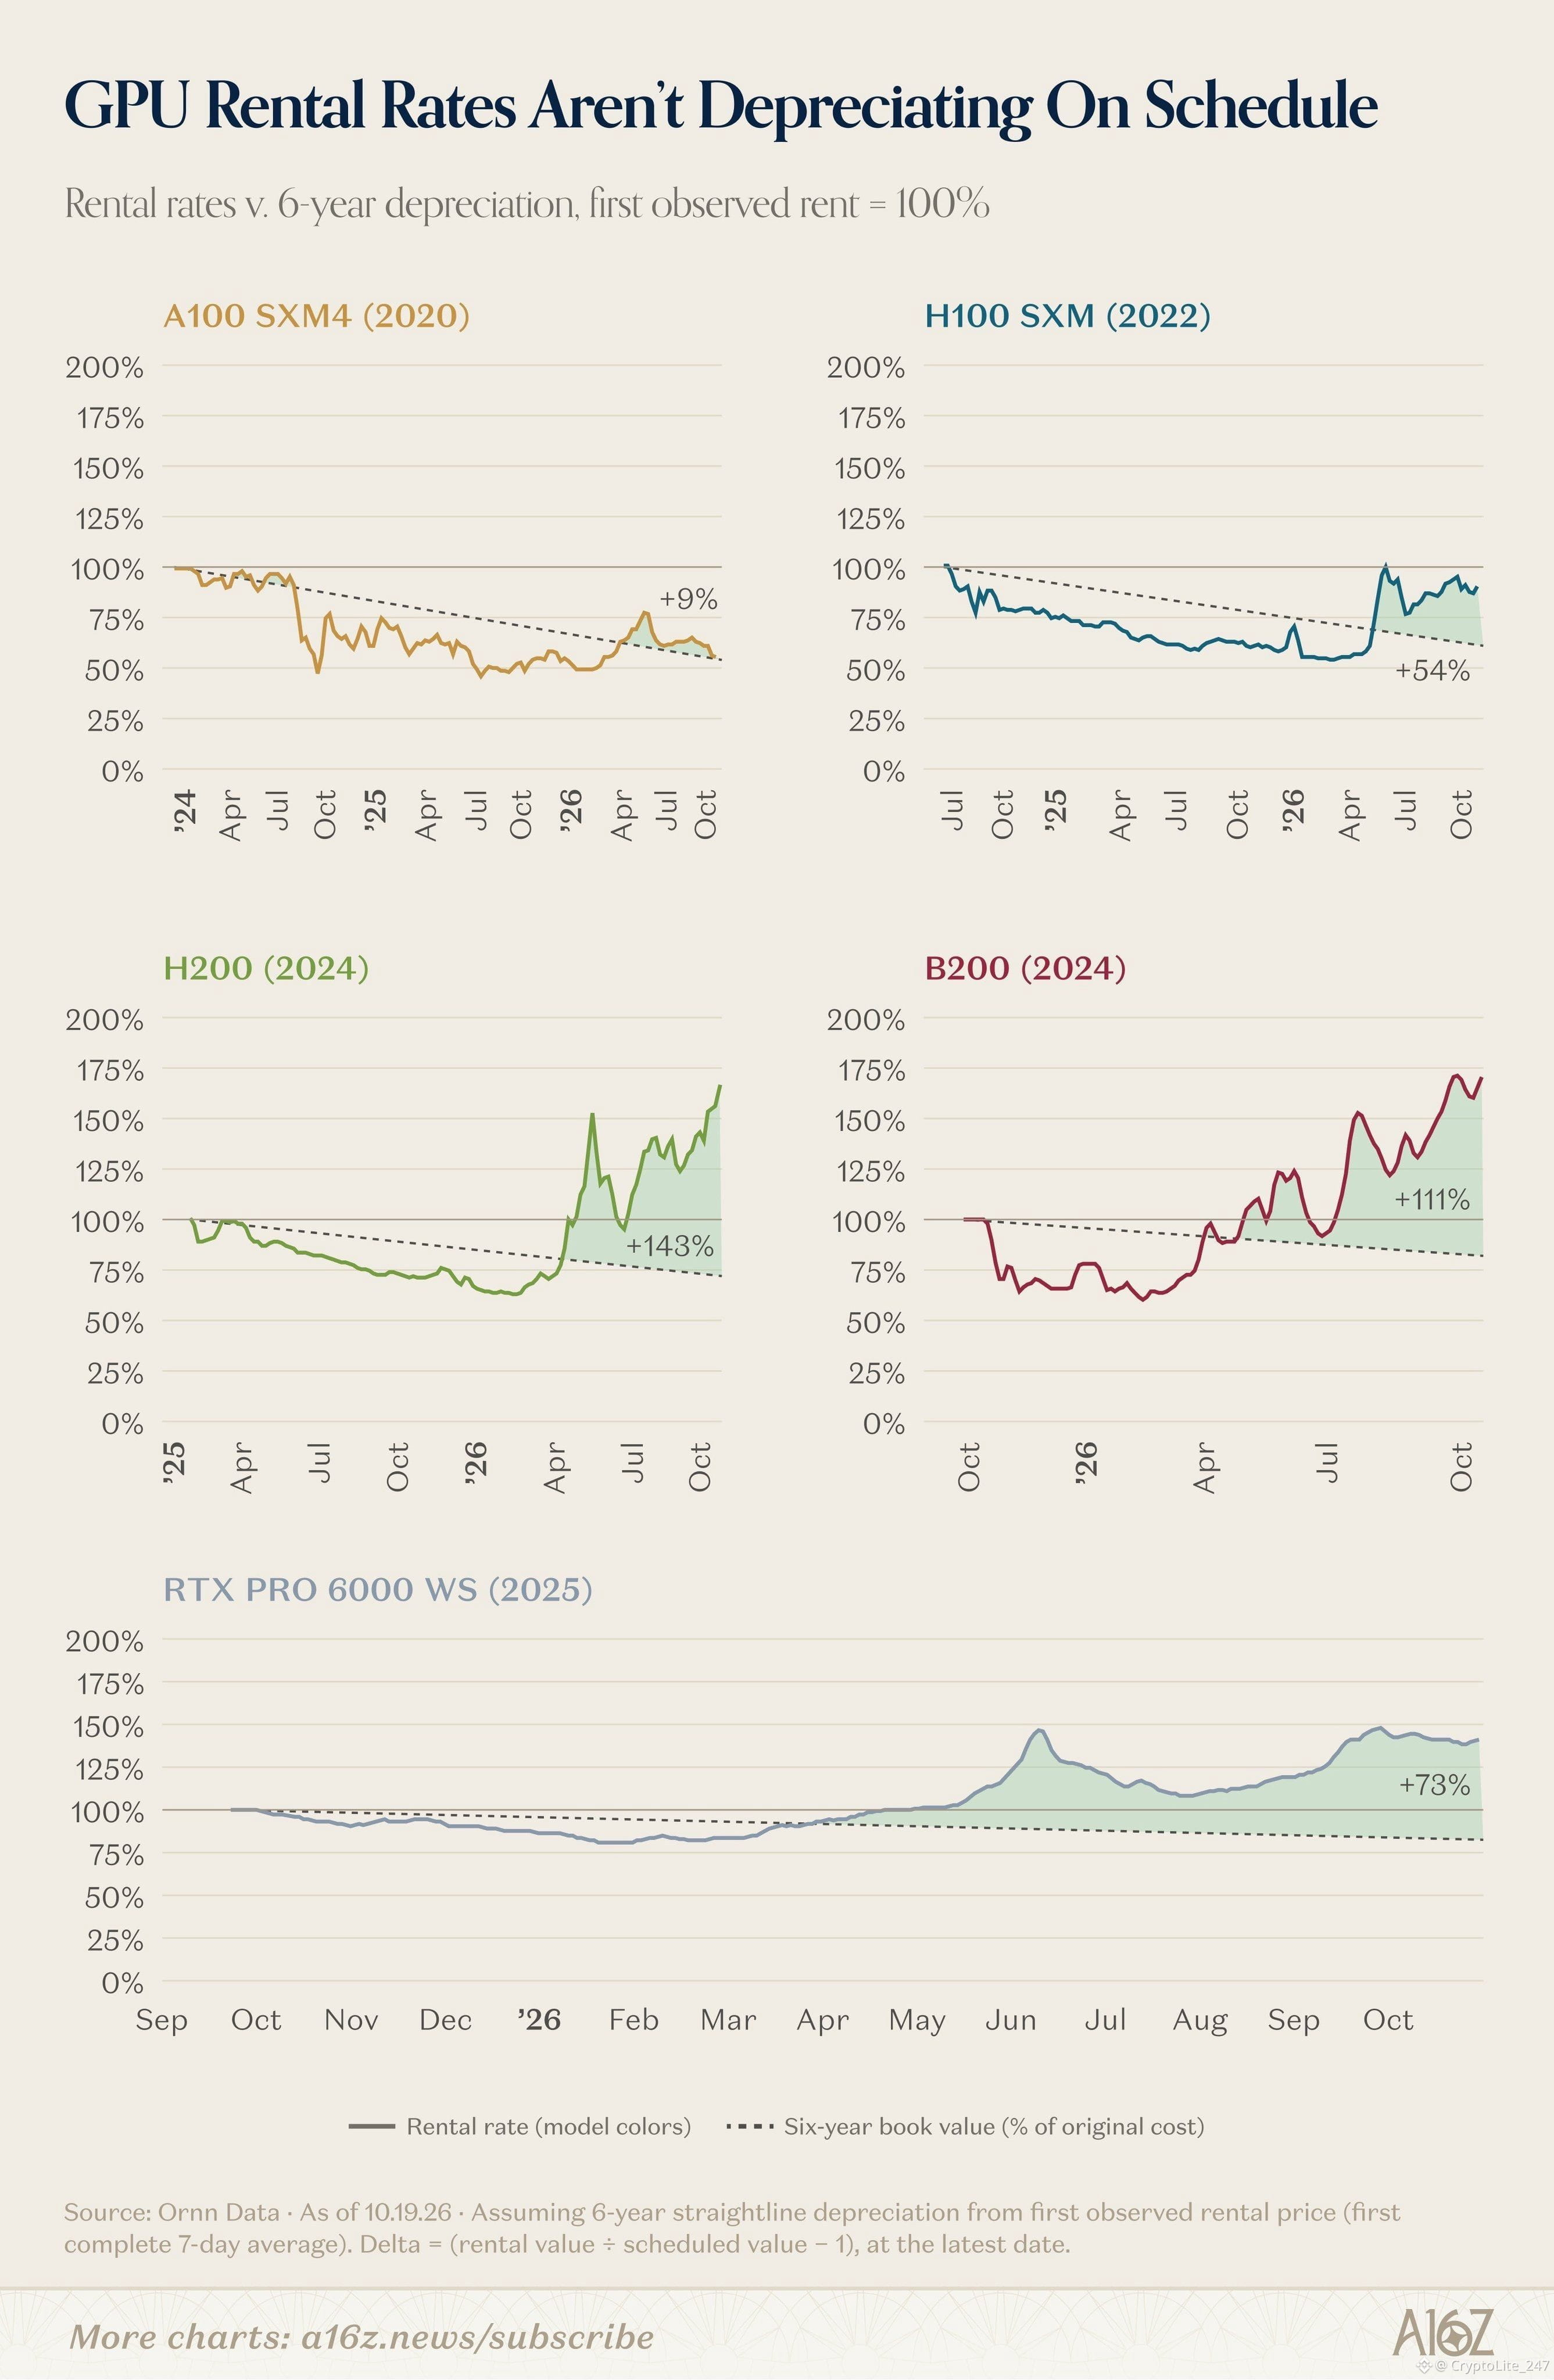
This is the kind of data that makes me even more bullish on the neocloud thesis. 👀
GPU rental prices are running ABOVE a standard 6-year depreciation schedule.
• H200: +143%
• B200: +111%
• RTX PRO 6000: +73%
• H100: +54%
• A100: +9%
Most of this gap opened up after April as token demand accelerated.
Think about what this means for $NBIS , $IREN and $CRWV .
AI compute demand is pushing rental prices beyond depreciation expectations, strengthening the case for sustained pricing power and stronger returns on GPU infrastructure.
The market is still underestimating what happens when demand keeps outpacing available capacity.
2
2
1.8k
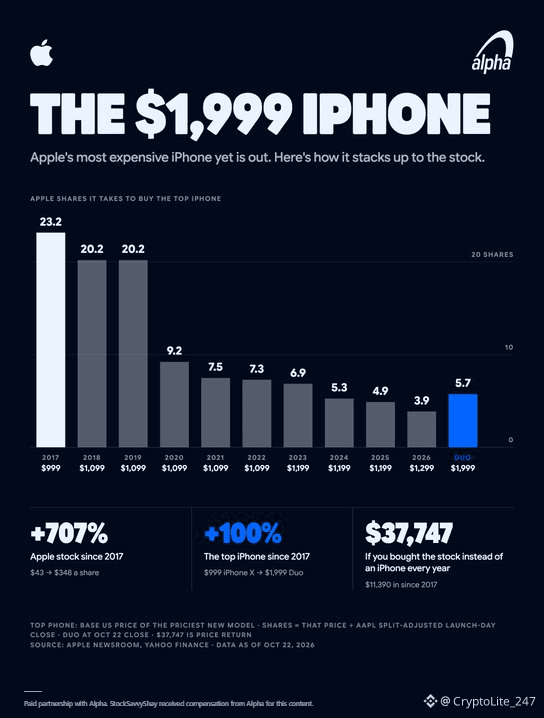
$AAPL just launched its most expensive iPhone ever with the $1,999 iPhone Duo and preorders reportedly sold out by 5:20 a.m.
Raising your top price 54% and still selling out that quickly is some serious pricing power.
$AAPL just launched its most expensive iPhone ever with the $1,999 iPhone Duo and preorders reportedly sold out by 5:20 a.m.
Raising your top price 54% and still selling out that quickly is some serious pricing power.
Raising your top price 54% and still selling out that quickly is some serious pricing power.
1
434
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone