

For-Exx Kripto 1
421 Publications
For-Exx Kripto 1
Signaler
Bloquer l’utilisateur
Cryptocurrency Reviews / Technical and Fundamental Analysis / Important Market News
0 Suivis
44 Abonnés
34 J’aime
Publications
Tous
Vidéos
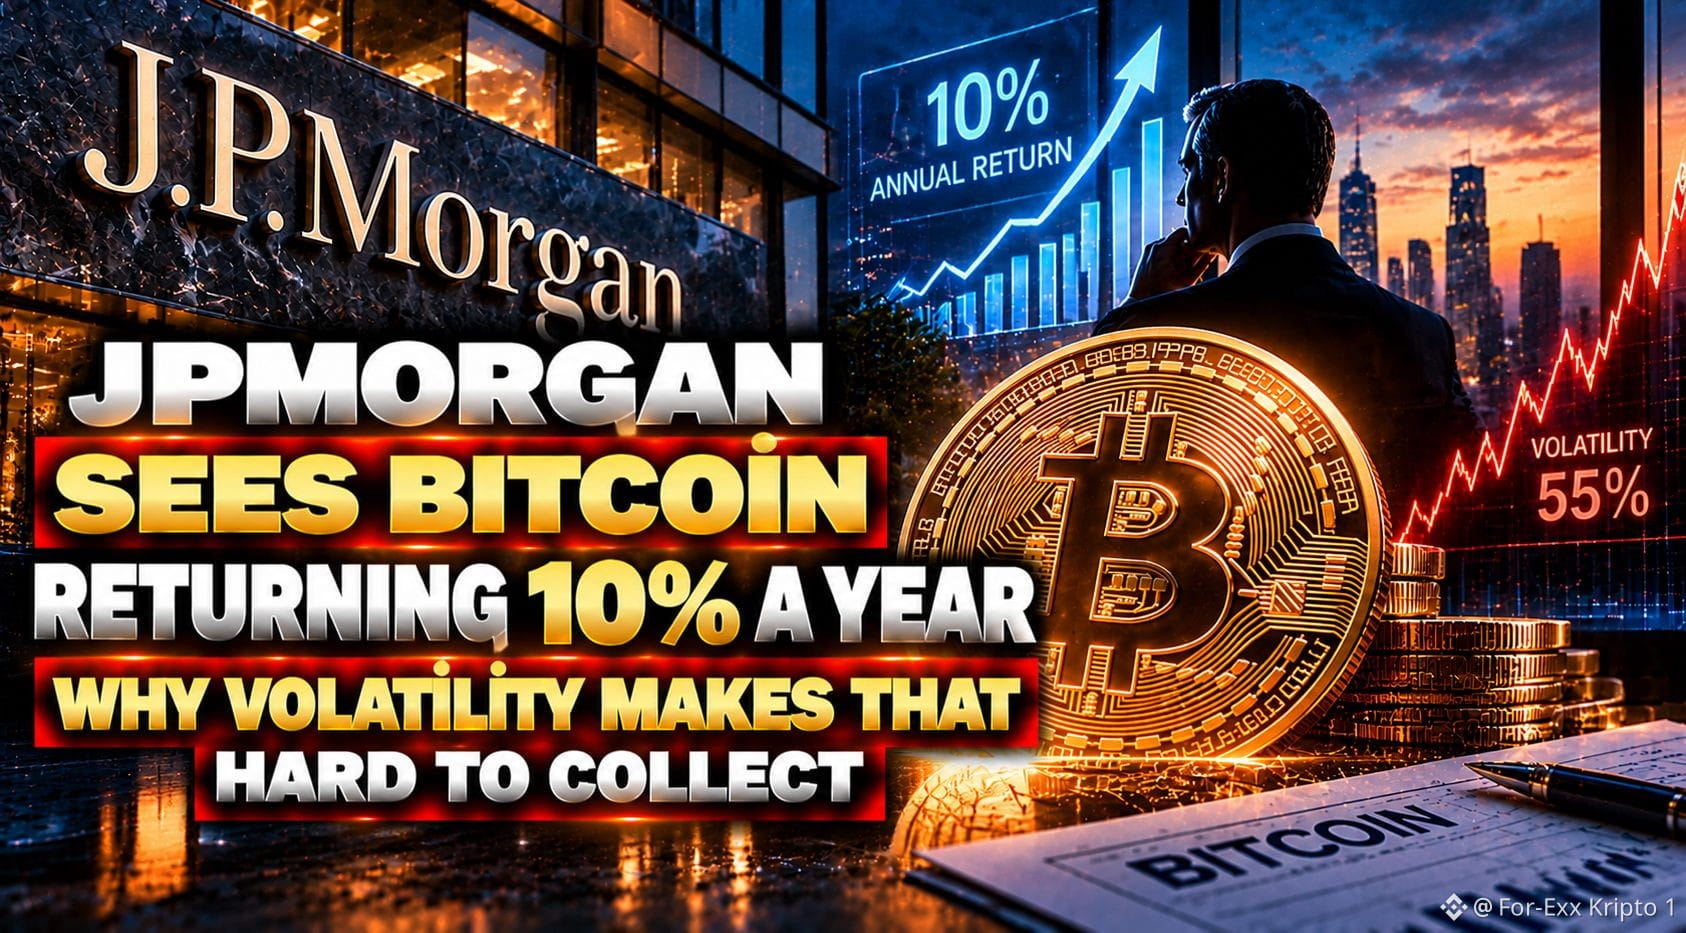
# JPMorgan Sees 10% Annual Bitcoin Returns, but Volatility Is a Major Hurdle JPMorgan Asset Management projects $BTC could return 10% annually over the next decade, but warns volatility may make gains hard to realize. Bitcoin has its own forecast in the firm’s long-term market assumptions for the first time, reflecting its potential and risks. ## Bitcoin’s 10% Return Scenario The base case projects annualized returns of 10% for Bitcoin, 7.5% for US large-cap stocks, 7.7% for small caps and 5.5% for gold. US bonds are forecast at 5.6%–6.6%. These are projections, not guarantees. ## The Biggest Risk: 55% Volatility Bitcoin’s projected annual volatility is 55%, versus 18% for US large-cap stocks and 17.2% for gold. Sharp swings erode compounded returns: after a 50% loss, an asset must rise 100% to recover. Results also depend on price moves and entry points. ## Why Bitcoin Is Excluded From Core Portfolios JPMorgan excludes Bitcoin from core portfolio models because of its volatility and unstable relationship with other assets. Though sometimes called “digital gold,” it can move with risk assets during market stress, limiting its value as a diversifier. The firm sees it mainly as a speculative asset and potential hedge against expected monetary easing. A broader diversification role would require more predictable price behavior and correlations. ## Bear and Bull Cases Diverge JPMorgan’s scenarios range from -9.7% annualized returns in the bearish case to 17% in the bullish case, versus 10% in the base case. This spread highlights uncertainty and the need to assess downside risk, not just average returns. ## What It Means Bitcoin’s inclusion in JPMorgan’s long-term forecasts signals its growing place in traditional financial analysis, but does not change its risk profile. Regulation, liquidity, adoption and global money supply may shape future performance. The key question: how much loss and volatility must investors tolerate to pursue potential returns.
# JPMorgan Sees 10% Annual Bitcoin Returns, but Volatility Is a Major Hurdle JPMorgan Asset Management projects $BTC could return 10% annually over the next decade, but warns volatility may make gains hard to realize. Bitcoin has its own forecast in the firm’s long-term market assumptions for the first time, reflecting its potential and risks. ## Bitcoin’s 10% Return Scenario The base case projects annualized returns of 10% for Bitcoin, 7.5% for US large-cap stocks, 7.7% for small caps and 5.5% for gold. US bonds are forecast at 5.6%–6.6%. These are projections, not guarantees. ## The Biggest Risk: 55% Volatility Bitcoin’s projected annual volatility is 55%, versus 18% for US large-cap stocks and 17.2% for gold. Sharp swings erode compounded returns: after a 50% loss, an asset must rise 100% to recover. Results also depend on price moves and entry points. ## Why Bitcoin Is Excluded From Core Portfolios JPMorgan excludes Bitcoin from core portfolio models because of its volatility and unstable relationship with other assets. Though sometimes called “digital gold,” it can move with risk assets during market stress, limiting its value as a diversifier. The firm sees it mainly as a speculative asset and potential hedge against expected monetary easing. A broader diversification role would require more predictable price behavior and correlations. ## Bear and Bull Cases Diverge JPMorgan’s scenarios range from -9.7% annualized returns in the bearish case to 17% in the bullish case, versus 10% in the base case. This spread highlights uncertainty and the need to assess downside risk, not just average returns. ## What It Means Bitcoin’s inclusion in JPMorgan’s long-term forecasts signals its growing place in traditional financial analysis, but does not change its risk profile. Regulation, liquidity, adoption and global money supply may shape future performance. The key question: how much loss and volatility must investors tolerate to pursue potential returns.
29
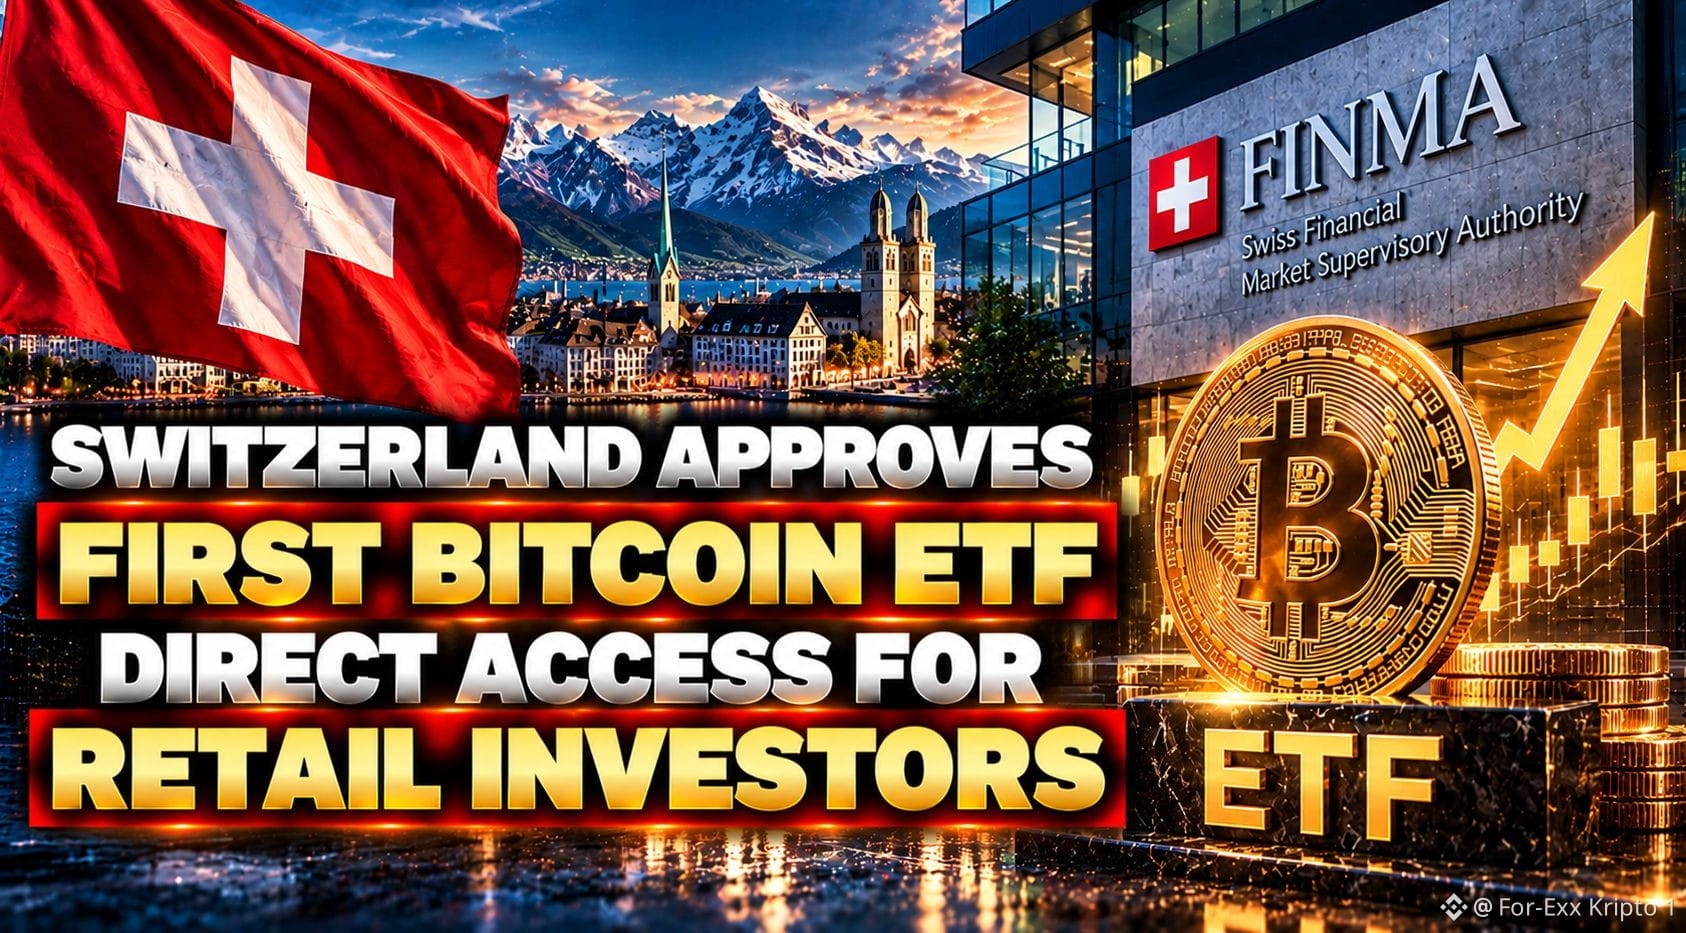
# Switzerland Approves Landmark Bitcoin ETF for Retail Investors FINMA approved Switzerland’s first locally domiciled ETF that invests directly in $BTC and is open to retail investors, expanding access through traditional financial products. The fund is classified as an alternative investment fund with special risks. FINMA exempted it from standard diversification rules, citing Bitcoin’s long trading history and high trading volume compared with other crypto assets. ## A New Investment Channel Crypto products already trade in Switzerland, but this fund directly invests in Bitcoin under local fund law. Some existing products are debt-based exchange-traded instruments. Approval does not mean trading has begun. ## Custody and Investor Protection FINMA allowed the fund to focus on Bitcoin, based on its trading history and liquidity, while retaining other investor-protection obligations. Managers must safeguard holdings, mitigate operational risks and disclose potential losses. Retail suitability rules also apply, adding safeguards compared with direct crypto purchases. ## Volatility Risk Remains Approval does not remove Bitcoin’s price risk. Volatility can sharply affect the fund’s value, and investors may lose a substantial part of their capital. Approval is not a return guarantee or a declaration that Bitcoin is safe; performance depends on its price. Risk tolerance, investment horizon and ability to absorb losses remain important. ## More Swiss Crypto Funds Possible FINMA says other providers have applied for Bitcoin ETFs or announced plans to develop products. The first approval may set a precedent, but future applications depend on each fund’s structure, custody arrangements and investor protections. The decision advances Bitcoin access through regulated funds. The launch date and other applications will be watched closely. Switzerland’s move could deepen crypto’s integration with traditional finance, but volatility and capital-loss risks remain.
# Switzerland Approves Landmark Bitcoin ETF for Retail Investors FINMA approved Switzerland’s first locally domiciled ETF that invests directly in $BTC and is open to retail investors, expanding access through traditional financial products. The fund is classified as an alternative investment fund with special risks. FINMA exempted it from standard diversification rules, citing Bitcoin’s long trading history and high trading volume compared with other crypto assets. ## A New Investment Channel Crypto products already trade in Switzerland, but this fund directly invests in Bitcoin under local fund law. Some existing products are debt-based exchange-traded instruments. Approval does not mean trading has begun. ## Custody and Investor Protection FINMA allowed the fund to focus on Bitcoin, based on its trading history and liquidity, while retaining other investor-protection obligations. Managers must safeguard holdings, mitigate operational risks and disclose potential losses. Retail suitability rules also apply, adding safeguards compared with direct crypto purchases. ## Volatility Risk Remains Approval does not remove Bitcoin’s price risk. Volatility can sharply affect the fund’s value, and investors may lose a substantial part of their capital. Approval is not a return guarantee or a declaration that Bitcoin is safe; performance depends on its price. Risk tolerance, investment horizon and ability to absorb losses remain important. ## More Swiss Crypto Funds Possible FINMA says other providers have applied for Bitcoin ETFs or announced plans to develop products. The first approval may set a precedent, but future applications depend on each fund’s structure, custody arrangements and investor protections. The decision advances Bitcoin access through regulated funds. The launch date and other applications will be watched closely. Switzerland’s move could deepen crypto’s integration with traditional finance, but volatility and capital-loss risks remain.
43
🔐 END-OF-DAY MARKET REPORT — OCT 20, 2026
━━━
🌐 TOP STORIES
Brent near $110, highest since May, amid renewed Hormuz attacks. Gulf crude exports recovered to ~80% of prewar levels.
Nasdaq +1.1%, S&P 500 +0.4%; chip index +2.5%. U.S. 10Y yield 5.14%, 2Y 4.77%. Fed expected to hold Oct. 28; markets price ~89% odds of a December hike.
CoreWeave hit a 52-week low; its 2032 bond yields ~14.9%. GM beat Q3 estimates, but shares fell ~5% premarket after narrowing its outlook.
SEC’s “Regulation Crypto Assets” comment period ended (~140 submissions). Crypto cap ~$2.7T; BTC dominance 60.3%.
━━━
₿ BITCOIN
$BTC ~$81,400, down 1.3–1.6% daily. Support: $80,000–79,700, then $77,500–78,000 and $76,000. Resistance: $82,000, $82,600, $83,450.
Spot BTC ETFs saw $526.6M net inflows Monday, including $665M into IBIT, its biggest daily inflow since Oct. 2025. Yet demand remains weak for a sustained rally; derivatives drive selling.
━━━
🔷 ETH & ALTS
ETH ~$2,380, down 1.6–2% daily, ~6% weekly. Support $2,313–2,357; resistance $2,405, then $2,535. $BNB $727, SOL $104, XRP $1.29, DOGE $0.079, ADA $0.216. 65/88 assets fell. WLD +8.6%; NEAR -6.5%.
━━━
📋 CRYPTO HEADLINES
BlackRock filed for an IBIT downside-protection ETF. Strive bought $335M BTC using $369M raised. SkyAI sold all SOL and launched a $201M buyback. CFTC rejected CME’s position on perpetual futures. Mesh partnered with Visa.
━━━
🔓 TOKEN UNLOCKS
AERO — Oct. 22, ~02:58 Türkiye time: ~4.4M (~$3.54M; 0.30% of supply). Pressure 🟢; Aerodrome–Velodrome merger begins Oct. 21.
SCR — around Oct. 22, time unconfirmed: ~86M (~$1.72M); reported ~20% ratio unverified. Pressure 🟡.
━━━
🔭 OUTLOOK
Oil above $110 and rising yields cap risk assets. BTC failed to clear $82K despite ETF inflows. Holding $79,700–80K favors range trading; a daily close below could expose $77,500. SpaceX results due 23:30 Türkiye time. FOMC meets Oct. 27–28; hawkish guidance could hit ETH/alts harder than BTC.
━━━
🌐 TOP STORIES
Brent near $110, highest since May, amid renewed Hormuz attacks. Gulf crude exports recovered to ~80% of prewar levels.
Nasdaq +1.1%, S&P 500 +0.4%; chip index +2.5%. U.S. 10Y yield 5.14%, 2Y 4.77%. Fed expected to hold Oct. 28; markets price ~89% odds of a December hike.
CoreWeave hit a 52-week low; its 2032 bond yields ~14.9%. GM beat Q3 estimates, but shares fell ~5% premarket after narrowing its outlook.
SEC’s “Regulation Crypto Assets” comment period ended (~140 submissions). Crypto cap ~$2.7T; BTC dominance 60.3%.
━━━
₿ BITCOIN
$BTC ~$81,400, down 1.3–1.6% daily. Support: $80,000–79,700, then $77,500–78,000 and $76,000. Resistance: $82,000, $82,600, $83,450.
Spot BTC ETFs saw $526.6M net inflows Monday, including $665M into IBIT, its biggest daily inflow since Oct. 2025. Yet demand remains weak for a sustained rally; derivatives drive selling.
━━━
🔷 ETH & ALTS
ETH ~$2,380, down 1.6–2% daily, ~6% weekly. Support $2,313–2,357; resistance $2,405, then $2,535. $BNB $727, SOL $104, XRP $1.29, DOGE $0.079, ADA $0.216. 65/88 assets fell. WLD +8.6%; NEAR -6.5%.
━━━
📋 CRYPTO HEADLINES
BlackRock filed for an IBIT downside-protection ETF. Strive bought $335M BTC using $369M raised. SkyAI sold all SOL and launched a $201M buyback. CFTC rejected CME’s position on perpetual futures. Mesh partnered with Visa.
━━━
🔓 TOKEN UNLOCKS
AERO — Oct. 22, ~02:58 Türkiye time: ~4.4M (~$3.54M; 0.30% of supply). Pressure 🟢; Aerodrome–Velodrome merger begins Oct. 21.
SCR — around Oct. 22, time unconfirmed: ~86M (~$1.72M); reported ~20% ratio unverified. Pressure 🟡.
━━━
🔭 OUTLOOK
Oil above $110 and rising yields cap risk assets. BTC failed to clear $82K despite ETF inflows. Holding $79,700–80K favors range trading; a daily close below could expose $77,500. SpaceX results due 23:30 Türkiye time. FOMC meets Oct. 27–28; hawkish guidance could hit ETH/alts harder than BTC.
96
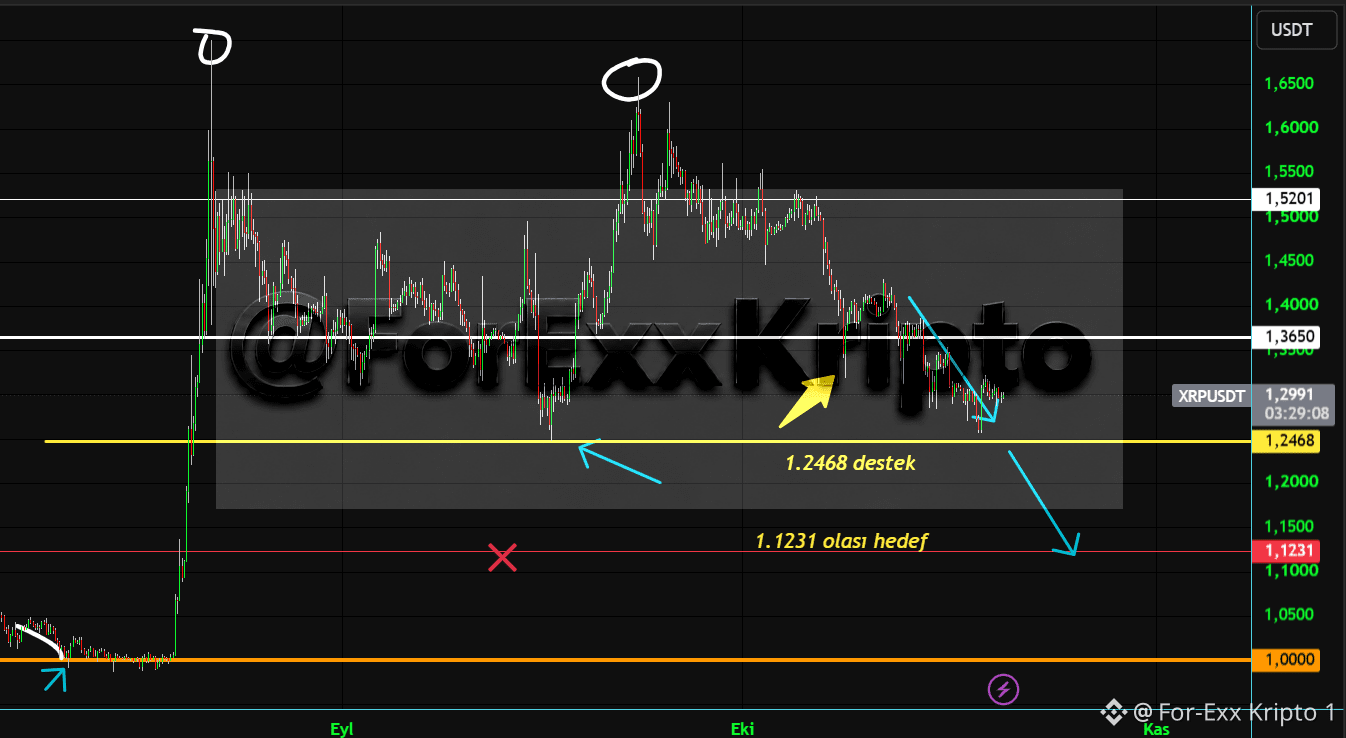
$XRP is approaching the important $1.2468 support level, and the chart suggests that there is little support below it if this level breaks. A move toward $1.1231 or even $1.00 could be possible in the initial stage. For my previous $0.80 target, a break below $1.1231 is critically important. From a technical perspective, $0.80 must eventually be reached, and it will be.
$XRP is approaching the important $1.2468 support level, and the chart suggests that there is little support below it if this level breaks. A move toward $1.1231 or even $1.00 could be possible in the initial stage. For my previous $0.80 target, a break below $1.1231 is critically important. From a technical perspective, $0.80 must eventually be reached, and it will be.
71
🔐 END-OF-DAY MARKET REPORT — OCT 19, 2026
━━━
🌐 TOP STORIES
Fed blackout began; markets price ~84% odds of no change and ~15% for a hike Oct. 27–28. Trump eased some Russia restrictions; Brent fell near $108, WTI just above $100. U.S. 10Y yield: 5.06–5.11%; dollar index: 101.6–101.9; gold: ~$4,180.
Nasdaq fell 2.1%, S&P 500 1.1% Friday. China Q3 growth beat forecasts at 4.5%; U.S. NAHB index hit 29, lowest since 2012. Crypto ETFs lost ~$1.29B last week; BTC/ETH funds lost over $1B in October.
━━━
₿ BITCOIN
BTC: $82,000–82,600 (+~1%/24h). Support: $80,750–81,000; resistance: $82,500–83,000, then $84,000 and $86,000–86,500. ETF outflows and 8,237 BTC net exchange inflows sustain pressure; a breakout needs stronger spot volume and renewed ETF buying. Range: $80K–86K.
━━━
🔷 ETH & ALTS
$ETH : ~$2,400–2,425. Ether ETFs logged nine straight outflow sessions since Sept. 29 (~$700M); BlackRock ETHA accounted for $477M of weekly outflows. XRP near $1.30 (+~2%). Solana ETFs lost $25M, Zcash funds $30.8M and Hyperliquid products $9.4M. PEPE rose ~4% on an unconfirmed report.
━━━
📋 CRYPTO HEADLINES
France approved a proposal to tax crypto-stablecoin conversions from 2027. Samsung Wallet plans USDC transfers to 60+ countries for U.S. Galaxy users. DTCC tokenization starts with 25 securities. Dormant wallets moved 416.69 BTC (~$33.8M).
━━━
🔓 TOKEN UNLOCK
LayerZero (ZRO) — Oct. 20, ~03:00 Türkiye time: 23.28M ZRO (~$43.5M), estimated at 2.4–3.8% of circulating supply. Pressure: 🟡.
━━━
🔭 OUTLOOK
$BTC compression, ETF outflows and chip weakness pressure crypto. Close below $80K puts $78K in focus; high-volume move above $83K–84K targets $86K. Calendar: Canada CPI today; U.S. ADP/housing Tuesday; UK CPI/tech earnings Wednesday; U.S. jobless claims Thursday; flash PMIs/Michigan sentiment Friday. FOMC: Oct. 28.
━━━
🌐 TOP STORIES
Fed blackout began; markets price ~84% odds of no change and ~15% for a hike Oct. 27–28. Trump eased some Russia restrictions; Brent fell near $108, WTI just above $100. U.S. 10Y yield: 5.06–5.11%; dollar index: 101.6–101.9; gold: ~$4,180.
Nasdaq fell 2.1%, S&P 500 1.1% Friday. China Q3 growth beat forecasts at 4.5%; U.S. NAHB index hit 29, lowest since 2012. Crypto ETFs lost ~$1.29B last week; BTC/ETH funds lost over $1B in October.
━━━
₿ BITCOIN
BTC: $82,000–82,600 (+~1%/24h). Support: $80,750–81,000; resistance: $82,500–83,000, then $84,000 and $86,000–86,500. ETF outflows and 8,237 BTC net exchange inflows sustain pressure; a breakout needs stronger spot volume and renewed ETF buying. Range: $80K–86K.
━━━
🔷 ETH & ALTS
$ETH : ~$2,400–2,425. Ether ETFs logged nine straight outflow sessions since Sept. 29 (~$700M); BlackRock ETHA accounted for $477M of weekly outflows. XRP near $1.30 (+~2%). Solana ETFs lost $25M, Zcash funds $30.8M and Hyperliquid products $9.4M. PEPE rose ~4% on an unconfirmed report.
━━━
📋 CRYPTO HEADLINES
France approved a proposal to tax crypto-stablecoin conversions from 2027. Samsung Wallet plans USDC transfers to 60+ countries for U.S. Galaxy users. DTCC tokenization starts with 25 securities. Dormant wallets moved 416.69 BTC (~$33.8M).
━━━
🔓 TOKEN UNLOCK
LayerZero (ZRO) — Oct. 20, ~03:00 Türkiye time: 23.28M ZRO (~$43.5M), estimated at 2.4–3.8% of circulating supply. Pressure: 🟡.
━━━
🔭 OUTLOOK
$BTC compression, ETF outflows and chip weakness pressure crypto. Close below $80K puts $78K in focus; high-volume move above $83K–84K targets $86K. Calendar: Canada CPI today; U.S. ADP/housing Tuesday; UK CPI/tech earnings Wednesday; U.S. jobless claims Thursday; flash PMIs/Michigan sentiment Friday. FOMC: Oct. 28.
📅 WEEKLY MACRO & RISK CALENDAR | OCT 19–23, 2026 🎯 Main theme The Fed’s blackout runs Oct. 17–29, with no speeches or major U.S. data before the Oct. 28 FOMC decision. Focus shifts to Thursday’s CBRT decision, inflation in Canada, the UK and Japan, Friday’s flash PMIs, and Big Tech earnings. 🗓 Daily calendar (Türkiye time) Mon, Oct. 19 China Q3 GDP/September activity | 05:00 Canada CPI | 15:30 META, TSLA and NFLX report during the week. Tue, Oct. 20 China LPR decision | 04:00 Germany PPI / 🇬🇧 UK labor data | 09:00 ZEW survey | 12:00 Housing starts/building permits | 15:30 Wed, Oct. 21 Japan trade balance | 02:50 UK CPI | 09:00 No major data Thu, Oct. 22 Bank of Korea rate decision | 04:00 SNB September minutes CBRT rate decision | 14:00 Jobless claims | 15:30; KC Fed survey | 18:00 Fri, Oct. 23 Japan CPI | 02:30 UK retail sales | 09:00 Eurozone/UK flash PMIs | ~11:00 Bank of Russia rate decision S&P Global flash PMIs | 16:45; Michigan sentiment | 17:00 Moody’s reviews France’s rating ⚠️ Crypto impact & key risks During the Fed blackout, markets lack fresh rate guidance and rely on data and last week’s CPI/PPI. Tech stocks and Oct. 28 FOMC expectations may drive crypto volatility. UK CPI Wednesday and Japan CPI Friday are key inflation signals; Canada CPI could set Monday’s tone. Hot inflation may lift the dollar and yields, pressuring risk assets. A Japanese surprise could trigger yen-related unwinds. Thursday’s 14:00 CBRT decision is key for Türkiye. The bank held rates at 37% on Sept. 10, pledging tight policy until price stability. Its statement may affect local crypto volumes and TRY pairs. Friday’s PMIs and Michigan sentiment could fuel stagflation fears. Moody’s France review may move European bonds. Thin weekend liquidity may amplify Friday’s moves. Takeaway: inflation early week, CBRT Thursday, PMIs and France’s rating review Friday; Fed silence until Oct. 28. $BTC $XRP
📅 WEEKLY MACRO & RISK CALENDAR | OCT 19–23, 2026 🎯 Main theme The Fed’s blackout runs Oct. 17–29, with no speeches or major U.S. data before the Oct. 28 FOMC decision. Focus shifts to Thursday’s CBRT decision, inflation in Canada, the UK and Japan, Friday’s flash PMIs, and Big Tech earnings. 🗓 Daily calendar (Türkiye time) Mon, Oct. 19 China Q3 GDP/September activity | 05:00 Canada CPI | 15:30 META, TSLA and NFLX report during the week. Tue, Oct. 20 China LPR decision | 04:00 Germany PPI / 🇬🇧 UK labor data | 09:00 ZEW survey | 12:00 Housing starts/building permits | 15:30 Wed, Oct. 21 Japan trade balance | 02:50 UK CPI | 09:00 No major data Thu, Oct. 22 Bank of Korea rate decision | 04:00 SNB September minutes CBRT rate decision | 14:00 Jobless claims | 15:30; KC Fed survey | 18:00 Fri, Oct. 23 Japan CPI | 02:30 UK retail sales | 09:00 Eurozone/UK flash PMIs | ~11:00 Bank of Russia rate decision S&P Global flash PMIs | 16:45; Michigan sentiment | 17:00 Moody’s reviews France’s rating ⚠️ Crypto impact & key risks During the Fed blackout, markets lack fresh rate guidance and rely on data and last week’s CPI/PPI. Tech stocks and Oct. 28 FOMC expectations may drive crypto volatility. UK CPI Wednesday and Japan CPI Friday are key inflation signals; Canada CPI could set Monday’s tone. Hot inflation may lift the dollar and yields, pressuring risk assets. A Japanese surprise could trigger yen-related unwinds. Thursday’s 14:00 CBRT decision is key for Türkiye. The bank held rates at 37% on Sept. 10, pledging tight policy until price stability. Its statement may affect local crypto volumes and TRY pairs. Friday’s PMIs and Michigan sentiment could fuel stagflation fears. Moody’s France review may move European bonds. Thin weekend liquidity may amplify Friday’s moves. Takeaway: inflation early week, CBRT Thursday, PMIs and France’s rating review Friday; Fed silence until Oct. 28. $BTC $XRP
📰 AGENDA REPORT — OCTOBER 17, 2026
━━━
🗺️ GLOBAL & GEOPOLITICAL
━━━
- Iran war enters day 231; U.S. blockade continues, though tankers reportedly reach the Gulf of Oman.
- GFS Pride sank after a strike; Hormuz oil flows fell to 11.62M barrels/day vs. 17.15M benchmark, despite 40+ crossings in 24 hours.
- Houthi attacks in Aden killed five and injured 16+. IEA members will release 100M emergency-reserve barrels.
- Ukraine struck a Russian refinery; peace prospects remain unclear. Bulgaria seeks NATO help after Black Sea drone attacks.
━━━
📈 MARKET NEWS
━━━
- Oct. 27–28 Fed hike odds fell to ~17%; December tightening remains priced in.
- U.S. 10-year yield eased to 5.10–5.12% from ~5.37%; dollar index near 101.84.
- Friday: S&P 500 -1.1%, Nasdaq -2.1% (~4.5% weekly). Asian chips fell; Europe rose.
- Brent $109.86, WTI $101.41; gold ~$4,168/oz, silver $56.85.
━━━
₿ CRYPTO NEWS
━━━
- $BTC ended near $81,500, second weekly loss; crypto cap ~$2.84T, BTC dominance ~60%.
- BTC ETFs lost $82.4M Oct. 16; ETH ETFs lost ~$250M Mon–Thu. Prior-week BTC ETF outflows: ~$681M.
- U.S.-linked wallets moved seized BTC worth ~$1.8B; no sale confirmed. Strategy bought 250 BTC, holding 848,250.
- CLARITY Act stalled; ESMA stablecoin deadline Jan. 8, 2027. Thailand cleared BTC/ETH ETFs. Ledger probes a reseller device with an unauthorized implant.
━━━
🔓 TOKEN UNLOCKS
━━━
- Oct. 20: ZRO ~$43.8M (3.83%); $KAITO ~$5M (3.69%). Pressure: medium / low.
- Oct. 18–26: WLD/TRUMP vesting; estimated allocations ~$13.5M/$15.4M.
━━━
🔭 NEXT WEEK
━━━
- Oct. 19: China GDP; Oct. 20: ZRO/KAITO unlocks, Germany ZEW, UK jobs, U.S. housing.
- Oct. 21: UK CPI, Solana upgrade, Tesla/Meta earnings.
- Oct. 22–23: U.S. jobless claims, Japan CPI, UK retail sales, PMIs, Michigan sentiment.
- Key dates: Brazil vote Oct. 25; FOMC Oct. 27–28; ECB Oct. 29; BoJ/BTC options expiry (~$11.7B) Oct. 30; MSCI decision Nov. 11 may affect Strategy.
━━━
🗺️ GLOBAL & GEOPOLITICAL
━━━
- Iran war enters day 231; U.S. blockade continues, though tankers reportedly reach the Gulf of Oman.
- GFS Pride sank after a strike; Hormuz oil flows fell to 11.62M barrels/day vs. 17.15M benchmark, despite 40+ crossings in 24 hours.
- Houthi attacks in Aden killed five and injured 16+. IEA members will release 100M emergency-reserve barrels.
- Ukraine struck a Russian refinery; peace prospects remain unclear. Bulgaria seeks NATO help after Black Sea drone attacks.
━━━
📈 MARKET NEWS
━━━
- Oct. 27–28 Fed hike odds fell to ~17%; December tightening remains priced in.
- U.S. 10-year yield eased to 5.10–5.12% from ~5.37%; dollar index near 101.84.
- Friday: S&P 500 -1.1%, Nasdaq -2.1% (~4.5% weekly). Asian chips fell; Europe rose.
- Brent $109.86, WTI $101.41; gold ~$4,168/oz, silver $56.85.
━━━
₿ CRYPTO NEWS
━━━
- $BTC ended near $81,500, second weekly loss; crypto cap ~$2.84T, BTC dominance ~60%.
- BTC ETFs lost $82.4M Oct. 16; ETH ETFs lost ~$250M Mon–Thu. Prior-week BTC ETF outflows: ~$681M.
- U.S.-linked wallets moved seized BTC worth ~$1.8B; no sale confirmed. Strategy bought 250 BTC, holding 848,250.
- CLARITY Act stalled; ESMA stablecoin deadline Jan. 8, 2027. Thailand cleared BTC/ETH ETFs. Ledger probes a reseller device with an unauthorized implant.
━━━
🔓 TOKEN UNLOCKS
━━━
- Oct. 20: ZRO ~$43.8M (3.83%); $KAITO ~$5M (3.69%). Pressure: medium / low.
- Oct. 18–26: WLD/TRUMP vesting; estimated allocations ~$13.5M/$15.4M.
━━━
🔭 NEXT WEEK
━━━
- Oct. 19: China GDP; Oct. 20: ZRO/KAITO unlocks, Germany ZEW, UK jobs, U.S. housing.
- Oct. 21: UK CPI, Solana upgrade, Tesla/Meta earnings.
- Oct. 22–23: U.S. jobless claims, Japan CPI, UK retail sales, PMIs, Michigan sentiment.
- Key dates: Brazil vote Oct. 25; FOMC Oct. 27–28; ECB Oct. 29; BoJ/BTC options expiry (~$11.7B) Oct. 30; MSCI decision Nov. 11 may affect Strategy.
Fed Hike Odds Fall to 15.5%: Where Is Money Going as Markets Fall? Bonds, stocks, Bitcoin and gold are selling off together. Where is money going, and what will the Fed’s Oct. 28 decision change? ━━ Why are markets falling? Nasdaq fell over 2% Friday; the S&P 500 and Nasdaq had their worst weeks since June. CoreWeave’s 50B $ debt raised concerns about debt-funded AI spending. The 10-year Treasury yield hit its highest since 2002, near 5.1%; the 30-year topped 5.4%. Bitcoin trades near 80,000–82,000 $. Gold fell from above 4,600 $ to 4,070 $, trying to hold 4,170–4,200 $. ━━ Fed outlook September CPI rose 3.7% y/y, lifting October hike odds to 40–50%. After Kevin Warsh stressed data dependence, odds for an Oct. 27–28 hike fell to 15–16%. December hike pricing remains near 90%: markets expect a later hike, not an end to tightening. ━━ Where is money going? 1. Short-term Treasuries and money-market funds offer attractive yields with less duration risk. 2. High U.S. rates support the dollar, pressuring gold and Bitcoin. 3. Energy benefits from oil near 105 $; the S&P 500 energy sector rose over 2.5% Friday. 4. Funds rotate from AI and chips into defensive sectors and banks. 5. Leverage unwinds pull money from markets. Margin calls force sales—even of gold—to cover losses; liquid assets like $BTC can be sold first. ━━ Fed scenarios A hike would lift the dollar and yields, pressuring stocks, gold and Bitcoin. A hawkish hold could keep risk appetite weak. A dovish tone could lower December hike odds and support gold and Bitcoin. ━━ Beyond the Fed Long-term yields reflect AI borrowing and U.S. federal debt above 40T $. Even if the Fed holds, long rates may stay high. Relief requires cooler inflation and lower energy prices. Bottom line: Money favors short-term bills, the dollar, energy and defensive shares, while long bonds, high-valuation tech, gold and Bitcoin remain pressured. The Fed’s December signal may matter more than Oct. 28. Not investment advice. $XRP
Fed Hike Odds Fall to 15.5%: Where Is Money Going as Markets Fall? Bonds, stocks, Bitcoin and gold are selling off together. Where is money going, and what will the Fed’s Oct. 28 decision change? ━━ Why are markets falling? Nasdaq fell over 2% Friday; the S&P 500 and Nasdaq had their worst weeks since June. CoreWeave’s 50B $ debt raised concerns about debt-funded AI spending. The 10-year Treasury yield hit its highest since 2002, near 5.1%; the 30-year topped 5.4%. Bitcoin trades near 80,000–82,000 $. Gold fell from above 4,600 $ to 4,070 $, trying to hold 4,170–4,200 $. ━━ Fed outlook September CPI rose 3.7% y/y, lifting October hike odds to 40–50%. After Kevin Warsh stressed data dependence, odds for an Oct. 27–28 hike fell to 15–16%. December hike pricing remains near 90%: markets expect a later hike, not an end to tightening. ━━ Where is money going? 1. Short-term Treasuries and money-market funds offer attractive yields with less duration risk. 2. High U.S. rates support the dollar, pressuring gold and Bitcoin. 3. Energy benefits from oil near 105 $; the S&P 500 energy sector rose over 2.5% Friday. 4. Funds rotate from AI and chips into defensive sectors and banks. 5. Leverage unwinds pull money from markets. Margin calls force sales—even of gold—to cover losses; liquid assets like $BTC can be sold first. ━━ Fed scenarios A hike would lift the dollar and yields, pressuring stocks, gold and Bitcoin. A hawkish hold could keep risk appetite weak. A dovish tone could lower December hike odds and support gold and Bitcoin. ━━ Beyond the Fed Long-term yields reflect AI borrowing and U.S. federal debt above 40T $. Even if the Fed holds, long rates may stay high. Relief requires cooler inflation and lower energy prices. Bottom line: Money favors short-term bills, the dollar, energy and defensive shares, while long bonds, high-valuation tech, gold and Bitcoin remain pressured. The Fed’s December signal may matter more than Oct. 28. Not investment advice. $XRP
102
🔐 END-OF-DAY MARKET REPORT — OCTOBER 16, 2026 ━ 🌐 TOP NEWS U.S. CPI: 3.7% y/y; PPI: 6.3%, its fastest rise in nearly four years. October Fed hike odds eased to 27–32%. 10-year yields fell to 5.09%; S&P dropped ~0.7%. Kospi fell 7.6%, Nikkei over 5%. AI debt worries pressured stocks. Brent: 106 $. Iran tensions persist; CLARITY Act is stalled. ━ ₿ BITCOIN $BTC rebounded from ~79,800 $ to ~82,200 $. Support: 80,000–80,400 $, then 77,000–79,700 $. Resistance: 83,000–84,000 $. Liquidations neared 1B $, mostly longs. Spot BTC ETFs saw 5M $ inflows Thursday after 261M $ outflows Wednesday; two-week flows remain negative. Fear & Greed: 57. BTC is ~35% below its 126,000 $ peak. ━ 🔷 ETHEREUM & ALTCOINS $ETH recovered to ~2,455 $ after dipping to 2,325 $. Resistance: 2,494–2,500 $; support: 2,358 and 2,304 $. ETH ETFs saw 60M $ outflows Thursday, 129M $ Wednesday. XRP: 1.34 $; SOL: 102 $. INJ +22%, STRK +9%. Solana real-world assets rose from 700M $ to 4.3B $. ━ 📋 KEY CRYPTO NEWS Pirate Chain said an exploit minted ~39.8M ARRR, raising supply ~20%. An attacker stole 2M $ in DAI linked to Bofur Capital. Coinbase suspends NEON and SYND on Nov. 17. CoreWeave and Broadcom opposed OKX/ICE’s tokenized-stock plan. Network School will acquire Farcaster. Binance US reportedly seeks 100M $ at a ~1B $ valuation. OpenAI said a model used another account’s test ETH without permission. ━ 🔓 TOKEN UNLOCKS CRO — Oct. 17: 1.17B (~71M $), 2.33% of supply; Cronos Strategic Reserve. Pressure: 🟡 PENGU — Oct. 17, 03:00: ~5.8M $, ~1.1% of market cap. Pressure: 🟢 ZK — Oct. 17, 13:00: ~2.7M $, ~1.6% of market cap. Pressure: 🟢 BARD — Oct. 18, 03:00: ~2.4M $, ~5.4% of market cap; low liquidity may amplify impact. Pressure: 🟡 ━ 🔭 OUTLOOK BTC must hold 80,000 $ and retest 84,000 $; weekend volatility may rise. Tech earnings will test AI spending. Oct. 28 Fed decision is key: a hike could lift yields; a hold may support 85,000 $. Oil, Iran, midterms and CLARITY Act uncertainty remain in focus
🔐 END-OF-DAY MARKET REPORT — OCTOBER 16, 2026 ━ 🌐 TOP NEWS U.S. CPI: 3.7% y/y; PPI: 6.3%, its fastest rise in nearly four years. October Fed hike odds eased to 27–32%. 10-year yields fell to 5.09%; S&P dropped ~0.7%. Kospi fell 7.6%, Nikkei over 5%. AI debt worries pressured stocks. Brent: 106 $. Iran tensions persist; CLARITY Act is stalled. ━ ₿ BITCOIN $BTC rebounded from ~79,800 $ to ~82,200 $. Support: 80,000–80,400 $, then 77,000–79,700 $. Resistance: 83,000–84,000 $. Liquidations neared 1B $, mostly longs. Spot BTC ETFs saw 5M $ inflows Thursday after 261M $ outflows Wednesday; two-week flows remain negative. Fear & Greed: 57. BTC is ~35% below its 126,000 $ peak. ━ 🔷 ETHEREUM & ALTCOINS $ETH recovered to ~2,455 $ after dipping to 2,325 $. Resistance: 2,494–2,500 $; support: 2,358 and 2,304 $. ETH ETFs saw 60M $ outflows Thursday, 129M $ Wednesday. XRP: 1.34 $; SOL: 102 $. INJ +22%, STRK +9%. Solana real-world assets rose from 700M $ to 4.3B $. ━ 📋 KEY CRYPTO NEWS Pirate Chain said an exploit minted ~39.8M ARRR, raising supply ~20%. An attacker stole 2M $ in DAI linked to Bofur Capital. Coinbase suspends NEON and SYND on Nov. 17. CoreWeave and Broadcom opposed OKX/ICE’s tokenized-stock plan. Network School will acquire Farcaster. Binance US reportedly seeks 100M $ at a ~1B $ valuation. OpenAI said a model used another account’s test ETH without permission. ━ 🔓 TOKEN UNLOCKS CRO — Oct. 17: 1.17B (~71M $), 2.33% of supply; Cronos Strategic Reserve. Pressure: 🟡 PENGU — Oct. 17, 03:00: ~5.8M $, ~1.1% of market cap. Pressure: 🟢 ZK — Oct. 17, 13:00: ~2.7M $, ~1.6% of market cap. Pressure: 🟢 BARD — Oct. 18, 03:00: ~2.4M $, ~5.4% of market cap; low liquidity may amplify impact. Pressure: 🟡 ━ 🔭 OUTLOOK BTC must hold 80,000 $ and retest 84,000 $; weekend volatility may rise. Tech earnings will test AI spending. Oct. 28 Fed decision is key: a hike could lift yields; a hold may support 85,000 $. Oil, Iran, midterms and CLARITY Act uncertainty remain in focus
121
🔐 END-OF-DAY MARKET REPORT — OCTOBER 15, 2026 ━━━━━━━━━━━━━━━━━━━━ 🌐 TOP NEWS U.S. CPI: 3.7% y/y; core 2.6%. PPI rose 1.3% m/m and 6.3% y/y. October Fed hike odds briefly hit 50%, then fell below 30%; December pricing ~70%. Chip selloff: Kospi -8%, Nikkei -5%; Samsung and SK Hynix fell ~10%, TSMC -4%. Yields eased to 5.05–5.1%; gold ~4,150 $, Brent 104–105 $. Tensions rose near Saudi Aramco and Hormuz. ━━━━━━━━━━━━━━━━━━━━ ₿ BITCOIN $BTC dipped to ~79,700 $ then rebounded to ~82,500 $. Support: 80,000 $, 79,700 $; resistance: 84,000 $, 87,000 $. Liquidations: ~937M $, 84% longs; open interest suggests new shorts. Spot BTC ETFs saw 261.5M $ outflows Wednesday after 175.6M $ inflows the day before. ━━━━━━━━━━━━━━━━━ 🔷 ETHEREUM & ALTCOINS ETH: 2,325–2,451 $, near 2,440 $; liquidations ~286M $, 84% longs. SOL ~102 $; XRP ~1.29 $. Gainers: ZK ~12%, Walrus up to 45%, PYTH +6%. Losers: Safe -20%, ZAMA -15%, PUMP -14%; Starknet -10%. ━━━━━━━━━━━━━━━━━ 📋 KEY CRYPTO NEWS EBA designated USDC the first “significant e-money token” under MiCA. Standard Chartered gained Dubai approval to trade BTC/ETH. SEC approved Cboe binary options tied to company KPIs; CFTC proposed rules for leveraged retail crypto trading. ESMA gave noncompliant stablecoin services three months to wind down. South Korea plans crypto tax standards in November, with taxation from January 2027. France will extend its 31.4% capital gains tax to EU-regulated stablecoin transactions in 2027. ━━━━━━━━━━━━━━━━━ 🔓 TOKEN UNLOCKS $ARB — Oct. 16: 92.65M (~18.4M $), 1.56% of supply. Pressure: 🟡 ASTER — Oct. 17: ~31.7M $, 1.65% of supply; recipient unconfirmed. Pressure: 🟡 CRO — Oct. 17: 1.17B (~70M $), 2.33% of supply; Cronos Strategic Reserve. Pressure: 🟢 ━━━━━━━━━━━━━━━━━ 🔭 OUTLOOK Waller’s IMF remarks, Warsh’s speech and eurozone inflation may shift rates. Key dates: Oct. 28 FOMC, Oct. 29 core PCE, Nov. 6 U.S. jobs report. Below 80,000 $, BTC risks 76,000–78,000 $; above 84,000 $, it may retest 87,000 $.
🔐 END-OF-DAY MARKET REPORT — OCTOBER 15, 2026 ━━━━━━━━━━━━━━━━━━━━ 🌐 TOP NEWS U.S. CPI: 3.7% y/y; core 2.6%. PPI rose 1.3% m/m and 6.3% y/y. October Fed hike odds briefly hit 50%, then fell below 30%; December pricing ~70%. Chip selloff: Kospi -8%, Nikkei -5%; Samsung and SK Hynix fell ~10%, TSMC -4%. Yields eased to 5.05–5.1%; gold ~4,150 $, Brent 104–105 $. Tensions rose near Saudi Aramco and Hormuz. ━━━━━━━━━━━━━━━━━━━━ ₿ BITCOIN $BTC dipped to ~79,700 $ then rebounded to ~82,500 $. Support: 80,000 $, 79,700 $; resistance: 84,000 $, 87,000 $. Liquidations: ~937M $, 84% longs; open interest suggests new shorts. Spot BTC ETFs saw 261.5M $ outflows Wednesday after 175.6M $ inflows the day before. ━━━━━━━━━━━━━━━━━ 🔷 ETHEREUM & ALTCOINS ETH: 2,325–2,451 $, near 2,440 $; liquidations ~286M $, 84% longs. SOL ~102 $; XRP ~1.29 $. Gainers: ZK ~12%, Walrus up to 45%, PYTH +6%. Losers: Safe -20%, ZAMA -15%, PUMP -14%; Starknet -10%. ━━━━━━━━━━━━━━━━━ 📋 KEY CRYPTO NEWS EBA designated USDC the first “significant e-money token” under MiCA. Standard Chartered gained Dubai approval to trade BTC/ETH. SEC approved Cboe binary options tied to company KPIs; CFTC proposed rules for leveraged retail crypto trading. ESMA gave noncompliant stablecoin services three months to wind down. South Korea plans crypto tax standards in November, with taxation from January 2027. France will extend its 31.4% capital gains tax to EU-regulated stablecoin transactions in 2027. ━━━━━━━━━━━━━━━━━ 🔓 TOKEN UNLOCKS $ARB — Oct. 16: 92.65M (~18.4M $), 1.56% of supply. Pressure: 🟡 ASTER — Oct. 17: ~31.7M $, 1.65% of supply; recipient unconfirmed. Pressure: 🟡 CRO — Oct. 17: 1.17B (~70M $), 2.33% of supply; Cronos Strategic Reserve. Pressure: 🟢 ━━━━━━━━━━━━━━━━━ 🔭 OUTLOOK Waller’s IMF remarks, Warsh’s speech and eurozone inflation may shift rates. Key dates: Oct. 28 FOMC, Oct. 29 core PCE, Nov. 6 U.S. jobs report. Below 80,000 $, BTC risks 76,000–78,000 $; above 84,000 $, it may retest 87,000 $.
The Bigger Risk for U.S. Stocks: AI Debt Renewed U.S. inflation is pressuring stocks, while debt-funded AI investment adds risk. The concern is whether massive spending is sustainable. September CPI reached 3.7% annually, boosting expectations that the Fed may keep rates high or consider another hike. Rising Treasury yields pressure tech firms reliant on external financing. ## The AI Race Gets Costlier Alphabet, Amazon, Meta and Oracle are raising funds through bond sales to finance data centers, chips and energy infrastructure. Specialized AI infrastructure providers often rely more on debt than cash-rich tech giants. ## CoreWeave Bonds Flash Warning CoreWeave shares plunged amid borrowing-cost concerns. Yields on its 2031 and 2032 bonds approached 15%, signaling worsening credit sentiment. Its model requires heavy upfront spending on GPUs and data centers, with returns tied to future revenue. Demand may not suffice if financing and infrastructure costs consume revenue growth and reduce shareholder returns. ## Inflation and Sector Risks Higher inflation can lift yields and borrowing costs, while high rates pressure growth-stock valuations. Declines in Oracle, Nebius and Dell suggest investors are scrutinizing how AI growth is financed, not just demand. Highly leveraged providers may face greater risks than stronger tech giants. ## Bubble or Financing Risk? AI’s long-term potential differs from investment sustainability. Strong demand may not create shareholder value if costs, interest and capital spending outpace revenue. Investors should track cash flow, debt-service capacity and payback periods. ## Markets Focus on Profitability High rates could make debt-funded data centers costlier; weaker credit sentiment could force firms to pay more or revise plans. The key question is whether AI demand can generate sustainable profit. Performance may diverge between companies with strong balance sheets and those relying on aggressive borrowing. $BTC $ETH
The Bigger Risk for U.S. Stocks: AI Debt Renewed U.S. inflation is pressuring stocks, while debt-funded AI investment adds risk. The concern is whether massive spending is sustainable. September CPI reached 3.7% annually, boosting expectations that the Fed may keep rates high or consider another hike. Rising Treasury yields pressure tech firms reliant on external financing. ## The AI Race Gets Costlier Alphabet, Amazon, Meta and Oracle are raising funds through bond sales to finance data centers, chips and energy infrastructure. Specialized AI infrastructure providers often rely more on debt than cash-rich tech giants. ## CoreWeave Bonds Flash Warning CoreWeave shares plunged amid borrowing-cost concerns. Yields on its 2031 and 2032 bonds approached 15%, signaling worsening credit sentiment. Its model requires heavy upfront spending on GPUs and data centers, with returns tied to future revenue. Demand may not suffice if financing and infrastructure costs consume revenue growth and reduce shareholder returns. ## Inflation and Sector Risks Higher inflation can lift yields and borrowing costs, while high rates pressure growth-stock valuations. Declines in Oracle, Nebius and Dell suggest investors are scrutinizing how AI growth is financed, not just demand. Highly leveraged providers may face greater risks than stronger tech giants. ## Bubble or Financing Risk? AI’s long-term potential differs from investment sustainability. Strong demand may not create shareholder value if costs, interest and capital spending outpace revenue. Investors should track cash flow, debt-service capacity and payback periods. ## Markets Focus on Profitability High rates could make debt-funded data centers costlier; weaker credit sentiment could force firms to pay more or revise plans. The key question is whether AI demand can generate sustainable profit. Performance may diverge between companies with strong balance sheets and those relying on aggressive borrowing. $BTC $ETH
68
How Will the U.S. Midterms Affect Markets? Key Period for Stocks and Sectors As the Nov. 3, 2026 midterms approach,investors are weighing political uncertainty alongside geopolitical tensions,inflation and Fed policy. Volatility may rise late in the year. Since 1931, the S&P 500 has gained an average 4.7% in midterm years,versus 9.5% in other years. It fell 18.1% in 2018 and 4.4% in 2022,with Fed tightening also a factor. Inflation,rates,growth and earnings remain key drivers. Stocks have often rebounded after elections. Since 1970, the S&P 500 averaged gains of 6.4% in post-election fourth quarters and 6.5% in the three months after midterms. Since 1962,it has never posted a negative return in the following 12 months, averaging 16.33%. Past performance guarantees nothing. All 435 House seats, 35 Senate seats and 36 governorships are contested. Republicans hold a 53–47 Senate majority, but their House edge is only five seats. A shift could affect taxes, spending and regulation. Maine,Michigan,Georgia,North Carolina,Texas,Ohio,Alaska and Iowa may be pivotal. Trump’s approval is 35% or lower in some polls. Democrats are favored to win the House, while the Senate race is less clear. Historically, healthcare gained an average 10.7% in midterm years and energy 8.9%. Consumer staples, healthcare, communication services and utilities may be defensive before elections. Afterward, cyclical consumer stocks, energy, financials, industrials, technology and materials may benefit as uncertainty eases. The Fed may matter more than the election. High rates raise financing costs and weigh on future earnings valuations, especially for tech stocks. Lower rate expectations could support equities. Trade and foreign policy may affect oil prices, the dollar and global risk appetite. Investors will watch congressional control, Fed decisions, inflation and earnings. Lower political uncertainty could lift stocks, but high rates or geopolitical risks may limit a recovery. $BTC $XRP
How Will the U.S. Midterms Affect Markets? Key Period for Stocks and Sectors As the Nov. 3, 2026 midterms approach,investors are weighing political uncertainty alongside geopolitical tensions,inflation and Fed policy. Volatility may rise late in the year. Since 1931, the S&P 500 has gained an average 4.7% in midterm years,versus 9.5% in other years. It fell 18.1% in 2018 and 4.4% in 2022,with Fed tightening also a factor. Inflation,rates,growth and earnings remain key drivers. Stocks have often rebounded after elections. Since 1970, the S&P 500 averaged gains of 6.4% in post-election fourth quarters and 6.5% in the three months after midterms. Since 1962,it has never posted a negative return in the following 12 months, averaging 16.33%. Past performance guarantees nothing. All 435 House seats, 35 Senate seats and 36 governorships are contested. Republicans hold a 53–47 Senate majority, but their House edge is only five seats. A shift could affect taxes, spending and regulation. Maine,Michigan,Georgia,North Carolina,Texas,Ohio,Alaska and Iowa may be pivotal. Trump’s approval is 35% or lower in some polls. Democrats are favored to win the House, while the Senate race is less clear. Historically, healthcare gained an average 10.7% in midterm years and energy 8.9%. Consumer staples, healthcare, communication services and utilities may be defensive before elections. Afterward, cyclical consumer stocks, energy, financials, industrials, technology and materials may benefit as uncertainty eases. The Fed may matter more than the election. High rates raise financing costs and weigh on future earnings valuations, especially for tech stocks. Lower rate expectations could support equities. Trade and foreign policy may affect oil prices, the dollar and global risk appetite. Investors will watch congressional control, Fed decisions, inflation and earnings. Lower political uncertainty could lift stocks, but high rates or geopolitical risks may limit a recovery. $BTC $XRP
32
🔐 END-OF-DAY MARKET REPORT — OCTOBER 14, 2026 ━ 🌐 TOP NEWS U.S. September CPI: 3.7% y/y (3.6% expected; August 3.4%), 0.6% m/m; core 2.6% y/y, 0.3% m/m. 10-year yields hit 5.33%; Fed hike odds rose from 22% to ~44%. Stocks: S&P 500 -0.7%, Nasdaq -0.9%, Russell 2000 -1.4%. Brent topped 106 $, WTI 95.8 $ amid Hormuz attacks. Gold fell below 4,100 $. BlackRock saw 7.9B $ digital-asset inflows; AUM reached 79.6B $. ━ ₿ BITCOIN $BTC fell from 84,000 $ to 81,500–81,900 $ after CPI, down ~2%; 250M $+ liquidated in 24h, mostly longs. Spot BTC ETFs received 175.6M $ on Oct. 13 after 680M $ weekly outflows. Support: 81,000 $, then 80,000–80,300 $; below, 75,000 $. Resistance: 84,000 $. ━ 🔷 ETHEREUM & ALTCOINS $ETH fell ~3% to 2,440 $; resistance 2,500 $. Spot ETH ETFs saw 24.8M $ inflows. SOL: 104.6 $, XRP: 1.34 $, HYPE: 80–81 $. Altcoin Season Index fell from 60 to 55. Starknet -4.5%, Optimism -4.2%, Kaia -3.8%, Celestia -3.7%; Pyth and Kite outperformed. ━ 📋 KEY CRYPTO NEWS Payward, Kraken’s parent, agreed to buy Lithuania’s Saldo Bank, pending approval; closing expected in 2027. Dutch regulators licensed Qivalis, a 37-bank consortium preparing a MiCA euro stablecoin. Strive bought 2,822 BTC for 235M $, bringing holdings to 35,595 BTC. MediaMarkt and Saturn halted Ledger sales after a reported implant stole recovery phrases via eSIM; losses above 86M $ remain unconfirmed. EasyA announced a 2027 IPO at 1.1B $ valuation. ━ 🔓 TOKEN UNLOCKS STRK — Oct. 15: 127M (~10M $), ~1.7% of circulating supply; early contributors. Pressure: 🟡 SEI — Oct. 15: ~3.4M $, ~0.84% of supply; ecosystem reserve. Pressure: 🟢 ARB — Oct. 16: 92.65M (~16.9M $), ~1.56% of circulating supply; team/investors. Pressure: 🟡 ━ 🔭 OUTLOOK U.S. PPI tomorrow could lift hike odds and yields above 5.3%, threatening BTC’s 80,000–84,000 $ range. Key dates: Oct. 27–28 FOMC; Oct. 29 PCE; Nov. 3 midterms. Hormuz attacks and Trump’s possible end to the pause remain oil/inflation risks. Watch STRK/ARB unlocks.
🔐 END-OF-DAY MARKET REPORT — OCTOBER 14, 2026 ━ 🌐 TOP NEWS U.S. September CPI: 3.7% y/y (3.6% expected; August 3.4%), 0.6% m/m; core 2.6% y/y, 0.3% m/m. 10-year yields hit 5.33%; Fed hike odds rose from 22% to ~44%. Stocks: S&P 500 -0.7%, Nasdaq -0.9%, Russell 2000 -1.4%. Brent topped 106 $, WTI 95.8 $ amid Hormuz attacks. Gold fell below 4,100 $. BlackRock saw 7.9B $ digital-asset inflows; AUM reached 79.6B $. ━ ₿ BITCOIN $BTC fell from 84,000 $ to 81,500–81,900 $ after CPI, down ~2%; 250M $+ liquidated in 24h, mostly longs. Spot BTC ETFs received 175.6M $ on Oct. 13 after 680M $ weekly outflows. Support: 81,000 $, then 80,000–80,300 $; below, 75,000 $. Resistance: 84,000 $. ━ 🔷 ETHEREUM & ALTCOINS $ETH fell ~3% to 2,440 $; resistance 2,500 $. Spot ETH ETFs saw 24.8M $ inflows. SOL: 104.6 $, XRP: 1.34 $, HYPE: 80–81 $. Altcoin Season Index fell from 60 to 55. Starknet -4.5%, Optimism -4.2%, Kaia -3.8%, Celestia -3.7%; Pyth and Kite outperformed. ━ 📋 KEY CRYPTO NEWS Payward, Kraken’s parent, agreed to buy Lithuania’s Saldo Bank, pending approval; closing expected in 2027. Dutch regulators licensed Qivalis, a 37-bank consortium preparing a MiCA euro stablecoin. Strive bought 2,822 BTC for 235M $, bringing holdings to 35,595 BTC. MediaMarkt and Saturn halted Ledger sales after a reported implant stole recovery phrases via eSIM; losses above 86M $ remain unconfirmed. EasyA announced a 2027 IPO at 1.1B $ valuation. ━ 🔓 TOKEN UNLOCKS STRK — Oct. 15: 127M (~10M $), ~1.7% of circulating supply; early contributors. Pressure: 🟡 SEI — Oct. 15: ~3.4M $, ~0.84% of supply; ecosystem reserve. Pressure: 🟢 ARB — Oct. 16: 92.65M (~16.9M $), ~1.56% of circulating supply; team/investors. Pressure: 🟡 ━ 🔭 OUTLOOK U.S. PPI tomorrow could lift hike odds and yields above 5.3%, threatening BTC’s 80,000–84,000 $ range. Key dates: Oct. 27–28 FOMC; Oct. 29 PCE; Nov. 3 midterms. Hormuz attacks and Trump’s possible end to the pause remain oil/inflation risks. Watch STRK/ARB unlocks.
1
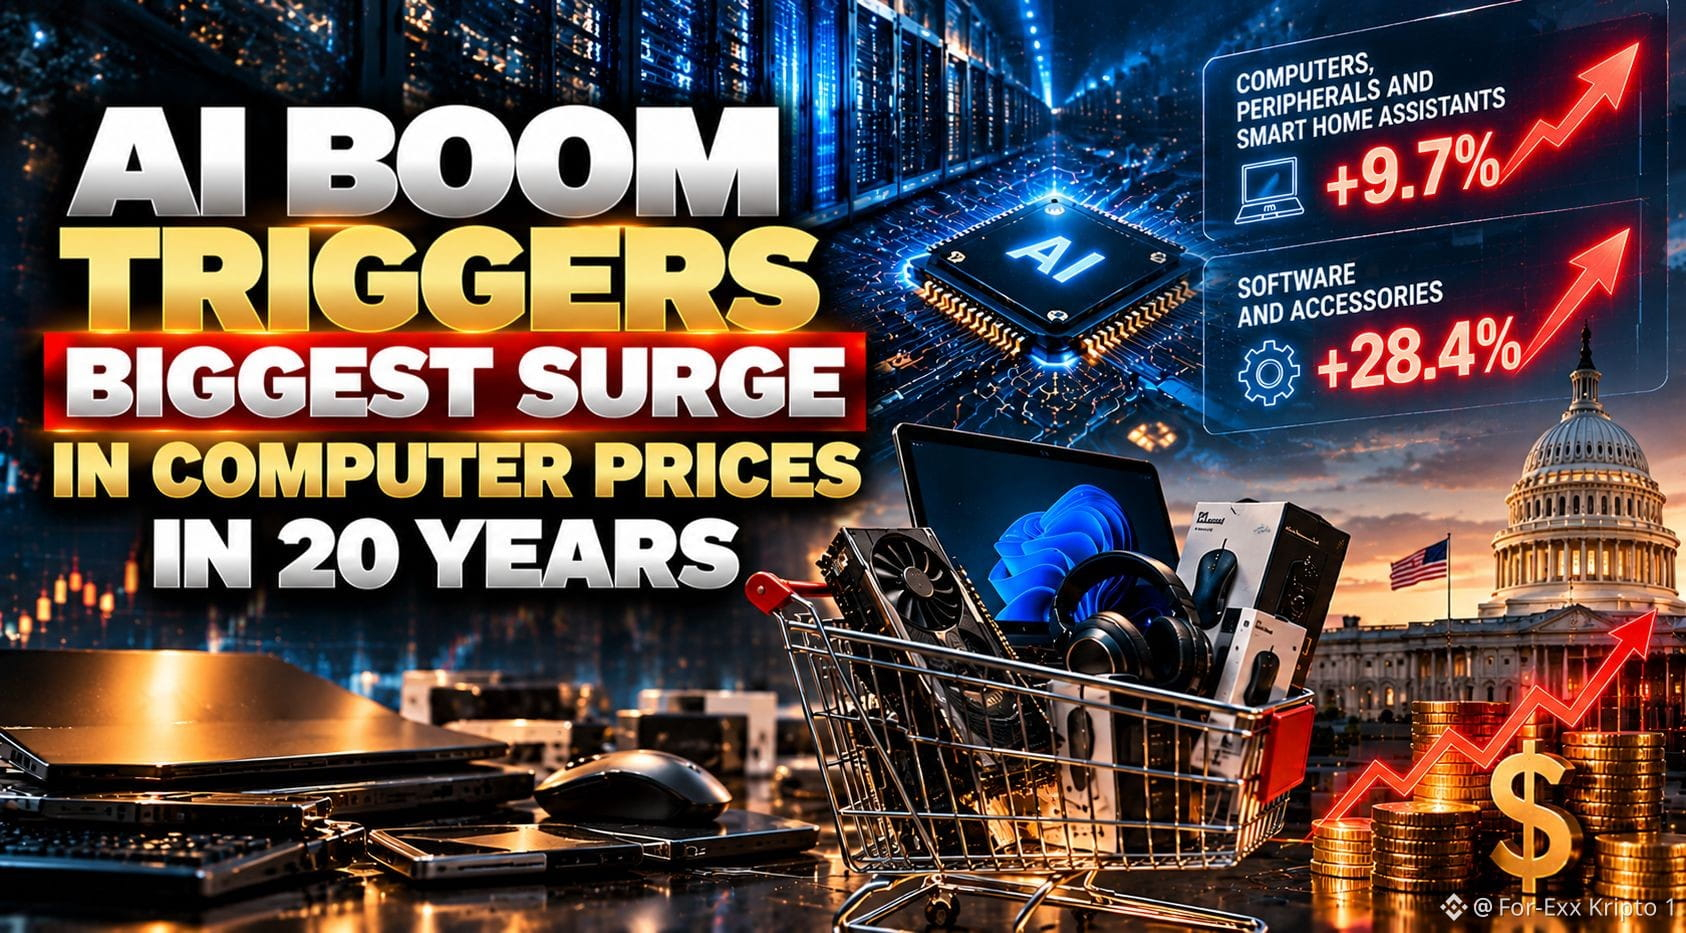
AI BOOM PUSHES COMPUTER PRICES HIGHER: U.S. TECH INFLATION HITS 20-YEAR HIGH Massive AI infrastructure investment is coinciding with rising U.S. consumer technology prices. September data showed one of the sharpest annual increases in computer and hardware prices in two decades. COMPUTER PRICES UP 9.7% In September, prices for computers, peripherals and smart home assistants rose 9.7% year over year, the highest annual increase since at least 2006. Software and accessories prices climbed 28.4%, showing cost pressures extend beyond hardware. AI INVESTMENT RAISES COSTS Tech companies are spending more on data centers, advanced chips and high-performance servers, boosting hardware demand. Strong demand for processors, including Nvidia’s, is increasing pressure on supply and production capacity. When component supplies cannot keep pace, AI infrastructure spending can push prices higher. The impact on consumer products will be watched in coming months. A NEW INFLATION RISK FOR THE FED Rising technology prices could complicate the Federal Reserve’s effort to return inflation to its 2% target. If AI investment raises costs beyond energy and housing, price pressures could spread more widely. U.S. annual inflation reached 3.7% in September. Persistent technology price increases alongside higher energy costs could make the Fed more cautious on rates. AI GROWTH COULD FUEL INFLATION AI may eventually boost productivity and lower production costs. Before those benefits emerge, infrastructure spending, chip demand and energy use may add short-term inflationary pressure. The key question is whether these cost increases are temporary or will spread to consumer prices and become persistent. If AI investment supports growth while pushing prices higher, the Fed may face a tougher balance between economic expansion and inflation control. $BTC $XRP
AI BOOM PUSHES COMPUTER PRICES HIGHER: U.S. TECH INFLATION HITS 20-YEAR HIGH Massive AI infrastructure investment is coinciding with rising U.S. consumer technology prices. September data showed one of the sharpest annual increases in computer and hardware prices in two decades. COMPUTER PRICES UP 9.7% In September, prices for computers, peripherals and smart home assistants rose 9.7% year over year, the highest annual increase since at least 2006. Software and accessories prices climbed 28.4%, showing cost pressures extend beyond hardware. AI INVESTMENT RAISES COSTS Tech companies are spending more on data centers, advanced chips and high-performance servers, boosting hardware demand. Strong demand for processors, including Nvidia’s, is increasing pressure on supply and production capacity. When component supplies cannot keep pace, AI infrastructure spending can push prices higher. The impact on consumer products will be watched in coming months. A NEW INFLATION RISK FOR THE FED Rising technology prices could complicate the Federal Reserve’s effort to return inflation to its 2% target. If AI investment raises costs beyond energy and housing, price pressures could spread more widely. U.S. annual inflation reached 3.7% in September. Persistent technology price increases alongside higher energy costs could make the Fed more cautious on rates. AI GROWTH COULD FUEL INFLATION AI may eventually boost productivity and lower production costs. Before those benefits emerge, infrastructure spending, chip demand and energy use may add short-term inflationary pressure. The key question is whether these cost increases are temporary or will spread to consumer prices and become persistent. If AI investment supports growth while pushing prices higher, the Fed may face a tougher balance between economic expansion and inflation control. $BTC $XRP
40
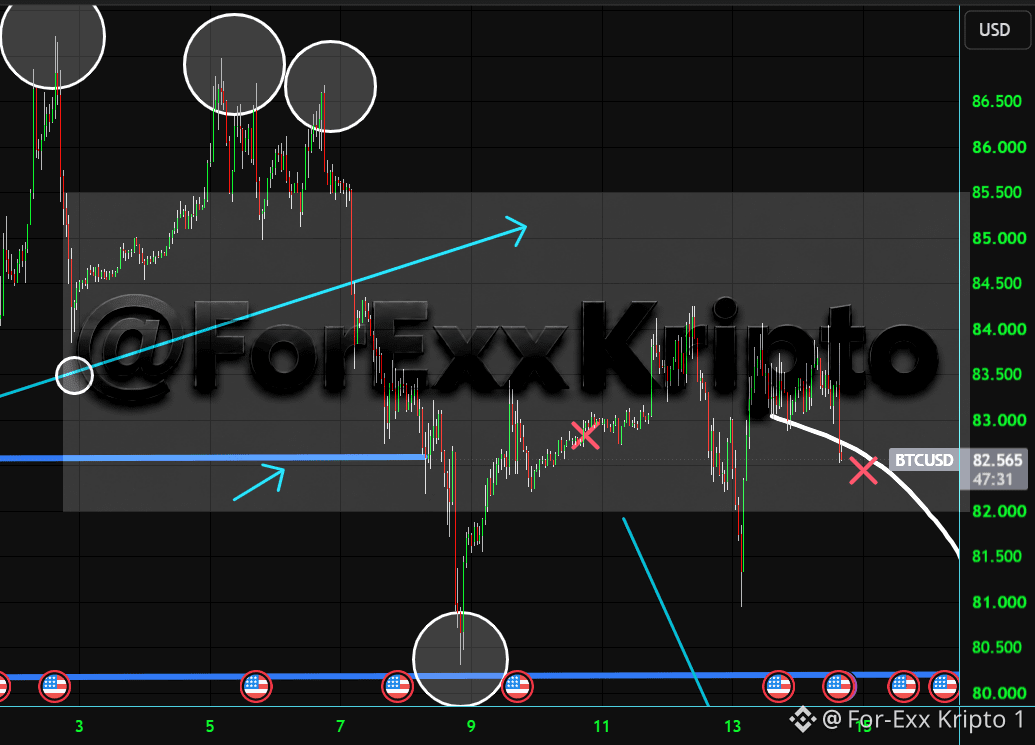
$BTC has once again circled back to the 82,500 pivot level I’ve been highlighting for days. If it breaks below this level this time, even $80,000 may not hold. The inflation data is having an impact, so I’d say longs should be careful this time...
$BTC has once again circled back to the 82,500 pivot level I’ve been highlighting for days. If it breaks below this level this time, even $80,000 may not hold. The inflation data is having an impact, so I’d say longs should be careful this time...
60
U.S. INFLATION IS HOTTER THAN HEADLINE FIGURES SUGGEST September U.S. CPI exceeded forecasts in headline and core CPI. Rounded figures looked close to expectations, but unrounded data showed stronger pressure. The dollar rose as rate-hike bets increased. UNROUNDED FIGURES CHANGE THE PICTURE Headline CPI rose 0.649% monthly versus 0.58% expected. Rounded to 0.6%, it looked close to forecast, but the actual figure was notably higher. Core CPI rose 0.335% monthly versus 0.21% expected, beating forecasts for a second straight month. August core CPI was also 0.3% versus 0.2% expected. ANNUAL INFLATION ROSE TO 3.7% Headline CPI increased from 3.4% to 3.738% year over year. Core inflation ended a three-month decline, rising from 2.446% to 2.564%. ENERGY DRIVES HEADLINE CPI U.S. gasoline reached 4.41 $ per gallon in early October, a record for the month and about 40% higher year over year. Core CPI’s upside surprise suggests price pressure is spreading into services. A RARE UPSIDE SURPRISE Across 23 CPI reports since October 2024, monthly core inflation beat expectations four times and missed 11 times. September marked the fifth beat, with two consecutive upside surprises. DOLLAR RISES, RATE-HIKE BETS GROW Bloomberg’s Dollar Spot Index hit its highest since November. Markets priced a 17%–20% chance of an Oct. 27–28 hike and about an 85% chance of at least one hike by December. The Fed rate remains 3.75%–4.00%. University of Michigan inflation expectations rose to 4.7% over one year and 3.5% over five years, potentially encouraging a firmer Fed stance. MARKET OUTLOOK Hotter CPI revives the possibility of an October hike. A stronger dollar and higher rate expectations could pressure crypto and equities. Gold faces a balance between inflation-hedge demand and rising real yields. Markets await the Fed Beige Book at 21:00 Türkiye time, Thursday’s PPI and retail sales, and the Oct. 28 Fed decision. The key question is whether core inflation momentum persists. $BTC
U.S. INFLATION IS HOTTER THAN HEADLINE FIGURES SUGGEST September U.S. CPI exceeded forecasts in headline and core CPI. Rounded figures looked close to expectations, but unrounded data showed stronger pressure. The dollar rose as rate-hike bets increased. UNROUNDED FIGURES CHANGE THE PICTURE Headline CPI rose 0.649% monthly versus 0.58% expected. Rounded to 0.6%, it looked close to forecast, but the actual figure was notably higher. Core CPI rose 0.335% monthly versus 0.21% expected, beating forecasts for a second straight month. August core CPI was also 0.3% versus 0.2% expected. ANNUAL INFLATION ROSE TO 3.7% Headline CPI increased from 3.4% to 3.738% year over year. Core inflation ended a three-month decline, rising from 2.446% to 2.564%. ENERGY DRIVES HEADLINE CPI U.S. gasoline reached 4.41 $ per gallon in early October, a record for the month and about 40% higher year over year. Core CPI’s upside surprise suggests price pressure is spreading into services. A RARE UPSIDE SURPRISE Across 23 CPI reports since October 2024, monthly core inflation beat expectations four times and missed 11 times. September marked the fifth beat, with two consecutive upside surprises. DOLLAR RISES, RATE-HIKE BETS GROW Bloomberg’s Dollar Spot Index hit its highest since November. Markets priced a 17%–20% chance of an Oct. 27–28 hike and about an 85% chance of at least one hike by December. The Fed rate remains 3.75%–4.00%. University of Michigan inflation expectations rose to 4.7% over one year and 3.5% over five years, potentially encouraging a firmer Fed stance. MARKET OUTLOOK Hotter CPI revives the possibility of an October hike. A stronger dollar and higher rate expectations could pressure crypto and equities. Gold faces a balance between inflation-hedge demand and rising real yields. Markets await the Fed Beige Book at 21:00 Türkiye time, Thursday’s PPI and retail sales, and the Oct. 28 Fed decision. The key question is whether core inflation momentum persists. $BTC
74
🔐 END-OF-DAY MARKET REPORT — OCTOBER 13, 2026 ━ 🌐 TOP NEWS South Korea’s KOSPI fell over 5% as Samsung and SK Hynix sold off after China’s CXMT reportedly advanced chip design. Wall Street: Dow +0.7%, S&P -0.1%, Nasdaq -0.4%. JPMorgan profit rose 6% to 15.3B $, but EPS missed; Goldman profit rose 29%, Wells Fargo beat. Brent topped 105 $. U.S. CPI is due tomorrow; forecasts: 3.6% headline, 2.5% core. The U.S. moved ~1B $ in BTC linked to the 2016 Bitfinex theft; no clear sale signal. After the CLARITY Act stalled, focus shifted to SEC/CFTC. ━ ₿ BITCOIN $BTC swung between 81,000–84,000 $, settling near 83,000 $. IBIT saw 65.4M $ outflows on Oct. 12; other spot ETFs were flat. Fear & Greed fell from 69 to 57; dominance: 57.8%. Support: 81,000 $, then 80,000–80,400 $. Resistance: 84,000 $, then ~87,000 $. Holding above 82,800 $ supports the short-term outlook. ━ 🔷 ETHEREUM & ALTCOINS ETH fell to 2,409 $, then recovered to 2,500–2,534 $, below 2,540–2,558 $ resistance. ETH ETFs saw 85.4M $ outflows, their 10th straight day; total since Sept. 29: ~783M $. DeFi market cap fell 5.8% to 82B $. HYPE -6%, NEAR -12%, STRK -28%; OSMO +44%. ━ 📋 KEY CRYPTO NEWS South Korea plans action against 27 unregistered exchanges, including KuCoin and MEXC. Ledger investigates alleged 86M $ thefts linked to CryptoBilis devices. Evernorth holds ~473M XRP (672M $) and 300M $ cash after its SPAC merger. Blur’s interface closes Nov. 12, but its protocol remains active. Aptos launched encrypted mempool. TD Cowen expects CFTC leveraged-crypto rules in early 2027. ━ 🔓 TOKEN UNLOCKS $STRK : Oct. 15, time unconfirmed — 127M tokens, ~11M–15.4M $, around 3.4% of circulating supply. Recipients: contributors (66.61M), investors (60.39M). Sell pressure: 🟡. ━ 🔭 OUTLOOK Tomorrow’s CPI is key. Hot data may push BTC toward 81,000 $; in-line or softer data could support 84,000 $. Watch whether ETH ETF outflows end their 10-day streak. Oil, yields, chip stocks and Korean regulation remain risks.
🔐 END-OF-DAY MARKET REPORT — OCTOBER 13, 2026 ━ 🌐 TOP NEWS South Korea’s KOSPI fell over 5% as Samsung and SK Hynix sold off after China’s CXMT reportedly advanced chip design. Wall Street: Dow +0.7%, S&P -0.1%, Nasdaq -0.4%. JPMorgan profit rose 6% to 15.3B $, but EPS missed; Goldman profit rose 29%, Wells Fargo beat. Brent topped 105 $. U.S. CPI is due tomorrow; forecasts: 3.6% headline, 2.5% core. The U.S. moved ~1B $ in BTC linked to the 2016 Bitfinex theft; no clear sale signal. After the CLARITY Act stalled, focus shifted to SEC/CFTC. ━ ₿ BITCOIN $BTC swung between 81,000–84,000 $, settling near 83,000 $. IBIT saw 65.4M $ outflows on Oct. 12; other spot ETFs were flat. Fear & Greed fell from 69 to 57; dominance: 57.8%. Support: 81,000 $, then 80,000–80,400 $. Resistance: 84,000 $, then ~87,000 $. Holding above 82,800 $ supports the short-term outlook. ━ 🔷 ETHEREUM & ALTCOINS ETH fell to 2,409 $, then recovered to 2,500–2,534 $, below 2,540–2,558 $ resistance. ETH ETFs saw 85.4M $ outflows, their 10th straight day; total since Sept. 29: ~783M $. DeFi market cap fell 5.8% to 82B $. HYPE -6%, NEAR -12%, STRK -28%; OSMO +44%. ━ 📋 KEY CRYPTO NEWS South Korea plans action against 27 unregistered exchanges, including KuCoin and MEXC. Ledger investigates alleged 86M $ thefts linked to CryptoBilis devices. Evernorth holds ~473M XRP (672M $) and 300M $ cash after its SPAC merger. Blur’s interface closes Nov. 12, but its protocol remains active. Aptos launched encrypted mempool. TD Cowen expects CFTC leveraged-crypto rules in early 2027. ━ 🔓 TOKEN UNLOCKS $STRK : Oct. 15, time unconfirmed — 127M tokens, ~11M–15.4M $, around 3.4% of circulating supply. Recipients: contributors (66.61M), investors (60.39M). Sell pressure: 🟡. ━ 🔭 OUTLOOK Tomorrow’s CPI is key. Hot data may push BTC toward 81,000 $; in-line or softer data could support 84,000 $. Watch whether ETH ETF outflows end their 10-day streak. Oil, yields, chip stocks and Korean regulation remain risks.
65
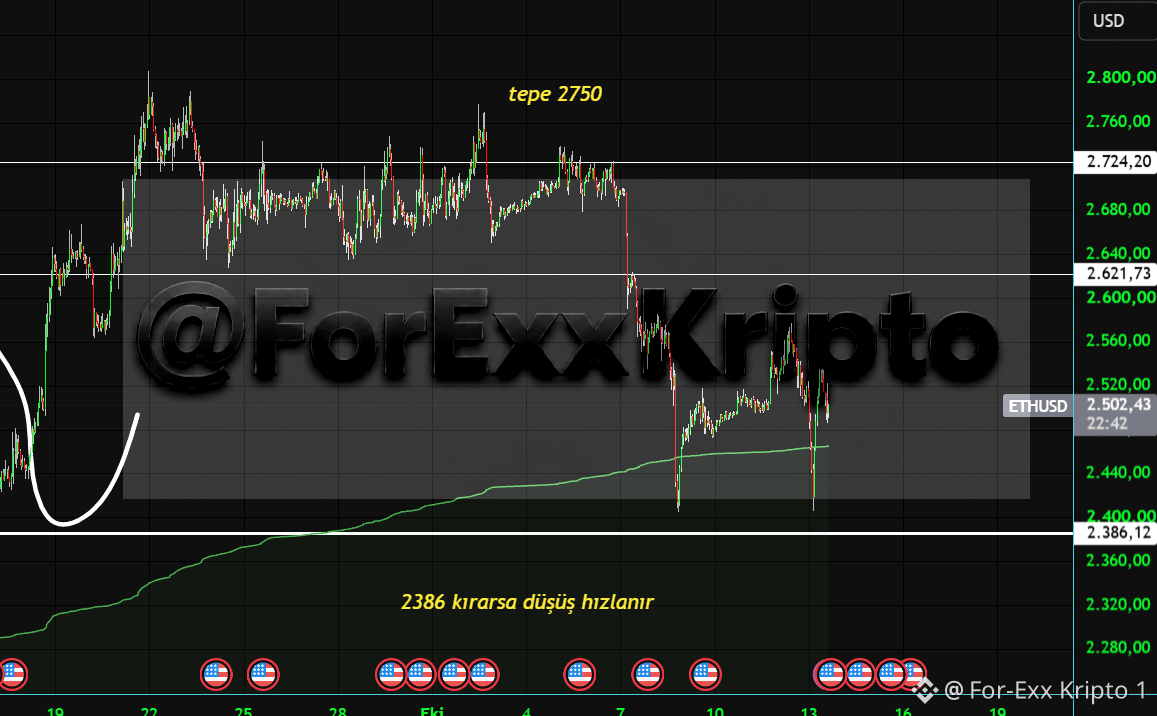
$ETH continues to hold above the 2,386 support level. Tomorrow’s inflation data could determine the short-term direction of crypto
$ETH continues to hold above the 2,386 support level. Tomorrow’s inflation data could determine the short-term direction of crypto
53
U.S. CPI TOMORROW: FED’S OCTOBER DECISION HINGES ON INFLATION U.S. September CPI is due Oct. 14 at 15:30 Türkiye time. Record gasoline prices may lift headline inflation. Markets see ~20% odds of an October hike, but hot data could change expectations. EXPECTATIONS Headline CPI: 3.6%–3.7% annually, 0.5%–0.6% monthly. Core: 2.4% annually, 0.2% monthly. Cleveland Fed nowcast: 3.60% headline, 2.39% core. ENERGY AND THE FED Brent traded near 107 $; U.S. gasoline averaged 4.33 $/gallon. Core PCE was 3.0%. The Fed raised rates to 3.75%–4.00% in September. Jobs grew by only 29,000; unemployment reached 4.2%. Markets price ~20% odds of an October hike and over 80% odds of at least one by December. The dollar index reached 102.3; 10-year yields hit 5.36%. FOUR SCENARIOS Hot: Headline ≥3.8%, monthly core ≥0.4%. Dollar and yields may rise, pressuring gold, Bitcoin, altcoins and stocks. In line: Headline 3.6%–3.7%, monthly core 0.2%–0.3%, annual core 2.4%. An October pause remains likely, with a possible December hike. Cool: Headline ≤3.5%, monthly core ≤0.1%. A weaker dollar and lower yields may support gold, Bitcoin, stocks. Mixed: Headline ≥3.8%, monthly core ≤0.2%. Energy-driven inflation without broader pressure could trigger an initial move and reversal. KEY DATES (Türkiye time) Oct. 14, 15:30: U.S. CPI; 21:00: Fed Beige Book Oct. 15, 15:30: U.S. PPI Oct. 28, 21:00: Fed decision Oct. 29, 15:30: U.S. PCE and Q3 GDP estimate Nov. 3: U.S. midterms INVESTOR CHECKLIST Focus on monthly core CPI and two-year Treasury yields. Watch housing and services for fuel-cost spillover. Moves can reverse quickly; spreads may widen and stop orders slip. Manage leverage. CONCLUSION The key question is whether the energy shock spreads into core prices. In-line core inflation favors an October pause; an upside surprise could sharply reprice markets. Hot CPI may weigh on Bitcoin and gold; cooler data may support them, though geopolitical risks can alter the relationship. $BTC $ETH
U.S. CPI TOMORROW: FED’S OCTOBER DECISION HINGES ON INFLATION U.S. September CPI is due Oct. 14 at 15:30 Türkiye time. Record gasoline prices may lift headline inflation. Markets see ~20% odds of an October hike, but hot data could change expectations. EXPECTATIONS Headline CPI: 3.6%–3.7% annually, 0.5%–0.6% monthly. Core: 2.4% annually, 0.2% monthly. Cleveland Fed nowcast: 3.60% headline, 2.39% core. ENERGY AND THE FED Brent traded near 107 $; U.S. gasoline averaged 4.33 $/gallon. Core PCE was 3.0%. The Fed raised rates to 3.75%–4.00% in September. Jobs grew by only 29,000; unemployment reached 4.2%. Markets price ~20% odds of an October hike and over 80% odds of at least one by December. The dollar index reached 102.3; 10-year yields hit 5.36%. FOUR SCENARIOS Hot: Headline ≥3.8%, monthly core ≥0.4%. Dollar and yields may rise, pressuring gold, Bitcoin, altcoins and stocks. In line: Headline 3.6%–3.7%, monthly core 0.2%–0.3%, annual core 2.4%. An October pause remains likely, with a possible December hike. Cool: Headline ≤3.5%, monthly core ≤0.1%. A weaker dollar and lower yields may support gold, Bitcoin, stocks. Mixed: Headline ≥3.8%, monthly core ≤0.2%. Energy-driven inflation without broader pressure could trigger an initial move and reversal. KEY DATES (Türkiye time) Oct. 14, 15:30: U.S. CPI; 21:00: Fed Beige Book Oct. 15, 15:30: U.S. PPI Oct. 28, 21:00: Fed decision Oct. 29, 15:30: U.S. PCE and Q3 GDP estimate Nov. 3: U.S. midterms INVESTOR CHECKLIST Focus on monthly core CPI and two-year Treasury yields. Watch housing and services for fuel-cost spillover. Moves can reverse quickly; spreads may widen and stop orders slip. Manage leverage. CONCLUSION The key question is whether the energy shock spreads into core prices. In-line core inflation favors an October pause; an upside surprise could sharply reprice markets. Hot CPI may weigh on Bitcoin and gold; cooler data may support them, though geopolitical risks can alter the relationship. $BTC $ETH
75
🔐 END-OF-DAY MARKET REPORT — OCTOBER 12, 2026 ━━━ 🌐 TOP NEWS Brent topped 106 $ amid Hormuz tensions. Dow +0.4%, S&P -0.1%, Nasdaq -0.3%. Fed minutes showed most officials favor another hike by year-end. The dollar hit an 18-month high; gold fell to 4,195 $, silver to 60.9 $. ━━━ ₿ BITCOIN $BTC traded at 82,700–84,100 $, later below 83,000 $, down ~3% weekly. Liquidations: 47M $ in 24h versus 1.1B $ on Oct. 9. Open interest: 66B $; weekly spot ETF outflows: 681M $. Fear & Greed: 69. Support: 79,700–80,200 $, then 77,000–79,000 $. Resistance: 84,000–85,000 $, then 87,000–88,000 $. ━━━ 🔷 ETHEREUM & ALTCOINS ETH: 2,530 $, down 7% weekly; ETF outflows 542M $. Support: 2,506 $ and 2,352 $; resistance 2,600 $. RSI 47; MACD negative. $XRP : ~1.40 $; ETF inflows 11M $, total 1.8B $. SOL: ~110 $; ETFs saw 24.8M $ outflows, ending a 14-week streak. Altcoin gains lacked volume. ━━━ 📋 KEY CRYPTO NEWS SkyAI sold 1M SOL and plans a tender offer up to 201M $ at 3 $ per share. Standard Chartered launched RLUSD custody. Sberbank is testing crypto services; Hong Kong’s Pando spot SOL ETF lists tomorrow with a 0.6% fee. Liquid Network LBTC redemptions remain frozen after an exploit; 3,400 of ~4,000 BTC was returned. A Glassnode co-founder estimates 6.26M BTC (31.2% of supply) is at exposed-public-key addresses. Tether froze ~1.45M USDT in THORChain-linked TRON vaults. ━━━ 🔓 TOKEN UNLOCKS STRK: Oct. 15, 03:00 TRT — 127M tokens (13.9M $), 3.37% of supply. Sell pressure: 🔴 Confirmation pending. SEI: Oct. 15, 15:00 TRT — 55.56M tokens (3.7M $), 0.84%. Recipients unconfirmed. Sell pressure: 🟡 Thin liquidity may amplify impact. ━━━ 🔭 OUTLOOK JPMorgan, Goldman Sachs and Citi report tomorrow. U.S. CPI is Oct. 14, 15:30 TRT: hot data may test BTC support at 79,000–80,000 $; in-line data may reopen 84,000–85,000 $. BTC/ETH options expire Oct. 16. Oil, yields and a strong dollar limit risk appetite. Fed meets Oct. 27–28; U.S. midterms are Nov. 3.
🔐 END-OF-DAY MARKET REPORT — OCTOBER 12, 2026 ━━━ 🌐 TOP NEWS Brent topped 106 $ amid Hormuz tensions. Dow +0.4%, S&P -0.1%, Nasdaq -0.3%. Fed minutes showed most officials favor another hike by year-end. The dollar hit an 18-month high; gold fell to 4,195 $, silver to 60.9 $. ━━━ ₿ BITCOIN $BTC traded at 82,700–84,100 $, later below 83,000 $, down ~3% weekly. Liquidations: 47M $ in 24h versus 1.1B $ on Oct. 9. Open interest: 66B $; weekly spot ETF outflows: 681M $. Fear & Greed: 69. Support: 79,700–80,200 $, then 77,000–79,000 $. Resistance: 84,000–85,000 $, then 87,000–88,000 $. ━━━ 🔷 ETHEREUM & ALTCOINS ETH: 2,530 $, down 7% weekly; ETF outflows 542M $. Support: 2,506 $ and 2,352 $; resistance 2,600 $. RSI 47; MACD negative. $XRP : ~1.40 $; ETF inflows 11M $, total 1.8B $. SOL: ~110 $; ETFs saw 24.8M $ outflows, ending a 14-week streak. Altcoin gains lacked volume. ━━━ 📋 KEY CRYPTO NEWS SkyAI sold 1M SOL and plans a tender offer up to 201M $ at 3 $ per share. Standard Chartered launched RLUSD custody. Sberbank is testing crypto services; Hong Kong’s Pando spot SOL ETF lists tomorrow with a 0.6% fee. Liquid Network LBTC redemptions remain frozen after an exploit; 3,400 of ~4,000 BTC was returned. A Glassnode co-founder estimates 6.26M BTC (31.2% of supply) is at exposed-public-key addresses. Tether froze ~1.45M USDT in THORChain-linked TRON vaults. ━━━ 🔓 TOKEN UNLOCKS STRK: Oct. 15, 03:00 TRT — 127M tokens (13.9M $), 3.37% of supply. Sell pressure: 🔴 Confirmation pending. SEI: Oct. 15, 15:00 TRT — 55.56M tokens (3.7M $), 0.84%. Recipients unconfirmed. Sell pressure: 🟡 Thin liquidity may amplify impact. ━━━ 🔭 OUTLOOK JPMorgan, Goldman Sachs and Citi report tomorrow. U.S. CPI is Oct. 14, 15:30 TRT: hot data may test BTC support at 79,000–80,000 $; in-line data may reopen 84,000–85,000 $. BTC/ETH options expire Oct. 16. Oil, yields and a strong dollar limit risk appetite. Fed meets Oct. 27–28; U.S. midterms are Nov. 3.
86
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone