

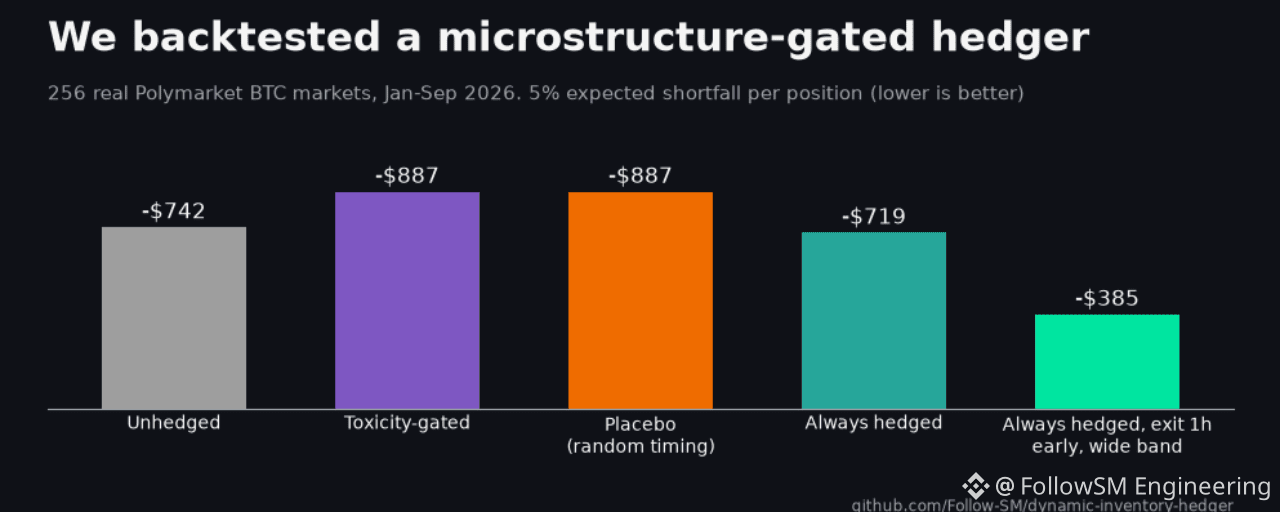
Can high-frequency microstructural signals improve risk management and hedging efficiency in prediction markets? We tested this hypothesis on Polymarket.
Here is what we engineered and discovered across 250+ real-market backtests:
💡 Core Concept
Instead of simple continuous delta hedging, our strategy gates dynamic hedging execution using real-time order book microstructure metrics (order flow toxicity, bid-ask spread liquidity dynamics, and depth imbalance).
🔑 Key Takeaways
Reduced Slippage & Execution Costs: Microstructure gating prevents aggressive hedging into illiquid order books, cutting adverse selection costs significantly.
Sharpe Ratio Improvement: Filtering hedge execution through microstructure signals generated a noticeable boost in risk-adjusted performance compared to static frequency rebalancing.
Liquidity Asymmetry Matters: Prediction markets exhibit extreme spread asymmetry during volatile events; micro-gating successfully mitigates execution drawdowns during these surges.
📖 Read the full breakdown & deep dive on DEV Community:
https://dev.to/followsm/we-built-a-microstructure-gated-hedger-for-polymarket-here-is-what-250-real-market-backtests-3hai