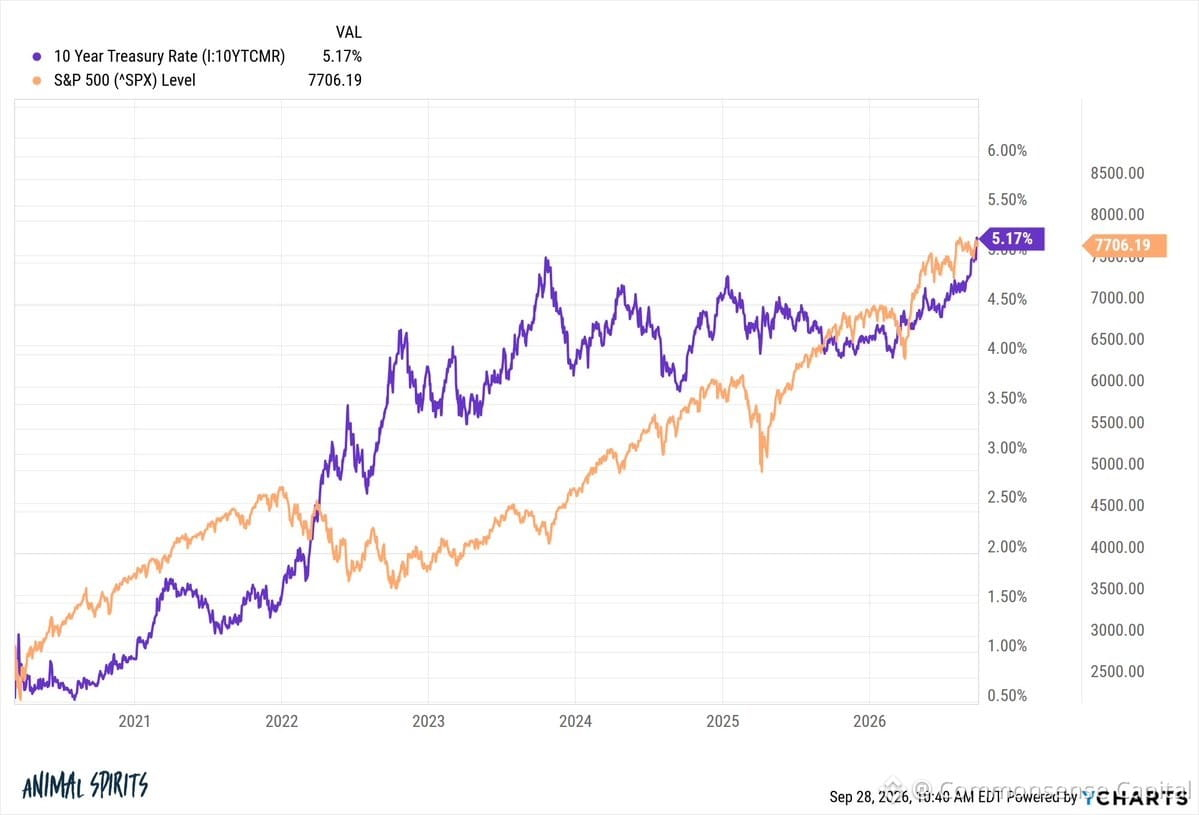
10-year Treasury yield: 0.5% in March 2020. Now sitting at 5.2%.
During one of the fastest rate hikes in modern history, the $SPY delivered 18.8% annualized returns. After inflation? Still around 15% real.
This breaks every textbook rule about bonds competing with stocks. High rates should crush equities. Instead, we got one of the best runs in years.
Why? Earnings grew faster than rates rose. Corporate profit margins held up. Tech adapted. Buybacks kept flowing. The "higher for longer" narrative became background noise while companies just kept printing money.
Doesn't mean it'll last forever. But it's a reminder: markets don't care about your macro thesis. They care about cash flow, pricing power, and whether companies can grow through the chaos.
Strange times indeed. Or maybe just proof that trying to time markets based on rate moves is a fool's game.