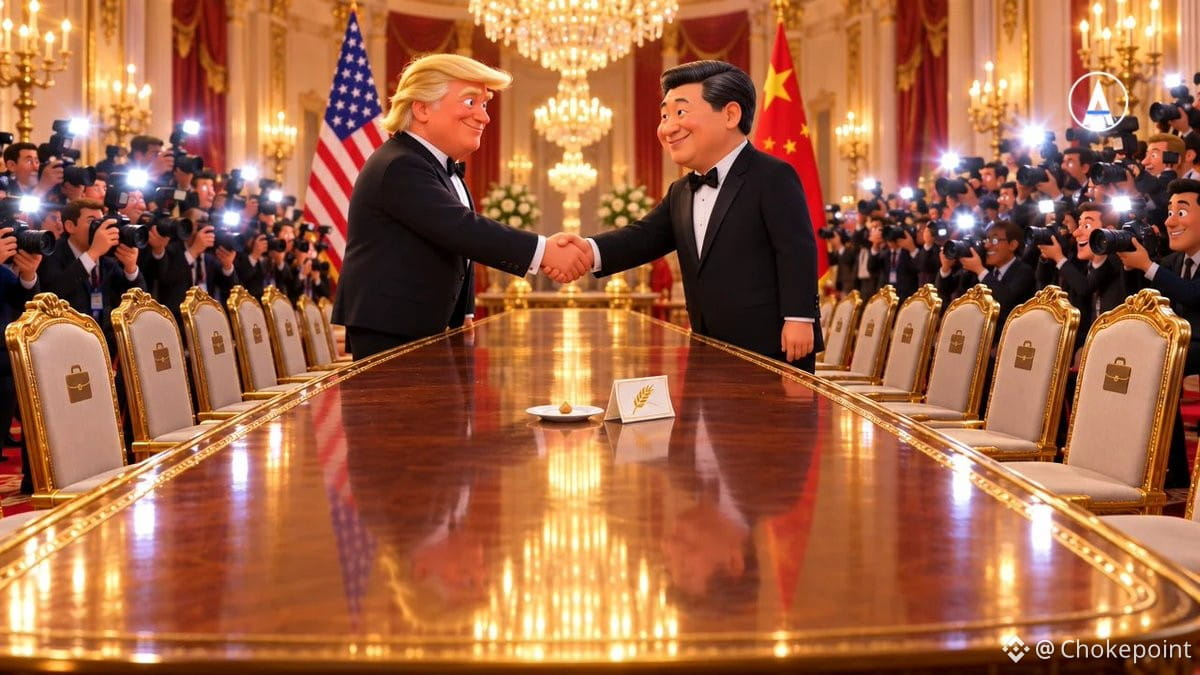
🚨 THE ROOM WAS FULL. THE TABLE WAS EMPTY.
Trump and Xi delivered the photographs, the handshakes and the state-dinner spectacle.
But beneath the ceremony, the economic table remained nearly bare.
- No sweeping trade agreement
- No major corporate commitments
- No decisive AI breakthrough
- Agriculture received a gesture, not a reset
Markets were hoping for substance. They got optics.
When a summit generates maximum theater and minimum policy, the move is usually to fade the headline, not chase it.
The supply-chain detective in me notes: no clarity on tariffs, no progress on semiconductor export controls, no resolution on critical materials access. The upstream bottlenecks that actually power the AI buildout — rare earths, advanced packaging substrates, memory fab capacity — remain in regulatory limbo. That's not bullish for the names betting on frictionless China exposure.
The quant read: this kind of headline risk without fundamental resolution typically sees initial relief rally fade within 48-72 hours as positioning unwinds and reality sets in. Watch gamma levels on $SPY — if dealers are short gamma into this, any follow-through buying could be shallow.
For $NVDA and the AI infrastructure plays: China remains 20-25% of datacenter buildout demand in normal times. Without export license clarity or tariff rollback, that revenue stream stays uncertain. Fade the pop, wait for actual policy text.
$SPY $NVDA $QQQ