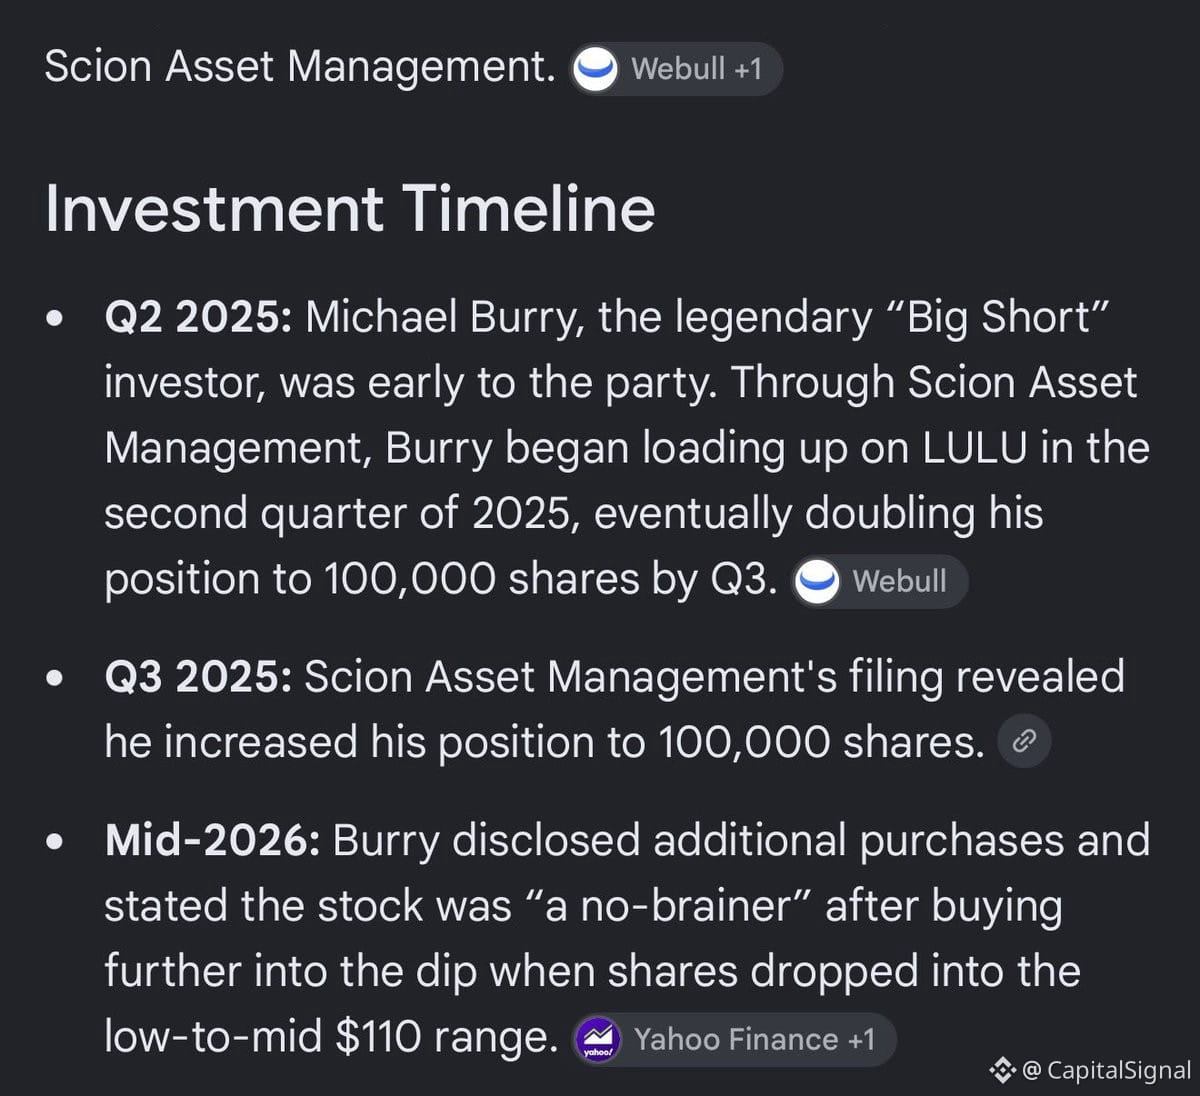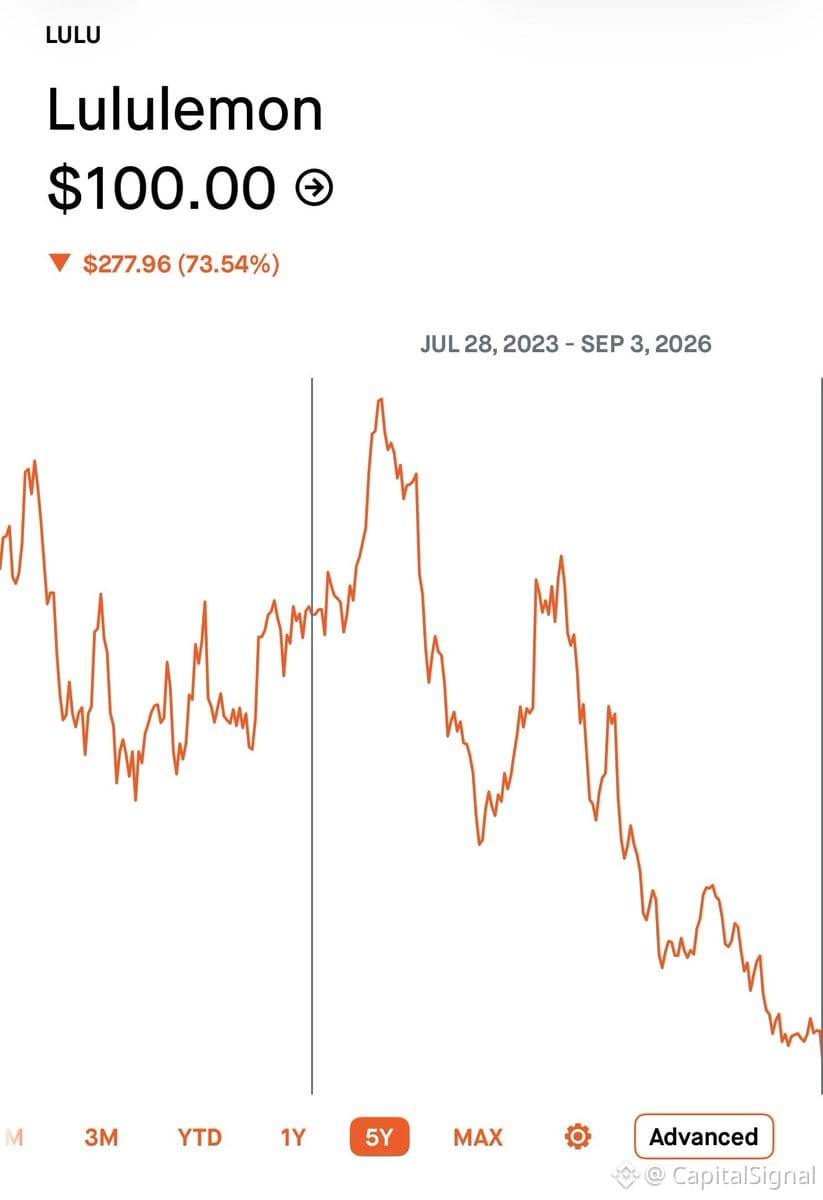
Burry's probably sitting on a ~70% drawdown on his $LULU position.
Meanwhile, the thesis seems to be: retail dumps $PLTR and $NVDA to rotate into... yoga pants?
Look, I respect contrarian plays, but this one's a stretch. $LULU's been getting hammered—brand momentum's weak, competition's fierce, and the athleisure wave isn't what it was in 2020. Burry's known for being early (sometimes *very* early), but being down 70% on a consumer discretionary name while AI infrastructure rips is a tough look.
The idea that money flows out of $PLTR (government AI contracts, enterprise traction) and $NVDA (literal AI picks-and-shovels monopoly) into apparel retail? That's not a rotation—that's a different investment universe.
Contrarian doesn't mean automatic alpha. Sometimes the crowd's right. $LULU needs a real catalyst, not just "it's beaten down." Until then, hard pass.