#termmax @TermMax Ran the actual numbers on a TermMax FT position instead of just reading "fixed-rate lending" and moving on. 🧮 Here's what a real position looks like, step by step.
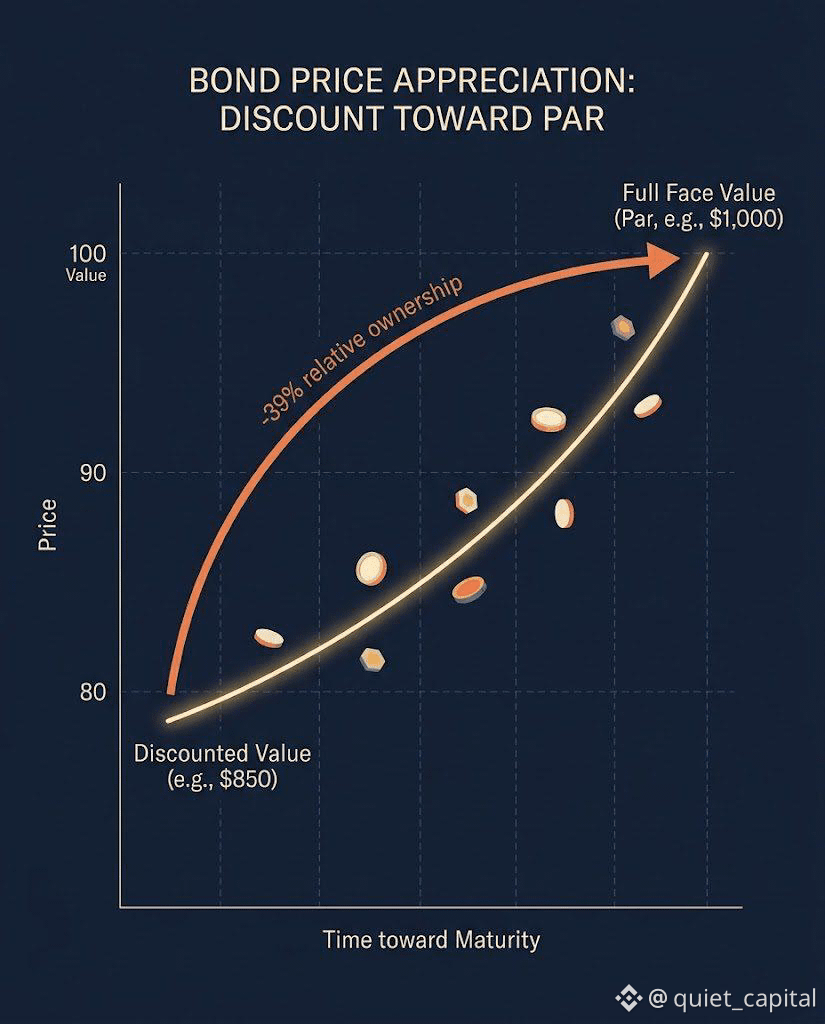
Say you buy 1,000 FT-USDC today for 980 USDC, with 60 days left until maturity. FT is a zero-coupon bond — no periodic interest, just a discount today that closes to full face value at maturity. 📉➡️📈
Your return: (1,000 − 980) / 980 = 2.04% over 60 days. Annualize that with a simple 365/60 multiplier: 2.04% × 6.08 ≈ 12.4% fixed APR. 🔒
That number is locked the moment you buy the FT. Doesn't matter what happens to floating rates on other platforms for the next 60 days — you already know your exact return in USDC terms, down to the cent, before you commit a single dollar. 💵
The part that took me a minute to actually appreciate: FT price isn't static, it's supposed to drift upward toward $1.00 as maturity approaches, purely from time passing — no news, no vote, no rate change required. 🕰️
Would a locked 12.4% for 60 days beat whatever floating rate you're currently getting somewhere else, or does floating still win when rates are trending up? 🤔 And has anyone actually held an FT to maturity and redeemed it — did it land exactly at face value like the mechanism promises?
@TermMax #TermMax
Say you buy 1,000 FT-USDC today for 980 USDC, with 60 days left until maturity. FT is a zero-coupon bond — no periodic interest, just a discount today that closes to full face value at maturity. 📉➡️📈
Your return: (1,000 − 980) / 980 = 2.04% over 60 days. Annualize that with a simple 365/60 multiplier: 2.04% × 6.08 ≈ 12.4% fixed APR. 🔒
That number is locked the moment you buy the FT. Doesn't matter what happens to floating rates on other platforms for the next 60 days — you already know your exact return in USDC terms, down to the cent, before you commit a single dollar. 💵
The part that took me a minute to actually appreciate: FT price isn't static, it's supposed to drift upward toward $1.00 as maturity approaches, purely from time passing — no news, no vote, no rate change required. 🕰️
Would a locked 12.4% for 60 days beat whatever floating rate you're currently getting somewhere else, or does floating still win when rates are trending up? 🤔 And has anyone actually held an FT to maturity and redeemed it — did it land exactly at face value like the mechanism promises?
@TermMax #TermMax