The setup in one line:
➠ In 2021, $LINK hit $52.70 as a DeFi oracle token. Price feeds for lending protocols, mostly.
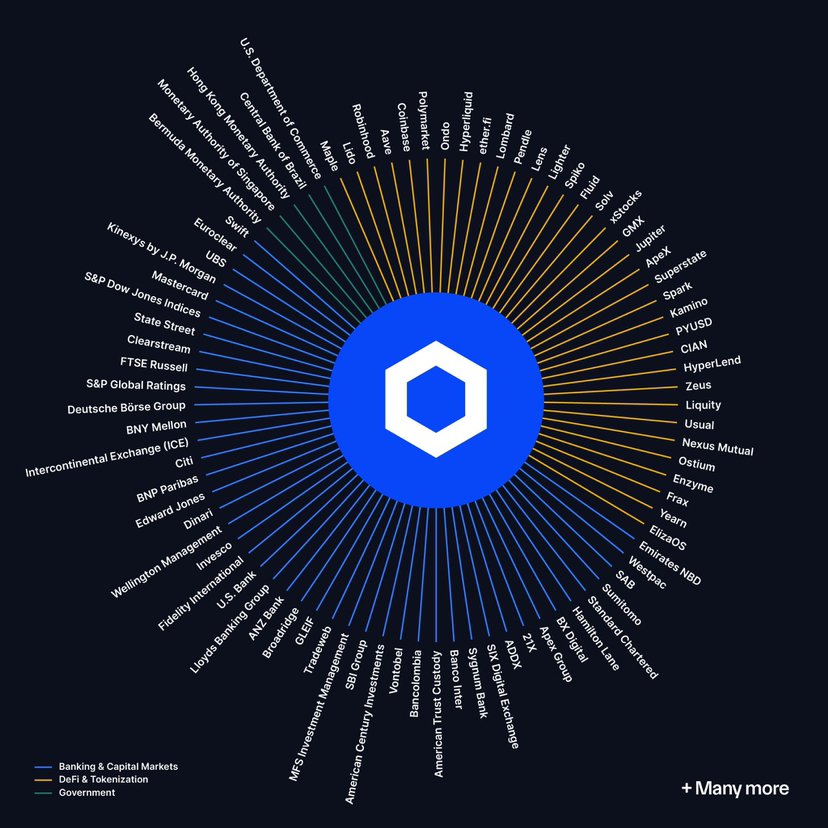
➠ In 2026, it’s the plumbing that Swift, DTCC and 50+ banks are wiring into. It has two spot ETFs and buys its own token with revenue, and it trades around $11.
✦ The gap, with honest math
ATH: $52.70, May 2021.
Today: ~$12, ~$9.2B cap, roughly 77% below the peak.
A new ATH is about a 4.4x from here. Not a prediction, just the distance 🤷♂️
But here’s the part most “LINK to $100” posts skip: circulating supply has grown a lot since 2021.
At today’s ~767M circulating, $52.70 means a market cap of roughly $40B.
That’s the real bar. It’s not impossible for a top infrastructure asset in a full bull run, but it needs real demand, not vibes.
✦ Supply, the honest version
Max supply is 1B LINK, ~767M circulating, so about 77% is out.
This was not a fair launch. A big chunk went to the team and to the node operator and ecosystem allocation, and the remaining ~233M sits in non-circulating wallets that get released over time. That overhang is real, and the market watches those wallets.
The offset arrived in August 2025: the Chainlink Reserve. Revenue, both on-chain fees and off-chain enterprise payments, gets converted into LINK and parked in a reserve with no withdrawals planned for years.
Early October 2026: ~6.12M LINK in the reserve, average cost around $11.21. Small against total supply, and I won’t pretend otherwise. But for the first time, enterprise revenue has a direct, on-chain path into buying the token. The size can grow. The mechanism is what matters.
Add staking and two ETFs pulling float off exchanges, and LINK has demand sinks it never had in 2021.
✦ The 2021 LINK and the 2026 LINK are different products
2021: price feeds for Aave and friends.
2026:
CCIP for cross-chain messaging and token transfers, with CCIP 2.0 launched at Sibos this month
CRE (Runtime Environment), the orchestration layer banks use to run workflows across chains
Proof of Reserve, NAV data and compliance tooling for tokenized funds
SVR, which recaptures oracle MEV for protocols
The oracle is now one product in a full stack.
✦ TradFi is not “exploring” anymore
This is the section that actually answers the hook.
➠ July 2026: Swift activated a blockchain ledger with 17 banks including HSBC, Citi and UBS for 24/7 tokenized deposit payments, with CCIP handling interoperability. At Sibos, Chainlink announced banks can connect to that ledger through CRE while keeping control of their own keys.
➠ DTCC is building its Collateral AppChain on CRE and Chainlink’s data standard, with go-live targeted for Q4 2026. That’s this quarter.
➠ Project Pangea: 50+ banks, $10T+ in AUM, targeting T+0 cross-border settlement through Chainlink and existing Swift rails.
➠ SIX Group and Chainlink: tokenizing €2T+ in European equities.
➠ ETFs: Grayscale’s GLNK launched December 2025, Bitwise’s CLNK in January 2026. Grayscale’s fund absorbed ~629K LINK in September alone, and Bitwise filed to stake 20% of its holdings.
✦ The usage numbers
$110B+ in total value secured. Somewhere between 60% and 68% of the oracle market by TVS for two years running. $30T+ in cumulative transaction value enabled.
On Ethereum, Chainlink secures roughly 83% of all oracle-dependent value.
✦ So, new ATH?
A full $52.70 needs a ~$40B LINK. That’s a real ask, a real real ask tbh.
But in 2021, LINK priced in a story. In 2026, that story is running in production at Swift and DTCC, and the price is 77% below where the story alone once took it.
So, does the network the world’s biggest banks are plugging into stay a $9B asset through the entire next bull run?