

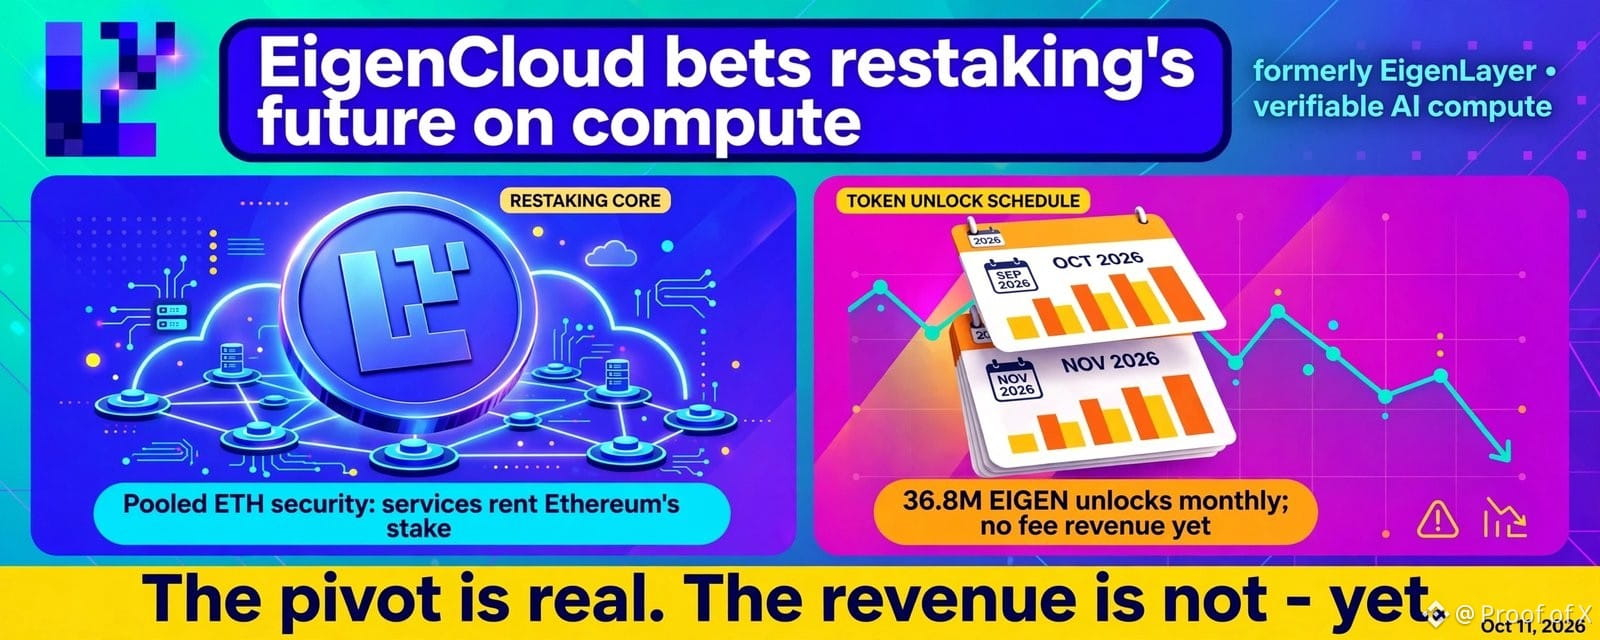
Restaking's biggest name is betting its future on compute, not collateral.
BUSINESS
EigenLayer, now rebranded as EigenCloud, invented restaking: ETH stakers extend their staked collateral to secure third-party services called Actively Validated Services and earn additional yield.
The business is now shifting from restaking to a verifiable cloud stack covering compute, data availability, and AI services, with cited integrations for Google's A2A payment protocol and Coinbase AgentKit.
The central business question is whether verifiable-compute demand turns into fee revenue, which has not been demonstrated yet.
TECHNOLOGY
The core primitive is pooled cryptoeconomic security: instead of each new service bootstrapping its own validator set, it rents security from Ethereum's existing stake.
The architecture runs restaking contracts on Ethereum with an operator and AVS registry, and EigenCloud is layering compute and data-availability services on top.
A governance proposal called ELIP-12 would route all EigenCloud fees into an $EIGEN buyback contract, but no such contract exists yet and no fee revenue currently flows to the token.
SECTOR
Restaking is cooling: yields have dried up, leading liquid-restaking protocols reported steep profit declines in 2026, and ether.fi is ending its EigenLayer integration.
EigenCloud's TVL of roughly $6.37B was overtaken by Hyperliquid Bridge's $6.53B in early September 2026.
The narrative is moving from restake everything to application-specific infrastructure and AI compute, which is the exact lane the EigenCloud rebrand is chasing.
COMPETITION
In classic restaking, EigenCloud competes with Symbiotic, Karak, and Jito Network's restaking ecosystem, the lane ether.fi just exited.
$JTO captures Solana-side staking and MEV flow, while $ETHFI represents the capital leaving restaking for safer yield.
EigenCloud still holds a dominant share of classic restaking, but that market is shrinking.
TOKENOMICS
CoinGecko reports $EIGEN market cap $234.1M against a fully diluted valuation of $446.3M, meaning the token trades near half its fully diluted value.
Circulating supply is about 971.4M of 1.85B total, so roughly 52% of supply is unlocked, and there is no hard max supply.
The unlock schedule is concrete and verified: about 36.8M EIGEN unlock for investors and early contributors on the first of each month through around October 2027, with the next tranche due November 1, 2026, worth about $9.6M at recent prices.
Until ELIP-12 or another fee mechanism is implemented, the token carries two sources of new supply and no demonstrated demand sink.
Not financial advice. DYOR.