

Binance Square News Update
What Is the CLARITY Act and How Does It Impact Payment Stablecoins?
Regulators around the globe, particularly in the United States, are establishing comprehensive frameworks to govern digital assets and dollar-backed payment instruments. As stablecoins evolve from niche trading collateral into widespread payment solutions, federal agencies are tightening oversight to ensure liquidity, systemic stability, and consumer protection.
Central to this effort are regulatory initiatives like the proposed CLARITY Act and recent supervisory framework updates introduced by the Federal Reserve.
Other key financial regulatory bodies, including the Federal Deposit Insurance Corporation (FDIC) and the Office of the Comptroller of the Currency (OCC), had already proposed their own stablecoin implementation rules.
Because the Federal Reserve is described as the last major agency to lay down such rules, its proposal helps complete the US supervisory picture under the GENIUS Act.
The Fed also plays a central role in the US financial system as the country’s central bank. Its involvement signals that regulators view large payment-focused stablecoins as a meaningful, systemic part of the modern payment landscape.
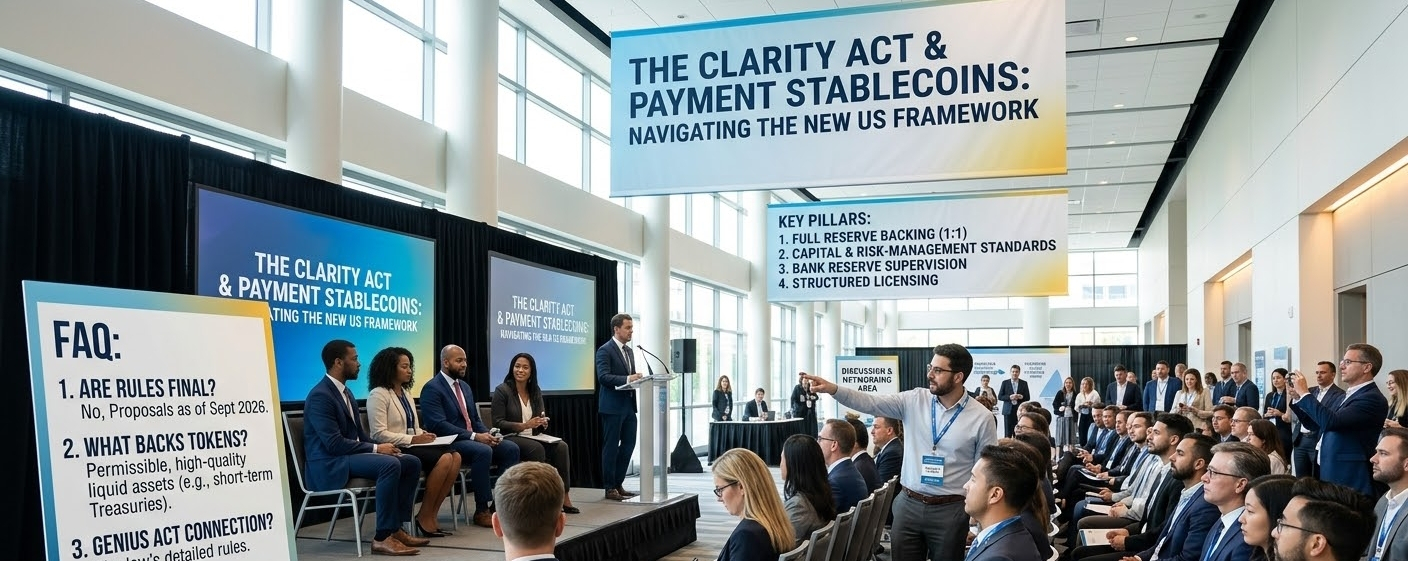
Core Pillars of the New Stablecoin Framework:
Full Reserve Backing: Issuers are required to back circulating tokens 1:1 with highly liquid, low-risk assets to guarantee instant redeemability.
Capital & Risk-Management Standards: Institutions must maintain robust buffer capital and operational risk frameworks to withstand market volatility.
Strict Bank Reserve Management: Financial institutions holding cash or short-term assets for stablecoin issuers are subject to direct supervision and auditing.
Structured Licensing Path: Qualified banks and licensed subsidiaries have a clear administrative process to apply for issuing digital payment assets.
FAQ
Are the Fed’s stablecoin rules final?
No. As of September 2026, they are proposals. The Fed will accept comments for 60 days after the proposals are published in the Federal Register, and details may change before any rules are finalized.
What must back a payment stablecoin under the proposal?
Supervised issuers would need to fully back tokens with permissible, high-quality liquid reserve assets, such as short-term Treasury bills, so holders can redeem reliably.
What is the connection to the GENIUS Act?
The GENIUS Act is the US law that sets the framework for payment stablecoins. The Fed’s proposals are the detailed rules meant to carry that law into practice.
Can banks issue stablecoins under these proposals?
The proposals include an application process for state member banks that want to issue stablecoins through subsidiaries, requiring materials like a business plan and financial information, with procedures for appeals and hearings.
Closing Thoughts
The Fed’s September 2026 proposals mark an important step in shaping how payment stablecoins are supervised in the United States. The confirmed pillars center on full reserve backing, capital and risk-management standards, rules for banks that hold reserves, and a clear path for banks that wish to issue stablecoins. Since these are still proposals, the final rules may look somewhat different once the comment period ends and feedback is reviewed.
Further Reading
Why Do Stablecoins Depeg?
What Is MiCA (Markets in Crypto Assets Regulation)?
What Is the GENIUS Act and Why Does It Matter for Stablecoin Users?
What Is the CLARITY Act and What Does It Mean for Crypto?
Central Bank Digital Currencies (CBDC) Explained