
I’ve been watching the memory cycle closely, and Micron’s latest earnings just made the story much harder to ignore.
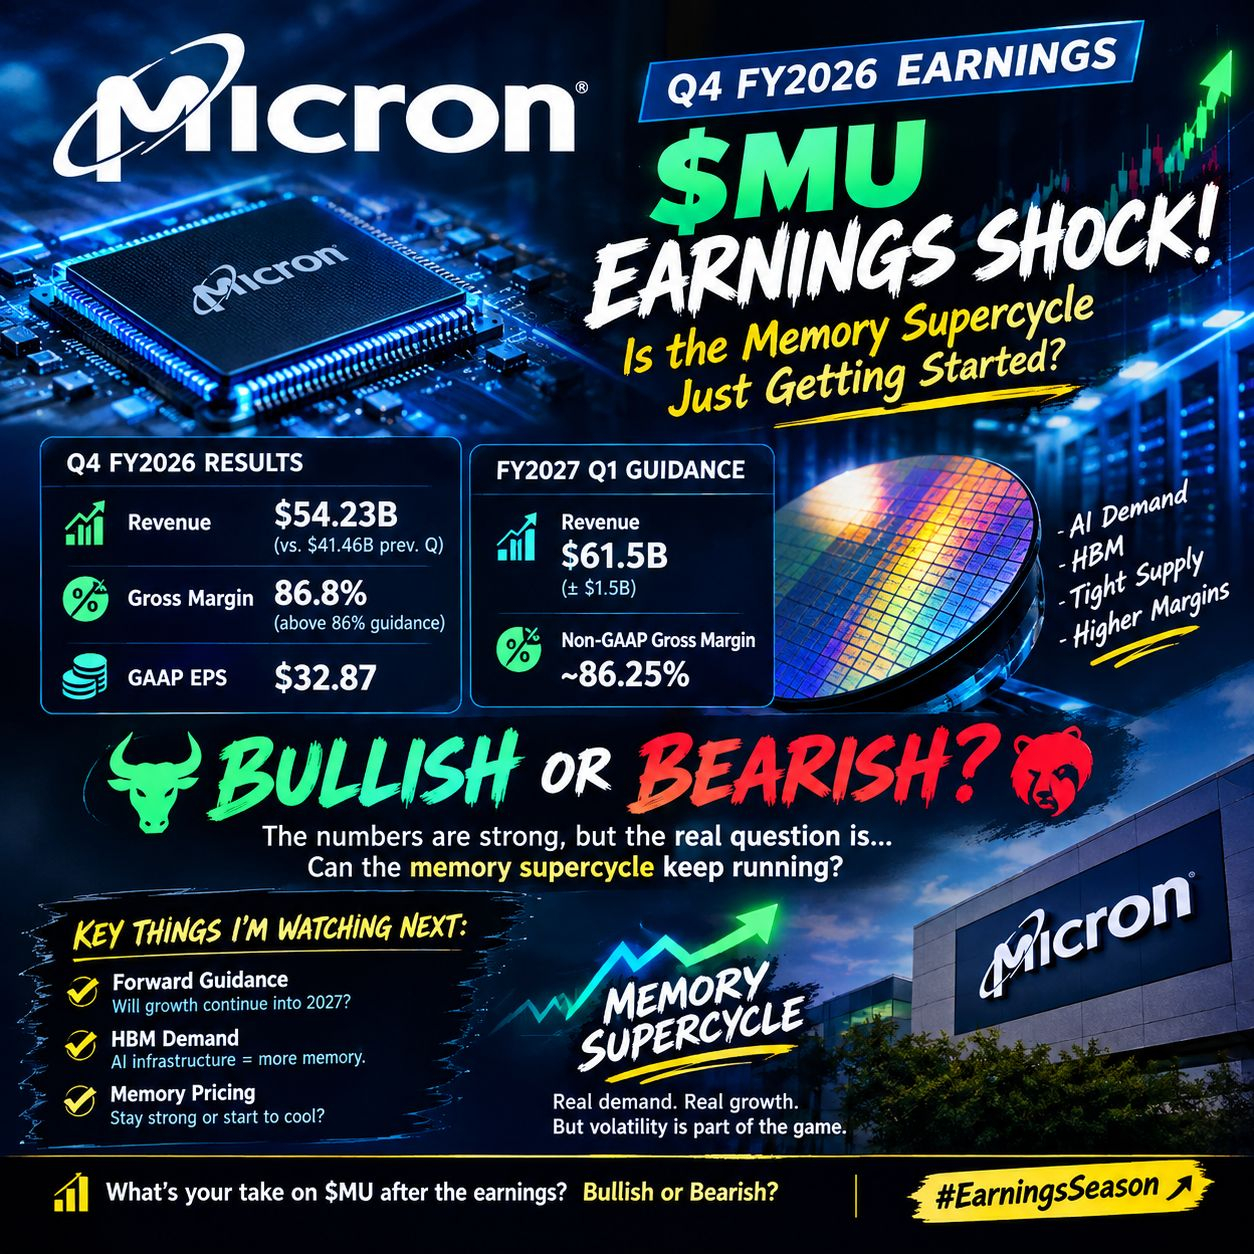
$MU delivered $54.23B in Q4 revenue, crushing its previous-quarter level of $41.46B. More importantly, gross margin reached 86.8%, above the ~86% guidance investors were watching. EPS came in at $32.87 GAAP.
But for me, the biggest signal isn’t the headline number.
It’s what comes next.
Micron is guiding FY2027 Q1 revenue to approximately $61.5B, with non-GAAP gross margin around 86.25%. That tells me the company isn’t treating this as a one-quarter spike.
The real question now is whether AI infrastructure demand can keep memory supply tight enough to sustain these extraordinary margins.
That’s where the memory supercycle gets interesting.
I’m not chasing a green candle blindly. After such powerful earnings, expectations can become just as dangerous as weak fundamentals.
For $MU, I’m watching three things next: forward guidance, HBM demand, and memory pricing.
If those remain strong, the earnings story may be far from finished.
Bullish fundamentals — but volatility is still part of the game.