

cryptotradehead
8.8k Publicaciones
cryptotradehead
Denunciar
Bloquear usuario
backtesting, analyse, how to use AI for trading - can you be a good trader?
Abrir trade
Traders de alta frecuencia
4.8 año(s)
7 Siguiendo
2.6K+ Seguidores
5.0K+ Me gusta
Publicaciones
Cartera
Todo
Citas
Artículo
Ver traducción
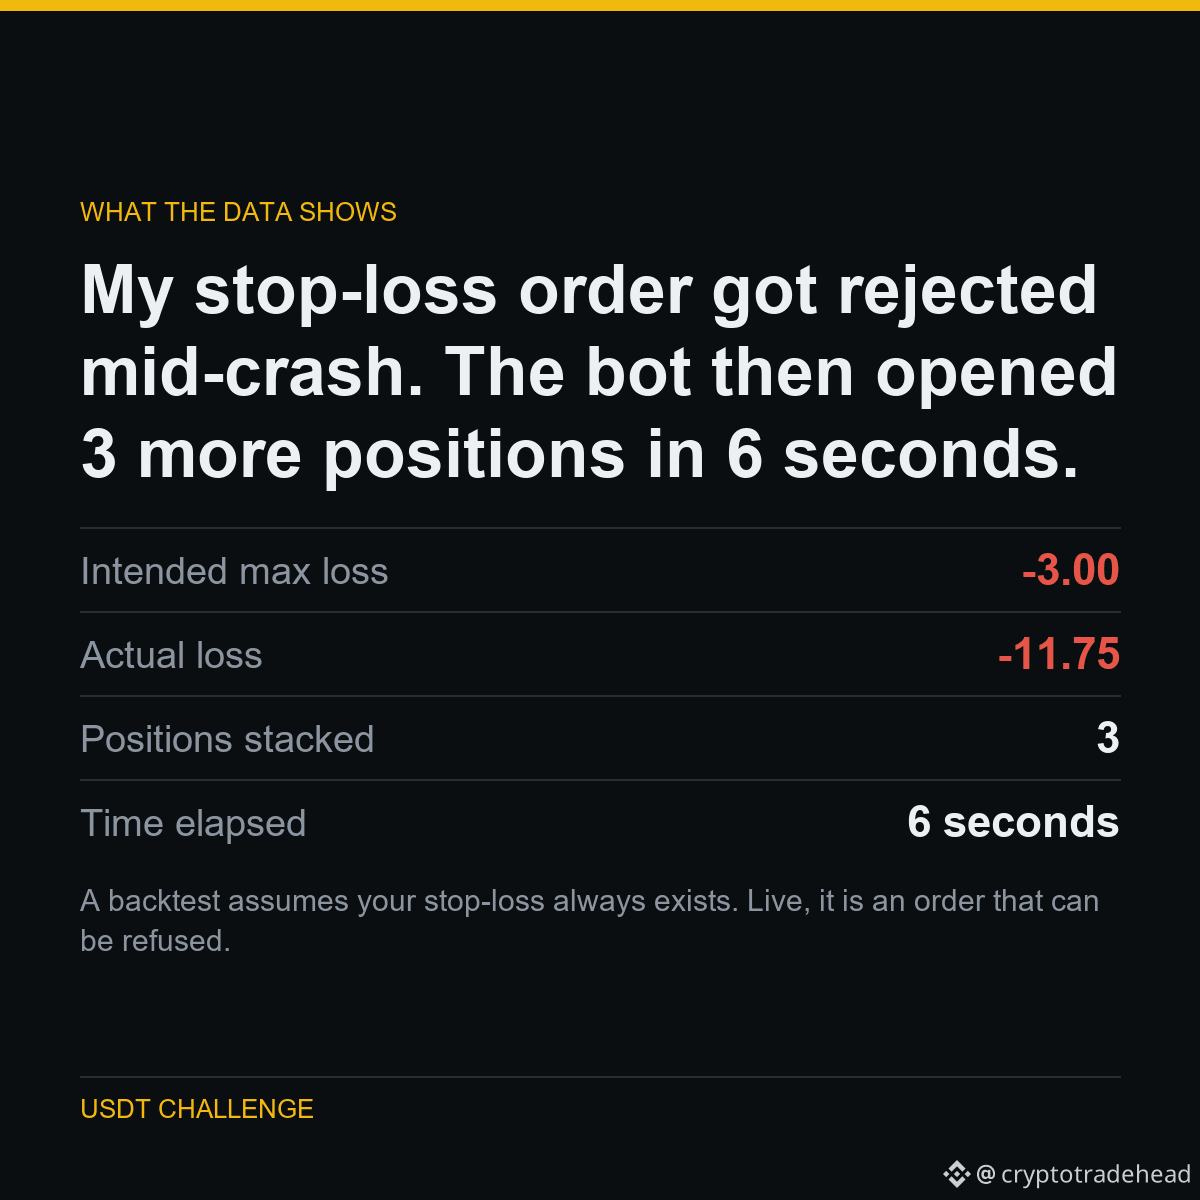
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconMy stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 secon
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
9
Artículo
Ver traducción
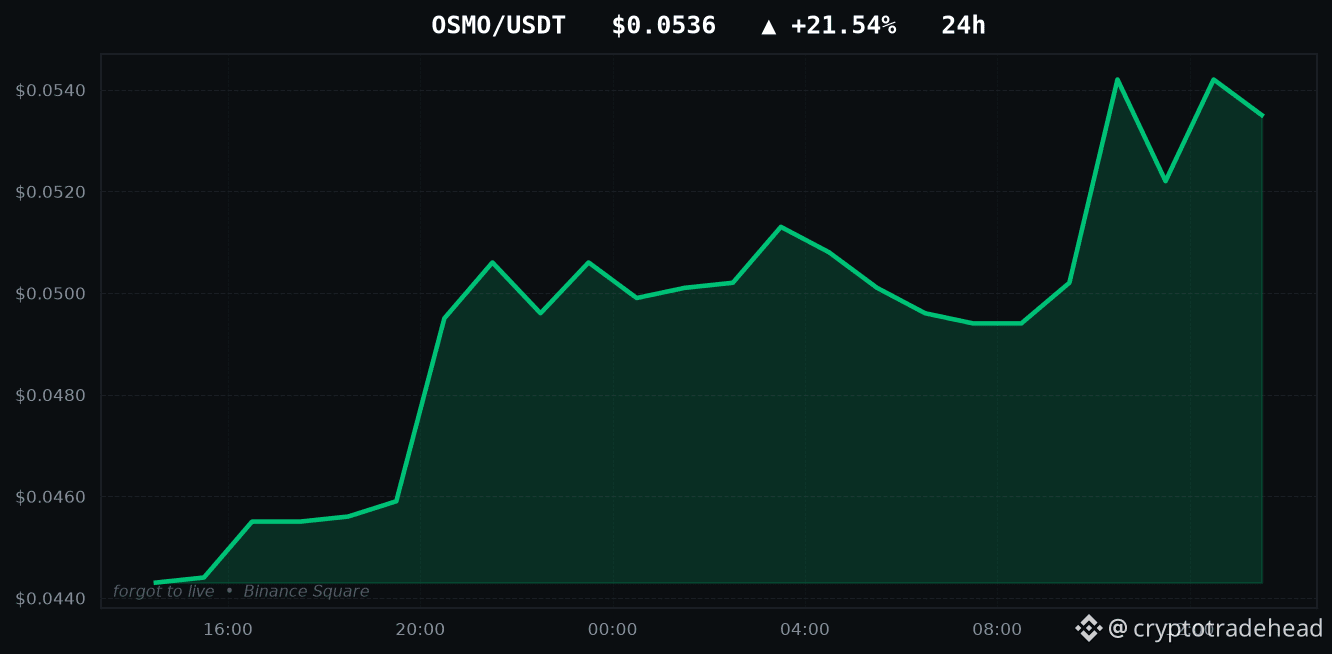
OSMO is up +21.54% - I tested both ways to trade itTODAY'S TOP GAINERS
OSMO: +21.54%
ERA: +17.48%
DODO: +12.41%
WIN: +12.21%
BEAMX: +9.88%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +21.54%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $DODO
#Binance #Altcoins #Futures #OSMO #CryptoData
OSMO is up +21.54% - I tested both ways to trade it
TODAY'S TOP GAINERS
OSMO: +21.54%
ERA: +17.48%
DODO: +12.41%
WIN: +12.21%
BEAMX: +9.88%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +21.54%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $DODO
#Binance #Altcoins #Futures #OSMO #CryptoData
4
Ver traducción
A strategy is not a fact about markets, it is a fact about a period. Anyone showing you a backtest without the year-by-year breakdown is hiding the years that did not work.
Here is what that came from.
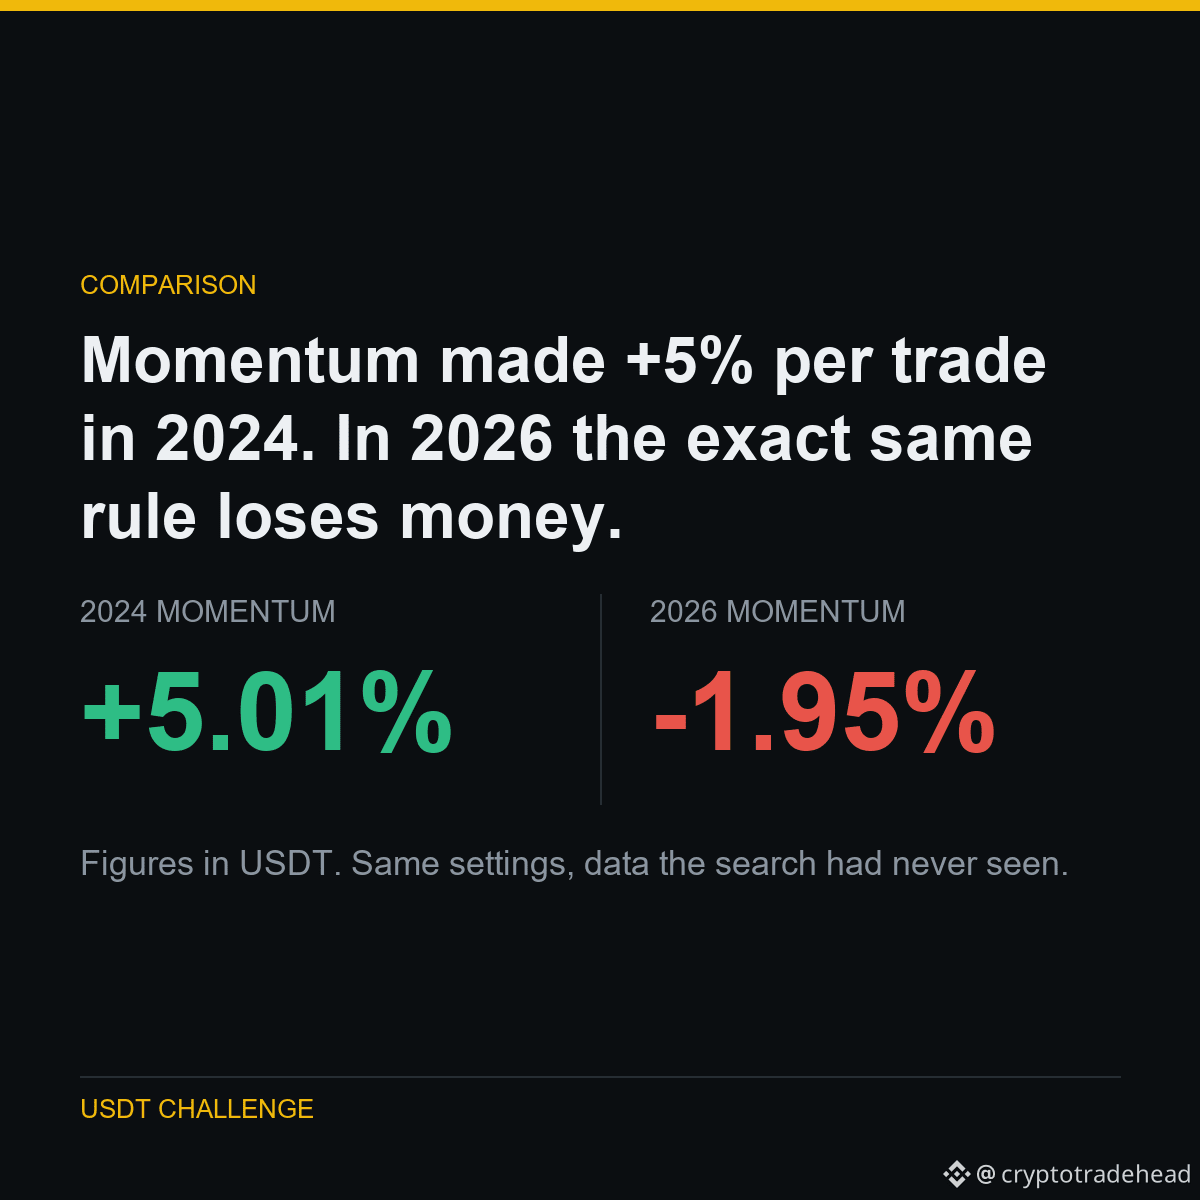
Momentum made +5% per trade in 2024. In 2026 the exact same rule loses money.
Same universe, same ranking rule, same holding period, five different years.
2024 and 2025 carried the whole strategy. 2026 is the worst year of the five - a 25% win rate over roughly nine months.
Buying the strongest coins and shorting the weakest has stopped working this year. Doing the opposite would have returned +1.47% per rebalance at a 69% win rate.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC $ETH
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Artículo
Ver traducción
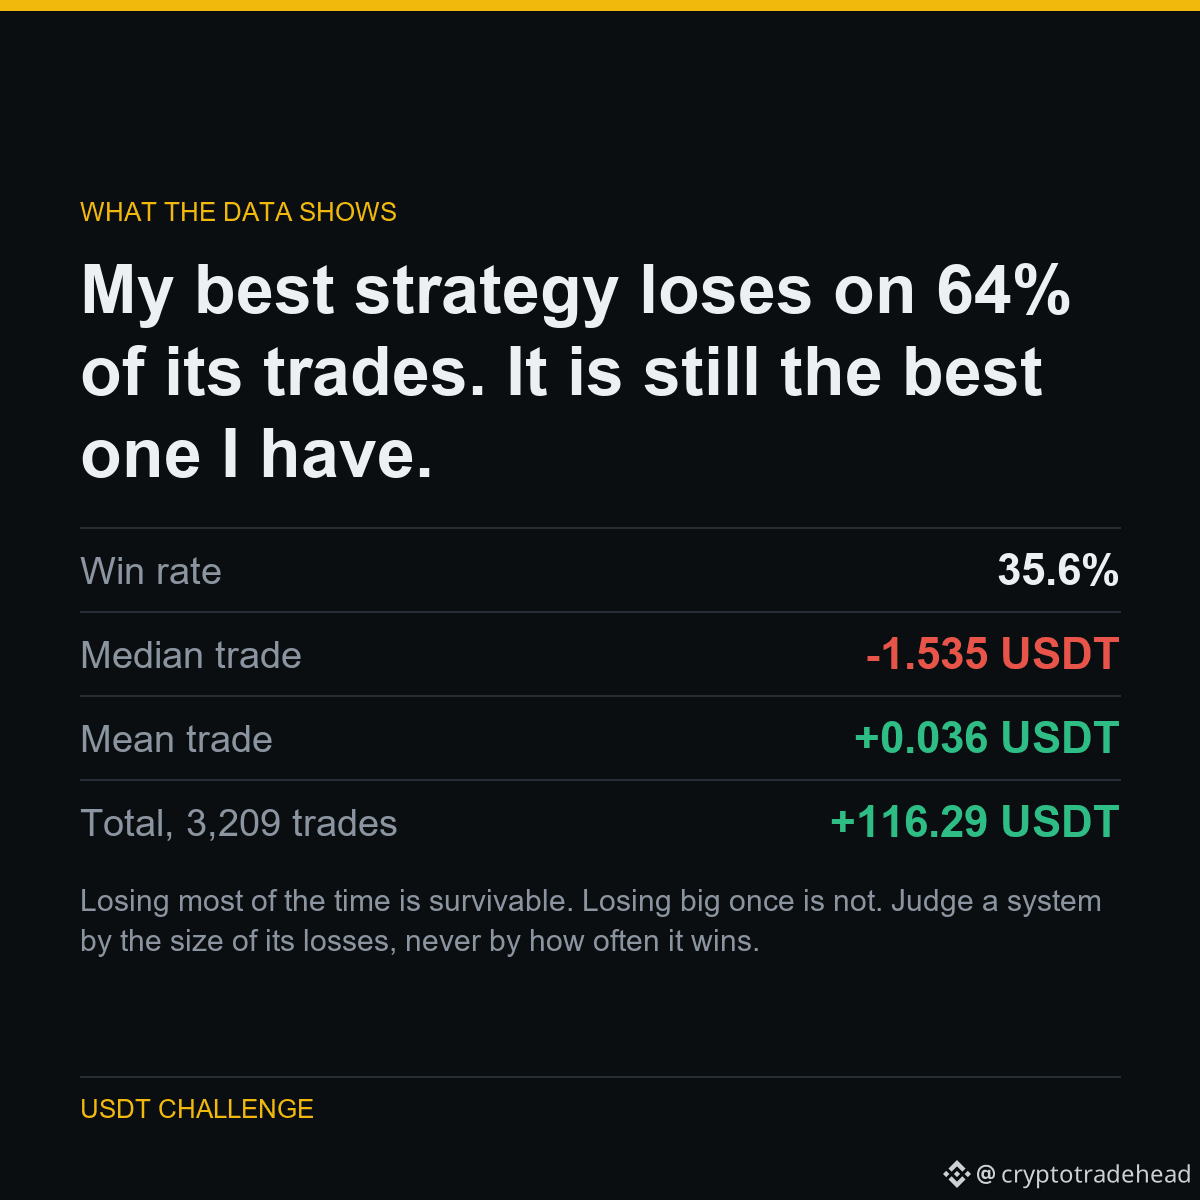
My best strategy loses on 64% of its trades. It is still the best one I have.My best strategy loses on 64% of its trades. It is still the best one I have.
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
My best strategy loses on 64% of its trades. It is still the best one I have.
My best strategy loses on 64% of its trades. It is still the best one I have.
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
8
Artículo
Ver traducción
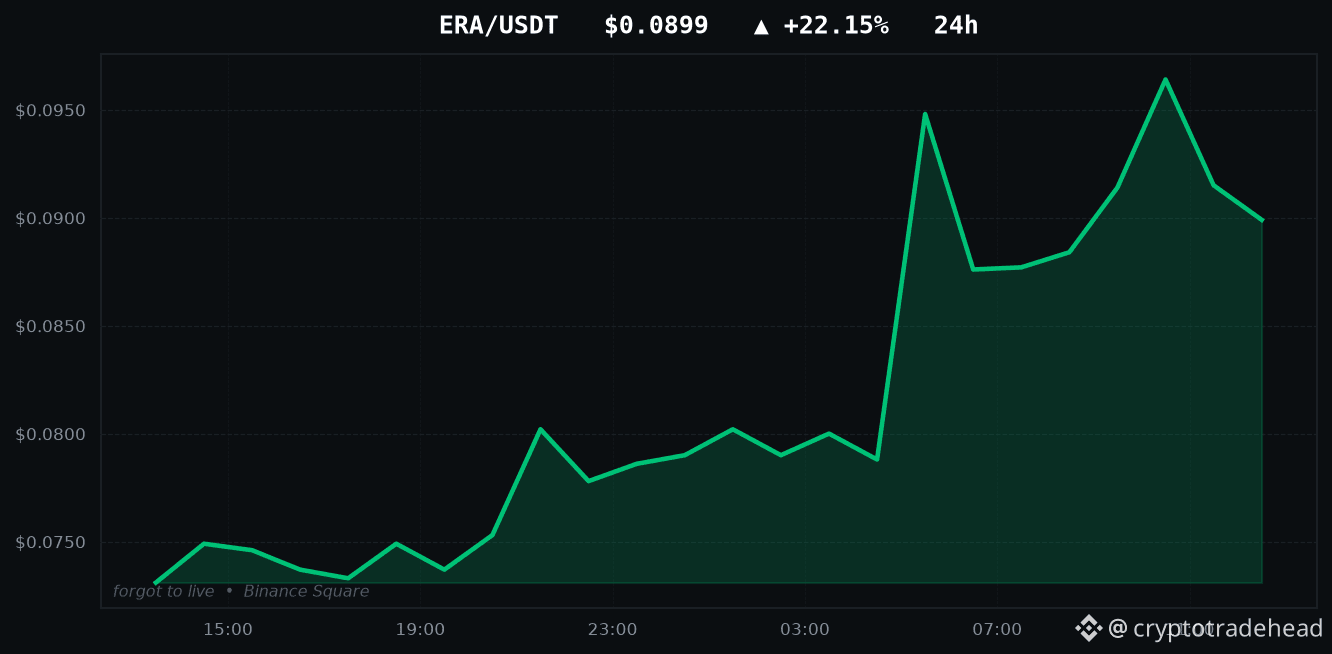
ERA is up +22.15% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +22.15%
OSMO: +18.57%
DODO: +10.44%
MITO: +10.20%
REZ: +9.90%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +22.15%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +22.15% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +22.15%
OSMO: +18.57%
DODO: +10.44%
MITO: +10.20%
REZ: +9.90%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +22.15%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
2
Ver traducción
HOW I TESTED IT
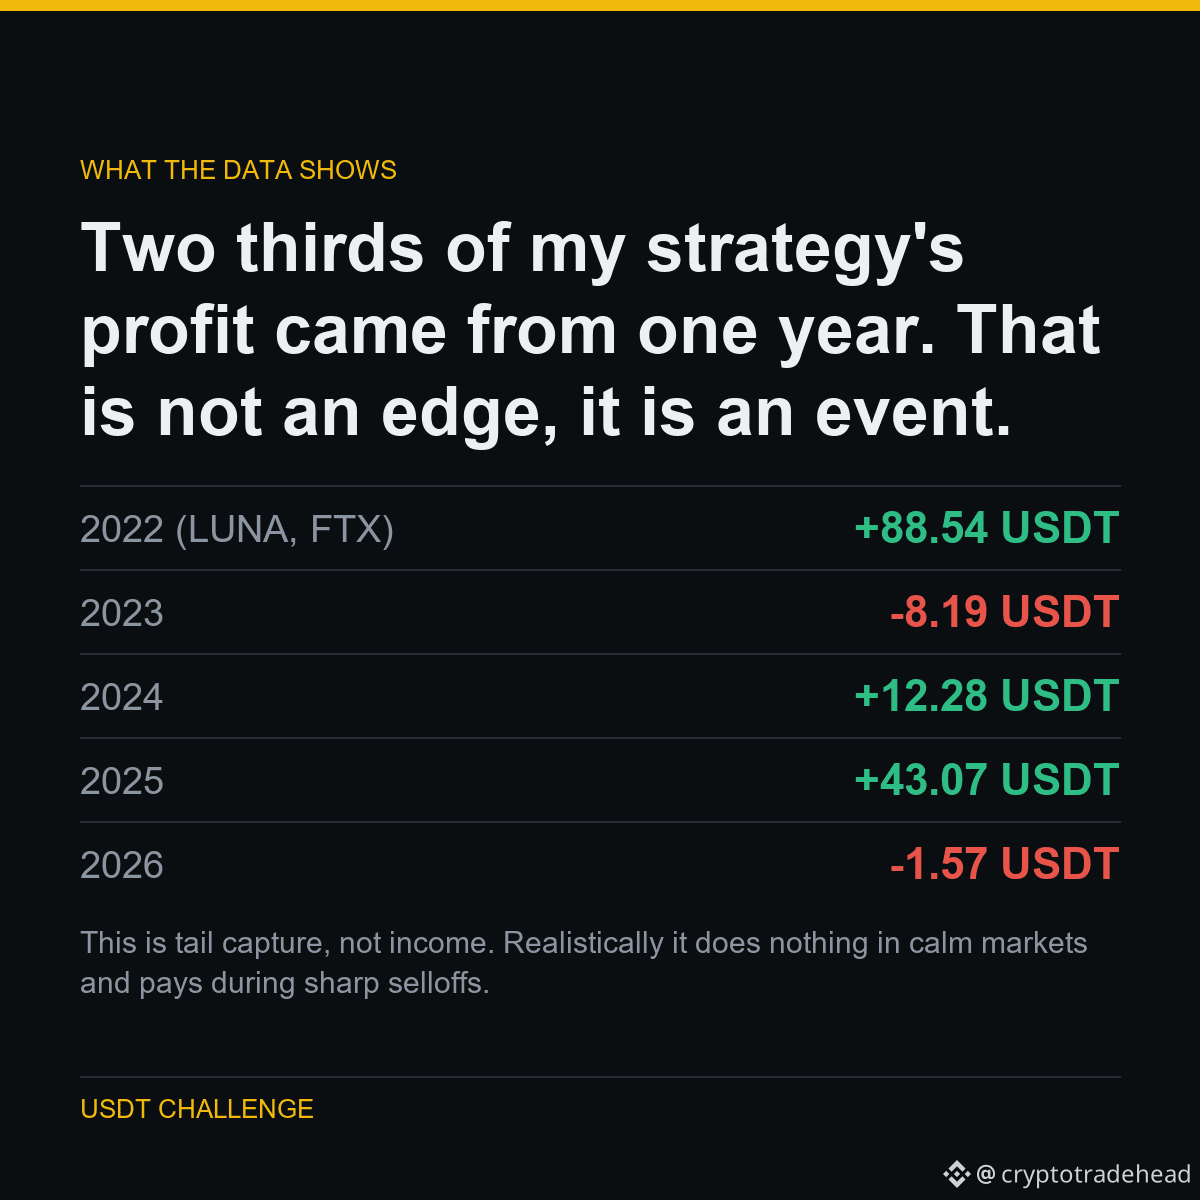
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
THE NUMBERS
2022 (LUNA, FTX): +88.54 USDT
2023: -8.19 USDT
2024: +12.28 USDT
2025: +43.07 USDT
2026: -1.57 USDT
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
2
Ver traducción
Searching hard enough through random data will always produce a winner. The out-of-sample test is the only thing that tells you whether you found an edge or just found noise wearing a costume.
Here is what that came from.
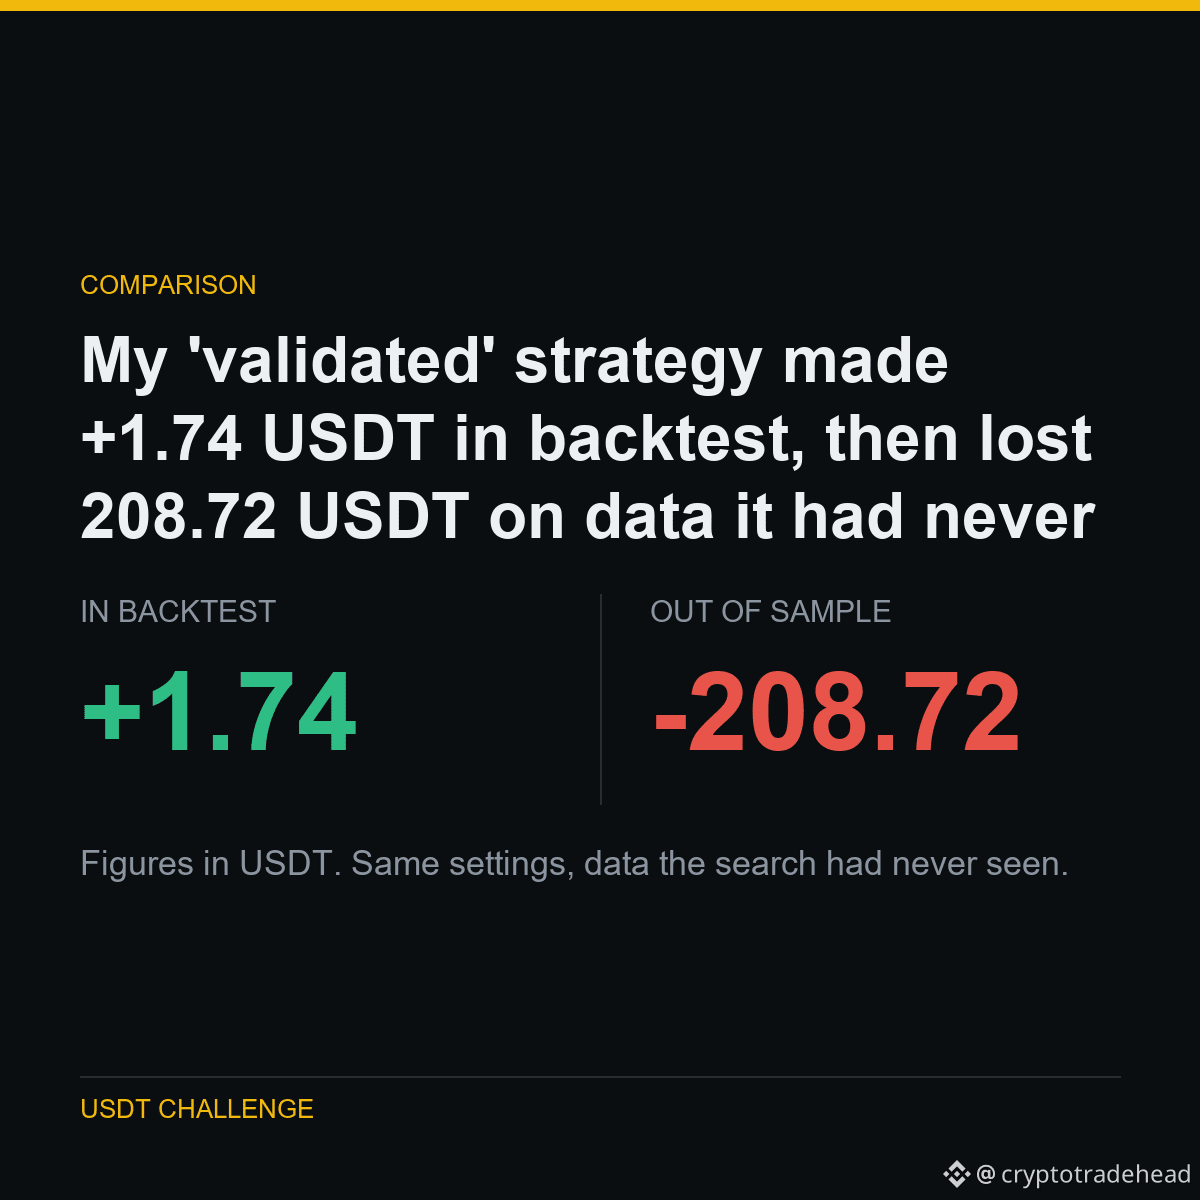
My 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it had never seen.
I swept 40 symbols and found three that looked profitable. I called them validated and put them live.
Then I tested the exact same settings on 751 days of price history the search had never touched. All three reversed. Not marginally - completely.
Three survivors out of 40 is roughly what pure chance produces at that sample size.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Artículo
Ver traducción
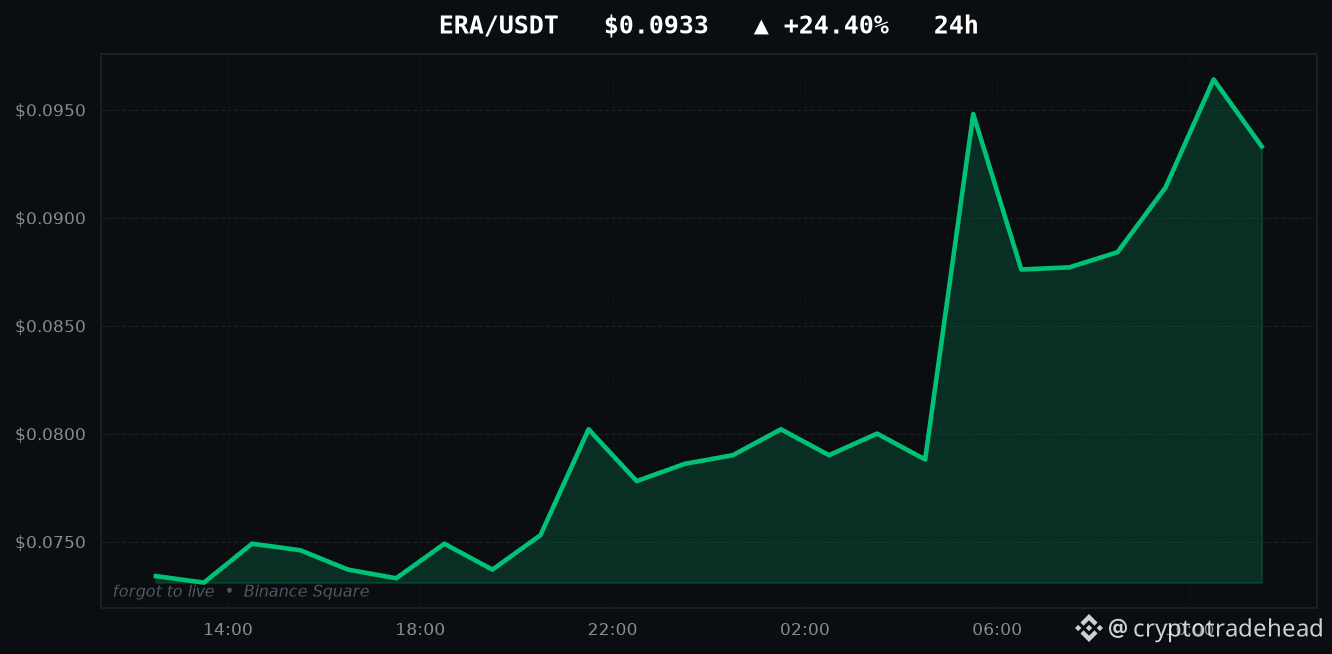
ERA is up +24.40% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +24.40%
OSMO: +16.26%
DODO: +10.69%
REZ: +9.96%
BABY: +9.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +24.40%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +24.40% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +24.40%
OSMO: +16.26%
DODO: +10.69%
REZ: +9.96%
BABY: +9.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +24.40%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
4
Ver traducción
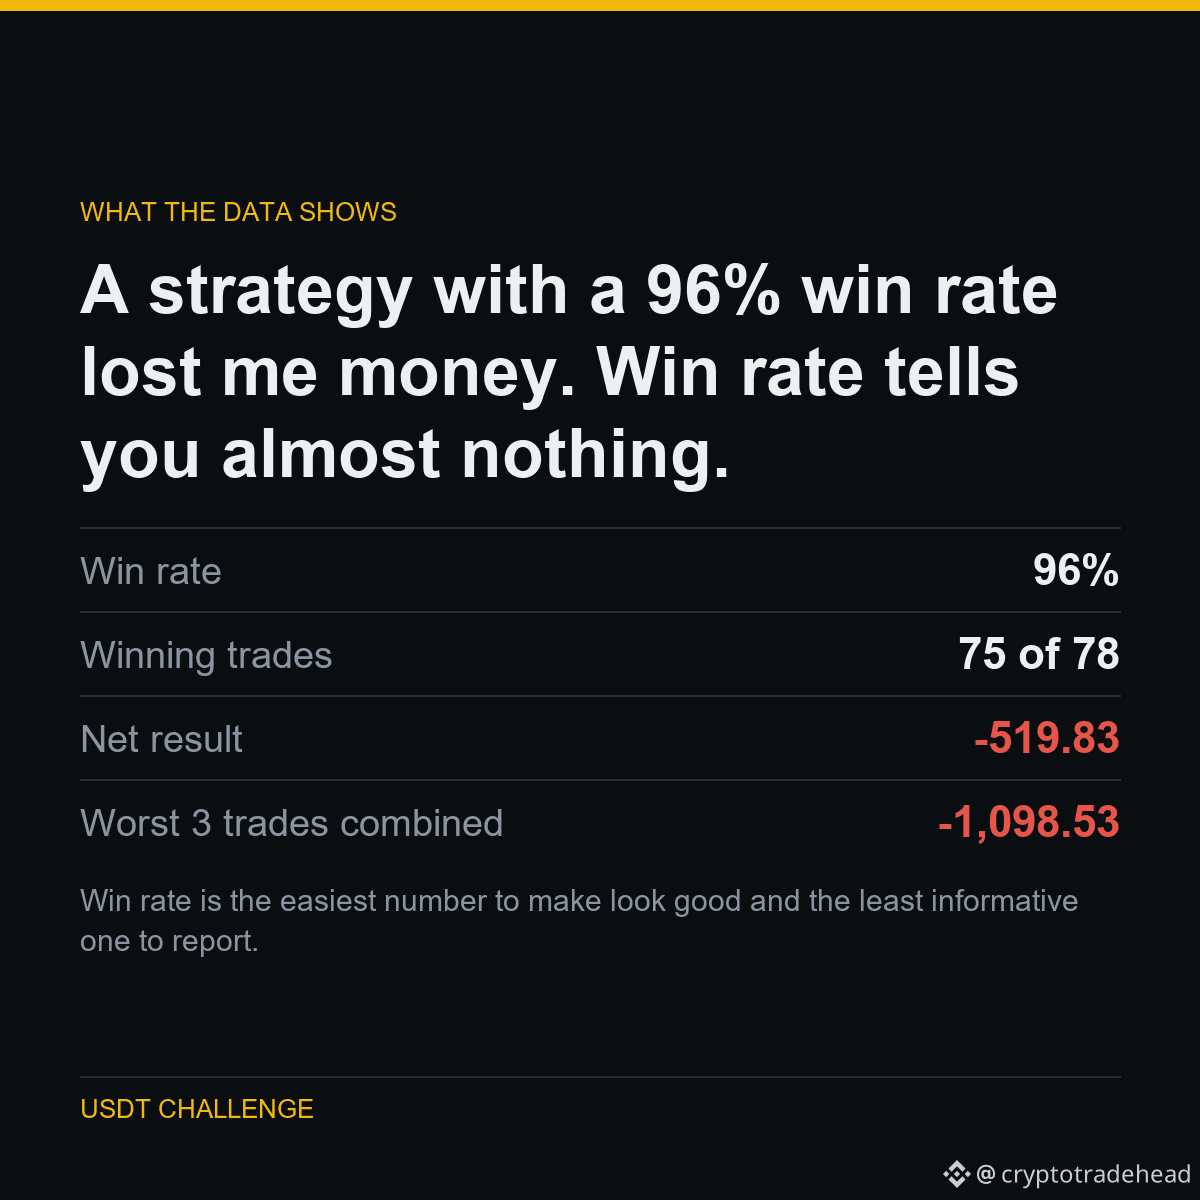
Win rate is the easiest number to make look good and the least informative one to report. Anyone showing you a win rate without the size of the losses is showing you the half of the picture that flatters them.
Here is what that came from.
A strategy with a 96% win rate lost me money. Win rate tells you almost nothing.
I backtested a martingale system - add to losers, close when it recovers. 75 of 78 trades were winners.
It still lost 519.83 USDT, because the three losing trades gave back more than all 75 winners made combined.
Peak margin on those trades reached 4x the entire account.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
6
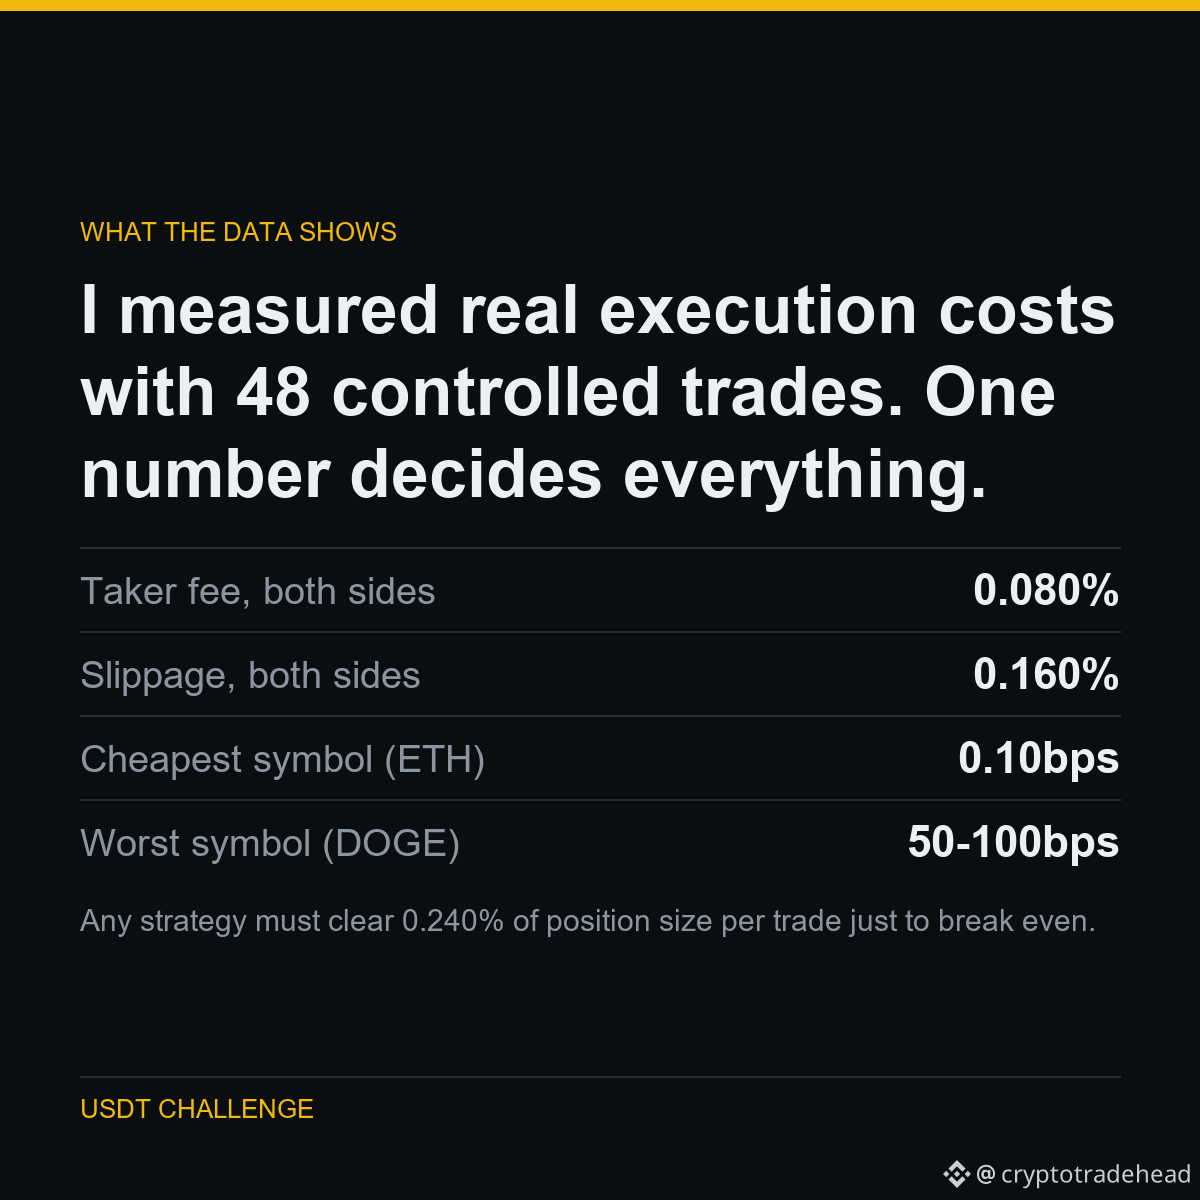
Cualquier estrategia debe cubrir el 0.240% del tamaño de la posición por operación solo para alcanzar el punto de equilibrio. La mayoría de las estrategias publicadas nunca menciona esta cifra, por eso la mayoría pierde dinero.
Esto es lo que descubrí.
Medí los costos reales de ejecución con 48 operaciones controladas. Una cifra lo decide todo.
Dejé de dar por sentado cuánto cuesta operar y lo medí: 48 operaciones completas controladas, entrando y saliendo de inmediato, y registrando el precio real de ejecución frente al precio de referencia.
La comisión se mantuvo constante en 0.04% por lado. El deslizamiento no: ETH se ejecutó prácticamente sin costo, mientras que operar con DOGE costó entre 50 y 100 puntos básicos por operación completa.
Con una posición de 150 USDT, una operación completa cuesta 0.36 USDT antes de que el mercado se mueva siquiera.
Como parte de un experimento público: de 5,063 USDT a 1,000,000 USDT; publico todos los resultados, incluso los que me dejan mal.
Ejecutado con $ETH $DOGE
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Artículo
Ver traducción
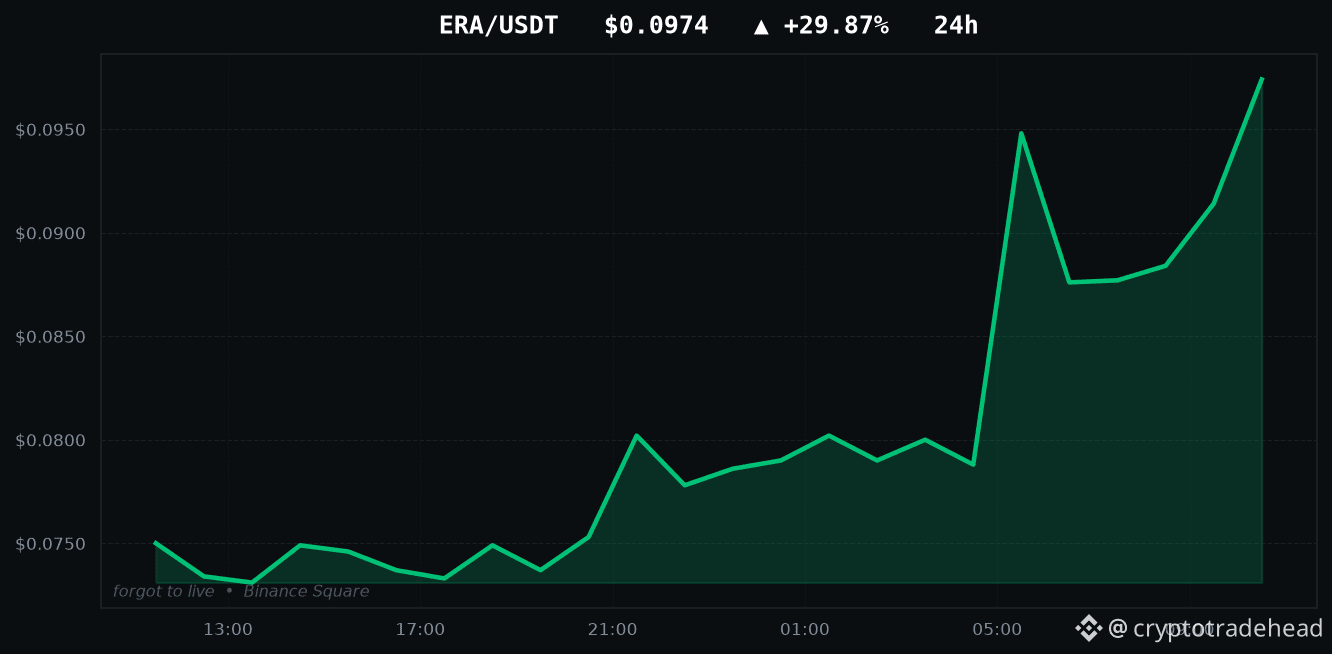
ERA is up +29.87% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +29.87%
OSMO: +12.12%
DODO: +11.73%
BREV: +10.90%
BMT: +10.09%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +29.87%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +29.87% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +29.87%
OSMO: +12.12%
DODO: +11.73%
BREV: +10.90%
BMT: +10.09%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +29.87%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
6
Artículo
Ver traducción
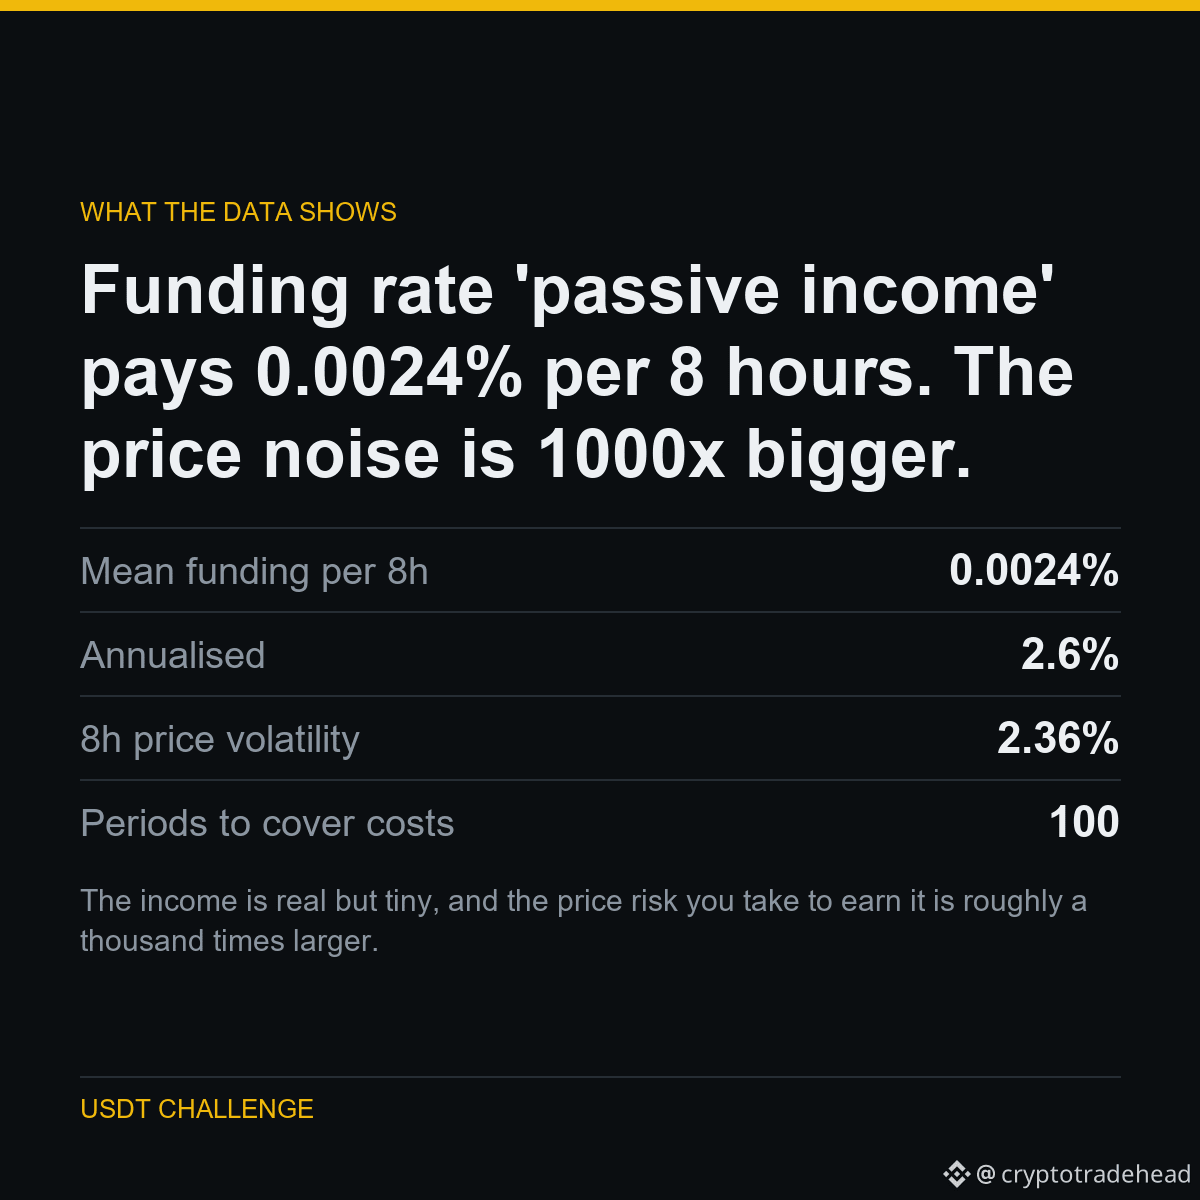
Funding rate 'passive income' pays 0.0024% per 8 hours. The price noise is 1000x bigger.Funding rate 'passive income' pays 0.0024% per 8 hours. The price noise is 1000x bigger.
Collecting funding on perpetuals is sold as passive yield. I pulled 34,431 funding events across 7 symbols and measured it.
Average funding is 0.0024% per 8-hour period. On a 150 USDT position that is 0.0036 USDT. A round trip costs 0.36 USDT - you would hold for 33 days just to cover entry and exit.
Meanwhile the price moves 2.36% in a typical 8 hours.
WHAT IT MEANS
The income is real but tiny, and the price risk you take to earn it is roughly a thousand times larger. This is why desks that trade it hedge with spot. Unhedged, it is not income - it is a directional bet with a rebate.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $SOL
#Binance #Futures #Backtesting #TradingBot #CryptoData
Funding rate 'passive income' pays 0.0024% per 8 hours. The price noise is 1000x bigger.
Funding rate 'passive income' pays 0.0024% per 8 hours. The price noise is 1000x bigger.
Collecting funding on perpetuals is sold as passive yield. I pulled 34,431 funding events across 7 symbols and measured it.
Average funding is 0.0024% per 8-hour period. On a 150 USDT position that is 0.0036 USDT. A round trip costs 0.36 USDT - you would hold for 33 days just to cover entry and exit.
Meanwhile the price moves 2.36% in a typical 8 hours.
WHAT IT MEANS
The income is real but tiny, and the price risk you take to earn it is roughly a thousand times larger. This is why desks that trade it hedge with spot. Unhedged, it is not income - it is a directional bet with a rebate.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $SOL
#Binance #Futures #Backtesting #TradingBot #CryptoData
7
Ver traducción
Adaptive rules feel like the answer to regime change. They are usually just a slower version of the same bet, with the losses already paid for the signal.
Here is what that came from.
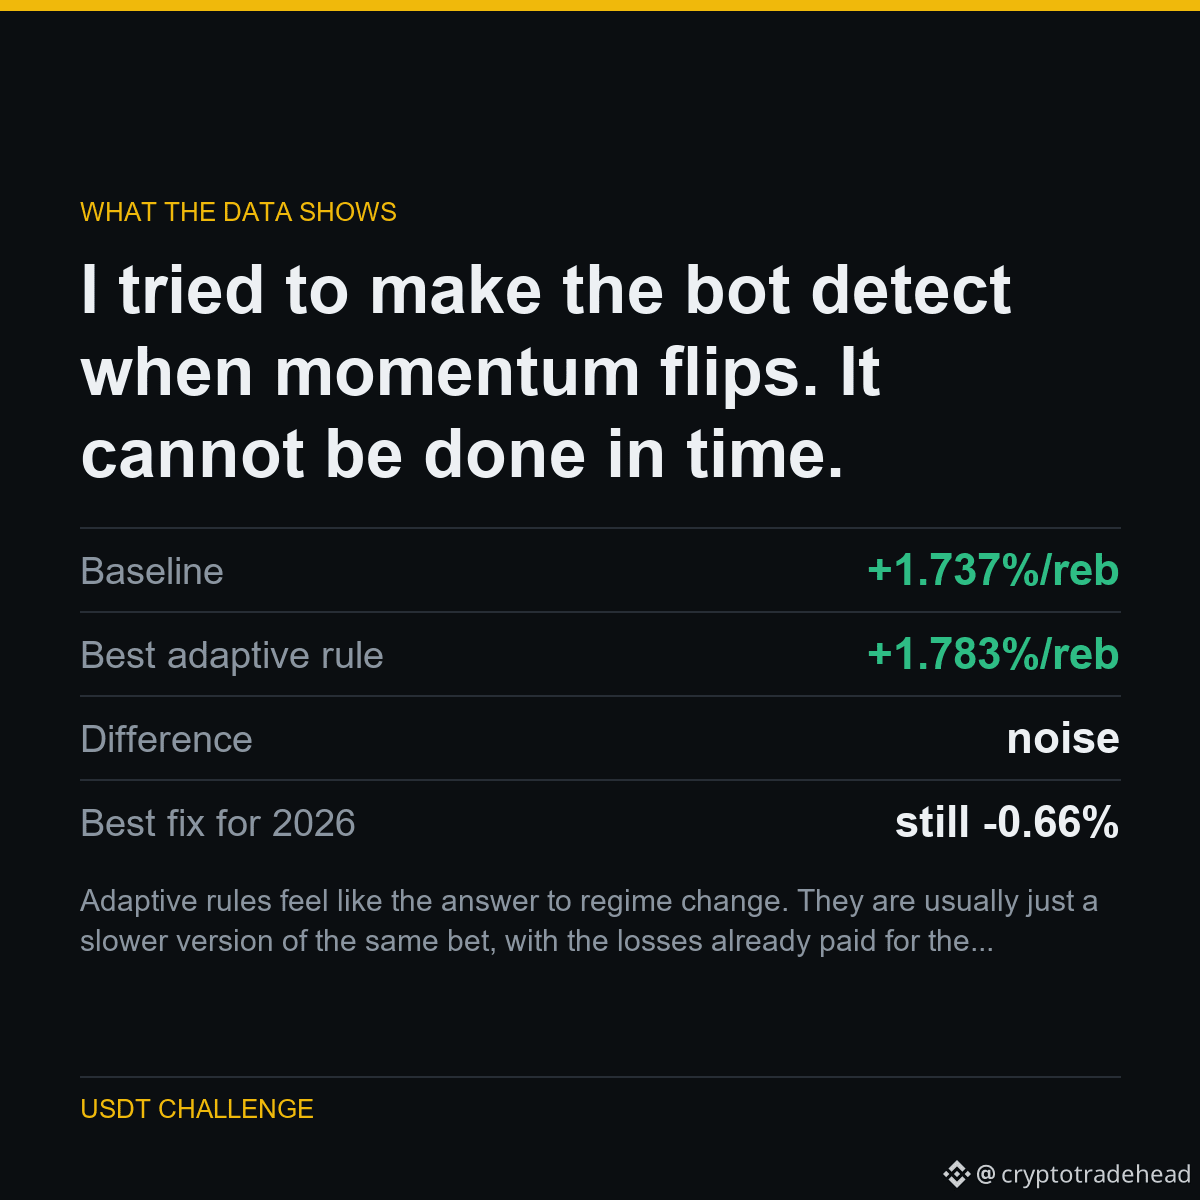
I tried to make the bot detect when momentum flips. It cannot be done in time.
Momentum inverted in 2026. The obvious fix: watch recent performance, and flip to the opposite rule when momentum stops paying.
I tested that over six different lookback windows. The best one returned +1.783% per rebalance against a +1.737% baseline - a difference indistinguishable from noise. Every other window was worse. None repaired 2026.
The reason is simple: by the time trailing performance tells you the regime flipped, you have already taken the losses that told you.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
Artículo
Ver traducción
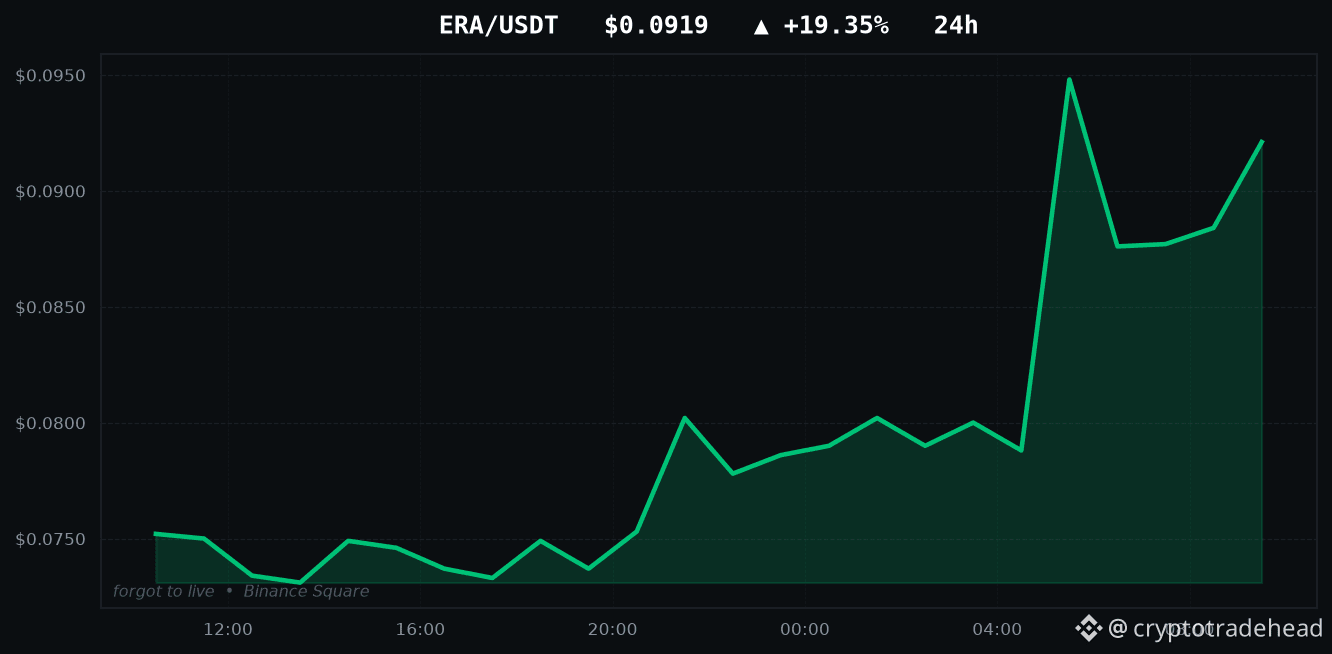
ERA is up +19.35% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +19.35%
DODO: +12.05%
REZ: +10.80%
OSMO: +9.65%
BABY: +7.53%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +19.35%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $DODO $REZ
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +19.35% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +19.35%
DODO: +12.05%
REZ: +10.80%
OSMO: +9.65%
BABY: +7.53%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +19.35%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $DODO $REZ
#Binance #Altcoins #Futures #ERA #CryptoData
4
Ver traducción
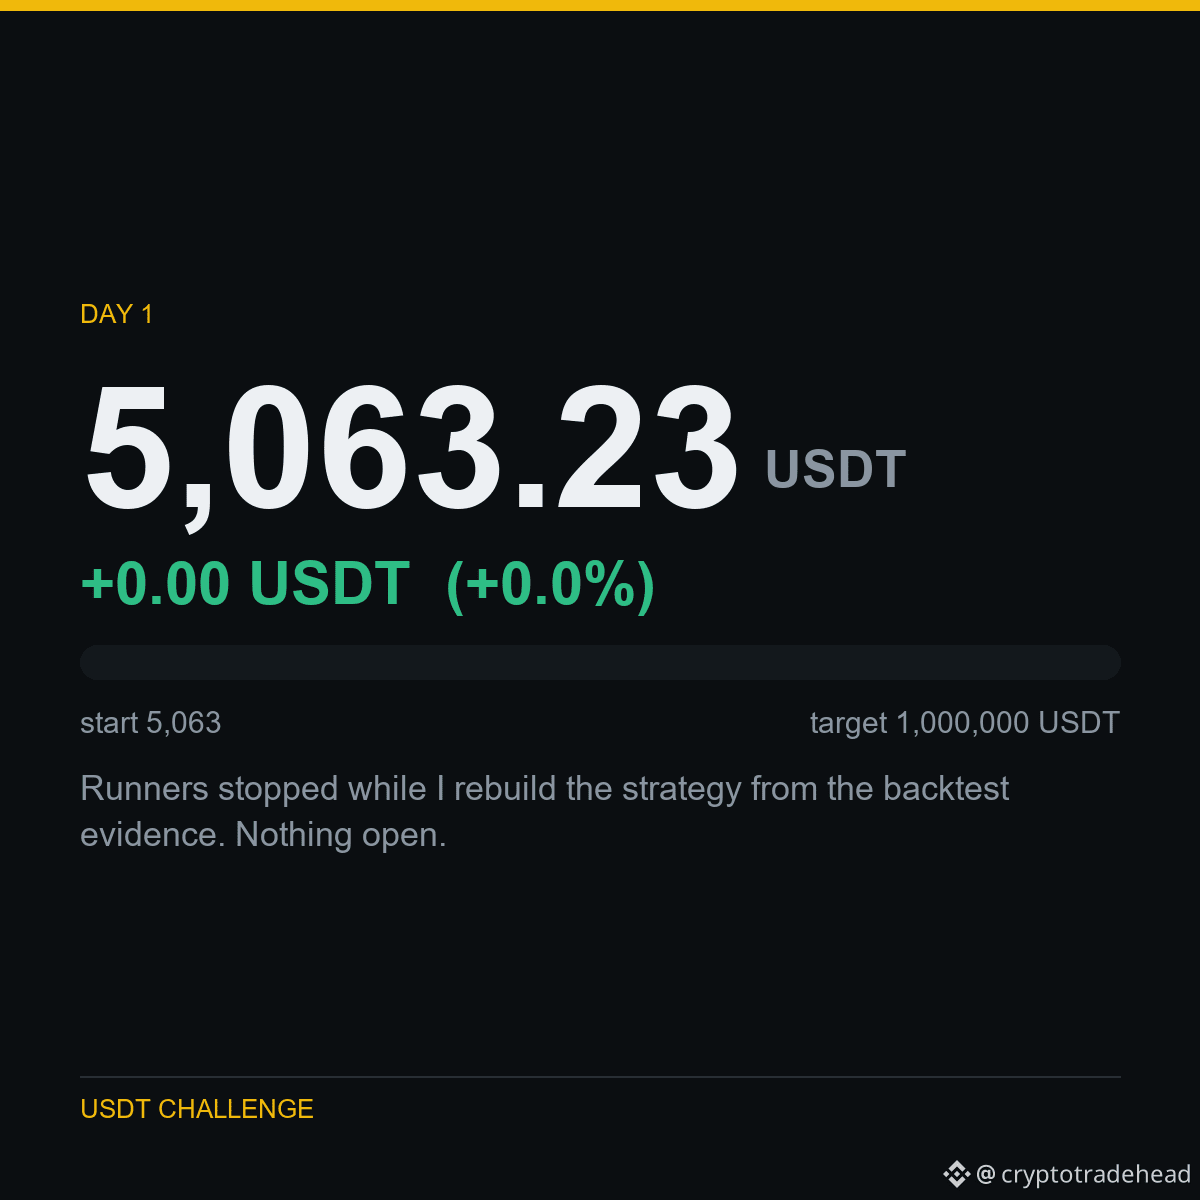
DAY 1 - 5,063 USDT to 1,000,000 USDT
Balance: 5,063.23 USDT
Change: +0.00 USDT (+0.0%)
Runners stopped while I rebuild the strategy from the backtest evidence. Nothing open.
Running on a Binance testnet account, so this is demo capital - I would rather say that than let you assume otherwise. The strategy, the costs and the losses are all real.
No signals for sale, no course, no affiliate link. Just the account and the data behind it.
Traded in this challenge: $BTC $SOL $AVAX
#Binance #USDT #Futures #TradingChallenge #Crypto
5
Ver traducción
HOW I TESTED IT
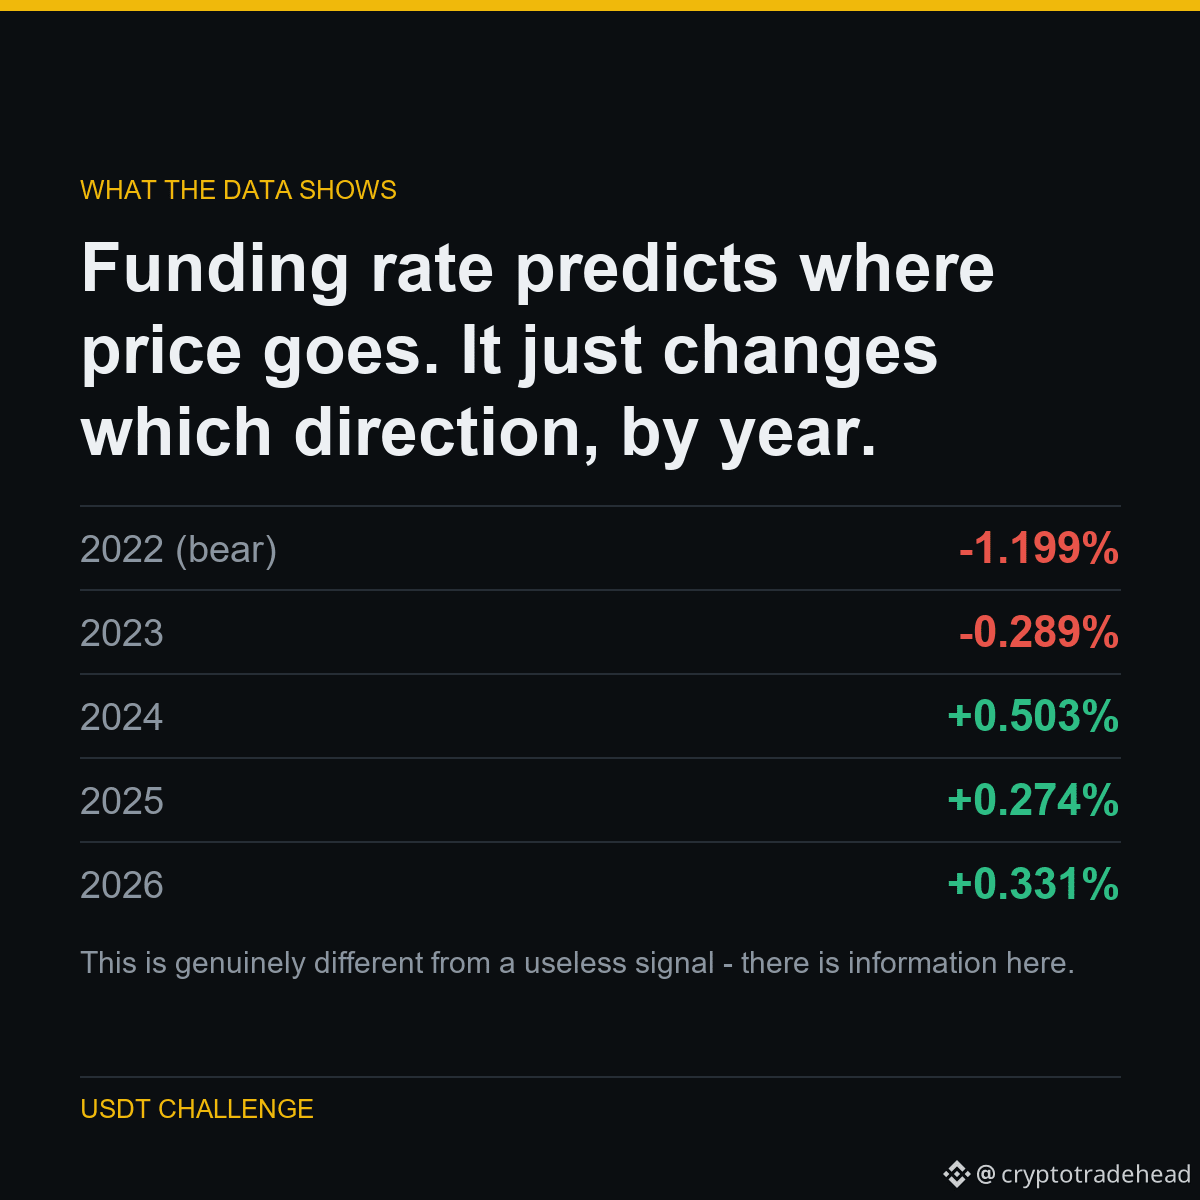
I sorted every funding print into quintiles and measured the forward 72-hour return of the highest versus the lowest.
In bear markets, high funding preceded WORSE returns - crowded longs getting squeezed. From 2024 onward it preceded BETTER returns - momentum.
The signal is real. The sign is not stable. Average it across all years and you get -0.08%, below the 0.240% it costs to trade.
THE NUMBERS
2022 (bear): -1.199%
2023: -0.289%
2024: +0.503%
2025: +0.274%
2026: +0.331%
This is genuinely different from a useless signal - there is information here. But to use it you would need to know the regime in advance, which is the same circular problem that kills everything else.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $DOGE
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Artículo
Ver traducción
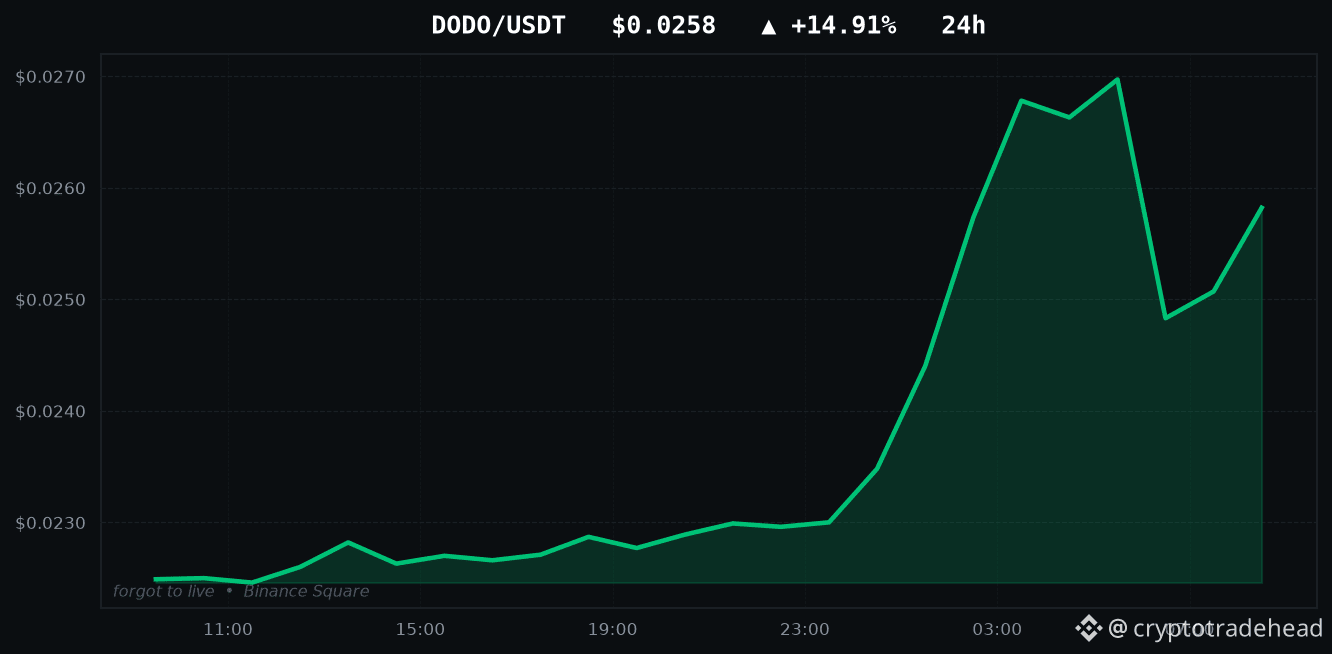
DODO is up +14.91% - I tested both ways to trade itTODAY'S TOP GAINERS
DODO: +14.91%
ERA: +14.53%
REZ: +10.03%
BABY: +9.24%
OSMO: +8.59%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like DODO's +14.91%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $DODO $ERA $REZ
#Binance #Altcoins #Futures #DODO #CryptoData
DODO is up +14.91% - I tested both ways to trade it
TODAY'S TOP GAINERS
DODO: +14.91%
ERA: +14.53%
REZ: +10.03%
BABY: +9.24%
OSMO: +8.59%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like DODO's +14.91%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $DODO $ERA $REZ
#Binance #Altcoins #Futures #DODO #CryptoData
3
CÓMO LO PROBÉ
Canal Donchian de 20 períodos, stop basado en ATR, 10 activos, cuatro años y medio.
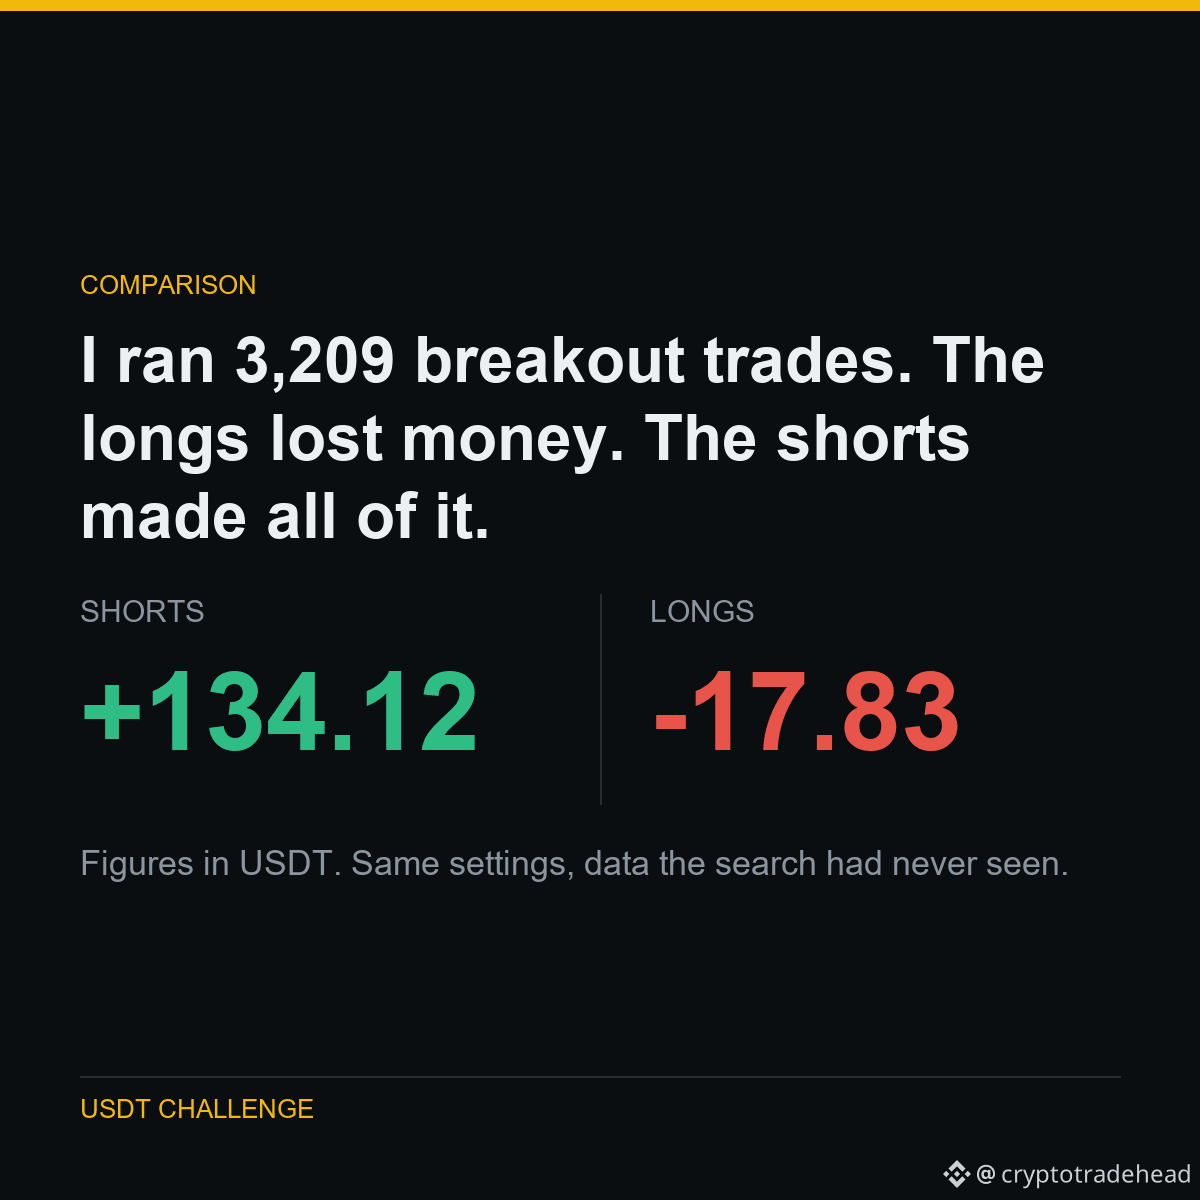
Si esto fuera simplemente aprovechar un mercado alcista, las posiciones largas serían las ganadoras. No lo son: dan pérdidas.
Las posiciones cortas incluso generaron ganancias con monedas que SUBIERON durante el período. BTC ganó un 94 % con una estrategia de comprar y mantener, y aun así ponerse corto en sus rupturas devolvió +22.83 USDT. XRP ganó un 87 %; las posiciones cortas devolvieron +24.27 USDT.
LAS CIFRAS
Operaciones cortas: +134.12 USDT
Operaciones largas: -17.83 USDT
Operaciones totales: 3,209
Activos con operaciones cortas rentables: 8 de 10
Las criptomonedas caen más rápido de lo que suben: las cascadas de liquidaciones son asimétricas. Esa estructura del mercado está documentada, por lo que este resultado es más creíble que uno que solo funciona cuando todo sube.
Parte de un experimento público: de 5,063 USDT a 1,000,000 USDT; publico todos los resultados, incluso los que me dejan mal.
Ejecutado en $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
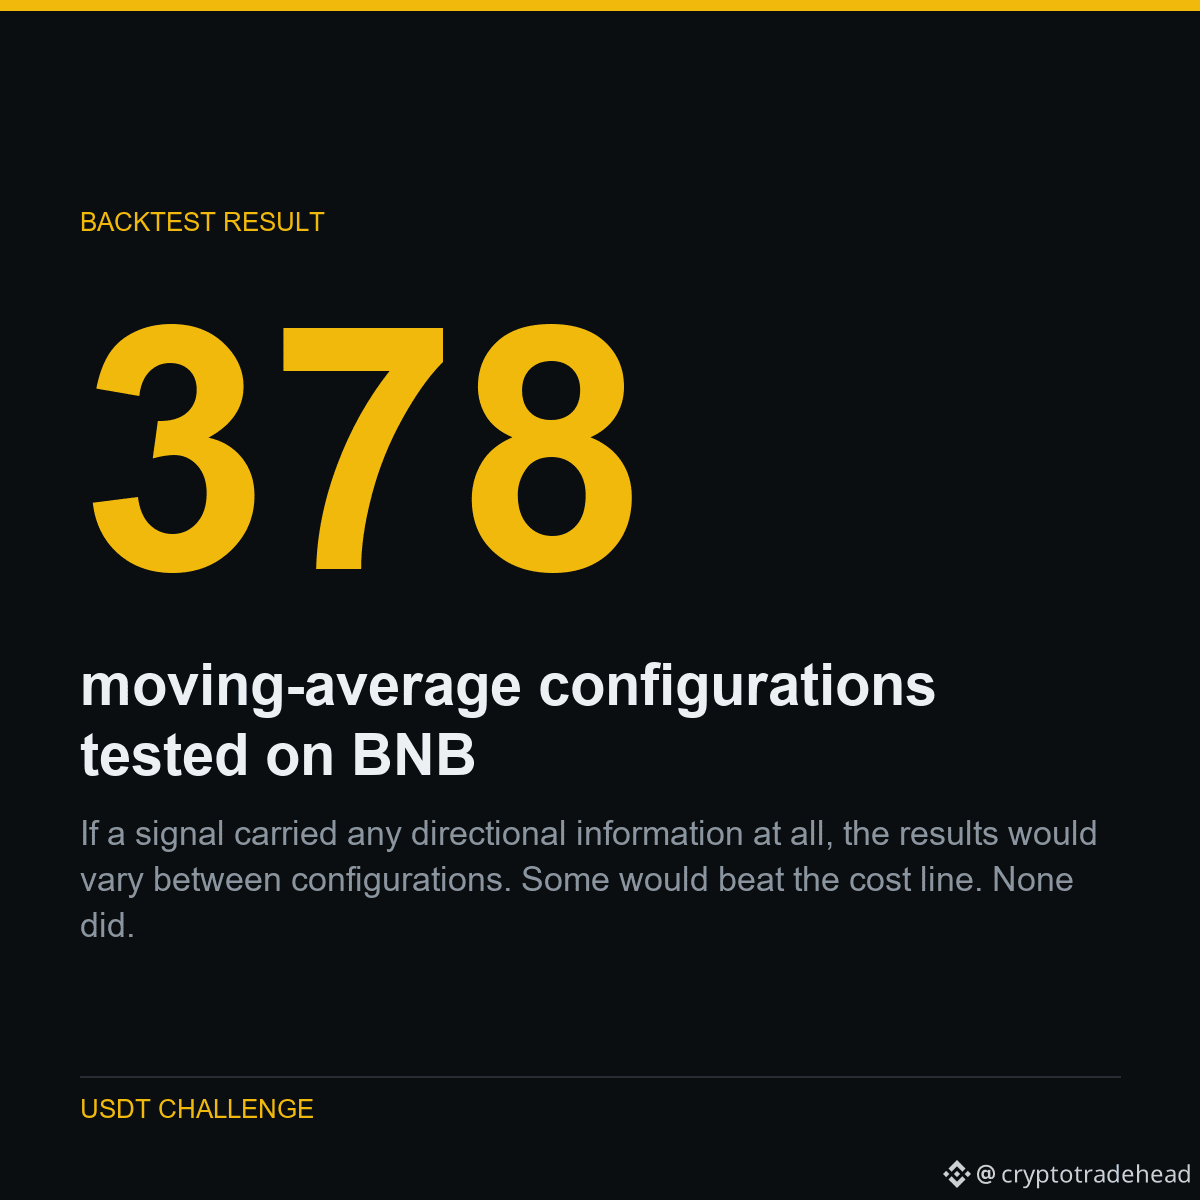
Si una señal aportara algún tipo de información direccional, los resultados variarían entre configuraciones. Algunas superarían el umbral de costes. Ninguna lo hizo. No se trata de una ventaja débil que haya que ajustar: es una ventaja nula a la que se le cobra una tarifa de entrada.
Esto es lo que dio ese resultado.
Probé 378 estrategias de medias móviles. Todas perdieron exactamente lo que costaba operar.
Dos familias de señales, cuatro marcos temporales, EMA y SMA, con y sin filtro de tendencia, solo posiciones largas y solo posiciones cortas. 378 combinaciones en total, todas con comisiones reales y deslizamiento medido real incluidos.
El coste de ida y vuelta de una operación es el 0,240 % del tamaño de la posición. El resultado promedio por operación, en todas y cada una de las configuraciones, se situó entre -0,361 % y -0,401 %.
Eso es el coste, y nada más.
Parte de un experimento público: de 5.063 USDT a 1.000.000 USDT. Publico todos los resultados, incluidos los que me dejan mal.
Ejecutado en $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
5
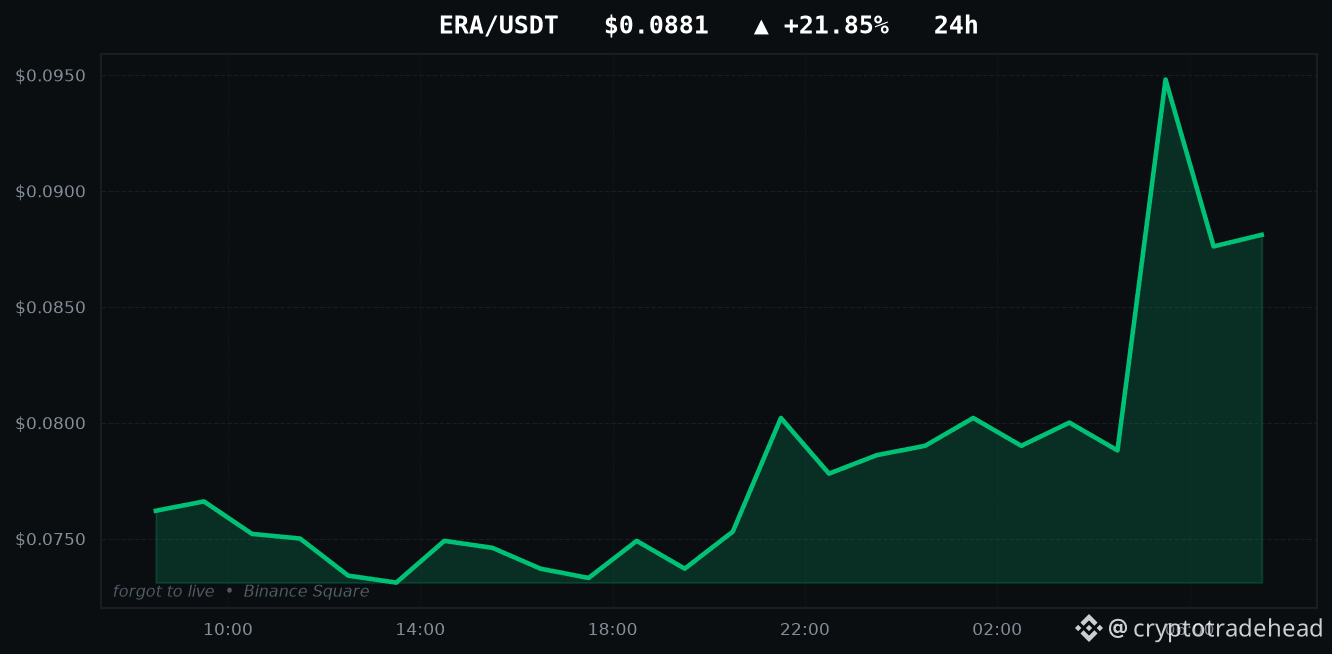
Artículo
ERA sube un +21.85%: probé las dos formas de operarMAYORES SUBIDAS DE HOY
ERA: +21.85%
BMT: +15.26%
DODO: +12.99%
OSMO: +7.91%
REZ: +7.46%
Todas las cuentas de esta app te mostrarán esta lista. Aquí está la parte que omiten.
Hice pruebas retrospectivas de las dos formas de operar un movimiento como el +21.85% de ERA: comprar la ruptura y apostar en su contra suponiendo que revertiría. En ambos casos perdí dinero. Y no por poco: las pérdidas fueron aproximadamente iguales al costo de transacción, un 0.240% por operación de ida y vuelta, que es lo que parece una señal sin información cuando se le cobran comisiones.
Un gran movimiento en 24 horas te dice que algo ya ocurrió. No te dice qué pasará después, y los datos lo confirman en ambos sentidos.
ERA sube un +21.85%: probé las dos formas de operar
MAYORES SUBIDAS DE HOY
ERA: +21.85%
BMT: +15.26%
DODO: +12.99%
OSMO: +7.91%
REZ: +7.46%
Todas las cuentas de esta app te mostrarán esta lista. Aquí está la parte que omiten.
Hice pruebas retrospectivas de las dos formas de operar un movimiento como el +21.85% de ERA: comprar la ruptura y apostar en su contra suponiendo que revertiría. En ambos casos perdí dinero. Y no por poco: las pérdidas fueron aproximadamente iguales al costo de transacción, un 0.240% por operación de ida y vuelta, que es lo que parece una señal sin información cuando se le cobran comisiones.
Un gran movimiento en 24 horas te dice que algo ya ocurrió. No te dice qué pasará después, y los datos lo confirman en ambos sentidos.
6
Inicia sesión para explorar más contenidos
Únete a usuarios globales de criptomonedas en Binance Square
⚡️ Obtén información útil y actualizada sobre criptos.
💬 Avalado por el mayor exchange de criptomonedas en el mundo.
👍 Descubre perspectivas reales de creadores verificados.
Email/número de teléfono
Temas populares
BinancePick
2.6M vistas
139,849 están debatiendo
¡Únete a #TemporadaDeResultados: predice resultados en Binance Pick y comparte tu opinión en Binance Square!
Binance Square Official
·400 me gusta
·337.7k vistas
EarningsSeason
5M vistas
24,133 están debatiendo
StrategyMSTRSurpassesNasdaqInMarketCap
115 vistas
22 están debatiendo